August 13, 2017
by Todd Shaver | Aug 13, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
Talk of “fire and fury, the likes of which the world has never seen” aimed at North Korea spooked anybody listening. The markets have been calm for so long and then BOOM, the VIX (^VIX: 15.45) spiked 44% in one day and 60% in two days of trading this week. Our take is that we had been in an unsustainable lull of inactivity. These things happen and you have to be prepared for them. But in the long run, they work themselves out and things get better. Stay the course. If you are worried, consider dialing back your exposure to some of the more aggressive equities out there in favor of looking toward our REIT and High Yield portfolios, where the income stream of dividends offers greater downside protection.
But no matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks/funds: Shopify, Apple, The Carlyle Group, Sabra, AstraZeneca, AllianzGI Equity & Convertible Income Fund, Twilio and Amazon.
BMR Companies & Commentary
Apple (AAPL: $158, up 1% - all prices are for the week)
Apple is hard at work sublet shifting its brand. Everybody knows Apple. But Apple isn’t the name of its products. Apple's greatest hits over the past 30 years don't have "Apple" in their name: Macintosh, PowerBook, iTunes, iPod, iPad, iPhone, Siri. The newer stuff that does carry the Apple moniker -- Apple Watch, Apple Music, Apple TV-- have been either outright disappointments or solid but not wildly popular businesses.
But Apple is as good a brand as any. Think Proctor & Gamble, Ford, General Electric - you get the point. It's hard to transition from a corporate brand to additional brand franchises, but if you can do it, the future is bright!
CEO Tim Cook is working hard to make it happen. The Apple brand speaks to the firm's culture and reputation to employees, shareholders and governments. A product brand communicates a specific message about the item's quality, design, or function to consumers. There is so much potential.
BMR Take: Apple is just one of the companies that always figures it out - just as we are seeing them do now with the focus on services revenue and rethinking the brand.
We remain very bullish. The stock is trading at 17x this year’s consensus EPS of $9.00. The Services business is on pace to double over the next few years. Our Target of $155 has now been breached. Yea! We hereby raise our Target Price to $170. This will bring the company close to a $900 billion valuation, now at $813 billion. Our Sell Price remains the same: “We would not sell Apple.”
The Carlyle Group (CG, $21, flat*)
Carlyle is really a master of the universe. The company’s private equity investments are behind so much of the world’s underlining economic activity it’s ridiculous. The latest example is with McDonald's.
This week McDonald's announced the successful completion of a strategic partnership with CITIC Capital Partners and The Carlyle Group. Ramping up a new era of growth and innovation, the partnership will operate and manage McDonald's businesses in mainland China and Hong Kong, leveraging combined expertise and strength to drive an expansion strategy.
The transaction has obtained China's regulatory approval and was completed on July 31st, creating the largest McDonald's franchisee outside of the United States. The sale to the new McDonald's China franchisee includes McDonald's existing businesses in Mainland China (2,500 restaurants) and Hong Kong (240 restaurants).
The new partnership announced a series of development initiatives for mainland China. Termed "Vision 2022," this strategy aims to drive double-digit sales growth in each of the next five years by increasing the number of restaurants from 2,500 to 4,500 by the end of 2022, bringing unparalleled convenience to Chinese customers. The opening pace of new McDonald's restaurants in mainland China is expected to progressively ramp up from approximately 250 per year in 2017 to 500 per year in 2022 under the new partnership. Vision 2022 also includes an increase of "Experience of the Future" restaurants to over 90%, which will enable the brand to offer a digitalized and personalized dining experience to more customers.
BMR Take: We believe Carlyle is heading to $30. Consensus is looking for a solid dividend of $1.80 next year and $2.15 the following. EPS is running closer to $3. Few institutional investors can buy the stock because the K1 tax structure creates issues. But that will change and when it does, look out on the upside.
* The stock was down 40 cents this week, but CG paid a 42 cent dividend on Thursday and when a stock pays a dividend the stock always opens that day down the amount of the dividend. Thus Carlyle was flat this past week.
Shopify (SHOP: $92, down 5%)
Shopify’s plan is to let half a million merchants run their business via Alexa and bots. Shopify wants its 500,000 merchants to be able to run their businesses almost entirely through the use of bots or voice apps like Alexa.
At F8, Facebook’s annual developer conference, Shopify announced plans to launch a Facebook Messenger bot, named “Kit”, the first commerce platform to do so. Through conversations on Facebook Messenger or SMS, Kit can do things like place a Facebook ad or start an email marketing campaign.
The development roadmaps of voice apps like the Shopify Alexa* skillset and text bots like Kit will begin to converge, so that the same merchant analytics available today by voice will become available in a text interface, and the same actions to run your business available today through text will someday be available with your voice.
* Shopify Alexa is a partnership with Amazon to use Alexa.
The Shopify Alexa skill first became available in January, but was launched with no marketing or promotion in order listen to the queries put forward by merchants to better understand the kinds of questions they want the skill to be able to answer. Before merchants are given the ability to run business operations in a conversational interface, a few other features will be added first.
Based on merchant feedback, more long-term business performance insights are on the way, and work will continue with engineers to ensure the bot can handle the range of questions a merchant has and understands the variety of ways a merchant may ask a question.
BMR Take: When we look at the core building blocks of how this company is advancing its growth potential of Total Addressable Market (TAM) is expanding. In addition, we see opportunities in international, in new merchant solutions and apps, and building scale with Shopify Plus, the company’s enterprise-focused solution. In our view, the valuation is supported by the long runway and expanding TAM given Shopify’s lower relative market share, still less than 5%. We reiterate our bullishness on the stock. The stock is currently trading at about 9 times the estimate of next year’s sales. This valuation is rich but justified.
Sabra Health Care REIT (SBRA: $21.45, down 7%)
We have decided to take our chips off the table in Sabra. Two reasons. First, the core senior housing portfolio growth is essentially flat so it’s hard to see any organic upside from the business. Second, the pending merger with Care Capital is being fought creating noise and possibly more risk.
Regarding the latter, two activist investors are urging Sabra to drop the Care Capital deal. They say shareholders of the healthcare-focused real estate investment trust should reject the merger at a shareholder meeting next month. Why? Sabra was overpaying for Care Capital's assets by up to 30%, the hedge fund said in a presentation. Ouch.
Consensus for Sabra Healthcare REIT:
1 Sell Rating, 6 Hold Ratings, 1 Buy Rating
BMR Take: We like to listen to the market and to other shareholders invested in the stocks we own. Especially when the other shareholders do great research and make objective points. We added the stock at $24 in May and are down a bit, but with the dividend, it wasn’t a great loss. Let’s move on to the next one.
AllianzGI Equity & Convertible Income Fund (NIE: $19.79, down 2%)
This fund seeks total return with capital appreciation and high current income through investment in convertible equity, income producing securities and through utilizing an options strategy. It’s top holdings are Microsoft, Apple, Amazon, Facebook, and Google. It does not use leverage. It does not hold fixed income.
60% of the stocks it holds are in the largest giant companies, and 37% in large cap companies. The Funds PE ratio is 19 versus the 17.2 benchmark, but sales, EPS, book value, and cash flow growth is all better than the benchmark.
See more discussion in The High Yield Report later in this newsletter.
BMR Take: Sometimes it is nice to own a fund and have some help picking all the right places to be. We like AllianzGI with its 7.7% yield. You can buy right now at a discount to the net asset value of $21.75, a very opportune entry point.
AstraZeneca (AZN: $29, flat*)
Fierce pharma rivals collaborating on cancer treatments are increasing the competitive landscape, hurting AstraZeneca. But we believe we must stay the course. AstraZeneca reported disappointing results for its clinical trials examining Tremelimumab combined with Imfinzi for the treatment of lung cancer. The market has become crowded with checkpoint inhibitors and immunotherapy drugs, which means that the number of such potential combinations of treatments is growing. Pharma rivals are now cooperating -- last week Merck bought half the rights to AstraZeneca's Lynparza, and in July Eli Lilly said it would out-license or co-develop one-third of its oncology pipeline.
BMR Take: Healthcare has been a minefield for months now. AstraZeneca has been beaten down. Analysts have been upgrading the stock on valuation. It is very cheap versus expectations for around $2 of EPS for next few years. Consider the 3% dividend yield on top of that. It’s a classic value here as the stock is truly undervalued. Our Target remains $42, and our Sell Price of $32 has been breached, so please make a decision with your own portfolio as to whether you personally wish to stay the course. We are trying to be patient here to give the company more time to perform.
*A dividend was paid on Wednesday of 45 cents.
Upcoming Economic News
Retail Sales
August 15th , 8:30 AM
Period: July
Consensus: 0.40%
Prior: -0.20%
Housing Starts
August 16th, 8:30 AM
Period: June
Consensus: 1,220,000
Prior: 1,215,000
Initial Claims
August 17th, 8:30 AM
Period: Through August 12
Consensus: 240,000
Prior: 244,000
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
Stocks finished mostly higher again the week before last, mainly because of good corporate earnings, a stronger-than-expected Jobs report, solid GDP performance, healthy Consumer Confidence and a little better than expected Export & Import numbers. Is it all "too good to be true?" [Well, indeed it was!]
According to the latest American Association of Individual Investors survey, individual investors are now holding their lowest cash allocation since 2000. They are now among the most invested in financial markets since 1988. The three other time periods with the lowest cash allocations were in 1998, 2000, and 2015, and all of these preceded times when investors probably wished they had more of a cushion.
We certainly do not think we're on the brink of another 1999 dotcom bubble or a 2008 financial crisis crater. But one thing's for sure, stocks don't always go straight up forever. There will be volatility and pullbacks as Fed-tightening continues. According to recent news reports, there is now a 50/50 chance the Fed will raise rates again in December. Whenever a pullback occurs, it is not going to be unexpected. It's overdue and as natural to the market as hot dogs are to ball games. With a backdrop of really solid earnings, we expect any pullback to be fairly brief in duration. If earnings keep growing and the job numbers keep getting stronger, pullbacks will just be setting up the next move higher. If Congress grows up and we get tax relief and corporate tax reform, investors will be saying, "Laissez les bon temps roulez".
Note what UBS has to say in their latest report on the Equity Markets: The bottom line: stocks are not cheap, BUT ARE NOT in "bubble" territory.
Amazon Update (AMZN: $968, down 2%)
The stock got hit last week as the rest of the market had some tough times as you know. There is an ongoing discussion over valuation with this company. We had a heated argument with a very astute investor who thinks the stock is overvalued saying that the company will NEVER report substantial earnings; that Bezos will ALWAYS have a new project in mind that will cause him to spend, spend, spend on new infrastructure.
We agree to a certain extent, but disagree with the profit story. As you know, we have said many times revenues are the key to all success in the market. Amazon had revenues of $89 billion, $107 billion and $136 billion in the last three calendar years. This year? Hard to say, but it looks like at least $175 billion? This is just huge of course. We remain bullish for as far as we can see forward.
We hereby raise our Price Target from $1000 to $1100 and leave the Sell Price at $900.
Twilio (TWLO: $31, up 7%)
Twilio had a huge week after reporting blowout revenues as we reported via News Flash on Tuesday. Total revenue – $96 million, up 49% from the second quarter of 2016 and 10% sequentially from the first quarter of 2017.
Loss from operations – $7 million, compared with a loss of $11 million for 2Q16.
And we love this stat: 43,000 Active Customer Accounts as of June 30, 2017, compared to 31,000 Active Customer Accounts as of June 30, 2016.
Profits are still at slightly below breakeven, but as you know, we are banking on the huge revenue gain.
Here is the consensus on the Street:
2 Hold Ratings, 15 Buy Ratings
Price Targets:
8/8/2017 Canaccord Genuity $38
8/8/2017 Robert W. Baird $39
8/8/2017 J P Morgan Chase $40
8/8/2017 Mitsubishi UFJ Financial Group $35
7/17/2017 Summit Redstone $36
BMR Take: We love this company and think it can be a monster. An Apple? A Microsoft? Hard to predict the next 10-15 years, but watch this one closely.
Wall Street Consensus for United Parcel Service (UPS: $111, up 1% in a very tough week, and after an 83 cent dividend on Thursday)
Consensus: 10 Hold Ratings, 5 Buy Ratings
Price Targets:
8/8/2017 Citigroup $128
7/3/2017 Sanford C. Bernstein $127
SNAP (SNAP: $11.83, down 13% - still at a $14 billion market cap)
Don’t buy SNAP
Don’t buy SNAP
Don’t buy SNAP
Revenues: $182 million up from $72 million
Loss: $443 million up from a loss of $116 million last year. WOW! (How is this actually possible?)
Don’t Buy SNAP
Don’t Buy SNAP
A Letter from a Subscriber about Netflix (NFLX: $171, down 5%)
From: Stan Makovsky [mailto:stan@stanxxxx.com]
Sent: Wednesday, August 09, 2017 3:11 PM
To: 'Todd at The Bull Market Report'
Subject: Netflix
Hi Todd,
Disney pulling out of Netflix seems to be a big deal for both stocks. Your thoughts please?
Best Regards,
Stan Makovsky
Our Response:
Hi Stan –
I am not really concerned too much. The market is getting slammed today as I write this [Wednesday] and Netflix is down just $4. If it were down $20 I’d be a little concerned. But I believe Disney needs Netflix more than Netflix needs Disney. Netflix is a force now and as you know is spending billions of dollars a year on programming. They will be just fine. The scary thing about Netflix is their profit level – which is tiny. This needs to change.
Todd Shaver
Founder and Editor in Chief
The Bull Market Report
A Powerful Financial Newsletter
Since 1998
@BullMarketRept on Twitter
The High Yield Report
By Michael Foster
Special to The Bull Market Report
It’s been a long time coming, but we finally see a bit of fear entering the market.
For high yield investors, this is a concern because downturns and mini-corrections tend to be amplified in high yield investments. The S&P 500 slid over 1% last week but many high yield investments fell much more, especially closed-end funds (CEF). The AllianzGI Equity and Convertible Income Fund (NIE: $19.80) fell nearly 2% over the last week due to a considerable decline in the fund’s NAV, which fell over 1% in a single day of trading last week. In many cases, a market correction will result in CEFs’ discounts widening as investors sell off the fund. Surprisingly, however, holders of the AGIC fund have been surprisingly calm, resulting in the discount staying less than 10% by the week’s end. Recently, the discount had shrunk to less than 9%, so this is definitely not as good as it has recently been. But it’s surprisingly not as bad as it could be.
Of course, if the selloff continues throughout the coming week, it would be more than reasonable to expect Allianz to see a larger discount as slower and more risk-averse investors finally get around to selling this and other closed-end funds. What does this mean for you? Well, we maintain a bullish outlook for the economy and for stocks, with corporate profits continuing to rise year-over-year and the Allianz fund in particular maintains a strong portfolio of respected and strong-performing stocks. There’s no reason to sell off amongst the fearful, but anyone with extra cash on the sidelines who wants a sustainable near-8% dividend stream could consider picking up some of this fund.
Similarly, The Bull Market Report’s second CEF pick, the Pimco Dynamic Income Fund (PDI: $29), had a rough week during the market’s selloff, falling over 4%, after paying out a 22 cent dividend on Wednesday. This has resulted in PDI’s premium price falling slightly, and now the fund trades at slightly over a 2% premium to NAV.
After the sell-off, investors may be eager to buy more of the Pimco fund and capture that 9% dividend yield plus the potential upside of special dividends at the end of the year. Before rushing to buy, however, there are a few things to consider. The fund’s NAV has risen 10% so far this year even after accounting for dividend payouts, which means the fund’s payout remains sustainable. However, this is a relatively weak performance compared to its past performance. Part of the reason for that is the growing burden of its promised payouts. Because it trades at a premium, it has been significantly harder for the fund to pay out dividends than to earn the comparable income in the open market. Since the fund’s premium rose to as much as 10% earlier this year, those dividend payouts were particularly burdensome for Pimco’s managers. Now that the premium is at its lowest point since November last year, that dividend is going to be slightly easier to pay.
Easier, but not easy. The real problem with this fund is that it has years and years of a solid track record thanks to its contrarian nature. The fund invested heavily in mortgage-backed securities (MBS’s) after 2008, when they were synonymous with financial ruin. In reality, however, many of these assets were extremely undervalued because of investor fear, and Pimco had the chops to find the good ones and buy them. Hence the fund’s massive outperformance.
However, 2008-2009 is becoming a fainter memory, and the market is finally realizing the huge mistake it made in avoiding many quite valuable MBS’s. As a result, more capital is coming into that market and creating more competition for Pimco. Ultimately, that means diminished returns for investors holding this fund.
Unfortunately, this has also happened as more investors have discovered the fund’s tremendous returns. Holding this fund has become a crowded trade. Back in 2013-2015, the fund almost always traded at a discount; in late 2015, shortly before The Bull Market Report recommended it, its discount fell to 11%. But now a flood of capital has come in and driven the fund to a consistent premium, while earning superior returns through MBS’s is getting harder for the fund.
This doesn’t mean you should sell the Pimco Dynamic Income Fund. But it does mean one has to wait before buying more and instead choose other strong dividend payers like the AllianzGI fund.
Finally, let’s briefly discuss REITs. These were a mixed bag, with pretty much all REITs down and some down much more than others. Omega Healthcare Investors (OHI: $30) fell 2% over the week alongside the broader market, with its greater volatility amplifying losses. Yet the similarly volatile Government Properties Trust (GOV: $18.13) fell about 1% over the same period, even beating the market. There are a couple of pretty obvious reasons for this. For one, Government Properties Trust’s big decline earlier this month means it’s found a bottom and can’t plunge much lower. Obviously this means buying now makes sense. Omega, however, hasn’t exactly found its bottom yet and only went negative YTD at the end of last month. There’s no fundamental reason for this – there is sustainable income, the dividend is still rising, and Omega’s expansionary plans are on track. But there is a lot of fear in the market, and that is reflected in the rapidly fluctuating price of this stock.
While buying Omega now is buying a bargain, investors should be prepared for more volatility. Government Properties, while not exactly strong, seems to have found a floor that is limiting further downside, making it a more appealing buy right now. But no matter what you do right now, selling is not a good idea. There is no fundamental reason to fear for the future of equities or high yield assets, so ignore the panic selling. It will be intense but brief-lived, as always.
Good Investing,
Todd Shaver, Editor, CEO and Founder
The Bull Market Report
Since 1998
July 23, 2017
by Todd Shaver | Jul 23, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
Have equity markets come too far too fast this year? Year-to-date the S&P 500 is up 12%. We are certainly not ringing any alarm bells. Rather we note that the market can’t just go up in a straight line for extended periods. While stock indexes ended the week higher, the underlining story is we are seeing the steadiest outflows of cash since 2009. Even as the S&P 500 clawed its way to a fresh record and squeezed out a third consecutive weekly gain, signs of fading enthusiasm in U.S. stocks have become increasingly difficult to ignore. The latest can be seen in the SPDR S&P 500 Trust, the biggest exchange-traded fund tracking the U.S. equity benchmark. As of Thursday, investors had pulled $3.8 billion out of it in July. That puts the fund on pace for a fourth consecutive monthly outflow, which would be the longest streak since the start of the bull rally in 2009. This push and pull will continue of course. The S&P 500 touched new highs this week before retreating as an intensifying investigation into President Donald Trump stoked concern that his economic agenda may stall. We expect more of the same in the week ahead.
However, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks: Microsoft, Visa, Athenahealth, Netflix, and Blackstone. We believe in these companies.
Highlights From The Past Week
Tech Index Eclipses Record From Dot-Com Era. Tech stocks broke a nearly two-decade-old record this past week. The S&P 500's Information-Technology sector ended the day on Wednesday at 992.29, closing above its previous all-time high of 988.49 set in March 2000 at the peak of the dot-com bubble. Tech stocks are by far the best-performing among the index's 11 sectors this year, up 23% after posting their ninth consecutive day of gains Wednesday.
Bank of America Chooses Dublin for Main EU Hub After Brexit. Bank of America has picked Dublin to locate its main European Union hub in preparation for Britain quitting the bloc in 2019, the latest global bank to finalize its contingency arrangements after Brexit. The bank will move some roles from London to the Irish capital and other cities across the EU. Bank of America already has a fully licensed operation in Dublin, and employs more than 700 people in the country. London has flourished as a hub for global finance in part because firms based in the capital have the right to do business across the 28-nation EU. British banks, as well as firms from the U.S., Japan and other non-EU countries with a base in London, stand to lose this “passport” after Brexit and may need to channel business throughout other locations in the bloc.
Dublin is the second most popular destination, after Frankfurt, for Financial Services companies seeking uninterrupted EU access post-Brexit. The city provides a low-tax English-speaking location and has similar laws and regulations to its U.K. neighbor. It is fascinating to watch the evolution of the European Union and what it means for business. There are certainly major changes ahead for companies.
Draghi Says ECB Isn't There Yet as Inflation Lag Takes Time. Mario Draghi said policy makers are still waiting for inflation to catch up with the economy’s recovery, as they put off any discussion on winding back stimulus until after the summer. Specifically, he said the EU is finally experiencing a robust recovery where one only has to wait for wages and prices to follow course. “We need to be persistent and patient and prudent, because we’re not there yet.” While the ongoing economic expansion provides confidence that inflation will gradually glide toward levels in line with the inflation aim, it has yet to translate into stronger inflation dynamics. A very substantial degree of monetary accommodation is still needed for underlying inflation pressures to gradually build up. What does this all mean? Continued easy money policy from Europe’s central bank is a big benefit for global equity markets including the US. Good for the US stock markets.
Congress Must Avoid Spooking Markets on Debt Limit. The U.S. debt limit needs to be raised in a calm, thoughtful manner that steers clear of political uncertainty that would spook markets. But will they do it? Congress must avoid any political standoff that could set in motion disruptive activities such as a need to choose which bills to pay and which to delay. The government will reach its statutory limit on borrowing in early October. President Donald Trump’s administration has asked Congress to raise the ceiling before then. Concerns have surfaced in the Treasuries market, with traders willing to pay more for bills maturing after October 19th to avoid being caught holding securities vulnerable to a technical default. Watch for the upcoming political discussion over the debt and let’s hope it doesn’t get contentious.
BMR Companies & Commentary
Microsoft (MSFT: $74, up 1% - all prices in the newsletter are for the week)
The company reported earnings this week. Revenue of $25 billion beat the consensus by 2% while EPS of 98 cents beat by a big 27 cents. Analysts were positive on the quarter itself, especially around commercial cloud and commercial bookings which both came in nicely above Street expectations. Commercial cloud growth accelerated and is also experiencing margin expansion which is helping increase both operating income and free cash flow generation. Some went further and talked on how Microsoft looks to be taking share from Amazon Web Services (AWS) and is becoming a larger force in the space.
Despite the strong revenue quarter, operating expenses came in higher than expected and the company is also seen to have a higher tax rate than estimated. On top of this, some wanted to see the “billings beat” seen in the quarter to flow into greater revenue guidance for Q1.
The cloud business – Azure - was the main story from the quarter due to 30% growth in commercial bookings. Office 365 and servers were both healthy, and execution on renewals was strong.
BMR Take: All in all a very solid quarter from Microsoft. The stock hit NATHs* this week and we see NATHs ahead. We believe the stock will hit $80 in the coming months, which represents 20x EPS. The market cap is now $570 billion, only topped by Apple at $780 billion and Google at $680 billion.
*NATH – New All-Time High
Visa (V: $100, up 3%)
Visa reported strong earnings. EPS beat on stronger revenue and the company raised expectations for the forward outlook.
Visa reported EPS of $0.86, $0.05 ahead of the Street. Visa is now guiding to approximately 20% EPS growth, which compares to the "high end of mid-teens" growth which was issued previously.
From management at the earnings announcement: “Results reflect strong growth in payments volume, cross-border volume, and processed transactions, which were powered by economic tailwinds in the U.S. and globally. Results and growth reflect the company’s strategy to pursue the conversion of cash and checks to electronic payments in partnership with our clients around the world.”
The story at Visa has been strong for decades and not much has changed. And that’s a good thing. Visa is a global payments technology company working to enable consumers, businesses, banks and governments to use digital currency. Visa connects billions of consumers, businesses, banks and governments in more than 200 countries and territories worldwide. The company is as close to an unstoppable machine as can be at this point.
Take a look at this chart of Visa for the past nine years:
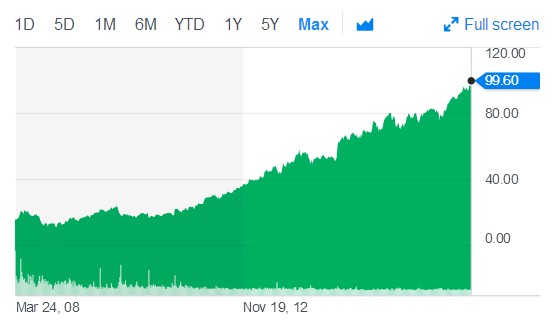
With a market cap of $230 billion, it is one of the greatest companies in the world. We would highly suggest you own some.
BMR Take: Consensus now sees EPS closing in on $5.00 in the next 1-2 years. With EPS growth running 20%, valuation looks awfully compelling to us still. We added the stock in early 2016 at $70. Our current Target is $95 which it has blown through this month, so we hereby raise our Price Target to $110. Our Sell Price remains “We would not sell Visa.”
Athenahealth (ATHN: $156, up 9%)
Athenahealth delivered an exciting quarter. The company believes it is at a key inflection point in its history and that 2017 will be a productive year for building out what differentiates them in the market. The company is demonstrating the power of its co-source model by simplifying and reducing client work. It’s building a new hospital service. It’s re-platforming AthenaNet. It’s grown its network to 100,000 providers, 98 million unique patient records, and 2.8 million covered lives, and is now positioned to be healthcare’s first true technology company. Stellar!
So many highlights from the quarter to discuss. Revenue increased 15% from last year to $293 million beating the consensus by $2 million. EPS of $0.51 crushed the consensus estimate of $0.39.
Moreover, the company continued the implementation waves at New York-Presbyterian Medical Groups, Adventist Health, and Tenet Health. The company gained access to the Centers of Medicare and Medicaid Services (“CMS”) claims data in certain states as a CMS Certified Qualified Entity. The company acquired Praxify Technologies to advance its platform strategy and mobile capabilities and accelerate its research and development initiatives by leveraging Praxify’s powerful app development platform. We could go on and on…
BMR Take: Athenahealth is a sleepy, off-the-radar company that is now firing on all cylinders. There is real upside potential ahead. Recall, big time activist investor Elliot Management has taken a stake in the company. Could we see all-time highs ahead which would be near $200? We feel this is a more than small probability.
Netflix (NFLX: $189, up 17%)
Netflix just does what it always does: Crushes expectations and the naysayers. The company delivered EPS of $0.15 just missing the consensus by a penny. But revenue of $2.8 billion was on the mark. The big story was the strength of subscriber growth and that was enough to send the stock soaring.
Netflix added 5.2 million net new subscribers in the June quarter vs. Wall Street's consensus estimate of 3.2 million. It also guided higher for the current quarter, with a forecast of 4.4 million net new subscribers, topping the consensus view for 4.0 million. This is huge subscriber growth. The company ended Q2 with 104 million subscribers worldwide, including 52 million in the U.S. and 52 million in foreign markets. Netflix's international streaming subscribers topped those in the U.S. for the first time.
Domestic net additions of 1.1 million represented the highest level of Q2 net adds since the second quarter of 2011. Better yet, Q3 guidance assumed much of this momentum will continue with the caveat that management is cognizant of the lessons of prior quarters when its over-forecasted.
The underlining fundamental story remains rock solid. With its content strategy paying off in strong member, revenue and profit growth. Management continues to believe that it is wise to continue to invest. In continued success, Netflix will deploy increased capital in content, particularly in owned originals, and, as management has said before, the business is likely to remain free cash flow negative for many years. That’s what it takes to build greatness!
The entertainment market is so broad that Netflix has now grown from zero to over 50 million streaming households in the US over the last 10 years. Netflix is growing with an expanding market, being co-pioneers of internet TV. The future is quite exciting.
BMR Take: Netflix is a premier growth story. The long term potential opportunity is quite big and we are still so early. This is one stock you just have to figure out how to own and hold onto.
The Blackstone Group (BX: $34, flat)
Blackstone delivered a decent quarter. EPS of $0.59 was just light of the $0.62 consensus. But revenue of $1.55 billion beat the $1.50 billion consensus. Total assets-under-management (AUM) was a ridiculous $370 billion. The $0.54 dividend was paid, giving the stock a dividend run-rate of 6.5%.
Management noted that it is continuing to see the benefits of its sustained large-scale capital deployment around the world, a patient focus on value creation in those investments, and then being able to choose the right moment to exit. They expect this momentum to continue. With pending realizations, including the historic sale of its European logistics portfolio, the company is on track for one of the best years for cash distributions to shareholders in its history. Wow!
In particular, the CEO said, the company’s distribution should not be viewed as one-off special dividends. They have demonstrated an ability to deliver consistently high payouts over time. Over the past three years for example, the company has distributed an average of nearly $2.50 per year, driven by over $130 billion of gains on investments.
BMR Take: EPS is running around $3.00 so the PE multiple is just over 10. The dividend yield strong and management is saying they can deliver you this dividend in the future as they have now done it now consistently for many years. We see compelling value here.
Upcoming Economic News
Existing Home Sales
Monday, July 24th, 10:00 AM
Period: June
Consensus: 5,560,000
Prior: 5,620,000
Consumer Confidence
Tuesday, July 25th, 10:00 AM
Period: July
Consensus: 116.0
Prior: 118.9
Note: The Conference Board's Consumer Confidence Survey is a monthly measure of the public's confidence in the health of the U.S. economy.
New Home Sales
Wednesday, July 26th, 10:00 AM
Period: June
Consensus: 615,000
Prior: 610,000
GDP
Friday, July 28th, 8:30 AM
Period: Q2
Consensus: +2.5%
Prior: +2.1%
Wall Street Consensus for Apple (AAPL: $150, up 1%)
Ratings Breakdown: 9 Hold Ratings, 39 Buy Ratings, No Sells
Targets
Wall Street Consensus Price Target: $16
7/22/2017 Wells Fargo $140
7/21/2017 Guggenheim $180
7/17/2017 Morgan Stanley $182
7/12/2017 Goldman Sachs Group $170
7/12/2017 Merrill Lynch $180
7/10/2017 Canaccord Genuity $180
7/9/2017 Credit Suisse Group $170
7/6/2017 Drexel Hamilton $202
BMR Take: Buy.
Wall Street Consensus for Opko Health (OPK: $6.59, up 8%)
Ratings Breakdown: 2 Hold Ratings, 6 Buy Ratings
Targets
Wall Street Consensus Price Target: $16
7/18/2017 Barrington Research $11
6/16/2017 Ladenburg Thalmann $19.50
6/12/2017 Jefferies Group $8
3/14/2017 Guggenheim $25
3/5/2017 Standpoint Research $14
1/3/2017 Laidlaw $19
BMR Take: We’re sticking with this one and are looking for a BIG upside. Look at what the brains of Wall Street think about the stock. We remain astounded that the stock has stayed down here for all this time. And the CEO and Founder just keeps buying shares.
Nutanix Insider Trading
We generally love it when insiders in a company are buying stock. Conversely, we get a little crazy when insiders are selling. Check this out about Nutanix (NTNX: $24), which had another great week, up 7%.
--- Director Jeffrey T. Parks sold 1,235,000 shares of the firm's stock in a transaction that occurred on July 14th. The stock was sold at an average price of $21.97, for a total transaction of $27,100,000.
--- Sr. VP Rajiv Mirani sold 20,000 shares of the firm's stock in a transaction that occurred on July 13th. The stock was sold at an average price of $19.63, for a total transaction of $400,000. Following the transaction, the senior vice president now directly owns 271,000 shares in the company, valued at $5,300,000. The sale was disclosed in a document filed with the Securities & Exchange Commission.
--- VP Kenneth W. Long III sold 30,000 shares of the firm's stock in a transaction that occurred on July 19th. The stock was sold at an average price of $24.00, for a total transaction of $720,000. Following the transaction, the vice president now directly owns 240,000 shares in the company, valued at $5,765,000. The sale was disclosed in a document filed with the Securities & Exchange Commission.
BMR Take: We are not happy about this. We want them to be buying the stock because as insiders, they know that the company is killing them and that the stock is going to go higher. This selling by insiders makes us very wary. We love this company and after adding the stock at $17.45 in late May, two months later we are up 36% and have high hopes for more gains. But our antennas are out do to these insider transactions and if the stock falls to the $22 level, we are out.
Amazon – A Discussion
People say Amazon (AMZN: $1,025, up 2.5%) is not making any money. The stock set a NATH this week and many see the stock peaking here, believing the stock is way over-valued since they are not making any money. We beg to differ.
The facts:
Profits the last five quarters, latest first:
$724,000,000
$749,000,000
$252,000,000
$857,000,000
$513,000,000
Revenues the past four years:
$136,000,000,000
$107,000,000,000
$89,000,000,000
$74,000,000,000
Check out this story about a new business to business website and operation in the UK and the US. This could be BIG:
http://www.businessinsider.com/interview-amazon-business-bill-burkland-017-7
A little survey on Amazon:
a) I have enough Amazon
b) I am thinking of buying more
c) I am going to buy more now
d) The stock price is too high – if they split I would buy some
e) The stock is way overvalued – their profits are too low and the PE at 190 is insanely too high.
Send your thoughts to us at Info@BullMarket.com
Home Depot, Best Buy Hit as Amazon Teams Up With Sears
Sears will sell Alexa-enabled Kenmore appliances via Amazon. But Whirlpool (WHR) and major sellers of appliances Home Depot (HD: $147, down 3%), Lowe's (LOW) and Best Buy (BBY) were hit. Home improvement chains Home Depot and Lowe's had been seen as Amazon-proof, or at least Amazon-resistant.
BMR Take: We are not ready to throw in the towel because of this one announcement, but we have to watch this development from Amazon. We added the stock to our Stocks for Success portfolio in early 2016 at $121 and are up 21%, so we don’t want to give up any of these gains. The market cap is $175 billion, they have $3.6 billion in cash supporting a sizeable debt load of $23 billion.
BMR Take: They are not going away anytime soon, but as noted above, Amazon is a monster that one needs to keep an eye on.
Google (GOOG: $973, up 2%)
July 3rd - $898. Today - $973. That’s an 8% move in three weeks.
BMR Take: Yes, they got fined big-time in Europe, but the $2.7 billion fine is peanuts to the company that has $92 billion in cash and virtually no debt, and makes over $20 billion a year. Yes, we have to watch the EU to see if there are any sanctions they will be putting on the company. But we believe the company will weather the storm and thrive. We await the break-through to NATHs of $988+ and raising our own Price Target from $1000 to $1100 or higher. Stay tuned. This just might happen sooner than you think.
Apollo Global Is Getting Ready to Take Security Firm ADT Public
Private-equity firm Apollo Global Management (APO: $28, up 2.5%) is preparing an initial public offering for ADT, just a year after it bought the home-security company.
The offering could value ADT at well over $15 billion, according to people familiar with the matter, making it one of the largest IPOs of the year. They paid $7 billion for the firm a little over a year ago. An offering would mark a quick turnaround for the private-equity firm, which began consolidating home-security providers two years ago.
BMR Take: This is just one example of the power of this firm. Apollo is way undervalued. With a 7% dividend, it's a joy waiting for a higher stock price.
The High Yield Corner
By Michael Foster
Special to The Bull Market Report
This week, we saw the AGIC Equity and Convertible Income Fund (NIE: $20) rise over 1% in the week thanks in no small part to a strong gain in the fund’s NAV. That increase was attributable to a solid week for the stocks in its portfolio, like Priceline (its second highest convertible holding) rising over 2% in the week. We’ve seen AGIC raise its equity exposure while using convertible bonds to provide a strong income stream throughout 2017, and that has resulted in two positives for investors. First, the dividend remains well-covered by investments; second, the fund has benefitted from this year’s bull market, despite how much many on the sidelines seem to hate this bull market. [That’s not us by the way. We like this bull market.]
The strong performance in the fund has helped its discount to NAV fall. This is the result of intense demand from investors for the fund, which is why the market price for the fund has risen over 11% YTD while its NAV has risen 6% over the same time period. We’re now seeing a discount of less than 10%, which is the fund’s highest since 2015. The AGIC fund has seen its discount shrink considerably from reaching a near 15% low in late 2016, which itself was an improvement from the near 20% discount at the start of 2016. This demonstrates continued interest in the fund from market participants, who see its 7.5% dividend yield as an attractive income stream, especially considering how sustainable it is.
Another Bull Market Report pick saw a similar gain this week. The Pimco Dynamic Income Fund (PDI: $30) rose nearly 1% for the week and is up 10% year-to-date. That’s not including the fund’s massive income stream, however. With an 8% yield from common dividends alone, Pimco Dynamic Income has already given an annualized return of 30%. Add in the special dividend and that number gets absolutely astronomic. This fund offered a similar return in 2016, thanks in part to its higher NAV but also thanks to investor demand. The fund has gone from a discount in 2016 to its current 7.4% premium to NAV, again indicating sustained demand for the fund from a variety of investors.
While diversified funds had a strong week, REITs were a bit less impressive. One of Bull Market Report’s top picks, Digital Realty Trust (DLR: $112), was flat for the week with little volatility. This is unusual; Digital Realty tends to bounce around a lot. But the fund has gone from a 6% yield in the past to now a 3% yield, thanks almost exclusively to its meteoric price appreciation. We’ve seen the stock jump 14% in 2017 alone, with 53% total capital gains in the last five years. It’s pretty obvious that, at this juncture, Digital Realty is no longer seen as a “high yield” risky opportunity, but is rather a low yielding REIT with long-term staying power. This makes sense; Digital Realty’s business of renting server space, is in no danger of shrinking anytime soon. This industry is also too new for us to determine whether it is cyclical or counter-cyclical. If it turns out that server space demand doesn’t go down during recessions in a cloud-computing world, then Digital Realty could quickly be perceived as one of the safest long term investments out there. For that reason, holding Digital Realty makes sense no matter what your investment profile or goals are, although the 3% yield is of course lower compared to many other REITs.
For instance, there’s Omega Healthcare Investors (OHI: $33), which also had a flat week with little volatility. Volume was much lower than average (nearly 50% of average daily shares traded). Omega has gone from a mid-8% yield to a mid-7% yield over the last couple of years, as investors have become much more aware of this stock. We’ve also seen the penny-per-quarter dividend jump continue, with dividend coverage ratios that demand respect.
There is much reason to believe this company is on solid ground, although the long-term and countercyclical sustainability of its business model (focusing on skilled nursing facilities - SNF) has been brought into question. Counterintuitively, we’ve seen an aging U.S. population be bad for SNFs for a variety of reasons. The relative wealth of aging baby boomers and the stigma associated with these facilities has made them much less popular than previous expectations. That, in turn, has put Omega and many of its peers under the spotlight, with mounting worries keeping stock prices muted (Omega is flat from a year ago and remains in the same range seen in late 2013). Five years ago and before, a lot of excitement around SNF-focused REITs drove price gains up a lot. The new perspective, and data from the industry, has kept investors more cautious.
Does this mean it’s time to sell Omega? Absolutely not. While the market is more competitive because demand is not as strong as previously expected, Omega Healthcare’s management has proven several times that they have the skill and acumen to identify and capitalize on those available opportunities in this tight market. The market, focused on the macro sentiment, has not priced in the premium that Omega Healthcare’s management should command. That makes them a buy, especially when the yield remains above 7%.
Looking ahead, investors should keep a close eye on the upcoming reports - Jobs, GDP, and Federal Reserve actions to come in late July and mid-August. This data is going to have a pretty significant impact on the future price trends for REITs and diversified funds. For now, however, The Bull Market Report’s High Yield stock picks look like solid holds, thanks to the high income stream and capital gains potential of a few of its constituents.
Good Investing,
Todd Shaver, CEO, Founder and Editor in Chief
The Bull Market Report
Since 1998
June 13, 2017
by Todd Shaver | Jun 13, 2017 | 6pm News Flash
It’s been an anxious two and a half days for all investors. Starting mid-day Friday Tech stocks sold off big time, with most down 3-4%. Netflix was down 5% Friday. Monday was a continuation of the selling and the big question was whether it would continue today. The market was up in overnight trading early this morning and the market rallied and held its gains, right to the close, closing at the highs of the day.
Tesla set a new all-time high today right after the close, at $377. Huge. The market cap is now $62 billion and is worth more than BMW. Wow. This just in – Tesla’s Model X was awarded the highest safety rating of any SUV. Tesla short sellers lost another $500 million today. Too bad. Ron Baron who manages $23 billion said today on CNBC that Tesla can go to $1000 by 2020. Wow. And he expects the company to have $70 billion in revenue and to be earning $10 billion in operating profits. By 2020, the company expects to be selling 1 million cars per year. And he loves the Solar City acquisition. Of course he has $300 million invested in the stock, so he is a bit biased. But we’ll take it.
OK, back to Tech. Most of the FAAMG stocks performed well today. Amazon was up $17 or 1.8%, Facebook was up 1.6%, Microsoft was up 1.3%, Apple +0.9% and Google up 1.1%. To say the least, we were pleased with the market today. Now we just have to get through Janet Yellen’s big interest rate announcement tomorrow.
June 11, 2017

by Todd Shaver | Jun 11, 2017 | Weekly Newsletter 7pm Sunday
To end the week, the market experienced a notable rotation out of Tech (particularly the mega-cap FAAMG* stocks) and into Financials and Energy. Recall that Tech is the market-leading sector this year (+19% YTD) while Financials and Energy have been two notable laggards relative to the S&P 500 (+4% and -13% YTD, respectively). The FAANG complex has seen some significant strength this year, though concerns have been raised about valuation, positioning extremes, and complex risk narratives. We wouldn’t worry too much about the weakness to end the week related to the sector rotation just described. The bull market is alive and well.
* Facebook, Amazon, Apple, Microsoft and Google. This moniker keeps changing. From FANG – which left out Apple, to FAANG, which had Netflix, to FAAMG. We like this the best. The market cap of these five stocks is $2.4 trillion, led by Apple at $780 billion (it was over $800 billion on Thursday). Amazon is at $470 billion, Google is at $665 billion and Facebook is sitting at $450 billion. Combined, the FAAMG stocks have added $660 billion in market value this year.
Friday was a wild day. Listen to this: the Dow was up 89 points to close at 21, 272, a new all-time high. But, the S&P was flat and the Nasdaq was hammered, down 1.8%. It was the Tech stocks, that did it. It started at about 11 AM – the sellers stepped up and sold and never quit until the close. We’re going to watch the futures as they open tonight (Sunday) at 6 PM eastern. We are hopeful things will be calm, but watch out for some fireworks Monday.
The cost to have lunch with Warren Buffett fell this year. Is that a sign of an impending bear market? Of course not – how silly people can be. Lunch went for $2,680,000, down from $3,460,000 last year. The new winner is anonymous. It’s amazing how much money he has, this Mr. Anonymous! The winner gets to bring seven friends to dine with Buffett, 86, at New York’s Smith & Wollensky Steakhouse. Proceeds benefit Glide, a San Francisco charity.
There is always a bull market here at The Bull Market Report! This week we highlight the following stocks: Apple, PayPal, Cloudera, Facebook, and Visa.
Highlights From The Past Week
Credit Card Defaults Surge Most Since Financial Crisis. In late April, after some disturbing monthly charge-off reports from major credit card vendors, per the latest data from the S&P/Experian Bankcard Default Index, as of March the default rate on US credit cards jumped to 3.3%, an increase of 13% from a year ago, and the highest default rate since 2013. The troubling deterioration prompted Moody's to warn investors about the steep increase in credit card charge-off rates in 1Q17 and 4Q16 that were the largest since 2009. The size of the jump was particularly surprising considering the ongoing strength of the US employment market.
Oil Price Drought Lingers On. With crude (and gasoline) prices doing nothing but tumble since OPEC announced that it was extending the production cutbacks, erasing all the hope-fueled bounce off cycle lows, the question once again becomes, is $50 oil still realistic? Oil prices have plunged back to levels not seen since OPEC announced its original production cut deal last November. The underlying factors for the price drop are the same as before: U.S. shale production continues to rise; inventories remain elevated; and the markets are concerned that the OPEC cuts are not doing enough to drain the surplus. But, in fact, the outlook has grown a bit darker more recently, as downside risks to the market have grown. Note that for the 21st week in a row, US rig count is up.
Household Wealth Has Never Been Higher Relative To Income. For 45 years - until roughly 1994 - the average wealth-to-income of American households had held steady around 4.9x. Then the stock bubbles started, first under Greenspan, then Bernanke, and now Yellen, and as a result, as of 1Q17 for the first time in US history, household wealth reached a point where it is over 6.6x larger than household disposable income in America. The surge in wealth, driven almost entirely by new all-time highs in the S&P, has pushed this measure of rational exuberance (think of it as the country's price-to-earnings ratio), above the housing boom peak of the mid-2000s and well above the dot-com bubble-driven highs of the late 1990s.
BMR Companies & Commentary
Apple (AAPL: $149, -4%. Note that all prices in the newsletter are for the week)
Founded in 1976 by Steve Jobs and Steve Wozniak, Apple began as a personal computer vendor. Today, Apple enjoys a more diverse portfolio with the iPhone, iPad, Mac, Apple TV, Apple Watch and iPod, combined with a growing service and software offering that includes Apple Pay, iTunes, Apple Music, CarPlay, iCloud, iBooks, the App Store and more.
Apple's quarterly results will be less important this summer as investors are focused on the iPhone 8 this fall, along with the potential for increased dividend payments, P/E multiple expansion, and new innovations as showcased at Worldwide Developers Conference this week.
On Monday, Apple's innovation engine was in full force at WWDC with a plethora of software and hardware announcements that further expanded the depth and breadth of “Planet Apple”. This included the introduction of a new product category called HomePod, combined with important augmented and virtual reality announcements.
The star of WWDC was HomePod, which Apple believes will “reinvent home music” and will be a “go to” gift this holiday season. It is designed to fight it out with Amazon’s Echo – Alexa (which we have at home and love.) The HomePod will be available just in time for the holidays. As part of the iOS 11 announcement, Apple unveiled ARKit that allows developers to create apps that will enable users to place virtual content over real-world scenes. Apple believes it will create the “largest augmented reality platform in the world” given the hundreds of millions of iPads and iPhones in the market. Also, Apple announced that virtual reality support for content creation will be coming to the Mac for the first time.
BMR Take: We can’t say it enough about this company. Apple remains among the most underappreciated stocks in the world. The stock trades at 9x this year’s consensus EPS estimate of $9, and sits there with over $255 billion of cash.
PayPal (PYPL: $54, flat)
PayPal Holdings provides a leading technology platform company that enables digital and mobile payments on behalf of consumers and merchants worldwide. PayPal’s Payments Platform offers a wide range of products, including PayPal, PayPal Credit, Venmo, Braintree, Paydiant, and Xoom.
The stock has steadily appreciated since the 1Q17 earnings announcement in April. Why? Fears about take-rate* deceleration have diminished, among other things. Qualms over the Apple Cash announcement and impending Zelle** launch have faded. Instead investors have re-focused on fundamental usage trends. We expect consistent performance in operating metrics in the quarters ahead will bolster the cause.
* take-rate is the % collected per transaction.
** Bank of America is launching a person to person payments platform called Zelle.
Instead investors have re-focused on fundamental usage trends. We expect consistent performance in operating metrics in the quarters ahead will bolster the cause.
Payments is obviously not just about the transaction. There is a lot that goes into the user interface, risk decision, merchant- and consumer-side protection and services, and easy onboarding. All these factors build platform relevance, which in turn supports ongoing robust growth.
BMR Take: We continue to view PayPal as the way to invest in the digital commerce trend. The stock is compelling, trading at 25x next year’s consensus EPS of $2.12, versus long-term EPS growth prospects of 20%. Don’t forget about the $9 billion of cash with no debt.
Cloudera (CLDR: $19.40, -15%)
Cloudera is a developer of a data management and analytics platform designed to turn data into real business value. The company's Enterprise Data Hub is a secure and flexible big data software program that offers data engineering, real-time insights for modern data-driven businesses, all within this single, easy-to-use product, enabling businesses to access untapped opportunities currently hidden within their data which allows them to gain value from both data at rest and data in motion and to explore data in deeper context.
A subscriber wrote in to us and said that it wasn’t clear that we were adding Cloudera to the portfolio. We’ll he was right. We didn’t actually say that. But we should have. So yes, we are adding Cloudera to our Special Opportunities Portfolio.
Cloudera reported a solid first quarter. We will walk through what happened Friday as the stock was down hard. We are buyers on the weakness.
The company reported strong 1QF18 results this week – its first quarter as a public company. EPS came in at -27 cents, beating consensus of -36 cents on revenue of $80 million, beating the consensus of $76 million. Sales were fueled by impressive subscription revenue growth of 60%. Moreover, the net expansion rate* remained best-in-class at 140%, cash flow from operations was a pleasant surprise at $5 million, versus consensus of -$15 million, and the company guided well for future quarters this year.
* How much sales did you have ffrom a customer this year? How much last year? 140% means your old customers are growing their revenue nearly 2.5x over how much business they did with you a year ago.
Total revenue in the quarter was $80 million, an increase of 41% from the first quarter fiscal 2017. Subscription revenue was $65 million, an increase of 60% from the year-ago period. Subscription revenue represented 81% of total revenue, up from 72% in first quarter fiscal 2017.
"We had a strong first quarter as a public company, making progress against many of our key objectives," said Tom Reilly, CEO.
Loss from operations for the quarter was $30 million, compared to a loss from operations of $37 million in the year-ago period. Operating cash flow for the quarter was +$5.0 million compared to operating cash flow of negative $24 million in the first quarter of fiscal 2017.
After brushing against the all-time high on Thursday, the stock traded down 15% Friday due to billings that came in below consensus expectations. Management does not consider billings to be an accurate proxy for its business. We note that the company was satisfied with the performance of its sales team.
BMR Take: We think management has credibility on the outlook and just can’t view the stock’s sell-off as anything other than a major over-reaction. Stepping back from the quarter details, our thesis on Cloudera remains unchanged - we like its huge top-line growth (60%), enterprise focus, subscription-based model, large addressable market opportunity, solid gross margins, and opportunities for operating leverage. The stock looks compelling now trading at 4x the 2020 consensus revenue forecast of $540 million (which is nearly double this year’s revenue target).
Facebook (FB: $149, down 3%)
Facebook is focused on building products that enable people to connect and share, through mobile devices, personal computers and other surfaces. The company's products include Facebook, Instagram, Messenger, WhatsApp and Oculus. Facebook enables people to connect, share, discover and communicate with each other on mobile devices and personal computers.
The door is open for Facebook to knock the cover off the ball in the second half of this year. We expect ad revenue growth outperformance. Let’s re-visit why.
Facebook will be able to drive long term revenue growth without a material lift in ad load volume as the rollout of Instagram, Premium Video, and Dynamic Ads* will increase the amount Facebook can charge to advertise.
* From the Facebook website: Facebook dynamic ads automatically promote products to people who have expressed interest on your website, in your app or elsewhere on the internet. Simply upload your product catalog and set up your campaign one time, and it will continue working for you — finding the right people for each product - for as long as you want, and always using up-to-date pricing and availability. [Wow. One more reason for us to love this company. And stock.]
Street models are too conservative and underestimate the long-term monetization potential of upcoming new products. So we see optionality and upward bias to estimates, which do not contemplate contributions from multiple other products including Messenger and WhatsApp.
There was a change in ad impressions and pricing growth which came in this most recent quarter at +32% on impressions and +14% on pricing (versus prior quarters' range of +50% on impressions and 6% on pricing. The company took steps to prioritize longer form video content higher up in the newsfeed. Hence, this opens the door for pricing growth to accelerate further in 2H17 when Facebook takes more deliberate steps to moderate ad load – and presumably ad impression growth.
BMR Take: We believe Facebook can continue to dominate advertising. The stock's valuation has room to the upside as it is trading at 28x the consensus EPS outlook for this year of $5.42 despite the massive long term growth prospects. EPS is expected to double by 2020. Stick around!
Visa (V: $95, -2%)
Visa is a global payments technology company that connects consumers, businesses, financial institutions, and governments in more than 200 countries and territories to fast, secure and reliable electronic payments. Visa operates one of the world’s most advanced processing networks — VisaNet — that is capable of handling more than 65,000 transaction messages a second, while offering fraud protection for consumers and assured payment for merchants.
What’s new at this blue chip? Visa recently added 13 new token service providers to broaden global access to Visa Token Service. What? Let us tell you why this is so cool and important.
Visa announced it has signed 13 new partners to participate in its token service provider (TSP) program, as the payments industry shifts from plastic to digital and broader access to new standards, such as tokenization*, are needed. With demand expected to increase for payments to be embedded into a growing number of devices, services and experiences, Visa has built out a global network of partners to offer secure, digital payment token services and ensure that regardless of form factor, an Internet-of-Things (IoT) device, appliance, wearable or beyond, can become a more secure place for commerce.
* Tokenization, when applied to data security, is the process of substituting a sensitive data element with a non-sensitive equivalent, referred to as a token, that has no extrinsic or exploitable meaning or value. In other words, when you swipe your Visa card at the Starbucks counter, your debit/credit card information gets tokenized. So if it gets stolen later on, it is just a random number and not your actual bank info.
IoT is a monster trend. Billions of devices in the next several decades are going to end up being connected to the internet. Your refrigerator. Cars. Tractors. And anything you can think of. Why not? Hence the name—Internet of Things.
By Visa getting in now with tokenization, the company will be able to process payments on all these devices. Money, money, money! The growth we see at Visa is going to continue.
Don’t just take it from just us. Jim McCarthy, executive vice president, innovation and strategic partnerships at Visa said: “A potential tidal wave of new payment accounts is approaching — conservative estimates expect 21 billion Internet-connected devices in just three more years, so having both the partner network and the right technology in place are fundamental to driving payments on those devices.”
BMR Take: Visa defines the word blue chip. Do you remember how much Visa is worth now? $220 billion. Unreal big. And getting bigger. The stock trades at 24x next year’s consensus EPS estimate of $3.94 with EPS growth running at 15-20%. And it will stay that way for a long time with the IoT mega-trend coming online in the next few years. Plenty of growth ahead for this cash machine. Speaking of cash, they have $8 billion, with $16 billion of debt. A good ratio.
Upcoming Economic News
Producer Price Index ex-Food & Energy Y/Y
Tuesday, 8:30 AM
Period: MAY
Actual: N/A
Consensus: 2.0%
Prior: 1.9%
The Producer Price Index (PPI) is for all items less food and energy, often referred to as Core PPI.
Consumer Price Index ex-Food & Energy Y/Y
Wednesday, 8:30 AM
Period: MAY
Actual: N/A
Consensus: 1.9%
Prior: 1.9%
The Consumer Price Index for all items less food and energy, often referred to as Core CPI, excludes the two most volatile components of the overall CPI.
Industrial Production M/M
Thursday, 9:15 AM
Period: MAY
Actual: N/A
Consensus: 0.20%
Prior: 0.98%
This includes data measuring output in the industrial sector, which the Federal Reserve defines as manufacturing, mining, and electric and gas utilities.
Housing Starts
Friday, 8:30 AM
Period: MAY
Actual: N/A
Consensus: 1,225,000
Prior: 1,172,000
The number of housing units started in the United States. The U.S. Census Bureau's New Residential Construction release provides statistics on the construction of new privately-owned residential structures in the United States.
Some Thoughts on Splunk (SPLK: $58, down 7%)
Growing Pains Emerge in Q1, but the Opportunity Remains. Splunk billings grew 30% YoY, beating consensus expectations by a solid 6% in FY1Q18. The Americas region showed strong execution despite a recent sales reorganization, but European execution faltered, necessitating a change in sales leadership in the region. We see Q1 more as evidence of near-term growing pains as the company puts into place a distribution channel capable of efficiently taking revenues to the $2 billion FY20 target.
Total billings of $240 million grew 30% YoY, a deceleration from 35% in Q4, but still 6% ahead of consensus. Total revenues at $242 million also sustained 30% YoY growth, despite a growing contribution from subscription based Cloud business pushing license growth down to +16% YoY in the quarter versus
35% in Q4. Splunk added 500 new customers in the quarter, in-line with the 500 added in each Q1-Q3 FY17.
FY18 Outlook Moves Modestly Higher. Despite European execution issues, management expressed confidence in the fundamental demand environment (and Splunk's ability to accrue that demand) via an increase to full year top line targets. The revenue guidance moves up modestly from $1.18 billion to $1.19 billion. Further, the company remains committed to expanded sales capacity in line with last year's increase, as the company remains capacity constrained versus opportunity constrained.
Large Deal Growth Slows. Splunk signed 360 deals over $100K in value, up 13% YoY, however this represents a deceleration vs. the 34% growth in large deals seen thru FY17 and 33% growth in Q4. The company saw 80% of business derived from existing customers in the quarter. We don’t really think getting 80% of its revenue from existing clients is a bad thing. In fact, that means 20% came from new business. We’ll buy that logic.
Q2 Guidance Brackets Consensus, FY18 Top Line Guidance Moves Higher. Management is looking for 2Q18 revenue of $268 million and operating margins of 4%.
BMR Take: We like this company; we like the numbers they are doing; we are long term investors at this price level.
SNAP (SNAP: $18.08, down 14%)
Snap, owner of Snapchat, had a rough week. We don’t like this one here at The Bull Market Report and we want to make you aware of why. We just think they are losing too much money and their user numbers are slowing. They are the most shorted Tech IPO out there, with a 28% short interest. Now some, including us, say that a large short position is bullish. Well, yes and no. It is bullish because those shares have to be bought back at some point. But it is bearish because many of the smartest minds on Wall St. think it is going lower. We’re in the latter camp this time.
Some negatives –
User growth is slowing.
Citigroup downgraded the stock.
CEO Evan Spiegel got a $750 million bonus for taking Snap public.
They lost $200 million in the 1st quarter of 2017. That’s a lot of dough.
BMR Take: Some say this is the next Facebook, so that’s the positive angle and this cannot be discounted – there is a lot of money riding on this company succeeding. We just don’t want to be playing this game at this time. A year or two from now? Maybe. We’re happy to watch and wait patiently on the sidelines.
Apple Corner
There was a rumor that the new Apple 8 can’t handle the new, faster data speeds that are coming down the pike. Well, let us say this. First of all, Apple doesn’t comment on new products that haven’t been announced, so there is no way we can know if this is true. Secondly, the new data speeds of the internet are years away. And guess what? Apple will have new software to handle the bigger speeds, AND they will have the Apple 9 out by then. So we say: Bunk.
Apple (AAPL: $149) had a bad day Friday, down $6 from $155, and after flirting with its all-time high of $156.65, set May 15th. We’re really not too concerned about this one-day, 3% drop. Nothing has changed really – just the perception that the Tech stocks can go down from time to time. But we already knew that. Stocks are inherently risky, but we’d rather take the risk of owning an Apple, as we are up 54% from the date we added it 16 months ago. And all the while the 10-year Treasury note is paying a little over 2% a year. Take your pick.
Tesla (TSLA: $357) Update
Pacific Crest, a Wall Street research firm, put a new price target on Tesla of $439. Wahoo! The stock hit an all-time high Friday of $377 and then got hammered down to $357, finishing the week up $17 or 5%. Our Target was $350 which we raised just a week or two ago. We actually think the stock can go a lot higher, as the future of the company is ahead of it, especially as they get closer to delivering cars in massive quantities later this year and next. But what if what happened Friday is indeed the beginning of the end for Tech stocks, including Tesla?
BMR Take: Let’s do this. If the stock gets hammered Monday and Tuesday and falls below $350, let’s get out, take a breather and watch what happens. After all, having added the stock at $199 17 months ago, we have had quite a run, now up 80%. We wouldn’t want to give up these gains.
The High Yield Corner
By Michael Foster
Before we start talking about high yield, we want to talk about oil.
Oil futures have not been doing well. If you’re a futures trader, you’re probably laughing at the absurd understatement of that sentence. Crude oil futures slumped 4% this week after the steep drop on Wednesday, bringing it closer to its 52-week low of $44, which it reached in early May during another moment of energy volatility. Oil is now down about 20% year-to-date, leading to the somewhat rational question of whether 2017 proves to be the worst year for the commodity since the blood bath of 2014.
With oil prices tumbling, everyone is affected. Of course, the effect is quite different depending on where you are in the market and who your customer base is. The classic argument is that low oil is good for consumer discretionary stocks. If Americans are spending less at the pump, so the theory goes, they’ll have more money to spend buying all kinds of stuff they normally wouldn’t buy.
Simple theory. It sounds logical enough to be compelling, although it’s very wrong. The problem with the theory is that it doesn’t take into account things like income growth, ex-energy CPI trends, and labor participation rates. The macroeconomics are quite different now, so consumer discretionary may not be as unaffected by cheaper oil than in 2014, but the Consumer Discretionary SPDR (XLY: $91) is already up 12% for 2017, so it may be too late to play oil’s weakness this way—especially since other macroeconomic factors make the correlation not so 1-to-1.
Likewise, other sectors and entire asset classes get impacted by changes in oil. High yield is one of them. Back in 2014, high yield assets were hit pretty hard with the fall in oil; when oil prices got even worse in 2015, high yield assets were hit yet again. To make matters worse, the Federal Reserve was hinting at raising interest rates, which itself tends to be bad for high yield. All of this meant high yield funds like the SPDR High Yield Bond Fund (JNK: $37) had an awful run, and high yield was being rejected as an asset class by the broader market.
Now that oil is repeating its 2014-2015 decline and consumer discretionary is repeating its 2014 run-up, you would expect high yield to also repeat its historical weakness and be at best on the decline and at worst in a full-on bearish downtrend. But the SPDR fund and most high yield bond funds are up healthily for 2017. The SPDR fund is up 2% so far excluding its near 6% yield, and The Bull Market Report pick Pimco Dynamic Income Fund (PDI: $30) is up 8% for the year excluding its near 9% dividend (which doesn’t exclude special dividends, which last year brought the yield up to a whopping 14%). From the start of 2016, the Pimco fund is up over 9% excluding the $5.19 in dividend payouts since then (giving the fund a 19% total return over the period, well above the S&P’s 15% return over the same period).
That leads to the question of whether it’s time to sell, since you’d expect cheap oil and rising interest rates to be significant problems for bonds. Remember the Fed is widely expected to raise rates this week. Cheaper oil will cause poor performing energy companies to be insolvent and default on loans; higher interest rates will make it harder for existing firms to pay back their loans while also lowering the price in the market for corporate bonds. All of this is really, really bad for junk bond funds.
Again: So the simple theory goes. In reality many of these problems have been priced into junk bonds for a long time. The low and depressed prices of junk bonds in 2014-2015 helped create the bull market from 2016 to today. But it goes back even further than that. If you look at the SPDR High Yield fund’s price return from 2013 to 2015, you’ll see that every year saw the fund’s net asset value go down due to lower and lower demand for risky corporate bonds. Junk was really acting like junk.
Go back even further, and you’ll see that junk bonds stayed pretty much at the same price range from the end of 2009 to early 2015, which is actually 8% lower than today’s current price for high yield corporate bonds.
High yield debt isn’t supposed to act this way. These debts are supposed to go up in price during times of economic growth and go down very sharply in times of economic weakness and/or recession. But the U.S. since 2012 has been in a state of admittedly slow but steady improvement. Corporate bonds should be attracting more capital, not less.
Finally, starting last year, this began to happen in a noticeable way. But the bonds are still not priced where they should be relative to the business cycle. This means high yield bonds still have room to go up in value.
This isn’t just true of corporate bonds. In fact, something very similar has been happening to municipal bonds and REITs, which is why we have been aggressively recommending them for a long time. Sadly, there isn’t enough room this week to go into the details of why these asset classes are also well-positioned in this odd business cycle. But next week we’ll take a closer look at why both of these, like junk bonds, are deeply underappreciated in today’s market.
Good Investing,
Todd Shaver
Editor, Founder and CEO
The Bull Market Report
Since 1998
Disclosure: The Bull Market Report is a compilation of original writings, news from publicly available sources, and third-party research. The subscriber agreement acknowledges that The Bull Market Report is an information source to give you the background to invest in the stock market.
May 15, 2017

by Todd Shaver | May 15, 2017 | Monthly Newsletter Daily 12pm if new
The Week Ahead
“President Fires FBI Director” was the headline of the week. Think of it. When was the last time you can recall the head of the FBI getting fired? What does this mean about the stability of the FBI (one of our most important institutions)? What does this mean about President’s Trump future in Washington DC? Democrats are not letting this one go. Democrats are now openly discussing impeaching Trump. Who knows what will happen. But one thing is for sure, uncertainty is at a high in terms of geopolitical risks. So far, the Bull Market doesn’t seem to mind. We hope that continues to be the case.
There is always a bull market here at The Bull Market Report! This week we highlight the following securities: Amazon, Netflix, Tesla, PayPal and Apple.
Highlights From The Past Week
Earnings season is off to a good start. Over 90% of the companies in the S&P 500 have now reported results for Q1. The blended Q1 S&P 500 EPS growth rate is 14%, better than the 9% expected at the end of the quarter. It also represents the strongest growth since the 17% in Q3 2011. We note favorable top-line trends and recognition of improving sentiment and growth expectations is prevalent on Q1 earnings calls. However, not all managers have seen it translate to higher demand. CEOs expressed hope for widespread deregulation and improved regulatory clarity, but uncertainty remains high. The US economy is at full employment and wage growth is accelerating. Rising labor costs as a headwind to profit margins.
Watchful eye on the Retail sector. Headline retail sales increased 0.4% year over year in April following an upwardly revised 0.1% increase in March (originally -0.2%). However, consensus was for a 0.6% increase. Sales at both general merchandise stores and clothing and clothing accessories stores were down 0.5%. However, it was not all bad. Nine of the 13 categories in fact posted sequential increases. The non-store category (Internet) was a standout, increasing 1.4%. All in all, we are concerned about the Retail sector and need to be mindful of what it means to the broader economy. Case and point, this week we saw Macy’s (M: $24, down 19%) crater on a worse than expected update to its financial outlook. Many are now calling for large scale bankruptcies.
Financials and Industrials lag; Utilities and Tech higher. This week Industrials were the worst performer. The weakness was fairly broad based with GE (GE: $28, down 3%) causing much of the drag. Energy and Construction and Machinery also saw outsized pullbacks. Financials also underperformed. The lower rate backdrop is an easy excuse for bank sluggishness. Regional banks fared much worst that the large money center banks. Life insurers and online brokers also were notable decliners. Pharma found a big rally following upbeat trial data for lung cancer treatment for an industry bellwether. Though hospitals were laggards. Tech outperformed as FAANG stocks are up $250 billion in market cap for the year with the rest of the S&P 500 down $250 billion (so the equity market is essentially down excluding FAANG).
BMR Companies and Commentary
Amazon (AMZN: $962, +3%)
Our dear beloved Amazon. Another week has come and gone. What new world-changing breakthrough do you have for us? Space exploration trips? No, not yet. Home furniture? Alrighty then!
Amazon now wants to furnish your home. The online retail giant is making a major push into furniture and appliances, including building at least four massive warehouses focused on fulfilling and delivering bulky items. With that move, the Seattle-based retailer is taking on the two companies that dominate online furniture sales -- Wayfair and Pottery Barn owner Williams-Sonoma. Furniture is one of the fastest-growing segments of U.S. online Retail, growing 18% in 2015, second only to Groceries. About 15% of the $70 billion U.S. furniture market has moved online.
But even the biggest players in online furniture are struggling to get the market right. Unlike established categories such as books and music or even apparel, retailers are still hammering out basic concepts like how much variety to offer on their sites and the most efficient ways to deliver couches and dining sets to customers' homes.
While Amazon has been selling furniture for years, it has lately decided to tackle the sector more forcefully. Furniture is one of the fastest-growing retail categories at Amazon. The company is expanding its selection of products, with offerings including Ashley Furniture sofas and Jonathan Adler home décor, and it is adding custom-furniture design services. Amazon is also speeding up delivery to one or two days in some cities.
While Amazon has disrupted industries from publishing to fashion with free, fast shipping and easy, one-click buying, furniture can be a tough sector to crack. For one, it is expensive to deliver a couch and other big items, and consumers typically want what are known as "white glove" services, extras like bringing it into the home, setting it up and removing trash. And while packing more small packages onto a delivery van brings the costs down because it can make more stops, you can only fit so many pieces of furniture onto a truck.
Shoppers are still generally willing to pay for furniture delivery, but some retailers and logistics companies say they are facing growing pressure to ship online orders faster. Wayfair offers free shipping on orders over $49, but delivery times can range up to two weeks and longer. Pottery Barn charges on a sliding scale based on price, with delivery costs running above $100 for more expensive items. Furniture sold and shipped directly by Amazon is free for Prime members, while items sold by third-party sellers may cost extra.
To guarantee two-day shipping to 99% of consumers, a retailer or logistics company needs up to a dozen large warehouses spread around the country, plus around 110 smaller facilities to stage deliveries to customers' homes. Amazon is expected to rely on other third-party providers to manage distribution centers and handle delivery of furniture and appliances for the near future, even as it takes more of its logistics in house in other parts of its business. Rising sales may help reduce delivery costs by creating better density. Costs go up for transportation companies as deliveries get more spread out and infrequent.
BMR Take: We see Amazon winning this business opportunity, as they normally do.
Total sales growth is projected to run greater than 20% for several years from the current level of $165 billion predicted this year (up from $135 billion last year.) What an extraordinary growth story Amazon is. What a great ride this stock has and will continue to be. If the company can reach the $30 of EPS analysts project by 2020, this stock easily goes much. Much higher.
Note: See more on Amazon below in “The Death of Retail?”
Netflix (NFLX: $161, +3%)
Netflix announced 400 new jobs in Europe and two new European original series. The expanding workforce complements $1.75 billion of investment in European content, with at least six new Netflix European original projects to be announced in 2017. Netflix is now taking over Europe!
The creation of 400 jobs is happening at its new European customer service hub, which opened this week in Amsterdam. The customer service center will support customers across 11 European countries (Belgium, Denmark, Finland, Ireland, Luxembourg, the Netherlands, Norway, Poland, Romania, Sweden and the UK). The multilingual hub will employ initially a workforce of 170, growing to 400 by the end of 2018.
Amsterdam is the location also of Netflix’s recently expanded European, Middle East and Africa headquarters, which has doubled its workforce since the beginning of 2016. More than 120 employees from 18 countries work at the HQ in business development, marketing, PR, public policy and corporate functions such as finance, legal and recruiting.
The ongoing expansion of Netflix’s workforce in Europe complements the company’s ever-growing investment in European productions (licensed, original and co-productions). The company confirmed plans to announce at least six new European original projects before the end of 2017. Netflix has committed more than $1.75 billion to European productions since entering Europe in 2012, including more than 90 original productions in various stages of development.
BMR Take: We are delighted to see the creation of jobs in Europe and the opening of a new customer service hub in Amsterdam, as well as two new European original series. Moving outside the US, Europe is a great market for Netflix to tap in to to make money longer term. We think Netflix is on track to meet or exceed analyst estimates for $10 of EPS in 2020, meaning the stock can not only grow into the current valuation, but likely head much higher. Our Target is $165. We can’t wait to raise it soon. We do hereby raise the Sell Price from $125 to $145.
Tesla (TSLA: $325, +5%)
Elon Musk has discovered a new passion in life — and it could be Tesla's best product yet. Tesla CEO Elon is the best car salesman in history. And as CEO of SpaceX, he's declared his intention to retire on Mars. But electric vehicles and low-Earth orbits might not hold a candle to what Musk ultimately ends up doing in the roofing business.
Against all odds, Musk has become the biggest booster in the history of the roofing business, thanks to a new Tesla product, the Solar Roof, that officially went on sale last week. It's the first post-Solar City-acquisition product that Tesla is selling, and it sounds as if it's been occupying at least as much of Musk's attention as the forthcoming launch of Tesla's Model 3 car.
Musk has always been big on solar power. Prior to Tesla buying SolarCity for over $2 billion, Musk was the company's Chairman (his cousin was the CEO). He likes to point out that humanity has a compelling alternative to fossil-fuel energy: the giant fusion reactor in the sky that bathes the planet every day with free power. Solar also fits into his master plan, which involves eliminating greenhouse-gas emissions by electrifying transportation; backing up the biosphere with SpaceX, which would make humanity a multi-planetary species; and powering it all with solar energy.
SolarCity has long been able to sell or lease a homeowner solar panels, but the Solar Roof offers a different value proposition. If you have to replace your roof anyway, why not replace it with a roof that generates power and saves you money over the long haul? With a 30-year-mortgage if you stay in the house, you'll replace your roof at least once. At a cost of about $10,000, you maintain the value of the home, but you don't necessarily add much to it. The Solar Roof should last twice as long as a traditional roof (and maybe much longer) and it will both mitigate your electricity costs and, paired with a Tesla Powerpack battery, provide you with backup energy. The up-front costs are high, but the overall economics are compelling. And in sunny states where electricity is costly, such as California, a Solar Roof could net a homeowner tens of thousands of dollars over 30 years.
BMR Take: Solar is the future of energy. Elon Musk and Tesla are already finding opportunities to tap into the trend. Solar roofs have a very bright future and can be a key driver of EPS for Tesla. Analysts currently project EPS to flip from a loss of $5.15 this year to over $11 in 2020. This stock has great potential. The stock set new all-time highs last week, defying the bears. Let’s put it this way – the shorts are getting killed.
PayPal (PYPL: $49, +3%)
The PayPal network effect is working like charm. Investors in PayPal had plenty of reason to cheer last week when the company reported earnings. Nearly every metric was up by a better-than-expected percentage, surpassing expectations of all but the most bullish on the company.
More exciting to long-term investors, however, was the account growth and increase in user engagement with the company's core platform. Six million active accounts were added during the quarter, increasing the total to 203 million for the digital payments company. These active accounts now average almost 32 transactions per year, a 12% increase year over year. More customers using the company's platforms more often was a winning combination that the market liked.
PayPal's growth is beginning to fuel a powerful network effect opening a new window for the company. The beauty of this type of growth is that it drives itself. The more users that sign up for the platform the more important the service becomes for retailers to adopt it and the more places that accept it, the more attractive it becomes to new users. Get it?
At the end of March, 16 million retailers were accepting PayPal's core platform as a method of payment. Management is well aware of this virtuous cycle. During the conference call, CEO Dan Schulman stated: “Our powerful two-sided network engages both consumers and merchants, and the larger our scale, the stronger our network effect becomes. We made meaningful progress in advancing merchant adoption of PayPal in the quarter. At the end of March, the number of active merchant accounts on our platform increased to 16 million. The size of our merchant base is a formidable competitive advantage and is extraordinarily difficult for others to replicate.”
BMR Take: We think PayPal is in the middle of a decade-plus growth cycle that will deliver real value for shareholders. Stick around. They are already closing in on $3 of EPS.
Apple (AAPL: $156, +5%)
Apple chose Corning as the recipient of the first investment from its Advanced Manufacturing Fund, giving $200 million to the maker of glass used in iPhone and iPad screens. Corning, a longtime Apple partner, will use the cash on equipment and glass-processing technology mainly at its Kentucky facility that developed the protective Gorilla Glass used on smartphones. Some of the money will also go toward research and development costs. Corning’s partnership with Apple started 10 years ago with the first iPhone.
Apple Chief Executive Officer Tim Cook said in May that the company planned to invest at least $1 billion to back advanced manufacturing companies in the U.S. and help create jobs in the industry. President Donald Trump has been a vocal critic of American companies -- and Apple in particular -- that outsource production to non-U.S. manufacturers. Apple said it now supports 2 million jobs in the U.S. and that the Corning relationship has helped create about 1,000.
The investment is also a good-will gesture toward Republicans, including President Trump, who has criticized Apple for building its iPhones in China, and the Senate majority leader, Mitch McConnell, who represents Kentucky. Apple said it spent $50 billion last year with American suppliers, although it manufactures just one product line, the Mac Pro, in the United States.
Last month, Mr. Trump sketched out a plan to slash overall corporate tax rates and offer companies a special break for bringing back profits held overseas. Apple has accumulated more cash than any other company in the United States — $260 billion now - and virtually all of it is stashed untaxed in foreign bank accounts. Cook, has repeatedly complained that taxes in the United States are too high and has vowed not to bring the cash home until taxes are cut. The Corning investment is a nice gesture for Apple to show the US government that it is a good US citizen.
BMR Take: EPS are on track to be near $9 this year and grow to $10-11 in the years ahead. The Corning investment and improving government relations is reassuring for us to see. Apple remains a favorite for us. We’re up 66% on our investment since we added the stock early last year. Not bad for the largest a company with the largest market cap in the world, now $814 billion. Our Target is $155, which it has just eclipsed. Yes!!!!!!!
We’ve been waiting to say this: WE HEREBY RAISE THE TARGET PRICE ON APPLE TO $170. The Sell Price is “We would not sell Apple” and we no reason to change this. Good investing out there!
Economic Outlook for the Coming Week
Monday, May 15, 2017 10:00 AM ET
NAHB Housing Market Index SA
Period: MAY
Actual: N/A
Consensus: 68.5
Prior: 68.0
The NAHB/Wells Fargo Housing Market Index is derived from a monthly survey of builders conducted by NAHB . Home builders are asked to rate current sales of single-family homes, and prospects for sales activity in the next six months, as "good," "fair" or "poor." They are also asked to rate traffic of prospective buyers as "high to very high," "average" or "low to very low." Scores for each component are then used to calculate a seasonally adjusted index where any number over 50 indicates that more builders view sales conditions as good than poor. 68.5 is a pretty strong indication of future growth.
Tuesday, May 16, 2017 8:30 AM
Housing Starts SAAR
Period: APR
Actual: N/A
Consensus: 1,263K
Prior: 1,215K
The number of housing units started in the United States. The U.S. Census Bureau's New Residential Construction release provides statistics on the construction of new privately-owned residential structures in the United States. The data relate to new housing units intended for occupancy and maintained by the occupants. They exclude hotels, motels, and group residential structures such as nursing homes and college dormitories. Also excluded are "HUD-code" manufactured (mobile) home units.
Thursday, May 18, 2017 8:30 AM
Initial Unemployment Insurance Claims
Period: 05/13
Actual: N/A
Consensus: 240K
Prior: 236.0K
Weekly data on initial claims for unemployment insurance under state programs. The U.S. Department of Labor's Employment and Training Administration collects weekly data on new and continued claims for unemployment insurance benefits under state programs.
Thursday, May 18, 2017 10:00 AM
Period: APR
Actual: N/A
Consensus: 0.30%
Prior: 0.40%
Leading indicators are economic series that tend to change direction ahead of shifts in the business cycle. There are 10 components of the U.S. Leading Composite Indicator published by The Conference Board. The index is constructed by averaging the individual components in order to smooth out a good part of the volatility of the individual series. Historically, the cyclical turning points in the leading index have occurred before those in aggregate economic activity.
Second Quarter Earnings Reports
About 50% of firms have beaten earnings forecasts, above the long-term average of 46%, according to Goldman Sachs. Further, 40% of companies have exceeded revenue estimates, the most positive ratio of surprises in almost six years.
The VIX (^VIX: 10.40)
The lack of concern amongst US equity investors can be seen in the CBOE Volatility Index, the VIX, a 30-day barometer of investor nervousness calculated using S&P 500 options. The so-called fear gauge on fell on Tuesday to the lowest on record, at 9.67, according to data compiled by Bloomberg, before rallying to close at 10.40.
BMR Take: Low volatility is a sign of bullishness. In times of panic when the market is falling day after day, the Vix is usually in the 20s and sometimes in the 30s. In 2008 when the world was caving in financially, the Vix reached the 60s at the worst of the financial crisis and even spiked into the 90s. The historical average is about 15-16, so at 10 we are in very calm, uncharted territories. Because of this ultra-low volatility level some people say: LOOK OUT; watch for something to happen. We’re not like that. If this market can handle this last week of Trumponomics, then it can handle anything.

c/o Business Insider
The Death of Retail?
Warren Buffett just proclaimed the death of Retail as we know it. In an article in Business Insider he says the future of the retail department store is online. This is not rocket science to us, but to hear Warren say these things holds a lot of weight in our book. Berkshire Hathaway fired a warning signal for the retail industry in February when it sold off $900 million of Walmart stock, choosing instead to invest billions in airlines.
In the age of Amazon, "I think retailing is just too tough for me, generally," Buffett said. "We bought a department store in 1966, and I got my head handed to me. I've been in various things in Retailing. ... I bought Tesco over in the UK and got my head handed to me. Retailing is very tough, and I think the online thing is hard to figure out."
Brick-and-mortar retailers have announced more than 3,200 store closures so far this year, and Credit Suisse expects that number to increase to more than 8,600 before the end of the year. For comparison, 6,200 stores shut down in 2008, the worst year for closures on record. Department stores like Macy's, Sears, and J. C. Penney have been hit the hardest by these trends - since 2001, department stores have lost half a million jobs.
BMR Take: In March we thought about buying Simon Property Group (SPG: $157, down from $186 in February), but we changed our minds quickly. Instead, we would buy Amazon now. The stock closed at $962 Friday, up $27 or 3% last week. Yikes – 10-year bonds pay less than 3% PER YEAR.
Please DON’T WORRY ABOUT THE HIGH STOCK PRICE – pretend it is trading for 1/10 or $93 a share. Buy 11 shares, or 32 shares, or 100 shares – but buy some Amazon. We can see $1000 a share soon; then $1100; then $1200. This one might hit $2000 sometime next year.
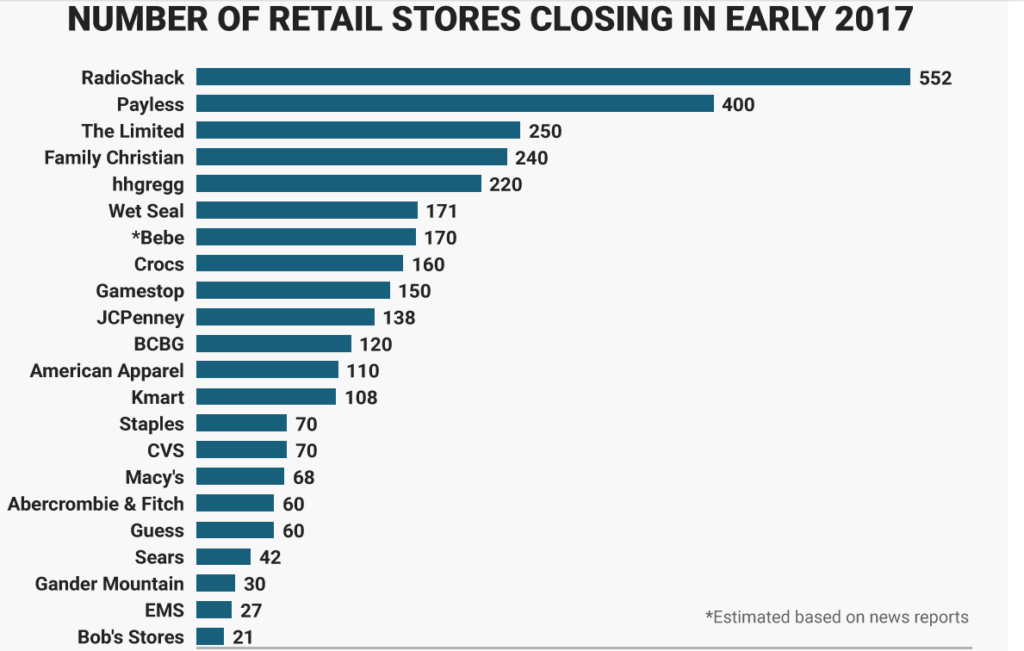
c/o Business Insider
Snap Posts $2.2 Billion Loss in First Quarterly Report
Snap (SNAP: $19.14, down 17%) reported a $2.2 billion loss Wednesday, in its first quarter as a publicly traded company, much deeper than the $105 million loss it posted a year ago, hurt by a one-time hit from IPO-related compensation expenses totaling $2 billion. The loss is one of the biggest in American corporate history. Snap had revenues of $150 million which more than quadrupled from the year-ago quarter but missed the consensus estimate of $158 million. Losses more than doubled to $188 million. We always find it strange for a company to lose more money than it actually took in in revenues.
Daily active users rose 36% to 166 million from the year-ago quarter, but the average revenue per user fell, while daily active user growth also disappointed.
Snap went public at $17 in March and reached $27 the second day of trading. We’ve been saying since the IPO that the company is overvalued. This earnings report goes a long way to backing us up on that.
Tesla Starts Taking Orders for its Rooftop Solar Tiles
Tesla has begun taking $1,000 deposits for its remarkable solar roof tiles at a lower price point than most folks expected. The company said it will begin with production of two of the four styles it unveiled in October: a smooth glass and a textured glass tile. They say that roofing a 2,000 square-foot home with 40% coverage of active solar tiles and battery backup for night-time use would cost about $50,000 after federal tax credits and generate $64,000 in energy over 30 years. That’s more expensive upfront than a typical roof, but less expensive than a typical roof with traditional solar and back-up batteries. The warranty is for the lifetime of your home.
They are obviously going after the wealthier clientele to start. Then again, so does Apple. And so do most companies. The cost for active solar tiles is about $42 per square foot, whereas normal roof tiles cost about $11 per foot. Tesla will manage the entire process of solar roof installation, including removal of existing roofs, design, permits, installation and maintenance. The company estimates that installation will take about a week.
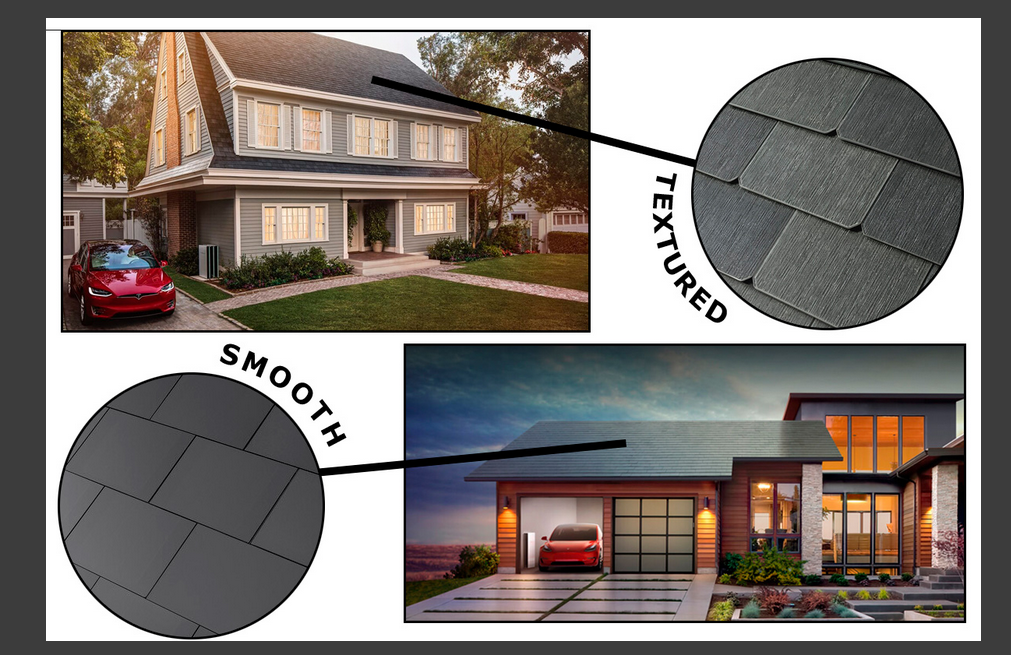
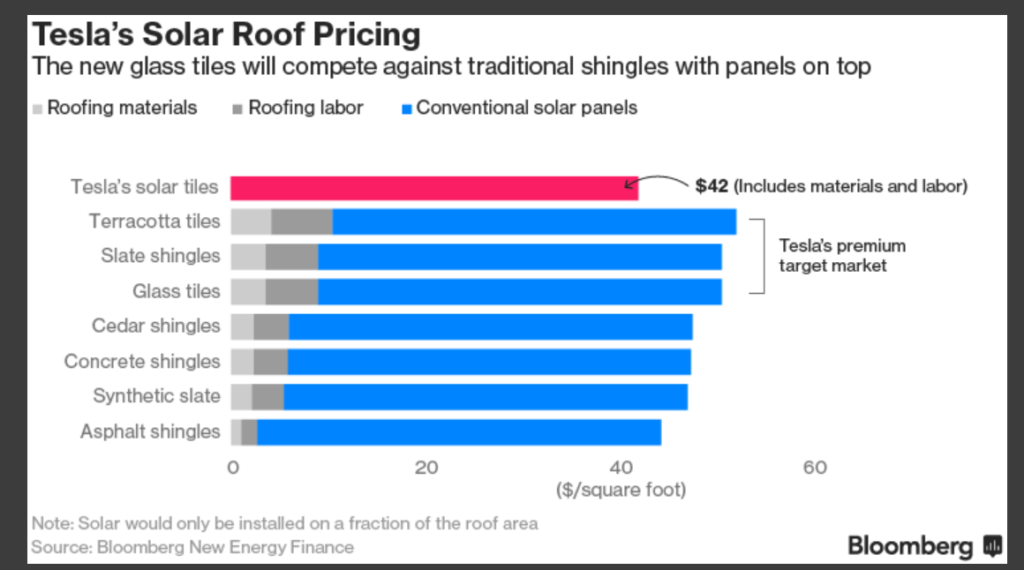
High Yield Report
The High Yield Corner
By Michael Foster
The biggest news of the week for The Bull Market Report’s High Yield portfolio came from AstraZeneca (AZN: $34), which jumped 9% thanks to positive results from a phase 3 study of its Imfinzi drug, a non-small cell lung cancer treatment. The FDA has already approved the drug for bladder cancer treatment, but of course lung cancer is a much bigger and more serious disease, so this is significant news for the company.
The stock had been struggling for nearly a year, falling precipitously both before and after the election. Before the election, fears that Clinton would gut pharma profits caused a big selloff, but that selling pressure increased tremendously following Trump’s election and the surprising news that Trump had little sympathy for pharma either, and he was going to take a scalpel to their profit margins as well. Things hit a low at the beginning of 2017, but recent political scandals and attention elsewhere, as well as the perhaps not too shocking news that Trump is finding it difficult to repeal the Affordable Care Act, have helped pharma companies revert back to a pre-election equilibrium.
Where does that leave us now? Clearly the market has taken its eye off the pipeline ball for a long time, and one has to wonder if the recent news on Imfinzi may in fact force some greater discipline on the market and make investors realize that a sub-30 P/E ratio on a company with many life-saving drugs in various stages of regulatory approval is perhaps unfair. Credit Suisse recently upgraded the stock for that very reason, and we expect more upgrades to come in coming weeks. We’re still 3% off the 52-week high, so there’s no reason to think the sudden buying pressure on Friday is a one-off.
In the more conventional world of ultra-high yield, we’re seeing a continuation of the BDC selloff and junk bond complacency that we have written about for several weeks now. BDC earnings results continue to come in, and for the most part things do not look good. The UBS BDC ETF (BDCS: $22, down 3%) was pummeled by a mix of falling NAVs at constituent firms and analyst downgrades. The downgrades partly come from the aforementioned weakness in NAV, but portfolio yields are also deteriorating at many BDCs. What is portfolio yield? Remember, a BDC is a collection of loans to small and medium-sized businesses. The BDC gets a coupon from each loan, which is the BDC’s yield per loan. Average those together and you get the BDC portfolio yield.
Here’s the real problem: those yields have been going down for a decade. That’s made investing in BDCs particularly tricky, and has caused the BDCs themselves to do a lot of things (lower fees, issue more stock, take on greater risk) to keep investors happy. But all that was supposed to stop when the Fed started raising interest rates, which would cause rates to rise everywhere else. And that is indeed happening elsewhere in the Financial world. Margin rates, preferred note rates, corporate debt rates, and even municipal bond rates have been inching up in anticipation of the Fed’s rate hikes. BDC rates have been on an almost constant slide downward - but the interest rates they need to pay for debt-based capital is going up. So BDCs’ cost of capital is broadly rising and their portfolio yields are going down, compressing margins.
This is a mess. Why is this happening? As far as we can tell, it’s a result of supply and demand. The supply of capital looking for yields has just grown and grown; there are more investors looking to lend to small and medium-sized businesses, thus competing with BDCs. Newer BDCs are showing up. Leveraged lending firms are competing with BDCs. Regional banks are getting back into the small business lending business too. All of this is a structural headwind to BDCs, as they face more competition and thus have to take on more risk or lower the rates they offer on loans. That’s a horrible place to be in, and is why we remain cautious on BDCs as a general rule.
So it’s not surprising that BDCs are down 3%, and we expect that to continue. At the same time, however, there is incredible calm in the junk bond market. The SPDR Barclays High Yield Bond ETF (JNK: $37, flat) barely shrugged this week thanks to little news of significance and a continuation of the declining bankruptcy trend that we’ve seen since early 2016. Again, this is a strong reminder that markets should be forward-looking. Bankruptcy rates were rising in 2015-2016, and junk bond funds were collapsing at the same time. But in early 2016 the bankruptcy problem largely came to a stop, partly thanks to a recovery in oil and partly thanks to the wave of bankruptcies already shaking out most of the weak hands. Yet investors were very slow to realize and jump in.
Now that oil is getting weaker again, one has to wonder if junk bonds are getting ready to peak and a new wave of defaults may be upon us. For sure, that is a possibility but few signs indicate that we will see a repeat of 2015-2016. Instead, we could see a lot of investors anticipate a repeat that never happens, resulting in a mini-correction that provides a buying opportunity.
This means right now is a good time to stick to well-yielding junk bond and high yield bond funds. The Bull Market Report portfolio includes the PIMCO Dynamic Income Fund (PDI: $29, down 1%) and the AGIC Equity and Convertible Income Fund (NIE: $20, down 1%). Admittedly, the discount to NAV on either fund is not particularly compelling right now, but the portfolio quality and historical track record are so good that investors are wise to hold onto these stocks if you have them. New purchases in new bond funds may be something worth considering in the future. More of that in future issues of The Bull Market Report.
Good Investing,
Todd Shaver, Founder, CEO and Editor
The Bull Market Report
www.BullMarket.com
Please consider subscribing to the Weekly Bull Market Report with all of our super research, as well as News Flashes during the week. We are just trying to help you find those stocks that will help you increase your wealth!
Go here: www.BullMarket.com/subscription
Thanks and Good Investing!