The Week Ahead
“President Fires FBI Director” was the headline of the week. Think of it. When was the last time you can recall the head of the FBI getting fired? What does this mean about the stability of the FBI (one of our most important institutions)? What does this mean about President’s Trump future in Washington DC? Democrats are not letting this one go. Democrats are now openly discussing impeaching Trump. Who knows what will happen. But one thing is for sure, uncertainty is at a high in terms of geopolitical risks. So far, the Bull Market doesn’t seem to mind. We hope that continues to be the case.
There is always a bull market here at The Bull Market Report! This week we highlight the following securities: Square, Amazon, Splunk, Netflix, Tesla, and Apple.

Highlights From The Past Week
Earnings season is off to a good start. Over 90% of the companies in the S&P 500 have now reported results for Q1. The blended Q1 S&P 500 EPS growth rate is 14%, better than the 9% expected at the end of the quarter. It also represents the strongest growth since the 17% in Q3 2011. We note favorable top-line trends and recognition of improving sentiment and growth expectations is prevalent on Q1 earnings calls. However, not all managers have seen it translate to higher demand. CEOs expressed hope for widespread deregulation and improved regulatory clarity, but uncertainty remains high. The US economy is at full employment and wage growth is accelerating. Rising labor costs as a headwind to profit margins.
Watchful eye on the Retail sector. Headline retail sales increased 0.4% year over year in April following an upwardly revised 0.1% increase in March (originally -0.2%). However, consensus was for a 0.6% increase. Sales at both general merchandise stores and clothing and clothing accessories stores were down 0.5%. However, it was not all bad. Nine of the 13 categories in fact posted sequential increases. The non-store category (Internet) was a standout, increasing 1.4%. All in all, we are concerned about the Retail sector and need to be mindful of what it means to the broader economy. Case and point, this week we saw Macy’s (M: $24, down 19%) crater on a worse than expected update to its financial outlook. Many are now calling for large scale bankruptcies.
Financials and Industrials lag; Utilities and Tech higher. This week Industrials were the worst performer. The weakness was fairly broad based with GE (GE: $28, down 3%) causing much of the drag. Energy and Construction and Machinery also saw outsized pullbacks. Financials also underperformed. The lower rate backdrop is an easy excuse for bank sluggishness. Regional banks fared much worst that the large money center banks. Life insurers and online brokers also were notable decliners. Pharma found a big rally following upbeat trial data for lung cancer treatment for an industry bellwether. Though hospitals were laggards. Tech outperformed as FAANG stocks are up $250 billion in market cap for the year with the rest of the S&P 500 down $250 billion (so the equity market is essentially down excluding FAANG).
BMR Companies and Commentary
Square (SQ: $20, +2%)
Square jumped to a record high after reporting results that beat analysts’ expectations, impressing investors with its ability to woo bigger sellers and offer newer software products that help merchants manage their businesses. Revenue in the first quarter rose 39% as more businesses signed on for payments processing, loans and software to help manage inventory. Square raised full-year sales and profit forecasts, adding an exclamation point to the quarter. The shares have now more than doubled from a low nearly a year ago.
Not long ago, investors questioned Square’s prospects as a provider of credit card processing for food trucks amid rising competition from PayPal and First Data. But the company, run by Twitter Chief Executive Officer Jack Dorsey, has plowed ahead with international expansion, partnerships and acquisitions. Square is targeting larger merchants with a growing suite of more-profitable services, including loans and software that manage inventory and analyze sales. In the fourth quarter of 2016, those newer offerings made up a quarter of revenue. It was even higher by the first quarter, Chief Financial Officer Sarah Friar said.
What continues to make us pleased with results is growth in large businesses. That ongoing shift is good to see because those folks are not net new to the payments world. They’ve probably had an alternate supplier, but now they want to be on the latest technology and their action of migrating over to Square speaks volumes. Square said revenue from larger sellers -- those with at least $125,000 in annualized gross payment volume -- grew 44% in the first quarter from a year earlier.
BMR Take: Square is battling it out with industry titans such as Visa, MasterCard, American Express, and PayPal. So far so good. The company is in growth mode as the top line is set to expand from $900 million this year to $1.8 billion in 2020. Profitability and EPS growth will follow, with some analysts calling for $0.50 of EPS as early as 2020. All in all, we think Square is a very sturdy long term growth story, one you definitely need in your portfolio.
Amazon (AMZN: $962, +3%)
Our dear Amazon. Another week has come and gone. What new world-changing breakthrough have you for us? Home furniture? Alrighty then!
Amazon now wants to furnish your home. The online retail giant is making a major push into furniture and appliances, including building at least four massive warehouses focused on fulfilling and delivering bulky items. With that move, the Seattle-based retailer is taking on the two companies that dominate online furniture sales -- Wayfair and Pottery Barn owner Williams-Sonoma. Furniture is one of the fastest-growing segments of U.S. online Retail, growing 18% in 2015, second only to Groceries. About 15% of the $70 billion U.S. furniture market has moved online.
But even the biggest players in online furniture are struggling to get the market right. Unlike established categories such as books and music or even apparel, retailers are still hammering out basic concepts like how much variety to offer on their sites and the most efficient ways to deliver couches and dining sets to customers' homes.
While Amazon has been selling furniture for years, it has lately decided to tackle the sector more forcefully. Furniture is one of the fastest-growing retail categories at Amazon. The company is expanding its selection of products, with offerings including Ashley Furniture sofas and Jonathan Adler home décor, and it is adding custom-furniture design services. Amazon is also speeding up delivery to one or two days in some cities.
While Amazon has disrupted industries from publishing to fashion with free, fast shipping and easy, one-click buying, furniture can be a tough sector to crack. For one, it is expensive to deliver a couch and other big items, and consumers typically want what are known as "white glove" services, extras like bringing it into the home, setting it up and removing trash. And while packing more small packages onto a delivery van brings the costs down because it can make more stops, you can only fit so many pieces of furniture onto a truck.
Shoppers are still generally willing to pay for furniture delivery, but some retailers and logistics companies say they are facing growing pressure to ship online orders faster. Wayfair offers free shipping on orders over $49, but delivery times can range up to two weeks and longer. Pottery Barn charges on a sliding scale based on price, with delivery costs running above $100 for more expensive items. Furniture sold and shipped directly by Amazon is free for Prime members, while items sold by third-party sellers may cost extra.
To guarantee two-day shipping to 99% of consumers, a retailer or logistics company needs up to a dozen large warehouses spread around the country, plus around 110 smaller facilities to stage deliveries to customers' homes. Amazon is expected to rely on other third-party providers to manage distribution centers and handle delivery of furniture and appliances for the near future, even as it takes more of its logistics in house in other parts of its business. Rising sales may help reduce delivery costs by creating better density. Costs go up for transportation companies as deliveries get more spread out and infrequent.
BMR Take: We see Amazon winning this business opportunity, as they normally do.
Total sales growth is projected to run greater than 20% for several years from the current level of $165 billion predicted this year (up from $135 billion last year.) What an extraordinary growth story Amazon is. What a great ride this stock has and will continue to be. If the company can reach the $30 of EPS analysts project by 2020, this stock easily goes much. Much higher.
Note: See more on Amazon below in “The Death of Retail?”
Splunk (SPLK: $67, +1%)
Splunk, a provider of the leading software platform for real-time Operational Intelligence, announced the results of new research that shows digital transformation* initiatives are more successful when they have buy-in from across the business.
* Digital transformation is the change associated with the application of digital technology in all aspects of human society. The transformation stage means that digital usages inherently enable new types of innovation and creativity in a particular domain, rather than simply enhance and support the traditional methods.
Findings from a survey of 400 senior IT executives across the U.S., U.K. and Germany show that adoption of digital transformation initiatives is widespread. When asked where they are in the journey, 36% believe they are ahead of the curve, while 55% believe they are moving with the masses. They said that 30% of their IT budget is dedicated to digital transformation projects, but the research reveals these initiatives are more likely to succeed when funded from outside IT. The organizations that are most mature when it comes to digital-first strategies are more likely to indicate that funding comes from departments such as product development, customer service, sales and marketing.
Having a digital transformation strategy and executing on it no longer means you have an edge. If the majority of organizations are ‘moving with the masses’ or believe they are ‘ahead of the curve’ then no one is really standing out. Organizations that rely on machine data to make better decisions gain a strategic advantage over their competitors. It is not surprising that those organizations with the most success are the ones collaborating – and funding – cross-functionally. Data is a key driver in enabling that collaboration and can help companies drive real-time business insights to move faster to differentiate, innovate, raise revenues, reduce costs and mitigate risks.
Key findings from the report include: (i) 67% of respondents expect digital transformation budgets to increase, while only 8% expect a decrease; (ii) 70% of respondents cite IT as a key funding source. (iii) 77% of respondents say security was a critical or very important driver; and (iv) insight into machine data is key to success: When asked about the ability to derive real-time insights and business value from machine data to achieve their digital business goals, more than two-thirds say this is a critical or very important priority.
BMR Take: Splunk is the market leader in analyzing machine data to deliver Operational Intelligence for security, IT and the business. Splunk software provides the enterprise machine data fabric that drives digital transformation. More than 13,000 customers in over 110 countries use Splunk solutions in the cloud and on premise. It is an exciting time for Splunk in this business. With EPS on track to go from $0.41 in this most recent fiscal year to $1.35 in 2020, the prospects for the stock look exciting too. We are up 46% since we added it in March of last year. Our Target is $75.
Netflix (NFLX: $161, +3%)
Netflix announced 400 new jobs in Europe and two new European original series. The expanding workforce complements $1.75 billion of investment in European content, with at least six new Netflix European original projects to be announced in 2017. Netflix is now taking over Europe!
The creation of 400 jobs is happening at its new European customer service hub, which opened this week in Amsterdam. The customer service center will support customers across 11 European countries (Belgium, Denmark, Finland, Ireland, Luxembourg, the Netherlands, Norway, Poland, Romania, Sweden and the UK). The multilingual hub will employ initially a workforce of 170, growing to 400 by the end of 2018.
Amsterdam is the location also of Netflix’s recently expanded European, Middle East and Africa headquarters, which has doubled its workforce since the beginning of 2016. More than 120 employees from 18 countries work at the HQ in business development, marketing, PR, public policy and corporate functions such as finance, legal and recruiting.
The ongoing expansion of Netflix’s workforce in Europe complements the company’s ever-growing investment in European productions (licensed, original and co-productions). The company confirmed plans to announce at least six new European original projects before the end of 2017. Netflix has committed more than $1.75 billion to European productions since entering Europe in 2012, including more than 90 original productions in various stages of development.
BMR Take: We are delighted to see the creation of jobs in Europe and the opening of a new customer service hub in Amsterdam, as well as two new European original series. Moving outside the US, Europe is a great market for Netflix to tap in to to make money longer term. We think Netflix is on track to meet or exceed analyst estimates for $10 of EPS in 2020, meaning the stock can not only grow into the current valuation, but likely head much higher. Our Target is $165. We can’t wait to raise it soon. We do hereby raise the Sell Price from $125 to $145.
Tesla (TSLA: $325, +5%)
Elon Musk has discovered a new passion in life — and it could be Tesla's best product yet. Tesla CEO Elon is the best car salesman in history. And as CEO of SpaceX, he's declared his intention to retire on Mars. But electric vehicles and low-Earth orbits might not hold a candle to what Musk ultimately ends up doing in the roofing business.
Against all odds, Musk has become the biggest booster in the history of the roofing business, thanks to a new Tesla product, the Solar Roof, that officially went on sale last week. It's the first post-Solar City-acquisition product that Tesla is selling, and it sounds as if it's been occupying at least as much of Musk's attention as the forthcoming launch of Tesla's Model 3 car.
Musk has always been big on solar power. Prior to Tesla buying SolarCity for over $2 billion, Musk was the company's Chairman (his cousin was the CEO). He likes to point out that humanity has a compelling alternative to fossil-fuel energy: the giant fusion reactor in the sky that bathes the planet every day with free power. Solar also fits into his master plan, which involves eliminating greenhouse-gas emissions by electrifying transportation; backing up the biosphere with SpaceX, which would make humanity a multi-planetary species; and powering it all with solar energy.
SolarCity has long been able to sell or lease a homeowner solar panels, but the Solar Roof offers a different value proposition. If you have to replace your roof anyway, why not replace it with a roof that generates power and saves you money over the long haul? With a 30-year-mortgage if you stay in the house, you'll replace your roof at least once. At a cost of about $10,000, you maintain the value of the home, but you don't necessarily add much to it. The Solar Roof should last twice as long as a traditional roof (and maybe much longer) and it will both mitigate your electricity costs and, paired with a Tesla Powerpack battery, provide you with backup energy. The up-front costs are high, but the overall economics are compelling. And in sunny states where electricity is costly, such as California, a Solar Roof could net a homeowner tens of thousands of dollars over 30 years.
BMR Take: Solar is the future of energy. Elon Musk and Tesla are already finding opportunities to tap into the trend. Solar roofs have a very bright future and can be a key driver of EPS for Tesla. Analysts currently project EPS to flip from a loss of $5.15 this year to over $11 in 2020. This stock has great potential. The stock set new all-time highs last week, defying the bears. Let’s put it this way – the shorts are getting killed.
Apple (AAPL: $156, +5%)
Apple chose Corning as the recipient of the first investment from its Advanced Manufacturing Fund, giving $200 million to the maker of glass used in iPhone and iPad screens. Corning, a longtime Apple partner, will use the cash on equipment and glass-processing technology mainly at its Kentucky facility that developed the protective Gorilla Glass used on smartphones. Some of the money will also go toward research and development costs. Corning’s partnership with Apple started 10 years ago with the first iPhone.
Apple Chief Executive Officer Tim Cook said in May that the company planned to invest at least $1 billion to back advanced manufacturing companies in the U.S. and help create jobs in the industry. President Donald Trump has been a vocal critic of American companies -- and Apple in particular -- that outsource production to non-U.S. manufacturers. Apple said it now supports 2 million jobs in the U.S. and that the Corning relationship has helped create about 1,000.
The investment is also a good-will gesture toward Republicans, including President Trump, who has criticized Apple for building its iPhones in China, and the Senate majority leader, Mitch McConnell, who represents Kentucky. Apple said it spent $50 billion last year with American suppliers, although it manufactures just one product line, the Mac Pro, in the United States.
Last month, Mr. Trump sketched out a plan to slash overall corporate tax rates and offer companies a special break for bringing back profits held overseas. Apple has accumulated more cash than any other company in the United States — $260 billion now - and virtually all of it is stashed untaxed in foreign bank accounts. Cook, has repeatedly complained that taxes in the United States are too high and has vowed not to bring the cash home until taxes are cut. The Corning investment is a nice gesture for Apple to show the US government that it is a good US citizen.
BMR Take: EPS are on track to be near $9 this year and grow to $10-11 in the years ahead. The Corning investment and improving government relations is reassuring for us to see. Apple remains a favorite for us. We’re up 66% on our investment since we added the stock early last year. Not bad for the largest a company with the largest market cap in the world, now $814 billion. Our Target is $155, which it has just eclipsed. Yes!!!!!!!
We’ve been waiting to say this: WE HEREBY RAISE THE TARGET PRICE ON APPLE TO $170. The Sell Price is “We would not sell Apple” and we no reason to change this. Good investing out there!
Economic Outlook for the Coming Week
Monday, May 15, 2017 10:00 AM ET
NAHB Housing Market Index SA
Period: MAY
Actual: N/A
Consensus: 68.5
Prior: 68.0
The NAHB/Wells Fargo Housing Market Index is derived from a monthly survey of builders conducted by NAHB . Home builders are asked to rate current sales of single-family homes, and prospects for sales activity in the next six months, as "good," "fair" or "poor." They are also asked to rate traffic of prospective buyers as "high to very high," "average" or "low to very low." Scores for each component are then used to calculate a seasonally adjusted index where any number over 50 indicates that more builders view sales conditions as good than poor. 68.5 is a pretty strong indication of future growth.
Tuesday, May 16, 2017 8:30 AM
Housing Starts SAAR
Period: APR
Actual: N/A
Consensus: 1,263K
Prior: 1,215K
The number of housing units started in the United States. The U.S. Census Bureau's New Residential Construction release provides statistics on the construction of new privately-owned residential structures in the United States. The data relate to new housing units intended for occupancy and maintained by the occupants. They exclude hotels, motels, and group residential structures such as nursing homes and college dormitories. Also excluded are "HUD-code" manufactured (mobile) home units.
Thursday, May 18, 2017 8:30 AM
Initial Unemployment Insurance Claims
Period: 05/13
Actual: N/A
Consensus: 240K
Prior: 236.0K
Weekly data on initial claims for unemployment insurance under state programs. The U.S. Department of Labor's Employment and Training Administration collects weekly data on new and continued claims for unemployment insurance benefits under state programs.
Thursday, May 18, 2017 10:00 AM
Period: APR
Actual: N/A
Consensus: 0.30%
Prior: 0.40%
Leading indicators are economic series that tend to change direction ahead of shifts in the business cycle. There are 10 components of the U.S. Leading Composite Indicator published by The Conference Board. The index is constructed by averaging the individual components in order to smooth out a good part of the volatility of the individual series. Historically, the cyclical turning points in the leading index have occurred before those in aggregate economic activity.
An Update on Twilio
Twilio (TWLO: $24, flat) survived another week in the low 20s. They reported earnings on Monday, two weeks ago with glowing revenues, weak earnings (expected), but gave notice that they are losing one of their big customers – Uber at 12% of revenues. They mentioned that they added 4,000 customers in the quarter to reach over 40,000 customers but the market only took notice of their losing the one customer. They have another big customer at over 10% of revenues – WhatsApp, which is owned by Facebook – and the market is worried about their losing this customer. We are not. We are focusing on the 12,000 customers a year that they are adding to their base.
Here is a letter to us on the day we issued the News Flash, from one of our subscribers, Bob Rood:
I bought some at the low yesterday. Bob
And our response:
OK, good, Bob. It has rallied a tad this morning. But be prepared for anything that might happen. We could see $20 before we see $30. I hope this is not the case, but it could happen. It looks like Uber is slowly leaving as a customer and they had 12% of revenues. So, this will take some time to work out. They did add 4,000 customers last quarter and are now at 41,000. They normally add 2,800 a quarter. But note that this is going to take some time.
Todd Shaver
Second Quarter Earnings Reports
About 50% of firms have beaten earnings forecasts, above the long-term average of 46%, according to Goldman Sachs. Further, 40% of companies have exceeded revenue estimates, the most positive ratio of surprises in almost six years.
The VIX (^VIX: 10.40)
The lack of concern amongst US equity investors can be seen in the CBOE Volatility Index, the VIX, a 30-day barometer of investor nervousness calculated using S&P 500 options. The so-called fear gauge on fell on Tuesday to the lowest on record, at 9.67, according to data compiled by Bloomberg, before rallying to close at 10.40.
BMR Take: Low volatility is a sign of bullishness. In times of panic when the market is falling day after day, the Vix is usually in the 20s and sometimes in the 30s. In 2008 when the world was caving in financially, the Vix reached the 60s at the worst of the financial crisis and even spiked into the 90s. The historical average is about 15-16, so at 10 we are in very calm, uncharted territories. Because of this ultra-low volatility level some people say: LOOK OUT; watch for something to happen. We’re not like that. If this market can handle this last week of Trumponomics, then it can handle anything.

c/o Business Insider
The Death of Retail?
Warren Buffett just proclaimed the death of Retail as we know it. In an article in Business Insider he says the future of the retail department store is online. This is not rocket science to us, but to hear Warren say these things holds a lot of weight in our book. Berkshire Hathaway fired a warning signal for the retail industry in February when it sold off $900 million of Walmart stock, choosing instead to invest billions in airlines.
In the age of Amazon, "I think retailing is just too tough for me, generally," Buffett said. "We bought a department store in 1966, and I got my head handed to me. I've been in various things in Retailing. ... I bought Tesco over in the UK and got my head handed to me. Retailing is very tough, and I think the online thing is hard to figure out."
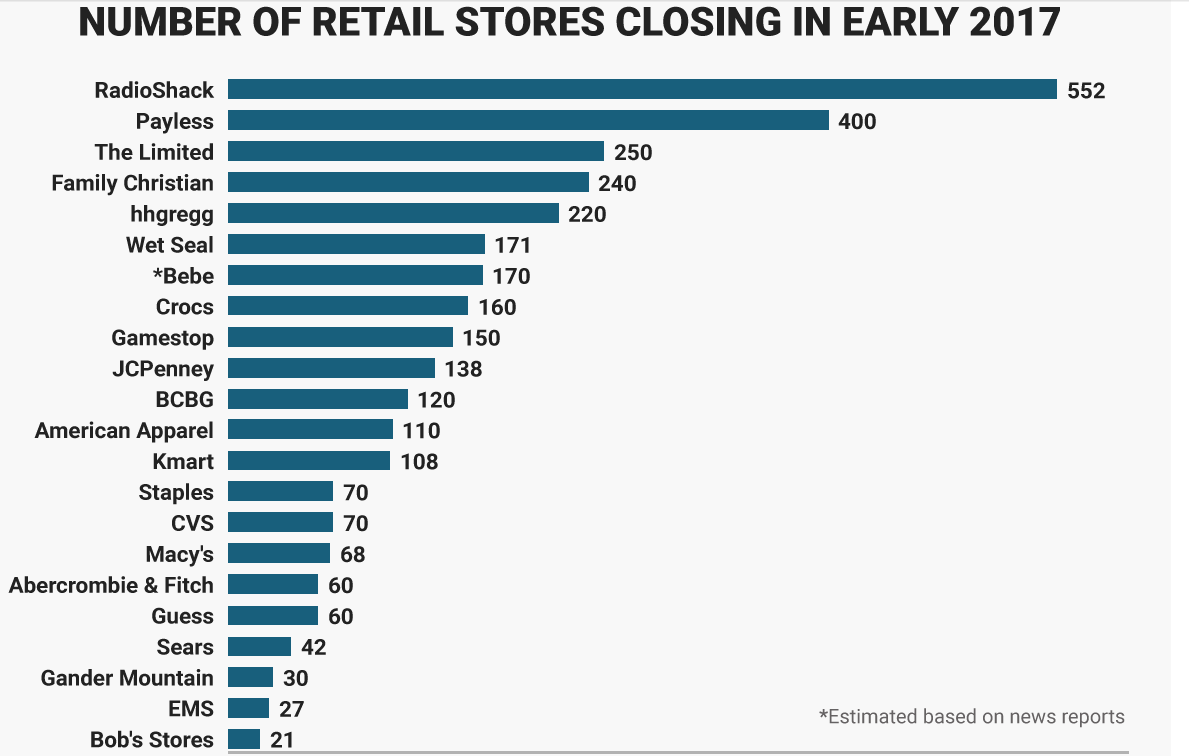
Brick-and-mortar retailers have announced more than 3,200 store closures so far this year, and Credit Suisse expects that number to increase to more than 8,600 before the end of the year. For comparison, 6,200 stores shut down in 2008, the worst year for closures on record. Department stores like Macy's, Sears, and J. C. Penney have been hit the hardest by these trends - since 2001, department stores have lost half a million jobs.
BMR Take: In March we thought about buying Simon Property Group (SPG: $157, down from $186 in February), but we changed our minds quickly. Instead, we would buy Amazon now. The stock closed at $962 Friday, up $27 or 3% last week. Yikes – 10-year bonds pay less than 3% PER YEAR.
Please DON’T WORRY ABOUT THE HIGH STOCK PRICE – pretend it is trading for 1/10 or $93 a share. Buy 11 shares, or 32 shares, or 100 shares – but buy some Amazon. We can see $1000 a share soon; then $1100; then $1200. This one might hit $2000 sometime next year.
c/o Business Insider
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
We have often referred to them as the four most dangerous words in our business – "this time is different.” We are beginning to pick up quite a bit of commentary lately that talks in terms of it being different this time. The words are not all the same, but the general gist is that "American equities may not be significantly overpriced; The market may be discounting a far-larger rise in future corporate earnings than most investors realize is possible (Trump tax cuts); or foreign investment may be altering the traditional valuation parameters used to determine share-price multiples so that it is quite possible that we have entered a new era for share price evaluation".
The bottom line to all of this is that we don't believe there are any "It's different this time fundamentals" that are going to change this market. There are obviously new and varied "wrinkles" attached to today's market scenario relative to history, but it will still, in our opinion, move in the direction that earnings take it. Earnings thus far have met or exceeded expectations. We believe that until they disappoint, the market will advance, but only so far as earnings allow……..not because of a pundit's idea that the market is going up due to some new theory about share price evaluation or of it being "different" this time.
Opko Health: A Letter from a Subscriber
We're sure you have all read the news on Opko Health (OPK: $7.19, down 4%) about their earnings report that we put out via News Flash on Thursday. After much consideration, we have decided to stick with it, even as the stock is down significantly from the price at which we added it in September. A reader wrote us on Friday:
From: John <jotenn@xxxxx.com>
To: The Bull Market Report <Info@BullMarket.com>
Sent: Thursday, May 11, 2017 11:03 AM
Subject: News Flash for May 11, 2017: Opko Health: An Uneventful Quarter. Time to Step Aside? Or Be Patient?
Hi Todd:
You are right about others buying OPKO. The CTO just bought 40,000 shares, and I see the Executive VP just picked up another couple of thousand shares under $7 too.
I bought a few hundred more shares at 6.80 yesterday also. I believe CEO Frost is playing the long game here. Lots of irons in the fire, and he is spending money to develop them, thus, less profit than analysts expected although revenue was good. Anyway, you win some (MZOR is a real home run, thanks!) and lose some, but I am still holding in there, and I keep averaging down whenever a whole number is breached. Did that with VRX too, and it is now paying off, big time!
Best, John Tennant
And we sent this back to John:
OK, thanks for sending this news, John. We were going to comment on it in the newsletter this weekend [which we are doing now!] Revenues are key. What do you have with no revenues? Nothing. Most biotech companies have no revenues and all they have is hope that their products will work out. Opko can coast while they work on the new stuff. But it sure is frustrating waiting and waiting….
Can’t wait to see if CEO Frost is buying more down here.
Todd Shaver
Snap Posts $2.2 Billion Loss in First Quarterly Report
Snap (SNAP: $19.14, down 17%) reported a $2.2 billion loss Wednesday, in its first quarter as a publicly traded company, much deeper than the $105 million loss it posted a year ago, hurt by a one-time hit from IPO-related compensation expenses totaling $2 billion. The loss is one of the biggest in American corporate history. Snap had revenues of $150 million which more than quadrupled from the year-ago quarter but missed the consensus estimate of $158 million. Losses more than doubled to $188 million. We always find it strange for a company to lose more money than it actually took in in revenues.
Daily active users rose 36% to 166 million from the year-ago quarter, but the average revenue per user fell, while daily active user growth also disappointed.
Snap went public at $17 in March and reached $27 the second day of trading. We’ve been saying since the IPO that the company is overvalued. This earnings report goes a long way to backing us up on that.
Tesla Starts Taking Orders for its Rooftop Solar Tiles
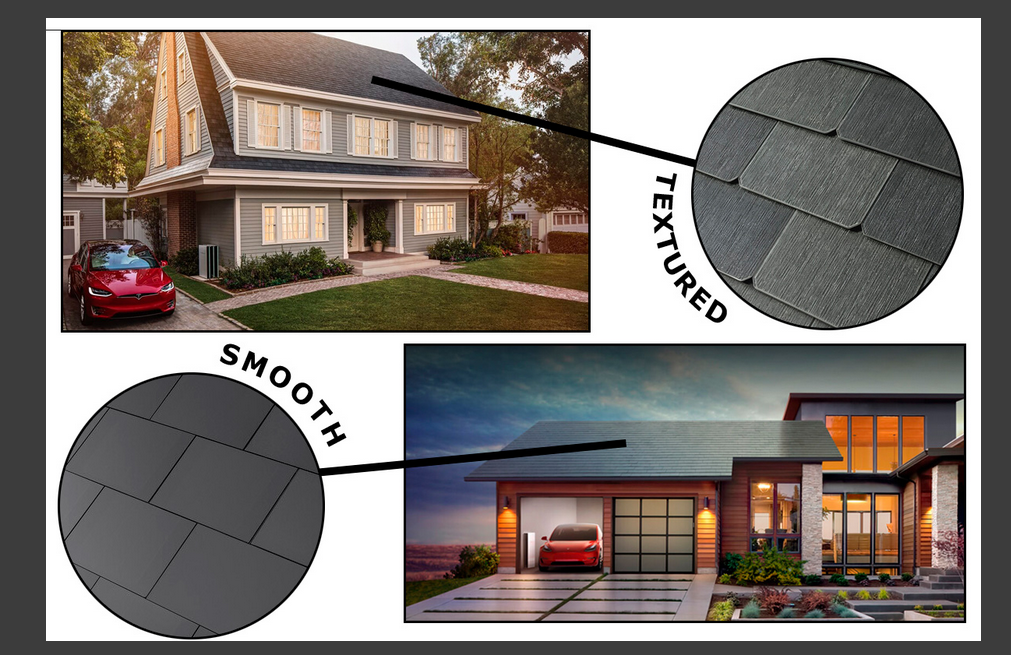
Tesla has begun taking $1,000 deposits for its remarkable solar roof tiles at a lower price point than most folks expected. The company said it will begin with production of two of the four styles it unveiled in October: a smooth glass and a textured glass tile. They say that roofing a 2,000 square-foot home with 40% coverage of active solar tiles and battery backup for night-time use would cost about $50,000 after federal tax credits and generate $64,000 in energy over 30 years. That’s more expensive upfront than a typical roof, but less expensive than a typical roof with traditional solar and back-up batteries. The warranty is for the lifetime of your home.
They are obviously going after the wealthier clientele to start. Then again, so does Apple. And so do most companies. The cost for active solar tiles is about $42 per square foot, whereas normal roof tiles cost about $11 per foot. Tesla will manage the entire process of solar roof installation, including removal of existing roofs, design, permits, installation and maintenance. The company estimates that installation will take about a week.

Kinder Morgan to raise up to $1.3 billion in Canadian IPO
Kinder Morgan (KMI: $19.91, down 1%) has a Canadian unit that is seeking to raise up to $1.3 billion in an IPO in Toronto. The deal would help fund the expansion of Kinder Morgan's Trans Mountain pipeline. Trans Mountain currently transports 300,000 barrels per day (bpd) of crude oil and refined petroleum products from the oil sands in Alberta to Vancouver, British Columbia and Washington State. In November, the Government of Canada granted approval for the $6.8 billion Trans Mountain Expansion Project, which will increase the capacity of the system to 890,000 bpd. The expanded pipeline is expected to be completed in 2019.
The company plans to offer between 80 million and 92 million shares. Toronto Dominion Bank and Royal Bank of Canada are the lead underwriters for the IPO.
The pipeline project has already won approval from the B.C. and federal governments.
Kinder Morgan will retain about 75% of Kinder Morgan Canada if the share sale were to proceed, the filing shows. Toronto-Dominion Bank and Royal Bank of Canada are leading the share sale.
BMR Take: We continue to feel Kinder Morgan is undervalued but we are content to wait patiently, collecting the 2.5% dividend. The stock was at $44 in the spring of 2015 and is now less than half that. It will start moving higher any day now.
High Yield Report
The High Yield Corner
By Michael Foster
The biggest news of the week for The Bull Market Report’s High Yield portfolio came from AstraZeneca (AZN: $34), which jumped 9% thanks to positive results from a phase 3 study of its Imfinzi drug, a non-small cell lung cancer treatment. The FDA has already approved the drug for bladder cancer treatment, but of course lung cancer is a much bigger and more serious disease, so this is significant news for the company.
The stock had been struggling for nearly a year, falling precipitously both before and after the election. Before the election, fears that Clinton would gut pharma profits caused a big selloff, but that selling pressure increased tremendously following Trump’s election and the surprising news that Trump had little sympathy for pharma either, and he was going to take a scalpel to their profit margins as well. Things hit a low at the beginning of 2017, but recent political scandals and attention elsewhere, as well as the perhaps not too shocking news that Trump is finding it difficult to repeal the Affordable Care Act, have helped pharma companies revert back to a pre-election equilibrium.
Where does that leave us now? Clearly the market has taken its eye off the pipeline ball for a long time, and one has to wonder if the recent news on Imfinzi may in fact force some greater discipline on the market and make investors realize that a sub-30 P/E ratio on a company with many life-saving drugs in various stages of regulatory approval is perhaps unfair. Credit Suisse recently upgraded the stock for that very reason, and we expect more upgrades to come in coming weeks. We’re still 3% off the 52-week high, so there’s no reason to think the sudden buying pressure on Friday is a one-off.
In the more conventional world of ultra-high yield, we’re seeing a continuation of the BDC selloff and junk bond complacency that we have written about for several weeks now. BDC earnings results continue to come in, and for the most part things do not look good. The UBS BDC ETF (BDCS: $22, down 3%) was pummeled by a mix of falling NAVs at constituent firms and analyst downgrades. The downgrades partly come from the aforementioned weakness in NAV, but portfolio yields are also deteriorating at many BDCs. What is portfolio yield? Remember, a BDC is a collection of loans to small and medium-sized businesses. The BDC gets a coupon from each loan, which is the BDC’s yield per loan. Average those together and you get the BDC portfolio yield.
Here’s the real problem: those yields have been going down for a decade. That’s made investing in BDCs particularly tricky, and has caused the BDCs themselves to do a lot of things (lower fees, issue more stock, take on greater risk) to keep investors happy. But all that was supposed to stop when the Fed started raising interest rates, which would cause rates to rise everywhere else. And that is indeed happening elsewhere in the Financial world. Margin rates, preferred note rates, corporate debt rates, and even municipal bond rates have been inching up in anticipation of the Fed’s rate hikes. BDC rates have been on an almost constant slide downward - but the interest rates they need to pay for debt-based capital is going up. So BDCs’ cost of capital is broadly rising and their portfolio yields are going down, compressing margins.
This is a mess. Why is this happening? As far as we can tell, it’s a result of supply and demand. The supply of capital looking for yields has just grown and grown; there are more investors looking to lend to small and medium-sized businesses, thus competing with BDCs. Newer BDCs are showing up. Leveraged lending firms are competing with BDCs. Regional banks are getting back into the small business lending business too. All of this is a structural headwind to BDCs, as they face more competition and thus have to take on more risk or lower the rates they offer on loans. That’s a horrible place to be in, and is why we remain cautious on BDCs as a general rule.
So it’s not surprising that BDCs are down 3%, and we expect that to continue. At the same time, however, there is incredible calm in the junk bond market. The SPDR Barclays High Yield Bond ETF (JNK: $37, flat) barely shrugged this week thanks to little news of significance and a continuation of the declining bankruptcy trend that we’ve seen since early 2016. Again, this is a strong reminder that markets should be forward-looking. Bankruptcy rates were rising in 2015-2016, and junk bond funds were collapsing at the same time. But in early 2016 the bankruptcy problem largely came to a stop, partly thanks to a recovery in oil and partly thanks to the wave of bankruptcies already shaking out most of the weak hands. Yet investors were very slow to realize and jump in.
Now that oil is getting weaker again, one has to wonder if junk bonds are getting ready to peak and a new wave of defaults may be upon us. For sure, that is a possibility but few signs indicate that we will see a repeat of 2015-2016. Instead, we could see a lot of investors anticipate a repeat that never happens, resulting in a mini-correction that provides a buying opportunity.
This means right now is a good time to stick to well-yielding junk bond and high yield bond funds. The Bull Market Report portfolio includes the PIMCO Dynamic Income Fund (PDI: $29, down 1%) and the AGIC Equity and Convertible Income Fund (NIE: $20, down 1%). Admittedly, the discount to NAV on either fund is not particularly compelling right now, but the portfolio quality and historical track record are so good that investors are wise to hold onto these stocks if you have them. New purchases in new bond funds may be something worth considering in the future. More of that in future issues of The Bull Market Report.
Good Investing,
Todd Shaver, Founder, CEO and Editor
The Bull Market Report
www.BullMarket.com