by Scott Martin | Apr 13, 2025 | Weekly Newsletter 7pm Sunday
The Bull Market Report
Probably the Best Financial Newsletter in the Country
Market Summary
After teasing a possible special edition of The Bull Market Report last week, we'd like to give you a little insight on what we've seen in the market and how investors can position themselves. So here we are. The mood remains extremely anxious, especially with Treasury bonds selling off contrary to the conventional wisdom where money flows into the safety of U.S. government debt when the economic outlook gets gloomy. While we aren't exactly shocked (correlations between stocks and bonds have gotten tighter in recent years than a lot of now-outdated textbooks taught), it can be harrowing to watch all major U.S. asset classes go over a cliff. Even the dollar is on the run, down 11% from its recent peak and circling lows last seen in the 2022 bear market.
But cut through the surface turmoil and the signs of resilience are clear. The volatility index or "VIX" is still extremely elevated, but dropped 23% last week as investors shook off the initial tariff shock. If the initial announcement had been as toxic as the market reaction suggests, the economy would already have collapsed and we would not be here talking about stocks. That's a lot better than a catastrophic worst-case scenario. Furthermore, developments in the past couple of days prove that trade policy isn't inflexible nor an ultimatum. Instead, there's a lot of room here for negotiation and compromise: timelines can be extended to give corporate leadership more time to react, some essential import categories can receive favorable treatment, and so on.
We've already seen tariffs on most countries delayed for 90 days, which gives purchasing managers until July to pivot their supply lines to the countries with the best odds of making a deal that works. And just over the weekend, we've seen tariffs on semiconductors and other computing components pulled back for adjustment, which takes the pressure off companies like Apple and Nvidia for the time being. Granted, the threat of additional trade barriers remains real. But the prospect for relief is real also. Right now, relief is winning. The trade war may be painful but at least it wasn't immediately fatal.
And stocks that were priced for the end of the world now look worth buying. Major benchmarks exploded on Wednesday when the 90-day pause was announced, with many of our stocks leading the way back. Our Early Stage recommendations, as small and theoretically vulnerable as they are, rebounded close to 30% in the last three trading days. On the other end of the market scale, giants like Apple, Amazon and Microsoft have recovered 8-10% from their lows while Nvidia bounced 15%. We could keep listing names (Meta, Broadcom, Reddit, Dell, Duolingo, Zscaler, Palo Alto Networks) but the deeper message is as simple as it gets: when 80-90% of all stocks move hard in the same direction, all that's required to get 80-90% of all stocks moving in the other direction is for the Wall Street tide to change.
That's what happened here. We are not exactly swimming in calm waters by any means, but the waves went our way this week. Money will likely keep flowing out of the bond market. Where will it go? We suspect a significant amount of capital will come back to stocks, which may be volatile but offer investors hope for better than a 3-5% return in the long run. Capital will also park in the ultimate safety of gold, where our SPDR Gold Shares (GLD) remains a real bulwark of our overall coverage universe. It's good to have a hedge when the world gets unsettled. Gold is the place.
Meanwhile, earnings season is underway, with the banks giving us pretty good numbers on Friday. JP Morgan and Citgroup don't see an immediate disaster unfolding. While we're early in the season, warnings and negative guidance revisions are NOT multiplying at too fast a speed yet. Executives might not like watching their supply chains and manufacturing costs get tangled, but they aren't surrendering either. They're fighting hard. And they think they have a handle on the situation. If they didn't, they'd warn us now and look like heroes in three months when they beat their own pessimistic forecasts.
The next few months will remain volatile, with bond yields back where they were two months ago and the VIX well above "normal" no matter where you draw the statistical boundaries. But at this stage, corporate earnings will probably come in 7% higher this quarter than they were a year ago and the growth trend still points up into 2026 and beyond. Remember, profit margins are relatively high by historical standards, so there's room for a shock or two without rocking the comparisons too much. And remember that interest rates have dropped significantly in the past year, with the Fed poised to cut again on any sign of economic damage more threatening than persistent inflation. Lower short-term rates are supportive. They're a net positive. And we don't recommend Treasury bonds here, so higher long-term rates are not our problem and should not be yours either.
What we're left with is an environment where 70% of the stocks in the S&P 500 are in correction territory and a full 40% are in the grip of a fresh bear market. Apple, Alphabet and Amazon are down 24% from their recent peaks. Nvidia and Meta are down 27%. And the list of great stocks at depressed levels goes on, both on the BMR buy lists and in the broader market. Walmart down 12%. ExxonMobil down 19%. Classic "defensive" names like Johnson & Johnson down 11%. This is classically an entry point, a chance to buy quality at a deep discount, provided that you aren't convinced that the world is about to end. Wall Street has faced every crisis that history could throw at it so far and gone back to breaking records. This time is no different.
Key Market Indicators
Good Investing,
Todd Shaver, Founder and CEO
The Bull Market Report
Since 1998
by Scott Martin | Jul 31, 2019 | 7am News Flash
Netflix (NFLX: $362, down 3% earlier this week) disappointed last night and the stock's precipitous overnight decline provides us with a different kind of wake-up call. Whether you're in Netflix or not, you're going to want to read this flash.
On the surface, Netflix delivered a quarter almost entirely in line with what investors told themselves they wanted to see. Revenue of $4.92 billion was only 0.1% below guidance and reflects healthy 26% year-over-year improvement. Even quarter-to-quarter, the company squeezed 9% more cash out of its subscribers than it did three months ago.
Furthermore, despite profit being a lower priority while management invests vast amounts in original content, it was nice to see that Netflix carried $0.60 per share across the bottom line, $0.04 better than we expected.
But the market found fault as Netflix missed its subscriber growth target, losing 126,000 paid U.S. accounts and only adding 2.83 million new viewers overseas. Management told us to expect the audience to grow by an even 5 million accounts, so it's a clear disappointment.
There are some compensating factors like the way revenue hit guidance. Netflix raised prices in many markets and this is apparently where the pain point is. We know that now. Furthermore, management has doubled down on its aggressive growth forecasts and now expects subscriber adds to accelerate again in the current quarter.
We've had it with Netflix. We've warned throughout that it's going to be a volatile ride. The stock is now down 20% since we started covering it this time around, after making 65% back in 2016-17. We're worried about competitors like Disney and Apple starting to crowd into the space. With a negative $3.5 billion of free cash flow this year and next, we'd rather be invested in a company that actually makes money. We hereby remove Netflix from our High Tech portfolio. We added them on July 16th last year. We're gone now on July 18th, 2019.
However, even for a volatile stock, the reaction to so-so numbers was so extreme that we now suspect that the market as a whole is getting overheated. It's not Netflix. It's Wall Street. And an overheated market can lurch lower as fast as it soars. Even counting the stocks that fizzled and left our list under a cloud, the BMR universe is up a dramatic 33% YTD. This is a great time to lock in some of that profit before a moody market can take it away.
Is It Time to Take Some Profits?
Why are we asking this question?We can’t predict the future. You may think we can, but we can’t. And we want YOU to think about where YOU are and where you are going with your investments. We have made some amazing stock picks and we’ve made you a lot of money in many of these. (We’ve had a few losers too.) Roku is now a triple since we added it last year. Shopify is up 350% in two years. Square is another quadruple play. PayPal, Twilio, Paycom, Microsoft, Apple, Visa: all strong performers.
Is it time to take some of that off the table? There are a lot of things to worry about in the world today: Trump, Chinese tariffs, Iran, immigrants, global slowdown, flat earnings for the past quarter and next; negative interest rates in Europe and Japan . . . can they happen here? If so, will the Fed run out of ammunition if short rates go to zero? What about the attacks on Big Tech by Congress and the European Union? Can Facebook, Amazon and Google survive this onslaught? Of course they will, but why sit around with someone hitting you on the head with a hammer. Maybe it’s better to step a little away from the scene.
Lots of questions. No solid answers. Irrational exuberance was proclaimed by Alan Greenspan on December 5, 1996 after an amazing bull run in the preceding few years. But the bull market continued to skyrocket until the Spring of 2000. That’s almost 3½ years after Greenspan’s call. So is it too early to start taking profits now?
Again, we don’t know, but we do know that there are things you can do. You can sell some calls against your stocks. This brings in cash and cushions you on the downside a bit. But if Roku, which was at $32 at the start of the year goes from $110 now to $90 or even lower, it’s not going to cushion you much with $5 of call option income. So perhaps you can take some profits off the table. Maybe you should put some stops in place. Sell some at $104. Sell some shares if it hits $96. Sell some more if it hits $90. Then if it goes to $70, which is a distinct possibility in a nasty bear market, you’ve protected your profits and have cash in the bank.
And don't forget, we’ve got 17 stocks in our High Yield and REIT portfolios that are paying from 3% to 11% dividends. (Be wary of Annaly and New Residential, though.) These stocks are just waiting for you to place some cash in them so that you can sleep better at night.
This content is for our beloved subscribers and anything you see on this page is just an excerpt!
Please note BullMarket.com access is available to paid subscribers only. Our Members Areas include archives of past Newsletters, News Flashes, our ten portfolios including STOCKS FOR SUCCESS, Healthcare, High Yield, High Technology, Exchange Traded Funds (ETF's), Energy, Senior Growth Opportunities, Financial, Long Term Growth, and Special Opportunities. Also, all of our in-depth research is available, and more.
Already a subscriber?
Login Here
Ready to join?
Subscribe Now!
by Scott Martin | Jul 30, 2019 | 7am News Flash
Netflix (NFLX: $362, down 3% earlier this week) disappointed last night and the stock's precipitous overnight decline provides us with a different kind of wake-up call. Whether you're in Netflix or not, you're going to want to read this flash.
On the surface, Netflix delivered a quarter almost entirely in line with what investors told themselves they wanted to see. Revenue of $4.92 billion was only 0.1% below guidance and reflects healthy 26% year-over-year improvement. Even quarter-to-quarter, the company squeezed 9% more cash out of its subscribers than it did three months ago.
Furthermore, despite profit being a lower priority while management invests vast amounts in original content, it was nice to see that Netflix carried $0.60 per share across the bottom line, $0.04 better than we expected.
But the market found fault as Netflix missed its subscriber growth target, losing 126,000 paid U.S. accounts and only adding 2.83 million new viewers overseas. Management told us to expect the audience to grow by an even 5 million accounts, so it's a clear disappointment.
There are some compensating factors like the way revenue hit guidance. Netflix raised prices in many markets and this is apparently where the pain point is. We know that now. Furthermore, management has doubled down on its aggressive growth forecasts and now expects subscriber adds to accelerate again in the current quarter.
We've had it with Netflix. We've warned throughout that it's going to be a volatile ride. The stock is now down 20% since we started covering it this time around, after making 65% back in 2016-17. We're worried about competitors like Disney and Apple starting to crowd into the space. With a negative $3.5 billion of free cash flow this year and next, we'd rather be invested in a company that actually makes money. We hereby remove Netflix from our High Tech portfolio. We added them on July 16th last year. We're gone now on July 18th, 2019.
However, even for a volatile stock, the reaction to so-so numbers was so extreme that we now suspect that the market as a whole is getting overheated. It's not Netflix. It's Wall Street. And an overheated market can lurch lower as fast as it soars. Even counting the stocks that fizzled and left our list under a cloud, the BMR universe is up a dramatic 33% YTD. This is a great time to lock in some of that profit before a moody market can take it away.
Is It Time to Take Some Profits?
Why are we asking this question?We can’t predict the future. You may think we can, but we can’t. And we want YOU to think about where YOU are and where you are going with your investments. We have made some amazing stock picks and we’ve made you a lot of money in many of these. (We’ve had a few losers too.) Roku is now a triple since we added it last year. Shopify is up 350% in two years. Square is another quadruple play. PayPal, Twilio, Paycom, Microsoft, Apple, Visa: all strong performers.
Is it time to take some of that off the table? There are a lot of things to worry about in the world today: Trump, Chinese tariffs, Iran, immigrants, global slowdown, flat earnings for the past quarter and next; negative interest rates in Europe and Japan . . . can they happen here? If so, will the Fed run out of ammunition if short rates go to zero? What about the attacks on Big Tech by Congress and the European Union? Can Facebook, Amazon and Google survive this onslaught? Of course they will, but why sit around with someone hitting you on the head with a hammer. Maybe it’s better to step a little away from the scene.
Lots of questions. No solid answers. Irrational exuberance was proclaimed by Alan Greenspan on December 5, 1996 after an amazing bull run in the preceding few years. But the bull market continued to skyrocket until the Spring of 2000. That’s almost 3½ years after Greenspan’s call. So is it too early to start taking profits now?
Again, we don’t know, but we do know that there are things you can do. You can sell some calls against your stocks. This brings in cash and cushions you on the downside a bit. But if Roku, which was at $32 at the start of the year goes from $110 now to $90 or even lower, it’s not going to cushion you much with $5 of call option income. So perhaps you can take some profits off the table. Maybe you should put some stops in place. Sell some at $104. Sell some shares if it hits $96. Sell some more if it hits $90. Then if it goes to $70, which is a distinct possibility in a nasty bear market, you’ve protected your profits and have cash in the bank.
And don't forget, we’ve got 17 stocks in our High Yield and REIT portfolios that are paying from 3% to 11% dividends. (Be wary of Annaly and New Residential, though.) These stocks are just waiting for you to place some cash in them so that you can sleep better at night.
This content is for our beloved subscribers and anything you see on this page is just an excerpt!
Please note BullMarket.com access is available to paid subscribers only. Our Members Areas include archives of past Newsletters, News Flashes, our ten portfolios including STOCKS FOR SUCCESS, Healthcare, High Yield, High Technology, Exchange Traded Funds (ETF's), Energy, Senior Growth Opportunities, Financial, Long Term Growth, and Special Opportunities. Also, all of our in-depth research is available, and more.
Already a subscriber?
Login Here
Ready to join?
Subscribe Now!
by Todd Shaver | Feb 11, 2018 | Weekly Newsletter 7pm Sunday
The Weekly Summary
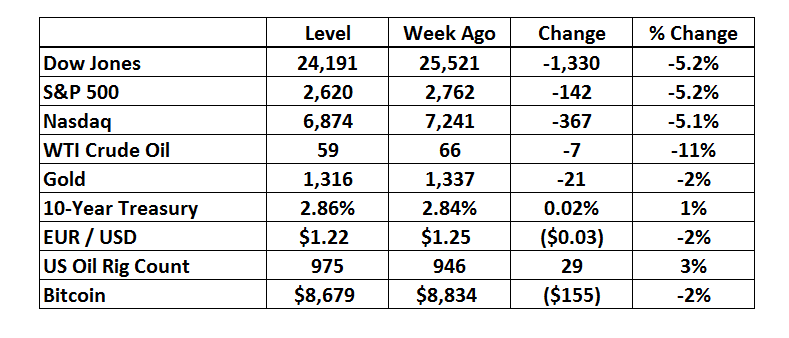
Volatility is back and in an uproar. We’ll run through what is happening in the markets below, but don’t lose sight that although the backdrop warrants caution, the bull market is alive and well. US equities ended their worst week in two years on a positive note with the Dow up 330 points on Friday, but rate-hike fears that pushed markets down remain in place as investors await inflation figures on Wednesday. The S&P 500 tumbled 5.2% in the week, its steepest slide since early 2016, jolting equity markets from an unprecedented stretch of calm. At one point, stocks were 12% below the highs set just two 11 days ago, before a strong rally Friday left the equity benchmark 1.5% higher on the day.
Still, the selloff has wiped out gains for the year. Signs are mounting that jitters spread to other assets, with measures of market unrest pushing higher junk bonds, emerging-market equities and treasuries. The CBOE Volatility Index ended at 29, almost 3x higher than its level January 26th. We at The Bull Market Report are staying calm. We believe stocks are on sale so we would suggest picking out one or two of your favorites and slowly buying more shares.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight: Blackrock, The Carlyle Group, Synaptics, Tesla, CBRE Group, and Ventas.
Key Market Measures (Friday’s Close)
BMR Companies & Commentary
Blackrock (BLK: $522, down 5%)
BlackRock is trusted to manage more money than any other investment firm. Its business is investing on behalf of clients from large institutions, to parents and grandparents, teachers, nurses, doctors and people from all walks of life who entrust their savings to the firm. Well, the company is getting even bigger.
BlackRock is seeking to raise $10 billion for "BlackRock Long-Term Private Capital" to buy and hold $500 million to $2 billion minority stakes in companies for periods of up to more than a decade. The move establishes BlackRock as a potential competitor to Wall Street private-equity giants like Carlyle Group and Apollo Global Management. It is the first-ever attempt by the world's largest asset manager to make such direct investments.
BlackRock has praised Berkshire Hathaway as the best-known example of the strategy. Well, of course. No one has ever done it better. We all know this. BlackRock Long-Term Private Capital will operate differently from most private equity funds, taking full commitments up front and reinvesting as it exits investments. As compared with most investments that return capital to investors after one deal. This is great for Blackrock shareholders because there is no need for ongoing fundraising.
BMR Take: The rock of the investment management industry right now is Blackrock. The company is going to generate nearly $14 billion of revenue this year and produce about $28.60 of EPS. With revenue and EPS growing to over $15 billion and $32.00 next year, respectively, the stock is far from expensive leaving a lot of room for upside.
---------------------------------------------------------------------------------------
The Carlyle Group (CG: $23, down 10%)
Carlyle delivered a solid quarter. Revenue was $1.0 billion versus just $435 million a year ago. EPS hit $1.01 versus just $0.02 a year ago.
Management discussed how the business concluded 2017 with great momentum across all businesses. Carlyle had record activity deploying $22 billion into new investments and raising $43 billion of capital across the platform. Investment performance was exceptional with 20% appreciation across carry funds enabling realizations of $26 billion that went to investors as proceeds for their investments.
The company declared a quarterly distribution of $0.33 per share on February 21st. For full year 2017, they paid out $1.41. That is nearly a 6% yield at the current price.
BMR Take: In private equity The Carlyle Group is a top-notch franchise, known everywhere, the who’s who of business, doing deals in the top floor offices of every major city. The business is raising money like weeds and generating big returns. It is a very compelling opportunity. EPS should hit $3.00 next year leaving this stock dirt cheap.
---------------------------------------------------------------------------------------
Synaptics (SYNA: $44, up 7% - yes really!)
Synaptics reported revenue of $430 million versus $461 million last year. EPS was $1.11 versus $1.49 a year ago. Not terribly pretty, but Synaptics is starting to benefit from the transition encompassing a more diversified product portfolio and customer base, and expects to see strong momentum from investments in infinity displays and consumer IoT in the second half of this calendar year. They continue to make meaningful strides across core growth priorities within chip-on-film, OLED (organic light-emitting diode*), in-display fingerprint technology, and consumer IoT. This includes retail availability of flagship smartphone products, such as new fingerprint, display, and voice-enabled technologies.
* OLED panels are made from organic (carbon based) materials that emit light when electricity is applied through them. Since OLEDs do not require a backlight and filters (unlike LCD displays), they are more efficient, simpler to make, and much thinner - and in fact can be made flexible and even rollable.
BMR Take: With all of the growth investments happening, and the lucrative opportunity emerging for consumer IoT, the quarter’s results were less important than the outlook for attacking this major opportunity. And the outlook is bright. EPS is expected to ramp from around $4 this year to $5 next year and substantially more in the years ahead. We added the stock at $41 in December and our Price Target is $54 and we are hopeful of seeing this during the current year. It would be helpful in achieving this goal if the market calms down and resumes its bull run.
---------------------------------------------------------------------------------------
Tesla (TSLA: $310, down 9%)
Tesla reported revenue of $3.3 billion this quarter versus $2.3 billion last year. For the full year Tesla did $12 billion versus $7 billion a year ago. EPS this quarter was a loss of $3.04.
However, the big ramp in profitability is on the horizon. Revenue is expected to jump to $20 billion this year and $27 billion next year. EPS is expected to swing from a loss to a positive $3.25 in 24 months.
The stock traded about flat after the earnings release that included a fractional revenue miss, and narrower-than-consensus EPS loss. Gross margins came in 190 basis points below consensus, with the Model 3 production ramp weighing on the overall margin profile. But that didn’t really matter as management reiterated its target of 5,000 Model 3 production units per week by the end of Q2.
BMR Take: Most continue to see many moving parts to the Tesla story, with the guidance for sustainable positive operating profits sometime in 2018 garnering more of a show-me attitude, especially given the checkered track record of not hitting guidance milestones or production targets. However, most agree the healthy demand for the Model 3 continues to be a good problem to have, and are spectators on the pace of production execution.
We put a Sell Price of $335 on the stock a few weeks ago so we don’t lose the tremendous profits we have on the stock, but the market this week smashed most stocks down including Tesla. Our Sell Prices are for YOU to decide what to do.
--- We love the concept of the company.
--- We love Elon Musk (Space X with its new successful launch this week has had positive ramifications on Tesla).
--- We love the cars they make.
--- But the debt is crushing.
--- But they have been able to weather the storm through debt and equity sales.
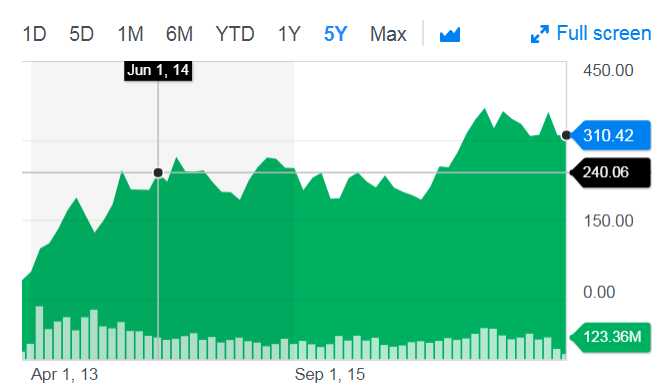
As we’ve said before, this stock could go to $200 or $500. And we’re not sure which will come first? It is very speculative. Should you be in this stock for the wild ride ahead? Only you can decide.
Here’s a 5-year chart. Pretty impressive:
---------------------------------------------------------------------------------------
CBRE Group (CBG: $42, down 5%)
CBRE is crushing it. The company reported revenue of $4.4 billion versus $3.8 billion last year. EPS was $0.99 up from $0.93 a year ago. The consensus expects this year’s revenue to grow from $14.2 billion to $16.5 billion in 2019. EPS is similarly expected to grow from $2.70 this year to $3.20 in 2019.
Fourth-quarter results capped another excellent year for CBRE. Performance significantly exceeded the expectations discussed on the third-quarter earnings call as some concerns surfaced about occupier outsourcing and leasing fee revenue growth. But all that went to the wayside as revenue and earnings for 2017 ended up reaching all-time highs. 2017 marked the 8th consecutive year of double-digit EPS growth for CBRE.
BMR Take: The macro environment is a supportive backdrop for this business, and management continues to operate within an industry poised for long-term growth. This is due to the growing acceptance of outsourced commercial real estate services, the increasing capital allocation to commercial real estate as an institutional asset class, and the continuing consolidation of activity within the industry to the highest-quality, globally diversified market leaders. CBRE Group is a must-own holding in your portfolio in the real estate sector.
We’re up over 60% in two years on this wonderful firm. No dividend yet, but we can see that coming. Our target is $54 and there’s an outside chance it can hit that this year. We know what this company does first hand – they save big multi-national companies money. Big money as in millions and millions of dollars. And the firm gets rewarded in brokerage fees, fixed fees and more. And so few people know about this great firm.
This chart shows the value this stock offers here, after this rough week:

---------------------------------------------------------------------------------------
Ventas (VTR: $52, down 5%)
Ventas reported revenue for the quarter of $895 million versus $875 million a year ago. Revenue for 2017 ended at $3.6 billion versus $3.4 billion in 2016. EPS was $0.50 versus $0.58 a year ago. EPS for 2017 ended at $1.78 versus $1.86 in 2016. Consensus expects revenue to drift upward toward $3.7 billion over the next 2 years. EPS is expected remain stable around $1.75 although we see several sources of EPS upside that are likely to drive revisions closer to the highest Street forecast of $2.15.
All in all, 2017 was another excellent year for Ventas, as the business generated record cash flow from operations and delivered same-store property cash net operating income growth at the high end of internal expectations. To further enhance their diverse portfolio, the company made nearly $2 billion in value-creating investments, including significant expansion of their university-based life science business. And they profitably disposed of almost $1 billion in assets and completed innovative deals with leading operating partners.
BMR Take: Ventas has proven resilient through cycles for two decades. They remain one of the world's best REITs with a specialty in healthcare among other areas.
This success is founded on solid strategic vision, superior foresight and innovation, intelligent and timely capital allocation decisions, rigorous execution and a cohesive, expert team. As they enter 2018 – the company’s 20th anniversary year – management is confident that they can continue the long track record of superior consistent performance as the industry leader.
We added Ventas at $60 in last 2016, a little over a year ago. Until the last two weeks, it was hovering around $56, down a bit, but still paying a nice 6% dividend. It’s worth $18 billion, and has over 1200 properties across the US, Canada and the UK. And as you know, they are in the senior living business along with medical facilities as well. Yes, the stock is down, but this company is strong, and we can only see good things happening from here. If you bought at $60 now is the time to add to your position to bring your cost down. Two years from now we wouldn’t be surprised to see the stock in the 70s, as remember, 10,000 people a day turn 65 in the US. They have to live somewhere!
---------------------------------------------------------------------------------------
We got a letter from one of our readers about Ventas
From: Richard Reed [mailto:reed995@]
Sent: Wednesday, February 07, 2018 10:21 AM
To: The Bull Market Report <Info@bullmarket.com>
Subject: Re: EARNINGS PREVIEW FOR THE WEEK AHEAD
Hi Todd,
Ventas (VTR) is below your Sell Price. Are you lowering the sell price? Thanks.
Richard
Our answer:
Hi Richard –
Look – they own 1200 assets in the United States, Canada and the UK. The properties are senior living properties and more. Are they all going down the tubes? NO WAY. A $19 billion asset paying 6%. We would buy more.
Furthermore, our Sell Price on Ventas is $58. But at $52, we have to say that we like it even more. Nothing has changed for the company in the past two weeks. Yes, interest rates are a shade higher, but nothing out of the ordinary. When the economy is good, rates go out. This is just normal. So to answer your question above, yes, we are lowering our Sell Price to $48. Of course, YOU can make up your own mind on this one, as always, but we would take this opportunity to buy an amazing company at an even lower price.
---------------------------------------------------------------------------------------
---------------------------------------------------------------------------------------
Economic Calendar
CPI Ex-Food & Energy
Wednesday, February 14th, 8:30 AM
Period: January
Consensus: 1.7%
Prior: 1.8%
CPI
Wednesday, February 14th, 8:30 AM
Period: January
Consensus: 1.9%
Prior: 2.1%
PPI
Thursday, February 15th, 8:30 AM
Period: January
Consensus: 2.5%
Prior: 2.6%
Housing Starts
Friday, February 16th, 8:30 AM
Period: January
Consensus: 3.7%
Prior: -8.2%
---------------------------------------------------------------------------------------
---------------------------------------------------------------------------------------
Apple has $285 Billion in Cash
Can you believe this? Again – a record high for any company in history. Apple (AAPL: $156, flat for the week) has $285 billion in cash, or $56 a share. With the stock at $156, that’s 36% of each share of stock in cash. We’re not sure of the Wall St. record, but we are guessing this is twice as much than any other company in history. With the stock flat for the week (amazing) this just screams out at us to add more to the portfolio.
---------------------------------------------------------------------------------------
If the Market Heads Back Up
No one knows where the market is heading. Will it calm down and move higher this coming week and month? Or will it be heading for 23,000 and lower? Again, we don’t know. But if things simmer down and the volatility abates – AND IT WILL – there are a few stocks that we would want to add to our positions in. Here are just a few:
Microsoft
PayPal
Google
Facebook
Apple
Eli Lilly
Yes, many of these are the super Tech stocks that have been leading the market. But guess what? These stocks will continue to lead the market for many years to come.
And one more note. Did you see Annaly Capital Mortgage (NLY: $10.21, down 1%) this week? Solid as a rock. So if you are super worried about things, we believe Annaly can be a store of value for a month or two or 12, and you can enjoy the 11% dividend in this $12 billion market cap company.
---------------------------------------------------------------------------------------
---------------------------------------------------------------------------------------
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
There was no comment Monday or Tuesday because everything I wrote was outdated and the numbers were obsolete within minutes of writing, rewriting and re-rewriting them. The dust may or may not have settled, but a few things are much clearer today.
In short, the seismic swings over the past few days have been based on three primary factors that we believe now form a consensus:
1. The threat of higher inflation (Rising bond yields)
2. The possibility of more Fed hikes
3. The long streak without a normal and healthy market shakeout.
How does that stack up against the best economy we've seen in over a decade? In other words, is it good news or bad news that economic growth is so strong the Fed may have to raise rates sooner than expected? Or, is it good news or bad news that nearly half the companies in the S&P 500 have reported fourth quarter results and more than 80% of them have beaten Wall Street's revenue expectations, the highest percentage since the third quarter of 2008? And, is it good news or bad news that the tax law will boost those profits further in the quarters ahead?
Let's put all this in perspective:
First, the market isn’t overbought anymore. We now know that. There was a "10% correction." Let’s get over it.
Second, earnings are robust.
Third, the rise in bond yields has been a headwind, but it’s not signaling a looming recession. Importantly, the 10-year vs. 2-year Treasury yield spread has widened out as yields have risen, implying the bond market is now discounting higher inflation and better economic growth, which over the medium term has almost always been positive for stocks.
While volatility has returned with a vengeance, the market fundamentals are now better and earnings growth prospects haven't looked better in years. Basically, all of the reasons why investors have been bullish on the market last week, last month and last year are still here.
---------------------------------------------------------------------------------------
The High Yield Report
by Michael Foster
VP High Yield
It should always be emphasized that much of a stock's action is not caused by only the underlying company, but also by the industry and the overall market. In a volatile environment, this emphasis is especially important. While our High Yield and REIT portfolios have shown lackluster performance over the past two weeks, the fundamental aspects of the companies that make up the portfolios have not changed.
The S&P 500 decreased 5.1% over the past week, leading to stocks officially being in correction territory. Much of the decline is being attributed to interest rate and liquidity fears, which is why much of the analysis on the portfolio below will focus on those aspects. It takes just one week to rattle bullish sentiment. As an investor, you should not put too much weight on what the general financial media is discussing. What should take priority is thinking about whether the fundamental aspects of the economy and market have changed. When this is the priority, our fear diminishes as we realize that earnings are still strong, nonfarm payrolls on February 2nd were above expectations, and a deregulatory environment is still present.
One metric, the yield curve, is worth looking at though. The spread between the 10-year Treasury yield and the 2-year Treasury yield has been constantly decreasing as a result of the Federal Reserve tightening policies and the lack of inflation. On a basic level, you can note that the presence of an inverted yield curve, if it were to happen, has been a common predictor of past recessions. Going deeper, the economic repercussions of the inversion are much more important. Consumers and banks are directly impacted. For consumers, the cost of credit increases, which leads to a larger portion of expendable income being dedicated to servicing debt. For banks, the spread between long-dated loans and deposits decreases, which leads to worse financial performance. We’re sharing this information so that you can keep the yield curve on your radar, but there’s no need to worry as of now. When the curve inverted in the past, it still took between 7 to 24 months to reach any sort of recessionary state.
AllianzGI Equity & Convertible Income Fund (NIE: $20.59, down 4%) fared slightly better than the S&P’s drop of over 5%. It moved from the weekly low of $19.50 to its current level after recovering about 2.5% in the last hour of trading on Friday. The performance of individual equities which it holds, including Microsoft, Alphabet, and Amazon, led to the recovery in the last hour. Given that the fund invests little in the bonds and the scenario of the inverted yield curve, we can expect the funds to be shifted from Equity to Bonds.
We still see Apollo Commercial RE Finance (ARI: $17.70, down 3%) as a cyclical play on the U.S. commercial real estate sector. Given that commercial real estate in the U.S. remains solid, with Apollo’s loan originations hitting $1.5 billion YTD and the economy of the US continuing to get stronger and stronger, Apollo is not a position to be worried about.
Digital Realty Trust (DLR: $102, down 5%) dropped almost by the same amount as the S&P. This was the opposite of the week prior, where the company maintained strength in the midst of widespread declines. While we noted the continued demand for data centers in the last summary, there are some other metrics to note. Digital Realty, owning many data centers in US and internationally, is affected by rising interest rates as the cost of borrowing rises. The company has a massive debt level of $5.8 billion with a Debt/EBITDA ratio of 22. Rising interest rates could cripple the company’s dividend payout and future prospects.
Invesco Municipal Trust (VKQ: $11.83, flat) ended up at the same level as the beginning of the week. With its investments primarily in investment grade U.S. municipal bond obligations (85%), the fund can expect to yield better returns amidst the current rising interest rates scenario. Also, a Fitch report stating that plans to cut federal funds to them won't impact the revenues of the municipal bond funds and ETFs, played a large part in keeping the fund’s price level stable. Nuveen Municipal (NVG: $14.43, flat), another high yield fund with major investments in U.S. investment grade municipal bonds, also maintained its price level.
Pimco Dynamic Fund (PDI: $30, down 1%) was less volatile. The firm, investing primarily in a range of debt securities, including mortgage-backed securities, high yield corporates, and emerging market bonds, could witness further issues with rising interest rates, changes in tax structure, and better yields.
The REIT sector has been partially impacted by the recent economic data, heightening fears of higher interest rates. Primarily, the sector is engaged in massive borrowings, and rising interest rates could increase the cost of the borrowings. With that said, rising interest rates often occur in a booming economy, which indicates higher demand by consumers.
Market corrections generally provide prudent investors with great buying opportunities. One way of going about this is finding relative strength in strong industries. Applying this analysis to REITs, the overall REIT sector was down only 3%. Within out portfolio, three of the five positions outperformed the sector. Annaly Capital Management (NLY: $10.21, down 1%), Government Properties (GOV: $16.37, down 1%), and Omega Healthcare Investors (OHI: $26, flat) composed that group.
As a company that primarily engages in buying mortgages and mortgage-backed securities (as well as other assets), Annaly could fare very well as interest rates go up and correspondingly coupon rates do as well. While this is not necessarily the reason for the less-than-average drop this week, going forward it is something we will keep in mind. Both Government Properties and Omega should not feel a significantly negative impact by rising rates either. The former gets offered attractive rates by the government as a result of its leases and the latter’s healthcare-related real estate is, for the most part, unaffected by the business cycles.
The other two positions, Ventas (VTR: $52, down 5%) and Welltower (HCN: $55, down 5%), ended up having declines that were in-line with the S&P 500 but larger than the move in the REIT sector.
Ventas reported positive 4th quarter earnings on Friday, which provided a minor boost to the stock. The reported income from continuing operations for 2017, $640,000, was a record for the company. In turn, the EPS and FFO per share numbers were also records. In a rising rate environment, this is a positive sign. With the earnings report occurring during a stock market decline, any overall S&P bounce should result in outperformance by Ventas.
The other relatively weak company, Welltower, did not have any news this week to explain the larger than average decline in the stock. As it is focused on owning senior living properties and funding real estate infrastructure, the large amount of debt maintained could pose an issue within the rising rate environment. Currently, though, the extensive track record of stock appreciation over the past 25 years leaves us unworried. Welltower is also at the lower end of its range for the past four years, so it is a good area to pick up more shares.
Good Investing,
Todd Shaver, Founder and CEO
The Bull Market Report
Since 1998