September 29, 2023
by Todd Shaver | Sep 29, 2023 | Instant News Flash
The valuation of automaker Tesla (TSLA: $252) has long been an enigma for Wall Street and the company continues to astound and astonish analysts to this day. The stock was considered overvalued when it first went public in 2010, with a valuation of $2.2 billion, just as it is today with a market cap of $760 billion. And in the preceding years, many short-sellers have lost fortunes trying to bet against the company. We have a personal friend, a former Merrill Lynch VP who ran an office in Florida, who has been short for the last four years. He has lost over seven figures. We have implored him to buy back the stock, especially when it went to $102 in January of this year, down from the all-time high of close to $400 set in late 2021.
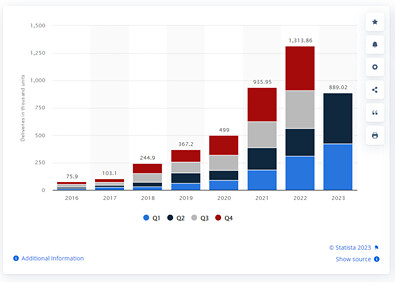
To be fair, it's hard not to question the exuberant valuations that the automaker has consistently held, which is 16 times the market cap of Ford Motors, a 120-year-old behemoth that sells twice as many cars as Tesla, and three times that of Toyota, which currently sells 10 times as many cars. Even considering Elon Musk’s ambitious goal of making 20 million cars a year by 2030, the valuations are a tough sell, particularly in the face of rising competition. The company is on track to deliver 2 million this year, up from 935,000 two years ago.
Number of Tesla vehicles delivered worldwide
Tesla has remained the most popular stock among retail investors for years. While it is also the most shorted stock as of now, with over $21 billion in short interest, the fate of these shorts looks increasingly shaky, similar to the many institutional, retail, and hedge fund bets made against the stock over the past decade. And as you know quite well by now since we have mentioned this numerous times, having a large short position is very bullish. Why? Because the only thing shorts can do is to BUY BACK their stock, which pushed the stock higher.
As discussed in our research report when we first began covering the stock two months ago, Tesla is not an automotive company, and it would be a mistake to value it as such. With its ambitious plans to flood the streets with robotaxis, its Dojo supercomputer that the Street estimates to be worth over $500 billion, the massive battery factory in Nevada, and innumerable other innovations, rather than an “automotive” company, this is a high-growth tech company through and through.
Reuters said this eight days ago: “Tesla has drawn up plans to make and sell battery storage systems in India and submitted a proposal to officials seeking incentives to build a factory, as Elon Musk continues a push to enter the country. Tesla has been in talks about setting up a new electric vehicle factory in India to build a [world] car priced around $24,000 for weeks, with discussions overseen directly by Prime Minister Narendra Modi.” We have heard that Tesla has plans for another large battery plant as well.
Another overlooked asset is the company’s extensive network of 45,000 superchargers, which it has yet to monetize. Most competitors have adopted Tesla’s North American Charging Standard. Rising competition and growing penetration of EVs on American roads only stand to benefit Tesla going forward.
Tesla is not just an automobile manufacturer; it is the future of mobility, computer vision, and sustainable technology, all rolled into one. Its vision-based AI system has applications beyond mobility, similar to its growing prowess in battery technology. With robust tailwinds across the board, and a well-capitalized balance sheet with $23 billion in cash, just $6 billion in debt, and $14 billion in cash flow, we believe that this company, with a market cap of $800 billion, run by an acknowledged genius, is poised to continue to change the world as we know it. Our Target is $325.
If you are still not convinced, get the new book called Elon Musk, by Walter Isaacson. We read all 615 pages in three days this week. He is changing the world that we live in.
February 11, 2018
by Todd Shaver | Feb 11, 2018 | Weekly Newsletter 7pm Sunday
The Weekly Summary
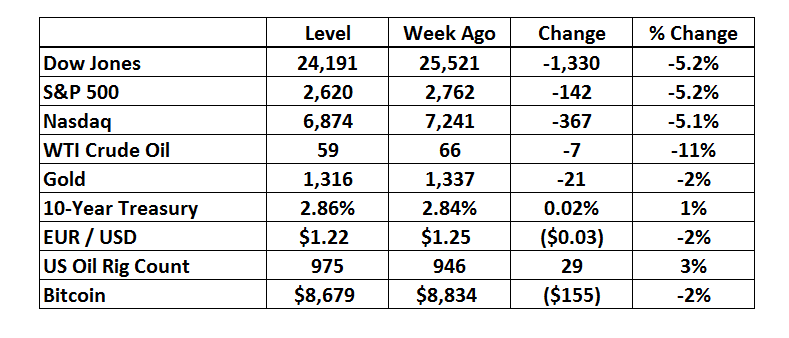
Volatility is back and in an uproar. We’ll run through what is happening in the markets below, but don’t lose sight that although the backdrop warrants caution, the bull market is alive and well. US equities ended their worst week in two years on a positive note with the Dow up 330 points on Friday, but rate-hike fears that pushed markets down remain in place as investors await inflation figures on Wednesday. The S&P 500 tumbled 5.2% in the week, its steepest slide since early 2016, jolting equity markets from an unprecedented stretch of calm. At one point, stocks were 12% below the highs set just two 11 days ago, before a strong rally Friday left the equity benchmark 1.5% higher on the day.
Still, the selloff has wiped out gains for the year. Signs are mounting that jitters spread to other assets, with measures of market unrest pushing higher junk bonds, emerging-market equities and treasuries. The CBOE Volatility Index ended at 29, almost 3x higher than its level January 26th. We at The Bull Market Report are staying calm. We believe stocks are on sale so we would suggest picking out one or two of your favorites and slowly buying more shares.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight: Blackrock, The Carlyle Group, Synaptics, Tesla, CBRE Group, and Ventas.
Key Market Measures (Friday’s Close)
BMR Companies & Commentary
Blackrock (BLK: $522, down 5%)
BlackRock is trusted to manage more money than any other investment firm. Its business is investing on behalf of clients from large institutions, to parents and grandparents, teachers, nurses, doctors and people from all walks of life who entrust their savings to the firm. Well, the company is getting even bigger.
BlackRock is seeking to raise $10 billion for "BlackRock Long-Term Private Capital" to buy and hold $500 million to $2 billion minority stakes in companies for periods of up to more than a decade. The move establishes BlackRock as a potential competitor to Wall Street private-equity giants like Carlyle Group and Apollo Global Management. It is the first-ever attempt by the world's largest asset manager to make such direct investments.
BlackRock has praised Berkshire Hathaway as the best-known example of the strategy. Well, of course. No one has ever done it better. We all know this. BlackRock Long-Term Private Capital will operate differently from most private equity funds, taking full commitments up front and reinvesting as it exits investments. As compared with most investments that return capital to investors after one deal. This is great for Blackrock shareholders because there is no need for ongoing fundraising.
BMR Take: The rock of the investment management industry right now is Blackrock. The company is going to generate nearly $14 billion of revenue this year and produce about $28.60 of EPS. With revenue and EPS growing to over $15 billion and $32.00 next year, respectively, the stock is far from expensive leaving a lot of room for upside.
---------------------------------------------------------------------------------------
The Carlyle Group (CG: $23, down 10%)
Carlyle delivered a solid quarter. Revenue was $1.0 billion versus just $435 million a year ago. EPS hit $1.01 versus just $0.02 a year ago.
Management discussed how the business concluded 2017 with great momentum across all businesses. Carlyle had record activity deploying $22 billion into new investments and raising $43 billion of capital across the platform. Investment performance was exceptional with 20% appreciation across carry funds enabling realizations of $26 billion that went to investors as proceeds for their investments.
The company declared a quarterly distribution of $0.33 per share on February 21st. For full year 2017, they paid out $1.41. That is nearly a 6% yield at the current price.
BMR Take: In private equity The Carlyle Group is a top-notch franchise, known everywhere, the who’s who of business, doing deals in the top floor offices of every major city. The business is raising money like weeds and generating big returns. It is a very compelling opportunity. EPS should hit $3.00 next year leaving this stock dirt cheap.
---------------------------------------------------------------------------------------
Synaptics (SYNA: $44, up 7% - yes really!)
Synaptics reported revenue of $430 million versus $461 million last year. EPS was $1.11 versus $1.49 a year ago. Not terribly pretty, but Synaptics is starting to benefit from the transition encompassing a more diversified product portfolio and customer base, and expects to see strong momentum from investments in infinity displays and consumer IoT in the second half of this calendar year. They continue to make meaningful strides across core growth priorities within chip-on-film, OLED (organic light-emitting diode*), in-display fingerprint technology, and consumer IoT. This includes retail availability of flagship smartphone products, such as new fingerprint, display, and voice-enabled technologies.
* OLED panels are made from organic (carbon based) materials that emit light when electricity is applied through them. Since OLEDs do not require a backlight and filters (unlike LCD displays), they are more efficient, simpler to make, and much thinner - and in fact can be made flexible and even rollable.
BMR Take: With all of the growth investments happening, and the lucrative opportunity emerging for consumer IoT, the quarter’s results were less important than the outlook for attacking this major opportunity. And the outlook is bright. EPS is expected to ramp from around $4 this year to $5 next year and substantially more in the years ahead. We added the stock at $41 in December and our Price Target is $54 and we are hopeful of seeing this during the current year. It would be helpful in achieving this goal if the market calms down and resumes its bull run.
---------------------------------------------------------------------------------------
Tesla (TSLA: $310, down 9%)
Tesla reported revenue of $3.3 billion this quarter versus $2.3 billion last year. For the full year Tesla did $12 billion versus $7 billion a year ago. EPS this quarter was a loss of $3.04.
However, the big ramp in profitability is on the horizon. Revenue is expected to jump to $20 billion this year and $27 billion next year. EPS is expected to swing from a loss to a positive $3.25 in 24 months.
The stock traded about flat after the earnings release that included a fractional revenue miss, and narrower-than-consensus EPS loss. Gross margins came in 190 basis points below consensus, with the Model 3 production ramp weighing on the overall margin profile. But that didn’t really matter as management reiterated its target of 5,000 Model 3 production units per week by the end of Q2.
BMR Take: Most continue to see many moving parts to the Tesla story, with the guidance for sustainable positive operating profits sometime in 2018 garnering more of a show-me attitude, especially given the checkered track record of not hitting guidance milestones or production targets. However, most agree the healthy demand for the Model 3 continues to be a good problem to have, and are spectators on the pace of production execution.
We put a Sell Price of $335 on the stock a few weeks ago so we don’t lose the tremendous profits we have on the stock, but the market this week smashed most stocks down including Tesla. Our Sell Prices are for YOU to decide what to do.
--- We love the concept of the company.
--- We love Elon Musk (Space X with its new successful launch this week has had positive ramifications on Tesla).
--- We love the cars they make.
--- But the debt is crushing.
--- But they have been able to weather the storm through debt and equity sales.
As we’ve said before, this stock could go to $200 or $500. And we’re not sure which will come first? It is very speculative. Should you be in this stock for the wild ride ahead? Only you can decide.
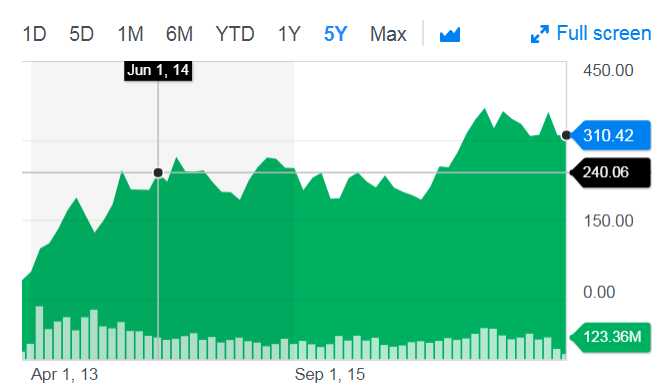
Here’s a 5-year chart. Pretty impressive:
---------------------------------------------------------------------------------------
CBRE Group (CBG: $42, down 5%)
CBRE is crushing it. The company reported revenue of $4.4 billion versus $3.8 billion last year. EPS was $0.99 up from $0.93 a year ago. The consensus expects this year’s revenue to grow from $14.2 billion to $16.5 billion in 2019. EPS is similarly expected to grow from $2.70 this year to $3.20 in 2019.
Fourth-quarter results capped another excellent year for CBRE. Performance significantly exceeded the expectations discussed on the third-quarter earnings call as some concerns surfaced about occupier outsourcing and leasing fee revenue growth. But all that went to the wayside as revenue and earnings for 2017 ended up reaching all-time highs. 2017 marked the 8th consecutive year of double-digit EPS growth for CBRE.
BMR Take: The macro environment is a supportive backdrop for this business, and management continues to operate within an industry poised for long-term growth. This is due to the growing acceptance of outsourced commercial real estate services, the increasing capital allocation to commercial real estate as an institutional asset class, and the continuing consolidation of activity within the industry to the highest-quality, globally diversified market leaders. CBRE Group is a must-own holding in your portfolio in the real estate sector.
We’re up over 60% in two years on this wonderful firm. No dividend yet, but we can see that coming. Our target is $54 and there’s an outside chance it can hit that this year. We know what this company does first hand – they save big multi-national companies money. Big money as in millions and millions of dollars. And the firm gets rewarded in brokerage fees, fixed fees and more. And so few people know about this great firm.
This chart shows the value this stock offers here, after this rough week:

---------------------------------------------------------------------------------------
Ventas (VTR: $52, down 5%)
Ventas reported revenue for the quarter of $895 million versus $875 million a year ago. Revenue for 2017 ended at $3.6 billion versus $3.4 billion in 2016. EPS was $0.50 versus $0.58 a year ago. EPS for 2017 ended at $1.78 versus $1.86 in 2016. Consensus expects revenue to drift upward toward $3.7 billion over the next 2 years. EPS is expected remain stable around $1.75 although we see several sources of EPS upside that are likely to drive revisions closer to the highest Street forecast of $2.15.
All in all, 2017 was another excellent year for Ventas, as the business generated record cash flow from operations and delivered same-store property cash net operating income growth at the high end of internal expectations. To further enhance their diverse portfolio, the company made nearly $2 billion in value-creating investments, including significant expansion of their university-based life science business. And they profitably disposed of almost $1 billion in assets and completed innovative deals with leading operating partners.
BMR Take: Ventas has proven resilient through cycles for two decades. They remain one of the world's best REITs with a specialty in healthcare among other areas.
This success is founded on solid strategic vision, superior foresight and innovation, intelligent and timely capital allocation decisions, rigorous execution and a cohesive, expert team. As they enter 2018 – the company’s 20th anniversary year – management is confident that they can continue the long track record of superior consistent performance as the industry leader.
We added Ventas at $60 in last 2016, a little over a year ago. Until the last two weeks, it was hovering around $56, down a bit, but still paying a nice 6% dividend. It’s worth $18 billion, and has over 1200 properties across the US, Canada and the UK. And as you know, they are in the senior living business along with medical facilities as well. Yes, the stock is down, but this company is strong, and we can only see good things happening from here. If you bought at $60 now is the time to add to your position to bring your cost down. Two years from now we wouldn’t be surprised to see the stock in the 70s, as remember, 10,000 people a day turn 65 in the US. They have to live somewhere!
---------------------------------------------------------------------------------------
We got a letter from one of our readers about Ventas
From: Richard Reed [mailto:reed995@]
Sent: Wednesday, February 07, 2018 10:21 AM
To: The Bull Market Report <Info@bullmarket.com>
Subject: Re: EARNINGS PREVIEW FOR THE WEEK AHEAD
Hi Todd,
Ventas (VTR) is below your Sell Price. Are you lowering the sell price? Thanks.
Richard
Our answer:
Hi Richard –
Look – they own 1200 assets in the United States, Canada and the UK. The properties are senior living properties and more. Are they all going down the tubes? NO WAY. A $19 billion asset paying 6%. We would buy more.
Furthermore, our Sell Price on Ventas is $58. But at $52, we have to say that we like it even more. Nothing has changed for the company in the past two weeks. Yes, interest rates are a shade higher, but nothing out of the ordinary. When the economy is good, rates go out. This is just normal. So to answer your question above, yes, we are lowering our Sell Price to $48. Of course, YOU can make up your own mind on this one, as always, but we would take this opportunity to buy an amazing company at an even lower price.
---------------------------------------------------------------------------------------
---------------------------------------------------------------------------------------
Economic Calendar
CPI Ex-Food & Energy
Wednesday, February 14th, 8:30 AM
Period: January
Consensus: 1.7%
Prior: 1.8%
CPI
Wednesday, February 14th, 8:30 AM
Period: January
Consensus: 1.9%
Prior: 2.1%
PPI
Thursday, February 15th, 8:30 AM
Period: January
Consensus: 2.5%
Prior: 2.6%
Housing Starts
Friday, February 16th, 8:30 AM
Period: January
Consensus: 3.7%
Prior: -8.2%
---------------------------------------------------------------------------------------
---------------------------------------------------------------------------------------
Apple has $285 Billion in Cash
Can you believe this? Again – a record high for any company in history. Apple (AAPL: $156, flat for the week) has $285 billion in cash, or $56 a share. With the stock at $156, that’s 36% of each share of stock in cash. We’re not sure of the Wall St. record, but we are guessing this is twice as much than any other company in history. With the stock flat for the week (amazing) this just screams out at us to add more to the portfolio.
---------------------------------------------------------------------------------------
If the Market Heads Back Up
No one knows where the market is heading. Will it calm down and move higher this coming week and month? Or will it be heading for 23,000 and lower? Again, we don’t know. But if things simmer down and the volatility abates – AND IT WILL – there are a few stocks that we would want to add to our positions in. Here are just a few:
Microsoft
PayPal
Google
Facebook
Apple
Eli Lilly
Yes, many of these are the super Tech stocks that have been leading the market. But guess what? These stocks will continue to lead the market for many years to come.
And one more note. Did you see Annaly Capital Mortgage (NLY: $10.21, down 1%) this week? Solid as a rock. So if you are super worried about things, we believe Annaly can be a store of value for a month or two or 12, and you can enjoy the 11% dividend in this $12 billion market cap company.
---------------------------------------------------------------------------------------
---------------------------------------------------------------------------------------
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
There was no comment Monday or Tuesday because everything I wrote was outdated and the numbers were obsolete within minutes of writing, rewriting and re-rewriting them. The dust may or may not have settled, but a few things are much clearer today.
In short, the seismic swings over the past few days have been based on three primary factors that we believe now form a consensus:
1. The threat of higher inflation (Rising bond yields)
2. The possibility of more Fed hikes
3. The long streak without a normal and healthy market shakeout.
How does that stack up against the best economy we've seen in over a decade? In other words, is it good news or bad news that economic growth is so strong the Fed may have to raise rates sooner than expected? Or, is it good news or bad news that nearly half the companies in the S&P 500 have reported fourth quarter results and more than 80% of them have beaten Wall Street's revenue expectations, the highest percentage since the third quarter of 2008? And, is it good news or bad news that the tax law will boost those profits further in the quarters ahead?
Let's put all this in perspective:
First, the market isn’t overbought anymore. We now know that. There was a "10% correction." Let’s get over it.
Second, earnings are robust.
Third, the rise in bond yields has been a headwind, but it’s not signaling a looming recession. Importantly, the 10-year vs. 2-year Treasury yield spread has widened out as yields have risen, implying the bond market is now discounting higher inflation and better economic growth, which over the medium term has almost always been positive for stocks.
While volatility has returned with a vengeance, the market fundamentals are now better and earnings growth prospects haven't looked better in years. Basically, all of the reasons why investors have been bullish on the market last week, last month and last year are still here.
---------------------------------------------------------------------------------------
The High Yield Report
by Michael Foster
VP High Yield
It should always be emphasized that much of a stock's action is not caused by only the underlying company, but also by the industry and the overall market. In a volatile environment, this emphasis is especially important. While our High Yield and REIT portfolios have shown lackluster performance over the past two weeks, the fundamental aspects of the companies that make up the portfolios have not changed.
The S&P 500 decreased 5.1% over the past week, leading to stocks officially being in correction territory. Much of the decline is being attributed to interest rate and liquidity fears, which is why much of the analysis on the portfolio below will focus on those aspects. It takes just one week to rattle bullish sentiment. As an investor, you should not put too much weight on what the general financial media is discussing. What should take priority is thinking about whether the fundamental aspects of the economy and market have changed. When this is the priority, our fear diminishes as we realize that earnings are still strong, nonfarm payrolls on February 2nd were above expectations, and a deregulatory environment is still present.
One metric, the yield curve, is worth looking at though. The spread between the 10-year Treasury yield and the 2-year Treasury yield has been constantly decreasing as a result of the Federal Reserve tightening policies and the lack of inflation. On a basic level, you can note that the presence of an inverted yield curve, if it were to happen, has been a common predictor of past recessions. Going deeper, the economic repercussions of the inversion are much more important. Consumers and banks are directly impacted. For consumers, the cost of credit increases, which leads to a larger portion of expendable income being dedicated to servicing debt. For banks, the spread between long-dated loans and deposits decreases, which leads to worse financial performance. We’re sharing this information so that you can keep the yield curve on your radar, but there’s no need to worry as of now. When the curve inverted in the past, it still took between 7 to 24 months to reach any sort of recessionary state.
AllianzGI Equity & Convertible Income Fund (NIE: $20.59, down 4%) fared slightly better than the S&P’s drop of over 5%. It moved from the weekly low of $19.50 to its current level after recovering about 2.5% in the last hour of trading on Friday. The performance of individual equities which it holds, including Microsoft, Alphabet, and Amazon, led to the recovery in the last hour. Given that the fund invests little in the bonds and the scenario of the inverted yield curve, we can expect the funds to be shifted from Equity to Bonds.
We still see Apollo Commercial RE Finance (ARI: $17.70, down 3%) as a cyclical play on the U.S. commercial real estate sector. Given that commercial real estate in the U.S. remains solid, with Apollo’s loan originations hitting $1.5 billion YTD and the economy of the US continuing to get stronger and stronger, Apollo is not a position to be worried about.
Digital Realty Trust (DLR: $102, down 5%) dropped almost by the same amount as the S&P. This was the opposite of the week prior, where the company maintained strength in the midst of widespread declines. While we noted the continued demand for data centers in the last summary, there are some other metrics to note. Digital Realty, owning many data centers in US and internationally, is affected by rising interest rates as the cost of borrowing rises. The company has a massive debt level of $5.8 billion with a Debt/EBITDA ratio of 22. Rising interest rates could cripple the company’s dividend payout and future prospects.
Invesco Municipal Trust (VKQ: $11.83, flat) ended up at the same level as the beginning of the week. With its investments primarily in investment grade U.S. municipal bond obligations (85%), the fund can expect to yield better returns amidst the current rising interest rates scenario. Also, a Fitch report stating that plans to cut federal funds to them won't impact the revenues of the municipal bond funds and ETFs, played a large part in keeping the fund’s price level stable. Nuveen Municipal (NVG: $14.43, flat), another high yield fund with major investments in U.S. investment grade municipal bonds, also maintained its price level.
Pimco Dynamic Fund (PDI: $30, down 1%) was less volatile. The firm, investing primarily in a range of debt securities, including mortgage-backed securities, high yield corporates, and emerging market bonds, could witness further issues with rising interest rates, changes in tax structure, and better yields.
The REIT sector has been partially impacted by the recent economic data, heightening fears of higher interest rates. Primarily, the sector is engaged in massive borrowings, and rising interest rates could increase the cost of the borrowings. With that said, rising interest rates often occur in a booming economy, which indicates higher demand by consumers.
Market corrections generally provide prudent investors with great buying opportunities. One way of going about this is finding relative strength in strong industries. Applying this analysis to REITs, the overall REIT sector was down only 3%. Within out portfolio, three of the five positions outperformed the sector. Annaly Capital Management (NLY: $10.21, down 1%), Government Properties (GOV: $16.37, down 1%), and Omega Healthcare Investors (OHI: $26, flat) composed that group.
As a company that primarily engages in buying mortgages and mortgage-backed securities (as well as other assets), Annaly could fare very well as interest rates go up and correspondingly coupon rates do as well. While this is not necessarily the reason for the less-than-average drop this week, going forward it is something we will keep in mind. Both Government Properties and Omega should not feel a significantly negative impact by rising rates either. The former gets offered attractive rates by the government as a result of its leases and the latter’s healthcare-related real estate is, for the most part, unaffected by the business cycles.
The other two positions, Ventas (VTR: $52, down 5%) and Welltower (HCN: $55, down 5%), ended up having declines that were in-line with the S&P 500 but larger than the move in the REIT sector.
Ventas reported positive 4th quarter earnings on Friday, which provided a minor boost to the stock. The reported income from continuing operations for 2017, $640,000, was a record for the company. In turn, the EPS and FFO per share numbers were also records. In a rising rate environment, this is a positive sign. With the earnings report occurring during a stock market decline, any overall S&P bounce should result in outperformance by Ventas.
The other relatively weak company, Welltower, did not have any news this week to explain the larger than average decline in the stock. As it is focused on owning senior living properties and funding real estate infrastructure, the large amount of debt maintained could pose an issue within the rising rate environment. Currently, though, the extensive track record of stock appreciation over the past 25 years leaves us unworried. Welltower is also at the lower end of its range for the past four years, so it is a good area to pick up more shares.
Good Investing,
Todd Shaver, Founder and CEO
The Bull Market Report
Since 1998
February 7, 2018
by Todd Shaver | Feb 7, 2018 | Earnings Preview 6 AM
Carlyle Group (CG: $24)
Bull Market Report Target Price: $28
Bull Market Report Sell Price: $24
Earnings Date: Wednesday, 8:30 AM ET
Consensus: 4Q17
Revenues: $780 million
EPS: $0.62
Year Ago Quarter Results
Revenues: $435 million
EPS: $0.02
Key Things to Watch For in the Quarter
Analysts expect The Carlyle Group to report a 79% increase in revenues with a huge increase in earnings per share for 4Q17. The stock has beaten analyst estimates in three of the past four quarters, and is up 43% since this time last year. The Carlyle Group is an investment firm specializing in direct investments in the Fintech Sector. We do not expect the recent selloff to have a grave effect on the stock because of the firm’s concentrated line of business.
--------------------------------------------------------------------------------------------------
Synaptics (SYNA: $41)
Bull Market Report Target Price: $54
Bull Market Report Sell Price: $35
Earnings Date: Wednesday, after market close
Consensus: 4Q17
Revenues: $430 million
EPS: $1.09
Year Ago Quarter Results
Revenues: $460 million
EPS: $1.49
Key Things to Watch For in the Quarter
Synaptics is expected to report a 7% decrease in revenues and a 27% decrease in earnings per share for 4Q17. Despite having beaten estimates in the past four quarters, the stock is down almost 30% since this time last year. We expect the firm’s underlying technology and management team to spur growth over the long-term horizon. Our Target is $54 and our Sell Price is $35.
--------------------------------------------------------------------------------------------------
Tesla (TSLA: $334)
Bull Market Report Target Price: $375
Bull Market Report Sell Price: $335
Earnings Date: Wednesday, 5:30 PM ET
Consensus: 4Q17
Revenues: $3.3 billion
EPS: -$3.10
Year Ago Quarter Results
Revenues: $2.3 billion
EPS: -$0.69
Key Things to Watch For in the Quarter
Analysts expect Tesla to report a 43% increase in revenues and an increase in the earnings deficit for 4Q17. Despite beating estimates in only one of the past four quarters, the stock is still up 27% this year, and that includes the recent sell-off. We expect Elon Musk to continue to drive top line growth as the economy continues to strengthen and electric cars continue to penetrate our roads.
But as we have mentioned we are worried about the capital that Tesla will need to sustain its growth. So we have a Sell Price in place of $335. With the latest market fall-off, the stock dropped from $354 to $333 on Monday, quite a bit below our Sell Price. The Sell Price is there for YOU to decide what to do. Sell? Hold? Buy more? We love this company but with the production delays and thus little money coming in, we're a bit concerned. We may have an update about the firm in the next few days.
--------------------------------------------------------------------------------------------------
CBRE (CBG: $42.50)
Bull Market Report Target Price: $52
Bull Market Report Sell Price: $40
Earnings Date: Thursday, 7:00 AM ET
Consensus: 4Q17
Revenues: $4.0 billion
EPS: $0.92
Year Ago Quarter Results
Revenues: $3.8 billion
EPS: $0.93
Key Things to Watch For in the Quarter
CBRE is expected to report a 6% increase in its revenues and a 1% decrease in its earnings per share for 4Q17. The stock is up 33% on the year, and has been at the forefront of its peers in the real estate industry. CBRE has beaten estimates in each of the past four quarters which helps explain the firm’s bull run. The stock took a pretty heavy hit early this week when investors shaved 10% off the market cap. We believe it has been oversold, especially given the strong economic growth and investor’s natural fear of real estate when markets turn south. We are big believers in CBRE and would accumulate shares here.
--------------------------------------------------------------------------------------------------
Ventas (VTR: $53)
Bull Market Report Target Price: $72
Bull Market Report Sell Price: $58
Earnings Date: Friday, 10:00 AM ET
Consensus: 4Q17Revenues: $875 million
EPS: $0.63
Year Ago Quarter Results
Revenues: $875 million
EPS: $0.58
Key Things to Watch For in the Quarter
Ventas is expected to report no growth in revenues and an 8% increase in earnings for 4Q17. Despite Ventas’s ability to beat estimates in each of the past four quarters, the stock is down 15% since this time last year. The stock currently yields a 6% dividend, and has developed a trend for earnings growth. While some investors are selling the stock due to a lack of revenue growth, we are confident in the ability of management to cut costs and produce growth their bottom line.
January 28, 2018

by Todd Shaver | Jan 28, 2018 | Weekly Newsletter 7pm Sunday
The Weekly Summary
The big news this week was Davos. Davos is an annual event hosted by the World Economic Forum that’s mission is to improve the state of the world by engaging business, political, academic, and other leaders of society to share global, regional and industry agendas. Davos is a mountain resort in the Alps of Switzerland. All of the top brass from companies and countries attend. Trump rocked the party with his message of America first. He said America first does not mean America alone, and that America is open for business. He promoted our 3% GDP growth, our massive tax reform, and our historic reduction in regulation. We put a billionaire in office exactly to do this. The S&P 500 is already up 6% so far this year and Trump’s deals in Davos could drive gains higher.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight: Gilead, Shopify, Bristol Myers, Nutanix, Google, and Tesla.
Key Market Measures
BMR Companies & Commentary
Gilead (GILD: $86, up 6%)
Gilead has had a tough time since 2015; however, its fortunes may finally be changing. The big event is that Celgene is buying Juno Therapeutics for a 50% premium. One of Juno’s most promising drugs directly competes with Gilead. Clearly, Gilead is playing in the right sandbox. The Wall Street research firm Jefferies poured some gas on the fire of excitement now burning for Gilead. They upgraded the stock this week and said to look for good things to happen soon. The company is looking at a February approval and launch of a drug for HIV, and highlighted some key Phase 3 data on another drug to be released by 2019.
BMR Take: The stock appears to be inexpensive at this level, as it trades at just 8x this year’s EPS of $8.70. But we know that earnings are set to decline to $6.50-$7.25 over the next few years as Gilead’s top two drugs face declining sales. These two drugs were among the top three best sellers of all time – but nothing lasts forever. Could Gilead fetch 15-20x EPS when the dust settles and new drugs re-invigorate some excitement? Possibly, but it’s going to take quite some time.
As you may remember, we had the stock in our portfolio and removed it a year ago as we were tired of waiting. It took a year to come back, but from here we think the run is over for at least the next few years. We will remain on the sidelines.
=========================================================
Shopify (SHOP: $129, up 12%)
Somebody stopped by Shopify this week to work on collaboration for the future of augmented reality. Tim Cook. CEO of Apple. No big deal. (HA!) He praised the companies “profound” emerging technology. No further explanation needed. Apple + Shopify = $1.8 billion added to Shopfy’s market cap, now at $13 billion. Wow.
BMR Take: Tim Cook met with developers and coders and listened to demonstrations. Augmented and virtual reality is a major part of Apple’s future plans. These markets are likely to balloon to $215 billion by just 2021. Maybe Apple works with Shopify. Maybe Apple buys Shopify. Either way we see this all leading to good things ahead for Shopify. Their sales are expected to grow from $660 million this year to $1.6 billion by 2020, without factoring in anything from the possibilities with Apple.
Andrew Left of Citron is crying in his beer. (He’s the guy who shorted the stock at $119 and made a big deal about it in the press. He drove it down to $92, and now is losing money big-time. YES!!! We don't like the way this guy operates.) Remember, if you hear that a stock is heavily shorted, that’s a BULLISH signal. Why? Because after you short a stock the only thing you can do from that point on is to BUY THE STOCK BACK. Very bullish.
Look at this chart:

=========================================================
Bristol-Myers Squibb (BMY: $64, up 3%)
Bristol-Myers received a big regulatory approval in Europe this week. The European Commission (EC) expanded the indication of Yervoy to include treatment of advanced melanoma in pediatric patients. The EC approval marks Bristol-Myers’ first pediatric indication for an Immuno-Oncology medicine in the European Union and allows for the marketing of Yervoy for this indication in all 28 Member States of the EU. This is just a key development for geographic market expansion and ultimately sales. Hip hip hooray!
BMR Take: Bristol-Myers is a leader in Immuno-Oncology. This space is red hot. Bristol’s EPS is expected to grow from $3.00 this year to $4.00 in 24 months. This Healthcare bellwether is overdue for a breakout in the stock. Remember, activist Carl Icahn is making some noise here and pushing for good things for all shareholders.
Looking at the 1-year chart, you can see that it is a slow mover, but steadily up. We’ll take that any day. The company is no small firm. The market cap is $105 billion and the stock is moving towards its all-time high of $74 set two years ago.

=========================================================
Nutanix (NTNX: $33, down 8%)
Nutanix caught some heat this week from a downgrade at JP Morgan. The report said nothing specific. They said: The market rally has gone on for eight long years. Valuations aren’t cheap. Nutanix is up a lot lately.
We say: Ignore this report – it appears to be just one person’s opinion. We believe there is more money to be made here. In fact, just this week Nutanix spoke to investors about how hosting providers like Amazon Web Services are taking steps to work with customers more broadly to support bare services, expanding the market opportunity for Nutanix.
BMR Take: Nutanix is a must-own stock. “The opportunity of a decade,” says Goldman Sachs. The customer base has doubled in 18 months. The average annual sales per customer is expanding from $1 million to $5 million, fueling greater than 30% top line growth. And we could see this $5 billion market cap company get bought by the likes of an IBM or Oracle any day. The stock is down this week to where it was in December. But in October, just three months ago, it was $22. Stay on this train!
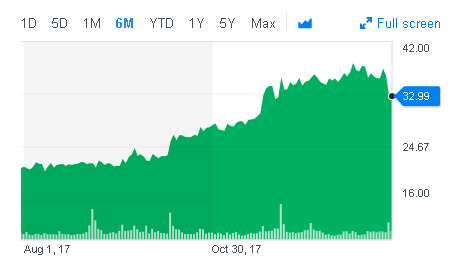
More on Nutanix below.
=========================================================
Google (GOOG: $1,176, up 3%)
The future of the Smart Home is a big deal. Whoever wins this market is going to make some big bucks. Google Home is now installed in 14 million homes and is well on its way to cementing itself as a key player in the space. The Smart Home of the future will allow you to use voice to control your thermostat, your TV, your lights, your locks, your security cameras, your car ignition, your coffee machine, and on and on. The hardware sales and the multi-year services contracts make for a lucrative revenue opportunity. Google is positioning itself to get in on the action.
BMR Take: One thing we really like about Google is its valuation. When you look elsewhere in Tech – like Facebook, Amazon, Netflix, or Adobe – the price to earnings ratios are way up there. Look, we understand growth and innovation can’t be valued just on a price to earnings ratio alone. But that subjectivity in the analysis leaves room for the high flyers to be in for a rougher valuation reversal in a correction. In contrast, Google is set to generate about $42 of EPS in 2018, which is 29% growth from 2017, and the price to earnings ratio is exactly 29. When the price to earnings ratio is equal to or is less than the earnings growth rate you know as an investor you are paying a reasonable price for growth. Again, that is why we like Google’s valuation.
And again, please have no fear of the high stock price. It’s just a number. Pretend that it has a 20-1 split tomorrow. The price would drop to $59. Would you buy more then? It’s all psychological. Google HAS split their stock 2-1 – once – in 2014. They just might be thinking of doing that again. And we would suggest the stock would shoot higher.

=========================================================
Tesla (TSLA: $343, down 2%)
Tesla’s Gigafactory is exciting! Tesla’s mission is to accelerate the world’s transition to sustainable energy through increasingly affordable electric vehicles and energy products. To achieve its planned production rate of 500,000 cars per year by 2018, Tesla alone will require today’s entire worldwide supply of lithium-ion batteries. The Tesla Gigafactory was born out of necessity and will supply enough batteries to support Tesla’s projected vehicle demand.
Tesla broke ground on the Gigafactory in 2014 in Nevada. The name Gigafactory comes from the word “Giga,” the unit of measurement representing “billions.” The factory’s planned annual battery production capacity is 35 gigawatt-hours (GWh), with one GWh being the equivalent of 1 billion watts for one hour. This is nearly as much as the entire world’s current battery production combined. With the Gigafactory ramping up production, Tesla’s cost of battery cells will decline significantly through economies of scale, innovative manufacturing, reduction of waste, and the simple optimization of locating most manufacturing processes under one roof. By reducing the cost of batteries, Tesla can make products available to more and more people, allowing them to make the biggest possible impact on transitioning the world to sustainable energy.
BMR Take: Seriously. Who builds a Gigafactory in Nevada because their business is using up all of the world’s lithium-ion batteries? Only Elon Musk. So innovative. So groundbreaking. World changing. If Tesla is right about the future of vehicles and takes over the crown of the auto industry from the old guards in Detroit, you don’t want to miss out on the future earnings potential of the company and what this stock could do in your portfolio.
As noted last week, we do have a $335 Sell Price on the stock because of our concern about how much capital they will have to raise this year. It would upset us to have to sell this wonderful company run by a genius, but we have to protect our gains. Watch closely this week.
Note on Musk’s New Pay Package:
Tesla announced a huge pay package this week for Elon Musk that again ties his compensation to key performance benchmarks. This time the goals include taking the electric-car maker to $650 billion in market value
Tesla outlined a massive compensation plan for its unorthodox CEO on Tuesday, setting a series of ambitious growth targets that, if various conditions are met, could net Musk as much as $55 billion over the next decade The package is based entirely on performance, guaranteeing no salary and no bonus, and requires Musk to reach aggressive market capitalization and financial goals in order to be paid. He would also have to hold onto his shares for five years after he receives them before selling. Musk would only receive the full payout if the company reaches a market capitalization of $650 billion, a more than 11-fold increase over its current $57 billion market cap.
=========================================================
=========================================================
Economic Calendar
Consumer Confidence
Tuesday, January 30th, 10:00 AM
Period: January
Consensus: 122.1
Prior: 122.1
Pending Home Sales
Wednesday, January 31st, 10:00 AM
Period: December
Consensus: 109.5
Prior: 109.5
Nonfarm Payrolls
Friday, February 2nd, 8:30 AM
Period: January
Consensus: 172.5K
Prior: 148.0K
=========================================================
=========================================================
We got a letter about Nutanix from Stanley Makovsky, of Stan Lee Marketing, one of our subscribers. He said:
"Todd,
Any opinion on the below report?
Nutanix Stock Falls After J.P. Morgan Warns That Software Shift Could Prove Disruptive"
Stanley Makovsky
Stan Lee Marketing
Hi Stanley – I many times take these things with a grain of salt. Yes, the stock is down 8%, but will it stay down here? Maybe. It might go to $30. But that just might be an amazing buying opportunity.
JP Morgan wrote this opinion based on this:
“on concerns that shares could lag those of peers in the near future following a recent rally.”
Lagging peers? What does that really mean? Who cares about their peers.
This is what matters to us:
The last four quarters of revenue:
$275 million
$226 million
$192 million
$160 million.
I call that growth.
Todd Shaver
=========================================================
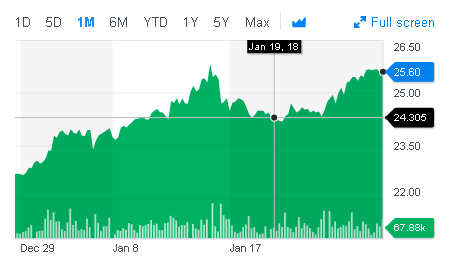
The Carlyle Group (CG: $25.60, up 5%)
We've been pounding the table on this stock for months. On December 19th the stock was $21.50. It's now at $26, up 21%. We are pounding the table on this one NOW. We expect $30 in a few months. Do the math. That's another 17%. We have it on good authority that one of the major stockholders is not selling a share until it hits $30. Our Target is $28, but we sure will be happy to raise it to $33 when it hits $28. The Sell Price is hereby raised from $20 to $24. We're up 54% on this one in less than a year; it's paying a 5% dividend. How can you go wrong.
Look at this chart:
=========================================================
CBRE (CBG: $46) Hits All-Time High
Friday saw another all-time high. Earnings are coming out soon and we understand that they will be announcing another solid quarter. Some say it might be called a blowout. We've passed our Target of $40 so we hereby raise it to $52. Our Sell Price is at $35, so we are raising that to $40. The company is in business to save corporations money with their real estate. And that they are doing with relish. This one is a sleeper.

=========================================================
=========================================================
The High Yield Corner
By Michel Foster
VP High Yield, The Bull Market Report
We wish to do a bit of a deep dive into what’s happening in stocks, the economy, and society at large - and what this tells us about high yield.
The reason we want to do this now is that there is a trend that looks very alarming on the surface that is actually not a problem at all. We’re referring to the incessant bull market of 2018.
January is ending in a few days, yet the S&P 500 is up over 6% already this year. Remember that this index goes up about 8% on average every year, so that a 6% gain in a month is very intense. So intense, in fact, that the market has already hit and surpassed the price target that a lot of big bank analysts had on the market for the entire year.
At the same time volatility is down, the financial mass media is getting more bullish, and the general anxieties in society seem to be drifting further and further away from economic issues and towards other domains of human life - politics, religion, identity. This is usually a cyclical trend.
To explain what we mean, think back to 2005 and 2011. Very different years with very different social concerns and economies. 2005 was the height of the housing bubble - a time when exotic dancers in Las Vegas were buying multiple homes to flip (as brilliantly documented in Michael Lewis’s The Big Short.) But Americans are a contentious bunch, so there was plenty of angst and debate going around - a lot of it about gender equality, the war in Iraq, Guantanamo Bay, race relations, and other things. Little talk about income inequality, wage growth, or other economic issues.
Now think about 2011. This was the time of the short-lived Occupy Wall Street movement. The Iraq War, still going on, wasn’t an issue; Guantanamo Bay didn’t come up unless you brought it up to the protestors. Race relations, gender issues were given brief lip service. But the real concern? Income inequality. “We are the 99%” was a rally cry of socio-economically disaffected people.
Whether or not you agreed with their message, their means or their complaints, doesn’t really matter - not for rational investors like us who want to grow our wealth by understanding what’s happening in the world. What matters much more is acknowledging what was going on and why it was going on. Namely, 2011 was a time when political and social unrest hinged on economic issues - because the 99% weren’t getting richer and weren’t even getting the illusion of getting richer that the debt-fueled housing bubble gave so many Americans.
Fast forward to 2018. What are the hot topics of the day? Donald Trump is the obvious one. And, again, whether you support Trump or do not, what does matter is acknowledging that the cultural fixation of the moment is on an issue that has relatively little to do with the economy.
From this perspective, 2018 feels a lot like 2005. The economy is, at least on the surface, showing enough strength to keep people from focusing on economic and financial issues. Corporate profits are rising and look to rise even further. Stocks are going up, as are housing prices and U.S. incomes. A weaker U.S. dollar is hurting imports, but it’s also helping exports and encouraging more tourism to the U.S. - another big boost.
What does all this have to do with the stock market and high yield investments? Two things. First, we seem to be at that stage in the business cycle where hope has already turned into optimism. But we aren’t at the point where optimism turns into euphoria, although it’s getting closer and closer on the horizon. In other words, a lot like 2005.
This tells us that the best thing to do is to buy and hold stocks. Stay in the market. Despite the monstrous gains in the market for 2018, the S&P 500 P/E ratio is down from where it was in the middle of 2016, and if earnings growth meets expectations (13% growth for the year), that P/E ratio isn’t going to go up much further.
It also tells us that high yield remains an option, but investors may become choosier when it comes to high yield as we go further into the greedy stage of the business cycle and away from the fearful stage. That could mean municipal bond prices will remain lower while junk bonds remain higher. That may mean little capital gains from Invesco Municipal Trust (VKQ: $12.30, flat) and Nuveen AMT-Free Municipal Credit (NVG: $15.09, down 2%) despite the fundamental strength in both funds’ incomes. Income may begin to rise if municipal bond yields rise alongside Treasuries. It does not mean a big crash in either fund, however - so don’t rush to sell. Just recognize that these funds’ income streams will remain intact, with some possible upside.
AllianzGI Equity & Convertible (NIE: $22.55, up 2%) and Pimco Dynamic Income Fund (PDI: $30, up 1%) are interesting options for investors. Since these funds have exposure to junk bonds and convertible bonds, the continued increase in profitability and financial strength among America’s companies could drive demand for these funds in excess of what we’ve seen in the past. Both have provided strong total returns since The Bull Market Report first recommended them. More good returns are becoming more likely, thanks to America’s increasingly complacent and euphoric economic mood.
Where does that leave us investors, concerned about volatility, wishing to preserve capital, and hoping for a reliable high income stream? It is too early to worry about a euphoric market, but it is time to recognize that worrisome euphoria and the bubbles they produce could come. That could take a couple of years, perhaps even longer. What matters is that we remain keenly aware of what’s happening in our economy and our society in an impartial and calm way, investing accordingly, and constantly looking, listening, and watching.
Good investing,
Todd Shaver
The Bull Market Report
Since 1998
January 21, 2018
by Todd Shaver | Jan 21, 2018 | Weekly Newsletter 7pm Sunday
The Weekly Summary
Time to get down to business. This week the US budget is in focus. The Senate rejected a one-month spending bill early Saturday, triggering the shutdown of many government services and setting off a partisan fight over who would bear the political consequences. The bill was blocked in a 50-49 vote, well short of the 60 votes it needed. After the vote, McConnell indicated he would take steps to set up a later vote on a 3-week spending bill, keeping the government funded through February 8th, but Senate Democrats are currently opposed to it, leaving lawmakers with no path to reopen the government. Fortunately, both chambers of Congress are expected to be in session Saturday, continuing discussions over how to resolve the underlying disputes over immigration and government funding. We are hopeful to see some progress made before the markets re-open on Monday.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight: Celgene, Microsoft, Splunk, Square, Cloudera and VMware.
BMR Companies & Commentary
Celgene (CELG: $103, down 3%)
Celgene is on a shopping spree to fill a looming revenue hole - a sensible course of action. The trouble is, there is no guarantee their purchases will solve anything. The biotech giant is in talks to acquire Juno Therapeutics (JUNO: $68, up 41%). This comes after Celgene announced the purchase of cancer startup Impact Biomedicines earlier this month for $1.1 billion upfront, plus significant milestone payments. Celgene, which already owns about 10% of Juno, would be acquiring a new kind of cancer treatment, known as CAR-T. The price tag of an outright purchase will be high - Juno’s market value approached $8 billion when trading opened on Wednesday and Celgene shares dropped Wednesday morning, which makes sense. CAR-T technology, which modifies and deploys a patient’s own immune cells to fight cancer, is a brilliant scientific innovation with highly uncertain commercial prospects. The treatment carries a high price tag and employs a complex, labor-intensive manufacturing process. When Gilead Sciences (GILD: $81) acquired Juno’s peer Kite Pharma over the summer, they warned that the deal wouldn’t contribute to earnings for about three years. Gilead and Novartis have programs that are already on the market, while Juno still is awaiting regulatory approval.
BMR Take: Celgene needs to take risks right now as some of their other pipeline drugs have not panned out as well as expected. For example, its best-selling product, the multiple myeloma drug Revlimid, is expected to face generic competition within a couple of years. Any erosion of the Revlimid business will sting. While financially speaking, Celgene can comfortably swallow Juno, the risk is that Celgene may soon have to open its wallet again to solidify its future.
Look, we get it, there are risks everywhere. We’ve had thoughts of throwing in the towel with Celgene. But the more we think about it, the more you have to stick with Celgene. Projections call for EPS of $8.80 in 2018 and $10.35 in 2019. Much of the bad news is already in the stock, as a major sell-off having recently occurred. Celgene is an $80+ billion large cap bellwether in Healthcare. They will figure this out. And when they do, we could be staring at big upside well in excess of standard market returns.
-------------------------------------------------------------------------------
Microsoft (MSFT: $90, flat)
Should the government break up large Tech companies? Standard Oil, American Telephone and Telegraph were the technological titans of their day, commanding more than 80% of their markets.
Today’s Tech giants are just as dominant: In the US, Google drives 89% of internet search; 95% of young adults on the internet use Facebook; and Amazon accounts for 75% of electronic book sales. Those firms that aren’t monopolists are duopolies: Google and Facebook absorbed 63% of online ad spending last year; Google and Apple provide 99% of mobile phone operating systems; while Apple and Microsoft supply 95% of desktop operating systems. A growing number of critics think these Tech giants need to be broken up or regulated as Standard Oil and AT&T once were. Microsoft has long dominated desktop operating systems, but has failed to extend that dominance to internet search or to mobile operating systems. It’s possible Microsoft might have become the dominant company in search and mobile without the scrutiny a federal antitrust case brought that opened the door for Apple and Google. Throughout history, entrepreneurs have often needed the government’s help to dislodge a monopolist - and may one day need it again.
BMR Take: We recognize this is a very real risk facing Microsoft and many of our other high technology companies. However, we see no near-term developments that suggest that anything materializes in 2018. Accordingly, we see compelling value in Microsoft as EPS is expected to grow from $3.40 this year to $4.50 in 2020. Without any major disruptions like an antitrust headache, we see this stock riding much higher.
Our Target has been $92 and it hit $92.80 on Tuesday, a new all-time high. With a market cap of close to $700 billion we expect to see $800 billion in the next 12-18 months. We’re going to leave our target at $92 for the time being, but we expect to raise it to $100 shortly.
-------------------------------------------------------------------------------
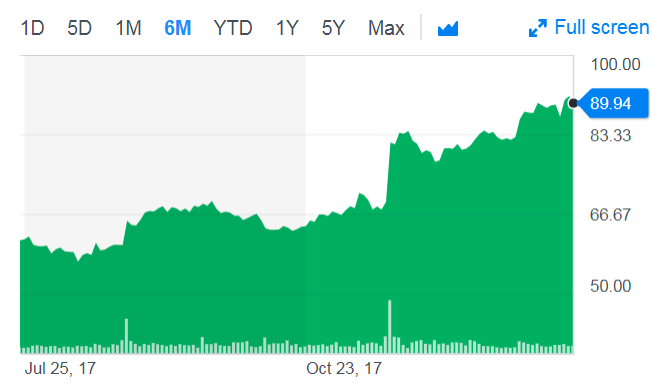
Splunk (SPLK: $90, flat)
Splunk, first in delivering “aha” moments from machine data, announced that Daimler, the German automotive group, will replace its legacy SIEM with Splunk® Enterprise and Splunk Enterprise Security (ES). The group will use Splunk ES as its nerve center for security analytics to gain security insights across the entire organization, including business critical environments such as vehicle systems and manufacturing lines. The company chose Splunk over open source alternatives as part of its strategy to buy best-of-breed solutions rather than building things in house. The automotive group will use Splunk ES to analyze multiple terabytes of data each day. The team expects to reduce security investigation times from hours to seconds, utilizing visualizations to improve analysts’ ability to explore and interrogate data as well as help spot and respond to issues more quickly to limit any potential impact to the business. By committing to a Splunk, the company is able to plan security for the future while benefiting from Splunk’s predictable pricing. The flexibility of the Splunk platform was also important; the group expects to realize future value from traditional IT use cases as well as in newly developed digital applications and services.
BMR Take: As digitization continues to transform industries and create new sources of security-relevant data, security strategies need to be built upon a strong data foundation. Splunk is very well-positioned in this megatrend happening around big data and artificial intelligence. This is a great example of how organizations are taking an analytics-driven approach and turning to Splunk software to do it. With EPS expected to grow from $0.60 this year to $1.30 in 2020 and $2.10 in 2021, there is a really big thing happening at Splunk and you definitely want to be involved.
Our Target is $95 and our Sell Price is $74. We hereby raise the Sell Price to $83. We don’t want to lose our tremendous gains in the stock, having added it at $46 a year and a half ago.
-------------------------------------------------------------------------------
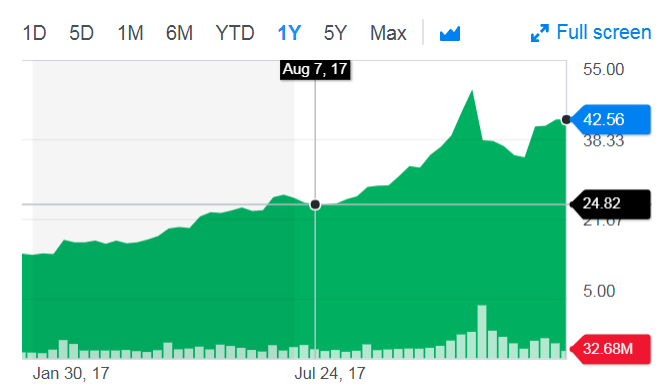
Square (SQ: $43, up 3%)
The meteoric rise in the price of bitcoin in 2017, from just under $1,000 to above $15,000 at year-end, has attracted the attention of investors around the world. Powered by the blockchain, the distributed ledger technology which verifies transactions without the need for third-party validation, the cryptocurrency made great strides during the past year in achieving acceptance by businesses willing to accept it as a means of payment. Investors are looking beyond bitcoin itself to find companies that stand to benefit from the growing usage of bitcoin for commercial transactions. Square. The has released a beta trial enabling users to buy and sell bitcoin on its cash app.
BMR Take: Bitcoin and the blockchain is a windowpane into what euphoria looks like. We haven’t seen this kind of excitement in the markets since the peak of the housing market last cycle. We’ll save a discussion of the future of bitcoin, blockchain, and cryptocurrency for another forum. All that matters is that Square has been caught up in the mix due to this beta cash app trial and investors have benefitted. While we remain optimistic that CEO Jack Dorsey can innovate and create great new products, we still don’t see any specific EPS contribution being called out from the bitcoin cash app, so just be aware. All of that might not matter too much anyway, as the company’s EPS is expected to grow from $0.25 this year to over $1.00 by 2020.
Square Price Target Raised to $64 from $48 at Nomura
This represents a 59% potential upside from current levels. A "looming positive inflection" in gross payment volume growth can help "ensure that 2018 will be yet another phenomenal year" for Square, the company said. Accelerating share gains from payment peers and "relentless disruption of services" like payroll and human resources will make Square a very different company in 10 years. They believe little of this upside is evident using conventional valuation methodologies. The analyst keeps a Buy rating on Square.
BMR Take II: We’ve been saying this all along of course and Square has been a big winner for us here at The Bull Market Report. We added the stock at $17 last year in March and it is up 150% in that short time. It is going a lot higher. Our Target is $45, but we expect to raise that soon. What Nomura said above is very interesting – they can’t value this company on “conventional valuation methodologies.” We’ve been trying to put this in words for you but Nomura has done it for us. The company is in a business that is sweeping the globe, is the clear leader, sells at a high multiple – we know, and is going higher in our opinion.
-------------------------------------------------------------------------------
Cloudera (CLDR: $18.45, up 2%)
Cloudera, the modern platform for machine learning and analytics optimized for the cloud, announced that it has been named a winner of two Internet of Things (IoT) Breakthrough Awards: the Overall Connected Car Innovation of the Year with Navistar, and Connected Car Insurance Solution of the Year with Octo Telematics. Cloudera Enterprise was recognized by this year's judging panel for empowering their customers, Navistar and Octo, to become data-driven enterprises with innovative solutions that combine data from (IoT) sensors, machine learning, and predictive analytics. The IoT Breakthrough Awards honor the world's top IoT companies, products, and people for the creativity, hard work, and success of their achievements.
BMR Take: This is a huge deal as we are sure you are well aware, of how big this mega trend of IoT, machine learnings, and predictive analytics is to the future of the market and our economy. We could rant and rave to you about our opinion of how good Cloudera is at it, but the industry itself just selected Cloudera as the best. This company will scale revenue from $350 million to nearly $600 million by 2020 and break the $1 billion milestone in the not too distant future after that.
-------------------------------------------------------------------------------
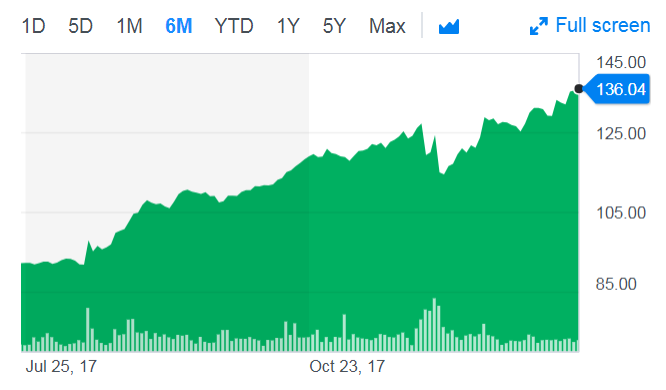
VMware (VMW: $136, up 3%)
This week at the National Retail Federation’s annual show, VMware highlighted several customers who have deployed their technology to modernize data centers, integrate public cloud solutions, empower the digital workspace and transform networking and security. The velocity of change in retail IT is making recognized brands rethink their IT strategies and consider cloud as a way to speed delivery. VMware helps create a foundation of shared technologies to serve both digital and in-store needs to create a connected retail environment. For example, one of the UK's largest furniture producers - DFS - moved to a scalable cloud-first infrastructure powered by VMWare. With this solution, the retailer said it can handle spikes in online traffic year-round with ease.
BMR Take: We continue to see so much potential for ecommerce and companies that are part of the explosive growth still occurring. VMware is expected to increase EPS from $5.15 this year to over $6.00 by 2020. The company's steady business model as an IT vender provides great visibility and a reliable source of earnings that will benefit your portfolio.
Our Price Target is $137, so we are oh so close. The Sell Price is $118, so we hereby raise it to $128 – again, so we don’t lose these great profits, having added the stock at $83, exactly a year ago. 64% is solid, don’t you think?
-------------------------------------------------------------------------------
Economic Calendar
Richmond Fed Index
Tuesday, January 23rd, 10:00 AM
Period: January
Consensus: 17.5
Prior: 20.0
Existing Home Sales
Wednesday, January 24th, 10:00 AM
Period: December
Consensus: 5,700,000
Prior: 5,810,000
GDP
Friday, January 26th, 8:30 AM
Period: Q4
Consensus: 2.5%
Prior: 2.3%
-------------------------------------------------------------------------------
-------------------------------------------------------------------------------
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
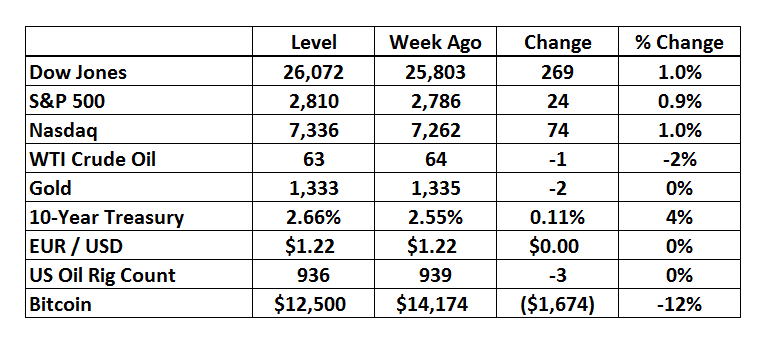
UBS recently upped our estimate of S&P 500 earnings for 2017 from $131 to $133, and increased our forecast for 2018 earnings from $151 to $154 (last week Bank of America estimated 2018 earnings at $153). Also, UBS estimated earnings for 2019 would come in around $162. These are numbers which will obviously be revised as we go through the next two years, but they give at least a reasonable base line for valuing the current market based on earnings. The S&P 500 ended the year at 2674, which would mean it was trading at 20X trailing earnings and 17.3X forward earnings. Today, at 2810, it is trading at 18X forward earnings and 21X trailing earnings. As you see, the higher it goes, the higher both the trailing and forward PE's become. However, if the market trades at 20X trailing earnings at the end of 2018 as it just did last year, the S&P 500 would be at the 3080 level ($154 X 20). This is 10% higher than today, and that would make for another very good year in the market.
Apple is a one-company global economic stimulus plan. Apple plans to invest $350 billion in the U.S. economy along with paying $38 billion in repatriation tax as it brings back over $200 billion from overseas. Apple is also granting $2,500 in restricted stock units to all non-director level employees including retail employees at its stores. The tax reform bill again drives all these actions.
China reported that Q4 GDP growth increased 6.8% YoY which is slightly above the 6.7% consensus and in line with the 6.8% increase in Q3. China’s full year 2017 growth rate was 6.9% which is significantly above the government’s growth target of 6.5%. Expectations for 2018 are for another year above the 6.5% target growth rate. China’s strong GDP growth remains the world’s economic growth driver. This is good news for both the U.S. economy and the U.S. stock market.
-------------------------------------------------------------------------------
-------------------------------------------------------------------------------
Update on BlackRock
BlackRock (BX: $590, up 6%) brought in $1 billion every day of the year in 2017. (On average of course.) Now THAT is amazing. And the $6 trillion in assets is amazing too, having added $1 trillion last year. They are the largest by far. Most of this money went to its iShares division, the ETF group. as investors are flocking to these indexed investments. Profits were big last year too as the income of $2.3 billion or $14 a share, compared with $850 million the year before, or $5.10 a share. Revenue was up a solid 20%.
We added the stock at $415 in August of last year, about five months ago, and we are sure some of you groaned that it was another high-priced stock that is hard to swallow. We tried to convince you not to worry about the stock "price" and we hope we did. We can see a stock split coming this year. Wouldn’t it be nice to see this thing split 5-1 and bring the price down around $100? You bet. If we were running the show and not Larry Fink, we would do a 10-1 split! Down to $50 a share. Well, even if that doesn’t happen, we can see this stock at $700 someday.
BMR Take: Guess what? We like this company. $590 was our Target. We are raising it to $650 now, and raising the Sell Price from $470 to $550.
-------------------------------------------------------------------------------
Tesla Update
Last week we were worried that Tesla (TSLA: $350) might drop due to all of the financing needs it faces this year and next. So we raised the Sell Price to $320 to protect our gains. Well the stock rose $14 or 4% to our Target Price of $350. Now what?
Good question. We are going to raise the Target to $375 and raise our Sell Price to a tight $335 and sit back and watch. We love this company, we love Elon Musk, but his delivery problems are making us nervous. This stock is going to $500 or $200. We just don’t know which one will hit first! So be careful with this great concept company.
-------------------------------------------------------------------------------
The High Yield Corner
By Michael Foster
Vice President High Yield
Ventas (VTR: $54, down 1%) was strong last week, but still sitting with a year-to-date loss of over 9%. That is a massive loss in a very short period of time. At the same time, both the REIT sector and the market as a whole are doing much better, which makes the situation with Ventas even more worrisome.
Let’s dig a bit deeper to understand what’s going on and how to respond.
Ventas has not released any news, and nothing particularly newsworthy has happened either to Ventas or to the Healthcare REIT world. The selloff, which really began in earnest back in September, has gained significant momentum in the last couple of weeks despite no news. Sales volumes, however, have increased significantly in the last two weeks, indicating that the number of sellers who are worried about Ventas’s future have increased.
This, then, is a typical market panic.
Market panics are rarely justified, and this is unjustifiable, too. Ventas increased its dividend in December slightly, and with the recent price collapse that means the stock is yielding close to 6%. Ventas has not yielded this much since early 2016. If an investor had bought at that time, their total return from then to now would be 9.6% - but much more importantly, their income stream would have gone up.
The reason for this is that Ventas is covering its dividends by a wide margin. The company’s dividend coverage ratio at its new dividend payout is 132% - just above the 130% level that readers know we prefer for REITs. This means that the dividend is well covered by rental income and is in no danger of being cut.
Yet it’s yielding near 6%, which is the market’s way of saying that the payout is in jeopardy. The market is wrong.
If the high dividend coverage ratio wasn’t enough to prove the market is wrong, let’s consider some recent disclosures from the company. The company’s senior housing property occupancy rate increased last quarter, reaching 88.7%. While that is slightly low (90% is typically the standard REITs aim for), the fast-expanding senior housing industry has faced a lot of headwinds from intense competition and looming bankruptcies or insolvencies from tenants who are poorly managing their businesses. For Ventas to get through these problems with an 88.7% occupancy and over 130% dividend coverage is a testament to management’s acumen and savviness.
Then there’s the life science portfolio - a part of Ventas that has seen the most aggressive growth. The numbers are breathtakingly good. Total occupancy is 97.5% and has remained at that level despite the company’s expansion. 75% of rents come from investment-grade tenants, and rents in the industry continue to rise.
Medical offices, another fast-growing part of Ventas’s more diversified strategy, have also seen strong, encouraging numbers. This arm of Ventas saw 91.8% occupancy rates and 80% tenant retention rates. These are high numbers for any REIT industry, but they are very high for healthcare REITs. Obviously, Ventas is doing a lot right.
So why is it crashing? Two reasons: SNF panic and the Fed.
Let’s start with the Senior Nursing Facilities panic, since that has hit Omega Healthcare Investors (OHI: $26.50, up 1%) for a long while. Omega’s 1% rise last week for a good showing for a stock that’s been beaten up a lot in the last few months. The reason, as we’ve discussed here repeatedly, is the looming bankruptcy or rent renegotiation with one of Omega’s big tenants.
Ventas does not have these problems.
Thanks to Ventas’s higher quality tenants, the company isn’t facing major declines in its cash flow from bankrupt tenants. That’s why the stock has always had a yield near half that of Omega. But recent sell-offs are coming from investors who are scared anyway, worried that the problems with some SNF operators are coming to the rest of the REIT universe. There’s no reason to believe this is the case.
A second and arguably much bigger specter that is hitting Ventas and REITs more broadly is the concern about the Federal Reserve. Interest rates are clearly going to go up three times this year. Even more rate hikes are a possibility, unthinkable a year ago. Aggressive hikes in interest rates are bad for REITs, because they cause debt costs to go up. Since REITs effectively work by arbitraging low interest rates on long-term loans and the higher rates buildings can get from rents, the higher rates theoretically cut into REITs’ profit margins. That is, however, if rents don’t go up.
But, as we all know, rents go up all the time. And, in fact, rents tend to go up faster in better economic times, because there’s more money floating around to pay rent and more demand to rent spaces. Thus, rising interest rates, while in theory bad for REITs, are only bad if they are not met with a commensurate rise in rents.
Rents are going up in America, although admittedly they are not going up as fast for SNF facilities. So there is a risk there, but the risk was priced into both Omega and Ventas at the end of 2017. Now instead of pricing in the risks of cash flow getting cut by 5% or so, we’re seeing the market price in a risk of a 20% or 30% reduction to cash flow. The math makes no sense. It’s impossible for these REITs to see such a major disruption to their cash flow unless there’s a really horrible recession AND the Fed keeps raising rates. But the Fed doesn’t raise rates when the economy is doing poorly. So. the market is pricing in a hypothetical that is impossible. And that is when assets get oversold, underpriced, and a bargain. That is the situation with Ventas and Omega right now.
Good Investing,
Todd Shaver, Founder and CEO
The Bull Market Report
Since 1998