August 25, 2023

by Scott Martin | Aug 25, 2023 | Weekly Newsletter 7pm Sunday
Market Summary
It's been a bumpy couple of weeks, but baby bull markets tend to sputter a little sometime between the 60- and 120-day mark. With that in mind, this test of investors' courage seems almost foreordained in terms of where it fits in the larger Wall Street cycle. Yes, things were going extremely well. Yes, stocks were racing back to the levels they comfortably commanded before the pandemic inflated and then deflated a bubble. And yes, that rebound is largely justified. We just need to test that justification in order to shake off our residual trauma from the bubble collapse; and the last few years in general.
This is how stocks normally behave. If the bull market has hit a wall this early, it will be the shortest significant rally in modern history. Bull markets generally run for 5-6 years and even in the depths of the Great Depression, the recovery was both more robust and more sustained. Granted, we live in unusually unsettled times, but sooner or later every statistical aberration reverts to the long-term trend. For the S&P 500 and large stocks in general, that means moving up 8-11% a year across the long term. And for Treasury yields, that means about 1% above inflation.
Keep that last part in the back of your head when people try to tell you that 4% bond yields are poison for the stock market. Across generations, inflation has averaged a little over 3% a year. Adding a full percentage point to that "normal" historical level gives you a number above 4%, which means this is where long-term yields should be. If anything, with the latest read on consumer prices coming in at 3.2%, both inflation and interest rates are exactly where they should be under normal circumstances.
Of course, accepting this argument means letting go of a lot of assumptions and expectations that have accumulated over the last 10-15 years. Extremely low interest rates were a historical aberration left over from the 2008 crisis. They needed to come back up, for a lot of reasons. Whether the trigger that gets them back on track is the Fed or a sudden Treasury credit downgrade is secondary. And stocks have historically rallied in the face of exactly this kind of interest rate environment. This is a market fact. Unless you think something fundamental has broken within the American psyche that will prevent us from rising above all current obstacles like we did in the wake of the 2008 crash, or the dotcom crash, or 911, or World War II, or the Great Depression itself for that matter, the numbers are on our side.
In the meantime, the numbers are not great, but they aren't terrible either. The S&P 500 is up 16% YTD, which is accelerated performance when you look at the statistics. Granted, a lot of investors still have wounds left to heal before they really start feeling good about their experience in the last few years, but things are still moving fast in the right direction. The Nasdaq is up a blistering 30% in barely 7 months. Our stocks, balanced between a strong defense and plenty of aggressive growth recommendations, are right in the middle. We've scored a 22% bounce so far this year. In just another 7 percentage points, we'll be back where we were at the end of 2021 ... right before the zero-rate bubble started to rupture.
The big market benchmarks are in a similar state. Even counting the recent pullback, Wall Street as a whole hasn't exactly fallen off a cliff. Stocks are within sight of record territory. And as you know, these relatively rarefied levels near all-time peaks tend to be a little precarious. Investors and traders challenge every move. The bulls need to fight for every inch. Sometimes we need a little time to build up our strength and go over each wall of worry in turn. But it happens. On average, the bulls run for 5-6 years before a real obstacle gets in the way and forces a major downswing. Across each multi-year run, the market as a whole tends to quadruple in value.
In other words, things look a long way from unsustainable or overheated. This is a pause, not a halt. Corporate earnings support this. This has been a mediocre earnings season but the mood has been more hopeful than depressed and a lot of investors have even showed signs of impatience. People can't wait to see the numbers on the current quarter and then guidance for the end of the year. There's a strong sense that by then, the Fed will be finished raising short-term interest rates, which means the pressure on the economy will not get much worse. And when things can't get much worse, they generally get better from there.
Inflation is no longer accelerating. The Fed is getting traction. Earnings across the S&P 500 are not great, but they aren't plunging either. At worst, the tone reads "stagnation," a stall instead of a swoon. That's not a hard landing. Unless the real cliff is coming, this is the soft landing we needed. The recession so mild that it barely even registers after years of disruption, upheaval and, most recently, an economy too strong for anyone's comfort. When investors run from signs of the job market running too hot, it's really a sign that we could all use a break. The economy needs to cool off. That's what the Fed is doing. The alternative is watching prices keep soaring indefinitely, which creates a vicious cycle in which the dollar ends up much lower. Nobody wants that. This is preferable. This is what normal feels like.
There's always a bull market here at The Bull Market Report. As earnings season winds down, the drama has shifted back to the bond market, which shifts The High Yield Investor into the spotlight as we work to explain how rising yields pushed our stocks back down 3% in the last two weeks. As a result, The Big Picture once again revolves around benchmarking the current stock market environment against history, and finds the results highly encouraging. And if you're still paying attention to earnings, we've got plenty of updates for you as always.
Key Market Indicators
-----------------------------------------------------------------------------
The Big Picture: From Baby Bull To Tempestuous Tot
If you’ve already written this bull market off for dead, we have to admit, you’ve given up on the stock market and we can’t help you. For this bull market to have been born in June and dead by August, the economic environment would need to be worse than it was in 1932, in the deepest depths of the Great Recession. That’s when the shortest bull market in modern memory happened. Back then, investors only got two months after rallying 20% from its peak before the bear recouped control of Wall Street. Those were truly bad times.
But even then, investors who bought the brief rally didn’t have a lot to complain about. That two-month rally sent the S&P 500 up a dizzying 91%. The brief but savage retreat that followed took about 30% off that peak, leaving the market roughly 55% off its low. Maybe you think the world is in worse shape now than it was 80 years ago and the market just no longer has what it takes to recover. In that scenario, you’ve effectively given up on stocks, the economy and the American people.
Because in every other crisis over the past eight decades, the bulls got years to run. Other than the 1932 shudder, the shortest modern bull market lasted 1.8 years, before the grim lead into World War II cut the rally short. Only the 2020-2021 pandemic bubble was anywhere near that truncated. It took real determination for the bulls to start running this time around. The mood bottomed out in October and it took eight months for the S&P 500 to recover 20% from that low point. During that period, it became clear that even the Fed’s aggressive rate hikes wouldn’t be severe enough to crash the economy immediately.
And in the absence of that crash, guess what? We survived. Corporations didn’t implode like people feared. A recession like the one we saw in 2008 didn’t happen this time around. We're thinking the recession is already well underway for corporations. Earnings are down from last year. But in the new third quarter, we’re looking for a slight uptick. Even if that doesn’t happen, the comparisons practically guarantee better times ahead for the end of the year. In that scenario, we’ve already lived through the worst of it. Things get better from here. In a few months, members of the S&P 500 will be getting bigger again in the aggregate. The economy will be growing.
That’s good for investors. It’s hard for stocks to go down for long when the economy is feeding more profit across big companies year after year, which is why bull markets are hard to kill once they get going. Admittedly, it isn’t a smooth ride. The first few months of any baby bull are the most intense. But then there’s generally a lull and a pause for the market to test its convictions. Things slow down. People get nervous and start second guessing themselves. But in history, the bull has never backed down this fast. History can bend, but it rarely breaks. If the bear takes over again, we'll be shocked.
Remember, bond yields move in the opposite direction from bond prices. If bonds are falling and rates rising, that means money is pouring out of that particular side of the global financial markets. Within the dollar sphere, money flowing out of bonds means money flows into cash or stocks. Cash is bad news as long as inflation remains high. You might be able to get 4% in money markets, but you’re probably going to lose it all from inflation. Only stocks can make enough right now to keep ahead of inflation. Some may go down instead but the right stocks have a fighting chance. When that’s the best bet you get, you take it. We have the right stocks.
-----------------------------------------------------------------------------
BMR Companies and Commentary
Moderna (MRNA: $101, down 6% last week)
Healthcare Portfolio
Get ready for a good long read on this extraordinary company. This is not a 1- or 2-minute read. It will be 5-10 minutes. So, hang on. Here we go.
Leading biotechnology company and mRNA pioneer, Moderna, released its second quarter results a week ago. The company posted $340 million in revenues, down by a colossal 94% YoY, compared to $4.7 billion a year ago. It further posted a loss of $1.4 billion, or $3.62 per share, against a profit of $2.2 billion, or $5.24. This was largely the result of the seasonal nature of its COVID-19 vaccine sales.
While this was expected as the world moves on from the pandemic, the company, however, expects $6 to $8 billion in revenues from its COVID shot this year, with the US alone expected to buy anywhere between 50 to 100 million doses for the fall. Its updated COVID vaccine, targeting the omicron subvariant XBB.1.5. Is still awaiting FDA approval, but will be ready for a rollout over the coming months.
The company is confident of seeing robust demand for the shot, not just in the US, but also in Europe, Japan, and other leading markets. With COVID-19 becoming ubiquitous, Moderna expects this great business to continue. Far from resting on its laurels, however, it has gone all out to ensure its pandemic windfall is used towards developing more sustainable products.
This includes a robust pipeline of vaccines targeting cancer, heart disease, and a slew of other conditions, and are all set to hit the market by 2030. This pipeline includes its experimental vaccine for respiratory syncytial virus, aimed at adults aged 60 and above, followed by its personalized cancer vaccine in partnership with Merck, which passed its first major clinical trial early last month, with flying colors.
The stock is down by 44% YTD and over 78% from its all-time high in 2021, and as such, is quite de-risked. It currently trades under 4 times sales and 35 times earnings, which might seem rich, but is perfectly justified for a growth stock such as this. It has since repurchased stock worth $1.5 billion and ended the quarter with $8.5 billion in cash, $1.2 billion in debt, and negative $230 million in cash flow. Our Target is $250 and our Sell Price is $150. SO, let’s discuss. These numbers are there for you to decide what to do. And each and every one of you has a different scenario of buying the stock. Some of you bought the stock in January 2023 when we added the stock at $193. Some of you bought the stock beforehand in February 2020 at $26. As the stock has come down from the all-time high of $464 in September of 2021, and more recently from the $218 level in January of this year, you have decisions to make on a day-to-day basis. And all of these decisions are personal, based on a myriad of things that are going on in your life. We could list them here, but you know what we mean here. It comes down to a decision that YOU have to make: Do I sell? Do I stay with it? Do I add more? Tough questions. We highly recommend GTC Stop Orders. Good-‘Til-Canceled orders are orders to sell a stock at a certain price. If it hits the number, the order executes and you are out of the stock. If you bought in January, you could have put a stop order in place to sell at say, $181. Or $171 or whatever price you picked. They used to call this order a Stop Loss order because that’s what it does. Now it is just called a Stop order.
We’re not real happy that the market has drubbed this company the way it has. But we believe in the firm long term, and since we are a long-term investment newsletter, we believe in the companies that we follow and if the stock moves lower, in many cases we like it even more than it was at the higher price. That is the case with Moderna. We would buy the stock here as they have a strong, diverse set of new products coming to market this year, in 2024 and 2025, and beyond.
The future looks bright for Moderna. The company has a strong pipeline of new products, including vaccines for influenza, respiratory syncytial virus (RSV), cytomegalovirus (CMV)*, and HIV. Moderna is also developing a personalized cancer vaccine that could revolutionize the treatment of cancer. The potential dollar size of these markets is enormous. The global market for influenza vaccines is estimated to be worth $8.5 billion, the RSV market is worth $2.5 billion, the CMV market is worth $1.5 billion, and the HIV market is worth $30 billion. Moderna could capture a significant share of these markets with its innovative products.
*CMV is related to the viruses that cause chickenpox, herpes simplex, and mononucleosis. CMV may cycle through periods when it lies dormant and then reactivates.
In addition to its new products, Moderna is also expanding its manufacturing capacity. This will allow the company to meet the growing demand for its vaccines and other products. Moderna is well-positioned to be a major player in the pharmaceutical industry for years to come.
Here are some specific examples of new products that Moderna has in the pipeline. The company is committed to using its mRNA technology to develop innovative new treatments for a wide range of diseases:
A bivalent influenza vaccine that protects against both influenza A and influenza B.
An RSV vaccine that is more effective than existing RSV vaccines.
A CMV vaccine that could prevent congenital CMV infection, which can lead to serious health problems in newborns.
A personalized cancer vaccine that is designed to target the specific mutations in a patient's cancer cells.
The company is worth $39 billion now. At its peak, it was worth $189 billion. Can it go there again in the future? We believe so.

-----------------------------------------------------------------------------
Axcelis Technologies (ACLS: $167, down 5%)
High Technology Portfolio
This company is one of the largest suppliers of capital equipment for the semiconductor industry, leading some industry observers to call it one of the most important companies in the world. During its second quarter, despite a glut in the Chip industry, the company has continued its strong streak, with $270 million in revenues, up 24% YoY, compared to $220 million a year ago. The company posted a profit of $62 million, or $1.86 per share, against $48 million, or $1.43, in addition to a beat on consensus estimates at the top and bottom lines. Its dominant position within this space, amid an industry that in many places has been turned upside down, has resulted in substantial tailwinds for Axcelis, something that is unlikely to subside even in the case of a glut in the market.
Axcelis Technologies ended the quarter with an order backlog of over $1.2 billion, including fresh orders of $200 million. This is largely the result of persistent demand for its Purion family of products, particularly from the silicon carbide power markets. These are semiconductors used in cars, particularly electric vehicles, which are growing fast around the world.
The company’s customers span markets of advanced logic chips, memory chips, and storage chips, all of which are set to witness robust demand, as a result of the unprecedented growth in AI, machine learning, and cloud computing. It is further the only ion implant company capable of providing full-recipe coverage for all power device applications, allowing for high-volume, low-cost manufacturing.
As a result, the company has increased its revenue forecast for the full year by $70 million, giving the stock that is already up by 115% YTD, more reason to rally. Axcelis has a strong balance sheet position with $450 million in cash, just $80 million in debt, and $250 million in cash flow. This puts many lucrative value-creation opportunities, such as dividends and stock repurchases on the horizon going forward. Our Target is $150 and our Sell Price is $125. We are raising the Target today to $195, and the Sell Price to $148.

-----------------------------------------------------------------------------
Roku (ROKU: $79, down 8%)
Early Stage Portfolio
Streaming giant Roku caught another break with its second quarter results a week ago. The company posted $850 million in revenues, up 11% YoY, compared to $760 million a year ago, with a loss of $110 million, or $0.76 per share, down from $112 million, or $0.82, in addition to a beat on consensus estimates on the top and bottom lines.
The company posted strong growth across key operational metrics, with total active accounts at 74 million, up 16% YoY, and reaching a level of 25 billion hours streamed on the platform during the quarter, up by 4 billion hours from last year. The Roku channel now accounts for 1.1% of total TV viewership, establishing it as a leading player in the global streaming space, with plenty of room to grow.
The platform’s average revenue per user slid 7% YoY, to $40.67, but this is mostly owing to a global advertising slowdown, which has since started to turn around, as recessionary fears abate. Roku is perfectly poised to reap rewards from this trend, given its dominance in the connected TV space with a market share of 50% in North America, and billions of dollars of unmonetized ad inventory.
Roku continues to face substantial challenges as a result of supply chain constraints and inflationary pressures, particularly when it comes to its hardware business. Its decision to not pass these additional costs onto customers is what led to the string of losses in recent quarters. This same strategy will pay off in the long run, as it faces stiff competition from the likes of Alphabet TV, Amazon, and Apple TV.
The stock is down by over 85% since its all-time high in 2021 but has posted a 95% rally YTD, amid substantial challenges and headwinds. It currently trades at under 3.5 times sales, which is very reasonable for a growth stock with a landed base and massive competitive moats. Roku ended the quarter with $1.8 billion in cash, just $650 million in debt, and $15 million in cash flow. Our Target is $110 and our Sell Price is $62.
With all of this said, we are not very happy about the fact that the company can’t make a profit. Yes, they have a ton of cash to tide them over the next year or two. But gee whiz, after all these years, WHY CAN’T THEY MAKE A PROFIT? We’ve always said to ourselves: When you are not happy about something, you have to take some action. We’re pretty darn tired of waiting for this one, so yes, their future looks bright, but the stock had better move higher, and if it doesn’t, we are going to move on. The way we like to do this is to set a Stop. We would suggest that you put a Sell Stop in place at $74. If it goes there, we are out. If it goes higher, we will move the stop up accordingly over time.

-----------------------------------------------------------------------------
PayPal (PYPL: $62, down 2%)
Financial Portfolio
PayPal released its second quarter results two weeks ago, reporting $7.3 billion in revenues, up 7% YoY, compared to $6.8 billion a year ago. The company posted a profit of $1.3 billion, or $1.16 per share, against $1.1 billion and $0.93. Despite posting in line with estimates, the stock witnessed a pullback following the results, owing to a slew of factors and operating metrics.
During the quarter, the company processed over $370 billion in payments, across 6.1 billion transactions, up 11% and 10% YoY, respectively. It processed 55 transactions per active account, an increase of 12% YoY, with total active accounts growing to 435 million, up marginally from 428 million during the same period a year ago. It is truly an astounding number of accounts.
PayPal is an online payment platform that facilitates payments between individuals and businesses. It is one of the most popular online payment platforms in the world. PayPal is successful because it is easy to use, secure, and trusted by businesses and consumers alike.
PayPal has a new deal with private-equity giant Kohlberg, Kravis & Roberts. According to this deal, the PE firm will be acquiring PayPal’s ‘Buy Now, Pay Later’ loans originated within the UK and other European countries, to the tune of $44 billion, with $1.8 billion in net proceeds to PayPal set to be realized over the next few months alone. This provides the fintech giant with much-needed liquidity and stability, as it forays deeper into the lucrative consumer credit markets. In addition to this, the company has seen enormous traction with its recent rollout of PayPal Complete Payments, onboarding big ticket channel partners, the likes of Adobe, WooCommerce, Shopify, Stack Payments, and LightSpeed among others.
As PayPal grows by leaps and bounds, it hasn’t lost sight of its promise to continue delivering exceptional value to shareholders, with $1.5 billion being returned via buybacks during the second quarter alone. It plans to scale past $5 billion in buybacks in 2023, giving strong support to the stock, while hardly denting its robust balance sheet, with $11 billion in cash, just $12 billion in debt, and $5.8 billion in cash flow. And the firm is quite profitable, as noted above in the first paragraph. The Target is $125 and we would not sell PayPal.

-----------------------------------------------------------------------------
The Trade Desk (TTD: $75, down 12%)
Early Stage Portfolio
One of the largest demand-side advertising platforms, The Trade Desk released its second quarter results last week, reporting $460 million in revenues, up 23% YoY, compared to $380 million a year ago. The company posted a profit of $140 million, or $0.28 per share, against $100 million, or $0.20, driven by its relentless streak of onboarding new brands, inventory, and partnerships throughout the past year.
Despite a beat on consensus estimates at the top and bottom lines, the market reaction following the results put a damper on the stock’s 100% YTD rally. The results themselves had nothing to warrant an adverse reaction, and in our opinion, this was everything to do with the company’s unjustifiably high valuations of 22 times sales and 290 times earnings, many times higher than the industry average.
The Trade Desk is a technology company that helps businesses buy and sell digital advertising. They are successful because they offer a platform that is easy to use, transparent, and effective. The company has a strong focus on data and analytics, which allows them to help businesses target their ads more effectively. While demand for advertising has hit a rough patch over the past few quarters, the company’s precision and transparency-driven platform has remained resilient nonetheless. Its business development initiatives have made its solutions indispensable for large brands, resulting in a 95% customer retention rate for the ninth consecutive year.
In a niche filled with walled gardens from the likes of Meta and Alphabet, The Trade Desk has succeeded by making this business more accessible to everyone. It has continually gained market share at the expense of its two major competitors, and while the threat of Alphabet’s renewed efforts in this space is substantial, TTD’s expansive moats, industry partnerships, and integrations will not be easy to breach.
The stock was upgraded by many firms on the Street, including Wells Fargo, raising their target to $100 from $82. Piper Sandler has a nice round $100 price target, with Morgan Stanley at $105. During the quarter the company repurchased stock worth over $40 million, with a further $360 million in pending authorizations. This should provide it with much-needed support during volatile times like the present. The Trade Desk ended the quarter with $1.4 billion in cash, a mere $250 million in debt, and $630 million in cash flow. Note: We wrote about The Trade Desk in The Bull Market Report of July 17th. Check it out on the website.

-----------------------------------------------------------------------------
HF Sinclair (DINO: $59, up 8%)
Energy Portfolio
Independent petroleum refiner HF Sinclair released its second quarter results two weeks ago, reporting $7.8 billion in revenues, down 30% YoY, compared to $11.2 billion a year ago. The company posted a profit of $500 million, or $2.60 per share, down from $1.3 billion, or $5.59, but the beat on consensus estimates at the top and bottom lines sent the stock on a strong rally from $51, and the $46 level in July. We added the stock at $61 in December, so the weakness this year has been put behind it.
During the quarter, the company was hurt by the drop in volumes due to the drop in energy prices and the economic slowdown globally, along with a slowdown in refining margins. The gross margin per barrel stood at $22, down 40% YoY, compared to $36 a year ago. This was coupled with lower production of 554,000 barrels of oil per day, down from 627,000 barrels during the second quarter of last year. This is in sharp contrast to the previous quarter, when the company looked upbeat as a result of increasing utilization rates, falling oil refining capacities, and a widening crack spread, owing to the normalization of global energy markets. (Crack Spread is the margin or pricing difference between a barrel of crude oil and the finished petroleum products.)
HF Sinclair is an energy company that produces and sells a variety of fuels, including gasoline, diesel, jet fuel, renewable diesel, specialty lubricant products, specialty chemicals, and specialty and modified asphalt. They have a long history in the energy industry, having been founded in 1916. They have a strong financial position and are committed to innovation. The company used its windfall gains over the past year exceptionally well, paring down debt to $3.6 billion, while offering a well-covered annualized dividend yield of 3%, ending the quarter with $1.6 billion in cash, and $2.5 billion in cash flow during the quarter. Our Target is at $72 and our Sell Price is at $51. This is a solid $11 billion company with a strong management team.

-----------------------------------------------------------------------------
Sunrun (RUN: $16.64, down 5%)
TERMINATING COVERAGE
Photovoltaic cells and energy storage solutions provider Sunrun is riding the post-IRA high life, as evidenced by its second quarter results two weeks ago. The company posted a profit of $55 million, or $0.25 per share, against a loss of $12 million, $0.06. This was still a fairly mixed quarter, with earnings blowing past estimates by a wide margin, with top-line figures coming in below expectations.
Market reactions aside, this was a spectacular quarter for the company, with 103 megawatt hours of fresh installations, up 35%. Total solar energy capacity installations reached 300 megawatts, exceeding the high-end of its guidance at the end of the quarter. Net subscriber value hit $12,320, up by $320 from the prior quarter. Much of this was made possible by the tax credits availed to consumers since the passing of the $700 billion Inflation Reduction Act last year. With tax credits now covering 30% of the installation costs, solar companies such as Sunrun are on a fiery streak.
The company unveiled a slew of new products and initiatives during the quarter, starting with the Sunrun Shift, a home solar subscription that aims at maximizing value under California’s new solar policy. It further signed a partnership with PG&E to develop a distributed power plant that turns home solar storage systems into resources during periods of peak demand, helping prevent blackouts.
Sunrun is an undisputed leader in an industry that is set to hit $400 billion by 2030, and following a 30% YTD pullback, and an 83% decline since its all-time high in 2021, it is trading at a mere 1.5 times sales. The company ended the quarter with $670 million in cash, and over $10 billion in debt which is concerning, but has the assets and is now generating sufficient cash flow to back this up.
With all of this said, we’re not happy with the performance of the firm. After thinking this through long and hard, we believe their marketing philosophy is skewed. The firm offers solar leases, solar loans, and purchase agreements where customers agree to buy the electricity generated by their solar panels for a fixed price over a set period. They don't have to pay upfront for the solar panels, and they don't have to worry about maintenance or repairs. This all sounds great at first glance, but the financing costs for the firm are exorbitant at $10 billion, which is WAY out of line. We added the stock at $29 and we reluctantly exit the stock here. We will be replacing this with a much better solar option in the coming weeks.
-----------------------------------------------------------------------------
Twilio (TWLO: $62, up 1%)
Long-Term Growth Portfolio
Twilio is the leading provider of cloud-based programmable communications solutions. It released its second quarter results last week, reporting $1.0 billion in revenues, up 10% YoY, compared to $940 million a year ago. It posted a profit of $120 million, or $0.54 per share, against a loss of $7 million, or $0.11, coupled with a beat on estimates for the next quarter sending the stock up from the $58 level following the results.
The company hit a rough patch over the past year, owing to persistent macro pressures, which in turn resulted in longer sales cycles, lower deal sizes, and a substantially lower dollar-based net expansion rate* at 103%, compared to 123% a year ago. The slowdown in the social, streaming, and crypto verticals has made things worse, yet Twilio has successfully managed to hold its ground as things start to turn around.
* Dollar-based net expansion rate (DBNER) is a measure of how much revenue you earned from existing customers due to add-ons, upselling, and cross-selling.
Twilio currently has 304,000 active customers on its platform, against 275,000 a year ago, which is largely in line with estimates. The company’s communications revenues led the way at $910 million, up 10% YoY, followed by data and applications at $125 million, up 12%.
Over the past few years, the company has made significant progress in offering a differentiated customer value proposition. It has done this via acquisitions, partnerships, and integrations, which have since resulted in wide, impenetrable moats. The tailwinds as a result of this are only just beginning to be realized and have since prompted a flurry of analyst rate hikes, with the high end of its target at $110.
The stock is up by 23% YTD, but is still off by 86% from its all-time high in 2021 at $457, while trading at a mere 2.8 times sales, making it a fairly priced growth stock. The company completed $500 million in stock repurchases during the quarter, from its $1 billion in authorizations at the beginning of this year. It ended the quarter with a strong balance sheet with $3.7 billion in cash, $1.2 billion in debt, and a stable cash flow position. Will the stock ever reach its all-time high again? We believe so, but certainly not for a few years. In the meantime, we see steady, profitable growth ahead and look forward to breaching our Target of $135. Our Sell Price is $65, with the stock under that price now, as you know, so if you are anxious, set a sell stop at your pain point, say $55 or so. We don’t believe this can happen, but a lot depends on the world economies and all of the potential negatives in the world. We are optimists, as the American economy and markets have grown through thick and thin, through war and viruses, and bull markets and bears, for 200 years. We’ll come through again, of that there is no doubt.

-----------------------------------------------------------------------------
The Bull Market High Yield Investor
It happened like clockwork. Something nudges long-term interest rates above 4% and a perfectly good rally in the stock market evaporates. This week, the trigger was a shock cut to the Treasury’s credit rating, a significant shift in the bond market but not necessarily anything the rest of Wall Street needs to worry about. Most of the big players blew off the downgrade. Warren Buffett, Jamie Dimon, Janet Yellen, everyone. The rating agency that pulled the trigger, Fitch, is relatively minor, with maybe 15% of the global heft in this space. Neither of the true giants spoke up.
And the timing of this downgrade is strange to say the least. It feels like a PR stunt, a desperate reach for relevance. But for now, that 15% of the world that pays attention now needs to adjust its bond portfolios to mirror this move, which means selling Treasury debt to make room for whatever this agency decides is still worth its top rating. Demand for Treasury bonds goes down a bit. And the laws of economics say that when demand for a thing suddenly drops, the price drops with it. When bond prices drop, yields go up. Suddenly yields on the 10-year are above 4%.
This is a historical pain point for the market. Round numbers scare people. The thought is that if you can lock in 4% a year on bonds for the foreseeable future, enough investors will pull their money out of stocks to buy those bonds. But wait a minute. Money flowing out of stocks into bonds means demand for bonds picks up again. Prices in this scenario firm up. And guess what, yields go down. The situation just resolved itself.
That’s how this works. It’s how it worked in 2011 and it’s how it’s going to work now. Yields have had trouble getting above 4% in this cycle. It’s going to take a massive shift in the landscape to get them permanently above that level now. If you’re worried about yields, buy bonds when they hit 4%. And if you’re unwilling to buy bonds at 4%, stick with the stocks that can deliver better under the right circumstances. Beyond that, 4% is just a number.
After all, there are two things here to keep in mind. First and foremost, when long bond yields are stuck at roughly 4% and the Fed has pushed short-term rates well above 5%, the system is showing dramatic signs of stress. That’s the inverted yield curve that tends to foreshadow a recession. The Fed controls the short end. The market decides the long end. When the market keeps buying so many Treasury bonds that long yields stay below short yields, the market is already so fixated on an economic downturn ahead that the prophecy becomes self fulfilling.
But if long-term Treasury yields were to rise back above the short end of the curve, that recession signal goes away. Keep that in mind when people talk about how lethal 4% really is. The only way this curve can heal is if those long yields climb well above 4% or if the Fed wakes up and decides there’s been a terrible mistake. You know the first scenario is the only plausible one. And that’s the second factor to watch. We remember back to 1994, when Treasury yields started at 5.92% and crossed 8% by November. They didn’t get back below 5.5% until 1998. That’s at least four years the world survived yields much higher than 4%, a period in which the S&P 500 doubled. It was the dotcom boom, one of the greatest rallies in history. And it happened in the face of those rates.
What’s lethal about 4% yields? Fear itself. We’ll get through this. Stocks will recover and get back to work. If yields stay above 4%, it’s going to be a lot harder to argue that there’s a recession looming. And if they fall below 4%, where does all that fear go? For now, if you're happy earning 4% a year, bonds are attractive. If you want more, you need to reach for a few of our higher-yield recommendations like the two profiled here.
Apollo Commercial Real Estate Finance (ARI: $10.74, flat. Yield=13.0%)
High Yield Portfolio
New York-based Apollo Commercial Real Estate Finance primarily invests in real estate-backed debt instruments, including senior mortgages and mezzanine loans. The company released its second quarter results recently, reporting $63 million in revenues, up 10% YoY, compared to $57 million a year ago, with a loss of $16 million, or $0.11 per share, against a profit of $50 million, or $0.35. The numbers were weighed down by net realized losses on investments of $82 million, or $0.61 per share, from a subordinate loan backed by an ultra-luxury residential property. This was a significant event, one that saw a $60 million increase to its special current expected credit loss allowance, bringing it to a total of $141 million. This includes an already realized loss of nearly $80 million on the same Manhattan-based ultra-luxurious residential property and is a reflection of the state of New York’s property market, which continues to struggle with a very tough post-COVID recovery.
The company continues to benefit from higher interest rates because 99% of its portfolio is held in floating debt. This led to another consistent quarter of strong distributable earnings of $0.51, well above the quarterly dividend of $0.35. There has been some talk of a dividend cut, but with the level of coverage, we are not concerned. We believe the likelihood of interest rates remaining high for the foreseeable future is quite high.
Leaving this aside, Apollo’s loan portfolio remains as sturdy as ever, with a total portfolio value of $8.3 billion, a weighted average yield of 8.6%, with nearly 94% of them being first mortgages, making this a good place to be in a high-interest rate environment. The trust further funded two first mortgage loans worth $170 million, and received repayments worth $600 million.
The stock is down by 1% YTD, trading at an enticing 27% discount to book value. Apollo ended the quarter with $370 million in cash, $7.0 billion in debt, and $330 million in cash flow.

BlackRock Income Trust (BKT: $11.82, down 2%. Yield=8.9%)
High Yield Portfolio
The BlackRock Income Trust, one of the leading investors in agency mortgage-backed securities and US Government securities offers plenty of value for conservative investors looking for capital preservation, alongside regular income. With its exposure to quality AAA-rated securities, its risk quotient is only a notch below treasuries and munis, while offering higher yields and avenues for capital appreciation.
Ever since the Fed began its hawkish stance, the fund has witnessed a steady pullback and is currently down 6% this year so far. As a result, it offers an enticing 9% dividend yield, all the while trading at a 5% discount to book. With inflation slowing down, and the Fed’s rate hikes finally coming to an end, this fund represents a stellar economic opportunity during the months ahead.
The thing about this fund is that while it may be affected by macroeconomic headwinds and market volatilities in the short term, for investors with a long enough time horizon, the risk of loss is very low. This is made possible thanks to its exposure to mortgage-backed securities, all insured by Fannie Mae, Freddie Mac, and Ginnie Mae, which while not explicitly guaranteed by the US government, we know for a fact that the latter will step in to keep these entities solvent.
The biggest drawback when it comes to investing in the BlackRock Income Trust is the lack of any significant hedges against interest rate risks. During a high-interest rate environment like the present, a portfolio of mortgage servicing rights offers much-needed cushioning against volatility, but they don’t own any, as Rithm Capital and others do. We feel that the company, at current levels, has limited downside risk as the current interest rate levels are very beneficial for the fund.

Good Investing,
Todd Shaver, Founder and CEO
The Bull Market Report
Since 1998
March 31, 2022
by Todd Shaver | Mar 31, 2022 | Instant News Flash
The Mood Is Improving
Global payments platform PayPal (PYPL: $118) and its shareholders have endured a rough couple of months. Triggered by poor fourth quarter results in early February and persistent worries about too much competition in Electronic Payments dooming the stock in a rising rate environment, shares fell to a 52-week low a few weeks ago and are now "only" up 27% from that deeply depressed level.
While several analysts have downgraded the stock for nebulous reasons, Goldman Sachs has initiated coverage with a “Buy” rating and a $144 price target, representing an upside of 21% from here. The analyst expects PayPal to return to earnings growth in excess of 20% after 2022, fueled by substantial tailwinds in the form of eCommerce growth, digitalization and more. That's historically all this company has ever needed to keep the stock climbing at a healthy rate, year after year.
PayPal has significantly upped its game when it comes to eCommerce, especially with its acquisition of HappyReturns, a solution that allows merchants who use PayPal Checkout to seamlessly handle returns. The company has further partnered with Ulta Beauty and a number of other firms to expand its return bar locations to over 5,000, offering a critical network for online retailers, especially at a time when average return rates are in excess of 20%.
On a fundamental level, PayPal remains as sturdy as ever. What it went through in recent months is an amalgamation of various factors, mainly the post-COVID overhang, that many of its peers continue to deal with, followed by the loss of eBay payment volumes (anticipated for years) and the lack of any visible growth catalysts in the medium term as the company enters into a “transition year.”
But this is a giant company, at $140 billion of market cap. The all time high is $310 less than a year ago. It WILL get back there – it’s just a matter of time. Last four years of revenues: $15 billion in 2018, followed by $18 billion, $21 billion and then $25 billion last year. Last quarter revenues: $7 billion. And the company is quite profitable too.
The market’s narrow-minded view has resulted in a strong opportunity for value investors to pick up this beaten-down Fintech giant and ride the indomitable growth of digital payments. Trading at just under 6 times sales, the stock is oversold and undervalued. We continue to maintain our Price Target at $305, and reiterate our pledge to never sell this company.
February 11, 2018
by Todd Shaver | Feb 11, 2018 | Weekly Newsletter 7pm Sunday
The Weekly Summary
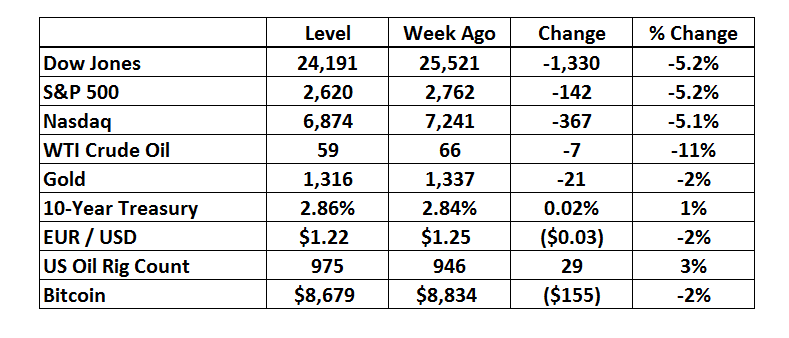
Volatility is back and in an uproar. We’ll run through what is happening in the markets below, but don’t lose sight that although the backdrop warrants caution, the bull market is alive and well. US equities ended their worst week in two years on a positive note with the Dow up 330 points on Friday, but rate-hike fears that pushed markets down remain in place as investors await inflation figures on Wednesday. The S&P 500 tumbled 5.2% in the week, its steepest slide since early 2016, jolting equity markets from an unprecedented stretch of calm. At one point, stocks were 12% below the highs set just two 11 days ago, before a strong rally Friday left the equity benchmark 1.5% higher on the day.
Still, the selloff has wiped out gains for the year. Signs are mounting that jitters spread to other assets, with measures of market unrest pushing higher junk bonds, emerging-market equities and treasuries. The CBOE Volatility Index ended at 29, almost 3x higher than its level January 26th. We at The Bull Market Report are staying calm. We believe stocks are on sale so we would suggest picking out one or two of your favorites and slowly buying more shares.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight: Blackrock, The Carlyle Group, Synaptics, Tesla, CBRE Group, and Ventas.
Key Market Measures (Friday’s Close)
BMR Companies & Commentary
Blackrock (BLK: $522, down 5%)
BlackRock is trusted to manage more money than any other investment firm. Its business is investing on behalf of clients from large institutions, to parents and grandparents, teachers, nurses, doctors and people from all walks of life who entrust their savings to the firm. Well, the company is getting even bigger.
BlackRock is seeking to raise $10 billion for "BlackRock Long-Term Private Capital" to buy and hold $500 million to $2 billion minority stakes in companies for periods of up to more than a decade. The move establishes BlackRock as a potential competitor to Wall Street private-equity giants like Carlyle Group and Apollo Global Management. It is the first-ever attempt by the world's largest asset manager to make such direct investments.
BlackRock has praised Berkshire Hathaway as the best-known example of the strategy. Well, of course. No one has ever done it better. We all know this. BlackRock Long-Term Private Capital will operate differently from most private equity funds, taking full commitments up front and reinvesting as it exits investments. As compared with most investments that return capital to investors after one deal. This is great for Blackrock shareholders because there is no need for ongoing fundraising.
BMR Take: The rock of the investment management industry right now is Blackrock. The company is going to generate nearly $14 billion of revenue this year and produce about $28.60 of EPS. With revenue and EPS growing to over $15 billion and $32.00 next year, respectively, the stock is far from expensive leaving a lot of room for upside.
---------------------------------------------------------------------------------------
The Carlyle Group (CG: $23, down 10%)
Carlyle delivered a solid quarter. Revenue was $1.0 billion versus just $435 million a year ago. EPS hit $1.01 versus just $0.02 a year ago.
Management discussed how the business concluded 2017 with great momentum across all businesses. Carlyle had record activity deploying $22 billion into new investments and raising $43 billion of capital across the platform. Investment performance was exceptional with 20% appreciation across carry funds enabling realizations of $26 billion that went to investors as proceeds for their investments.
The company declared a quarterly distribution of $0.33 per share on February 21st. For full year 2017, they paid out $1.41. That is nearly a 6% yield at the current price.
BMR Take: In private equity The Carlyle Group is a top-notch franchise, known everywhere, the who’s who of business, doing deals in the top floor offices of every major city. The business is raising money like weeds and generating big returns. It is a very compelling opportunity. EPS should hit $3.00 next year leaving this stock dirt cheap.
---------------------------------------------------------------------------------------
Synaptics (SYNA: $44, up 7% - yes really!)
Synaptics reported revenue of $430 million versus $461 million last year. EPS was $1.11 versus $1.49 a year ago. Not terribly pretty, but Synaptics is starting to benefit from the transition encompassing a more diversified product portfolio and customer base, and expects to see strong momentum from investments in infinity displays and consumer IoT in the second half of this calendar year. They continue to make meaningful strides across core growth priorities within chip-on-film, OLED (organic light-emitting diode*), in-display fingerprint technology, and consumer IoT. This includes retail availability of flagship smartphone products, such as new fingerprint, display, and voice-enabled technologies.
* OLED panels are made from organic (carbon based) materials that emit light when electricity is applied through them. Since OLEDs do not require a backlight and filters (unlike LCD displays), they are more efficient, simpler to make, and much thinner - and in fact can be made flexible and even rollable.
BMR Take: With all of the growth investments happening, and the lucrative opportunity emerging for consumer IoT, the quarter’s results were less important than the outlook for attacking this major opportunity. And the outlook is bright. EPS is expected to ramp from around $4 this year to $5 next year and substantially more in the years ahead. We added the stock at $41 in December and our Price Target is $54 and we are hopeful of seeing this during the current year. It would be helpful in achieving this goal if the market calms down and resumes its bull run.
---------------------------------------------------------------------------------------
Tesla (TSLA: $310, down 9%)
Tesla reported revenue of $3.3 billion this quarter versus $2.3 billion last year. For the full year Tesla did $12 billion versus $7 billion a year ago. EPS this quarter was a loss of $3.04.
However, the big ramp in profitability is on the horizon. Revenue is expected to jump to $20 billion this year and $27 billion next year. EPS is expected to swing from a loss to a positive $3.25 in 24 months.
The stock traded about flat after the earnings release that included a fractional revenue miss, and narrower-than-consensus EPS loss. Gross margins came in 190 basis points below consensus, with the Model 3 production ramp weighing on the overall margin profile. But that didn’t really matter as management reiterated its target of 5,000 Model 3 production units per week by the end of Q2.
BMR Take: Most continue to see many moving parts to the Tesla story, with the guidance for sustainable positive operating profits sometime in 2018 garnering more of a show-me attitude, especially given the checkered track record of not hitting guidance milestones or production targets. However, most agree the healthy demand for the Model 3 continues to be a good problem to have, and are spectators on the pace of production execution.
We put a Sell Price of $335 on the stock a few weeks ago so we don’t lose the tremendous profits we have on the stock, but the market this week smashed most stocks down including Tesla. Our Sell Prices are for YOU to decide what to do.
--- We love the concept of the company.
--- We love Elon Musk (Space X with its new successful launch this week has had positive ramifications on Tesla).
--- We love the cars they make.
--- But the debt is crushing.
--- But they have been able to weather the storm through debt and equity sales.
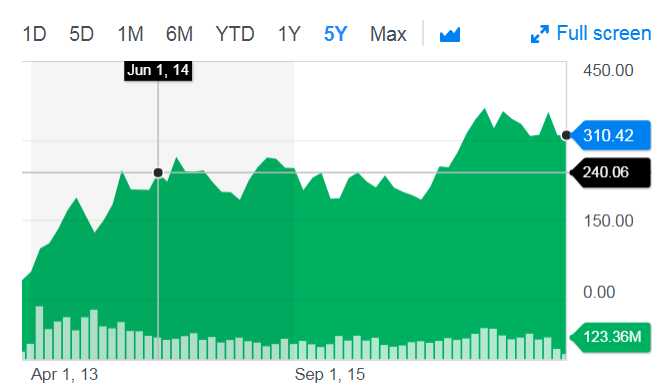
As we’ve said before, this stock could go to $200 or $500. And we’re not sure which will come first? It is very speculative. Should you be in this stock for the wild ride ahead? Only you can decide.
Here’s a 5-year chart. Pretty impressive:
---------------------------------------------------------------------------------------
CBRE Group (CBG: $42, down 5%)
CBRE is crushing it. The company reported revenue of $4.4 billion versus $3.8 billion last year. EPS was $0.99 up from $0.93 a year ago. The consensus expects this year’s revenue to grow from $14.2 billion to $16.5 billion in 2019. EPS is similarly expected to grow from $2.70 this year to $3.20 in 2019.
Fourth-quarter results capped another excellent year for CBRE. Performance significantly exceeded the expectations discussed on the third-quarter earnings call as some concerns surfaced about occupier outsourcing and leasing fee revenue growth. But all that went to the wayside as revenue and earnings for 2017 ended up reaching all-time highs. 2017 marked the 8th consecutive year of double-digit EPS growth for CBRE.
BMR Take: The macro environment is a supportive backdrop for this business, and management continues to operate within an industry poised for long-term growth. This is due to the growing acceptance of outsourced commercial real estate services, the increasing capital allocation to commercial real estate as an institutional asset class, and the continuing consolidation of activity within the industry to the highest-quality, globally diversified market leaders. CBRE Group is a must-own holding in your portfolio in the real estate sector.
We’re up over 60% in two years on this wonderful firm. No dividend yet, but we can see that coming. Our target is $54 and there’s an outside chance it can hit that this year. We know what this company does first hand – they save big multi-national companies money. Big money as in millions and millions of dollars. And the firm gets rewarded in brokerage fees, fixed fees and more. And so few people know about this great firm.
This chart shows the value this stock offers here, after this rough week:

---------------------------------------------------------------------------------------
Ventas (VTR: $52, down 5%)
Ventas reported revenue for the quarter of $895 million versus $875 million a year ago. Revenue for 2017 ended at $3.6 billion versus $3.4 billion in 2016. EPS was $0.50 versus $0.58 a year ago. EPS for 2017 ended at $1.78 versus $1.86 in 2016. Consensus expects revenue to drift upward toward $3.7 billion over the next 2 years. EPS is expected remain stable around $1.75 although we see several sources of EPS upside that are likely to drive revisions closer to the highest Street forecast of $2.15.
All in all, 2017 was another excellent year for Ventas, as the business generated record cash flow from operations and delivered same-store property cash net operating income growth at the high end of internal expectations. To further enhance their diverse portfolio, the company made nearly $2 billion in value-creating investments, including significant expansion of their university-based life science business. And they profitably disposed of almost $1 billion in assets and completed innovative deals with leading operating partners.
BMR Take: Ventas has proven resilient through cycles for two decades. They remain one of the world's best REITs with a specialty in healthcare among other areas.
This success is founded on solid strategic vision, superior foresight and innovation, intelligent and timely capital allocation decisions, rigorous execution and a cohesive, expert team. As they enter 2018 – the company’s 20th anniversary year – management is confident that they can continue the long track record of superior consistent performance as the industry leader.
We added Ventas at $60 in last 2016, a little over a year ago. Until the last two weeks, it was hovering around $56, down a bit, but still paying a nice 6% dividend. It’s worth $18 billion, and has over 1200 properties across the US, Canada and the UK. And as you know, they are in the senior living business along with medical facilities as well. Yes, the stock is down, but this company is strong, and we can only see good things happening from here. If you bought at $60 now is the time to add to your position to bring your cost down. Two years from now we wouldn’t be surprised to see the stock in the 70s, as remember, 10,000 people a day turn 65 in the US. They have to live somewhere!
---------------------------------------------------------------------------------------
We got a letter from one of our readers about Ventas
From: Richard Reed [mailto:reed995@]
Sent: Wednesday, February 07, 2018 10:21 AM
To: The Bull Market Report <Info@bullmarket.com>
Subject: Re: EARNINGS PREVIEW FOR THE WEEK AHEAD
Hi Todd,
Ventas (VTR) is below your Sell Price. Are you lowering the sell price? Thanks.
Richard
Our answer:
Hi Richard –
Look – they own 1200 assets in the United States, Canada and the UK. The properties are senior living properties and more. Are they all going down the tubes? NO WAY. A $19 billion asset paying 6%. We would buy more.
Furthermore, our Sell Price on Ventas is $58. But at $52, we have to say that we like it even more. Nothing has changed for the company in the past two weeks. Yes, interest rates are a shade higher, but nothing out of the ordinary. When the economy is good, rates go out. This is just normal. So to answer your question above, yes, we are lowering our Sell Price to $48. Of course, YOU can make up your own mind on this one, as always, but we would take this opportunity to buy an amazing company at an even lower price.
---------------------------------------------------------------------------------------
---------------------------------------------------------------------------------------
Economic Calendar
CPI Ex-Food & Energy
Wednesday, February 14th, 8:30 AM
Period: January
Consensus: 1.7%
Prior: 1.8%
CPI
Wednesday, February 14th, 8:30 AM
Period: January
Consensus: 1.9%
Prior: 2.1%
PPI
Thursday, February 15th, 8:30 AM
Period: January
Consensus: 2.5%
Prior: 2.6%
Housing Starts
Friday, February 16th, 8:30 AM
Period: January
Consensus: 3.7%
Prior: -8.2%
---------------------------------------------------------------------------------------
---------------------------------------------------------------------------------------
Apple has $285 Billion in Cash
Can you believe this? Again – a record high for any company in history. Apple (AAPL: $156, flat for the week) has $285 billion in cash, or $56 a share. With the stock at $156, that’s 36% of each share of stock in cash. We’re not sure of the Wall St. record, but we are guessing this is twice as much than any other company in history. With the stock flat for the week (amazing) this just screams out at us to add more to the portfolio.
---------------------------------------------------------------------------------------
If the Market Heads Back Up
No one knows where the market is heading. Will it calm down and move higher this coming week and month? Or will it be heading for 23,000 and lower? Again, we don’t know. But if things simmer down and the volatility abates – AND IT WILL – there are a few stocks that we would want to add to our positions in. Here are just a few:
Microsoft
PayPal
Google
Facebook
Apple
Eli Lilly
Yes, many of these are the super Tech stocks that have been leading the market. But guess what? These stocks will continue to lead the market for many years to come.
And one more note. Did you see Annaly Capital Mortgage (NLY: $10.21, down 1%) this week? Solid as a rock. So if you are super worried about things, we believe Annaly can be a store of value for a month or two or 12, and you can enjoy the 11% dividend in this $12 billion market cap company.
---------------------------------------------------------------------------------------
---------------------------------------------------------------------------------------
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
There was no comment Monday or Tuesday because everything I wrote was outdated and the numbers were obsolete within minutes of writing, rewriting and re-rewriting them. The dust may or may not have settled, but a few things are much clearer today.
In short, the seismic swings over the past few days have been based on three primary factors that we believe now form a consensus:
1. The threat of higher inflation (Rising bond yields)
2. The possibility of more Fed hikes
3. The long streak without a normal and healthy market shakeout.
How does that stack up against the best economy we've seen in over a decade? In other words, is it good news or bad news that economic growth is so strong the Fed may have to raise rates sooner than expected? Or, is it good news or bad news that nearly half the companies in the S&P 500 have reported fourth quarter results and more than 80% of them have beaten Wall Street's revenue expectations, the highest percentage since the third quarter of 2008? And, is it good news or bad news that the tax law will boost those profits further in the quarters ahead?
Let's put all this in perspective:
First, the market isn’t overbought anymore. We now know that. There was a "10% correction." Let’s get over it.
Second, earnings are robust.
Third, the rise in bond yields has been a headwind, but it’s not signaling a looming recession. Importantly, the 10-year vs. 2-year Treasury yield spread has widened out as yields have risen, implying the bond market is now discounting higher inflation and better economic growth, which over the medium term has almost always been positive for stocks.
While volatility has returned with a vengeance, the market fundamentals are now better and earnings growth prospects haven't looked better in years. Basically, all of the reasons why investors have been bullish on the market last week, last month and last year are still here.
---------------------------------------------------------------------------------------
The High Yield Report
by Michael Foster
VP High Yield
It should always be emphasized that much of a stock's action is not caused by only the underlying company, but also by the industry and the overall market. In a volatile environment, this emphasis is especially important. While our High Yield and REIT portfolios have shown lackluster performance over the past two weeks, the fundamental aspects of the companies that make up the portfolios have not changed.
The S&P 500 decreased 5.1% over the past week, leading to stocks officially being in correction territory. Much of the decline is being attributed to interest rate and liquidity fears, which is why much of the analysis on the portfolio below will focus on those aspects. It takes just one week to rattle bullish sentiment. As an investor, you should not put too much weight on what the general financial media is discussing. What should take priority is thinking about whether the fundamental aspects of the economy and market have changed. When this is the priority, our fear diminishes as we realize that earnings are still strong, nonfarm payrolls on February 2nd were above expectations, and a deregulatory environment is still present.
One metric, the yield curve, is worth looking at though. The spread between the 10-year Treasury yield and the 2-year Treasury yield has been constantly decreasing as a result of the Federal Reserve tightening policies and the lack of inflation. On a basic level, you can note that the presence of an inverted yield curve, if it were to happen, has been a common predictor of past recessions. Going deeper, the economic repercussions of the inversion are much more important. Consumers and banks are directly impacted. For consumers, the cost of credit increases, which leads to a larger portion of expendable income being dedicated to servicing debt. For banks, the spread between long-dated loans and deposits decreases, which leads to worse financial performance. We’re sharing this information so that you can keep the yield curve on your radar, but there’s no need to worry as of now. When the curve inverted in the past, it still took between 7 to 24 months to reach any sort of recessionary state.
AllianzGI Equity & Convertible Income Fund (NIE: $20.59, down 4%) fared slightly better than the S&P’s drop of over 5%. It moved from the weekly low of $19.50 to its current level after recovering about 2.5% in the last hour of trading on Friday. The performance of individual equities which it holds, including Microsoft, Alphabet, and Amazon, led to the recovery in the last hour. Given that the fund invests little in the bonds and the scenario of the inverted yield curve, we can expect the funds to be shifted from Equity to Bonds.
We still see Apollo Commercial RE Finance (ARI: $17.70, down 3%) as a cyclical play on the U.S. commercial real estate sector. Given that commercial real estate in the U.S. remains solid, with Apollo’s loan originations hitting $1.5 billion YTD and the economy of the US continuing to get stronger and stronger, Apollo is not a position to be worried about.
Digital Realty Trust (DLR: $102, down 5%) dropped almost by the same amount as the S&P. This was the opposite of the week prior, where the company maintained strength in the midst of widespread declines. While we noted the continued demand for data centers in the last summary, there are some other metrics to note. Digital Realty, owning many data centers in US and internationally, is affected by rising interest rates as the cost of borrowing rises. The company has a massive debt level of $5.8 billion with a Debt/EBITDA ratio of 22. Rising interest rates could cripple the company’s dividend payout and future prospects.
Invesco Municipal Trust (VKQ: $11.83, flat) ended up at the same level as the beginning of the week. With its investments primarily in investment grade U.S. municipal bond obligations (85%), the fund can expect to yield better returns amidst the current rising interest rates scenario. Also, a Fitch report stating that plans to cut federal funds to them won't impact the revenues of the municipal bond funds and ETFs, played a large part in keeping the fund’s price level stable. Nuveen Municipal (NVG: $14.43, flat), another high yield fund with major investments in U.S. investment grade municipal bonds, also maintained its price level.
Pimco Dynamic Fund (PDI: $30, down 1%) was less volatile. The firm, investing primarily in a range of debt securities, including mortgage-backed securities, high yield corporates, and emerging market bonds, could witness further issues with rising interest rates, changes in tax structure, and better yields.
The REIT sector has been partially impacted by the recent economic data, heightening fears of higher interest rates. Primarily, the sector is engaged in massive borrowings, and rising interest rates could increase the cost of the borrowings. With that said, rising interest rates often occur in a booming economy, which indicates higher demand by consumers.
Market corrections generally provide prudent investors with great buying opportunities. One way of going about this is finding relative strength in strong industries. Applying this analysis to REITs, the overall REIT sector was down only 3%. Within out portfolio, three of the five positions outperformed the sector. Annaly Capital Management (NLY: $10.21, down 1%), Government Properties (GOV: $16.37, down 1%), and Omega Healthcare Investors (OHI: $26, flat) composed that group.
As a company that primarily engages in buying mortgages and mortgage-backed securities (as well as other assets), Annaly could fare very well as interest rates go up and correspondingly coupon rates do as well. While this is not necessarily the reason for the less-than-average drop this week, going forward it is something we will keep in mind. Both Government Properties and Omega should not feel a significantly negative impact by rising rates either. The former gets offered attractive rates by the government as a result of its leases and the latter’s healthcare-related real estate is, for the most part, unaffected by the business cycles.
The other two positions, Ventas (VTR: $52, down 5%) and Welltower (HCN: $55, down 5%), ended up having declines that were in-line with the S&P 500 but larger than the move in the REIT sector.
Ventas reported positive 4th quarter earnings on Friday, which provided a minor boost to the stock. The reported income from continuing operations for 2017, $640,000, was a record for the company. In turn, the EPS and FFO per share numbers were also records. In a rising rate environment, this is a positive sign. With the earnings report occurring during a stock market decline, any overall S&P bounce should result in outperformance by Ventas.
The other relatively weak company, Welltower, did not have any news this week to explain the larger than average decline in the stock. As it is focused on owning senior living properties and funding real estate infrastructure, the large amount of debt maintained could pose an issue within the rising rate environment. Currently, though, the extensive track record of stock appreciation over the past 25 years leaves us unworried. Welltower is also at the lower end of its range for the past four years, so it is a good area to pick up more shares.
Good Investing,
Todd Shaver, Founder and CEO
The Bull Market Report
Since 1998
February 4, 2018

by Todd Shaver | Feb 4, 2018 | Weekly Newsletter 7pm Sunday
The Weekly Summary
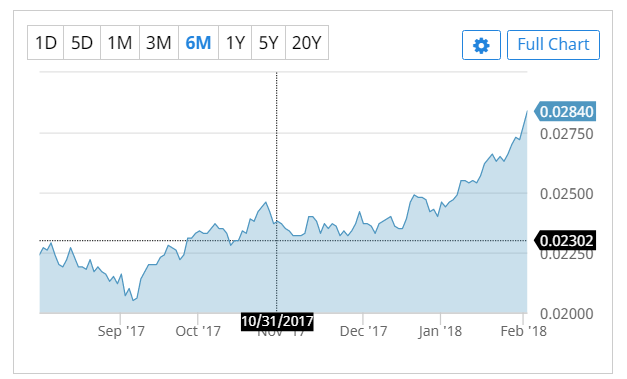
The stock market took a hit this week. It was down almost 200 on Monday, almost 400 on Tuesday, rallied a tad on Wednesday and Thursday, and got hammered on Friday to the tune of 666 points. It’s a week we can happily say has been put to bed and we can now forget about it. The long-awaited correction has now occurred. Happy now Wall Street pundits? (We don’t feel this way.) The big reason for the sell-off was interest rates. The 10-year was up again to 2.84%. And the 30-year moved up above 3%. But this is what happens when you have a strong economy – interest rates move up. This has been happening for over 100 years. The economy shines; interest rates go up. Why do you think rates have been so low? Because the Fed drove down rates after the debacle of 2008-2009 and kept them there for almost 10 years. Look at this chart here; it’s a bit hard to read at first – note that the right column shows the rate today – 1.48% and in 2008 it was 1.04%.
Now take a look at these two charts. The first one is the 10-year Treasury for the past six months. It's gone straight up.
And this one is the 10-year for the past 20 years. Basically straight down.

The key takeaway here is the interest rates are STILL VERY LOW HISTORICALLY. This is actually good news for the economy and stocks. Thus it is our take that 1) We had a bad week last week 2) Things will calm down this week and in the coming months, and 3) Good solid companies will continue to thrive and grow as the US economy continues to strengthen.
Easy for us to say. Hard for you to implement. We understand that. But we want you to put this past weekly move in perspective. The market is where it was just three weeks ago, at 25,500. A year ago it was at 20,000.
The big oil companies came up a bit short on the earnings front last week. Most of the Street was expecting good things, as the price of crude has remained strong at $65. But Exxon’s production dropped by 130,000 barrels a day and has lost money now for 12 quarters a row on its US drilling business, even as US production touched the record production of 10 million barrels a day in November, the previous record being set in 1970. Plus they took a $1.3 billion write-down on its natural gas business. But overall, Exxon made $3.73 billion, a decline of just 2%. These big companies are expected to generate huge amounts of cash in 2018, so we aren’t feeling too sorry for them. The number could be over $40 billion, in excess of dividends and new spending.
Super Bowl Sunday is here! $5 million for a 30 seconds ad. Over 110 million viewers likely watched. The legacy of Tom Brady’s Patriots against the surprisingly better than you think Eagles. The Patriots are favored by 4.5 points. It is interesting. Very often in sports or in the markets whatever people expect to happen, doesn’t materialize. For all sorts of reasons: Cognitive dissonance. Conservative bias. Confirmation bias. Extrapolating past performance. Loss aversion. Overconfidence. Self-control. Regret aversion. Affinity. Status quo. The list of mental mistakes people make when investing is long and always at play. We saw a 666 point drop on the Dow on Friday. This was the 3rd largest one-day point decline in history. The market is digesting something. The Bull & Bear indicator managed by Merrill Lynch has finally flashed a firm sell signal after weeks of overextended conditions. We will see what happens Monday. The unexpected could happen. Just like in football.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight: Microsoft, Google, Amazon, Facebook, PayPal, and Blackstone.
Key Market Measures

BMR Companies & Commentary
Microsoft (MSFT: $92, down 2%)
Revenue was $28.9 billion and increased 12%. EPS hit a solid $0.96 crushing the $0.87 consensus. This quarter’s results speak to the differentiated value Microsoft is delivering to customers across productivity solutions and as the hybrid cloud provider of choice. The firm’s investments in IoT, data, and AI services across cloud, position the business to further accelerate growth. In particular, Microsoft delivered another strong quarter with commercial cloud revenue growing 56% year-over-year to $5.3 billion, which is just amazing to see such a huge growth figure in the lucrative cloud opportunity. Guidance for Q3 was largely in-line or better than consensus expectations. All in all, a very good quarter.
BMR Take: Microsoft is a stock market darling. The business is well-rounded. Legacy Window products to the up and coming Azure product in commercial cloud. We see Microsoft continuing to piece together solid earnings results in the year ahead. With $4.25 of EPS in direct sight, the stock still screens reasonable at around 22x.
----------------------------------------------------------------------------------
Google (GOOG: $1,112, down 5%)
Revenue of $32 billion increased 24% from a year ago. EPS of $9.70 just missed the consensus for $10.00. Overall, we are interpreting the quarter’s results favorably (unlike the Street.) Mobile and desktop search along with YouTube are powering accelerating growth and these trends should drive sustained above average growth going forward. Google Cloud momentum is good now generating $1 billion in revenue per quarter, where the number of $1 million or more contracts across cloud products tripled in 2017. Google has now sold ‘tens of millions’ of its Mini, Max, and Chromecast devices as Google Assistant is now on over 400 million devices globally. Waymo’s progress is accelerating. They plan to launch a ride-sharing program in Phoenix operated by self-driving cars this year. Wow.
BMR Take: We really don’t care much about the slight EPS miss. The stock being down is an opportunity to accumulate shares. Scouring through all the analysis on the quarter, nobody is really saying anything that seriously concerns us. What we want to see going forward is more progress on the cloud business. Amazon AWS is now at 35% market share versus Google Cloud only in the high single digits. If Google can close that gap, this stock can continue its strong move higher. With nearly $50 of EPS coming into view, the current valuation of 23x is far from stretched.
----------------------------------------------------------------------------------
Amazon (AMZN: $1,430, up 2%)
Amazon is crushing it. What else is new? (!) Net sales increased 38% to $60 billion in the fourth quarter, compared with $44 billion in 4Q16. EPS of $6.15 was well above $4.90 a year ago. There is so much to discuss here. What we are really excited about is the Echo business. Earlier in the year Amazon introduced three new Echo devices: the all-new Echo ($100), featuring a new design, improved sound, a lower price, and a choice of colors to personalize your device; Echo Plus ($150) with a built-in smart home hub so customers can easily set up and control their smart home devices; and Echo Spot ($130), a compact Echo with a screen so you can see the weather, get the news with a video flash briefing, view lyrics with Amazon Music, watch a camera monitor, browse and listen to Audible, and more.
This new business opportunity could be huge. Said Jeff Bezos, Amazon founder and CEO, “Our 2017 projections for Alexa were very optimistic, and we far exceeded them. We don’t see positive surprises of this magnitude very often — expect us to double down. We’ve reached an important point where other companies and developers are accelerating adoption of Alexa. There are now over 30,000 skills from outside developers; customers can control more than 4,000 smart home devices from 1,200 unique brands with Alexa; and we’re seeing strong response to our new far-field voice kit for manufacturers. Much more to come and a huge thank you to our customers and partners.”
While Amazon doesn’t break out the financials on Alexa and its other electronics business, the results from its cloud-computing business, Amazon Web Services (AWS), were obvious and contributed much more to the company’s record profit total. AWS saw revenue shoot 45% higher to $5.1 billion, with profits of $1.3 billion. Wow – that’s 26% after tax. AWS and the tax gain of $790 million for the changes in the U.S. tax code, which lowers Amazon’s tax rate to 21%, were the biggest contributors to the company’s overall net income of $1.86 billion. Watch for a possible spin-off of the cloud business sometime this year. Can you imagine what this will do to the stock? Does “shoot higher” ring in your head?
BMR Take: Look, when Jeff Bezos gets surprised by how good a business is doing, and says he is doubling down, you have to take note. But don’t just take note. Take action on it too. You have to have Amazon in your portfolio. You can’t look at the business on current revenue or earnings and say it’s cheap or expensive. It’s an innovation machine. They are constantly doing start-ups, like Echo. More new paid members joined Prime in 2017 than any previous year — both worldwide and in the US. The business is roaring with momentum and still has a very bright future ahead even at the current stock price level.
----------------------------------------------------------------------------------
Facebook (FB: $190, flat)
Flat for the week. Not bad in the whole scheme of things. Facebook increased revenue 47% to $13 billion. EPS of $1.44 was up 19%. What a good quarter frankly. Though while 2017 was a strong year for Facebook, it was also a hard one," said Mark Zuckerberg, Facebook founder and CEO. "In 2018, we're focused on making sure Facebook isn't just fun to use, but also good for people's well-being and for society. We're doing this by encouraging meaningful connections between people rather than passive consumption of content. Already last quarter, we made changes to show fewer viral videos to make sure people's time is well spent. In total, we made changes that reduced time spent on Facebook by roughly 50 million hours every day. By focusing on meaningful connections, our community and business will be stronger over the long term."
Some analysts were scrambling a bit to figure out what this all mean. But monthly active users increased 14% from a year ago to 2.13 billion. Essentially, the issue is that Facebook has had a huge growth engine coming from adding users. Seriously 2.2 billion users is huge. The runway here is slowing down and that means Facebook is going to have to find another way to take over the world. And that is what Zuckerberg is saying. They will be focusing on quality of usage and fully monetizing existing users.
BMR Take: The company is look at EPS growing from $5.40 in 2017 to $8.70 in 2019. It is not easy to find a 20% earnings growth story. We really like the global platform Facebook has built and all the future opportunities it creates for advertising and other revenue opportunities. We see the same story here as elsewhere in large cap tech, trading for 22x is just not stretched.
The stock hit a new all-time high of $195 on Thursday and even traded at $194 on Friday, before the deluge. What a great company.
Stay the course.
Look at this 5-year chart. Where do you think it is headed, as it moves to 2.5 billion users?

Active Users Chart

----------------------------------------------------------------------------------
PayPal (PYPL: $77, down 10%)
PayPal delivered strong numbers. Revenue increased 26% to $3.7 billion. EPS increased 57% to $0.50. Overall, PayPal had a transformative year in 2017. The company brought record numbers of new customer accounts to the platform by simplifying life for consumers and merchants.
PayPal also substantially expanded its opportunities for future growth and redefined its competitive position through successful partnership strategies. For example, PayPal and Synchrony Financial announced an agreement expanding their consumer credit relationship. Under the terms of the transaction, Synchrony Financial will acquire PayPal's U.S. consumer credit receivables portfolio, which totaled approximately $6.4 billion at the end of 2017.
BMR Take: So why is the stock down? PayPal and eBay have signed a term sheet to make PayPal available as a way to pay on eBay, through July 2023. But the fact that PayPal’s exclusivity on eBay is going away has people up in arms. This aspect of the PayPal and eBay relationship has been well-discussed and should not surprise people. Don’t let it fool you.
We look at PayPal like this. This quarter new customers increased 9 million up to 227 million total customers. Facebook has over 2 billion users. With time PayPal could look a lot more like Facebook. That means massive growth still lies ahead. We believe in riding this train. We are talking about the next gen MasterCard or Visa here. A 10% drop in the stock is a good opportunity to take advantage of.
----------------------------------------------------------------------------------
The Blackstone Group (BX: $35, down 4%)
Total revenue ended the year at $7 billion up 39% from last year. EPS of $2.21 compared to just $1.56 a year ago, a huge 42% jump. This business is grooving! It was another strong quarter of core business trends. Specifically, total assets under management increased an elevated 12% sequentially to a record $435 billion, driven primarily by $62 billion of inflows. Capital deployment of $20 billion in the quarter represented a record. And dry powder remained elevated at $95 billion, which bodes well for future capital deployment levels. Just to put that in perspective, Blackstone realized half of the $7 billion of revenue this year from carried interest on prior year inflows, that were deployed to generate big gains of which Blackstone gets a percentage of the profits.
You are telling me the company has $95 billion to put to work to do more of this? Let’s assume on average they can collect a 10% carry on that money. They just doubled the business.
BMR Take: It was a truly exceptional year for Blackstone, reflected by outstanding earnings growth and record capital activity that drove their highest-ever level of aggregate cash distributions to shareholders. Blackstone’s tireless drive to innovate has enabled the company to launch large-scale new product areas that reach a wider client base and serve existing clients in new ways. Our investors in turn have entrusted the company with more capital than ever before, leading to a new record total assets under management of $435 billion, up 18% year-over-year. The stock is a good value at just 10x the current EPS of $3.25.
----------------------------------------------------------------------------------
----------------------------------------------------------------------------------
Economic Calendar
Total Light Vehicle Sales
Monday, February 5th, 10:00 AM
Period: January
Consensus: 17.2 million
Prior: 17.8 million
Consumer Credit
Wednesday, February 7th, 3:00 PM
Period: December
Consensus: $19.5 billion
Prior: $28.0 billion
Initial Claims
Thursday, February 8th 8:30 AM
Period: February 3rd
Consensus: 233,000
Prior: 230,000
----------------------------------------------------------------------------------
----------------------------------------------------------------------------------
Apple Reports Earnings
Apple (AAPL: $161, down 6%) sold 77 million iPhones in the holiday quarter. Apple’s forecast for the next quarter was also lighter than expected. Apple says they expect to sell 50 million iPhones this quarter, slightly lower than the Street expected, and this equates to slightly lower revenue and the main reason the stock got hammered last week.
Apple still blew past its own and analysts’ expectations for revenue and profit for its fiscal first quarter, reporting record sales of $88.3 billion and net income of slightly more than $20 billion. The company was able to increase revenue by 13% year-over-year by increasing iPhone prices and generating more money from the people buying Apple’s smartphones.
Apple jacked up the price on its premium iPhone X smartphone, starting the 10th-anniversary model at $1,000, pushing the average selling price, or ASP, of an iPhone far higher than analysts had ever experienced. IPhone buyers paid an average of more than $796 for their phones in Apple’s fiscal first quarter; iPhone ASP had never previously topped $700.
Apple also boosted its software and services segment revenue 18% year-over-year in the quarter to $8.5 billion. And listen to this:The App Store, Apple Music, iCloud and Apple Pay all had their biggest quarters ever.
Apple said, “During the week beginning Dec. 24, a record number of customers made purchases or downloaded apps from the App Store, spending $900 million in that 7-day period, followed by $300 million in purchases on New Year’s Day alone.”
“Other products” revenue grew the biggest of all. This includes smartphone accessories like the Apple Watch, which grew sales 50% year-over-year for the fourth consecutive quarter, as well as AirPods. Revenue hit $5.5 billion by selling such hardware, up 36% more than a year ago.
Apple is capitalizing on the opportunity at hand by producing more money out of iPhone users in every way possible. Apple is making more money on each iPhone, selling a few accessories to go with it, then signing up iPhone users for monthly subscription plans for services such as Apple Music and iCloud.
If Apple Music continues to grow at its current rate, it will officially overtake Spotify this summer as the streaming world's number one service. Apple Music has a monthly growth rate of around 5%. Spotify has a growth rate of just around 2%. If that keeps up, Apple Music will officially bump Spotify off the top in summer - and there's no reason to believe it can't, given that part of Apple's success in building an audience for Apple Music lies in the fact that the service comes bundled with most of the major devices the company sells.
BMR Take: The all-time high of $180 was hit January 18th. Two weeks ago the stock was down $7 and last week $11. Looks like a sale is going on in shares of this great company. Wait until that overseas cash starts hitting the books here in the US.

----------------------------------------------------------------------------------
VMware (VMW: $123) is Wrapped Up in a Dell Move
One way or the other it’s time to move on from VMware. Why? Dell Technologies owns 80% of the company and is discussing in the press whether to have VMware buy Dell in order for Dell to go public. It’s a back door tactic very rarely, if ever used before. It has impacted VMware greatly because no one really knows how it is going to play out. It looks like VMware might end up owning Dell, creating a behemoth Tech company consisting of Dell, VMware and EMC, plus a host of other tech businesses like cloud computing and cybersecurity. This might be a good investment, but little is known of its financials at this time, so we feel it best to wait and see how things shake out.
VMware was much higher a week ago, and Wall Street is quite nervous because it doesn’t really understand what is going on. The Street doesn’t like uncertainty, remember? (!)
BMR Take: We added the stock a year ago at $83 and we are up a shade under 50%. We think that’s a nice return (a GREAT return) and with everything going on with these new moves by Dell, we think it is time to take profits, sit on the sidelines and watch. Dell may be a stock to buy someday after they go public, but we will leave that decision for another day.
----------------------------------------------------------------------------------
----------------------------------------------------------------------------------
The High Yield Corner
By Michael Foster
Vice President of High Yield
After the S&P 500’s 2% drop on Friday, which has inspired headlines such as “stocks have worst decline in 2 years”, it’s easy to lose sight of the fact that the S&P 500 is up 3.4% YTD.
Before the decline, stocks were up 7.5%, so a drop was clearly necessary [so they say.] Investors who have gotten comfortable with a bull market may be a little scared, because they aren’t used to down days. And it’s easy to forget what is driving the bull market. Wages are up nearly 3% in the U.S., unemployment keeps dropping, corporate earnings are rising, and, perhaps most impressively, this strong economy is being mirrored around the world. The typically cautious IMF and World Bank have asserted that growth is strong around the world, and while these institutions have made a lot of blunders in the past, they aren’t SO euphoric as to bring out the contrarian bear in us.
For high yield, the cautions are amplified. Riskier income producers like Government Properties Income Trust (GOV: $16.65, down 7%) and AllianzGI Equity & Convertible Fund (NIE: $21, down 5%) are down heavy, although they operate in very different markets and are entirely different asset classes (REITs versus convertible bonds and covered-call stocks). To wit: the AllianzGI’s 5% decline on the stock is far steeper than its 2.9% NAV decline, which is itself slightly better than the S&P 500’s 3.2%. Now, of course we can’t read too heavily into short-term price movements, but at the very least this tells us something about the AllianzGI Fund: it is not making extremely risky bets on very volatile assets, so it isn’t in any danger right now. So why did it sell off in excess of its NAV selloff? You got it. Because of fear. And that’s why the fund remains a buy. It’s up 1.6% for the year, lagging the overall market by a bit.
And what about Government Properties Trust (GOV: $16.65, down 7%)? We recommended this REIT back in 2016 and although the REIT is down 7% since then on a price return basis, much more importantly its dividend has not been cut since then, and investors have actually gotten cash dividends of about 19% on their original investment since our recommendation. As a result, we’ve made a profit on a total return basis. And the dynamics of the fund haven’t changed. The REIT’s FFO over the last 12 months is $2.28, while the dividend is $1.72. Thus its FFO is 133% of dividend payouts, so it’s out-earning its dividend. There is no threat to the dividend stream in the short term, and rising rents thanks to a booming economy mean FFO will go up, resulting in even higher FFO coverage.
The income stream here is not at any risk, despite the implications of the recent absurd sell-off. Revenues have been rising by about 8%, so we don’t see any indication that revenues can’t support the current dividend payout. For this reason, there’s no reason to be more cautious about Government Properties, and plenty of reason to shrug off the recent price declines. In fact, it is a great time to add more to this very stable company that is absurdly undervalued.
Elsewhere in REITs, declines were much less severe. Only Omega Healthcare Investors (OHI: $26, down 3%) saw a decline in-line with the S&P 500, but that’s not surprising. We’ve discussed at length why this company’s dividend hikes are threatened, but the threat won’t materialize for years (we’ve estimated 5 years). Dips are buying opportunities for now, as long as investors are cognizant of the fact that the dividend hikes won’t last forever and the stock could sell off in a few years as a result. But if you want a strong and secure high income stream now, Omega is one way to do it.
Digital Realty Trust (DLR: $108) was the second-best investment in the Bull Market Report High Yield portfolio. It was flat for the week. That sounds bad, especially if you’ve gotten used to gains upon gains and few down days, which has been the market norm since the High Yield portfolio began in 2016. But it also shows, interestingly, that the market has a lot of confidence in Digital Realty (which also outperformed a lot of the Tech sector). This week, Amazon, Apple, and Alphabet reported earnings that proved the world’s demand for data centers isn’t going away. Alas, Digital Realty’s yield is tiny, but as an investment in a good company, it’s a great option for investors.
Apollo Commercial Real Estate (ARI: $18.14, down 1%), Ventas, (VTR: $54, down 3%), and Welltower (HCN: $58, down 3%) all saw slight declines, which we can consider to be more a result of REIT investors following the broader market trend. No big news came from any of these companies last week to warrant the selloff.
Similarly, AstraZeneca (AZN: $36, down 2%) fell a lot less than the broader market after weeks of strength in the Biopharma sector. AstraZeneca has not released any major news and there wasn’t any major sector announcements. We can dismiss this 2% decline as being relatively good in a week of short-term worriers cutting bets on all kinds of things more because of fear than for any fundamental reason.
Now, on to municipal bonds. The end-of-year sell-off in this asset class in anticipation of 2018’s rate cuts meant that these funds were attractively priced for income investors, and we still think long-term capital gains are in the cards. What we need to see is the market get used to our new Fed Chairman. While Janet Yellen did a wonderful job of managing monetary policy and bringing the Fed funds rate closer to historical norms, the job isn’t done. Jay Powell has already said that he will continue in the same mode. And that will limit enthusiasm for municipal bonds. that is, until the booming economy results in higher tax revenues for municipalities that, in turn, results in credit upgrades and thus increasing NAVs for our muni Closed End Funds. The timing on this eventuality is unclear, but there is good reason to be confident that it will happen eventually. Nuveen AMT-Free Municipal Credit Fund (NVG: $14.48, down 3%) and Invesco Municipal Trust (VKQ: $11.83, down 4%) are worth holding for the tax-free income as we wait.
PIMCO Dynamic Income Fund (PDI: $30) is the only High Yield holding to be up for the week, and for that we are grateful! But just as there’s little to read into the short-term declines, the short-term gain here isn’t a reason to celebrate. The market is all about short-term emotion-driven trading. If anything, the fact that the panic didn’t hit the Pimco fund may indicate that no matter how crazy the broader market is, we aren’t in full-blown panic mode. And that, quite possibly, could mean this correction won’t last very long.
Good Investing,
Todd Shaver, Founder and CEO
The Bull Market Report
Since 1998
January 30, 2018
by Todd Shaver | Jan 30, 2018 | Earnings Preview 12 PM
Equity Residential (EQR: $61)
Bull Market Report Target Price: $85
Bull Market Report Sell Price: $55
Earnings Date: Tuesday, After market close
Consensus: 4Q17
Revenues: $625 million
EPS: $0.36
Year Ago Quarter Results
Revenues: $605 million
EPS: $0.75
Key Things to Watch For in the Quarter
Analysts expect Equity Residential to report a 3% increase in revenues with a 50% decrease in earnings per share. Despite having beat estimates in each of the past four quarters, the stock is only trading 2% above its price this time last year. Nearly all of the stock’s 15% gains for the year have been wiped out since November with the oversupply issues in the real estate market. We believe the stock is oversold at its current levels, and will see support in the $60 range.
---------------------------------------------------------------------
Eli Lilly (LLY: $86)
Bull Market Report Target Price: $96
Bull Market Report Sell Price: $82
Earnings Date: Wednesday, 9:00 AM ET
Consensus: 4Q17
Revenues: $6.0 billion
EPS: $1.07
Year Ago Quarter Results
Revenues: $5.8 billion
EPS: $0.95
Key Things to Watch For in the Quarter
Eli Lilly is expected to report a 3% increase in revenues and a 13% increase in earnings per share for 4Q17. The stock has beat estimates in three of the past four quarters, and is currently trading 17% above its price levels from this time last year. The stock saw a bit of resistance at $86 earlier this year, and it had recently broken through, but with the tough market of the last two days, the stock is back to $86. This pharmaceutical company invests heavily in its research and development, which will drive its future sales and earnings growth.
---------------------------------------------------------------------
Facebook (FB: $186)
Bull Market Report Target Price: $190
Bull Market Report Sell Price: $155
Earnings Date: Wednesday, 5:00 PM ET
Consensus: 4Q17
Revenues: $12.5 billion
EPS: $1.95
Year Ago Quarter Results
Revenues: $8.8 billion
EPS: $1.41
Key Things to Watch For in the Quarter
Analysts expect Facebook to report a 42% increase in revenues and a 38% increase in earnings per share for 4Q17. Facebook has beaten estimates in three of the past four quarters which has been reflected in the stock’s 42% appreciation over the past year. Facebook’s growth over the past years has been unprecedented for a company of its size. It truly is adhering to its mission of creating a more connected world. We look forward to seeing what kind of developments CEO Mark Zuckerberg has in store for the connected world in 2018. We know it will be good.
---------------------------------------------------------------------
PayPal Holdings (PYPL: $83)
Bull Market Report Target Price: $87
Bull Market Report Sell Price: We would not sell PayPal
Earnings Date: Wednesday, 5:00 PM ET
Consensus: 4Q17
Revenues: $3.6 billion
EPS: $0.52
Year Ago Quarter Results
Revenues: $3.0 billion
EPS: $0.42
Key Things to Watch For in the Quarter
We are looking for a 20% increase in its sales and a 24% increase in its earnings per share for the 4th quarter of 2017. The stock has been on a tear since last year, returning investors a 110% capital appreciation since this time last year. The stock has gone nowhere but up since posting earnings that have exceeded expectations in the past four quarters. PayPal’s market cap is just over $100 billion, making it the largest publicly traded electronic payments company in the world. We look forward to seeing what PayPal has to offer as they continue to lead this growing industry.
---------------------------------------------------------------------
Microsoft (MSFT: $93)
Bull Market Report Target Price: $92
Bull Market Report Sell Price: We would not sell Microsoft
Earnings Date: Wednesday, 5:30 PM ET
Consensus: 2Q18
Revenues: $28 billion
EPS: $0.86
Year Ago Quarter Results
Revenues: $26 billion
EPS: $0.80
Key Things to Watch For in the Quarter
Microsoft is expected to report an 8% increase in revenues and a 7.5% increase in earnings per share for 2Q18. Microsoft’s ability to beat analyst estimates has been reflected in the stock’s 44% increase over the past year. The firm continues to produce high quality hardware and software, and has a very good understanding of their customer base. Microsoft also allocates an incredible amount of capital to research and development, with its most recent announcement being a push into quantum computing, which some say could be similar to the internet revolution in the 1990s.
---------------------------------------------------------------------
Blackstone Group (BX: $36)
Bull Market Report Target Price: $36
Bull Market Report Sell Price: $31
Earnings Date: Thursday, 11:00 AM ET
Consensus: 4Q17
Revenues: $3.3 billion
EPS: $6.43
Year Ago Quarter Results
Revenues: $2.8 billion
EPS: $5.25
Key Things to Watch For in the Quarter
Blackstone is expected to report an 18% increase in revenue along with a 22% increase in its earnings per share for 4Q17. Blackstone has exceeded analyst estimates in three of the past four quarters, and has seen its stock appreciate 17% over the past year. Technically speaking, the stock has underperformed both the market and the sector, and we believe this is a huge mispricing by the market. Blackstone currently trades at a PE of 15 and yields 5%. At these price levels the stock looks like a steal compared to its competitors.
---------------------------------------------------------------------
United Parcel Service (UPS: $129)
Bull Market Report Target Price: $125
Bull Market Report Sell Price: $106
Earnings Date: Thursday, Exact Time not Available
Consensus: 4Q17
Revenues: $18 billion
EPS: $1.66
Year Ago Quarter Results
Revenues: $17 billion
EPS: $1.63
Key Things to Watch For in the Quarter
Analysts expect UPS to report a 6% increase in revenues and a 2% increase in earnings per share for 4Q17. Despite beating estimates in three of the past four quarters, the stock has slightly underperformed the overall market. The stock has appreciated 24% since this time last year, and we expect to see similar returns moving forward as the demand for logistical services increases. Although we remain bullish on the stock, we are keeping a close eye on Amazon as it begins to roll out its own logistics services, posing a potential threat to UPS.
The stock has passed our Target of $125, and we believe the stock will go higher, as long as the market holds here and moves higher in the coming months. We hereby raise our Target to $142 and our Sell Price to $118.
---------------------------------------------------------------------
Alphabet (GOOG: $1,170)
Bull Market Report Target Price: $1,450
Bull Market Report Sell Price: We would not sell Google
Earnings Date: Thursday, 4:30 PM ET
Consensus: 4Q17
Revenues: $32 billion
EPS: $10.00
Year Ago Quarter Results
Revenues: $26 billion
EPS: $9.36
Key Things to Watch For in the Quarter
We are looking for a 31% increase in revenues and a 7% increase in earnings per share for 1Q18. The company has beaten estimates in three of the past four quarters, which has been reflected in the stock’s 45% appreciation since this time last year. The stock currently boasts a market cap of $815 billion, making it one of the largest publicly traded companies in the world. Although Alphabet is best known for its Google Search Engine, the company touches all aspects of technology from cloud computing to its most recent Television Streaming service through YouTube.
---------------------------------------------------------------------
Apple (AAPL: $165)
Bull Market Report Target Price: $194
Bull Market Report Sell Price: We would not sell Apple
Earnings Date: Thursday, 5:00 PM ET
Consensus: 1Q18
Revenues: $87 billion
EPS: $3.81
Year Ago Quarter Results
Revenues: $78 billion
EPS: $3.36
Key Things to Watch For in the Quarter
We expect to see a 13% increase in earnings per share along with an 11% increase in sales for 1Q18, despite less than ideal results with the release of the iPhone X. The stock has beaten estimates in each of the past four quarters, and has appreciated 38% since this time last year. We also saw Warren Buffet add more stock to his portfolio, which should definitely not be overlooked. We expect to see growth in iPhone and iPad sale over the next year, and remain bullish on the stock. The cash repatriation should begin soon and that will produce some changes – in the dividend and in their outlook on buying new technology firms.
---------------------------------------------------------------------
Visa (V: $123)
Bull Market Report Target Price: $123
Bull Market Report Sell Price: We would not sell Visa
Earnings Date: Thursday, 5:30 PM ET
Consensus: 1Q18
Revenues: $4.8 billion
EPS: $0.99
Year Ago Quarter Results
Revenues: $4.4 billion
EPS: $0.86
Key Things to Watch For in the Quarter
Visa is expected to report a 9% increase in revenues and a 15% increase in earnings per share for 1Q18. Visa has beaten estimates in each of the past four quarters, and seen a 50% appreciation in its stock since this time last year. Despite paying a relatively small dividend, the stock still trades at a PE of 44, suggesting it is fairly valued compared to its competitors. We are confident in Visa’s ability to drive earnings growth through the new year. This $280 billion market cap company is a long term hold.
---------------------------------------------------------------------
Amazon (AMZN: $1,420)
Bull Market Report Target Price: $1,500
Bull Market Report Sell Price: $1,225
Earnings Date: Thursday, 5:30 PM ET
Consensus: 4Q17
Revenues: $60 billion
EPS: $1.84
Year Ago Quarter Results
Revenues: $44 billion
EPS: $1.54
Key Things to Watch For in the Quarter
Analysts expect Amazon to report a 36% increase in revenues and a 19% increase in earnings per share for 4Q17. Despite having only beaten estimates in three of the past four quarters, the stock currently trades 70% higher than its levels this time last year. Amazon continues to lead the charge in the online retail space, and we firmly believe in the longevity of the firm. Although the company trades at a very high PE of 350, we believe this is explained by the company’s inherent ability dominate and revolutionize the Retail industry.
---------------------------------------------------------------------
AstraZeneca (AZN: $36)
Bull Market Report Target Price: $42
Bull Market Report Sell Price: $32
Earnings Date: Friday, exact time not available
Consensus: 4Q17
Revenues: $5.4 billion
EPS: $0.45
Year Ago Quarter Results
Revenues: $5.6 billion
EPS: $0.61
Key Things to Watch For in the Quarter
AstraZeneca is expected to report a 4% decrease in revenues and a 26% decrease in earnings per share for 4Q17. Despite the lack of top line growth, the stock has still managed to beat analyst estimates in each of the past four quarters, and has shown 30% year-over-year appreciation as a result. The stock currently trades at a PE of 26, which is relatively cheap compared to other firms in healthcare which average around 40. The stock pays a 4% dividend, and has room to grow in 2018.
We’re not liking this new development with a slowdown in revenues and earnings and are re-evaluating our take on this stock. More to come this weekend. In the meantime, we are moving our Sell Price to $34.
