December 23, 2019

by Todd Shaver | Dec 23, 2019 | Free Newsletter (Sent Weekly Monday at 12pm), Weekly Newsletter 7pm Sunday
The Weekly Summary
December was chaotic last year, keeping investors glued to their screens as we watched a miserable season turn into one of the biggest rebounds in recent memory. This time around, conditions are unusually quiet as a late Thanksgiving turns into a compressed holiday season. Wall Street is already looking toward the Christmas and New Year breaks. So are we.
After all, Santa came early and often this year. The market as a whole has rebounded 28% YTD, handily recovering all ground lost in the 4Q18 rout and then continuing to push into record territory. The S&P 500 has now rallied a healthy 12% past last year's peak, with more than half of that surge coming in the last four months. Whether the motive is relief that we've skirted another year without a recession or more straightforward optimism, the mood is as good as it gets.
If anything, we're inclined to urge a little caution here. When a full 44% of investors are actively bullish and the so-called "greed index" flashing at extreme levels, this is as good a time as ever to take a little profit and rotate the returns back into stocks that haven't flown as far as the rest of your holdings or offer a comparable return for lower risk. The perfect time to buy was a year ago when everyone but us was terrified that the trade war and the Fed had triggered the end of the world. While today this is not an awful entry point, a selective approach can be your friend here . . . we would definitely not pour money into index funds right now.
After all, while the active BMR universe is up 42% so far this year, our stocks have tangible growth on their side. Earnings for the S&P 500, on the other hand, have spent the entire year in a stall, so there's no compelling mathematical reason for the index to keep moving up without straining historical multiples to the bubble point. Right now the market as a whole carries an 18X earnings multiple, well above the 15-16X that investors have normally been willing to pay.
In exchange for those inflated fundamentals, investors are getting negative growth. Those companies are actually tracking lower earnings than they did a year ago, and are likely to keep deteriorating at least into the 4Q19 reporting season. After that, we'll simply have to see if the combination of lower interest rates and a truce in the global trade war shakes a little growth free. If not, stocks will look increasingly vulnerable to any external shock to sentiment . . . the higher the multiples get, the more precipitous the fall from grace becomes.
However, there's a lot to be said for a sympathetic Federal Reserve and any relief from the trade war. The White House estimates that even Phase One in a deal with China coupled with a new NAFTA accord will boost GDP growth 0.5% in the coming year, which is enough to drive a so-so economic expansion into something approaching spectacular. It's definitely far from the recession zone that everyone was worried about a few months ago.
You need growth to decline in order to realistically talk about recession ahead. No decline means no recession. And no recession means people who retreated to the market sidelines are now having a hard time resisting the urge to get back in before they miss out completely.
Remember, while earnings haven't moved up in the past year, they haven't dropped a lot either. The trade war has delayed a lot of new corporate investment initiatives without driving executives to pull the plug on any established cost centers. We haven't seen mass layoffs. No sprawling Financial conglomerates or prominent hedge funds have imploded the last time the Treasury yield curve briefly inverted.
And that curve is healthier than a few months ago. Barring a lot of dread around the coming election, the rate environment once again reflects lower risk in the short term and higher uncertainty farther out into the future, exactly as it should. The Fed has done its work well. Investors have a reason to cheer.
So what can go wrong? While we are always quick to accentuate the positive, we also acknowledge that other investors make errors when the mood swings too far in either direction. Expectations can get stretched to unsustainable levels, setting up the next inevitable round of disappointment, second guessing and nervous selling. That's ultimately a good thing for those of us who have been watching and waiting for a chance to buy great stocks on the dip. Throughout our career (collectively well past a half century actively in the market) the long-term trend always points up and the dip is always worth buying.
There’s always a bull market here at The Bull Market Report! Gary Jefferson has the week off and with the holiday approaching, we decided to use his absence to try something new with an in-depth review of Todd's Stocks For Success. We hope that you come away from this issue with deeper understanding of why our founder likes Berkshire Hathaway so much. He would buy any of these stocks on weakness.
Finally, a scheduling note ahead of the Christmas holiday. The market will close early on Tuesday and stay shut until Thursday morning, so news will be light and our News Flashes will probably taper off a bit. We'll use the time to reflect on the year that's gone and cement our thinking on the year ahead. Ideally we'll also be able to update the site a little and perform other housekeeping as we get the portfolios in position for 2020. We'll be in touch either way, but as always, we wish you a happy holiday and the best possible experience as an investor.
Key Market Indicators
-----------------------------------------------------------------------------
BMR Companies and Commentary
The Big Picture: Big Rally, Narrow Bench
While the last few months have been great for the S&P 500 and our stocks as well, the gains remain restricted to a narrow field of relatively safe bets. Investors simply aren't thinking outside the box right now. They're content to park their money in a few big stocks that don't require a lot of patience or even conviction. While we'd love a little of that capital to flow immediately to a few of our smaller and more neglected recommendations, we don't mind in the slightest.
For one thing, we already recommend many of the leaders. Just seven BMR stocks account for 40% of the S&P 500's gains for the past quarter, and Apple (AAPL: $279, up 2%) alone contributed almost half of that upside. If you weren't bullish on Apple in the last few months, you missed the boat. We were right to keep the giant in our sights, and it gave us everything we hoped to see. Apple has surged a full 77% this year, recovering $700 billion in market capitalization along the way.
Microsoft, Alphabet and to some extent Facebook, Berkshire Hathaway, Johnson & Johnson and Visa also contributed a significant amount to the market's gains in the last few months . . . not to mention the year as a whole. Big stocks got big because the enterprises driving them were some of the most dynamic companies around. This year, they got even bigger. All are hitting all-time highs. How far can they go before taking a break? We'll simply have to see, but as long as earnings keep outperforming everyone else around, the stocks have all the room they need.
Then there's Amazon (AMZN: $1,787, up 1%), which is as dynamic as ever but the stock hasn't gone anywhere in the last quarter. It's also down 12% from its peak, so there's no sense of straining any kind of historical limit. When investors come back, this can once again be a $2,000 stock and a trillion-dollar company. And in that scenario, the S&P 500 gets enough of a boost to break another record. No other stock has to do any work. Amazon can do it on its own.
We see that story play out again and again. A full 3 in 5 S&P 500 constituents are actively lagging the market and the lower you go on the market food chain, the rarer true leadership gets. A staggering 85% of the stocks on Wall Street have underperformed the S&P 500 this quarter. Most are doing okay. True losses are limited. They're simply getting left out.
But the market will never tolerate an imbalance for long. Sooner or later, one or more giants will hit a wall and the money that's flowing to them now will rotate into smaller stocks. When that happens, we'll have a reason to cheer. On average, our recommendations are still down 12% from their 52-week highs, let alone lifetime peak levels. We've come a long way back in the last few months without even clearing what are still formally correction conditions from late in the summer, when Technology took a huge step back. There's money to be made here.
Look at Roku (ROKU: $137, up 3%). It's up close to 350% YTD but is 22% off its peak. That's an opportunity. Even though a handful of giant companies are doing most of Wall Street's work, plenty of smaller names keep breaking records as well. Splunk (SPLK: $151, up 5% this week), for example, is once again within sight of an all-time high, set in early December, capping a year that's literally run rings around the market as a whole. This stock has gained 44% YTD but the ride has been wild. We've seen it plunge from above $140 to below $110 twice this year, so the moral here is to hold on tight through the retreats.
-----------------------------------------------------------------------------
Berkshire Hathaway (BRK-B: $226, flat last week but setting an all-time high)
This stock is a must-own. If you believe in America, then Berkshire is the place to put your money where your mouth is. The stock is worth $553 billion, making it one of the top 10 largest companies in the world. Do you want to know what they do? Well, here it is, straight from Yahoo Finance. Breathe it all in:
Berkshire Hathaway Inc., through its subsidiaries engages in insurance, freight rail transportation, and utility businesses. It provides property and casualty insurance and reinsurance, as well as life, accident, and health reinsurance; and operates railroad systems in North America. The company also generates, transmits, stores, and distributes electricity from natural gas, coal, wind, solar, hydro, nuclear, and geothermal sources; operates natural gas distribution and storage facilities, interstate pipelines, and compressor and meter stations; and holds interest in coal mining assets. In addition, it offers real estate brokerage services; and leases transportation equipment and furniture. Further, the company manufactures boxed chocolates and other confectionery products; specialty chemicals, metal cutting tools, and components for aerospace and power generation applications; flooring, insulation, roofing and engineered, building and engineered components, paints and coatings, and bricks and masonry products, as well as offers homebuilding and manufactured housing finance; recreational vehicles, apparel products, jewelry, and custom picture framing products; and alkaline batteries. Additionally, it manufactures castings, forgings, fasteners/fastener systems, and aerostructures; titanium, steel, and nickel; and seamless pipes and fittings. The company distributes newspapers, televisions, and information; franchises and services quick service restaurants; distributes electronic components; and offers logistics services, grocery and foodservice distribution services, professional aviation training programs, and fractional aircraft ownership programs. In addition, it retails automobiles; furniture, bedding, and accessories; household appliances, electronics, and computers; jewelry, watches, crystal, china, stemware, flatware, gifts, and collectibles; kitchenware; and motorcycle accessories.
Here are the company’s top five holdings:
Apple
Comprising 24% of the Berkshire Hathaway portfolio, Apple represents Buffett's largest holding, with a whopping 250 million shares in the tech giant, as of November 2019. Currently worth approximately $65 billion, in 2018, Apple surpassed Wells Fargo to capture the #1 spot after Berkshire Hathaway purchased additional shares of the Steve Jobs-founded company in February of that year.
Bank of America
Warren Buffett's second-largest holding is in Bank of America, valued at $27 billion and comprising 13% of his portfolio. Buffett's interest in this company began in 2011 when he helped solidify the firm's finances, following the 2008 economic collapse. Investing in Bank of America, which is the nation's second-largest bank by assets, falls in line with Buffett's attraction to financial stocks, including Wells Fargo & Company and American Express (see below).
The Coca-Cola Company
Buffett once claimed to consume at least five cans of Coca-Cola per day, which may explain why the Coca-Cola stock is his third-largest holding. But one thing is for certain: Buffett appreciates the durability of the company’s core product, which has remained virtually unchanged over time, with the exception of the ill-fated "New Coke" formula rebranding, in the mid-1980s. This makes sense, given that Buffett started buying Coca-Cola shares in the late 1980s, following the stock market crash of 1987. Presently with 400,000,000 shares, valued at $22,000,,000,000, Coca-Cola accounts for 10% of the portfolio.
Wells Fargo
At 9% of his portfolio, Buffett currently holds shares valued at over $19 billion. Although this is Buffett's fourth-largest position, Wells Fargo previously occupied the top slot for many years. A series of scandals that began in 2016, including the creation of millions of dummy bank accounts, unauthorized modifications to mortgage plans, and the fraudulent sale of unnecessary car insurance, has hurt the bank's reputation.
American Express
This company is the third financial services company to make Buffett's top five list, occupying 8% of the portfolio. Valued at nearly $18 billion, Buffett acquired his initial stake in the credit card company in 1963, when it sorely needed capital to expand its operations. Buffett has since been a savior to the company, many times over, including during the 2008 financial crisis. With 12.5% average annual return over the past quarter-century, American Express has proven to be a valuable asset.
We’d like to say THEY COVER IT ALL. Again, if you believe in America and free enterprise, you might just want to buy one share of the A series – it’s only $340,000 per share! (A good friend of ours used to call us up at the office back in our Morgan Stanley days in the 1990s and would leave a message: “I just called to place an order for 100 shares.” That’s when the stock sold for $35,000 a share, so 100 shares was worth $3.5 million. He thought this was hilarious! Well, how about now? 100 shares is worth $34 million! HAHA.
What’s the point about all of this hilarity? Get a piece of this company. 10 shares. 100 shares. 1000 shares. Whatever you can afford. You’ll never regret it. Our Target of $230 is about to be breached. We hereby raise it to $255. Our Sell Price remains the same: We would not sell Berkshire Hathaway.

-----------------------------------------------------------------------------
Good Investing,
Todd Shaver, Founder and CEO
The Bull Market Report
Since 1998
July 22, 2019
by Scott Martin | Jul 22, 2019 | Earnings Preview 6 PM, Instant News Flash
Netflix (NFLX: $362, down 3% earlier this week) disappointed last night and the stock's precipitous overnight decline provides us with a different kind of wake-up call. Whether you're in Netflix or not, you're going to want to read this flash.
On the surface, Netflix delivered a quarter almost entirely in line with what investors told themselves they wanted to see. Revenue of $4.92 billion was only 0.1% below guidance and reflects healthy 26% year-over-year improvement. Even quarter-to-quarter, the company squeezed 9% more cash out of its subscribers than it did three months ago.
Furthermore, despite profit being a lower priority while management invests vast amounts in original content, it was nice to see that Netflix carried $0.60 per share across the bottom line, $0.04 better than we expected.
But the market found fault as Netflix missed its subscriber growth target, losing 126,000 paid U.S. accounts and only adding 2.83 million new viewers overseas. Management told us to expect the audience to grow by an even 5 million accounts, so it's a clear disappointment.
There are some compensating factors like the way revenue hit guidance. Netflix raised prices in many markets and this is apparently where the pain point is. We know that now. Furthermore, management has doubled down on its aggressive growth forecasts and now expects subscriber adds to accelerate again in the current quarter.
We've had it with Netflix. We've warned throughout that it's going to be a volatile ride. The stock is now down 20% since we started covering it this time around, after making 65% back in 2016-17. We're worried about competitors like Disney and Apple starting to crowd into the space. With a negative $3.5 billion of free cash flow this year and next, we'd rather be invested in a company that actually makes money. We hereby remove Netflix from our High Tech portfolio. We added them on July 16th last year. We're gone now on July 18th, 2019.
However, even for a volatile stock, the reaction to so-so numbers was so extreme that we now suspect that the market as a whole is getting overheated. It's not Netflix. It's Wall Street. And an overheated market can lurch lower as fast as it soars. Even counting the stocks that fizzled and left our list under a cloud, the BMR universe is up a dramatic 33% YTD. This is a great time to lock in some of that profit before a moody market can take it away.
Is It Time to Take Some Profits?
Why are we asking this question?We can’t predict the future. You may think we can, but we can’t. And we want YOU to think about where YOU are and where you are going with your investments. We have made some amazing stock picks and we’ve made you a lot of money in many of these. (We’ve had a few losers too.) Roku is now a triple since we added it last year. Shopify is up 350% in two years. Square is another quadruple play. PayPal, Twilio, Paycom, Microsoft, Apple, Visa: all strong performers.
Is it time to take some of that off the table? There are a lot of things to worry about in the world today: Trump, Chinese tariffs, Iran, immigrants, global slowdown, flat earnings for the past quarter and next; negative interest rates in Europe and Japan . . . can they happen here? If so, will the Fed run out of ammunition if short rates go to zero? What about the attacks on Big Tech by Congress and the European Union? Can Facebook, Amazon and Google survive this onslaught? Of course they will, but why sit around with someone hitting you on the head with a hammer. Maybe it’s better to step a little away from the scene.
Lots of questions. No solid answers. Irrational exuberance was proclaimed by Alan Greenspan on December 5, 1996 after an amazing bull run in the preceding few years. But the bull market continued to skyrocket until the Spring of 2000. That’s almost 3½ years after Greenspan’s call. So is it too early to start taking profits now?
Again, we don’t know, but we do know that there are things you can do. You can sell some calls against your stocks. This brings in cash and cushions you on the downside a bit. But if Roku, which was at $32 at the start of the year goes from $110 now to $90 or even lower, it’s not going to cushion you much with $5 of call option income. So perhaps you can take some profits off the table. Maybe you should put some stops in place. Sell some at $104. Sell some shares if it hits $96. Sell some more if it hits $90. Then if it goes to $70, which is a distinct possibility in a nasty bear market, you’ve protected your profits and have cash in the bank.
And don't forget, we’ve got 17 stocks in our High Yield and REIT portfolios that are paying from 3% to 11% dividends. (Be wary of Annaly and New Residential, though.) These stocks are just waiting for you to place some cash in them so that you can sleep better at night.
This content is for our beloved subscribers and anything you see on this page is just an excerpt!
Please note BullMarket.com access is available to paid subscribers only. Our Members Areas include archives of past Newsletters, News Flashes, our ten portfolios including STOCKS FOR SUCCESS, Healthcare, High Yield, High Technology, Exchange Traded Funds (ETF's), Energy, Senior Growth Opportunities, Financial, Long Term Growth, and Special Opportunities. Also, all of our in-depth research is available, and more.
Already a subscriber?
Login Here
Ready to join?
Subscribe Now!
July 19, 2019
by Scott Martin | Jul 19, 2019 | Instant News Flash
Netflix (NFLX: $362, down 3% earlier this week) disappointed last night and the stock's precipitous overnight decline provides us with a different kind of wake-up call. Whether you're in Netflix or not, you're going to want to read this flash.
On the surface, Netflix delivered a quarter almost entirely in line with what investors told themselves they wanted to see. Revenue of $4.92 billion was only 0.1% below guidance and reflects healthy 26% year-over-year improvement. Even quarter-to-quarter, the company squeezed 9% more cash out of its subscribers than it did three months ago.
Furthermore, despite profit being a lower priority while management invests vast amounts in original content, it was nice to see that Netflix carried $0.60 per share across the bottom line, $0.04 better than we expected.
But the market found fault as Netflix missed its subscriber growth target, losing 126,000 paid U.S. accounts and only adding 2.83 million new viewers overseas. Management told us to expect the audience to grow by an even 5 million accounts, so it's a clear disappointment.
There are some compensating factors like the way revenue hit guidance. Netflix raised prices in many markets and this is apparently where the pain point is. We know that now. Furthermore, management has doubled down on its aggressive growth forecasts and now expects subscriber adds to accelerate again in the current quarter.
We've had it with Netflix. We've warned throughout that it's going to be a volatile ride. The stock is now down 20% since we started covering it this time around, after making 65% back in 2016-17. We're worried about competitors like Disney and Apple starting to crowd into the space. With a negative $3.5 billion of free cash flow this year and next, we'd rather be invested in a company that actually makes money. We hereby remove Netflix from our High Tech portfolio. We added them on July 16th last year. We're gone now on July 18th, 2019.
However, even for a volatile stock, the reaction to so-so numbers was so extreme that we now suspect that the market as a whole is getting overheated. It's not Netflix. It's Wall Street. And an overheated market can lurch lower as fast as it soars. Even counting the stocks that fizzled and left our list under a cloud, the BMR universe is up a dramatic 33% YTD. This is a great time to lock in some of that profit before a moody market can take it away.
Is It Time to Take Some Profits?
Why are we asking this question?We can’t predict the future. You may think we can, but we can’t. And we want YOU to think about where YOU are and where you are going with your investments. We have made some amazing stock picks and we’ve made you a lot of money in many of these. (We’ve had a few losers too.) Roku is now a triple since we added it last year. Shopify is up 350% in two years. Square is another quadruple play. PayPal, Twilio, Paycom, Microsoft, Apple, Visa: all strong performers.
Is it time to take some of that off the table? There are a lot of things to worry about in the world today: Trump, Chinese tariffs, Iran, immigrants, global slowdown, flat earnings for the past quarter and next; negative interest rates in Europe and Japan . . . can they happen here? If so, will the Fed run out of ammunition if short rates go to zero? What about the attacks on Big Tech by Congress and the European Union? Can Facebook, Amazon and Google survive this onslaught? Of course they will, but why sit around with someone hitting you on the head with a hammer. Maybe it’s better to step a little away from the scene.
Lots of questions. No solid answers. Irrational exuberance was proclaimed by Alan Greenspan on December 5, 1996 after an amazing bull run in the preceding few years. But the bull market continued to skyrocket until the Spring of 2000. That’s almost 3½ years after Greenspan’s call. So is it too early to start taking profits now?
Again, we don’t know, but we do know that there are things you can do. You can sell some calls against your stocks. This brings in cash and cushions you on the downside a bit. But if Roku, which was at $32 at the start of the year goes from $110 now to $90 or even lower, it’s not going to cushion you much with $5 of call option income. So perhaps you can take some profits off the table. Maybe you should put some stops in place. Sell some at $104. Sell some shares if it hits $96. Sell some more if it hits $90. Then if it goes to $70, which is a distinct possibility in a nasty bear market, you’ve protected your profits and have cash in the bank.
And don't forget, we’ve got 17 stocks in our High Yield and REIT portfolios that are paying from 3% to 11% dividends. (Be wary of Annaly and New Residential, though.) These stocks are just waiting for you to place some cash in them so that you can sleep better at night.
This content is for our beloved subscribers and anything you see on this page is just an excerpt!
Please note BullMarket.com access is available to paid subscribers only. Our Members Areas include archives of past Newsletters, News Flashes, our ten portfolios including STOCKS FOR SUCCESS, Healthcare, High Yield, High Technology, Exchange Traded Funds (ETF's), Energy, Senior Growth Opportunities, Financial, Long Term Growth, and Special Opportunities. Also, all of our in-depth research is available, and more.
Already a subscriber?
Login Here
Ready to join?
Subscribe Now!
February 4, 2018

by Todd Shaver | Feb 4, 2018 | Weekly Newsletter 7pm Sunday
The Weekly Summary
The stock market took a hit this week. It was down almost 200 on Monday, almost 400 on Tuesday, rallied a tad on Wednesday and Thursday, and got hammered on Friday to the tune of 666 points. It’s a week we can happily say has been put to bed and we can now forget about it. The long-awaited correction has now occurred. Happy now Wall Street pundits? (We don’t feel this way.) The big reason for the sell-off was interest rates. The 10-year was up again to 2.84%. And the 30-year moved up above 3%. But this is what happens when you have a strong economy – interest rates move up. This has been happening for over 100 years. The economy shines; interest rates go up. Why do you think rates have been so low? Because the Fed drove down rates after the debacle of 2008-2009 and kept them there for almost 10 years. Look at this chart here; it’s a bit hard to read at first – note that the right column shows the rate today – 1.48% and in 2008 it was 1.04%.
Now take a look at these two charts. The first one is the 10-year Treasury for the past six months. It's gone straight up.
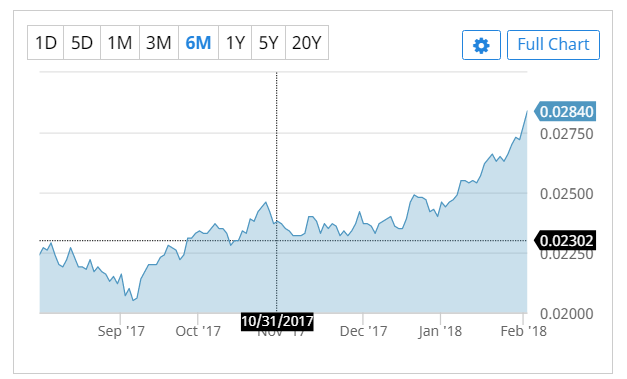
And this one is the 10-year for the past 20 years. Basically straight down.

The key takeaway here is the interest rates are STILL VERY LOW HISTORICALLY. This is actually good news for the economy and stocks. Thus it is our take that 1) We had a bad week last week 2) Things will calm down this week and in the coming months, and 3) Good solid companies will continue to thrive and grow as the US economy continues to strengthen.
Easy for us to say. Hard for you to implement. We understand that. But we want you to put this past weekly move in perspective. The market is where it was just three weeks ago, at 25,500. A year ago it was at 20,000.
The big oil companies came up a bit short on the earnings front last week. Most of the Street was expecting good things, as the price of crude has remained strong at $65. But Exxon’s production dropped by 130,000 barrels a day and has lost money now for 12 quarters a row on its US drilling business, even as US production touched the record production of 10 million barrels a day in November, the previous record being set in 1970. Plus they took a $1.3 billion write-down on its natural gas business. But overall, Exxon made $3.73 billion, a decline of just 2%. These big companies are expected to generate huge amounts of cash in 2018, so we aren’t feeling too sorry for them. The number could be over $40 billion, in excess of dividends and new spending.
Super Bowl Sunday is here! $5 million for a 30 seconds ad. Over 110 million viewers likely watched. The legacy of Tom Brady’s Patriots against the surprisingly better than you think Eagles. The Patriots are favored by 4.5 points. It is interesting. Very often in sports or in the markets whatever people expect to happen, doesn’t materialize. For all sorts of reasons: Cognitive dissonance. Conservative bias. Confirmation bias. Extrapolating past performance. Loss aversion. Overconfidence. Self-control. Regret aversion. Affinity. Status quo. The list of mental mistakes people make when investing is long and always at play. We saw a 666 point drop on the Dow on Friday. This was the 3rd largest one-day point decline in history. The market is digesting something. The Bull & Bear indicator managed by Merrill Lynch has finally flashed a firm sell signal after weeks of overextended conditions. We will see what happens Monday. The unexpected could happen. Just like in football.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight: Microsoft, Google, Amazon, Facebook, PayPal, and Blackstone.
Key Market Measures

BMR Companies & Commentary
Microsoft (MSFT: $92, down 2%)
Revenue was $28.9 billion and increased 12%. EPS hit a solid $0.96 crushing the $0.87 consensus. This quarter’s results speak to the differentiated value Microsoft is delivering to customers across productivity solutions and as the hybrid cloud provider of choice. The firm’s investments in IoT, data, and AI services across cloud, position the business to further accelerate growth. In particular, Microsoft delivered another strong quarter with commercial cloud revenue growing 56% year-over-year to $5.3 billion, which is just amazing to see such a huge growth figure in the lucrative cloud opportunity. Guidance for Q3 was largely in-line or better than consensus expectations. All in all, a very good quarter.
BMR Take: Microsoft is a stock market darling. The business is well-rounded. Legacy Window products to the up and coming Azure product in commercial cloud. We see Microsoft continuing to piece together solid earnings results in the year ahead. With $4.25 of EPS in direct sight, the stock still screens reasonable at around 22x.
----------------------------------------------------------------------------------
Google (GOOG: $1,112, down 5%)
Revenue of $32 billion increased 24% from a year ago. EPS of $9.70 just missed the consensus for $10.00. Overall, we are interpreting the quarter’s results favorably (unlike the Street.) Mobile and desktop search along with YouTube are powering accelerating growth and these trends should drive sustained above average growth going forward. Google Cloud momentum is good now generating $1 billion in revenue per quarter, where the number of $1 million or more contracts across cloud products tripled in 2017. Google has now sold ‘tens of millions’ of its Mini, Max, and Chromecast devices as Google Assistant is now on over 400 million devices globally. Waymo’s progress is accelerating. They plan to launch a ride-sharing program in Phoenix operated by self-driving cars this year. Wow.
BMR Take: We really don’t care much about the slight EPS miss. The stock being down is an opportunity to accumulate shares. Scouring through all the analysis on the quarter, nobody is really saying anything that seriously concerns us. What we want to see going forward is more progress on the cloud business. Amazon AWS is now at 35% market share versus Google Cloud only in the high single digits. If Google can close that gap, this stock can continue its strong move higher. With nearly $50 of EPS coming into view, the current valuation of 23x is far from stretched.
----------------------------------------------------------------------------------
Amazon (AMZN: $1,430, up 2%)
Amazon is crushing it. What else is new? (!) Net sales increased 38% to $60 billion in the fourth quarter, compared with $44 billion in 4Q16. EPS of $6.15 was well above $4.90 a year ago. There is so much to discuss here. What we are really excited about is the Echo business. Earlier in the year Amazon introduced three new Echo devices: the all-new Echo ($100), featuring a new design, improved sound, a lower price, and a choice of colors to personalize your device; Echo Plus ($150) with a built-in smart home hub so customers can easily set up and control their smart home devices; and Echo Spot ($130), a compact Echo with a screen so you can see the weather, get the news with a video flash briefing, view lyrics with Amazon Music, watch a camera monitor, browse and listen to Audible, and more.
This new business opportunity could be huge. Said Jeff Bezos, Amazon founder and CEO, “Our 2017 projections for Alexa were very optimistic, and we far exceeded them. We don’t see positive surprises of this magnitude very often — expect us to double down. We’ve reached an important point where other companies and developers are accelerating adoption of Alexa. There are now over 30,000 skills from outside developers; customers can control more than 4,000 smart home devices from 1,200 unique brands with Alexa; and we’re seeing strong response to our new far-field voice kit for manufacturers. Much more to come and a huge thank you to our customers and partners.”
While Amazon doesn’t break out the financials on Alexa and its other electronics business, the results from its cloud-computing business, Amazon Web Services (AWS), were obvious and contributed much more to the company’s record profit total. AWS saw revenue shoot 45% higher to $5.1 billion, with profits of $1.3 billion. Wow – that’s 26% after tax. AWS and the tax gain of $790 million for the changes in the U.S. tax code, which lowers Amazon’s tax rate to 21%, were the biggest contributors to the company’s overall net income of $1.86 billion. Watch for a possible spin-off of the cloud business sometime this year. Can you imagine what this will do to the stock? Does “shoot higher” ring in your head?
BMR Take: Look, when Jeff Bezos gets surprised by how good a business is doing, and says he is doubling down, you have to take note. But don’t just take note. Take action on it too. You have to have Amazon in your portfolio. You can’t look at the business on current revenue or earnings and say it’s cheap or expensive. It’s an innovation machine. They are constantly doing start-ups, like Echo. More new paid members joined Prime in 2017 than any previous year — both worldwide and in the US. The business is roaring with momentum and still has a very bright future ahead even at the current stock price level.
----------------------------------------------------------------------------------
Facebook (FB: $190, flat)
Flat for the week. Not bad in the whole scheme of things. Facebook increased revenue 47% to $13 billion. EPS of $1.44 was up 19%. What a good quarter frankly. Though while 2017 was a strong year for Facebook, it was also a hard one," said Mark Zuckerberg, Facebook founder and CEO. "In 2018, we're focused on making sure Facebook isn't just fun to use, but also good for people's well-being and for society. We're doing this by encouraging meaningful connections between people rather than passive consumption of content. Already last quarter, we made changes to show fewer viral videos to make sure people's time is well spent. In total, we made changes that reduced time spent on Facebook by roughly 50 million hours every day. By focusing on meaningful connections, our community and business will be stronger over the long term."
Some analysts were scrambling a bit to figure out what this all mean. But monthly active users increased 14% from a year ago to 2.13 billion. Essentially, the issue is that Facebook has had a huge growth engine coming from adding users. Seriously 2.2 billion users is huge. The runway here is slowing down and that means Facebook is going to have to find another way to take over the world. And that is what Zuckerberg is saying. They will be focusing on quality of usage and fully monetizing existing users.
BMR Take: The company is look at EPS growing from $5.40 in 2017 to $8.70 in 2019. It is not easy to find a 20% earnings growth story. We really like the global platform Facebook has built and all the future opportunities it creates for advertising and other revenue opportunities. We see the same story here as elsewhere in large cap tech, trading for 22x is just not stretched.
The stock hit a new all-time high of $195 on Thursday and even traded at $194 on Friday, before the deluge. What a great company.
Stay the course.
Look at this 5-year chart. Where do you think it is headed, as it moves to 2.5 billion users?

Active Users Chart

----------------------------------------------------------------------------------
PayPal (PYPL: $77, down 10%)
PayPal delivered strong numbers. Revenue increased 26% to $3.7 billion. EPS increased 57% to $0.50. Overall, PayPal had a transformative year in 2017. The company brought record numbers of new customer accounts to the platform by simplifying life for consumers and merchants.
PayPal also substantially expanded its opportunities for future growth and redefined its competitive position through successful partnership strategies. For example, PayPal and Synchrony Financial announced an agreement expanding their consumer credit relationship. Under the terms of the transaction, Synchrony Financial will acquire PayPal's U.S. consumer credit receivables portfolio, which totaled approximately $6.4 billion at the end of 2017.
BMR Take: So why is the stock down? PayPal and eBay have signed a term sheet to make PayPal available as a way to pay on eBay, through July 2023. But the fact that PayPal’s exclusivity on eBay is going away has people up in arms. This aspect of the PayPal and eBay relationship has been well-discussed and should not surprise people. Don’t let it fool you.
We look at PayPal like this. This quarter new customers increased 9 million up to 227 million total customers. Facebook has over 2 billion users. With time PayPal could look a lot more like Facebook. That means massive growth still lies ahead. We believe in riding this train. We are talking about the next gen MasterCard or Visa here. A 10% drop in the stock is a good opportunity to take advantage of.
----------------------------------------------------------------------------------
The Blackstone Group (BX: $35, down 4%)
Total revenue ended the year at $7 billion up 39% from last year. EPS of $2.21 compared to just $1.56 a year ago, a huge 42% jump. This business is grooving! It was another strong quarter of core business trends. Specifically, total assets under management increased an elevated 12% sequentially to a record $435 billion, driven primarily by $62 billion of inflows. Capital deployment of $20 billion in the quarter represented a record. And dry powder remained elevated at $95 billion, which bodes well for future capital deployment levels. Just to put that in perspective, Blackstone realized half of the $7 billion of revenue this year from carried interest on prior year inflows, that were deployed to generate big gains of which Blackstone gets a percentage of the profits.
You are telling me the company has $95 billion to put to work to do more of this? Let’s assume on average they can collect a 10% carry on that money. They just doubled the business.
BMR Take: It was a truly exceptional year for Blackstone, reflected by outstanding earnings growth and record capital activity that drove their highest-ever level of aggregate cash distributions to shareholders. Blackstone’s tireless drive to innovate has enabled the company to launch large-scale new product areas that reach a wider client base and serve existing clients in new ways. Our investors in turn have entrusted the company with more capital than ever before, leading to a new record total assets under management of $435 billion, up 18% year-over-year. The stock is a good value at just 10x the current EPS of $3.25.
----------------------------------------------------------------------------------
----------------------------------------------------------------------------------
Economic Calendar
Total Light Vehicle Sales
Monday, February 5th, 10:00 AM
Period: January
Consensus: 17.2 million
Prior: 17.8 million
Consumer Credit
Wednesday, February 7th, 3:00 PM
Period: December
Consensus: $19.5 billion
Prior: $28.0 billion
Initial Claims
Thursday, February 8th 8:30 AM
Period: February 3rd
Consensus: 233,000
Prior: 230,000
----------------------------------------------------------------------------------
----------------------------------------------------------------------------------
Apple Reports Earnings
Apple (AAPL: $161, down 6%) sold 77 million iPhones in the holiday quarter. Apple’s forecast for the next quarter was also lighter than expected. Apple says they expect to sell 50 million iPhones this quarter, slightly lower than the Street expected, and this equates to slightly lower revenue and the main reason the stock got hammered last week.
Apple still blew past its own and analysts’ expectations for revenue and profit for its fiscal first quarter, reporting record sales of $88.3 billion and net income of slightly more than $20 billion. The company was able to increase revenue by 13% year-over-year by increasing iPhone prices and generating more money from the people buying Apple’s smartphones.
Apple jacked up the price on its premium iPhone X smartphone, starting the 10th-anniversary model at $1,000, pushing the average selling price, or ASP, of an iPhone far higher than analysts had ever experienced. IPhone buyers paid an average of more than $796 for their phones in Apple’s fiscal first quarter; iPhone ASP had never previously topped $700.
Apple also boosted its software and services segment revenue 18% year-over-year in the quarter to $8.5 billion. And listen to this:The App Store, Apple Music, iCloud and Apple Pay all had their biggest quarters ever.
Apple said, “During the week beginning Dec. 24, a record number of customers made purchases or downloaded apps from the App Store, spending $900 million in that 7-day period, followed by $300 million in purchases on New Year’s Day alone.”
“Other products” revenue grew the biggest of all. This includes smartphone accessories like the Apple Watch, which grew sales 50% year-over-year for the fourth consecutive quarter, as well as AirPods. Revenue hit $5.5 billion by selling such hardware, up 36% more than a year ago.
Apple is capitalizing on the opportunity at hand by producing more money out of iPhone users in every way possible. Apple is making more money on each iPhone, selling a few accessories to go with it, then signing up iPhone users for monthly subscription plans for services such as Apple Music and iCloud.
If Apple Music continues to grow at its current rate, it will officially overtake Spotify this summer as the streaming world's number one service. Apple Music has a monthly growth rate of around 5%. Spotify has a growth rate of just around 2%. If that keeps up, Apple Music will officially bump Spotify off the top in summer - and there's no reason to believe it can't, given that part of Apple's success in building an audience for Apple Music lies in the fact that the service comes bundled with most of the major devices the company sells.
BMR Take: The all-time high of $180 was hit January 18th. Two weeks ago the stock was down $7 and last week $11. Looks like a sale is going on in shares of this great company. Wait until that overseas cash starts hitting the books here in the US.

----------------------------------------------------------------------------------
VMware (VMW: $123) is Wrapped Up in a Dell Move
One way or the other it’s time to move on from VMware. Why? Dell Technologies owns 80% of the company and is discussing in the press whether to have VMware buy Dell in order for Dell to go public. It’s a back door tactic very rarely, if ever used before. It has impacted VMware greatly because no one really knows how it is going to play out. It looks like VMware might end up owning Dell, creating a behemoth Tech company consisting of Dell, VMware and EMC, plus a host of other tech businesses like cloud computing and cybersecurity. This might be a good investment, but little is known of its financials at this time, so we feel it best to wait and see how things shake out.
VMware was much higher a week ago, and Wall Street is quite nervous because it doesn’t really understand what is going on. The Street doesn’t like uncertainty, remember? (!)
BMR Take: We added the stock a year ago at $83 and we are up a shade under 50%. We think that’s a nice return (a GREAT return) and with everything going on with these new moves by Dell, we think it is time to take profits, sit on the sidelines and watch. Dell may be a stock to buy someday after they go public, but we will leave that decision for another day.
----------------------------------------------------------------------------------
----------------------------------------------------------------------------------
The High Yield Corner
By Michael Foster
Vice President of High Yield
After the S&P 500’s 2% drop on Friday, which has inspired headlines such as “stocks have worst decline in 2 years”, it’s easy to lose sight of the fact that the S&P 500 is up 3.4% YTD.
Before the decline, stocks were up 7.5%, so a drop was clearly necessary [so they say.] Investors who have gotten comfortable with a bull market may be a little scared, because they aren’t used to down days. And it’s easy to forget what is driving the bull market. Wages are up nearly 3% in the U.S., unemployment keeps dropping, corporate earnings are rising, and, perhaps most impressively, this strong economy is being mirrored around the world. The typically cautious IMF and World Bank have asserted that growth is strong around the world, and while these institutions have made a lot of blunders in the past, they aren’t SO euphoric as to bring out the contrarian bear in us.
For high yield, the cautions are amplified. Riskier income producers like Government Properties Income Trust (GOV: $16.65, down 7%) and AllianzGI Equity & Convertible Fund (NIE: $21, down 5%) are down heavy, although they operate in very different markets and are entirely different asset classes (REITs versus convertible bonds and covered-call stocks). To wit: the AllianzGI’s 5% decline on the stock is far steeper than its 2.9% NAV decline, which is itself slightly better than the S&P 500’s 3.2%. Now, of course we can’t read too heavily into short-term price movements, but at the very least this tells us something about the AllianzGI Fund: it is not making extremely risky bets on very volatile assets, so it isn’t in any danger right now. So why did it sell off in excess of its NAV selloff? You got it. Because of fear. And that’s why the fund remains a buy. It’s up 1.6% for the year, lagging the overall market by a bit.
And what about Government Properties Trust (GOV: $16.65, down 7%)? We recommended this REIT back in 2016 and although the REIT is down 7% since then on a price return basis, much more importantly its dividend has not been cut since then, and investors have actually gotten cash dividends of about 19% on their original investment since our recommendation. As a result, we’ve made a profit on a total return basis. And the dynamics of the fund haven’t changed. The REIT’s FFO over the last 12 months is $2.28, while the dividend is $1.72. Thus its FFO is 133% of dividend payouts, so it’s out-earning its dividend. There is no threat to the dividend stream in the short term, and rising rents thanks to a booming economy mean FFO will go up, resulting in even higher FFO coverage.
The income stream here is not at any risk, despite the implications of the recent absurd sell-off. Revenues have been rising by about 8%, so we don’t see any indication that revenues can’t support the current dividend payout. For this reason, there’s no reason to be more cautious about Government Properties, and plenty of reason to shrug off the recent price declines. In fact, it is a great time to add more to this very stable company that is absurdly undervalued.
Elsewhere in REITs, declines were much less severe. Only Omega Healthcare Investors (OHI: $26, down 3%) saw a decline in-line with the S&P 500, but that’s not surprising. We’ve discussed at length why this company’s dividend hikes are threatened, but the threat won’t materialize for years (we’ve estimated 5 years). Dips are buying opportunities for now, as long as investors are cognizant of the fact that the dividend hikes won’t last forever and the stock could sell off in a few years as a result. But if you want a strong and secure high income stream now, Omega is one way to do it.
Digital Realty Trust (DLR: $108) was the second-best investment in the Bull Market Report High Yield portfolio. It was flat for the week. That sounds bad, especially if you’ve gotten used to gains upon gains and few down days, which has been the market norm since the High Yield portfolio began in 2016. But it also shows, interestingly, that the market has a lot of confidence in Digital Realty (which also outperformed a lot of the Tech sector). This week, Amazon, Apple, and Alphabet reported earnings that proved the world’s demand for data centers isn’t going away. Alas, Digital Realty’s yield is tiny, but as an investment in a good company, it’s a great option for investors.
Apollo Commercial Real Estate (ARI: $18.14, down 1%), Ventas, (VTR: $54, down 3%), and Welltower (HCN: $58, down 3%) all saw slight declines, which we can consider to be more a result of REIT investors following the broader market trend. No big news came from any of these companies last week to warrant the selloff.
Similarly, AstraZeneca (AZN: $36, down 2%) fell a lot less than the broader market after weeks of strength in the Biopharma sector. AstraZeneca has not released any major news and there wasn’t any major sector announcements. We can dismiss this 2% decline as being relatively good in a week of short-term worriers cutting bets on all kinds of things more because of fear than for any fundamental reason.
Now, on to municipal bonds. The end-of-year sell-off in this asset class in anticipation of 2018’s rate cuts meant that these funds were attractively priced for income investors, and we still think long-term capital gains are in the cards. What we need to see is the market get used to our new Fed Chairman. While Janet Yellen did a wonderful job of managing monetary policy and bringing the Fed funds rate closer to historical norms, the job isn’t done. Jay Powell has already said that he will continue in the same mode. And that will limit enthusiasm for municipal bonds. that is, until the booming economy results in higher tax revenues for municipalities that, in turn, results in credit upgrades and thus increasing NAVs for our muni Closed End Funds. The timing on this eventuality is unclear, but there is good reason to be confident that it will happen eventually. Nuveen AMT-Free Municipal Credit Fund (NVG: $14.48, down 3%) and Invesco Municipal Trust (VKQ: $11.83, down 4%) are worth holding for the tax-free income as we wait.
PIMCO Dynamic Income Fund (PDI: $30) is the only High Yield holding to be up for the week, and for that we are grateful! But just as there’s little to read into the short-term declines, the short-term gain here isn’t a reason to celebrate. The market is all about short-term emotion-driven trading. If anything, the fact that the panic didn’t hit the Pimco fund may indicate that no matter how crazy the broader market is, we aren’t in full-blown panic mode. And that, quite possibly, could mean this correction won’t last very long.
Good Investing,
Todd Shaver, Founder and CEO
The Bull Market Report
Since 1998
January 30, 2018
by Todd Shaver | Jan 30, 2018 | Earnings Preview 12 PM
Equity Residential (EQR: $61)
Bull Market Report Target Price: $85
Bull Market Report Sell Price: $55
Earnings Date: Tuesday, After market close
Consensus: 4Q17
Revenues: $625 million
EPS: $0.36
Year Ago Quarter Results
Revenues: $605 million
EPS: $0.75
Key Things to Watch For in the Quarter
Analysts expect Equity Residential to report a 3% increase in revenues with a 50% decrease in earnings per share. Despite having beat estimates in each of the past four quarters, the stock is only trading 2% above its price this time last year. Nearly all of the stock’s 15% gains for the year have been wiped out since November with the oversupply issues in the real estate market. We believe the stock is oversold at its current levels, and will see support in the $60 range.
---------------------------------------------------------------------
Eli Lilly (LLY: $86)
Bull Market Report Target Price: $96
Bull Market Report Sell Price: $82
Earnings Date: Wednesday, 9:00 AM ET
Consensus: 4Q17
Revenues: $6.0 billion
EPS: $1.07
Year Ago Quarter Results
Revenues: $5.8 billion
EPS: $0.95
Key Things to Watch For in the Quarter
Eli Lilly is expected to report a 3% increase in revenues and a 13% increase in earnings per share for 4Q17. The stock has beat estimates in three of the past four quarters, and is currently trading 17% above its price levels from this time last year. The stock saw a bit of resistance at $86 earlier this year, and it had recently broken through, but with the tough market of the last two days, the stock is back to $86. This pharmaceutical company invests heavily in its research and development, which will drive its future sales and earnings growth.
---------------------------------------------------------------------
Facebook (FB: $186)
Bull Market Report Target Price: $190
Bull Market Report Sell Price: $155
Earnings Date: Wednesday, 5:00 PM ET
Consensus: 4Q17
Revenues: $12.5 billion
EPS: $1.95
Year Ago Quarter Results
Revenues: $8.8 billion
EPS: $1.41
Key Things to Watch For in the Quarter
Analysts expect Facebook to report a 42% increase in revenues and a 38% increase in earnings per share for 4Q17. Facebook has beaten estimates in three of the past four quarters which has been reflected in the stock’s 42% appreciation over the past year. Facebook’s growth over the past years has been unprecedented for a company of its size. It truly is adhering to its mission of creating a more connected world. We look forward to seeing what kind of developments CEO Mark Zuckerberg has in store for the connected world in 2018. We know it will be good.
---------------------------------------------------------------------
PayPal Holdings (PYPL: $83)
Bull Market Report Target Price: $87
Bull Market Report Sell Price: We would not sell PayPal
Earnings Date: Wednesday, 5:00 PM ET
Consensus: 4Q17
Revenues: $3.6 billion
EPS: $0.52
Year Ago Quarter Results
Revenues: $3.0 billion
EPS: $0.42
Key Things to Watch For in the Quarter
We are looking for a 20% increase in its sales and a 24% increase in its earnings per share for the 4th quarter of 2017. The stock has been on a tear since last year, returning investors a 110% capital appreciation since this time last year. The stock has gone nowhere but up since posting earnings that have exceeded expectations in the past four quarters. PayPal’s market cap is just over $100 billion, making it the largest publicly traded electronic payments company in the world. We look forward to seeing what PayPal has to offer as they continue to lead this growing industry.
---------------------------------------------------------------------
Microsoft (MSFT: $93)
Bull Market Report Target Price: $92
Bull Market Report Sell Price: We would not sell Microsoft
Earnings Date: Wednesday, 5:30 PM ET
Consensus: 2Q18
Revenues: $28 billion
EPS: $0.86
Year Ago Quarter Results
Revenues: $26 billion
EPS: $0.80
Key Things to Watch For in the Quarter
Microsoft is expected to report an 8% increase in revenues and a 7.5% increase in earnings per share for 2Q18. Microsoft’s ability to beat analyst estimates has been reflected in the stock’s 44% increase over the past year. The firm continues to produce high quality hardware and software, and has a very good understanding of their customer base. Microsoft also allocates an incredible amount of capital to research and development, with its most recent announcement being a push into quantum computing, which some say could be similar to the internet revolution in the 1990s.
---------------------------------------------------------------------
Blackstone Group (BX: $36)
Bull Market Report Target Price: $36
Bull Market Report Sell Price: $31
Earnings Date: Thursday, 11:00 AM ET
Consensus: 4Q17
Revenues: $3.3 billion
EPS: $6.43
Year Ago Quarter Results
Revenues: $2.8 billion
EPS: $5.25
Key Things to Watch For in the Quarter
Blackstone is expected to report an 18% increase in revenue along with a 22% increase in its earnings per share for 4Q17. Blackstone has exceeded analyst estimates in three of the past four quarters, and has seen its stock appreciate 17% over the past year. Technically speaking, the stock has underperformed both the market and the sector, and we believe this is a huge mispricing by the market. Blackstone currently trades at a PE of 15 and yields 5%. At these price levels the stock looks like a steal compared to its competitors.
---------------------------------------------------------------------
United Parcel Service (UPS: $129)
Bull Market Report Target Price: $125
Bull Market Report Sell Price: $106
Earnings Date: Thursday, Exact Time not Available
Consensus: 4Q17
Revenues: $18 billion
EPS: $1.66
Year Ago Quarter Results
Revenues: $17 billion
EPS: $1.63
Key Things to Watch For in the Quarter
Analysts expect UPS to report a 6% increase in revenues and a 2% increase in earnings per share for 4Q17. Despite beating estimates in three of the past four quarters, the stock has slightly underperformed the overall market. The stock has appreciated 24% since this time last year, and we expect to see similar returns moving forward as the demand for logistical services increases. Although we remain bullish on the stock, we are keeping a close eye on Amazon as it begins to roll out its own logistics services, posing a potential threat to UPS.
The stock has passed our Target of $125, and we believe the stock will go higher, as long as the market holds here and moves higher in the coming months. We hereby raise our Target to $142 and our Sell Price to $118.
---------------------------------------------------------------------
Alphabet (GOOG: $1,170)
Bull Market Report Target Price: $1,450
Bull Market Report Sell Price: We would not sell Google
Earnings Date: Thursday, 4:30 PM ET
Consensus: 4Q17
Revenues: $32 billion
EPS: $10.00
Year Ago Quarter Results
Revenues: $26 billion
EPS: $9.36
Key Things to Watch For in the Quarter
We are looking for a 31% increase in revenues and a 7% increase in earnings per share for 1Q18. The company has beaten estimates in three of the past four quarters, which has been reflected in the stock’s 45% appreciation since this time last year. The stock currently boasts a market cap of $815 billion, making it one of the largest publicly traded companies in the world. Although Alphabet is best known for its Google Search Engine, the company touches all aspects of technology from cloud computing to its most recent Television Streaming service through YouTube.
---------------------------------------------------------------------
Apple (AAPL: $165)
Bull Market Report Target Price: $194
Bull Market Report Sell Price: We would not sell Apple
Earnings Date: Thursday, 5:00 PM ET
Consensus: 1Q18
Revenues: $87 billion
EPS: $3.81
Year Ago Quarter Results
Revenues: $78 billion
EPS: $3.36
Key Things to Watch For in the Quarter
We expect to see a 13% increase in earnings per share along with an 11% increase in sales for 1Q18, despite less than ideal results with the release of the iPhone X. The stock has beaten estimates in each of the past four quarters, and has appreciated 38% since this time last year. We also saw Warren Buffet add more stock to his portfolio, which should definitely not be overlooked. We expect to see growth in iPhone and iPad sale over the next year, and remain bullish on the stock. The cash repatriation should begin soon and that will produce some changes – in the dividend and in their outlook on buying new technology firms.
---------------------------------------------------------------------
Visa (V: $123)
Bull Market Report Target Price: $123
Bull Market Report Sell Price: We would not sell Visa
Earnings Date: Thursday, 5:30 PM ET
Consensus: 1Q18
Revenues: $4.8 billion
EPS: $0.99
Year Ago Quarter Results
Revenues: $4.4 billion
EPS: $0.86
Key Things to Watch For in the Quarter
Visa is expected to report a 9% increase in revenues and a 15% increase in earnings per share for 1Q18. Visa has beaten estimates in each of the past four quarters, and seen a 50% appreciation in its stock since this time last year. Despite paying a relatively small dividend, the stock still trades at a PE of 44, suggesting it is fairly valued compared to its competitors. We are confident in Visa’s ability to drive earnings growth through the new year. This $280 billion market cap company is a long term hold.
---------------------------------------------------------------------
Amazon (AMZN: $1,420)
Bull Market Report Target Price: $1,500
Bull Market Report Sell Price: $1,225
Earnings Date: Thursday, 5:30 PM ET
Consensus: 4Q17
Revenues: $60 billion
EPS: $1.84
Year Ago Quarter Results
Revenues: $44 billion
EPS: $1.54
Key Things to Watch For in the Quarter
Analysts expect Amazon to report a 36% increase in revenues and a 19% increase in earnings per share for 4Q17. Despite having only beaten estimates in three of the past four quarters, the stock currently trades 70% higher than its levels this time last year. Amazon continues to lead the charge in the online retail space, and we firmly believe in the longevity of the firm. Although the company trades at a very high PE of 350, we believe this is explained by the company’s inherent ability dominate and revolutionize the Retail industry.
---------------------------------------------------------------------
AstraZeneca (AZN: $36)
Bull Market Report Target Price: $42
Bull Market Report Sell Price: $32
Earnings Date: Friday, exact time not available
Consensus: 4Q17
Revenues: $5.4 billion
EPS: $0.45
Year Ago Quarter Results
Revenues: $5.6 billion
EPS: $0.61
Key Things to Watch For in the Quarter
AstraZeneca is expected to report a 4% decrease in revenues and a 26% decrease in earnings per share for 4Q17. Despite the lack of top line growth, the stock has still managed to beat analyst estimates in each of the past four quarters, and has shown 30% year-over-year appreciation as a result. The stock currently trades at a PE of 26, which is relatively cheap compared to other firms in healthcare which average around 40. The stock pays a 4% dividend, and has room to grow in 2018.
We’re not liking this new development with a slowdown in revenues and earnings and are re-evaluating our take on this stock. More to come this weekend. In the meantime, we are moving our Sell Price to $34.