52 Week Price Range: $23-$35
EPS: $1.61
Shares Outstanding: 84 million
Market Capitalization: $2.5 billion
Dividend: $2.28
Yield: 7.7%
Target Price: $33
Sell Price: $24
Price as we publish: $28
Background and Company Overview
Care Capital Properties (CCP) was spun off from Ventas (VTR; $67), with a $24 billion market cap, last summer. This was done to offer Care Capital the opportunity to add value to shareholders by focusing on its investments in skilled nursing facilities and real estate assets catering to Healthcare industry tenants. The company focuses on triple-net lease assets, where tenants pay rent plus real estate taxes, insurance, and maintenance.
Usually, only the highest quality tenants choose triple-net leases because the large overhead is a hurdle for smaller, more cash-strapped companies. This is why triple-net lease real estate investment trusts (REITs) are more popular with risk-averse investors, and usually offer lower yields.
At a near 8% yield, however, Care Capital Properties offers this lower risk focus and with a higher yield. This is largely a result of its specialization in Healthcare facilities, which have received little attention from investors in 2016, and the fact that the company is very new as a standalone firm. However, its longer history as part of Ventas means the company already has a portfolio of 340 properties across the United States. With properties in California, Oregon, Washington, Nevada, Arizona, New Mexico, Wyoming, Texas, Arkansas, Missouri, Minnesota, Wisconsin, Illinois, New York, Georgia, and several other states, Care Capital Properties is geographically diversified, offering you more security.
The vast majority of its assets are skilled nursing facilities, with less than a dozen specialty hospitals and senior housing facilities. Skilled nursing facilities are seeing strong growth, with a combined annual revenue of $130 billion, according to Ibis World*. They see growth to continue for several years:
"Due to the necessary nature of services provided by nursing care facilities, the industry was able to grow despite broad economic stagnation. Additionally, the continued aging of the population has spurred demand for industry services. Since the elderly are more prone to injury and illness, the larger share of senior adults has propelled demand for nursing care facilities. We see favorable demographic trends: Over the five years to 2021, the industry is expected to continue expanding. Continued aging of the population, which is expected to accelerate over the five-year period, will drive industry growth."
*IBISWorld is a global business intelligence leader specializing in Industry Market Research and Procurement and Purchasing research reports.
Healthcare REIT Marketplace
Care Capital Properties has several competitors in the Skilled Nursing facilities and Healthcare real estate marketplace. Of the largest and well known are Welltower (HCN), HCP (HCP), and Omega Healthcare Investors (OHI). Additionally, smaller firms Sabra Healthcare (SBRA) and Medical Properties Trust (MPW) have gained tremendous interest in 2016. A quick comparison of these stocks is below:

Note that Welltower's lower yield is largely due to its large size and sustainable payouts. With funds from operation (FFO) at 132% of dividend payouts, Welltower's dividend is secure and expected to rise as it has for over 30 years.
Price to Earnings and Dividend Coverage
However, Care Capital Properties is in a better position to raise dividends although it lacks the history of the larger Healthcare REITs. The company’s dividend coverage is 144%, as FFO has risen markedly since the company went public in 2015. In fact, it has the second highest dividend coverage of this basket of Healthcare REITs:
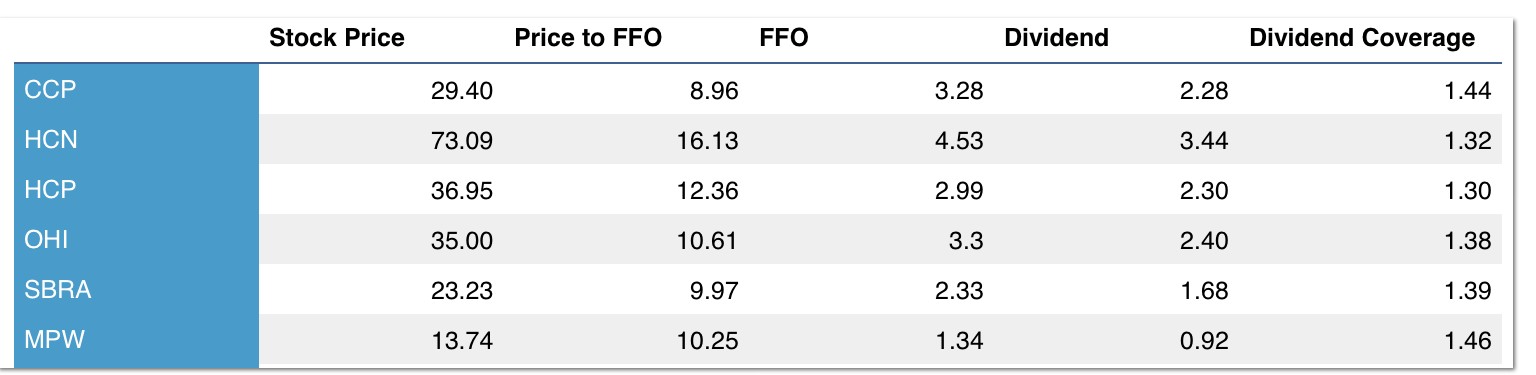
In addition to a higher dividend coverage, implying both a safe payout and room for dividend increases, the company’s price-to-FFO is the lowest of this group. Price-to-FFO, like the more familiar price-to-earnings ratio, is used to see exactly how much an investor is paying for a REIT’s earnings. Because FFO is a more accurate metric of rental income than EPS, we can use this metric to see how expensive each stock is.
Business Growth
Care Capital’s low price-to-FFO is largely a result of the newness of the company, while Welltower’s high price-to-FFO is a result of the company’s established track record. However new and small Care Capital Properties is, the company’s FFO growth and rising revenue demonstrate its ability to increase payouts. On the growth of the company’s size, note its trailing 12-month revenue increase since going public:

Over the last year, revenue has grown by over 12% on a year-over-year basis. This is largely the result of continued investment in new real estate opportunities, and the company is positioned to further its investments, as the CEO stated in the company’s last earnings release:
"Based on our first half results in 2016 and the revised timing as it relates to optimization of the portfolio, we are able to raise our guidance. We intend to continue to reinvest and upgrade the portfolio, while evaluating recycling of capital through dispositions. The net result of these activities will make our company even stronger over the long term."
BMR Take:
As one of the few REIT sectors to rise significantly in 2016, the Healthcare REIT sector is a rare place where investors can get high yields and earnings at a good price. Additionally, demographic headwinds due to an aging population make Healthcare REITs a lower risk bet for a long-term hold than many alternatives in the market. Finally, when choosing which Healthcare REIT to choose, we have chosen Care Capital Properties due to its low price and high dividend coverage.
We see future growth over the long term for the company in both dividend payout and stock price. The company has not yet increased dividends despite its very high dividend coverage. Being just a year old, the company may surprise the market with a dividend increase, and that may cause a sharp inflow of capital into the stock. We recommend buying and holding Care Capital Properties now in anticipation of growing demand for the stock in the market as its FFO and dividends rise.