by Todd Shaver | Sep 1, 2017 | 11am News Flash
September 1, 2017
Nutanix (NTNX: $22, up 2%) announced financial results for its fourth quarter and fiscal year ended July 31st, yesterday after the close.
Fiscal 4Q 2017 Financials
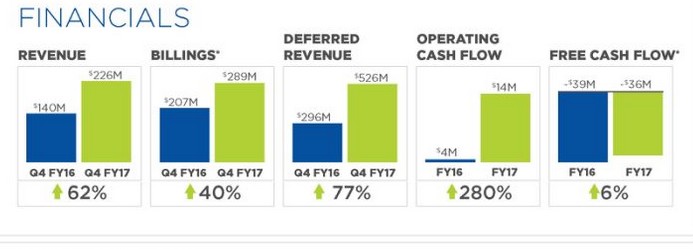
Revenue: $226 million, up 62% year-over-year from $140 million in 4Q16
Net Loss: $50 million, compared to a net loss of $47 million in 4Q16
Operating Cash Flow: $6 million, compared to $2.5 million in 4Q16
Cash and Short-term Investments: $350 million, up 90% from 4Q16
Deferred Revenue: $525 million, up 77% from 4Q16*
Free Cash Flow: $(6.5) million, compared to $(6.5) million in the fourth quarter of fiscal 2016
Billings: $289 million, growing 40% year-over-year from $207 million in 4Q16
* We are not clear on exactly what deferred revenue means in this case. We understand deferred revenue - it is an accounting rule. We are looking into this and will let you know. Note that this number is very big, and generally very bullish.
Full-year Fiscal 2017 Financials
Revenue: $770 million, growing 72% year-over-year from $445 million in fiscal 2017
Billings: $990 million, growing 55% year-over-year from $640 million
Net Loss: $200 million, compared to a net loss of $150 million
Operating Cash Flow: $14 million, compared to $4 million
Dheeraj Pandey, CEO, had this to say:
“The fourth quarter was another record quarter and an outstanding conclusion to the fiscal year. This quarter, marked by record revenues, increased software-only sales, strong growth from our OEM partners, and positive operating cash flow, was a great way to end our first year as a public company.”
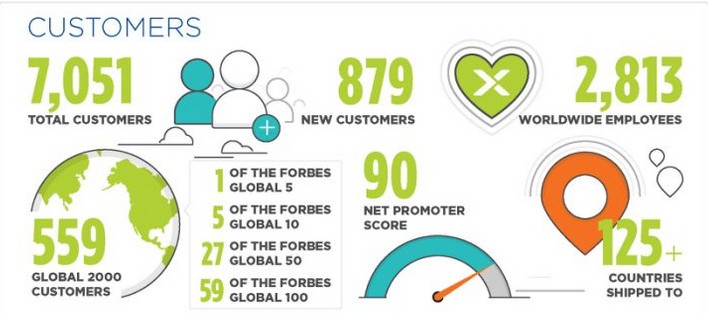
Continued Customer Growth: Nutanix ended their fiscal year on July 31st with 7,050 customers, adding almost 900 new customers during the quarter. Fourth quarter customer wins included ABC Stores, Amgen, Bacardi, HCA Healthcare, Konica Minolta, The Hershey Company and The Home Depot among many others.
Increased Number of $1 Million+ Deals: 43 customers came on board in deals over $1 million in the quarter, up 39% YoY.
BMR Take: As you know, the stock has been hovering at our Sell Price. We have tried to explain how much we like this company and how we would hate to have to sell the stock at the bottom. We believe this company can be a triple-digit stock in the next few years. This quarterly report is a stellar one and reinforces why we believe in the company. Remember, with revenues comes all. Yes, the company is still losing money but they have a big stash of cash ($350 million) and can withstand some losses for a bit as they continue to add customers. However, this will be a drag on the stock until they can turn profitable, likely in fiscal 2019, a long time from now. The company is on track to hit $1 billion in revenue this coming fiscal year ending July 31, 2018. We are very pleased.
by Todd Shaver | Jul 11, 2017 | 11am News Flash
The Carlyle Group (CG: $20.40)
The stock took off yesterday on no discernible news. It closed up $1.08 or 6% hitting $20.50 before settling at $20.45. We added the stock on June 14th at $18.75 so we are up 8% in three weeks. Our Target Price is $22, and we are approaching this level now. Again, we see no news that could send the stock up so much like this. We just believe investors are seeing the light and we continue to believe this company is undervalued by Wall Street. Stay tuned.
by Todd Shaver | Jun 28, 2017 | 11am News Flash
First Potomac Realty Trust (FPO) is being acquired in a $1.4 billion deal announced today. The stock of Government Properties (GOV) is down 7% this morning to $20.25. First Potomac is a REIT with 11 million square feet of office space in and around Washington, DC. Government Properties, at a market cap of $1.4 billion, will now have an opportunity to prove its worth and assimilate the properties. This is creating a buying opportunity if you believe that management can turn around this company We believe they can and would be buyers of the stock here at the $20 level.
by Todd Shaver | May 11, 2017 | 11am News Flash
Opko Health (OPK: $6.95, down 6 cents today) recently reported first quarter financial results with a loss of $31 million versus the Street estimate of -$22 million – ouch, up from -$12 million last year. Revenues were solid at $296 million up from $290 million.
The Rayaldee launch is making disappointing progress relative to our expectations. Opko is working on gaining more access for Rayaldee as it has the coverage of just 60% of U.S. eligible patients. Management anticipates that expanding insurance coverage along with more active marketing, including the anticipated release of updated guidance from the Kidney Disease Improving Global Outcomes organization, could likely increase access going forward. We had expected to see more progress by now and the hiccups raise our concerns.
Sentiment is souring and turning to be more focused on the risks in front of the company. As a reminder, we discuss each of the key risks below.
One of the key risks for Opko is failure of clinical studies that could potentially result in sunk costs in both capital and time lost. Opko currently has several mid- to late stage clinical trials underway. Failures of these studies, especially the Phase III pivotal trials, could have significant negative impact on the stock. More specifically, clinical study success of MOD-4023, a human growth hormone, is very important given it accounts for substantial valuation of the stock. We are just not seeing the company express a confident tone to comfort our concerns about this risk.
Although OPK’s current pipeline products have exhibited the potential to generate positive clinical outcomes from current and future trials, it remains too early to project whether any of these products would be approved by regulatory agencies. Even if the products were to enter the market, sales could be below projections due to various reasons. A revenue outlook below expectations could also negatively affect the stock. It is hard to ignore these concerns as we see slow progress in the company quarterly results.
BMR Take: The stock has been a disappointment for us at The Bull Market Report. While there is a lot of potential, the underlying fundamentals suggest the company is having a hard time executing. We see much risk in riding out the turbulence. We prefer to allocate capital to our other great ideas that are working, like Apple, Facebook, and Shopify. But something makes us want to keep Opko around for a little while longer. We are going to give it three more months.
The CEO, Philip Frost, has millions of shares and continues to buy more stock virtually every day – we are not exaggerating here. With the stock down below $7, he may increase his buying and others may do as well. So we might just see the stock stabilize here and mover higher later this year. The market cap is $3.9 billion for a company that has a revenue stream of $1.2 billion, and a lot of potential. Not overly expensive.
The stock is down from $10 where we added it in September. We've stuck with it too long, as we had Sell Prices of $9 and lowered it to $8, but still didn’t remove it, even at the $7 level yesterday. We now lower it to $6. Some might say we should be more diligent in following our own rules. Others might say we are being patient as we believe in the company and its continual announcements of future success. We do believe in giving a company a chance to be successful, like Mazor that is up over 150% since we added it last summer. So we will wait as patient investors.
by Todd Shaver | May 3, 2017 | 11am News Flash
First Solar (FSLR: $35, up 17%) reported first-quarter earnings of 25 cents a share. The Street was looking for a loss of 13 cents.
Revenues hit $890 million in the quarter killing the estimate of $700 million. (Who are these analysts anyway? So out of touch.) Revenues grew slightly from last year, up 2%. Profit was $84 million, down from $275 million a year ago. Ouch, but expected.
First Solar has $1.65 billion in cash, up from $1.35 billion at the end of the previous quarter. Long-term debt is $265 million at the end of the first quarter.
The big news is guidance. The company raised its revenue guidance to $2.9 billion from $2.85 billion. This is minuscule, but the Street like it, pushing the stock up big today. Gross margins guidance was moved to 13.5% from 12% earlier.
Full-year earnings are now expected in the range of 25−75 cents per share, compared with the prior guidance of a breakeven to 50 cents.
We’ve said many times that this company is good and that the turnaround will take time. This is the first positive information we have seen publicly that good things are actually happening. If you have patience, stick with First Solar. If you don’t, now is the time to take it off the table, after this nice 17% run-up today.
by Todd Shaver | Apr 19, 2017 | 11am News Flash
Tesoro: (TSO: $77)
Recent Developments:
Sputtering stock price presents an opportunity. After a post-4Q EPS bounce from the low 80s to the high 80s, Tesoro shares have sputtered all the way back down, breaking through the $80 psychological threshold. While there has been a recent flurry of company-specific data points that could be perceived negatively, we do not see any of these as particularly material to the longer term investment thesis about why we like the stock. We continue to believe that closing the Western Refining deal will be a key fundamental and technical catalyst for the stock.
A flurry of tough data points recently. Tesoro shares have been weak over the past month, with factors like positive RINs (renewable identification number) headlines for merchant refiners (of which Tesoro is not one) and a soft Western Refining 4Q result hurting Tesoro’s stock price notably in early March. The past few weeks have been particularly tough, with (1) an Energy Index reweighting that caused very heavy volume in a few trading sessions. (2) California gasoline inventories that built on a spike in production, likely ahead of a sizeable electrical outage at Torrance in October; and, (3) headlines of a proposed 12 cents per gallon gasoline tax increase in California to help fund road repairs. While each is potentially negative, we are not overly concerned.
* Refiners have to pay a RIN tax. Just a fixed percentage of volume. This tax was putting small refiners out of business, which was a positive for Tesoro. But then came Trump and a new head of the EPA. Now "positive RIN" headlines is reference to discussion of doing away with the RIN tax or more likely reducing it materially – a bright outlook for small refiners to stop being clobbered by the RIN tax. The slight positive that Tesoro was experiencing from this regulatory matter is now normalizing.
We continue to believe in our positive long-term thesis. We recommended Tesoro, with the view that (1) financial performance was stable, (2) California fundamental risks do not present a death threat to the business, and (3) the Western Refining deal could lead to upside from both synergies and the MLP-value unlock potential, Western’s hidden MLP-like value. Our longer term thesis is unchanged, particularly with the Western Refining deal still on track to close in 2Q.
We see Tesoro as an attractive story in refining, with upside levers from Western Refining synergies and the possibility of corporate structure simplification. The acquisition of Western Refining adds a new element to the story, as it further diversifies Tesoro’s refining geographic mix and adds scale with a top-tier refining asset. It also adds an interesting Permian Basin growth angle to the midstream story. We think the recent stock weakness is overdone on perceived tough conditions in California.
Refinery margins move opposite the way you typically think of the Energy sector. So in the big selloff in Energy in recent years the refineries like Tesoro reported record performance. Warren Buffet of Berkshire Hathaway (BRK-B: $164) owns around 15% of peer refiner Phillips 66 (PSX: $76 , $39 billion market cap) at a premium to net asset value. Tesoro ($9 billion market cap) trades at a discount to net asset value. We think Tesoro is worth at least net asset value. Perhaps one day Buffet buys Tesoro through Phillips 66. Measures of Tesoro NAV are $100+.
BMR Take. We see substantial value in the shares with upside potential to net asset value north of $100. We note that recently Boston Partners and Point72 (two well-known investor groups) bought shares near current levels. Boston bought 3.2 million shares or 2.7%; Point72 bought 6.6 million shares or 5.6%.
We have a Target of $110 on the stock and a Sell Price of $75.