The Week Ahead
Well, it’s graduation week. Class of 2017 graduates are hitting the stage to accept their diplomas, listen to a keynote speech, make one last party, and then head out into the great big world. What will they find? GDP growth moving to 4% or stalling out around 2%. Will geopolitical tensions escalate as early as this year or find a sustainable comfort zone? Can equity prices hold? How bad will rising rates hurt the bond market? Everybody from the newest participant in the labor force to the most experienced must wrestle with these questions in the year ahead. We at The Bull Market Report hope to help you with some good insights about what to make of it all—week in and week out.
There is always a bull market here at The Bull Market Report! This week we highlight the following securities: Eli Lilly, Home Depot, Netflix, Splunk, PayPal, and VMWare. And a few others!
Highlights From The Past Week
Federal government expanding investigation of Fox News. The aggression against the media continues. Current and former Fox News employees have been interviewed, as authorities try to determine how settlement payments for sexual-harassment allegations were structured and which executives played roles in the payments. One source tells the WSJ that the investigators seem to be interested in intimidation tactics that former CEO Roger Ailes signed off on. The investigators are in the securities unit of the US attorney’s office, and no prosecution will necessarily follow. What does this all mean? You need to find trusted sources of information in this world. We strive to make The Bull Market Report a reliable and honest source of information for you to rely on.
It's the strangest thing: A hedge-fund manager apologizing for bad calls. Wellington Management Sr. VP Nick Adams isn't just apologizing for his mistakes on Silicon Valley venture deals -- which differ from the bank stocks he has a proven record with -- he's refunding fees. Adams, who has lost money two out of the past three years, put hundreds of millions of dollars into Mozido and Powa Technologies, which are both financially distressed. Adams has promised he won't ever invest in similar private deals in his flagship fund again. People familiar with the firm's finances say that after investors including Blackstone (BX) withdrew their cash, Adams's portfolio at the start of 2017 was $6 billion, down 40% from 2014. Adams has now returned to investing in traditional lenders like Bank of America and Citi, and his main fund rose 12% in Q1. We think there are lots of lessons to learn from this situation. For instance, if you ever wonder why many of The Bull Market Report’s stock picks are in household names that are often large cap stocks, well, now you know why. Traditional investing is a proven money maker and we try to take you where you can make money.
Don't assume the Healthcare industry will be fine. We think the market is right to assume that the Republican replacement for Obamacare won't be passed in its current version, but anything that hurts earnings for the sector could bring prices down, and the failure to pass any sort of healthcare reform may make a tax reform harder to achieve, which will be a negative for stocks more broadly. We all must keep an eye on this important event unfolding in Washington in the weeks ahead.
BMR Companies and Commentary
Eli Lilly (LLY: $83, +0.5% - All changes are for the week) Eli Lilly has more growth drivers than all its peers, but its continued pledge of "at least 5% annual sales growth" for 2015-20 is being called into question because a big portion of growth comes from two drugs - Jardiance and Trulicity - that have recently faced setbacks. We think Eli Lilly is a topnotch franchise in Healthcare and will overcome these hurdles.
Jardiance is a drug for type 2 diabetes. Johnson & Johnson has a competing drug called, Invokana, which is set to release new trial data in June. Everybody is saying that if Johnson & Johnson’s drug has good data, then there will be more pricing competition in 2018 for Eli Lilly’s drug. We think this risk is widely known, already factored into the numbers, and not a reason to not own Eli Lilly’s common stock.
Trulicity is also used for type 2 diabetes. It faces risks from the FDA's decision last August on Novo Victoza, specifically that this drug had problematic heart effects. Will the FDA say the same thing about Trulicity? We will find out in 2018. For now, it is overly pessimistic to assume Trulicity faces serious FDA challenges.
Note that Lilly's drug unit accounted for 83% of 2016 sales, with the balance coming from animal health, so the story is not just all about drugs. Also, Eli Lilly's operating margin trails most of its peers, except Bayer, and by leveraging new-drug launches, it aims to reduce R&D and SG&A expenses to 50% or less of sales in 2018 versus 56% in 2015. This target is achievable by Pharma standards as Jardiance's new heart label drives growth and Trulicity, an established product, continues to add to margins.
Lilly investors may be relieved by the good set of results in 1Q following recent drug setbacks. Older drugs, such as Cymbalta and Strattera, beat consensus, lifting margins and feeding through to the 2% EPS beat. Diabetes was strong with both Trulicity and Humalog beating consensus, while Jardiance missed by a little. Jardiance is a key driver of growth and while the miss raised eyebrows we say stay the course.
BMR Take: Eli Lilly is a top franchise in Healthcare boasting a market cap of $91 billion. On track to clear $5 of EPS, the stock is a good value.
Home Depot (HD: $156, flat)
A lingering debit/credit card breach has kept a lid on shares of Home Depot. The bad news is that it is so sad to see some large-scale breaches at US companies like Target and now Home Depot. The good news is Home Depot has taken strong steps to remedy the situation. In any case the stock is $1 from an all-time high, fast approaching $200 billion in market cap.
Companies hit by data breaches often face class action complaints filed by consumers. They also face lawsuits from shareholders looking to thwart future breaches and restore financial stability to companies in which they have invested. Home Depot's willingness to take meaningful but financially limited remedial mitigating action achieves a mutually beneficial resolution that companies facing any kind of data breach lawsuits, such as Yahoo, may rely on to improve their corporate data governance.
Under the proposed settlement, Home Depot will change many of its cybersecurity corporate governance policies. Home Depot agreed to document the duties and responsibilities of the chief information security officer; conduct table top exercises; monitor computer networks; maintain a “Data Security and Privacy Governance Committee;” hire a “dark web mining service;” receive reports on the company's information technology budget; join an information sharing program; and authorize the board to retain its own IT and data security professionals. Home Depot also agreed to pay $1.1 million in attorney’s fees and and $1.5 million to the shareholder representatives. They agreed to the settlement because it saw the attorneys’ fees as a minimal money issue and it believed the actions “would restore trust” in the company.
BMR Take: Home Depot is on track to deliver $10 of EPS and $100+ billion of sales. Don’t sweat the small stuff. Sorry to see the cyber breach, but the core business is doing great.
Netflix (NFLX: $157, +3%)
What could be more exciting than a Netflix merger with Apple? The world continues to talk about the prospects. Let’s break down the potential reality.
There may be as good as 40% odds that Apple acquires Netflix. The research arm of the investment bank Citi released a report with seven potential merger and acquisition targets for Apple. Tops on the list is Netflix. Elon Musk's Tesla, on the other hand, is only 5% likely. The full list of acquisition targets includes three media firms, three game developers, and, of course, one car manufacturer. Disney and Hulu are the media firms joining Netflix, while Activision, Electronic Arts, and Take-Two are the gaming companies.
Netflix makes a ton of sense, of course, as the company dominates streaming media both domestically and abroad. Disney has a strong list of properties as well, but slightly more oriented to traditional media consumption, whereas Netflix is well-positioned to take advantage of the continuing trend to cut the cord (cord-cutting has jumped 5x). Plus, Disney is worth $177 billion, whereas Netflix is worth $67 billion.
BMR Take: The future of TV consumption swings in the balance as the world moves away from traditional cable to the internet. Netflix is the powerhouse making the company a coveted asset in media. On track to do $10 of EPS by 2020 we see compelling value in the shares as a standalone entity even at current levels. A take-out could offer huge upside.
PayPal (PYPL: $49, +3%)
The PayPal network effect is working like charm. Investors in PayPal had plenty of reason to cheer last week when the company reported earnings. Nearly every metric was up by a better-than-expected percentage, surpassing expectations of all but the most bullish on the company.
More exciting to long-term investors, however, was the account growth and increase in user engagement with the company's core platform. Six million active accounts were added during the quarter, increasing the total to 203 million for the digital payments company. These active accounts now average almost 32 transactions per year, a 12% increase year over year. More customers using the company's platforms more often was a winning combination that the market liked.
PayPal's growth is beginning to fuel a powerful network effect opening a new window for the company. The beauty of this type of growth is that it drives itself. The more users that sign up for the platform the more important the service becomes for retailers to adopt it and the more places that accept it, the more attractive it becomes to new users. Get it?
At the end of March, 16 million retailers were accepting PayPal's core platform as a method of payment. Management is well aware of this virtuous cycle. During the conference call, CEO Dan Schulman stated: “Our powerful two-sided network engages both consumers and merchants, and the larger our scale, the stronger our network effect becomes. We made meaningful progress in advancing merchant adoption of PayPal in the quarter. At the end of March, the number of active merchant accounts on our platform increased to 16 million. The size of our merchant base is a formidable competitive advantage and is extraordinarily difficult for others to replicate.”
BMR Take: We think PayPal is in the middle of a decade-plus growth cycle that will deliver real value for shareholders. Stick around. They are already closing in on $3 of EPS.
Splunk (SPLK: $67, +4%)
Progress at Splunk is happening. Splunk, a provider of the leading software platform for real-time Operational Intelligence, recently announced support for SaaS Contracts in AWS Marketplace. Working with Amazon is a big deal!
The new globally available API capability* enables seamless procurement and deployment of Splunk® Cloud. The automated and accelerated purchasing process for Splunk Cloud via AWS Marketplace ensures fast time-to-value for customers leveraging Splunk solutions to gain real-time security, operational and cost management insights across their Amazon Web Services (AWS) and hybrid environment.
* Application program interface (API) is a set of routines, protocols, and tools for building software applications
The University of San Francisco is home to an innovative academic community of more than 12,000 students, faculty and staff. “As a higher education institution, USF prides itself on being at the forefront of technology, which is why we turned to Splunk and AWS,” said the vice president of information technology and chief information technology officer, University of San Francisco.
BMR Take: Working with Amazon gives Splunk big growth potential. The EPS outlook calls for great than 3x growth from $0.41 of EPS in 2017 to $1.35 of EPS in 2020. Ride this growth wave!
VMware (VMW: $94, flat)
VMware is out with some good news. The company is the first mobile application management provider to manage and secure hundreds of Oracle business applications and custom applications. As such, enterprise IT organizations can manage their Oracle application suite on a single unified platform together with their other business-critical applications and devices. Users who count on Oracle's business applications to make better decisions, reduce costs and increase performance can benefit by being able to access these applications through a simple digital workspace environment – be it from a mobile device, laptop or desktop – with VMware Workspace ONE and AirWatch.
What does that mean? VMware is continuing to make end roads in the lucrative cloud business, where growth is driving real results for stockholders.
The Chief Operating Officer, customer operations, said: "Mobilizing critical business processes is at the core of both of our organizations' DNA and this collaboration will help us advance this shared vision for our customers and their end users alike. We're proud to come together with Oracle to make it easier for IT administrators to secure and manage these critical mobile apps and help their end users seamlessly access them from any endpoint.” VMware Workspace ONE is the industry's only integrated platform for application and access management and unified endpoint management that enables simple enterprise secure access to any app from any device, accelerating adoption of digital workspaces.
BMR Take: The company is working. EPS is on track for $4.90 this year with growth upside to $6 in the next few years led by the cloud business and partnerships like the one described above serving Oracle.
Economic Outlook for the Coming Week
Monday, May 08, 2017 10:00 AM ET
United States - Labor Market Conditions
Period: APR
Actual: N/A
Consensus: N/A
Prior: 0.40
Labor market conditions index is derived from a dynamic factor model that extracts the primary common variation from 19 labor market indicators. It measures the changes of condition in the labor market. We expect to continue to see signs of a healthy labor market.
Tuesday, May 09, 2017 6:00 AM ET
United States - NFIB Small Business Index
Period: APR
Actual: N/A
Consensus: N/A
Prior: -$176B
NFIB Research Foundation has collected Small Business Economic Trends data from a sample of members from the National Federation of Independent Business (NFIB). Data from quarterly surveys since 1973 is based on 10 survey indicators. We expect to see an improving small business economy.
Tuesday, May 09, 2017 10:00 AM ET
United States - JOLTS Job Openings
Period: MAR
Actual: N/A
Consensus: 5,750K
Prior: 5,740K
Part of the US Bureau of Labor Statistics, the Job Openings and Labor Turnover Survey (JOLTS) program produces a monthly study that has been developed to address the need for data on job openings, hires, and separations. With the release of 2003 data, the JOLTS program began publishing industry estimates. We expect to see the JOLTS figures reveal a healthy labor market.
Wednesday, May 10, 2017 2:00 PM ET
United States - Treasury Budget NSA
Period: APR
Consensus: $166B
The monthly U.S. government surplus/deficit is published in the Monthly Treasury Statement (MTS). The MTS is assembled from data in the central accounting system. The major sources of data include monthly accounting reports by Federal entities and disbursing officers, and daily reports from the Federal Reserve banks. These reports detail accounting transactions affecting receipts and outlays of the Federal Government and off-budget Federal entities, and their related effect on the assets and liabilities of the U.S. Government. It is very critical what happens with Trump now negotiating the government budget and we are excited to see if he can get it under control and address the national debt.
Friday, May 12, 2017 08:30 AM ET
United States - Retail Sales ex-Auto
Period: APR
Actual: N/A
Consensus: 0.45%
Prior: 0.0%
Retail and food service sales data excluding motor vehicle are included in the Advance Monthly Sales for Retail and Food Service report, which provides an early indication of sales of retail and food service companies. We are keenly concerned about brick and mortar Retail sales declines and look to this economic release to assess the damage and potential impact.
MORE COMMENTARY ON BULL MARKET REPORT STOCKS
First Solar (FSLR: $35, up 17%) reported first-quarter earnings of 25 cents a share. The Street was looking for a loss of 13 cents.
Revenues hit $890 million in the quarter destroying the estimate of $700 million. (Who are these analysts anyway?) Revenues grew slightly from last year, up 2%. Profit was $84 million, down from $275 million a year ago. Ouch, but expected.
First Solar has $1.65 billion in cash, up from $1.35 billion at the end of the previous quarter. Long-term debt is $265 million at the end of the first quarter.
The big news is guidance. The company raised its revenue guidance to $2.9 billion from $2.85 billion. This is minuscule, but the Street liked it, pushing the stock up big. Gross margins guidance was moved to 13.5% from 12%.
Full-year earnings are now expected in the range of 25−75 cents per share, compared with the prior guidance of a breakeven to 50 cents.
We’ve said many times that this company is innovative and successful and that the turnaround will take time. This is the first positive information we have seen publicly that good things are actually happening. If you have patience, stick with First Solar. If you don’t, now is the time to take it off the table after this nice 17% run-up.
Facebook (FB: $150, flat)
Monthly active users totaled 1.94 billion while daily active users hit 1.28 billion. Expectations were for these numbers to hit 1.90 billion and 1.26 billion, respectively.
Facebook reported earnings of $2.5 billion or $1.04 per share on revenue of $8.03 billion. Expectations were for earnings of $0.87 on revenue of $7.83 billion. Huge beat. “We had a good start to 2017,” Mark Zuckerberg, Facebook founder and CEO, said. “We’re continuing to build tools to support a strong global community.”
Mobile is big at the company, as advertising revenue on mobile represented 85% of total advertising revenue, up from 82% a year ago. Ad revenue grew 51% over last year to $7.85 billion.
As of the end of the first quarter, the company had $32 billion in cash, and had almost 19,000 employees, up 38% from last year.
As Facebook nears the 5-year anniversary of its initial public offering, note this: In 2012, Facebook was the world's 10th-biggest seller of ads behind a bunch of traditional media companies such as CBS and 21st Century Fox. It has trounced almost all of them to rise to number two in the rankings, surpassed only by Alphabet, the Google parent that dominates search ads. Together, these two companies controlled 20% of the $550 billion spent on ads last year, up from 10% in 2012.


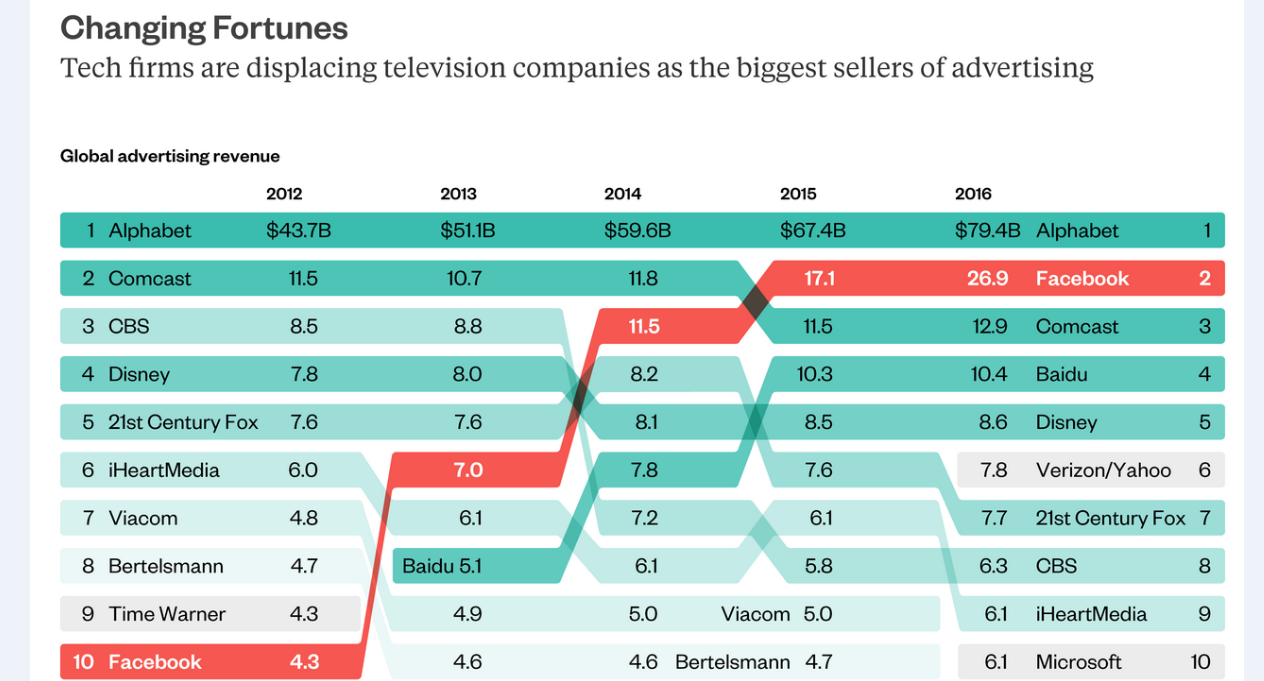
Source: Zenith Media
Jefferies hiked its price target on Facebook to $192 from $175, JPMorgan to $182 from $170, RBC Capital to $185 from $175, and Cowen to $170 from $156.
BMR Take: Our Target is in reach at $165. We would add to our positions at every opportunity. Wait until they hit 2 billion users. There will be fireworks and articles about the company galore and we just might see this as early as July. When this happens we can predict new all-time highs hit left and right.
Shopify News
We Tweeted this out on Friday:
“Shopify is on fire! All-time high at $86, up 5%. Stock was $73 a week ago. STRONG REVENUES will do it! Will eBay make an offer?” [The stock closed at $86 on Friday, up 13% for the week!]
The stock (SHOP) closed at $86 on Friday. We’re up 18% since we added the stock a little over a month ago. Our Target is $90. We can’t wait for it to hit so we can raise it to $100 or higher. And wouldn’t it be nice to see a stock split soon? What ever happened to stock splits? The markets in the 80s and 90s LOVED splits. We could see a 10-1 split for Amazon, bringing the price down to $93, and Google could split 20-1 bringing the price down to $46. Now wouldn’t THAT shake things up on Wall Street! The market would go wild.
Square (SQ: $19.78, up 8%) had a super good week. Square makes credit-card readers that plug into mobile phones and tablets and we were happy to see Square swing to a profit in the first quarter and raise full-year revenue guidance.
Led by Twitter Chief Executive Jack Dorsey, the company posted a quarterly loss of 4 cents per share on a revenue jump of 22% of $460 million. Analysts had expected a loss of 8 cents per share on revenue of $450 million, so of course the market liked what they saw. Square has predicted 2017 total revenue of $2.14 billion.
The company's gross payment volume - the total dollar amount of all credit card payments processed by sellers - jumped 33% to about $14 billion. We like numbers like this.
Another subsidiary, Square Capital, which offers loans to customers in exchange for a fixed percentage of their daily card sales, originated $250 million in loans in the first quarter of 2017, up 64% from a year earlier. We like large percentage increases like this. (We sound like a broken record…)
Square continues to move towards bigger customers. They said that 44% of the money flowing through its systems came from merchants that have over $125,000 in volume on the company’s platform, up from 39% a year ago. CFO Sarah Friar said: “That ongoing shift is good to see because those folks are not new to the payments world.”
Citigroup upped its price target on Square to $23 from $21, and Pacific Crest to $21 from $19.
BMR Take: We’re looking for $24, and hereby raise our Sell Price from $14 to $17.
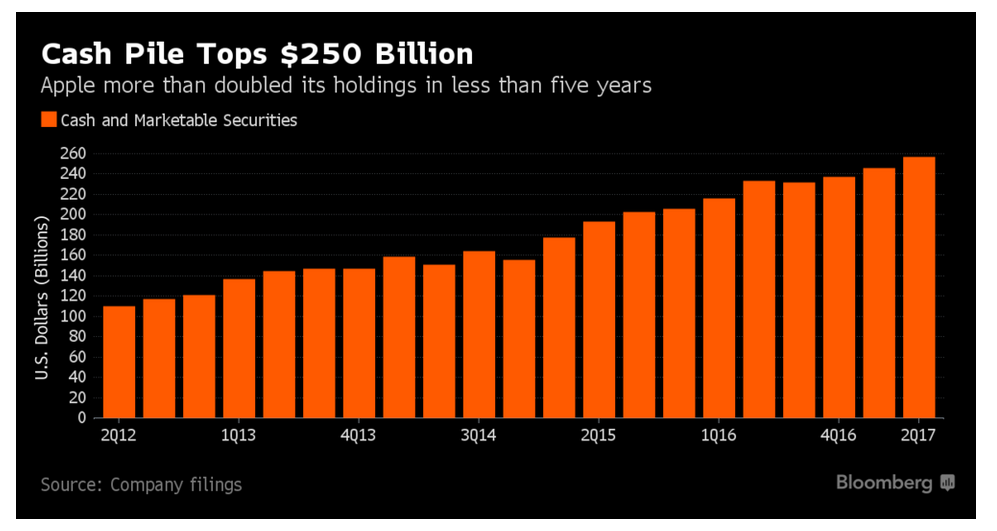
Apple (AAPL: $148, up 4%) announced that it has $257 billion in cash as of the end of the quarter. They added $10 billion in the quarter which equates to about $800 million a week, or over $150 million per work day! Repeat: $150 million per work day. The company said it will return more of that to shareholders, announcing $50 billion in new stock buybacks and a 63-cent quarterly dividend. The company had already announced $175 billion in repurchases, helping maintain the stock price in lulls between new products, so the upcoming total is now $225 billion. Take a look at this chart of their cash buildup over the years:
Twilio (TWLO: $24, down 27%) We reported via News Flash on Tuesday that despite strong revenues the market didn’t like the results. The biggest knockoff was the fact that one of their big customers, Uber, has decided to go it alone. Uber provides 12% of total revenue for the company, but Twilio grew revenue by 60% not including Uber. So ultimately, we are not that worried about future revenues. We believe they will continue strong. (We think they will come back to Twilio at some point.) WhatsApp, owned by Facebook is also a large customer, so some people are worried about this large concentration of revenue in one customer. We’re not. There is no word as to whether they are considering leaving. We would suggest that they are quite happy with the service they receive. And again, note that the company added 4,000 customers in the quarter – amazing really – giving them more than 41,000 customers, up from 29,000 at this time last year.
We had a letter from a reader about Twilio and we said this to him:
Bob -- Be prepared for anything that might happen. We could see $20 before we see $30. I hope this is not the case, but it could happen. Uber is slowly leaving as a customer and they had 12% of revenues. So, this will take some time to work out. They did add 4000 customers last quarter and are now over 40,000. They normally add 2800 a quarter. But unfortunately, like First Solar, this is going to take some time.
The Options Corner
We had mentioned in our News Flash about Twilio that we would do a column about options if anyone was interested. Well, we had a strong show of support for this. So here you go.
There are myriad of options strategies if you want to maintain a position in Twilio and you believe it will come back like we do. Of course, most options trades are risky except for selling covered calls, which are still risky but less so than buying options outright. The premiums on Twilio options are relatively high so that usually points to two types of options trades: doing covered calls, and selling naked puts or calls. The latter two are very dangerous.
Selling covered calls: Selling covered calls on Twilio is fairly straight forward. With the stock at $24 you can get about $1.80 for the January $30 call. If you have 1000 shares, you can sell 10 options and receive $1800 in your account that day. The downside is that you would be obligated to sell your stock at $30 if it goes higher than that. But, you can always buy back the option if the stock goes above $30. Depending on how long it takes the stock to get there will determine the price at which you have to buy back the options. If the stock goes to say $32 by January, then you could buy them back for about $2, losing about 20 cents, or $200. But with the stock at $32, you would feel good about that. The downside is that if someone buys Twilio out at $40 a share, you would be forced to sell your stock at $30. Not pretty.
If the stock stays below $30 until January, then you can turn around and sell another out-of-the-money option for a few dollars and wait for the stock to move higher and each time you do this you put cash into your account.
As you can see there are lots of scenarios that can happen so you have to watch carefully. Make sure you have the advice of your broker.
Buying options: If you think the stock can get to the $40 level or higher by say January 2019, you can buy out-of-the-money options inexpensively. But you could lose all of your money if the stock doesn’t reach the strike price that you choose. For example, you can buy 10 options, controlling 1000 shares, at a strike price of $40 expiring in January 2019 for about $2,300. If the stock goes to $45, these options would be worth at least $5,000. If it goes to $50, the options would be worth $10,000.
Or you could buy the January 2019 50s for about $1400 and if the stock goes to $55 they would be worth $5,000. BUT, if the stock doesn’t get to your strike price, they expire worthless.
Selling naked puts: YOU SHOULD ONLY DO THIS IF YOU WISH TO BUY THE STOCK and if you have the money to do so. You could sell the January 2019 $25 put for about $7, or $7,000 for 10 options. That would obligate you to buy the stock at some point between now and the expiration date at $25, BUT you got $7 per share so your net price is $18. You could do the same thing with a $20 put and get $4.30 per share, obligating you to buy the stock for a bit below $16. We like this latter strategy. Suffice it to say that selling naked puts on stocks you want to buy at a lower price, is a good thing. Again – very risky. Why? What if the stock goes to $10. You would be forced to buy the stock at $18 or $16 as described above. Not fun.
Send us your questions and comments please! Info@BullMarket.com.
Tesoro (TSO: $80, up 1%) moves in the wind with crude oil. Crude got down to $45 early Friday and bounced back to $46 by the close. We like the company but can’t be part of it if crude is headed to $40. If you know where crude is headed you’ll know what to do with your position in this fabulous refiner. Unfortunately, we don’t. If we knew, we could make $1 million trading crude oil futures. We added the stock at $85 in November and have a Sell Price of $75. But we would hate to have the stock go that low, so we are hereby raising our Sell Price to $78, which is two dollars below the current price. So, if Tesoro closes below $78 we are out.
Carlyle Group (CG: $18.10, up 2%) posted first quarter earnings that handily beat expectations on Wednesday, in line with its peers, after a strong stock market last quarter lifted investment returns. Carlyle's peer Blackstone Group (BX: $30, down 2%), a Bull Market Report favorite, reported first-quarter earnings that surpassed expectations.
Carlyle said it earned economic net income (ENI)* of $365 million after taxes, more than six times what it earned a year earlier. That translated into $1.09 EPS, well above analyst forecasts for 38 cents per share and the second-highest on record since the fourth quarter of 2013.
* ENI is a crucial performance measure for U.S. private equity firms as it accounts for unrealized gains or losses in investments.
Carlyle said its private equity investments appreciated 9% in the first three months, better than a 5% gain in the S&P 500 index in the same period. Carlyle Co-CEO William E. Conway, Jr. said, “We deployed capital at a strong pace in the first quarter, with $4.4 billion of capital invested despite a difficult environment. We believe we are well-positioned to continue this strong pace. We have already announced substantial new investments and almost $4 billion of exits that we expect to close in the coming quarters.”
BMR Take: Carlyle is still way undervalued but is paying you 4% while you wait. We’re waiting patiently for the market to recognize this situation. We are up 12% since March, but we sure would like to see our Target hit of $20.
The High Yield Corner
By Michael Foster
It’s finally started.
It’s a bit late, but we’re finally seeing a correction in the BDC world. The UBS BDC ETF (BDCS: $23, down 3%) got hammered in a week that was pretty humdrum for high yield and not bad for the stock market as a whole, despite a lot of drama. Yet BDCs are back to underperforming, as they should. Overstretched valuations and high premiums to NAV were unjustifiable before this week. Now that many companies have reported lackluster earnings, those premiums are even less justifiable.
Ironically, however, this isn’t hurting the most overvalued BDC of them all: Main Street Capital Corporation (MAIN: $40, up 1%), which closed the week strong as investors sighed relief following the company’s earnings. Net interest income rose 9% from a year ago to 61 cents per share and the company’s NAV rose nearly 2% to $22.44. There are two big implications for this: firstly, the company’s dividend coverage is 109% and there’s room for years of dividend growth to continue. We have a feeling Main Street management has the ultimate goal of becoming the first BDC Dividend Aristocrat*. We’ve still got about two decades until they can qualify, so it won’t be easy. But if that is their goal, Main Street is easily the best managed and most long-term focused BDC in the world.
* The Dividend Aristocrats are a select group of 51 S&P 500 stocks with 25+ years of consecutive dividend increases.
That doesn’t mean you should go out and buy. We at The Bull Market Report were happy with our pick and happy to see it rise. But we are not happy to pay an 80% premium to net asset value. Consider this: if you considered Main Street to be the best BDC in the world, you wouldn’t want to compare its premium valuation to the valuation of other BDCs. You’d probably want something safer, like a megabank like Bank of America, which not only lends to small and medium sized banks but also mega-corps and governments while diversifying in other banking activities like M&A advisory, retail deposits, and so on. Or at least you’d want your BDC valuation to be less than the valuation of these banks, right? But if you compare Main Street’s valuation to the price-to-book valuations of these big banks, Main Street is overvalued by 40% at a minimum. This just isn’t good enough for a very well-run but extremely undiversified asset.
The market has begun to realize just how silly BDC valuations were getting, but the market has made an exception for main Street largely due to the fact that just about every other BDC reported awful earnings. Net investment income fell for almost all BDCs that have reported so far, with Hercules Capital (HTGC: $13) seeing NII down 33% from the prior quarter. The dividend is now less than 100% covered. NAV fell a bit as well (over 1%). What happened? The market dumped shares, which fell over 16% in a week. This used to be considered one of the safest and best specialty BDCs out there, but the market can turn very quickly on this asset class. We’re not saying anything similar will happen to Main Street anytime soon, but it is a serious risk.
Then there’s Goldman Sachs’s BDC (GSBD: $24), which fell 3% this week due to a decline in net investment income and virtually flat NAV. The stock is still up 3% year-to-date so you’re paying a higher premium for shares, though. Now you’re paying 32% over what the underlying assets are worth. Of course, this BDC is up big over the past year, thanks in part to the secular bull market in BDCs and thanks in part to the Goldman brand. But, as we’ve written here previously, there is a complicated conflict of interest going on with this BDC that makes us extremely cautious. Goldman Sachs’s management is not duty bound to restrict their deal making just to this BDC, and so there’s a chance (although no evidence this is the case) that management can select better deals for the parent company and keep lesser deals for the BDC business. Without clearer governance resolutions, this makes us extremely cautious. And, at the end of the day, this demonstrates one of the structural problems with many BDCs: management and investors’ interests do not align.
Some of the BDCs in the business were loved for avoiding this trap. The big Ares Capital Corporation (ARCC: $16.60, down 6%) is a good example. But this stock tanked as well, after reporting earnings fell 50% from a quarter ago and NAV rose less than 1%. We don’t need to emphasize how bad those results are, and how they deserve a discounted valuation. But Ares is still trading at a slight premium to NAV.
Obviously, a bigger correction in the BDC market is coming, so where else can we look? REITs and municipal bonds remain our favorite corners of the high yield market. The iShares S&P National AMT-Free Municipal Bond Fund (MUB: $109, flat) remained sleepy due to the risk-on nature of the market encouraging more investors to avoid the asset class, despite the growing number of undervalued bonds and great opportunities to get low risk yield for fund managers. Bull Market Report favorites remained flat for the week, Invesco Municipal Trust (VKQ: $12.69, flat) and The Nuveen AMT-Free Fund (NVG: $14.79, flat) Buying more of either fund at this juncture would make a lot of sense.
And then as REITs go, the SPDR Dow Jones REIT ETF (RWR: $92, down 1%) fell slightly with investor apathy hitting the asset class on little news. This again is resulting in plenty of good deals among REITs, and The Bull Market Report continues to have high conviction for long-term sustainable yields from Digital Realty Trust (DLR: $114, down 1%), Omega Healthcare Investors (OHI: $32, down 2%), and Care Capital Properties (CCP: $27, flat) in particular. Looking forward, we will be looking closely at how REIT earnings results and more market responses from the BDC market causes a reset in high-yield land that offers an opportunity to rebalance the portfolio.
Good Investing,
Todd Shaver, Founder
The Bull Market Report
CEO and Editor in Chief
Founded 1998