
Mazor Robotics (MZOR)
Key Measures:
Recent Price: $15.80
52 Week Price Range: $8.30-$17.35
EPS: (-$0.36)
Shares Outstanding: 42 million
Market Capitalization: $355 million
Target Price: $25
Sell Price: $14
Robotic Surgery: The Spine Is Next
Minimally invasive surgery has been around for a while. Intuitive Surgical (ISRG) pioneered the wave with its da Vinci robotic suite designed for urological procedures like prostatectomies and hysterectomies. We tracked Intuitive back 15 years to 2001 when it was $11 per share. Today the shares sell for $648. To say that Intuitive Surgical investors are happy is an understatement.
New innovations in medical technology can be tricky and their stocks can be volatile. So if you waited until just 10 years ago when the da Vinci system was well accepted, your investment return would still have been a tidy 600%. Not too shabby.
Well, we have found what could be the next Intuitive Surgical. The name is Mazor Robotics. This company, founded in 2000 is focused on minimally invasive robotic surgery for the spine and the brain. Their Renaissance System has regulatory approval for use in the United States and most everywhere else in the world. There are already 110 units in place worldwide with 65 in the United States.
The company makes money from three sources. The Renaissance Surgical suite sells for $850,000. With the sale, Mazor offers maintenance and service under contract. This is like an annuity income that is highly profitable. The third source is Disposables. At a cost of $1,500 per operation, this is the second most important revenue stream to Mazor. The gross profit on these items is over 80%.
Why should Mazor be successful? First off, they are already successful in pioneering a better product. This gives them valuable time for marketing without serious competitors. In the medical equipment business, this is especially important. Once a surgical team has been trained on a new procedure, it practically takes an Act of Congress to get them to change. Next, the Renaissance System simplifies the complicated nature of spinal surgery. The system is 98-99% accurate, reduces complications by more than two-thirds and reduces exposure to harmful radiation by 35-50%. Finally, it reduces recovery time which makes for happy patients. When it comes to alleviating back pain a satisfied customer is a walking endorsement for the Renaissance System.
We referenced Intuitive Surgical above for more reasons than its spectacular stock performance. Both Mazor and Intuitive Surgical use the same “razor and blades” business model that makes these two comparable. Mazor has one advantage at this early stage, which Intuitive did not. In May, Mazor signed an agreement with healthcare powerhouse, Medtronic (MDT) to accelerate their marketing in the United States. As a research- and technology-centric company based in Israel, Mazor will benefit enormously from this arrangement.
Potential for Robotic Spinal Surgery is Staggering
In the United States alone, over 500,000 spinal surgeries are conducted each year. Globally, we estimate the figure is in excess of 1,000,000. The North American spine surgery devices market is expected to grow at a 7% compound annual growth rate by 2019, according to a Research and Markets. Figuring out the number of machines to service this market; how long it will take to reach maximum potential; the number of service contracts; and the quantity of disposables is the puzzle to solve in placing a value on Mazor. Here is where Intuitive’s experience is a real help.
The most recent data shows da Vinci was used in over 650,000 procedures last year employing 3,600 machines. That works out to one surgery suite for every 180 procedures. If we use this as a proxy, Mazor will need to sell roughly 2,800 Renaissance Systems to service 500,000, and that is just half the global market. This translates into equipment revenues of $2.4 billion. Add to that $750 million in disposables and another $300 million in service contracts and the revenue potential hits $3.4 billion. If Mazor matches Intuitive’s scale and efficiencies, their after tax earnings will reach over $650 million. Valuing these earnings at a market multiple of 20 times works out to $13 billion. (Just so you don’t think we are crazy, Intuitive’s market cap today is $25 billion). Mazor is presently valued at $355 million – a third of a billion dollars.
Please note with all our work on the Renaissance Spinal System, we are leaving out Mazor’s suite of neurosurgery opportunities. But you get the idea: Even though the stock has rebounded off it 52 week low of $8.30 a share, it is just getting started and there is a lot more to the Mazor story.
Recent Results: Lots of Growth Now, Profits Will Follow
Our enthusiasm is based in reality; the business is taking off. As the table below shows, after a meager 6% revenue growth in 2014, the pace picked up to 23% in 2015 as more systems were placed in service. The acceleration continued in 1Q16 with revenues gaining 42% to $6.4 million. It is noteworthy that disposable sales increased at the same pace. That tells us that surgeons are willingly converting to the Renaissance System in their Operating Rooms.
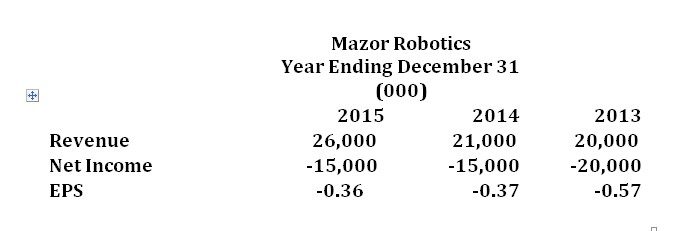
The Medtronics Deal is a Winner
On May 18, Mazor signed a major agreement whereby giant Medtronics will buy 15 Mazor spinal systems and will purchase 4% of Mazor’s stock. Medtronic agreed to promote the Renaissance System and even took an option to buy as much as 15% of the company. This deal is beneficial to both sides. It aids the placement of Renaissance Systems and enhances the existing spinal surgery business of Medtronics.
The implication of the Medtronics deal goes beyond money and marketing benefits. It creates a more valuable company from the standpoint of a potential acquisition. Is it possible that Intuitive Surgical would want to get into the spinal surgery business and look to Mazor to get them started? Is there a possibility of a bidding war developing between Medtronics and Intuitive Surgical? Any answer would be mere speculation but having two strong players standing nearby is great news.
Balance Sheet: The Company Has Ample Liquidity To Grow
For a young company on the verge of breakout growth, Mazor’s balance sheet shows good liquidity. Cash amounts to $33 million with virtually no long-term debt. The stock purchase agreement with Medtronic will add a further $12 million in cash to the balance sheet. Under the agreement, if Medtronic acquires fully 15% of Mazor, it will add a further $40 million in cash. This is an important safety blanket. Mazor has been operating at a cash flow deficit until now and that is only likely to continue as it growth rate accelerates.
BMR TAKE:
Investing in high growth companies typically demands overpaying in the beginning with the hopes that earnings will grow into the valuation. Just look at names like Facebook and Google. With Mazor, we have an exception. Way back in January 2014, investors valued the company at the same $25 price tag that we place on the company today. Since then the number of Renaissance Systems in service has nearly doubled. In the past 2½ years, the value of the company has only increased while the price of the stock has dropped by more than one third. Now is time to get on the Mazor horse. It is going to be an interesting and profitable ride.