The Week Ahead
“Trump Mulls New Order On Travel” was the weekend’s front page Wall Street Journal headline. Everyone can’t seem to look away from what is happening in the oval office. Big name after big name investor keeps trying to make a call on the future from what is happening in Washington, only to be proved wrong. The latest is the $30 billion money manager Seth Klarman of Baupost. He says to look out for a negative year from equities due to elevated volatility from Trump’s leadership style; a major pick-up in inflation; problems from rising rates to the US debt; and slower global growth from protectionist trade policies.
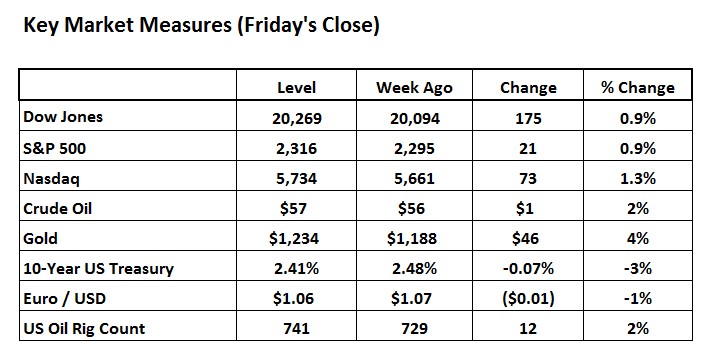
The S&P and Dow closed at a record high for a second straight session, while the Nasdaq extended its streak of record closes to a fourth day.
With more than 70% the S&P 500 having reported results, fourth-quarter earnings are on track to have climbed 8%, which would be the best performance since the third quarter of 2014. The S&P 500 posted 48 new 52-week highs and no new lows; the Nasdaq Composite recorded 150 new highs and 22 new lows.
The reality is there is always a Bull Market somewhere and right now it is in the United States. This week we provide some insights on our latest thinking for Twilio, the iShares Energy Sector ETF, CBRE Group, the Nuveen Municipal fund, and Facebook.
Highlights From The Past Week
Leadership Turnover At The Fed. This week Dan Tarullo unexpectedly announced that he is resigning in early April, just days after the Fed's general counsel Alvarez also announced that he is departing the Fed. What makes Tarullo's resignation particularly notable is that he has been the Fed's "regulatory point man" since 2009, suggesting some regulatory friction has emerged. In light of Trump's vow to crush Wall Street regulations, one can see why Tarullo thought his services are no longer necessary. His brief resignation letter to Fed Chairwoman Janet Yellen didn’t give a reason for his departure. He said he has been privileged to serve at the Fed for eight years. The letter said his resignation will take effect “on or about” April 5. We wonder just what is in store for Yellen and other members of the Fed. This is such a critical juncture for interest rates.
Prime Minister Abe Visits The USA. With a hug and a handshake, President Donald Trump and Japanese Prime Minister Shinzo Abe opened a new chapter in U.S.-Japan relations on Friday with Trump abruptly setting aside campaign pledges to force Tokyo to pay more for U.S. defense aid. Trump avoided repeating harsh campaign rhetoric that accused Japan of taking advantage of U.S. security aid and stealing American jobs. "We are committed to the security of Japan and all areas under its administrative control and to further strengthening our very crucial alliance," Trump said. "The bond between our two nations and the friendship between our two peoples runs very, very deep. This administration is committed to bringing those ties even closer," he added.
BMR Companies and Commentary
Twilio (TWLO: $32, +2% for the week*)
*All prices in The Bull Market Report are for the week
We wrote early this week about Twilio’s encouraging quarter. We wanted to circle back and follow up with more detail here about what investors are worried about. Sometimes when you ask the hard questions and go searching for the answers, you find out that the risks are less of a concern than one fears on the surface.
Investors’ worries on this stock generally fall into several categories: 1) gross margins; 2) eventual competition from AWS**; 3) pricing pressure from current competitors; and 4) the lock-up expiration. Let’s hit each one.
**Amazon Web Services
Twilio’s gross margin of 59% this quarter was above consensus of 56%. When asked about how the company plans to get from here to its long-term target 60-65%, CFO Lee Kirkpatrick pointed out that Twilio has “significant levers” that it can pull. The first is product mix. Management described the second lever as efficiencies gained through scale – this includes driving better deals with carriers and passing less of the savings to customers.
Another risk for investors to keep an eye on longer term is the potential for competition from AWS. AWS is not a competitor today, but Amazon CEO Jeff Bezos is known to covet large markets and the communications services market is substantial. In fact, Amazon and Twilio are currently working together. The Amazon relationship seems to be strong and is multifaceted. Note that Twilio runs entirely on AWS. Second, Twilio is already helping AWS with mobile products. Third, CEO Jeff Lawson was on stage at AWS re:Invent in November and commented, “We’re really excited to announce some upcoming collaboration with AWS soon.” Last, Rick Dalzell (Amazon’s former SVP of Worldwide Architecture and Platform Software and CIO) has been a member of Twilio’s board of directors since 2014.
Investors are also concerned Twilio may face pricing pressure from its current competitors, which include Nexmo (Vonage acquired them in May) and Plivo, among others. Twilio’s services are generally priced at a premium to these competitors. For example, for outbound SMS messages, Twilio charges $0.0075/message, compared to $0.0061 for Nexmo and $0.0035 for Plivo. Our view is that Twilio is generally able to charge a premium because it: 1) has significant mindshare within the developer community; 2) offers a high-quality, reliable solution; and 3) continues to release new features and software products. Mr. Lawson indicated on the earnings call that he seeks to “build a broad platform that is widely applicable, priced aggressively, and designed to enable developers’ creativity to flourish across the widest set of use cases imaginable.”
The availability of additional shares for sale in the market could adversely affect Twilio’s stock price. Twilio went public in June, selling 10 million shares at $15. Twilio completed a follow-on offering in October selling 7 million shares at $40. Roughly 30 million shares cleared lock-up restrictions in December and another 36 million shares were set to clear lock-up restrictions on January 19th. However, roughly 31M of those shares were subject to the company’s black-out period for insiders. Our understanding is these shares will clear the restricted period this Friday. Some of the largest shareholders of Twilio include Bessemer Venture Partners, Union Square Ventures, and Redpoint Ventures, which owned 17M, 10M, and 3M shares immediately after the follow-on offering, respectively.
BMR Take: Okay, we might see some pressure from the lock-up expiration that happened on Friday, but this is normal Wall Street procedure. Besides, we are sure that many of these owners will want to hold on for the coming years of growth. Furthermore, the business is building momentum making the stock attractively priced at this level.
CBRE Group (CBG: $34, +8%)
What a week. CBRE ended 2016 on a high note. For the year, revenue was $13.1 billion, up 20%, and EPS was $2.30, up 12%. CBRE recorded double-digit earnings growth for the fourth quarter and the year, with excellent performance in all three regional services businesses.
These results are particularly noteworthy in a year of generally softer market-wide property sales volumes, virtually no carried interest income, and tepid global economic growth. In fact, the company’s revenue and earnings performance set new record highs in 2016.
In addition to achieving record financial performance, very importantly, CBRE continued to advance its strategy. This strategy centers around delivering exceptional outcomes to clients. The company’s people and the operating platform that supports them are the key elements to delivering these outcomes. Both advanced materially in 2016, and the impact is showing up on the company’s results.
CBRE is in a stronger competitive position than ever. A good example of the strategic gains made in 2016 is the work done integrating the Global Workplace Solutions acquisition, one of the largest and quite possibly the most complex in the history of the real estate sector. This effort involved massive client facing, and line of business and back-office transformations. The result of having largely completed this challenging work is that the company’s occupier outsourcing business is much larger, much more capable of producing strong client outcomes, and well-positioned for strong long-term growth.
The company is now serving clients with employees on the ground in over 100 countries. What a big business. CBRE remains riveted on sustaining progress with particular focus on areas such as technology and data analytics where it can capitalize on the expertise and vast amounts of information it possesses. For example, last month CBRE acquired Floored, a leading software-as-a-service platform that produces scalable, interactive 3D visualization technologies for commercial real estate. Clients should expect continued visible advancements from CBRE in the technology area.
BMR Take: CBRE’s nickname is the “Bentley” of the real estate sector and in 2016 the business lived up to the expectations. The key takeaway from the earnings call was that no matter the interest rate environment, performance should be rock solid in 2017.
iShares Energy Sector ETF (IYE: $40, -1%)
The largest holding of the ETF at 22% is Exxon Mobil (XOM: $83, $340 billion market cap). The second largest holding is Chevron (CVX: $113, $210 billion market cap) at 14%. With the most recent earnings reports of these two behemoths of the Energy sector still being digested by the markets, we wanted to weigh in.
Exxon delivered its first increase in revenue after nine quarters of declines. The company provided a reassuring long term outlook. Global energy demand is expected to grow about 25% by 2040. Oil and natural gas is expected to meet about 60% of global energy demand by then. Attention quickly turned to 2017 capital expenditure guidance, with several suggesting the plans may be a bit aggressive at an early stage in the recovery, while others believe the increase shows increased management confidence in the recovery and the company's cash cycle. Everyone is much anticipating the expected detailed presentation on spending during the March analyst day meeting.
Chevron returned to profitability on Friday, reporting a huge quarterly earnings beat as the company continued to cut costs amid a protracted oil price rout now entering its third year. The company made progress toward its goals of lowering the cash breakeven in the upstream business and getting cash flow balanced. Capital spending and operating expenses have been reduced by over $10 billion since September 2015 as a result of a series of deliberate actions taken by the company.
BMR Take: The Energy sector recovery is happening. You can see in the rig count numbers and the earnings results out of both industry titans Exxon and Chevron. The IYE ETF gives you broad diversified exposure to the whole sector. There is a lot more room to run here for this stock.
Nuveen Municipal Credit Income Fund (NVG: $14.62, flat)
The AAA municipal curve steepened over the week outpacing the sell-off in Treasuries. 2 yr, 10 yr and 30 yr AAA municipal yields increased 2 bp, 17 bp, and 15 bp respectively over the past week. Supply dwindled at the end of January as this week's supply is projected to be just under $7 billion after $9 billion last week.
Meanwhile, the upcoming 30-day supply is at $11 billion, near the lowest level in a month and below the $12 billion 1 year average. On the demand front, mutual funds saw their first weekly inflow since the election. Mutual funds saw $1.6 billion of inflows for the week ending January 11th after 13 weeks of outflows. The outflow cycle was relatively short from a historical perspective as the last 3 cycles of mutual fund outflows averaged 24 weeks while this current outflow cycle stands at just 13 weeks. However, there is more room for outflows as new taxes are debated and uncertainty looms over the municipal market.
On the macro front, the Treasury curve steepened over the past week as 30 year rates increased 6 bp while the 2 yr was unchanged due to elevated CPI and positive NY Empire Manufacturing Survey buoyed rates. After two months of gains following the November post-election optimism, we are not yet seeing the underlying economic data improve to match the optimistic expectations. The Fed’s Empire Manufacturing Survey moved lower highlighting no spike in manufacturing business conditions. Hard data like industrial production remains lackluster. The decline in forward looking indicators such as new orders further suggests that underlying activity in the factory sector is not building any momentum. Trump-related euphoria might begin to dissipate.
All eyes remain on underfunded pension risks. Connecticut may be the next shoe to drop. The chief investment officer of the $30 billion Connecticut Retirement Plans, Hartford, resigned last week. We see a back story here that is troublesome.
BMR Take: The Municipal bond sector still represents a safe haven for those of you more focused on protecting your principal right now as opposed to trying to make a fortune. Nuveen Municipal Credit Income Fund is a solid fund for the job.
Facebook (FB: $134, +3%)
The controversy is nearing an end as Facebook committed to an audit of ad metrics by a media watchdog. Facebook agreed to submit to audits by the media industry’s measurement watchdog, the Media Rating Council, helping address concerns among some advertisers who had become skeptical of the social network’s metrics.
Facebook had come under fire recently after a series of missteps in which it disclosed several mistakes in reporting data to partners and advertisers. The company conducted its own review of practices and vowed to be more transparent about errors in the future. According to plans for the next year laid out in a statement Friday, Facebook said it aims to release more detailed information, such as metrics on how long users view an ad and how much of it was visible on the screen.
“We want to provide transparency, choice and accountability,” Facebook said. “Transparency through verified data that shows which campaigns drive measurable results, choice in how advertisers run campaigns across our platforms, and accountability through an audit and third-party verification.” Representatives from Facebook gave a presentation Thursday in Washington to the board of the Association of National Advertisers, a trade group for marketers. The meeting attendees were particularly interested in the promise for more transparency and an audit process.
BMR Take: Investors have been waiting for the advertising reporting issues to go away. Well, here we are - the event is happening. This new audit should address and resolve the issue. No more overhang for the stock from this. Having an independent organization validate the metrics Facebook puts out makes the data more trustworthy and provides advertisers with the ability to compare results across ad platforms. Now we can go back to focusing on the fundamentals where Facebook is firing on all cylinders. We are big believers in Facebook as it hovers near its all-time high of $135.50. And despite all of the controversy as discussed above, the stock stays within a whisker of its all-time high.
Upcoming Economic News
TUESDAY, FEBRUARY 14
Producer Price Index – January
Time: 8:30 am
Forecast: 0.2% overall, 0.2% core
The January Producer Price Index is forecast to report steady gains for the third straight month. The recent run-up in the index brought the yearly gain to 1.6% in December, the fastest rate in 27 months. Yet businesses should be well-equipped to handle somewhat quicker cost growth after the PPI rose only 0.9% annualized over the past five years.
WEDNESDAY, FEBRUARY 15
Consumer Price Index – January
Time: 8:30 am Forecast: 0.3% overall, 0.2% core
Higher gasoline costs can lead the Consumer Price Index to expand for the sixth straight month in January. Those fuel price gains have joined with rising housing costs to lift the broad CPI by the 30- month high rate of 2.1% yearly to December. Yet with crude oil prices holding flat last month, the significant feed-through to higher consumer prices may not accelerate substantially after the first quarter.
Retail Sales – January
Time: 8:30 am
Forecast: 0.1% overall, 0.4% ex auto
The drop in Auto sales may produce a lackluster overall result for January Retail sales. Auto sales eked out only a 0.7% year-over-year gain in the three months ending January, removing a once strong contributor to retail results. Sales outside of autos and gasoline managed a stronger if not overly robust 3.6% yearly gain in the fourth quarter, aided by rapid growth in online sales.
Industrial Production & Capacity Utilization – January
Time: 9:15 am
Forecast: 0.0% industrial production, 75.4% capacity utilization
Moderating Utility sector output can leave industrial production unchanged in January. December’s 6.6% gain in utility output was the largest monthly advance in 27 years. Meanwhile, manufacturing is pushing toward more sustained growth, rising 0.2% yearly to December for the first annual gain in six months.
NAHB Housing Market Index – February
Time: 10:00 am
Forecast: 68
Homebuilder confidence is likely to remain elevated in February, keying off especially strong expectations for future sales. The index of projected sales was at 76 in January, well above the historical average of 57. Seasonally warm weather is giving a near-term boost to building, with the 36,000 added construction jobs in January representing the most in 10 months.
Business Inventories – December
Time: 10:00 am
Forecast: 0.4%
Business inventories are expected to expand strongly for the second straight month in December. Inventories added 1.7% to the overall gain in fourth quarter GDP, the largest such positive contribution in 10 quarters. The inventories-to-sales ratio is edging lower after hitting the post-recession high last March, giving businesses reason to boost output.
THURSDAY, FEBRUARY 16
Housing Starts & Building Permits – January
Time: 8:30 am
Forecast: 1.23 million starts, 1.23 million permits
Recent gains in building permits give Homebuilding activity an upward bias in the near future. Permits rose 20% annualized in the fourth quarter, undoing the weak levels seen early in 2016. That raises the prospects that 2017’s total starts can achieve the projection of 8% yearly growth after almost always falling short of expectations over the past decade.
FRIDAY, FEBRUARY 17
Leading Economic Indicators Index – January
Time: 10:00 am
Forecast: 0.5%
The Leading Economic Indicators Index is anticipated to equal December’s strong gain thanks in part to falling unemployment insurance claims and a projected increase in building permits. Multi-decade lows in unemployment insurance claims point to labor market tightness where firms are extremely reluctant to cut staff. That condition naturally points to continued hiring gains and potential wage increases.
More On Stocks We Follow
Opko Health Update (OPK: $8.22, down 4%) Here is a typical report from a typical day in the life of Opko CEO Philip Frost: “CEO Philip Frost bought 10,000 shares of the business's stock in a transaction on Monday, January 30th. The shares were acquired at an average price of $8.49 per share, with a total value of $85,000. Following the transaction, the chief executive officer now directly owns 3,069,000 shares of the company's stock, valued at $26,055,000. The acquisition was disclosed in a document filed with the Securities & Exchange Commission.”
Here is another: “Opko Health CEO Phillip Frost acquired 12,000 shares of the business's stock in a transaction dated Friday, January 27th.”
BMR Take: This guy knows something we don’t know. Have you read the article in Forbes about him yet? We published the url twice now. (If you haven’t read it and would like to, please write us at Info@BullMarket.com) Despite these purchases the stock remains weak. We believe in this man and this company. We would buy some here, buy some at $7 if it goes lower, and we would buy some every dollar higher as it moves towards $15 again.
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
According to Thomson Reuters, 72% of the S&P 500 companies that have already reported have beaten earnings estimates. Based on the current reports and estimates, profit growth looks to be around 7% for the fourth quarter - its fastest pace in two years. That's good news and guidance for 2017 earnings seem to indicate there is more of this to come.
Prior UBS predictions as to what Trump growth policies could add to overall earnings growth estimates: as much as 15% over the next three years. Gains follow earnings, and assuming the 15% is equally divided over the three years, estimates could reasonably be revised upwards to gains hitting around 12% at yearend. If the economy does get jump-started by the repatriation of cash overseas, deregulation and infrastructure stimulus, we could see far more than a 5% rise for the Dow and S&P 500. Even if this happens, however, it should still beat bonds on a total return basis.
On the flip side, fund managers are holding the least cash in history. As of the end of December, mutual fund managers had 3% of their assets invested in the most liquid instruments that are readily exchanged for cash. That's the smallest cash cushion they've ever had, and with the increase in short-term interest rates, their "cash deficit" is now the most extreme since 2007.
Regardless of how good earnings are, money has to come from somewhere in order to buy stocks and drive prices higher. If it comes from selling one stock to buy another, we may be facing big sector rotation moves, a scenario of haves and have nots, and a lot more volatility than we would like to see. Fund managers have no alternative to selling stocks to cover redemptions when their cash positions are too low. This could be an interesting twist to an otherwise very positive outlook.
The World of the Supernova
This is Tom Friedman’s name for the Cloud. We don’t generally plug books here at The Bull Market Report, but if you want to know what the world of Technology is doing right now, the book to read is his new book, Thank You for Being Late. What the internet and Moore’s Law* is doing in this world of ours is astounding. Here’s some food for thought, a quote from Tom Goodwin of Havas Media in March, 2015: “Uber, the world’s largest taxi company, owns no vehicles. Facebook, the world’s most popular media owner, creates no content. Alibaba, the most valuable retailer, has no inventory. And Airbnb, the world’s largest accommodation provider, owns no real estate. Something interesting is happening.” Friedman goes on to say: “In the age of the supernova, there has never been a better time to be a maker – anywhere.”
*Moore’s Law – The power of the microprocessor doubles every two years. Since 1971.
BMR Take: Why are we printing this here? We want you to THINK about the Technology companies that are driving this growth. The Facebooks, the Apples, the Googles, the Amazons, the Microsofts. These companies are all in our High Technology portfolio and they will continue to lead and drive the growth and innovation in the world in the next decade(s).
What the Street Thinks of Athenahealth (ATHN: $114, up 5%)
Consensus Ratings: 1 Sell, 8 Hold, 12 Buy
Consensus Price Target: $135
Some Ratings from the Street:
2/6/2017 KeyCorp Target $140
2/7/2017 Piper Jaffray Target $162
2/7/2017 Berenberg Bank Target $143
2/6/2017 Dougherty Target $143
2/4/2017 Oppenheimer Holdings Target $142
2/3/2017 Robert W. Baird Target $155
1/31/2017 Cantor Fitzgerald Target $135
1/4/2017 Pacific Crest Target $140
What the Street Thinks of United Parcel Service (UPS: $107, flat)
Ratings Rating: 1 Sell, 8 Hold, 5 Buy
Consensus Price Target: $114
Some Ratings from the Street:
2/8/2017 Aegis Target $120
2/7/2017 Loop Capital Target $124
2/5/2017 Credit Suisse Group Target $110
2/1/2017 Barclays PLC Target $115
2/1/2017 BMO Capital Markets Target $115
A Letter from a Subscriber
From: Richard Reed [reed99277@xxxx.com]
Sent: Friday, February 10, 2017
To: Info at The Bull Market Report
Hello Todd,
I owned Annaly years ago when I subscribed to your service the first time. Three questions about it. First, is this a good entry point? The current price is near the 52 week high. Second, how safe is the dividend? Last, based on your email statements you feel that rising rates may not necessarily impact the stock price negatively. If rates go up gradually over the next few years do you feel the stock price won't be negatively impacted?
Richard Reed
Our Answer:
Hi Richard –
Annaly Capital Management (NLY: $10.52, up 2%, 11.5% dividend) – The stock could be headed to $11 or $10; no one can really say. What we do know is that they have weathered bull markets and bear; and high interest rate environments and low for the last 20 years. They are worth almost $11 billion, listed on the NYSE.
Interest rates – I personally feel that the bull market in bonds is NOT over (meaning rates will continue to go down.) Yes, they are up big since November, but they have actually been declining since December 15th, almost two months. So predicting interest rates is of course impossible.
Their dividend varies each quarter. Up a little; down a little. Management knows what they are doing and unless interest rates jump 100 basis points in a month or two, which is highly unlikely, Annaly should be able to continue to churn out their high dividends each month.
Todd Shaver
The Bull Market Report
PS: Note that we featured Annaly back in the late 1990s when it was paying 18% a year. It’s one of our favorites.
The High Yield Corner
By Michael Foster
Special to The Bull Market Report
This week was another quiet one for the markets, and high yield assets saw minimal movements with a couple of important exceptions. The biggest exception is the BDC sector, which was driven higher by some good earnings results. The UBS BDC ETF (BDCS: $23, up 2%) was one of the biggest gainers among high yield ETFs this week, thanks to constituent firms like Pennant Park Floating Rate Capital (PFLT: $14.00) and Medley Capital Corporation (MCC: $8.00) reporting solid earnings. Medley alone soared over 4% by the end of the week despite a 1% decrease to NAV that has become expected for BDCs. Also baked into valuations was a 16% decrease in net investment income per share - we’re now sitting at 19 cents for the company. Yet Medley’s dividend is 22 cents per share, so this quarter the company under-earned its payout by over 13%. That’s a pretty big miss.
Medley Capital is just one example of a problematic industry that requires more selective investing and a lot more due diligence than was necessary in the past for BDCs. These are effectively funds that leverage assets that are then lent to companies picked by management. In such a situation, debt quality is critical. Yet many of these companies have no real credit rating to speak of - and many of them are tiny, with revenues below $100 million per year. BDCs comprise dozens, sometimes over 100 of such companies. To really determine the value of a BDC and its relative future strength, you would need to look into the revenue trends for each of these companies and the condition of their existing capital. No small task, and a lot of time to invest for what should ultimately remain a very small portion of any one investor’s portfolio.
And that’s why we’re currently on the BDC sidelines, despite some strength in the broader index. The problem is this: we’re seeing net investment income per share drop for most of these companies, with only the best and brightest outperforming. In the past, such as in 2013, the market viciously punished these sorts of declines, but we’re not seeing that punishment yet. There is a clear disconnect between fundamentals and the value that the market is seeing in the BDC space. That’s enough to make anyone cautious, and has left us clearly on the sidelines until we can get some more coherent and consistent income growth. Especially since income growth is easy to find in many other pockets of the market.
Take, for instance, PIMCO Dynamic Income Fund (PDI: $29, up 1%), which has seen its NAV grow at an annualized 17% since its IPO. The fund has already appreciated by over 2% in 2017, and we’re not even at Valentine’s Day. The feat this fund has accomplished is really incredible - so much so that many people fundamentally misunderstand and mistrust how this fund makes money.
So how do they do it? The rather simple answer is asset selection. By combining undervalued corporate bonds with a variety of mortgage-backed securities, the Dynamic Income Fund has been able to sustainably return double-digit yields to investors without depleting capital. The market has rewarded this outperformance with a premium to NAV - something that one must always watch carefully, especially in a world as volatile as closed-end funds. And PDI’s premium is growing. In fact, PDI’s 10% premium is almost at the highest level we have ever seen for this fund. But there’s no fundamental weakness in this fund and no reason to expect its strong historical performance to stop.
So what is an investor to do? At the moment, we recommend holding, but a rotation of assets from PDI to a similar but better-valued fund may be in order in the future. This is an area worth watching closely and we’ll have ideas for you if things change.
It would be nice to see a similar problem come to the AllianzGI Equity and Convertible Income Fund (NIE: $19.44, up 1%), but this fund’s current 10% discount is pretty much par for the course when we look at its historical discount. Allianz’s fund hasn’t been priced at a premium since 2009, but its discount has frequently dipped below 15% in recent years. The fact that we’re at the upper end of the historical range for the discount indicates that even this unloved but strong performer is getting closer to pricing to perfection. But that doesn’t mean we need to sell the fund. This is a great closed end fund that has given investors a 6% annualized NAV return since inception, and its NAV is even 9% higher than it was at inception - a rare feat for CEFs. Allianz has done a great job of doing, in the convertible and equity sectors, what Pimco has done with its Dynamic Income Fund in the corporate and mortgage-backed bond markets: Make great investments by selective choices, and provide a strong return as a result.
This doesn’t mean we’re recommending holding these funds forever. We are getting closer and closer to a portfolio rotation moment in high yield, which means watching the market weekly is getting more important than ever before.
And the markets are telling us that there’s some exhaustion in the protracted Trump bull rally. Again, you can forget the political controversies surrounding the executive orders; they make great talking points for both sides of the aisle, and they’ve unfortunately made their ways into the editorial pages of the financial press, but none of this has any significant impact on America’s financial or economic future at the moment. The real action is elsewhere, namely in monetary policy and GDP growth. We really need to see changes to the Fed’s monetary policy (or at least a delivered rate hike as promised) or significant changes in the GDP growth rate to drive high yield assets away from their current trendline.
We’re not seeing that, so the indexes are a bit sleepy. The SPDR Barclays High Yield Bond ETF (JNK: $37) and the SPDR Dow Jones REIT ETF (RWR: $94) were flat for the week, with minimal gains in the REIT world offset by a small decline in the Alerian MLP ETF (AMLP: $13.04, down -2%). Meanwhile, there was more sleepy action with the iShares S&P National AMT-Free Municipal Bond Fund (MUB: $108, flat).
This quiet is actually good news for long-term investors. We’ve been inundated with gloom and doom economic forecasting since 2008 - and why not? Plenty of data points look bad, and the Global Financial Crisis is still a recent memory for most of us. And every passing year since the crash urges more pundits and analysts to tell us that we’re “overdue” for a correction or an outright recession. Yet the markets do not see things that way.
At the same time, markets aren’t going crazy. We’re not seeing the heady bubble days of 2006-2007. No one is suggesting there is any “sure thing” in the markets, just like people insisted buying a house was a “sure thing” in 2006. There is a lot of price growth in equities, but no real sign of a runaway market where prices have gone far past fundamentals. Things look even more cautious in the municipal and junk bond markets, where prices still remain below their high point in 2014 and 2015. We are far away from the irrational exuberance that Nobel-winning economist Robert Shiller warned about both before the dotcom bust and before the housing crisis. That means income-seeking investors can still find funds to invest their money and get strong returns.
Unfortunately, such a state of affairs won’t last forever, so investors need to remain aware of the risks in the market. But they don’t need to be in a panic.
Finally, a quick word on one outperformer that bears a bit of particular scrutiny. AstraZeneca (AZN: $29.50, up 6%) continued to have a monstrous bull run after their recent earnings results. Fourth quarter earnings surged 56% and beat expectations by 3 cents at $1.21 per share despite a 13% slide in total revenues. This was driven by a 52% decline in Crestor sales and a 14% decline in Symbicort sales, which was offset by growth in newer drugs like Zoladex. Following the news, Bloomberg published a rumor that the company may sell off its old drug businesses to raise cash that could be applied to new research initiatives.
Our take on all this is clear: AstraZeneca has been a thorn in our high yield portfolio, being the only significant decliner in a portfolio of otherwise sharp outperformers. It was only a matter of time before the company lived up to its potential, and we’re happy to finally see that start to happen. We’re still down slightly from a year ago (excluding dividends.) But the recent turnaround tells us there’s more room for Astra-Zeneca to redeem itself.
Good Investing,
Todd Shaver, Founder, CEO and Editor
The Bull Market Report