February 4, 2018

by Todd Shaver | Feb 4, 2018 | Weekly Newsletter 7pm Sunday
The Weekly Summary
The stock market took a hit this week. It was down almost 200 on Monday, almost 400 on Tuesday, rallied a tad on Wednesday and Thursday, and got hammered on Friday to the tune of 666 points. It’s a week we can happily say has been put to bed and we can now forget about it. The long-awaited correction has now occurred. Happy now Wall Street pundits? (We don’t feel this way.) The big reason for the sell-off was interest rates. The 10-year was up again to 2.84%. And the 30-year moved up above 3%. But this is what happens when you have a strong economy – interest rates move up. This has been happening for over 100 years. The economy shines; interest rates go up. Why do you think rates have been so low? Because the Fed drove down rates after the debacle of 2008-2009 and kept them there for almost 10 years. Look at this chart here; it’s a bit hard to read at first – note that the right column shows the rate today – 1.48% and in 2008 it was 1.04%.
Now take a look at these two charts. The first one is the 10-year Treasury for the past six months. It's gone straight up.
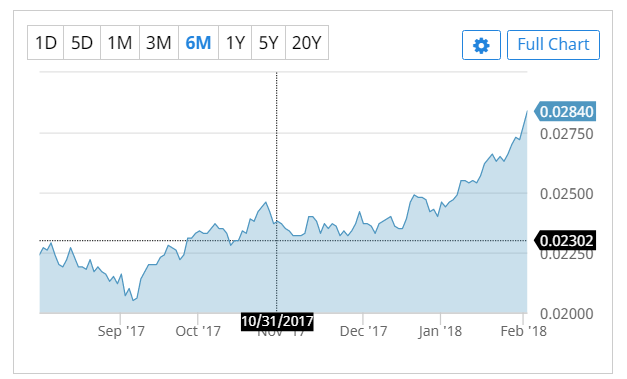
And this one is the 10-year for the past 20 years. Basically straight down.

The key takeaway here is the interest rates are STILL VERY LOW HISTORICALLY. This is actually good news for the economy and stocks. Thus it is our take that 1) We had a bad week last week 2) Things will calm down this week and in the coming months, and 3) Good solid companies will continue to thrive and grow as the US economy continues to strengthen.
Easy for us to say. Hard for you to implement. We understand that. But we want you to put this past weekly move in perspective. The market is where it was just three weeks ago, at 25,500. A year ago it was at 20,000.
The big oil companies came up a bit short on the earnings front last week. Most of the Street was expecting good things, as the price of crude has remained strong at $65. But Exxon’s production dropped by 130,000 barrels a day and has lost money now for 12 quarters a row on its US drilling business, even as US production touched the record production of 10 million barrels a day in November, the previous record being set in 1970. Plus they took a $1.3 billion write-down on its natural gas business. But overall, Exxon made $3.73 billion, a decline of just 2%. These big companies are expected to generate huge amounts of cash in 2018, so we aren’t feeling too sorry for them. The number could be over $40 billion, in excess of dividends and new spending.
Super Bowl Sunday is here! $5 million for a 30 seconds ad. Over 110 million viewers likely watched. The legacy of Tom Brady’s Patriots against the surprisingly better than you think Eagles. The Patriots are favored by 4.5 points. It is interesting. Very often in sports or in the markets whatever people expect to happen, doesn’t materialize. For all sorts of reasons: Cognitive dissonance. Conservative bias. Confirmation bias. Extrapolating past performance. Loss aversion. Overconfidence. Self-control. Regret aversion. Affinity. Status quo. The list of mental mistakes people make when investing is long and always at play. We saw a 666 point drop on the Dow on Friday. This was the 3rd largest one-day point decline in history. The market is digesting something. The Bull & Bear indicator managed by Merrill Lynch has finally flashed a firm sell signal after weeks of overextended conditions. We will see what happens Monday. The unexpected could happen. Just like in football.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight: Microsoft, Google, Amazon, Facebook, PayPal, and Blackstone.
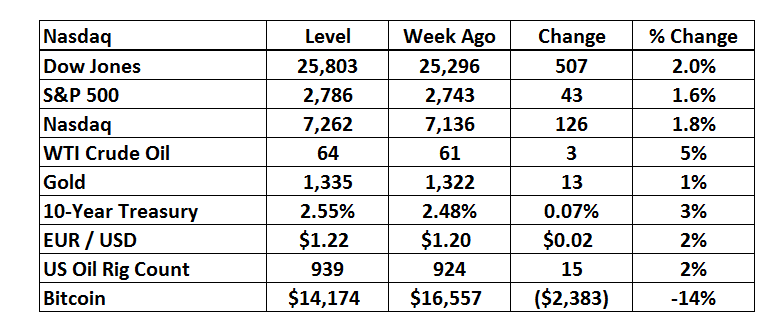
Key Market Measures

BMR Companies & Commentary
Microsoft (MSFT: $92, down 2%)
Revenue was $28.9 billion and increased 12%. EPS hit a solid $0.96 crushing the $0.87 consensus. This quarter’s results speak to the differentiated value Microsoft is delivering to customers across productivity solutions and as the hybrid cloud provider of choice. The firm’s investments in IoT, data, and AI services across cloud, position the business to further accelerate growth. In particular, Microsoft delivered another strong quarter with commercial cloud revenue growing 56% year-over-year to $5.3 billion, which is just amazing to see such a huge growth figure in the lucrative cloud opportunity. Guidance for Q3 was largely in-line or better than consensus expectations. All in all, a very good quarter.
BMR Take: Microsoft is a stock market darling. The business is well-rounded. Legacy Window products to the up and coming Azure product in commercial cloud. We see Microsoft continuing to piece together solid earnings results in the year ahead. With $4.25 of EPS in direct sight, the stock still screens reasonable at around 22x.
----------------------------------------------------------------------------------
Google (GOOG: $1,112, down 5%)
Revenue of $32 billion increased 24% from a year ago. EPS of $9.70 just missed the consensus for $10.00. Overall, we are interpreting the quarter’s results favorably (unlike the Street.) Mobile and desktop search along with YouTube are powering accelerating growth and these trends should drive sustained above average growth going forward. Google Cloud momentum is good now generating $1 billion in revenue per quarter, where the number of $1 million or more contracts across cloud products tripled in 2017. Google has now sold ‘tens of millions’ of its Mini, Max, and Chromecast devices as Google Assistant is now on over 400 million devices globally. Waymo’s progress is accelerating. They plan to launch a ride-sharing program in Phoenix operated by self-driving cars this year. Wow.
BMR Take: We really don’t care much about the slight EPS miss. The stock being down is an opportunity to accumulate shares. Scouring through all the analysis on the quarter, nobody is really saying anything that seriously concerns us. What we want to see going forward is more progress on the cloud business. Amazon AWS is now at 35% market share versus Google Cloud only in the high single digits. If Google can close that gap, this stock can continue its strong move higher. With nearly $50 of EPS coming into view, the current valuation of 23x is far from stretched.
----------------------------------------------------------------------------------
Amazon (AMZN: $1,430, up 2%)
Amazon is crushing it. What else is new? (!) Net sales increased 38% to $60 billion in the fourth quarter, compared with $44 billion in 4Q16. EPS of $6.15 was well above $4.90 a year ago. There is so much to discuss here. What we are really excited about is the Echo business. Earlier in the year Amazon introduced three new Echo devices: the all-new Echo ($100), featuring a new design, improved sound, a lower price, and a choice of colors to personalize your device; Echo Plus ($150) with a built-in smart home hub so customers can easily set up and control their smart home devices; and Echo Spot ($130), a compact Echo with a screen so you can see the weather, get the news with a video flash briefing, view lyrics with Amazon Music, watch a camera monitor, browse and listen to Audible, and more.
This new business opportunity could be huge. Said Jeff Bezos, Amazon founder and CEO, “Our 2017 projections for Alexa were very optimistic, and we far exceeded them. We don’t see positive surprises of this magnitude very often — expect us to double down. We’ve reached an important point where other companies and developers are accelerating adoption of Alexa. There are now over 30,000 skills from outside developers; customers can control more than 4,000 smart home devices from 1,200 unique brands with Alexa; and we’re seeing strong response to our new far-field voice kit for manufacturers. Much more to come and a huge thank you to our customers and partners.”
While Amazon doesn’t break out the financials on Alexa and its other electronics business, the results from its cloud-computing business, Amazon Web Services (AWS), were obvious and contributed much more to the company’s record profit total. AWS saw revenue shoot 45% higher to $5.1 billion, with profits of $1.3 billion. Wow – that’s 26% after tax. AWS and the tax gain of $790 million for the changes in the U.S. tax code, which lowers Amazon’s tax rate to 21%, were the biggest contributors to the company’s overall net income of $1.86 billion. Watch for a possible spin-off of the cloud business sometime this year. Can you imagine what this will do to the stock? Does “shoot higher” ring in your head?
BMR Take: Look, when Jeff Bezos gets surprised by how good a business is doing, and says he is doubling down, you have to take note. But don’t just take note. Take action on it too. You have to have Amazon in your portfolio. You can’t look at the business on current revenue or earnings and say it’s cheap or expensive. It’s an innovation machine. They are constantly doing start-ups, like Echo. More new paid members joined Prime in 2017 than any previous year — both worldwide and in the US. The business is roaring with momentum and still has a very bright future ahead even at the current stock price level.
----------------------------------------------------------------------------------
Facebook (FB: $190, flat)
Flat for the week. Not bad in the whole scheme of things. Facebook increased revenue 47% to $13 billion. EPS of $1.44 was up 19%. What a good quarter frankly. Though while 2017 was a strong year for Facebook, it was also a hard one," said Mark Zuckerberg, Facebook founder and CEO. "In 2018, we're focused on making sure Facebook isn't just fun to use, but also good for people's well-being and for society. We're doing this by encouraging meaningful connections between people rather than passive consumption of content. Already last quarter, we made changes to show fewer viral videos to make sure people's time is well spent. In total, we made changes that reduced time spent on Facebook by roughly 50 million hours every day. By focusing on meaningful connections, our community and business will be stronger over the long term."
Some analysts were scrambling a bit to figure out what this all mean. But monthly active users increased 14% from a year ago to 2.13 billion. Essentially, the issue is that Facebook has had a huge growth engine coming from adding users. Seriously 2.2 billion users is huge. The runway here is slowing down and that means Facebook is going to have to find another way to take over the world. And that is what Zuckerberg is saying. They will be focusing on quality of usage and fully monetizing existing users.
BMR Take: The company is look at EPS growing from $5.40 in 2017 to $8.70 in 2019. It is not easy to find a 20% earnings growth story. We really like the global platform Facebook has built and all the future opportunities it creates for advertising and other revenue opportunities. We see the same story here as elsewhere in large cap tech, trading for 22x is just not stretched.
The stock hit a new all-time high of $195 on Thursday and even traded at $194 on Friday, before the deluge. What a great company.
Stay the course.
Look at this 5-year chart. Where do you think it is headed, as it moves to 2.5 billion users?

Active Users Chart

----------------------------------------------------------------------------------
PayPal (PYPL: $77, down 10%)
PayPal delivered strong numbers. Revenue increased 26% to $3.7 billion. EPS increased 57% to $0.50. Overall, PayPal had a transformative year in 2017. The company brought record numbers of new customer accounts to the platform by simplifying life for consumers and merchants.
PayPal also substantially expanded its opportunities for future growth and redefined its competitive position through successful partnership strategies. For example, PayPal and Synchrony Financial announced an agreement expanding their consumer credit relationship. Under the terms of the transaction, Synchrony Financial will acquire PayPal's U.S. consumer credit receivables portfolio, which totaled approximately $6.4 billion at the end of 2017.
BMR Take: So why is the stock down? PayPal and eBay have signed a term sheet to make PayPal available as a way to pay on eBay, through July 2023. But the fact that PayPal’s exclusivity on eBay is going away has people up in arms. This aspect of the PayPal and eBay relationship has been well-discussed and should not surprise people. Don’t let it fool you.
We look at PayPal like this. This quarter new customers increased 9 million up to 227 million total customers. Facebook has over 2 billion users. With time PayPal could look a lot more like Facebook. That means massive growth still lies ahead. We believe in riding this train. We are talking about the next gen MasterCard or Visa here. A 10% drop in the stock is a good opportunity to take advantage of.
----------------------------------------------------------------------------------
The Blackstone Group (BX: $35, down 4%)
Total revenue ended the year at $7 billion up 39% from last year. EPS of $2.21 compared to just $1.56 a year ago, a huge 42% jump. This business is grooving! It was another strong quarter of core business trends. Specifically, total assets under management increased an elevated 12% sequentially to a record $435 billion, driven primarily by $62 billion of inflows. Capital deployment of $20 billion in the quarter represented a record. And dry powder remained elevated at $95 billion, which bodes well for future capital deployment levels. Just to put that in perspective, Blackstone realized half of the $7 billion of revenue this year from carried interest on prior year inflows, that were deployed to generate big gains of which Blackstone gets a percentage of the profits.
You are telling me the company has $95 billion to put to work to do more of this? Let’s assume on average they can collect a 10% carry on that money. They just doubled the business.
BMR Take: It was a truly exceptional year for Blackstone, reflected by outstanding earnings growth and record capital activity that drove their highest-ever level of aggregate cash distributions to shareholders. Blackstone’s tireless drive to innovate has enabled the company to launch large-scale new product areas that reach a wider client base and serve existing clients in new ways. Our investors in turn have entrusted the company with more capital than ever before, leading to a new record total assets under management of $435 billion, up 18% year-over-year. The stock is a good value at just 10x the current EPS of $3.25.
----------------------------------------------------------------------------------
----------------------------------------------------------------------------------
Economic Calendar
Total Light Vehicle Sales
Monday, February 5th, 10:00 AM
Period: January
Consensus: 17.2 million
Prior: 17.8 million
Consumer Credit
Wednesday, February 7th, 3:00 PM
Period: December
Consensus: $19.5 billion
Prior: $28.0 billion
Initial Claims
Thursday, February 8th 8:30 AM
Period: February 3rd
Consensus: 233,000
Prior: 230,000
----------------------------------------------------------------------------------
----------------------------------------------------------------------------------
Apple Reports Earnings
Apple (AAPL: $161, down 6%) sold 77 million iPhones in the holiday quarter. Apple’s forecast for the next quarter was also lighter than expected. Apple says they expect to sell 50 million iPhones this quarter, slightly lower than the Street expected, and this equates to slightly lower revenue and the main reason the stock got hammered last week.
Apple still blew past its own and analysts’ expectations for revenue and profit for its fiscal first quarter, reporting record sales of $88.3 billion and net income of slightly more than $20 billion. The company was able to increase revenue by 13% year-over-year by increasing iPhone prices and generating more money from the people buying Apple’s smartphones.
Apple jacked up the price on its premium iPhone X smartphone, starting the 10th-anniversary model at $1,000, pushing the average selling price, or ASP, of an iPhone far higher than analysts had ever experienced. IPhone buyers paid an average of more than $796 for their phones in Apple’s fiscal first quarter; iPhone ASP had never previously topped $700.
Apple also boosted its software and services segment revenue 18% year-over-year in the quarter to $8.5 billion. And listen to this:The App Store, Apple Music, iCloud and Apple Pay all had their biggest quarters ever.
Apple said, “During the week beginning Dec. 24, a record number of customers made purchases or downloaded apps from the App Store, spending $900 million in that 7-day period, followed by $300 million in purchases on New Year’s Day alone.”
“Other products” revenue grew the biggest of all. This includes smartphone accessories like the Apple Watch, which grew sales 50% year-over-year for the fourth consecutive quarter, as well as AirPods. Revenue hit $5.5 billion by selling such hardware, up 36% more than a year ago.
Apple is capitalizing on the opportunity at hand by producing more money out of iPhone users in every way possible. Apple is making more money on each iPhone, selling a few accessories to go with it, then signing up iPhone users for monthly subscription plans for services such as Apple Music and iCloud.
If Apple Music continues to grow at its current rate, it will officially overtake Spotify this summer as the streaming world's number one service. Apple Music has a monthly growth rate of around 5%. Spotify has a growth rate of just around 2%. If that keeps up, Apple Music will officially bump Spotify off the top in summer - and there's no reason to believe it can't, given that part of Apple's success in building an audience for Apple Music lies in the fact that the service comes bundled with most of the major devices the company sells.
BMR Take: The all-time high of $180 was hit January 18th. Two weeks ago the stock was down $7 and last week $11. Looks like a sale is going on in shares of this great company. Wait until that overseas cash starts hitting the books here in the US.

----------------------------------------------------------------------------------
VMware (VMW: $123) is Wrapped Up in a Dell Move
One way or the other it’s time to move on from VMware. Why? Dell Technologies owns 80% of the company and is discussing in the press whether to have VMware buy Dell in order for Dell to go public. It’s a back door tactic very rarely, if ever used before. It has impacted VMware greatly because no one really knows how it is going to play out. It looks like VMware might end up owning Dell, creating a behemoth Tech company consisting of Dell, VMware and EMC, plus a host of other tech businesses like cloud computing and cybersecurity. This might be a good investment, but little is known of its financials at this time, so we feel it best to wait and see how things shake out.
VMware was much higher a week ago, and Wall Street is quite nervous because it doesn’t really understand what is going on. The Street doesn’t like uncertainty, remember? (!)
BMR Take: We added the stock a year ago at $83 and we are up a shade under 50%. We think that’s a nice return (a GREAT return) and with everything going on with these new moves by Dell, we think it is time to take profits, sit on the sidelines and watch. Dell may be a stock to buy someday after they go public, but we will leave that decision for another day.
----------------------------------------------------------------------------------
----------------------------------------------------------------------------------
The High Yield Corner
By Michael Foster
Vice President of High Yield
After the S&P 500’s 2% drop on Friday, which has inspired headlines such as “stocks have worst decline in 2 years”, it’s easy to lose sight of the fact that the S&P 500 is up 3.4% YTD.
Before the decline, stocks were up 7.5%, so a drop was clearly necessary [so they say.] Investors who have gotten comfortable with a bull market may be a little scared, because they aren’t used to down days. And it’s easy to forget what is driving the bull market. Wages are up nearly 3% in the U.S., unemployment keeps dropping, corporate earnings are rising, and, perhaps most impressively, this strong economy is being mirrored around the world. The typically cautious IMF and World Bank have asserted that growth is strong around the world, and while these institutions have made a lot of blunders in the past, they aren’t SO euphoric as to bring out the contrarian bear in us.
For high yield, the cautions are amplified. Riskier income producers like Government Properties Income Trust (GOV: $16.65, down 7%) and AllianzGI Equity & Convertible Fund (NIE: $21, down 5%) are down heavy, although they operate in very different markets and are entirely different asset classes (REITs versus convertible bonds and covered-call stocks). To wit: the AllianzGI’s 5% decline on the stock is far steeper than its 2.9% NAV decline, which is itself slightly better than the S&P 500’s 3.2%. Now, of course we can’t read too heavily into short-term price movements, but at the very least this tells us something about the AllianzGI Fund: it is not making extremely risky bets on very volatile assets, so it isn’t in any danger right now. So why did it sell off in excess of its NAV selloff? You got it. Because of fear. And that’s why the fund remains a buy. It’s up 1.6% for the year, lagging the overall market by a bit.
And what about Government Properties Trust (GOV: $16.65, down 7%)? We recommended this REIT back in 2016 and although the REIT is down 7% since then on a price return basis, much more importantly its dividend has not been cut since then, and investors have actually gotten cash dividends of about 19% on their original investment since our recommendation. As a result, we’ve made a profit on a total return basis. And the dynamics of the fund haven’t changed. The REIT’s FFO over the last 12 months is $2.28, while the dividend is $1.72. Thus its FFO is 133% of dividend payouts, so it’s out-earning its dividend. There is no threat to the dividend stream in the short term, and rising rents thanks to a booming economy mean FFO will go up, resulting in even higher FFO coverage.
The income stream here is not at any risk, despite the implications of the recent absurd sell-off. Revenues have been rising by about 8%, so we don’t see any indication that revenues can’t support the current dividend payout. For this reason, there’s no reason to be more cautious about Government Properties, and plenty of reason to shrug off the recent price declines. In fact, it is a great time to add more to this very stable company that is absurdly undervalued.
Elsewhere in REITs, declines were much less severe. Only Omega Healthcare Investors (OHI: $26, down 3%) saw a decline in-line with the S&P 500, but that’s not surprising. We’ve discussed at length why this company’s dividend hikes are threatened, but the threat won’t materialize for years (we’ve estimated 5 years). Dips are buying opportunities for now, as long as investors are cognizant of the fact that the dividend hikes won’t last forever and the stock could sell off in a few years as a result. But if you want a strong and secure high income stream now, Omega is one way to do it.
Digital Realty Trust (DLR: $108) was the second-best investment in the Bull Market Report High Yield portfolio. It was flat for the week. That sounds bad, especially if you’ve gotten used to gains upon gains and few down days, which has been the market norm since the High Yield portfolio began in 2016. But it also shows, interestingly, that the market has a lot of confidence in Digital Realty (which also outperformed a lot of the Tech sector). This week, Amazon, Apple, and Alphabet reported earnings that proved the world’s demand for data centers isn’t going away. Alas, Digital Realty’s yield is tiny, but as an investment in a good company, it’s a great option for investors.
Apollo Commercial Real Estate (ARI: $18.14, down 1%), Ventas, (VTR: $54, down 3%), and Welltower (HCN: $58, down 3%) all saw slight declines, which we can consider to be more a result of REIT investors following the broader market trend. No big news came from any of these companies last week to warrant the selloff.
Similarly, AstraZeneca (AZN: $36, down 2%) fell a lot less than the broader market after weeks of strength in the Biopharma sector. AstraZeneca has not released any major news and there wasn’t any major sector announcements. We can dismiss this 2% decline as being relatively good in a week of short-term worriers cutting bets on all kinds of things more because of fear than for any fundamental reason.
Now, on to municipal bonds. The end-of-year sell-off in this asset class in anticipation of 2018’s rate cuts meant that these funds were attractively priced for income investors, and we still think long-term capital gains are in the cards. What we need to see is the market get used to our new Fed Chairman. While Janet Yellen did a wonderful job of managing monetary policy and bringing the Fed funds rate closer to historical norms, the job isn’t done. Jay Powell has already said that he will continue in the same mode. And that will limit enthusiasm for municipal bonds. that is, until the booming economy results in higher tax revenues for municipalities that, in turn, results in credit upgrades and thus increasing NAVs for our muni Closed End Funds. The timing on this eventuality is unclear, but there is good reason to be confident that it will happen eventually. Nuveen AMT-Free Municipal Credit Fund (NVG: $14.48, down 3%) and Invesco Municipal Trust (VKQ: $11.83, down 4%) are worth holding for the tax-free income as we wait.
PIMCO Dynamic Income Fund (PDI: $30) is the only High Yield holding to be up for the week, and for that we are grateful! But just as there’s little to read into the short-term declines, the short-term gain here isn’t a reason to celebrate. The market is all about short-term emotion-driven trading. If anything, the fact that the panic didn’t hit the Pimco fund may indicate that no matter how crazy the broader market is, we aren’t in full-blown panic mode. And that, quite possibly, could mean this correction won’t last very long.
Good Investing,
Todd Shaver, Founder and CEO
The Bull Market Report
Since 1998
January 30, 2018
by Todd Shaver | Jan 30, 2018 | Earnings Preview 12 PM
Equity Residential (EQR: $61)
Bull Market Report Target Price: $85
Bull Market Report Sell Price: $55
Earnings Date: Tuesday, After market close
Consensus: 4Q17
Revenues: $625 million
EPS: $0.36
Year Ago Quarter Results
Revenues: $605 million
EPS: $0.75
Key Things to Watch For in the Quarter
Analysts expect Equity Residential to report a 3% increase in revenues with a 50% decrease in earnings per share. Despite having beat estimates in each of the past four quarters, the stock is only trading 2% above its price this time last year. Nearly all of the stock’s 15% gains for the year have been wiped out since November with the oversupply issues in the real estate market. We believe the stock is oversold at its current levels, and will see support in the $60 range.
---------------------------------------------------------------------
Eli Lilly (LLY: $86)
Bull Market Report Target Price: $96
Bull Market Report Sell Price: $82
Earnings Date: Wednesday, 9:00 AM ET
Consensus: 4Q17
Revenues: $6.0 billion
EPS: $1.07
Year Ago Quarter Results
Revenues: $5.8 billion
EPS: $0.95
Key Things to Watch For in the Quarter
Eli Lilly is expected to report a 3% increase in revenues and a 13% increase in earnings per share for 4Q17. The stock has beat estimates in three of the past four quarters, and is currently trading 17% above its price levels from this time last year. The stock saw a bit of resistance at $86 earlier this year, and it had recently broken through, but with the tough market of the last two days, the stock is back to $86. This pharmaceutical company invests heavily in its research and development, which will drive its future sales and earnings growth.
---------------------------------------------------------------------
Facebook (FB: $186)
Bull Market Report Target Price: $190
Bull Market Report Sell Price: $155
Earnings Date: Wednesday, 5:00 PM ET
Consensus: 4Q17
Revenues: $12.5 billion
EPS: $1.95
Year Ago Quarter Results
Revenues: $8.8 billion
EPS: $1.41
Key Things to Watch For in the Quarter
Analysts expect Facebook to report a 42% increase in revenues and a 38% increase in earnings per share for 4Q17. Facebook has beaten estimates in three of the past four quarters which has been reflected in the stock’s 42% appreciation over the past year. Facebook’s growth over the past years has been unprecedented for a company of its size. It truly is adhering to its mission of creating a more connected world. We look forward to seeing what kind of developments CEO Mark Zuckerberg has in store for the connected world in 2018. We know it will be good.
---------------------------------------------------------------------
PayPal Holdings (PYPL: $83)
Bull Market Report Target Price: $87
Bull Market Report Sell Price: We would not sell PayPal
Earnings Date: Wednesday, 5:00 PM ET
Consensus: 4Q17
Revenues: $3.6 billion
EPS: $0.52
Year Ago Quarter Results
Revenues: $3.0 billion
EPS: $0.42
Key Things to Watch For in the Quarter
We are looking for a 20% increase in its sales and a 24% increase in its earnings per share for the 4th quarter of 2017. The stock has been on a tear since last year, returning investors a 110% capital appreciation since this time last year. The stock has gone nowhere but up since posting earnings that have exceeded expectations in the past four quarters. PayPal’s market cap is just over $100 billion, making it the largest publicly traded electronic payments company in the world. We look forward to seeing what PayPal has to offer as they continue to lead this growing industry.
---------------------------------------------------------------------
Microsoft (MSFT: $93)
Bull Market Report Target Price: $92
Bull Market Report Sell Price: We would not sell Microsoft
Earnings Date: Wednesday, 5:30 PM ET
Consensus: 2Q18
Revenues: $28 billion
EPS: $0.86
Year Ago Quarter Results
Revenues: $26 billion
EPS: $0.80
Key Things to Watch For in the Quarter
Microsoft is expected to report an 8% increase in revenues and a 7.5% increase in earnings per share for 2Q18. Microsoft’s ability to beat analyst estimates has been reflected in the stock’s 44% increase over the past year. The firm continues to produce high quality hardware and software, and has a very good understanding of their customer base. Microsoft also allocates an incredible amount of capital to research and development, with its most recent announcement being a push into quantum computing, which some say could be similar to the internet revolution in the 1990s.
---------------------------------------------------------------------
Blackstone Group (BX: $36)
Bull Market Report Target Price: $36
Bull Market Report Sell Price: $31
Earnings Date: Thursday, 11:00 AM ET
Consensus: 4Q17
Revenues: $3.3 billion
EPS: $6.43
Year Ago Quarter Results
Revenues: $2.8 billion
EPS: $5.25
Key Things to Watch For in the Quarter
Blackstone is expected to report an 18% increase in revenue along with a 22% increase in its earnings per share for 4Q17. Blackstone has exceeded analyst estimates in three of the past four quarters, and has seen its stock appreciate 17% over the past year. Technically speaking, the stock has underperformed both the market and the sector, and we believe this is a huge mispricing by the market. Blackstone currently trades at a PE of 15 and yields 5%. At these price levels the stock looks like a steal compared to its competitors.
---------------------------------------------------------------------
United Parcel Service (UPS: $129)
Bull Market Report Target Price: $125
Bull Market Report Sell Price: $106
Earnings Date: Thursday, Exact Time not Available
Consensus: 4Q17
Revenues: $18 billion
EPS: $1.66
Year Ago Quarter Results
Revenues: $17 billion
EPS: $1.63
Key Things to Watch For in the Quarter
Analysts expect UPS to report a 6% increase in revenues and a 2% increase in earnings per share for 4Q17. Despite beating estimates in three of the past four quarters, the stock has slightly underperformed the overall market. The stock has appreciated 24% since this time last year, and we expect to see similar returns moving forward as the demand for logistical services increases. Although we remain bullish on the stock, we are keeping a close eye on Amazon as it begins to roll out its own logistics services, posing a potential threat to UPS.
The stock has passed our Target of $125, and we believe the stock will go higher, as long as the market holds here and moves higher in the coming months. We hereby raise our Target to $142 and our Sell Price to $118.
---------------------------------------------------------------------
Alphabet (GOOG: $1,170)
Bull Market Report Target Price: $1,450
Bull Market Report Sell Price: We would not sell Google
Earnings Date: Thursday, 4:30 PM ET
Consensus: 4Q17
Revenues: $32 billion
EPS: $10.00
Year Ago Quarter Results
Revenues: $26 billion
EPS: $9.36
Key Things to Watch For in the Quarter
We are looking for a 31% increase in revenues and a 7% increase in earnings per share for 1Q18. The company has beaten estimates in three of the past four quarters, which has been reflected in the stock’s 45% appreciation since this time last year. The stock currently boasts a market cap of $815 billion, making it one of the largest publicly traded companies in the world. Although Alphabet is best known for its Google Search Engine, the company touches all aspects of technology from cloud computing to its most recent Television Streaming service through YouTube.
---------------------------------------------------------------------
Apple (AAPL: $165)
Bull Market Report Target Price: $194
Bull Market Report Sell Price: We would not sell Apple
Earnings Date: Thursday, 5:00 PM ET
Consensus: 1Q18
Revenues: $87 billion
EPS: $3.81
Year Ago Quarter Results
Revenues: $78 billion
EPS: $3.36
Key Things to Watch For in the Quarter
We expect to see a 13% increase in earnings per share along with an 11% increase in sales for 1Q18, despite less than ideal results with the release of the iPhone X. The stock has beaten estimates in each of the past four quarters, and has appreciated 38% since this time last year. We also saw Warren Buffet add more stock to his portfolio, which should definitely not be overlooked. We expect to see growth in iPhone and iPad sale over the next year, and remain bullish on the stock. The cash repatriation should begin soon and that will produce some changes – in the dividend and in their outlook on buying new technology firms.
---------------------------------------------------------------------
Visa (V: $123)
Bull Market Report Target Price: $123
Bull Market Report Sell Price: We would not sell Visa
Earnings Date: Thursday, 5:30 PM ET
Consensus: 1Q18
Revenues: $4.8 billion
EPS: $0.99
Year Ago Quarter Results
Revenues: $4.4 billion
EPS: $0.86
Key Things to Watch For in the Quarter
Visa is expected to report a 9% increase in revenues and a 15% increase in earnings per share for 1Q18. Visa has beaten estimates in each of the past four quarters, and seen a 50% appreciation in its stock since this time last year. Despite paying a relatively small dividend, the stock still trades at a PE of 44, suggesting it is fairly valued compared to its competitors. We are confident in Visa’s ability to drive earnings growth through the new year. This $280 billion market cap company is a long term hold.
---------------------------------------------------------------------
Amazon (AMZN: $1,420)
Bull Market Report Target Price: $1,500
Bull Market Report Sell Price: $1,225
Earnings Date: Thursday, 5:30 PM ET
Consensus: 4Q17
Revenues: $60 billion
EPS: $1.84
Year Ago Quarter Results
Revenues: $44 billion
EPS: $1.54
Key Things to Watch For in the Quarter
Analysts expect Amazon to report a 36% increase in revenues and a 19% increase in earnings per share for 4Q17. Despite having only beaten estimates in three of the past four quarters, the stock currently trades 70% higher than its levels this time last year. Amazon continues to lead the charge in the online retail space, and we firmly believe in the longevity of the firm. Although the company trades at a very high PE of 350, we believe this is explained by the company’s inherent ability dominate and revolutionize the Retail industry.
---------------------------------------------------------------------
AstraZeneca (AZN: $36)
Bull Market Report Target Price: $42
Bull Market Report Sell Price: $32
Earnings Date: Friday, exact time not available
Consensus: 4Q17
Revenues: $5.4 billion
EPS: $0.45
Year Ago Quarter Results
Revenues: $5.6 billion
EPS: $0.61
Key Things to Watch For in the Quarter
AstraZeneca is expected to report a 4% decrease in revenues and a 26% decrease in earnings per share for 4Q17. Despite the lack of top line growth, the stock has still managed to beat analyst estimates in each of the past four quarters, and has shown 30% year-over-year appreciation as a result. The stock currently trades at a PE of 26, which is relatively cheap compared to other firms in healthcare which average around 40. The stock pays a 4% dividend, and has room to grow in 2018.
We’re not liking this new development with a slowdown in revenues and earnings and are re-evaluating our take on this stock. More to come this weekend. In the meantime, we are moving our Sell Price to $34.
January 14, 2018
by Todd Shaver | Jan 14, 2018 | Weekly Newsletter 7pm Sunday
The Weekly Summary
Everybody has an opinion. Go search the internet and you’ll hear one fellow say the market is going to crumble, the next person say new highs are on the horizon, and the third individual tell you something that doesn’t make sense because they don’t even know what they are talking about. Accordingly, we feel the need to break it all down this week. No fluff. No spin. No wild opinions. Just a little ‘telling it like it is’ as a reminder that this The Bull Market Report. We aren’t like what you see on TV. And we aren’t like what you read elsewhere. We are just like you. Looking for the cold hard honest facts.
US equities ended the week higher in a quiet Friday of trading. Cyclical and value plays were among the better performers. The equity market is already up over 3% this year with some of our stocks like Amazon and Nutanix up more. Bonds are down this year and Treasuries were mostly weaker as investors realize the Fed is serious about raising rates. We saw more flattening of the yield curve indicating caution. In fact, the two-year T-note rose and hit 2.0% for the first time since 2008. Gold was higher for fifth straight week. Crude ended higher for the fourth straight week.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight: Cloudera, Blackstone, Amazon, Google, Eli Lilly, and Home Depot.
BMR Companies & Commentary
Cloudera (CLDR: $18.14, up 5%)
Cloudera met with investors this week at Citi’s Global TMT West Conference. The CEO discussed all that they are doing in terms of new technology. Let’s recap. Remember, understanding the big picture of what the company is doing is how you build real confidence in your investments.
First it is important to understand the backdrop of why Cloudera is such an exciting company. Everything right now is going through a major technological revolution. Look what is happening in cars, health, and virtual reality. Everything is getting connected. This newly-created connected world is creating a backdrop for data that is unprecedented. And in this area of the economy is where the world’s most valuable companies reside—Apple, Google, Facebook, and Amazon. They are all data driven. Economists say the world’s most valuable resource is now no longer oil, but data.
So where does Cloudera fit it? Cloudera helps enterprises enter this new world of machine learnings and artificial intelligence. Cloudera gives them access to this data to transform their business to become data dependent. The old days of just working with a database storage provider and some simple analytics are gone. Today, companies turn to Cloudera to build best-in-class artificial intelligence solutions that optimize all the available data out there, not just their own.
BMR Take: Machine learning and artificial intelligence are megatrends for the next 5 years. Get involved. Cloudera is a great opportunity. Revenue will explode from $360 million this year to $570 million in 2 years. We see Cloudera breaking the $1 billion revenue mark possibly as early as 2020. We added the stock at $22 in June so it has certainly been an underperformer for us. But we are very confident in the success of this company and continue to have a $28 price target on the stock. Sometimes one has to be patient to see the big gains that we expect. Cloudera is still tiny with a market cap of $2.5 billion. But they are growing 40% a year. We would expect to see this little gem grow to the $10 billion level at some point and then get plucked up by one of the big boys. And this might even happen sooner than you think.
------------------------------------------------------------------------------
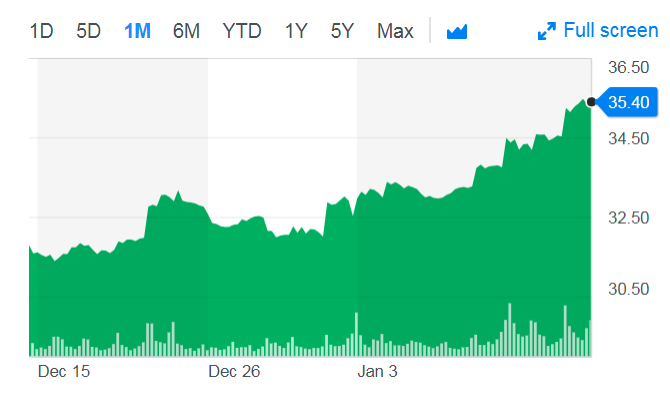
Blackstone (BX: $35, up 7%)
Blackstone is on a roll and caught an upgrade from JP Morgan. We love it when the professionals come around to our side of the table!
The reason to be excited at this point is that there is going to be a major fundraising cycle for Blackstone over the next two years. The company is expected to raise over $200 billion. The way the company makes money is through these massive fundraisings, then deploying the capital, and then getting a share in the profits from the investments.
The fundraising will happen in two funds. The first is Flagship Real Estate BREP-IX in 2018. The second is Flagship Private Equity BCP-VII in 2019.
BMR Take: Blackstone has been an underperformer relative to its peer group. And the peer group of these private equity companies hasn’t done too well. The entire space is relatively new to the public equity markets. Retail investors just don’t have the comfort level they have with other financials like AIG or JP Morgan. But we think that will all change. These companies print money. Blackstone will do over $3.00 of EPS in 2018. The stock is very inexpensive right now.
We’re up 30% on the stock since we added it in early 2016. Good but not great. The dividend has helped though, as that 5% a year adds up. But we expect more from this great company. Our Target was just reached this week, so we are going to go out on a limb and raise the Target to $42. If things go right, we would expect to see this by year end, but perhaps sooner.

------------------------------------------------------------------------------
Amazon (AMZN: $1,305, up 6%)
Amazon Fresh prices are up to 20% cheaper than major UK supermarkets.
Look out! We are going to see Amazon really shake-up the grocery market this year. Amazon's online grocery service Amazon Fresh is selling some products up to 19% cheaper than major supermarkets, new research suggests.
Amazon Fresh is a subsidiary of the Amazon.com. It is a grocery delivery service currently available in some U.S. states, London, Tokyo, Berlin, Hamburg and Munich. It will also launch in Australia soon.
The cost of a shopping cart from Amazon Fresh turned out to be 11% cheaper than the same online shopping from Tesco, and up to 19% cheaper than other competitors. The study was done by the consulting firm Oliver Wyman. The geography was in London.
Amazon Fresh is still relatively small but the internet giant has very serious ambitions in the grocery sector, suggesting that it may be looking at more acquisitions.
BMR Take: Amazon is a never-ending innovation machine; essentially a massive start-up. Look, the company will do $177 billion of revenue this year and we could rant and rave about the revenue growth outlook. But nobody knows what businesses Amazon will even be in over the next 3 years. They are knocking down doors and running through walls into new markets. Grocery will be tens of billions of dollars for Amazon in a market that the firm has been in for less than a year.
The stock had a banner week and hit our $1300 Target, setting a new all-time high. We believe we will see $2,000 someday in the future, but obviously not right away. But we can see $1,500 in the not-too-distant future, so we hereby raise our target to that level. The Sell Price is raised from $1,030 to $ 1,225.
------------------------------------------------------------------------------
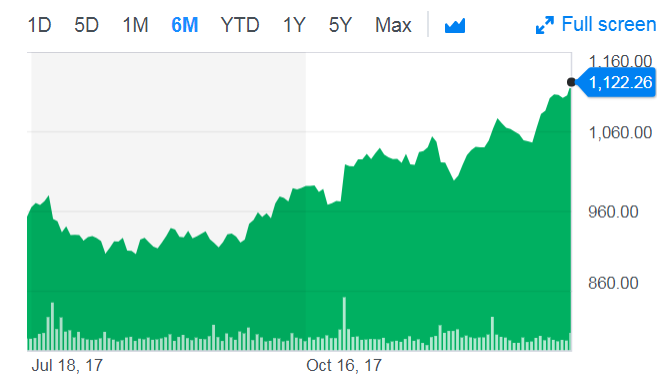
Google (GOOG: $1,122, up 2%)
Apple came under massive scrutiny this week. Parental oversight organizations said Apple should take more responsibility over how children use their devices in particular addition to the technology. We think Apple, Google, and Facebook in particular are making so much money they are likely to be the target of increased scrutiny by governmental authorities. In fact, we saw this week similar outcries against Google. We keep an eye on this risk but would not let it shake us out of any of these holdings.
Google has been profiting from a practice in the United Kingdom but banned in the US, in which brokers secretly reap millions of pounds from addicts seeking treatment in the UK. An undercover investigation by the Sunday Times has discovered a large fraud in this area. As a result of an in-house investigation, Google pulled all addiction-industry-related advertisements from its UK platforms.
BMR Take: Without question, Google and its peers will have to invest more in meeting social responsibilities and being a good corporate citizen. That said, Google can manage through this. We are looking at EPS going from $32 this year to nearly $60 by 2020. We can live without $1 or $2 of EPS if the company addresses these social issues and spends money to prevent thing like this advertising scheme being run through the platform in the UK. In fact, we encourage it, as it could result in a premium valuation.
Google set a new all-time high this week and is now worth $780 billion, closing in on Apple at $900 billion. (Of course, Apple set a new all-time high this week as well, so it’s certainly a good race!) Our Target has been $11,00 which was hit this week, and we expect a continued strong stock market which should proper Google higher. Thus, we hereby raise our Target to $1,450 and our Sell Price to $1,010.
Don’t like high-priced stocks? GET OVER IT. Buy some Google. Buy some Amazon. Buy 7 shares. Buy 23 shares. Just own these fabulous companies!
------------------------------------------------------------------------------
Eli Lilly (LLY: $87, flat)
Eli Lilly caught a big upgrade from Argus Research. Again, we love it when the professionals come around to liking our holdings!
What’s the excitement? Tax reform is a major positive for the company. Additionally, the company is working to sell its Animal Health business. The combination of these two events will create a cash windfall. Now the CEO is talking about doing a large acquisition.
Previously, big time M&A was just a distraction for the company as Lilly could not be competitive due to its balance sheet. However, now there is some real interest to move bigger into immune-oncology. Could we see them try to buy Bristol-Myers? (BMY: $63) Maybe; but that’s a big bite to chew off – around $120 billion.
BMR Take: Lilly is going to do $4.65 of EPS in 2018. They have $4.5 billion of cash. They have more cash than debt. They could do a mega-deal and this could get really exciting. We see why Argus upgraded the stock with a $115 price target.
We at The Bull Market Report have a Price Target of $88 on the stock at the moment, but we expect mid-90s by summer, so we hereby raise our Target to $96. Our Sell Price moves higher too, from $76 to $82.
------------------------------------------------------------------------------
Home Depot (HD: $196, up 2%)
To be honest, we are frankly a bit upset at Home Depot right now. We expect a lot from our companies - we wouldn’t recommend them to you otherwise. Home Depot put out this official statement on tax reform back in November, “The Home Depot is very supportive of tax reform that would fuel the economy by putting more money in the majority of Americans' pockets while improving the competitive position of companies so they can create more jobs. We applaud Congress for its efforts in moving tax reform forward.”
What is it missing?
Where is the minimum wage hike? Where is the $1,000+ bonus to employees. Walmart, some big banks, and many other companies took additional actions. All Home Depot did was issue a press release of encouragement.
We will get over it. But Home Depot missed an opportunity to demonstrate its corporate leadership in this country.
BMR Take: Home Depot is going to do nearly $9 of EPS in 2019. EPS should grow at least mid-single digits. The housing market is doing great and we expect ongoing favorable tailwinds for Home Depot. The stock is still going to go higher, but it could go much higher if they would not miss opportunities to build goodwill with the market as an exceptional corporate citizen.
Our Price Target is $205 which we will leave here for the time being. The Sell Price of $178 is hereby increased to $186.
------------------------------------------------------------------------------
------------------------------------------------------------------------------
Economic Calendar
Capacity Utilization
Wednesday, January 17th, 9:15 AM
Period: December
Consensus: 77.3%
Prior: 77.1%
Housing Starts
Thursday, January 18th, 8:30 AM
Period: December
Consensus: 1,278,000
Prior: 1,297,000
Michigan Sentiment
Friday, January 19th, 10:00 AM
Period: January
Consensus: 97.0
Prior: 95.9
------------------------------------------------------------------------------
------------------------------------------------------------------------------
Time to Take Our Profits in Tesla?
Tesla (TSLA: $336, up 6%) had a great week, but the more we think about it, the more worried we become. They have orders for 400,000 Model S cars and said last year that they would be delivering 5,000 a week starting in October, 2017. Well, guess what, this 5,000 number has slipped a number of times so that now they are talking about the 2nd quarter of this year. That’s a big slip. Maybe there is something seriously wrong here. No one seems to know and the company certainly isn’t helping us with solid information.
The company is going to need massive amounts of cash this year. They are bleeding money each day, each week, each month, so we expect more secondaries this year, diluting existing stockholders. And more bond sales as well.
Can the company survive and thrive? That’s the question that we are wrestling with.
We love the company; the world loves the cars. We love Elon Musk, but he is a promoter for sure. A loveable genius with a $56 billion market cap company.
The more we think about it and the more we write about it, we just have to book our profits. We are up 69% since we added the company two years ago at $199. OK, wait a minute. We’ll let the market tell us when to sell: If the stock goes to $320, we are OUT.
It’s tough to invest in a visionary. The vision always takes longer than the genius or the masses of followers expect.
------------------------------------------------------------------------------
Apple's App Store Broke Records this Holiday Season
Apple’s App Store started off 2018 by breaking app purchasing records on New Year's Day. Consumers spent $300 million in app purchases on January 1, 2018, marking the highest sales day for the App Store since its launch in 2008.
This outstrips last year’s record-breaking figure of $240 million in purchases on New Year’s Day. Customers spent $890 million on apps from December 24th-31st. Insights into app spending during the holiday season are indicative of the strength of the iOS platform for the year to come, as many consumers receive smartphone devices and purchase new apps, games, and subscriptions over the holiday period.
Apple’s App Store revenue gets bigger each quarter and each year. Developers received $26.5 billion for the year, up 30% year-over-year, and is now over $86 billion since 2008. For 2017 the $11.4 billion in revenue was almost 5% of the company’s projected $237 billion in total revenue.
------------------------------------------------------------------------------
------------------------------------------------------------------------------
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
Earnings season officially kicked off last week with the big banks leading the way. We expect decent to good numbers, but the big thing to watch for will be forward guidance, particularly on how much tax cuts will impact the bottom lines. Some sectors like Energy will likely benefit more than others which traditionally have been able to pay lower effective rates such astech.
Last week, Bank of America analysts raised their earnings forecast for the S&P 500 by $14 to $153 per share, as a result of the new lower 21% tax rate. (Source: Merrill Lynch). In market-speak, that means that if corporate earnings for 2018 reach $153, and the market's trailing PE is 18, the S&P 500 will be trading at 2754. Today it is trading at 2786…………………….oops, that doesn't sound very promising. For the market to reach 3029 (a 9% gain), the S&P 500 would need to trade around 20X trailing earnings. That is of course doable, and not outside the realm of just being a high-priced market rather than a bubble, but it would be a lot better from a fundamental standpoint if the market could see fit to earn a higher number this year. We should have a better grasp on a projected year-end earnings target after earnings and guidance are announced over the next several weeks.
Meanwhile, what a week the market enjoyed two weeks ago. It was one of the best first weeks of any new year in history. There are plenty of historical stats which show that if the market has a good January, most of the time the year will end up with positive numbers as well.
Even though the jobs report missed expectations for 191,000 new jobs being created last month by coming in at 148,000 instead, the great big story was that this number had 146,000 private sector jobs versus only 2,000 public sector ones. Always remember that government doesn't create jobs – it only takes away from the private sector when it grows, and because it is the private sector that creates jobs, a growing government is the worst case scenario for a growing economy. So "hip, hip hooray" for this ratio of jobs because it is just what the doctor could order for a healthy and robust economy.
The biggest winners for job creation were in Healthcare with 31,000 new jobs (300,000 for 2017), Construction with 30,000 new jobs (210,000 for all of last year), and Manufacturing with 25,000 new jobs (196,000). We also saw gains in Food Services & Drinking Places (government-speak for restaurants and bars), and Professional & Business Services. Thus, these are not part time or low paying jobs for the most part, which is equally important for a growing economy.
Again, we have to keep everything in perspective. The following stats are from Pension Partners:
"From August 18th to November 29th, the Dow went 72 straight trading days without an intraday move greater than 1%, by far the longest stretch in history.
“The S&P has now risen for 14 consecutive months, the longest run in history.
“The Dow closed at an all-time high 71 times during the year, the most in history.
“There was a sharp flattening in the yield curve throughout 2017. At 0.51%, the spread between 10-year and 2-year yields on the last day of trading was the flattest level of the expansion. (This is a "flag" we are watching).
“In spite of this backdrop, the Fed only hiked rates 3 times in 2017, to a year-end range of 1.25 to 1.50%. After subtracting inflation (core CPI of 1.7%), this leaves the Real Effective Fed Funds Rate in negative territory for the 9th year in a row – another longest stretch in history.
“On the flip side:
Unemployment rate (4.1%) – lowest since 2000
Jobless Claims – lowest since 1973
Consumer Confidence – highest since 2004
ISM Manufacturing Index – highest since 2004"
Our take is that we should expect a correction along the way this year to keep this market from reaching the dreaded "bubble status", but we should also not be scared out of the market due to the length of this bull market. All good things eventually come to an end, but all records are also made to be broken. We have no idea when this earnings growth cycle will come to an end, but we simply do not see earnings growth stuttering or falling at this time - just the opposite, in fact, as corporations become ever so more competitive with the reduction of what had been among the world's highest and most onerous tax rates. (35% now cut to 21%). In this environment, we believe earnings will be the game changer – i.e., we are in the proverbial market of stocks, not a stock market. Companies with outstanding earnings growth will continue to provide outstanding returns.
------------------------------------------------------------------------------
PayPal Holdings (PYPL: $80.50) was upgraded by analysts at Cowen from a "market perform" rating to an "outperform" rating. They now have a $88 price target on the stock, up previously from $79. They must be reading The Bull Market Report. Interesting: Our price Target is $87, because that’s the price at which the company will be worth $100 billion. The stock set a new all-time high on Friday.
------------------------------------------------------------------------------
------------------------------------------------------------------------------
The High Yield Corner
By Michael Foster
Vice President, High Yield
Let’s start with a stock that fell below an important number and then quickly recovered.
Omega Healthcare Investors, Inc (OHI: $26, down 3%) has been The Bull Market Report’s big contrarian call for a while now. If you’re a regular reader, you know that we’ve frequently discussed the issues regarding Omega’s tenant insolvency and current negotiations. This has spooked a lot of investors and turned a once 8% yielding stock into a 9% yielding one. At the start of last week, the stock dipped below $27 for the first time since 2014 - a significant development.
There’s no news to drive this. No insider selling announcements, no updates on the ongoing negotiations with Orianna, which could result in a small decline in income or a protracted dispute in bankruptcy court. In either case, Omega is very likely to get paid out something. In both cases, though, Omega’s cash flow is going to suffer.
And what of that cash flow? Again, it’s helpful to look at the numbers. FFO for the last 12 months is $3.40, while annualized dividends are $2.60. In other words, the dividend coverage ratio is 131% - just above the important 130% level that we demarcate as the start of the safest REIT distributions. At its current level, Omega will maintain its payouts with ease.
But what about the haircuts? Orianna provides 5% of Omega’s FFO, so if Omega lost all of that money (a virtual impossibility), the FFO would fall to $3.23, leaving Omega with a 124% coverage ratio. That’s lower than we like, but it’s still over 100%, meaning we aren’t anywhere near a cut.
Let’s project into the future to see exactly when the dividend would get risky. If Omega lost 5% of its portfolio every year, 2019’s FFO would fall to $3.07. The next year’s would be $2.92…and in fact, it would take until 2023 (i.e., 5 years from now) before Omega’s FFO would fall to less than its current payouts. Then, it would hit $2.50.
Keep in mind that we’re playing with the worst possible case here - but let’s play with the math and see what happens to our income stream.
If the future was as bleak as this, 2023 would result in a 3.8% dividend cut to make payouts sustainable. At current prices, that would make Omega Healthcare yield 9.2% (instead of its current 9.6%).
If this is our worst case scenario, it looks pretty rosy. Getting a near 10% dividend over 5 years before a dividend cut that then brings your yield to a still impressive 9% - that’s not much downside.
There is one other consideration. Omega increases its dividend by a penny per quarter. We’ve have written in the past about this; it’s good for investors in the short term, but it will expedite the schedule for when Omega will have to cut its distributions. For that reason, we think it would be best for Omega to stop its quarterly hikes and telegraph to the market its plans to do so many, many months in advance.
We are disappointed that Omega hasn’t done that yet, but we also wouldn’t be surprised if they did this sometime this year. The recent price action demonstrates that the market is expecting the dividend hikes to stop relatively soon. That gives Omega a nice window to make the move without hitting the stock too much further - but we are not sure they will actually make this move at all.
And the reason is simple. We on the outside see a very slow demise of the dividend - management does not. In the last earnings call, CEO Taylor Pickett addressed the issue with some promising numbers:
"We are hopeful, we can develop an out-of-court plan, which if successful, would likely result in cash rents of $32 million to $38 million per year, as compared to the current annual contractual rent of $46 million.”
If successful, that would lower FFO by 1.5% - in other words, hardly anything at all.
Additionally, Omega continues to expand. The company invested over $300 million in the third quarter of 2016, which on its own more than covers the lost FFO from the Orianna issue. By how much? Pickett noted that Omega targets a 9% capitalization rate for investments, meaning that $300 million investment will be almost twice that of the lost cash rents from Orianna.
What about the properties currently occupied by Orianna? Omega is currently working to sell or rent to new operators who are in a better financial position. If successful, this could cause FFO to grow significantly in the next 2 years - and that will make Omega shares skyrocket.
We have faith that Omega’s managers can navigate this admittedly complicated and tricky transition, and that’s why we remain constructive on the stock.
Finally, let’s quickly turn to some other high yield assets: Municipal bonds and closed-end funds. Nuveen AMT-Free Municipal Credit (NVG: $15.65, down 2%) and Invesco Municipal Trust (VKQ: $12.65, down 1%) had a decent showing for the week, in no small part thanks to a seasonal and rather predictable trend. Retail investors sell municipal bonds at the end of the year and buy again in January. This is classic tax loss harvesting at work, and any year where losses in munis are to be found, this trend is noticeable. So far, 2018 has been good to munis - and that is likely to continue. Thanks to the investors looking for their tax-free income streams, both the Nuveen and Invesco funds are seeing positive inflows - something that we are also seeing across the municipal bond market.
Good Investing,
Todd Shaver, CEO and Founder
The Bull Market Report
Since 1998
December 6, 2017
by Todd Shaver | Dec 6, 2017 | 7am News Flash
Square (SQ: $38, up $1) had a good day yesterday, after a rough week last week. We wish we could say the same about Twilio (TWLO) which was down 2% to $25. These are two of our favorites (plus Nutanix, makes three) and Square has been a home run while Twilio has been a strike out. We still believe in Twilio but the market is telling us another story. We can’t quite believe it as revenues for the past few years have been stellar. We saw $90 million in 2014, $165 million in 2015 and $280 million in 2016. And they did $100 million in the 3rd quarter of 2017. We don’t get it. Revenues always win in the end, but Wall Street is making us suffer for the time being.
As to Nutanix (NTNX: $34), the stock is up $2 from where it was at the beginning of November. Yes, it had a run to $38 on Friday, but the stock was at $23 in the beginning of October for heaven’s sake. We’re not worried in the slightest.
Apple and Facebook are doing just fine, with both hovering around the $170 mark. Apple was at $151 in late September, just a little over two short months ago. Facebook was at $148 in July. Things are really quite OK out there.
But if you are afraid of the world at large and concerned about your investments (and not willing to climb a wall of worry with the rest of the market) then take some profits and put your money to work in Annaly Capital Management (NLY) paying over 10% or Government Properties Income Trust (GOV) paying over 9%. Or Pimco Dynamic Income Fund (PDI) paying 8.6%.
Relax – It’s almost Christmas!
November 26, 2017

by Todd Shaver | Nov 26, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
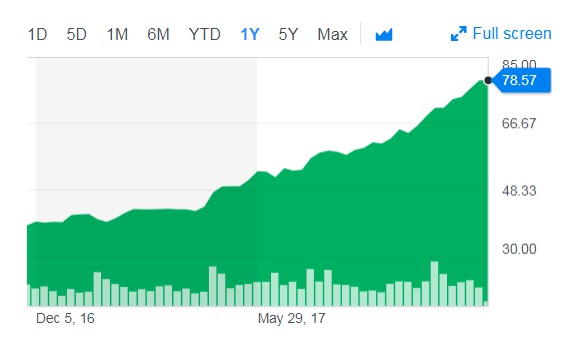
The big story this week was Jeff Bezos breaking the $100 billion level in net worth. Unreal! Bill Gates was the last person to attain the 12-figure fortune in 1999 but then the stock halved and didn’t reach its peak again until 2016. (Take a look at Microsoft’s 5-year chart just below this paragraph.) It’s a very relevant event as we head into the holiday season. Every retailer has been hard at work not to get “Amazoned” this holiday season. Expectations are moderate and the data out for Black Friday shows consumer demand is healthy. With this healthy spending, the economy should grow 2-3%, which means new Fed Chair Jerome Powell is about to take the world for a ride of at least seven rate hikes over the next 24 months. Hmmm. When it comes to interest rates we always get the good with the bad and the bad with the good.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks where you can still make good money, including: Facebook, Apple, Tesla, and PayPal.
This issue will be slightly shortened from our normal newsletter as the week was a short one with the Thanksgiving holiday and a very quiet market. We will be back to normal next week.

BMR Companies & Commentary
Facebook (FB: $183, up 2%)
Italy is bracing for an electoral season of fake news and demanding Facebook’s help. We think this is just the beginning of major future reliance of governments on Facebook.
With critical national elections only months away, anxiety is building that Italy will be the next target of a destabilizing campaign of fake news and propaganda, prompting the leader of the country’s governing party to call on Facebook and other social media companies to police their platforms. What can Facebook really do though? They are between a rock and a hard place. Where is the line between free speech and mal-behavior? Facebook could potentially get this really right or really wrong. There will definitely be a significant impact to the user base over the long haul from all this.
In a global atmosphere already thick with suspicion of Russian meddling in elections in the United States, France and Germany, as well as in the British referendum to leave the European Union and the Catalan independence movement in Spain, many analysts consider Italy to be the weak link in an increasingly vulnerable European Union. Hopefully Facebook could catch a few bad actors and look like heroes!
BMR Take: You know, we’ve thought this for years now but haven’t said it and we believe Facebook knows this to be true but they haven’t said it either, and that is that Facebook is like the phone company. People use Facebook like they use a phone. They use it for good and they use it for bad. Same with a phone. If a terrorist calls up a bank and says to look out, you can’t come down on the phone company for this offense. Same with Facebook. But you don’t hear the company complaining about this because they don’t want to be REGULATED like the phone companies are. So we won’t talk about it any more!
Facebook is closing in on earnings of $6 of EPS with revenue soon to exceed $50 billion. The numbers the company is posting are massive and we are still far from the end of the growth cycle for Facebook. Our $190 target is within reach.
------------------------------------------------------------------------
Apple (AAPL: $175, up 3%)
Apple typically sells tens of millions of iPhones each holiday season, regardless of whether the company offers holiday discounts. But with its HomePod smart speaker officially delayed until next year, a limited supply of the iPhone X and no virtual reality headset yet, Apple faces intense pressure this shopping season. This is not the normal expansive product line-up we see from Apple. They have some challenges this holiday season.
But the super-hot iPhone should get the job done. While they were a bit late in their deliveries, and Apple's iPhone X may be popular, it's behind competitors like Samsung in adding features like bigger and brighter screens. The good news is the Apple users are very loyal and unlikely to switch to Samsung for a screen.
BMR Take: Apple is about to do over $12 of EPS, over $275 billion of sales, and sell millions of iPhones. This stock is a core holding for any portfolio. We continue to closely watch the company generate new services revenue from the massive customer base of iPhone users. Our Target Price of $194 is coming into view and our Sell Price of “We would not sell Apple” tells you our conviction in this great company. Note that at $194 Apple will reach the $1 trillion market cap threshold.
------------------------------------------------------------------------
PayPal (PYPL: $79, up 3%)
The biggest thing happening this holiday season is mobile purchases. And mobile purchases don’t get paid for with cash. They get paid for with PayPal much of the time. According to PayPal, people will spend $630 billion during the holiday shopping season, of which 10-12% is done mobile.
The story is just getting started for PayPal.
In China, 60-70% of sales are done online and mobile. PayPal is making strategic deals and partnerships to build out a global platform that touches every corner of the world including China.
We expect explosive growth in mobile shopping this holiday seasons. We anticipate PayPal and all its various entities to experience robust business in the fourth quarter.
BMR Take: EPS is closing in on $2.50. With a few hundred million users, versus Facebook’s 2.1 billion, this is just the early innings. Our Sell Price is “We would not sell PayPal” and as noted last week, we have just blown past our prior target of $77 and have raised the bar to $87.
------------------------------------------------------------------------
Bitcoin Continues Its Huge Run
The chart just below here was produced on the 21st, just six days ago and is already obsolete. Bitcoin was up over $800 just this weekend and is now over $9000. The market cap of bitcoin is $155 billion, up from $100 billion earlier this month. The market cap of all cryptocurrencies is now $290 billion, up about $100 billion in just two weeks. This is not a fly-by-night scenario. It is real and the market is exploding.
If you want a good site to explore, go here:
https://CoinMarketCap.com

------------------------------------------------------------------------
The Significance of the New Tesla Roadster and Tesla's Main Intention in Unveiling It
We got this letter from a subscriber who just loves Tesla (TSLA: $315, flat).
Hi, Todd. A member of the Tesla Motors Club wrote us his thoughts on the new Tesla Roadster, which I'm pasting in below.
Wishing you a happy Thanksgiving,
Janice
From: jmgnyc@aol.com [mailto:jmgnycx@gxxx.com]
Sent: Wednesday, November 22, 2017 9:36 AM
To: info@bullmarket.com
Subject: A Roadster Thought
“Last night I was able to attend the Tesla Semi-truck event at Tesla’s Design Studio in California. As usual, gobs of Tesla enthusiasts cheered and were blown away by what Elon Musk and his team shared about the Tesla Semi and the unexpected new Tesla Roadster - which came as a surprise to many. I can say that the car looks even better in person than in photos or video. It’s truly a gorgeous and stunning car, and also the specs are insane. Not only can it do 0-60 mph in 1.9 seconds (which is hard to fathom) but it also has a 200kWh battery that can go over 600 miles. This is stuff that most didn’t think was even possible.
“I don’t expect Tesla to sell tens of thousands of these annually and I don’t think Tesla thinks they will also. I think their main intention is to show a proof of concept that the ICE (internal combustion engine) car is truly dead. In no way can an ICE car be better than the new Roadster. Basically, last night Elon and Tesla gave the ICE their farewell. Sure it will take many years before ICEs stop getting produced, but last night was the final reason why - because ICEs stink compared to what electric can do for cars. And that’s the significance of the new Roadster.”
BMR Take: We must say that this new Roadster could be a good source of funds for Tesla since it costs $250,000. If a couple of thousand enthusiasts order it, there's half a billion dollars coming into the company. The big test for Tesla in 2018 will be cash. They are burning through it like there is no tomorrow. But with a market cap of $53 billion, selling new shares of just 3% dilution will raise over $1.5 billion in fresh capital. We would expect investors to jump to be first in line to send the company money. With that said, if the money markets are tight next year, there may be issues for the firm.
Again, this one is not for the weak-hearted. Want to sleep at night? Buy Microsoft. Want to have some fun with funds you might lose? Jump on board with the Elon Musk and hang on for the ride.
------------------------------------------------------------------------
The High Yield Corner
By Michael Foster
Let’s deal with an interesting development hitting Omega Healthcare Investors (OHI: $27). Two different legal firms have filed suits against Omega Healthcare. The first lawsuit, filed by Brower Piven, accuses Omega’s management of "violations of the Securities Exchange Act of 1934 by virtue of the defendants’ failure to disclose that financial and operating results of certain of the Company’s operators were deteriorating, certain of the Company’s operators were experiencing worsening liquidity issues that were significantly impacting the operators’ ability to make timely rent payments, and certain of the Company’s direct financing leases were impaired and certain receivables uncollectible.”
The second, by Rosen Law Firm, is very similar (although more succinctly worded). This was announced Monday and accuses Omega’s management of failing to disclose that “financial and operating results of certain of Omega’s operators were deteriorating” and that these operators "were experiencing worsening liquidity issues that were significantly impacting the operators’ ability to make timely rent payments.” Finally, the lawsuit claims that "certain of Omega’s direct financing leases were impaired and certain receivables were uncollectible”.
What are these firms accusing Omega of? In short, Omega’s big tenant Orianna Health System is struggling to pay its rent because of disappointing occupancy rates and high costs. We’ve spoken at length here about the difficulties of the skilled nursing facility sector (SNF), and how growing revenues by increasing rents is extremely difficult because of the limited incomes of tenants. Furthermore, Medicare reforms could threaten Omega and other SNF-focused Healthcare REITs to grow their incomes in the future, which limits expansion plans and makes growing the base operations risky. On top of that, the lower than expected demand and higher than expected competition in the SNF sector make it difficult for a company like Omega to expand. It’s a triple-whammy.
That sounds really, really bad. And, as we have said here repeatedly, it does mean that Omega Healthcare is not a “buy and hold forever” stock. There will come a time when Omega’s expansions will reach their limits, where the cash flow cannot keep up with the dividend growth, and the stock will have to fall to reflect the structural challenges Omega has.
But here’s the other thing to consider: We all know this to be the case.
In fact, we also knew about the problems with Orianna; Omega has publicly discussed issues with this tenant in the past, and the SNF industry has been well aware of cash flow issues. The company has faced legal challenges in Idaho and scrutiny elsewhere in the country. Investors who didn’t do their due diligence may have been surprised by Omega Healthcare’s recent revelations -but those who did knew that this was a problem.
However, we also knew this was a problem that was priced into the stock. That’s why Omega yielded 8% upon Bull Market Report’s recommendation and competitors in the SNF REIT space were yielding less than 6%. It’s also why we demanded a higher dividend coverage ratio upon recommendation. Keep in mind that the REIT’s FFO-to-dividend ratio is now 130%, meaning it is still well out-earning its dividend. There is no cash flow issue to worry about here.
There also is not a debt issue. Total liabilities are $5.3 billion on $8.9 billion in assets, a 59% debt-to-asset ratio. This is low by REIT standards. The company’s annualized income was $900 million in 2016 and total operating expenses were $390 million for the same period. That’s a massive operating margin thanks in large part due to the lease conditions that Omega hammers out with tenants - conditions that are extremely favorable to shareholders.
So let’s go back to the lawsuits. It’s true that operating income took a dive because of the write-downs related to Orianna, and the future is uncertain because we don’t know what kind of deal is going to be hammered between the two firms. As we’ve discussed in previous weeks, it could be very ugly or it could be amenable, and we’re expecting the latter as the likelier result. But the real issue is this: the market has priced in the worst possible outcome. You just don’t get 8% dividends that grow a penny per quarter with a 130% or higher dividend coverage ratio every day. Omega Healthcare is one of a handful of such companies. Of course with such metrics there is risk, and that risk has been priced into the stock since The Bull Market Report first recommended it in March of last year. Now, obviously, it’s underpriced, and we expect that the stock will be re-priced early in 2018 when a settlement or agreement is reached between Omega and Orianna.
Omega’s portfolio is composed of 85% senior nursing facilities and 15% senior housing facilities. Omega operates approximately 1,000 properties, which in turn are run by 77 independent operators.
So where does that leave shareholders now? Holding and collecting these well-covered dividends makes sense. Growing more exposure to the stock also makes sense. What doesn’t make sense is freaking out because of these lawsuits, which are quite vaguely worded in and of themselves.
To give a bit of context, note that shareholder lawsuits are a pretty common thing on Wall Street. They sometimes have merit, and sometimes are levied by legal firms who smell an opportunity. Facebook was sued in 2012 after its IPO because of how disastrous its early performance was. look at what Facebook stock has done since then.
In short, it’s unlikely that these lawsuits will come to much. What’s much likelier is that Omega’s mounting pressure to reach a settlement with Orianna is going to result in a faster settlement, which will in turn result in investor relief and a boost to the stock. We don’t expect a massive price spike, but we do expect the stock to come back to an 8-handle on its dividend yield when an announcement is made. After all, the financial picture hasn’t changed and, with the massive price decline of late, there’s little downside priced in and a lot of upside available for investors who understand the risks.
Good Investing,
Todd Shaver, CEO and Founder
The Bull Market Report
Since 1998
