April 16, 2017
by Todd Shaver | Apr 16, 2017 | Weekly Newsletter 7pm Sunday
The Week Ahead
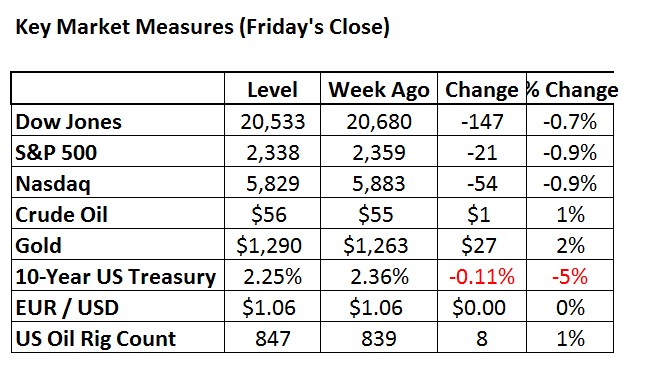
What did the Easter Bunny bring this April to the markets? Much lower interest rates! The 10-year dropped 11 bp to 2.25%. Who says interest rates are going up this year? Not us, for sure. Geopolitical worries are the primary culprit. North Korea, Syria, the Middle East, all the regular actors are to blame. The 10-year Treasury now rests around 5 month lows. Everyone will look to the Fed for guidance about where the markets are going. Interestingly, Trump is now praising Yellen in a public call for Fed consistency, which contradicts his accusations on the campaign trail that she was artificially manipulating the economy in a detrimental way. Hmmm…does Trump see an opportunity to take advantage of low borrowing costs for his $1 trillion infrastructure plan? His Treasury Secretary Steven Mnuchin has publicly expressed interest in doing big time deals for 100 year bonds. And we applaud this. We’ll have to wait and see.
There is always a bull market right here at The Bull Market Report! This week we highlight the following securities: Shopify, VMware, Amazon, Annaly, Apple, and Tesla.
Highlights From The Past Week
Watchful Eye On North Korea. US officials are saying the Trump administration is focusing its North Korea strategy on tougher economic sanctions, possibly including and oil embargo, banning its airline, intercepting cargo ships, and punishing Chinese banks doing business with Pyongyang. According to one official, US President Donald Trump has approved a preliminary broad approach on North Korea and asked his national security team to craft a more detailed framework for new international sanctions and other actions. The official said the administration is considering an array of stiffer sanctions that could be applied on a "sliding scale," proportionate to North Korean actions. Some steps could be applied unilaterally, with others through the United Nations.
Business Returning to the Center Stage in the USA. Business leaders are gaining more and more influence in Trump's White House. Most recently, Jared Kushner, the president's son-in-law, is trying to orchestrate more power for National Economic Council Director Gary Cohn while dampening the influence of chief strategist Steve Bannon. It is quiet the change in scenery to see Washington acting as a friend to business led by accomplished business people. All good news for the markets.
Infrastructure Bill On The Horizon. One of Trump's top policy advisers said the timing of the President's $1 trillion infrastructure package is still up in the air as the administration considers its best path forward. D.J. Gribbin, special assistant to the president for infrastructure policy, said the timeline will hinge on whether it moves as a standalone measure or if it is attached to another legislative priority. It adds that they are still crafting the infrastructure measure. Transportation Secretary Chao said the package could be unveiled as soon as next month. We can’t wait.
BMR Companies and Commentary
Shopify (SHOP: $71, +4%, all price changes in this report are for the week)
Shopify had a solid week as talks of a takeover swirled. If true, we could see some very nice upside in the near-term. If not, that’s fine with us, as we still like the company’s fundamentals and prospects. Bottom line, Shopify still has room to run whether there is a takeover. Let’s re-visit why.
One can hardly kick back on the couch and watch CNBC or browse through your favorite financial publication these days for more than a few minutes before you come across a discussion of Amazon, as the online Retail juggernaut has skyrocketed to become an American business behemoth. And rightfully so.
For investors who want to capitalize on the undeniable secular growth trend of eCommerce, but who either missed the boat on Amazon or are wary of its nosebleed valuation, is there another road less traveled that they could embark on to get exposure to the eCommerce tidal wave? One that has impressive momentum and an ascendant stock price, but just not as frothy of a gain as Amazon? Yes there is. That’s Shopify.
Shopify not long ago announced its full-year financial results for 2016, and boasted 90% revenue growth and 99% growth in gross merchandise volume, (a term used in online retailing to indicate a total sales dollar value for merchandise sold through a particular marketplace over a certain time frame.) As an added bonus, Shopify's “Sell on Amazon” integration was made generally available to merchants in December. This mean Shopify now seamlessly connects store owners to the millions of customers searching for products to buy on Amazon, and merchants can now conveniently manage their product catalog for their eCommerce website, retail store, Amazon store, and other sales channels all in one place. This is big time! Since this integration just took place in December, we are only at the tip of the iceberg in terms of benefits and synergies from the move for Shopify.
BMR Take: The consensus calls for Shopify to more than double revenue from $600 million this year to $1.4 billion by 2020. This kind of explosive growth could cause the stock to double over the same period.
VMware (VMW: $91, -1.6%)
VMware made some waves this week announcing intentions to acquire Wavefront, the leading metrics monitoring service for cloud and modern application environments. Terms were not disclosed. The transaction is expected to close in calendar Q217. VMware does not expect this transaction to have a material impact on its 2017 operating results. But don’t write off the deal as not important just because the financial impact isn’t going to be seen in the near-term.
Digital enterprises face challenges of a new order of magnitude when monitoring modern applications -- consisting of hundreds of microservices in containers with lifespans of seconds -- spread across private and public clouds. To identify and fix operational issues in these dynamic cross-cloud environments, developers need new instrumentation for their applications, and teams require sophisticated real-time analytics on their high-scale distributed systems to adapt to problems before they impact the business.
Wavefront provides metrics to optimize clouds and modern applications by delivering operational insights using millions of data points per second in real-time. Operators and developers can interrogate real-time data streams to discover new ways to address problems, identify bottlenecks, and test algorithms and hypotheses. A cloud-hosted service, Wavefront ingests, stores, visualizes, and alerts on streaming data from clouds and modern applications enabling superior operational performance. The service can measure, correlate, and analyze data across servers, devices, applications, end-user behavior, multiple public cloud and data center attributes, and business metrics. (Now that’s a mouthful.)
This is big news for the underlying story at VMware, which is most exciting given the company’s increasing presence in the cloud marketplace. For seven-plus years, VMware has invested in solutions featuring advanced metrics and analytics to help customers simplify and automate how they manage, monitor and troubleshoot services in dynamic virtual and cloud environments. As all these investment start paying off, we see VMware as a top pick for Technology investors.
BMR Take: The company is currently generating $5-6 of EPS annually. The current valuation seems like a bargain considering all the progress with the cloud business. Our Price Target is $95 which would be a 2-year high and a more than double from the $44 low it hit in February last year. If the stock hits $95, we are moving our Price Target up into triple-digits, especially if revenues continue to soar. You know what we say about revenues and earnings: Revenues first, then earnings.
Amazon (AMZN: $884, down 1%)
A new week; Another big move brewing for Amazon. It is said that the eCommerce giant considered internally whether Whole Foods would help invigorate its nearly decade-long push into groceries. That is, Amazon kicked around the idea of buying the grocery chain!
Whole Foods has long been seen as a buyout target. Activist investor Jana Partners set off a new wave of speculation this week when it acquired a stake and urged the company to evaluate a sale. With a market valuation of $11 billion, the ailing organic-food retailer would be a powerful acquisition for Amazon -- dwarfing its 2009 purchase of online shoe retailer Zappos for about $1.2 billion. But the deal would turn Amazon into a grocery giant overnight and help it sideline Instacart, a startup that delivers grocery orders from Whole Foods stores in more than 20 states.
Jana has called for Whole Foods to overhaul its operations and brought in retail and food experts to help foster a turnaround. It also urged the company to consider a sale. A list of potential bidders includes Amazon, as well as traditional grocery chains such as Kroger and Albertsons. Whole Foods remains an attractive asset, even after a sales slump and the loss of market share to mainstream supermarkets, because the brand is strong and could be leveraged into something big.
BMR Take: Amazon and CEO Jeff Bezos are winning at everything. Why not grocery? Current Street earnings estimates call for $27 per share by 2020. With so much growth and strong earnings potential, the shares are compelling here.
Annaly Capital Management (NLY: $11.63, +5%)
Looking for yield in this market? Look here! Annaly Capital Management is a top pick in the Mortgage REIT sector.
Let’s review some of the reasons to like Annaly. Home price gains were up 6% in latest report from Case-Shiller, showing acceleration in home price increases. Tight supplies and rising prices may be deterring some people from trading up to a larger house, further aggravating supplies because fewer people are selling their homes. This is a good trend for Annaly. Annaly owns mortgages so rising home prices means the credit risk of owning the bonds is safer.
Annaly has a broad exposure across the US unlike other competitors more narrowly focused on only a particular market like New York. Yet another reason to like Annaly.
BMR Take: With a yield of 10.6% and a track record of over 20 years doing this, we continue to pound the table on Annaly. Look at this stock – up from $10.12 in mid-January in the midst of a strong interest rate rise with EVERY pundit saying that Annaly will be impacted sharply with the higher rates. Boy oh boy where they ever wrong. And boy oh boy were we ever right. Of course we’ve been saying this since we founded The Bull Market Report in 1998!
Apple (AAPL: $141, -2%)
Apple to buy Disney? Now that’s exciting! It could be more realistic than you think. Apple has the cash to pull off a $200 billion-plus takeover of Disney — creating a company worth $1 trillion with “almost limitless opportunities in content and technology.
A combined Apple-Disney would create an instant competitor to Netflix that would take advantage of the Mouse House’s content and Apple’s user base. Other benefits include: integrating Apple consumer tech as experiences in Disney’s theme parks; and landing global streaming sports rights for ESPN via Disney and Apple distribution and a strong balance sheet. Content is a major focus for Apple, target size is not an issue, and Disney offers an avenue to diversify away from hardware without diluting the strong Apple brand.
The M&A rumor mill got new grist last fall, when Apple chief Tim Cook told analysts that he was “open to acquisitions of any size.” In addition, Apple execs met with Time Warner honchos in 2015 in a discussion that raised the possibility of a merger - before AT&T moved on its $85 billion bid for Time Warner,
Per one analyst’s estimates, the merger of Apple and Disney would be highly accretive to earnings, to the tune of a 15%-20% increase in earnings per share based on the presumed 40% premium deal price and Disney’s low debt load. Nice!
BMR Take: We say it every week and we’ll say it again. Apple is really cheap compared to the current EPS outlook for this year of nearly $9. And all that cash put to good use through buying a storied franchise like Disney could be an exciting catalyst/prospect for the company.
Tesla (TSLA: $306, flat)
Tesla is a new entrant into the automobile, solar and battery storage businesses. Since Tesla’s current revenue is roughly 99% automobile related and, due to the Model 3 introduction and projected sales, this ratio will likely remain similar for quite some time. Thus, Tesla is an auto manufacturer, plain and simple. Panasonic supplies Tesla with batteries. Other companies provide Tesla with electric motors, tires, wheels, etc. Thus, with a few extraneous business lines, Tesla designs and assembles cars. Until Tesla’s battery storage business and solar equipment business become majority contributors, it will remain viewed as an auto company.
The good news is that’s okay!
Tesla CEO Elon Musk says his company will unveil its electric tractor-trailer truck this September, calling the vehicle “seriously next level” and praising the Tesla team for doing “an amazing job.” He also revealed that Tesla will show off an electric pickup truck in 18 to 24 months. Awesome innovation.
BMR Take: Street estimates call for sales growth from $7 billion last year to $11 billion this year to $33 billion in 2020. This is an exciting time for the business and the stock.
Note that Tesla was upgraded by Piper Jaffray from a "neutral" rating to an "overweight" rating last week. They now have a $368 price target on the stock, up previously from $223. We have a $325 Price Target on the stock.
Netflix (NFLX:$143, flat) had its price objective hoisted by Cowen from $165 to $170 in a research note released on Tuesday. Our Price Target is $165.
Upcoming Economic News
FRIDAY, APRIL 14 (Yes, this was on Friday – Good Friday)
Consumer Price Index
For March
Forecast: -0.1%
Actual: -0.1%
The Consumer Price Index was forecast to fall 0.1% in March following a 0.1% gain in February and 0.6% increase in January. It did. This was the first decline in the CPI since February 2016. Energy prices were a net drag on the CPI in March. The CPI for food and beverages rose 0.2% in February, the strongest since September 2013.
Retail Sales (This too was announced on Friday the 14th.)
For March
Forecast: -0.3%
Actual: -0.2%
Consensus expected retail sales to have dropped 0.3% in March following a 0.1% gain in February and 0.6% increase in January. Results were slightly better than expected. We believe weather was likely a small negative for sales. Non-store sales (online) have been contributing more to growth in retail sales recently. Already released data showed that unit vehicle sales dropped 5.5% in March and shaved 0.4% off total retail sales growth.
Tuesday, April 18th
Housing Starts
Period: March
8:30 AM
Consensus: 1,245,000
Prior: 1,288,000
Housing starts should continue to signal a healthy economy. The data reveals the number of housing units started in the United States. The U.S. Census Bureau's New Residential Construction release provides statistics on the construction of new privately-owned residential structures in the United States.
Thursday, April 20th
Leading Indicators
Period: March
10:00 AM
Consensus: 0.3%
Prior: 0.6%
This one is interesting to watch. Everybody is so focused on trying to figure out what direction the markets are heading. This is one of the key metrics that tells us. Leading indicators are economic series that tend to change direction ahead of shifts in the business cycle. There are 10 components of the U.S. Leading Composite Indicator published by The Conference Board. The index is constructed by averaging the individual components in order to smooth out a good part of the volatility of the individual series. Historically, the cyclical turning points in the leading index have occurred before those in actual economic activity.
Notes at the Margin
By Phil K. Verleger, Jr.
Former Director of the Office of Energy Policy
at the United States Department of Treasury
This item published by Platts Global Alert first caught my eye: “The Permian Basin [in Texas] is going to become the largest oil field in the world, surpassing the legendary Ghawar field of Saudi Arabia,” Bill Marko, managing director of Jefferies, said on the sidelines of the conference.
The basin holds an estimated 210 billion barrels of oil that will become economically recoverable in the future, or 325 billion barrels of oil equivalent when oil and natural gas liquids are counted, he said.
The 210 billion barrel estimate caught my attention. After all, Saudi Arabia’s reserves are put at “only” 260 billion barrels per the BP Statistical Review of World Energy. It is hard to believe that one US field has oil reserves equal to 80% of Saudi reserves.
The US Energy Information Administration recently published a short-term outlook predicting an 8% increase in US production from 8.8 million barrels per day in December 2016 to 9.5 million barrels per day in December 2017. Given recent trends, the estimate will likely need to be revised again, perhaps to 10 million barrels per day or more.
BMR Take: Phil – Knowing you the way I do, this is your way of jumping up and down and waving your arms like a madman. This is certainly big news. We have seen it coming to a certain extent but when you put it in writing the way you do, this is making us stand up and take notice. There are big changes afoot in the energy world. We would venture to say that $100 oil is not going to be seen for a long, long time to come. Prepare accordingly.
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
They honored Arnold Palmer this past weekend at the Masters Golf Tournament. He was one of the few greats who turned the game into a hugely popular spectator's sport. One of his best known quotes is: "Golf is deceptively simple and endlessly complicated."
As words of wisdom go, we can't think of a quote that could be any more applicable to the stock market. As simple as "buy low, sell high," to as complicated as the blackboard full of equations in Einstein's office. Our formula for investment success has always been "Success = preparation, recognition of value and proper seizing of opportunity." Preparation is fairly simple in the sense that it's mostly reading. But it takes a lot of reading and research on an endless basis. The complicated part is filtering out all the "noise" and learning what resources you can rely on and trust. Overall, we are believers in the KISS principle when applying our formula because we have learned over the years that the more complicated the investment process becomes, the harder it is to stay on track.
If you want to keep it as simple as possible, just think of one word - earnings. Good earnings signal a rising stock market. Weak earnings are normally a forecast of a weak or falling market.
That's where we are today. First quarter earnings season kicked off last week with several big banks reporting. First quarter earnings growth is expected to be 10%, the best since 2014. Sales growth, a laggard in the financial recovery, is expected to grow by 7.5% - its best pace since 2011! (Source: Thomson Reuters)
In addition to corporate earnings, investors will also likely monitor the economic calendar to be sure there is no unexpected deterioration in important statistical areas. And if you want to complicate it just a bit, throw in the fact that investors will probably just continue to wait for word from Washington on their pro-growth agenda. When that will actually be announced, and how long it takes to pass, are currently unknown and unknowable. So, while we may be stuck in a trading range pending the agenda results, earnings should provide a simple-to-understand reason to expect that the market will eventually work its way to a higher level.
Facebook Adds a Million Advertisers in 7 Months
There is a big move going on in the digital marketing world that many are not aware of. More than 5 million businesses are advertising on Facebook each month, Reuters reports. That is up from 4 million monthly advertisers in September 2016, and the 3 million monthly advertisers it had in March 2016. Significant upside remains as Facebook’s 5 million advertisers are less than 10% of the 65 million businesses that are active on the network.
Facebook is one of two undisputed leaders in digital advertising. Alongside Google, the company is expected to generate about half of online ad spend in 2018. Facebook generated close to $27 billion, and Google close to $80 billion, in ad revenue last year.
Small and midsize brands are flocking to advertise on Facebook. Big brands may drive the bulk of revenue in advertising markets, but there is still ample opportunity for growth with the smaller brand advertisers. The sheer volume of advertisers on Facebook reflects the company’s success in attracting these smaller firms its platform.
A few industries are generating the bulk of Facebook ad spend. E-commerce and Retail, and Entertainment and Media are the biggest industries represented in Facebook's advertiser base.
Facebook is doing a great job at building its advertising base overseas - over 75% of advertisers are outside of the US. India, Thailand, Brazil, Mexico and Argentina are the fastest-growing markets.
Mobile is big, as you know. Almost 50% of advertisers create ads on mobile devices. More than 90% of Facebook users access the network via mobile. And mobile advertising accounts for 85% of ad revenue. Creating mobile-first experiences is particularly key in emerging markets.
The biggest users of Facebook are the US at 220 million; India at 210 million; Brazil at 120 million; Indonesia at 75 million and Mexico at 65 million.
Our Take on SNAP
Snap (SNAP: $20) went public at $17 in early March and promptly opened at $24. They raised $3.4 billion making it the largest IPO since Alibaba went public in 2014, raising $20 billion. The market cap is now $23 billion and all of this for a company with no revenue in 2015, $400 million in 2016 and losses of $500 million in 2016. Ouch. More losses than revenues. Not a good business model.
Snapchat has grabbed the attention of a generation of younger smartphone users, who post and share photos and videos on the app that can disappear after a set amount of time. The app - developed by Stanford University students, two of whom are still executives at Snap had 160 million daily active users as of December 2016,
BMR Take: We are steering clear of this one. One might compare this a bit to Facebook, but Facebook had huge revenues and real earnings when it went public, and the growth since then has been phenomenal as you know. The Snap IPO has invigorated the IPO market and Wall Street is generally pleased, but for this company to get to $40 or $50 a share, we will have to see revenues of 10-20 times current levels, and big profitability, both of which may never materialize. We are steering clear.
The High Yield Report
By Michael Foster
Special to The Bull Market Report
It was a short week, but an eventful one. Already we’re seeing tons of articles about how the stock market is in crisis. Looking at volatility, there seems to be reason to think this; we went from a VIX of about 10 to nearly 16 in days. This means there is more caution in the market, and expectations of a short-term downturn. However, those expectations will disappear as they always do and the bull market will return as it always does.
We can already see pockets of optimism in the high yield world. In fact, We’d go so far as to say we’re beginning to see a sector rotation among investors that is benefitting parts of the high yield universe.
Before we get into that, though, let’s look at who is not winning. The UBS BDC ETF (BDCS: $23, down 1%) saw a soft week that was no worse than the broader market, but definitely was not good. This move is actually not that bad, considering that BDCs have had a massive run-up for months and has driven the entire sector higher. One well-known BDC analyst recently pointed out that the sector has beaten the S&P 500 since the start of 2014. This kind of cherry-picking time series doesn’t tell us much, but it does remind us that BDCs had an extremely vicious decline in 2013 and have been recovering for years since then as the market readjusts its understanding of what a rising rate environment means for these assets. It also means that the bargains in this odd corner of the business lending universe have dried up. That’s a shame, because The Bull Market Report is eagerly awaiting adding a BDC to the high yield portfolio, but this week’s 1% decline isn’t enough for us to do it. In fact, the recent decline may indicate that weaker prices might be just on the horizon, indicating a need to buy some BDCs when the price is right. Stay tuned as we keep focusing on this story.
So if BDCs aren’t benefiting from the fall in stocks this week, who is?
The answer is obvious: REITs. The SPDR Dow Jones REIT ETF (RWR: $94) was mostly flat for the last four days but is up 1% from last Friday - and comparing REITs to a week ago is really key here, because the momentum in REITs really started to kick off on Monday and has stayed strong with the many REITs in the Bull Market Report portfolio.
Let’s start with Kimco Realty (KIM: $22, up 4%), which shot up at the start of the week and has maintained its higher price level. Kimco is expected to report earnings by the end of this month, and analysts’ expectations are strong. Despite expectations of a 1% revenue decline, FFO expectations put Kimco’s dividend coverage in the 140% range. This means that Kimco is expected to far cover its dividend and have room to increase payouts. That should mean the company should be a low yielder, but this company’s 5% dividend yield indicates market expectations of risk are growing. Why the disconnect?
Simple: the decline in Retail.
Long story short, shopping malls are collapsing. The high-profile news of bankruptcies at Sears and JCPenny are making investors grow increasingly confident that the Retail sector is an apocalypse that no investor should come near. Of course these people are forgetting just how strong things are for Whole Foods, upscale outlet malls, Apple stores, and several other corners of the retail market that Kimco just happens to be focused on. In fact, Kimco’s tenants tend to be the most well-heeled and revenue-safe firms in the Retail landscape, so this collapse has little impact on them. Their occupancy rates have remained near 99% throughout. And although these issues are now high profile, they’ve been top of mind for Kimco management for a decade - and management has addressed these issues both in their strategic decisions and in their earnings calls.
In short, Kimco is not affected by the slowdown of the suburban American shopping mall.
Investors don’t know this, of course, so they’re throwing out the baby with the bathwater. That means now is a buying opportunity unlike no other. In fact, Kimco looks like one of the most attractive options for high yield investors. Of all our picks, Kimco looks like one of the most undervalued.
A similar story hit Government Properties Trust (GOV: $22, up 3%) over the past week, making it one of the top performers in a well-performing sector. Government Properties is heavily exposed to federal government tenants, and lower government spending has been seen as a real risk for the company. As a result of this fear, the company has looked to diversify by investing in office space that would be more insulated from the expected weaker demand in government properties. That has created a swiftly diversified portfolio that also has firm dividend coverage, but the market never really saw it that way. Instead, Government Properties is always seen as a risky option, which is why it often traded at an 11% yield. That’s what the stock was yielding when we first recommended it, and now it’s trading at less than an 8% yield, thanks entirely to capital gains. Sadly, that means buying more of Government Properties isn’t the greatest idea right now, but it does remain a solid hold thanks to its capital gains. The last week’s recent 3% jump is likely just the beginning; this company has a much safer income stream than its yield would indicate, meaning price gains are likely to come. We recommend staying in the stock to enjoy those gains as demand for REITs continues to rise.
Our other REITs did well this week too. Digital Realty Trust (DLR: $110, up 1%), Omega Healthcare Investors (OHI: $34, up 1%), and Care Capital Properties (CCP: $27, up 1%) all saw modest gains largely as a result of the continuation of a recent trend. CCP and OHI have been recovering recently from an oversold situation in healthcare REITs - in short, the market sold way too many of these because they thought a variety of risks (interest rates, cuts to Medicaid and Obamacare, etc.) would damage these firms permanently. These were considered long-tail risks not priced into the stocks, and yet these companies are doing fine and the risks the market has perceived are not materializing. In fact, they may never be real concerns for the companies. As a result, the stocks have no place to go but up. While we’re sitting on double-digit gains for Care Capital, we see more room to grow and thus recommend holding tight on these firms.
Finally, a word on municipal bonds. The iShares S&P National AMT-Free Municipal Bond Fund (MUB: $110, flat) didn’t move much this week although our muni bond picks did. Invesco Municipal Trust (VKQ: $13, up 1%) and the Nuveen AMT-Free Fund (NVG: $15, up 1%) outpaced the market, and we expect further gains in the municipal bond market to drive both of these funds higher. What’s going on is quite simply secular demand for munis returning to the market, largely a result of the higher uncertainty and fear that is driving stocks lower. In short, many retail investors are getting skittish and feel a need to pull out of risk and get lower risk assets.
This is driving a broad base of investors to demand more municipal bonds, driving up their value and in turn driving up the net asset values of these and other municipal bond funds. Since munis are far undervalued again due to risks that were feared but are not materializing, there is a lot more room for these funds to rise in price before they’re fairly valued. Thus muni fund holders should enjoy the gains they’re getting now but shouldn’t sell yet; if the market stays afraid these funds are destined to rise considerably. If the market gets more courageous, these funds are still destined to rise (although perhaps at a slower pace) because they have been massively undervalued due to ridiculous fears about muni bonds that aren’t materializing. Either way, the direction is clear: Keep and hold these funds and wait for their pricing to better match their real value.
Good Investing,
Todd Shaver
Editor, Founder and CEO
The Bull Market Report
Since 1998
February 26, 2017
by Todd Shaver | Feb 26, 2017 | Weekly Newsletter 7pm Sunday
The Week Ahead
“US Talks With Mexico Clouded By Mixed Message” was the front page Wall Street Journal headline going into the weekend. For months now all the focus has been on the new administration. Does anything else matter? Washington DC policy is seemingly the only driver of financial markets right now. Accordingly, we will likely need to start seeing some tangible results on healthcare, tax, and trade reform sooner than later. We eagerly await to see where reality meets the promises made on the campaign trail.
No matter what, there is always a bull market here. Week in and week out, we you can find it right here at The Bull Market Report. This week we highlight evidence of a bull market in the following securities: Amazon, Apple, Home Depot, Netflix, Bristol-Myers Squibb, and Tesla.
Highlights From The Past Week
Top Investor Says He Is Disinvesting. Jeffrey Ubben, the CEO of activist investor ValueAct Capital, told the press that his firm had been taking money out of the capital markets as valuations have become overextended, leaving it with $3 billion in cash. "I really feel that the large-cap activist plays are very treacherous with high PEs and not a lot of growth," Ubben said, speaking at the Reuters "Future of Shareholder Activism" event in New York.
Well, it takes all kinds. That’s what makes a market. We certainly aren’t jumping on his bandwagon. We’re watching, but this market may have a LONG way to go on the upside. Over-extended markets can get more over-extended and who’s to say the market is over-extended? We don’t think so. Either way, we at The Bull Market Report are not trying to predict the macro direction of the world. Our philosophy is that it is unknowable. What we can do is recognize good companies that will do well no matter what the world throws its way.
Are Trump’s Aggressive Plans Achievable? Concerns about Trump's tax cut plan - arguably the biggest catalyst behind the market's daily record highs - are mounting. Rising opposition to a simple "repeal and replace" of Obamacare could spill-over into other domestic policy targets, most notably tax reform. The current debate suggests that tax legislation might not be finalized until late 2017 or early 2018. Along with the potential for a phased-in tax cut, this would likely spread the growth effects between 2018 and 2019. That’s a long way away and lots can happen in the meantime.
We at The Bull Market Report feel that a tax cut is a bad idea. The budget is operating at a deficit now, so a tax cut will make it worse. David Stockman, former Budget Director under Reagan and the perennial bear feels this would be a disaster financially for the United States. We generally don’t agree with Stockman much because he is SO negative but we sure do in this case.
Look – we are flirting with a debt of $20 trillion. Cut taxes and we could be looking at $22 trillion to $25 trillion in debt. It just scares us to write this. And it seems like no one is talking about the debt any more. Listen, if you own a company and it brings in $5 million in revenue but you have $5.5 million in expenses you have to borrow that $500,000 to move to the next year. If it happens the following year, you now owe $1 million. If you do it EVERY YEAR you eventually have to cut people, cut expenses, and ultimately if you don’t act fast enough, you go bankrupt. Just add 10 or 20 zeros to this example to get the results for the United States. (Just kidding about the 20 zeros, but we hope you get our point.)
BMR Companies and Commentary
Amazon (AMZN: $845, flat for the week – all prices in The Bull Market Report are for the week)
This week was the launch of DXagents, a first-of-its-kind group of business leaders and technologists from leading private, public and not-for-profit organizations in Canada, that aims to accelerate the national digital transformation. The year-long partnership includes Deloitte, SAP, Amazon Web Services (AWS), Intel, and others. The mission of the group is to help Canadian businesses better understand and get on the path to realizing their digital transformation opportunities.
Digital transformation refers to the adoption of digital technologies such as cloud, big data, mobile and social media. With recent IDC research finding that 63% of Canadian companies are 'digital laggards' leaving themselves vulnerable to competition from less risk-averse global peers, DXagents was created as a community for Canada-based CIOs, CFOs and other decision makers to more easily and effectively share and discuss experiences related to digital innovation.
BMR Take: Here is a big growth opportunity (this time Canada). Yet again, guess who is involved? (Amazon). Where is Microsoft Azure? Where is Google Cloud? It sure looks like Amazon Web Services has an “in” to doing more business with Canadian companies.
Apple (AAPL: $137, +1%)
Apple has Samsung on the ropes like never before. The competition for the lucrative high-end of the smartphone market is a race between these two companies, which ship over 36% of smartphones globally, according to an IDC estimate.
The war between the two companies for smartphone buyers has raged for years, but the power balance is shifting in favor of Apple, especially after last year's Galaxy Note 7 fiasco and the rising anticipation for the next iPhone.
Mobile World Congress kicks off Monday. This event is one of the biggest smartphone trade shows of the year. Although Apple never makes announcements at the conference, competitors, especially Samsung, usually launch their new mobile product in order to get some press. This year, Samsung is not expected to launch a new phone at the show. Instead, it will likely launch new tablets. While it could be nothing, it could also be a leading indicator that Samsung is really in a tough spot this year, perhaps something has gone really wrong with this year’s model. In contrast, over in Apple’s camp, Apple's Asian supply chain is raising rumors of a very cool redesigned iPhone, with a better screen, longer battery life, and a next-generation 3D selfie sensor.
BMR Take: Apple is taking a bigger bite out of the smartphone market as Samsung is stumbling. Apple is leading the way by innovation. That is what we love to see for our stock picks at The Bull Market Report.
SEE MORE on Apple below in this Report.
Home Depot (HD: $146, +2%)
It’s not too late to buy into the housing recovery. While some fear we are in the 8th or 9th inning of the housing cycle, a recent fundamental analysis published by a major Wall Street investment bank suggests we are not yet that far along. This mean there is still some gas left in the tank for Home Depot.
Home Depot is enjoying strong fundamentals as housing demand continues to outstrip supply. Rising interest rates are not likely to hurt the industry near-term as bad as some may think. For example, it usually takes as much as eight quarters for tightening interest rate cycles to hurt home improvement spending, and Home Depot stock has performed well in rising rate environments in the past.
There is more to like. Home Depot has more stores than peer Lowe’s in yet-to-recover and recovering markets. Accordingly, many think there is upside to the consensus same-store growth outlook of 4-4.5% for Home Depot in 2017-2018. One can also argue that the stock is nowhere near stretched, trading at a PE of 20 that is on par with the 3-year average, and is compelling relative to expectations for low-teens EPS growth.
BMR Take: Business at Home Depot is charging forward. Don’t let all the “late-cycle” discussion talk you out of this holding.
Bristol-Myers Squibb (BMY: $56, +3%)
Bristol is our featured story of the week. It has been a bit of a turbulent ride so far. But hang in there, big time help has just arrived. While JANA Partners pushing for more buybacks and board seats has been helpful, the one and only Mr. Carl Icahn just showed up. Icahn has a history of taking positions in companies and then working to force a sale. Worth about $20 billion, Icahn primarily invests his own fortune.
Icahn was reported to see this drug-maker as potentially ripe for a takeover. Possible buyers could include Pfizer, Gilead Sciences. and Novartis, all of which have an interest in cancer drugs and have money to spend. “I think everybody is looking at Bristol,” Allergan CEO Brent Saunders said in an interview.
Bristol-Myers was itself once one of the drug industry’s major acquirers, snapping up pipeline assets in what it referred to as its “string of pearls” strategy. Those deals landed it the drug Opdivo, which uses the immune system to attack cancers and got remarkable results in once-fatal diseases like advanced melanoma. More recently, though, it’s lost ground to rivals like Merck, which has a similar drug, Keytruda, that has taken the lead in some oncology markets.
Bristol-Myers is still a tempting takeout target. If you believe in the immuno-oncology franchise, then it’s obviously an attractive asset because there’s not many ways to get into this space. While Pfizer has a partnership in immune-system-based cancer drugs, it’s well behind Bristol-Myers and Merck. Novartis, another player in oncology, could raise the cash to do a deal through asset sales and debt. Gilead has amassed billions of dollars from sales of its hepatitis C drugs and is looking for its next move.
BMR Take: Icahn has made a fortune for himself as well as the shareholders who have been there alongside him. Bristol just became one of the most interesting holdings in your portfolio.
Tesla (TSLA: $257, -6%)
What does Tesla's new CFO mean for business? Tesla CFO Jason Wheeler is leaving the company after just 14 months on the job and will be replaced by the electric car maker's original CFO. Tough to be the new guy?
Wheeler, who left his job as vice president of finance at Google to join Tesla in 2015, is leaving to pursue a position in public policy. Hmmm. We wonder what the real story is. When a company changes CFOs -- particularly by returning to a previous CFO -- it's often an indication that it's "tightening up operating performance” and specifically focusing on margins. Tesla's gross margins showed a drastic decline from 28% in the third quarter to 19% in the fourth quarter. The executive level change is likely a step to fix this problem.
Investors want to know if Tesla is going to lose money on each car it manufactures now as it ramps up production, or if it can come close to earning money off each sale. Tesla said that its Model 3 automobiles will start at a price of $35,000, but the company spends about $80,000 to build each car. Many say that this includes capital investment so it not a comparable statistic. There is a lot of heavy lifting to be done to get to profitability.
BMR Take: Change can be good or bad. In this case, we see good things happening. Tesla is getting back some needed deep expertise at a critical juncture. We continue to see long term value in Tesla. Who else is disrupting the Auto industry is such a big way? (Hint: no one.) But we also note that innovation in the Auto industry is a tough business. It hasn’t been done for decades, so an investment here is fraught with risk. As we’ve said many times using different numbers, Tesla could be heading to $400, or $150, we’re not sure which. And if it does go to $400, it just might hit $150 first. If you don’t like risk, please exit the kitchen.
Netflix (NFLX: $143, +1%)
Competition is getting red hot. Sling TV is helping Dish Networks add subscribers. U.S. satellite TV provider Dish Network reported a better-than-expected profit as it unexpectedly added more pay-TV subscribers in the fourth quarter than expected.
Analysts said the subscriber additions were largely driven by Dish's lower-priced streaming service Sling TV, even as the company's quarterly revenue missed estimates. Sling TV, launched in 2015, is a way for Dish to target cord-cutters, or customers who are dropping traditional cable TV for streaming services like Netflix.
BMR Take: The success of Sling TV can be viewed from a few different angles. On one hand, it further reaffirms the momentum in chord cutting, meaning the sandbox Netflix is playing in is extremely lucrative. On the other hand, perhaps Sling TV is turning into more of a competitor for Netflix. Even if the latter trend is true, we think the former trend is big enough overall to take Netflix shares higher. Remember we also have the potential upside of the rumored Apple Services move into TV. People are saying Apple is going to get much, much bigger in this area. After all, everyone is watching Netflix on their Apple phones and tablets!
Upcoming Economic News
MONDAY, FEBRUARY 27
Durable Goods Orders – January
Time: 8:30 am
Forecast: 2.0% overall, 0.5% ex transportation
Durable goods orders are forecast to expand in January after being held back by the Transportation sector in the two previous months. Core orders growth is steadily improving, rising 2.1% year-over-year in the fourth quarter for the largest gain in two years. The general strengthening of global growth prospects and the upturn in the commodity sector are lifting demand for US produced goods.
Pending Home Sales Index – January
Time: 10:00 am
Forecast: 0.9%
The Pending Home Sales Index is set to rise for the second straight month in January as the housing recovery remains firmly on track. Existing home sales rose to a 10-year high in January, lifting sales over the past three months by 6% year-over-year. The home sales pace is aided by rising home lending volume. The MBA index of mortgage applications for home purchases saw its moving four-week average reach a 7-month high in January before dipping a bit in February.
TUESDAY, FEBRUARY 28
GDP – Fourth Quarter (Second Estimate)
Time: 8:30 am
Forecast: 2.1%
Trade activity held back GDP growth in the fourth quarter and continued gains in imports may produce a similar result in the current quarter. But the underlying pace of consumer spending is holding firm, with Retail sales excluding autos and gasoline rising 0.7% in January, equaling an 11-month high. Though annual growth for real GDP is still likely to top 2% this year, lowered expectations for fiscal stimulus reduce much of the potential upside.
S&P Case-Shiller Home Price Index – December
Time: 9:00 am
Forecast: 5.2% yearly change of 20-city index
Historically tight supply of existing home available for sales can keep the S&P Case-Shiller Home Price Index chugging along in excess of 5% annually to December. The four months’ worth of inventory of existing homes at January’s sales pace is near the record low. That has kept home prices rising significantly faster than broad inflation growth for over four years, as seen in the 6.9% yearly rise of the median price of existing homes sold in January.
Conference Board Consumer Confidence – February
Time: 10:00 am
Forecast: 110.9
The Conference Board measure of consumer confidence can continue to ease back a bit in February after reaching the 15-year high in December. Robust levels of confidence will not necessarily translate into a big burst of consumer spending, as the share consumers who indicated in January that they intend to buy a car or home lags the average of the past three years. Yet firmly positive income expectations still point to a solid pace of spending among other consumer goods and services.
WEDNESDAY, MARCH 1
Personal Income & Spending – January
Time: 8:30 am
Forecast: 0.3% income, 0.3% spending
Skimpy recent monthly gains in average hourly earnings hint of a restrained advance for personal income in January. The recent 2.5% annual advance in hourly earnings is not showing the break out in wages many expected, although some other indicators point to faster growth. Continued labor market progress will be needed to push annual income growth back above 4% for the first time since late 2015.
ISM Manufacturing Index – February
Time: 10:00 am
Forecast: 55.8
Heightened business sector confidence and positive output trends are forecast to keep the February ISM Manufacturing Index near January’s two-year high. The new orders component of the index topped 60 in each of the past two months, a firm signal of rising demand. And manufacturing output’s annual pace was positive in each of the three months ending January after declining on this basis throughout much of last year.
Construction Spending – January
Time: 10:00 am
Forecast: 0.8%
Sturdier growth in residential activity is expected to lift overall January construction spending after a decline in December. Housing starts rose 6% year-over-year in the three months ending January following lackluster results towards the middle of last year. And private commercial construction is also aiding the cause, rising 7% year-over-year last quarter.
Vehicle Sales – February
Forecast: 17.6 million
Vehicle sales may show little movement in February relative to January after falling sharply from December’s 11-year high. Even including December’s cyclical high, the yearly advance in the three months ending January was a mere 0.7%. While vehicle sales volume is likely to remain strong in 2017 amid improving consumer finances, sharp gains of the recent past leave little room for further growth.
FRIDAY, MARCH 3
ISM Non-Manufacturing Index – February
Time: 10:00 am
Forecast: 56.5
The ISM Non-Manufacturing Index is projected to hold onto its post-election bounce in February due to sturdy demand for domestic services. The sub-index measuring general business activity in the service sector topped 60 in each of the past three months, signaling a sustained upturn in sales growth. Yet businesses will have to contend with some rising cost pressures, as the Non-Manufacturing index reading on prices rose to the 30-month high in January
Our Take on the Snap IPO
If you are looking at the soon-to-come Snap IPO, look long and hard. It’s coming out at a high valuation and the market may push it much higher after it starts trading. Note that management has gone overboard on the different classes of stock, offering stock to you with NO voting rights, and maintaining 100% control, no matter how many shares you own. This is not the American way. Google has done this and Facebook has done this, but they have done it in a quiet, professional way. And furthermore we know their track record. Snap is being belligerent about it and they have no public track record. We are passing on the stock.
How to Use Options to Lower the Cost of Buying High-Priced Stocks
Tesla ($257), Google (GOOG: $829) and Amazon (AMZN: $845) have risen so much that sometimes folks don’t like to buy the stock at these lofty levels. After all, with Google, 100 shares will cost you $83,000. We at The Bull Market Report don’t have a problem with this but many of you do. If you only have $20,000 to invest in Google then just buy 24 shares. After all, they could split the stock tomorrow 10 for 1 and the price would drop to $83, and you would then have 240 shares. It’s all the same. It is just psychological.
OK, with that said, using options you can control 100 shares of Google for only $18,000. How? You could buy the January $700 2019 option (called a LEAP) for $18,000, or $180 per share. There are two negatives though. 1) You would control the stock for only two years, and 2) You would pay a $50 premium to the price of the stock today. In this example this option allows you to buy the stock at $700, but you have to pay $180 for it, which gives you a breakeven price of $880. If the stock goes higher than $880 in two years you make money, possibly a lot. If it goes lower, you can lose some or all of your investment. So it is not for all. And like everything in life there are at least two sides to every story. If you would like us to expound on this concept please drop us a note at Info@BullMarket.com.
A Word from Gary Jefferson
First Vice-President, Investments
Jefferson Financial Group
UBS Financial Services
"Don't fight the tape." "The trend is your friend." "If you're not long, you're wrong"…………..These are just a few of the Wall Street adages being bantered about as the market continues to climb higher.
What the market senses and, more importantly, expects, is a reduction in corporate and personal income taxes and a meaningful reduction in government regulations that stand to increase (perhaps doubling) the rate of gross domestic product (GDP) growth by the year's end. Investors who are betting against this inertia are, in track parlance, trying to beat the favorite horse by picking longshots.
How high can the market go? That's the biggest question on investors' minds. What we have learned over the past 30 years is that market predictions are not much better than a coin flip. In fact, a lot of them are mostly headline grabbers and entertainment marketing rather than a serious study of behavioral science. Remember back in the 1990s, when some of the best sellers were "DOW 36,000: Why This Time Is Different"…….or "DOW 40,000: Strategies for Profiting from the Greatest Bull Market in History". That said, every serious investment firm is obligated to make a prediction, and each one generally has one which is reasonably based on a set of "what if's"; i.e., if earnings are this, then the market should be that. One publication that has taken forecasting to a new level based on scientific quantifying of "uncertainty" is Modern Trader. They say that there is a possible downside of about 6% and upside of about 24%.
Some other interesting forecasts we read recently include what many experts believe will be the most profitable sectors. There is a consensus that the best performers include Healthcare (biotechs), Financials (regional banking) and Technology, with a lot of support for Energy.
There are many opinions on what will be the biggest fundamental factors affecting the market. Some of our favorite picks were:
1. Interest rates, the dollar, and the price of oil. (Throughout our 30 years in the business, oil has always been a wild card for the market.)
2. Tax cuts and infrastructure investment.
3. Brexit, Chinese economic growth, South China Sea tension.
4. Three things: Trump, Trump and Trump.
Finally, Modern Trader selected Cybersecurity as the one sector every investor should own in 2017, citing the consistently growing number of cyber incidents across the globe and analyst expectation of worldwide spending on cybersecurity to eclipse $1 trillion cumulatively for the five-year period from 2017 to 2021.
[Note that The Bull Market Report pick Splunk (SPLK: $63) is up 36% since we added it 11 months ago. Our Target Price is $75.]
Letter to the Editor – about First Solar (FSLR: $38, up 9%)
From: Peter Goransson
[Note that we had sent out a News Flash last week saying that the stock was down sharply in after-hours trading after the earnings report came out, and we were a bit worried about the stock.]
Peter said: “First Solar is actually up 11% today [Thursday]. Looks like yesterday's movement may have been an overreaction. Are you still considering removing this from portfolio?”
Our response:
Hi Peter –
The market turned around this morning when level heads prevailed. We are breathing a sigh of relief.
It was terribly disappointing to us to see the reaction to the earnings announcement Wednesday evening, so this 11% move today is very heartening. No, we are not going to remove the stock from our portfolios. We are going to hang with it for a while.
We really do love this company and if you look at their history, their revenues have been very big, and we believe they will get big again. And earnings will follow, because historically they are very profitable.
Todd Shaver
Ferrellgas (FGP: $5.89, down 8%)
This stock continues to disappoint and we’ve decided not to wait any longer. The company made a terrible decision in buying Bridger Logistics with the whopping price tag of $840 million. And it bought Sable Environmental for $125 million in 2014. These purchases were financed mostly by new debt and this is what is dragging down the company. The firm has made over 240 acquisitions over the past 75 years but these two are icing on the cake – heavily, sludge-filled icing – that is bringing down the company. When we added Ferrellgas to our High Yield portfolio last year we had no idea how bad a deal this was for the firm and more importantly for the stockholders. We have said many times that the turnaround is going to take 12-18 months. We now feel it may be on the order of 2-3 years, if not longer, and may in fact bring the entire company down.
We’re not going to wait any longer. We hereby remove the stock from our High Yield portfolio. (It’s not even a high yield stock anymore. As they have cut their dividend so drastically because they are losing money.)
Now, what should YOU do? If you have a small position in the company you might just forget about it, keep it in your portfolio, and take a look in a year. If you have a big position then you might consider taking a loss and moving into some stable growth companies.
More on Apple
Berkshire Hathaway’s gain on Apple is more than $1.6 billion after shares have surged since it hit $105 in November. In fact, Apple was the Dow’s best performer in 2016. The news just came out on Warren Buffett’s investment in Apple: Berkshire Hathaway bought 61 million shares last year for $6.75 billion, at an average of about $110 apiece. The holding was valued at more than $8.3 billion as of Friday’s $137 closing price.
Berkshire became one of the top 10 Apple investors in 2016, taking a stake of more than 9 million shares in the first quarter and then accelerating purchases in the last three months of the year. The initial purchases were for an average of $99. Not that Buffett’s company bought $12 billion in stocks after the Nov. 8 U.S. election, indicating a continued strong faith in the American economy. Buffett said the market system that has propelled U.S. economic growth for more than two centuries will continue unabated, echoing his optimism about the country. “The build-up of wealth will be interrupted for short periods from time to time, but it will not, however, be stopped. I’ll repeat what I’ve both said in the past and expect to say in future years: Babies born in America today are the luckiest crop in history.”
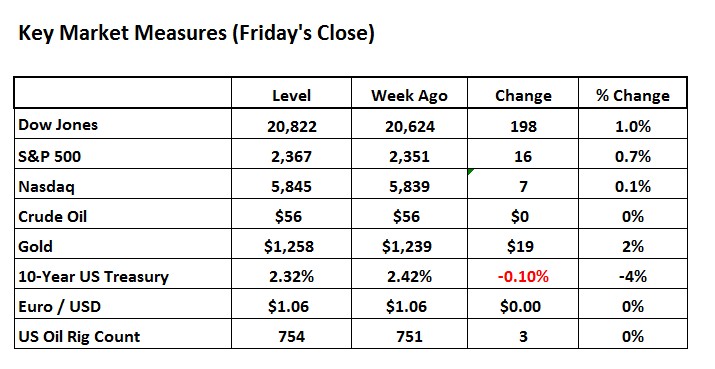
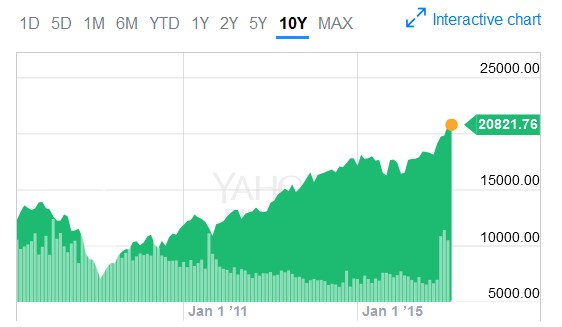
Now there is one bullish investor! (With a stock price of over $250,000 a share!) We tend to agree with Warren and we would be vigilant in making changes in our portfolio if the market decides it has peaked. If, and we repeat IF that were to happen, there are lots of great stocks in our High Yield portfolio that will allow us 6, 8 and more than 10% a year returns while we sit and watch the market take a breather. However, at this time the market remains strong, with the Dow at 20 thousand eight. That’s 20.8 thousand. Or 20,822. For heaven’s sake, we just hit 20,000 on February 3rd!
The Weekly High Yield Report
By Michael Foster
Special to The Bull Market Report
It's been another quiet week in the markets, and even quieter in high yield than anywhere else. But before we get to that, we want to talk a bit about some Wall Street chatter we've been hearing from friends both on the buy side and the sell side of the business. Hiring is up in fixed income, especially in the high yield and distressed debt sectors. This bit of insider gossip doesn't sound all that exciting, but it's actually a really big deal. Wall Street hiring is trend driven and often a leading contrarian indicator. When Wall Street starts to invest heavily in one particular corner of the market that is a signal that that part of the market is at or near its peak and a downturn in the next couple of years is likely.
Let's take a look at why that's the case. If you're an investment bank, you make money buying and selling assets for investors. Investors tend to avoid assets when they're down (thus exacerbating the trend) and pile in when they're up (think of how many people were buying investment houses in 2005-2006). When more investors want to buy, say, junk bonds, that creates more demand for people to buy and sell junk bonds, thus turning into more jobs in that sector.
This is especially worrying because hiring is down across Wall Street. This has been an issue since 2008 and it is just getting worse. The fact that fixed income has a temporary reprieve suggests that demand in that sector is really getting hot.
If you want proof, just look at the SPDR Barclays High Yield Bond ETF (JNK: $37). This fund is already up 20% including dividends over the last year, the best one-year performance since 2009. Volumes have also exploded five-fold over the same period. Demand for high yield bonds has heated up.
But what about those surging defaults? Remember in late 2015 when everyone was panicking about the oil-driven defaults in corporate bonds? There was worry that the real risk that higher interest rates would cause even more defaults as cash-strapped companies struggled to keep cash flow enough to service their outstanding obligations. Remember that revenues hadn't been growing for years back then? That's why high yield bonds fell 20% in a little over a year after Yellen raised interest rates.
Those risks remain, but investors don't care anymore. This doesn't surprise us, as the risk of those defaults have been priced into the corporate bond market for over a year now.
There are two lessons to learn here. Firstly, ignore financial press headlines warning about an upcoming apocalypse in an asset class. Trading on that noise is a fast track to poverty. Secondly, being a contrarian investor and rotating into unfavored assets can produce strong medium-term returns.
But now that corporate bonds aren't unfavored, does that mean it's time to sell? Not exactly. There remain good funds that trade in corporate bonds or similar assets like the AGIC Equity and Convertible Income Fund (NIE: $19.46) and the PIMCO Dynamic Income Fund (PDI: $28), which are up about 24% and 26% respectively, including dividend payouts, over the last year. And the dividend payouts haven't gone down and remain safe. If anything, they're getting safer as interest rates go up. That means there is no reason to sell either of these until the market bids their prices to an absurd premium. The Pimco fund is unfortunately trading at an 8% premium to NAV, almost its highest premium in history.
This is especially disconcerting because the Pimco fund historically trades at a discount and it's rarely desirable to buy a closed-end fund at a premium pricing. We would not recommend buying this fund at its current price level, but selling is not a good idea yet either. This is a very obvious hold in lieu of desirable alternatives. Outside of Pimco, there are few funds that can deliver such a substantial market out-performance.
But we also don't think the fund's premium is going to disappear anytime soon. The closed-end fund investment world is getting smarter and the fund's primary income stream (mortgage-backed securities) are getting less underpriced. In the past, a lot of money avoided this sector because of the hangover of the subprime mortgage crisis. That was an irrational mispricing of the sector, so now money is coming back. As money comes back, it makes sense for Mortgage Backed-focused funds to start trading at smaller discounts or, in the case of Pimco's Dynamic Income Fund, at a premium.
Elsewhere in the high yield world, funds have had a muted week indicating there's still time to buy where there is an undervaluation relative to history. The Invesco Municipal Trust (VKQ: $12.65 , down -1%) and Nuveen AMT-Free Fund (NVG: $14.64, flat) had a week of muted action although the news regarding interest rate hikes remains unchanged: The Fed signaled what everyone was already expecting this week, which is great for high yield. Similarly, things were quiet in REITs as higher borrowing costs is causing less panic than it used to. The SPDR Dow Jones REIT ETF (RWR: $95) rose a bit over 1%, with only a few REITs under- or over-performing in a week of little news.
For now, high yield remains an attractive sector but it's not a "no brainer buy” like it was a year ago. There are pockets of attractive undervaluations, especially municipal bonds and some REITs, while fair valuation is becoming more common in the junk bond sector. This is a trend that's likely to continue for a while, assuming we don't get any shocking news to the upside or downside. This confirms our view to buy and hold these funds, since they have outperformed the broader market and are likely to continue to do so for a very long time.
Good Investing,
Todd Shaver, CEO, Founder and Editor
The Bull Market Report
Since 1998
January 22, 2017

by Todd Shaver | Jan 22, 2017 | Weekly Newsletter 7pm Sunday
The Week Ahead
This week will be a thriller. President Trump and his cabinet of business leaders will be laying out action plans for a new governing structure for America. Carl Icahn said we haven’t seen a structural reform like this in government in a generation. In this newsletter, we provide some insights on our latest thinking for Bristol-Myers Squibb, Splunk, Kinder Morgan, VMware, Visa, Home Depot, Invesco Municipal Trust, Under Armour, Tesla and Netflix.
Highlights From The Past Week
Trump releases formal agenda. According to a statement posted on the White House website, President Trump’s economic plan will create 25 million new jobs in the next decade, return to 4% annual economic growth, lower rates for Americans in every tax bracket, simplify the tax code, and reduce the U.S. corporate tax rate. We’ll see how Congress will modify these lofty goals.
A few ways the markets could be surprised, according Credit Suisse. The S&P 500 hits 2,500 before falling back to 2,000, versus the consensus view of the index going to 2,300 and leveling off. The Euro falls to $0.90 then strengthens sharply to $1.20, versus consensus outlook for moderate drift to $1.00. Chinese GDP growth slows to 5%, versus consensus of 6.8%. Trump’s policies don’t work, as inflation expectations rise and protectionist policies disrupt world trade. Oil prices hit $75 by year end, versus consensus outlook of $62.
Wake up call. Yes, American politics is not great. But at least we aren’t Brazil. The death of Brazilian Supreme Court Justice Teori Zavascki who had presided over the sprawling "Carwash" corruption scandal, and who died yesterday in a freak airplane crash Thursday has sent shockwaves both around the globe and in Brazil, because while few in polite company will discuss it, it has opened the possibility of political assassinations as a means of "quieting" legal proceedings.
BMR Companies and Commentary
Bristol-Myers Squibb (BMY: $49, -12% for the week)
Bristol-Myers announced that it has decided not to pursue an accelerated regulatory pathway for the combination of Opdivo plus Yervoy in first-line lung cancer in the United States based on a review of data available at this time. In order to protect the integrity of ongoing studies, the company will not be providing additional details. This news sent the stock price tumbling this week.
The situation is just very unfortunate. As Citi’s analyst put it, “We never believed Bristol-Myers had an accelerated pathway to market for Opdivo and Yervoy in front line lung cancer.” This was just totally botched communication by management. As the Citi’s analyst went on to put it, “On a fundamental basis, in our view, nothing has really changed aside from credibility in the guidance.”
What happened? Some people in the investment community started speculating Bristol-Myers could take the accelerated regulatory pathway to catch up to Merck on developing imuno-oncology. The company never stated this. Bristol should have been more vocal that this strategy was not in the cards. They needed to be more pro-active.
The reality is unfortunate for us shareholders having to stomach the near-term volatility. But we should not be worried about the long term picture. As the company put it, “Our vision for the future of cancer care is focused on researching and developing transformational Immuno-Oncology (I-O) medicines that will raise survival expectations in hard-to-treat cancers and will change the way patients live with cancer.”
BMR Take: Bristol is still going to do great things over the long term in cancer and healthcare. We are excited about it. If you aren’t involved in Bristol yet, lucky you. If you have some shares and you have some additional cash to put into this company, we would do it. The shares under $50 are a screaming value. This is an $82 billion market cap behemoth in Healthcare we are talking about; not some pre-revenue biotech moonshot.
Splunk (SPLK: $54, -5%)
Splunk recently hosted its analyst day setting the stage for the stock to rock and roll. Specifically, management laid out monster guidance. Management spoke of the path for Splunk, which is expected to end 2016 at nearly $1 billion in revenue, to hit $2 billion in revenue and $2.3 billion in billings in 2019. This path is driven by accelerating customer growth (with Splunk ending 2019 with 20,000 customers, up from 12,700 in 3Q16; growing deals over $1 million (reaching 300 such deals in 2019, up from 140 in 2016), and the license average selling price growing from $55,000 in 2017 to $80,000 in 2019. This guidance suggests a 3-year revenue growth rate of 29% annually.
On top of the revenue picture, management said that at $2 billion in revenue, Splunk is expected to more than double its operating margin from 5.5% (the midpoint of 2016 guidance) to 12-14% in 2019, mostly through sales and marketing leverage. Wow!
BMR Take: We like Splunk because: 1) it is the leader in operational intelligence software that helps enterprises make sense of machine data; 2) it addresses a large and expanding market; 3) its model is becoming more predictable as the revenue base grows; 4) the company has a long runway to sustain 30%+ growth; and 5) we believe its strong business momentum will continue.
Kinder Morgan (KMI: $22.50, flat)
Kinder Morgan reported earnings of $0.08 per share, which was better than the $0.32 loss reported a year ago, but not as good as consensus analyst expectations for $0.18. There were minor disappointments causing some weakness in the stock after the announcement, but expectations were and remain low and overall you should walk away from the quarterly results feeling that operations are in a stable to improving place.
The company plans to invest $3.2 billion in growth projects during 2017, which it says will be funded with internally generated cash flow without the need to access equity markets. We are encouraged to hear the word “growth” being discussed in the Energy market nowadays.
Even though Kinder Morgan's balance sheet remains of a concern for us, the company did significantly enhance its credit profile by reducing debt by over $3 billion during 2016. You have to give them some credit. In fact, they finished ahead of plan for 2016 year-end leverage, and are progressing toward reaching the targeted leverage level of around 5 times debt to earnings, which will position them to return substantial value to shareholders through some combination of dividend increases, share repurchases, additional attractive growth projects or further debt reduction.
BMR Take: We remain bullish on the rebound for Kinder Morgan along with the rest of the MLP sector. Kinder Morgan has an unparalleled asset footprint spanning the breadth of the United States with leading North American industry positions in each of its five business segments – Natural Gas Pipelines, CO2, Products Pipelines, Terminals, and Kinder Morgan Canada. They really have a great franchise here.
VMware (VMW: $83, +1%)
We are excited to now be involved in VMware. The company’s server virtualization technology helped spark the cloud computing phenomenon. VMware has nearly doubled revenues in the last five years, growing from $3.8 billion in 2011 to $6.6 billion last year. We think there is more room for this bull to run.
Sanjay Poonen is chief operating officer at VMware. He joined VMware in 2013 from SAP, where he was responsible to “build bridges” between the data center and the public cloud, and to the end user through better mobile tools. Serving enterprise mobile users is an effort SAP began in earnest in 2014, with the acquisition of mobile device management company AirWatch. Now VMware has Poonen working on building a similar strategy for shareholders.
VMware sees the hybrid-cloud model as an extension of VMware’s original mission. In a hyper-cloud setup, storage, computing and networking capabilities are integrated and handled largely by software, rather than hardware. The “single box” can save companies from having to buy separate components to integrate manually. Managing a unified system through software also lets technology executives to make changes, such as adding storage space, more easily and less expensively than performing the same changes on individual pieces of hardware and software. It better technology for users. It’s cheaper for users. It’s a major win.
BMR Take: Hybrid-cloud is changing the economics of enterprise IT. VMware is going to win a good chunk of the opportunity. Partnerships are already in place with Amazon and IBM.
Visa (V: $82, +1%)
Walmart reached an agreement to continue accepting Visa credit cards across Canada, ending the retailer’s threat to bar the world’s largest payments network from its 410 stores in the country.
Walmart’s Canadian unit threatened to expel Visa from all of its stores nationwide unless the network agreed to lower the amount it charges for credit-card transactions. Walmart Canada, which has said it pays more than $76 million annually on credit-card transaction fees, called the amount Visa charges “unacceptably high.”
BMR Take: What a battle royal. Visa versus MasterCard. Not quite as good as Ali vs. Frazier. The bad news is that they had to cut their fees. The good news is that Visa didn’t lose the battle and will reap huge revenues from the largest retailed in the land.
Home Depot (HD: $136, flat)
Home Depot has fallen right in the middle of a big debate. The Republican border-adjustment proposal aimed at taxing imports may pressure retailers’ earnings by driving up the cost of their inventory.
However, gauging the plan’s exact impact on retailers including Home Depot is difficult because the companies do not break out what percentage of their inventory is imported, and many goods produced in the United States rely on imported material.
Trade associations for large retailers have been voicing opposition to the proposal, with the National Retail Federation saying it is a “scary proposal with a lot of unknowns.”
One analyst’s research that suggests the tax bills of six large retailers may jump about $15 billion to a total of $28 billion under the current House plan, though some advocates say currency adjustments will offset the tax changes and mute retailers’ objections.
BMR Take: Trump’s first 100 days will be loaded with market moving events. We will be closely watching the border-adjusted tax situation. Trump is already backing away from the proposal saying it is too complicated. So the outlook is all clear for the moment.
Invesco Municipal Trust (VKQ: $12.51, flat)
The recent blow-up of the Dallas Police and Fire Pension System was entirely predictable. While it is tempting to blame unusual circumstances for the recent lock-up of redemptions and substantial reductions to pensions for those still in the fund, many other American pension funds are heading down the same road.
The combination of overpriced financial markets, inadequate contributions and overly generous pension promises mean dozens of US local and state government pension plans will end up in the same situation. The simple math and political factors at play mean what happened at GM, Chrysler, Detroit and now Dallas will happen nationwide in the coming decade.
Pew Charitable Trusts research estimates a $1.5 trillion pension funding gap for the states alone, with Kentucky, New Jersey, Illinois, Pennsylvania and California going backwards at a rapid rate. Using a wider range of fiscal health measures the Mercatus Center has the five worst states as Kentucky, Illinois, New Jersey, Massachusetts and Connecticut. The five state pension plans in Illinois have an average funded ratio of just 38%.
BMR Take: All the above is not good and is unsustainable. It’s weighing on Invesco Municipal Trust. But honestly, it is not as bad as it sounds. One needs to be more specific and not paint everything with the same brush. Take for instance the Dallas Texas credit in the portfolio. They are getting crushed on this pension news story. But the reality is Dallas is one of the most vibrant cities in the America. You can pick-up some of the general obligation bonds of the city at a 4% yield right now compared to the benchmark curve at just 2%. They are rated AA too!
Upcoming Economic News
TUESDAY, JANUARY 24
Existing Home Sales – December
Time: 10:00 am
Forecast: 5.50 million
December existing home sales are forecast to decline after rising a 9-year high in November. The Pending Home Sales Index fell to the 10-month low in November, a warning that existing home sales have lost some momentum. Yet some buyers are looking to move before mortgage rates potentially rise further, as the moving 4-week average of mortgage applications for home purchases recently rose to the highest level since last June.
THURSDAY, JANUARY 26
New Home Sales – December
Time: 10:00 am
Forecast: 585,000
New home sales may have dipped in December after reaching a 4-month high in November. But the long-term sales trend has been stellar, with sales of new homes rising 20% year-over-year in the quarter ending November. And sales still have much more room to grow to get back to historically normal levels relative to the size of the population. The most recent monthly new home sales pace trails the average of the past 20 years by 19%.
Leading Economic Indicators Index – December
Time: 10:00 am
Forecast: 0.5%
Spikes in stock prices and consumer confidence can power the Leading Economic Index in December to the largest gain in five months. The policies of the incoming administration will determine if this burst in optimism can translate into a sustained upturn in growth. Yet quickening wage growth gives a clear signal that consumers now have more resources to increase spending.
FRIDAY, JANUARY 27 GDP
Fourth Quarter (Advance Estimate)
Time: 8:30 am
Forecast: 2.1%
A widening trade gap is expected to lead slower GDP growth in the fourth quarter after reaching the fastest rate in two years in the previous quarter. The future effects of trade on US output are rife with uncertainty with regard to the evolution of policy and the value of the dollar. But the underlying pace of consumer spending is holding firm, getting a lift from the recent upside surprise in auto sales.
Durable Goods Orders – December
Time: 8:30 am
Forecast: 2.2% overall, 0.4% ex transportation
Solid recent indicators for industrial demand hint that Durable Goods orders can rise for the fourth straight month in December. The new orders reading from the ISM Manufacturing Index jumped to the two-year high of 60.2 last month, raising expectations for near-term industrial output. Core durable goods orders have also shown similar vigor of late, rising at the 2-year high rate of 5% annualized in the three months ending November.
University of Michigan Consumer Sentiment – January
Final Time: 10:00 am
Forecast: 98.0
The final reading on sentiment in the January Michigan survey is forecast to show only a mild decline from December’s multi-year high. Significant increases in consumer inflation expectations in the initial January survey signal that prices are poised to accelerate a bit.
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services
Earnings season will continue this week. Fourth quarter results for several of the largest banks were announced last week - JPMorgan Chase, Bank of America, Wells Fargo and PNC – and they were generally quite strong.
Remember – earnings for 3Q16 were up 3.1%, which broke the back of the preceding 6-quarter earnings recession. According to Thomson Reuters, earnings for the S&P 500 are expected to increase by 6.1% in the fourth quarter. Last year still didn't see 3% GDP growth, but expectations are for that plus more this year. UBS's pre-Trump forecast was for earnings growth of 5.9% in 2017, and that figure is expected to be revised higher based on the implementation of Trump economic policies.
The biggest question marks for 2017 may not come from economic data alone, but instead, from changes in political leadership. As everyone knows, stocks have already rallied on hopes that President-elect Trump will reduce regulation and taxes while increasing infrastructure investment. However, no one knows for sure what actual changes could be on the horizon - or how Trump's policies will affect trade. Or how Congress may bottle up his potential policies. Trump will lay out an economic "game plan" which could ease some of the market uncertainty that still swirls around the dramatic change in Washington politics. One thing we are concerned about is the formula of “Hope + Uncertainty = ?” In our experience, the answer to that equation is most often "volatility".
Meanwhile, the market still functions on basic fundamentals [and as noted above there are lots of economic reports coming out this week.] And, investors will be watching oil prices, along with gold, the dollar and interest rates. That's because the investment landscape has changed from the expectation of lower interest rates and slower growth for longer periods of time to the possibility of moderately stronger growth and a stronger dollar with higher interest rates due to potentially higher future domestic inflation.
• Oil Prices - Oil began the new year higher as U.S. Crude rose to $54 a barrel.
• Gold - Gold has recovered a bit to start the year, closing at $1210 an ounce on Friday.
• U.S. Dollar - The U.S. dollar index continued to show strength.
• U.S. Treasury Rates - The yield on the benchmark 10-year Treasury settled at 2.47%.
Tesla Motors (TSLA; $245, up 3%) Tesla continues higher. From a low of $181 in early December, the stock is up 35% reaching $39 billion in market cap and stretching for the all-time high of $275 in the summers of 2014 and 2015. What will this summer bring? Good question, but we will tell you that this summer the firm will be a lot closer to delivering the new exciting Model 3 that they are holding 400,000 $1000 deposits on. That’s $400 million in cash that the firm can use for corporate purposes.
Tesla saw some upgrades on Wall Street recently. Morgan Stanley raised their Target to $305 from $242. Goldman is stuck at $190. Wake up Goldman! Robert Baird is looking at $338 and Guggenheim has a $280 target in place. There are six Sell Ratings, 11 Hold Ratings and 12 Buy Ratings. We maintain our Target Price of $290.
Under Armour (UA: $25.16; UAA: $29.02) Two things here. First, the stock. The Class A shares trade under the symbol UA, and the Class C shares trade under the symbol UAA. They both have close to 200 million shares outstanding and the average volume for both is around 3 million a day. But, the company has changed the voting rights of each class of stock. The UAA shares have one vote per share. The UA shares have none. Many other companies have done this, primarily so the founders can maintain control. Google has done it – GOOG has no voting rights, GOOGL has one vote – same story as Under Armour. And there is a class B share in both companies that actually have 10 times the voting rights of the Class A shares. Guess who owns the Class B shares? Kevin Plank, the founder.
BMR Take: Both classes of stock are fine for us, the small investor. Ultimately the UA shares will have more liquidity as the UAA shares are retired, so go with the UA shares if you are buying new positions.
Secondly, the company. What can we say? The company had a bad year and the stock has been hammered. We believe that over the course of the next five years the firm will grow and prosper dramatically. With the stock this low (trading at the same level as 2014), we see tremendous value here. The all-time high is $50 set in the summer of 2015 and we see no reason why it won’t hit this level again. Yes, that’s right – a double from here.
Look at revenues: $2.3 billion in 2013, $3.1 billion in 2014 and $4.0 billion in 2015. We think they could hit $5 billion in 2016 when they report 4th quarter earnings on January 31st. We think they will hit $6 billion in 2017. Long story short – we think this is a huge growth story – the kind of company we would love to own for the coming decade.
Netflix killed last quarter. Netflix (NFLX; $139, up 4% to a new all-time high)
The bad news: The DVD service shed 160,000 subscribers during the final three months of last year to end December with 4.1 million customers. That’s an 11-year low. But the business hangs on and is VERY profitable.
The good news: The streaming service now boasts 94 million subscribers in 190 countries, after adding another 1.9 million in the U.S. and 5.1 million in overseas markets during the final three months of last year. One firm predicts Netflix will have 160 million streaming subscribers by 2020. The company is coming off its biggest quarter of customer growth yet.
The financial quarter for Netflix was huge. The company reported revenues of $2.48 billion, up 36% from $1.8 billion. Earnings were $66 million, up 55%. Cash flow – up 125%. These are huge numbers. One small problem, their earnings equate to only 15 cents a share. They need to beef this up in the coming quarters and years. We think they can and they will.
The stock has blown through our Target of $133. We still like the stock and think it is going much higher over the coming decade. We hereby raise our Target to $165 and raise our Sell Price to $125.
We had a question from a reader about our new Invesco Municipal Trust recommendation (VKQ: $12.49)
From: Bob Valentine
Sent: Thursday, January 19, 2017 2:59 PM
To: info@bullmarket.com – The Bull Market Report
1. Just because bonds can be called, why do you think they will be called over the next couple of years?
2. Your research report says 25% of the fund’s assets will or could either mature or be called over the next two years. Can you send me your calculation as I do not come close to this.
3. Why do you think bonds that are maturing will be invested at higher rates than what they are already invested at? it appears possible that they will have to be invested at lower rates based on my review.
Here is our response:
Hi Bob –
1. Bonds tend to be called when debtors can get a lower interest rate. This may still be possible for municipalities if they call shorter-term bonds and issue longer-term ones or if their credit quality improves. In a rising interest rate environment, there’s good reason to call short-term bonds and issue new long-term bonds to lock in lower interest rates. Of course in a falling interest rate environment (which is extremely unlikely right now) you call bonds and issue new ones to cut down your interest costs.
2. The article does not say 25% of the fund’s assets - it says 25% of the bonds. That’s an important difference. Look at all of the portfolio here:
http://hosted.rightprospectus.com/Invesco/Fund.aspx?cu=46131J103&dt=AR&ss=ce
You’ll see that 20 holdings expire in 2017 and 32 expire in 2018. There are a bit over 200 bonds in the portfolio total, meaning nearly a quarter of its bonds will either be called or redeemed by the end of 2018.
3. Interest rates have gone up for all municipal bond indices over the last year, see here:
https://www.bloomberg.com/markets/rates-bonds/government-bonds/us
Thanks you for writing, Bob.
Todd Shaver and Michael Foster
The Bull Market Report
The High Yield Corner
By Michael Foster
Special to The Bull Market Report
The biggest news for markets and the world was the inauguration of President Trump. The markets’ response to this news was muted. at the start of the new President’s speech, stocks dipped but by the end of Friday, all of the major indices had recovered to pre-speech levels.
The excitement that gripped political pundits and policy junkies has been a non-starter for us more economically- and financially-minded types. You can see this by tracking the changes in asset classes around the election according to retail investor interest. More esoteric asset classes like junk bonds and market volatility were relatively unmoved. The SPDR Barclays High Yield Bond ETF (JNK: $37) stayed pretty much flat before and after, and ended the week flat. We also saw trading volumes below average for this ETF and for the asset class as a whole.
This observation leads us to a much more pressing issue: The market is losing steam. If you look at the S&P 500’s performance since the election, you see a hockey stick jump after the slight pre-results dip. That bull run peaked on December 13th and the index has not recovered from that level since. But it hasn’t crashed either (we’re less than 1% down from the all-time high). Instead, we’ve seen a tight range of around 2% movement from top to bottom in the last month - and the bottom was at the end of December, where tax-loss harvesting is to be expected. The market quickly recovered, but has stayed flat since the start of 2017 excluding the recovery on January 3rd.
What does this mean? It means the bull run has either stopped or is taking a pause. It may come back before turning into a bear trend. This will ultimately depend on upcoming economic data over the next few weeks, especially unemployment, CPI trends, and GDP estimates. None of these are expected to be weak, so a slight miss probably won’t cause a huge decline.
But markets are fickle. One bad note, however minor, can lead to a panic. We remember the start of 2014 when weak manufacturing data from China led to a huge market correction; investors were terrified that this single data point was the canary in the coal mine, and a broad global slowdown was in the works. This didn’t happen and the markets recovered, but this kind of irrational response to one data point is always possible after a long-term bull run loses steam. This bears watching right now.
For these reasons there is good reason to be cautious in the short term and keep some dry powder available to buy heavily discounted assets. When it comes to high yield, we remain constructive on all of our recommendations but the possibility of a major price correction in these assets in the short term is greater than it has been since last summer. Investors should keep this in mind.
Alongside junk bonds, most high yield asset classes showed little signs of life this week, staying mostly flat. One exception was The SPDR Dow Jones REIT ETF (RWR: $93, up 1%) as REITs continue their recovery from the summer sell-off that extended after Trump’s victory.
We’ve remained positive on selected REITs, and our picks once again outperformed the sector. Digital Realty Trust (DLR: $106, up 2%), Omega Healthcare Investors (OHI: $32, up 3%), Kimco Realty (KIM: $25, up 2%), Government Properties Trust (GOV: $19.80, up 2%), and Care Capital Properties (CCP: $25, up 1%) all saw higher price growth this week, and once again it’s interesting to note that the more volatile picks in our REIT portfolio did not go up significantly more than the lower-volatility ones. This is often a sign of complacency, but it seems a bit early to come to that conclusion for REITs. It does however suggest that one may want to wait for a correction before adding more in these assets, and instead look for alternatives in the high yield space.
For alternatives, The AllianzGI Equity and Convertible Income Fund (NIE: $18.80, down -1%) offers a yield as strong as REITs without leverage despite the fund’s strong holdings in high quality firms in various sectors. The fund’s discount is now over 12%, slightly lower than its historical average but not significantly so. There is a chance, but not a certainty, that a major market correction would lower this fund’s NAV and cause the discount to widen, bringing its price lower, which would make it a great buy. How low can it go? Assuming a 5% market correction and a premium widening to 17%, which is at the extreme end of the fund’s historical trend, we could see the stock fall to around $16.90. That’s a full 10% lower than its current level, so there is a lot of downside potential here. With that in mind, an investor who wants to invest cash now might be wise to buy some NIE, wait and track the markets for the next month, and buy more if the market falls by around 5%.
Keep in mind that these short-term market timing strategies are not for the faint of heart and involve some level of risk. Nonetheless, a post-bull run flat market like this very frequently results in a short-term correction. Making some liquid assets available for such an opportunity can often result in higher long-term returns and, most crucial for the high yield investor, provide opportunities to buy high quality assets and get a high dividend yield.
Good Investing,
Todd Shaver, Founder, CEO and Editor in Chief
The Bull Market Report
January 19, 2017

by Todd Shaver | Jan 19, 2017 | Monthly Newsletter Daily 6am if new
The Week Ahead
We are quickly approaching Donald Trump’s Friday inauguration. The event will mark a key inflection point for the markets. After the big rally in stocks and sharp sell-off in bonds following the November election, a plethora of expectations for the future will soon meet the reality of what is possible, as we move into the first 100 days of the President’s term.
This week we provide some insights on our latest thinking for Amazon, Facebook, Google, Netflix, Bristol-Myers Squibb, and Tesoro Petroleum.
Highlights From The Past Week
Recession Watch. History has shown us that a recession has generally occurred during the first term of a new president, especially when following a two-term presidency. Could this be the case this time around? The leading economic indicators (LEIs) are positive, and there has never been a recession without those indicators going negative. CEO confidence is moving up and consumer confidence is exploding, which seemingly points to the likelihood that a recession is not imminent. We are not big believers in patterns, to tell you the truth. So we are leaning towards a continued strong economy and a continued bullish stock market.
There may be a Trump backlash coming though. You know, the one we expected in November after the election. We have talked to a number of our subscribers and many of you are worried about this. Our suggestion is that if you are worried so much so that you are losing sleep, with commissions as low as they are in this century, it is easy enough for you to sell those stocks that make you nervous and look to some of the issues in our High Yield Portfolio. They are generally more stable than other stocks.
However, there is also talk that the Trump presidency could be the best thing Wall Street has seen in a long time. Cutting taxes, bringing back the huge horde of cash overseas, tackling the infrastructure building that needs to be done, etc.; these are all things that could help the economy. Dow 25,000 soon? Oh wait – we haven’t hit 20,000 yet! Stay tuned.
Interest Rates. If the economy continues to grow steadily, the US Treasury 10-year Note could hit 6% in four years, about the time of the next presidential election, up from its current level of 2.4%. Inflation and economic growth are already at levels similar to 2006, when interest rates were at that level.
Stronger dollar. The dollar holds a unique position in the global economy, and a rapidly rising dollar exchange rate has historically caused something somewhere in the global economy to break. Those in emerging markets that have borrowed in dollars face the reality of a liability stream that has become more expensive to repay. Meanwhile, the second largest economy on the planet, China, has informally pegged the yuan to the dollar. A stronger dollar generally means a stronger yuan; a stronger yuan means a less competitive export sector for an economy that is all about trade.
BMR Companies and Commentary
Amazon (AMZN: $817, +3% for the week)
JP Morgan Chase is offering a new, co-branded Visa rewards card through Amazon that offers compelling rewards for both Amazon Prime purchases and all other purchases outside of Amazon. Specifically, the new Chase card offers 5% cash back on all Amazon purchases by eligible Amazon Prime members. This deal marks another win for Amazon deepening their existence in banking.
How about the core business of Retailing? What started out as an online bookseller is now on pace to overtake Macy’s as the world’s largest apparel retailer, a startling development when you remember that e-commerce was once considered an impossible way to sell clothing. Amazon has reportedly recorded record holiday season sales at the same time that traditional department stores, including Macy’s, Sears, and Kohl’s, have reported declines. These companies aren’t adding thousands of new workers like Amazon. To the contrary, Macy’s plans to close 100 stores to improve profitability, and Sears has sold its Craftsman tools line for $900 million to raise cash.
BMR Take: Amazon is currently not far from its all-time high of $844, set in October. There is still the potential for upside for investors here, and the stock could go even further, perhaps passing the $1,000 mark sometime in 2017 or 2018.
Facebook (FB: $128, +4%)
Facebook has underperformed the Nasdaq since the company’s 3Q16 earnings report, due to a number of factors, including concerns about slowing growth, heightened expenses in 2017, and sector rotation out of Technology.
Investors have also cited concern about the headwind from a possible 1Q17 IPO of Snap. As far as the competitive risks of new more exciting Tech IPOs stealing away investors from Facebook, any impact is likely to be temporary and potentially more modest than investors fear. Press reports suggest that Snap (aka Snapchat) was considering an IPO as early as March at a valuation as high as $40 billion. Given that Snap’s IPO will represent the largest tech IPO since Alibaba went public in 2014, some investors have begun to question how the issuance may impact existing public market Tech stocks and in particular its closest comp, Facebook.
BMR Take: Yes, it has underperformed since November, but it has been on a TEAR since the start of the year. Be advised that the upcoming Snapchat IPO will be all over the headlines, but don’t sell your Facebook over this. Facebook’s long term prospects are fantastic. Facebook is fast approaching its all-time high of $133.50 set in October. And fast approaching 2 billion users. The company adds 1 million subscribers every two days. With growth of 35% a year projected for the next two years, the stock is not over-priced.
Netflix (NFLX: $134, +2%)
A big name stock analyst that was short Netflix covered his call this week. It’s nice to see them come join our camp. There is so much to like about Netflix. In fact, the stock hit an all-time high of $133.93 this week!
On the heels of new details about Hulu’s upcoming live TV offering (pricing, content lineup, etc.), Netflix reiterated that it has no plans to make any other meaningful changes to its business model or content strategy, stressing that the simplicity of its offering is a key advantage.
The company has also evaluated the merits of an ad-supported model but continues to believe that focusing on its core business provides the greatest return on investment. Looking back at Netflix’s pricing changes and the un-grandfathering it worked through in 2016, the company feels good about its pricing power and is satisfied with the outlook. They also expect future price increases to be more staggered by country/region rather than by universal global changes.
While Netflix intends to keep pricing relatively consistent globally, in Japan, for instance, it has a lower price for its lowest tier ($5/month) in order to address Netflix’s more limited brand recognition in that market (i.e., to better spur new user adoption).
Netflix now has 50%+ of its content catalog available for downloads on Android and iOS today, and it expects that percent to increase. The company is increasingly self-producing content, which it believes can ultimately be 30%+ cheaper than licensing. Like what began in 3Q16, this will continue to impact cash burn in the near-term given the up-front costs associated with producing content.
BMR Take: Netflix is changing the game for television. We continue to believe they are on a long term path to 2020 EPS of $10 where a 20x PE multiple supports a $200+ valuation.
Google (GOOG: $808, flat)
Speaking of the future of media, Google’s YouTube is just crushing it. We highlight the following data points tracking YouTube through December 2016:
--- YouTube worldwide video views for the top 1000 publishers in December 2016 totaled 70 billion, which was up dramatically from last year. This brings total cumulative views on YouTube for these top publishers to 1.97 trillion – wow. On a trailing three-month basis, total views were 190 billion - these numbers are astronomical! In November 2016 alone, videos uploaded to YouTube generated 147 Billion views, both organic and paid.
--- The total number of subscriptions to the top 1000 YouTube video publishers’ channels was 3.9 billion at the end of December, adding 120 million channel subscriptions in the last month alone, up nearly 70% from this time last year.
--- The total number of videos available on YouTube from these top publishers was 5 million at the end of December, accounting for 19% more content on the platform than in December 2015.
BMR Take: If these numbers don’t describe a healthy business, we don’t know what does. We view Google as a core holding, given: 1) the company remains a top player in the internet space 2) management's track record of execution, 3) the potential to maintain double-digit earnings growth for many years, and 4) attractive valuation.
Tesla (TSLA: $238. Up 4%) has been on a tear. At $182 on December 1st, the stock is up over 30%. The company just opened a showroom in Aspen and the place is packed. I met a friend on the street on Friday and motioned for him to come in. Guess what: He is taking a test drive next week and might buy one of the Model X’s that start at $85,000. 0-60 in 2.9 seconds. Call it a cult, or call it what you will, but this company is real and this company is exciting. With Saturday’s Space X launch of 10 satellites on the Falcon 9 and then landing the rocket on the drone ship in the ocean, Elon Musk’s star is riding high. Musk sent out this Tweet:
Elon Musk @elonmusk
Mission looks good. Started deploying the 10 Iridium satellites. Rocket is stable on the droneship.
BMR Take: We’ve said many times before in these pages that the stock is not for the conservative and that the stock could go to $150 before it goes to $250 due to its volatility, but we will tell you that this stock could go to $400 this year or next. We hereby raise the Price Target from $250 to $290 and raise the Sell Price from $150 to $180.
FAANG Stocks Bite Back Adding $90 Billion In Market Cap Over the Past Two Weeks. Technology stocks have found a cure for whatever was plaguing them during the early stages of the Donald Trump bull market. In especially brisk health is the FAANG block of Facebook, Amazon, Apple, Netflix and Google, which have rallied at 3.8% on average this week, poised for their best performance since October. About $85 billion has been added to their value as investors rotate back into post-election laggards. FAANG stocks were oversold after the election, although there’s likely no real impact from a Trump administration on the highest quality internet names. These five stocks could potentially outperform in 2017, despite pretty clear skepticism among almost all investors, who see a sustained rotation away from growth stocks in the wake of the Trump election. Not us. We are sticking with them. Like glue.
Alphabet (GOOG: $802, up $30)
Apple (AAPL: $119, up $3)
Facebook (FB: $127, up $12)
Amazon (AMZN: $808, up $58)
Netflix (NFLX: $140, up $16)
The Border Tax
Notes at the Margin
Philip K. Verleger, Jr.
Former Director of the Office of Energy Policy
at the United States Department of Treasury
The House of Representatives’ Republican leadership seems set on pushing the plan through despite suggestions from some experts that it is a bad idea. Indeed, their determination to pass the law seems palpable even though major economic players such as James Bullard, president of the Federal Reserve Bank of St. Louis, have admitted publicly that they do not understand the concept.
Still, for the world’s oil industry, it is critical to understand the border tax quickly. Why? Because its passage will likely change oil flows completely. Most US oil producers would have every incentive to sell at home and none to export. Bluntly speaking, for oil the law’s passage is pure mercantilism. Exporters from Mexico, Canada, and the rest of the world could be shut out.
How might this happen? Start with the fact that the “Made in America” price could be 25% higher than world prices. The boost occurs because US producers would pay no tax if they export oil while US importers would pay a 20% tax. This means US producers would receive $50 per barrel if they export. On “paper,” at the margin they would have to pay a 20% tax if they sell to domestic buyers. This means those buyers would have to pay $62.50 per barrel in a $50-per-barrel world for the domestic producer to net $50.
The High Yield Corner
By Michael Foster
Special to The Bull Market Report
It was a quiet week for the markets, with the S&P 500 ending flat with few dramatic days. Donald Trump’s odd press conference, in which the president-elect took a victory lap after his election win but failed to provide clarity on fiscal spending plans or an economic blueprint, caused a brief upset to the markets, but strong results from financial firms on Friday offset the macro worries quickly.
With that in mind, it’s unsurprising that the market was mostly quiet for high yield assets. The UBS BDC ETF (BDCS: $23) was mostly unchanged this week after accounting for its dividend payout, while the SPDR Barclays High Yield Bond ETF (JNK: $37) also saw no major move in any direction. Impatient traders may be frustrated at the lack of volatility, but we are pleased. Junk bonds and BDCs had a tremendous year in 2016, causing many funds and companies in these spaces to become worryingly overvalued. If we don’t see an aggressive run-up in pricing this year, we would be in a better position to hold our positions, add more on short-term dips, and avoid the need to sell overbought assets without viable alternatives for our cash.
This situation is particularly good for the PIMCO Dynamic Income Fund (PDI: $28, down -1%), which fell slightly this week but still has excellent dividend coverage and growth potential. After the fund paid out a massive special dividend last month (which we predicted), the fund is now in a position to accumulate new investment income and pay another big special at the end of this year. We fully expect this to happen, so we want to hold on. There’s only one problem: this fund's premium to its NAV is around 9%, bringing us dangerously close to a point where we would need to offload and choose another, lower-priced bond fund. We’d rather avoid making that trade because there are maybe two funds in the world that can match this fund in terms of yield, portfolio quality, and management acumen. As it stands, we can avoid choosing an alternative to the Pimco fund and enjoy its massive yield.
While things were quiet in BDCs and corporate bonds, there was a bit more action in municipal bonds, although this sleepy asset class is notorious for its low volatility and small moves. The iShares S&P National AMT-Free Municipal Bond Fund (MUB: $109) was flat this week, but our municipal bond picks both outperformed the broader index. Invesco Municipal Trust (VKQ: $12.58) and the Nuveen AMT-Free Fund (NVG: $14.63) both rose over 1% this week thanks to the market finally realizing these funds were underpriced relative to their portfolio quality. It makes little sense for these funds to offer discounts to their NAV, so we expect both to continue to rise in price as municipal bonds strengthen from the blood bath of 2016. For this reason we recommend a solid weighting of your overall portfolio in these bond funds for the foreseeable future.
Our biggest winner this week was AstraZeneca (AZN: $29, up 3%), which has been recovering from the broad panic that President-elect Trump is going to reign in drug prices and pressure Pharmaceutical firms’ profit margins. While a lot of talk before the election from both sides of the aisle pressured Pharma firms, the lack of clarity in Trump’s speech this week was ironically a positive for AstraZeneca. Investors are becoming more certain than ever that promises to reign in drug prices will get watered down heavily before they ever become a legislative reality - and that might never even happen. With that in mind, the big dip that this and other Pharma companies have suffered over the last year is becoming a buying opportunity. We’re pleased to keep AstraZeneca in our high yield portfolio for this very reason.
There is one sector that really took a beating this week: REITs. The SPDR Dow Jones REIT ETF (RWR: $93, down 2%) was the biggest loser of all the indices we track, but our REIT picks outperformed by a substantial margin. Even high-risk and overly volatile Government Properties Trust (GOV: $20, down 1%) saw declines only a fraction of the REIT sector as a whole. This is rare, as Government Properties Trust is notorious for rising more aggressively and falling more precipitously than REITs more broadly.
With one exception, our other REITs fared as well or better. Omega Healthcare Investors (OHI: $32, down 1%) and Care Capital Properties (CCP: $25, down 1%) fell slightly alongside the market, but Digital Realty Trust (DLR: $102) held on to its 2016 gains and ended the week flat. Digital Realty Trust has seen some of the highest capital gains of any of our high yield picks, but we aren’t selling quite yet. As we lap the year since we picked this stock and short-term capital gains become long-term capital gains, we might revisit this stock and consider changing our recommendation to a sell if (and only if) its price rises too fast and its upcoming earnings results shows weak FFO growth. This is something for us to keep our eye on.
Finally, our REIT under-performer is a surprising one: Kimco Realty (KIM: $25, down 3%). Usually a solid and low volatile firm, Kimco slid this week despite getting an upgrade by Raymond James. Kimco also announced that its next dividend will match its last one: 27 cents per share, which is up over 6% from just four months ago. The sell-off may be a result of impatient investors disappointed that we aren’t seeing another rate hike, although Kimco tends to do just one rate hike per year, and they did their last one last quarter. We’re shrugging at this dip, although it does mean Kimco is now flat on a year-over-year basis. Still, we aren’t in Kimco for capital gains, we’re in it for the dividend, so if we see Kimco start to fall further we might recommend doubling down.
All in all, a peaceful week for high yield, which is great for us since we’re getting paid 8% to hold these names. It’s also nice to see high yield resist growing market certainty that an interest rate hike is around the corner. If this trend continues for a few more weeks, we could easily expect high yield to be one of the strongest asset classes of 2017.
This coming week: Watch for a new research report on a fast-growing, powerful company in the virtualization and cloud infrastructure solutions space. Sounds pretty technical, doesn’t it? We’ll make it simple and understandable for you. As always.
Good Investing,
Todd Shaver, Founder, CEO and Editor
The Bull Market Report
January 17, 2017
by Todd Shaver | Jan 17, 2017 | Earnings Preview 6 PM
Goldman Sachs (GS: $239)
Earnings Date: Wednesday, 4:00 PM ET
Consensus: 4Q16
Revenues: $7.7B
EPS: $4.82
Year Ago Quarter Results
Revenues: $7.2B
EPS: $1.27
Key Things to Watch For in the Quarter
Analysts throughout Wall Street estimate that Goldman Sachs will report a drastic increase in earnings per share by 280% to $4.82 along with a 7% increase in revenue to $7.7 billion in the fourth quarter of 2016. The election played a large part in the performance of bank stocks, which received positive response. With relaxed regulations on the horizon for the Financial sector, analysts expect to see gains from trading desks across Wall Street. We remain bullish on Goldman for their leadership, strategy, and their impeccable intelligence.
------------------------------------------------------------
Kinder Morgan (KMI: $22.50)
Earnings Date: Wednesday, 4:00 PM ET
Consensus: 4Q16
Revenues: $3.5B
EPS: $0.19
Year Ago Quarter Results
Revenues: $3.6B
EPS: $0.13
Key Things to Watch For in the Quarter
Wall Street analysts estimate earnings growth of 45% to $0.19 for Kinder Morgan in the fourth quarter with a decrease in revenues of 3% to $3.5 billion. The company’s forward P/E ratio (measure of price-to-earnings using forecasting earnings) of 31 is comparable to many of its competitors, and with Mr. Trump in office the outlook for the gas and oil pipeline industry is very bright. Kinder Morgan’s shares have nearly doubled over the course of the last year, after hitting the $11 level in January, supporting our bullishness even further.
---------------------------------------------------------
Netflix (NFLX: $133)
Earnings Date: Wednesday, 4:00 PM ET
Consensus: 4Q16
Revenues: $2.5B
EPS: $0.13
Year Ago Quarter Results
Revenues: $1.8B
EPS: $0.10
Key Things to Watch For in the Quarter
Analysts estimate a healthy fourth quarter for Netflix, with an estimated 30% increase in earnings per share and a 4% increase in revenues. The country’s growing economy and bull market have provided Netflix stockholders with significant gains over the past year, with shares climbing almost 25%. As a major leader in the streaming business, Netflix will continue to outperform its competitors and the market into the new year.