January 30, 2018
by Todd Shaver | Jan 30, 2018 | Earnings Preview 12 PM
Equity Residential (EQR: $61)
Bull Market Report Target Price: $85
Bull Market Report Sell Price: $55
Earnings Date: Tuesday, After market close
Consensus: 4Q17
Revenues: $625 million
EPS: $0.36
Year Ago Quarter Results
Revenues: $605 million
EPS: $0.75
Key Things to Watch For in the Quarter
Analysts expect Equity Residential to report a 3% increase in revenues with a 50% decrease in earnings per share. Despite having beat estimates in each of the past four quarters, the stock is only trading 2% above its price this time last year. Nearly all of the stock’s 15% gains for the year have been wiped out since November with the oversupply issues in the real estate market. We believe the stock is oversold at its current levels, and will see support in the $60 range.
---------------------------------------------------------------------
Eli Lilly (LLY: $86)
Bull Market Report Target Price: $96
Bull Market Report Sell Price: $82
Earnings Date: Wednesday, 9:00 AM ET
Consensus: 4Q17
Revenues: $6.0 billion
EPS: $1.07
Year Ago Quarter Results
Revenues: $5.8 billion
EPS: $0.95
Key Things to Watch For in the Quarter
Eli Lilly is expected to report a 3% increase in revenues and a 13% increase in earnings per share for 4Q17. The stock has beat estimates in three of the past four quarters, and is currently trading 17% above its price levels from this time last year. The stock saw a bit of resistance at $86 earlier this year, and it had recently broken through, but with the tough market of the last two days, the stock is back to $86. This pharmaceutical company invests heavily in its research and development, which will drive its future sales and earnings growth.
---------------------------------------------------------------------
Facebook (FB: $186)
Bull Market Report Target Price: $190
Bull Market Report Sell Price: $155
Earnings Date: Wednesday, 5:00 PM ET
Consensus: 4Q17
Revenues: $12.5 billion
EPS: $1.95
Year Ago Quarter Results
Revenues: $8.8 billion
EPS: $1.41
Key Things to Watch For in the Quarter
Analysts expect Facebook to report a 42% increase in revenues and a 38% increase in earnings per share for 4Q17. Facebook has beaten estimates in three of the past four quarters which has been reflected in the stock’s 42% appreciation over the past year. Facebook’s growth over the past years has been unprecedented for a company of its size. It truly is adhering to its mission of creating a more connected world. We look forward to seeing what kind of developments CEO Mark Zuckerberg has in store for the connected world in 2018. We know it will be good.
---------------------------------------------------------------------
PayPal Holdings (PYPL: $83)
Bull Market Report Target Price: $87
Bull Market Report Sell Price: We would not sell PayPal
Earnings Date: Wednesday, 5:00 PM ET
Consensus: 4Q17
Revenues: $3.6 billion
EPS: $0.52
Year Ago Quarter Results
Revenues: $3.0 billion
EPS: $0.42
Key Things to Watch For in the Quarter
We are looking for a 20% increase in its sales and a 24% increase in its earnings per share for the 4th quarter of 2017. The stock has been on a tear since last year, returning investors a 110% capital appreciation since this time last year. The stock has gone nowhere but up since posting earnings that have exceeded expectations in the past four quarters. PayPal’s market cap is just over $100 billion, making it the largest publicly traded electronic payments company in the world. We look forward to seeing what PayPal has to offer as they continue to lead this growing industry.
---------------------------------------------------------------------
Microsoft (MSFT: $93)
Bull Market Report Target Price: $92
Bull Market Report Sell Price: We would not sell Microsoft
Earnings Date: Wednesday, 5:30 PM ET
Consensus: 2Q18
Revenues: $28 billion
EPS: $0.86
Year Ago Quarter Results
Revenues: $26 billion
EPS: $0.80
Key Things to Watch For in the Quarter
Microsoft is expected to report an 8% increase in revenues and a 7.5% increase in earnings per share for 2Q18. Microsoft’s ability to beat analyst estimates has been reflected in the stock’s 44% increase over the past year. The firm continues to produce high quality hardware and software, and has a very good understanding of their customer base. Microsoft also allocates an incredible amount of capital to research and development, with its most recent announcement being a push into quantum computing, which some say could be similar to the internet revolution in the 1990s.
---------------------------------------------------------------------
Blackstone Group (BX: $36)
Bull Market Report Target Price: $36
Bull Market Report Sell Price: $31
Earnings Date: Thursday, 11:00 AM ET
Consensus: 4Q17
Revenues: $3.3 billion
EPS: $6.43
Year Ago Quarter Results
Revenues: $2.8 billion
EPS: $5.25
Key Things to Watch For in the Quarter
Blackstone is expected to report an 18% increase in revenue along with a 22% increase in its earnings per share for 4Q17. Blackstone has exceeded analyst estimates in three of the past four quarters, and has seen its stock appreciate 17% over the past year. Technically speaking, the stock has underperformed both the market and the sector, and we believe this is a huge mispricing by the market. Blackstone currently trades at a PE of 15 and yields 5%. At these price levels the stock looks like a steal compared to its competitors.
---------------------------------------------------------------------
United Parcel Service (UPS: $129)
Bull Market Report Target Price: $125
Bull Market Report Sell Price: $106
Earnings Date: Thursday, Exact Time not Available
Consensus: 4Q17
Revenues: $18 billion
EPS: $1.66
Year Ago Quarter Results
Revenues: $17 billion
EPS: $1.63
Key Things to Watch For in the Quarter
Analysts expect UPS to report a 6% increase in revenues and a 2% increase in earnings per share for 4Q17. Despite beating estimates in three of the past four quarters, the stock has slightly underperformed the overall market. The stock has appreciated 24% since this time last year, and we expect to see similar returns moving forward as the demand for logistical services increases. Although we remain bullish on the stock, we are keeping a close eye on Amazon as it begins to roll out its own logistics services, posing a potential threat to UPS.
The stock has passed our Target of $125, and we believe the stock will go higher, as long as the market holds here and moves higher in the coming months. We hereby raise our Target to $142 and our Sell Price to $118.
---------------------------------------------------------------------
Alphabet (GOOG: $1,170)
Bull Market Report Target Price: $1,450
Bull Market Report Sell Price: We would not sell Google
Earnings Date: Thursday, 4:30 PM ET
Consensus: 4Q17
Revenues: $32 billion
EPS: $10.00
Year Ago Quarter Results
Revenues: $26 billion
EPS: $9.36
Key Things to Watch For in the Quarter
We are looking for a 31% increase in revenues and a 7% increase in earnings per share for 1Q18. The company has beaten estimates in three of the past four quarters, which has been reflected in the stock’s 45% appreciation since this time last year. The stock currently boasts a market cap of $815 billion, making it one of the largest publicly traded companies in the world. Although Alphabet is best known for its Google Search Engine, the company touches all aspects of technology from cloud computing to its most recent Television Streaming service through YouTube.
---------------------------------------------------------------------
Apple (AAPL: $165)
Bull Market Report Target Price: $194
Bull Market Report Sell Price: We would not sell Apple
Earnings Date: Thursday, 5:00 PM ET
Consensus: 1Q18
Revenues: $87 billion
EPS: $3.81
Year Ago Quarter Results
Revenues: $78 billion
EPS: $3.36
Key Things to Watch For in the Quarter
We expect to see a 13% increase in earnings per share along with an 11% increase in sales for 1Q18, despite less than ideal results with the release of the iPhone X. The stock has beaten estimates in each of the past four quarters, and has appreciated 38% since this time last year. We also saw Warren Buffet add more stock to his portfolio, which should definitely not be overlooked. We expect to see growth in iPhone and iPad sale over the next year, and remain bullish on the stock. The cash repatriation should begin soon and that will produce some changes – in the dividend and in their outlook on buying new technology firms.
---------------------------------------------------------------------
Visa (V: $123)
Bull Market Report Target Price: $123
Bull Market Report Sell Price: We would not sell Visa
Earnings Date: Thursday, 5:30 PM ET
Consensus: 1Q18
Revenues: $4.8 billion
EPS: $0.99
Year Ago Quarter Results
Revenues: $4.4 billion
EPS: $0.86
Key Things to Watch For in the Quarter
Visa is expected to report a 9% increase in revenues and a 15% increase in earnings per share for 1Q18. Visa has beaten estimates in each of the past four quarters, and seen a 50% appreciation in its stock since this time last year. Despite paying a relatively small dividend, the stock still trades at a PE of 44, suggesting it is fairly valued compared to its competitors. We are confident in Visa’s ability to drive earnings growth through the new year. This $280 billion market cap company is a long term hold.
---------------------------------------------------------------------
Amazon (AMZN: $1,420)
Bull Market Report Target Price: $1,500
Bull Market Report Sell Price: $1,225
Earnings Date: Thursday, 5:30 PM ET
Consensus: 4Q17
Revenues: $60 billion
EPS: $1.84
Year Ago Quarter Results
Revenues: $44 billion
EPS: $1.54
Key Things to Watch For in the Quarter
Analysts expect Amazon to report a 36% increase in revenues and a 19% increase in earnings per share for 4Q17. Despite having only beaten estimates in three of the past four quarters, the stock currently trades 70% higher than its levels this time last year. Amazon continues to lead the charge in the online retail space, and we firmly believe in the longevity of the firm. Although the company trades at a very high PE of 350, we believe this is explained by the company’s inherent ability dominate and revolutionize the Retail industry.
---------------------------------------------------------------------
AstraZeneca (AZN: $36)
Bull Market Report Target Price: $42
Bull Market Report Sell Price: $32
Earnings Date: Friday, exact time not available
Consensus: 4Q17
Revenues: $5.4 billion
EPS: $0.45
Year Ago Quarter Results
Revenues: $5.6 billion
EPS: $0.61
Key Things to Watch For in the Quarter
AstraZeneca is expected to report a 4% decrease in revenues and a 26% decrease in earnings per share for 4Q17. Despite the lack of top line growth, the stock has still managed to beat analyst estimates in each of the past four quarters, and has shown 30% year-over-year appreciation as a result. The stock currently trades at a PE of 26, which is relatively cheap compared to other firms in healthcare which average around 40. The stock pays a 4% dividend, and has room to grow in 2018.
We’re not liking this new development with a slowdown in revenues and earnings and are re-evaluating our take on this stock. More to come this weekend. In the meantime, we are moving our Sell Price to $34.
October 23, 2017
by Todd Shaver | Oct 23, 2017 | Earnings Preview 12 PM
Eli Lilly (LLY: $88)
Bull Market Report Target Price: $88
Bull Market Report Sell Price: $76
Earnings Date: Tuesday, 9:00 AM ET
Consensus: 3Q17
Revenues: $5.5 billion
EPS: $1.03
Year Ago Quarter Results
Revenues: $5.2 billion
EPS: $0.88
Key Things to Watch For in the Quarter
Eli Lilly is expected to report a 17% increase in earnings per share and a 5% increase in revenues for 3Q17. This moderate growth in revenues accompanied by a strong growth in EPS indicates a reduction of the firm’s costs. Although Lilly has only beaten analyst estimates in two of the past four quarters, the stock still trades up 12% since this time last year. By cutting costs in SG&A Eli Lilly has freed up capital for R&D, which will help drive future sales and contribute to the company’s prolonged growth.
Our Target has been reached, so we hereby raise it to $96.
-----------------------------------------------------------------------------------------------------------------------------
Equity Residential (EQR: $66)
Bull Market Report Target Price: $85
Bull Market Report Sell Price: $55
Earnings Date: Tuesday, 4:00 PM ET
Consensus: 3Q17
Revenues: $620 million
EPS: $0.33
Year Ago Quarter Results
Revenues: $605 million
EPS: $0.56
Key Things to Watch For in the Quarter
Analysts expect Equity Residential to report a 2% increase in revenues and a 41% decrease in earnings per share for 3Q17. The stock has beaten estimates in each of the past four quarters, and has still managed to appreciate 8% over the past year. This is most likely a result of the shrinking of the company’s earnings over the past two years. The stock is currently trading 4% off its 52-week high and has been trading with lower volume than it did in the beginning of the year, indicating it could be oversold.
-----------------------------------------------------------------------------------------------------------------------------
Visa (V: $107)
Bull Market Report Target Price: $110
Bull Market Report Sell Price: We would not sell Visa
Earnings Date: Wednesday, 8:00 AM ET
Consensus: 3Q17
Revenues: $4.6 billion
EPS: $0.85
Year Ago Quarter Results
Revenues: $4.2 billion
EPS: $0.78
Key Things to Watch For in the Quarter
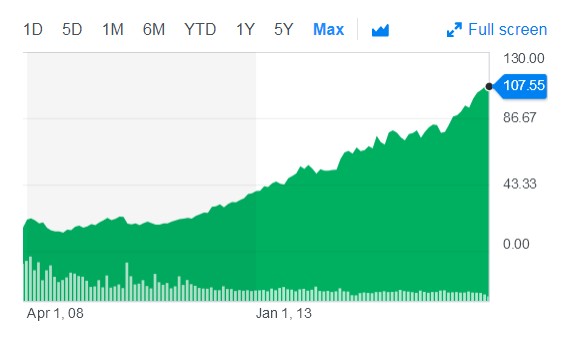
Analysts estimate Visa will report a 9% increase in revenues and a 9% increase in earnings per share for 3Q17. Visa has surpassed estimates in each of the past four quarters, contributing to the stock’s 30% appreciation since this time last year. Visa has seen significant increase in sales over the past few years and we expect this growth to continue as consumers shift from cash to online and credit card payments.
How’s this for a nice looking chart over the past five years? Where would you say it is headed?
-----------------------------------------------------------------------------------------------------------------------------
United Parcel Service (UPS: $120)
Bull Market Report Target Price: $125
Bull Market Report Sell Price: $106
Earnings Date: Thursday, 8:00 AM ET
Consensus: 3Q17
Revenues: $15.6 billion
EPS: $1.45
Year Ago Quarter Results
Revenues: $15.0 billion
EPS: $1.44
Key Things to Watch For in the Quarter
UPS is expected to report a 4% increase in revenues and no change in earnings per share for 3Q17. Despite only having beaten estimates in two of the past four quarters, the stock has still managed to climb 10% since this time last year and is currently trading 16% above its 52-week low. Companies like UPS and FedEx are perfectly positioned to benefit from the growing trend of online shopping. Growth in e-commerce has been accelerating over the past few years, up 16% from 2016 alone, and shows no signs of slowing down. The stock currently yields 2.75% making it a good investment for investors who are seeking both growth and income.
-----------------------------------------------------------------------------------------------------------------------------
Celgene (CELG: $123)
Bull Market Report Target Price: $150
Bull Market Report Sell Price: $125
Earnings Date: Thursday, 9:00 AM ET
Consensus: 3Q17
Revenues: $3.4 billion
EPS: $1.87
Year Ago Quarter Results
Revenues: $3.0 billion
EPS: $1.58
Key Things to Watch For in the Quarter
Celgene is expected to report a 13% increase in sales and a 18% increase in earnings per share for 3Q17. The stock has beaten analyst estimates in each of the past four quarters and was up nearly 50% this year until recent weeks when it announced that it would not continue to phase 3 trials for its Crohn’s disease drug. The stock pulled back 17% on the announcement and opened a window of opportunity for investors who felt the stock was overbought at its previous levels. Celgene continues to invest heavily in R&D and we expect it will continue to produce growing sales with the rest of its pipeline.
The stock is below our Sell Price and we covered Celgene in our report that went out Sunday evening the 22nd. Please review for our thoughts on the stock.
-----------------------------------------------------------------------------------------------------------------------------
Bristol-Meyers Squibb (BMY: $64)
Bull Market Report Target Price: $77
Bull Market Report Sell Price: $51
Earnings Date: Thursday, 10:30 AM ET
Consensus: 3Q17
Revenues: $5.2 billion
EPS: $0.77
Year Ago Quarter Results
Revenues: $5.0 billion
EPS: $0.77
Key Things to Watch For in the Quarter
Analysts estimate that Bristol Meyers will report a slight 4% increase in sales and no change in earnings per share for 3Q17. Bristol has beaten estimates in three of the past four quarters, contributing to the stock’s 30% gain over the past year. The company generates about 30% of its revenues from oncology related drugs, and we expect the stock to continue growing as it gains more market share.
We hereby raise our Sell Price from $51 to $59.
-----------------------------------------------------------------------------------------------------------------------------
Alphabet (GOOG: $978)
Bull Market Report Target Price: $1100
Bull Market Report Sell Price: We would not sell Alphabet
Earnings Date: Thursday, 4:30 PM ET
Consensus: 3Q17
Revenues: $27 billion
EPS: $8.33
Year Ago Quarter Results
Revenues: $22 billion
EPS: $9.06
Key Things to Watch For in the Quarter
Analysts estimate that Alphabet will report a 22% increase in revenues and an 8% decrease in earnings per share for 3Q17. The stock is up 21% over the past, which has been driven by its ability to beat analyst estimates in three of the past four quarters and to grow revenues and earnings. Alphabet’s institutional owners have been increasing their positions in the company over the past six months by 3%, indicating they believe in the long-term success of the business. Alphabet has recently released new products that have put pressure on some of the largest tech companies like Apple and Samsung.
Our Price Target is $1000, but we think somehow that has been an uncorrected error and we believe it was and should be $1100. Thus we hereby make the change. The all-time high is $997 set just last week, and if the stock market remains stable, we expect to see the stock blow through $1000 and move significantly higher by the end of the year.
-----------------------------------------------------------------------------------------------------------------------------
First Solar (FSLR: $49)
Bull Market Report Target Price: $55
Bull Market Report Sell Price: $39
Earnings Date: Thursday, 4:30 PM ET
Consensus: 3Q17
Revenues: $800 million
EPS: $0.85
Year Ago Quarter Results
Revenues: $ 690 million
EPS: $1.22
Key Things to Watch For in the Quarter
While First Solar is expected to increase its revenues by 15%, analysts estimate that earnings per share will decrease by 30% for 3Q17. The stock has beaten earnings estimates in each of the past four quarters. We expect First Solar to continue with its positive performance as the year ends and on into 2018 as well.
This has been a long slog with this firm. We have been patient and have stuck with it and now the stock is moving up to where it belongs. This is a great company management is on the right path and the firm is certainly in the right business.
-----------------------------------------------------------------------------------------------------------------------------
Amazon (AMZN: $972)
Bull Market Report Target Price: $1,100
Bull Market Report Sell Price: $900
Earnings Date: Thursday, 5:30 AM ET
Consensus: 3Q17
Revenues: $42 billion
EPS: $0.52
Year Ago Quarter Results
Revenues: $33 billion
EPS: $0.03
Key Things to Watch For in the Quarter
Amazon is expected to report a 27% increase in sales and a 94% decrease in earnings per share for 3Q17. We expect this large reduction in EPS is from the company’s increased spending on R&D, which should pay off with large revenue increases down the road. Despite having only beaten estimates in two of the past four quarters, the stock is still up 17% since last year. In each of the two quarters it missed, the stock pulled back no more than 5% and provided investors with an entry opportunity. With the firm’s continued domination of e-commerce, we remain bullish on Amazon here at The Bull Market Report.
-----------------------------------------------------------------------------------------------------------------------------
Microsoft (MSFT: $79)
Bull Market Report Target Price: $84
Bull Market Report Sell Price: We would not sell Microsoft
Earnings Date: Thursday, 5:30 PM ET
Consensus: 3Q17
Revenues: $23 billion
EPS: $0.72
Year Ago Quarter Results
Revenues: $22 billion
EPS: $0.72
Key Things to Watch For in the Quarter
Analysts expect that Microsoft will report a 4.5% increase in sales and no change in earnings per share for 3Q17. The stock has climbed 30% over the past year, especially having beaten estimates in each of the past four quarters. Microsoft is another great investment for those seeking both growth and income. The stock has appreciated 180% over the past five years while paying out a 2% dividend. In addition to improving product sales, Microsoft has made a number of upgrades on its Windows operating system, driving growth over the years.
-----------------------------------------------------------------------------------------------------------------------------
Ventas (VTR: $63)
Bull Market Report Target Price: $82
Bull Market Report Sell Price: $61
Earnings Date: Friday, 8:00 AM ET
Consensus: 3Q17
Revenues: $880 million
EPS: $0.45
Year Ago Quarter Results
Revenues: $865 million
EPS: $0.42
Key Things to Watch For in the Quarter
Ventas is expected to report a slight 2% increase in revenues and a 7% increase in earnings per share for 3Q17. Despite having beaten estimates in three of the past four quarters, the stock is down 8% since last year. With most of its properties focused in senior housing and healthcare facilities, Ventas’s long-term growth looks very positive. Ventas owns a highly diversified portfolio of nearly 1,300 seniors housing and healthcare properties in the United States, Canada and the United Kingdom. The underperformance of the stock has given investors the opportunity to enter into this high dividend yielding (5%) growth stock.
October 1, 2017

by Todd Shaver | Oct 1, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
Welcome to October! Boo! October can be a scary time in more ways than just Halloween. October has a special place in finance, known as the October effect, and is one of the most feared months in the financial calendar. Why? Check the history. There was The Panic of 1907 (October), where multiple bank runs and heavy panic selling occurred on the stock exchange. There was The Crash of 1929 (October), where stock market slides set records. There was Black Monday in 1987 (October), when automatic stop-loss orders and financial contagion gave the market a thorough throttling as a domino effect echoed across the world in a quick 22% drop. In summary, keep a close eye on what’s around the next corner, and don’t get surprisingly spooked by market volatility.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks where you can still make good money, including: Celgene, BlackRock, Facebook, UPS, Home Depot, PayPal, and Government Properties Income Trust.
BMR Companies & Commentary
BlackRock (BLK: $447, up 3% - all prices are for the week)
BlackRock was upgraded to buy this week by Goldman Sachs and placed on the conviction buy list. We love to see Goldman following The Bull Market Report into the stocks we like. This demonstrates the quality of our research and the sincere value we price it at to you our dear subscriber. In other words, it’s not $10,000 a year!
So why all the love for BlackRock right now? It really is as simple as this. The world of ETF investing is dominating the investment management business and BlackRock is the leading provider of ETF products.
BlackRock has $5.1 trillion of assets under management as of December 31, 2016. With employees in more than 30 countries who serve clients in over 100 countries across the globe, BlackRock provides a broad range of investment and risk management services to institutional and retail clients worldwide. The company’s flagship product line-up is the popular iShares exchange-traded funds (“ETFs”). These ETFs are used by everyone from tax-exempt institutions; to charities, foundations and endowments; official institutions such as central banks, sovereign wealth funds, supranationals and other government entities; taxable institutions, including insurance companies, financial institutions, corporations and third-party fund sponsors, and retail investors.
BMR Take: We think BlackRock is a compelling value trading at 17x next year’s consensus EPS estimate of $25. But don’t take it from just us. One of the world’s best hedge funds, Third Point, just bought the stock and believes BlackRock is a “misunderstood franchise” with a massive 38% market share of exchange-traded funds. Third Point’s CEO said he thinks this acceleration in ETFs is just getting started and BlackRock is valued like a traditional asset manager, but it has much greater potential for structural revenue growth and operating margin expansion. We stand by our $510 price target and have already made some good ground on the path here since our initiation to the stock in late August at $415.
Price too high for you? Just buy 20 shares. Just buy 50 shares. Buy 11 shares – but get some BlackRock. Remember, the “price” is irrelevant. What if BlackRock split their stock 10-1 next week? Would that change your thinking because you now have 10 times as many shares at $44 a share? You answered correctly if you said – NO. Of course. The price of the stock would change nothing.
Celgene (CELG: $146, up 1%)
Celgene recently announced that the FDA has placed a partial clinical hold on five trials and a full clinical hold on one trial of the FUSION program for Imfinzi (durvalumab). This is not the best outcome for Celgene, but remember the company’s portfolio is broadly diversified so we view the development as a minor set-back not a game-changer. In fact, most analysts had not yet even been considering the financial impact of these drugs into their estimates. The trials subject to the hold are studying drugs for leukemia and lymphoma. We emphasize that the decision by the FDA was based on safety data derived from other trials involving drugs in patients with multiple myeloma in combination with immunomodulatory agents.
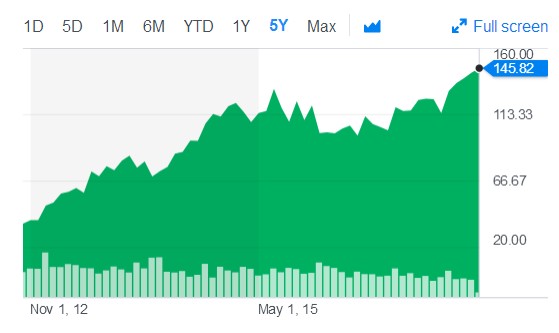
BMR Take: We expect Celgene’s four blockbuster drugs (Revlimid, Abraxane, Otezla, and Pomalyst) to drive revenues of over $13 billion in 2017, and over $21 billion in 2020, while the recent acquisitions of Receptos and Delinia as well as investments in collaborators like Acceleron, Epizyme, Agios, and others will likely ensure growth in 2018 and beyond. We continue to view Celgene as a top large-cap pick in Healthcare. We continue to see our $150 price target as fair for right now, but admit there is upside to our target as the business executes on the revenue path we anticipate.
This is no small company, with a market cap of $115 billion, setting a new all-time high this week. Check out this 5-year chart:
Facebook (FB: $171, flat, after dropping like a stone on Monday to $162)
Instagram recently disclosed that it's added another 100 million monthly users. That brings the photo-sharing app to 800 million monthly active users, up from 700 million in April. This is the fastest 100 million the firm has ever added – five months. When do you think they will hit a billion? Let's see... August 2018?
Five hundred million of those are daily active users, or consistently engaged using the service. That means that Instagram is still far, far ahead of rival Snap in terms of users. Snap said in August that it had 173 million daily active users. The announcement from Facebook-owned Instagram further solidifies Facebook as one of the most dominant companies in online advertising.
Why does all this matter so much? Viewing photos on Facebook used to be very clunky. It was a muddled, buggy experience, yet it’s what most people use Facebook for the most. Over 250 million images are uploaded to Facebook each day, making it the most popular photo-sharing site on the internet. Facebook is without a doubt the YouTube of photos. So Instagram is a critical piece of technology, ensuring the health of the Facebook platform and the future growth and engagement activity of users.
BMR Take: Facebook is an advertising machine and the business is nowhere near mature. EPS is expected to grow more than 20% per year into 2020 bringing EPS close to $10. We hereby raise our target price from $178 to $190 and strongly recommend you get this stock into your portfolio. The Sell Price remains at $155.
UPS (UPS: $120, up 2%)
UPS has been doing all the right things for a long, long time. The latest out of the company this week is a new JV in China.
UPS and SF Express announced approval of their planned joint venture by China’s Ministry of Commerce. The JV enables UPS and SF to collaborate on development and provision of international delivery services from China to the U.S. and, in the future, to other trade lanes. The JV approval is a positive development for international trade and allows the two leading companies to leverage their complementary networks, service portfolios, technologies and logistics expertise.
UPS is the world’s largest express delivery company and a leading global supply chain integrator. SF is a market leader in express delivery in China, with extensive China-wide network coverage, comprehensive service capabilities, and the highest brand recognition in the Chinese small package industry. The newly approved joint venture is a continuation of UPS and SF’s collaboration that began in 2015, when UPS Worldwide Express service was made available at SF’s retail stores in Shanghai and Shenzhen.
BMR Take: This JV is highly symbolic of UPS’s confidence in long-term growth opportunities in China. With EPS growing high-single-digits on its way to $8/share by 2020, we think this stock is a reliable performer for any stock portfolio and stand by our $125 price target for the time being. We’d love to raise it when it hits that magic number.
Home Depot (HD: $164, up 2%)
The story here at Home Depot is that growth is soaring right now. Why? The underlying fundamentals show us one of the best housing markets seen on record. Imagine that after the sub-prime crisis not all that long ago!
Indicators of the housing market were strong in the first half of 2017. Construction starts were healthy for both single-family and multifamily housing. Home purchases were solid while the supply of homes for sale rose for both new single-family homes and previously owned housing. The Federal Housing Finance Agency’s and the CoreLogic Case-Shiller repeat-sales house price indices showed home values rising, with annual price appreciation stable in a reasonable 5-6% range. Based on its National Delinquency Survey, the Mortgage Bankers Association reported that measures of delinquency declined, so people are paying their bills!
BMR Take: A resilient housing market means great things for Home Depot and we sure are seeing that effect take hold. With EPS growing around 10% per year and heading to $10, we raise our price target from $170 to $180 and see even more upside ahead. How’s this for a 5-year chart:

Government Properties Income Trust (GOV: $18.77, up 2%)
Government Properties Income Trust is a real estate investment trust (REIT) focused on owning and operating properties mostly leased to government tenants. Government Properties is the U.S. Government’s largest landlord and owns 74 properties located in 31 states and Washington D.C. containing approximately 11.5 million square feet. Historically, government tenants remain in place significantly longer than private sector tenants, with U.S. Government tenants occupying the same space for more than 20 years.
Properties are 95% leased and occupancy has remained well above 90% since inception. The company is rated investment grade by Moody’s (Baa3) and S&P (BBB-). 88% of rental income is paid by the U.S. Government (on behalf of 37 agencies.)
BMR Take: Look, Government Properties is a niche REIT serving government clients unlike anybody else in the business. They own and rent some of the best properties to clients like the Department of Justice and the IRS. Yes, we need to keep an eye on Trump cutting out all of the fat from the government budget and reducing the size of government. But in reality he can’t vacate signed leases, so there is not much he can do. For right now, however, the outlook looks just fine, and the juicy dividend yield of 9.25% is very attractive.
Moreover, in June, GOV agreed to acquire First Potomac Realty Trust for approximately $1.4 billion. Upon completion, this acquisition will increase exposure to the metro Washington, D.C. market, and expand GOV’s acquisition strategy in that area. We like this catalyst to spur excitement for the stock and for the positive impact it will have on the business. We trim our price target to $24 ($27 previously) out of conservatism.
Update on PayPal Holdings (PYPL: $64, down 1%)
PayPal Holdings is likely to make a strategic acquisition in coming months, according to Bernstein Research and Loop Capital. Last week, the firm put out a note to its customers wherein they believe a purchase of a European payments asset is most probable, with top targets Adyen (private), Klarna (private), Square (SQ) and Stripe (private.) The have an outperform rating on the stock.
“Acquiring Square (SQ: $29) would help PayPal increase its offerings at brick-and-mortar retailers and bring in more customers for PayPal’s Venmo service, as the small business customers on Square could accept Venmo transactions as payment,” they said. “By having both consumers and retailers on its platform, the combined entity would have significantly increased strategic positioning and optionality,” they wrote.
BMR Take: Both PayPal and Square are within a whisker of all-time highs. Square is on a roll and as we have said many times, could be a takeout prospect, and we are only at the beginning stages of Square’s future as a disruptive company in payments. With a market cap of just $11 billion we see big times ahead for this innovative company. And they could be bought out for $15-18 billion in a whisker by one of the big boys. PayPal? We see no top to this amazing success story.
Note this about Jack Dorsey of Twitter and Square:
Dorsey has bought over 1 million shares of Twitter in 2017, while selling much of his position in Square. Dorsey has sold more than $31 million worth of Square stock in that time. After Friday’s purchase, Dorsey owns more than 16 million shares in Twitter. He still owns a big stake in Square, but he is obviously moving to up his investment in Twitter at this time.
Upcoming Economic News
ISM Manufacturing
Monday, October 2nd, 10:00 AM
Period: September
Consensus: 58.0
Prior: 58.0
Total Light Vehicle Sales
Tuesday, October 3rd, 8:00 AM
Period: September
Consensus: 16.3M
Prior: 16.0M
Trade Balance SA
Thursday, October 5th, 8:30 AM
Period: August
Consensus: -$42.9B
Prior: -$43.7B
What follows is not a recommendation, but an information piece on a Nasdaq stock that invests in bitcoin.
Bitcoin Investment Trust (GBTC: $702, market cap - $1.2 billion)
Bitcoin Investment Trust, the only exchange-traded product that offers Bitcoin exposure, is an exchange-traded note, backed by Bitcoin, and it trades at an astonishing 95% premium that has been as high as 125%. That means investors are paying twice as much, plus fees, to own Bitcoin - a premium that will probably disappear as the Bitcoin market matures and access becomes less of an issue.
That’s already happening. In July, the U.S. Commodity Futures Trading Commission unanimously approved LedgerX’s cryptocurrency-trading platform for clearing derivatives; it will start with Bitcoin options. CBOE Holdings and Gemini Trust, the digital currency exchange founded by the Winklevoss twins, announced a partnership to offer Bitcoin futures as early as this year. VanEck has filed to bring products holding Bitcoin “instruments” to market. Exchange-traded fund provider REX is planning two Bitcoin-based derivatives ETFs.
The SEC has rejected Bitcoin exchange-traded funds, citing a lack of regulation of the Bitcoin spot market; a derivatives market in Bitcoin would remedy that. It also doesn’t hurt that Dalia Blass, who hails from the law firm that represented the Winklevoss twins’ ETF, has been named director of the SEC’s Division of Investment Management.
Bitcoin, the cryptocurrency polarizing governments, banks, and investors alike, is currently trading at $4,330, down from its peak of $4,980 in early September, but up from its lows of $3,000 in the middle of September. The sell-off was largely driven by Chinese regulators formally shutting major Bitcoin exchanges. As you can see, it is quite volatile, rising from $600 a year ago.
It didn’t help that JP Morgan Chase CEO Jamie Dimon called Bitcoin a “fraud” and “worthless” and that Bridgewater’s Ray Dalio called it “a bubble” in the days following China’s crackdown. Fundstrat Global Advisors’ Thomas Lee disagrees, saying that China’s recent moves are a short-term head wind, given that the region represents just 20% to 25% of global trading volume. Lee, in a recent note to clients, wrote that Bitcoin was “increasingly representing the gold investment” for millennials and will ultimately displace the precious metal in portfolios. He contends that Bitcoin could reach $25,000 by 2022, given that it accounts for 5% of the $7.5 trillion alternative currency market, which is growing by 6% annually. By early 2018, he sees it hitting $6,000, a whopping upside of 60%.
Here’s an interesting commentary on the bitcoin world, and an interview with John McAfee, the founder of McAfee Associates, the anti-virus software company that was eventually sold to Intel. McAfee is a bitcoin miner now, and appears to be "all-in" on bitcoin.
https://www.cnbc.com/2017/09/13/john-mcafee-challenges-jamie-dimon-bitcoin-skepticism.html
McAfee has stated that bitcoin could go to $500,000. Wow.
Teva Pharmaceuticals Names New CEO
Seven months after Erez Vigodman stepped down, Teva Pharmaceuticals (TEVA: $17.60, up 2%) has appointed a new CEO - Kare Schultz. Schultz, who has served as CEO of Danish pharmaceutical company H. Lundbeck since 2015, will be tasked with reviving sales and reducing debt for the world’s largest generics manufacturer. According to Bloomberg, Schultz will likely face pressure to split the company - with one focusing on “patented specialty medicines and the other on cheap copycat drugs.”
Twilio Shares Drop after Amazon Text Messaging Announcement
Twilio (TWLO: $30, down 3%) is a communications company that uses a cloud-based software to help businesses insert "real-time" communication into their apps. Amazon announced this past week that its Pinpoint system now allows users to trigger 2-way SMS messaging.
Some on the Street think this is bad for Twilio, but Twilio management thinks this is a good thing. "This is a continuation of our technology partnership with Amazon. Two-way texting is another capability being utilized by Amazon Pinpoint as part of our existing relationship," said a Twilio spokesperson.
Twilio CEO Jeff Lawson, who used to work at Amazon, said in a tweet that he's "excited that Twilio is now helping to power engagement on Amazon Web Services Pinpoint."
BMR Take: We believe in this company. Watch revenues – revenues rule all. And revenues have been spectacular as you know, since we have reported on this company continually. The stock is way off its highs of course, but we feel the stock is putting in a strong base here at this level.
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
What's going on with the Fed and why should we care? Today, the Fed is sitting tight with rates of 1.0-1.25%. Two weeks it announced it would start reducing their balance sheet in October. So, what does that mean? For years the Fed has been buying trillions of dollars' worth of US Treasuries and mortgage backed bonds, and reinvesting all the earnings back into more of the same. Next month it will start "shrinking" its balance sheet by not buying (reinvesting, or as some call it, "normalizing") tens of billion worth of Treasury's and mortgage bonds. Going forward, the Fed will ramp up the amount "normalized" every three months, hoping that this stair-step approach will not create turmoil in the markets. However, everyone knows the US government has to issue bonds to raise the money needed to pay its debts, so who is going to step in and buy these bonds now that the Fed is gone? That is something that no one knows because it's never happened before.
Our take is that the Fed will continue to monitor the economy and if it senses trouble – either from rising interest rates or the shrinking of their balance sheets – they will back down by either leaving rates alone or even halting the balance sheet reduction strategy. Thus, if the Fed continues to raise and shrink, it means the economy remains on solid footing. If things begin to slow, the Fed will most likely keep rates low and start buying again, both of which should benefit the market. An optimist will see this as a win-win scenario for keeping the market's prospects of continued growth intact.
We tend to be optimists at this point even though we don't like the fact that there seems to be so much dependence upon the Fed. We are optimistic because the market seems to have been able to shrug off not one, but several things that normally would have had some sort of consequential impact upon it. When one considers that Hurricanes Harvey, Irma and Maria slammed into the United States and Puerto Rico, North Korea tested another missile (and have threatened more), President Trump upset the establishment at the United Nations, and London was hit by another terrorist attack – it is remarkable that the market didn't suffer a significant correction. All this tells us that the earnings growth story for the market is for real and, if we can actually get a tax reform bill from D.C. – well, that would conjure up images of Gene Autry back in the saddle singing "Happy Days Are Here Again".
The High Yield Corner
By Michael Foster
The week saw a small bit of volatility for high yield investments in a surprising divergence from the stock market, which has virtually no volatility, and which had yet another strong week.
Is this a cause for concern? To answer that question, let’s take a look at where the biggest weakness was, determine what was the cause of that weakness, and try to extrapolate the probability of that weakness continuing.
Several of The Bull Market Report's high yield picks saw a 1% drop in the last week, such as Omega Healthcare Investors, Inc (OHI: $32, down 1%). For those of you who have followed this Healthcare REIT for a while, you know that a one-week 1% decline isn’t really terribly unusual, so it isn’t something that should inspire any alarm. On top of that, the decline happened without any unusual spike in volume and without any significant news, so we can’t conclude that there’s any material public information driving this decline. Short-term volatility caused by random inflows and outflows of investor capital seem the driver of the 1% fall here.
Not the same could be said for Apollo Commercial Real Estate Fund (ARI: $18.15, up 4%), which announced a 46 cent dividend just two weeks ago - a payout in-line with its previous payouts. It was paid out Thursday, and as per usual, the stock opened up 46 cents lower. So with the stock closing the week up 21 cents, plus the dividend, the stock was up a huge 4% for the week. Remember that the Apollo Fund isn’t a Property REIT but a Mortgage REIT, meaning that the way it earns income and its structure are more like a loan fund than a company like Omega. As a result, Apollo Commercial Real Estate Fund is sensitive to interest rate changes and default rate trends more than on the market’s perception of the value of its holdings, its property cap rates and occupancy rates, and other real-estate specific metrics. And we are in fact seeing an increase in long-term interest rates as we get nearer the December rate hike that the Federal Reserve has strongly hinted is inevitable.
While that’s bad for the Apollo Fund and a justifiable reason for caution, it’s offset by the fact that commercial real estate defaults are extremely low and are not going up. Thanks in part to improving profitability for companies, rising sales, and a stronger GDP growth rate, companies’ ability to pay their mortgages is as strong as could reasonably be expected. That, at the end of the day, is an arguably more important factor in determining the safety of Apollo’s future cash flow.
Is Apollo’s 10% dividend worth investing in? We think so. Risks of a cut are far lower than a double-digit yield would suggest, so investors should consider holding this even if we see some more volatility in the next couple of months before the drama from the Fed plays out in December.
Municipal bonds, which started the week in solid recovery mode, are taking a bit of a break. We’ve seen the sector weaken slightly in the last couple of weeks, and that trend has continued this week. As a result, Nuveen AMT-Free Municipal Credit (NVG: $15.39, down 1%) and Invesco Municipal Trust (VKQ: $12.77, down 1%) both had a bit of softness. While a 1% decline isn’t a lot when compared to just about any other asset class, it is a lot for the typically sleepy muni market. These bonds rarely see big price moves, so a 1% decline is something to consider. We’re still in positive territory for 2017, but that may not last long. The Fed’s interest rate hikes spook muni investors more than perhaps any other group of investors - even if interest rate hikes don’t hurt munis all that much. For that reason, we can’t promise these funds won’t fall later in the year, and even fall into red territory. Looking further, however, there will be a recovery when the market realizes the mistake they made and they start buying back in. After all, that’s what we saw after the hike in December 2015 and the hike in December 2016.
Interestingly enough, the taxable bond world is shrugging off the upcoming Fed rate hikes in the most contemptuous way. Let’s start with AllianzGI Equity & Convertible Fund (NIE: $21, up 1%), which announced its quarterly results that didn’t yield any major surprises. NAV growth and investment income are more than sufficient to yield a strong total return for investors, and the dividend of 7.3% remains very sustainable.
The convertible bond part of the portfolio is rising in value despite the clear message of an interest rate hike. Why? Again, it goes back to the fundamentals. Economic growth is strong enough for companies to pay their bills, which helps bonds rise in value. A similar tailwind has also helped PIMCO Dynamic Income Fund (PDI: $31, up 1%) enjoy a NAV boost for a long time now, so its last week of strength is no surprise. This fund remains priced at a premium to NAV, albeit just 6.5%, which is admittedly a cause for concern.
Additionally, Pimco Dynamic is under-earning its payouts, which means the year-end special dividend is likely to be smaller than it’s been in previous years - if there’s one at all. Still, on a total return basis there is just too much upside still in PDI because of its focus on mortgage-backed securities and corporate bonds.
Good Investing,
Todd Shaver, Founder, CEO and Editor
The Bull Market Report
Since 1998
August 13, 2017
by Todd Shaver | Aug 13, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
Talk of “fire and fury, the likes of which the world has never seen” aimed at North Korea spooked anybody listening. The markets have been calm for so long and then BOOM, the VIX (^VIX: 15.45) spiked 44% in one day and 60% in two days of trading this week. Our take is that we had been in an unsustainable lull of inactivity. These things happen and you have to be prepared for them. But in the long run, they work themselves out and things get better. Stay the course. If you are worried, consider dialing back your exposure to some of the more aggressive equities out there in favor of looking toward our REIT and High Yield portfolios, where the income stream of dividends offers greater downside protection.
But no matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks/funds: Shopify, Apple, The Carlyle Group, Sabra, AstraZeneca, AllianzGI Equity & Convertible Income Fund, Twilio and Amazon.
BMR Companies & Commentary
Apple (AAPL: $158, up 1% - all prices are for the week)
Apple is hard at work sublet shifting its brand. Everybody knows Apple. But Apple isn’t the name of its products. Apple's greatest hits over the past 30 years don't have "Apple" in their name: Macintosh, PowerBook, iTunes, iPod, iPad, iPhone, Siri. The newer stuff that does carry the Apple moniker -- Apple Watch, Apple Music, Apple TV-- have been either outright disappointments or solid but not wildly popular businesses.
But Apple is as good a brand as any. Think Proctor & Gamble, Ford, General Electric - you get the point. It's hard to transition from a corporate brand to additional brand franchises, but if you can do it, the future is bright!
CEO Tim Cook is working hard to make it happen. The Apple brand speaks to the firm's culture and reputation to employees, shareholders and governments. A product brand communicates a specific message about the item's quality, design, or function to consumers. There is so much potential.
BMR Take: Apple is just one of the companies that always figures it out - just as we are seeing them do now with the focus on services revenue and rethinking the brand.
We remain very bullish. The stock is trading at 17x this year’s consensus EPS of $9.00. The Services business is on pace to double over the next few years. Our Target of $155 has now been breached. Yea! We hereby raise our Target Price to $170. This will bring the company close to a $900 billion valuation, now at $813 billion. Our Sell Price remains the same: “We would not sell Apple.”
The Carlyle Group (CG, $21, flat*)
Carlyle is really a master of the universe. The company’s private equity investments are behind so much of the world’s underlining economic activity it’s ridiculous. The latest example is with McDonald's.
This week McDonald's announced the successful completion of a strategic partnership with CITIC Capital Partners and The Carlyle Group. Ramping up a new era of growth and innovation, the partnership will operate and manage McDonald's businesses in mainland China and Hong Kong, leveraging combined expertise and strength to drive an expansion strategy.
The transaction has obtained China's regulatory approval and was completed on July 31st, creating the largest McDonald's franchisee outside of the United States. The sale to the new McDonald's China franchisee includes McDonald's existing businesses in Mainland China (2,500 restaurants) and Hong Kong (240 restaurants).
The new partnership announced a series of development initiatives for mainland China. Termed "Vision 2022," this strategy aims to drive double-digit sales growth in each of the next five years by increasing the number of restaurants from 2,500 to 4,500 by the end of 2022, bringing unparalleled convenience to Chinese customers. The opening pace of new McDonald's restaurants in mainland China is expected to progressively ramp up from approximately 250 per year in 2017 to 500 per year in 2022 under the new partnership. Vision 2022 also includes an increase of "Experience of the Future" restaurants to over 90%, which will enable the brand to offer a digitalized and personalized dining experience to more customers.
BMR Take: We believe Carlyle is heading to $30. Consensus is looking for a solid dividend of $1.80 next year and $2.15 the following. EPS is running closer to $3. Few institutional investors can buy the stock because the K1 tax structure creates issues. But that will change and when it does, look out on the upside.
* The stock was down 40 cents this week, but CG paid a 42 cent dividend on Thursday and when a stock pays a dividend the stock always opens that day down the amount of the dividend. Thus Carlyle was flat this past week.
Shopify (SHOP: $92, down 5%)
Shopify’s plan is to let half a million merchants run their business via Alexa and bots. Shopify wants its 500,000 merchants to be able to run their businesses almost entirely through the use of bots or voice apps like Alexa.
At F8, Facebook’s annual developer conference, Shopify announced plans to launch a Facebook Messenger bot, named “Kit”, the first commerce platform to do so. Through conversations on Facebook Messenger or SMS, Kit can do things like place a Facebook ad or start an email marketing campaign.
The development roadmaps of voice apps like the Shopify Alexa* skillset and text bots like Kit will begin to converge, so that the same merchant analytics available today by voice will become available in a text interface, and the same actions to run your business available today through text will someday be available with your voice.
* Shopify Alexa is a partnership with Amazon to use Alexa.
The Shopify Alexa skill first became available in January, but was launched with no marketing or promotion in order listen to the queries put forward by merchants to better understand the kinds of questions they want the skill to be able to answer. Before merchants are given the ability to run business operations in a conversational interface, a few other features will be added first.
Based on merchant feedback, more long-term business performance insights are on the way, and work will continue with engineers to ensure the bot can handle the range of questions a merchant has and understands the variety of ways a merchant may ask a question.
BMR Take: When we look at the core building blocks of how this company is advancing its growth potential of Total Addressable Market (TAM) is expanding. In addition, we see opportunities in international, in new merchant solutions and apps, and building scale with Shopify Plus, the company’s enterprise-focused solution. In our view, the valuation is supported by the long runway and expanding TAM given Shopify’s lower relative market share, still less than 5%. We reiterate our bullishness on the stock. The stock is currently trading at about 9 times the estimate of next year’s sales. This valuation is rich but justified.
Sabra Health Care REIT (SBRA: $21.45, down 7%)
We have decided to take our chips off the table in Sabra. Two reasons. First, the core senior housing portfolio growth is essentially flat so it’s hard to see any organic upside from the business. Second, the pending merger with Care Capital is being fought creating noise and possibly more risk.
Regarding the latter, two activist investors are urging Sabra to drop the Care Capital deal. They say shareholders of the healthcare-focused real estate investment trust should reject the merger at a shareholder meeting next month. Why? Sabra was overpaying for Care Capital's assets by up to 30%, the hedge fund said in a presentation. Ouch.
Consensus for Sabra Healthcare REIT:
1 Sell Rating, 6 Hold Ratings, 1 Buy Rating
BMR Take: We like to listen to the market and to other shareholders invested in the stocks we own. Especially when the other shareholders do great research and make objective points. We added the stock at $24 in May and are down a bit, but with the dividend, it wasn’t a great loss. Let’s move on to the next one.
AllianzGI Equity & Convertible Income Fund (NIE: $19.79, down 2%)
This fund seeks total return with capital appreciation and high current income through investment in convertible equity, income producing securities and through utilizing an options strategy. It’s top holdings are Microsoft, Apple, Amazon, Facebook, and Google. It does not use leverage. It does not hold fixed income.
60% of the stocks it holds are in the largest giant companies, and 37% in large cap companies. The Funds PE ratio is 19 versus the 17.2 benchmark, but sales, EPS, book value, and cash flow growth is all better than the benchmark.
See more discussion in The High Yield Report later in this newsletter.
BMR Take: Sometimes it is nice to own a fund and have some help picking all the right places to be. We like AllianzGI with its 7.7% yield. You can buy right now at a discount to the net asset value of $21.75, a very opportune entry point.
AstraZeneca (AZN: $29, flat*)
Fierce pharma rivals collaborating on cancer treatments are increasing the competitive landscape, hurting AstraZeneca. But we believe we must stay the course. AstraZeneca reported disappointing results for its clinical trials examining Tremelimumab combined with Imfinzi for the treatment of lung cancer. The market has become crowded with checkpoint inhibitors and immunotherapy drugs, which means that the number of such potential combinations of treatments is growing. Pharma rivals are now cooperating -- last week Merck bought half the rights to AstraZeneca's Lynparza, and in July Eli Lilly said it would out-license or co-develop one-third of its oncology pipeline.
BMR Take: Healthcare has been a minefield for months now. AstraZeneca has been beaten down. Analysts have been upgrading the stock on valuation. It is very cheap versus expectations for around $2 of EPS for next few years. Consider the 3% dividend yield on top of that. It’s a classic value here as the stock is truly undervalued. Our Target remains $42, and our Sell Price of $32 has been breached, so please make a decision with your own portfolio as to whether you personally wish to stay the course. We are trying to be patient here to give the company more time to perform.
*A dividend was paid on Wednesday of 45 cents.
Upcoming Economic News
Retail Sales
August 15th , 8:30 AM
Period: July
Consensus: 0.40%
Prior: -0.20%
Housing Starts
August 16th, 8:30 AM
Period: June
Consensus: 1,220,000
Prior: 1,215,000
Initial Claims
August 17th, 8:30 AM
Period: Through August 12
Consensus: 240,000
Prior: 244,000
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
Stocks finished mostly higher again the week before last, mainly because of good corporate earnings, a stronger-than-expected Jobs report, solid GDP performance, healthy Consumer Confidence and a little better than expected Export & Import numbers. Is it all "too good to be true?" [Well, indeed it was!]
According to the latest American Association of Individual Investors survey, individual investors are now holding their lowest cash allocation since 2000. They are now among the most invested in financial markets since 1988. The three other time periods with the lowest cash allocations were in 1998, 2000, and 2015, and all of these preceded times when investors probably wished they had more of a cushion.
We certainly do not think we're on the brink of another 1999 dotcom bubble or a 2008 financial crisis crater. But one thing's for sure, stocks don't always go straight up forever. There will be volatility and pullbacks as Fed-tightening continues. According to recent news reports, there is now a 50/50 chance the Fed will raise rates again in December. Whenever a pullback occurs, it is not going to be unexpected. It's overdue and as natural to the market as hot dogs are to ball games. With a backdrop of really solid earnings, we expect any pullback to be fairly brief in duration. If earnings keep growing and the job numbers keep getting stronger, pullbacks will just be setting up the next move higher. If Congress grows up and we get tax relief and corporate tax reform, investors will be saying, "Laissez les bon temps roulez".
Note what UBS has to say in their latest report on the Equity Markets: The bottom line: stocks are not cheap, BUT ARE NOT in "bubble" territory.
Amazon Update (AMZN: $968, down 2%)
The stock got hit last week as the rest of the market had some tough times as you know. There is an ongoing discussion over valuation with this company. We had a heated argument with a very astute investor who thinks the stock is overvalued saying that the company will NEVER report substantial earnings; that Bezos will ALWAYS have a new project in mind that will cause him to spend, spend, spend on new infrastructure.
We agree to a certain extent, but disagree with the profit story. As you know, we have said many times revenues are the key to all success in the market. Amazon had revenues of $89 billion, $107 billion and $136 billion in the last three calendar years. This year? Hard to say, but it looks like at least $175 billion? This is just huge of course. We remain bullish for as far as we can see forward.
We hereby raise our Price Target from $1000 to $1100 and leave the Sell Price at $900.
Twilio (TWLO: $31, up 7%)
Twilio had a huge week after reporting blowout revenues as we reported via News Flash on Tuesday. Total revenue – $96 million, up 49% from the second quarter of 2016 and 10% sequentially from the first quarter of 2017.
Loss from operations – $7 million, compared with a loss of $11 million for 2Q16.
And we love this stat: 43,000 Active Customer Accounts as of June 30, 2017, compared to 31,000 Active Customer Accounts as of June 30, 2016.
Profits are still at slightly below breakeven, but as you know, we are banking on the huge revenue gain.
Here is the consensus on the Street:
2 Hold Ratings, 15 Buy Ratings
Price Targets:
8/8/2017 Canaccord Genuity $38
8/8/2017 Robert W. Baird $39
8/8/2017 J P Morgan Chase $40
8/8/2017 Mitsubishi UFJ Financial Group $35
7/17/2017 Summit Redstone $36
BMR Take: We love this company and think it can be a monster. An Apple? A Microsoft? Hard to predict the next 10-15 years, but watch this one closely.
Wall Street Consensus for United Parcel Service (UPS: $111, up 1% in a very tough week, and after an 83 cent dividend on Thursday)
Consensus: 10 Hold Ratings, 5 Buy Ratings
Price Targets:
8/8/2017 Citigroup $128
7/3/2017 Sanford C. Bernstein $127
SNAP (SNAP: $11.83, down 13% - still at a $14 billion market cap)
Don’t buy SNAP
Don’t buy SNAP
Don’t buy SNAP
Revenues: $182 million up from $72 million
Loss: $443 million up from a loss of $116 million last year. WOW! (How is this actually possible?)
Don’t Buy SNAP
Don’t Buy SNAP
A Letter from a Subscriber about Netflix (NFLX: $171, down 5%)
From: Stan Makovsky [mailto:stan@stanxxxx.com]
Sent: Wednesday, August 09, 2017 3:11 PM
To: 'Todd at The Bull Market Report'
Subject: Netflix
Hi Todd,
Disney pulling out of Netflix seems to be a big deal for both stocks. Your thoughts please?
Best Regards,
Stan Makovsky
Our Response:
Hi Stan –
I am not really concerned too much. The market is getting slammed today as I write this [Wednesday] and Netflix is down just $4. If it were down $20 I’d be a little concerned. But I believe Disney needs Netflix more than Netflix needs Disney. Netflix is a force now and as you know is spending billions of dollars a year on programming. They will be just fine. The scary thing about Netflix is their profit level – which is tiny. This needs to change.
Todd Shaver
Founder and Editor in Chief
The Bull Market Report
A Powerful Financial Newsletter
Since 1998
@BullMarketRept on Twitter
The High Yield Report
By Michael Foster
Special to The Bull Market Report
It’s been a long time coming, but we finally see a bit of fear entering the market.
For high yield investors, this is a concern because downturns and mini-corrections tend to be amplified in high yield investments. The S&P 500 slid over 1% last week but many high yield investments fell much more, especially closed-end funds (CEF). The AllianzGI Equity and Convertible Income Fund (NIE: $19.80) fell nearly 2% over the last week due to a considerable decline in the fund’s NAV, which fell over 1% in a single day of trading last week. In many cases, a market correction will result in CEFs’ discounts widening as investors sell off the fund. Surprisingly, however, holders of the AGIC fund have been surprisingly calm, resulting in the discount staying less than 10% by the week’s end. Recently, the discount had shrunk to less than 9%, so this is definitely not as good as it has recently been. But it’s surprisingly not as bad as it could be.
Of course, if the selloff continues throughout the coming week, it would be more than reasonable to expect Allianz to see a larger discount as slower and more risk-averse investors finally get around to selling this and other closed-end funds. What does this mean for you? Well, we maintain a bullish outlook for the economy and for stocks, with corporate profits continuing to rise year-over-year and the Allianz fund in particular maintains a strong portfolio of respected and strong-performing stocks. There’s no reason to sell off amongst the fearful, but anyone with extra cash on the sidelines who wants a sustainable near-8% dividend stream could consider picking up some of this fund.
Similarly, The Bull Market Report’s second CEF pick, the Pimco Dynamic Income Fund (PDI: $29), had a rough week during the market’s selloff, falling over 4%, after paying out a 22 cent dividend on Wednesday. This has resulted in PDI’s premium price falling slightly, and now the fund trades at slightly over a 2% premium to NAV.
After the sell-off, investors may be eager to buy more of the Pimco fund and capture that 9% dividend yield plus the potential upside of special dividends at the end of the year. Before rushing to buy, however, there are a few things to consider. The fund’s NAV has risen 10% so far this year even after accounting for dividend payouts, which means the fund’s payout remains sustainable. However, this is a relatively weak performance compared to its past performance. Part of the reason for that is the growing burden of its promised payouts. Because it trades at a premium, it has been significantly harder for the fund to pay out dividends than to earn the comparable income in the open market. Since the fund’s premium rose to as much as 10% earlier this year, those dividend payouts were particularly burdensome for Pimco’s managers. Now that the premium is at its lowest point since November last year, that dividend is going to be slightly easier to pay.
Easier, but not easy. The real problem with this fund is that it has years and years of a solid track record thanks to its contrarian nature. The fund invested heavily in mortgage-backed securities (MBS’s) after 2008, when they were synonymous with financial ruin. In reality, however, many of these assets were extremely undervalued because of investor fear, and Pimco had the chops to find the good ones and buy them. Hence the fund’s massive outperformance.
However, 2008-2009 is becoming a fainter memory, and the market is finally realizing the huge mistake it made in avoiding many quite valuable MBS’s. As a result, more capital is coming into that market and creating more competition for Pimco. Ultimately, that means diminished returns for investors holding this fund.
Unfortunately, this has also happened as more investors have discovered the fund’s tremendous returns. Holding this fund has become a crowded trade. Back in 2013-2015, the fund almost always traded at a discount; in late 2015, shortly before The Bull Market Report recommended it, its discount fell to 11%. But now a flood of capital has come in and driven the fund to a consistent premium, while earning superior returns through MBS’s is getting harder for the fund.
This doesn’t mean you should sell the Pimco Dynamic Income Fund. But it does mean one has to wait before buying more and instead choose other strong dividend payers like the AllianzGI fund.
Finally, let’s briefly discuss REITs. These were a mixed bag, with pretty much all REITs down and some down much more than others. Omega Healthcare Investors (OHI: $30) fell 2% over the week alongside the broader market, with its greater volatility amplifying losses. Yet the similarly volatile Government Properties Trust (GOV: $18.13) fell about 1% over the same period, even beating the market. There are a couple of pretty obvious reasons for this. For one, Government Properties Trust’s big decline earlier this month means it’s found a bottom and can’t plunge much lower. Obviously this means buying now makes sense. Omega, however, hasn’t exactly found its bottom yet and only went negative YTD at the end of last month. There’s no fundamental reason for this – there is sustainable income, the dividend is still rising, and Omega’s expansionary plans are on track. But there is a lot of fear in the market, and that is reflected in the rapidly fluctuating price of this stock.
While buying Omega now is buying a bargain, investors should be prepared for more volatility. Government Properties, while not exactly strong, seems to have found a floor that is limiting further downside, making it a more appealing buy right now. But no matter what you do right now, selling is not a good idea. There is no fundamental reason to fear for the future of equities or high yield assets, so ignore the panic selling. It will be intense but brief-lived, as always.
Good Investing,
Todd Shaver, Editor, CEO and Founder
The Bull Market Report
Since 1998
July 26, 2017
by Todd Shaver | Jul 26, 2017 | Earnings Preview 6 AM
We are a shade late this week. We had computer and internet issues. Sorry.
Alphabet (GOOG: $954)
Bull Market Report Target Price: $1000
Bull Market Report Sell Price: We would not sell Alphabet
Earnings Date: Monday, 4:00 PM ET
Consensus: 2Q17
Revenues: $26 billion
EPS: $5.01
Alphabet reported a heavy drop in 2Q17 EPS due to the $2.7 billion fine from the European antitrust regulators. Shares currently trade down about 3% as the company missed expectations on its cost per click which rose by 23%. We are still bullish on Alphabet as they continue to innovate and bring to market new technologies like their most recent Google Home.
****************************************************
Eli Lilly (LLY: $82)
Bull Market Report Target Price: $88
Bull Market Report Sell Price: $76
Earnings Date: Tuesday, 8:00 AM ET
Consensus: 2Q17
Revenues: $5.4 B
EPS: $1.05
Year Ago Quarter Results
Revenues: $5.5 B
EPS: $0.86
Lilly reported yesterday with revenues up 8% and earnings up a powerful 22% to $1.11. Despite having missed estimates in two of the past four quarters, the stock is up 3% since this time last year and is currently trading 28% above its 52-week-low. Like other companies in our portfolios, Eli Lilly is also trading relatively cheap in comparison to the overall industry. Eli’s PE is 40 while Healthcare industry PE is around 60.
****************************************************
Equity Residential (EQR: $66)
Bull Market Report Target Price: $85
Bull Market Report Sell Price: $55
Earnings Date: Tuesday, 4:00 PM ET
Consensus: 2Q17
Revenues: $610 M
EPS: $0.35
Year Ago Quarter Results
Revenues: $595 M
EPS: $0.59
Key Things to Watch For in the Quarter
The company reported yesterday that it had net income of $195 million, or 53 cents per share, well above the Street estimate. Revenues came in at $613 million. Although Equity Residential has beaten estimates in the past four quarters, the stock still trades down 5% from this time last year. However, EQR is trading 13% above its 52-week low indicating positive investor sentiment within the Real Estate industry. The stock currently trades at a PE ratio of 20, relatively low compared to the industry’s PE of 40.
****************************************************
PayPal (PYPL: $58)
Bull Market Report Target Price: $56
Bull Market Report Sell Price: We would not sell PayPal
Earnings Date: Wednesday, 11:00 AM ET
Consensus: 2Q17
Revenues: $3.1 B
EPS: $0.43
Year Ago Quarter Results
Revenues: $2.7 B
EPS: $0.36
Key Things to Watch For in the Quarter
Analysts across Wall Street expect that PayPal will report a healthy 16% growth in EPS to $0.36 and a 14% increase in revenue to $3.1 billion. PayPal has either met or beaten estimates in each of the past four quarters. This success has contributed to the 55% appreciation in the stock since this same time last year. We expect PayPal to continue its top line growth as more transactions shift away from cash and onto digital platforms.
PayPal has hit our Target of $56. We still love the company and expect big things in the future. We hereby raise our Price Target to $66, and maintain our Sell Price as “We would not sell PayPal.”
****************************************************
Facebook (FB: $165)
Bull Market Report Target Price: $165
Bull Market Report Sell Price: $140
Earnings Date: Wednesday, 4:00 PM ET
Consensus: 2Q17
Revenues: $9.2 B
EPS: $1.12
Year Ago Quarter Results
Revenues: $6.4 B
EPS: $0.97
Key Things to Watch For in the Quarter
Analysts across Wall Street expect that Facebook will report strong EPS growth of 15% growth to $0.97 and a 30% increase in revenue to $9.2 billion. Despite having missed estimates last quarter, Facebook’s stock has climbed 36% since this time last year. In addition to the flagship Facebook.com, Zuckerberg has been innovating through his various offerings which include WhatsApp, Instagram, and Oculus Virtual Reality. We expect Facebook will continue to thrive as it tries to connect people throughout the world.
Facebook has hit our Target of $165. We added the stock at $97 a year and half ago and have been beating the drums every chance we get. We are still beating the drums. This company is amazing and is changing the world. We hereby raise our Target Price to $178 and raise the Sell Price from $140 to $155.
****************************************************
Omega Healthcare Investors (OHI: $33)
Bull Market Report Target Price: $45
Bull Market Report Sell Price: $28
Earnings Date: Wednesday, 4:00 PM ET
Consensus: 2Q17
Revenues: $235 M
EPS: $0.49
Year Ago Quarter Results
Revenues: $185 M
EPS: $0.57
Key Things to Watch For in the Quarter
Analysts estimate that Omega will report a 20% increase in revenue to $235 million and a 14% decrease in EPS to $0.49. Although Omega beat estimates in three of the past four quarters, the stock is down 6% this past year. This price depreciation has provided investors with an opportunity for entry especially as the stock only trades at a PE of 16 compared to the industry average of 60.
The stock hasn’t gone anywhere in a year, but that’s OK as we love the almost 8% dividend it pays.
****************************************************
CBRE (CBG: $38)
Bull Market Report Target Price: $40
Bull Market Report Sell Price: $32
Earnings Date: Thursday, 8:00 AM ET
Consensus: 2Q17
Revenues: $3.4 B
EPS: $0.53
Year Ago Quarter Results
Revenues: $3.2 B
EPS: $0.52
Key Things to Watch For in the Quarter
CBRE is expected to report moderate revenue and EPS growth for 1Q17. Analysts estimate that CBRE will report a 6% increase in revenue to $3.4 billion and a 2% increase in EPS to $0.53. The firm reported earnings that beat estimates in 3 of the last 4 quarters and provided investors with a 31% return year-over-year. CBRE’s stock currently trades at a PE ratio of 20, which is extremely cheap compared to the industry’s average PE of 91.
We love this one and can’t wait for it to hit $40 so we can raise the Target. The company is doing amazing things in real estate, saving companies money and manpower, and they are so low-key very few investors know about the firm. The market cap is a shade under $13 billion now, and this coming weekend we will give you some examples of what they do for their customers and why $38 for this stock will seem cheap in a year. We hereby raise the Sell Price from $32 to $35. We don’t want to lose the 48% gains we have in the stock since we added it at $26 last year.
****************************************************
United Parcel Service (UPS: $113)
Bull Market Report Target Price: $125
Bull Market Report Sell Price: $106
Earnings Date: Thursday, 8:00 AM ET
Consensus: 2Q17
Revenues: $15.5 B
EPS: $1.47
Year Ago Quarter Results
Revenues: $14.6 B
EPS: $1.43
Key Things to Watch For in the Quarter
UPS is expected to report moderate revenue and EPS growth for 2Q17. Analysts estimate that UPS will report a 5% increase in revenue to $15.5 billion and a 3% increase in EPS to $1.47. The firm reported mixed earnings in the last four quarters. Having only beat estimates once, the stock has underperformed the market at a mere 2% increase. It currently trades at a PE ratio of 28, which is slightly high compared to its competitors in the 25 range.
We still like the company a lot, as they have to deliver all those packages from Amazon! We are maintaining our Price Target of $125.
****************************************************
Bristol Myers Squibb (BMY: $56)
Bull Market Report Target Price: $77
Bull Market Report Sell Price: $51
Earnings Date: Thursday, 8:00 AM ET
Consensus: 2Q17
Revenues: $5.1 B
EPS: $0.73
Year Ago Quarter Results
Revenues: $4.9 B
EPS: $0.69
Key Things to Watch For in the Quarter
Bristol Myers is expected to report moderate revenue and EPS growth for 2Q17. Analysts estimate that Bristol will report a 4% increase in revenue to $5.1 billion and a 6% increase in EPS to $0.73. Although Bristol Myer beat estimates in three of the past four quarters, the stock is down over 25% this past year. This price depreciation has provided investors with cheaper opportunities for entry especially as the stock only trades at a PE of 20 compared to the industry average of 60.
****************************************************
Celgene (CELG: $137)
Bull Market Report Target Price: $135
Bull Market Report Sell Price: $115
Earnings Date: Thursday, 8:00 AM ET
Consensus: 1Q17
Revenues: $3.2 B
EPS: $1.78
Year Ago Quarter Results
Revenues: $2.8 B
EPS: $1.44
Key Things to Watch For in the Quarter
Analysts across Wall Street expect that Celgene will report both strong revenue and EPS growth of 15% and 24% to $3.2 billion and $1.44 respectively. while Amazon will increase its revenues by 19% to $37 billion, it will decrease its EPS nearly 20% to $1.42. Amazon has beat estimates in all of the past 4 quarters and has helped return investors 27% since this time last year. Celgene still only trades at a PE ratio of 50, making it relatively cheap compared to the industry’s PE of 60.
Since June at $114, the stock has gone straight up. It has reached our Target of $135, but we still love this huge company ($107 billion market cap,) so we hereby raise our Price Target to $150 and raise our Sell Price from $115 to $125. We added the stock at $95 a year ago and are now up 44% as it just set a new all-time high last week. Lovin’ it.
****************************************************
Amazon (AMZN: $1,040 – a new all-time high)
Bull Market Report Target Price: $1,100
Bull Market Report Sell Price: $875
Earnings Date: Thursday, 4:00 PM ET
Consensus: 1Q17
Revenues: $37 B
EPS: $1.42
Year Ago Quarter Results
Revenues: $30 B
EPS: $1.78
Key Things to Watch For in the Quarter
Wall Street expects that while Amazon will increase its revenues by 19% to $37 billion, it will show a decrease in EPS of nearly 20% to $1.42. Amazon has beat estimates in three the past four quarters and has helped carry many tech heavy indices. Amazon traded at $765 this time last year and has since climbed over 35% to its current levels. This past Prime Day, Amazon’s version of Black Friday, the company broke its own record for the largest online shopping day in history.
We are keeping the Target Price at $1100, but raise our Sell Price to $970 from $875.
****************************************************
First Solar (FSLR: $45)
Bull Market Report Target Price: $55
Bull Market Report Sell Price: $28
Earnings Date: Thursday, 4:00 PM ET
Consensus: 2Q17
Revenues: $540 M
EPS: $0.10
Year Ago Quarter Results
Revenues: $935 M
EPS: $0.87
Key Things to Watch For in the Quarter
This company is regrouping, as we know, and the comparisons are not pretty. Analysts estimate that First Solar will report a decrease in revenues by 43% to $540 million and an 88% decrease in EPS to $0.10. Although First Solar has beat estimates in the past four quarters, the stock is down 5% this year.
The stock is inching its way back, little by little. We certainly had bad timing on the addition of the stock to our Special Opportunities portfolio last year in February, but we are believers in the business and the company and have had amazing patience with this one. We hereby raise the Sell Price from $28 to $39.
****************************************************
Ventas (VTR: $68)
Bull Market Report Target Price: $82
Bull Market Report Sell Price: $43
Earnings Date: Friday, 8:00 AM ET
Consensus: 2Q17
Revenues: $880 M
EPS: $0.44
Year Ago Quarter Results
Revenues: $850 M
EPS: $0.42
Key Things to Watch For in the Quarter
Wall Street expects that Ventas will report moderate EPS growth of 7% to $0.45 and a 4% increase in revenue to $880 million. Although the firm has beat estimates in the past four quarters, its stock is down 8% over the past year. The company’s 5% dividend and relatively cheap PE of 35 make it an attractive stock in today’s markets. This is not a small company, as the market cap of $25 billion tells us.
We hereby raise our Sell Price from $43 to $61.
****************************************************
Welltower (HCN: $73)
Bull Market Report Target Price: $84
Bull Market Report Sell Price: $60
Earnings Date: Friday, 8:00 AM ET
Consensus: 2Q17
Revenues: $1 B
EPS: $0.44
Year Ago Quarter Results
Revenues: $1 B
EPS: $0.54
Key Things to Watch For in the Quarter
Analysts estimate that Welltower will report no change in revenues at $1 billion and a 18% decrease in EPS to $0.44. Although Welltower has beat estimates in the past 4 quarters, its stock is down 7% this past year. This move has provided investors with cheaper opportunities for entry especially as the stock continues to pay a 5% dividend and trades at a PE that is 25% lower than its industry’s.
We hereby raise the Sell Price from $60 to $68.
