June 2, 2024

by Scott Martin | Jun 2, 2024 | Weekly Newsletter 7pm Sunday
Market Summary
The Bull Market Report
The last two weeks were a tale of one stock. We spent a few days waiting for NVIDIA (NVDA) to release its quarterly results, leaving Wall Street almost literally breathless in the meantime. Then we watched money crowd into NVIDIA after the SEC filing, swelling the stock to lofty levels ($2.7 trillion, more than the entire German market). And finally, investors tired of scrutinizing this AI giant found a distraction in the form of a potentially threatening uptick in bond yields. We're happy we have NVIDIA in our High Technology portfolio. It's already soared close to 140% in the last six months for us.
But we'll never be satisfied with exposure to just one stock, no matter how strong it is in the moment. If that were the case, we'd have cut everything but Apple (AAPL) or Berkshire Hathaway (BRK-B) long ago, and had to live with the day-to-day consequences of that decision. In our world, a balanced portfolio of themes will win in the end. When Technology is triumphant, we have plenty of those stocks scattered around our universe. When Silicon Valley hits a wall, our Financials or Energy or Real Estate holdings tend to benefit as the pendulum of sentiment swings in their favor. And throughout the cycle, our High Yield recommendations keep paying dividends.
How has that paid out for us in the last two weeks? NVIDIA obviously did extremely well on its own, but its success sucked all the air out of the Technology portfolio and cut big holes into our results in the Stocks For Success and Long-Term Growth portfolios as well. Only mighty Apple managed to rise above the tide on the Stocks For Success side. First Solar (FSLR) was an absolute triumph and helped buoy Long-Term Growth. See below.
What's more interesting is the way the Early Stage recommendations were split between a 12% gain in the past two weeks for C3.ai (AI) and a 12% loss from Recursion Pharmaceuticals (RXRX), leaving the portfolio neutral for the period. A lot of our portfolios sat out the NVIDIA cycle close to neutral. This was a non-event as far as they were concerned. Now that Wall Street's attention has moved on, we expect them to recover their momentum and get back to work.
For now, this was a "rebuilding" period for our stocks. The Dow Industrials lost more ground but the Nasdaq, overweight NVIDIA as it is, held up better than the BMR universe in the aggregate. That's okay. Ordinarily our "equal weight" system for accounting for our performance plays out in our favor. This time, the single standout name was so strong (and nearly everything else was so tentative) that only portfolios that were heavily concentrated in NVIDIA managed to do well. One way or another, earnings season is over. It was a good one. We can afford to let the AI giant hog the spotlight. After all, we own it too.
In our view, bond yields are a sideshow. They sting, but the real story is what the Fed said two weeks ago. It's going to take serious pain in the Treasury market to feed back into our stocks. And get serious: that kind of pain in the Treasury market is not going to entice smart investors to pull their money out of stocks and flood into the "safety" of bonds paying less than 5% a year. That kind of pain is not enticing. It's scary. And it feeds on itself. Stocks like ours may even look defensive in that scenario. But in our view, the scenario is unlikely. The bond market corrects itself. When yields are attractive to the people who want bonds, you'll know. Otherwise, we focus on stocks.
There's always a bull market here at The Bull Market Report. With earnings season on the books, The Big Picture tackles the question of whether stocks have gotten ahead of their growth rates, while The Bull Market High Yield Investor sets the scene for the next Fed meeting And as always, we can't resist updating you on our latest thoughts on our favorite recommendations.
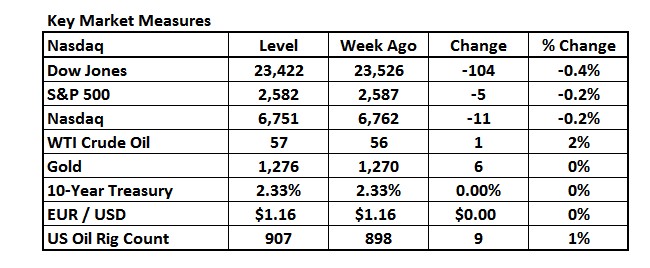
Key Market Indicators
-----------------------------------------------------------------------------
The Big Picture: Record Earnings, Record Stocks
Despite the persistent drag from the Fed on the short end of the yield curve and a weakening bond market on the long end, the economy remains resilient and the largest corporations in the world are making more money than ever. With 98% of S&P 500 companies reporting results, the index is on track for a healthy 6% growth in earnings per share. This surpasses analysts’ earlier forecasts of 3.2% growth, marking the biggest year-over-year increase since mid-2022 and quite the upside surprise. So far, nothing in the recent past has provided even a speed bump, and guidance suggests that things get even stronger in the current quarter and beyond.
When earnings hit records, stocks deserve to hit records too. That part is inevitable. The only question is how far investors' comfort zone will stretch to accommodate stronger fundamentals when valuations across the market are already on the high side of recent memory. After doing the math, we aren't especially worried that stocks have gotten ahead of their growth trend.
Think about it. Yes, the S&P 500 is currently priced at 20.3X forward earnings, which is significantly elevated when you consider that across the past decade the market only commanded a 17.8X multiple. However, it's barely a notch above where it's averaged out over the last five extreme bear-and-bull-and-bear-and-bull years. And because growth shows every sign of accelerating in the coming year, we wouldn't be shocked next summer to see the market as a whole at least 15% above where it is now. That's better than what stocks have historically delivered over the long haul. It's a boom.
And even in this 15% scenario, there's a strong argument that stocks will be strategically attractive at that point. The Fed will find an excuse to guide the short end of the yield curve down. That's a good thing for the market, giving valuations an excuse to reinflate as the "risk-free" return rate on cash drops. Long-term yields should drop far enough with it to take a lot of pressure off the economy and Wall Street alike.
Meanwhile, earnings expansion is on track to speed up from 11% for this year to 14% in 2025.
Those extra 3 percentage points bend the P/E calculations just enough to eliminate just about any rational fear that stocks are overvalued now. Remember, smart investors pay extra for faster growth because every additional percentage point on that side shortens the amount of time you need to wait in uncertainty and doubt to see your companies grow into what would otherwise look like high valuations. We wouldn't be shocked to recheck the numbers in 12 months and see the S&P 500 in the aggregate bringing in as much as $50 more per "share" (spread across all 500 stocks of course) than it's making now, and then at the end of 2025, adding another $35-$40 to that pool of cash takes the S&P 500 multiple down BELOW long-term historical averages if the market doesn't move appreciably in either direction in the meantime.
All you need to take advantage of that discounted future is buy stocks today and hold on until next summer. There will undoubtedly be volatility. Maybe it will take the market down, in which case the discount will be even more substantial a year from now. And maybe it will take the market up, in which case the route to positive returns pays off earlier. All in all, analysts collectively think the market can rally another 13% or so in the next 12 months. At that point, if all the projections line up with reality, the market looks LESS overheated on an earnings basis, even though investors would have reason to cheer with a better-than-average annual gain on the books.
We like the odds of executives continuing to outperform. They've already successfully weathered an earnings recession, a slowing global economy and just about everything inflation and interest rates can throw at them. Give them a little relief and the numbers will go through the roof. All we need to provide is that year of fortitude. It feels like a pretty good bet.
-----------------------------------------------------------------------------
BMR Companies and Commentary
C3.ai (AI: $30, up 23% last week)
Early Stage Portfolio
Enterprise AI company C3.ai released its fourth-quarter results last week, reporting $87 million in revenue, up 20% YoY, compared to $72 million a year ago. The company posted a loss of $14 million, or $0.11 per share, against $15 million, or $0.13, with a beat on estimates on the top and bottom lines, coupled with robust guidance for the new year bringing much-needed glad tidings for investors.
For the full year, the company posted $310 million in revenue, up 16% YoY, compared to $270 million a year ago, with a loss of $56 million, or $0.47, against $46 million, or $0.42. With demand for enterprise AI solutions continuing to intensify across industries, the company exceeded the top end of its guidance for the full year as well. It marked its fifth consecutive quarter of accelerating revenue growth.
During the quarter, the company signed 47 new agreements, including 32 new pilots, with marquee clients such as ExxonMobil, General Mills, BASF Petronas, and the US Navy, among others. This has resulted in subscription revenues rising 41% YoY, constituting 92% of its total revenue, giving the company much-needed stability and certainty regarding its cash flow position going forward.
C3’s focus on expanding its partner network has paid off well, with 91 of the 115 agreements closed last year from companies such as AWS, Google Cloud, and Microsoft Azure. The qualified opportunity pipeline with the partner network grew a huge 63% YoY. The company received a blockbuster response for its GenAI offerings, with 50,000 inquiries coming from 3,000 businesses during the fourth quarter; alone.
Some thoughts:
C3.ai's future holds promise, but it's definitely on the speculative side of the AI industry. Here's a breakdown of their potential and competition where it fits into the landscape of the AI revolution:
Strengths:
- Focus on Enterprise Applications: Unlike some AI companies targeting broad consumer markets, C3.ai focuses on developing enterprise-grade AI solutions for specific industries like manufacturing, energy, and healthcare. This targeted approach allows them to cater to specific needs and potentially achieve faster adoption.
- C3 AI Suite: Their core product, the C3 AI Suite, offers a comprehensive platform for developing, deploying, and managing AI applications. This can be attractive to businesses looking for an all-in-one solution.
- Partnerships: C3.ai has established partnerships with major technology players like Microsoft and Google. This gives them a leg up in terms of access to resources and market reach.
Challenges and Competition:
- Emerging Market: The enterprise AI market is still evolving, and it's not guaranteed that its approach will be the most successful in the long run. They face competition from established tech giants like Microsoft, Amazon (AWS), and IBM, all with significant resources and cloud computing expertise.
Profitability: C3.ai is not yet profitable, and it's unclear how quickly they can achieve profitability in this competitive landscape
The best choice for you depends on your risk tolerance and specific investment goals. The company offers a potentially high reward but also carries a higher risk due to the competitive landscape and its unproven track record of profitability.
The stock has had a fairly volatile year so far, but the recent rally following its fourth-quarter results has put it firmly in the green. As of now, the company is focused on growth, giving profitability a pass, but a pole position in the potentially $1 trillion enterprise AI market will ultimately will make it worthwhile. The company has sound financials, with $750 million in cash, and no debt. Our Target for this very speculative high-flyer is $50 with the Sell Price at $24. We added the stock at $22 in 2023, so we are up 34%. But is it worth the anguish or the volatility? Only YOU can decide that!

-----------------------------------------------------------------------------
The Trade Desk (TTD: $93, down 2%)
High Technology Portfolio
Pioneering ad tech company The Trade Desk released its first quarter results recently, reporting $490 million in revenue, up 28% YoY, compared to $380 million a year ago. It produced a profit of $130 million, or $0.26 per share, compared to $110 million, or $0.23, with a beat on consensus estimates on the top and bottom lines, coupled with an upbeat forecast for the second quarter. We are impressed by the profitability level – 27% after tax. That’s up there with some of the greatest companies in the market, like Apple, Google and Facebook.
During the quarter, the company was aided by continued penetration of connected TVs, with industry giants such as Disney, NBC Universal, and Roku making deeper pivots into this segment. This comes as the company’s UID2*, its alternative to the aging browser cookies, as it becomes more and more ubiquitous across the open internet, resulting in robust value for advertisers, and undeniably strong moats for Trade Desk. Unified ID 2.0 (UID2) is a non-proprietary, open standard accessible to constituents across the advertising ecosystem. It enables advertisers, agencies, ad technology companies, and ad publishers selling advertising to interoperate together in advertising workflows. The company struck a string of new collaborations and partnerships with its UID2 during the quarter, starting with Times Internet, a leading media conglomerate in India, followed by satellite TV giant, Dish Media, along with TF1 and M6, two of the largest broadcasters in France. As a result, the platform now has access to ad inventory in over 11,000 destinations across connected TV, display, mobile, and audio.
The Trade Desk isn't just another ad network; it provides a self-service, cloud-based platform for ad buyers. This platform allows businesses and agencies to plan, manage, and optimize their advertising campaigns across various channels and devices. Here's what makes them special:
- Independent and Open Platform: Unlike some ad networks that prioritize their own inventory, The Trade Desk offers an independent platform with access to a vast marketplace of ad inventory. This gives ad buyers more control and flexibility in reaching their target audience.
- Data-Driven Targeting: The Trade Desk leverages data and analytics to help ad buyers target specific audiences with greater precision. This can lead to more effective and efficient advertising campaigns.
- Programmatic Bidding: They automate the ad buying process, allowing advertisers to bid on ad impressions in real-time based on pre-defined criteria. This can help them secure better ad placements at more competitive prices.
Why They Are Leaders:
- Focus on Innovation: The Trade Desk is constantly innovating and developing new features to stay ahead of the curve in the fast-evolving advertising landscape.
- Transparency & Control: They prioritize transparency and control for advertisers. This builds trust and encourages long-term partnerships.
- Global Reach: The Trade Desk operates in a global marketplace, giving advertisers access to a vast audience.
The Trade Desk has strong secular tailwinds in its favor within the digital advertising market, which stood at $600 billion in 2023, expected to rise to over $870 billion by 2027. Global streaming giants are doubling down on advertising: Netflix with its 40 million ad-tier subscribers and Disney+ have already announced partnerships with the company to monetize their massive ad inventory.
The stock had a phenomenal year in 2023, up 60%, which has been extended this year with a YTD rally of 31%. While the valuation is anything but cheap, at 22 times sales and 120 times earnings, the massive addressable market and an impressive compound annual growth rate of 32% largely make up for it. The company ended the quarter with $1.4 billion in cash, just $240 million in debt, and $600 million in cash flow. Our Target is $100 and our Sell Price is $64. We’re raising both to $120 and $84 respectively. The stock hit $97 two weeks ago, not quite a new all-time high, as that was set in 2021 at $114. But we can see that number being broken later this year if the market holds steady and moves higher. If not, that is why we have such a tight stop. No matter how good a company is, if the overall market tanks hard, it will bring these high flyers down with it. Revenues are great – moving from $840 million in 2020 to $1.2 billion, to $1.6 billion to $1.95 billion in 2023. What worries us the most, is its low level of profitability. Watch this one closely.

-----------------------------------------------------------------------------
Workday (WDAY: $211, up 4%)
TERMINATING COVERAGE
Workday, a leading financial and human capital management solutions provider, released its first quarter results last week, reporting $2.0 billion in revenue, up 18% YoY, compared to $1.7 billion a year ago. It posted a profit of $103 million, or $0.38 per share, against -$10 million, or $0. The company beat on consensus estimates but lowered full-year guidance a bit. See below.
As always, subscription revenues led the way at $1.8 billion, up 19% YoY, with the rest coming from professional services at $180 million, up 12% YoY. The company’s 12-month subscription backlog now stands at $6.6 billion, up 18% YoY, followed by total subscription backlog at $21 billion, an increase of 24% YoY. The gross revenue retention rate came in at 95%, representing a churn of just 5% over the year.
During the quarter, the company onboarded several marquee new companies. This includes Asda, Electrolux, TopGolf, and LVHM, among others. In the public sector, the company acquired the Defense Intelligence Agency (DIA) as a customer for its Workday Government Cloud. It now counts 60% of the global Fortune 500 as customers and was named a leader in cloud Human Capital Management for 1,000+ employees by Gartner.
The company continues to double down on AI and now has 50 AI and 25 generative AI use cases in its roadmap. Workday completed the acquisition of HiredScore, an AI-powered talent acquisition and internal mobility solution. With 65 million users and 800 billion transactions on its platform each year, the company has a wealth of data to train its AI and leapfrog competitors.
Following a robust performance last year, the stock has had a rough start to 2024, and is down 21% YTD, mostly owing to its high valuation. We believe that this is unjustifiable, and overblown, considering the massive addressable market of $140 billion, and an impressive 5-year CAGR of 20%. Workday ended the quarter with $7.2 billion in cash, $3.3 billion in debt, and $2.2 billion in cash flow. Our Target is $325 and our Sell Price is $250.
We, that is, you and we have a decision to make. Do we let the company go here? Or do we buckle down and add more? We added the stock at $139 in 2018, so we are up over 50%. You, however, may have a higher entry price. Not that that makes any difference. It just feels better if you can sell and take a profit, even though the stock was at $311 in February. Revenues have been growing for the past four years, from $4.3 billion in 2020, to $5.1 billion, to $6.2 billion, to $7.3 billion in 2023. At the current rate it looks like $8.0 billion is probable for 2024. Growth appears to be slowing and we wonder: Is this 10% growth rate worth such a high valuation? The market just might have something here.
Here’s what occurred: When Workday reported quarterly earnings a week ago, it lowered its forecast for fiscal 2025 subscription revenue to between $7.7 billion to $7.725 billion from a prior call for $7.725 billion to $7.775 billion. That prompted a flurry of price-target cuts from Wall Street. This is a tiny lowering. It is such a small reduction, that you have to re-read the sentence to understand the difference. The stock was smashed. This is what the market is doing to great companies. We’re not happy about it, but it is reality. For this reason, and the slowdown in growth discussed in the previous paragraph, we are going to exit the stock. Tough decision, but the market is just destroying growth companies with slower growth in the forecast.
If you wish to stay in the stock, the knockdown of the stock by $52 a share (19%) since earnings a week ago, certainly creates a better valuation now. It’s down $100 (32%) since February. With cash of $7.2 billion and debt of $3.3 billion, the balance sheet is strong.
-----------------------------------------------------------------------------
First Solar (FSLR: $272, up 2%)
Long-Term Growth Portfolio
First Solar released its first quarter results recently, reporting $800 million in revenue, up 45% YoY, compared to $550 million a year ago. It posted a profit of $240 million, or $2.20 per share, against $42 million, or $0.40, with a beat on consensus estimates on the top and bottom lines, all driven by macro regulatory tailwinds, ever since the passing of the IRA Act in 2022.
The company has a sales backlog of 78.3 GW, up from 71.6 GW a year ago, with net YTD bookings at 2.7 GW, down from 12.1 GW. Its average selling price stands at 31.3 cents per watt, down from 31.8 cents a year ago. The company expects its bookings backlog to extend through 2030, as there is seemingly no stopping demand for rooftop solar and large-scale solar energy generation projects.
While much of the solar energy industry reels from the structural overcapacity in China, First Solar has circumvented this threat, with its focus on differentiation and its business model. The company’s cadmium telluride semiconductor technology is vastly better than the commoditized crystalline silicon modules coming from China, which are known to harbor various reliability and quality issues.
Beyond the regulatory tailwinds, the company stands to benefit from the rise of generative AI as tech giants look to transition towards green energy to operate their massive new data centers, with First Solar being the preferred choice. A typical query on ChatGPT consumes 50 times more energy than a Google Search, so the giants of AI must make this shift to solar if they want to save money and don’t want to come under criticism.
It is already up 58% YTD and is showing no signs of slowing with plenty of tailwinds in its favor, and a pole position in the market. First Solar ended the quarter with a robust balance sheet, with $2 billion in cash reserves, just $680 million in debt, and $900 million in cash flow.
Many leading analysts from UBS, Piper Sandler, and JP Morgan Chase have increased their Price Targets for the stock. UBS raised its target to $320, from $270, the highest on the Street. Our Target was destroyed in the last two weeks as the stock rallied from $187 on May 14th to its present level of $272. We’re up 40% in less than a year. At $215 it is time to raise. We love this company so we are going to best UBS and place a $325 Target on the stock. Our Sell Price of $140 is hereby raised to $240.

-----------------------------------------------------------------------------
iShares US Oil & Gas Exploration & Production ETF (IEO: $103, up 2%)
Energy Portfolio
A pure-play energy fund with concentrated exposure to oil and gas companies that are exclusively involved in exploration and production, this fund closely tracks global energy companies and is thus subject to the industry’s swings and volatility. So far this year, the fund is off to a flying start and is up 9% YTD, mainly owing to the recovery in natural gas prices following a prolonged slump over the past year.
Given a short to medium-term horizon, the oil and gas industry is always eventful, with plenty of geopolitics and macroeconomic factors coming into play. For example, right now there is the Red Sea crisis, a prolonged conflict in the Middle East, and Ukraine intensifying its attacks on Russian oil refineries, among a host of other things to factor in, that could lead to swings in global energy prices.
On the macro front, the demand from China is still weak, but a recovery is in the cards, which could push oil prices beyond the $85 mark. Apart from that, a rate cut by the Fed sometime later this year, and a recovery in demand from Europe this winter for space heating and other residential and commercial uses can all lead to a much-needed rally in natural gas prices, which remain at multi-year lows.
When taking a long-term view, there is a lot to be optimistic about oil and gas stocks. This might seem counterintuitive considering the growing environmental movements the world over, alongside new alternative energy sources, but we believe that natural gas and hydrogen will play an outsized role in this transition. This too will take anywhere from two to three decades to become a reality, and in the meantime, oil and gas giants will be reaping profits.
The Exchange Traded Fund allows investors to ride this trend with its highly concentrated portfolio, with 45% of its assets held in ConocoPhillips, EOG Resources, Marathon Petroleum, and Phillips 66. These are all companies with massive inventories and low production costs, helping generate outsized returns during bullish streaks in energy prices, while still outperforming when prices slump.
Our Target is $120 and our Sell Price is $95. This fund is a great way to own an assortment of energy companies in one transaction. We added the fund at $80 two years ago.

-----------------------------------------------------------------------------
Recursion Pharmaceuticals (RXRX: $8.28, down 10%)
Early Stage Portfolio
Recursion Pharmaceuticals, a leading AI and machine learning company in the biotech space, released its first quarter results a month ago, reporting $13.8 million in revenue, up 14% YoY, compared to $12.1 million a year ago. It posted a loss of $91 million, or $0.39 per share, as against a loss of $65 million, or $0.34 the prior year, but posted a beat on consensus estimates on the top and bottom lines.
Rising losses were largely the result of increasing R&D expenses, at $68 million, up from $47 million a year ago. This was followed by a similar rise in administrative expenses at $31 million, up from $23 million, as the company has been on a hiring spree. Revenues during the quarter were entirely from its partnership with Swiss life sciences company, Roche, which the company expects to scale further.
Recursion has plenty of value catalysts coming up over the next few quarters, which can be quite profitable for the company in a significant way. This includes five drugs in phase 2 clinical trials, each with over 100,000 potential patients worldwide, and no competitor. If the company can successfully commercialize just one of these five drugs, it can add significant value from current levels.
Its AI-enabled drug discovery platform continues to gain momentum, with potential new partnerships and the exercising of existing partnership options capable of driving top-line growth. The company’s 20 petabytes of data collected from real patients, when used with its internal AI software is a game changer for the industry, prompting Roche and Bayer to start working with Recursion.
The company’s AI play has been formidable enough to warrant a $50 million investment from Nvidia, and it has grand plans in this regard, including a next-generation supercomputer. The stock is down 16% YTD, and it stands to offer enormous value if catalysts start to align going forward from present levels. It has a robust balance sheet, with $300 million in cash, and just $50 million in debt. Our Target is $28 and our Sell Price is $8, which is getting tight. We added the stock at $10 just six months ago and it ran up to $17 in February but has since settled down. This is a speculative stock for sure. Enjoy the ride, but be careful.

-----------------------------------------------------------------------------
ARK Innovation ETF (ARKK: $42, down 4%)
TERMINATING COVERAGE
Cathie Wood's flagship Innovation ETF has had a rough start to the year and is down 16% YTD. This comes as the broader equity markets, including disruptive tech stocks, have posted a rally this year. The pullback can be attributed to its high exposure to Tesla, which has been a key detractor for the fund in recent quarters.
The fund’s overreliance on Tesla is clearly wearing it down, and alongside this, other key weak investments include Roku (down 88% from peak), Unity Software (down 90%), Pacific Biosciences (down 96$), and Teladoc, which is down 50% this year and over 95% from its peak in 2021. Ark attributes the weakness in Tesla to auto sales still being lower than pre-COVID levels, but we think the various controversies surrounding Tesla’s founder, Elon Musk, and his controversial $45 billion compensation package could have contributed just as much, not to mention his purchase of Twitter, spending half his time with SpaceX, and many other strange personal quirks that this genius brings to the table. In our opinion, the fund’s underperformance in recent quarters is largely due to it being underweight on market leaders and mega-cap stocks, which have led the rally in 2023 and this year so far.
Investors should start treating the Ark Innovation ETF like a venture capital or private equity fund, which often comes with a lock-in period lasting a few years, up to a decade. That’s how long it takes for disruptive innovations to pay off, and at current levels the stock offers robust value, making it perfect for value-seeking investors with a long enough time horizon.
We are asking ourselves some tough questions lately. Cathie Wood has clearly lost her magic. We added the stock in 2021 at $117, after it had hit an all-time high of $158. We thought it was overvalued and waited patiently for it to come down. Come down it did, but it has continued to erode for the past three years, going nowhere for the past two years, languishing in the low 40s. Why do we continue to hang on to this stock? That’s a good question. We have again been patient with this fund, but for far too long. We don’t have the time to wait any longer. There are much better places for our funds, than the many pie-in-the-sky investments she has made these past few years.
We are exiting the fund and moving on. We’d rather own more Nvidia, more Super Micro Computers, or Eli Lilly and Novo Nordisk.
-----------------------------------------------------------------------------
The Bull Market High Yield Investor
The clock is now ticking on the next Fed policy meeting on June 12. Nobody expects a rate cut or a rate hike at this point. We're more interested in seeing whether consumer inflation numbers due out that morning have any impact on Jay Powell's prepared marks: a soft or "cool" print could once again prompt a lot of talk about relaxing overnight lending rates when the moment is right, while anything hotter than expected could have the opposite effect. Whatever we see this month, it's unlikely to change the primary narrative around the Fed, which is that we'll probably be in a place where Powell and company can start relaxing in September and cut more aggressively after that.
We've been saying it for months and we were right. Short-term interest rates have peaked. People parked in money markets are unlikely to earn more on those accounts than they're making right now. And as the short end of the yield curve recedes, upward pressure on the long end will evaporate along with it. There simply won't be a reason for capital to keep flowing out of Treasury bonds into those money market accounts. And as the bond market stabilizes, long-term yields have less reason to keep climbing to the point where they spook us here in the stock market.
Add it all up and if you're looking for a relatively smooth income stream without the strain of life in the stock market, you need to lock in Treasury yields where they are. That means settling for 4-5% a year, which translates into 2-3% above where the Fed wants to guide inflation in the long term. Maybe a 2-3% real return is enough for you. We have a feeling most investors will want their money to work a little harder, which is why we're banging the drum on stocks and funds like these.
Arbor Realty (ABR: $13.68, up 2%. Yield=12.6%)
REIT Portfolio
Leading Mortgage REIT Arbor Realty released its first quarter results recently, reporting $104 million in revenue, down 5% YoY, compared to $109 million a year ago. It posted a profit or FFO of $58 million, or $0.31 per share, down from $84 million, or $0.46. This was a mixed quarter for the company, with a beat on the top line, but a miss at the bottom, largely owing to a big drop in loan originations across the board due to the tougher mortgage business, due to 7% 30-year loans.
Agency loan originations during the quarter stood at $850 million, down from $1.1 billion a year ago, which Arbor had warned against a couple of months back. The company believes that the first two quarters of this year will include peak stress, as interest rates remain higher, with a possibility of a rate cut in late 2024. Borrowers are deferring taking loans in anticipation of lower rates.
Arbor’s structured portfolio, however, continues to do well, albeit with a small YoY decline, with $256 million in originations, down from $266 million the prior year, with a total of 59 loans being originated, the same as last year. Similarly, the company’s servicing portfolio hit new highs during the quarter, at $31 billion, up 8% YoY, compared to $29 billion a year ago, with a net servicing revenue of $31 million.
The company has done remarkably well throughout the pandemic, and the volatile interest rates environment that followed. This was largely owing to its diversified business model with multiple countercyclical income streams. For instance, if interest rates continue to remain high, originations will take a hit, but the mortgage servicing rights portfolio will increase in value due to low refinancing rates. Who is going to refinance a 3-4% loan at today’s 7% level?
This has helped it maintain its distributable earnings in excess of dividends, and a payout ratio of at least 90% throughout, all the while maintaining its book value, currently at $13.02. Over the past few months, Arbor has held outsized reserves to hedge against delinquencies and has continued to shore up liquidity, resulting in a robust balance sheet, with $910 million in cash, $12 billion in debt, and $550 million in cash flow.

Realty Income Corporation (O: $53, up 2%. Yield=5.9%)
REIT Portfolio
Realty Income, "the Monthly Dividend Company," is one of the largest investors in commercial real estate across the globe and recently reported $1.2 billion in revenue, up 40% YoY, compared to $940 million a year ago. It posted a profit or FFO of $790 million, or $0.94 per share, against $680 million, or $1.03, with a beat on top-line estimates, but a miss at the bottom, making it a mixed performance.
The company is structured as a real estate investment trust, and its monthly dividends are supported by the cash flow from over 13,250 real estate properties owned under long-term lease agreements with commercial clients. During the quarter, the company invested $600 million across a wide range of properties, with a weighted average yield of 7.8%. A significant chunk of these investments, or $320 million was allocated towards assets in the UK and Europe, with an average yield of 8.2%. The company invested $38 million in a US-based data center joint venture, marking its first investment in the space.
Another big milestone during the quarter was the completion of the $9.2 billion acquisition of Spirit Realty Capital, with the new combined firm valued at $63 billion, and Spirit shareholders set to own 13% of it. The CEO of Arbor stated that the transaction is immediately accretive. This gives Realty Income significantly more size, scale, and diversification across asset, geographical, and demographic lines, along with the potential for realizing various cost and operational synergies.
This was an eventful quarter for the company in terms of capital activity, starting with a secondary offering to raise $550 million an at average price of $56.93 per share. Followed by $450 million in 4.750% senior unsecured notes due on February 2029, and $800 million worth of 5.125% senior unsecured notes due on February 2034, resulting in $4 billion in liquidity, to fund $2 billion in investments during the year.
The stock is down by nearly 10% so far this year, but there are a few key catalysts that could turn things around, most importantly a rate cut by the Fed, later this year. What makes this REIT truly impressive is its diversification across classes, assets, and geographies, leaving it well off in all market conditions. It ended the quarter with $680 million in cash, $26 billion in debt, and $3 billion in cash flow.

Invesco Municipal Trust (VKQ: $7.93, up 2%. Yield=5.1% tax free, or the equivalent of 7.8% taxable)
High Yield Portfolio
The Invesco Municipal Trust is a closed-end fund that invests in tax-free municipal bonds, with the aim of generating steady current income for investors, with limited volatility and downside risks given a long-term horizon. It is a perfect product for retirees and other conservative investors seeking consistent tax-free income, but don’t want to stomach any excessive market risks.
The fund posted a stellar rally starting in October when the Fed officially ended its hawkish stance, but as the anticipation of further rate cuts soured, it has been increasingly rangebound over this year. It is, however, making the most of the higher nominal yields in recent months.
Following two consecutive years of net outflows, $140 billion in 2022, and $8 billion in 2023, muni bonds are set for a turnaround this year. Bonds posted negative performance in April, mostly owing to the better-than-expected employment and inflation data, prompting a hawkish reaction from the Fed. New issuances, however, swelled to $45 billion, 29% over the 5-year average, and were oversubscribed 3.8 times. After several months of limited supply, this quarter presented an opportunity for funds to add yield to their portfolios at an attractive risk-reward proposition.
Despite its phenomenal 22% rally since mid-year 2023, the fund offers an attractive discount of 12% to book value, while providing tax-free yields of 5.15%. This makes for a very impressive proposition, not just for conservative, income-seeking investors, but for speculators seeking value as well. With its extensive 30-year track record and a low expense ratio of just 1.3%, this fund is for those who want no risk from equities.

Good Investing,
Todd Shaver, Founder and CEO
The Bull Market Report
Since 1998
December 10, 2017

by Todd Shaver | Dec 10, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
The countdown to Christmas is underway, which means this year is coming to an end and the focus is turning to the outlook for 2018. This bull market has been nothing short of spectacular. We expect high-single digit returns in the stock market again in 2018. Our view is supported by rigorous analysis from Guggenheim Research, which points to the US not reaching a recession until late 2019 or 2020. Specifically, they say, the business cycle is one of the most important drivers of investment performance. It is therefore critical for investors to have a well-informed view on the business cycle so portfolio allocations can be adjusted accordingly.
At this stage, with the current U.S. expansion showing signs of aging, focus is now just gradually shifting toward the timing of the next downturn. Using history as a guide, however, you will find that it is possible to get an early read on when the next recession will begin by analyzing the late-cycle behavior of several key economic and market indicators. Together, they have provided advance warnings of a downturn. The best indicator is the Leading Economic Indicator Index, which compiles all the various indicators into one data set. The 10 components of the index cover weekly hours worked, manufacturing orders, initial jobless claims, building permits, new private housing units, interest rate spreads, and consumer sentiment. An analysis of these metrics suggests that the current expansion won’t end until late 2019. So keep your foot on the gas!
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks where you can still make good money, including: Tesla, Twilio, PIMCO Dynamic Income Fund, Amazon, Google, First Solar, and more.
BMR Companies & Commentary
Tesla (TSLA: $315, up 3%)
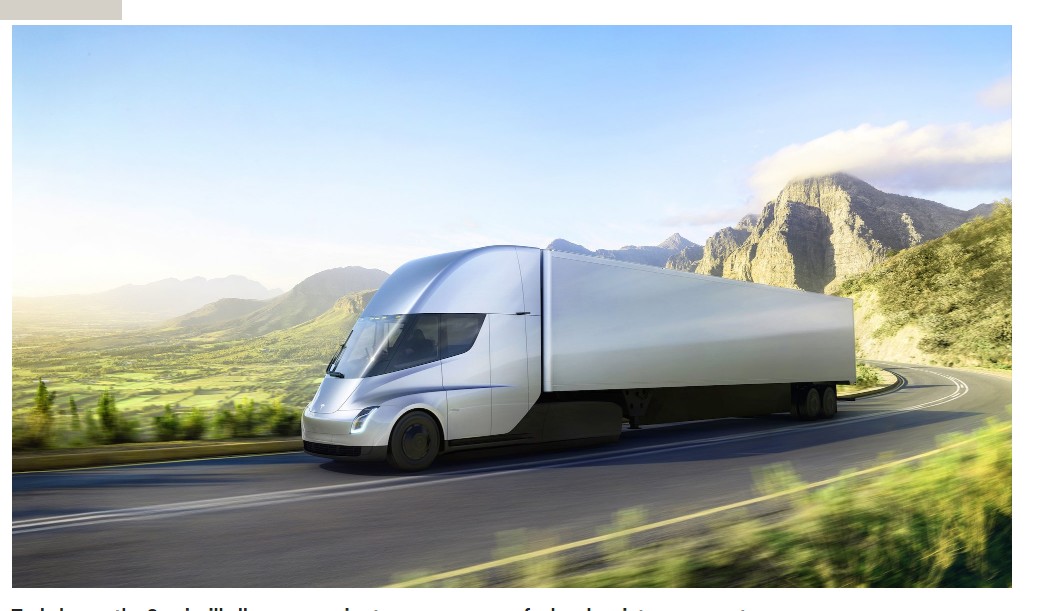
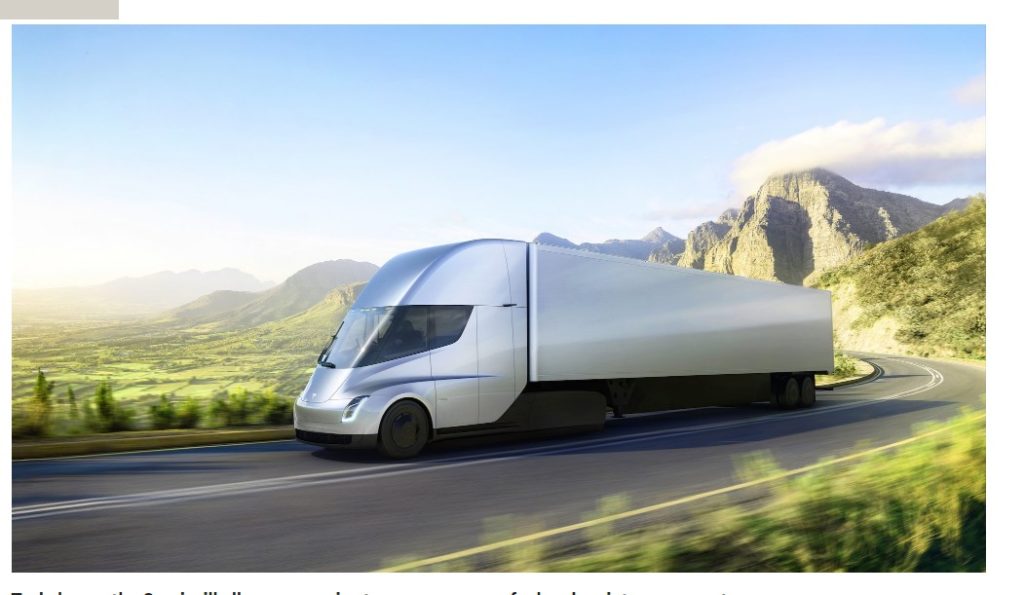
Anheuser-Busch has placed an order for 40 of Tesla’s new all-electric Semi trucks. The maker of Budweiser seeks to reduce fuel costs and vehicle emissions, along with other companies across sectors through the Tesla revolution.
Anheuser-Busch plans to use the trucks for shipments to wholesalers within 150 to 200 miles of its brewery locations - well within the 500-mile range that Tesla Chief Executive Elon Musk has promised. The vehicles would be deployed among the brewer’s dedicated fleet of 750 trucks, which bear the company’s branding but are owned and managed by outside carriers.
Anheuser-Busch’s preorder is still tiny relative to the broader heavy-duty-truck market, which produces 250,000 to 300,000 big rigs a year. Anheuser-Busch spends about $120 million on fuel each year for its dedicated fleets and long-haul transportation by for-hire carriers moving beer between breweries and wholesalers. The company wants to cut its carbon footprint by 30% by 2025, and has invested in alternative-fuel vehicles, such delivery trucks that run on compressed natural gas. This is big stuff!
BMR Take: Tesla is currently losing money, but the consensus 2020 EPS outlook is over $10. At some point we see all the innovation, like electric trucks, turning into major profits. Tesla remains one of the most exciting businesses in America.
--------------------------------------------------------------------
Twilio (TWLO: $25, down 5%)
Twilio hosted its analyst day in San Francisco this week. It was a good day. Twilio did a nice job of conveying the momentum in its business and how it plans to continue to drive rapid revenue growth at scale, but it did not guide to gross margins for 2018, and suggested that near term, gross margins may still move around a bit, even though management is confident in its longer-term target of 60-65%. The stock was under modest pressure accordingly.
Twilio provided three new disclosures to help investors better understand these gross margin dynamics, including: 1) gross margins have consistently been around 60%; 2) gross margins are negatively impacted by the international mix, which was 53% in 3Q17 for core voice and messages, far higher than the 24% figure Twilio discloses for the international revenue breakdown by account location; and 3) gross margins are positively impacted by application services revenue, which was $10 million in 3Q17, up 100% from a year ago and representing 9% of total revenue.
The company reinforced that demand is not an issue for Twilio. For example, the COO shared a story about how one sales representative was “drowning in leads.” He also disclosed that Twilio receives more than 7,000 “data-driven alerts,” or leads per month.
Twilio claims that it won 80% of new business opportunities against the top-five competitors in the first three quarters of the year. According to management, the top reasons customers select Twilio include: 1) trust; 2) omni-channel capabilities; 3) flexibility; and 4) innovation.
Twilio Investor Day tone was positive, says Baird. They remain positive on the company's competitive position and long-term growth opportunity fueled by increasing cloud communications use cases. They also remain positive on its stronger revenue growth and ability to improve margins long term. Baird reiterated their Outperform rating and $37 price target on Twilio shares.
BMR Take: Twilio currently trades at a big discount to where comparable high-growth cloud communications companies trade. We think this valuation disconnect will correct itself, leading to strong stock appreciation. With revenue exploding at greater than 60% per year towards $600 million by 2019, we see a compelling value here. The stock has been painful to watch but one of these days, Wall Street will take notice (again) and we will all be rewarded with our patience. If you can't take the pain, then you may just want to switch to some of the larger, safer investments like Apple or Google. We’re going to be right on this. Eventually. Watch and wait.
--------------------------------------------------------------------
PIMCO Dynamic Income Fund (PDI $31, up 1%)
With rising geopolitical tensions and good money been made in the stock market, we stress the importance of increasing your bond allocation. Pimco Dynamic Income is a great way to do it.
The portfolio maintains moderate exposure to US interest rates, where Pimco continues to emphasize the intermediate portion of the yield curve. However, due to historically low yield levels and continued flattening of the yield curve, the fund has some exposure to the long end of the US Treasury curve. Outside of the US, Pimco also has modest exposure to UK rates and an underweight to Eurozone rates.
Pimco maintains a focus on non-agency Mortgage-back securities (MBS) purchased at discounts to par, which provide a potential source of income and capital appreciation, as prices in this asset class continue to be supported by limited new supply and a strong US housing market. Pimco maintains exposure to corporate credit, including an allocation to high yield bonds in the Financial sector. The banking exposure is focused on slightly more risky opportunities that are more lucrative, given how stable the banking system is at this moment. PDI has exposure elsewhere in corporate credit, including allocations to select attractive names in Retail, Media, and Telecom. Pimco’s exposure to emerging markets remains highly selective and is focused on issues offering attractive spread premium and real yields coupled with strong underlying fundamentals, such as select Brazilian and Russian corporates, as well as Argentinian sovereign debt.
BMR Take: Pimco is offering just less than a 9% yield. And the fund is up over 20% this year. For fixed income this is amazing. This fund is a great place to increase your fixed income exposure and protect against unexpected drawdowns in the stock market.
--------------------------------------------------------------------
Amazon (AMZN: $1,162, flat)
The road is not always easy. Not even for Amazon.
Maine has canceled Amazon’s application to become a pharmaceuticals wholesaler. Their applications were canceled because they did not contain all the required information, and no action had been taken by the applicant to complete them, according to the state Department of Professional & Financial Regulation.
Amazon had submitted three pharmaceutical applications in October – all three expired on Friday, Dec. 1, according to the board’s online license check. Analysts are trying to decide whether Amazon merely stumbled and missed a local deadline, or if Amazon abandoned the license applications because it realized they were unnecessary if all it wants to sell are medical devices, not pharmaceuticals.
We have confidence Amazon will get it right!
BMR Take: The innovation machine is disrupting the globe. EPS estimates are now up over $20 by 2020. Amazon continues to have a long way to run. Our Target is $1200, but in our heads we are looking for $1500 and then $2000. We can’t tell you when the latter will occur, but we sure would like to see the former happen sometime next year.
--------------------------------------------------------------------
Google (GOOG: $1,037, up 3%)
Google is about to launch a small but useful update to Google Maps that will give you live guidance and interactive real-time notifications during your journey. The idea here is to give you real-time updates while you are traveling.
To get started, you search for your transit directions in Google Maps as usual. So far, so good. What’s new here is that you’ll soon be able to tap a “start” button at the bottom the screen with the details about your route and get live updates as you walk or ride on your local buses and trains.
Our understanding is that Google Maps will even remind you to get off your bus or train when you get close to your stop. That’s definitely useful when you’re traveling somewhere new. The notifications on the lock screen are also new. One nifty feature here is that they are interactive, so you can scroll right through your journey’s steps.
While Google Maps always did a good job of giving you detailed directions, the process generally involved keeping track of your own progress along the route. With this update, transit notifications become a bit more like using Maps for walking, biking and driving. This update is to go live soon.
BMR Take: Google is always advancing the world and this is just the latest example. When you can make the world a better place, revenue and profits follow. Google is expected to earn $57 of EPS by 2020 up from $32 this year. What a great place to invest!
The information here isn’t earth-shattering – (it’s hard to come up with earth-shattering news every single day (but we try)), but we’re trying to make a point here and that is that this company continues to innovate every day. A little here and a little there and eventually it goes to the bottom line. Revenues for the past few years look like this: $55 billion in 2013, $66 billion in 2014, $75 billion in 2015 and $90 billion in 2016. What about 2017? They’re on track for $105 billion. They made $19 billion after tax last year and they are going to better that for 2017, and with $100 billion in cash on the books and virtually no debt, we can’t think of a better place to put some of our hard-earnings savings.
--------------------------------------------------------------------
First Solar (FSLR: $70, up 16%)
A lot of bad press is confusing the outlook for renewables. Don’t get confused. Renewables are the future and First Solar is going to play a critical role.
What is being said? Less than a year into President Trump’s time in office, clean energy developers face a slew of unanticipated threats from the White House and Republicans in Congress that could slow the industry’s growth in ways unimaginable just a year ago. During Trump’s presidential campaign, energy analysts were skeptical of his promise to preserve the coal industry at the expense of wind and solar. Even the most aggressive attempts at regulatory rollback couldn’t reverse the market forces driving the decline in coal, they reasoned.
But the administration has not stopped at mere deregulation. From the threat of a subsidy for coal-fired power plants to a tax bill that hurts the financing of clean-energy projects, Republicans in Washington have launched a campaign against renewable energy that includes market interventions that alarm other industries, including Oil and Gas. Even if these measures never come to fruition (advocates of transitioning from fossil fuels are pushing back) the changed mood in Washington threatens to undermine the confidence of companies planning to invest in renewables.
BMR Take: First Solar is taking the Energy sector forward with the most sustainable technology on the market. Expected EPS of nearly $4 by 2020 is up from $2.50 this year, but the 10-year outlook is where the real money is. This company is just getting started. Our Target is $65, but the stock has blown through this. So we hereby raise our Target to $78 and our Sell Price from $45 to $61.
--------------------------------------------------------------------
--------------------------------------------------------------------
Economic Calendar
JOLTS Job Openings
Monday, December 11th, 10 AM Eastern
Period: October
Actual: N/A
Consensus: 6,100,000
Prior: 6,093,000
PPI ex-Food & Energy NSA
Tuesday, December 12th, 8:30AM
Period: November
Actual: N/A
Consensus: +2.3%
Prior: +2.4%
Initial Claims
Thursday, December 14th, 8:30 AM
Period: December 9th
Actual: N/A
Consensus: 240,000
Prior: 236,000
Capacity Utilization
Friday, December 15th, 9:15 AM
Period: November
Actual: N/A
Consensus: 77.2%
Prior: 77.0%
--------------------------------------------------------------------
--------------------------------------------------------------------
Some Tidbits – Apple, Home Depot, Cloudera, Bitcoin
Apple (AAPL: $169, down 1%) is confident that apps removed from the China app store will be reinstated, Reuters says. Apple's CEO Tim Cook said the company is optimistic that apps that were pulled from its China App Store will be reinstated.
Also, Dialog Semiconductor is losing staff to Apple, Business Insider reports. Apple is continuing to hire away designers and engineers from Dialog Semiconductor (DLGNF), one of its suppliers. Around 28 Dialog engineers and designers have moved to Apple between March 2016 and now.
Also, the new tax plan would cut $47 billion from Apple's tax liability, The Financial Times reports, if Republicans push through their current tax plan, making it the biggest beneficiary of the legislation now working its way through Congress.
--------------------------------------------------------------------
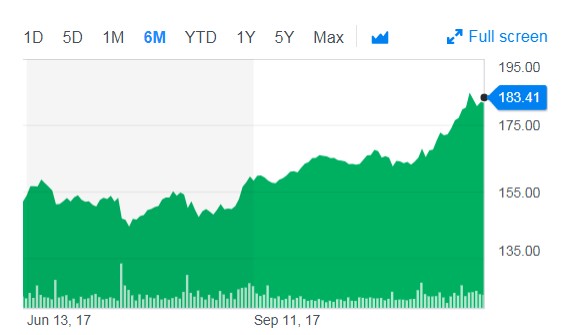
Home Depot (HD: $183, up 2%) set a new all-time high this week. It is now worth $215 billion. Wow. The company announced a $15 billion stock buyback, and the initial reaction on the Street was a slight sell-off. Silly.
How’s this for a 6-month chart?
--------------------------------------------------------------------
Cloudera Reports Strong Revenues
Cloudera (CLDR: $16.84, up 6%) reported that revenue rose to $95 million from $67 million in the year-ago period, a gain of 42%. Profits were in the negative, so although we are pleased with the revenue growth, we’re not happy with the losses. The stock had a little bump last week and it may go a bit higher, but it is not going to $30 or higher where it ought to be until it starts actually making money. We love this company but realize this is a multi-year investment from here. Patience is key here. But our patience is certainly running thin. The quarter was strong, so that gives us hope.
Bitcoin (BTC-USD: $14,840) has a market cap of about $250 billion, about the size of Visa. It was quite a week, as it rose from the $11,000 just one week ago. In the interim it hit $17,000 or so, and futures trading starts Sunday (the 10th).
Bitcoin Chart for the Past Month

--------------------------------------------------------------------
--------------------------------------------------------------------
The High Yield Corner
By Michael Foster
While the stock market went nowhere fast last week, high yield investments were a bit more mixed. We saw strength in municipal bonds for the first time in a long while, as this was overdue. The uncertainty regarding tax reforms caused some selling, but now the market is realizing that muni bonds are vastly oversold, which is helping to bring some money back into the market. Additionally, the slightly more risk-averse market is helping some money flow into muni bond funds, driving them up again.
As a result, Nuveen AMT-Free Municipal Credit (NVG: $15.68, up 2%) and Invesco Municipal Trust (VKQ: $12.57, up 2%) both had a good week, meaning the strong buying opportunity is mostly over. It’s not entirely over, however. Both funds are trading at about a 6% discount to NAV on average, a bit lower than the 5% discount we saw for much of 2017. What’s much more encouraging is the positive change in NAV we’ve enjoyed throughout 2017 - these funds are up about 5% on average on their net asset value even after their 5% dividend payouts. That means these dividend payouts remain sustainable and investors can expect a strong total return in addition to the tax-free income stream these funds provide. We wouldn’t be surprised if we saw more investors jump into the muni market, driving these funds higher and their discounts lower.
Elsewhere in the high yield world, we saw growing discontent. Specifically, Government Properties Income Trust (GOV: $18.29, down 3%) had a challenging weak on no news. This is largely a result of continued concern that Government Properties is overly levered and highly dependent on government agencies who are squarely in the majority Republicans’ crosshairs when it comes to cutting expenses wherever possible.
Of course, neither of these facts have changed in the last week, but admittedly the 8% and 7.5% yields that this stock offered earlier in the year were too low to compensate for the risks that the fund’s portfolio afforded.
Some context is important here. The Bull Market Report first recommended this stock back in April of last year when it was yielding 9.5%. Since then, the stock has given a near 14% total return to investors thanks to a slight bump in price and a consistent 43 cent quarterly dividend payout.
The Bull Market Report did not recommend selling this fund during its run-up earlier in 2017 for one specific reason: income sustainability. The most crucial metric to look at with REITs is FFO* and its relation to dividend payouts. Over the last 12 months, this REIT’s FFO was $2.15, while the dividend is an annualized $1.72. That’s a 125% dividend coverage ratio, slightly short of our preferred 130% dividend coverage target. But that shortfall is compensated for by the higher yield.
* Funds From Operations
To put that into context, let’s think about another beaten-down REIT: Omega Healthcare Investors, Inc (OHI: $28, up 1%), which has around a 130% dividend coverage ratio and a 9.4% dividend yield. With such a strong and sustainable income stream and a high yield, these are ideal contrarian income plays despite the justifiable concerns about the fundamentals. With Omega, the worry is that there are too many skilled nursing facilities and lower-than-expected demand. With Government Properties, the worry is that there is going to be depressed demand from a belt-tightening government.
These concerns are well compensated for by yields over 9%. When you get to double-digit yields (which is very unlikely with Omega but not impossible with Government Properties), you’re getting paid too much for the risks. We believe there is a chance of seeing its stock drop to a level where yields are 10%, which makes it a hold right now but not an absolute great buy. But when it comes to the sustainability of the dividend, we clearly see no risks at all to the dividend for a long time - in fact, possibly for several years.
How many years? To answer that, we need to look at the duration of outstanding leases in Government Properties’ portfolio. At 5.1 years, 28% of the company’s leases will expire before 2020. And in the next 5 years, almost 60% of the company’s leases will expire.
This is a double-edged sword. On the one hand, there is a risk that the company won’t be able to lease those properties to new tenants, causing occupancy rates to fall, income to fall as well, and the dividend to be increasingly at risk. On the other hand, there’s an opportunity for the company to lease those properties to those tenants or new tenants at the same or higher (possibly much higher) rents. This latter scenario is how we feel. The government needs the space and the record of the government in cutting down its size is, as you know, abominable.
So what is the likelier scenario - falling occupancies or rising rents? Bears are arguing for the former, and we would argue that that scenario is already priced in. However, falling occupancies is more unlikely than the market is expecting for a couple reasons.
Firstly, commercial leasing activities are going up. According to Jones Lang LaSalle, one of the biggest commercial leasing firms in America, leasing activity is at its highest point in 2 years and it’s trending higher. Government Properties has been shifting away from government leasing to office leasing, so it will benefit more and more from this trend. Thus the chances of finding new tenants paying higher rents is actually pretty good.
Secondly, there’s a paradoxical market lockup in commercial real estate REITs despite strong rent growth. Office-space REITs are one of the most heavily discounted (infrastructure and data centers are the most premium priced) in large part because of the market jitters about future occupancy rates, which paradoxically is forcing more conservative fiscal decisions among office REITs like Government Properties. But we have clearly hit a bottom in terms of pessimism, and when enthusiasm comes back to office space REITs, which will likely come as soon as the market notes the strong growth in leasing activity and rent growth, companies like Government Properties will be able to expand even more.
That means patience is in order. Expect more negativity and worries about Government Properties in the short term. But the fears about its soon-to-expire portfolio are overblown, and when the market realizes this, more capital will flood into the stock. It may take until 2019, when 18% of the company’s portfolio expires. If those spaces are re-leased at the same or higher rates (which seems inevitable given the strength in the commercial real estate market), expect the stock to rise. Best to hold the stock now, collect the income, and wait for that bump in a couple of years.
Good Investing,
Todd Shaver, Founder and CEO
The Bull Market Report
Since 1998
November 12, 2017
by Todd Shaver | Nov 12, 2017 | Weekly Newsletter 7pm Sunday
[Note that the formatting is not up to our normal layout. We are having some editing issues. Next week should be better.]
The Weekly Summary
The big story right now remains central banks. The reversal of easy central bank monetary policies across the globe has begun to reverse. Quantitative easing had a meaningful favorable impact to asset prices to the upside. The removal of this stimulus will work in reverse. Accordingly, investors should be prepared for more volatility in the months ahead. Major central banks say they want to normalize monetary policy, which suggests higher interest rates and the eventual end of nearly a decade of quantitative easing. As widely expected, the US Federal Reserve said in September that it would begin the multiyear process of reducing its $4.5 trillion portfolio of US Treasury and mortgage-backed bonds. But it also confirmed that another interest-rate hike is likely in December and we could see three more hikes in each of 2018 and 2019. By this time next year, investors will be staring at a completely different market environment.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks and one not so favorite including: First Solar, Opko Health, Apple, CBRE Group, Twilio, and Andeavor.
BMR Companies & Commentary
First Solar (FSLR: $62, up 3%)
First Solar designs and manufactures solar modules using a proprietary thin film semiconductor technology that is one of the lowest cost in the world. The firm’s objective is to reduce the cost of solar electricity to levels that compete on a non-subsidized basis with the price of retail electricity in key markets throughout the world. What a lofty goal and an exciting opportunity!
What is the most recent progress to report? First Solar has confirmed that PlantPredict, the company’s solar photovoltaic energy prediction software, has been used to generate the reference energy predictions in the sale of three utility-scale projects totaling more than 350 MW.
PlantPredict is a sophisticated solar energy modeling tool designed to develop energy estimates for utility-scale solar PV installations. Easy to use with advanced modeling options, PlantPredict reduces uncertainty to generate more accurate energy predictions. More than 500 companies have already used PlantPredict to model energy predictions for their solar sites.
The transactions demonstrate that the cloud-based modeling tool has gained acceptance by lenders and asset owners as a bankable primary resource in analyzing and predicting performance of utility-scale solar projects.
This is a lot of jargon. What it means is that there remains big demand out there for solar.
BMR Take: First Solar is doing $3 billion in sales and $2 of EPS right now. Looking down the road, we think there is plenty of room in the overall market opportunity for sales and EPS to double. Now that is the kind of growth we love to find.
----------------------------------------------
Opko Health (OPK: $5.50, down 16%)
Opko took an unfortunate nose dive on its earnings report this week. Revenue of $264 million badly missed the consensus for $319 million and was down from $298 million a year ago. OPKNet loss was $46 million compared to a loss of $15 million for the comparable 2016 period.
What the heck happened?
Rayaldee commercial activities continued to progress, but just not as much as expected. Total prescriptions for Rayaldee, as reported by IMS, increased 66% during the three months ended September 30th compared to the three months ended June 30th. Opko expanded its sales force from 35 to 71 as of October 1st. The commercial and medical science liaison teams now total more than 80 professionals.
BMR Take: Many are saying to be patient; that Rayaldee still has big time long term potential and this is just one of multiple opportunities in front of Opko; that revenue is forecast to double from $1.0 billion to $2.0 billion by 2020. Some say that if we see this top line growth, profitability is going to come quickly, and when that happens, the stock is off to the races.
Well, we say hogwash. We are VERY DISAPPOINTED in this company. They have one of the biggest hype machines out there and we have fallen for it. We have waited and waited, being very patient, as the stock goes down down and down.
Look, if you wish to stay in an wait another year, more power to you and I hope the company crushes from here and the stock goes to $15.
But we are OUT. We added the stock 14 months ago at $10 and exit Monday at $5.50. Not happy about this one.
----------------------------------------------
Apple (AAPL: $175, up 2%)
Augmented reality (AR) is a big theme in the markets. The technology is going to shake things up. This means some people are going to make money and some people are going to lose money. Apple is on the right side of the trend.
Apple is working on a augmented reality display. In the company’s most recent financial results conference call, Apple CEO Tim Cook once again made it clear that AR is at the top of his agenda, saying it will “change the way we use technology forever.”
Of the new iPhones and a new version of iOS just released, all boast augmented reality as a selling point. Apple says the A11 Bionic chip inside both the iPhone X and the iPhone 8 series is specifically designed for AR.
At least 13 brokerages raised their price targets on the stock, with Citigroup making the most bullish move by raising its price target by $30 to $200.Of the 37 analysts that track the stock, 31 had a “buy”, or higher rating. None had a “sell”. With the latest brokerage actions, at least nine Wall Street analysts now have target prices that put Apple’s market value above $1 trillion. Drexel Hamilton is still the most bullish raising their target price further to $235.
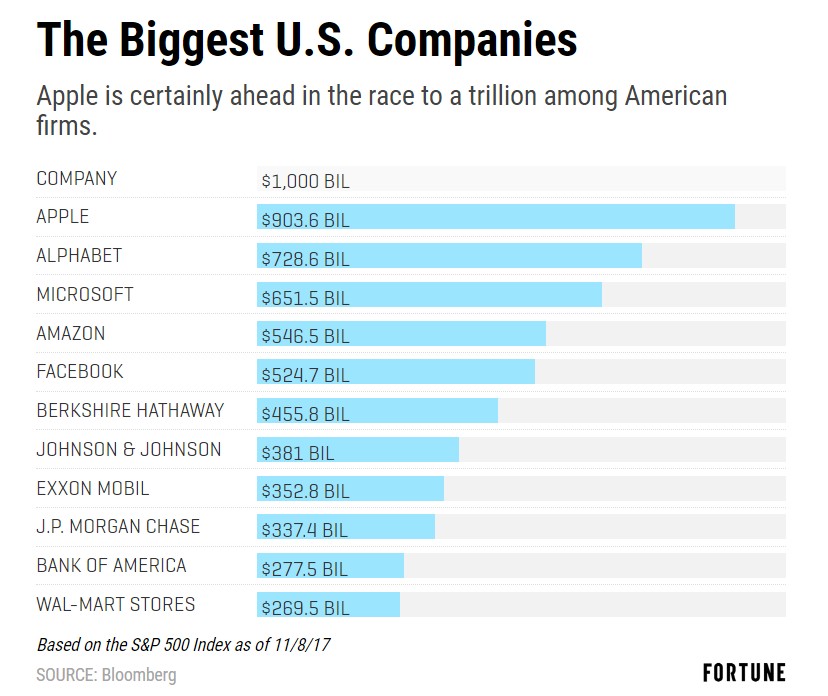
Apple has 5.17 billion shares outstanding and could reach the $1 trillion-dollar market cap level if its shares rose to $194.
Apple is already the largest market cap stock in the S&P 500 and made up 4.5% of the index's market cap as of Friday's close. If Apple's market cap rose to $1 trillion, the stock would be 4.75% of the S&P 500's market cap, ranking Apple ninth when looking at the stocks with the largest percentage of the S&P's market cap at year-end since 1980. IBM holds the top four spots with AT&T taking the next two and Exxon and Microsoft (in 1999) rounding out the top eight.
If Apple's stock can reach the $1 trillion market cap some on Wall Street say that it validates the belief that Apple is not just a smartphone business but a platform.
BMR Take: Apple did $9.21 of EPS this year and estimates call for greater than $11 next year. AR technology is the future and Apple’s ability to participate supports EPS growth continuing on like we are seeing now for a long time ahead. Apple set a new all-time high last week and since the stock has passed our Target of $170, we hereby raise our target to the level to which the market cap will reach $1 trillion. That number is $194. Our Sell Price remains: “We would not sell Apple.”
CBRE Group (CBG: $41.50, up 4%)
Never higher. CBRE has never been higher. CBRE is arguably the leading real estate company on the planet. As a highlight of how locked in the company is, look at CBRE Research’s 2017 Tech-30 report that was just published where they demonstrated exceptional expertise. The company ranked the strength of tech job growth across 30 North American office markets, which is creating stability and demand-driven performance through occupancy gains and rent premiums. Four key points are highlighted below.
--- Tech jobs grew four times faster than the national average. San Francisco was the top high-tech job growth market for the sixth year in a row.
--- Eighteen markets added more tech jobs over the past two years than the prior two-year period.
--- Tech’s share of major leasing activity has nearly doubled to 19% over the past five years, resulting in strong occupancy and net absorption gains.
--- Desirable tech submarkets are priced at a premium, while emerging submarkets often offer discounts. The overall average asking rent of tech submarkets is priced at a 16% premium.
BMR Take: We are staring at the company’s EPS power closing in on $3. This stock remains a compelling value at the current level. We don’t see the company doing anything but maintaining and growing its leading market share for the foreseeable future.
----------------------------------------------
Twilio (TWLO: $25.50, down 15%) on Earnings Report
Revenue reported was strong, and you know how we feel about revenue. We will tell you what happened, and let’s stay focused on the long term.
The company lost $0.08 versus $0.04 a year ago. Revenue was $101 million versus $72 million a year ago. The good news is that revenue beat the consensus of $93 million. Moreover, the company guided to a better outlook for the remainder of the year.
So what the happened here? Uber.
While total revenue growth of 41% was strong, we believe it is important to look at the underlying growth of Twilio’s core business. In particular, we consider base revenue excluding Uber, which came in at $87 million, up 63% from a year ago. Revenue from Uber hit $14 million in 4Q16 and came in at $5 million in 3Q17, down 53% y/y. Management expects a modest sequential decline in Uber revenue in 4Q17. The loss of Uber business continues to weigh on results.
Total revenue rose to $100 million from $71 million. Management itself had called for a net loss of $0.08 per share on sales near $92 million. The adjusted loss was right in line with that forecast, but Twilio crushed its own sales expectations.
For the upcoming quarter, Twilio expects an adjusted loss per share of 6 cents and revenue of $103 million. Analysts are predicting an adjusted loss per share of 6 cents and revenue of $99 million.
Jeff Lawson, Twilio’s Co-Founder and Chief Executive Officer said, “We hit a number of exciting milestones in Q3, including our first $100 million revenue quarter, our first enterprise license agreement for our higher level software products, and the launch of Twilio Studio. With Twilio Studio, the visual builder for Twilio, we can accelerate our customers’ roadmaps and help an even larger set of users build on our platform. We are excited by the size, scale and diversity of what new and existing customers are creating with Twilio.”
Recent Business Highlights – released by the company:
46,500 Active Customer Accounts compared to 34,400 a year ago. Twilio Studio was introduced in the third quarter, giving clients a simple drag-and-drop tool to simplify and accelerate their production efforts. Twilio already offers separate production tools for popular platforms such as Android and iOS, but the new Studio streamlines the development process in ways that had not been available before.
Announced our commitment to meet the new GDPR (General Data Protection Regulation) requirements coming from the EU, using this as an opportunity to raise the bar for data protection worldwide for all of our customers.
Expanded the reach of our Super Network by announcing the availability of Twilio phone numbers in more than 100 countries.
Average revenue per user rose 18% to $8,000.
Cash position strong: Twilio held $284 million of cash equivalents at the end of the third quarter, down from $289 million in the second quarter and $306 million by the end of fiscal year 2016.
Guidance: – released by the company:
Full year ending December 31, 2017:
Total Revenue - $387 million
Loss from operations (millions) $22.0 to $23.0
Net loss per share - 0.22 to 0.23
BMR Take: The good news is Twilio continues to innovate and add net new customers at a remarkable clip (3,100 in 3Q17), which is driving strong underlying revenue growth. The company remains one of the fastest top line growers in all of cloud computing.
This company is one the most frustrating that we follow. With another stellar report like we describe above, any normal stock would be up 10%. Not Twilio. Down 15%, now well below our Sell Price of $29. We are going to stay the course but you might get tired of waiting and sell in order to redeploy these assets into something better like Nutanix or Square. With that said, we believe Twilio should be a $50 stock, a long way from where it is today. But again, top line growth will win in the end. Do you and we have enough patience to endure these losses? That is the ultimate question.
----------------------------------------------
Andeavor (ANDV: $107, down 3%)
Could oil breech $80 before Christmas? Some options traders think so. With oil trading near its highest level in two years, some traders are betting that the price rise could have more room to run.
A total of 48,000 option contracts traded over the last few days that would profit most if crude spikes before Christmas, including several large individual trades. They all expire on Dec. 21.
Oil prices have rallied in recent weeks as OPEC supply cuts help to rebalance an oil market plagued by oversupply. More recently, growing tensions between Saudi Arabia, OPEC’s largest oil producer, and some of its neighbors helped prices break above $60 a barrel for the first time since 2015.
Andeavor Reported Third Quarter 2017 Results on November 8th.
Earnings of $550 million, or $3.50 per share; results included the following pre-tax items
Returned $345 million to shareholders including $252 million in share repurchases; they expect to repurchase $300 million of shares in 4Q17
Total retail and branded stations up 27% year-over-year to over 3,100 stores
On October 30th, Andeavor closed its $1.7 billion acquisition of Western Refining Logistics
New totals for Andeavor
Number of Refineries: 10
Refining Capacity: 1.2 million bpd
Employee Count: More than 13,000
Retail Sites: More than 3,100
Barrels of Storage Capacity: More than 46 million
Miles of Pipelines: More than 5,300
Marine, Rail and Storage Terminals: 40
Natural Gas Processing Complexes: 6
States where they operate: 18
BMR Take: Higher oil prices above $80 could be a huge positive for many companies including our beloved refiner Andeavor. Recall, Andeavor’s net asset value is $120 and the stock still trades an unwarranted discount. We think more stable energy markets are the first step needed for good sentiment to return to the oil patch stocks like Andeavor. And we’re certainly on the way with crude being so strong of late.
----------------------------------------------
Upcoming Economic News
PPI ex-Food & Energy
Tuesday, November 14th, 8:30 AM Eastern
Period: October
Consensus: 2.2%Prior: 2.2%
Retail Sales ex-Auto Wednesday, November 15th, 8:30 AM
Period: October
Consensus: 0.20%
Prior: 1.0%
Initial Claims
Thursday, November 16th, 8:30 AM
Period: 11/11
Consensus: 235,000
Prior: 239,000
Housing Starts
Friday, November 17th, 8:30 AM
Period: October
Consensus: 1,193,000
Prior: 1,127,000
----------------------------------------------
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
The markets seem to be firing on all cylinders. Is there anything that could derail it before year-end? About all we can see is the Russian investigation (none and no chance), the tax-cut drama (possibly, but more likely to cause a correction rather than a derailment), a government shutdown (slim if any chance at all) or a major Fed rate hike (little to no chance).
A couple of things have caught our attention, however. What usually derails a bull market is a recession. At this point, we don't see the usual suspects that signal a coming recession, such as widening credit spreads, deteriorating market internals, collapsing commodity prices, falling new orders or falling earnings. In fact, it is just the opposite.
However, two things are not making sense from a historical perspective. First, with near full employment and accelerating worldwide growth, inflation remains stubbornly low. This is usually not the case. Inflation signals rising prices and continued rising earnings. It should be readily apparent but it simply isn't expressing itself even at this stage of the earnings growth cycle.
Secondly, if there is one warning signal for an approaching recession that is more reliable than all the others, it might be an inverted yield curve. Since January, the spread between the 10-year Treasury and the 2-year Treasury has fallen from about 1.30% to 0.75%. In our experience, whenever we have seen accelerating revenue growth, rising earnings, potential tax cuts – i.e. so many positives – the yield curve should be steepening, not flattening. Maybe we are experiencing a "new norm" in the markets, or it "is different this time" (the four most dangerous words in our industry), or this is going to be normal as part of the 4th Industrial Revolution we have supposedly entered (artificial intelligence, augmented reality etc.). In any event, we are going to closely follow the lack of inflation and the yield curve because neither is "confirming" this bull market rally as each would normally do if one looks back at the history of the market.
----------------------------------------------
Square (SQ: $39, up 6%) Continues to Shine
A few Wall Street firms had some new announcements on Square this week. The target raised to $38 from $34 at Stephens. They believe the stock "can grind higher" following the company's Q3 report. They still sees Square as likely to change the game for Small and Mid-sized business payments and thinks the likelihood of it achieving true "platform for small business" status gets more likely every quarter.
Square price target raised to $33 from $23 at Craig-Hallum
Square price target raised to $35 from $24 at SunTrust. SunTrust said that it is entering a period requiring heavier investment which will weigh on margin expansion. They said that Square trades at a significant premium of about 60-times FY18 EBITDA relative to 13-times for its peer group.
GoDaddy (GDDY: $48) announced two new integrations with Square that help small businesses thrive with online and offline selling and payment capabilities. By collaborating with Square, GoDaddy is making this an easy reality for tens of millions of people building small businesses. Integrating GoCentral Online Store and Square online payments enables small businesses to easily sell their products and services online and in person through a single Square account and GoDaddy website. The second integration provides service-based businesses, such as personal trainers, hair stylists and photographers, the ability to book client appointments online, sync calendars using GoCentral, and get paid using Square. Payment transactions can be processed online, in-person or both without switching accounts.
Square target raised to $41 from $31 at Cantor Fitzgerald citing accelerating revenue growth. The firm expects Square's "rapid growth" to continue and further margin expansion going forward. He notes that Gross Payment Volume growth remained above 30% in the quarter.
Square target raised to $41 from $31 at RBC Capital. The firm says the Q3 beat and raise for 2017 outlook is indicative of the company's ability to drive its products into existing partners and expanding to larger merchants.
BMR Take: This one has a long way to go on the upside.
----------------------------------------------
Options Corner – All about Square
From time to time we like to bring you an interesting options trade. We like to do long-term bullish trades on stocks, unless we find one that is going to go bankrupt in which case we can design a trade to profit from the demise of a firm using puts.
Square has been knocking the cover off of the ball of late. We added the stock at $17 in March of this year and it is now $39, setting a new all-time high on Friday, so we are up 130% in 8 months, giving us an annualized return of ……. Well, you get the point! A great stock pick. A great stock. Better yet: A great company. With a market cap of $15 billion now, it is moving into the big leagues. We have said quite a few times that Square would be a great buyout candidate for one of the big boys (Amazon, Microsoft, Apple, etc.) but they better move fast before the stock hits $20 billion.
And in fact, we think a $20 billion valuation is quite possible next year. That would equate to a $52 stock. Can that happen here with Square? We certainly think so.
An options trade can produce much bigger returns than this 33% increase, if it were to happen. But guess what? OPTIONS ARE RISKY! Please repeat after us. Options are very risky.
OK. Let’s get started.
We love long term options called LEAPS. They expire in January as long as they have at least six months of life. So the January 2018 options aren’t called LEAPs any more. But the Jan 2019 options are. And soon we should see the Jan 2020 options start trading. We can’t wait.
We like to buy options that are in the money. With the stock at $39, the 35s are $4 in the money. Better yet the 30s are $9 in the money. They are worth $9 but they trade for $13. Why is that? The $4 is the TIME PREMIUM. And note that that time premium will go to zero eventually as it approaches the end of its life in January 2019.
In order to pay for the time premium we like to SELL calls against the long LEAP to recoup this time premium and also to help us get our cost down on the option that we bought. Let’s look at some real numbers.
Buy the Jan 2019 30 LEAPs for $13,Sell the June 45 call for a little less than $6.
The cost of this trade is now $7 for an option WORTH $9. Do you understand this? If not, go back to the top of this article and re-read. These options discussions are confusing the first time, but It WILL come to you if you re-read this 3-4 times. We are serious.
Now, let’s say the stock goes up a bit and is selling at $45 in June. Your June option is going to expire worthless (great) and now you SELL a January 2019 call, say the 50 call, for approximately $7. (We are not sure of these numbers because it is so far into the future but we think this is about right -- we hope you get the point.) The cost of the trade is now zero. You are in this trade for zero dollars. (Gosh, we love this trade!)
Now, let’s tally up. If the stock goes to $50 or higher by January 2019, you will be left with an option worth $20 ($50-$30). If you had bought 10 options for $7,000, they are now worth $20,000, almost a triple (185%), with a stock that went from $39 to $50 or 28%. If you had put $25,000 in this trade (the equivalent of buying 640 shares of Square) you would now have $75,000 and that’s real money.
This options trade will more than likely take lots of tweaking of your position and the return could be better or worse depending on where the stock goes. No one is going to hand you a triple without a little bit of work. But it could be a super trade IF the stock heads to $50.
The downside is that the stock goes down to $30. You will lose money but if you religiously sell calls against your position, you can get your cost down to close to zero, thus minimizing your losses.
Note that if this all-options trade is too risky or confusing to you, you can just do a normal covered call trade by buying the stock and selling calls against it. If you were to buy 1000 shares at $39 for $39,000 and the sell the calls as described above, you would bring in $6000 for the June $45 call and $7000 for the January $50 call giving you a purchase price of $26,000. If the stock goes to $50 you have a $50,000 position, and a return of 92%. Not bad.
But, again, lots of “ifs” in these scenarios. Invest with caution.
----------------------------------------------
The High Yield Corner
By Michael Foster
Last week, AstraZeneca PLC (AZN: $33, down 5%) reported strong revenue and earnings above expectations, but that wasn’t enough to keep the stock from being the biggest loser of the week for the Bull Market Report’s high yield portfolio. A deeper dive into the results can explain what happened—and why this isn’t really a cause for concern.
To start with: revenues rose 9.3% on a year-over-year basis in the third quarter to $6.23 billion with solid EPS of $0.54, which was a little shy of expectations: analysts were expecting just 55 cents per share in earnings. In their press release, the company highlighted weak sales in the U.S. as a cause of the weaker earnings, while also pointing out that weakness was offset by major growth elsewhere: emerging markets were up 5%, China was up 12%, and Japan was up 3%. Those numbers were all higher on a constant currency basis.
But the U.S. weakness is a large part of the stock decline. AstraZeneca pointed to continued weakness in Symbicort as a cause for the weakness; the asthma drug’s challenges have been a major issue for this company, which analysts see as being heavily reliant on for future sales. Nonetheless, a closer look at the drug pipeline indicates there are other sources of growth to come.
More specifically, AstraZeneca highlighted that Lynparza, a breast cancer drug, has received priority reviews in America and Japan, while Imfinzi, a lung cancer drug, has received the same in America while also getting regulatory acceptance in the EU and Japan. A total of 7 drugs got new regulatory approvals as of the end of the reporting period, including two type-2 diabetes drugs that will obviously have tremendous appeal for this widespread ailment.
So the company’s pipeline looks fine. The focus on Symbicort unquestionably overlooks that fact, and provides a buying opportunity at this current price—provided the pipeline remains healthy.
Elsewhere in high yield investing, we saw a really mixed week despite the market’s weakness towards the end of the week. This is pretty unusual—high yield tends to be more volatile in REITs, high yield bonds, and BDCs, but we didn’t see that happen yet. That could mean more aggressive selling is yet to come in late 2017, especially as tax-loss harvesting becomes more commonplace, but that doesn’t change the fundamental strength and attractiveness of many high yield assets.
There are exceptions, however. Municipal bonds were relatively untouched by last week’s jitters, possibly as risk-averse investors were adding to municipal allocations as a result of what they saw in the stock market. Invesco Municipal Trust (VKQ: $12.34, flat) saw little movement on strong volume while Nuveen AMT-Free Municipal Credit (NVG: $15.36, up 1%) gained slightly. Both remain high-quality municipal bond funds with above-average yields and excellent management teams. Neither looks significantly overpriced right now.
Bigger news came from the REIT world, but the news had little effect. Welltower (HCN: $68, up 2.5%) had strong earnings, with FFO per share of $1.08 a 2 cent jump from the prior quarter and NOI up 4.1% on same-store senior housing operations. RevPAR also gained by 3.9%, which helped the company’s revenue rise nearly 1% to $1.1 billion for the quarter. FFO was a 3 cent beat over expectations, and higher earnings guidance (the company now expects normalized FFO per share of $4.19 to $4.25 for the full year) make Welltower’s valuations even more attractive, especially after the stock price remained stuck for the week. Defying negativity in the skilled nursing facility world, Welltower’s massive size and market penetration are proving stores of value and investor safety; the stock is a better buy now than it’s been for most of this year.
*Revenue per available room
That’s it for earnings news this week, but a lack of major news didn’t stop Government Properties Income Trust (GOV: $18.76, up 2%) from having a strong week, thanks in small part to the continued recovery from last month’s anxiety that the company’s earnings results at the end of October proved to be a paranoid non-issue. However, protracted worries about Omega Healthcare Investors, Inc (OHI: $28, down 1%) and their very disappointing earnings are keeping shares down and the yield up at the 9% level. That more than compensates for the risks, which makes this a very appealing option for investors who accept that the dividend growth is likely going to end in 3-5 years’ time. The market is discounting a cut to dividend growth much sooner, making this an irrational price and a good bargain right now.
Elsewhere, we are seeing growing anxiety in Collateralized loan obligations (CLO) and high yield corporate bonds, but that hasn’t stopped AllianzGI Equity & Convertible (NIE: $21, unch.) and PIMCO Dynamic Income Fund (PDI: $30, up 1%) from proving resilient. That’s in no small part thanks to the high-quality management teams of each, which have wisely avoided the more exotic high-yielding CLO markets and shifted towards much safer MBS’s and away from the riskiest junk bonds. The market is rewarding both with price stability. That may not last - after all, irrational selling is still very much a thing in modern markets - but that just means a buying opportunity will open up. Neither fund shows any indication of weakness despite the broader worries growing in the credit sectors.
Good Investing,
Todd Shaver, Founder and CEO
The Bull Market Report
Since 1998
(Again, sorry about the crazy formatting this week.)
October 23, 2017
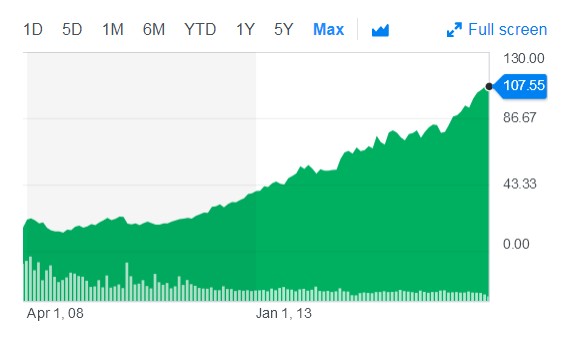
by Todd Shaver | Oct 23, 2017 | Earnings Preview 12 PM
Eli Lilly (LLY: $88)
Bull Market Report Target Price: $88
Bull Market Report Sell Price: $76
Earnings Date: Tuesday, 9:00 AM ET
Consensus: 3Q17
Revenues: $5.5 billion
EPS: $1.03
Year Ago Quarter Results
Revenues: $5.2 billion
EPS: $0.88
Key Things to Watch For in the Quarter
Eli Lilly is expected to report a 17% increase in earnings per share and a 5% increase in revenues for 3Q17. This moderate growth in revenues accompanied by a strong growth in EPS indicates a reduction of the firm’s costs. Although Lilly has only beaten analyst estimates in two of the past four quarters, the stock still trades up 12% since this time last year. By cutting costs in SG&A Eli Lilly has freed up capital for R&D, which will help drive future sales and contribute to the company’s prolonged growth.
Our Target has been reached, so we hereby raise it to $96.
-----------------------------------------------------------------------------------------------------------------------------
Equity Residential (EQR: $66)
Bull Market Report Target Price: $85
Bull Market Report Sell Price: $55
Earnings Date: Tuesday, 4:00 PM ET
Consensus: 3Q17
Revenues: $620 million
EPS: $0.33
Year Ago Quarter Results
Revenues: $605 million
EPS: $0.56
Key Things to Watch For in the Quarter
Analysts expect Equity Residential to report a 2% increase in revenues and a 41% decrease in earnings per share for 3Q17. The stock has beaten estimates in each of the past four quarters, and has still managed to appreciate 8% over the past year. This is most likely a result of the shrinking of the company’s earnings over the past two years. The stock is currently trading 4% off its 52-week high and has been trading with lower volume than it did in the beginning of the year, indicating it could be oversold.
-----------------------------------------------------------------------------------------------------------------------------
Visa (V: $107)
Bull Market Report Target Price: $110
Bull Market Report Sell Price: We would not sell Visa
Earnings Date: Wednesday, 8:00 AM ET
Consensus: 3Q17
Revenues: $4.6 billion
EPS: $0.85
Year Ago Quarter Results
Revenues: $4.2 billion
EPS: $0.78
Key Things to Watch For in the Quarter
Analysts estimate Visa will report a 9% increase in revenues and a 9% increase in earnings per share for 3Q17. Visa has surpassed estimates in each of the past four quarters, contributing to the stock’s 30% appreciation since this time last year. Visa has seen significant increase in sales over the past few years and we expect this growth to continue as consumers shift from cash to online and credit card payments.
How’s this for a nice looking chart over the past five years? Where would you say it is headed?
-----------------------------------------------------------------------------------------------------------------------------
United Parcel Service (UPS: $120)
Bull Market Report Target Price: $125
Bull Market Report Sell Price: $106
Earnings Date: Thursday, 8:00 AM ET
Consensus: 3Q17
Revenues: $15.6 billion
EPS: $1.45
Year Ago Quarter Results
Revenues: $15.0 billion
EPS: $1.44
Key Things to Watch For in the Quarter
UPS is expected to report a 4% increase in revenues and no change in earnings per share for 3Q17. Despite only having beaten estimates in two of the past four quarters, the stock has still managed to climb 10% since this time last year and is currently trading 16% above its 52-week low. Companies like UPS and FedEx are perfectly positioned to benefit from the growing trend of online shopping. Growth in e-commerce has been accelerating over the past few years, up 16% from 2016 alone, and shows no signs of slowing down. The stock currently yields 2.75% making it a good investment for investors who are seeking both growth and income.
-----------------------------------------------------------------------------------------------------------------------------
Celgene (CELG: $123)
Bull Market Report Target Price: $150
Bull Market Report Sell Price: $125
Earnings Date: Thursday, 9:00 AM ET
Consensus: 3Q17
Revenues: $3.4 billion
EPS: $1.87
Year Ago Quarter Results
Revenues: $3.0 billion
EPS: $1.58
Key Things to Watch For in the Quarter
Celgene is expected to report a 13% increase in sales and a 18% increase in earnings per share for 3Q17. The stock has beaten analyst estimates in each of the past four quarters and was up nearly 50% this year until recent weeks when it announced that it would not continue to phase 3 trials for its Crohn’s disease drug. The stock pulled back 17% on the announcement and opened a window of opportunity for investors who felt the stock was overbought at its previous levels. Celgene continues to invest heavily in R&D and we expect it will continue to produce growing sales with the rest of its pipeline.
The stock is below our Sell Price and we covered Celgene in our report that went out Sunday evening the 22nd. Please review for our thoughts on the stock.
-----------------------------------------------------------------------------------------------------------------------------
Bristol-Meyers Squibb (BMY: $64)
Bull Market Report Target Price: $77
Bull Market Report Sell Price: $51
Earnings Date: Thursday, 10:30 AM ET
Consensus: 3Q17
Revenues: $5.2 billion
EPS: $0.77
Year Ago Quarter Results
Revenues: $5.0 billion
EPS: $0.77
Key Things to Watch For in the Quarter
Analysts estimate that Bristol Meyers will report a slight 4% increase in sales and no change in earnings per share for 3Q17. Bristol has beaten estimates in three of the past four quarters, contributing to the stock’s 30% gain over the past year. The company generates about 30% of its revenues from oncology related drugs, and we expect the stock to continue growing as it gains more market share.
We hereby raise our Sell Price from $51 to $59.
-----------------------------------------------------------------------------------------------------------------------------
Alphabet (GOOG: $978)
Bull Market Report Target Price: $1100
Bull Market Report Sell Price: We would not sell Alphabet
Earnings Date: Thursday, 4:30 PM ET
Consensus: 3Q17
Revenues: $27 billion
EPS: $8.33
Year Ago Quarter Results
Revenues: $22 billion
EPS: $9.06
Key Things to Watch For in the Quarter
Analysts estimate that Alphabet will report a 22% increase in revenues and an 8% decrease in earnings per share for 3Q17. The stock is up 21% over the past, which has been driven by its ability to beat analyst estimates in three of the past four quarters and to grow revenues and earnings. Alphabet’s institutional owners have been increasing their positions in the company over the past six months by 3%, indicating they believe in the long-term success of the business. Alphabet has recently released new products that have put pressure on some of the largest tech companies like Apple and Samsung.
Our Price Target is $1000, but we think somehow that has been an uncorrected error and we believe it was and should be $1100. Thus we hereby make the change. The all-time high is $997 set just last week, and if the stock market remains stable, we expect to see the stock blow through $1000 and move significantly higher by the end of the year.
-----------------------------------------------------------------------------------------------------------------------------
First Solar (FSLR: $49)
Bull Market Report Target Price: $55
Bull Market Report Sell Price: $39
Earnings Date: Thursday, 4:30 PM ET
Consensus: 3Q17
Revenues: $800 million
EPS: $0.85
Year Ago Quarter Results
Revenues: $ 690 million
EPS: $1.22
Key Things to Watch For in the Quarter
While First Solar is expected to increase its revenues by 15%, analysts estimate that earnings per share will decrease by 30% for 3Q17. The stock has beaten earnings estimates in each of the past four quarters. We expect First Solar to continue with its positive performance as the year ends and on into 2018 as well.
This has been a long slog with this firm. We have been patient and have stuck with it and now the stock is moving up to where it belongs. This is a great company management is on the right path and the firm is certainly in the right business.
-----------------------------------------------------------------------------------------------------------------------------
Amazon (AMZN: $972)
Bull Market Report Target Price: $1,100
Bull Market Report Sell Price: $900
Earnings Date: Thursday, 5:30 AM ET
Consensus: 3Q17
Revenues: $42 billion
EPS: $0.52
Year Ago Quarter Results
Revenues: $33 billion
EPS: $0.03
Key Things to Watch For in the Quarter
Amazon is expected to report a 27% increase in sales and a 94% decrease in earnings per share for 3Q17. We expect this large reduction in EPS is from the company’s increased spending on R&D, which should pay off with large revenue increases down the road. Despite having only beaten estimates in two of the past four quarters, the stock is still up 17% since last year. In each of the two quarters it missed, the stock pulled back no more than 5% and provided investors with an entry opportunity. With the firm’s continued domination of e-commerce, we remain bullish on Amazon here at The Bull Market Report.
-----------------------------------------------------------------------------------------------------------------------------
Microsoft (MSFT: $79)
Bull Market Report Target Price: $84
Bull Market Report Sell Price: We would not sell Microsoft
Earnings Date: Thursday, 5:30 PM ET
Consensus: 3Q17
Revenues: $23 billion
EPS: $0.72
Year Ago Quarter Results
Revenues: $22 billion
EPS: $0.72
Key Things to Watch For in the Quarter
Analysts expect that Microsoft will report a 4.5% increase in sales and no change in earnings per share for 3Q17. The stock has climbed 30% over the past year, especially having beaten estimates in each of the past four quarters. Microsoft is another great investment for those seeking both growth and income. The stock has appreciated 180% over the past five years while paying out a 2% dividend. In addition to improving product sales, Microsoft has made a number of upgrades on its Windows operating system, driving growth over the years.
-----------------------------------------------------------------------------------------------------------------------------
Ventas (VTR: $63)
Bull Market Report Target Price: $82
Bull Market Report Sell Price: $61
Earnings Date: Friday, 8:00 AM ET
Consensus: 3Q17
Revenues: $880 million
EPS: $0.45
Year Ago Quarter Results
Revenues: $865 million
EPS: $0.42
Key Things to Watch For in the Quarter
Ventas is expected to report a slight 2% increase in revenues and a 7% increase in earnings per share for 3Q17. Despite having beaten estimates in three of the past four quarters, the stock is down 8% since last year. With most of its properties focused in senior housing and healthcare facilities, Ventas’s long-term growth looks very positive. Ventas owns a highly diversified portfolio of nearly 1,300 seniors housing and healthcare properties in the United States, Canada and the United Kingdom. The underperformance of the stock has given investors the opportunity to enter into this high dividend yielding (5%) growth stock.
September 17, 2017
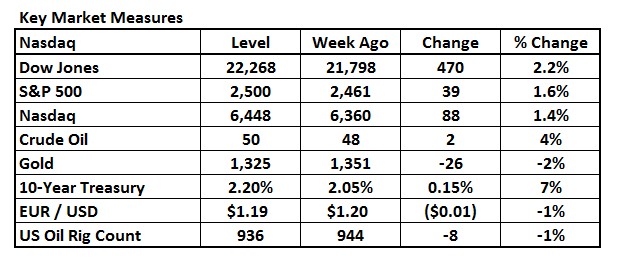
by Todd Shaver | Sep 17, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
Equity markets ended the week up, again! New all-time highs were set Friday (again) with all three indices. The threat of conflict with North Korea can’t stop the bull market. Gridlock in DC isn’t shaking confidence. The unemployment rate is low. GDP growth is fair though under pressure from severe weather. It’s really a “Goldilocks” economy and a market backdrop of not too hot and not too cold. The biggest threat might simply be the Fed’s Janet Yellen who must unwind a $4.5 trillion balance sheet. The September Fed meeting is upon us and nobody is expecting a rate hike because of the pressures on GDP growth from weather. Though pay attention to plans for the Fed balance sheet as these moves could be worth as much as three rate hikes depending on the pace of unwinding. We are as eager as you to see what happens.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks where we think you can still make good money, including: First Solar, Apple, Twilio, Bristol-Myers, Amazon, Google, and Square.
BMR Companies & Commentary
First Solar (FSLR: $51, up 8%)
First Solar caught a lot of press this week as Deutsche Bank upgraded the stock to a Buy and said the stock is heading to the mid-60s.
What is there not to like? First, US demand is so strong it is driving pricing higher. Beyond the typical demand there is something else happening. Customers are flocking to make purchases ahead of the ruling on the section 201 tariff.
What is this? There is a high likelihood of the International Trade Commission finding injury in the section 201 case. This case basically makes a determination on the safety of the product. A favorable decision is expected to result in 2018 margins between 20 and 30%, against a 2017 rate of 17.5%. This regulatory relief for First Solar is welcomed!
Lastly, monetization of the phase 1 California Flats Solar Project coupled with the anticipated sale of the company’s stake in 8Point3 Energy Partners (CAFD: $14.49) could result in upward revisions to EPS estimate.
BMR Take: Putting it all together, First Solar is in the right spot at the right time. We recognized it early. Now we see a big Wall Street investment bank get behind the name. Yea! With EPS running around $2.50, the stock is not expensive here considering the quality and future of the franchise.
Apple (AAPL: $160, up 1%)
Apple unveiled its latest slate of new products on Tuesday including a new $1,000 iPhone that is sure to bring out aficionados of the company's devices when they arrive in local stores later this month and again in early November.
In a live-streaming event, Apple introduced a new version of its Apple Watch and Apple TV set-top box, plus two new phones, the iPhone 8 ($700) and a larger iPhone 8 Plus ($800) version. But the highlight was the iPhone X (pronounced “10”), a thin, sleek phone that has 3D face-recognition technology, a state-of-the-art camera, and a $1000 price tag -- double the price of the first iPhone that Apple introduced 10 years ago.
The other products will be available for pre-order starting Friday and should hit stores a week later.
The $1,000 price tag is causing all sorts of buzz. Will consumers pay that much? Well, most think so because you just make monthly payments through a plan and not a lump sum. Is there new technology that is exciting? Yes, from face recognition for security to the largest screen yet. All in all, the timing of the launch could push sales from 4Q to 1Q, but we expect Apple to sell a lot of phones.
BMR Take: Apple is going to do over $250 billion of sales this year. This is a staggering amount of money pouring into the company’s bank accounts from consumers who love Apple. Remember, as long as Apple continues to be a fan-favorite for customers, we think there is a huge opportunity for the company to do more and more services on top of selling hardware. The future is bright!
Remember, 65% of Apple is now the iPhone. And every new user is going right to the App Store to buy apps, increasing the Services business incrementally. Recurring income, baby. That’s what it’s all about.
We have a few notes we made from a research report from UBS Securities.
Apple Price Target - $180 (We are at $170) with a $195 potential upside.
iPhone growth in F18/19 – UBS expects double-digit unit growth in F18 and single-digit growth in F19 driven by a growing installed base and high retention rate. They expect a bulge of F15 iPhone 6 owners to upgrade in F18, creating a strong year if not a "supercycle." Supply and pricing could affect the degree of growth.
“Apple innovation to drive long-term revenue growth?
“Augmented reality (AR) is an area where Apple could leapfrog competition in offering a superior user experience. Features will take time to be released as the technology must reach a level of maturity suitable for Apple's brand. Other products like the Watch and AirPods are slowly
becoming material to the business and represent another way to monetize a loyal base of customers.
“The installed base continues to grow double digits and retention rates remain high. The retention rate for Apple above 80%, at a seven point premium to the Android retention rate. There is pent-up demand for the iPhone 8, with over a third of the base consisting of handsets older than two years old, the highest ever.
“Around the world Apple is gaining share everywhere except China. China remains a wildcard. Encouragingly, shipments to Mainland China stabilized in June. Our survey indicates interest in the next iPhone is similar to last year.
“At a P/E of 15x, Apple is trading at near an all-time high valuation. This suggests the market is pricing in a strong product cycle in F18 with double-digit EPS growth. It's also possible investors are gradually re-rating the multiple to recognize the strength and stability of the brand.”
Twilio (TWLO: $31, up 4%)
Twilio is one of the most exciting growth stories out there. And the CEO’s recent Bloomberg TV interview re-ignited our conviction in the story.
As you have been following the growth of Twilio lately, you’ll know it’s an exciting addition to the communications space. Twilio is a developer platform that powers communications for more than 40,000 global companies, including Netflix, Airbnb, and Lyft.
Twilio has emerged as a simple way for companies and software teams to begin adding communications capabilities to their applications in the form of text, video, and voice, providing companies with the flexibility that they need to implement more engaging customer experiences into their daily operations.
Twilio was built around the growing desire to provide a better customer experience for end-users and companies alike. Across numerous industries, enterprises have begun to recognize that the only way to truly differentiate their businesses from other competitors in the marketplace, is to give their customers an experience that is seamless, integrated, and engaging. Unfortunately, it’s difficult to achieve that level of service when your communication technology is not all run from one central place.
BMR Take: Sometimes the daily news is just noise. You have to step back and do a simple fundamental analysis. What does this company do? Why is the value proposition a winner? What is the big picture story? Twilio has this nailed in spades and the CEO provided a great reminder of that to the equity markets this week talking on Bloomberg.
Look at revenues for the past three years. $89 million in 2014. $167 million in 2015. $277 million in 2016. (Note: they’ve already done $180 million in the first six months of 2017.) With revenue growing greater than 30% and nearing $500 million, the momentum is there and we are still early. Repeat, we are still VERY EARLY on this company. Where is this company’s growth going to stop? (Hint: it isn’t.) Take a hard look at owning this company.
Bristol-Myers Squibb (BMY: $62, flat)
At Bristol-Myers, patients are at the center of the universe. The company’s vision for the future of cancer care is focused on researching and developing transformational Immuno-Oncology (I-O) medicines for hard-to-treat cancers that could improve outcomes for these patients. The I-O opportunity is a breakthrough for cancer, and Bristol is a key player.
Bristol is in fact leading the scientific understanding of I-O through its extensive portfolio of investigational compounds and approved agents. The company’s differentiated clinical development program is studying broad patient populations across more than 50 types of cancers with 14 clinical-stage molecules designed to target different immune system pathways. Bristol continues to pioneer research that will help facilitate a deeper understanding of the role of immune biomarkers and how patients’ tumor biology can be used as a guide for treatment decisions throughout their journey.
This week Bristol announced some good data on I-O drugs. This reaffirmed the market’s confidence is Bristol’s ability to execute on the important I-O market opportunity.
BMR Take: Bristol is a top franchise is the Drug industry. The stock has been badly beaten down for about a year but now is coming back, as top franchises always do. With nearly $4 of EPS potential, this drugmaker is a screaming deal in our view.
Amazon (AMZN: $987, up 2%)
The future is here and guess what? Amazon created it! Alexa, Amazon's voice-activated digital assistant for the home, has learned a new skill -- dispensing medical information about first aid from one of the best-known names in medicine, Minnesota's Mayo Clinic.
The information is accessible by speaking to the Amazon device, which users appreciate if they're busy doing something with their hands, like putting aloe on a burn or examining someone who has stopped breathing.
The device advises in its robotic-female voice to begin cardiopulmonary resuscitation for one minute and then call 911 if the person is unresponsive from suffocation. If the user asks for it, the device will go on to discuss specific techniques for doing CPR on an adult, child, or baby.
BMR Take: Amazon is the innovation machine and to see Echo break through into the medical field is a just another key data point about the possibilities of the future. With over $20 of future EPS power or more, Amazon is unlike any stock ever in the history of the world. We are strong believers in the future of Amazon.
Google (GOOG: $920, down 1%)
There is talk that Google is considering making a $1 billion investment in Lyft to take on Uber. This could be exciting!
Google and Lyft can really help each other. With the possibility of autonomous driving being central to its future, Lyft badly needs a solution. Google is considering putting up to $1 billion into Lyft in a move that would see it become one of Lyft’s biggest shareholders at a crucial time.
Lyft is far smaller than Uber and when it comes to market places that can be fatal. For money to be made, generally, one player needs to have 60% share or be twice the size of its nearest competitor. In the US, Uber has already achieved this hallowed status and in theory should be able to crush Lyft simply by applying sustained competitive pressure until Lyft runs out of money.
Google could be the solution for Lyft to emerge as a fierce Uber competitor.
BMR Take: Google is a tech giant, a robust franchise, and reasonably priced versus EPS of $40. The all-time high is $988, set in early June, so it is off 7% from that high. With driverless cars a key part of the future economy, and Google paving the way, we are excited about what a Lyft investment could mean and think the general market will be too if the deal is announced. UBS Securities has a $1,080 Price Target with a $1,410 upside. We have $1000 as our Target, but will raise it when it hits.
Square (SQ: $28.50, up 7%)
Square is at all-time highs. Last week we talked about Square getting into banking. That was all the buzz. This week Jack Dorsey, CEO, is talking a hard look at blockchain technology and what it could mean for Square. This company is on the leading edge of innovation all the time.
You’ve been hearing or reading a lot about blockchain but you probably still aren’t entirely certain how to define it. You’re not alone. It’s something that Jack Dorsey, the CEO of Square (and CEO of Twitter), describes as the “next big unlock”.
Blockchain is often defined as a ledger that enables secure, encrypted transactions. Some financial and technical experts have described it as analogous to the early days of the internet: it’s a framework or backbone for transactions.
But Dorsey also went beyond that interpretation of it, adding that the ability to “distribute and decentralize the ledger enables proof of work, and proof of one entity, in an untrusted network.” “Even if there’s a hostile entity or a mistrust in the network,” Dorsey continued, “we can still account for value creation and the transfer of values as well.”
BMR Take: If Square can get blockchain right, the company could take on the likes of Visa and/or MasterCard to change the world of payments how we know it. How exciting. This is sending the stock to new all-time highs and we are only at the beginning stages of Square’s life as a publicly traded company. Note that JP Morgan and Bank of America as well as Goldman Sachs are experimenting with blockchain. With a market cap of just $11 billion we see very big times ahead for this innovative company. And they could be bought out for $15-18 billion in a whisker by one of the big boys.
Upcoming Economic News
Housing Starts
Tuesday, September 19th, 8:30 AM ET
Period: August
Consensus: 1,175,000
Prior: 1,155,000
Fed Funds Target Upper Bound
Wednesday, September 20th, 2:00 PM
Consensus: 1.3%
Prior: 1.3%
Leading Indicators
Thursday, September 21st, 10:00 AM
Period: August
Consensus: 0.20%
Prior: 0.30%
BlackRock Consensus Ratings on the Street
(BLK: $429, up 3%)
4 Hold Ratings, 8 Buy Ratings
Consensus Price Target: $448
9/08/2017 Barclays $475
8/18/2017 Jefferies Group $440
7/18/2017 Morgan Stanley $476.
7/18/2017 Deutsche Bank $455
7/14/2017 Keefe, Bruyette & Woods $440
6/19/2017 Bank of America Corporation $450
BMR Take: Market cap is $69 billion. Huge. They manage over $5.7 trillion of assets. HUGE. All-time high is $443 set in July. We think this is easily breakable. The Street likes this stock. We like this stock.
Cloudera Consensus Ratings on the Street
(CLDR: $18.38, down 12%)
4 Hold Ratings, 4 Buy Ratings
Consensus Price Target: $23
9/8/2017 J P Morgan Chase $24
9/8/2017 Morgan Stanley $19
9/8/2017 Stifel Nicolaus $24
5/24/2017 Bank of America $23
5/23/2017 Raymond James $23
5/23/2017 Deutsche Bank $25
BMR Take: Bad week for Cloudera. The stock got hammered. They announced a follow-on offering of shares from the IPO they did in April. This is normal stuff – some shares will be sold by insiders and some by the company. No details yet. We are not concerned, although it would be nice to see the stock at $25 where it ought to be. Remember, this is a tiny company. Market cap is $2.4 billion – a puppy. Very speculative. But we are believers.
Andeavor (ANDV: $102, up 1%)
We have a note we made from a research report from UBS Securities.
“The recent Western Refining merger is expected to generate $350-
$425 million in synergies.”
Their Price Target is $116, with an upside to $125. Ours is $110, but if it hits that we would consider raising it.
Cryptocurrencies Update
Bitcoin had a wild week, closing at around $3500 on Friday. Bitcoin doesn’t really “close” as it trades 24-7. Bitcoin began a colossal price reversal on Tuesday that finally culminated with the latest $2,972 weekly low, which ended up becoming the new monthly low as well. The massive 32% reduction, was followed by a flurry of negative news coverage with China shutting down the biggest bitcoin exchange in the country and Jamie Dimon of JP Morgan saying that this is the biggest bubble since tulip bulbs in 1637. He said that the cryptocurrency "won't end well." Dimon was speak at a conference presented by CNBC and Institutional Investor.
Bitcoin hit $4,980 all-time high on September 1st. It plunged about 13% Thursday after one of the biggest exchanges in China said it will shut down its operation. Bitcoin surged more than 10% on Friday, but was still on track for a big weekly loss during a tumultuous period of trading.
JPMorgan's global head of quantitative and derivatives strategy, said in a note on Wednesday that in addition to being volatile and difficult to value, "another worrying aspect of cryptocurrencies are some parallels to fraudulent pyramid schemes."
But to be sure, many see bitcoin as a huge opportunity.
Former JPMorgan strategist Tom Lee said the cryptocurrency could surge another 600% in five years. "It's not worth it to look at bitcoin two months, two weeks ahead," Lee argued, saying he still believes each bitcoin will be worth $25,000 in five years.
We at The Bull Market Report find this whole story fascinating and have been following bitcoin and Ethereum closely. If you would like to know more about it, please write us here: Info@BullMarket.com.
Opko Health Update
Opko (OPK: $5.97) had a wild week. It rallied the first three days of the week, closing at $6.47 on Wednesday. Then it got hammered on Thursday and was flat on Friday. We have seen no news to account for this, but please note that this one is quite speculative. Opko has had to deal with disappointment on multiple fronts, including less-than-encouraging results in clinical studies and slow starts for approved drugs. Yet even though several institutional investors have thrown in the towel and given up on the company, Opko has strong potential for sales of its chronic kidney disease treatment Rayaldee to pick up. Moreover, Opko's diagnostic testing business has good prospects as well. Although the company hasn't executed well yet, some are optimistic. We have high hopes for the company but it is testing our patience.
The High Yield Investor
By Michael Foster
After a lot of good weeks, we’ve had a week that was - well, slow.
Almost everything in the Bull Market Report high yield portfolio ended the week flat, as investors focused on the big headlines (North Korea, Irma, etc.), which actually had minimal impact on any high yield investment.
This might be surprising, so let’s talk a little bit about why the big macro events aren’t moving the needle. You’d be right to wonder why municipal bonds, especially bonds in Texas, Florida, and nearby weren’t negatively affected by the hurricanes that have caused still undetermined billions of dollars of damage and human misery. In light of that tremendous destruction, municipal bonds barely budged. Even bonds issued in the hardest hit areas were unaffected. To take one example, Miami’s transit authority issues bonds are backed by the revenue received from toll roads, parking lots, and so on. Surely less travel to the city and less use of parking lots by tourists due to the storm will hit revenue and thus put these bonds at risk - yet their prices barely budged.
The reality is that municipal bond issues use a combination of insurance and risk management to plan for major catastrophes, especially in catastrophe-prone areas like southern Florida. The storms were severe, but Florida financiers and civil servants plan for these things as part of their regular work. So while the timing of the storms was a bit of a surprise, the reality of hurricanes hitting Florida every once in a while is priced into the municipal bond market.
Thus muni funds continue to have a strong year after last week’s relatively small price movements. Nuveen AMT-Free Municipal Credit Fund (NVG: $15.70, down -1%) took a very slight hit, but that was counterbalanced by the small rise in Invesco Municipal Trust (VKQ: $12.96, up 1%). The most important lesson to learn, by far, is that big catastrophic events don’t really hurt muni bonds - at least, not in the way that the mainstream financial press would like you to believe (since, after all, they’re desperate for controversy and know fear-mongering headlines get clicks and pageviews).
Moving on to taxable income funds, we saw more quietness among AllianzGI Equity & Convertible Fund (NIE: $20, up 1%) and PIMCO Dynamic Income Fund (PDI: $30, up 0%). There are a couple of things to note about both of these funds with regards to their pricing. The income stream for both remains somewhat reliable, although the Pimco fund’s net investment income has dropped significantly in 2017 (this, however, is being counterbalanced by an increase in NAV growth). What investors should focus more of their time on is the pricing. The Pimco fund is now priced at a 4.8% premium to NAV, which is significantly lower than the 10% premium that it reached earlier this year. A big drop-off in the premium this summer has caused that pricing to go closer to its historical norm, and a small premium to NAV is a lot more tolerable than 10%. For that reason, investors who like the Pimco fund and have been waiting to buy more are finally in a position where they can seriously consider adding to their positions. However, if you can wait for a discount to show up, you might be wise to wait for a bigger market sell-off to provide that opportunity.
As for the AllianzGI fund - its discount to NAV has been steadily disappearing throughout 2017, and we’re now at slightly less than a 9% discount, which is a relatively high price for the fund relative to its historical average. That means investors should be a tad more cautious about adding to their position right now, but the fund is far from a sell. We’ll need to see discounts of 5% before offloading this fund makes any sense at all. In reality, the fund’s continued NAV appreciation (NAV is up 6% even after paying its 7.5% dividend consistently over the last year, giving a total NAV return of over 13%) demonstrates that the fund’s management knows what they’re doing and are able to provide a stable, reliable income by picking the right stocks and convertible bonds and handing profits to shareholders. At the end of the day, we can’t really ask more from a fund.
So with all of the humdrum, low level action of the last week, let’s discuss the two stocks that actually had pretty big moves. The first is Digital Realty Trust, Inc. (DLR: $118, down -3%), which closed its DuPont merger and proceeded to fall significantly thereafter. We’re pretty much off the 52-week high hit on Monday, so it’s hard to say whether the decline is a result of profit taking or a lack of faith in the value of the merger. We see no reason to be skeptical of the merger, so we are not changing our view on the stock.
There is, however, one other issue with cloud-based REITs like Digital Realty - earlier this week, a Silicon Valley venture capitalist gave a presentation arguing that server size was about to decline significantly due to semiconductor and other technological innovations. Obviously, this will be bad for datacenter stocks - or is it? Considering the explosive growth in data storage and users’ tendency to fill up datacenters faster than the space needed to store data shrinks, demonstrates that this is a pretty specious reason to be bearish on datacenter stocks.
Finally, AstraZeneca (AZN: $32.50, 1%) took a bit of a hit earlier this week on little news. Again, this seems to be a bit of profit taking, considering the significant rise in the stock from a month ago. There’s little news about the company’s product pipeline or balance sheet to indicate caution, so we’ll wait and see how the stock performs next week before concluding this price movement is anything more than noise.
Good Investing,
Todd Shaver, CEO, Editor and Founder
The Bull Market Report
Since 1998