October 30, 2017
by Todd Shaver | Oct 30, 2017 | Earnings Preview 6 AM
Omega Healthcare Investors (OHI: $32)
Bull Market Report Target Price: $45
Bull Market Report Sell Price: $28
Earnings Date: Monday, 4:00 PM ET
Consensus: 3Q17
Revenues: $238 million
EPS: $0.46
Year Ago Quarter Results
Revenues: $185 million
EPS: $0.40
Key Things to Watch For in the Quarter
Omega Healthcare is expected to report a 15% increase in earnings per share and a 30% increase in revenues for 3Q17. The stock has had mixed earnings results over the past four quarters, missing estimates twice and beating twice. This lack of certainty has been reflected in the stock’s performance over the past year, as it has barely moved from its price of $32 this time last year. Although the stock has underperformed the market over the past year, we are still very bullish for Omega as they continue to grow their sales and yield a very attractive 8% dividend.
-----------------------------------------------------------------------------------------------------------------------------
The Carlyle Group (CG: $22)
Bull Market Report Target Price: $28
Bull Market Report Sell Price: $20
Earnings Date: Tuesday, 8:00 AM ET
Consensus: 3Q17
Revenues: $680 million
EPS: $0.49
Year Ago Quarter Results
Revenues: $540 million
EPS: $0.21
Key Things to Watch For in the Quarter
Analysts expect The Carlyle Group to report a 26% increase in revenues and a 133% increase in earnings per share for 3Q17. Although the stock has beaten estimates in only two of the past four quarters, it has still managed to outperform the S&P 500 over the past year, providing shareholders with 44% return. We love this stock! It returns an 8% dividend and currently trades at a PE ratio of only 16, which is quite cheap compared to most of its competitors which are in the 18-20 range.
-----------------------------------------------------------------------------------------------------------------------------
Shopify (SHOP: $107)
Bull Market Report Target Price: $115
Bull Market Report Sell Price: $105
Earnings Date: Tuesday, 8:30 AM ET
Consensus: 3Q17
Revenues: $165 million
EPS: -$0.01
Year Ago Quarter Results
Revenues: $99 million
EPS: -$0.11
Key Things to Watch For in the Quarter
Analysts estimate Shopify will report a 66% increase in revenues and a reduction of its earnings deficit for 3Q17. The stock has been one of the best performers in all of our portfolios this past year, as it appreciated 160%. The company’s ability to growth its profits has been demonstrated over the past three years or so. Since 2014, Shopify has to increased its bottom line by 300%. We expect to see continued growth from Shopify as it continues to provide value for its customers with its cloud-based multi-channel commerce platform.
-----------------------------------------------------------------------------------------------------------------------------
Government Properties Income Trust (GOV: $18.14)
Bull Market Report Target Price: $23
Bull Market Report Sell Price: $15
Earnings Date: Thursday, 11:00 AM ET
Consensus: 3Q17
Revenues: $70 million
EPS: $0.05
Year Ago Quarter Results
Revenues: $65 million
EPS: $0.16
Key Things to Watch For in the Quarter
Government Properties is expected to report an 8% increase in revenues and a 68% reduction in earnings per share for 3Q17. Despite having beaten estimates in three of the past four quarters, the stock has fallen about 5% since this time last year and is currently trading 21% below its 52-week high of $23. The stock took a big hit in July this year when the company announced a secondary offering of 25,000,000 common shares, plus an overallotment sale of 2.9 million shares, raising close to $500 million. Although this action took a toll on the stock in the short term, we don’t see it affecting the performance of the underlying company moving forward. In fact, we love it when a company sells stock and raises capital. We remain bullish on Government Properties and continue to look forward to the 10% dividends that come with this stock.
-----------------------------------------------------------------------------------------------------------------------------
Annaly Capital Management (NLY: $11.61)
Bull Market Report Target Price: $12
Bull Market Report Sell Price: $11
Earnings Date: Wednesday, After Market Close
Consensus: 3Q17
Revenues: $625 million
EPS: $0.30
Year Ago Quarter Results
Revenues: $560 million
EPS: $0.29
Key Things to Watch For in the Quarter
Annaly Capital Management is expected to report an 11% increase in revenues and a 3% increase in earnings per share for 3Q17. The stock has beaten analyst estimates in each of the past four quarters and is up 12% over the past year. The stock returns a 10% dividend and currently trades at a PE of 4, making it one of the cheapest (compared to earnings) stocks in our portfolio. Our confidence in Annaly has increased with recent insider trades from their Chief Investment Officer, David Finkelstein. Just last month, he purchased $1.25 million worth of Annaly’s stock, showing his faith in the company moving forward over the long term.
-----------------------------------------------------------------------------------------------------------------------------
Facebook (FB: $177)
Bull Market Report Target Price: $190
Bull Market Report Sell Price: $155
Earnings Date: Wednesday, 5:00 PM ET
Consensus: 3Q17
Revenues: $10 billion
EPS: $1.28
Year Ago Quarter Results
Revenues: $9 billion
EPS: $1.09
Key Things to Watch For in the Quarter
Analysts estimate that Facebook will report an 11% increase in sales and an 18% increase in earnings for 3Q17. Facebook has beaten estimates in three of the past four quarters, contributing to the stock’s 35% gain over the past year. Facebook’s reinvestment back into the company has been driving growth and innovation, and with increasing capital expenditures we don’t see this growth slowing any time soon.
-----------------------------------------------------------------------------------------------------------------------------
Tesla (TSLA: $320)
Bull Market Report Target Price: $350
Bull Market Report Sell Price: $280
Earnings Date: Wednesday, 5:30 PM ET
Consensus: 3Q17
Revenues: $3.0 billion
EPS: -$2.29
Year Ago Quarter Results
Revenues: $2.3 billion
EPS: $0.71
Key Things to Watch For in the Quarter
Analysts estimate that Tesla will report a 30% increase in revenues and a large earnings deficit for 3Q17. Although Tesla has only managed to beat estimates in two of the past four quarters, the stock is up 60% over the past year. You've heard us speak about Tesla and being patient, and how speculative the stock is. Be careful.
-----------------------------------------------------------------------------------------------------------------------------
Apple (AAPL: $163)
Bull Market Report Target Price: $170
Bull Market Report Sell Price: We would not sell Apple
Earnings Date: Thursday, 5:00 PM ET
Consensus: 3Q17
Revenues: $51 billion
EPS: $1.87
Year Ago Quarter Results
Revenues: $47 billion
EPS: $1.50
Key Things to Watch For in the Quarter
Apple is expected to increase its revenues by 8% and its earnings by 25% for 3Q17. The stock has beatdn earnings estimates in three of the past four quarters and is up nearly 45% since this time last year. This quarter was interesting for Apple, as we saw a number of product releases, namely its iPhone 8 and X. We also suspect an increase in the sale of Apple’s iPad over the next few quarters, which, although isn’t the largest revenue driver, will definitely continue to help push Apple’s top line higher.
-----------------------------------------------------------------------------------------------------------------------------
CBRE (CBG: $39)
Bull Market Report Target Price: $40
Bull Market Report Sell Price: $35
Earnings Date: Friday, 7:00 AM ET
Consensus: 3Q17
Revenues: $3.5 billion
EPS: $0.54
Year Ago Quarter Results
Revenues: $3.2 billion
EPS: $0.50
Key Things to Watch For in the Quarter
CBRE is expected to report a 9% increase in revenues and a 9% increase in earnings for 3Q17. CBRE has beaten analyst estimates in each of the past four quarters, which has been reflected in the stock’s 50% appreciation over the past year. Although the stock doesn’t pay a dividend, it does trade at a reasonable PE ratio of 19. We view this stock as one of the best growth investments in our Stocks for Success Portfolio.
October 22, 2017
by Todd Shaver | Oct 22, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
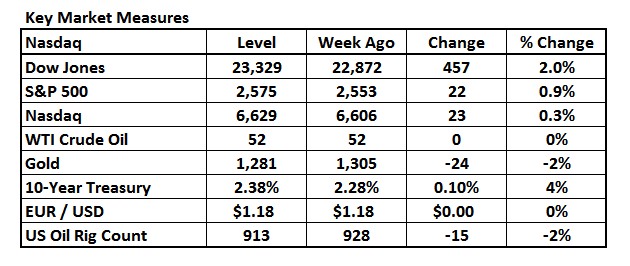
Earnings-day blowups, leverage warnings in China, Apple’s worst rout since August. Oh, and a sixth straight week of gains for the S&P 500. No matter what happens lately, stocks just keep rising, with record closes piling up in U.S. markets at a rate that is starting to defy precedent. The Nasdaq 100 Index has finished at all-time highs 62 different times this year, on par with the most ever in 1999, while the S&P 500 and Dow Jones Industrial Average are closing in on historic levels, too. For bears, the elongating list of highs bespeaks euphoria, particularly when the market has been spared a 3% pullback for more than a year. Investors have ignored bad news ranging from North Korea to political drama at the White House to what may be the biggest profit slowdown in six years. It has been a great ride this year. We remind you, our dear reader, it certainly will not always be this good.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks where we think you can still make good money, including: PayPal, Shopify, Celgene, WageWorks, Amazon, and Blackstone.
BMR Companies & Commentary
PayPal (PYPL: $71, up 3%)
PayPal delivered another great quarter for investors. The company not only showed no signs that its platform growth is slowing, it demonstrated that it is actually increasing its rate of growth as the network effects that management has repeatedly cited during the past couple of years continue in earnest. Yet many of its initiatives – the monetization of social peer-to-peer payment app Venmo, the expansion of instant-checkout feature One Touch, customer choice – are still in the very early innings of the game.
Toss in the $7.1 billion in cash that PayPal had on its balance sheet that could be used to fund M&A initiatives and the potential of the company’s worldwide network becomes daunting. We recall that PayPal acquired Braintree – the online and mobile payment platform that has fueled much of the company’s recent growth – in 2013 for just $800 million. And Braintree had spent just $26 million to purchase Venmo, which is a game-changing driver of revenue and earnings for PayPal.
BMR Take: PayPal has been the best way for equity investors to play the global growth of mobile payments. Again we see PayPal deliver an exceptional quarter backing up that point of view. We find nothing to critique about the firm. We raised our Target from $67 to $77 last week. We look forward to raising it again.

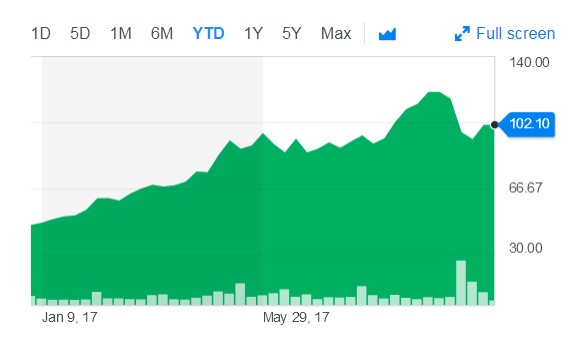
Now THERE’s a great chart. What’s next? 75? $80? $100. We think they are all possible.
Shopify (SHOP: $102, up 9%)
Remember that scary short seller, Andrew Left of Citron. Well the short call they were making on Shopify is turning out to be terribly wrong. Ouch! What good news for us and all the other shareholders behind the company.
Since 2014, Shopify, the leading multi-channel commerce platform, has been steadily building its presence in Waterloo, the cornerstone of Canada’s technology Corridor. Just recently, the company announced that it plans to grow its full-time, Waterloo-based workforce by 300-500 new jobs over the next couple of years. Growth continues!
These new positions in Waterloo will focus on growing Shopify Plus, which supports the largest and most complex customers on the Shopify platform. Roles in engineering, product, sales, and merchant services will range from entry-level to senior manager-level, and all will focus on developing innovative solutions capable of scaling for the changing retail landscape.
To accommodate this growth, Shopify also formally announced the opening of their second building in Waterloo. Steps from their current building, the new space will nearly double their physical footprint and further demonstrates Shopify’s dedication to building a strong and sustainable economy. The new space is expected to open in the first quarter of 2018.
BMR Take: It was admittedly a bit nerve-racking to see a short seller like Citron, who nailed Valeant, come out against one of our holdings. But we trust our research and our hard work. Shopify is a remarkable well-positioned technology company for the future of eCommerce.
Celgene (CELG: $121, down 11%)
Rough week for Celgene. Celgene announced the discontinuation of the Phase III REVOLVE trial in GED-0301 for Crohn’s disease (CD). This was unexpected and unfortunate news.
Celgene’s decision comes after recommendation by the independent data monitoring committee upon its review of
the overall benefit/risk during a recent interim futility analysis. The company points to no meaningful safety imbalances identified during this analysis, suggesting a lack of efficacy for the drug.
At this time, Celgene has chosen to not initiate the Phase III DEFINE trial in CD. The company is awaiting review of the full dataset from the Phase II trial of GED-0301 in ulcerative colitis to determine next steps in this situation.
In our opinion, this represents more of a psychological blow than a fundamental one to the company. Recall that Celgene paid $710 million upfront to Nogra Pharma Limited for the rights to this drug in 2014 and has since funded development of the asset.
BMR Take: Sometimes you just have to sift through the headlines to find the real facts. This one drug was only supposed to be a $1 billion revenue contributor. But the company is expected to still do more than $20 billion by 2020. So we see no reason to panic. We added the stock at $95 a little over a year ago so we have a nice 28% return and our Target is still a hefty $150. We continue to believe in Celgene. But if you are worried, then get out of the kitchen. There are lots of other choices for your money.

WageWorks (WAGE: $65, up 1%)
WageWorks a little over a year ago acquired Automatic Data Processing’s Consumer Health Spending Account (CHSA) and Consolidated Omnibus Reconciliation Act (COBRA) businesses. This transaction further strengthened WageWorks' leadership position in the Consumer-Directed Benefits market.
Why do we bring it up? Because WageWorks is eating ADP’s lunch and sometimes it’s good to reflect and remind ourselves why.
ADP’s CHSA and COBRA businesses provide a range of services including HSA, HRA, FSA, commuter benefits, and direct bill administration to approximately 10,000 employer clients in the United States.
Not long after this deal, WageWorks won a contract to service the entire federal government with consumer benefits programs, taking away the business from Automatic Data Processing.
BMR Take: WageWorks is serving a niche in the world of payments running consumer benefits programs for employers. It’s a tricky business. The global opportunity is huge and they are just getting started. We don’t hear a lot out of WageWorks week in and week out, but that doesn’t mean it's not exciting. Remember, the company just raised equity and we could see another acquisition occur in the near future.
Amazon (AMZN: $982, down 2%)
Amazon and Google (GOOG: $988) are at virtually the same price. Who will be first to $1100? Let the race begin. We think Amazon will win.
Why? Just look at the craze around the world competing for Amazon’s new headquarters. You can just see the excitement.
New York City mayor Bill de Blasio said that key landmarks around the city like the Empire State Building, billboards, and Wi-Fi charging stations are going to light up in Amazon’s signature orange color. The four bids that New York is pitching Amazon on - including areas upstate and in the city - just aren’t enough, so New York is also going for frills and extra decorations to pretty up its proposal.
Tucson certainly whipped out the big guns when its economic development group hauled a 21-foot saguaro cactus to Amazon’s main Seattle headquarters via a truck. The plan didn’t turn out the way that Tucson’s economic group had hoped: Amazon refused to accept the gift.
Kansas City mayor Sly James is not one to let the competition outdo him. He wrote 1,000 reviews about Amazon products, giving them all five stars. His reviews had slick one-liners like, “I live in beautiful Kansas City where the average home price is just $122K, so I know luxe living doesn’t have to cost a ton.“ Of course, in every review, he never failed to drop a mention of why Kansas City is great. Then, he posted a trendy “unboxing” video on social media to share his efforts. You gotta love this guy.
On Tuesday, Ottawans were told to cheer for Amazon during intermission for a hockey game between the Vancouver Canucks and the Ottawa Senators. A gauge showed up on screen, with Calgary at the bottom if the audience made the least noise and Ottawa on top. It being Canada, of course, the message to make noise was reiterated in French: “Faites du bruit!”
Pittsburgh has local restaurant Primanti Bros. offering free sandwiches to every Amazon employee who ends up working there. Each Pitts-Burger and Cheese sandwich goes for $7.39 normally, so if each of the 50,000 new employees got a sandwich, that would run for a total of $350,000, the Pittsburgh Post-Gazette hypothesizes.
Birmingham tried wooing Amazon online and in person. The city set up three giant Amazon boxes around town. It also set up giant replicas of Amazon’s Dash Buttons that send pregenerated flirty tweets to the company, according to AP, like “Amazon, we got a 100% match on Bumble. Wanna go on a date?” Another tweet reads, "We are Chipotle and these other cities are Taco Bell.”
Honestly, it’s hard to top this next one: This small, recently formed town, located close to Atlanta, offered to rename itself Amazon, Georgia. Stonecrest’s proposal also includes 345 acres of land if Amazon selects it as the HQ destination.
BMR Take: Amazon is the world’s greatest innovation machine. We think the new headquarters is going to spur even more great things and send the stock much higher.
The Blackstone Group (BX: $34, up 5%)
The U.S. real estate market may have slowed down, but Blackstone Group President Tony James still sees plenty of opportunities for profit. “Real estate is a gargantuan market. There are always undermanaged assets,” he said.
Blackstone has been investing heavily in logistics real estate, hoping to capitalize in the rise of online retail, and more acquisitions are possible.
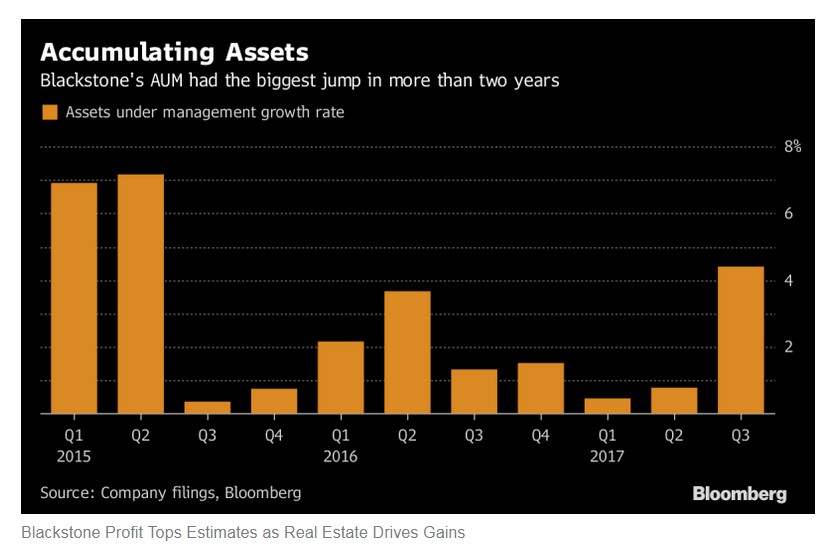
Blackstone’s real estate assets under management grew to $110 billion in the second quarter, up 9% from $102 billion a year ago. Its core-plus portfolio, which includes Stuyvesant Town-Peter Cooper Village, grew 36% to $18 billion.
In May, Blackstone won a $20 billion commitment from Saudi Arabia’s sovereign wealth fund for a new infrastructure investment fund, but it may be a while before the money gets spent. Saudi Arabia’s commitment depends on Blackstone raising additional cash from other investors, and the firm has only just began marketing the fund.
Real estate continues to fuel gains for Blackstone, which reported a jump in third-quarter profit that exceeded all analysts’ estimates. Economic net income, a measure of earnings that reflects both realized and unrealized investment gains, was $835 million, or 69 cents a share, compared with $690 million a year earlier.
Real estate led the charge for Blackstone’s asset sales in the quarter. The unit, sold $3.1 billion in holdings, including a U.K. office property and a portfolio of French hotels. The firm also continued trimming its stake in Hilton, selling shares it held in both its real estate and private equity funds.
Asset sales helped fuel $625 million of distributable earnings, which reflect profits on those disposals and fund management fees, compared with $590 million a year earlier. The metric is on track for its second-best year ever, President Tony James said on a call with media Thursday. Blackstone plans to draw from that pool to pay stockholders a dividend of 44 cents a share on Nov. 6.
BMR Take: We are really excited about Blackstone, especially real estate. Real estate is a “hard asset” meaning the value is more stable than for instance technology or biotech companies where the value is based on expectations of future growth. This real estate angle to Blackstone should give you less downside risk in a tough market.
Our Target is $36 and we fully expect to see this shortly. We can’t wait to raise the Target to the all-time high set in 2015 at $44. This $42 billion market cap company ought to be in the mid-40s for sure.
Upcoming Economic News
New Home Sales
Wednesday, October 25th, 10:00 AM
Period: September
Consensus: 552,500
Prior: 560,000
Initial Claims
Thursday, October 26th, 8:30 AM
Period: 10/21
Consensus: 231,500
Prior: 222,000
GDP
Friday, October 27th, 8:30 AM
Period: Q3
Consensus: 2.2%
Prior: 2.2%
The Word on the Street about Apple
Street Consensus Ratings for Apple (AAPL: $156, flat)
Ratings Breakdown: 7 Hold, 41 Buy Ratings
Consensus Price Target: $193
Wall Street Targets:
10/16/2017 KeyCorp $187
10/16/2017 Pacific Crest $187
10/15/2017 Rosenblatt Securities $150
10/13/2017 Barclays $161
10/11/2017 Piper Jaffray $196
10/11/2017 Morgan Stanley $199
10/10/2017 Royal Bank Of Canada $180
10/9/2017 Drexel Hamilton $208
Microsoft (MSFT: $79, up 2%) Sets New All-Time High
My Oh My. What shall we do? What shall we do with this stock at its all-time high of $79? Sell, Hold, Buy more?
BMR Take: WE SAY THE LATTER. Why would you sell one of the greatest companies in the history of the world? Yes, revenues are slowing, but profits are increasing and the profitability of software is second to none. For the year ended June 30th the company did $90 billion in revenue and had $21 billion in net income AFTER TAX. That’s 23% after tax. Wow. So for every $1 of software they sell, 23 cents goes to the bottom line, and much of that is in cash. The company has over $130 billion in cash, albeit over $80 billion in debt, much of it taken out at historically low interest rates. With a $607 billion market cap there are only two stocks higher. – Google at $690 billion and Apple at $810 billion.
We hereby raise our Target from $78 to $84. Go M S F T!
The Word on the Street about AstraZeneca
Street Consensus Ratings for AstraZeneca (AZN: $35, flat)
Ratings Breakdown: 2 Sell Ratings, 9 Hold Ratings, 14 Buy Ratings
Consensus Price Target: $37
Wall Street Targets:
10/17/2017 Cowen $37
09/6/2017 BMO Capital Markets $38
09/1/2017 Argus $35
BMR Take: We added the stock just below $30 last year. We are being very patient with this one. We have a 17% gain in over a year and the 2.6% dividend helps, but we would like to see this thing take off to our Target of $42. It’s no small company at a $85 billion market cap. Revenues are solid at $23 billion and profitability is strong at $5 billion but we want to see more in 2018. If you have patience, you will win.
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
We are getting ready to get down to the nitty-gritty of tax-reform. Listening to all the political pundits (which is extremely hard to stomach), it appears that the odds are now slightly favoring the failure of tax reform happening this year. Admittedly, we are talking about a government which is trillions of dollars in debt already, but that number seems to be "just a number". How do we actually comprehend a trillion dollars? One market guru described it as follows:
"Numbers, like billions and trillions tend to numb the mind. They are too large to grasp in any “real” sense. Thirty years ago an older member of the NYSE gave me a graphic and memorable example. “Young man,” he said, “would you like a million dollars?” “I sure would, sir!”, I replied anxiously. “Then just put aside $500 every week for the next 40 years.” I have never forgotten that a million dollars is enough to pay you $500 per week for 40 years (and that’s without benefit of interest). To get a billion dollars you would have to set aside $500,000 dollars per week for 40 years. And a trillion that would require $500 million every week for 40 years. Even with these examples, the enormity is difficult to grasp."
Despite our debt, the market wants and believes that a smaller government (lower taxes) will result in a higher GDP which in turn means higher tax revenues. Thus, the argument that the government has to "pay" for any tax cuts - by raising taxes on the left hand if lowering them on the right hand so as to keep the "debt" constant - is tantamount to keeping the status quo and, ultimately, the same drag on business that we have today. It is apparent that the $5 trillion gain in the overall stock market since the election is because of both increased earnings and the perception that those earnings will continue to grow in part due to lower taxes which drop directly to the bottom line of businesses. Our view is that it will be difficult for the market to act as if tax reform failure is a non-event. It's a major event that could make US companies more competitive in world markets and super-charge domestic small business like nothing has for the past 20 or 30 years.
Business and the markets both need an overhaul of a tax system that is so out-of-control that, as a generality, if one hundred experts file the same tax return, there will be ninety-nine different results. That said, tax reform failure by itself should not derail the current bull market - rather it will likely result in a "reset", or as the pundits like to say, a "consolidation of gains" before the next move higher. Until we see a recession or a bad policy move that, for example, results in an inverted yield curve, we expect that the market will continue to grind higher based on the quality and stability of earnings growth.
The High Yield Corner
By Michael Foster
Let’s start with the elephant in the room.
Government Properties Income Trust (GOV: $18.22, down -2%*) fell just 1% on Friday after receiving an unfavorable mention on Jim Cramer’s Mad Money. This move surprised us for two reasons. Firstly, we didn’t think anyone still watched Cramer’s show, and, secondly, we didn’t think anyone actually listened to him for investing advice. Apparently this failed hedge funder still has a following, though, and the selloff is a result of that.
* The company paid a 43 cent dividend on Friday and a stock that goes x-dividend always opens up down the amount of the dividend on that day, so in reality, the stock was down just a touch last week.
And what exactly is Cramer’s thesis? To be honest, we’re not sure. We’ve seen the clips and read a couple of takes, but the dismissal seems to be without any substance beyond “it’s a high dividend stock and it’s not for me.” No close look at FFO, dividend coverage, or revenue growth.
So, we will give you that here.
Let’s start with revenues. Government Properties Trust saw a 9% year-over-year increase last quarter, an acceleration from a decline at the start of 2016. Revenue growth acceleration has been occurring for nearly two years now, fueled in part by acquisitions and the company’s diversification away from government offices and towards office space leased to think tanks, public companies, private contractors, and so on. That investment has cost money, which means FFO has been weaker than it was back in 2014-2015, which also means dividend coverage is below 100% (it’s actually about 76% over the last 12 months).
Investors should in theory be rewarded for that lower dividend coverage with a higher yield, and at 9% that is exactly what they are getting. But really what we need to think about is the REIT’s ability to generate cash from operations to fuel the distribution in a sustainable manner.
If its expansion efforts bear fruit, this is exactly what we should see. But keep in mind that a bet on Government Properties is a bet on its future growth potential - and with revenue growth still accelerating, it remains a REIT growth stock. The second we see that sales growth weaken is the second we reconsider the stock. No matter what the bald guy on CNBC says.
Elsewhere in REIT land, things were extremely quiet. Omega Healthcare Investors, Inc (OHI: $32, up 1.5%) saw slight gains, whereas we saw a little dip in Ventas (VTR: $63, flat). Welltower (HCN: $68) ended the week flat, as did Apollo Commercial Real Estate (ARI: $18.44). One other REIT had a very fine showing, which is little surprise to us, since it’s been doing a lot of that lately.
Namely, Digital Realty Trust (DLR: $124, up 1%) had another strong week that pushed its dividend yield even lower, and we’ve finally hit the 3% mark yet again. Last week we discussed the significance of this barrier, and it’s not too surprising that it was hit. That should also make investors pause and consider why exactly they’re in the stock. At a 3% dividend or less, it’s more than generous to call Digital Realty a high yield stock. Yet it is unquestionably a high growth stock. Revenue growth, at 10% last quarter, fell from the 20%+ growth of 2016, but considering just how tough it was to compare revenues to 2016’s figures, that slowdown was more than expected. And at near 10% sales growth, the company is still growing like a weed. That has helped FFO growth accelerate markedly, which should indicate more aggressive dividend increases are on their way.
That leads us to the question: what to do with this stock. If you aren’t in need of a high yield, Digital Realty is a great place to be, because you’re essentially Google and Amazon’s landlord for their most precious assets: their data and global presence. But if your goal is to target a 7% income stream or higher, you could easily make do with removing allocations to Digital Realty with a nice profit and move into other higher yielding stocks in our two high-dividend-paying stocks. That’s especially true now that we’ve seen Digital’s stock soar 83% in 3 years. Yes, more upside is on the way, but maybe not as quickly and as profoundly as we’ve seen so far this year and in recent history.
Now let’s move on to the other, somewhat smaller elephant in the room: PIMCO Dynamic Income Fund (PDI: $30, down 4%), which wasn’t the worst performing Pimco fund of the week, although it was pretty close. Across the board, the market punished Pimco’s funds after the company announced that net investment income for most of its funds was far from covering distributions. This wasn’t a surprise, but the market has mostly ignored this issue until just now. Both the Dynamic fund and other Pimco funds have seen dividend coverage slip to less than 100%, although Dynamic’s coverage is not the worst of the lot. Still, the market is worried that the fund won’t be able to cover its payouts.
This is an overly simplistic view. Dynamic’s NAV has gone up 12% in 2017 - more than many bond funds and even some other Pimco funds. Since closed-end funds can fund distributions from Net Investment Income (NII), this just means Dynamic’s payouts can come from capital gains instead of NII. There are some tax issues here, but in terms of dividend sustainability, Dynamic’s distributions are fine.
But there is one implication many aren’t talking about, and we have addressed it earlier this year: the specials. Dynamic is famous for paying a huge special dividend at the end of the year, which has historically come from massive NII. Now that NII is weak, Pimco has a great excuse to tell investors, “Worry, income was weak, so no big special dividend this year.” We are not sure this will happen, but we’re leaning more to this being likely than we were earlier this year. If you were depending on this fund’s special distribution like the big one we saw last year, be prepared for disappointment. Also be prepared for that to hit the stock at the end of the year.
Is this a bad thing? Not really. The regular dividends are still safe, and the fund’s yield is a very nice 9%. And we could see NII improve significantly next year. There’s definitely more to come with Pimco funds in the coming months! But, if you don’t like drama, take your profits and squirrel them away in Annaly Mortgage (NLY – 10% div.) or any of the other stocks in our two high-yield portfolios and sleep like a baby.
Good Investing,
Todd Shaver, Founder and CEO
The Bull Market Report
Since 1998
October 16, 2017
by Todd Shaver | Oct 16, 2017 | Monthly Newsletter Daily 12pm if new
The Weekly Summary
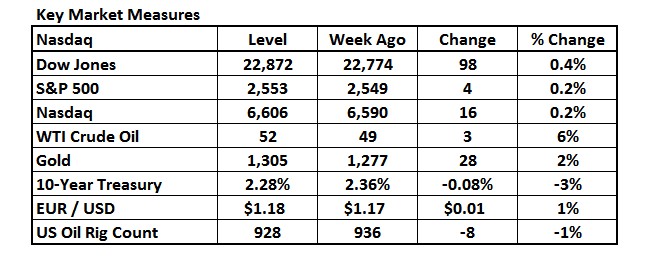
Tulip Mania was a period in the Dutch Golden Age when the price of bulbs reach ridiculously high levels in a craze only to eventually have the price crash badly in 1637. While we are not seeing broad-based craze in today’s markets, we must be mindful that there are pockets of risk out there, and that while market prices today haven’t reached “ridiculously high levels” they have still come a long way, raising the bar for how much risk lingers around out there. For example, this week the mainstream news media extensively covered Wall Street’s junk market bond binge. Junk rated companies are raising debt at the fastest pace since 2012. Not just is the issuance up a lot, but the terms of the deals (i.e. the debt covenants) are getting looser and looser, and thus easier to borrow money. We only raise these points to say, please be mindful of the risks, but there remains plenty of opportunity for future profits!
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks/funds where we think you can still make good money, including: Nutanix, Opko, Apple, Annaly and BlackRock.
BMR Companies & Commentary
Another week, another all-time record high. Does this scare you? Not us. Why should it scare you? The economy is strong. We have 325 million people who are trying to better themselves by starting companies, by investing in real estate, by buying equities and bonds. No one thing or no one event can bring down the entrepreneurial nature of this country. The market is climbing a wall of worry. Trump, North Korea, breaking the Iran deal, the Taliban, our war in Afghanistan (that Trump is escalating now – ouch), Trump – oh wait, we just said that above. Yes, climbing a wall of worry. But the stock market has been doing this for over 100 years. Seriously. Look what it has been through and look where it is now. Look where our economy is now. Amazing. So Dow 23,000 look out and who knows, maybe in a year or two we will be saying “Dow 30,000 look out.”
If you really are worried and/or if things do get worse, sell your growth stocks and buy some income producing stocks from our REIT portfolio or our High Yield portfolio. Annaly Capital Mortgage (NLY: $12.22, up 1%) has been paying over 10% for over 20 years. I am going to repeat this for you here: Annaly Capital Mortgage has been paying over 10% for over 20 years. Since 1997 they have operated through bull and bear markets in stocks and bonds and they have survived and thrived. You’re worried about the stock market? Buy some Annaly – it is non-correlated with the market.*
*It has a beta of 0.30. A beta of 1 means it follows the overall stock market equally – if the market is up 1%, Annaly is up 1%. But no, Annaly has a beta of 0.30% meaning little to no correlation. The beta of an investment indicates whether the investment is more or less volatile than the market as a whole. In general, a beta less than 1 indicates that the investment is less volatile than the market, while a beta more than 1 indicates that the investment is more volatile than the market Beta can be zero. Some zero-beta assets are risk-free, such as treasury bonds and cash.
You want diversification? There are many other stocks in those two portfolios that pay from 4% to 9% dividends. Buy a basket of them and sit back and sleep like a baby at night!
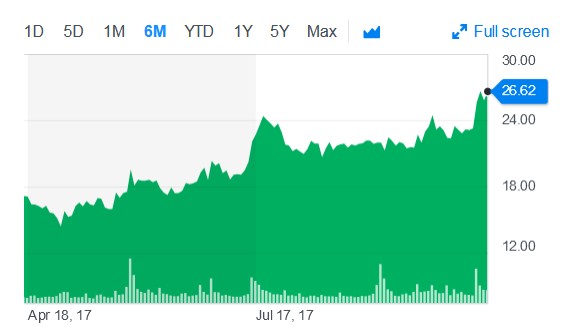
Nutanix (NTNX: $27, up 15%)
Goldman Sachs called Nutanix the investment opportunity of a decade. Why?
The demand pendulum appears to be swinging toward emerging, best-of-breed vendors with more modern approaches, and away from traditional, one-stop shop vendors that are often viewed to be out-of-step with the latest trends.
The proof is in the success or failure of new clients. Just this past quarter Nutanix had a strong quarter for large deals, including multiple deals in the high seven-figure range (several of these in the public sector). Nutanix is now working with a big chunk of the Fortune 500.
The big exciting part about Nutanix is that the company has doubled the number of clients in the past year. The typical client starts with a small contract, but then increases the amount of business they do, often 3x, 5x, or even 10x within a few years. So if Nutanix does nothing else but take care of the clients it already has, we should see strong growth in the years ahead.
BMR Take: We think Nutanix is a must-buy at current levels. Don't be worried about the current valuation. Let's look at why. This year the consensus is for EPS of $0.07, which is nothing much. However, the company is plowing money into sales and marketing to grow the business. Did you know they could save a few hundred million dollars tomorrow generating $1.50+ of EPS if they wanted to stop investing for growth? You see this analysis reveals the serious earnings power embedded in the business model, which is why we like the company so much.
Opko Health (OPK: $6.95, flat)
Opko is a diversified healthcare company that seeks to establish industry leading positions in large, rapidly growing markets. The diagnostics business includes BioReference Laboratories, the nation's third largest clinical laboratory with a core genetic testing business and a 400 person sales and marketing team to drive growth and leverage new products, including the 4Kscore® prostate cancer test and the Claros® 1 in-office immunoassay platform. The pharmaceutical business features Rayaldee, an FDA approved treatment for Secondary hyperparathyroidism in stage 3-4 chronic kidney disease (CKD) patients with vitamin D insufficiency.
Opko recently announced that it has entered into an exclusive agreement with Japan Tobacco (JT) for the development and commercialization in Japan of Rayaldee for the treatment of SHPT in dialysis patients with chronic kidney disease. This is great news for growth!
Under the terms of the agreement, JT will make an upfront payment to Opko of $6 million with another $6 million payment to be made upon initiation of Opko’s planned phase 2 study of Rayaldee in US dialysis patients. In addition, Opko will be eligible to receive up to an additional $31 million in development and regulatory milestones and $75 million in sales-based milestones. JT will also pay Opko tiered, double digit royalties on net product sales. Wow!
BMR Take: Consensus calls for about $1.2 billion of revenue for the company this year heading to $2 billion in a few years. We could be in for some major upside to estimates. Now wouldn’t that be nice, after being so patient with this little $3.9 billion company.
Apple (AAPL: $157, up 1%)
Apple could be disrupting more industries soon.
Barclays, the British bank, will need to defend its advantages in the payments business from encroachment by technology companies including Amazon and Apple, according to Barclay’s CEO Jes Staley.
There are some tectonic shifts going on, driven by tech and the geopolitical environment. The banks are very focused on the payments space and that may be where the battleground of finance is fought over the next 15 years. Could you imagine if Apple started taking share of the banking business from the world’s largest banks (like Barclays, JP Morgan, and Wells Fargo) as well as the world’s largest payments companies (like Visa and MasterCard). This would be another huge long-term growth driver.
BMR Take: Note that Apple has $260 billion in cash now, and with a market cap of $810 billion cash is 32% of the stock price. So more than $50 of the stock price is in cash. This is UNPRECEDENTED in the history of Wall Street. Apple remains an exciting investment opportunity. The services business is projected to double in revenue to $50 billion over the next several years. The Services business is much more profitable than hardware so the impact to earnings is even better. Don’t sell a share. We believe Apple has a lot more room to go on the upside.
BlackRock (BLK: $475, up 3%)
BlackRock, the world's largest money manager with $5.7 trillion in assets under management, reported better-than-expected earnings on Wednesday, which sent its stock to a record high.
And shares could go even higher, according to Credit Suisse (and us!) Following 3Q17 results, BlackRock remains the best-positioned traditional asset manager in the world with EPS growth expected to run 15-20% through 2019.
Most of the company's growth has come from its wildly successful exchange-traded fund business, known as iShares, which now accounts for half of all US investments in the products. There continues to be strong demand for iShares's ETFs driven by the evolution of the US retail channel (from commission-based to fee-based) and increased adoption by institutional clients and pricing reductions in its core series. Year to date, iShares accounted for about 50% of total ETF flows in the US.
Passive investments, like ETFs and other products that track a weighted index rather than a single equity, have steadily eaten away at active managers' portfolios in recent years.
BMR Take: BlackRock is among the best-positioned companies in investment management owning the top ETF franchise that is growing rapidly due to passive investing, as well as an increasing product portfolio of technology. Recall, there are several top hedge funds on the list of shareholders in BlackRock. With EPS set to approach $30 over the next 3 years, this stock pick is among our favorites.
Upcoming Economic News
Industrial Production
Tuesday, October 17, 2017 09:15 AM
Period: September
Consensus: 0.30%
Prior: -0.90%
Housing Starts
Wednesday, October 18th, 8:30 AM
Period: September
Consensus: 1,180,000
Prior: 1,180,000
Continuing Jobless Claims
Thursday, October 19th, 8:30 AM
Period: October
Consensus: 1,895,000
Prior: 1,889,000
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
The 4th quarter is off and running strongly, which is not uncommon. Even though it includes October (Octoberphobia), Q4 has historically been the strongest quarter of the year for the S&P 500. Since 1950, the S&P 500 has gained 4% on average in the fourth quarter, advancing 79% of the time. Oil dipped back under $50 per barrel and gold has fallen over 7% in just the last month because the US Dollar has strengthened due to the belief that the Fed will hike rates again in December. Maybe or maybe not. We still think tax reform is a bigger wild card than another Fed hike. The expectation of tax reform has resulted in just about everything with the exception of energy being up for the year, but even energy has some building tailwinds.
According to Boone Pickens Advisors, worldwide demand is soaring and set to hit 100 million barrels per day next year – a feat that was only expected around 2025 by most long-term forecasts including those from OPEC and Exxon. Growing energy demand is normally associated with growing economies, so this continues to be good news for future market gains based on earnings growth. The point being made is that if the market suffers a setback due to the failure of tax reform, it should not develop into a real bear market because of the support to be found in continued earnings growth. If Boone Pickens Advisors is right about soaring demand for energy, there is plenty of upside left in this bull.
General Electric (GE: $23, down 10% this week, and down from $32 in December - wow)
The drop in the stock in the last 10 months is almost 30%. With a market cap of $200 billion GE is not going away. But they are the Dog of the Dow. You know what the Dogs of the Dow are, right? They are the five worst performing stocks of the 30 Dow stocks. GE is gunning for THE DOG of the Dow this year. Many value money managers love this stuff. They buy the Dogs and historically, they have been big winners the following year and years.
We are thinking of adding GE to our Stocks For Success portfolio, not just because of the thinking in the above paragraph but for a host of other reasons. It has just had a shakeup in management, which will continue for the next few months. Old CEO out (Immelt), new CEO in (John Flannery). Lots of executives leaving or getting pushed out. Dividend is 4% which is pretty darn good for a Dow stock. 100+ year history of success as a global business leader. Lots going on with this huge company.
A note about the dividend. Some analysts think the dividend could get cut in order to conserve cash. This would be bad and good news. The stock would probably get nailed by another 10% down to $21 or even lower, but that would most likely mark the bottom. So if you are thinking of taking a position, keep this in mind. In other words, keep some cash around (keep your powder dry) in order to buy more at a lower price. If this dividend cut doesn’t happen, then buy some more as the stock moves up over the coming 24 months as it gets back into the $30s. The all-time high is about $58 back in 2000, right after the bubble started bursting in the dotcoms. It dropped to $24 in 2002 and then rallied to $41 in 2007. It got whacked to $12 in 2009 in the financial crisis and has moved straight up for eight years to $32 in 2016. We think there is a good possibility of seeing $30 and $40 in this great franchise as we move into the latter stages of the twenty teens.
Again, we are thinking of writing a research piece on GE soon. We believe it is a long term winner for the super conservative investor.
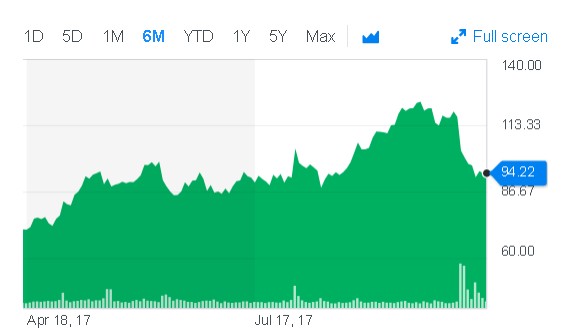
Update on Shopify
As you know, we love Shopify (SHOP: $94, down 4%) but along came Andrew Left and his firm Citron announcing that he was short the stock, that it was going way down, and that the company was fraudulent, among other silly claims. Many analysts jumped in this past week on the story. Here’s what one of them said:
"Citron’s Argument is Weak
"Let’s call a spade a spade - Shopify is selling a dream.
"So, is the Shopify stock news on-point? Is Shopify using illegal marketing tactics in selling that dream? That’s a gray area to be sure, but is the marketing message remarkably more misleading than the TV commercials inviting consumers to participate in class action lawsuits that mostly enrich attorneys, but rarely pan out as well as expected for the actual plaintiffs?
"Is a vision of a healthy cancer patient within a television commercial for a cancer drug some sort of unspoken guarantee of long-term survival? Does a young man that uses the Axe brand of personal-hygiene products actually expect to be besieged by young women, as depicted in Axe’s television commercials?
"The answer to all these questions is, of course, no. The FTC tolerates the imagery simply because it knows it has to give consumers at least a modicum of credit in distinguishing the difference between a contract and a commercial.
"And as for Shopify’s lack of profits, Shopify is in good company. Most young companies don’t turn a profit until after they’ve matured, but savvy investors know the time to get into some of them is before, not after, that fact. Look at Amazon, the most prominent of the rags-to-riches stories. It’s been one of the best long-term investments anyone could have made over the course of the past couple of decades. Investors don’t care where a company is, they care about where it’s going.
"Looking Ahead for SHOP Stock
"Don’t misread the message. The FTC might crack down on Shopify’s advertising. The company might never turn a profit. The market might not care if Shopify does eventually turn a profit. Nobody really knows the future. That’s the speculative nature of stock-picking.
"Andrew Left, however, seems to be grasping at straws with this one. Though he certainly rattled shareholders by generating some rather alarming Shopify stock news headlines, this time his claims are more bark than bite.
"If your gut is telling you this may be a time to scoop up shares at bargain prices, you may want to trust your gut."
BMR Take: Again, this was an opinion of a consensus of Wall Street analysts. But we certainly concur. We think this guy Left is out in left field. Here’s a chart of the last six months. You can see that the stock is where it was in August, just two short months ago. In April it was $71. We think there is tremendous value here with this company and believe Andrew Left will be left high and dry.
The High Yield Corner
By Michael Foster
Remember the slight volatility we recently saw in REITs? That’s gone. Instead, 4 of the 6 REITs in the High Yield portfolio were up this week, while two were flat. While not rising the most, Omega Healthcare Investors, Inc (OHI: $32, up 1%) is the most important and interesting story of the week. Extremely cautious, risk-averse investors dislike this stock because of its high yield (8%) and relative youth. Having been around since the late 1990s, it lacks the history of many dividend growth stocks. It also had a pretty disastrous collapse in its dividend back in 2000. However, that’s all long history by now. More recently, Omega Healthcare has devoted itself to a penny-per-quarter dividend hike that makes it a uniquely high yielding dividend growth stock. Some will warn that these dividend increases are unsustainable, and that may be true. But if the hikes last 10 years instead of 2 quarters and you avoid it because it won’t last forever, you’re giving up some extreme gains over a decade. This is how risk averse behavior cuts into returns.
The more aggressive investors who own Omega realize this, which is why they look at both the firm’s FFO and its dividend growth rate like a hawk. Last week, Omega yet again gave investors a penny-per-share raise. At the new payout, FFO covers the dividend pretty well - at a 125% rate. Bear in mind that that’s below the 130% threshold that we frequently write about here, which makes us cautious about the longevity of the rate hikes. We need to see FFO per share slow significantly before that dividend coverage ratio gets hurt and a cut becomes a mathematical necessity.
But how long could that take? Our best guess is that we have at least three years until a cut becomes necessary, but there are two factors that could grossly change that estimate. For one, shares outstanding growth. The more shares Omega releases, the more dividends it has to pay, which makes its FFO less powerful in covering payouts. Total shares outstanding have risen to 197 million from 196 million in the last year - a pretty small jump. But shares were just 68 million a decade ago, meaning an 11% annualized growth rate in total shares outstanding. That brings us to our second factor: FFO - funds from operations. During that same decade, FFO has risen 22% annualized over the same period. So you can see how Omega has been able to grow far beyond its obligations to shareholders and keep that growth rate going!
Can Omega continue? The real answer is no one knows, but there is reason to be concerned. The growth rate has slowed significantly in recent years, especially since Omega was smart to expand during the post-2009 years when all real estate was on sale. Deals are harder to find now, making growth a lot harder.
There’s another lever Omega can pull, though: Getting strong rent hikes. Keep in mind that Omega’s wheelhouse is a customer base that struggles with inflation, which makes rent hikes particularly challenging. For that reason, we think the long term trend of strong growth at Omega is definitely a thing of the past, and the penny-per-quarter hike cannot continue forever. But selling now and missing out on years of high yield dividend growth would be folly. Instead, we need to keep our positions and look closely at the numbers before jumping out. Now is not the time.
Our strongest REIT of the week is in many ways the exact opposite of Omega. Digital Realty Trust (DLR: $122, up 3%) saw a really strong week without too much relevant news. Last week the firm announced it would expand its Silicon Valley Connected Campus, with a new six-megawatt facility planned for 1Q18 delivery. This is a really small part of Digital Realty’s portfolio, comprising just a $75 million investment, so it isn’t enough to move the needle. Also, as counterintuitive as it sounds, Digital Realty’s strength isn’t in the Valley but in its distributed presence around the country. The company has many retail-facing clients, as well as the U.S. government, where the need is to have many hubs where human beings who use the Valley’s services are located.
Digital Realty is on track to grow that business, but the real story of last week’s price movement is more technical than fundamental. The stock has retreated from its 52-week high hit last month ($127), and after this week’s gains is approaching it yet again. The dividend yield is also nearing the sub-3% level, which it hit in September briefly before rising. We fear we may have a repeat of that in the short term - but that’s hardly a cause for concern. It simply means that Digital Realty is for the most part range bound right now, and we need to content ourselves with that while we wait for the company to aggressively ramp up its dividend. The last rate hike was in March, and another one by the end of the year would be nice. In reality, this company’s management has settled itself into a predictable pattern of one-per-year dividend hikes despite a rapid acceleration in FFO growth. FFO per share is now over double payouts - an absurd ratio to say the least! We would like to see Digital Realty aggressively ramp up its dividend hike schedule.
We doubt we’ll see it anytime soon, but we do think it’s an inevitability with this company. Simply put, it cannot stop making money, and its business is growing too rapidly for it to be at risk anytime soon. Eventually, Digital Realty will need to start increasing its dividend more frequently or doing much more aggressive dividend hikes. Either way, its 3% yield at current prices is destined to turn into more of a 5% yield in the next 3-5 years. For that reason, investors long the stock should stay tight even if you’ve been in it for the past year and are sitting on some attractive capital gains.

Good Investing,
Todd Shaver, CEO, Founder and Editor
The Bull Market Report
Since 1998
Now wouldn't you want to get this newsletter every week? You bet you would! Just click here or go to BullMarket.com/subscription. You'll be glad you did!
October 15, 2017
by Todd Shaver | Oct 15, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
Tulip Mania was a period in the Dutch Golden Age when the price of bulbs reach ridiculously high levels in a craze only to eventually have the price crash badly in 1637. While we are not seeing broad-based craze in today’s markets, we must be mindful that there are pockets of risk out there, and that while market prices today haven’t reached “ridiculously high levels” they have still come a long way, raising the bar for how much risk lingers around out there. For example, this week the mainstream news media extensively covered Wall Street’s junk market bond binge. Junk rated companies are raising debt at the fastest pace since 2012. Not just is the issuance up a lot, but the terms of the deals (i.e. the debt covenants) are getting looser and looser, and thus easier to borrow money. We only raise these points to say, please be mindful of the risks, but there remains plenty of opportunity for future profits!
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks/funds where we think you can still make good money, including: Athenahealth, Nutanix, Cloudera , Opko, Apple, Annaly and BlackRock.
BMR Companies & Commentary
Another week, another all-time record high. Does this scare you? Not us. Why should it scare you? The economy is strong. We have 325 million people who are trying to better themselves by starting companies, by investing in real estate, by buying equities and bonds. No one thing or no one event can bring down the entrepreneurial nature of this country. The market is climbing a wall of worry. Trump, North Korea, breaking the Iran deal, the Taliban, our war in Afghanistan (that Trump is escalating now – ouch), Trump – oh wait, we just said that above. Yes, climbing a wall of worry. But the stock market has been doing this for over 100 years. Seriously. Look what it has been through and look where it is now. Look where our economy is now. Amazing. So Dow 23,000 look out and who knows, maybe in a year or two we will be saying “Dow 30,000 look out.”
If you really are worried and/or if things do get worse, sell your growth stocks and buy some income producing stocks from our REIT portfolio or our High Yield portfolio. Annaly Capital Mortgage (NLY: $12.22, up 1%) has been paying over 10% for over 20 years. I am going to repeat this for you here: Annaly Capital Mortgage has been paying over 10% for over 20 years. Since 1997 they have operated through bull and bear markets in stocks and bonds and they have survived and thrived. You’re worried about the stock market? Buy some Annaly – it is non-correlated with the market.*
*It has a beta of 0.30. A beta of 1 means it follows the overall stock market equally – if the market is up 1%, Annaly is up 1%. But no, Annaly has a beta of 0.30% meaning little to no correlation. The beta of an investment indicates whether the investment is more or less volatile than the market as a whole. In general, a beta less than 1 indicates that the investment is less volatile than the market, while a beta more than 1 indicates that the investment is more volatile than the market Beta can be zero. Some zero-beta assets are risk-free, such as treasury bonds and cash.
You want diversification? There are many other stocks in those two portfolios that pay from 4% to 9% dividends. Buy a basket of them and sit back and sleep like a baby at night!
Athenahealth (ATHN: $115, down 7%)
While Athenahealth didn’t perform well this week, as far as we can tell the issues are just some pre-earnings jitters, not anything serious. The company is scheduled to report earnings on Friday. The consensus is looking for EPS of $0.50 on $310 million of revenue.
We expect all the key fundamentals to remain solid. Recall, the company recently committed to several key initiatives, including: (i) targeting approximately $100 million in cost-savings to increase profitability and drive growth; (ii) committing to significant operating margin expansion; (iii) launching a search to recruit a seasoned independent chairman of the board and additional independent director; and (iv) augmenting the senior management structure to establish the role of president, in addition to an ongoing CFO search.
We do note that the interim CFO sold 4,000 shares this week. Sometimes this news spooks people, but in this case we see no reasons to be concerned about it.
BMR Take: With Elliott Management in there shaking things up, there is a lot of excitement ahead. We love this company but believe now is the time to take profits. For those of you who bought on our recommendation, we made a fair amount of money since we added the stock at $103 in November. While we already officially removed the stock from our portfolio on 8/7/17, we once more reiterate taking profits. Why again? We know some of you out there may have stayed the course selling calls, as that’s what we recommended to do at the time if you weren’t ready to get out. Well, we want to be sure to now say without any hedging - time to exit completely! Let’s buy this one back below $100.
Nutanix (NTNX: $27, up 15%)
Goldman Sachs called Nutanix the investment opportunity of a decade. Why?
The demand pendulum appears to be swinging toward emerging, best-of-breed vendors with more modern approaches, and away from traditional, one-stop shop vendors that are often viewed to be out-of-step with the latest trends.
The proof is in the success or failure of new clients. Just this past quarter Nutanix had a strong quarter for large deals, including multiple deals in the high seven-figure range (several of these in the public sector). Nutanix is now working with a big chunk of the Fortune 500.
The big exciting part about Nutanix is that the company has doubled the number of clients in the past year. The typical client starts with a small contract, but then increases the amount of business they do, often 3x, 5x, or even 10x within a few years. So if Nutanix does nothing else but take care of the clients it already has, we should see strong growth in the years ahead.
BMR Take: We think Nutanix is a must-buy at current levels. Don't be worried about the current valuation. Let's look at why. This year the consensus is for EPS of $0.07, which is nothing much. However, the company is plowing money into sales and marketing to grow the business. Did you know they could save a few hundred million dollars tomorrow generating $1.50+ of EPS if they wanted to stop investing for growth? You see this analysis reveals the serious earnings power embedded in the business model, which is why we like the company so much.
Cloudera (CLDR: $15.72, down 6%)
Remember the company we really like just mentioned above, Nutanix? Well they are doing great things with Cloudera, which means there is more than one way to make money here.
Nutanix, a leader in enterprise cloud computing, announced that its Enterprise Cloud Platform software has been certified to run Cloudera Enterprise workloads. Through this certification, joint customers can reduce management complexity and derive more value by deploying and managing their Cloudera analytics workloads on the market’s leading hyperconverged software platform.
For big data deployments, choosing the right hardware and software is critical to success but often challenging for IT teams balancing ambitious corporate goals with smaller budgets and fewer resources. Joint customers can now run Cloudera workloads on an on-premises, elastic, software-driven infrastructure that can scale on-demand, one node at a time. And because Cloudera workloads can run on the same shared infrastructure as other workloads, IT teams can reduce costs and focus their attention on strategic projects, rather than managing multiple silos of underutilized infrastructure. Great news!
BMR Take: With $360 million of sales projected this year, a growth of 40%, Cloudera is an emerging growth stock worth keeping an eye on. With acquisitions building out the product suite and accelerating revenue growth, momentum is undeniably picking up. A $2 billion market cap, this company is a pipsqueak in the world of commerce. But given its high growth rate, in 2-3 years, the firm can be a major factor (if the company doesn’t get taken out by the big boys.)
Wall Street Consensus Ratings for Cloudera
Ratings Breakdown: 5 Hold Ratings, 4 Buy Ratings
Consensus Price Target: $22.40
10/11/2017 Mizuho $18
9/8/2017 J P Morgan Chase $24
9/8/2017 Morgan Stanley $19
9/8/2017 Stifel Nicolaus $24
5/24/2017 Bank of America $23
5/23/2017 Raymond James Financial $23
5/23/2017 Citigroup $23
5/23/2017 Deutsche Bank $25
Opko Health (OPK: $6.95, flat)
Opko is a diversified healthcare company that seeks to establish industry leading positions in large, rapidly growing markets. The diagnostics business includes BioReference Laboratories, the nation's third largest clinical laboratory with a core genetic testing business and a 400 person sales and marketing team to drive growth and leverage new products, including the 4Kscore® prostate cancer test and the Claros® 1 in-office immunoassay platform. The pharmaceutical business features Rayaldee, an FDA approved treatment for Secondary hyperparathyroidism in stage 3-4 chronic kidney disease (CKD) patients with vitamin D insufficiency.
Opko recently announced that it has entered into an exclusive agreement with Japan Tobacco (JT) for the development and commercialization in Japan of Rayaldee for the treatment of SHPT in dialysis patients with chronic kidney disease. This is great news for growth!
Under the terms of the agreement, JT will make an upfront payment to Opko of $6 million with another $6 million payment to be made upon initiation of Opko’s planned phase 2 study of Rayaldee in US dialysis patients. In addition, Opko will be eligible to receive up to an additional $31 million in development and regulatory milestones and $75 million in sales-based milestones. JT will also pay Opko tiered, double digit royalties on net product sales. Wow!
BMR Take: Consensus calls for about $1.2 billion of revenue for the company this year heading to $2 billion in a few years. We could be in for some major upside to estimates. Now wouldn’t that be nice, after being so patient with this little $3.9 billion company.
Apple (AAPL: $157, up 1%)
Apple could be disrupting more industries soon.
Barclays, the British bank, will need to defend its advantages in the payments business from encroachment by technology companies including Amazon and Apple, according to Barclay’s CEO Jes Staley.
There are some tectonic shifts going on, driven by tech and the geopolitical environment. The banks are very focused on the payments space and that may be where the battleground of finance is fought over the next 15 years. Could you imagine if Apple started taking share of the banking business from the world’s largest banks (like Barclays, JP Morgan, and Wells Fargo) as well as the world’s largest payments companies (like Visa and MasterCard). This would be another huge long-term growth driver.
BMR Take: Note that Apple has $260 billion in cash now, and with a market cap of $810 billion cash is 32% of the stock price. So more than $50 of the stock price is in cash. This is UNPRECEDENTED in the history of Wall Street. Apple remains an exciting investment opportunity. The services business is projected to double in revenue to $50 billion over the next several years. The Services business is much more profitable than hardware so the impact to earnings is even better. Don’t sell a share. We believe Apple has a lot more room to go on the upside.
BlackRock (BLK: $475, up 3%)
BlackRock, the world's largest money manager with $5.7 trillion in assets under management, reported better-than-expected earnings on Wednesday, which sent its stock to a record high.
And shares could go even higher, according to Credit Suisse (and us!) Following 3Q17 results, BlackRock remains the best-positioned traditional asset manager in the world with EPS growth expected to run 15-20% through 2019.
Most of the company's growth has come from its wildly successful exchange-traded fund business, known as iShares, which now accounts for half of all US investments in the products. There continues to be strong demand for iShares's ETFs driven by the evolution of the US retail channel (from commission-based to fee-based) and increased adoption by institutional clients and pricing reductions in its core series. Year to date, iShares accounted for about 50% of total ETF flows in the US.
Passive investments, like ETFs and other products that track a weighted index rather than a single equity, have steadily eaten away at active managers' portfolios in recent years.
BMR Take: BlackRock is among the best-positioned companies in investment management owning the top ETF franchise that is growing rapidly due to passive investing, as well as an increasing product portfolio of technology. Recall, there are several top hedge funds on the list of shareholders in BlackRock. With EPS set to approach $30 over the next 3 years, this stock pick is among our favorites.
Upcoming Economic News
Industrial Production
Tuesday, October 17, 2017 09:15 AM
Period: September
Consensus: 0.30%
Prior: -0.90%
Housing Starts
Wednesday, October 18th, 8:30 AM
Period: September
Consensus: 1,180,000
Prior: 1,180,000
Continuing Jobless Claims
Thursday, October 19th, 8:30 AM
Period: October
Consensus: 1,895,000
Prior: 1,889,000
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
The 4th quarter is off and running strongly, which is not uncommon. Even though it includes October (Octoberphobia), Q4 has historically been the strongest quarter of the year for the S&P 500. Since 1950, the S&P 500 has gained 4% on average in the fourth quarter, advancing 79% of the time. Oil dipped back under $50 per barrel and gold has fallen over 7% in just the last month because the US Dollar has strengthened due to the belief that the Fed will hike rates again in December. Maybe or maybe not. We still think tax reform is a bigger wild card than another Fed hike. The expectation of tax reform has resulted in just about everything with the exception of energy being up for the year, but even energy has some building tailwinds.
According to Boone Pickens Advisors, worldwide demand is soaring and set to hit 100 million barrels per day next year – a feat that was only expected around 2025 by most long-term forecasts including those from OPEC and Exxon. Growing energy demand is normally associated with growing economies, so this continues to be good news for future market gains based on earnings growth. The point being made is that if the market suffers a setback due to the failure of tax reform, it should not develop into a real bear market because of the support to be found in continued earnings growth. If Boone Pickens Advisors is right about soaring demand for energy, there is plenty of upside left in this bull.
General Electric (GE: $23, down 10% this week, and down from $32 in December - wow)
The drop in the stock in the last 10 months is almost 30%. With a market cap of $200 billion GE is not going away. But they are the Dog of the Dow. You know what the Dogs of the Dow are, right? They are the five worst performing stocks of the 30 Dow stocks. GE is gunning for THE DOG of the Dow this year. Many value money managers love this stuff. They buy the Dogs and historically, they have been big winners the following year and years.
We are thinking of adding GE to our Stocks For Success portfolio, not just because of the thinking in the above paragraph but for a host of other reasons. It has just had a shakeup in management, which will continue for the next few months. Old CEO out (Immelt), new CEO in (John Flannery). Lots of executives leaving or getting pushed out. Dividend is 4% which is pretty darn good for a Dow stock. 100+ year history of success as a global business leader. Lots going on with this huge company.
A note about the dividend. Some analysts think the dividend could get cut in order to conserve cash. This would be bad and good news. The stock would probably get nailed by another 10% down to $21 or even lower, but that would most likely mark the bottom. So if you are thinking of taking a position, keep this in mind. In other words, keep some cash around (keep your powder dry) in order to buy more at a lower price. If this dividend cut doesn’t happen, then buy some more as the stock moves up over the coming 24 months as it gets back into the $30s. The all-time high is about $58 back in 2000, right after the bubble started bursting in the dotcoms. It dropped to $24 in 2002 and then rallied to $41 in 2007. It got whacked to $12 in 2009 in the financial crisis and has moved straight up for eight years to $32 in 2016. We think there is a good possibility of seeing $30 and $40 in this great franchise as we move into the latter stages of the twenty teens.
Again, we are thinking of writing a research piece on GE soon. We believe it is a long term winner for the super conservative investor.
Update on Shopify
As you know, we love Shopify (SHOP: $94, down 4%) but along came Andrew Left and his firm Citron announcing that he was short the stock, that it was going way down, and that the company was fraudulent, among other silly claims. Many analysts jumped in this past week on the story. Here’s what one of them said:
"Citron’s Argument is Weak
"Let’s call a spade a spade - Shopify is selling a dream.
"So, is the Shopify stock news on-point? Is Shopify using illegal marketing tactics in selling that dream? That’s a gray area to be sure, but is the marketing message remarkably more misleading than the TV commercials inviting consumers to participate in class action lawsuits that mostly enrich attorneys, but rarely pan out as well as expected for the actual plaintiffs?
"Is a vision of a healthy cancer patient within a television commercial for a cancer drug some sort of unspoken guarantee of long-term survival? Does a young man that uses the Axe brand of personal-hygiene products actually expect to be besieged by young women, as depicted in Axe’s television commercials?
"The answer to all these questions is, of course, no. The FTC tolerates the imagery simply because it knows it has to give consumers at least a modicum of credit in distinguishing the difference between a contract and a commercial.
"And as for Shopify’s lack of profits, Shopify is in good company. Most young companies don’t turn a profit until after they’ve matured, but savvy investors know the time to get into some of them is before, not after, that fact. Look at Amazon, the most prominent of the rags-to-riches stories. It’s been one of the best long-term investments anyone could have made over the course of the past couple of decades. Investors don’t care where a company is, they care about where it’s going.
"Looking Ahead for SHOP Stock
"Don’t misread the message. The FTC might crack down on Shopify’s advertising. The company might never turn a profit. The market might not care if Shopify does eventually turn a profit. Nobody really knows the future. That’s the speculative nature of stock-picking.
"Andrew Left, however, seems to be grasping at straws with this one. Though he certainly rattled shareholders by generating some rather alarming Shopify stock news headlines, this time his claims are more bark than bite.
"If your gut is telling you this may be a time to scoop up shares at bargain prices, you may want to trust your gut."
BMR Take: Again, this was an opinion of a consensus of Wall Street analysts. But we certainly concur. We think this guy Left is out in left field. Here’s a chart of the last six months. You can see that the stock is where it was in August, just two short months ago. In April it was $71. We think there is tremendous value here with this company and believe Andrew Left will be left high and dry.
Update on Cloudera (CLDR: $15.72, down 6%)
Nothing new this week, just a lower stock price, giving the stock even more value for the investor.
Here’s what we said three weeks ago on September 24th.
Cloudera (CLDR: $16.90, down 8%)
Cloudera is issuing new stock, diluting existing stockholders, hence why the stock is down. Specifically, Cloudera announced that it has filed a registration statement with the U.S. Securities and Exchange Commission relating to a proposed follow-on public offering of its common stock. A portion of the shares to be sold in the offering will be sold by existing stockholders of Cloudera, and a portion of the shares will be sold by the company. Cloudera will not retain any proceeds from the shares sold by existing stockholders. The number of shares to be sold and the allocation of the shares between existing stockholders and the company have not yet been determined.
Morgan Stanley, J.P. Morgan, and Allen & Company are acting as lead bookrunners for the offering. Merrill Lynch, Citigroup, and Deutsche Bank Securities are acting as book-running managers and Stifel, JMP Securities, and Raymond James are acting as co-managers.
BMR Take: Two weeks ago they reported this:
Recent Business and Financial Highlights:
Subscription revenue was up 46% year-over-year to $74 million
Subscription revenue represented 82% of total revenue, up from 79% in year-ago period
Subscription gross margin for the quarter was 85%, 200 basis points higher than second quarter fiscal 2017
Dollar-based net expansion rate was 140% for the quarter
45 net new Global 8000 customers added
And they have $500 million in the bank. Yes, they aren’t profitable yet, but remember, revenues tell all.
Taking a step back, companies do what Cloudera just did all the time — raise equity and use the proceeds for corporate purposes. It is not a reason for us to sell the stock or for the stock to be down as much as it is. The fundamental business has not changed one iota on this development. So it makes sense for us to stay invested. We will certainly keep a close eye on this management team though. For the time being, we are sticking with the company.
The High Yield Corner
By Michael Foster
Remember the slight volatility we recently saw in REITs? That’s gone. Instead, 4 of the 6 REITs in the High Yield portfolio were up this week, while two were flat. While not rising the most, Omega Healthcare Investors, Inc (OHI: $32, up 1%) is the most important and interesting story of the week. Extremely cautious, risk-averse investors dislike this stock because of its high yield (8%) and relative youth. Having been around since the late 1990s, it lacks the history of many dividend growth stocks. It also had a pretty disastrous collapse in its dividend back in 2000. However, that’s all long history by now. More recently, Omega Healthcare has devoted itself to a penny-per-quarter dividend hike that makes it a uniquely high yielding dividend growth stock. Some will warn that these dividend increases are unsustainable, and that may be true. But if the hikes last 10 years instead of 2 quarters and you avoid it because it won’t last forever, you’re giving up some extreme gains over a decade. This is how risk averse behavior cuts into returns.
The more aggressive investors who own Omega realize this, which is why they look at both the firm’s FFO and its dividend growth rate like a hawk. Last week, Omega yet again gave investors a penny-per-share raise. At the new payout, FFO covers the dividend pretty well - at a 125% rate. Bear in mind that that’s below the 130% threshold that we frequently write about here, which makes us cautious about the longevity of the rate hikes. We need to see FFO per share slow significantly before that dividend coverage ratio gets hurt and a cut becomes a mathematical necessity.
But how long could that take? Our best guess is that we have at least three years until a cut becomes necessary, but there are two factors that could grossly change that estimate. For one, shares outstanding growth. The more shares Omega releases, the more dividends it has to pay, which makes its FFO less powerful in covering payouts. Total shares outstanding have risen to 197 million from 196 million in the last year - a pretty small jump. But shares were just 68 million a decade ago, meaning an 11% annualized growth rate in total shares outstanding. That brings us to our second factor: FFO - funds from operations. During that same decade, FFO has risen 22% annualized over the same period. So you can see how Omega has been able to grow far beyond its obligations to shareholders and keep that growth rate going!
Can Omega continue? The real answer is no one knows, but there is reason to be concerned. The growth rate has slowed significantly in recent years, especially since Omega was smart to expand during the post-2009 years when all real estate was on sale. Deals are harder to find now, making growth a lot harder.
There’s another lever Omega can pull, though: Getting strong rent hikes. Keep in mind that Omega’s wheelhouse is a customer base that struggles with inflation, which makes rent hikes particularly challenging. For that reason, we think the long term trend of strong growth at Omega is definitely a thing of the past, and the penny-per-quarter hike cannot continue forever. But selling now and missing out on years of high yield dividend growth would be folly. Instead, we need to keep our positions and look closely at the numbers before jumping out. Now is not the time.
Our strongest REIT of the week is in many ways the exact opposite of Omega. Digital Realty Trust (DLR: $122, up 3%) saw a really strong week without too much relevant news. Last week the firm announced it would expand its Silicon Valley Connected Campus, with a new six-megawatt facility planned for 1Q18 delivery. This is a really small part of Digital Realty’s portfolio, comprising just a $75 million investment, so it isn’t enough to move the needle. Also, as counterintuitive as it sounds, Digital Realty’s strength isn’t in the Valley but in its distributed presence around the country. The company has many retail-facing clients, as well as the U.S. government, where the need is to have many hubs where human beings who use the Valley’s services are located.
Digital Realty is on track to grow that business, but the real story of last week’s price movement is more technical than fundamental. The stock has retreated from its 52-week high hit last month ($127), and after this week’s gains is approaching it yet again. The dividend yield is also nearing the sub-3% level, which it hit in September briefly before rising. We fear we may have a repeat of that in the short term - but that’s hardly a cause for concern. It simply means that Digital Realty is for the most part range bound right now, and we need to content ourselves with that while we wait for the company to aggressively ramp up its dividend. The last rate hike was in March, and another one by the end of the year would be nice. In reality, this company’s management has settled itself into a predictable pattern of one-per-year dividend hikes despite a rapid acceleration in FFO growth. FFO per share is now over double payouts - an absurd ratio to say the least! We would like to see Digital Realty aggressively ramp up its dividend hike schedule.
We doubt we’ll see it anytime soon, but we do think it’s an inevitability with this company. Simply put, it cannot stop making money, and its business is growing too rapidly for it to be at risk anytime soon. Eventually, Digital Realty will need to start increasing its dividend more frequently or doing much more aggressive dividend hikes. Either way, its 3% yield at current prices is destined to turn into more of a 5% yield in the next 3-5 years. For that reason, investors long the stock should stay tight even if you’ve been in it for the past year and are sitting on some attractive capital gains.
Good Investing,
Todd Shaver, CEO, Founder and Editor
The Bull Market Report
Since 1998
August 21, 2017

by Todd Shaver | Aug 21, 2017 | Monthly Newsletter Daily 12pm if new
The Weekly Summary
It was rough week with lots of domestic and international issues popping up, producing anguish. In particular, nine CEOs turned their back on Trump. It all started when first Merck’s Kenneth Frazier, then Under Armour’s Kevin Plank and Intel’s Brian Krzanich stepped down from a White House business group set up to advise Donald Trump. While none mentioned the president, Frazier, one of the country’s most-prominent black chief executive officers, quit the council as Trump was being assailed for failing to quickly condemn white supremacists for deadly violence at a rally Saturday in Charlottesville. Frazier said he was acting on a “matter of personal conscience.” Trump shot back on Twitter Tuesday morning, saying, “For every CEO that drops out of the Manufacturing Council, I have many to take their place.
Then on Wednesday President Trump rushed to announce that he was shutting down the two advisory councils of business leaders, after the members had decided on their own to disband in the wake of the president’s comments on the events in Charlottesville. Of course, these kinds of advisory councils seldom accomplish much of anything.
Look, all this drama will pass. The market will move on. But there is definitely an unsettled feeling out there. It is good that the market showed signs of turning around at week’s end, but we did see a few glimpses of nasty selloffs in a few trading sessions this week. It was a rough week. If you are super worried, then we suggest you take some profits off the table. There are many choices for you to move your money to in the High Yield and the REIT portfolios. These are much more secure, stable stocks with very nice dividends that you can enjoy and sleep better with.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks/funds where we think you can still make good money, including: high yield equities like Annaly and larger caps like Apple, Google, Microsoft, Home Depot, and Visa,
BMR Companies & Commentary
Annaly Capital Management (NLY: $12.34, up 1%)
Annaly recently reported respectable earnings at the beginning of the month. Here are our thoughts on the outlook for the rest of the year and what to watch. Many people are cautious given Annaly’s fixed-rate agency exposure and the current valuation. We know that the company has a set yield on government guaranteed paper. So while there is no credit risk other than the full faith and credit of the United States, there is interest rate risk – we know this and accept this. The newer investments are coming on at lower rates with higher yielding holdings rolling off. And we know that if short term rates rise the current portfolio valuation will be sensitive to the movements. We are likely to see some pressure on Annaly’s business model.
But what can the company do? They can rotate into higher yielding MBS* investments. They can increase leverage. They can do a number of things to cover the dividend. Look, if you think a business model is flawless without risk then you don’t know it well enough. Annaly has rsk to higher rates, but higher rates are ultimately good for the company. And investors are missing all the offsetting possible moves management can take. Remember, this is a company that is 18x the size of the median mortgage REIT by market cap, has outperformed the S&P 500 by 3x since its IPO for total return, and has successfully raised $1.5 billion in new capital this year. They know the world they live in and have survived and thrived for 20 years.
* Mortgage-backed Securities
BMR Take: A Director at the company just bought 13,500 shares. Another one just bought 17,700 shares. We love love love to see that! We are looking at a $0.30 dividend paid quarterly for the time being which is good. The stock looks compelling based on this income stream, producing a dividend over 10%.
Apple (AAPL: $158, flat) is Getting into Programming
Apple has set a 12-month budget of $1 billion to develop original programming. Apple could buy and produce as many as 10 TV shows. Apple's first two efforts -- Planet of the Apps and Carpool Karaoke -- have not been warmly received by critics. Apple executives are talking with Hollywood agents about shows that Apple can buy.
BMR Take: Note that Apple has $260 billion in cash now, and with a market cap of $813 billion cash is 32% of the stock price. So $50 of the stock price is in cash. This is UNPRECEDENTED in the history of Wall Street. Apple remains an exciting investment opportunity. The services business is projected to double in revenue to $50 billion over the next several years. The Services business is much more profitable than hardware so the impact to earnings is even better. Don’t sell a share. We believe Apple has a lot more room to go on the upside.
And how about Apple's performance last week in a very tough week for equities.
Google (GOOG: $911, flat)
The Cloud is a huge opportunity in technology and all the industry giants are fighting to grab their fair share. Let's stipulate up front that Amazon Web Services (AWS) remains the top choice for most companies that are thinking about moving their data and software into cloud data centers. Having said that, however, Amazon's cloud is no longer the only option that companies consider. For example, those companies wanting extensive analytics are taking a good hard look at the Google Cloud Platform. And many firms are hedging their bets by using multiple cloud providers to avoid being stuck with one down the road.
While AWS is still the largest cloud provider by far, Microsoft and Google are coming on strong. AWS's revenue growth appears to be slowing, in part because it's hard for such a huge business - AWS is expected to produce $16 billion in revenue this year - to grow as fast as its younger, smaller incarnations. Startups are considering alternatives now for several reasons: standard cloud computing and storage services from the three top players are all seen as competitive, and no one thinks any of the three major cloud contenders is going away. Basically, AWS, Microsoft, and Google are seen as safe bets.
BMR Take: Google took a hit on the recent earnings report. Buy the dip. This company will generate over $40 of EPS in 2018. The stock is far from a stretched valuation.
Microsoft (MSFT: $72, up 1%)
As Internet-of-Things (IoT), artificial intelligence (AI), smart factories and intelligent applications continue to advance, businesses are increasingly turning to these technologies to create new business solutions with greater agility in order to drive competitive advantages. Microsoft launched its IoT Innovation Center in Taiwan last October to spur development between IoT partners and international enterprises and organizations. In September, Microsoft will hold its second IoT Expo in conjunction with the World Congress on Information Technology. Jason Zander, Corporate Vice President, Microsoft Azure, will deliver a keynote on "Leading Digital Transformation and Landing IOT Value with a Strong IoT Partner." Zander oversees the development and global deployment of cloud infrastructure and technology, including Microsoft Azure IoT. In addition to sharing the success of Microsoft's IoT Innovation Center and its partners, Mr. Zander will also provide Microsoft's vision of the development of IoT and in-depth analysis on the integrated application solutions of the world's leading IoT partners.
BMR Take: The Internet of Things is a megatrend. We are going from 10 billion devices connected to the internet to 30 billion. Your hair dryer will be connected to the internet someday. All of this is going to be a huge opportunity for Microsoft. The company is on track to generate $4 of EPS in 2018. The valuation remains compelling.
And note how strong Microsoft was last week in the very rough week on Wall Street. This company is solid.
Upcoming Economic News
Richmond Fed Index
August 22th, 10:00 AM
Period: August
Consensus: 12.0
Prior: 14.0
New Home Sales
August 23th, 10:00 AM
Period: July
Consensus: 614,000
Prior: 610,000
Building Permits
August 24th, 8:00 AM
Period: July
Consensus: 1,223,000
Prior: 1,223,000
Blackstone Entity Merging with Starwood Homes
Invitation Homes (INVH, $23), a portfolio company of The Blackstone Group (BX: $32, down 1%) , is merging with Starwood Waypoint Homes. The combined company, to be called Invitation Homes, will have 82,000 homes. Once the deal closes Invitation Homes stockholders will own about 59% of the combined company. The total enterprise value of the deal is $20 billion.
Invitation Homes, a U.S. home rental company, went public in February. Blackstone will own about 40% of Invitation.
--- The portfolio of homes will be focused on high-growth markets, with nearly 70% of revenue coming from the Western US and Florida.
--- The merger is expected to drive $50 million in annual synergies.
--- Continued strong performance with the combined company experiencing 7% same-store NOI growth in Q217 with over 95% occupancy.
--- The two companies have invested nearly $2 billion, an average of approximately $22,000 per home, in renovations and maintenance, improving resident experience and driving economic growth and job creation in local communities.
BMR Take: Just one more example of the innovation that Blackstone is involved with day in and day out. With a dividend of 7% and a leader (Schwarzman) dedicated 24-7 to moving the stock higher, what is there not to like. $38 billion market cap. Reaching the all-time high of $44 set in 2012 is surely on the horizon.
Tesla Near to Completion of Gigafactory
Tesla ($348, down 3%) has released some interesting pictures and a video of their gigafactory in Nevada, 95 times bigger (sic) than a football field. New drone footage shows how massive Tesla's Gigafactory is.
http://www.businessinsider.com/tesla-gigafactory-pictures-facts-2017-8
In other news, Tesla raised $1.8 billion in a bond sale on Friday, boosting the amount by $300 million to meet demand. The 8-year bonds were priced at a record-low yield of 5.3%. The 5.3% coupon is a record low for a bond of its rating and maturity, according to data compiled by Bloomberg. The sale was managed by Goldman Sachs Group and Morgan Stanley.
BMR Take: The bond market loves this company. We do too. But we know the risk involved here is on the high end of the scale. Tesla is either headed to $400 a share or $300. And one could make an argument for either. If it hits $400 and they continue to ramp up production as promised, then $500 is a great possibility. But if it goes to $300, $200 would be in range. You want a risky stock? Then Tesla is your baby.
Amazon Sells Bonds for Whole Foods Acquisition
Speaking of bond sales, Amazon (AMZN: $958, down 1%) went to the markets for money last week and sold $16 billion of unsecured bonds to fund its $14 billion acquisition of Whole Foods Market. And in a sign of market interest, the longest portion of the offering, a 40-year security, was sold at a yield of 1.45 percentage points above Treasuries.
BMR Take: Now that is just unreal low. The company has $21 billion in cash so they didn’t need to go to the bond market but did because rates are so low. Smart thinking, Jeff. The deal is the 4th largest this year, behind ATT and Microsoft.
Apple Goes to the Debt Market in Canada
Apple raised $2.5 billion at a rate of 2.51% in a 7-year note sale in Canada on Tuesday. At $2.5 billion the financing is the largest corporate non-financial borrowing in Canadian history.
Stocks Cheap Compared to Bonds
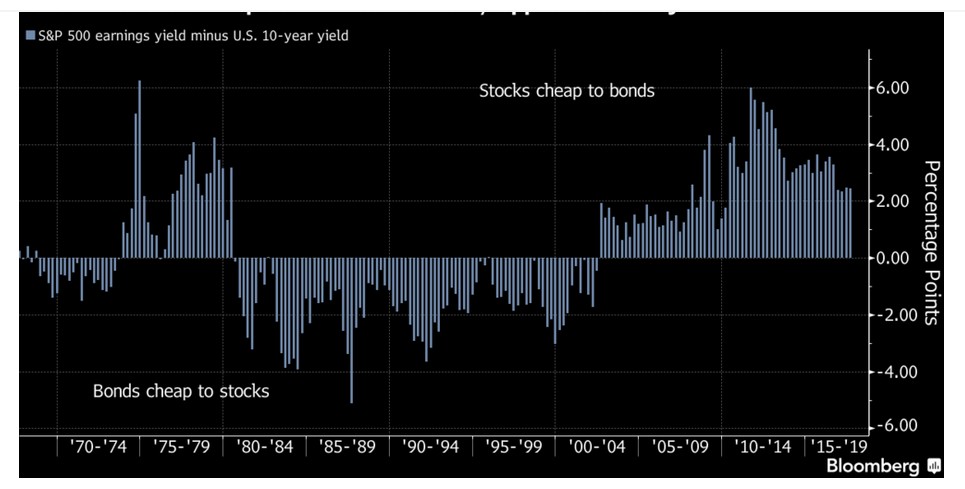 We’re Just Sayin’
The High Yield Report
By Michael Foster
We’re continuing to see market chaos and a lot of selling of high quality assets although the macro risks from political uncertainty are dwindling. But the current selloff is very different from the previous week’s in one very telling, interesting way: Not all assets are falling at the same rate, and some are actually doing very well.
To wit, take a look at The Bull Market Report’s Healthcare REIT pick Omega Healthcare Investors (OHI: $31) which had a strong showing this week after some initial weakness, helping Omega Healthcare end the week up 2%.
We’re seeing a lot of reshuffling in the markets, with investors rotating in and out of funds, stocks, and assets as they rise or fall due to market demand. This is the real “random walk” of Wall Street, and it’s a dynamic that makes short term trends for any individual asset to be unpredictable. In reality, we’re seeing a lot of individual investors making choices to buy on the dip - and they’re pulling money from other assets to do so.
What can an investor do in such an environment? Simple: sit tight. If you have extra cash on the sidelines, now is the time to deploy into the high yield picks that The Bull Market Report has been recommending for a long time. Last week we suggested buying more of Omega Healthcare shares; it’s up 2% since then. Now is the time to do the same with other REITs seeing irrational weakness like Sabra.
You can also consider adding Kimco Realty Corporation (KIM: $19.34) and Apollo Commercial Real Estate (ARI: $17.92) to your shopping list after Kimco fell over 3% in the last week and Apollo remained flat. There is no change in these companies FFO to justify the decline, and Kimco’s year-long weakness on the often-touted (and always inaccurate) “death of retail” has made it just that much more compelling. We have discussed at length here why Retail isn’t dead, and how Amazon’s recent purchase of Whole Foods indicates that the shift from pre-dotcom retail to mobile “bricks and clicks” commerce is far more complicated than the simple narrative of dying malls. In any case, Kimco doesn’t buy enclosed malls! It’s a high-quality strip mall-focused REIT, and Whole Foods (and thus soon Amazon) is one of its biggest tenants.
There are more buying opportunities beyond REITs, and investors are keen to lighten up their cash allocation to consider the other funds and stocks in the High Yield portfolio. However, there is one word of caution to consider when it comes to one of our best performing picks, the PIMCO Dynamic Income Fund (PDI: $29). This fund was flat last week.
What’s going on here is a pretty basic misunderstanding of the fund’s future income potential. You see, Pimco releases a monthly scorecard of net investment income (NII) on its website, while also calculating its dividend coverage ratio. And, simply put, the news isn’t good for the Dynamic Income Fund.
In the past, Pimco easily out-earned its dividend and had a tremendous amount of undistributed net investment income (UNII). That’s why the fund paid a special dividend of $1.45 at the end of 2016. By this time last year, the fund had around $1 in UNII, so it was pretty obvious that a big special dividend was coming (we discussed this at the time and estimated a strong special dividend at the end of last year – and nailed it). This year, however, the Dynamic Income fund has only 4 cents in UNII - a pretty tremendous drop from a year ago!
There are a few reasons why the fund isn’t earning as much income as it used to, most of which revolves around the crowding out of great investment opportunities in mortgage backed securities. The MBS is a pretty daunting asset made sinister by The Big Short and growing awareness of their role in the subprime housing crisis. However, that crisis is a decade behind us, and the quality of MBS investments has skyrocketed. While Pimco was one of the few asset managers aggressively buying up these assets in the past, there are now a lot of people wanting to buy them. That means lower yields for the assets, thus weaker income for the Dynamic Income Fund.
However, at the same time, it also means growing market prices for these assets. This fund’s NAV has risen by 10% so far in 2017, largely a result of that constant demand for MBS’s in the market. Last year, the Dynamic Income Fund’s NAV had risen by far less than 1% over the same time period, because the demand for these assets simply wasn’t there. That means that the fund is sitting on a lot of capital gains with dwindling income.
What does this mean for shareholders? In all honesty, it’s hard to tell. The fund hasn’t really faced a crowding out of supply due to strong demand since 2012. It has enjoyed both NAV and income gains in earlier years, and the end-of-year special dividends reflected that. We simply don’t know if the fund’s managers will decide to return some of those capital gains to shareholders or hold on to it and give a massively reduced special dividend at the end of the year.
It seems that the market has begun to price in the likelihood of a lower special dividend. The fund’s premium to NAV has plummeted from over 10% earlier this year to just 3%. It may fall even further as we get closer to December. If Pimco surprises and gives a big special payout at the end of the year, that could reverse quickly. If it doesn’t, we’ll probably see middling price growth throughout 2017.
The risk with the fund is that its Net Investment Income continues to fall and it fails to cover its dividend on a long-term basis. While we’ve seen hints of that now, it’s far too early to conclude that this risk is really here and it’s time to sell. But investors need to prepare for that eventuality. We will keep a close eye on this trend and advise you if it’s time to move out of this great fund. Hopefully we won’t have to recommend selling anytime soon.
How should you react? Holding the fund for its income stream makes sense now, and buying more when the fund’s premium disappears and it starts trading at a discount also makes sense. That means there’s no reason for investors to get scared and sell off the fund, but it also means investors shouldn’t expect a massive jump in the fund’s price throughout 2017. That’s not a bad thing - it really reflects what the fund should be seen as: A source of steady and reliable income.
Good Investing,
Todd Shaver, Founder, CEO and Editor
The Bull Market Report
Since 1998
