December 10, 2017

by Todd Shaver | Dec 10, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
The countdown to Christmas is underway, which means this year is coming to an end and the focus is turning to the outlook for 2018. This bull market has been nothing short of spectacular. We expect high-single digit returns in the stock market again in 2018. Our view is supported by rigorous analysis from Guggenheim Research, which points to the US not reaching a recession until late 2019 or 2020. Specifically, they say, the business cycle is one of the most important drivers of investment performance. It is therefore critical for investors to have a well-informed view on the business cycle so portfolio allocations can be adjusted accordingly.
At this stage, with the current U.S. expansion showing signs of aging, focus is now just gradually shifting toward the timing of the next downturn. Using history as a guide, however, you will find that it is possible to get an early read on when the next recession will begin by analyzing the late-cycle behavior of several key economic and market indicators. Together, they have provided advance warnings of a downturn. The best indicator is the Leading Economic Indicator Index, which compiles all the various indicators into one data set. The 10 components of the index cover weekly hours worked, manufacturing orders, initial jobless claims, building permits, new private housing units, interest rate spreads, and consumer sentiment. An analysis of these metrics suggests that the current expansion won’t end until late 2019. So keep your foot on the gas!
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks where you can still make good money, including: Tesla, Twilio, PIMCO Dynamic Income Fund, Amazon, Google, First Solar, and more.
BMR Companies & Commentary
Tesla (TSLA: $315, up 3%)
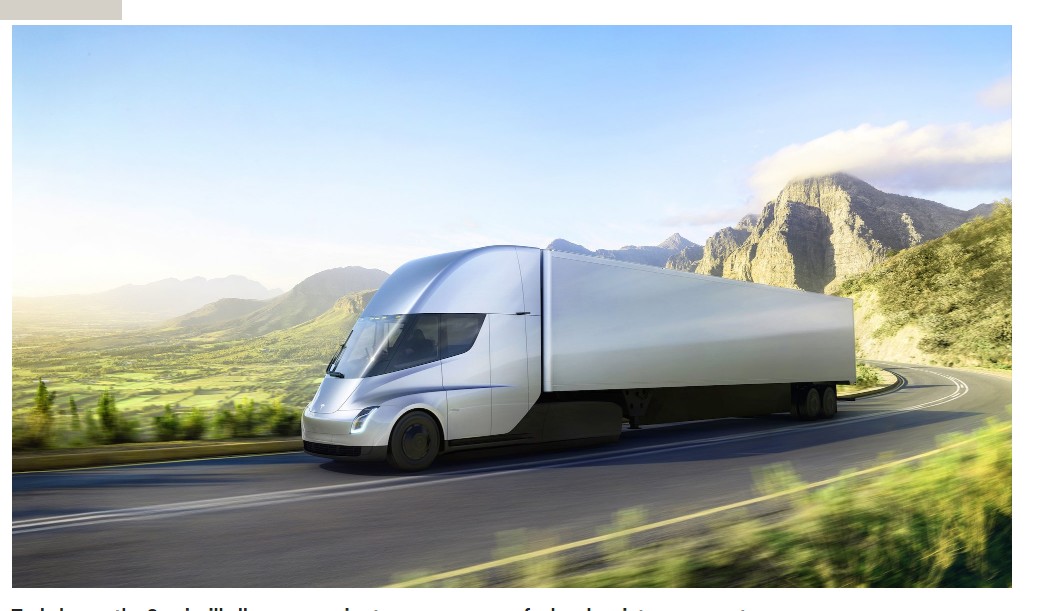
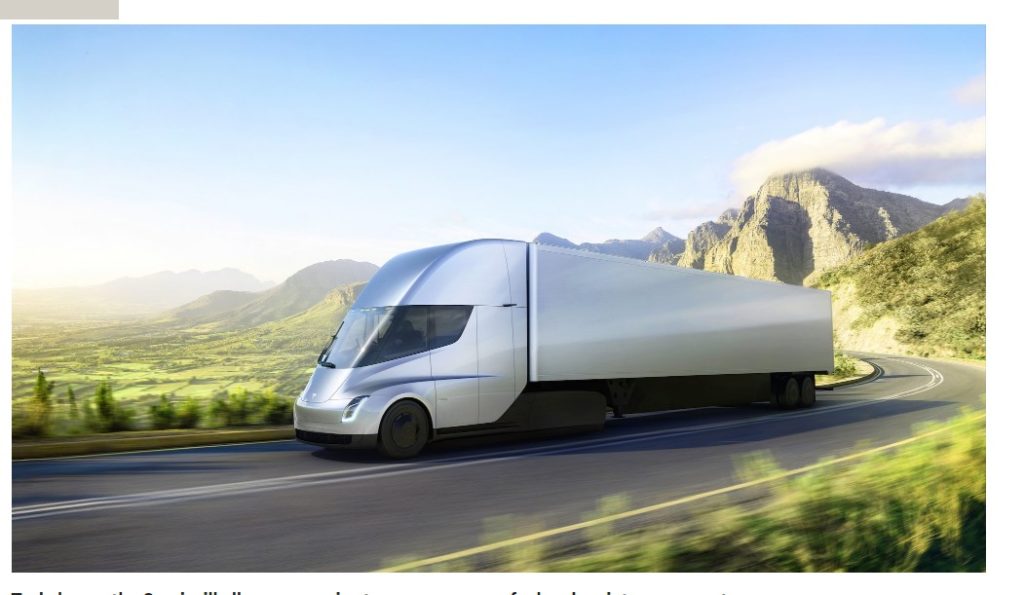
Anheuser-Busch has placed an order for 40 of Tesla’s new all-electric Semi trucks. The maker of Budweiser seeks to reduce fuel costs and vehicle emissions, along with other companies across sectors through the Tesla revolution.
Anheuser-Busch plans to use the trucks for shipments to wholesalers within 150 to 200 miles of its brewery locations - well within the 500-mile range that Tesla Chief Executive Elon Musk has promised. The vehicles would be deployed among the brewer’s dedicated fleet of 750 trucks, which bear the company’s branding but are owned and managed by outside carriers.
Anheuser-Busch’s preorder is still tiny relative to the broader heavy-duty-truck market, which produces 250,000 to 300,000 big rigs a year. Anheuser-Busch spends about $120 million on fuel each year for its dedicated fleets and long-haul transportation by for-hire carriers moving beer between breweries and wholesalers. The company wants to cut its carbon footprint by 30% by 2025, and has invested in alternative-fuel vehicles, such delivery trucks that run on compressed natural gas. This is big stuff!
BMR Take: Tesla is currently losing money, but the consensus 2020 EPS outlook is over $10. At some point we see all the innovation, like electric trucks, turning into major profits. Tesla remains one of the most exciting businesses in America.
--------------------------------------------------------------------
Twilio (TWLO: $25, down 5%)
Twilio hosted its analyst day in San Francisco this week. It was a good day. Twilio did a nice job of conveying the momentum in its business and how it plans to continue to drive rapid revenue growth at scale, but it did not guide to gross margins for 2018, and suggested that near term, gross margins may still move around a bit, even though management is confident in its longer-term target of 60-65%. The stock was under modest pressure accordingly.
Twilio provided three new disclosures to help investors better understand these gross margin dynamics, including: 1) gross margins have consistently been around 60%; 2) gross margins are negatively impacted by the international mix, which was 53% in 3Q17 for core voice and messages, far higher than the 24% figure Twilio discloses for the international revenue breakdown by account location; and 3) gross margins are positively impacted by application services revenue, which was $10 million in 3Q17, up 100% from a year ago and representing 9% of total revenue.
The company reinforced that demand is not an issue for Twilio. For example, the COO shared a story about how one sales representative was “drowning in leads.” He also disclosed that Twilio receives more than 7,000 “data-driven alerts,” or leads per month.
Twilio claims that it won 80% of new business opportunities against the top-five competitors in the first three quarters of the year. According to management, the top reasons customers select Twilio include: 1) trust; 2) omni-channel capabilities; 3) flexibility; and 4) innovation.
Twilio Investor Day tone was positive, says Baird. They remain positive on the company's competitive position and long-term growth opportunity fueled by increasing cloud communications use cases. They also remain positive on its stronger revenue growth and ability to improve margins long term. Baird reiterated their Outperform rating and $37 price target on Twilio shares.
BMR Take: Twilio currently trades at a big discount to where comparable high-growth cloud communications companies trade. We think this valuation disconnect will correct itself, leading to strong stock appreciation. With revenue exploding at greater than 60% per year towards $600 million by 2019, we see a compelling value here. The stock has been painful to watch but one of these days, Wall Street will take notice (again) and we will all be rewarded with our patience. If you can't take the pain, then you may just want to switch to some of the larger, safer investments like Apple or Google. We’re going to be right on this. Eventually. Watch and wait.
--------------------------------------------------------------------
PIMCO Dynamic Income Fund (PDI $31, up 1%)
With rising geopolitical tensions and good money been made in the stock market, we stress the importance of increasing your bond allocation. Pimco Dynamic Income is a great way to do it.
The portfolio maintains moderate exposure to US interest rates, where Pimco continues to emphasize the intermediate portion of the yield curve. However, due to historically low yield levels and continued flattening of the yield curve, the fund has some exposure to the long end of the US Treasury curve. Outside of the US, Pimco also has modest exposure to UK rates and an underweight to Eurozone rates.
Pimco maintains a focus on non-agency Mortgage-back securities (MBS) purchased at discounts to par, which provide a potential source of income and capital appreciation, as prices in this asset class continue to be supported by limited new supply and a strong US housing market. Pimco maintains exposure to corporate credit, including an allocation to high yield bonds in the Financial sector. The banking exposure is focused on slightly more risky opportunities that are more lucrative, given how stable the banking system is at this moment. PDI has exposure elsewhere in corporate credit, including allocations to select attractive names in Retail, Media, and Telecom. Pimco’s exposure to emerging markets remains highly selective and is focused on issues offering attractive spread premium and real yields coupled with strong underlying fundamentals, such as select Brazilian and Russian corporates, as well as Argentinian sovereign debt.
BMR Take: Pimco is offering just less than a 9% yield. And the fund is up over 20% this year. For fixed income this is amazing. This fund is a great place to increase your fixed income exposure and protect against unexpected drawdowns in the stock market.
--------------------------------------------------------------------
Amazon (AMZN: $1,162, flat)
The road is not always easy. Not even for Amazon.
Maine has canceled Amazon’s application to become a pharmaceuticals wholesaler. Their applications were canceled because they did not contain all the required information, and no action had been taken by the applicant to complete them, according to the state Department of Professional & Financial Regulation.
Amazon had submitted three pharmaceutical applications in October – all three expired on Friday, Dec. 1, according to the board’s online license check. Analysts are trying to decide whether Amazon merely stumbled and missed a local deadline, or if Amazon abandoned the license applications because it realized they were unnecessary if all it wants to sell are medical devices, not pharmaceuticals.
We have confidence Amazon will get it right!
BMR Take: The innovation machine is disrupting the globe. EPS estimates are now up over $20 by 2020. Amazon continues to have a long way to run. Our Target is $1200, but in our heads we are looking for $1500 and then $2000. We can’t tell you when the latter will occur, but we sure would like to see the former happen sometime next year.
--------------------------------------------------------------------
Google (GOOG: $1,037, up 3%)
Google is about to launch a small but useful update to Google Maps that will give you live guidance and interactive real-time notifications during your journey. The idea here is to give you real-time updates while you are traveling.
To get started, you search for your transit directions in Google Maps as usual. So far, so good. What’s new here is that you’ll soon be able to tap a “start” button at the bottom the screen with the details about your route and get live updates as you walk or ride on your local buses and trains.
Our understanding is that Google Maps will even remind you to get off your bus or train when you get close to your stop. That’s definitely useful when you’re traveling somewhere new. The notifications on the lock screen are also new. One nifty feature here is that they are interactive, so you can scroll right through your journey’s steps.
While Google Maps always did a good job of giving you detailed directions, the process generally involved keeping track of your own progress along the route. With this update, transit notifications become a bit more like using Maps for walking, biking and driving. This update is to go live soon.
BMR Take: Google is always advancing the world and this is just the latest example. When you can make the world a better place, revenue and profits follow. Google is expected to earn $57 of EPS by 2020 up from $32 this year. What a great place to invest!
The information here isn’t earth-shattering – (it’s hard to come up with earth-shattering news every single day (but we try)), but we’re trying to make a point here and that is that this company continues to innovate every day. A little here and a little there and eventually it goes to the bottom line. Revenues for the past few years look like this: $55 billion in 2013, $66 billion in 2014, $75 billion in 2015 and $90 billion in 2016. What about 2017? They’re on track for $105 billion. They made $19 billion after tax last year and they are going to better that for 2017, and with $100 billion in cash on the books and virtually no debt, we can’t think of a better place to put some of our hard-earnings savings.
--------------------------------------------------------------------
First Solar (FSLR: $70, up 16%)
A lot of bad press is confusing the outlook for renewables. Don’t get confused. Renewables are the future and First Solar is going to play a critical role.
What is being said? Less than a year into President Trump’s time in office, clean energy developers face a slew of unanticipated threats from the White House and Republicans in Congress that could slow the industry’s growth in ways unimaginable just a year ago. During Trump’s presidential campaign, energy analysts were skeptical of his promise to preserve the coal industry at the expense of wind and solar. Even the most aggressive attempts at regulatory rollback couldn’t reverse the market forces driving the decline in coal, they reasoned.
But the administration has not stopped at mere deregulation. From the threat of a subsidy for coal-fired power plants to a tax bill that hurts the financing of clean-energy projects, Republicans in Washington have launched a campaign against renewable energy that includes market interventions that alarm other industries, including Oil and Gas. Even if these measures never come to fruition (advocates of transitioning from fossil fuels are pushing back) the changed mood in Washington threatens to undermine the confidence of companies planning to invest in renewables.
BMR Take: First Solar is taking the Energy sector forward with the most sustainable technology on the market. Expected EPS of nearly $4 by 2020 is up from $2.50 this year, but the 10-year outlook is where the real money is. This company is just getting started. Our Target is $65, but the stock has blown through this. So we hereby raise our Target to $78 and our Sell Price from $45 to $61.
--------------------------------------------------------------------
--------------------------------------------------------------------
Economic Calendar
JOLTS Job Openings
Monday, December 11th, 10 AM Eastern
Period: October
Actual: N/A
Consensus: 6,100,000
Prior: 6,093,000
PPI ex-Food & Energy NSA
Tuesday, December 12th, 8:30AM
Period: November
Actual: N/A
Consensus: +2.3%
Prior: +2.4%
Initial Claims
Thursday, December 14th, 8:30 AM
Period: December 9th
Actual: N/A
Consensus: 240,000
Prior: 236,000
Capacity Utilization
Friday, December 15th, 9:15 AM
Period: November
Actual: N/A
Consensus: 77.2%
Prior: 77.0%
--------------------------------------------------------------------
--------------------------------------------------------------------
Some Tidbits – Apple, Home Depot, Cloudera, Bitcoin
Apple (AAPL: $169, down 1%) is confident that apps removed from the China app store will be reinstated, Reuters says. Apple's CEO Tim Cook said the company is optimistic that apps that were pulled from its China App Store will be reinstated.
Also, Dialog Semiconductor is losing staff to Apple, Business Insider reports. Apple is continuing to hire away designers and engineers from Dialog Semiconductor (DLGNF), one of its suppliers. Around 28 Dialog engineers and designers have moved to Apple between March 2016 and now.
Also, the new tax plan would cut $47 billion from Apple's tax liability, The Financial Times reports, if Republicans push through their current tax plan, making it the biggest beneficiary of the legislation now working its way through Congress.
--------------------------------------------------------------------
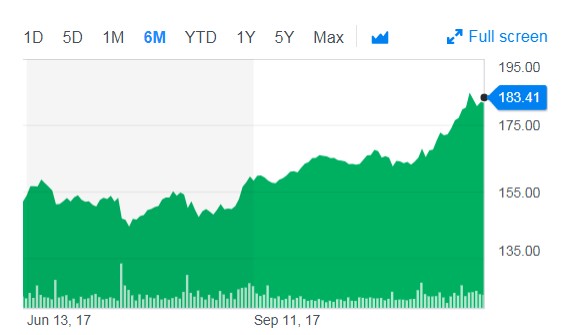
Home Depot (HD: $183, up 2%) set a new all-time high this week. It is now worth $215 billion. Wow. The company announced a $15 billion stock buyback, and the initial reaction on the Street was a slight sell-off. Silly.
How’s this for a 6-month chart?
--------------------------------------------------------------------
Cloudera Reports Strong Revenues
Cloudera (CLDR: $16.84, up 6%) reported that revenue rose to $95 million from $67 million in the year-ago period, a gain of 42%. Profits were in the negative, so although we are pleased with the revenue growth, we’re not happy with the losses. The stock had a little bump last week and it may go a bit higher, but it is not going to $30 or higher where it ought to be until it starts actually making money. We love this company but realize this is a multi-year investment from here. Patience is key here. But our patience is certainly running thin. The quarter was strong, so that gives us hope.
Bitcoin (BTC-USD: $14,840) has a market cap of about $250 billion, about the size of Visa. It was quite a week, as it rose from the $11,000 just one week ago. In the interim it hit $17,000 or so, and futures trading starts Sunday (the 10th).
Bitcoin Chart for the Past Month

--------------------------------------------------------------------
--------------------------------------------------------------------
The High Yield Corner
By Michael Foster
While the stock market went nowhere fast last week, high yield investments were a bit more mixed. We saw strength in municipal bonds for the first time in a long while, as this was overdue. The uncertainty regarding tax reforms caused some selling, but now the market is realizing that muni bonds are vastly oversold, which is helping to bring some money back into the market. Additionally, the slightly more risk-averse market is helping some money flow into muni bond funds, driving them up again.
As a result, Nuveen AMT-Free Municipal Credit (NVG: $15.68, up 2%) and Invesco Municipal Trust (VKQ: $12.57, up 2%) both had a good week, meaning the strong buying opportunity is mostly over. It’s not entirely over, however. Both funds are trading at about a 6% discount to NAV on average, a bit lower than the 5% discount we saw for much of 2017. What’s much more encouraging is the positive change in NAV we’ve enjoyed throughout 2017 - these funds are up about 5% on average on their net asset value even after their 5% dividend payouts. That means these dividend payouts remain sustainable and investors can expect a strong total return in addition to the tax-free income stream these funds provide. We wouldn’t be surprised if we saw more investors jump into the muni market, driving these funds higher and their discounts lower.
Elsewhere in the high yield world, we saw growing discontent. Specifically, Government Properties Income Trust (GOV: $18.29, down 3%) had a challenging weak on no news. This is largely a result of continued concern that Government Properties is overly levered and highly dependent on government agencies who are squarely in the majority Republicans’ crosshairs when it comes to cutting expenses wherever possible.
Of course, neither of these facts have changed in the last week, but admittedly the 8% and 7.5% yields that this stock offered earlier in the year were too low to compensate for the risks that the fund’s portfolio afforded.
Some context is important here. The Bull Market Report first recommended this stock back in April of last year when it was yielding 9.5%. Since then, the stock has given a near 14% total return to investors thanks to a slight bump in price and a consistent 43 cent quarterly dividend payout.
The Bull Market Report did not recommend selling this fund during its run-up earlier in 2017 for one specific reason: income sustainability. The most crucial metric to look at with REITs is FFO* and its relation to dividend payouts. Over the last 12 months, this REIT’s FFO was $2.15, while the dividend is an annualized $1.72. That’s a 125% dividend coverage ratio, slightly short of our preferred 130% dividend coverage target. But that shortfall is compensated for by the higher yield.
* Funds From Operations
To put that into context, let’s think about another beaten-down REIT: Omega Healthcare Investors, Inc (OHI: $28, up 1%), which has around a 130% dividend coverage ratio and a 9.4% dividend yield. With such a strong and sustainable income stream and a high yield, these are ideal contrarian income plays despite the justifiable concerns about the fundamentals. With Omega, the worry is that there are too many skilled nursing facilities and lower-than-expected demand. With Government Properties, the worry is that there is going to be depressed demand from a belt-tightening government.
These concerns are well compensated for by yields over 9%. When you get to double-digit yields (which is very unlikely with Omega but not impossible with Government Properties), you’re getting paid too much for the risks. We believe there is a chance of seeing its stock drop to a level where yields are 10%, which makes it a hold right now but not an absolute great buy. But when it comes to the sustainability of the dividend, we clearly see no risks at all to the dividend for a long time - in fact, possibly for several years.
How many years? To answer that, we need to look at the duration of outstanding leases in Government Properties’ portfolio. At 5.1 years, 28% of the company’s leases will expire before 2020. And in the next 5 years, almost 60% of the company’s leases will expire.
This is a double-edged sword. On the one hand, there is a risk that the company won’t be able to lease those properties to new tenants, causing occupancy rates to fall, income to fall as well, and the dividend to be increasingly at risk. On the other hand, there’s an opportunity for the company to lease those properties to those tenants or new tenants at the same or higher (possibly much higher) rents. This latter scenario is how we feel. The government needs the space and the record of the government in cutting down its size is, as you know, abominable.
So what is the likelier scenario - falling occupancies or rising rents? Bears are arguing for the former, and we would argue that that scenario is already priced in. However, falling occupancies is more unlikely than the market is expecting for a couple reasons.
Firstly, commercial leasing activities are going up. According to Jones Lang LaSalle, one of the biggest commercial leasing firms in America, leasing activity is at its highest point in 2 years and it’s trending higher. Government Properties has been shifting away from government leasing to office leasing, so it will benefit more and more from this trend. Thus the chances of finding new tenants paying higher rents is actually pretty good.
Secondly, there’s a paradoxical market lockup in commercial real estate REITs despite strong rent growth. Office-space REITs are one of the most heavily discounted (infrastructure and data centers are the most premium priced) in large part because of the market jitters about future occupancy rates, which paradoxically is forcing more conservative fiscal decisions among office REITs like Government Properties. But we have clearly hit a bottom in terms of pessimism, and when enthusiasm comes back to office space REITs, which will likely come as soon as the market notes the strong growth in leasing activity and rent growth, companies like Government Properties will be able to expand even more.
That means patience is in order. Expect more negativity and worries about Government Properties in the short term. But the fears about its soon-to-expire portfolio are overblown, and when the market realizes this, more capital will flood into the stock. It may take until 2019, when 18% of the company’s portfolio expires. If those spaces are re-leased at the same or higher rates (which seems inevitable given the strength in the commercial real estate market), expect the stock to rise. Best to hold the stock now, collect the income, and wait for that bump in a couple of years.
Good Investing,
Todd Shaver, Founder and CEO
The Bull Market Report
Since 1998
November 26, 2017

by Todd Shaver | Nov 26, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
The big story this week was Jeff Bezos breaking the $100 billion level in net worth. Unreal! Bill Gates was the last person to attain the 12-figure fortune in 1999 but then the stock halved and didn’t reach its peak again until 2016. (Take a look at Microsoft’s 5-year chart just below this paragraph.) It’s a very relevant event as we head into the holiday season. Every retailer has been hard at work not to get “Amazoned” this holiday season. Expectations are moderate and the data out for Black Friday shows consumer demand is healthy. With this healthy spending, the economy should grow 2-3%, which means new Fed Chair Jerome Powell is about to take the world for a ride of at least seven rate hikes over the next 24 months. Hmmm. When it comes to interest rates we always get the good with the bad and the bad with the good.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks where you can still make good money, including: Facebook, Apple, Tesla, and PayPal.
This issue will be slightly shortened from our normal newsletter as the week was a short one with the Thanksgiving holiday and a very quiet market. We will be back to normal next week.

BMR Companies & Commentary
Facebook (FB: $183, up 2%)
Italy is bracing for an electoral season of fake news and demanding Facebook’s help. We think this is just the beginning of major future reliance of governments on Facebook.
With critical national elections only months away, anxiety is building that Italy will be the next target of a destabilizing campaign of fake news and propaganda, prompting the leader of the country’s governing party to call on Facebook and other social media companies to police their platforms. What can Facebook really do though? They are between a rock and a hard place. Where is the line between free speech and mal-behavior? Facebook could potentially get this really right or really wrong. There will definitely be a significant impact to the user base over the long haul from all this.
In a global atmosphere already thick with suspicion of Russian meddling in elections in the United States, France and Germany, as well as in the British referendum to leave the European Union and the Catalan independence movement in Spain, many analysts consider Italy to be the weak link in an increasingly vulnerable European Union. Hopefully Facebook could catch a few bad actors and look like heroes!
BMR Take: You know, we’ve thought this for years now but haven’t said it and we believe Facebook knows this to be true but they haven’t said it either, and that is that Facebook is like the phone company. People use Facebook like they use a phone. They use it for good and they use it for bad. Same with a phone. If a terrorist calls up a bank and says to look out, you can’t come down on the phone company for this offense. Same with Facebook. But you don’t hear the company complaining about this because they don’t want to be REGULATED like the phone companies are. So we won’t talk about it any more!
Facebook is closing in on earnings of $6 of EPS with revenue soon to exceed $50 billion. The numbers the company is posting are massive and we are still far from the end of the growth cycle for Facebook. Our $190 target is within reach.
------------------------------------------------------------------------
Apple (AAPL: $175, up 3%)
Apple typically sells tens of millions of iPhones each holiday season, regardless of whether the company offers holiday discounts. But with its HomePod smart speaker officially delayed until next year, a limited supply of the iPhone X and no virtual reality headset yet, Apple faces intense pressure this shopping season. This is not the normal expansive product line-up we see from Apple. They have some challenges this holiday season.
But the super-hot iPhone should get the job done. While they were a bit late in their deliveries, and Apple's iPhone X may be popular, it's behind competitors like Samsung in adding features like bigger and brighter screens. The good news is the Apple users are very loyal and unlikely to switch to Samsung for a screen.
BMR Take: Apple is about to do over $12 of EPS, over $275 billion of sales, and sell millions of iPhones. This stock is a core holding for any portfolio. We continue to closely watch the company generate new services revenue from the massive customer base of iPhone users. Our Target Price of $194 is coming into view and our Sell Price of “We would not sell Apple” tells you our conviction in this great company. Note that at $194 Apple will reach the $1 trillion market cap threshold.
------------------------------------------------------------------------
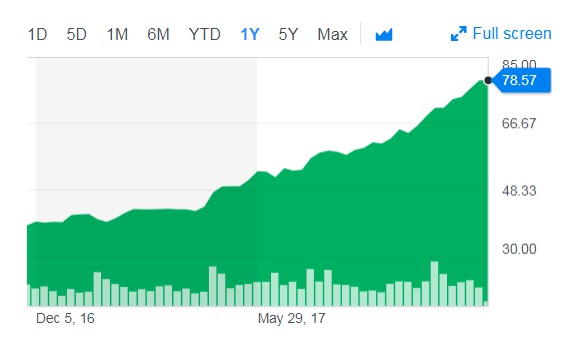
PayPal (PYPL: $79, up 3%)
The biggest thing happening this holiday season is mobile purchases. And mobile purchases don’t get paid for with cash. They get paid for with PayPal much of the time. According to PayPal, people will spend $630 billion during the holiday shopping season, of which 10-12% is done mobile.
The story is just getting started for PayPal.
In China, 60-70% of sales are done online and mobile. PayPal is making strategic deals and partnerships to build out a global platform that touches every corner of the world including China.
We expect explosive growth in mobile shopping this holiday seasons. We anticipate PayPal and all its various entities to experience robust business in the fourth quarter.
BMR Take: EPS is closing in on $2.50. With a few hundred million users, versus Facebook’s 2.1 billion, this is just the early innings. Our Sell Price is “We would not sell PayPal” and as noted last week, we have just blown past our prior target of $77 and have raised the bar to $87.
------------------------------------------------------------------------
Bitcoin Continues Its Huge Run
The chart just below here was produced on the 21st, just six days ago and is already obsolete. Bitcoin was up over $800 just this weekend and is now over $9000. The market cap of bitcoin is $155 billion, up from $100 billion earlier this month. The market cap of all cryptocurrencies is now $290 billion, up about $100 billion in just two weeks. This is not a fly-by-night scenario. It is real and the market is exploding.
If you want a good site to explore, go here:
https://CoinMarketCap.com

------------------------------------------------------------------------
The Significance of the New Tesla Roadster and Tesla's Main Intention in Unveiling It
We got this letter from a subscriber who just loves Tesla (TSLA: $315, flat).
Hi, Todd. A member of the Tesla Motors Club wrote us his thoughts on the new Tesla Roadster, which I'm pasting in below.
Wishing you a happy Thanksgiving,
Janice
From: jmgnyc@aol.com [mailto:jmgnycx@gxxx.com]
Sent: Wednesday, November 22, 2017 9:36 AM
To: info@bullmarket.com
Subject: A Roadster Thought
“Last night I was able to attend the Tesla Semi-truck event at Tesla’s Design Studio in California. As usual, gobs of Tesla enthusiasts cheered and were blown away by what Elon Musk and his team shared about the Tesla Semi and the unexpected new Tesla Roadster - which came as a surprise to many. I can say that the car looks even better in person than in photos or video. It’s truly a gorgeous and stunning car, and also the specs are insane. Not only can it do 0-60 mph in 1.9 seconds (which is hard to fathom) but it also has a 200kWh battery that can go over 600 miles. This is stuff that most didn’t think was even possible.
“I don’t expect Tesla to sell tens of thousands of these annually and I don’t think Tesla thinks they will also. I think their main intention is to show a proof of concept that the ICE (internal combustion engine) car is truly dead. In no way can an ICE car be better than the new Roadster. Basically, last night Elon and Tesla gave the ICE their farewell. Sure it will take many years before ICEs stop getting produced, but last night was the final reason why - because ICEs stink compared to what electric can do for cars. And that’s the significance of the new Roadster.”
BMR Take: We must say that this new Roadster could be a good source of funds for Tesla since it costs $250,000. If a couple of thousand enthusiasts order it, there's half a billion dollars coming into the company. The big test for Tesla in 2018 will be cash. They are burning through it like there is no tomorrow. But with a market cap of $53 billion, selling new shares of just 3% dilution will raise over $1.5 billion in fresh capital. We would expect investors to jump to be first in line to send the company money. With that said, if the money markets are tight next year, there may be issues for the firm.
Again, this one is not for the weak-hearted. Want to sleep at night? Buy Microsoft. Want to have some fun with funds you might lose? Jump on board with the Elon Musk and hang on for the ride.
------------------------------------------------------------------------
The High Yield Corner
By Michael Foster
Let’s deal with an interesting development hitting Omega Healthcare Investors (OHI: $27). Two different legal firms have filed suits against Omega Healthcare. The first lawsuit, filed by Brower Piven, accuses Omega’s management of "violations of the Securities Exchange Act of 1934 by virtue of the defendants’ failure to disclose that financial and operating results of certain of the Company’s operators were deteriorating, certain of the Company’s operators were experiencing worsening liquidity issues that were significantly impacting the operators’ ability to make timely rent payments, and certain of the Company’s direct financing leases were impaired and certain receivables uncollectible.”
The second, by Rosen Law Firm, is very similar (although more succinctly worded). This was announced Monday and accuses Omega’s management of failing to disclose that “financial and operating results of certain of Omega’s operators were deteriorating” and that these operators "were experiencing worsening liquidity issues that were significantly impacting the operators’ ability to make timely rent payments.” Finally, the lawsuit claims that "certain of Omega’s direct financing leases were impaired and certain receivables were uncollectible”.
What are these firms accusing Omega of? In short, Omega’s big tenant Orianna Health System is struggling to pay its rent because of disappointing occupancy rates and high costs. We’ve spoken at length here about the difficulties of the skilled nursing facility sector (SNF), and how growing revenues by increasing rents is extremely difficult because of the limited incomes of tenants. Furthermore, Medicare reforms could threaten Omega and other SNF-focused Healthcare REITs to grow their incomes in the future, which limits expansion plans and makes growing the base operations risky. On top of that, the lower than expected demand and higher than expected competition in the SNF sector make it difficult for a company like Omega to expand. It’s a triple-whammy.
That sounds really, really bad. And, as we have said here repeatedly, it does mean that Omega Healthcare is not a “buy and hold forever” stock. There will come a time when Omega’s expansions will reach their limits, where the cash flow cannot keep up with the dividend growth, and the stock will have to fall to reflect the structural challenges Omega has.
But here’s the other thing to consider: We all know this to be the case.
In fact, we also knew about the problems with Orianna; Omega has publicly discussed issues with this tenant in the past, and the SNF industry has been well aware of cash flow issues. The company has faced legal challenges in Idaho and scrutiny elsewhere in the country. Investors who didn’t do their due diligence may have been surprised by Omega Healthcare’s recent revelations -but those who did knew that this was a problem.
However, we also knew this was a problem that was priced into the stock. That’s why Omega yielded 8% upon Bull Market Report’s recommendation and competitors in the SNF REIT space were yielding less than 6%. It’s also why we demanded a higher dividend coverage ratio upon recommendation. Keep in mind that the REIT’s FFO-to-dividend ratio is now 130%, meaning it is still well out-earning its dividend. There is no cash flow issue to worry about here.
There also is not a debt issue. Total liabilities are $5.3 billion on $8.9 billion in assets, a 59% debt-to-asset ratio. This is low by REIT standards. The company’s annualized income was $900 million in 2016 and total operating expenses were $390 million for the same period. That’s a massive operating margin thanks in large part due to the lease conditions that Omega hammers out with tenants - conditions that are extremely favorable to shareholders.
So let’s go back to the lawsuits. It’s true that operating income took a dive because of the write-downs related to Orianna, and the future is uncertain because we don’t know what kind of deal is going to be hammered between the two firms. As we’ve discussed in previous weeks, it could be very ugly or it could be amenable, and we’re expecting the latter as the likelier result. But the real issue is this: the market has priced in the worst possible outcome. You just don’t get 8% dividends that grow a penny per quarter with a 130% or higher dividend coverage ratio every day. Omega Healthcare is one of a handful of such companies. Of course with such metrics there is risk, and that risk has been priced into the stock since The Bull Market Report first recommended it in March of last year. Now, obviously, it’s underpriced, and we expect that the stock will be re-priced early in 2018 when a settlement or agreement is reached between Omega and Orianna.
Omega’s portfolio is composed of 85% senior nursing facilities and 15% senior housing facilities. Omega operates approximately 1,000 properties, which in turn are run by 77 independent operators.
So where does that leave shareholders now? Holding and collecting these well-covered dividends makes sense. Growing more exposure to the stock also makes sense. What doesn’t make sense is freaking out because of these lawsuits, which are quite vaguely worded in and of themselves.
To give a bit of context, note that shareholder lawsuits are a pretty common thing on Wall Street. They sometimes have merit, and sometimes are levied by legal firms who smell an opportunity. Facebook was sued in 2012 after its IPO because of how disastrous its early performance was. look at what Facebook stock has done since then.
In short, it’s unlikely that these lawsuits will come to much. What’s much likelier is that Omega’s mounting pressure to reach a settlement with Orianna is going to result in a faster settlement, which will in turn result in investor relief and a boost to the stock. We don’t expect a massive price spike, but we do expect the stock to come back to an 8-handle on its dividend yield when an announcement is made. After all, the financial picture hasn’t changed and, with the massive price decline of late, there’s little downside priced in and a lot of upside available for investors who understand the risks.
Good Investing,
Todd Shaver, CEO and Founder
The Bull Market Report
Since 1998
November 19, 2017

by Todd Shaver | Nov 19, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
The big story this week was the sale of a Leonardo da Vinci painting for $450 million. Leonardo da Vinci’s Salvator Mundi went to auction Wednesday night at Christie’s in New York and the selling price broke sales records. Watching the top part of the market is an interesting tell. It is noticeable when the luxury art market hits fresh highs. We further note that luxury apartment prices in New York City are down 10% to an average of $8.1 million this month compared to a year ago.
Construction is under way setting new height records of high-rise buildings in cities like Los Angeles and Philadelphia. What does this mean? Things are good, though often new peaks signal a top. We must watch very closely. When the luxury market starts hitting new records, you have to step back and realize trees don’t grow to the sky, and that this bull market is not guaranteed to last forever.
Don't get us wrong. We're still very bullish and expect a strong earnings year in 2018. But it never hurts to be a bit cautious.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks/funds where we think you can still make good money, including: VMware, Annaly, Shopify, Tesla, Nutanix, and Celgene.
BMR Companies & Commentary
VMware (VMW: $123, up 1%)
Singaporean communications company M1 Limited and software and services provider VMware announced a new cloud offering made for digital start-ups, and small-and-medium enterprises. The service will enable budding tech businesses to develop software-based products quickly in addition to growing their business without an expensive infrastructure expenditure.
M1 said it is improving its next-generation software-defined data center, which is powered by the VMware cloud provider program, with shipping support from Pivotal Container Service. The new cloud offering provides advanced technology that allows businesses to run faster and introduce new products quicker.
BMR Take: It is great to see new product development! VMware is expected to produce earnings of $5 per share this year and $6 by 2020. With such a solid market presence and brand, we see additional upside in the stock.

----------------------------------------------------------------
Annaly (NLY: $11.49, up 2%)
CEO & President Kevin Keyes bought 300,000 shares of stock this week in the open market. There is nothing like insider buying to signal a stock is a good buy. Who is Mr. Keyes?
Kevin Keyes serves as President and Chief Executive Officer of Annaly and is a member of the Board of Directors. Prior to joining Annaly in 2009, Mr. Keyes worked for 20 years in senior Investment Banking and Capital Markets roles in the Real Estate and Financial Institution Industries among others. From 2005-2009, Mr. Keyes served in senior management and business origination roles in the Global Capital Markets and Banking Group at Merrill Lynch. Prior to that, he worked at Credit Suisse First Boston from 1997-2005 in various Capital Markets Origination roles and Morgan Stanley from 1990-1997 in the Mergers and Acquisitions Group and Real Estate Investment Banking Group. Mr. Keyes holds a B.A. in Economics and a B.S. in Business Administration from the University of Notre Dame.
BMR Take: Mr. Keyes is a smart businessman. Annaly is currently producing earnings of about $1.20 and pays this out in a dividend yielding over 10%. Follow the smart money here. The company has been successful over 20 years through bull markets and bear. With a market cap of $13 billion, this stock is rock steady.
----------------------------------------------------------------
Shopify (SHOP: $105, up 5%)
Shopify is just not the ‘short’ some of the naysayers say. The best way for the company to prove it and crush the shorts is by building the underlining business. The truth is that while the stock market is a voting-machine in the short-term, over the long-term it is a weighing machine. You build a great business with earnings and the stock goes higher, every time. This is just what Shopify is doing.
Just in time for the holiday season, UPS and Shopify are unveiling a platform integration that make UPS's premium services available to small businesses. Shopify’s hundreds of thousands of small U.S. business customers will now receive competitive, pre-negotiated domestic and international rates that save on list prices, along with a streamlined shipping and fulfillment solution.
By embedding UPS natively into Shopify’s platform, merchants will get the breadth and reliability of UPS’s services to more than 220 countries and territories, while easily managing all aspects of shipping and fulfillment in one place
BMR Take: The consensus outlook calls for Shopify to put up EPS of $0.05 this year, $0.27 next year, $0.75 the following year, and over $2.00 in 2020. Look up “earnings growth” in your financial dictionary. We suspect you might find a picture of Shopify’s logo!
We wonder if Andrew Left knows when to throw in the towel? Remember, Mr. Big Short has to BUY BACK his stock to get out of the positions. MY OH MY we can’t wait to see him get SQUEEZED with this amazing company.
----------------------------------------------------------------
Tesla (TSLA: $315, up 4%)
Tesla made a huge announcement this week. Electric semi-trucks. They go 500+ miles and cost $1.26/mile to operate, and can haul 80,000 pounds. It might even one day drive itself. Companies like Walmart, JB Hunt, and UPS all immediately placed orders. This is going to be huge and change the entire infrastructure of the trucking industry.
Environmentally, the impact is massive. Every truck you move with electricity instead of diesel has an outsize effect on the health of the planet and everything living on it. Eighteen-wheelers are the ultimate force multiplier. This green effect is worth real money to the world.
BMR Take: Yes, Tesla is losing money. Specifically, they will lose almost $9 per share this year. But recall that the list of other companies down this path include Amazon and Netflix. Elon Musk will go down in history as a visionary. Let the man build a better world. There will be surreal profits for shareholders over the course of time.
ANOTHER TAKE ON TESLA
In case you missed it, here are a couple of views of the new Tesla semi-truck. Gorgeous! Unbelievably awesome features!
https://www.tesla.com/semi - Just view and scroll down for a brief video and beautiful photos.
This one is a 9 minute condensation of the 51 minute presentation. It shows all the outrageously wonderful features of the truck.
https://www.youtube.com/watch?v=5n9xafjynJA
And how about the new Roadster that they announced with speeds of just 1.9 seconds for 0 to 60 and 4.2 seconds for 0 to 100. It can handle a quarter-mile in 8.9 seconds. And it’s only $200,000!
(Funny – Porsche announced the new 911 two days before Tesla had this big PR event and said their Porsche was super-fast, going from 0 to 60 in 2.9 seconds. And then Tesla comes out and blows them away!)
This will be the fastest production car ever produced.
Check this out here:
https://techcrunch.com/2017/11/16/tesla-unveils-the-new-roadster
BMR Take: Are these new vehicles going to help the bottom line this year? No. How about next year? No. Is a lot of these new announcements hype until they actually start producing these new vehicles? Yes. But if you believe in Elon Musk it may just make you want to own more stock in this amazing company. We personally believe he will make it work. The losses will be stemmed next year as the Model 3 is delivered (500,000 orders are on the books. At $45,000 each, that’s $22 billion in revenue for just the orders on the books. Can you imagine the new orders they will receive when your best friends get one delivered and they RAVE about it?)
Is this stock an investment for the conservative investor? Not really. But for money that you can afford to lose, some say Tesla could be worth $1000 a share by 2020.
----------------------------------------------------------------
Nutanix (NTNX: $29, up 1%)
This stock is on fire. Let’s review why.
Nutanix closed its fiscal year with a bang recording 62% Q4 revenue growth year over year, exceeding analyst expectations. For the 2017 fiscal year, Nutanix grew revenue 72% from 2016. Other notable highlights from the most recent quarter include a record number of large deals, 75% growth in adoption of the AHV hypervisor product that is the future, and 875+ new customers added. The company guidance for its fiscal 1Q18 was above Wall Street expectations.
Other notable metrics highlighted:
• 96% increase in software-only bookings in fiscal 2017
• Closed the quarter with a strong balance sheet with approximately $350 million in cash and NO debt
• 4th year in a row with a customer satisfaction score of 90+
• Total customers of 7,000+, with enviable repeat purchase metrics of 4.1x for all customers greater than 18 months, and 8.1x for the Global 2000 greater than 18 months
• 404 customers that have purchased greater than $1 million lifetime to date; 39 customers that have purchased greater than $5 million; and 11 customers with greater than $10 million in business lifetime.
BMR Take: Nutanix could be the stock of the next decade. The company could cut marketing expenses and deliver earnings of over $1.00 per share tomorrow versus $0.05 expected by analysts. But why do that when you are adding new customers like mad and generating 50% revenue growth? Invest in the future with this company. One of our favorites.

----------------------------------------------------------------
Celgene (CELG: $104, up 2%)
Scripps Research Institute hopes for a royalty windfall from the potential blockbuster drug, ozanimod. If the new drug achieves blockbuster status, it could generate tens of millions of dollars a year in royalties for Scripps, and provide relief from the ongoing financial challenges facing the nonprofit lab. Scripps won't say how much it stands to receive from sales of this drug, a drug that slows brain atrophy in patients with multiple sclerosis. Scripps discovered the drug, then partnered with Celgene to shepherd the medicine through clinical trials. Celgene expects to begin marketing the drug to multiple sclerosis patients in late 2018.
The drug is expected to generate sales of $4 billion, all but 2% of that would go to Celgene. Dr. Hugh Rosen, a Scripps researcher who's the co-inventor of ozanimod, said the institute's agreement with Celgene calls for royalty payments through 2033.
BMR Take: Don’t lose faith in Celgene. This business is a core part of the Healthcare sector and is not going anywhere. The company will continue to find big opportunities as highlighted above. Celgene is still likely to double revenue and deliver over $12 of earnings by 2020. Look out - this stock can roar back!
----------------------------------------------------------------
----------------------------------------------------------------
Upcoming Economic News
Leading Indicators
Monday, November 20th at 10:30 AM Eastern
Period: October
Consensus: 0.80%
Prior: -0.20%
Existing Home Sales
Tuesday, November 21st at 10:30 AM
Period: October
Consensus: 5,440K
Prior: 5,390K
Durable Orders
Wednesday, November 22nd at 8:30 AM
Period: October
Consensus: 0.30%
Prior: 2.0%
Initial Claims
Thursday, November 23rd at 8:30 AM
Period: 11/18
Consensus: 240,000
Prior: 249,000
----------------------------------------------------------------
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
In the UBS 2018 Market Outlook report we discuss "What worries us the most?" UBS answer: "Inflation - a sudden return that is independent of growth (e.g. persistent oil-price spike,
supply-side bottlenecks) is one worry. We show that, at least in the context of labor-market dynamics, this risk is still reasonably low. The flip side of the same coin reflects the risk of policy "overtightening" despite stale inflation. Low inflation, however, allows policy makers the optionality to reverse course and stabilize markets……"
As we mentioned last week, there seems to be a lack of broad-based inflation with respect to the sizable gains in stock valuations and the rise in earnings growth rates. Yet, UBS believes the markets need to worry for two reasons: first, a sudden surge in inflation without matching earnings growth, and secondly, a lack of inflation accompanied by continued Fed rate hikes. While UBS rates the inflationary risks as low, we believe the bond markets (and yield curves) will help alert the markets to the occurrence of any substantial inflationary problems on the horizon.
Meanwhile, the good news is that UBS believes that the markets still have room to grow in 2018.
With that said, bonds are not signaling "full speed ahead." When President Trump was elected, the yield on the 30-year Treasury bond surged from 2.60% to almost 3.20%. This was probably because the bond market reassessed the likely influence this political shock would mean for the markets.
As a reminder, there were three key pieces to the accelerating economic growth argument: Increased infrastructure spending, deregulation (mainly the repeal of Obamacare), and most importantly, tax reform.
Unfortunately, the once-in-a-lifetime Republican trifecta is 0-3, and right now the 'smart money' in the bond market is not impressed with how things are going in both D.C., and the broader US economy.
The 30-year yield has retraced almost all its post-election move higher and is now only slightly higher than it was pre-election, and the 10-year yield curve has flattened rather than steepened.
Meanwhile, progress on tax reform, the real engine behind the stock rally, has been pretty slow. As we have said numerous times, the market needs tax reform to happen or we can expect a correction. At this moment in time, our best guess on tax reform getting passed isn't any better than a coin flip.
Bottom line, while stocks climb to new highs due to optimism about tax reform and the subsequent improving uptick in growth, the bond market continues to display doubts about the health of the economy and the general outlook for risk assets, both medium and longer term. Maybe that's another wall of worry that the market likes to climb. It is, however, very much worth monitoring.
For now, though, most stock gurus still give the benefit of the doubt to the stock bulls based on momentum alone. Today, the stock market is in the hands of tax reform. But tomorrow, next year, and as it always is for the long-term, it will be in the hands of earnings growth.
----------------------------------------------------------------
PayPal (PYPL: $76, up 3%) Gets a Target Upgrade
Jefferies ups PayPal’s target. After rolling forward their valuations to reflect 2019 estimates, Jefferies raised their price target for PayPal to $86 from $80. The market cap is now $92 billion. Most people have no idea this company is so big. With the stock setting a new all-time high Friday we are going to jump on the band wagon and raise our Target. Wait. They are jumping on OUR band wagon as we added the stock in January of last year at $31, so we are up 145% on the stock. We hereby raise our Price Target to $87.

----------------------------------------------------------------
Square (SQ: $44, up 13%) Gets Some Target Upgrades
What a week for our favorite payments company, Square. Wait a minute – what about PayPal? Ah yes, we love them both. But Square is a pipsqueak compared to PayPal. Just $17 billion (up from $10 billion a few short months ago.) Jefferies raised its target for Square to $47 from $44
The Square price target was raised to $48 from $45 at Nomura Instinet saying the company is "well underway to becoming a major disruptor in the payments ecosystem." After speaking with Sarah Friar, Square's CFO, the company raised its long-term estimates for the company. They see Square's revenue and profits being lifted by its "intuitive and cohesive software ecosystem."

----------------------------------------------------------------
The High Yield Corner
By Michael Foster
After tons of big news stories coming at us hard and fast, it was nice to have a bit of a quiet week with little news relating to The Bull Market Report’s High Yield portfolio. A lot of picks remained flat over the week as a result, such as Nuveen AMT-Free Municipal Credit (NVG: $15.43), Welltower (HCN: $68), and Government Properties Income Trust (GOV: $18.85).
Government Properties’ dull week was a bit of a sea change. We wrote about the intense reaction to the REIT’s slightly disappointing earnings results a few weeks ago, predicting a recovery. We’re now at price levels we saw in mid-October, so it seems that the market has realized its initial shock was overblown. Furthermore, growing stability in the credit market and the realization that REITs are already positioned for next year’s interest rate hikes has also helped this and other REITs stabilize. For instance, Apollo Commercial Real Estate (ARI: $18.41, up 1%) had a healthy albeit somewhat quiet week, and we fully expect the market to slowly pour back into REITs in the coming weeks thanks to a better understanding of the robustness of the balance sheets throughout the sector. This is a good time to sit back and wait for capital gains to continue to roll in.
Of course, there are exceptions to the quiet in REIT-land. Most notably, Omega Healthcare Investors, Inc (OHI: $27, down 3%) continued its protracted sell-off. This was partly to be expected. As we wrote a couple of weeks ago, the market is going to panic about this company’s cash flow in the short run until they realize their mistake in the long run (probably in early 2018 after the company’s next earnings report).
This is a good buying opportunity, and staging into the fund if you have cash on the sidelines would be a great way to secure this stock’s now 9.6% dividend yield. We’re approaching 10% yields - an unthinkable feat, but not impossible. We can’t imagine the market being that horrified about a company that is out-earning its dividend by a large margin. But the market’s short-term irrationality has surprised us before.
Another Healthcare REIT handpicked by The Bull Market Report did a bit better, but still didn’t do great: Ventas (VTR: $64, down 1%) dipped again slightly for a simple and silly reason: contagion. The worries about Omega Healthcare Investors is spreading to other REITs in the sector, because Omega’s problem stems from the fact that skilled nursing facilities (SNFs) are struggling to generate revenue and thus pay their rent. We’ve already discussed how Omega has positioned themselves to weather that storm, so let us discuss Ventas. Long ago, Ventas saw the dangers in the SNF sector and slowly but steadily worked to get out. They did so by diversifying into life science research facilities and medical office buildings. These buildings have a higher rent tolerance threshold, which is good for Ventas.
What we mean is that they can easily push rent hikes over time, because their revenues are significant thanks to growing demand and the deep pockets of the tenants. Universities have big endowments, and doctors have large profit margins from expensive short-term visits from patients. Both put Ventas in a very financially healthy position. In fact, the company’s dividend coverage ratio is 134%, which is above our 130% threshold. This remains a solid hold, and we dismiss the slight downturn this week as noise due to an irrational fear of the SNF market, which affects Ventas less and less over time.
Another REIT with a bit of a bad week was Digital Realty Trust (DLR: $118, down 2%), which has been a fascinating stock to track over the year. Almost all of those losses happened on Friday on little news, but we suspect the sell-off is a result of the continued fear that server space demand is going to decline over time as servers themselves get smaller, which in theory should mean less square footage will be necessary to hold those smaller servers. We discussed this weeks ago when the controversy first came up over a Silicon Valley investor’s vague prognostications, but let us reiterate the most important point: demand for server space is growing at a breakneck pace. All those Millennials uploading selfies to Instagram, sending short videos on Snapchat, and having political debates on Twitter increase the demand for server space. So we are not worried in the slightest.
We’ve also seen a growing trend in social media away from deleting previous data to lower storage space. Instead, these companies realize that more data gives them advantages they cannot ignore. Hence more demand for server space. Can this growth outstrip the technological advancements that make servers smaller? So far it has, and there’s no semiconductor or other tech development lately to suggest this trend will end anytime soon. For that reason, Digital Realty is a great buy on weakness, although we want to see dividend hikes increase radically next year.
Finally, let’s discuss AstraZeneca (AZN: $33, up 2%). A ton of news has hit the company since it beat revenue and earnings expectations on November 9th. This week, the FDA approved expanded use of the company’s new breast cancer medicine Faslodex and approved its asthma medicine Benralizumab. The company is also presenting to medical experts on clinical trials for its cancer drugs at a conference in Singapore this weekend. Little news has come out about those presentations so far, but if they are strong enough we could see the market react on today, Monday. Holding this stock remains advisable considering its tremendous and improving track record when it comes to research and development. We’re already sitting on 23% price gains in the last year. More is likely to come.
Good Investing,
Todd Shaver, CEO, Founder and Editor
The Bull Market Report
Since 1998
November 12, 2017
by Todd Shaver | Nov 12, 2017 | Weekly Newsletter 7pm Sunday
[Note that the formatting is not up to our normal layout. We are having some editing issues. Next week should be better.]
The Weekly Summary
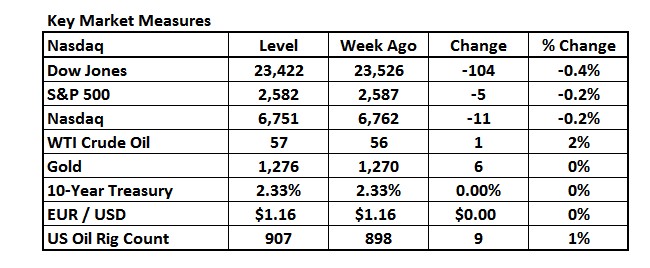
The big story right now remains central banks. The reversal of easy central bank monetary policies across the globe has begun to reverse. Quantitative easing had a meaningful favorable impact to asset prices to the upside. The removal of this stimulus will work in reverse. Accordingly, investors should be prepared for more volatility in the months ahead. Major central banks say they want to normalize monetary policy, which suggests higher interest rates and the eventual end of nearly a decade of quantitative easing. As widely expected, the US Federal Reserve said in September that it would begin the multiyear process of reducing its $4.5 trillion portfolio of US Treasury and mortgage-backed bonds. But it also confirmed that another interest-rate hike is likely in December and we could see three more hikes in each of 2018 and 2019. By this time next year, investors will be staring at a completely different market environment.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks and one not so favorite including: First Solar, Opko Health, Apple, CBRE Group, Twilio, and Andeavor.
BMR Companies & Commentary
First Solar (FSLR: $62, up 3%)
First Solar designs and manufactures solar modules using a proprietary thin film semiconductor technology that is one of the lowest cost in the world. The firm’s objective is to reduce the cost of solar electricity to levels that compete on a non-subsidized basis with the price of retail electricity in key markets throughout the world. What a lofty goal and an exciting opportunity!
What is the most recent progress to report? First Solar has confirmed that PlantPredict, the company’s solar photovoltaic energy prediction software, has been used to generate the reference energy predictions in the sale of three utility-scale projects totaling more than 350 MW.
PlantPredict is a sophisticated solar energy modeling tool designed to develop energy estimates for utility-scale solar PV installations. Easy to use with advanced modeling options, PlantPredict reduces uncertainty to generate more accurate energy predictions. More than 500 companies have already used PlantPredict to model energy predictions for their solar sites.
The transactions demonstrate that the cloud-based modeling tool has gained acceptance by lenders and asset owners as a bankable primary resource in analyzing and predicting performance of utility-scale solar projects.
This is a lot of jargon. What it means is that there remains big demand out there for solar.
BMR Take: First Solar is doing $3 billion in sales and $2 of EPS right now. Looking down the road, we think there is plenty of room in the overall market opportunity for sales and EPS to double. Now that is the kind of growth we love to find.
----------------------------------------------
Opko Health (OPK: $5.50, down 16%)
Opko took an unfortunate nose dive on its earnings report this week. Revenue of $264 million badly missed the consensus for $319 million and was down from $298 million a year ago. OPKNet loss was $46 million compared to a loss of $15 million for the comparable 2016 period.
What the heck happened?
Rayaldee commercial activities continued to progress, but just not as much as expected. Total prescriptions for Rayaldee, as reported by IMS, increased 66% during the three months ended September 30th compared to the three months ended June 30th. Opko expanded its sales force from 35 to 71 as of October 1st. The commercial and medical science liaison teams now total more than 80 professionals.
BMR Take: Many are saying to be patient; that Rayaldee still has big time long term potential and this is just one of multiple opportunities in front of Opko; that revenue is forecast to double from $1.0 billion to $2.0 billion by 2020. Some say that if we see this top line growth, profitability is going to come quickly, and when that happens, the stock is off to the races.
Well, we say hogwash. We are VERY DISAPPOINTED in this company. They have one of the biggest hype machines out there and we have fallen for it. We have waited and waited, being very patient, as the stock goes down down and down.
Look, if you wish to stay in an wait another year, more power to you and I hope the company crushes from here and the stock goes to $15.
But we are OUT. We added the stock 14 months ago at $10 and exit Monday at $5.50. Not happy about this one.
----------------------------------------------
Apple (AAPL: $175, up 2%)
Augmented reality (AR) is a big theme in the markets. The technology is going to shake things up. This means some people are going to make money and some people are going to lose money. Apple is on the right side of the trend.
Apple is working on a augmented reality display. In the company’s most recent financial results conference call, Apple CEO Tim Cook once again made it clear that AR is at the top of his agenda, saying it will “change the way we use technology forever.”
Of the new iPhones and a new version of iOS just released, all boast augmented reality as a selling point. Apple says the A11 Bionic chip inside both the iPhone X and the iPhone 8 series is specifically designed for AR.
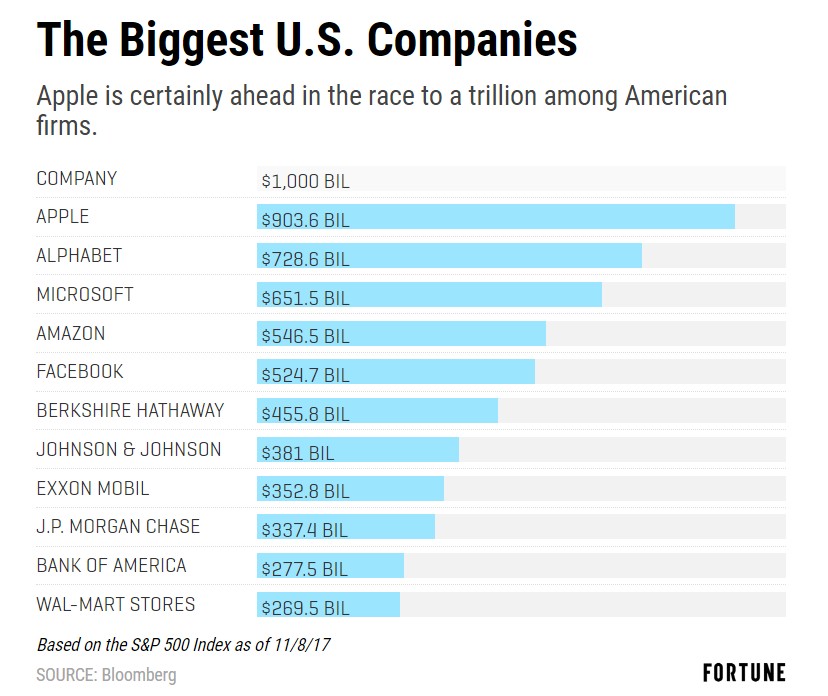
At least 13 brokerages raised their price targets on the stock, with Citigroup making the most bullish move by raising its price target by $30 to $200.Of the 37 analysts that track the stock, 31 had a “buy”, or higher rating. None had a “sell”. With the latest brokerage actions, at least nine Wall Street analysts now have target prices that put Apple’s market value above $1 trillion. Drexel Hamilton is still the most bullish raising their target price further to $235.
Apple has 5.17 billion shares outstanding and could reach the $1 trillion-dollar market cap level if its shares rose to $194.
Apple is already the largest market cap stock in the S&P 500 and made up 4.5% of the index's market cap as of Friday's close. If Apple's market cap rose to $1 trillion, the stock would be 4.75% of the S&P 500's market cap, ranking Apple ninth when looking at the stocks with the largest percentage of the S&P's market cap at year-end since 1980. IBM holds the top four spots with AT&T taking the next two and Exxon and Microsoft (in 1999) rounding out the top eight.
If Apple's stock can reach the $1 trillion market cap some on Wall Street say that it validates the belief that Apple is not just a smartphone business but a platform.
BMR Take: Apple did $9.21 of EPS this year and estimates call for greater than $11 next year. AR technology is the future and Apple’s ability to participate supports EPS growth continuing on like we are seeing now for a long time ahead. Apple set a new all-time high last week and since the stock has passed our Target of $170, we hereby raise our target to the level to which the market cap will reach $1 trillion. That number is $194. Our Sell Price remains: “We would not sell Apple.”
CBRE Group (CBG: $41.50, up 4%)
Never higher. CBRE has never been higher. CBRE is arguably the leading real estate company on the planet. As a highlight of how locked in the company is, look at CBRE Research’s 2017 Tech-30 report that was just published where they demonstrated exceptional expertise. The company ranked the strength of tech job growth across 30 North American office markets, which is creating stability and demand-driven performance through occupancy gains and rent premiums. Four key points are highlighted below.
--- Tech jobs grew four times faster than the national average. San Francisco was the top high-tech job growth market for the sixth year in a row.
--- Eighteen markets added more tech jobs over the past two years than the prior two-year period.
--- Tech’s share of major leasing activity has nearly doubled to 19% over the past five years, resulting in strong occupancy and net absorption gains.
--- Desirable tech submarkets are priced at a premium, while emerging submarkets often offer discounts. The overall average asking rent of tech submarkets is priced at a 16% premium.
BMR Take: We are staring at the company’s EPS power closing in on $3. This stock remains a compelling value at the current level. We don’t see the company doing anything but maintaining and growing its leading market share for the foreseeable future.
----------------------------------------------
Twilio (TWLO: $25.50, down 15%) on Earnings Report
Revenue reported was strong, and you know how we feel about revenue. We will tell you what happened, and let’s stay focused on the long term.
The company lost $0.08 versus $0.04 a year ago. Revenue was $101 million versus $72 million a year ago. The good news is that revenue beat the consensus of $93 million. Moreover, the company guided to a better outlook for the remainder of the year.
So what the happened here? Uber.
While total revenue growth of 41% was strong, we believe it is important to look at the underlying growth of Twilio’s core business. In particular, we consider base revenue excluding Uber, which came in at $87 million, up 63% from a year ago. Revenue from Uber hit $14 million in 4Q16 and came in at $5 million in 3Q17, down 53% y/y. Management expects a modest sequential decline in Uber revenue in 4Q17. The loss of Uber business continues to weigh on results.
Total revenue rose to $100 million from $71 million. Management itself had called for a net loss of $0.08 per share on sales near $92 million. The adjusted loss was right in line with that forecast, but Twilio crushed its own sales expectations.
For the upcoming quarter, Twilio expects an adjusted loss per share of 6 cents and revenue of $103 million. Analysts are predicting an adjusted loss per share of 6 cents and revenue of $99 million.
Jeff Lawson, Twilio’s Co-Founder and Chief Executive Officer said, “We hit a number of exciting milestones in Q3, including our first $100 million revenue quarter, our first enterprise license agreement for our higher level software products, and the launch of Twilio Studio. With Twilio Studio, the visual builder for Twilio, we can accelerate our customers’ roadmaps and help an even larger set of users build on our platform. We are excited by the size, scale and diversity of what new and existing customers are creating with Twilio.”
Recent Business Highlights – released by the company:
46,500 Active Customer Accounts compared to 34,400 a year ago. Twilio Studio was introduced in the third quarter, giving clients a simple drag-and-drop tool to simplify and accelerate their production efforts. Twilio already offers separate production tools for popular platforms such as Android and iOS, but the new Studio streamlines the development process in ways that had not been available before.
Announced our commitment to meet the new GDPR (General Data Protection Regulation) requirements coming from the EU, using this as an opportunity to raise the bar for data protection worldwide for all of our customers.
Expanded the reach of our Super Network by announcing the availability of Twilio phone numbers in more than 100 countries.
Average revenue per user rose 18% to $8,000.
Cash position strong: Twilio held $284 million of cash equivalents at the end of the third quarter, down from $289 million in the second quarter and $306 million by the end of fiscal year 2016.
Guidance: – released by the company:
Full year ending December 31, 2017:
Total Revenue - $387 million
Loss from operations (millions) $22.0 to $23.0
Net loss per share - 0.22 to 0.23
BMR Take: The good news is Twilio continues to innovate and add net new customers at a remarkable clip (3,100 in 3Q17), which is driving strong underlying revenue growth. The company remains one of the fastest top line growers in all of cloud computing.
This company is one the most frustrating that we follow. With another stellar report like we describe above, any normal stock would be up 10%. Not Twilio. Down 15%, now well below our Sell Price of $29. We are going to stay the course but you might get tired of waiting and sell in order to redeploy these assets into something better like Nutanix or Square. With that said, we believe Twilio should be a $50 stock, a long way from where it is today. But again, top line growth will win in the end. Do you and we have enough patience to endure these losses? That is the ultimate question.
----------------------------------------------
Andeavor (ANDV: $107, down 3%)
Could oil breech $80 before Christmas? Some options traders think so. With oil trading near its highest level in two years, some traders are betting that the price rise could have more room to run.
A total of 48,000 option contracts traded over the last few days that would profit most if crude spikes before Christmas, including several large individual trades. They all expire on Dec. 21.
Oil prices have rallied in recent weeks as OPEC supply cuts help to rebalance an oil market plagued by oversupply. More recently, growing tensions between Saudi Arabia, OPEC’s largest oil producer, and some of its neighbors helped prices break above $60 a barrel for the first time since 2015.
Andeavor Reported Third Quarter 2017 Results on November 8th.
Earnings of $550 million, or $3.50 per share; results included the following pre-tax items
Returned $345 million to shareholders including $252 million in share repurchases; they expect to repurchase $300 million of shares in 4Q17
Total retail and branded stations up 27% year-over-year to over 3,100 stores
On October 30th, Andeavor closed its $1.7 billion acquisition of Western Refining Logistics
New totals for Andeavor
Number of Refineries: 10
Refining Capacity: 1.2 million bpd
Employee Count: More than 13,000
Retail Sites: More than 3,100
Barrels of Storage Capacity: More than 46 million
Miles of Pipelines: More than 5,300
Marine, Rail and Storage Terminals: 40
Natural Gas Processing Complexes: 6
States where they operate: 18
BMR Take: Higher oil prices above $80 could be a huge positive for many companies including our beloved refiner Andeavor. Recall, Andeavor’s net asset value is $120 and the stock still trades an unwarranted discount. We think more stable energy markets are the first step needed for good sentiment to return to the oil patch stocks like Andeavor. And we’re certainly on the way with crude being so strong of late.
----------------------------------------------
Upcoming Economic News
PPI ex-Food & Energy
Tuesday, November 14th, 8:30 AM Eastern
Period: October
Consensus: 2.2%Prior: 2.2%
Retail Sales ex-Auto Wednesday, November 15th, 8:30 AM
Period: October
Consensus: 0.20%
Prior: 1.0%
Initial Claims
Thursday, November 16th, 8:30 AM
Period: 11/11
Consensus: 235,000
Prior: 239,000
Housing Starts
Friday, November 17th, 8:30 AM
Period: October
Consensus: 1,193,000
Prior: 1,127,000
----------------------------------------------
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
The markets seem to be firing on all cylinders. Is there anything that could derail it before year-end? About all we can see is the Russian investigation (none and no chance), the tax-cut drama (possibly, but more likely to cause a correction rather than a derailment), a government shutdown (slim if any chance at all) or a major Fed rate hike (little to no chance).
A couple of things have caught our attention, however. What usually derails a bull market is a recession. At this point, we don't see the usual suspects that signal a coming recession, such as widening credit spreads, deteriorating market internals, collapsing commodity prices, falling new orders or falling earnings. In fact, it is just the opposite.
However, two things are not making sense from a historical perspective. First, with near full employment and accelerating worldwide growth, inflation remains stubbornly low. This is usually not the case. Inflation signals rising prices and continued rising earnings. It should be readily apparent but it simply isn't expressing itself even at this stage of the earnings growth cycle.
Secondly, if there is one warning signal for an approaching recession that is more reliable than all the others, it might be an inverted yield curve. Since January, the spread between the 10-year Treasury and the 2-year Treasury has fallen from about 1.30% to 0.75%. In our experience, whenever we have seen accelerating revenue growth, rising earnings, potential tax cuts – i.e. so many positives – the yield curve should be steepening, not flattening. Maybe we are experiencing a "new norm" in the markets, or it "is different this time" (the four most dangerous words in our industry), or this is going to be normal as part of the 4th Industrial Revolution we have supposedly entered (artificial intelligence, augmented reality etc.). In any event, we are going to closely follow the lack of inflation and the yield curve because neither is "confirming" this bull market rally as each would normally do if one looks back at the history of the market.
----------------------------------------------
Square (SQ: $39, up 6%) Continues to Shine
A few Wall Street firms had some new announcements on Square this week. The target raised to $38 from $34 at Stephens. They believe the stock "can grind higher" following the company's Q3 report. They still sees Square as likely to change the game for Small and Mid-sized business payments and thinks the likelihood of it achieving true "platform for small business" status gets more likely every quarter.
Square price target raised to $33 from $23 at Craig-Hallum
Square price target raised to $35 from $24 at SunTrust. SunTrust said that it is entering a period requiring heavier investment which will weigh on margin expansion. They said that Square trades at a significant premium of about 60-times FY18 EBITDA relative to 13-times for its peer group.
GoDaddy (GDDY: $48) announced two new integrations with Square that help small businesses thrive with online and offline selling and payment capabilities. By collaborating with Square, GoDaddy is making this an easy reality for tens of millions of people building small businesses. Integrating GoCentral Online Store and Square online payments enables small businesses to easily sell their products and services online and in person through a single Square account and GoDaddy website. The second integration provides service-based businesses, such as personal trainers, hair stylists and photographers, the ability to book client appointments online, sync calendars using GoCentral, and get paid using Square. Payment transactions can be processed online, in-person or both without switching accounts.
Square target raised to $41 from $31 at Cantor Fitzgerald citing accelerating revenue growth. The firm expects Square's "rapid growth" to continue and further margin expansion going forward. He notes that Gross Payment Volume growth remained above 30% in the quarter.
Square target raised to $41 from $31 at RBC Capital. The firm says the Q3 beat and raise for 2017 outlook is indicative of the company's ability to drive its products into existing partners and expanding to larger merchants.
BMR Take: This one has a long way to go on the upside.
----------------------------------------------
Options Corner – All about Square
From time to time we like to bring you an interesting options trade. We like to do long-term bullish trades on stocks, unless we find one that is going to go bankrupt in which case we can design a trade to profit from the demise of a firm using puts.
Square has been knocking the cover off of the ball of late. We added the stock at $17 in March of this year and it is now $39, setting a new all-time high on Friday, so we are up 130% in 8 months, giving us an annualized return of ……. Well, you get the point! A great stock pick. A great stock. Better yet: A great company. With a market cap of $15 billion now, it is moving into the big leagues. We have said quite a few times that Square would be a great buyout candidate for one of the big boys (Amazon, Microsoft, Apple, etc.) but they better move fast before the stock hits $20 billion.
And in fact, we think a $20 billion valuation is quite possible next year. That would equate to a $52 stock. Can that happen here with Square? We certainly think so.
An options trade can produce much bigger returns than this 33% increase, if it were to happen. But guess what? OPTIONS ARE RISKY! Please repeat after us. Options are very risky.
OK. Let’s get started.
We love long term options called LEAPS. They expire in January as long as they have at least six months of life. So the January 2018 options aren’t called LEAPs any more. But the Jan 2019 options are. And soon we should see the Jan 2020 options start trading. We can’t wait.
We like to buy options that are in the money. With the stock at $39, the 35s are $4 in the money. Better yet the 30s are $9 in the money. They are worth $9 but they trade for $13. Why is that? The $4 is the TIME PREMIUM. And note that that time premium will go to zero eventually as it approaches the end of its life in January 2019.
In order to pay for the time premium we like to SELL calls against the long LEAP to recoup this time premium and also to help us get our cost down on the option that we bought. Let’s look at some real numbers.
Buy the Jan 2019 30 LEAPs for $13,Sell the June 45 call for a little less than $6.
The cost of this trade is now $7 for an option WORTH $9. Do you understand this? If not, go back to the top of this article and re-read. These options discussions are confusing the first time, but It WILL come to you if you re-read this 3-4 times. We are serious.
Now, let’s say the stock goes up a bit and is selling at $45 in June. Your June option is going to expire worthless (great) and now you SELL a January 2019 call, say the 50 call, for approximately $7. (We are not sure of these numbers because it is so far into the future but we think this is about right -- we hope you get the point.) The cost of the trade is now zero. You are in this trade for zero dollars. (Gosh, we love this trade!)
Now, let’s tally up. If the stock goes to $50 or higher by January 2019, you will be left with an option worth $20 ($50-$30). If you had bought 10 options for $7,000, they are now worth $20,000, almost a triple (185%), with a stock that went from $39 to $50 or 28%. If you had put $25,000 in this trade (the equivalent of buying 640 shares of Square) you would now have $75,000 and that’s real money.
This options trade will more than likely take lots of tweaking of your position and the return could be better or worse depending on where the stock goes. No one is going to hand you a triple without a little bit of work. But it could be a super trade IF the stock heads to $50.
The downside is that the stock goes down to $30. You will lose money but if you religiously sell calls against your position, you can get your cost down to close to zero, thus minimizing your losses.
Note that if this all-options trade is too risky or confusing to you, you can just do a normal covered call trade by buying the stock and selling calls against it. If you were to buy 1000 shares at $39 for $39,000 and the sell the calls as described above, you would bring in $6000 for the June $45 call and $7000 for the January $50 call giving you a purchase price of $26,000. If the stock goes to $50 you have a $50,000 position, and a return of 92%. Not bad.
But, again, lots of “ifs” in these scenarios. Invest with caution.
----------------------------------------------
The High Yield Corner
By Michael Foster
Last week, AstraZeneca PLC (AZN: $33, down 5%) reported strong revenue and earnings above expectations, but that wasn’t enough to keep the stock from being the biggest loser of the week for the Bull Market Report’s high yield portfolio. A deeper dive into the results can explain what happened—and why this isn’t really a cause for concern.
To start with: revenues rose 9.3% on a year-over-year basis in the third quarter to $6.23 billion with solid EPS of $0.54, which was a little shy of expectations: analysts were expecting just 55 cents per share in earnings. In their press release, the company highlighted weak sales in the U.S. as a cause of the weaker earnings, while also pointing out that weakness was offset by major growth elsewhere: emerging markets were up 5%, China was up 12%, and Japan was up 3%. Those numbers were all higher on a constant currency basis.
But the U.S. weakness is a large part of the stock decline. AstraZeneca pointed to continued weakness in Symbicort as a cause for the weakness; the asthma drug’s challenges have been a major issue for this company, which analysts see as being heavily reliant on for future sales. Nonetheless, a closer look at the drug pipeline indicates there are other sources of growth to come.
More specifically, AstraZeneca highlighted that Lynparza, a breast cancer drug, has received priority reviews in America and Japan, while Imfinzi, a lung cancer drug, has received the same in America while also getting regulatory acceptance in the EU and Japan. A total of 7 drugs got new regulatory approvals as of the end of the reporting period, including two type-2 diabetes drugs that will obviously have tremendous appeal for this widespread ailment.
So the company’s pipeline looks fine. The focus on Symbicort unquestionably overlooks that fact, and provides a buying opportunity at this current price—provided the pipeline remains healthy.
Elsewhere in high yield investing, we saw a really mixed week despite the market’s weakness towards the end of the week. This is pretty unusual—high yield tends to be more volatile in REITs, high yield bonds, and BDCs, but we didn’t see that happen yet. That could mean more aggressive selling is yet to come in late 2017, especially as tax-loss harvesting becomes more commonplace, but that doesn’t change the fundamental strength and attractiveness of many high yield assets.
There are exceptions, however. Municipal bonds were relatively untouched by last week’s jitters, possibly as risk-averse investors were adding to municipal allocations as a result of what they saw in the stock market. Invesco Municipal Trust (VKQ: $12.34, flat) saw little movement on strong volume while Nuveen AMT-Free Municipal Credit (NVG: $15.36, up 1%) gained slightly. Both remain high-quality municipal bond funds with above-average yields and excellent management teams. Neither looks significantly overpriced right now.
Bigger news came from the REIT world, but the news had little effect. Welltower (HCN: $68, up 2.5%) had strong earnings, with FFO per share of $1.08 a 2 cent jump from the prior quarter and NOI up 4.1% on same-store senior housing operations. RevPAR also gained by 3.9%, which helped the company’s revenue rise nearly 1% to $1.1 billion for the quarter. FFO was a 3 cent beat over expectations, and higher earnings guidance (the company now expects normalized FFO per share of $4.19 to $4.25 for the full year) make Welltower’s valuations even more attractive, especially after the stock price remained stuck for the week. Defying negativity in the skilled nursing facility world, Welltower’s massive size and market penetration are proving stores of value and investor safety; the stock is a better buy now than it’s been for most of this year.
*Revenue per available room
That’s it for earnings news this week, but a lack of major news didn’t stop Government Properties Income Trust (GOV: $18.76, up 2%) from having a strong week, thanks in small part to the continued recovery from last month’s anxiety that the company’s earnings results at the end of October proved to be a paranoid non-issue. However, protracted worries about Omega Healthcare Investors, Inc (OHI: $28, down 1%) and their very disappointing earnings are keeping shares down and the yield up at the 9% level. That more than compensates for the risks, which makes this a very appealing option for investors who accept that the dividend growth is likely going to end in 3-5 years’ time. The market is discounting a cut to dividend growth much sooner, making this an irrational price and a good bargain right now.
Elsewhere, we are seeing growing anxiety in Collateralized loan obligations (CLO) and high yield corporate bonds, but that hasn’t stopped AllianzGI Equity & Convertible (NIE: $21, unch.) and PIMCO Dynamic Income Fund (PDI: $30, up 1%) from proving resilient. That’s in no small part thanks to the high-quality management teams of each, which have wisely avoided the more exotic high-yielding CLO markets and shifted towards much safer MBS’s and away from the riskiest junk bonds. The market is rewarding both with price stability. That may not last - after all, irrational selling is still very much a thing in modern markets - but that just means a buying opportunity will open up. Neither fund shows any indication of weakness despite the broader worries growing in the credit sectors.
Good Investing,
Todd Shaver, Founder and CEO
The Bull Market Report
Since 1998
(Again, sorry about the crazy formatting this week.)
November 5, 2017

by Todd Shaver | Nov 5, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
US equities ended higher this week, again! Major indexes ended at their best levels in history. Economic data, earnings, M&A and the recently released House tax plan grabbed most of the attention. Tech and Healthcare were the best performing sectors. There was lots of focus on the recently released House tax plan. As expected, backlash has heated up quickly, particularly when it comes to who get the benefits of new incentives between the super-rich and the middle class. The tax bill is not expected to survive in current form and some focus is already shifting to the Senate’s revisions.
In terms of other developments surrounding Washington, Trump said "We'll see" if Secretary of State Tillerson makes it through his term. Jay Powell was named by President Donald Trump as his nominee to serve as the next chair of the Federal Reserve, as he moved to make his mark on the world’s most powerful central bank. The news ends months of speculation ahead of the end of Janet Yellen’s first term as chair in February. The 64-year-old Mr. Powell has been a serving Fed governor since 2012. A centrist on monetary policy, he is known as a pragmatic and down-to-earth official with private sector and government experience. A trained lawyer and former partner at private equity firm Carlyle Group, he also served in the Treasury under former president George H. W. Bush in the 1990s. Powell is worth upwards of $50 million.
Consumer Confidence hit a 17 year high. Are you confident in this bull market? Good. We are too. And again, if you want to cash in some chips and buy some REITs and some high-yield stocks, we have two fabulous portfolios loaded with stocks that are paying 4%, 6%, 8% and 10%. But we are sticking with our Tech stocks, especially FAAMG stocks – Facebook, Apple, Amazon, Microsoft and Google. Their combined market cap is $3.3 trillion. We’re looking for $4 trillion next year. With Apple at $890 billion now, we could see them be the first trillion dollar company in history. (That price would be around $194 – not too far away.)
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks where we know you can still make good money, including: Facebook, Microsoft, Home Depot, CBRE Group, Tesla, and Apple.
BMR Companies & Commentary
Facebook (FB: $179, up 0.5% - all % changes are for the week)
Facebook reported revenue of $10.3 billion compared to just $7.0 billion last year. EPS was $1.59 versus $1.09 last year. Revenue beat expectations by nearly 5% and EPS was a big $0.31 ahead of the consensus.
Wow.
“Our community continues to grow and our business is doing well," said Mark Zuckerberg, Facebook founder and CEO. "But none of that matters if our services are used in ways that don't bring people closer together. We're serious about preventing abuse on our platforms. We're investing so much in security that it will impact our profitability. Protecting our community is more important than maximizing our profits."
The majority of analysts were bullish on the report. Facebook continues to grow at an impressive rate with strong profitability as gross margin was way better than expected. User engagement continues to increase and is helping drive demand and in turn pricing. One of the more negative data points brought up was how duplicate accounts now compromise 10% of global monthly active users, but nonetheless both monthly and daily active users came in slightly ahead of consensus expectations.
BMR Take: Facebook remains the greatest advertising machine the world has ever known. With consensus EPS forecasts of $5.80 this year heading to $10.00 by 2020, this stock remains a compelling value.

A 1-year Chart for Facebook
+++++++++++++++++++++++++++++++++++++++++++++++++++
Microsoft (MSFT: $84, flat)
We love to see marquee deals and partnerships. They are symbolic signs of a vibrant business.
Microsoft and United Technologies (UTX: $121 - $97 billion market cap), a major industrial company, on Wednesday announced a strategic agreement that will create a differentiated customer and employee experience using intelligent technology innovation.
United Technologies builds and services millions of products in the field, from elevators in some of the world's tallest buildings, to engines and aerospace equipment in the skies, to commercial products that power smart buildings. Leveraging Microsoft Dynamics 365 and Azure, United Technologies intends to empower employees globally with the digital tools and information needed to support customer interactions for faster, better and more personalized service.
"United Technologies is a global leader in the aerospace and building industries and has a deep commitment to innovation," said the executive vice president, Worldwide Commercial Business, Microsoft. "The combination of United Technologies’ customer service expertise together with Microsoft's intelligent cloud will provide a digital business model for United Technologies businesses across multiple industries."
BMR Take: One of the reasons we see so much upside ahead for Microsoft is the breadth of their customer base that includes so much of the Fortune 500. This deal with United Technologies is just a reminder that Microsoft can sell the right product into this customer base with ease. Recall that earnings expectations were recently reset much higher by most analysts, calling for upward of $5.00 of EPS, which supports this stock heading much higher.

A 1-year chart for Microsoft
+++++++++++++++++++++++++++++++++++++++++++++++++++
The Home Depot (HD: $164, down 2%)
Don’t fret about Home Depot being down a bit this week. There was some chat that concerns about e-commerce have driven down the valuations of some retailers, and that short interest in the six largest brick-and-mortar retailers is currently higher than the levels hit in 2008 during the throes of the economic downturn. This impacted Home Depot’s stock this week.
There was also chat about how management teams at a number of beaten-up retailers are buying back shares, and that the economy should keep consumers shopping during the holiday season. So the world is not coming to end this year.
In other news, while online competition may be pressuring some retailers to hire fewer seasonal workers this holiday season, staffing firms suggest the problem is deeper, with prospective employees seeking more flexibility with their schedules, training, and pay. This could cause some more ongoing headline news that negatively impacts Home Depot.
BMR Take: Home Depot is a bellwether of industry. In such cases, these types of stocks are more susceptible to the large macroeconomic factors as opposed to company specific fundamentals. Stay focused on the latter. Home Depot is due to report EPS of $7.25+ this year heading to around $10.00 by 2020. Earnings power ultimately drives stock prices and we expect that to happen here. Can you believe this company is worth almost $200 billion? $170 a share will do it!

A 1-year chart for Home Depot
+++++++++++++++++++++++++++++++++++++++++++++++++++
CBRE Group (CBG: $40, up 1%)
CBRE reported revenue of $3.6 billion versus $3.2 billion last year. EPS was $0.64 versus $0.50 a year ago. Revenue was about $100 million above the consensus estimate. EPS beat expectations by $0.07. The strength in the quarter was expected to be maintained as the company raised its full year EPS guidance up by $0.05. Awesome quarter!
The strength of performance in Q3 was broad-based. Each of the company’s three global regions produced solid organic growth. Leasing returned to double-digit growth, and was especially strong in the U.S. Revenue growth accelerated in outsourcing business, as the company continue to capitalize on its commanding position in this growing sector. Global property sales saw healthy growth, despite a generally tepid market for transaction activity, reflecting the strength of the company’s brand and ability to take market share. Finally, the business also delivered excellent performance across all of their real estate investment businesses.
BMR Take: With the business closing in on $3 of EPS, we think the current stock price undervalues this leading franchise. CBRE is the ‘Mercedes Benz’ of the real estate world. Own this one for the long-haul!
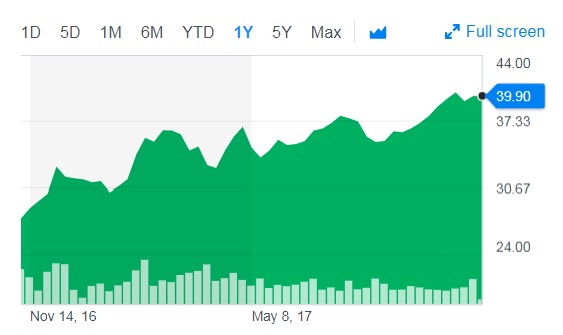
1-year chart for CBRE
+++++++++++++++++++++++++++++++++++++++++++++++++++
Tesla (TSLA: $306, down 5%)
Tesla reported revenue of $3.0 billion versus $2.3 billion a year ago. EPS was -$2.92 versus +$0.71 a year ago. Revenue barely beat expectations but earnings were much worse than expected. Ouch!
Tesla is one of the most closely watched tech companies in the world, where its zero-emissions vehicles resonate with environmental sensibilities. But with that scrutiny has come a great deal of criticism over labor issues in its plant, along with customer complaints about materials and workmanship, and frequent production delays with all of its vehicles.
Analysts were quick to jump on the per-share losses and problems getting the entry-level Model 3 sedan to market. Though Tesla is promising more Model 3 production in 2018, 2017 has been a miss to this point in terms of model production. Of note is Tesla pointing to difficulties in producing the battery packs at the Gigafactory for the vehicle. On a brighter note, Model S and Model X demand still seems to be doing well, but the fact remains that Tesla is still burning cash and needs to right the ship with Model 3 in order to succeed.
BMR Take: Tesla is set to lose over $3 per share this year. But the 2020 consensus forecast is for great than $11. Somewhere here we expect a major swing to profitability. With a brand that stands for innovation, we can see Tesla emerging to become a cherished stock once the profits start rolling in. Speculative? You bet. But we love that buy Musk.
+++++++++++++++++++++++++++++++++++++++++++++++++++
Apple (AAPL: $173, up 6%)
Apple delivered $53 billion of revenue versus $47 billion a year ago. EPS was $2.07 versus $1.67 a year ago. It was a really good quarter for Apple.
In a quarter which many thought would be more subpar due to delayed shipments of the iPhone X and due to many reports indicating weaker than expected sales of the iPhone 8, Apple delivered results that were much better than expected, and it is guiding for a generally strong next quarter as well.
iPhone sales of 47 million grew by 3% from a year ago and were slightly above consensus of 46 million. We saw strong and accelerating growth in services (up 24% from last year). Apple’s Services revenue of $8.5 billion is heading towards $50 billion annually. We observed good growth in China and strong growth in emerging markets (with India more than doubling). iPhone X is about to ramp in sales helping the average selling price. The iPhone X, with a price of $999 to $1,149 (vs. Apple’s blended price of $618 last quarter) becomes available this week, and we expect iPhone average selling price to increase to over $700. We could go on and on.
BMR Take: We reiterate our strong enthusiasm for Apple that we had before the quarter now that the results are in. EPS was $9.20+ this year and heading to greater than $11 next year. With cash and equivalents now totaling $270 billion, wow, this company remains as solid as a rock!
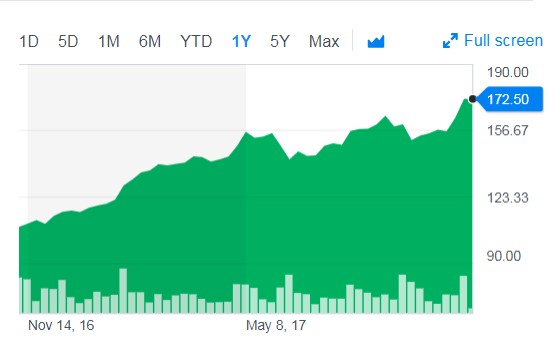
1-year Chart for Apple
+++++++++++++++++++++++++++++++++++++++++++++++++++
+++++++++++++++++++++++++++++++++++++++++++++++++++
Upcoming Economic News
JOLTS Job Openings
Tuesday, November 7th, 10:00 AM, Eastern
Period: September
Consensus: 6,082,000
Prior: 6,082,000
Initial Claims
Thursday, November 9th, 8:30 AM
Period: Week of 11/4
Consensus: 230,000
Prior: 229,000
Michigan Sentiment (Preliminary)
Friday, November 10th, 10:00 AM
Period: October
Consensus: 100.2
Prior: 100.7
+++++++++++++++++++++++++++++++++++++++++++++++++++
Eli Lilly ($87, flat)
Solidity Personified
If you want solidity and stability you can get it here. Eli Lilly and Company was founded in 1876 and is headquartered in Indianapolis. The company is worth $87 billion, pays a 2.5% dividend and has moved from $20 in 2008 to its current level, in a pretty straight line. Revenues are solid too. Revenues had a nice bump from the $20 billion in 2015 to the 2016 total of $21.2 billion. This year looks like $23 billion is in the bag. Slow and steady. And profitable. $2.7 billion ($3.00 a share) to the bottom line after taxes in 2016 up from $2.4 billion in 2015. Not counting some non-recurring charges this year, the company should hit north of $4 billion before tax and about the same as last year in 2017. Solid.
The company is in two primary areas of pharmaceuticals: Human Pharmaceutical Products and Animal Health Products. The company offers products to treat diabetes; osteoporosis in postmenopausal women and men; human growth hormone deficiency; and testosterone deficiency. It also provides neuroscience products for the treatment of depressive disorders, diabetic peripheral neuropathic pain, anxiety disorders, fibromyalgia, and chronic musculoskeletal pain; schizophrenia; attention-deficit hyperactivity disorders; depressive, obsessive-compulsive, bulimia nervosa, and panic disorders; and adult brain imaging. In addition, the company offers products to treat non-small cell lung, colorectal, head and neck, pancreatic, metastatic breast, ovarian, bladder, and metastatic gastric cancers, as well as malignant pleural mesothelioma; and cardiovascular products to treat erectile dysfunction and benign prostatic hyperplasia; and migraine headaches. And this is just a small part of what they do for humans. They do similar things for animals and are noted for their science and expertise. Plus they have collaboration agreements with Daiichi Sankyo, Incyte, Pfizer, AstraZeneca, William Sansum Diabetes Center, Purdue University, and Nektar Therapeutics. Truly a worldwide leader in big pharma.
BMR Take: This amazing company should hit another $3 a share in 2017, giving the firm a PE of under 28. We expect the company to hit the $4 level in a few years and wouldn’t be surprised to see the stock in the 90s within two years. Solid as a rock.
+++++++++++++++++++++++++++++++++++++++++++++++++++
Amazon’s Jeff Bezos Sells Shares
Jeff Bezos sold 1 million shares of Amazon (AMZN: $1112, up 1%) this week for $1.1 billion. The sale represented 1.3% of his holding and leaves Bezos with a 16.4% stake in the company. The world’s richest man said in April he would sell $1 billion a year in Amazon stock to fund Blue Origin, the rocket company he owns to explore Mars and outer space. He had already sold another batch of a million shares in May. So that’s 2 million shares in our book.
+++++++++++++++++++++++++++++++++++++++++++++++++++
From: Ron Shepro [ronshepro@xxxzz.com]
Sent: Tuesday, October 24, 2017 8:50 PM
To: 'The Bull Market Report'
Subject: RE: EARNINGS PREVIEW FOR THE WEEK AHEAD
Hi Todd – I Just wanted to say thanks for your good work. I find it interesting that Paul Mxxxxxx (a money manager), comes up with new recommendations that you had ages ago. Latest one being Splunk (SPLK: $68, up 1.5%). Looks like you are ahead of the legends. There are more, but I am sure you are aware of them. You also made the call on Paypal earlier.
Our Answer: Thanks, Ron. I think we have a fine little financial newsletter here. We just need another 5000 subscribers! We’ve had some nice wins with Nutanix, Square, PayPal as you mentioned, and CBRE (CBG) – the quiet real estate company.) And of course Splunk, which we added at $46.
Good Investing,
Todd Shaver
+++++++++++++++++++++++++++++++++++++++++++++++++++
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services
After the week before "melt-up", we noticed that the fear factor kicked up another notch. This past weekend, media pundits again started making comparisons to the March 2000 crash. Back then it was referred to as either the dot.Com bubble or the Tech Wreck. But there are some differences that should be noted. In 2000, the PE of the S&P 500 was about 30X, and many tech stocks had PE's in the triple digits or no PE's at all because they didn't even have revenues yet, much less earnings. Today's trailing PE is estimated to end the year somewhere in the area of 18X. This is higher than average, but not nearly as frothy as the 2000 period.
The question now becomes, "With this being the second longest and second biggest bull market in history, and with valuations as high as they are, can stocks keep climbing?" The easy answer is "yes", and the reasons are readily apparent. We have a strong economy and it is getting stronger. It is not just the US economy either – most major world economies such as Europe, Japan and China are also experiencing solid economic growth. Thus, we are part of a worldwide bull market, which makes it much easier on the US market.
More importantly, earnings are still getting stronger rather than leveling off or declining. According to Thomson Reuters, earnings growth for the third quarter is now 6.7%. Of the companies that have posted earnings, 74% have topped expectations - compared to the 72% average that beat expectations over the past four quarters. Good earnings growth is the key reason stocks can and should continue to climb higher. And, any tax reform will make it all the more likely that earnings growth will continue to be robust for the next year or two.
We also have history on our side. In the year after reaching a new peak, the S&P 500 has had positive growth 72% of the time. (Bloomberg) We would, however, caution investors that the bar is much higher today than it was over the past several years, and therefore the pace of growth may not be as rapid or the returns as high as we have experienced over recent years. In our experience, "euphoria" has never been a part of any successful investment strategy.
+++++++++++++++++++++++++++++++++++++++++++++++++++
The High Yield Corner
By Michael Foster
Obviously, the biggest news of the week for high yield investors came from Omega Healthcare Investors ($28), which fell massively on an earnings and revenue miss. The stock immediately fell over 3% on the news and has been falling further, causing a stock that was flat year-to-date to suddenly be down 7%. Panic selling also means the dividend yield has risen to 9.2% - a level we haven’t seen since 2011. Note that the company paid out a 65 cent dividend on Monday. So it really wasn’t as bad as it seemed.
This sounds like a time to sell, but it really isn’t. When we take a deeper look at the earnings result, we quickly see why.
The company reported a 2.2% decline in revenues on a year-over-year basis and a near 5% decline in FFO per share for the same period. This was all due to a $6.3 million loss in FFO, which was itself the result of late rent payments from the company’s biggest tenant, Orianna Health Systems. The story is pretty complicated, but it means that Omega Healthcare and Orianna are going to need to renegotiate their current arrangement, which could mean Omega cutting their rent down (this would be the best case), or an outright bankruptcy that results in Omega fighting for their back payments in court (the worst case).
If they are able to reduce rents, it could mean Orianna will start paying their bills again and FFO will start to trend upwards. And even if we are stuck with a bankruptcy proceeding, Omega will still get some money back, but predicting how much and when would be impossible (anyone who has ever been through America’s civil court system knows rulings can get pretty bizarre).
So what we are facing now with the stock, following Omega’s write-down of Orianna, is the worst situation. There is upside in either the best or worst case, but the amount of upside will depend on which route they go and how fast a deal is made. For now, Omega Healthcare’s dividend coverage has taken a hit - there’s no denying that. With the decline in earnings, the dividend is now only covered by… 130%.
That’s right. What we are looking at right now is a REIT yielding 9% that still has 130% dividend coverage. That’s at the bottom end of what’s ideal for REITs in our mind (regular readers know we look for 130% dividend coverage for REITs as the starting point for a safe yield), and that’s more than compensated by the 9% dividend yield.
It also means that a dividend cut is really unlikely to happen anytime soon. Omega Healthcare has established a track record of penny-per-quarter dividend increases, and if it continues that trend for the next year, its dividend coverage will fall to 128% by the end of next year, assuming no increase in earnings.
Do we think Omega will be able to continue its penny-per-quarter dividend increases forever? No. But we do think it can continue this trend for the next five years at the very least. But with the latest price drop, the market is pricing in the company stopping these increases much sooner. The market will probably realize the error of its ways pretty soon. Maybe next quarter when Omega shows stability or improvements, the market will buy in again. Maybe it’ll take a few quarters until Omega and Orianna reach a deal and the market realizes their fears were overblown.
Either way, now’s a great time to buy a 9% yielding stock with 130% dividend coverage.
Let’s move on to other news - there was a lot last week.
Digital Realty (DLR: $119, up 2%) announced another dividend (the December one) at a 93 cent per share distribution, in-line with the previous payout. This is not good. As we’ve written about frequently, we want Digital Realty to increase distributions because of their exploding FFO, which is far ahead of the dividend. But we understand why the company sees no need to give shareholders a pay raise quite yet - the stock has rebounded about 3% off its post-earnings low, so demand for the stock is definitely still there.
That, by the way, is why investors should continue to hold Digital Realty. There is tremendous value here, and the recent price dip was a buying opportunity - not unlike the more recent dip in Omega.
In other earnings results, Apollo Commercial Real Estate Finance (ARI: $18.35) saw NII jump 34% from a year ago, above expectations. This is pretty impressive, because expectations have heated up for this specialty mortgage REIT, and its stock price has soared in recent months accordingly. But the company is not running out of deals to make, with $425 million in new investments in the recent quarter, bringing the annualized deal flow to $1 billion by the end of the year. Also, last quarter’s dividend coverage ratio was a nice 117%. Keep in mind that coverage ratio thresholds are different for mREITs compared to property REITs. Because of their use of bond spreads to make a profit and their lack of dividend growth, lower coverage ratios are to be expected. And from a mREIT perspective, 117% is nice.
The stock got a slight price bump after the results, but nothing major. That was no surprise - the market has had high expectations for this firm for a while.
Finally, another REIT reported earnings last week: Government Properties (GOV: $18.43, up 2%), which beat on revenues thanks to a near 9% year-over-year increase, but FFO was a penny shy of expectations. That’s really too small of a miss to matter, especially since the market has discounted poor earnings for months now. So the stock actually went up over 1% following the release and over 2% for the week. We still need to see dividend coverage improve, but there is fundamental stability which indicates this remains an attractive 9% yielder.
Good Investing,
Todd Shaver, Founder and CEO
The Bull Market Report
Since 1998