May 14, 2017

by Todd Shaver | May 14, 2017 | Weekly Newsletter 7pm Sunday
The Week Ahead
“President Fires FBI Director” was the headline of the week. Think of it. When was the last time you can recall the head of the FBI getting fired? What does this mean about the stability of the FBI (one of our most important institutions)? What does this mean about President’s Trump future in Washington DC? Democrats are not letting this one go. Democrats are now openly discussing impeaching Trump. Who knows what will happen. But one thing is for sure, uncertainty is at a high in terms of geopolitical risks. So far, the Bull Market doesn’t seem to mind. We hope that continues to be the case.
There is always a bull market here at The Bull Market Report! This week we highlight the following securities: Square, Amazon, Splunk, Netflix, Tesla, and Apple.
Highlights From The Past Week
Earnings season is off to a good start. Over 90% of the companies in the S&P 500 have now reported results for Q1. The blended Q1 S&P 500 EPS growth rate is 14%, better than the 9% expected at the end of the quarter. It also represents the strongest growth since the 17% in Q3 2011. We note favorable top-line trends and recognition of improving sentiment and growth expectations is prevalent on Q1 earnings calls. However, not all managers have seen it translate to higher demand. CEOs expressed hope for widespread deregulation and improved regulatory clarity, but uncertainty remains high. The US economy is at full employment and wage growth is accelerating. Rising labor costs as a headwind to profit margins.
Watchful eye on the Retail sector. Headline retail sales increased 0.4% year over year in April following an upwardly revised 0.1% increase in March (originally -0.2%). However, consensus was for a 0.6% increase. Sales at both general merchandise stores and clothing and clothing accessories stores were down 0.5%. However, it was not all bad. Nine of the 13 categories in fact posted sequential increases. The non-store category (Internet) was a standout, increasing 1.4%. All in all, we are concerned about the Retail sector and need to be mindful of what it means to the broader economy. Case and point, this week we saw Macy’s (M: $24, down 19%) crater on a worse than expected update to its financial outlook. Many are now calling for large scale bankruptcies.
Financials and Industrials lag; Utilities and Tech higher. This week Industrials were the worst performer. The weakness was fairly broad based with GE (GE: $28, down 3%) causing much of the drag. Energy and Construction and Machinery also saw outsized pullbacks. Financials also underperformed. The lower rate backdrop is an easy excuse for bank sluggishness. Regional banks fared much worst that the large money center banks. Life insurers and online brokers also were notable decliners. Pharma found a big rally following upbeat trial data for lung cancer treatment for an industry bellwether. Though hospitals were laggards. Tech outperformed as FAANG stocks are up $250 billion in market cap for the year with the rest of the S&P 500 down $250 billion (so the equity market is essentially down excluding FAANG).
BMR Companies and Commentary
Square (SQ: $20, +2%)
Square jumped to a record high after reporting results that beat analysts’ expectations, impressing investors with its ability to woo bigger sellers and offer newer software products that help merchants manage their businesses. Revenue in the first quarter rose 39% as more businesses signed on for payments processing, loans and software to help manage inventory. Square raised full-year sales and profit forecasts, adding an exclamation point to the quarter. The shares have now more than doubled from a low nearly a year ago.
Not long ago, investors questioned Square’s prospects as a provider of credit card processing for food trucks amid rising competition from PayPal and First Data. But the company, run by Twitter Chief Executive Officer Jack Dorsey, has plowed ahead with international expansion, partnerships and acquisitions. Square is targeting larger merchants with a growing suite of more-profitable services, including loans and software that manage inventory and analyze sales. In the fourth quarter of 2016, those newer offerings made up a quarter of revenue. It was even higher by the first quarter, Chief Financial Officer Sarah Friar said.
What continues to make us pleased with results is growth in large businesses. That ongoing shift is good to see because those folks are not net new to the payments world. They’ve probably had an alternate supplier, but now they want to be on the latest technology and their action of migrating over to Square speaks volumes. Square said revenue from larger sellers -- those with at least $125,000 in annualized gross payment volume -- grew 44% in the first quarter from a year earlier.
BMR Take: Square is battling it out with industry titans such as Visa, MasterCard, American Express, and PayPal. So far so good. The company is in growth mode as the top line is set to expand from $900 million this year to $1.8 billion in 2020. Profitability and EPS growth will follow, with some analysts calling for $0.50 of EPS as early as 2020. All in all, we think Square is a very sturdy long term growth story, one you definitely need in your portfolio.
Amazon (AMZN: $962, +3%)
Our dear Amazon. Another week has come and gone. What new world-changing breakthrough have you for us? Home furniture? Alrighty then!
Amazon now wants to furnish your home. The online retail giant is making a major push into furniture and appliances, including building at least four massive warehouses focused on fulfilling and delivering bulky items. With that move, the Seattle-based retailer is taking on the two companies that dominate online furniture sales -- Wayfair and Pottery Barn owner Williams-Sonoma. Furniture is one of the fastest-growing segments of U.S. online Retail, growing 18% in 2015, second only to Groceries. About 15% of the $70 billion U.S. furniture market has moved online.
But even the biggest players in online furniture are struggling to get the market right. Unlike established categories such as books and music or even apparel, retailers are still hammering out basic concepts like how much variety to offer on their sites and the most efficient ways to deliver couches and dining sets to customers' homes.
While Amazon has been selling furniture for years, it has lately decided to tackle the sector more forcefully. Furniture is one of the fastest-growing retail categories at Amazon. The company is expanding its selection of products, with offerings including Ashley Furniture sofas and Jonathan Adler home décor, and it is adding custom-furniture design services. Amazon is also speeding up delivery to one or two days in some cities.
While Amazon has disrupted industries from publishing to fashion with free, fast shipping and easy, one-click buying, furniture can be a tough sector to crack. For one, it is expensive to deliver a couch and other big items, and consumers typically want what are known as "white glove" services, extras like bringing it into the home, setting it up and removing trash. And while packing more small packages onto a delivery van brings the costs down because it can make more stops, you can only fit so many pieces of furniture onto a truck.
Shoppers are still generally willing to pay for furniture delivery, but some retailers and logistics companies say they are facing growing pressure to ship online orders faster. Wayfair offers free shipping on orders over $49, but delivery times can range up to two weeks and longer. Pottery Barn charges on a sliding scale based on price, with delivery costs running above $100 for more expensive items. Furniture sold and shipped directly by Amazon is free for Prime members, while items sold by third-party sellers may cost extra.
To guarantee two-day shipping to 99% of consumers, a retailer or logistics company needs up to a dozen large warehouses spread around the country, plus around 110 smaller facilities to stage deliveries to customers' homes. Amazon is expected to rely on other third-party providers to manage distribution centers and handle delivery of furniture and appliances for the near future, even as it takes more of its logistics in house in other parts of its business. Rising sales may help reduce delivery costs by creating better density. Costs go up for transportation companies as deliveries get more spread out and infrequent.
BMR Take: We see Amazon winning this business opportunity, as they normally do.
Total sales growth is projected to run greater than 20% for several years from the current level of $165 billion predicted this year (up from $135 billion last year.) What an extraordinary growth story Amazon is. What a great ride this stock has and will continue to be. If the company can reach the $30 of EPS analysts project by 2020, this stock easily goes much. Much higher.
Note: See more on Amazon below in “The Death of Retail?”
Splunk (SPLK: $67, +1%)
Splunk, a provider of the leading software platform for real-time Operational Intelligence, announced the results of new research that shows digital transformation* initiatives are more successful when they have buy-in from across the business.
* Digital transformation is the change associated with the application of digital technology in all aspects of human society. The transformation stage means that digital usages inherently enable new types of innovation and creativity in a particular domain, rather than simply enhance and support the traditional methods.
Findings from a survey of 400 senior IT executives across the U.S., U.K. and Germany show that adoption of digital transformation initiatives is widespread. When asked where they are in the journey, 36% believe they are ahead of the curve, while 55% believe they are moving with the masses. They said that 30% of their IT budget is dedicated to digital transformation projects, but the research reveals these initiatives are more likely to succeed when funded from outside IT. The organizations that are most mature when it comes to digital-first strategies are more likely to indicate that funding comes from departments such as product development, customer service, sales and marketing.
Having a digital transformation strategy and executing on it no longer means you have an edge. If the majority of organizations are ‘moving with the masses’ or believe they are ‘ahead of the curve’ then no one is really standing out. Organizations that rely on machine data to make better decisions gain a strategic advantage over their competitors. It is not surprising that those organizations with the most success are the ones collaborating – and funding – cross-functionally. Data is a key driver in enabling that collaboration and can help companies drive real-time business insights to move faster to differentiate, innovate, raise revenues, reduce costs and mitigate risks.
Key findings from the report include: (i) 67% of respondents expect digital transformation budgets to increase, while only 8% expect a decrease; (ii) 70% of respondents cite IT as a key funding source. (iii) 77% of respondents say security was a critical or very important driver; and (iv) insight into machine data is key to success: When asked about the ability to derive real-time insights and business value from machine data to achieve their digital business goals, more than two-thirds say this is a critical or very important priority.
BMR Take: Splunk is the market leader in analyzing machine data to deliver Operational Intelligence for security, IT and the business. Splunk software provides the enterprise machine data fabric that drives digital transformation. More than 13,000 customers in over 110 countries use Splunk solutions in the cloud and on premise. It is an exciting time for Splunk in this business. With EPS on track to go from $0.41 in this most recent fiscal year to $1.35 in 2020, the prospects for the stock look exciting too. We are up 46% since we added it in March of last year. Our Target is $75.
Netflix (NFLX: $161, +3%)
Netflix announced 400 new jobs in Europe and two new European original series. The expanding workforce complements $1.75 billion of investment in European content, with at least six new Netflix European original projects to be announced in 2017. Netflix is now taking over Europe!
The creation of 400 jobs is happening at its new European customer service hub, which opened this week in Amsterdam. The customer service center will support customers across 11 European countries (Belgium, Denmark, Finland, Ireland, Luxembourg, the Netherlands, Norway, Poland, Romania, Sweden and the UK). The multilingual hub will employ initially a workforce of 170, growing to 400 by the end of 2018.
Amsterdam is the location also of Netflix’s recently expanded European, Middle East and Africa headquarters, which has doubled its workforce since the beginning of 2016. More than 120 employees from 18 countries work at the HQ in business development, marketing, PR, public policy and corporate functions such as finance, legal and recruiting.
The ongoing expansion of Netflix’s workforce in Europe complements the company’s ever-growing investment in European productions (licensed, original and co-productions). The company confirmed plans to announce at least six new European original projects before the end of 2017. Netflix has committed more than $1.75 billion to European productions since entering Europe in 2012, including more than 90 original productions in various stages of development.
BMR Take: We are delighted to see the creation of jobs in Europe and the opening of a new customer service hub in Amsterdam, as well as two new European original series. Moving outside the US, Europe is a great market for Netflix to tap in to to make money longer term. We think Netflix is on track to meet or exceed analyst estimates for $10 of EPS in 2020, meaning the stock can not only grow into the current valuation, but likely head much higher. Our Target is $165. We can’t wait to raise it soon. We do hereby raise the Sell Price from $125 to $145.
Tesla (TSLA: $325, +5%)
Elon Musk has discovered a new passion in life — and it could be Tesla's best product yet. Tesla CEO Elon is the best car salesman in history. And as CEO of SpaceX, he's declared his intention to retire on Mars. But electric vehicles and low-Earth orbits might not hold a candle to what Musk ultimately ends up doing in the roofing business.
Against all odds, Musk has become the biggest booster in the history of the roofing business, thanks to a new Tesla product, the Solar Roof, that officially went on sale last week. It's the first post-Solar City-acquisition product that Tesla is selling, and it sounds as if it's been occupying at least as much of Musk's attention as the forthcoming launch of Tesla's Model 3 car.
Musk has always been big on solar power. Prior to Tesla buying SolarCity for over $2 billion, Musk was the company's Chairman (his cousin was the CEO). He likes to point out that humanity has a compelling alternative to fossil-fuel energy: the giant fusion reactor in the sky that bathes the planet every day with free power. Solar also fits into his master plan, which involves eliminating greenhouse-gas emissions by electrifying transportation; backing up the biosphere with SpaceX, which would make humanity a multi-planetary species; and powering it all with solar energy.
SolarCity has long been able to sell or lease a homeowner solar panels, but the Solar Roof offers a different value proposition. If you have to replace your roof anyway, why not replace it with a roof that generates power and saves you money over the long haul? With a 30-year-mortgage if you stay in the house, you'll replace your roof at least once. At a cost of about $10,000, you maintain the value of the home, but you don't necessarily add much to it. The Solar Roof should last twice as long as a traditional roof (and maybe much longer) and it will both mitigate your electricity costs and, paired with a Tesla Powerpack battery, provide you with backup energy. The up-front costs are high, but the overall economics are compelling. And in sunny states where electricity is costly, such as California, a Solar Roof could net a homeowner tens of thousands of dollars over 30 years.
BMR Take: Solar is the future of energy. Elon Musk and Tesla are already finding opportunities to tap into the trend. Solar roofs have a very bright future and can be a key driver of EPS for Tesla. Analysts currently project EPS to flip from a loss of $5.15 this year to over $11 in 2020. This stock has great potential. The stock set new all-time highs last week, defying the bears. Let’s put it this way – the shorts are getting killed.
Apple (AAPL: $156, +5%)
Apple chose Corning as the recipient of the first investment from its Advanced Manufacturing Fund, giving $200 million to the maker of glass used in iPhone and iPad screens. Corning, a longtime Apple partner, will use the cash on equipment and glass-processing technology mainly at its Kentucky facility that developed the protective Gorilla Glass used on smartphones. Some of the money will also go toward research and development costs. Corning’s partnership with Apple started 10 years ago with the first iPhone.
Apple Chief Executive Officer Tim Cook said in May that the company planned to invest at least $1 billion to back advanced manufacturing companies in the U.S. and help create jobs in the industry. President Donald Trump has been a vocal critic of American companies -- and Apple in particular -- that outsource production to non-U.S. manufacturers. Apple said it now supports 2 million jobs in the U.S. and that the Corning relationship has helped create about 1,000.
The investment is also a good-will gesture toward Republicans, including President Trump, who has criticized Apple for building its iPhones in China, and the Senate majority leader, Mitch McConnell, who represents Kentucky. Apple said it spent $50 billion last year with American suppliers, although it manufactures just one product line, the Mac Pro, in the United States.
Last month, Mr. Trump sketched out a plan to slash overall corporate tax rates and offer companies a special break for bringing back profits held overseas. Apple has accumulated more cash than any other company in the United States — $260 billion now - and virtually all of it is stashed untaxed in foreign bank accounts. Cook, has repeatedly complained that taxes in the United States are too high and has vowed not to bring the cash home until taxes are cut. The Corning investment is a nice gesture for Apple to show the US government that it is a good US citizen.
BMR Take: EPS are on track to be near $9 this year and grow to $10-11 in the years ahead. The Corning investment and improving government relations is reassuring for us to see. Apple remains a favorite for us. We’re up 66% on our investment since we added the stock early last year. Not bad for the largest a company with the largest market cap in the world, now $814 billion. Our Target is $155, which it has just eclipsed. Yes!!!!!!!
We’ve been waiting to say this: WE HEREBY RAISE THE TARGET PRICE ON APPLE TO $170. The Sell Price is “We would not sell Apple” and we no reason to change this. Good investing out there!
Economic Outlook for the Coming Week
Monday, May 15, 2017 10:00 AM ET
NAHB Housing Market Index SA
Period: MAY
Actual: N/A
Consensus: 68.5
Prior: 68.0
The NAHB/Wells Fargo Housing Market Index is derived from a monthly survey of builders conducted by NAHB . Home builders are asked to rate current sales of single-family homes, and prospects for sales activity in the next six months, as "good," "fair" or "poor." They are also asked to rate traffic of prospective buyers as "high to very high," "average" or "low to very low." Scores for each component are then used to calculate a seasonally adjusted index where any number over 50 indicates that more builders view sales conditions as good than poor. 68.5 is a pretty strong indication of future growth.
Tuesday, May 16, 2017 8:30 AM
Housing Starts SAAR
Period: APR
Actual: N/A
Consensus: 1,263K
Prior: 1,215K
The number of housing units started in the United States. The U.S. Census Bureau's New Residential Construction release provides statistics on the construction of new privately-owned residential structures in the United States. The data relate to new housing units intended for occupancy and maintained by the occupants. They exclude hotels, motels, and group residential structures such as nursing homes and college dormitories. Also excluded are "HUD-code" manufactured (mobile) home units.
Thursday, May 18, 2017 8:30 AM
Initial Unemployment Insurance Claims
Period: 05/13
Actual: N/A
Consensus: 240K
Prior: 236.0K
Weekly data on initial claims for unemployment insurance under state programs. The U.S. Department of Labor's Employment and Training Administration collects weekly data on new and continued claims for unemployment insurance benefits under state programs.
Thursday, May 18, 2017 10:00 AM
Period: APR
Actual: N/A
Consensus: 0.30%
Prior: 0.40%
Leading indicators are economic series that tend to change direction ahead of shifts in the business cycle. There are 10 components of the U.S. Leading Composite Indicator published by The Conference Board. The index is constructed by averaging the individual components in order to smooth out a good part of the volatility of the individual series. Historically, the cyclical turning points in the leading index have occurred before those in aggregate economic activity.
An Update on Twilio
Twilio (TWLO: $24, flat) survived another week in the low 20s. They reported earnings on Monday, two weeks ago with glowing revenues, weak earnings (expected), but gave notice that they are losing one of their big customers – Uber at 12% of revenues. They mentioned that they added 4,000 customers in the quarter to reach over 40,000 customers but the market only took notice of their losing the one customer. They have another big customer at over 10% of revenues – WhatsApp, which is owned by Facebook – and the market is worried about their losing this customer. We are not. We are focusing on the 12,000 customers a year that they are adding to their base.
Here is a letter to us on the day we issued the News Flash, from one of our subscribers, Bob Rood:
I bought some at the low yesterday. Bob
And our response:
OK, good, Bob. It has rallied a tad this morning. But be prepared for anything that might happen. We could see $20 before we see $30. I hope this is not the case, but it could happen. It looks like Uber is slowly leaving as a customer and they had 12% of revenues. So, this will take some time to work out. They did add 4,000 customers last quarter and are now at 41,000. They normally add 2,800 a quarter. But note that this is going to take some time.
Todd Shaver
Second Quarter Earnings Reports
About 50% of firms have beaten earnings forecasts, above the long-term average of 46%, according to Goldman Sachs. Further, 40% of companies have exceeded revenue estimates, the most positive ratio of surprises in almost six years.
The VIX (^VIX: 10.40)
The lack of concern amongst US equity investors can be seen in the CBOE Volatility Index, the VIX, a 30-day barometer of investor nervousness calculated using S&P 500 options. The so-called fear gauge on fell on Tuesday to the lowest on record, at 9.67, according to data compiled by Bloomberg, before rallying to close at 10.40.
BMR Take: Low volatility is a sign of bullishness. In times of panic when the market is falling day after day, the Vix is usually in the 20s and sometimes in the 30s. In 2008 when the world was caving in financially, the Vix reached the 60s at the worst of the financial crisis and even spiked into the 90s. The historical average is about 15-16, so at 10 we are in very calm, uncharted territories. Because of this ultra-low volatility level some people say: LOOK OUT; watch for something to happen. We’re not like that. If this market can handle this last week of Trumponomics, then it can handle anything.

c/o Business Insider
The Death of Retail?
Warren Buffett just proclaimed the death of Retail as we know it. In an article in Business Insider he says the future of the retail department store is online. This is not rocket science to us, but to hear Warren say these things holds a lot of weight in our book. Berkshire Hathaway fired a warning signal for the retail industry in February when it sold off $900 million of Walmart stock, choosing instead to invest billions in airlines.
In the age of Amazon, "I think retailing is just too tough for me, generally," Buffett said. "We bought a department store in 1966, and I got my head handed to me. I've been in various things in Retailing. ... I bought Tesco over in the UK and got my head handed to me. Retailing is very tough, and I think the online thing is hard to figure out."
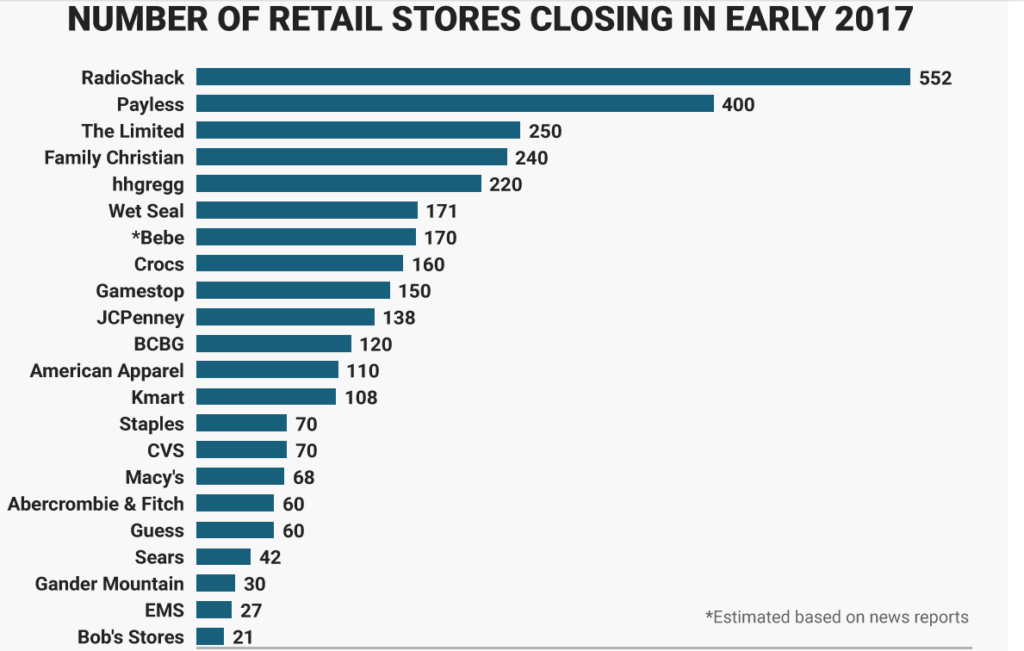
Brick-and-mortar retailers have announced more than 3,200 store closures so far this year, and Credit Suisse expects that number to increase to more than 8,600 before the end of the year. For comparison, 6,200 stores shut down in 2008, the worst year for closures on record. Department stores like Macy's, Sears, and J. C. Penney have been hit the hardest by these trends - since 2001, department stores have lost half a million jobs.
BMR Take: In March we thought about buying Simon Property Group (SPG: $157, down from $186 in February), but we changed our minds quickly. Instead, we would buy Amazon now. The stock closed at $962 Friday, up $27 or 3% last week. Yikes – 10-year bonds pay less than 3% PER YEAR.
Please DON’T WORRY ABOUT THE HIGH STOCK PRICE – pretend it is trading for 1/10 or $93 a share. Buy 11 shares, or 32 shares, or 100 shares – but buy some Amazon. We can see $1000 a share soon; then $1100; then $1200. This one might hit $2000 sometime next year.
c/o Business Insider
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
We have often referred to them as the four most dangerous words in our business – "this time is different.” We are beginning to pick up quite a bit of commentary lately that talks in terms of it being different this time. The words are not all the same, but the general gist is that "American equities may not be significantly overpriced; The market may be discounting a far-larger rise in future corporate earnings than most investors realize is possible (Trump tax cuts); or foreign investment may be altering the traditional valuation parameters used to determine share-price multiples so that it is quite possible that we have entered a new era for share price evaluation".
The bottom line to all of this is that we don't believe there are any "It's different this time fundamentals" that are going to change this market. There are obviously new and varied "wrinkles" attached to today's market scenario relative to history, but it will still, in our opinion, move in the direction that earnings take it. Earnings thus far have met or exceeded expectations. We believe that until they disappoint, the market will advance, but only so far as earnings allow……..not because of a pundit's idea that the market is going up due to some new theory about share price evaluation or of it being "different" this time.
Opko Health: A Letter from a Subscriber
We're sure you have all read the news on Opko Health (OPK: $7.19, down 4%) about their earnings report that we put out via News Flash on Thursday. After much consideration, we have decided to stick with it, even as the stock is down significantly from the price at which we added it in September. A reader wrote us on Friday:
From: John <jotenn@xxxxx.com>
To: The Bull Market Report <Info@BullMarket.com>
Sent: Thursday, May 11, 2017 11:03 AM
Subject: News Flash for May 11, 2017: Opko Health: An Uneventful Quarter. Time to Step Aside? Or Be Patient?
Hi Todd:
You are right about others buying OPKO. The CTO just bought 40,000 shares, and I see the Executive VP just picked up another couple of thousand shares under $7 too.
I bought a few hundred more shares at 6.80 yesterday also. I believe CEO Frost is playing the long game here. Lots of irons in the fire, and he is spending money to develop them, thus, less profit than analysts expected although revenue was good. Anyway, you win some (MZOR is a real home run, thanks!) and lose some, but I am still holding in there, and I keep averaging down whenever a whole number is breached. Did that with VRX too, and it is now paying off, big time!
Best, John Tennant
And we sent this back to John:
OK, thanks for sending this news, John. We were going to comment on it in the newsletter this weekend [which we are doing now!] Revenues are key. What do you have with no revenues? Nothing. Most biotech companies have no revenues and all they have is hope that their products will work out. Opko can coast while they work on the new stuff. But it sure is frustrating waiting and waiting….
Can’t wait to see if CEO Frost is buying more down here.
Todd Shaver
Snap Posts $2.2 Billion Loss in First Quarterly Report
Snap (SNAP: $19.14, down 17%) reported a $2.2 billion loss Wednesday, in its first quarter as a publicly traded company, much deeper than the $105 million loss it posted a year ago, hurt by a one-time hit from IPO-related compensation expenses totaling $2 billion. The loss is one of the biggest in American corporate history. Snap had revenues of $150 million which more than quadrupled from the year-ago quarter but missed the consensus estimate of $158 million. Losses more than doubled to $188 million. We always find it strange for a company to lose more money than it actually took in in revenues.
Daily active users rose 36% to 166 million from the year-ago quarter, but the average revenue per user fell, while daily active user growth also disappointed.
Snap went public at $17 in March and reached $27 the second day of trading. We’ve been saying since the IPO that the company is overvalued. This earnings report goes a long way to backing us up on that.
Tesla Starts Taking Orders for its Rooftop Solar Tiles
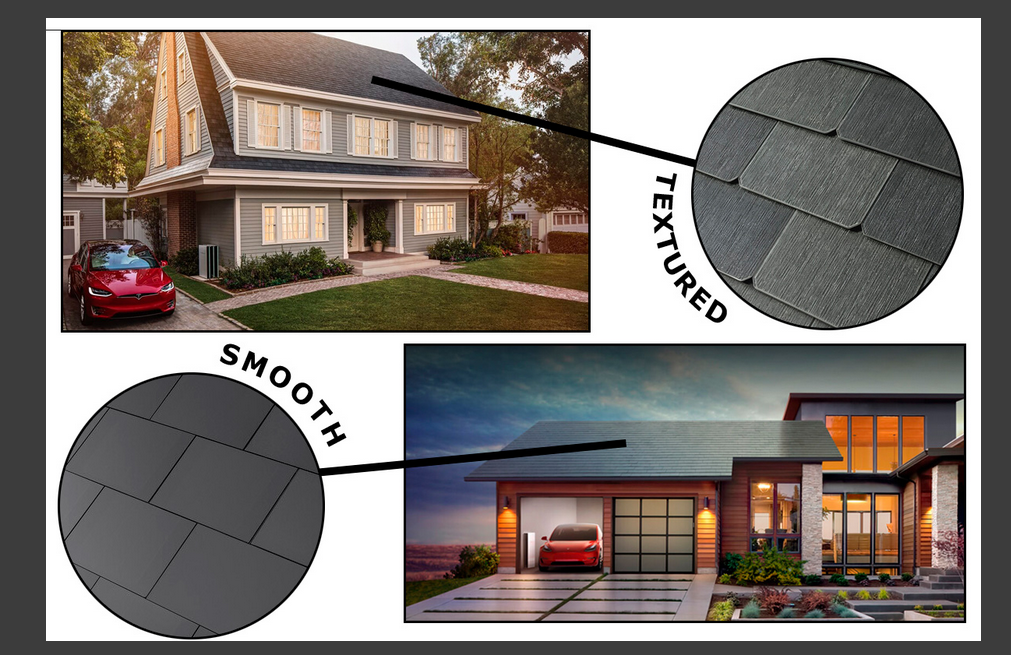
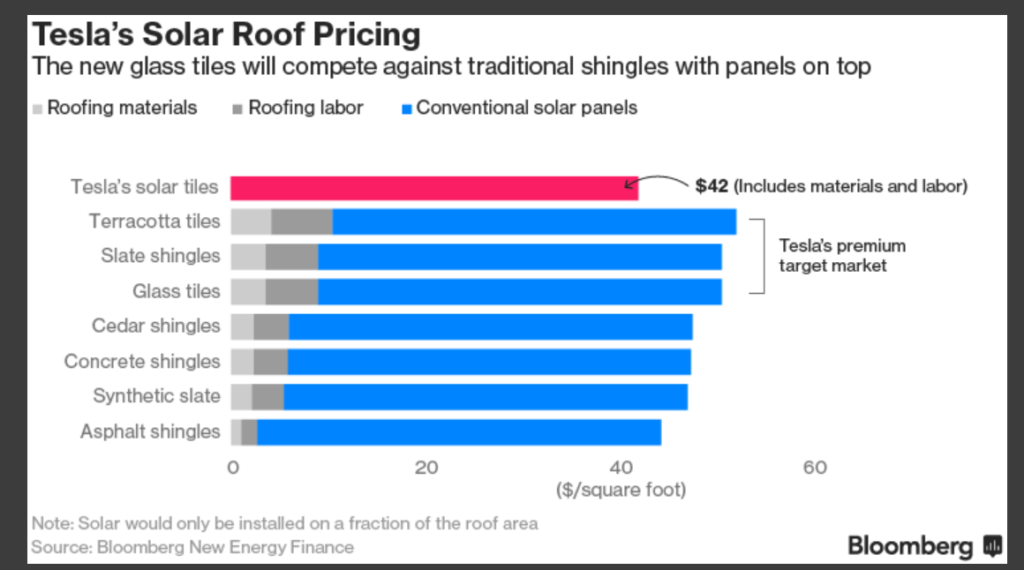
Tesla has begun taking $1,000 deposits for its remarkable solar roof tiles at a lower price point than most folks expected. The company said it will begin with production of two of the four styles it unveiled in October: a smooth glass and a textured glass tile. They say that roofing a 2,000 square-foot home with 40% coverage of active solar tiles and battery backup for night-time use would cost about $50,000 after federal tax credits and generate $64,000 in energy over 30 years. That’s more expensive upfront than a typical roof, but less expensive than a typical roof with traditional solar and back-up batteries. The warranty is for the lifetime of your home.
They are obviously going after the wealthier clientele to start. Then again, so does Apple. And so do most companies. The cost for active solar tiles is about $42 per square foot, whereas normal roof tiles cost about $11 per foot. Tesla will manage the entire process of solar roof installation, including removal of existing roofs, design, permits, installation and maintenance. The company estimates that installation will take about a week.
Kinder Morgan to raise up to $1.3 billion in Canadian IPO
Kinder Morgan (KMI: $19.91, down 1%) has a Canadian unit that is seeking to raise up to $1.3 billion in an IPO in Toronto. The deal would help fund the expansion of Kinder Morgan's Trans Mountain pipeline. Trans Mountain currently transports 300,000 barrels per day (bpd) of crude oil and refined petroleum products from the oil sands in Alberta to Vancouver, British Columbia and Washington State. In November, the Government of Canada granted approval for the $6.8 billion Trans Mountain Expansion Project, which will increase the capacity of the system to 890,000 bpd. The expanded pipeline is expected to be completed in 2019.
The company plans to offer between 80 million and 92 million shares. Toronto Dominion Bank and Royal Bank of Canada are the lead underwriters for the IPO.
The pipeline project has already won approval from the B.C. and federal governments.
Kinder Morgan will retain about 75% of Kinder Morgan Canada if the share sale were to proceed, the filing shows. Toronto-Dominion Bank and Royal Bank of Canada are leading the share sale.
BMR Take: We continue to feel Kinder Morgan is undervalued but we are content to wait patiently, collecting the 2.5% dividend. The stock was at $44 in the spring of 2015 and is now less than half that. It will start moving higher any day now.
High Yield Report
The High Yield Corner
By Michael Foster
The biggest news of the week for The Bull Market Report’s High Yield portfolio came from AstraZeneca (AZN: $34), which jumped 9% thanks to positive results from a phase 3 study of its Imfinzi drug, a non-small cell lung cancer treatment. The FDA has already approved the drug for bladder cancer treatment, but of course lung cancer is a much bigger and more serious disease, so this is significant news for the company.
The stock had been struggling for nearly a year, falling precipitously both before and after the election. Before the election, fears that Clinton would gut pharma profits caused a big selloff, but that selling pressure increased tremendously following Trump’s election and the surprising news that Trump had little sympathy for pharma either, and he was going to take a scalpel to their profit margins as well. Things hit a low at the beginning of 2017, but recent political scandals and attention elsewhere, as well as the perhaps not too shocking news that Trump is finding it difficult to repeal the Affordable Care Act, have helped pharma companies revert back to a pre-election equilibrium.
Where does that leave us now? Clearly the market has taken its eye off the pipeline ball for a long time, and one has to wonder if the recent news on Imfinzi may in fact force some greater discipline on the market and make investors realize that a sub-30 P/E ratio on a company with many life-saving drugs in various stages of regulatory approval is perhaps unfair. Credit Suisse recently upgraded the stock for that very reason, and we expect more upgrades to come in coming weeks. We’re still 3% off the 52-week high, so there’s no reason to think the sudden buying pressure on Friday is a one-off.
In the more conventional world of ultra-high yield, we’re seeing a continuation of the BDC selloff and junk bond complacency that we have written about for several weeks now. BDC earnings results continue to come in, and for the most part things do not look good. The UBS BDC ETF (BDCS: $22, down 3%) was pummeled by a mix of falling NAVs at constituent firms and analyst downgrades. The downgrades partly come from the aforementioned weakness in NAV, but portfolio yields are also deteriorating at many BDCs. What is portfolio yield? Remember, a BDC is a collection of loans to small and medium-sized businesses. The BDC gets a coupon from each loan, which is the BDC’s yield per loan. Average those together and you get the BDC portfolio yield.
Here’s the real problem: those yields have been going down for a decade. That’s made investing in BDCs particularly tricky, and has caused the BDCs themselves to do a lot of things (lower fees, issue more stock, take on greater risk) to keep investors happy. But all that was supposed to stop when the Fed started raising interest rates, which would cause rates to rise everywhere else. And that is indeed happening elsewhere in the Financial world. Margin rates, preferred note rates, corporate debt rates, and even municipal bond rates have been inching up in anticipation of the Fed’s rate hikes. BDC rates have been on an almost constant slide downward - but the interest rates they need to pay for debt-based capital is going up. So BDCs’ cost of capital is broadly rising and their portfolio yields are going down, compressing margins.
This is a mess. Why is this happening? As far as we can tell, it’s a result of supply and demand. The supply of capital looking for yields has just grown and grown; there are more investors looking to lend to small and medium-sized businesses, thus competing with BDCs. Newer BDCs are showing up. Leveraged lending firms are competing with BDCs. Regional banks are getting back into the small business lending business too. All of this is a structural headwind to BDCs, as they face more competition and thus have to take on more risk or lower the rates they offer on loans. That’s a horrible place to be in, and is why we remain cautious on BDCs as a general rule.
So it’s not surprising that BDCs are down 3%, and we expect that to continue. At the same time, however, there is incredible calm in the junk bond market. The SPDR Barclays High Yield Bond ETF (JNK: $37, flat) barely shrugged this week thanks to little news of significance and a continuation of the declining bankruptcy trend that we’ve seen since early 2016. Again, this is a strong reminder that markets should be forward-looking. Bankruptcy rates were rising in 2015-2016, and junk bond funds were collapsing at the same time. But in early 2016 the bankruptcy problem largely came to a stop, partly thanks to a recovery in oil and partly thanks to the wave of bankruptcies already shaking out most of the weak hands. Yet investors were very slow to realize and jump in.
Now that oil is getting weaker again, one has to wonder if junk bonds are getting ready to peak and a new wave of defaults may be upon us. For sure, that is a possibility but few signs indicate that we will see a repeat of 2015-2016. Instead, we could see a lot of investors anticipate a repeat that never happens, resulting in a mini-correction that provides a buying opportunity.
This means right now is a good time to stick to well-yielding junk bond and high yield bond funds. The Bull Market Report portfolio includes the PIMCO Dynamic Income Fund (PDI: $29, down 1%) and the AGIC Equity and Convertible Income Fund (NIE: $20, down 1%). Admittedly, the discount to NAV on either fund is not particularly compelling right now, but the portfolio quality and historical track record are so good that investors are wise to hold onto these stocks if you have them. New purchases in new bond funds may be something worth considering in the future. More of that in future issues of The Bull Market Report.
Good Investing,
Todd Shaver, Founder, CEO and Editor
The Bull Market Report
www.BullMarket.com
May 1, 2017
by Todd Shaver | May 1, 2017 | Earnings Preview 6 PM
Mazor Robotics (MZOR: $36)
Bull Market Report Target Price: $44
Bull Market Report Sell Price: $32
Earnings Date: Tuesday, (exact time unavailable)
Consensus: 1Q17
Revenues: $11.5 M
EPS: -$0.17
Year Ago Quarter Results
Revenues: $6.5 M
EPS: -$0.24
Key Things to Watch For in the Quarter
Mazor Robotics is expected to report healthy revenue and EPS growth for 1Q17. Analysts estimate that Mazor will report a 79% increase in revenue to $11.5 million and a 30% increase in EPS to -$0.17. The firm reported earnings that missed estimates in all four quarters of 2016, and the stock has provided investors with a 200% return. The CEO made an appearance on Mad Money last week, contributing to the 55% upwards move since March 22nd, just 10 days ago. Mazor had a market cap of approximately $550 million at the beginning of this year, relatively small by Wall Street’s standards, allowing it to fly slightly unnoticed by larger investors. But not by readers of The Bull Market Report!
Shopify (SHOP: $77)
Bull Market Report Target Price: $90
Bull Market Report Sell Price: $59
Earnings Date: Tuesday, before the market open (exact time unavailable)
Consensus: 1Q17
Revenues: $122 M
EPS: -$0.09
Year Ago Quarter Results
Revenues: $72 M
EPS: -$0.06
Key Things to Watch For in the Quarter
Analysts across Wall Street estimate that Shopify will report a revenues increase of 67% to $122 million and an earnings deficit of -$0.09 (-50%) for 1Q17. Shopify beat analyst estimates in all four quarters of 2016, which has been reflected in the stock’s 134% return over the past year. Shopify provides a cloud-based, multi-channel commerce platform designed for small and medium-sized businesses. They assist in web design, set up, and facilitation of sales for their customers. Shopify is an industry leader and has positioned itself to catch more of the growing online retail business in the years to come.
We hereby raise the Sell Price from $59 to $65.
Apple (AAPL: $147, new all-time high)
Bull Market Report Target Price: $155
Bull Market Report Sell Price: We would not sell Apple
Earnings Date: Tuesday, 5:00 PM ET
Consensus: 2Q17
Revenues: $53.0 B
EPS: $2.02
Year Ago Quarter Results
Revenues: $50.5 B
EPS: $1.90
Key Things to Watch For in the Quarter
Analysts expect Apple to report modest growth in both EPS and revenues of about 6% and 5% to $2.02 and $53 billion respectively for 2Q17. When Apple beat estimates in 2Q16 the stock rose 5%. Since this time last year, investors have seen returns of over 50%, including a 1.6% dividend yield. Apple’s R&D department has been very busy in recent months. Rumors say they are looking into driverless car technology and revamping Apple Maps to incorporate features similar to Google Maps’ Street View. Apple continues its climb towards our $155 target.
The Carlyle Group (CG: $17.75)
Bull Market Report Target Price: $20
Bull Market Report Sell Price: $13
Earnings Date: Wednesday, 8:30 am ET
Consensus: 1Q17
Revenues: $550 M
EPS: $0.38
Year Ago Quarter Results
Revenues: $451 M
EPS: $0.18
Key Things to Watch For in the Quarter
Analysts estimate that The Carlyle Group will report a 22% increase in revenues to $550 million and an astounding 110% increase in EPS to $0.18 for 1Q17. Carlyle beat estimates in the first two quarters of 2016, but fell short to analyst’s aggressive third and fourth quarter estimates. Although the stock took an 8% hit following the 1Q16 earnings release, it has still managed to climb 2% over the past year. Add Carlyle’s incredible 10% dividend yield and shareholders who purchased this stock just last year would have already seen a 12% return. The stock has been trading horizontally over the past year; however we see it breaking out in the coming months towards our $20 target.
Tesla (TSLA: $327, a new all-time high)
Bull Market Report Target Price: $325
Bull Market Report Sell Price: $280
Earnings Date: Wednesday, (exact time unavailable)
Consensus: 1Q17
Revenues: $2.6 B
EPS: -$0.76
Year Ago Quarter Results
Revenues: $1.2 B
EPS: -$1.45
Key Things to Watch For in the Quarter
Analysts estimate that Tesla will report a 48% decrease in the earnings deficit to -$0.76 and 115% increase in revenues to $2.6 billion for 1Q17. Tesla only beat analyst estimates in the third quarter last year, but the stock still managed to climb 25%. Elon Musk, Tesla’s famed CEO, has continuously grown the firm’s Research and Development operations. These expenditures have made huge contributions to the firm’s top line revenue, allowing it to provide affordable electric cars to the mass market. The firm has struggled to make a profit thus far, however we are confident in Musk’s vision and ability to change the landscape of the automotive market.
It just hit our Target today, so we hereby raise our Target to $350 from $325. Expect a stock split at any time too.
Facebook (FB: $152, a new all-time high)
Bull Market Report Target Price: $165
Bull Market Report Sell Price: $140
Earnings Date: Wednesday, 5:00 PM EST
Consensus: 1Q17
Revenues: $7.8 B
EPS: $1.12
Year Ago Quarter Results
Revenues: $5.4 B
EPS: $0.77
Key Things to Watch For in the Quarter
Analysts estimate that Facebook will report a 45% increase in both revenue and EPS to $7.8 billion and $1.12 respectively for 1Q17. Facebook reported earnings that beat analyst estimates in 2Q17 and the stock climbed around 3% in the weeks following the announcement. Facebook is trading up 30% from this time last year. The firm continues to dominate the global advertising market through its main website Facebook.com and its subsidiaries Instagram, WhatsApp, and Messenger. Analysts project that Facebook will realize a 12% market share of global digital advertising and a 30% market share of all display advertising in the U.S. by the end of 2018. CEO Mark Zuckerberg has a vision of globalization that continues to drive Facebook’s growth.
Square (SQ: $18.75)
Bull Market Report Target Price: $24
Bull Market Report Sell Price: $14
Earnings Date: Wednesday, 5:00 PM ET
Consensus: 1Q17
Revenues: $450 M
EPS: -$0.08
Year Ago Quarter Results
Revenues: $380 M
EPS: -$0.29
Key Things to Watch For in the Quarter
Analysts estimate that Square will report a revenue increase of 19% to $450 million and an improvement in the earnings deficit by nearly 80% to -$0.08 for 1Q17. Despite a rough start to the year in 2016, where shares fell nearly 30% following the 1Q16 earnings release, the stock has managed to provide investors with a 140% return from the stock’s 52-week low. Square announced last week that it would be acquiring a team from the struggling social app Yik Yak, a move that will bring a new perspective and high level talent to Square’s human resources.
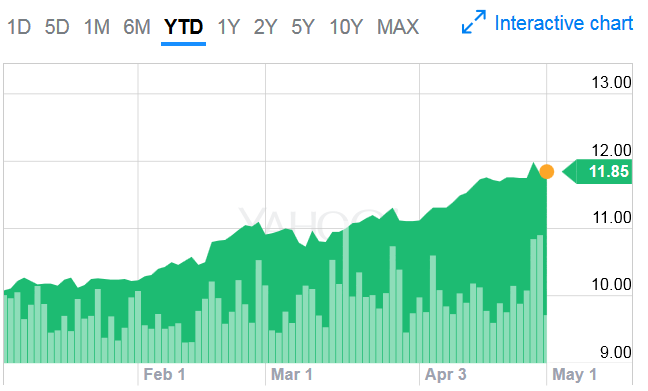
Annaly Capital Management (NLY: $11.85)
Bull Market Report Target Price: $12
Bull Market Report Sell Price: $9, hereby raised to $11.
Earnings Date: Wednesday, after market close (exact time unavailable)
Consensus: 1Q17
Revenues: $575 M
EPS: $0.30
Year Ago Quarter Results
Revenues: $390 M
EPS: $0.30
Key Things to Watch For in the Quarter
Things are going well at Annaly. The company met earnings estimates in the first 3 quarters of 2016 and beat estimates in the fourth quarter. The stock is up 13% over the past year and pays an astonishing 10% dividend. Market sentiment on Annaly is quite bullish; only 2% of its outstanding shares have been shorted (bet against). Insiders have increased their holdings by 5% over the past year, showing a positive outlook by the firm’s executive team.
We love this chart here:
Omega Healthcare Investors (OHI: $33)
Bull Market Report Target Price: $45
Bull Market Report Sell Price: $28
Earnings Date: Thursday, 10:00 AM ET
Consensus: 1Q17
Revenues: $200 M
EPS: $0.51
Year Ago Quarter Results
Revenues: $177 M
EPS: $0.29
Key Things to Watch For in the Quarter
Things are going well at Omega Healthcare Investors, and is paying a beautiful 7% dividend. When Omega missed analyst estimates in the first quarter of 2016 the stock dipped 10% before recovering to a 52-week high of $38. The stock currently trades at a P/E ratio of 18 (Healthcare Industry P/E: 60), which is very cheap, especially considering its high dividend yield.
Welltower (HCN: $71)
Bull Market Report Target Price: $84
Bull Market Report Sell Price: $60
Earnings Date: Friday, before market opening (exact time unavailable)
Consensus: 1Q17
Revenues: $1 B
EPS: $0.42
Year Ago Quarter Results
Revenues: $1 B
EPS: $0.42
Key Things to Watch For in the Quarter
In the first quarter of 2016, Welltower missed estimates by 3 cents and the stock still climbed 4% in the days following the announcement. Welltower is a REIT that invests in senior living and retirement homes. The stock is up 2% over the past year and we expect that it will continue to grow as the demand for senior living increases.
April 17, 2017
by Todd Shaver | Apr 17, 2017 | Monthly Newsletter Daily 6am if new
The Week Ahead
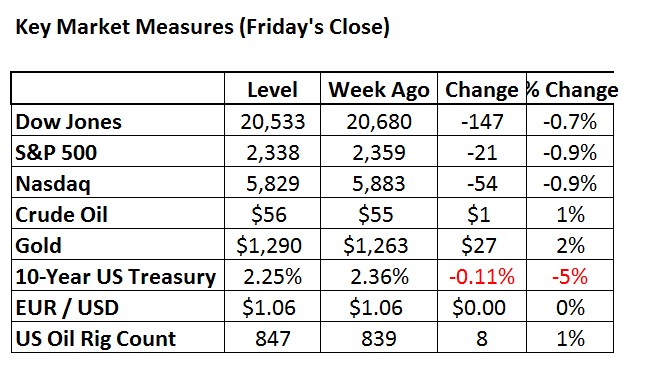
What did the Easter Bunny bring this April to the markets? Much lower interest rates! The 10-year dropped 11 bp to 2.25%. Who says interest rates are going up this year? Not us, for sure. Geopolitical worries are the primary culprit. North Korea, Syria, the Middle East, all the regular actors are to blame. The 10-year Treasury now rests around 5 month lows. Everyone will look to the Fed for guidance about where the markets are going. Interestingly, Trump is now praising Yellen in a public call for Fed consistency, which contradicts his accusations on the campaign trail that she was artificially manipulating the economy in a detrimental way. Hmmm…does Trump see an opportunity to take advantage of low borrowing costs for his $1 trillion infrastructure plan? His Treasury Secretary Steven Mnuchin has publicly expressed interest in doing big time deals for 100 year bonds. And we applaud this. We’ll have to wait and see.
There is always a bull market right here at The Bull Market Report! This week we highlight the following securities: Shopify, VMware, Amazon, Annaly, Apple, and Tesla.
Highlights From The Past Week
Watchful Eye On North Korea. US officials are saying the Trump administration is focusing its North Korea strategy on tougher economic sanctions, possibly including and oil embargo, banning its airline, intercepting cargo ships, and punishing Chinese banks doing business with Pyongyang. According to one official, US President Donald Trump has approved a preliminary broad approach on North Korea and asked his national security team to craft a more detailed framework for new international sanctions and other actions. The official said the administration is considering an array of stiffer sanctions that could be applied on a "sliding scale," proportionate to North Korean actions. Some steps could be applied unilaterally, with others through the United Nations.
Business Returning to the Center Stage in the USA. Business leaders are gaining more and more influence in Trump's White House. Most recently, Jared Kushner, the president's son-in-law, is trying to orchestrate more power for National Economic Council Director Gary Cohn while dampening the influence of chief strategist Steve Bannon. It is quiet the change in scenery to see Washington acting as a friend to business led by accomplished business people. All good news for the markets.
Infrastructure Bill On The Horizon. One of Trump's top policy advisers said the timing of the President's $1 trillion infrastructure package is still up in the air as the administration considers its best path forward. D.J. Gribbin, special assistant to the president for infrastructure policy, said the timeline will hinge on whether it moves as a standalone measure or if it is attached to another legislative priority. It adds that they are still crafting the infrastructure measure. Transportation Secretary Chao said the package could be unveiled as soon as next month. We can’t wait.
BMR Companies and Commentary
Shopify (SHOP: $71, +4%, all price changes in this report are for the past week)
Shopify had a solid week as talks of a takeover swirled. If true, we could see some very nice upside in the near-term. If not, that’s fine with us, as we still like the company’s fundamentals and prospects. Bottom line, Shopify still has room to run whether there is a takeover. Let’s re-visit why.
One can hardly kick back on the couch and watch CNBC or browse through your favorite financial publication these days for more than a few minutes before you come across a discussion of Amazon, as the online Retail juggernaut has skyrocketed to become an American business behemoth. And rightfully so.
For investors who want to capitalize on the undeniable secular growth trend of eCommerce, but who either missed the boat on Amazon or are wary of its nosebleed valuation, is there another road less traveled that they could embark on to get exposure to the eCommerce tidal wave? One that has impressive momentum and an ascendant stock price, but just not as frothy of a gain as Amazon? Yes there is. That’s Shopify.
Shopify not long ago announced its full-year financial results for 2016, and boasted 90% revenue growth and 99% growth in gross merchandise volume, (a term used in online retailing to indicate a total sales dollar value for merchandise sold through a particular marketplace over a certain time frame.) As an added bonus, Shopify's “Sell on Amazon” integration was made generally available to merchants in December. This mean Shopify now seamlessly connects store owners to the millions of customers searching for products to buy on Amazon, and merchants can now conveniently manage their product catalog for their eCommerce website, retail store, Amazon store, and other sales channels all in one place. This is big time! Since this integration just took place in December, we are only at the tip of the iceberg in terms of benefits and synergies from the move for Shopify.
BMR Take: The consensus calls for Shopify to more than double revenue from $600 million this year to $1.4 billion by 2020. This kind of explosive growth could cause the stock to double over the same period.
Amazon (AMZN: $884, down 1%)
A new week; Another big move brewing for Amazon. It is said that the eCommerce giant considered internally whether Whole Foods would help invigorate its nearly decade-long push into groceries. That is, Amazon kicked around the idea of buying the grocery chain!
Whole Foods has long been seen as a buyout target. Activist investor Jana Partners set off a new wave of speculation this week when it acquired a stake and urged the company to evaluate a sale. With a market valuation of $11 billion, the ailing organic-food retailer would be a powerful acquisition for Amazon -- dwarfing its 2009 purchase of online shoe retailer Zappos for about $1.2 billion. But the deal would turn Amazon into a grocery giant overnight and help it sideline Instacart, a startup that delivers grocery orders from Whole Foods stores in more than 20 states.
Jana has called for Whole Foods to overhaul its operations and brought in retail and food experts to help foster a turnaround. It also urged the company to consider a sale. A list of potential bidders includes Amazon, as well as traditional grocery chains such as Kroger and Albertsons. Whole Foods remains an attractive asset, even after a sales slump and the loss of market share to mainstream supermarkets, because the brand is strong and could be leveraged into something big.
BMR Take: Amazon and CEO Jeff Bezos are winning at everything. Why not grocery? Current Street earnings estimates call for $27 per share by 2020. With so much growth and strong earnings potential, the shares are compelling here.
Annaly Capital Management (NLY: $11.63, +5%)
Looking for yield in this market? Look here! Annaly Capital Management is a top pick in the Mortgage REIT sector.
Let’s review some of the reasons to like Annaly. Home price gains were up 6% in latest report from Case-Shiller, showing acceleration in home price increases. Tight supplies and rising prices may be deterring some people from trading up to a larger house, further aggravating supplies because fewer people are selling their homes. This is a good trend for Annaly. Annaly owns mortgages so rising home prices means the credit risk of owning the bonds is safer.
Annaly has a broad exposure across the US unlike other competitors more narrowly focused on only a particular market like New York. Yet another reason to like Annaly.
BMR Take: With a yield of 10.6% and a track record of over 20 years doing this, we continue to pound the table on Annaly. Look at this stock – up from $10.12 in mid-January in the midst of a strong interest rate rise with EVERY pundit saying that Annaly will be impacted sharply with the higher rates. Boy oh boy where they ever wrong. And boy oh boy were we ever right. Of course we’ve been saying this since we founded The Bull Market Report in 1998!
Apple (AAPL: $141, -2%)
Apple to buy Disney? Now that’s exciting! It could be more realistic than you think. Apple has the cash to pull off a $200 billion-plus takeover of Disney — creating a company worth $1 trillion with “almost limitless opportunities in content and technology.
A combined Apple-Disney would create an instant competitor to Netflix that would take advantage of the Mouse House’s content and Apple’s user base. Other benefits include: integrating Apple consumer tech as experiences in Disney’s theme parks; and landing global streaming sports rights for ESPN via Disney and Apple distribution and a strong balance sheet. Content is a major focus for Apple, target size is not an issue, and Disney offers an avenue to diversify away from hardware without diluting the strong Apple brand.
The M&A rumor mill got new grist last fall, when Apple chief Tim Cook told analysts that he was “open to acquisitions of any size.” In addition, Apple execs met with Time Warner honchos in 2015 in a discussion that raised the possibility of a merger - before AT&T moved on its $85 billion bid for Time Warner,
Per one analyst’s estimates, the merger of Apple and Disney would be highly accretive to earnings, to the tune of a 15%-20% increase in earnings per share based on the presumed 40% premium deal price and Disney’s low debt load. Nice!
BMR Take: We say it every week and we’ll say it again. Apple is really cheap compared to the current EPS outlook for this year of nearly $9. And all that cash put to good use through buying a storied franchise like Disney could be an exciting catalyst/prospect for the company.
Tesla (TSLA: $306, flat)
Tesla is a new entrant into the automobile, solar and battery storage businesses. Since Tesla’s current revenue is roughly 99% automobile related and, due to the Model 3 introduction and projected sales, this ratio will likely remain similar for quite some time. Thus, Tesla is an auto manufacturer, plain and simple. Panasonic supplies Tesla with batteries. Other companies provide Tesla with electric motors, tires, wheels, etc. Thus, with a few extraneous business lines, Tesla designs and assembles cars. Until Tesla’s battery storage business and solar equipment business become majority contributors, it will remain viewed as an auto company.
The good news is that’s okay!
Tesla CEO Elon Musk says his company will unveil its electric tractor-trailer truck this September, calling the vehicle “seriously next level” and praising the Tesla team for doing “an amazing job.” He also revealed that Tesla will show off an electric pickup truck in 18 to 24 months. Awesome innovation.
BMR Take: Street estimates call for sales growth from $7 billion last year to $11 billion this year to $33 billion in 2020. This is an exciting time for the business and the stock.
Note that Tesla was upgraded by Piper Jaffray from a "neutral" rating to an "overweight" rating last week. They now have a $368 price target on the stock, up previously from $223. We have a $325 Price Target on the stock.
Netflix (NFLX:$143, flat) had its price objective hoisted by Cowen from $165 to $170 in a research note released on Tuesday. Our Price Target is $165.
Upcoming Economic News
FRIDAY, APRIL 14 (Yes, this was on Friday – Good Friday)
Consumer Price Index
For March
Forecast: -0.1%
Actual: -0.1%
The Consumer Price Index was forecast to fall 0.1% in March following a 0.1% gain in February and 0.6% increase in January. It did. This was the first decline in the CPI since February 2016. Energy prices were a net drag on the CPI in March. The CPI for food and beverages rose 0.2% in February, the strongest since September 2013.
Retail Sales (This too was announced on Friday the 14th.)
For March
Forecast: -0.3%
Actual: -0.2%
Consensus expected retail sales to have dropped 0.3% in March following a 0.1% gain in February and 0.6% increase in January. Results were slightly better than expected. We believe weather was likely a small negative for sales. Non-store sales (online) have been contributing more to growth in retail sales recently. Already released data showed that unit vehicle sales dropped 5.5% in March and shaved 0.4% off total retail sales growth.
Tuesday, April 18th
Housing Starts
Period: March
8:30 AM
Consensus: 1,245,000
Prior: 1,288,000
Housing starts should continue to signal a healthy economy. The data reveals the number of housing units started in the United States. The U.S. Census Bureau's New Residential Construction release provides statistics on the construction of new privately-owned residential structures in the United States.
Thursday, April 20th
Leading Indicators
Period: March
10:00 AM
Consensus: 0.3%
Prior: 0.6%
This one is interesting to watch. Everybody is so focused on trying to figure out what direction the markets are heading. This is one of the key metrics that tells us. Leading indicators are economic series that tend to change direction ahead of shifts in the business cycle. There are 10 components of the U.S. Leading Composite Indicator published by The Conference Board. The index is constructed by averaging the individual components in order to smooth out a good part of the volatility of the individual series. Historically, the cyclical turning points in the leading index have occurred before those in actual economic activity.
Facebook Adds a Million Advertisers in 7 Months
There is a big move going on in the digital marketing world that many are not aware of. More than 5 million businesses are advertising on Facebook each month, Reuters reports. That is up from 4 million monthly advertisers in September 2016, and the 3 million monthly advertisers it had in March 2016. Significant upside remains as Facebook’s 5 million advertisers are less than 10% of the 65 million businesses that are active on the network.
Facebook is one of two undisputed leaders in digital advertising. Alongside Google, the company is expected to generate about half of online ad spend in 2018. Facebook generated close to $27 billion, and Google close to $80 billion, in ad revenue last year.
Small and midsize brands are flocking to advertise on Facebook. Big brands may drive the bulk of revenue in advertising markets, but there is still ample opportunity for growth with the smaller brand advertisers. The sheer volume of advertisers on Facebook reflects the company’s success in attracting these smaller firms its platform.
A few industries are generating the bulk of Facebook ad spend. E-commerce and Retail, and Entertainment and Media are the biggest industries represented in Facebook's advertiser base.
Facebook is doing a great job at building its advertising base overseas - over 75% of advertisers are outside of the US. India, Thailand, Brazil, Mexico and Argentina are the fastest-growing markets.
Mobile is big, as you know. Almost 50% of advertisers create ads on mobile devices. More than 90% of Facebook users access the network via mobile. And mobile advertising accounts for 85% of ad revenue. Creating mobile-first experiences is particularly key in emerging markets.
The biggest users of Facebook are the US at 220 million; India at 210 million; Brazil at 120 million; Indonesia at 75 million and Mexico at 65 million.
Our Take on SNAP
Snap (SNAP: $20) went public at $17 in early March and promptly opened at $24. They raised $3.4 billion making it the largest IPO since Alibaba went public in 2014, raising $20 billion. The market cap is now $23 billion and all of this for a company with no revenue in 2015, $400 million in 2016 and losses of $500 million in 2016. Ouch. More losses than revenues. Not a good business model.
Snapchat has grabbed the attention of a generation of younger smartphone users, who post and share photos and videos on the app that can disappear after a set amount of time. The app - developed by Stanford University students, two of whom are still executives at Snap had 160 million daily active users as of December 2016,
BMR Take: We are steering clear of this one. One might compare this a bit to Facebook, but Facebook had huge revenues and real earnings when it went public, and the growth since then has been phenomenal as you know. The Snap IPO has invigorated the IPO market and Wall Street is generally pleased, but for this company to get to $40 or $50 a share, we will have to see revenues of 10-20 times current levels, and big profitability, both of which may never materialize. We are steering clear.
The High Yield Report
By Michael Foster
Special to The Bull Market Report
It was a short week, but an eventful one. Already we’re seeing tons of articles about how the stock market is in crisis. Looking at volatility, there seems to be reason to think this; we went from a VIX of about 10 to nearly 16 in days. This means there is more caution in the market, and expectations of a short-term downturn. However, those expectations will disappear as they always do and the bull market will return as it always does.
We can already see pockets of optimism in the high yield world. In fact, We’d go so far as to say we’re beginning to see a sector rotation among investors that is benefitting parts of the high yield universe.
Before we get into that, though, let’s look at who is not winning. The UBS BDC ETF (BDCS: $23, down 1%) saw a soft week that was no worse than the broader market, but definitely was not good. This move is actually not that bad, considering that BDCs have had a massive run-up for months and has driven the entire sector higher. One well-known BDC analyst recently pointed out that the sector has beaten the S&P 500 since the start of 2014. This kind of cherry-picking time series doesn’t tell us much, but it does remind us that BDCs had an extremely vicious decline in 2013 and have been recovering for years since then as the market readjusts its understanding of what a rising rate environment means for these assets. It also means that the bargains in this odd corner of the business lending universe have dried up. That’s a shame, because The Bull Market Report is eagerly awaiting adding a BDC to the high yield portfolio, but this week’s 1% decline isn’t enough for us to do it. In fact, the recent decline may indicate that weaker prices might be just on the horizon, indicating a need to buy some BDCs when the price is right. Stay tuned as we keep focusing on this story.
So if BDCs aren’t benefiting from the fall in stocks this week, who is?
The answer is obvious: REITs. The SPDR Dow Jones REIT ETF (RWR: $94) was mostly flat for the last four days but is up 1% from last Friday - and comparing REITs to a week ago is really key here, because the momentum in REITs really started to kick off on Monday and has stayed strong with the many REITs in the Bull Market Report portfolio.
Let’s start with Kimco Realty (KIM: $22, up 4%), which shot up at the start of the week and has maintained its higher price level. Kimco is expected to report earnings by the end of this month, and analysts’ expectations are strong. Despite expectations of a 1% revenue decline, FFO expectations put Kimco’s dividend coverage in the 140% range. This means that Kimco is expected to far cover its dividend and have room to increase payouts. That should mean the company should be a low yielder, but this company’s 5% dividend yield indicates market expectations of risk are growing. Why the disconnect?
Simple: the decline in Retail.
Long story short, shopping malls are collapsing. The high-profile news of bankruptcies at Sears and JCPenny are making investors grow increasingly confident that the Retail sector is an apocalypse that no investor should come near. Of course these people are forgetting just how strong things are for Whole Foods, upscale outlet malls, Apple stores, and several other corners of the retail market that Kimco just happens to be focused on. In fact, Kimco’s tenants tend to be the most well-heeled and revenue-safe firms in the Retail landscape, so this collapse has little impact on them. Their occupancy rates have remained near 99% throughout. And although these issues are now high profile, they’ve been top of mind for Kimco management for a decade - and management has addressed these issues both in their strategic decisions and in their earnings calls.
In short, Kimco is not affected by the slowdown of the suburban American shopping mall.
Investors don’t know this, of course, so they’re throwing out the baby with the bathwater. That means now is a buying opportunity unlike no other. In fact, Kimco looks like one of the most attractive options for high yield investors. Of all our picks, Kimco looks like one of the most undervalued.
A similar story hit Government Properties Trust (GOV: $22, up 3%) over the past week, making it one of the top performers in a well-performing sector. Government Properties is heavily exposed to federal government tenants, and lower government spending has been seen as a real risk for the company. As a result of this fear, the company has looked to diversify by investing in office space that would be more insulated from the expected weaker demand in government properties. That has created a swiftly diversified portfolio that also has firm dividend coverage, but the market never really saw it that way. Instead, Government Properties is always seen as a risky option, which is why it often traded at an 11% yield. That’s what the stock was yielding when we first recommended it, and now it’s trading at less than an 8% yield, thanks entirely to capital gains. Sadly, that means buying more of Government Properties isn’t the greatest idea right now, but it does remain a solid hold thanks to its capital gains. The last week’s recent 3% jump is likely just the beginning; this company has a much safer income stream than its yield would indicate, meaning price gains are likely to come. We recommend staying in the stock to enjoy those gains as demand for REITs continues to rise.
Our other REITs did well this week too. Digital Realty Trust (DLR: $110, up 1%), Omega Healthcare Investors (OHI: $34, up 1%), and Care Capital Properties (CCP: $27, up 1%) all saw modest gains largely as a result of the continuation of a recent trend. CCP and OHI have been recovering recently from an oversold situation in healthcare REITs - in short, the market sold way too many of these because they thought a variety of risks (interest rates, cuts to Medicaid and Obamacare, etc.) would damage these firms permanently. These were considered long-tail risks not priced into the stocks, and yet these companies are doing fine and the risks the market has perceived are not materializing. In fact, they may never be real concerns for the companies. As a result, the stocks have no place to go but up. While we’re sitting on double-digit gains for Care Capital, we see more room to grow and thus recommend holding tight on these firms.
Finally, a word on municipal bonds. The iShares S&P National AMT-Free Municipal Bond Fund (MUB: $110, flat) didn’t move much this week although our muni bond picks did. Invesco Municipal Trust (VKQ: $13, up 1%) and the Nuveen AMT-Free Fund (NVG: $15, up 1%) outpaced the market, and we expect further gains in the municipal bond market to drive both of these funds higher. What’s going on is quite simply secular demand for munis returning to the market, largely a result of the higher uncertainty and fear that is driving stocks lower. In short, many retail investors are getting skittish and feel a need to pull out of risk and get lower risk assets.
This is driving a broad base of investors to demand more municipal bonds, driving up their value and in turn driving up the net asset values of these and other municipal bond funds. Since munis are far undervalued again due to risks that were feared but are not materializing, there is a lot more room for these funds to rise in price before they’re fairly valued. Thus muni fund holders should enjoy the gains they’re getting now but shouldn’t sell yet; if the market stays afraid these funds are destined to rise considerably. If the market gets more courageous, these funds are still destined to rise (although perhaps at a slower pace) because they have been massively undervalued due to ridiculous fears about muni bonds that aren’t materializing. Either way, the direction is clear: Keep and hold these funds and wait for their pricing to better match their real value.
Good Investing,
Todd Shaver
Editor, Founder and CEO
The Bull Market Report
Since 1998
April 16, 2017
by Todd Shaver | Apr 16, 2017 | Weekly Newsletter 7pm Sunday
The Week Ahead
What did the Easter Bunny bring this April to the markets? Much lower interest rates! The 10-year dropped 11 bp to 2.25%. Who says interest rates are going up this year? Not us, for sure. Geopolitical worries are the primary culprit. North Korea, Syria, the Middle East, all the regular actors are to blame. The 10-year Treasury now rests around 5 month lows. Everyone will look to the Fed for guidance about where the markets are going. Interestingly, Trump is now praising Yellen in a public call for Fed consistency, which contradicts his accusations on the campaign trail that she was artificially manipulating the economy in a detrimental way. Hmmm…does Trump see an opportunity to take advantage of low borrowing costs for his $1 trillion infrastructure plan? His Treasury Secretary Steven Mnuchin has publicly expressed interest in doing big time deals for 100 year bonds. And we applaud this. We’ll have to wait and see.
There is always a bull market right here at The Bull Market Report! This week we highlight the following securities: Shopify, VMware, Amazon, Annaly, Apple, and Tesla.
Highlights From The Past Week
Watchful Eye On North Korea. US officials are saying the Trump administration is focusing its North Korea strategy on tougher economic sanctions, possibly including and oil embargo, banning its airline, intercepting cargo ships, and punishing Chinese banks doing business with Pyongyang. According to one official, US President Donald Trump has approved a preliminary broad approach on North Korea and asked his national security team to craft a more detailed framework for new international sanctions and other actions. The official said the administration is considering an array of stiffer sanctions that could be applied on a "sliding scale," proportionate to North Korean actions. Some steps could be applied unilaterally, with others through the United Nations.
Business Returning to the Center Stage in the USA. Business leaders are gaining more and more influence in Trump's White House. Most recently, Jared Kushner, the president's son-in-law, is trying to orchestrate more power for National Economic Council Director Gary Cohn while dampening the influence of chief strategist Steve Bannon. It is quiet the change in scenery to see Washington acting as a friend to business led by accomplished business people. All good news for the markets.
Infrastructure Bill On The Horizon. One of Trump's top policy advisers said the timing of the President's $1 trillion infrastructure package is still up in the air as the administration considers its best path forward. D.J. Gribbin, special assistant to the president for infrastructure policy, said the timeline will hinge on whether it moves as a standalone measure or if it is attached to another legislative priority. It adds that they are still crafting the infrastructure measure. Transportation Secretary Chao said the package could be unveiled as soon as next month. We can’t wait.
BMR Companies and Commentary
Shopify (SHOP: $71, +4%, all price changes in this report are for the week)
Shopify had a solid week as talks of a takeover swirled. If true, we could see some very nice upside in the near-term. If not, that’s fine with us, as we still like the company’s fundamentals and prospects. Bottom line, Shopify still has room to run whether there is a takeover. Let’s re-visit why.
One can hardly kick back on the couch and watch CNBC or browse through your favorite financial publication these days for more than a few minutes before you come across a discussion of Amazon, as the online Retail juggernaut has skyrocketed to become an American business behemoth. And rightfully so.
For investors who want to capitalize on the undeniable secular growth trend of eCommerce, but who either missed the boat on Amazon or are wary of its nosebleed valuation, is there another road less traveled that they could embark on to get exposure to the eCommerce tidal wave? One that has impressive momentum and an ascendant stock price, but just not as frothy of a gain as Amazon? Yes there is. That’s Shopify.
Shopify not long ago announced its full-year financial results for 2016, and boasted 90% revenue growth and 99% growth in gross merchandise volume, (a term used in online retailing to indicate a total sales dollar value for merchandise sold through a particular marketplace over a certain time frame.) As an added bonus, Shopify's “Sell on Amazon” integration was made generally available to merchants in December. This mean Shopify now seamlessly connects store owners to the millions of customers searching for products to buy on Amazon, and merchants can now conveniently manage their product catalog for their eCommerce website, retail store, Amazon store, and other sales channels all in one place. This is big time! Since this integration just took place in December, we are only at the tip of the iceberg in terms of benefits and synergies from the move for Shopify.
BMR Take: The consensus calls for Shopify to more than double revenue from $600 million this year to $1.4 billion by 2020. This kind of explosive growth could cause the stock to double over the same period.
VMware (VMW: $91, -1.6%)
VMware made some waves this week announcing intentions to acquire Wavefront, the leading metrics monitoring service for cloud and modern application environments. Terms were not disclosed. The transaction is expected to close in calendar Q217. VMware does not expect this transaction to have a material impact on its 2017 operating results. But don’t write off the deal as not important just because the financial impact isn’t going to be seen in the near-term.
Digital enterprises face challenges of a new order of magnitude when monitoring modern applications -- consisting of hundreds of microservices in containers with lifespans of seconds -- spread across private and public clouds. To identify and fix operational issues in these dynamic cross-cloud environments, developers need new instrumentation for their applications, and teams require sophisticated real-time analytics on their high-scale distributed systems to adapt to problems before they impact the business.
Wavefront provides metrics to optimize clouds and modern applications by delivering operational insights using millions of data points per second in real-time. Operators and developers can interrogate real-time data streams to discover new ways to address problems, identify bottlenecks, and test algorithms and hypotheses. A cloud-hosted service, Wavefront ingests, stores, visualizes, and alerts on streaming data from clouds and modern applications enabling superior operational performance. The service can measure, correlate, and analyze data across servers, devices, applications, end-user behavior, multiple public cloud and data center attributes, and business metrics. (Now that’s a mouthful.)
This is big news for the underlying story at VMware, which is most exciting given the company’s increasing presence in the cloud marketplace. For seven-plus years, VMware has invested in solutions featuring advanced metrics and analytics to help customers simplify and automate how they manage, monitor and troubleshoot services in dynamic virtual and cloud environments. As all these investment start paying off, we see VMware as a top pick for Technology investors.
BMR Take: The company is currently generating $5-6 of EPS annually. The current valuation seems like a bargain considering all the progress with the cloud business. Our Price Target is $95 which would be a 2-year high and a more than double from the $44 low it hit in February last year. If the stock hits $95, we are moving our Price Target up into triple-digits, especially if revenues continue to soar. You know what we say about revenues and earnings: Revenues first, then earnings.
Amazon (AMZN: $884, down 1%)
A new week; Another big move brewing for Amazon. It is said that the eCommerce giant considered internally whether Whole Foods would help invigorate its nearly decade-long push into groceries. That is, Amazon kicked around the idea of buying the grocery chain!
Whole Foods has long been seen as a buyout target. Activist investor Jana Partners set off a new wave of speculation this week when it acquired a stake and urged the company to evaluate a sale. With a market valuation of $11 billion, the ailing organic-food retailer would be a powerful acquisition for Amazon -- dwarfing its 2009 purchase of online shoe retailer Zappos for about $1.2 billion. But the deal would turn Amazon into a grocery giant overnight and help it sideline Instacart, a startup that delivers grocery orders from Whole Foods stores in more than 20 states.
Jana has called for Whole Foods to overhaul its operations and brought in retail and food experts to help foster a turnaround. It also urged the company to consider a sale. A list of potential bidders includes Amazon, as well as traditional grocery chains such as Kroger and Albertsons. Whole Foods remains an attractive asset, even after a sales slump and the loss of market share to mainstream supermarkets, because the brand is strong and could be leveraged into something big.
BMR Take: Amazon and CEO Jeff Bezos are winning at everything. Why not grocery? Current Street earnings estimates call for $27 per share by 2020. With so much growth and strong earnings potential, the shares are compelling here.
Annaly Capital Management (NLY: $11.63, +5%)
Looking for yield in this market? Look here! Annaly Capital Management is a top pick in the Mortgage REIT sector.
Let’s review some of the reasons to like Annaly. Home price gains were up 6% in latest report from Case-Shiller, showing acceleration in home price increases. Tight supplies and rising prices may be deterring some people from trading up to a larger house, further aggravating supplies because fewer people are selling their homes. This is a good trend for Annaly. Annaly owns mortgages so rising home prices means the credit risk of owning the bonds is safer.
Annaly has a broad exposure across the US unlike other competitors more narrowly focused on only a particular market like New York. Yet another reason to like Annaly.
BMR Take: With a yield of 10.6% and a track record of over 20 years doing this, we continue to pound the table on Annaly. Look at this stock – up from $10.12 in mid-January in the midst of a strong interest rate rise with EVERY pundit saying that Annaly will be impacted sharply with the higher rates. Boy oh boy where they ever wrong. And boy oh boy were we ever right. Of course we’ve been saying this since we founded The Bull Market Report in 1998!
Apple (AAPL: $141, -2%)
Apple to buy Disney? Now that’s exciting! It could be more realistic than you think. Apple has the cash to pull off a $200 billion-plus takeover of Disney — creating a company worth $1 trillion with “almost limitless opportunities in content and technology.
A combined Apple-Disney would create an instant competitor to Netflix that would take advantage of the Mouse House’s content and Apple’s user base. Other benefits include: integrating Apple consumer tech as experiences in Disney’s theme parks; and landing global streaming sports rights for ESPN via Disney and Apple distribution and a strong balance sheet. Content is a major focus for Apple, target size is not an issue, and Disney offers an avenue to diversify away from hardware without diluting the strong Apple brand.
The M&A rumor mill got new grist last fall, when Apple chief Tim Cook told analysts that he was “open to acquisitions of any size.” In addition, Apple execs met with Time Warner honchos in 2015 in a discussion that raised the possibility of a merger - before AT&T moved on its $85 billion bid for Time Warner,
Per one analyst’s estimates, the merger of Apple and Disney would be highly accretive to earnings, to the tune of a 15%-20% increase in earnings per share based on the presumed 40% premium deal price and Disney’s low debt load. Nice!
BMR Take: We say it every week and we’ll say it again. Apple is really cheap compared to the current EPS outlook for this year of nearly $9. And all that cash put to good use through buying a storied franchise like Disney could be an exciting catalyst/prospect for the company.
Tesla (TSLA: $306, flat)
Tesla is a new entrant into the automobile, solar and battery storage businesses. Since Tesla’s current revenue is roughly 99% automobile related and, due to the Model 3 introduction and projected sales, this ratio will likely remain similar for quite some time. Thus, Tesla is an auto manufacturer, plain and simple. Panasonic supplies Tesla with batteries. Other companies provide Tesla with electric motors, tires, wheels, etc. Thus, with a few extraneous business lines, Tesla designs and assembles cars. Until Tesla’s battery storage business and solar equipment business become majority contributors, it will remain viewed as an auto company.
The good news is that’s okay!
Tesla CEO Elon Musk says his company will unveil its electric tractor-trailer truck this September, calling the vehicle “seriously next level” and praising the Tesla team for doing “an amazing job.” He also revealed that Tesla will show off an electric pickup truck in 18 to 24 months. Awesome innovation.
BMR Take: Street estimates call for sales growth from $7 billion last year to $11 billion this year to $33 billion in 2020. This is an exciting time for the business and the stock.
Note that Tesla was upgraded by Piper Jaffray from a "neutral" rating to an "overweight" rating last week. They now have a $368 price target on the stock, up previously from $223. We have a $325 Price Target on the stock.
Netflix (NFLX:$143, flat) had its price objective hoisted by Cowen from $165 to $170 in a research note released on Tuesday. Our Price Target is $165.
Upcoming Economic News
FRIDAY, APRIL 14 (Yes, this was on Friday – Good Friday)
Consumer Price Index
For March
Forecast: -0.1%
Actual: -0.1%
The Consumer Price Index was forecast to fall 0.1% in March following a 0.1% gain in February and 0.6% increase in January. It did. This was the first decline in the CPI since February 2016. Energy prices were a net drag on the CPI in March. The CPI for food and beverages rose 0.2% in February, the strongest since September 2013.
Retail Sales (This too was announced on Friday the 14th.)
For March
Forecast: -0.3%
Actual: -0.2%
Consensus expected retail sales to have dropped 0.3% in March following a 0.1% gain in February and 0.6% increase in January. Results were slightly better than expected. We believe weather was likely a small negative for sales. Non-store sales (online) have been contributing more to growth in retail sales recently. Already released data showed that unit vehicle sales dropped 5.5% in March and shaved 0.4% off total retail sales growth.
Tuesday, April 18th
Housing Starts
Period: March
8:30 AM
Consensus: 1,245,000
Prior: 1,288,000
Housing starts should continue to signal a healthy economy. The data reveals the number of housing units started in the United States. The U.S. Census Bureau's New Residential Construction release provides statistics on the construction of new privately-owned residential structures in the United States.
Thursday, April 20th
Leading Indicators
Period: March
10:00 AM
Consensus: 0.3%
Prior: 0.6%
This one is interesting to watch. Everybody is so focused on trying to figure out what direction the markets are heading. This is one of the key metrics that tells us. Leading indicators are economic series that tend to change direction ahead of shifts in the business cycle. There are 10 components of the U.S. Leading Composite Indicator published by The Conference Board. The index is constructed by averaging the individual components in order to smooth out a good part of the volatility of the individual series. Historically, the cyclical turning points in the leading index have occurred before those in actual economic activity.
Notes at the Margin
By Phil K. Verleger, Jr.
Former Director of the Office of Energy Policy
at the United States Department of Treasury
This item published by Platts Global Alert first caught my eye: “The Permian Basin [in Texas] is going to become the largest oil field in the world, surpassing the legendary Ghawar field of Saudi Arabia,” Bill Marko, managing director of Jefferies, said on the sidelines of the conference.
The basin holds an estimated 210 billion barrels of oil that will become economically recoverable in the future, or 325 billion barrels of oil equivalent when oil and natural gas liquids are counted, he said.
The 210 billion barrel estimate caught my attention. After all, Saudi Arabia’s reserves are put at “only” 260 billion barrels per the BP Statistical Review of World Energy. It is hard to believe that one US field has oil reserves equal to 80% of Saudi reserves.
The US Energy Information Administration recently published a short-term outlook predicting an 8% increase in US production from 8.8 million barrels per day in December 2016 to 9.5 million barrels per day in December 2017. Given recent trends, the estimate will likely need to be revised again, perhaps to 10 million barrels per day or more.
BMR Take: Phil – Knowing you the way I do, this is your way of jumping up and down and waving your arms like a madman. This is certainly big news. We have seen it coming to a certain extent but when you put it in writing the way you do, this is making us stand up and take notice. There are big changes afoot in the energy world. We would venture to say that $100 oil is not going to be seen for a long, long time to come. Prepare accordingly.
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
They honored Arnold Palmer this past weekend at the Masters Golf Tournament. He was one of the few greats who turned the game into a hugely popular spectator's sport. One of his best known quotes is: "Golf is deceptively simple and endlessly complicated."
As words of wisdom go, we can't think of a quote that could be any more applicable to the stock market. As simple as "buy low, sell high," to as complicated as the blackboard full of equations in Einstein's office. Our formula for investment success has always been "Success = preparation, recognition of value and proper seizing of opportunity." Preparation is fairly simple in the sense that it's mostly reading. But it takes a lot of reading and research on an endless basis. The complicated part is filtering out all the "noise" and learning what resources you can rely on and trust. Overall, we are believers in the KISS principle when applying our formula because we have learned over the years that the more complicated the investment process becomes, the harder it is to stay on track.
If you want to keep it as simple as possible, just think of one word - earnings. Good earnings signal a rising stock market. Weak earnings are normally a forecast of a weak or falling market.
That's where we are today. First quarter earnings season kicked off last week with several big banks reporting. First quarter earnings growth is expected to be 10%, the best since 2014. Sales growth, a laggard in the financial recovery, is expected to grow by 7.5% - its best pace since 2011! (Source: Thomson Reuters)
In addition to corporate earnings, investors will also likely monitor the economic calendar to be sure there is no unexpected deterioration in important statistical areas. And if you want to complicate it just a bit, throw in the fact that investors will probably just continue to wait for word from Washington on their pro-growth agenda. When that will actually be announced, and how long it takes to pass, are currently unknown and unknowable. So, while we may be stuck in a trading range pending the agenda results, earnings should provide a simple-to-understand reason to expect that the market will eventually work its way to a higher level.
Facebook Adds a Million Advertisers in 7 Months
There is a big move going on in the digital marketing world that many are not aware of. More than 5 million businesses are advertising on Facebook each month, Reuters reports. That is up from 4 million monthly advertisers in September 2016, and the 3 million monthly advertisers it had in March 2016. Significant upside remains as Facebook’s 5 million advertisers are less than 10% of the 65 million businesses that are active on the network.
Facebook is one of two undisputed leaders in digital advertising. Alongside Google, the company is expected to generate about half of online ad spend in 2018. Facebook generated close to $27 billion, and Google close to $80 billion, in ad revenue last year.
Small and midsize brands are flocking to advertise on Facebook. Big brands may drive the bulk of revenue in advertising markets, but there is still ample opportunity for growth with the smaller brand advertisers. The sheer volume of advertisers on Facebook reflects the company’s success in attracting these smaller firms its platform.
A few industries are generating the bulk of Facebook ad spend. E-commerce and Retail, and Entertainment and Media are the biggest industries represented in Facebook's advertiser base.
Facebook is doing a great job at building its advertising base overseas - over 75% of advertisers are outside of the US. India, Thailand, Brazil, Mexico and Argentina are the fastest-growing markets.
Mobile is big, as you know. Almost 50% of advertisers create ads on mobile devices. More than 90% of Facebook users access the network via mobile. And mobile advertising accounts for 85% of ad revenue. Creating mobile-first experiences is particularly key in emerging markets.
The biggest users of Facebook are the US at 220 million; India at 210 million; Brazil at 120 million; Indonesia at 75 million and Mexico at 65 million.
Our Take on SNAP
Snap (SNAP: $20) went public at $17 in early March and promptly opened at $24. They raised $3.4 billion making it the largest IPO since Alibaba went public in 2014, raising $20 billion. The market cap is now $23 billion and all of this for a company with no revenue in 2015, $400 million in 2016 and losses of $500 million in 2016. Ouch. More losses than revenues. Not a good business model.
Snapchat has grabbed the attention of a generation of younger smartphone users, who post and share photos and videos on the app that can disappear after a set amount of time. The app - developed by Stanford University students, two of whom are still executives at Snap had 160 million daily active users as of December 2016,
BMR Take: We are steering clear of this one. One might compare this a bit to Facebook, but Facebook had huge revenues and real earnings when it went public, and the growth since then has been phenomenal as you know. The Snap IPO has invigorated the IPO market and Wall Street is generally pleased, but for this company to get to $40 or $50 a share, we will have to see revenues of 10-20 times current levels, and big profitability, both of which may never materialize. We are steering clear.
The High Yield Report
By Michael Foster
Special to The Bull Market Report
It was a short week, but an eventful one. Already we’re seeing tons of articles about how the stock market is in crisis. Looking at volatility, there seems to be reason to think this; we went from a VIX of about 10 to nearly 16 in days. This means there is more caution in the market, and expectations of a short-term downturn. However, those expectations will disappear as they always do and the bull market will return as it always does.
We can already see pockets of optimism in the high yield world. In fact, We’d go so far as to say we’re beginning to see a sector rotation among investors that is benefitting parts of the high yield universe.
Before we get into that, though, let’s look at who is not winning. The UBS BDC ETF (BDCS: $23, down 1%) saw a soft week that was no worse than the broader market, but definitely was not good. This move is actually not that bad, considering that BDCs have had a massive run-up for months and has driven the entire sector higher. One well-known BDC analyst recently pointed out that the sector has beaten the S&P 500 since the start of 2014. This kind of cherry-picking time series doesn’t tell us much, but it does remind us that BDCs had an extremely vicious decline in 2013 and have been recovering for years since then as the market readjusts its understanding of what a rising rate environment means for these assets. It also means that the bargains in this odd corner of the business lending universe have dried up. That’s a shame, because The Bull Market Report is eagerly awaiting adding a BDC to the high yield portfolio, but this week’s 1% decline isn’t enough for us to do it. In fact, the recent decline may indicate that weaker prices might be just on the horizon, indicating a need to buy some BDCs when the price is right. Stay tuned as we keep focusing on this story.
So if BDCs aren’t benefiting from the fall in stocks this week, who is?
The answer is obvious: REITs. The SPDR Dow Jones REIT ETF (RWR: $94) was mostly flat for the last four days but is up 1% from last Friday - and comparing REITs to a week ago is really key here, because the momentum in REITs really started to kick off on Monday and has stayed strong with the many REITs in the Bull Market Report portfolio.
Let’s start with Kimco Realty (KIM: $22, up 4%), which shot up at the start of the week and has maintained its higher price level. Kimco is expected to report earnings by the end of this month, and analysts’ expectations are strong. Despite expectations of a 1% revenue decline, FFO expectations put Kimco’s dividend coverage in the 140% range. This means that Kimco is expected to far cover its dividend and have room to increase payouts. That should mean the company should be a low yielder, but this company’s 5% dividend yield indicates market expectations of risk are growing. Why the disconnect?
Simple: the decline in Retail.
Long story short, shopping malls are collapsing. The high-profile news of bankruptcies at Sears and JCPenny are making investors grow increasingly confident that the Retail sector is an apocalypse that no investor should come near. Of course these people are forgetting just how strong things are for Whole Foods, upscale outlet malls, Apple stores, and several other corners of the retail market that Kimco just happens to be focused on. In fact, Kimco’s tenants tend to be the most well-heeled and revenue-safe firms in the Retail landscape, so this collapse has little impact on them. Their occupancy rates have remained near 99% throughout. And although these issues are now high profile, they’ve been top of mind for Kimco management for a decade - and management has addressed these issues both in their strategic decisions and in their earnings calls.
In short, Kimco is not affected by the slowdown of the suburban American shopping mall.
Investors don’t know this, of course, so they’re throwing out the baby with the bathwater. That means now is a buying opportunity unlike no other. In fact, Kimco looks like one of the most attractive options for high yield investors. Of all our picks, Kimco looks like one of the most undervalued.
A similar story hit Government Properties Trust (GOV: $22, up 3%) over the past week, making it one of the top performers in a well-performing sector. Government Properties is heavily exposed to federal government tenants, and lower government spending has been seen as a real risk for the company. As a result of this fear, the company has looked to diversify by investing in office space that would be more insulated from the expected weaker demand in government properties. That has created a swiftly diversified portfolio that also has firm dividend coverage, but the market never really saw it that way. Instead, Government Properties is always seen as a risky option, which is why it often traded at an 11% yield. That’s what the stock was yielding when we first recommended it, and now it’s trading at less than an 8% yield, thanks entirely to capital gains. Sadly, that means buying more of Government Properties isn’t the greatest idea right now, but it does remain a solid hold thanks to its capital gains. The last week’s recent 3% jump is likely just the beginning; this company has a much safer income stream than its yield would indicate, meaning price gains are likely to come. We recommend staying in the stock to enjoy those gains as demand for REITs continues to rise.
Our other REITs did well this week too. Digital Realty Trust (DLR: $110, up 1%), Omega Healthcare Investors (OHI: $34, up 1%), and Care Capital Properties (CCP: $27, up 1%) all saw modest gains largely as a result of the continuation of a recent trend. CCP and OHI have been recovering recently from an oversold situation in healthcare REITs - in short, the market sold way too many of these because they thought a variety of risks (interest rates, cuts to Medicaid and Obamacare, etc.) would damage these firms permanently. These were considered long-tail risks not priced into the stocks, and yet these companies are doing fine and the risks the market has perceived are not materializing. In fact, they may never be real concerns for the companies. As a result, the stocks have no place to go but up. While we’re sitting on double-digit gains for Care Capital, we see more room to grow and thus recommend holding tight on these firms.
Finally, a word on municipal bonds. The iShares S&P National AMT-Free Municipal Bond Fund (MUB: $110, flat) didn’t move much this week although our muni bond picks did. Invesco Municipal Trust (VKQ: $13, up 1%) and the Nuveen AMT-Free Fund (NVG: $15, up 1%) outpaced the market, and we expect further gains in the municipal bond market to drive both of these funds higher. What’s going on is quite simply secular demand for munis returning to the market, largely a result of the higher uncertainty and fear that is driving stocks lower. In short, many retail investors are getting skittish and feel a need to pull out of risk and get lower risk assets.
This is driving a broad base of investors to demand more municipal bonds, driving up their value and in turn driving up the net asset values of these and other municipal bond funds. Since munis are far undervalued again due to risks that were feared but are not materializing, there is a lot more room for these funds to rise in price before they’re fairly valued. Thus muni fund holders should enjoy the gains they’re getting now but shouldn’t sell yet; if the market stays afraid these funds are destined to rise considerably. If the market gets more courageous, these funds are still destined to rise (although perhaps at a slower pace) because they have been massively undervalued due to ridiculous fears about muni bonds that aren’t materializing. Either way, the direction is clear: Keep and hold these funds and wait for their pricing to better match their real value.
Good Investing,
Todd Shaver
Editor, Founder and CEO
The Bull Market Report
Since 1998
April 2, 2017
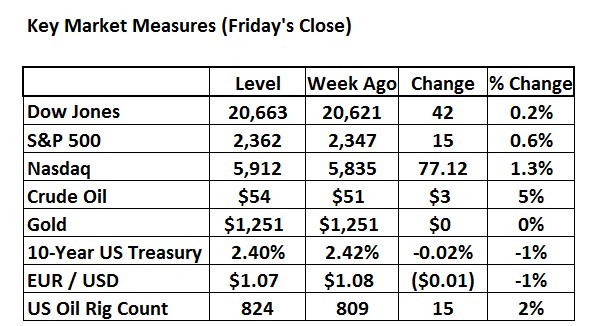
by Todd Shaver | Apr 2, 2017 | Weekly Newsletter 7pm Sunday
The Week Ahead
This past week was more of the same calm and collected march higher for the stock market. Optimism is at record highs for business and consumers. There are pockets of softness in the economy, like historically low labor force participation and declining commercial and industrial loan activity at banks, but with the credit market dealing with the stresses of low interest rates the stock market just keeps drawing interest from investors. We now head into April after what was a strong 1Q 2017. The consensus estimate for 2017 S&P 500 EPS is currently $129 revealing a reasonable 18x P/E multiple for today’s overall stock market.
The first quarter closed Friday with the S&P 500 notching its best quarter since 2015, up 5.5%. The Nasdaq had its best quarter since 2013, up 10%. The Volatility Index (^VIX), the fear gauge, posted its second lowest quarterly average in history at 12.37. And listen to this, the average daily percentage change for the Dow Jones during the quarter was the lowest since 1965. Things are CALM out there!
Apple (AAPL: $144, up 2%. All changes in this report are for the WEEK), a component in all three major indexes, jumped 24% during the quarter, nestled next to an all-time high set again this week. The company added $145 billion to its market cap in the quarter, besting its own record set in 2012 of adding more market cap in a quarter than any other company. It was the biggest gainer in the Dow Jones 30. Facebook, Amazon and Netflix all added 18%.
There is always a bull market right here at The Bull Market Report! This week we highlight the following securities: Visa, Amazon, Microsoft, Tesla, Splunk, and Shopify.
Highlights From The Past Week
Trump Talks Tough on U.S.-China Trade. President Trump appeared to follow through Friday on his promises to get tough on trade with China, less than a week before he is to meet with President Xi Jinping of China. In two executive orders, Mr. Trump called for tighter enforcement of tariffs imposed in anti-dumping and anti-subsidy trade cases, as well as a comprehensive review of the United States trade deficits - measures that reflect America’s economic tensions with China. Straightening out the US trade balance with China would be a major positive for US GDP growth, if Trump can accomplish the goal.
Why the Urge to Merge Could Return to Wall Street. Nothing appears to be off the table for the Trump administration as it seeks to pare back the regulations imposed on Wall Street and banks after the financial crisis. There has already been considerable talk about rolling back much of the Dodd-Frank Act of 2010, as well as the Volcker Rule that is intended to prevent Wall Street firms from engaging in proprietary trading. Already, the acting chairman of the Securities and Exchange Commission, Michael Piwowar, says his agency has stopped writing the rules and regulations mandated by Dodd-Frank - more than 20,000 pages so far - in anticipation of the confirmation of Jay Clayton as the commission’s new chairman. There is little doubt change is coming. But no one seems to be talking about whether Wall Street banks will again be able to engage in what has historically been one of their favorite pastimes: getting bigger through mergers and acquisitions. We could be in for an M&A boom across sectors not just Financials.
"Valeant Bet Was a ‘Huge Mistake," Hedge Fund Chief Ackman Says. It is rare that William Ackman, the brash activist investor, apologizes for anything. As a successful hedge fund manager, Mr. Ackman has made billions of dollars for himself and his investors with bold and counterintuitive bets. But this week he conceded that his firm’s biggest wager yet - on Valeant Pharmaceuticals International - was “a huge mistake” that has cost his hedge fund firm, Pershing Square Capital Management, “a tremendous amount.” “I deeply and profoundly apologize,” Mr. Ackman added in an annual letter to investors. It was an unusual moment of contrition for Mr. Ackman and a stark contrast to his emphatic support of Valeant in recent years. In the bigger picture, this event is just the latest of many recent developments pointing to troubling times for hedge fund managers as more and more investors turn to do-it-yourself and/or ETF investing.
BMR Companies and Commentary
Visa (V: $89, flat)
Samsung Electronics announced a strategic partnership with Visa to help bring Samsung Pay to online merchants. Starting later this year, Samsung Pay users will be able to shop online at hundreds of thousands of merchants around the world where Visa Checkout is accepted. The partnership just goes to show everybody in payments relies heavily on Visa.
Samsung Pay’s simple, secure checkout experience using fingerprint authentication gives users a more streamlined online shopping experience, eliminating the lengthy process of adding their payment card data, billing or shipping details each time they shop. Users with fingerprint authentication-enabled Samsung devices will be able to click the Visa Checkout/Samsung Pay co-branded button and touch the fingerprint sensor and the payment will proceed instantly, without needing to enter a user name and password for each purchase.
How cool! The days of filling out long forms or remembering usernames and passwords to make online purchases are continuing to wind down, as options like Visa Checkout’s open platform become accessible on hundreds of thousands of merchant sites, and companies like Samsung see the value in simplifying the process for both consumers and merchants.
BMR Take: Visa trades at 26x the consensus estimate for this year’s fiscal EPS of $3.45. Take a look at this 5-year chart from Yahoo. Where do you think they are headed in 2017/8 and beyond?
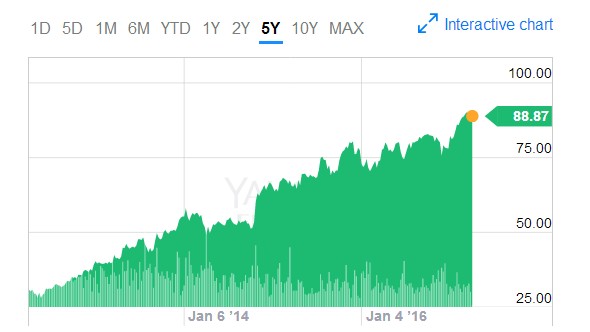
Amazon (AMZN: $887, +5%)
Amazon is expected to enter the Australian market soon. Estimates call for this region to eventually contribute upward to $15 billion of sales to Amazon’s top line, which compares to this year’s sales tracking to be around $165 billion for the company.
What is great about Australia for Amazon? Online sales will account for just 12.5% of Australian retail sales by 2025, up from only 7% in 2016. In other words, Australia is just barely into the online sales phenomenon. We are likely heading to online sales being greater than 25% so there is just much growth runway ahead for Amazon in Australia.
What will be interesting to watch is what Amazon’s entry into Australia means for local retailers. Could it be an imminent disaster? Certainly, many local players will have to adjust to smaller store footprints, change pricing, and improve their customer engagement.
BMR Take: Amazon trades at 125x the consensus estimate for this year’s fiscal EPS of $7.09. It’s a big valuation, but growth is exceptional. EPS was a loss in 2014, $1.25 in 2015, and $4.90 in 2016 and now we see estimates for $7.10 in 2017, $12.35 in 2018, and almost $20 in 2019.
Consensus Ratings for Amazon
4 Hold Ratings, 45 Buy Ratings
Targets:
3/30/2017 Loop Capital $1,100
3/29/2017 Cantor Fitzgerald $970
3/28/2017 Stifel Nicolaus $1,025
3/17/2017 Pacific Crest $895
Apple (AAPL: $144, +2%)
In January, Forbes reported that a White House advisory panel issued a report recommending that the U.S. strengthen protection of the Semiconductor industry, especially against threats posed by Chinese policies to dominate the sector.
Then in March, Apple discussed publicly that the Japanese government is likely to ensure Toshiba is acquired. Prime Minister Shinzo Abe recently met with President Trump to discuss among other topics this one. There are now swirling talks that Apple is going to buy part of Toshiba. The deal could be executed for as much as $18 billion.
What does it all mean? Apple farms out their production for Macs, iDevices and accessories so that they can focus the bulk of their investments on software and engineering companies, setting up R&D centers around the world and building out new flagship Apple stores. We very well might be looking at the early signs of Apple soon making many of their products in the United States. Exciting.
BMR Take: Apple is again setting new all-time highs this week. The stock trades for just 15.5x this year’s consensus EPS estimate of $9.25. We are still seeing healthy EPS growth from Apple, as seen in the consensus forecast for EPS of $10.35 in 2018 and almost $11 in 2019.
Microsoft (MSFT: $66, +1%)
Last October Microsoft released the preview of Azure Analysis Services, which is built on the proven analytics engine in Microsoft SQL Server Analysis Services. With Azure Analysis Services, you can host data in the cloud. Users in your organization can then connect to your data models using tools like Excel, Power BI, and many others to create reports and perform ad-hoc data analysis. This is exciting stuff for the business community. You no longer need to run a big back office. You have Microsoft Azure!
Well, just this week, Microsoft announced that Azure Analysis Services is now available in two additional regions: Japan and the UK. This means that Azure Analysis Services is now available in the following regions: Australia, Canada, Brazil, Southeast Asia, North Europe, West Europe, the US, Japan and the UK.
BMR Take: Again a new all-time high for Microsoft this week as the cloud is taking over and Microsoft Azure is one of the top players. The stock trades at 21x this year’s EPS estimate of $3.10 though estimates call for EPS of $3.50 in 2018 and $4 in 2019.
Tesla (TSLA: $278, +6%)
Earlier this week, Tesla announced that Chinese Internet firm Tencent had acquired a 5% stake in the company for $1.8 billion. The cash infusion is good news for Tesla’s financial health, and the company’s growth prospects in the region.
In a recent filing, Tesla said that 2016 sales in China were $1.06 billion. That’s roughly a quarter of what the company made in the U.S. last year. And while the China figures represent significant growth from 2015, it’s still well below what CEO Elon Musk once imagined. In a 2014 interview with Bloomberg, Musk projected that China could eventually become the electric-car maker’s largest market. Admittedly, that day is a long way off, but we are moving closer and closer.
One big hurdle left to clear in China for Tesla is market share. According to CleanTechnica, 352,000 electric car sales were registered in China last year, which is nearly half of all plug-ins sold worldwide. Tesla, however, is the underdog. Despite being the best-selling foreign electric vehicle manufacturer to crack the Chinese market, the company only had a 3% share in 2016. Plenty of room left for improvement to drive more growth.
BMR Take: Tesla is selling cars in China like hotcakes. China LOVES Tesla and Elon Musk. We are excited to see the company make some progress in the attractive China market. The company is still losing money, basically because they are not making cars in mass quantities yet, so the extra money raised from the 5% stake sold is a welcomed boost of cash on the balance sheet. Tesla ended last quarter with over $8 billion in debt on total assets of $23 billion, a definitely elevated level.
Splunk (SPLK: $62, +2%)
An activist may have just shown up at the Splunk table. A notable language change in Splunk’s 10k filing was noticed this week. The new disclosure alerted investors to possible activist involvement in company operations.
The 2017 10-K included following phrasing absent from the previous year’s filing: "From time to time, public companies are subject to campaigns by investors seeking to increase short-term stockholder value through actions such as financial restructuring, increased debt, special dividends, stock repurchases or sales of assets or the entire company. If stockholders attempt to effect such changes or acquire control over us, responding to such actions would be costly, time-consuming and disruptive, which could adversely affect our results of operations, financial results and the value of our common stock. These factors could also make it more difficult for us to attract and retain qualified employees, executive officers and members of our board of directors."
BMR Take: The added language essentially fulfills the company’s legal obligation to warn investors of activist interference. So we would be in a for a nice catalyst here. We really like Splunk. All anybody ever talks about now is cybersecurity. The company has $1 billion in cash and just $100 million in debt. Consensus estimates call for meaningful growth from $0.40 of EPS last year to $0.60 this year and $0.90 next year.
Shopify (SHOP: $68, -1%)
There was a whirlwind of poor press circulating on the company this week. First of all, a research firm downgraded Shopify to a strong sell to reflect negative estimate revisions following an unimpressive full-year 2017 outlook and growing near-term headwinds. This is just near-term noise. We are focused on the longer term big picture, which is very attractive for Shopify. In particular, many investors are asking the question if it would make sense for Amazon to acquire Shopify. After all, the market cap is only $6 billion. This would be a rounding error on Amazon’s balance sheet.
Shopify offers an easy-to-use multi-channel commerce platform that targets small and medium-sized businesses. Its 2016 revenue was $390 million. This would be a bolt-on acquisition for the Amazon Web Services (AWS) business if the rumor is true. As far as what Amazon or another buyer might get for a bid of $7-8 billion or so, the Shopify website showed that more than 380,000 people have sold over $29 billion using Shopify. The service allows small and mid-sized businesses to fully customize their online stores and to add new sales channels, while managing unlimited products and inventory and tracking sales.
BMR Take: We are not worried that the stock took a few points of pullback this past week. This is a long-term investment that will pay off big in five years. EPS is expected to go from a slight loss this year of $0.18 to something like $1.25 by 2020. Given all the potential of Shopify’s technology and the earnings ramp set to occur, we remain excited about the future for this company.
Upcoming Economic News
It is a very quiet week ahead for economics news. Stay tuned for more economic news next week.
A Letter from a Reader
To: The Bull Market Report
From: Arthur Weed
Twilio, First Solar and Ferrellgas were all recommended at the high end of the price range. Shopify also is at the high end of the range in this market. Sometimes riding the market out for lower prices is a good option. I just prefer to watch for weakness and then go for it.
Hi Art –
OK, I understand. We all have our personal philosophies. I like to shoot for the fences with some of my assets. I missed Microsoft at 3 cents. And Apple at 11 cents . But I got AOL at $1 in the 90s and it went to $71. And I got Iomega at $17 even though the low was $3 for the year and it went to $330.
The facts:
Twilio was added after it dropped from its high of $71, and in fact, it had a fairly sharp drop from that level to $52 where we added it.
First Solar was added at $63 and a month later was $73. Revenues have fallen sharply.
The average price of Ferrellgas for the last 23 years is around $20. At $17 we thought we had a nice discount and an opportunity for it to go to $20 and then $25.
Our thoughts:
--- We believe Twilio will be a huge player in the internet communications marketplace. And we believe the stock can triple or more from $50.
--- First Solar has been a leader in this business for decades and until recently has the revenue to go with it. Unfortunately, we have to wait until 2019 for this one to play out. And that is not guaranteed, but we believe management can do it.
Note: First Solar was given a hold rating at JPMorgan Chase. They now have a $38.00 price target on the stock.
--- Ferrellgas has been a leader in the natural gas business forever. We didn’t know their big acquisition would go down as one of the worst in Wall Street history.
--- Shopify is the leader in e-Commerce by a wide margin and has big growth ahead of it. It is a potential Microsoft-like opportunity as the world is moving to mobile every single day, every week, every month, every year. We wish we had discovered it at $25 or $50. But if the stock goes to $100 and then $150-200 we won’t mind too much. We think this is quite possible over time.
Todd Shaver
A Letter from a Reader
From: Chet Malek
Sent: Thursday, March 30, 2017 9:07 AM
To: info@bullmarket.com
Subject: SNAP and Twitter
Todd – Do you have any thoughts on SNAP? Do you like Twitter better (I assume you do)?
Hi Chet –
We do not like Snap. They may surprise me and go to $50 and $100 but at the moment they are WAY behind where Facebook was when Facebook went public. And if you remember, they went public at $37, hit $43 that day, closed at $37 and then proceeded to go down to $16 in the next few months. Now the stock is at $142. BUT Facebook had big revenues and big profits at that time. Snap has good revenues but super negative earnings – They lost $515 million last year and $380 million in 2015! And they are a niche business unlike Facebook which covers it all.
We do like Twitter. One day they will figure it out. And one day someone will buy them at a 40% premium. If I were a gambling man I would buy 2-year LEAP options with a strike price of $25 or $30, cheap. [This is not for all. Consult your broker. High risk here.]
We really like Twilio – good business concept; strong revenues last quarter. No profits yet. But profits will come if the revenue is there, and it is.
Todd Shaver, Founder and Editor in Chief
Twilio Extends Relationship with Amazon
Twilio (TWLO: $29, flat) announced a further step in their relationship with Amazon. They said: Amazon Connect will use Twilio's programmable APIs to provide enhanced capabilities for customers.
(What are APIs? An Application Programming Interface is a set of subroutine definitions, protocols, and tools for building application software. In general terms, it is a set of clearly defined methods of communication between various software components. A good API makes it easier to develop a computer program by providing all the building blocks, which are then put together by the programmer. An API may be for a web-based system, operating system, database system, computer hardware or software library.)
From their public announcement Tuesday: Twilio, the leading cloud communications platform company, today announced support for Amazon Connect, the newly announced cloud-based contact center service from Amazon Web Services (AWS). Twilio's Programmable APIs will enable a range of new capabilities, including integrating phone intelligence lookup to personalize Amazon Connect contact flows, enhance customer contact details, and follow up with post-call surveys via text.
"We're pleased to further extend our work with Amazon Web Services by helping to power and further enhancing the capabilities of Amazon Connect," said Twilio CEO and co-founder Jeff Lawson. "Supporting the continued advancement of the contact center to its more agile future in software, frees developers and businesses from the legacy approach to contact centers -- an approach that simply can't keep pace with customer expectations today."
The announcement furthers the long-standing relationship between the two companies. Note that Twilio is built and globally deployed on the highly scalable AWS Cloud. Some say that Amazon can do what Twilio does and that all this hype is bad news for Twilio. We say the opposite. We think there is a symbiotic relationship here that appears to grow stronger and stronger each month.
Here’s what the company includes in their press releases:
About Twilio
Twilio's mission is to fuel the future of communications. Developers and businesses use Twilio to make communications relevant and contextual by embedding messaging, voice and video capabilities directly into their software applications. Founded in 2008, Twilio has over 650 employees, with headquarters in San Francisco and other offices in Bogotá, Dublin, Hong Kong, London, Madrid, Mountain View, Munich, Sweden, New York City, Singapore, and Tallinn [the capital of Estonia.]
Alphabet (GOOG: $830) is now covered by Barclays. They set an "overweight" rating and a target of $1,065. Our target is $900 but when that level is hit we fully expect to raise it to at least $1100. The only question is when.
The High Yield Corner
By Michael Foster, Special to The Bull Market Report
We start this week’s high yield summary with the GDP report. The headline news looks good: GDP grew at 2.1% versus 2% in the fourth quarter. Politically-minded Americans may want to dismiss this (and who isn’t politically minded these days?), arguing either things will get better or worse under Trump, depending on the flag they bear. We would suggest resisting the urge to devolve the topic to partisan bickering, because the details under this report are very important because they signal where exactly we are in the credit cycle. This, in turn, is important for one of the world’s biggest credit markets: U.S. corporate bonds.
The mainstream press focused on a couple of dynamics under the headline number, although both are relatively unimportant. A big theme, according to journalists, was consumer spending. This rose 3.5%, a sharp upwards revision from 3% previously. Since consumer consumption is the biggest driver of demand in the U.S., which in turn drives demand for the big industries abroad (manufacturing in China and Germany, exporting in Hong Kong and Singapore, commodities in Latin America, and so on), this is good news.
But it’s actually not the most important bit of good news from the report. The National Income and Product Accounts (NIPA) data, which makes up part of the GDP, gave significant and good surprises that have much more predictive power than consumer activity. According to the NIPA release, corporate profits rose after declining for three years. The “corporate profits” metric, jumped over 9% on a year-over-year basis in the 4th quarter of 2016, a sharp acceleration from the 2% increase seen in the 3rd quarter. Some economists have already said the so-called “corporate profit recession” has ended.
This decline, which was partly a result of the crash in commodity prices and partly the result of cash-strapped consumers pulling back, was a primary reason why the S&P 500 got more expensive. Because stock values are measured by dividing their current price by their earnings over a one-year period (the “price-to-earnings” ratio), stock values climbed higher and higher because profits were falling lower even as stock prices were going up. This caused the S&P 500 P/E ratio to shoot up to over 26 by the end of March, about 50% higher than its historical average. That definitely looked and smelled like an overbought market, but investors held their noses and bought stocks anyway.
We’re here to tell you that you can stop holding your nose. While the corporate profits measurement is not identical to the way S&P 500 companies report their earnings, they’re close enough. And with a 9% jump, that means the S&P 500’s one-year forward P/E ratio is less than 20, a very reasonable level.
At the same time, this increase in earnings is extremely good for corporate bonds, BDCs, and REITs for similar reasons. Let us go through these one by one to explain why.
Firstly, corporate bonds. The SPDR Barclays High Yield Bond ETF (JNK: $37) had a good week (up 1%) thanks in no small part to the GDP data, although investors are continuing to recognize what we have been saying for a long time: the default risks are over and will decline significantly because corporate profits are going up, meaning firms will have enough cash to pay their debts. What does this mean? All the risks that were priced into junk bonds back in 2015 are evaporating but the price hasn’t fully recovered on a real adjusted basis. Great news - this means we can buy junk bonds. But we can’t be indiscriminate about it. Well-managed funds like the PIMCO Dynamic Income Fund (PDI: $29) are ideally positioned to outperform. Last year PDI paid out a special dividend well over 4% of the fund’s value, bringing the annualized yield to over 13%. With the strength in junk bonds this type of return will be even easier for this fund to do this year, making it an obvious strong hold even though it is priced at a premium.
A similar rationale exists for why BDCs shot up this week: more corporate profits mean less concern companies will default on their debts. The UBS BDC ETF (BDCS: $24, up 2%) had an incredibly strong week as a result. However, we do not see this as a good enough reason to buy BDCs, especially the larger cap ones that are facing growing competition from banks that are increasing their middle market business lending practices. The market is cheering the macro conditions for BDCs, which are clearly much better than a year or two ago. However, the market is not taking into account the industry conditions for BDCs, which is more competitive and thus will force some BDCs to look for lower yielding or higher risk loans. This makes us cautious on BDCs just as we are more positive about their lower yielding competitors - namely, financial stocks.
Finally, let’s talk REITs. In the simplest sense, higher corporate profits mean more room to raise rents for industrial, commercial, and infrastructural tenants. Retail and commercial REITs make up a healthy chunk of the SPDR Dow Jones REIT ETF (RWR: $92, up 1%), but it also plays into the wheelhouse of The Bull Market Report’s favorite REITs.
Digital Realty Trust (DLR: $105, up 2.5%), Omega Healthcare Investors (OHI: $33, up 2%), Kimco Realty (KIM: $22, down 2%), Government Properties Trust (GOV: $21, up 2%), and Care Capital Properties (CCP: $27, up 6%) are all exposed to corporate and government tenants whose ability to tolerate raising rents is going up as corporate profits rise. This doesn’t mean the market is irrationally exuberant about the sector like they were in mid-2016, which again makes this a good sector to be into, especially if you’re choosing firms relying on commercial rents.
The market is stronger than the fearmongers would have you expect, and that strength is particularly acute in the high yield universe. It’s a great time to buy income.
Funny – as we write this last sentence above we think of all the folks out there who are thinking: How can I buy yield when interest rates are going to go up which means prices will go down? Well, we at The Bull Market Report don’t believe rates are going that much higher. In fact, if anything, we think rates could go lower, despite the Fed’s best wishes. Besides, as noted above and every week that we write this report, you surely notice that we are writing about strong companies with strong management who are well-aware of the world of interest rate risk. We believe in management of the companies we follow. Look at Annaly (NLY:$11.11). They paid a 30 cent divided this week (11% annualized), and the stock was flat. That’s a 2.7% gain for the week in our book. The stock is up over 10% from its low in December! And they’ve been doing this for 20 years.
Good Investing,
Todd Shaver
Founder and Editor in Chief
The Bull Market Report
Since 1998