March 5, 2017
by Todd Shaver | Mar 5, 2017 | Weekly Newsletter 7pm Sunday
The Week Ahead
“Smart Investors Turn To ETFs” was the front page Wall Street Journal headline over the weekend. It is sort of laughable. Wall Street seems to always proclaim it has found the holy grail. They sell product after product with the same pitch. This time we are seeing it happen in ETFs. Don’t be fooled. Look, we like ETFs. We have the Energy ETF in our portfolio. Beyond Sector ETFs, we think there are good investment opportunities in broad-reaching global ETFs. Yet, there remains good investment opportunities in individual common stocks. If anything, the time to by buying your favorite stocks is when everyone else is blindly buying ETFs.
No matter what, there is always a bull market here. Week in and week out, you can find it right here at The Bull Market Report. We currently see a bull market in the REIT universe. This week we highlight the following securities: Simon Property Group, Anally Capital Management, Care Capital Properties, Government Properties, and Welltower. Check out our new REIT portfolio on the website. If you have forgotten your User ID or Password, write us here: Info@BullMarket.com.
Highlights From The Past Week
IPO window wide open as Snap goes public. Having priced at $17, Snap (SNAP) opened for trading at $24, valuing the company over $34 billion - almost three times the size of Twitter, bigger than both HP and CBS, and almost as big as eBay. With losses running greater than revenue, investor demand for the Snap IPO reveals nothing less than a vibrant IPO market. And some craziness! And then the next day it jumped another 10%.
Goldman raises March rate hike odds move to 95% after Yellen speech. Following Yellen's speech which did not throw any curve balls to this week's sharply revised, hawkish narrative by her FOMC peers, a March rate hike - according to Goldman Sachs Research - appears to be in the books. Fed Chair Yellen said that a rate increase at the March FOMC meeting “would likely be appropriate”, as long as incoming data continue to confirm officials’ outlook. Goldman sees this as a “strong signal for action at the upcoming meeting, and we have raised our subjective odds of a hike to 95%." We’re not too worried. Rates hikes are good and bad. They are bad because no one wants to pay higher rates for loans. But they are good because it shows the economy is doing well.
The Fed Is preparing $1 trillion in Qualitative Easing (QE) for the next recession. Should the US encounter a recession in the next several years, the most likely reaction by the Fed would be another $1 trillion in QE, according to Deutsche Bank, delaying indefinitely any expectations for a return to a "normal" balance sheet. This provides downside protection in the event the current bull market loses any momentum.
BMR Companies and Commentary
Simon Property Group (SPG: $179, down 3%)
Houston we have a problem? Nope. Houston-area malls owned by Simon Property Group have not been harmed by market-specific energy-related challenges or broader retail-industry struggles.
Simon’s two Houston properties total 3.7 million square feet worth about 2% of the portfolio. Trends have been stable. Its top Houston mall, The Galleria, is in the midst of a redevelopment to add high-end shops and restaurants into a former Saks. The Galleria is anchored by Neiman Marcus, Nordstrom, Macy’s, and previously Saks. The other of the two malls, Katy Mills, is anchored by Neiman Marcus and Saks 5th Off.
It is not just Simon’s properties holding up. We see the same stability from General Growth Properties (GGP), which owns five Houston properties that total 5.5 million square feet, which is much larger than Simon’s.
BMR Take: The oil bust of late has placed some sour sentiment on any security with exposure to the commodity. The same thing is happening with regard to brick and mortar retail sales. We have not yet seen the two concerns hurt Simon. We are keeping a close eye out for any signs of stress. There is some concern in certain quarters that online shopping will ultimately impact the mall owners of the world like Simon. We don’t believe so, as people like the concept of shopping at 150 stores at a time in real stores, rather than sitting hunched over a computer. But, with that said, if Simon heads lower from here we are going to take a quick, minor loss and look for other places to put our money.
In the interim, we believe stocks like Simon are trading at compelling values.
Annaly Capital Management (NLY: $10.96, down 1%)
Annaly is an internally-managed Mortgage REIT based in New York City with total assets of $83 billion. Incorporated in 1996 and public since 1997, Annaly is by far the largest of the six public Mortgage REITs, which invest in Agency residential mortgage-backed securities.
The company currently invests solely in mortgage securities that are guaranteed by government-sponsored entities, Freddie Mac and Fannie Mae, or by an agency of the federal government, Ginnie Mae. All of these securities have an actual or implied AAA credit rating.
Annaly's principal business objective is to generate income for distribution to investors from the spread between its agency RMBS portfolio and the cost of borrowings. The key point to understand is that Annaly’s business model is very sensitive to interest rates, more so than even other REITs.
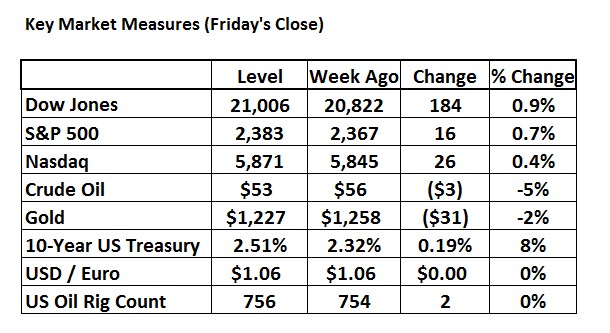
BMR Take: With the 10-year Treasury stepping up 19 basis points to 2.51% this week, Annaly shares remained relatively stable. This was a $10.22 stock a month ago, so we remain quite pleased with this investment.
Care Capital Properties (CCP: $26, up 1%)
Care Capital is a self-administered, self-managed Real Estate Investment Trust ("REIT") engaged in the ownership, acquisition and leasing of skilled nursing facilities and other healthcare assets operated by private regional and local care providers.
Care Capital primarily generate revenues by leasing properties to third-party operators under triple-net leases, pursuant to which the tenants are obligated to pay all property-related expenses, including maintenance, utilities, repairs, taxes, insurance and capital expenditures.
As of December 31, 2016, Care Capital had a diverse portfolio of 345 properties and 40 private regional and local care provider relationships. The portfolio is spread across 36 states and contains a total of roughly 38,000 beds/units.
Management is in the process of “re-positioning” the portfolio to improve portfolio metrics. The company was spun out of Ventas in August 2015 and since then has been selling assets and reinvesting in new development and redevelopment.
BMR Take: While near-term portfolio “re-positioning” is weighing on rental revenues and divestitures are resulting in lower earnings assets, ultimately we think the transition is working to produce a high quality better run portfolio that will receive more favor from the market.
Government Properties (GOV: $20, down 2%)
Government Properties is an externally advised real estate investment trust that owns, acquires, and manages office properties leased primarily to government tenants. The company’s niche focus afforded it the opportunity to go public in the midst of the financial crisis in 2009 where it raised $230 million.
Admittedly, core results have been mixed. Despite solid leasing volume, the real estate optimization strategy among government tenants remains a headwind. Average term of just 3.3 years marks the lowest term in recent memory. Tenants contributing 2.6% of rents are scheduled to vacate soon, as the Department of Justice, which currently represents 3% of rents, has moved from the “at risk” bucket to “vacating”. Fortunately, there is some offset by the National Institutes of Health, which has decided to stay. We don’t want to alarm you about recently mixed core results. It is the natural ebb and flow of the business. It could all easily swing the other way.
Providing some comfort, management had alluded to an expanding deal pipeline, given frothy pricing and demand for government-tenanted properties. We are seeing it happen. The company recently announced three acquisitions totaling roughly $130 million, with the largest asset being a 98% leased office park in Virginia; this property represents the largest investment since 2014.
BMR Take: Government Properties serves a unique niche in the REIT space and we see compelling value in the shares.
Welltower (HCN: $70, down 1%)
Welltower is at the forefront of investing in innovative healthcare infrastructure to create the physical and social environments necessary to promote wellness and quality of life for the aging population. Welltower’s operating platform supports post-acute care, independent living, assisted living and memory care facilities for more than 200,000 elderly residents and state-of-the-art outpatient medical facilities handling more than 16 million patient visits annually.
Recently, Welltower began collaborating with Johns Hopkins in a major new partnership. Johns Hopkins Medicine is one of the world’s pre-eminent patient care, research, and teaching institutions. Initially, Welltower and Johns Hopkins Medicine will explore joint initiatives in areas including: measuring quality outcomes in assisted living and memory care; educational programs for patients and care givers; and sharing of health and wellness and business expertise, information, best practices and research. The collaboration will also assess healthcare market opportunities and investments in modern, efficient infrastructure to deliver better care at a lower cost.
Americans ages 65 to 85 is the fastest growing segment of our population and the largest consumers of healthcare. Welltower is a leader in the space on all fronts from infrastructure to science.
BMR Take: The consensus forecast is for a dividend of $3.50 this year, $3.57 next year, and $3.82 in 2019. This 5% dividend yield looks compelling for a leading Healthcare REIT.
Upcoming Economic News
MONDAY, MARCH 6
Factory Orders – January
Time: 10:00 am
Forecast: 0.9%
Sizable growth in transportation sector orders is likely to lead overall factory orders higher in January. Core durable orders are showing positive trends for business investment in the near-term. Such orders rose 10.1% annualized in the three months ending January—the best such gain in nearly three years.
TUESDAY, MARCH 7
Trade Balance – January
Time: 8:30 am
Forecast: -$45.7 billion
The US trade deficit is likely to widen in January as the advance report on trade in goods showed significant gains in imports. Despite the growing trade gap, exports are once again adding to US output as opposed to representing a major drag on growth. Exports rose at the two-year high rate of 1.8% year-over-year in the fourth quarter while December’s 2.7% monthly advance was the best result in four years.
WEDNESDAY, MARCH 8
Productivity & Unit Labor Costs – Fourth Quarter
Time: 8:30 am
Forecast: 1.5% productivity, 1.5% unit labor costs
Long moribund productivity trends showed some uplift in the second half of last year, rising 2% annualized. Yet that recent bump needs to be sustained for quite some time to greatly undo the sickly 0.5% annualized gain for productivity over the past three years. Of concern to the Federal Reserve is the stronger pace of gains exhibited by unit labors costs, which rose 2.4% annualized over the same three-year period.
Import Price Index – February
Time: 8:30 am
Forecast: 0.1%
Moderation in the pace of raw materials price gains is expected to limit the February Import Price Index to its smallest gain of the past three months. Higher oil prices are facing resistance as current values entice a broader array of producers to drill. But the rising cost of imported goods is already weighing on consumer purchases, as the Import Index rose at the five-year high annual rate of 3.7% in January.
FRIDAY, MARCH 10
Employment Report - February
Time: 8:30 am
Forecast: 174,000 nonfarm payrolls, 4.7% unemployment rate
Job growth is showing no signs of stalling out after workers on nonfarm payrolls increased at the four-month high count of 227,000 in January. Employers are very hesitant to lay off staff, resulting in new claims for unemployment insurance hovering near lows not seen in over 40 years. That signal of labor market tightness can carry over to faster wage growth, helping to push up worker earnings above levels that remain historically weak for an extended economic expansion.
Apple Increases Research and Development Spend
Apple (AAPL: $140, up 2%) is pouring money into R&D in an attempt to improve products that don't currently generate revenue, but might in the future, according to remarks made by Apple CFO Luca Maestri at the Goldman Sachs investor conference Tuesday.
The company spent a huge $2.8 billion on R&D in 4Q16, bringing the total to nearly $10.5 billion in total for the year. Apple's annual spend is up by roughly $4 billion since 2014, marking a very noteworthy increase.
Why? Apple's hardware product range is growing. The iPhone is driving the company’s growth and it is adding new products to the lineup to further growth. The price of the phone is pricing out many customers, so we expect to see lower priced phones in the future, allowing them to sell a phone to everyone in the world.
Plus Apple's Services business, which comprises revenue from internet services, Apple Care, Apple Pay, licensing, and the App Store, is expected to grow to the size of a Fortune 100 company this year, according to Apple CEO Tim Cook. That's about $28 billion in revenue for the year, or a year-over-year growth of 15%.
BMR Take: Apple is sitting at an all-time high. We’ve been beating the drums, through endless negativity, especially when the stock fell into the 90s last summer. We were right and we are here to tell you that $150 is not out of sight. And we CAN’T WAIT until the President comes up with his repatriation plan for the $250 billion in cash the Apple has tucked away overseas.
Opko Health Discussion
Opko Health (OPK) had a rough week, losing 12% to $7.45. Earnings were reported last week. Revenue for the quarter was $275 million, flat from the year before. For the year: $1.22 billion, up from $490 million last year. Earnings for the quarter – a loss of $14 million. For the year: a loss of $25 million, compared to a small profit last year. The numbers were skewed by the purchase of BioReference Labs in 2015 for $1.5 billion, which added over $1 billion to revenues last year.
Opko says the potential market for Rayaldee, the kidney disease drug, could be as high as $10 billion but the drug didn't launch until November so there was no breakout of revenues that many were waiting for. We’ll just have to wait until next quarter to see any type of results from this drug.
The 4KScore test, launched several years ago, measures four prostate-specific substances in the blood to identify men who have a high likelihood of developing an aggressive form of prostate cancer. Opko that in Q4 about 18,000 4Kscore prostate cancer tests were ordered, representing growth of more than 12% compared to Q316. Some said they were looking for much bigger numbers here. The company has $170 million in cash and long-term debt of $110 million.
Consensus in the analytical community show that of the six analysts that follow the stock, four rate Opko a Buy, while two rate the stock a Hold. The stock’s consensus target price stands at $13.30.
BMR Take: We’ve said two things before: that if the stock hit $8 we would sell. But recently we said if the stock hit $8 we would buy more. We are going to reiterate this position now. We would buy more here. The caveat is that you have time to wait. Good things comes from patience. But patience in the financial world can be upsetting and cause you to lose sleep. So if this is the case with you, there are lots of other places to put your money. This company has great potential but we don’t control the marketplace that they live in and we don’t control management. We believe in management, but they might disappoint us. (See Under Armour.) Wall Street certainly thinks highly of the company. We give you the Consensus so that you can evaluate the whole picture. Some say that Wall Street analysts are mostly wrong. We don’t believe that. (See Apple, where EVERY ANALYST thinks the stock is going higher, and of course, the stock is sitting at an all-time high.) In any case, this company has amazing potential. Revenues are strong; cash and debt are certainly in line; it should be just a matter of time before we see positive results.
A Letter to the Editor about Simon Property Group (SPG: $179, down 3%)
Hello Bull Market,
Simon Property Group has been doing well but my concern is about the trend toward online retail which has and should continue to have a chilling effect on mall traffic. Doesn't it worry you that several large retailers that are anchor tenants at malls like Macy's and Sears have plans to close stores all over the country? To the extent that online purchases increase won't that hurt brick and mortar retail and foot traffic through malls? Thanks.
Richard Reed
Hi Richard -
We've discussed this with some folks on the Street as well as my own analyst team and it's no doubt that this is the biggest risk factor. If we start to see the risk having a bigger impact on the business, that would be a reason for us to exit. Not that we like to play with fire or pick up coins on the railroad track, but the reality is all businesses are not flawless and have their risks, so it not a reason to not invest. The good news here is that everyone knows this risk so we would argue that it is already baked into the stock's current price. And we must say that shopping online and shopping at 150 stores in a mall are two completely different experiences. It's pretty tough to buy a suit online. And furthermore, people love the social aspect of shopping in stories. That will never change.
BMR Take: Bottom line – if the overall stock market falters, and/or if Simon moves lower, we will take a small loss and move on. But we are believers in the company long term and we are watching closely.
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
There are plenty of fundamental evidence in favor of US equities. The ISM Manufacturing Index, NFIB small business confidence gauge, and Consumer Confidence measures are all higher than 12 months ago and, historically, S&P 500 earnings growth has averaged nearly 15% in the year after such a simultaneous rise. UBS Financial is looking for 11% growth in 2017. UBS research also shows that since 1960, investors who have bought in when the market has been at an all-time high have performed similarly to those who have bought at other times. And investors who have bought in when the market has been trading in the current 18-20x PE valuation range have seen annualized returns of 10% and 7%, over one and 10- year time frames, respectively.
With all that being said, we are still in a rhetoric phase rather than a reality phase. In order to buck the odds of major stock market correction, we believe the following promised catalysts will have to show up this year:
Corporate Tax Break: The campaign pledge of a 15% rate is a powerful idea that would generate abundant earnings, GDP and equity growth. This is the "Holy Grail" for investors.
Individual Tax Break: This is also good for the economy, but the direct correlation to stock price gains is not expected to be as strong as the corporate tax break.
Infrastructure Spending: This should provide another big economic benefit.
We still believe an overweight in US equities and underweight in traditional bonds remains a valid tactical allocation in a rising interest rate cycle and expanding economy.
Analysts' Ratings for Under Armour (UA, $18.64, down 6%)
6 Sell Ratings, 21 Hold Ratings, 9 Buy Ratings
2/27/2017 Nomura $16
2/27/2017 Instinet $16
2/14/2017 Morgan Stanley $20
Things just keep getting worse at Under Armour. A tragedy.
Analysts' Ratings for Tesla Motors (TSLA: $251, down 2%)
7 Sell Ratings, 10 Hold Ratings, 12 Buy Ratings
Consensus Price Target: $256
2/27/2017 Morgan Stanley Outperform $305
2/27/2017 Guggenheim Buy $300
2/27/2017 Goldman Sachs Group Sell $185
2/24/2017 Deutsche Bank AG Hold $215
2/23/2017 RBC Capital Markets Target $314
2/23/2017 Royal Bank of Canada Target $314
2/23/2017 Robert W. Baird Outperform $368
Tesla was downgraded by analysts at Goldman Sachs from a “neutral” rating to a “sell” rating in a research note issued to investors on Monday, They presently have a $185 price target on the stock. Dougherty & Co lowered their price target from $500 to $375 and set a “buy” rating on the stock. Royal Bank of Canada increased their price target from $245 to $314 and gave the company a “sector perform” rating.
Analyst Ratings for Kimco Realty (KIM: $24, down 4%)
1 Sell Rating, 7 Hold Ratings, 8 Buy Ratings
Consensus Price Target: $30
2/3/2017 Canaccord Genuity Buy $34
1/23/2017 Barclays Overweight $27
1/9/2017 Raymond James Financial Outperform $28
THE HIGH YIELD CORNER
BY MICHAEL FOSTER
In high yield, this week was eventful on two fronts. Those who invest in closed-end funds likely received shareholder notices during the week, but the more exciting activity was in the BDC sector. A few BDCs reported this week and more are coming. Among the companies reporting was Goldman Sachs BDC (GSBD: $24.20), which reported a NAV decline exceeding 1% during the quarter and a near 3% decline in net investment income (NII). That wasn’t as bad as TCP Capital Corporation’s (TCPC: $17.20) 7% NII decline over the same period.
Neither stock was negatively impacted by the news, which wasn’t far from expectations anyhow, although Goldman’s BDC fell for the week and TCP Capital surprisingly rose. Goldman’s decline was modest and may ironically be a result of the company’s conservative approach. As one analyst wrote shortly after the earnings release, NAV’s decline is largely “a result of restructurings of non-accruals” and the firm’s more conservative approach to credit issuance. To wit, Goldman has not been expanding its loan portfolio significantly in a market that the fund’s managers have complained is not conducive to BDCs because of tight credit spreads, too much capital chasing too few deals, and overall risks in the marketplace. That has kept Goldman out of the market.
But surely Goldman can originate loans easily. Isn’t Goldman’s management in a position to throw billions of dollars’ worth of loans to their BDC? Well, yes; Goldman knows just about every wealthy person and multi-million dollar company on Earth.
The problem is a lack of incentives; Goldman has little reason to throw business the way of the totally separate and autonomous Goldman Sachs BDC, which is itself an entirely separate corporate structure. Combine this with the challenge of finding deals in a highly competitive marketplace, and you see why Goldman’s BDC is choosing to grow slowly rather than quickly.
The big takeaway from this is that now is not a good time to be in the BDC business. This is even truer for investors that rely on BDCs for passive income. There is so much competition between BDCs, that getting yields on loans is getting harder. And then there is so much competition between investors in BDCs, that premiums to stock values are getting higher, which in turn lowers dividend yields. Goldman Sachs’s BDC is trading at nearly a 30% premium to its NAV and is near its highest premium in history.
This is why we reluctantly sold Main Street Capital Corp (MAIN: $37) and continue to fret over the now absurd the 68% premium to NAV that the stock is currently trading at. Main Street is in our view the best BDC in the world but it’s just too expensive to own with a clear conscience. A diversified BDC fund like the UBS BDC ETF (BDCS: $23) is even worse, providing exposure to overpriced BDCs AND BDCs with bad portfolios or shady management. The sector provides value when it’s out of the market’s favor, but it’s in favor now so we continue to urge caution.
So where can an investor go for high yield? Other sectors are faring much better, and the 2016 muni bond rout seems to be fully behind us. The iShares S&P National AMT-Free Municipal Bond Fund (MUB: $108) had a flat week, but BMR pick Invesco Municipal Trust (VKQ: $12.53, up 1%) fared slightly better. Nuveen AMT-Free Fund (NVG: $14.41) fell a bit though, dropping just a shade over 1.5%.
These funds are paying around 5% in dividends, but remember that this is tax-free money. Depending on your tax status, that could mean an 8% taxable equivalent yield. With such a return, there is little rationale in staying away from municipals and taking on higher risk BDCs where defaults are much more likely, management fees are much higher, leverage is much more severe, and dividend payouts are much less sustainable.
On the issue of returns, let’s consider a moment the concept of the risk premium. Basic financial theory states that at-risk investments will always earn a return that is higher than the risk-free rate of return (ROR). There’s no such thing as 100% risk free, but U.S. Treasuries are about as close to risk free as you can get as long as you hold them to maturity. The Fed Funds rate is set to rise to 0.75% or even higher if Janet Yellen raises interest rates this month, which she says she will, and could go as high as 1.5% or above within a year or so. At-risk assets, then, need to offer a ROR above 0.75% for short-term assets. The calculation that is made is always between Treasuries and whatever risky investment you’re analyzing: Treasuries and oil junk bonds for instance.
However, there is another risk premium calculation that investors should make even though they generally don’t: The difference between the ROR on the investment you are considering and the taxable equivalent yield on municipal bonds. Why? Because retail investors can easily buy municipal bonds and get the income from those instead of choosing the riskier asset. This alternative means there is always a limit to just how low yields can go on at-risk assets before retail investors turn away from them.
Just how low is that yield? That’s a complicated calculation that would take a lot of data and a lot of analysis to figure out, but we can do a rough spot calculation by looking at the popular municipal bond ETFs, calculate their taxable equivalent yields, and compare that to the yields on taxable high yield assets. Doing so tells us that 4% is pretty much the limit. Corporate bonds now are apparently at or around their fair value from this metric.
Does that mean it’s time to buy these assets? Not really, but it’s not time to sell either. That means the SPDR Barclays High Yield Bond ETF (JNK: $37, flat) is not set for any great collapse but it isn’t exactly where you want to be either. It also means the near-term seems OK for BMR picks. The PIMCO Dynamic Income Fund (PDI: $29, up 1%) has reached a somewhat distressing premium to NAV of 8% but the fund’s sharp performance makes this bearable. The AGIC Equity and Convertible Income Fund (NIE: $19.73, up 1%) is seeing its discount to NAV remain around 11%, rather high from a long-term perspective and an attractive reason to hold.
Now, to REITs. The best news for BMR subscribers came from this sector this week, as the SPDR Dow Jones REIT ETF (RWR: $94.45, down 1%) saw a modest decline that was overshadowed by BMR’s REIT picks. Digital Realty Trust (DLR: $107, flat), Omega Healthcare Investors (OHI: $33, flat), and Care Capital Properties (CCP: $26, up 3%) were significantly better performers with flat to slightly up growth for the week. Government Properties Trust (GOV: $20, down 1%) tracked the market quite closely, showing that risky REITs are not selling off greater than the broader market, which is usually the signal of a broader and more worrisome panic. However, the most risk averse investors who look for more stable and less risky REITs are clearly selling off, as Kimco Realty (KIM: $24, down -4%) had a truly awful week. This appears indicative of a broader market trend towards risk aversion that is only beginning in the REIT sector but may continue in the weeks to come. Now is a good time to remain vigilant with the REIT sector and look to rebalance as mispricings continue. For now BMR’s recommendations remain unchanged, but more declines in Kimco could cause us to suggest a bit of rebalancing in the short term.
A final word on AstraZeneca (AZN: $30, up 2%). BMR has been following this drugmaker for a while and have held through months of weakness as the biotech industry was destroyed by political risk-related fears. Trump is now president and despite his tweets about drug prices, drugmakers don’t seem to be in any immediate danger. The market has recognized this and is slowly tiptoeing back into the sector. Astra-Zeneca is up 10% year-to-date for this reason alone. The pipeline hasn’t changed, but everyone is getting more enthusiastic about the company’s prospects. This remains a good time to remain long this stock.
Good Investing,
Todd Shaver, Founder, CEO and Editor
The Bull Market Report
Since 1998
February 21, 2017
by Todd Shaver | Feb 21, 2017 | Earnings Preview 12 PM
Tesla Motors (TSLA: $275)
Bull Market Report Target Price: $280
Bull Market Report Sell Price: $180
Earnings Date: Wednesday, 5:30 PM ET
Consensus: 4Q16
Revenues: $2.0B
EPS: -$0.43
Year Ago Quarter Results
Revenues: $1.75B
EPS: -$0.87
Key Things to Watch For in the Quarter
Analysts expect Tesla to report a 15% increase in revenue to $2.0 billion with a 50% improvement in the firm’s EPS to a $0.43 deficit for the fourth quarter of 2016. Tesla has missed analyst estimates each quarter. In the weeks following the releases, shares jumped 4% after the Q1 report, fell 3% after the Q2 report and remained fairly stagnant following the Q3 report. In addition to the firm’s stellar performance over the past year, providing investors with a 53% return, we are also very optimistic about the firm’s potential production levels. Despite missing their estimates of 80,000 cars last year, they have projected the production of 500,000 cars in 2018. It remains to be seen whether they can do this or not. We don't think they can do 500,000 cars, but even 200,000 will be a huge step forward.
We hereby raise our Sell Price to $250. We will raise our Target Price if the stock shoots higher than $280 and stays there.
February 5, 2017

by Todd Shaver | Feb 5, 2017 | Weekly Newsletter 7pm Sunday
The Week Ahead
“US Stocks Rise On Banks” was the front page of the paper going into the weekend. This highlights continued optimism about the prospects for the economy under the new administration. Specifically, at the moment, the rolling-back of Dodd-Frank is front and center. Can the momentum continue? Will new policies lead to real results? These are questions yet to be answered. But there is certainly a widespread optimism good things can happen.
This week we provide some insights on our latest thinking for Amazon, Facebook, Apple, Google, Athenahealth, Visa, and Blackstone Group.
Highlights From The Past Week
Trump signs order to roll-back Dodd-Frank. President Trump signed an executive order to begin rolling-back Dodd-Frank. The legislation was put in place after the Financial Crisis to crack down on the banking system and help protect the consumer. The Financial sector traded up on the news. Among the targets are rules that protect against predatory lenders, force brokers to lower fees for retirees, and ban proprietary trading. While it will take a while to fully roll back the financial regulations, Wall Street is likely already preparing for a big push into more aggressive business practices. And this latter point is why the market rallies in spite of what many in this country call chaos in the White House. Let’s give it some time. Remember, the checks and balances built into the Constitution may just begin to take effect over the coming months and years.
Japan set to make huge investment in the United States. They are calling it the "Appease Trump" proposal. Japan is putting together a package it says could generate 700,000 U.S. jobs. The five-part package, to be unveiled when Prime Minister Shinzo Abe visits Trump on Friday in Washington, encompasses investments in infrastructure projects such as high-speed trains and cyber security. Apparently, Abe wants to be sure Trump doesn't blow up at Japan again as he did earlier this week when he accused it of devaluing its currency, which hurt Japan’s yen and government bond yields.
Military tensions rise. While there were some hopes President Trump would demilitarize US presence in the Middle East, they are quickly getting dashed with every passing day. Following Trump's announcement last week that he would implement "safe zones" in Syria which would boost US troop presence in the region, US officials announced Friday they had moved a Navy destroyer - the USS Cole, which in 2000 was infamously attacked by terrorists while on dock in Yemen's Aden harbor - off the coast of Yemen to protect waterways from Houthi militia aligned with Iran. Tensions with Iran increased further on Friday when the U.S. Treasury Department announced sanctions on 13 people and 12 entities.
BMR Companies and Commentary
Amazon (AMZN: $810, -3% for the week)
Amazon traded lower on earnings results. The spending outlook took the shine off profit in the holiday quarter that beat analysts’ estimates. Net income was $750 million, or $1.54 a share versus analyst estimates for profit of $1.36 a share. We are happy to see the company bring profits higher but the Street didn’t feel quite the same.
Amazon will spend big in the coming months on warehouses, movies, gadgets and growth into India, renewing investor concerns that CEO Jeff Bezos cares more about generating revenue far in the future than turning a profit now. The company will double-down on its delivery system that gets products quickly into the hands of its customers. It will keep investing in original movies and shows to encourage people to buy Amazon Prime memberships, which makes them loyal shoppers. It will enhance its hot-selling Echo voice-activated personal assistant to gain a presence in homes.* And it will keep pushing into India, which it sees as a vast frontier for e- commerce growth.
*We at The Bull Market Report have one here at home and we love it. We get most of our music from Alexa and query Wikipedia through her probably 10 times a day.
All these initiatives will crimp profits. Operating income in the current quarter will be $250 million to $900 million, less than a year ago even though revenue is forecast to increase as much as 23% to $36 billion. “When you see revenue go up and earnings go down, it spooks people,” said a Wall Street analyst. “It’s called negative leverage and the Street hates it.”
Some Street Ratings on Amazon:
2/3/2017 Wedbush Reiterated Outperform $900.00
2/3/2017 FBN Securities Boost Price Target Buy $925.00
2/3/2017 J P Morgan Chase Price Target Buy $945.00
2/3/2017 Jefferies Group Set Price Target Buy $975.00
2/3/2017 Macquarie Set Price Target Buy $895.00
2/3/2017 Atlantic Securities Set Price Target Buy $960.00
2/3/2017 Stifel Nicolaus Boost Price Target Buy $912.00
2/3/2017 Cantor Fitzgerald Price Target Buy $965.00
2/3/2017 Credit Suisse Price Target Buy $900.00
2/3/2017 RBC Capital Mkts Price Target Buy $900.00
2/3/2017 Mizuho Price Target $905.00
2/3/2017 Evercore ISI Price Target $970.00
2/3/2017 Morgan Stanley Price Target $900.00
2/1/2017 Piper Jaffray Reiterated Rating $900.00
Amazon posted a 55% rise in fourth-quarter profit. But shares of the online retailer dropped in after-hours trading as the company's total sales fell short of analyst expectations. Again, for the quarter, profits rose to $750 million, or $1.54 a share, from $480 million, or $1.00 per share, a year earlier. Sales of $44 billion, up from $36 billion, were below analysts' expectations of $44.7 billion. Sure didn’t miss by much.
BMR Take: Amazon is in growth mode again. We like the long term outlook, but admit heavy investment could bring more near-term volatility. Hold on tight through the turbulence. Amazon is doing all the right things to cause the stock to soar over the long term, including announcing last Monday it would build a $1.5 billion air hub near Cincinnati to accommodate its growing fleet of cargo planes!
More on Amazon:
Amazon has something up its sleeve that may just compete heavily with Google and Facebook. Online advertising. There’s a category in their financials called Other Revenue which jumped 60% in 2016 to $1.3 billion. Still small, but obviously growing rapidly. Amazon has been ramping up its online advertising offerings and could one day be a major threat in the industry. The company said: "Our goals in advertising are to be helpful to customers and enhance their shopping and viewing experiences, mostly with targeted recommendations. We think that's a good strategy rather than invasive things that take away from the shopping experience."
They also said "sponsored product" ads were "off to a great start" and a "very effective way" to reach interested customers, adding that the company was working on some video ads as well. "We are balancing customer experience with advertising at all times, and we like the team that's working on it."
Facebook (FB: $131, -1%)
Facebook’s fourth-quarter revenue climbed more than forecast, driven by advertisers’ continued push to reach consumers on mobile phones. The world’s largest social-media company said sales jumped 51% to $8.8 billion, topping the $8.5 billion average analyst projection. Monthly active users on its main social network increased 17% from a year earlier to 1.86 billion people, with 1.2 billion checking daily and 1.7 billion accessing it via their smartphones.
Total revenue of $8.8 billion increased 51% from last year. The company posted a profit of $4.15 billion, or $1.41 a share, compared to the year-earlier profit of $1.56 billion, or 54 cents a share. We were particularly encouraged with engagement trends whereby improvement was seen across the U.S. and Canada, Europe, and Asia. We like that Instagram now has 400+ million daily active user, adding 100 million new daily users to its impressive tally in just over seven months. We note that WhatsApp now has 1.2 billion monthly active users. We also like the fact that Facebook’s top 100 advertisers represent less than 25% of total revenue, a ratio that decreased from 4Q15, highlighting the company’s increasingly broad and diverse marketplace revenue stream.
Facebook has solidified its position as #2 in the market for mobile advertising, behind only Google. However, it’s still early in the game, as just last year Facebook started selling more marketing spots and added e-commerce tools to Instagram, its photo-sharing app that now has more than 600 million users. Facebook also just recently expanded video advertising, drawing ad dollars that might otherwise have gone to television commercials. So the fight between Facebook and Google over the top spot in advertising is just getting going.
Facebook’s revenue gains had been expected to slow this year because the company has said it won’t keep increasing the percentage of ads shown in users’ News Feeds. That means it’s leaning on other growth areas, like Instagram, as well as new forms of advertising, such as ads in live video. Meanwhile, the company has said it plans to substantially increase its spending on new data centers and engineers.
All in all, “There’s effectively no change in the outlook,” per Chief Financial Officer David Wehner on the earnings call. “We continue to invest aggressively to grow out the business for the long term.”
BMR Take: As Facebook’s influence grows, its users have also started to hold it more accountable for its role in society. Around the U.S. presidential election last year, the company faced an uproar over the use of its social network to spread fake news. Accordingly, poor sentiment has really held the stock back in recent months, but that trend seems to be turning, and turning quickly.
Facebook earnings. Listen to this:
Revenue (Q4): $8.8 billion vs. $5.8 billion last year
Revenue Change (Y-o-Y): 51%
Earnings (Q4): $4.15 billion vs. $2.27 billion last year
Earnings Growth (Y-o-Y): 83%
The stock set a new all-time high of $135 in after-hours trading after they announced. The company is now worth almost $400 billion.
So on $8.8 billion of revenue they made $4.15 billion in profit, AFTER TAXES!! That’s 47% after tax. Insane.
Apple (AAPL: $129, +6%)
Apple will begin assembling iPhones in India by the end of April. The U.S. company has tapped Taiwan’s Wistron Corp to put together its phones in the tech capital of Bangalore. The start of iPhone assembly in India signals a renewed focus on India, perhaps as growth begins to slow in China and other more mature markets. Apple is said to have put forward a long list of demands in negotiations with India’s federal government, including a 15-year tax holiday to import components and equipment.
We highlight the above because we could see President Trump soon having something to say about this. Chief Executive Officer Tim Cook said on the earnings call this week that India is “the place to be.” Apple doesn’t manufacture devices itself, but rather partners with contract manufacturers to handle the capital intensive demands of building factories and hiring staff. Could Trump force Apple’s hand to move all that activity to the US? He expressed interest in doing so during the campaign.
BMR Take: We see a lot of upside for Apple. We just hope the company stays out of the political spotlight. The all-time high of $134 is within sight. The market cap is now a stone’s throw from $700 billion and they have $246 billion in cash, or $47 per share. So, of the $129 you pay for a share, $46 or 36% is in cash. This is unprecedented in the history of Wall Street. We continue to wait for the repatriation push from President Trump – the freeing up of the more than $1.3 trillion of cash being held overseas. This alone could cause a surge in stock prices in the Tech world as well as the overall market.
Blackstone Group (BX: $31, -2%)
President Donald Trump and top U.S. executives had a spirited, balanced discussion about tax issues during a gathering Friday, according to Blackstone’s CEO Steve Schwarzman, who attended the meeting.
“It was spirited intellectually,” Schwarzman said in an interview, adding that differing views were raised about the new administration’s proposed border-adjusted tax, which would put tariffs on imports.
Some companies run by leaders in attendance, including Walmart’s CEO Doug McMillon, have disagreed with Trump and Congressional Republicans on the proposal. “You don’t want to do something that hurts a significant part of the economy, but you want to get benefits from the exports,” Schwarzman said. “Both sides have good points.”
Trump invited 18 executives to the White House to discuss topics ranging from trade and education to women’s roles in the workforce. He called the members “the biggest and best minds in the country.” Trump appointed Schwarzman, who has a net worth of $11 billion, as chairman of the council in December, with the goal of receiving advice on economic growth and job creation from a group of business leaders.
BMR Take: We think Schwarzman’s tight relationship with the President positions Blackstone to be on the winning end of the political change happening. We continue to believe the stock is undervalued. And we can’t help but note a level of optimism in the stock. It appears to us to be “inching up.” Watch this one please. We believe this stock should be at $40. With Schwarzman's more public profile lately, this just might relate to a higher stock price. But at the same time, beware of getting too close to Trump. The CEO of Uber, Travis Kalanick, has resigned from the Trump Advisory Council after taking lots of flak from investors and customers. You just never know.
Athenahealth (ATHN: $109, -13%)
Athenahealth missed the mark this quarter. Earnings were 42 cents per share, which beat consensus of 27 cents. However, the figure came below the 45 cents posted in the year-ago quarter. Revenues of $288 million missed consensus of $304 million but increased 12% from $257 million a year ago.
The company’s expanding network now connects care across nearly 88,000 providers, nearly 86 million patients*, and over 143,000 offices. And, as the largest network in Healthcare, its data-driven insights combined with highly efficient and scalable back office work enables doctors to focus on the health of their patients, not paperwork, and expand their market share and get paid more, faster. Management is more confident than ever about its ability to achieve its vision of building the Healthcare internet. Its increasing depth and breadth of product management, technical design and development expertise, combined with increasing bandwidth to focus on its strategy versus the government mandates of recent years, should make Athena even more productive in 2017 as it deepen its services and builds out its unique network.
*We find this number hard to believe, but it came from the company. We double- and triple-checked.
That said, near-term, the business is tracking below annual targets. The number of new enterprises that went live with the platform was at an all-time high, growing the large customer base. But some doctor and hospital attrition offset some of this and weighed on growth.
Cash was $147 million at the end of 2016 compared with $142 million at 2015 end. Long-term debt was $18 million compared with the 2015-end level of $11 million.
BMR Take: All in all, management maintained 2017 guidance calling for revenue of $1.31 billion and annual bookings of $425 million. The prospects for the company are still bright. We think this week’s sell-off was overdone.
Google (GOOG: $801, -3%)
Planet Labs, a startup that launches small satellites into orbit and sells the imagery, is acquiring the Terra Bella satellite business of Alphabet in a bid to take on larger industry incumbents. In return, Alphabet’s Google is taking a stake in the startup. Google has agreed to purchase satellite images captured by Planet in a multiyear deal.
"It’s a big deal," said Will Marshall, Planet’s chief executive officer. "What this enables us to do is tap into new markets, like certain aspects of the financial markets, insurance and disaster relief." With the deal, Planet will receive seven high-resolution satellites that Terra Bella currently has in orbit. Planet plans to launch an additional six of Terra Bella’s satellites. They are larger than Planet’s existing satellites and offer up to six times better imagery resolution.
Google acquired its satellite division, then called Skybox Imaging, for $500 million in 2014. About 80 Google employees are heading to the startup which has raised more than $180 million. Marshall said the company does not plan to raise additional funds despite the influx of employees and equipment.
BMR Take: Google is at it again. The company is just doing things nobody else is doing. Through innovation, the company is creating its own growth path thereby controlling their own destiny. To re-visit the latest numbers, which were great, Google reported 4Q16 revenue of $26.1 billion, which grew 22% from a year ago and came in about 3% above the consensus. EPS of $8.81 also grew nicely from $7.06 a year ago and was about 7% above the consensus. There was much to like about the quarter - we can't highlight it all, but we will highlight this: Google demonstrated commitment to being an AI-first (Artificial Intelligence) organization with 350+ product launches enabled by AI in 2016. This is just great to see as we believe long term, AI is a mega-trend. All in all, the business is firing on all cylinders, we see compelling long term prospects ahead, and our $900 target is in reach as long as Trump doesn’t derail the stock market. If we hit that target we are raising it to $1000.
Visa (V: $86, +3%)
Visa climbed the most in the Dow Jones Industrial Average on Friday after fiscal first-quarter profit beat analysts’ estimates and the payments network said it expects to meet 2017 revenue forecasts even as a stronger U.S. dollar weighs more heavily on its business.
Revenue will probably increase 16-18% for the full year, the firm reiterated, even accounting for a bigger drag from currency swings. “I feel great about the future of Visa,” CEO Al Kelly told the Street. “We’re on track to meet our financial goals.”
Visa went on to discuss how it completed its roughly $20 billion purchase of Visa Europe, bringing the two firms together after eight years as separate companies. The deal is part of Visa’s strategy to increase its presence in the region and improve global digital offerings to better compete against Mastercard. Getting the event out of the way has been long awaited for.
BMR Take: We are very encouraged to see the stock performance and business results overcome foreign currency risks. The outlook for a stronger dollar could really hurt an international company like Visa. This week was very relieving. For example, foreign exchange effects weighed on growth by 3% this quarter. This figure could easily be greater than 10% in a more tough currency environment.
Upcoming Economic News
TUESDAY, FEBRUARY 7
Trade Balance – December
Time: 8:30 am
Forecast: -$45 billion
The advance report on trade in goods showed solid gains for both imports and exports in December, likely leaving the overall trade deficit little changed. Higher commodity costs and dollar strength helped turn trade into a major drag on last quarter’s GDP, subtracting 1.7% from the real growth rate.
FRIDAY, FEBRUARY 10
Import Price Index – January
Time: 8:30 am
Forecast: 0.2%
Gains in raw materials costs are projected to lift the Import Price Index in January for the fourth time in the past five months. Import prices have not been a major drag on broad price trends of late; the 1.8% yearly rise of the Import Index through December is the quickest pace in four years. While improved prospects for the commodities sector are lifting inflation pressures, renewed dollar strength can moderate the ongoing acceleration in prices.
University of Michigan Consumer Sentiment – February
Preliminary Time: 10:00 am
Forecast: 97.9
Sentiment in the February Michigan survey is expected to dip after ascending to the 13-year high in January. Continued strong jobs gains and quicker income growth can keep confidence above the average level seen during the current recovery. Yet elevated expectations can be curbed a bit as some of the more overly optimistic projections for economic growth may fall short of the mark.
A Letter from a Reader
From: John Tennant [mailto:jotenn@xxxxx.com]
Sent: Sunday, January 29, 2017 5:10 PM
To: Info@BullMarket.com
Subject: OPKO (OPK: $8.61)
Great Forbes article on CEO Frost of Opko. He just keeps buying his stock too, showing the tenacity cited in the article. I sure hope he continues his successful ways, as I am also a firm believer in OPKO and just bought more as the stock drifted below $8.50.
Regards, John
Our thoughts: John was referring to the Forbes article we told you about last week, which blew our mind. Here’s what we said last week:
“Frost is the CEO of Opko and after reading this article, if we at The Bull Market Report invested in our stocks, which we don’t, we would take a lot of our pennies and dollars and invest in this man. Read for yourself:
https://www.forbes.com/sites/schifrin/2017/01/03/meet-miamis-renaissance-billionaire/#3912053b7306
“The chart below lists all of Frost’s and Opko’s investments. This list is AMAZING, and we are not exaggerating. We would strongly suggest that some or all of them will pay off in the future.
https://www.forbes.com/sites/schifrin/2017/01/03/the-buffett-of-biotechs-portfolio/#5cd7e7c3a4a3
BMR Take: We have a Sell Price of $8 on the stock, but we are contemplating buying more if it hits this level. Stay tuned. And write us here after you read the article: Info@BullMarket.com. We would love to hear your thoughts.”
Tesla (TSLA: $251, flat) Morgan Stanley upgraded Tesla to $305. We note that the stock held steady last week after rising from $215 at the end of the year.
A Word From Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
What was GDP growth for 2016? It began with 0.8% the first quarter; 0.9% the second; 3.5% the third and then – uh oh – only 1.9% in the 4th quarter. That's well short of the consensus forecasts, and results in a very lackluster 2016 number for annual GDP growth of about 1.4%. Fortunately, earnings guidance for 2017 has been much better than what we saw this time last year. This is important because the market looks ahead, not behind. And, disposable personal income (income after taxes) increased 0.3% in December and is up 3.7% from a year ago.
It appears to us that President Trump is very intent on providing a clear and consistent pro-growth agenda. This should pave the way for the market to continue on a move towards a break above 2300 on the S&P 500 Index. The market reacted negatively to what is being described as "uncertainty" following President Trump's orders to curb travel and immigration from Syria, Iraq, Iran and four other countries on the grounds of national security. This type of "noise" will likely be around for the foreseeable future. Regardless of your political perspectives, moments of change can elicit emotional reactions from even the most rational investors. As always, emotions have no place in investing. Remember that "fear, greed or hope" will get you every time if you let your emotions guide you. That said, we agree with this recent comment from a market maven: "We believe that now is the time to continue focusing on quality U.S. companies with consistent dividend increases, earnings growth and strong fundamentals - not who is in the White House".
The problem we had the past eight years of getting to at least a 3% GDP rate was not so much the private sector, but rather expanding government largess. Before the Panic of 2008, government transfers – Medicare, Medicaid, Social Security, disability, welfare, food stamps, and unemployment insurance – had climbed to roughly 14% of income, which certainly didn't help prevent the recession. Now they're surged even higher to around 17%. Redistribution hurts growth because it shifts resources away from productive ventures and, among those getting the transfers, weakens work incentives. That's why, for the first time we still have a Plow Horse economy, not a Race Horse economy.
The RACE
In which we plot the prices of four of our favorites. Price of course is irrelevant, but fun to watch. So skip this if you think it is silly. But sometimes we like to be a little silly at The Bull Market Report
Google - $801, down $22.
Apple - $129, up $7 – but we have to reverse out the 7-1 split from 2014, so we get $903, up $49. WOW.
Facebook - $130, down 1 (but setting an all-time high Thursday of $135.) Again, we bring Facebook into the race by multiplying by 7, giving us $910. Facebook had its big run from $115 at the end of the year.
Amazon - $810, down $26.
Results: Google and Amazon fell sharply while Apple had an amazing week and almost caught Facebook. The Race heats up!
UPS Got Hit This Week
This $93 billion market cap company had a rough week. UPS (UPS: $107, down 9%) reported earnings this week. The company reported 4Q16 revenues of $16.9 billion against analysts’ estimates of $17.0 billion. Compared with 4Q15’s revenues of $16.0 billion, the company’s 4Q16 revenues rose 5.5%. On a yearly basis, UPS’s revenue increased to an all-time high of $61 billion in 2016. It was up 4.4% compared with the previous year. UPS Ground business segment saw revenue growth of 7.1% in 4Q16. The Cargo business saw revenue growth fall 12% on a year-over-year basis in 4Q16. During the 2016 peak season, UPS delivered more than 710 million packages around the world, representing a 16% growth compared with 2015. It’s all about e-commerce demand fueling the company’s record package volumes.
Management expects total revenues to grow 5%–7% in 2017, surpassing its historical norms. The company expects e-commerce continued growth to drive revenues. And they believe they will have the power to increase prices due to their size and strength.
BMR Take: We think the reaction on Wall Street was unwarranted and would look at the 9% price drop as an opportunity to buy the biggest and best delivery service on the planet. 710 million packages delivered last year? Two and quarter million packages a day for six days a week? This is strength. This is power. This will drive the company to the $150 billion club within 2-3 three years. And they are paying 3% a year to boot.
Apple Sells a Record Number of iPhones, Beating Expectations as Cash Hits $246 Billion
Apple reported Q1 earnings which not only beat on the top and bottom lines, but also sold a record number of iPhones - 78 million, 2 million more than expected. Earnings of $3.36 were higher than the $3.22 expected, on record revenue of $78.4 billion, above the $77.3 billion expected, and 3.3% higher than a year ago. Revenue in China declined by 12% in the quarter, the 4th consecutive quarterly decline in a row.
--- Gross margin: 38.4%
--- iPhone sales generated $54.4 billion in revenue, 69% of total. This compares to 2.5% in Q1 2008
--- iPhone average selling price: $695
--- Cash now at $246 billion, or $46 per share.
--- App store sales increased 40% YoY in the quarter.
Tim Cook had this to say: “We’re thrilled to report that our holiday quarter results generated Apple’s highest quarterly revenue ever, and broke multiple records along the way. We sold more iPhones than ever before and set all-time revenue records for iPhone, Services, Mac and Apple Watch. Revenue from Services grew strongly over last year, led by record customer activity on the App Store, and we are very excited about the products in our pipeline.”
BMR Take: Now that’s EXACTLY what we thought Cook might say! Seriously, we can see no reason why Apple won’t set a new all-time high sometime soon, as long as the market stays above 20,000 and in fact starts a run towards 21,000.
Twilio
JMP Securities upgrades the company less than a week before it steps up for an important earnings report. One of the most encouraging aspects of JMP Securities turning bullish is the timing of the move.
Twilio (TWLO: $31, up 6%) moved higher this week. The provider of cloud-based communications solutions got a boost after JMP Securities upgraded the stock from Market Perform to Outperform.
They show that developer demand remains strong for Twilio's platform that integrates communication features into existing applications. The Twilio sales team is having a hard time keeping up with all of the inbound leads, a good problem to have when it comes to assessing the dot-com darling's near-term growth potential.
They see a scenario where the stock could hit as high $45 if things go really well for Twilio, a call that would result in a pop of 50% if it plays out.
Twilio reports quarterly results Tuesday. An analyst firm jumping into the fray at this point implies a high degree of confidence in the call. They could have just waited six days for the report to confirm or debunk his refreshed thesis.
The stock has nearly doubled since going public at $15 seven months ago, but the shares have fallen sharply since peaking north of $70 in late September. JMP Securities says there is a real company here -- and it's hitting all of the right notes. And we at The Bull Market Report couldn’t agree more.
JMP says that developers behind some of the hottest apps -- from Uber to WhatsApp to Airbnb – have hopped on Twilio's real-time communications solutions. There were 34,000 developers on Twilio at the end of September, a 45% surge over the past year. We can’t be more pleased. Fingers crossed for a strong earnings report on Tuesday.
Letter to the Editor
Todd, Have you ever looked at Verizon (VZ, $49)? Might be good at this level ? Art
From: Art Weed
Our response:
Hi Art –
Yes, down from $54 – looks appealing. For us though, it is just too big. Almost $200 billion in market cap. Not that we don’t like big companies, but Verizon has have never really gone anywhere. It was $60 in 1999!! So, not for us.
Thanks for writing and good investing in 2017.
Todd Shaver, Founder and Editor in Chief
GoPro was down 13% to $9.57
Thursday, GoPro (GPRO) said it earned 29 cents a share on sales of $541 million in Q4. GoPro lost $115 million, or 82 cents a share.
GoPro went public in June 2014 at $24 and rose as high as $98 in October 2014 before flaming out. It hit a low of $8.55 on Dec. 15.
We’re glad we got out of this one in July at $13.
The High Yield Report
By Michael Foster
Special to The Bull Market Report
The biggest move this week was in BDCs. The UBS BDC ETC (BDCS: $23, down 2%) was the weakest of all high yield sectors. This sell-off happened for a very good reason: The industry has gotten far overbought. This overbought situation drove us to remove Main Street Capital (MAIN: $36) from our high yield portfolio and as we see growing risks with the sector as a whole. Main Street continues to be an outperformer in the sector, but we don’t like what we’re seeing in broader terms. The sell-off looks like the beginning of profit taking. This may reverse, but the risks seem much higher for this already risky sector. We want to jump back in and get 8% yields from companies that can provide credit to high quality smaller firms, but it’s going to take a while for this trade to become attractive again.
There is one additional concern to consider before jumping into a BDC: Dodd-Frank. BDCs were an unexpected beneficiary of greater banking regulations and “banker paranoia” about regulators breathing down their necks. Did you know the big banks are now spending roughly 25% of earnings on regulatory compliance? The overhead that regulations have put on banks, combined with the fear of public embarrassment, shame, and fines has driven investment and retail bank management to conservatism to a fault. This was most noticeable in 2009-2010 when it was almost impossible to get a mortgage with less than 25% down; the banks were just too paranoid to lend. Things are laxer now, but in the corporate finance world there is still a relative tightness compared to actual credit demand.
That’s where the BDCs came in; they could lend to firms that got turned down by big banks. Fueled by a clever common stock issuance structure that allowed them to expand when deals were possible, this industry exploded to fill demand. This was also happening when Treasury yields were crashing, so there was more investor demand for BDCs to get higher yields.
What if banks come back to lending to the middle market firms that now rely on BDCs? Surely more competition will be a headwind for the industry. That makes us wonder if paying a high premium to NAV for a company in the sector, even one as well managed as Main Street, is wise. And that keeps us firmly on the sidelines.
In the rest of the high yield universe, things were rather quiet. The SPDR Barclays High Yield Bond ETF (JNK: $37) and the Alerian MLP ETF (AMLP: $13.29) ended the week flat. High yield bonds are in a state of uncertainty at the moment as a result of higher interest rates (which is bad) but stronger economic tailwinds (which is good). On the one hand you have investors who worry that companies will struggle to refinance their debt load given higher servicing costs, but on the other hand you have investors who are certain that higher economic growth will translate into better revenues and profit margins that will counteract the servicing costs. And, of course, you have the issue of tax reform, which will also be a boon to American firms if it manifests itself. That could also give firms a lot more room to pay back loans, thus counteracting the higher interest rate issue even further.
What this tells us is that the interest rate hike paranoia of 2013-2015 is over. We’re now seeing capital flows being driven by new considerations and new developments in the market. This is a good thing. It means we can be less obsessed with Janet Yellen & Co. and focus on fund quality over all else.
That brings us to our favored high yield funds. The AGIC Equity and Convertible Income Fund (NIE: $19.26, down -1%) and the PIMCO Dynamic Income Fund (PDI: $29, up 1%) cancelled each other out and ended the week with relative stable pricing. This no action keeps us in a holding pattern and encourages us to stand pat on these two funds.
Finally, a quick word on municipals. Invesco Municipal Trust (VKQ: $12.67, up 1%) and the Nuveen AMT-Free Municipal Credit Income Fund (NVG: $14.59, up 1%) had a solid week of gains, with Invesco continuing to be a strong performer since our recommendation. We don’t see massive capital appreciation in municipal bonds anytime soon, but we think this sector remains overly ignored by investors looking for 7%-9% yields. This is folly when you can get tax-free yields of 4-5% that effectively becomes the same cash in hand as you’d get from 7% taxable yields. More investors will realize this, probably after they file their taxes. That in turn is going to increase demand for municipals. Fears about their tax treatment and again about interest rates are overly priced into these assets. Investors will come back to munis - and we encourage you to be there first.
Good Investing,
Todd Shaver, Founder, CEO and Editor
The Bull Market Report
Since 1998
January 24, 2017
by Todd Shaver | Jan 24, 2017 | Earnings Preview 6 AM
Blackstone (BX: $30)
Earnings Date: Thursday, before the market opens
Consensus: 4Q16
Revenues: $1.5B
EPS: $0.64
Year Ago Quarter Results
Revenues: $880M
EPS: $0.37
Key Things to Watch For in the Quarter
2016 started off slow for Blackstone, which missed EPS estimates in the first quarter, however it made up for its losses by outperforming in the second and third quarters. Analysts estimate that the fourth quarter will be another one of healthy growth. Earnings per share are estimated to grow 40% to $0.64 along with growth in revenue of 50% to $1.5 billion. Although the firm beat analyst estimates for the past two quarters, it still saw a decline in the stock following the earnings release. These small hiccups should not be looked at too deeply especially with its year-to-date performance of 20%. As one of the leading asset managers, Blackstone has seen significant gains over the course of the past year, contributing its success to its diversified investment vehicles including private equity, real estate and hedge funds.
*************************************************************
PayPal (PYPL: $42)
Earnings Date: Thursday, 1:30 PM ET
Consensus: 4Q16
Revenues: $3.0B
EPS: $0.42
Year Ago Quarter Results
Revenues: $2.5B
EPS: $0.36
Key Things to Watch For in the Quarter
PayPal reported its previous quarter in October with earnings that matched estimates of $0.35. The stock surged the next day, up 10%. Analysts expect 20% growth in revenue and 16% growth in EPS for the fourth quarter of 2016. Wall Street certainly reacts to earnings with this stock. In 1Q16, when PayPal beat earnings estimates, the stock fell nearly 5% by the end of the week. We saw an even more severe reaction to the second quarter’s earnings release when shares dove 9% to $34. PayPal remains a strong buy at The Bull Market Report, especially with management raising its 3-year outlook for revenue growth to a range of 16%-17% largely because of partnerships with credit card issuers and banks.
*************************************************************
Tesla (TSLA: $249)
Earnings Date: Wednesday afternoon (exact time not stated)
Consensus: 4Q16
Revenues: $2.0B
EPS: -$0.28
Year Ago Quarter Results
Revenues: $1.5B
EPS: -$0.87
Key Things to Watch For in the Quarter
The early quarters of 2016 were a struggle for Tesla as they underperformed compared to estimates. The first quarter earnings report received a negative response from investors as shares declined to $211 by the end of the week earnings were released. Shares remained relatively unchanged after the announcement of the second quarter 2016 earnings report. Tesla really surprised analysts in the third quarter however, when it reported EPS of $0.71 compared to estimates of -$0.54. Analysts estimate negative EPS for the fourth quarter of 2016, however earnings are definitely headed in the right direction. We continue to support our call about Tesla, especially with their stellar leadership from the great visionary Elon Musk.
*************************************************************
Bristol-Myers Squibb (BMY: $50)
Earnings Date: Thursday, 10:30 AM ET
Consensus: 4Q16
Revenues: $5.1B
EPS: $0.66
Year Ago Quarter Results
Revenues: $4.3B
EPS: $0.38
Key Things to Watch For in the Quarter
Bristol-Myers has exceeded analyst’s expectations for the first three quarters of 2016, however the stock has not responded positively. Shares remained relatively unchanged with the release of the first quarter’s earnings, however when the announcement was made for the second quarter, shares fell nearly $13. The stock reacted best to the earnings release for the third quarter, when shares climbed nearly 20% in the weeks following the release. Analysts estimate a 25% increase in revenue and a 73% increase in EPS for the fourth quarter of 2016. The stock is down nearly 20% over the course of the year, however with a low PE ratio of 24 compared to the Healthcare Industry’s P/E of 60, we like the buying opportunity that this lower prices presents to us at this level.
*************************************************************
Celgene (CELG: $112)
Earnings Date: Thursday, 9:00 AM ET
Consensus: 4Q16
Revenues: $3.0B
EPS: $1.59
Year Ago Quarter Results
Revenues: $2.5B
EPS: $1.18
Key Things to Watch For in the Quarter
Celgene has sustained healthy growth in earnings and revenue over the course of 2016. Although investors responded fairly negatively to the first quarter results, pushing the stock down 5% over the course of the following week, the second and third quarters definitely impressed. The second quarter release resulted in a 4% increase in the stock followed by a stunning 20% jump after the release of the third quarter earnings on October 27th. Analysts estimate a 20% increase in revenue to $3 billion, and a 41% increase in earnings per share for the fourth quarter of 2016. Shares have seen modest gains over the past year, climbing almost 5%. We continue to be bullish on Celgene with a target of $125.
*************************************************************
Alphabet (GOOG: $819)
Earnings Date: Thursday, 4:30 PM ET
Consensus: 4Q16
Revenues: $25B
EPS: $9.65
Year Ago Quarter Results
Revenues: $21B
EPS: $8.67
Key Things to Watch For in the Quarter
Alphabet shares have climbed 15% over the past year, making it one of the best performing stocks in our portfolio. Alphabet made up for its missed earnings in the first quarter of 2016 when it beat estimates in the second and third quarters. Investors responded with fear after the first quarter report. Shares dropped $70 over the course of the next week following the release, but had recovered by the time the third quarter’s earnings were released. Estimates for 4Q16 include a 19% increase in revenue and 12% increase in earnings per share. We expect unrelenting future growth from Alphabet, as the company continues to introduce society to technological innovation.
*************************************************************
Microsoft (MSFT: $63)
Earnings Date: Thursday, after market hours
Consensus: 4Q16
Revenues: $25B
EPS: $0.78
Year Ago Quarter Results
Revenues: $26B
EPS: $0.78
Key Things to Watch For in the Quarter
The first three earnings releases of the year were a bit of a roller coaster for Microsoft shareholders in 2016. Shares were down 10% following the release of the first earnings report. In the second and third quarters investors responded much better with shares climbing around 5% on each occasion. Analysts do not expect much growth from Microsoft in the fourth quarter. Earnings per share are estimated to remain the same as compared to last year’s fourth quarter, and revenues are expected to decline by 4% to $25 billion. Microsoft currently trades at a PE of 30, which is relatively low compared to its competitors. We remain bullish on Microsoft with a target of $66. The stock has increased 21% since a year ago.
*************************************************************
Amazon (AMZN: $818)
Earnings Date: Thursday afternoon (exact time not available)
Consensus: 4Q16
Revenues: $45B
EPS: $1.35
Year Ago Quarter Results
Revenues: $36B
EPS: $1.86
Key Things to Watch For in the Quarter
Amazon has made a killing for its investors over the course of the past fiscal year. The stock is 33% higher than a year ago. Amazon reported earnings of $1.07 and $1.78 in the first and second quarters, surprising analysts by 84% and 80% respectively. The 10% jump in the stock following the first quarter highlighted investors’ excitement with the company. Analysts expect EPS for the fourth quarter of 2016 to decrease by 33% to $1.35. However revenue is expected to increase by nearly 25% to $45 billion. The recent holiday season once again proved the migration of consumers from brick and mortar to online shopping, keeping Amazon at the helm of our picks with a target of $1,000.
January 22, 2017

by Todd Shaver | Jan 22, 2017 | Weekly Newsletter 7pm Sunday
The Week Ahead
This week will be a thriller. President Trump and his cabinet of business leaders will be laying out action plans for a new governing structure for America. Carl Icahn said we haven’t seen a structural reform like this in government in a generation. In this newsletter, we provide some insights on our latest thinking for Bristol-Myers Squibb, Splunk, Kinder Morgan, VMware, Visa, Home Depot, Invesco Municipal Trust, Under Armour, Tesla and Netflix.
Highlights From The Past Week
Trump releases formal agenda. According to a statement posted on the White House website, President Trump’s economic plan will create 25 million new jobs in the next decade, return to 4% annual economic growth, lower rates for Americans in every tax bracket, simplify the tax code, and reduce the U.S. corporate tax rate. We’ll see how Congress will modify these lofty goals.
A few ways the markets could be surprised, according Credit Suisse. The S&P 500 hits 2,500 before falling back to 2,000, versus the consensus view of the index going to 2,300 and leveling off. The Euro falls to $0.90 then strengthens sharply to $1.20, versus consensus outlook for moderate drift to $1.00. Chinese GDP growth slows to 5%, versus consensus of 6.8%. Trump’s policies don’t work, as inflation expectations rise and protectionist policies disrupt world trade. Oil prices hit $75 by year end, versus consensus outlook of $62.
Wake up call. Yes, American politics is not great. But at least we aren’t Brazil. The death of Brazilian Supreme Court Justice Teori Zavascki who had presided over the sprawling "Carwash" corruption scandal, and who died yesterday in a freak airplane crash Thursday has sent shockwaves both around the globe and in Brazil, because while few in polite company will discuss it, it has opened the possibility of political assassinations as a means of "quieting" legal proceedings.
BMR Companies and Commentary
Bristol-Myers Squibb (BMY: $49, -12% for the week)
Bristol-Myers announced that it has decided not to pursue an accelerated regulatory pathway for the combination of Opdivo plus Yervoy in first-line lung cancer in the United States based on a review of data available at this time. In order to protect the integrity of ongoing studies, the company will not be providing additional details. This news sent the stock price tumbling this week.
The situation is just very unfortunate. As Citi’s analyst put it, “We never believed Bristol-Myers had an accelerated pathway to market for Opdivo and Yervoy in front line lung cancer.” This was just totally botched communication by management. As the Citi’s analyst went on to put it, “On a fundamental basis, in our view, nothing has really changed aside from credibility in the guidance.”
What happened? Some people in the investment community started speculating Bristol-Myers could take the accelerated regulatory pathway to catch up to Merck on developing imuno-oncology. The company never stated this. Bristol should have been more vocal that this strategy was not in the cards. They needed to be more pro-active.
The reality is unfortunate for us shareholders having to stomach the near-term volatility. But we should not be worried about the long term picture. As the company put it, “Our vision for the future of cancer care is focused on researching and developing transformational Immuno-Oncology (I-O) medicines that will raise survival expectations in hard-to-treat cancers and will change the way patients live with cancer.”
BMR Take: Bristol is still going to do great things over the long term in cancer and healthcare. We are excited about it. If you aren’t involved in Bristol yet, lucky you. If you have some shares and you have some additional cash to put into this company, we would do it. The shares under $50 are a screaming value. This is an $82 billion market cap behemoth in Healthcare we are talking about; not some pre-revenue biotech moonshot.
Splunk (SPLK: $54, -5%)
Splunk recently hosted its analyst day setting the stage for the stock to rock and roll. Specifically, management laid out monster guidance. Management spoke of the path for Splunk, which is expected to end 2016 at nearly $1 billion in revenue, to hit $2 billion in revenue and $2.3 billion in billings in 2019. This path is driven by accelerating customer growth (with Splunk ending 2019 with 20,000 customers, up from 12,700 in 3Q16; growing deals over $1 million (reaching 300 such deals in 2019, up from 140 in 2016), and the license average selling price growing from $55,000 in 2017 to $80,000 in 2019. This guidance suggests a 3-year revenue growth rate of 29% annually.
On top of the revenue picture, management said that at $2 billion in revenue, Splunk is expected to more than double its operating margin from 5.5% (the midpoint of 2016 guidance) to 12-14% in 2019, mostly through sales and marketing leverage. Wow!
BMR Take: We like Splunk because: 1) it is the leader in operational intelligence software that helps enterprises make sense of machine data; 2) it addresses a large and expanding market; 3) its model is becoming more predictable as the revenue base grows; 4) the company has a long runway to sustain 30%+ growth; and 5) we believe its strong business momentum will continue.
Kinder Morgan (KMI: $22.50, flat)
Kinder Morgan reported earnings of $0.08 per share, which was better than the $0.32 loss reported a year ago, but not as good as consensus analyst expectations for $0.18. There were minor disappointments causing some weakness in the stock after the announcement, but expectations were and remain low and overall you should walk away from the quarterly results feeling that operations are in a stable to improving place.
The company plans to invest $3.2 billion in growth projects during 2017, which it says will be funded with internally generated cash flow without the need to access equity markets. We are encouraged to hear the word “growth” being discussed in the Energy market nowadays.
Even though Kinder Morgan's balance sheet remains of a concern for us, the company did significantly enhance its credit profile by reducing debt by over $3 billion during 2016. You have to give them some credit. In fact, they finished ahead of plan for 2016 year-end leverage, and are progressing toward reaching the targeted leverage level of around 5 times debt to earnings, which will position them to return substantial value to shareholders through some combination of dividend increases, share repurchases, additional attractive growth projects or further debt reduction.
BMR Take: We remain bullish on the rebound for Kinder Morgan along with the rest of the MLP sector. Kinder Morgan has an unparalleled asset footprint spanning the breadth of the United States with leading North American industry positions in each of its five business segments – Natural Gas Pipelines, CO2, Products Pipelines, Terminals, and Kinder Morgan Canada. They really have a great franchise here.
VMware (VMW: $83, +1%)
We are excited to now be involved in VMware. The company’s server virtualization technology helped spark the cloud computing phenomenon. VMware has nearly doubled revenues in the last five years, growing from $3.8 billion in 2011 to $6.6 billion last year. We think there is more room for this bull to run.
Sanjay Poonen is chief operating officer at VMware. He joined VMware in 2013 from SAP, where he was responsible to “build bridges” between the data center and the public cloud, and to the end user through better mobile tools. Serving enterprise mobile users is an effort SAP began in earnest in 2014, with the acquisition of mobile device management company AirWatch. Now VMware has Poonen working on building a similar strategy for shareholders.
VMware sees the hybrid-cloud model as an extension of VMware’s original mission. In a hyper-cloud setup, storage, computing and networking capabilities are integrated and handled largely by software, rather than hardware. The “single box” can save companies from having to buy separate components to integrate manually. Managing a unified system through software also lets technology executives to make changes, such as adding storage space, more easily and less expensively than performing the same changes on individual pieces of hardware and software. It better technology for users. It’s cheaper for users. It’s a major win.
BMR Take: Hybrid-cloud is changing the economics of enterprise IT. VMware is going to win a good chunk of the opportunity. Partnerships are already in place with Amazon and IBM.
Visa (V: $82, +1%)
Walmart reached an agreement to continue accepting Visa credit cards across Canada, ending the retailer’s threat to bar the world’s largest payments network from its 410 stores in the country.
Walmart’s Canadian unit threatened to expel Visa from all of its stores nationwide unless the network agreed to lower the amount it charges for credit-card transactions. Walmart Canada, which has said it pays more than $76 million annually on credit-card transaction fees, called the amount Visa charges “unacceptably high.”
BMR Take: What a battle royal. Visa versus MasterCard. Not quite as good as Ali vs. Frazier. The bad news is that they had to cut their fees. The good news is that Visa didn’t lose the battle and will reap huge revenues from the largest retailed in the land.
Home Depot (HD: $136, flat)
Home Depot has fallen right in the middle of a big debate. The Republican border-adjustment proposal aimed at taxing imports may pressure retailers’ earnings by driving up the cost of their inventory.
However, gauging the plan’s exact impact on retailers including Home Depot is difficult because the companies do not break out what percentage of their inventory is imported, and many goods produced in the United States rely on imported material.
Trade associations for large retailers have been voicing opposition to the proposal, with the National Retail Federation saying it is a “scary proposal with a lot of unknowns.”
One analyst’s research that suggests the tax bills of six large retailers may jump about $15 billion to a total of $28 billion under the current House plan, though some advocates say currency adjustments will offset the tax changes and mute retailers’ objections.
BMR Take: Trump’s first 100 days will be loaded with market moving events. We will be closely watching the border-adjusted tax situation. Trump is already backing away from the proposal saying it is too complicated. So the outlook is all clear for the moment.
Invesco Municipal Trust (VKQ: $12.51, flat)
The recent blow-up of the Dallas Police and Fire Pension System was entirely predictable. While it is tempting to blame unusual circumstances for the recent lock-up of redemptions and substantial reductions to pensions for those still in the fund, many other American pension funds are heading down the same road.
The combination of overpriced financial markets, inadequate contributions and overly generous pension promises mean dozens of US local and state government pension plans will end up in the same situation. The simple math and political factors at play mean what happened at GM, Chrysler, Detroit and now Dallas will happen nationwide in the coming decade.
Pew Charitable Trusts research estimates a $1.5 trillion pension funding gap for the states alone, with Kentucky, New Jersey, Illinois, Pennsylvania and California going backwards at a rapid rate. Using a wider range of fiscal health measures the Mercatus Center has the five worst states as Kentucky, Illinois, New Jersey, Massachusetts and Connecticut. The five state pension plans in Illinois have an average funded ratio of just 38%.
BMR Take: All the above is not good and is unsustainable. It’s weighing on Invesco Municipal Trust. But honestly, it is not as bad as it sounds. One needs to be more specific and not paint everything with the same brush. Take for instance the Dallas Texas credit in the portfolio. They are getting crushed on this pension news story. But the reality is Dallas is one of the most vibrant cities in the America. You can pick-up some of the general obligation bonds of the city at a 4% yield right now compared to the benchmark curve at just 2%. They are rated AA too!
Upcoming Economic News
TUESDAY, JANUARY 24
Existing Home Sales – December
Time: 10:00 am
Forecast: 5.50 million
December existing home sales are forecast to decline after rising a 9-year high in November. The Pending Home Sales Index fell to the 10-month low in November, a warning that existing home sales have lost some momentum. Yet some buyers are looking to move before mortgage rates potentially rise further, as the moving 4-week average of mortgage applications for home purchases recently rose to the highest level since last June.
THURSDAY, JANUARY 26
New Home Sales – December
Time: 10:00 am
Forecast: 585,000
New home sales may have dipped in December after reaching a 4-month high in November. But the long-term sales trend has been stellar, with sales of new homes rising 20% year-over-year in the quarter ending November. And sales still have much more room to grow to get back to historically normal levels relative to the size of the population. The most recent monthly new home sales pace trails the average of the past 20 years by 19%.
Leading Economic Indicators Index – December
Time: 10:00 am
Forecast: 0.5%
Spikes in stock prices and consumer confidence can power the Leading Economic Index in December to the largest gain in five months. The policies of the incoming administration will determine if this burst in optimism can translate into a sustained upturn in growth. Yet quickening wage growth gives a clear signal that consumers now have more resources to increase spending.
FRIDAY, JANUARY 27 GDP
Fourth Quarter (Advance Estimate)
Time: 8:30 am
Forecast: 2.1%
A widening trade gap is expected to lead slower GDP growth in the fourth quarter after reaching the fastest rate in two years in the previous quarter. The future effects of trade on US output are rife with uncertainty with regard to the evolution of policy and the value of the dollar. But the underlying pace of consumer spending is holding firm, getting a lift from the recent upside surprise in auto sales.
Durable Goods Orders – December
Time: 8:30 am
Forecast: 2.2% overall, 0.4% ex transportation
Solid recent indicators for industrial demand hint that Durable Goods orders can rise for the fourth straight month in December. The new orders reading from the ISM Manufacturing Index jumped to the two-year high of 60.2 last month, raising expectations for near-term industrial output. Core durable goods orders have also shown similar vigor of late, rising at the 2-year high rate of 5% annualized in the three months ending November.
University of Michigan Consumer Sentiment – January
Final Time: 10:00 am
Forecast: 98.0
The final reading on sentiment in the January Michigan survey is forecast to show only a mild decline from December’s multi-year high. Significant increases in consumer inflation expectations in the initial January survey signal that prices are poised to accelerate a bit.
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services
Earnings season will continue this week. Fourth quarter results for several of the largest banks were announced last week - JPMorgan Chase, Bank of America, Wells Fargo and PNC – and they were generally quite strong.
Remember – earnings for 3Q16 were up 3.1%, which broke the back of the preceding 6-quarter earnings recession. According to Thomson Reuters, earnings for the S&P 500 are expected to increase by 6.1% in the fourth quarter. Last year still didn't see 3% GDP growth, but expectations are for that plus more this year. UBS's pre-Trump forecast was for earnings growth of 5.9% in 2017, and that figure is expected to be revised higher based on the implementation of Trump economic policies.
The biggest question marks for 2017 may not come from economic data alone, but instead, from changes in political leadership. As everyone knows, stocks have already rallied on hopes that President-elect Trump will reduce regulation and taxes while increasing infrastructure investment. However, no one knows for sure what actual changes could be on the horizon - or how Trump's policies will affect trade. Or how Congress may bottle up his potential policies. Trump will lay out an economic "game plan" which could ease some of the market uncertainty that still swirls around the dramatic change in Washington politics. One thing we are concerned about is the formula of “Hope + Uncertainty = ?” In our experience, the answer to that equation is most often "volatility".
Meanwhile, the market still functions on basic fundamentals [and as noted above there are lots of economic reports coming out this week.] And, investors will be watching oil prices, along with gold, the dollar and interest rates. That's because the investment landscape has changed from the expectation of lower interest rates and slower growth for longer periods of time to the possibility of moderately stronger growth and a stronger dollar with higher interest rates due to potentially higher future domestic inflation.
• Oil Prices - Oil began the new year higher as U.S. Crude rose to $54 a barrel.
• Gold - Gold has recovered a bit to start the year, closing at $1210 an ounce on Friday.
• U.S. Dollar - The U.S. dollar index continued to show strength.
• U.S. Treasury Rates - The yield on the benchmark 10-year Treasury settled at 2.47%.
Tesla Motors (TSLA; $245, up 3%) Tesla continues higher. From a low of $181 in early December, the stock is up 35% reaching $39 billion in market cap and stretching for the all-time high of $275 in the summers of 2014 and 2015. What will this summer bring? Good question, but we will tell you that this summer the firm will be a lot closer to delivering the new exciting Model 3 that they are holding 400,000 $1000 deposits on. That’s $400 million in cash that the firm can use for corporate purposes.
Tesla saw some upgrades on Wall Street recently. Morgan Stanley raised their Target to $305 from $242. Goldman is stuck at $190. Wake up Goldman! Robert Baird is looking at $338 and Guggenheim has a $280 target in place. There are six Sell Ratings, 11 Hold Ratings and 12 Buy Ratings. We maintain our Target Price of $290.
Under Armour (UA: $25.16; UAA: $29.02) Two things here. First, the stock. The Class A shares trade under the symbol UA, and the Class C shares trade under the symbol UAA. They both have close to 200 million shares outstanding and the average volume for both is around 3 million a day. But, the company has changed the voting rights of each class of stock. The UAA shares have one vote per share. The UA shares have none. Many other companies have done this, primarily so the founders can maintain control. Google has done it – GOOG has no voting rights, GOOGL has one vote – same story as Under Armour. And there is a class B share in both companies that actually have 10 times the voting rights of the Class A shares. Guess who owns the Class B shares? Kevin Plank, the founder.
BMR Take: Both classes of stock are fine for us, the small investor. Ultimately the UA shares will have more liquidity as the UAA shares are retired, so go with the UA shares if you are buying new positions.
Secondly, the company. What can we say? The company had a bad year and the stock has been hammered. We believe that over the course of the next five years the firm will grow and prosper dramatically. With the stock this low (trading at the same level as 2014), we see tremendous value here. The all-time high is $50 set in the summer of 2015 and we see no reason why it won’t hit this level again. Yes, that’s right – a double from here.
Look at revenues: $2.3 billion in 2013, $3.1 billion in 2014 and $4.0 billion in 2015. We think they could hit $5 billion in 2016 when they report 4th quarter earnings on January 31st. We think they will hit $6 billion in 2017. Long story short – we think this is a huge growth story – the kind of company we would love to own for the coming decade.
Netflix killed last quarter. Netflix (NFLX; $139, up 4% to a new all-time high)
The bad news: The DVD service shed 160,000 subscribers during the final three months of last year to end December with 4.1 million customers. That’s an 11-year low. But the business hangs on and is VERY profitable.
The good news: The streaming service now boasts 94 million subscribers in 190 countries, after adding another 1.9 million in the U.S. and 5.1 million in overseas markets during the final three months of last year. One firm predicts Netflix will have 160 million streaming subscribers by 2020. The company is coming off its biggest quarter of customer growth yet.
The financial quarter for Netflix was huge. The company reported revenues of $2.48 billion, up 36% from $1.8 billion. Earnings were $66 million, up 55%. Cash flow – up 125%. These are huge numbers. One small problem, their earnings equate to only 15 cents a share. They need to beef this up in the coming quarters and years. We think they can and they will.
The stock has blown through our Target of $133. We still like the stock and think it is going much higher over the coming decade. We hereby raise our Target to $165 and raise our Sell Price to $125.
We had a question from a reader about our new Invesco Municipal Trust recommendation (VKQ: $12.49)
From: Bob Valentine
Sent: Thursday, January 19, 2017 2:59 PM
To: info@bullmarket.com – The Bull Market Report
1. Just because bonds can be called, why do you think they will be called over the next couple of years?
2. Your research report says 25% of the fund’s assets will or could either mature or be called over the next two years. Can you send me your calculation as I do not come close to this.
3. Why do you think bonds that are maturing will be invested at higher rates than what they are already invested at? it appears possible that they will have to be invested at lower rates based on my review.
Here is our response:
Hi Bob –
1. Bonds tend to be called when debtors can get a lower interest rate. This may still be possible for municipalities if they call shorter-term bonds and issue longer-term ones or if their credit quality improves. In a rising interest rate environment, there’s good reason to call short-term bonds and issue new long-term bonds to lock in lower interest rates. Of course in a falling interest rate environment (which is extremely unlikely right now) you call bonds and issue new ones to cut down your interest costs.
2. The article does not say 25% of the fund’s assets - it says 25% of the bonds. That’s an important difference. Look at all of the portfolio here:
http://hosted.rightprospectus.com/Invesco/Fund.aspx?cu=46131J103&dt=AR&ss=ce
You’ll see that 20 holdings expire in 2017 and 32 expire in 2018. There are a bit over 200 bonds in the portfolio total, meaning nearly a quarter of its bonds will either be called or redeemed by the end of 2018.
3. Interest rates have gone up for all municipal bond indices over the last year, see here:
https://www.bloomberg.com/markets/rates-bonds/government-bonds/us
Thanks you for writing, Bob.
Todd Shaver and Michael Foster
The Bull Market Report
The High Yield Corner
By Michael Foster
Special to The Bull Market Report
The biggest news for markets and the world was the inauguration of President Trump. The markets’ response to this news was muted. at the start of the new President’s speech, stocks dipped but by the end of Friday, all of the major indices had recovered to pre-speech levels.
The excitement that gripped political pundits and policy junkies has been a non-starter for us more economically- and financially-minded types. You can see this by tracking the changes in asset classes around the election according to retail investor interest. More esoteric asset classes like junk bonds and market volatility were relatively unmoved. The SPDR Barclays High Yield Bond ETF (JNK: $37) stayed pretty much flat before and after, and ended the week flat. We also saw trading volumes below average for this ETF and for the asset class as a whole.
This observation leads us to a much more pressing issue: The market is losing steam. If you look at the S&P 500’s performance since the election, you see a hockey stick jump after the slight pre-results dip. That bull run peaked on December 13th and the index has not recovered from that level since. But it hasn’t crashed either (we’re less than 1% down from the all-time high). Instead, we’ve seen a tight range of around 2% movement from top to bottom in the last month - and the bottom was at the end of December, where tax-loss harvesting is to be expected. The market quickly recovered, but has stayed flat since the start of 2017 excluding the recovery on January 3rd.
What does this mean? It means the bull run has either stopped or is taking a pause. It may come back before turning into a bear trend. This will ultimately depend on upcoming economic data over the next few weeks, especially unemployment, CPI trends, and GDP estimates. None of these are expected to be weak, so a slight miss probably won’t cause a huge decline.
But markets are fickle. One bad note, however minor, can lead to a panic. We remember the start of 2014 when weak manufacturing data from China led to a huge market correction; investors were terrified that this single data point was the canary in the coal mine, and a broad global slowdown was in the works. This didn’t happen and the markets recovered, but this kind of irrational response to one data point is always possible after a long-term bull run loses steam. This bears watching right now.
For these reasons there is good reason to be cautious in the short term and keep some dry powder available to buy heavily discounted assets. When it comes to high yield, we remain constructive on all of our recommendations but the possibility of a major price correction in these assets in the short term is greater than it has been since last summer. Investors should keep this in mind.
Alongside junk bonds, most high yield asset classes showed little signs of life this week, staying mostly flat. One exception was The SPDR Dow Jones REIT ETF (RWR: $93, up 1%) as REITs continue their recovery from the summer sell-off that extended after Trump’s victory.
We’ve remained positive on selected REITs, and our picks once again outperformed the sector. Digital Realty Trust (DLR: $106, up 2%), Omega Healthcare Investors (OHI: $32, up 3%), Kimco Realty (KIM: $25, up 2%), Government Properties Trust (GOV: $19.80, up 2%), and Care Capital Properties (CCP: $25, up 1%) all saw higher price growth this week, and once again it’s interesting to note that the more volatile picks in our REIT portfolio did not go up significantly more than the lower-volatility ones. This is often a sign of complacency, but it seems a bit early to come to that conclusion for REITs. It does however suggest that one may want to wait for a correction before adding more in these assets, and instead look for alternatives in the high yield space.
For alternatives, The AllianzGI Equity and Convertible Income Fund (NIE: $18.80, down -1%) offers a yield as strong as REITs without leverage despite the fund’s strong holdings in high quality firms in various sectors. The fund’s discount is now over 12%, slightly lower than its historical average but not significantly so. There is a chance, but not a certainty, that a major market correction would lower this fund’s NAV and cause the discount to widen, bringing its price lower, which would make it a great buy. How low can it go? Assuming a 5% market correction and a premium widening to 17%, which is at the extreme end of the fund’s historical trend, we could see the stock fall to around $16.90. That’s a full 10% lower than its current level, so there is a lot of downside potential here. With that in mind, an investor who wants to invest cash now might be wise to buy some NIE, wait and track the markets for the next month, and buy more if the market falls by around 5%.
Keep in mind that these short-term market timing strategies are not for the faint of heart and involve some level of risk. Nonetheless, a post-bull run flat market like this very frequently results in a short-term correction. Making some liquid assets available for such an opportunity can often result in higher long-term returns and, most crucial for the high yield investor, provide opportunities to buy high quality assets and get a high dividend yield.
Good Investing,
Todd Shaver, Founder, CEO and Editor in Chief
The Bull Market Report
