January 19, 2017

by Todd Shaver | Jan 19, 2017 | Monthly Newsletter Daily 6am if new
The Week Ahead
We are quickly approaching Donald Trump’s Friday inauguration. The event will mark a key inflection point for the markets. After the big rally in stocks and sharp sell-off in bonds following the November election, a plethora of expectations for the future will soon meet the reality of what is possible, as we move into the first 100 days of the President’s term.
This week we provide some insights on our latest thinking for Amazon, Facebook, Google, Netflix, Bristol-Myers Squibb, and Tesoro Petroleum.
Highlights From The Past Week
Recession Watch. History has shown us that a recession has generally occurred during the first term of a new president, especially when following a two-term presidency. Could this be the case this time around? The leading economic indicators (LEIs) are positive, and there has never been a recession without those indicators going negative. CEO confidence is moving up and consumer confidence is exploding, which seemingly points to the likelihood that a recession is not imminent. We are not big believers in patterns, to tell you the truth. So we are leaning towards a continued strong economy and a continued bullish stock market.
There may be a Trump backlash coming though. You know, the one we expected in November after the election. We have talked to a number of our subscribers and many of you are worried about this. Our suggestion is that if you are worried so much so that you are losing sleep, with commissions as low as they are in this century, it is easy enough for you to sell those stocks that make you nervous and look to some of the issues in our High Yield Portfolio. They are generally more stable than other stocks.
However, there is also talk that the Trump presidency could be the best thing Wall Street has seen in a long time. Cutting taxes, bringing back the huge horde of cash overseas, tackling the infrastructure building that needs to be done, etc.; these are all things that could help the economy. Dow 25,000 soon? Oh wait – we haven’t hit 20,000 yet! Stay tuned.
Interest Rates. If the economy continues to grow steadily, the US Treasury 10-year Note could hit 6% in four years, about the time of the next presidential election, up from its current level of 2.4%. Inflation and economic growth are already at levels similar to 2006, when interest rates were at that level.
Stronger dollar. The dollar holds a unique position in the global economy, and a rapidly rising dollar exchange rate has historically caused something somewhere in the global economy to break. Those in emerging markets that have borrowed in dollars face the reality of a liability stream that has become more expensive to repay. Meanwhile, the second largest economy on the planet, China, has informally pegged the yuan to the dollar. A stronger dollar generally means a stronger yuan; a stronger yuan means a less competitive export sector for an economy that is all about trade.
BMR Companies and Commentary
Amazon (AMZN: $817, +3% for the week)
JP Morgan Chase is offering a new, co-branded Visa rewards card through Amazon that offers compelling rewards for both Amazon Prime purchases and all other purchases outside of Amazon. Specifically, the new Chase card offers 5% cash back on all Amazon purchases by eligible Amazon Prime members. This deal marks another win for Amazon deepening their existence in banking.
How about the core business of Retailing? What started out as an online bookseller is now on pace to overtake Macy’s as the world’s largest apparel retailer, a startling development when you remember that e-commerce was once considered an impossible way to sell clothing. Amazon has reportedly recorded record holiday season sales at the same time that traditional department stores, including Macy’s, Sears, and Kohl’s, have reported declines. These companies aren’t adding thousands of new workers like Amazon. To the contrary, Macy’s plans to close 100 stores to improve profitability, and Sears has sold its Craftsman tools line for $900 million to raise cash.
BMR Take: Amazon is currently not far from its all-time high of $844, set in October. There is still the potential for upside for investors here, and the stock could go even further, perhaps passing the $1,000 mark sometime in 2017 or 2018.
Facebook (FB: $128, +4%)
Facebook has underperformed the Nasdaq since the company’s 3Q16 earnings report, due to a number of factors, including concerns about slowing growth, heightened expenses in 2017, and sector rotation out of Technology.
Investors have also cited concern about the headwind from a possible 1Q17 IPO of Snap. As far as the competitive risks of new more exciting Tech IPOs stealing away investors from Facebook, any impact is likely to be temporary and potentially more modest than investors fear. Press reports suggest that Snap (aka Snapchat) was considering an IPO as early as March at a valuation as high as $40 billion. Given that Snap’s IPO will represent the largest tech IPO since Alibaba went public in 2014, some investors have begun to question how the issuance may impact existing public market Tech stocks and in particular its closest comp, Facebook.
BMR Take: Yes, it has underperformed since November, but it has been on a TEAR since the start of the year. Be advised that the upcoming Snapchat IPO will be all over the headlines, but don’t sell your Facebook over this. Facebook’s long term prospects are fantastic. Facebook is fast approaching its all-time high of $133.50 set in October. And fast approaching 2 billion users. The company adds 1 million subscribers every two days. With growth of 35% a year projected for the next two years, the stock is not over-priced.
Netflix (NFLX: $134, +2%)
A big name stock analyst that was short Netflix covered his call this week. It’s nice to see them come join our camp. There is so much to like about Netflix. In fact, the stock hit an all-time high of $133.93 this week!
On the heels of new details about Hulu’s upcoming live TV offering (pricing, content lineup, etc.), Netflix reiterated that it has no plans to make any other meaningful changes to its business model or content strategy, stressing that the simplicity of its offering is a key advantage.
The company has also evaluated the merits of an ad-supported model but continues to believe that focusing on its core business provides the greatest return on investment. Looking back at Netflix’s pricing changes and the un-grandfathering it worked through in 2016, the company feels good about its pricing power and is satisfied with the outlook. They also expect future price increases to be more staggered by country/region rather than by universal global changes.
While Netflix intends to keep pricing relatively consistent globally, in Japan, for instance, it has a lower price for its lowest tier ($5/month) in order to address Netflix’s more limited brand recognition in that market (i.e., to better spur new user adoption).
Netflix now has 50%+ of its content catalog available for downloads on Android and iOS today, and it expects that percent to increase. The company is increasingly self-producing content, which it believes can ultimately be 30%+ cheaper than licensing. Like what began in 3Q16, this will continue to impact cash burn in the near-term given the up-front costs associated with producing content.
BMR Take: Netflix is changing the game for television. We continue to believe they are on a long term path to 2020 EPS of $10 where a 20x PE multiple supports a $200+ valuation.
Google (GOOG: $808, flat)
Speaking of the future of media, Google’s YouTube is just crushing it. We highlight the following data points tracking YouTube through December 2016:
--- YouTube worldwide video views for the top 1000 publishers in December 2016 totaled 70 billion, which was up dramatically from last year. This brings total cumulative views on YouTube for these top publishers to 1.97 trillion – wow. On a trailing three-month basis, total views were 190 billion - these numbers are astronomical! In November 2016 alone, videos uploaded to YouTube generated 147 Billion views, both organic and paid.
--- The total number of subscriptions to the top 1000 YouTube video publishers’ channels was 3.9 billion at the end of December, adding 120 million channel subscriptions in the last month alone, up nearly 70% from this time last year.
--- The total number of videos available on YouTube from these top publishers was 5 million at the end of December, accounting for 19% more content on the platform than in December 2015.
BMR Take: If these numbers don’t describe a healthy business, we don’t know what does. We view Google as a core holding, given: 1) the company remains a top player in the internet space 2) management's track record of execution, 3) the potential to maintain double-digit earnings growth for many years, and 4) attractive valuation.
Tesla (TSLA: $238. Up 4%) has been on a tear. At $182 on December 1st, the stock is up over 30%. The company just opened a showroom in Aspen and the place is packed. I met a friend on the street on Friday and motioned for him to come in. Guess what: He is taking a test drive next week and might buy one of the Model X’s that start at $85,000. 0-60 in 2.9 seconds. Call it a cult, or call it what you will, but this company is real and this company is exciting. With Saturday’s Space X launch of 10 satellites on the Falcon 9 and then landing the rocket on the drone ship in the ocean, Elon Musk’s star is riding high. Musk sent out this Tweet:
Elon Musk @elonmusk
Mission looks good. Started deploying the 10 Iridium satellites. Rocket is stable on the droneship.
BMR Take: We’ve said many times before in these pages that the stock is not for the conservative and that the stock could go to $150 before it goes to $250 due to its volatility, but we will tell you that this stock could go to $400 this year or next. We hereby raise the Price Target from $250 to $290 and raise the Sell Price from $150 to $180.
FAANG Stocks Bite Back Adding $90 Billion In Market Cap Over the Past Two Weeks. Technology stocks have found a cure for whatever was plaguing them during the early stages of the Donald Trump bull market. In especially brisk health is the FAANG block of Facebook, Amazon, Apple, Netflix and Google, which have rallied at 3.8% on average this week, poised for their best performance since October. About $85 billion has been added to their value as investors rotate back into post-election laggards. FAANG stocks were oversold after the election, although there’s likely no real impact from a Trump administration on the highest quality internet names. These five stocks could potentially outperform in 2017, despite pretty clear skepticism among almost all investors, who see a sustained rotation away from growth stocks in the wake of the Trump election. Not us. We are sticking with them. Like glue.
Alphabet (GOOG: $802, up $30)
Apple (AAPL: $119, up $3)
Facebook (FB: $127, up $12)
Amazon (AMZN: $808, up $58)
Netflix (NFLX: $140, up $16)
The Border Tax
Notes at the Margin
Philip K. Verleger, Jr.
Former Director of the Office of Energy Policy
at the United States Department of Treasury
The House of Representatives’ Republican leadership seems set on pushing the plan through despite suggestions from some experts that it is a bad idea. Indeed, their determination to pass the law seems palpable even though major economic players such as James Bullard, president of the Federal Reserve Bank of St. Louis, have admitted publicly that they do not understand the concept.
Still, for the world’s oil industry, it is critical to understand the border tax quickly. Why? Because its passage will likely change oil flows completely. Most US oil producers would have every incentive to sell at home and none to export. Bluntly speaking, for oil the law’s passage is pure mercantilism. Exporters from Mexico, Canada, and the rest of the world could be shut out.
How might this happen? Start with the fact that the “Made in America” price could be 25% higher than world prices. The boost occurs because US producers would pay no tax if they export oil while US importers would pay a 20% tax. This means US producers would receive $50 per barrel if they export. On “paper,” at the margin they would have to pay a 20% tax if they sell to domestic buyers. This means those buyers would have to pay $62.50 per barrel in a $50-per-barrel world for the domestic producer to net $50.
The High Yield Corner
By Michael Foster
Special to The Bull Market Report
It was a quiet week for the markets, with the S&P 500 ending flat with few dramatic days. Donald Trump’s odd press conference, in which the president-elect took a victory lap after his election win but failed to provide clarity on fiscal spending plans or an economic blueprint, caused a brief upset to the markets, but strong results from financial firms on Friday offset the macro worries quickly.
With that in mind, it’s unsurprising that the market was mostly quiet for high yield assets. The UBS BDC ETF (BDCS: $23) was mostly unchanged this week after accounting for its dividend payout, while the SPDR Barclays High Yield Bond ETF (JNK: $37) also saw no major move in any direction. Impatient traders may be frustrated at the lack of volatility, but we are pleased. Junk bonds and BDCs had a tremendous year in 2016, causing many funds and companies in these spaces to become worryingly overvalued. If we don’t see an aggressive run-up in pricing this year, we would be in a better position to hold our positions, add more on short-term dips, and avoid the need to sell overbought assets without viable alternatives for our cash.
This situation is particularly good for the PIMCO Dynamic Income Fund (PDI: $28, down -1%), which fell slightly this week but still has excellent dividend coverage and growth potential. After the fund paid out a massive special dividend last month (which we predicted), the fund is now in a position to accumulate new investment income and pay another big special at the end of this year. We fully expect this to happen, so we want to hold on. There’s only one problem: this fund's premium to its NAV is around 9%, bringing us dangerously close to a point where we would need to offload and choose another, lower-priced bond fund. We’d rather avoid making that trade because there are maybe two funds in the world that can match this fund in terms of yield, portfolio quality, and management acumen. As it stands, we can avoid choosing an alternative to the Pimco fund and enjoy its massive yield.
While things were quiet in BDCs and corporate bonds, there was a bit more action in municipal bonds, although this sleepy asset class is notorious for its low volatility and small moves. The iShares S&P National AMT-Free Municipal Bond Fund (MUB: $109) was flat this week, but our municipal bond picks both outperformed the broader index. Invesco Municipal Trust (VKQ: $12.58) and the Nuveen AMT-Free Fund (NVG: $14.63) both rose over 1% this week thanks to the market finally realizing these funds were underpriced relative to their portfolio quality. It makes little sense for these funds to offer discounts to their NAV, so we expect both to continue to rise in price as municipal bonds strengthen from the blood bath of 2016. For this reason we recommend a solid weighting of your overall portfolio in these bond funds for the foreseeable future.
Our biggest winner this week was AstraZeneca (AZN: $29, up 3%), which has been recovering from the broad panic that President-elect Trump is going to reign in drug prices and pressure Pharmaceutical firms’ profit margins. While a lot of talk before the election from both sides of the aisle pressured Pharma firms, the lack of clarity in Trump’s speech this week was ironically a positive for AstraZeneca. Investors are becoming more certain than ever that promises to reign in drug prices will get watered down heavily before they ever become a legislative reality - and that might never even happen. With that in mind, the big dip that this and other Pharma companies have suffered over the last year is becoming a buying opportunity. We’re pleased to keep AstraZeneca in our high yield portfolio for this very reason.
There is one sector that really took a beating this week: REITs. The SPDR Dow Jones REIT ETF (RWR: $93, down 2%) was the biggest loser of all the indices we track, but our REIT picks outperformed by a substantial margin. Even high-risk and overly volatile Government Properties Trust (GOV: $20, down 1%) saw declines only a fraction of the REIT sector as a whole. This is rare, as Government Properties Trust is notorious for rising more aggressively and falling more precipitously than REITs more broadly.
With one exception, our other REITs fared as well or better. Omega Healthcare Investors (OHI: $32, down 1%) and Care Capital Properties (CCP: $25, down 1%) fell slightly alongside the market, but Digital Realty Trust (DLR: $102) held on to its 2016 gains and ended the week flat. Digital Realty Trust has seen some of the highest capital gains of any of our high yield picks, but we aren’t selling quite yet. As we lap the year since we picked this stock and short-term capital gains become long-term capital gains, we might revisit this stock and consider changing our recommendation to a sell if (and only if) its price rises too fast and its upcoming earnings results shows weak FFO growth. This is something for us to keep our eye on.
Finally, our REIT under-performer is a surprising one: Kimco Realty (KIM: $25, down 3%). Usually a solid and low volatile firm, Kimco slid this week despite getting an upgrade by Raymond James. Kimco also announced that its next dividend will match its last one: 27 cents per share, which is up over 6% from just four months ago. The sell-off may be a result of impatient investors disappointed that we aren’t seeing another rate hike, although Kimco tends to do just one rate hike per year, and they did their last one last quarter. We’re shrugging at this dip, although it does mean Kimco is now flat on a year-over-year basis. Still, we aren’t in Kimco for capital gains, we’re in it for the dividend, so if we see Kimco start to fall further we might recommend doubling down.
All in all, a peaceful week for high yield, which is great for us since we’re getting paid 8% to hold these names. It’s also nice to see high yield resist growing market certainty that an interest rate hike is around the corner. If this trend continues for a few more weeks, we could easily expect high yield to be one of the strongest asset classes of 2017.
This coming week: Watch for a new research report on a fast-growing, powerful company in the virtualization and cloud infrastructure solutions space. Sounds pretty technical, doesn’t it? We’ll make it simple and understandable for you. As always.
Good Investing,
Todd Shaver, Founder, CEO and Editor
The Bull Market Report
January 15, 2017
by Todd Shaver | Jan 15, 2017 | Weekly Newsletter 7pm Sunday
The Week Ahead
We are quickly approaching Donald Trump’s Friday inauguration. The event will mark a key inflection point for the markets. After the big rally in stocks and sharp sell-off in bonds following the November election, a plethora of expectations for the future will soon meet the reality of what is possible, as we move into the first 100 days of the President’s term.
This week we provide some insights on our latest thinking for Amazon, Facebook, Google, Netflix, Bristol-Myers Squibb, and Tesoro Petroleum.
Highlights From The Past Week
Recession Watch. History has shown us that a recession has generally occurred during the first term of a new president, especially when following a two-term presidency. Could this be the case this time around? The leading economic indicators (LEIs) are positive, and there has never been a recession without those indicators going negative. CEO confidence is moving up and consumer confidence is exploding, which seemingly points to the likelihood that a recession is not imminent. We are not big believers in patterns, to tell you the truth. So we are leaning towards a continued strong economy and a continued bullish stock market.
There may be a Trump backlash coming though. You know, the one we expected in November after the election. We have talked to a number of our subscribers and many of you are worried about this. Our suggestion is that if you are worried so much so that you are losing sleep, with commissions as low as they are in this century, it is easy enough for you to sell those stocks that make you nervous and look to some of the issues in our High Yield Portfolio. They are generally more stable than other stocks.
However, there is also talk that the Trump presidency could be the best thing Wall Street has seen in a long time. Cutting taxes, bringing back the huge horde of cash overseas, tackling the infrastructure building that needs to be done, etc.; these are all things that could help the economy. Dow 25,000 soon? Oh wait – we haven’t hit 20,000 yet! Stay tuned.
Interest Rates. If the economy continues to grow steadily, the US Treasury 10-year Note could hit 6% in four years, about the time of the next presidential election, up from its current level of 2.4%. Inflation and economic growth are already at levels similar to 2006, when interest rates were at that level.
Stronger dollar. The dollar holds a unique position in the global economy, and a rapidly rising dollar exchange rate has historically caused something somewhere in the global economy to break. Those in emerging markets that have borrowed in dollars face the reality of a liability stream that has become more expensive to repay. Meanwhile, the second largest economy on the planet, China, has informally pegged the yuan to the dollar. A stronger dollar generally means a stronger yuan; a stronger yuan means a less competitive export sector for an economy that is all about trade.
BMR Companies and Commentary
Amazon (AMZN: $817, +3% for the week)
JP Morgan Chase is offering a new, co-branded Visa rewards card through Amazon that offers compelling rewards for both Amazon Prime purchases and all other purchases outside of Amazon. Specifically, the new Chase card offers 5% cash back on all Amazon purchases by eligible Amazon Prime members. This deal marks another win for Amazon deepening their existence in banking.
How about the core business of Retailing? What started out as an online bookseller is now on pace to overtake Macy’s as the world’s largest apparel retailer, a startling development when you remember that e-commerce was once considered an impossible way to sell clothing. Amazon has reportedly recorded record holiday season sales at the same time that traditional department stores, including Macy’s, Sears, and Kohl’s, have reported declines. These companies aren’t adding thousands of new workers like Amazon. To the contrary, Macy’s plans to close 100 stores to improve profitability, and Sears has sold its Craftsman tools line for $900 million to raise cash.
BMR Take: Amazon is currently not far from its all-time high of $844, set in October. There is still the potential for upside for investors here, and the stock could go even further, perhaps passing the $1,000 mark sometime in 2017 or 2018.
Facebook (FB: $128, +4%)
Facebook has underperformed the Nasdaq since the company’s 3Q16 earnings report, due to a number of factors, including concerns about slowing growth, heightened expenses in 2017, and sector rotation out of Technology.
Investors have also cited concern about the headwind from a possible 1Q17 IPO of Snap. As far as the competitive risks of new more exciting Tech IPOs stealing away investors from Facebook, any impact is likely to be temporary and potentially more modest than investors fear. Press reports suggest that Snap (aka Snapchat) was considering an IPO as early as March at a valuation as high as $40 billion. Given that Snap’s IPO will represent the largest tech IPO since Alibaba went public in 2014, some investors have begun to question how the issuance may impact existing public market Tech stocks and in particular its closest comp, Facebook.
BMR Take: Yes, it has underperformed since November, but it has been on a TEAR since the start of the year. Be advised that the upcoming Snapchat IPO will be all over the headlines, but don’t sell your Facebook over this. Facebook’s long term prospects are fantastic. Facebook is fast approaching its all-time high of $133.50 set in October. And fast approaching 2 billion users. The company adds 1 million subscribers every two days. With growth of 35% a year projected for the next two years, the stock is not over-priced.
Netflix (NFLX: $134, +2%)
A big name stock analyst that was short Netflix covered his call this week. It’s nice to see them come join our camp. There is so much to like about Netflix. In fact, the stock hit an all-time high of $133.93 this week!
On the heels of new details about Hulu’s upcoming live TV offering (pricing, content lineup, etc.), Netflix reiterated that it has no plans to make any other meaningful changes to its business model or content strategy, stressing that the simplicity of its offering is a key advantage.
The company has also evaluated the merits of an ad-supported model but continues to believe that focusing on its core business provides the greatest return on investment. Looking back at Netflix’s pricing changes and the un-grandfathering it worked through in 2016, the company feels good about its pricing power and is satisfied with the outlook. They also expect future price increases to be more staggered by country/region rather than by universal global changes.
While Netflix intends to keep pricing relatively consistent globally, in Japan, for instance, it has a lower price for its lowest tier ($5/month) in order to address Netflix’s more limited brand recognition in that market (i.e., to better spur new user adoption).
Netflix now has 50%+ of its content catalog available for downloads on Android and iOS today, and it expects that percent to increase. The company is increasingly self-producing content, which it believes can ultimately be 30%+ cheaper than licensing. Like what began in 3Q16, this will continue to impact cash burn in the near-term given the up-front costs associated with producing content.
BMR Take: Netflix is changing the game for television. We continue to believe they are on a long term path to 2020 EPS of $10 where a 20x PE multiple supports a $200+ valuation.
Google (GOOG: $808, flat)
Speaking of the future of media, Google’s YouTube is just crushing it. We highlight the following data points tracking YouTube through December 2016:
--- YouTube worldwide video views for the top 1000 publishers in December 2016 totaled 70 billion, which was up dramatically from last year. This brings total cumulative views on YouTube for these top publishers to 1.97 trillion – wow. On a trailing three-month basis, total views were 190 billion - these numbers are astronomical! In November 2016 alone, videos uploaded to YouTube generated 147 Billion views, both organic and paid.
--- The total number of subscriptions to the top 1000 YouTube video publishers’ channels was 3.9 billion at the end of December, adding 120 million channel subscriptions in the last month alone, up nearly 70% from this time last year.
--- The total number of videos available on YouTube from these top publishers was 5 million at the end of December, accounting for 19% more content on the platform than in December 2015.
BMR Take: If these numbers don’t describe a healthy business, we don’t know what does. We view Google as a core holding, given: 1) the company remains a top player in the internet space 2) management's track record of execution, 3) the potential to maintain double-digit earnings growth for many years, and 4) attractive valuation.
Bristol-Myers Squibb (BMY: $56, -6%)
We take Donald Trump’s critical comments on drug pricing and overseas manufacturing in this past week’s press conference as tapping into his two pre-election populists themes of Healthcare affordability and US job creation. While we understand the market’s nervous reaction, there remain considerable political and practical barriers to implementation of the much-feared worst case scenario for the industry. We continue to envisage a robust reimbursement for drugs covered under a medical as opposed to a pharmacy benefit despite the evident uncertainty.
Combative comments on drug pricing and price controls triggered the industry selloff this week. Little here is new as Trump has addressed all the above issues previously, most recently in a TIME interview. However, we believe he will face resistance from within the GOP given 1) minimally anticipated savings as scored by the CBO for Medicare negotiation and 2) the proposed Health Savings Account replacement for Obamacare depends heavily on the very same high deductibles that he has criticized. Separately, border taxes for generic companies would impair cost savings associated with the introduction of multi-source generics.
BMR Take: Bristol along with others in Healthcare are simply an out-of-favor sector for the time being. We think sentiment will change and that now is an opportune time to take a hard look at this exceptional franchise.
Tesoro Corporation (TSO: $80, down 5%)
As the post-election euphoria for US refiners surrounding potential tax cuts begins to fade, talk of a Border Tax Adjustment (BTA) has forced investors to consider its impacts. (See Notes at the Margin, below) Washington policy analysts currently peg the chance of passage as only 40% as the impact would be highly complicated with far too many moving pieces to address with confidence. But the overall impact would be clearly negative for US refiners, driving the US crude price to a material premium, reversing recent global advantages, while increasing domestic product prices and accelerating demand destruction. Tesoro is one of the most exposed companies.
As part of the House GOP tax plan, a Border Tax Adjustment would significantly alter how taxes are calculated, by imposing a 20% tariff on imports, while exempting revenues earned through exports. (The plan has several other key changes including a reduction in the corporate tax rate to 20%, immediate and full deduction of capital investments, the elimination of tax breaks and subsidies, among others). Tax-reform has been a priority for the incoming administration, with a vote expected in the first 100 days. Implementation would likely be a late 2017/early 2018 event but could take effect sooner. The myriad impacts of a BTA will be difficult to gauge until they can be observed in real time due to their interdependency. But the big picture is obvious, refiners like Tesoro import a lot of crude oil, meaning they would face a new more onerous tax burden.
We see reason to add to our positions here. First, as we initially highlighted, the BTA will be extremely complicated to put into place and there is still a good change it never happens. Second, Tesoro is now trading at just .67 times its Net Asset Value, a cheap valuation relative to Phillips 66 which is trading at a premium to NAV. Third, we scrubbed some Wall Street analyst estimates, and do you know what the EPS impact would be of the BTA? About 10%, so the stock has already adjusted for the worst case scenario.
BMR Take: They are undergoing a transformational expansion through the acquisition of Western Refining in the first half of this year as announced in November ($4.1 billion.) We think Tesoro is having a bargain bin sale right now and we see a very compelling risk/reward in the shares at current levels.
Upcoming Economic News
WEDNESDAY, JANUARY 18
Consumer Price Index – December
Time: 8:30 am
Forecast: 0.3% overall, 0.2% core
Higher fuel costs can bring annual growth in the Consumer Price Index above 2% for the first time in over two years. The core CPI had long ago breached that level, as growth in shelter costs in excess of 3% has been a consistent cost pressure for consumers. Alternative measures of core price growth have not run as hot. The Federal Reserve’s preferred core PCE Price Index has not topped 2% yearly growth since 2012.
Industrial Production & Capacity Utilization – December
Time: 9:15 am Forecast: 0.6% industrial production, 75.5% capacity utilization
Undoing declines in Auto and Utility sector output can guide industrial production in December to one of the largest monthly increases of the past two years. Warm weather created three consecutive monthly declines of at least 2% in Utility sector output for the first time on record. December’s unexpectedly sharp gain in auto sales can give a near-term boost to US output.
NAHB Housing Market Index – January
Time: 10:00 am
Forecast: 69
Homebuilder confidence may dip a bit in January after leaping to the 12-year high in December. Yet based on builder sentiment, 2017 is shaping up for strong gains in residential construction. The index measuring expected sales over the next six months rose to 78 last month, far above the historical average of 57.
THURSDAY, JANUARY 19
Housing Starts & Building Permits – December
Time: 8:30 am
Forecast: 1.20 million starts, 1.22 million permits
Housing starts look to surge ahead in December after taking a dive in the previous month. Permits rose 32% annualized in the three months ending November against the prior three months, a strong indicator for near-term building activity. That spike in permits is pointing starts to a much faster pace than the limp 1.4% year-over-year advance to the quarter ending November.
Tesla (TSLA: $238. Up 4%) has been on a tear. At $182 on December 1st, the stock is up over 30%. The company just opened a showroom in Aspen and the place is packed. I met a friend on the street on Friday and motioned for him to come in. Guess what: He is taking a test drive next week and might buy one of the Model X’s that start at $85,000. 0-60 in 2.9 seconds. Call it a cult, or call it what you will, but this company is real and this company is exciting. With Saturday’s Space X launch of 10 satellites on the Falcon 9 and then landing the rocket on the drone ship in the ocean, Elon Musk’s star is riding high. Musk sent out this Tweet:
Elon Musk @elonmusk
Mission looks good. Started deploying the 10 Iridium satellites. Rocket is stable on the droneship.
BMR Take: We’ve said many times before in these pages that the stock is not for the conservative and that the stock could go to $150 before it goes to $250 due to its volatility, but we will tell you that this stock could go to $400 this year or next.
We hereby raise the Price Target from $250 to $290 and raise the Sell Price from $150 to $180.
The RACE:
Facebook (FB: $128 = $896)
Apple (AAPL: $119 = $833)
Amazon: (AMZN: $817)
Google (GOOG: $808)
Facebook is the clear leader for the 2nd week in a row.
Twilio (TWLO: $28, flat) continues to underperform. And we at The Bull Market Report continue to hold out hope for this company. There were some upgrades announced on the Street this past week. On Thursday Oppenheimer made Twilio its Top Pick with a Price Target of $50. Two other firms issued a Buy rating with targets of $35 and $36. And the week before, KeyCorp and Pacific Crest issued an Overweight rating with price targets at $36. All in all, out of 15 firms, there are 8 Hold ratings and 7 Buys with a Consensus Price Target of $40.
BMR Take: We are going to be right about this one - you wait and see! We await the earnings report in early February. If revenues are stellar for the last quarter of 2016, we are going to a very happy newsletter. In this case, as in most cases (see Amazon), it is all about revenues.
The Border Tax
Notes at the Margin
Philip K. Verleger, Jr.
Former Director of the Office of Energy Policy
at the United States Department of Treasury
The House of Representatives’ Republican leadership seems set on pushing the plan through despite suggestions from some experts that it is a bad idea. Indeed, their determination to pass the law seems palpable even though major economic players such as James Bullard, president of the Federal Reserve Bank of St. Louis, have admitted publicly that they do not understand the concept.
Still, for the world’s oil industry, it is critical to understand the border tax quickly. Why? Because its passage will likely change oil flows completely. Most US oil producers would have every incentive to sell at home and none to export. Bluntly speaking, for oil the law’s passage is pure mercantilism. Exporters from Mexico, Canada, and the rest of the world could be shut out.
How might this happen? Start with the fact that the “Made in America” price could be 25% higher than world prices. The boost occurs because US producers would pay no tax if they export oil while US importers would pay a 20% tax. This means US producers would receive $50 per barrel if they export. On “paper,” at the margin they would have to pay a 20% tax if they sell to domestic buyers. This means those buyers would have to pay $62.50 per barrel in a $50-per-barrel world for the domestic producer to net $50.
The High Yield Corner
By Michael Foster
Special to The Bull Market Report
It was a quiet week for the markets, with the S&P 500 ending flat with few dramatic days. Donald Trump’s odd press conference, in which the president-elect took a victory lap after his election win but failed to provide clarity on fiscal spending plans or an economic blueprint, caused a brief upset to the markets, but strong results from financial firms on Friday offset the macro worries quickly.
With that in mind, it’s unsurprising that the market was mostly quiet for high yield assets. The UBS BDC ETF (BDCS: $23) was mostly unchanged this week after accounting for its dividend payout, while the SPDR Barclays High Yield Bond ETF (JNK: $37) also saw no major move in any direction. Impatient traders may be frustrated at the lack of volatility, but we are pleased. Junk bonds and BDCs had a tremendous year in 2016, causing many funds and companies in these spaces to become worryingly overvalued. If we don’t see an aggressive run-up in pricing this year, we would be in a better position to hold our positions, add more on short-term dips, and avoid the need to sell overbought assets without viable alternatives for our cash.
This situation is particularly good for the PIMCO Dynamic Income Fund (PDI: $28, down -1%), which fell slightly this week but still has excellent dividend coverage and growth potential. After the fund paid out a massive special dividend last month (which we predicted), the fund is now in a position to accumulate new investment income and pay another big special at the end of this year. We fully expect this to happen, so we want to hold on. There’s only one problem: this fund's premium to its NAV is around 9%, bringing us dangerously close to a point where we would need to offload and choose another, lower-priced bond fund. We’d rather avoid making that trade because there are maybe two funds in the world that can match this fund in terms of yield, portfolio quality, and management acumen. As it stands, we can avoid choosing an alternative to the Pimco fund and enjoy its massive yield.
While things were quiet in BDCs and corporate bonds, there was a bit more action in municipal bonds, although this sleepy asset class is notorious for its low volatility and small moves. The iShares S&P National AMT-Free Municipal Bond Fund (MUB: $109) was flat this week, but our municipal bond picks both outperformed the broader index. Invesco Municipal Trust (VKQ: $12.58) and the Nuveen AMT-Free Fund (NVG: $14.63) both rose over 1% this week thanks to the market finally realizing these funds were underpriced relative to their portfolio quality. It makes little sense for these funds to offer discounts to their NAV, so we expect both to continue to rise in price as municipal bonds strengthen from the blood bath of 2016. For this reason we recommend a solid weighting of your overall portfolio in these bond funds for the foreseeable future.
Our biggest winner this week was AstraZeneca (AZN: $29, up 3%), which has been recovering from the broad panic that President-elect Trump is going to reign in drug prices and pressure Pharmaceutical firms’ profit margins. While a lot of talk before the election from both sides of the aisle pressured Pharma firms, the lack of clarity in Trump’s speech this week was ironically a positive for Astra-Zeneca. Investors are becoming more certain than ever that promises to reign in drug prices will get watered down heavily before they ever become a legislative reality - and that might never even happen. With that in mind, the big dip that this and other Pharma companies have suffered over the last year is becoming a buying opportunity. We’re pleased to keep Astra-Zeneca in our high yield portfolio for this very reason.
There is one sector that really took a beating this week: REITs. The SPDR Dow Jones REIT ETF (RWR: $93, down 2%) was the biggest loser of all the indices we track, but our REIT picks outperformed by a substantial margin. Even high-risk and overly volatile Government Properties Trust (GOV: $20, down 1%) saw declines only a fraction of the REIT sector as a whole. This is rare, as Government Properties Trust is notorious for rising more aggressively and falling more precipitously than REITs more broadly.
With one exception, our other REITs fared as well or better. Omega Healthcare Investors (OHI: $32, down 1%) and Care Capital Properties (CCP: $25, down 1%) fell slightly alongside the market, but Digital Realty Trust (DLR: $102) held on to its 2016 gains and ended the week flat. Digital Realty Trust has seen some of the highest capital gains of any of our high yield picks, but we aren’t selling quite yet. As we lap the year since we picked this stock and short-term capital gains become long-term capital gains, we might revisit this stock and consider changing our recommendation to a sell if (and only if) its price rises too fast and its upcoming earnings results shows weak FFO growth. This is something for us to keep our eye on.
Finally, our REIT under-performer is a surprising one: Kimco Realty (KIM: $25, down 3%). Usually a solid and low volatile firm, Kimco slid this week despite getting an upgrade by Raymond James. Kimco also announced that its next dividend will match its last one: 27 cents per share, which is up over 6% from just four months ago. The sell-off may be a result of impatient investors disappointed that we aren’t seeing another rate hike, although Kimco tends to do just one rate hike per year, and they did their last one last quarter. We’re shrugging at this dip, although it does mean Kimco is now flat on a year-over-year basis. Still, we aren’t in Kimco for capital gains, we’re in it for the dividend, so if we see Kimco start to fall further we might recommend doubling down.
All in all, a peaceful week for high yield, which is great for us since we’re getting paid 8% to hold these names. It’s also nice to see high yield resist growing market certainty that an interest rate hike is around the corner. If this trend continues for a few more weeks, we could easily expect high yield to be one of the strongest asset classes of 2017.
This coming week: Watch for a new research report on a fast-growing, powerful company in the virtualization and cloud infrastructure solutions space. Sounds pretty technical, doesn’t it? We’ll make it simple and understandable for you. As always.
Good Investing,
Todd Shaver, Founder, CEO and Editor
The Bull Market Report
December 11, 2016

by Todd Shaver | Dec 11, 2016 | Weekly Newsletter 7pm Sunday
The Week Ahead
This was the first week in history that the Dow Jones, S&P, and Nasdaq all moved higher every single day in a week. What a rally we are experiencing! Some of our subscribers have suggested worry over these new highs. Our thoughts below.
The week ahead brings a FOMC meeting and a certain rate hike. We will all need to watch to make sure Yellen doesn’t point to raising rates more than two times next year, which would turn down the music at this market rally party.
This week we provide some insights on our latest thinking for Athenahealth, Goldman Sachs, Under Armour, Aetna, Blackstone, and Bristol Myers-Squibb.
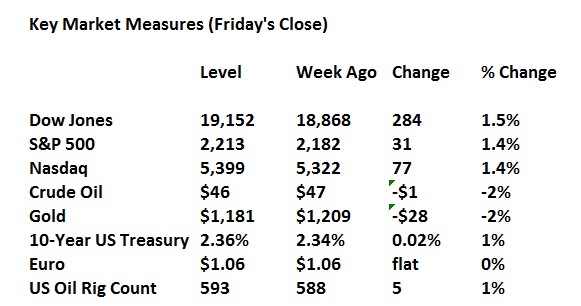
Key Market Measures (Friday’s Close)
Highlights From The Past Week
Financials Valuations. The sounding board of the stock market is arguably the Financials sector. These are controlled by the so-called money men. They live and breadth arbitrage, risk-parity, and all things finance. With the recent big run-up in the past several weeks in the Financial sector, what are we all to make of it? Here are two anecdotes. First, JP Morgan CEO Jamie Dimon was asked at this week’s Goldman Sachs Financials Conference what he was currently doing with the company’s stock buyback program. Dimon answered by saying the buyback program has been halted as he wants the staying shareholders to be getting a deal not the exiting shareholders. How telling! Second, Customers Bank (CUBI) issued a press release stating how big of an accomplishment that its market capitalization has reached $1 billion since the company was founded seven years ago, which is being ridiculed as an indicator of euphoria not seen in a long time - what company issues a press release regarding their market capitalization?!?
Looming Pension Crisis. Two days after the Mayor of Dallas filed a lawsuit against the Dallas Police and Fire Pension system to block withdrawals, which he referred to as a "run on the bank" of an "insolvent" pension system in "financial crisis”, the Pension's board has finally taken steps to halt further withdrawals. Of course, this delayed action has come only after $500 million in deposits have been withdrawn since just August. Nonetheless, The Dallas Police and Fire Pension System's Board of Trustees suspended lump-sum withdrawals from the pension fund Thursday, staving off a possible restraining order and stopping $154 million in withdrawal requests. Approving the request would have sent the pension below mandatory minimum liquid asset levels. This is just the tip of the iceberg of a looming pension crisis. It is unclear exactly how bad the situation will get.
ECB Starts Tapering. In an unexpected twist to the consensus announcement, Mario Draghi turned hawkish after all, and while the European Central Bank kept all rates unchanged, it announced that it would effectively taper its bond purchases from €80 billion a month to €60 billion starting in April, until the end of the year. This matters big time. We saw the taper tantrum in the US back in 2013 crush bond returns. The implications of Europe now heading this direction could spell at the very least volatility overseas that spreads to US markets.
BMR Companies and Commentary
Under Armour (UA: $28, +16%) Big news out of Under Armour this week! The company will outfit all Major League Baseball players starting in 2020 in a 10-year deal announced Monday, marking the brand's first uniform agreement with an American professional league. The sports apparel and footwear maker will supply all 30 MLB clubs with uniforms. Under Armour's partner in the agreement, sports merchandise retailer Fanatics, will have licensing rights to manufacture and distribute fan gear. The deal represents a "watershed moment" for the 20-year-old Baltimore-based company. You are watching Under Armour continue to cement itself as the millennials’ leading sports brand.
Separately, the company’s class A shares now trade under the ticker UAA and the class C shares have the old ticker UA. The A shares have one vote and the C shares have none. Founder and CEO Kevin Plank still owns all outstanding B shares, giving him 65% of the company's total voting rights. Thus, the voting rights that come with Class A shares offer virtually no benefit to the vast majority of smaller investors. For us, the jury is still out on which shares to track from here on out, although we think that ultimately the class C shares (UA) will be the stock to buy. We will let you know as time progresses which one we favor. For now, if you are an owner there is nothing for you to do. Just sit back and enjoy this stock getting back to its all-time highs of $72 in 2014. We will settle for $40 in the first half of 2017 though.
BMR Take: We remain very excited about the prospects for Under Armour. Management sees revenues hitting $10 billion in the years ahead versus current levels of $7-8 billion. We think the stock at this level is a compelling value.
Goldman Sachs (GS: $242, +8%) Goldman Sachs had another great week pushing to fresh new highs. What’s happening?
The large-cap banks and investment banks have been the most structurally impacted by the burdensome regulatory regime following the financial crisis. Accordingly, the Trump administration’s general proposals for “less regulation” will most positively impact these sectors, which includes Goldman Sachs.
What could change? Financial companies like Goldman Sachs may be required to hold less capital on their balance sheet as reserves for future losses. However, all the specifics remain unclear at this point. Looking at the Financial CHOICE Act as a potential blueprint, we note that both Morgan Stanley and Goldman Sachs are currently operating below the 10% leverage ratio threshold. (Goldman is at 6.3%.) What does this mean? In order to fall into the technical category for having "too much regulation", the Financial CHOICE Act states you would need to currently have a 10% leverage ratio or higher. Those with 10% leverage ratio or higher will be given an "off ramp" to less regulation in a Trump Administration. However, since Goldman doesn't meet the initial qualification in terms of capital levels, they may not even get to participate in what the Trump Administration is planning.
BMR Take: The stock is trading well above book value of $172 as of the most recent quarter. Goldman has been a great pick for is and the franchise is strong. This is a company that knows how to make money in good markets and bad. But good markets are always much better for Financial firms like Goldman. And we are in a big bull market now as you know. We issued a News Flash on Thursday raising the Target to $270 and moving the Sell Price to $234 which will cement our gains, having added the stock in January at $147.
Bristol Myers-Squibb (BMY: $57, +2%) Bristol shares are putting in a strong bottom at this point. The stock moved off of the $50 lows around the third quarter earnings release and it hasn’t looked back. This week Bristol announced it increased its quarterly dividend by 2.6% to $0.39 from $0.38 per share. The dividend hike is tiny, yes, but it is also a reminder to the market that Bristol is delivering very healthy profitability and returning a lot of money to shareholders. Recall, along with the release of 3Q16 results, Bristol announced a new $3 billion repurchase authorization and a commitment to flat operating expenses through 2020. Also note that Bristol has an extensive track record of not just paying their dividend, but hiking it, and current earnings are comfortably above the dividend level, meaning it is safe.
BMR Take: We see a turnaround ahead for Bristol and considerable upside. The immuno-oncology franchise has recently stumbled, but the core business is healthy and there remains prospects for a turnaround in immuno-oncology. The stock screams cheap relative to the 2017 EPS outlook of around $3.00 where expectations call for 15% EPS growth through 2020.
Athenahealth (ATHN: $96, flat) Athena shares are still finding their floor. We continue to like what we see from the company and would be buyers at this level. On the drug pricing front, Athena’s CEO did some public relations work this week to help people better understand the drug pricing debate that is crushing sentiment for many Healthcare stocks including Athena. He said a lot of the criticism is misplaced. If new drugs are keeping people out of the hospital, and offsetting the much higher cost of surgery, then they're worth it. This thinking is underpinned by what's called “value-based care,” a way of paying for healthcare that aims to improve the quality of care and cut costs. He said, "If you make a 99% profit on a $80,000 drug, and you take $120,000 of 2% profit margin hospital cost out of the system, God bless you, you just took $40,000 of cost out of the Healthcare system." It’s a very insightful perspective, we believe.
Second, Athena is the leading cloud IT company in the Healthcare market and they aren’t holding back. This week Athena announced a deal with Automatic Data Processing (ADP) to offer payroll, and time and attendance software to the small hospital market. This is great news as ADP is a wonderful partner for Athena. We hope to see more products offerings like this.
BMR Take: Sentiment remains weak for Healthcare stocks including Athena but the company is fighting back. The core business is doing well with new product offerings cementing the company’s leadership as the top cloud IT company. We think shares are a compelling value on this recent pullback.
Blackstone (BX: $30, +14%) The sails of Blackstone are catching wind causing momentum for the shares to acceleration. We’ve been saying this for months now, and are almost blue in the face. But this week the market finally took notice. Beyond the broader market rally, there is a particular force at play garnering more attention from the investment community for Blackstone.
Recall, this past quarter management reiterated the “huge” opportunity within the Retail channel (retail in reference to products sold with little to no minimum requirements, as opposed to institutional products that require at least a $1 million minimum purchase). All of Blackstone's products fully comply with the new Department of Labor (DOL) Fiduciary rule, which will do away with more aggressive products being sold. Basically, the new rule expands the standard of fiduciary obligation to apply to more brokers in more circumstances. Accordingly, many corners of the market, like non-traded REITs in particular, are not going to be able to be sold like they used to.
What does all this mean for Blackstone? Blackstone offers a world class investment product line-up, which should benefit as the new DOL rule cleans up some of the bad behavior in the industry and pushes the investment community toward Blackstone's products.
Demonstrating early favorable indicators of the trend, retail fundraising historically represented about 10% of firm-wide capital raised, but accounted for a higher 15-20% over the past three years, a trend we anticipate will persist.
BMR Take: Given the elevated growth trajectory at Blackstone, we view shares to be a compelling risk/reward. We think the stock is still cheap trading at under 10x the 2017 EPS outlook, and you get a huge 5.6% dividend yield along the way.
Aetna (AET: $129, -3%) The Justice Department hammered away in court Thursday at the viability of a plan by Aetna and Humana to sell off assets to alleviate antitrust concerns about their proposed $34 billion merger. The department, which is suing to block the merger, questioned the ability of the proposed asset buyer, California-based Molina Healthcare, to keep the market competitive for private Medicare plans for senior citizens if Aetna and Humana combine. Currently the two large health insurers compete head-to-head in hundreds of counties for the sale of Medicare Advantage plans, which are government-backed alternatives to traditional Medicare.
BMR Take: With the big recent run-up in the stock, the valuation is looking pretty reasonable on earnings assumptions that account for the merger happening. If the merger were to be blocked and were to fall apart, there could be severe damage ahead for the stock. We added the stock at $105 in February and currently at $129 the stock is up 25%. We hereby exit our position considering the unfavorable risk/reward.
But stay tuned for a substitute that we will issue a News Flash about on Tuesday morning.
Upcoming Economic News
TUESDAY, DECEMBER 13
Import Price Index – November
Time: 8:30 am
Forecast: -0.4%
The Import Price Index is projected to fall in November after two straight monthly advances. Even after expanding in seven out of eight months through October, the Import Index only managed a piddling 0.5% annual advance. Uplift in oil prices can boost the index in the near-term, yet dollar strength is likely to limit gains in the year ahead.
WEDNESDAY, DECEMBER 14
Retail Sales – November
Time: 8:30 am
Forecast: 0.4% overall, 0.5% ex auto
Retail sales look to grow strongly for the third consecutive month in November, bolstered by steady job and income gains. Disposable personal income grew 4.1% year-over-year in October, the fastest such pace since January. That acceleration in income growth suggests strongly positive, but not overly robust results for holiday retail sales.
Producer Price Index – November
Time: 8:30 am
Forecast: 0.1% overall, 0.2% core
The Producer Price Index is forecast to edge higher in November after holding flat in the previous month. Although the 0.8% annualized increase in the PPI in October is the highest in almost two years, that pace points to very modest pressure on business costs. The core PPI presents a similarly subdued trend, rising no more than 1.3% annually at any point over the past 21 months.
Industrial Production & Capacity Utilization – November
Time: 9:15 am
Forecast: -0.2% industrial production, 75.1% capacity utilization
Industrial production is expected to decline for the third time in four months in November, with warm weather greatly limiting utility sector output. Manufacturing sector production has been lackluster over the long-term, falling 0.2% yearly as of October. Positive industrial orders data in recent months and auto sales volume that has beat expectations of late can help turn around overall output trends.
Business Inventories – October
Time: 10:00 am
Forecast: -0.1%
Business inventories are projected to fall slightly in October after expanding in the two previous months. After long being a drag on overall output, businesses have a better handle on their stockpiling needs. Inventories added 0.5% to third quarter GDP growth, the first such positive contribution of the past six quarters.
FOMC Rate Decision
Time: 2:00 pm
Forecast: 0.5%-0.75% fed funds target range
The first and only fed funds hike of 2016 is all but certain to occur at the December 2016 FOMC meeting. The more interesting question revolves around policymaker projections for the fed funds rate in 2017. Consistent uplift in inflation and wage growth will be needed to increase the pace of policy tightening. Until the data for inflation and wage growth comes in consistently strong, we don't see Yellen quickly moving up the Fed Funds rate. It will be slow and steady, unless the numbers portend an overall economic slowdown.
THURSDAY, DECEMBER 15
Consumer Price Index – November
Time: 8:30 am
Forecast: 0.2% overall, 0.2% core
The Consumer Price Index is in line to increase steadily in November, keeping the annual core price trend north of 2%. Housing costs are keeping the core price growth elevated, with the cost of shelter rising 3.5% year-over-year in October.
FRIDAY, DECEMBER 16
Housing Starts & Building Permits – November
Time: 8:30 am
Forecast: 1.23 million starts, 1.23 million permits
After jumping to the 9-year high in October, housing starts are likely to step backwards in November. Yet an improving permits trend will continue to guide starts higher over the long-term. Permits rose 4% year-over-year in the three months ending October, greatly improving on the 10% yearly decline recorded in the second quarter.
Ferrellgas Partners (FGP: $6.65, up 19% after paying a 10 cent dividend) has been hit hard as you know. What do some of the big Street research firms have to say about the company? Barclay’s is looking for $15. Janney Montgomery Scott has a $20 price target. Royal Bank of Canada - $11. Citigroup - $21. Wow.
BMR Take: We think the selloff is way over done. This is a franchise that has been making money for decades. They made a bad mistake by buying into a new business they knew little about. And now they are paying for it with increased debt service and much lower profits. For the patient investor hopefully the bottom has been reached and we can see $10 in the first half of 2017.
The Google Amazon Apple Race
Google (GOOG: $789, up $40, 5%)
Amazon (AMZN: $769, up $29, 4%)
Apple (AAPL: $114, up $4, 4%) - $798 equivalent, reversing out the 7-1 split in 2014.
Apple leads the race!
Tesla On Track to Ship 80,000 Cars This Year
Tesla (TSLA: $192, up 6%) has stated numerous times that it will produce the first Model 3 by late 2017. This is the car that almost 400,000 people gave the company $1000 as a down payment earlier this year when it was announced. (That’s $400 million in cash that the company gets to use.) Other pundits state it will be late 2018 before the first unit roles off the assembly line. And remember, the company has said they will produce 500,000 cars by 2018. So there is conjecture in the air. This is why we have always said the stock could be so volatile, perhaps hitting $150 before it hits $300. And some skeptics think there is no chance that Tesla will ever survive. But Tesla has hired an expert production executive from Audi to help make this transition from assembling around 100,000 vehicles annually to 500,000 by 2018. All this appears completely doable to us and we continue to be believers in the company.
OPEC CUTS
OPEC has persuaded 11 non-members to cut oil production. Non-members agreed to cut almost 600,000 barrels per day for six months starting Jan. 1st, renewable for another six months after that. These non-member cuts come on top of an OPEC decision in late November to reduce their own output by 1.2 million barrels a day. We personally feel this is a drop in the bucket, as the world burns 95 million barrels of oil a day, but sentiment is important here. The thinking is that if OPEC can cut here, they may just cut more in order to prop up the price of crude which hovers around the $50 mark. The 11 non-OPEC countries taking part in the agreement are: Azerbaijan, Bahrain, Brunei, Equatorial Guinea, Kazakhstan, Malaysia, Mexico, Oman, Russia, Sudan and South Sudan. Most of the cuts would come from Russia.
High Yield Corner
It’s been something of a quiet week for high yield after weeks of volatility and uncertainty. This is ironic, since we’re a week away from the Fed’s expected rate hike announcement, but that is already priced in to just about every asset class, and the market seems to be accepting higher interest rates. Some believe that high yield bonds are not pricing this rate hike in well enough, which is why we have diversified our high yield portfolio with stocks, REITs, and other asset classes that are pricing in the rate hike more clearly. That said, we are confident that bond markets will not collapse after the Fed makes its move, and we believe the response is going to be quite muted. Remember, last year the rate hike was relatively unprecedented and unexpected; this year it’s widely expected and we have recent history to guide us in how high yield assets will respond. High yield assets are all up strongly before the rate hike, which suggests the risks aren’t really that great. The lack of a sell-off right now makes a lot of sense in that context.
So let’s take a look at individual asset classes. The SPDR High Yield Bond ETF (JNK: $36) and the iShares AMT-Free Municipal Bond ETF (MUB: $108) rose over 1% this week. The market seems to have accepted that the rate hike is coming and is already well priced in. Some high yield asset classes acted as if the market has over-priced the rate hike in. The SPDR Dow Jones REIT ETF (RWR: $94) surged over 3% this week, and many of our REIT picks performed even better. REITs were theoretically going to be hard hit by rate hikes with higher borrowing costs and less investor demand. While that’s true, the downside was clearly overstated in the recent sell-off. The market now realizes this, and REITs are climbing upwards.
AstraZeneca (AZN: $27) got a huge bump this week after durvalumab, a new cancer drug being developed by the company, got priority review status by the FDA. When we first recommended AstraZeneca, we liked the drug pipeline of this company, and we’re happy to see the pipeline perform strongly. The company still has a long way to go; the stock is down 20% year-to-date and down 4% from when we recommended it. Still, we fully expect investors to realize this company has many tricks up its sleeve, and we’re confident that the company will outperform the Biopharma industry even as it appears to be under attack by newly elected Donald Trump, who has targeted high drug costs as one focus of his upcoming presidency.
On the issue of government intervention in capitalism, Government Properties Income Trust (GOV: $19.70) surged over 6% this week and is up 24% year-to-date. The REIT rout that we’ve suffered since summer is waning and the market finally realizes it has oversold many great companies. We’re not surprised to see this REIT return to a more appropriate valuation, although we are getting close to our price target. When we recommended this company, it was yielding 11%. Don’t expect that yield to return anytime soon. FFO over the last 12 months is 142% of the dividend, meaning the company will have no problem paying out distributions in the short term. This dividend coverage is also higher than many other REITs, meaning its high yield implies more risk than is really there.
What about our other REIT picks? Starting with Kimco Realty (KIM: $26), up over 3% for the week. Yet Kimco is still down slightly year-to-date, meaning more upside is available very soon. The company’s FFO has gone up since we started the year, and the dividend went up 6% in October while FFO also went up 6%. This all demonstrates the durability of this high-yielding REIT and makes it a hard hold. Ignore analysts at Goldman Sachs who downgraded the REIT to Sell at the end of November. The stock is flat since they made that call, and the argument that rising rates will hit REITs is getting weaker - the market has clearly already priced that risk in.
Digital Realty Trust (DLR: $94) is one of the most exciting REITs in our portfolio because it benefits with the growth of cloud computing yet has little volatility relative to tech stocks. We’re up 6% last week, bringing DLR’s year-to-date performance to 24%. FFO is still far above the payout and 25% year-over-year revenue growth last quarter shows just how much growth is in this stock. At a 3.7% yield, the market has realized there’s limited risk in this stock, but that also means we’re reaching a sell point. We aren’t there yet, however, so we recommend holding this stock for now.
Finally, we have two Healthcare REIT picks to go over. Omega Healthcare Investors (OHI: $31) and Care Capital Properties (CCP: $25) rose nearly 5% each this week on fundamental optimism in the Healthcare REIT sector. With this entire sector down double digits year-to-date and many Healthcare REITs near 52-week lows, it seems clear that investors realize we’re at a bottom for this asset class. That’s why we recommend holding and enjoying the 8% to 9% yields these REITs offer.
Now let’s turn to the more diversified funds, which had a subdued week. AllianzGI Equity and Convertible Income Fund (NIE: $18.80) rose over 2% thanks to steady NAV appreciation in its equity holdings. This fund holds great companies like Amazon and Google, but it trades at a 14% discount. This means for every $1 you spend on NIE shares, you’re getting $1.14 in assets. Unfortunately, this fund has traded at a discount to NAV since 2009, and it hasn’t traded at a discount larger than 10% since early 2015. We feel this price pressure is due to the smallish size of the fund and concerns that rising interest rates (which have been an ongoing drama for years now) will hurt the value of the convertible bonds in the fund. Ironically, rising rates will help the covered call side of the fund, meaning the downside is hedged internally in the fund. The market doesn’t really care about this, though, so its discount is still large. But markets don’t stay inefficient forever, and we’re fairly confident the market will realize it has underpriced this fund for years. That’s why we recommend holding it and enjoying the NAV appreciation and the 8% income stream.
Our other big fund pick is Pimco Dynamic Income Fund (PDI: $29) which was flat this week and paid out another 22 cent dividend. There’s nothing to report on the Pimco fund from a price or performance standpoint, but the real frustration is that Pimco still hasn’t released its special dividends for this fund or any other fund. This fund traditionally pays a very large special dividend, and there is a lot of undistributed net investment income that is likely to be paid out by the end of the year. Last year, Pimco announced its special payouts on December 11th; since the 11th is a Sunday this year, we were expecting Pimco to announce earlier. The announcement is coming later, however, and we wouldn’t be surprised if was made on Monday. It could be as late as Friday, however. This means sit tight and wait one more week to see just how much extra income we’re going to get. It seems there is a high probability that the extra income will be over $1.00 and could be even as high as $1.40. We just need to be patient and see.
Good Investing,
Todd Shaver
Founder and Editor
The Bull Market Report
November 27, 2016
by Todd Shaver | Nov 27, 2016 | Weekly Newsletter 7pm Sunday
The Week Ahead
We finished this week at all-time highs - again! The ‘Trump’ rally has turned into the ‘feel-good’ rally we often see around Thanksgiving and Christmas. With the election over, political uncertainty is down (but not out.) With the post-election rally, the odds of a December rate hike is being priced in by the bond market at 100%, (actually 100.2%), reducing rate uncertainty. What’s left to focus on? We dare say company-specific fundamentals. If that’s the case, we really like the prospects for active stock selection. This week we provide some insights on our latest thinking for Apple, Blackstone, Tesla, Facebook, and Welltower.
Highlights From The Past Week
First, there was Brexit. Then, there was Trump. Now the discussion is turning to Frexit - France electing to exit the European Union (EU). Many are saying that the European Union could not conceivably survive in its current form if France elects National Front leader Marine Le Pen to the Presidency next May. Le Pen is campaigning for a wholesale renegotiation of the EU’s treaties, restoring the primacy of national law, de-emphasizing the European Central Bank, and ending the free movement of labor and goods across the region. We all must watch closely. The political system as we know it in several regions across the globe is crumbling.
Mortgage Market. The rapid rise in interest rates since Election Day is taking a toll on the mortgage market, and lenders are scrambling to adjust. Since Donald Trump’s surprise victory, average rates for a 30-year, fixed-rate mortgage have leapt by more than half a point, to 4.18% on Wednesday. The fast rise in rates has spurred homeowners to pull back from refinancing their mortgages. Applications dropped 3% in the week ended November 18th from the prior one, the seventh consecutive weekly decline, and the second since Election Day. The Mortgage Bankers Association estimates refinances will fall 46% next year, to $485 billion, which will hurt Americans’ ability to free up cash by reducing the cost of their monthly mortgages. As we learned from the 2008 Financial Crisis, given its size, the Mortgage market is a key pillar of the economy. Higher monthly mortgage payments and slower loan growth for banks matter to the economy and sentiment. We need to care about what goes on here.
Infrastructure. The talk of the town right now is Trump’s $1 trillion fiscal stimulus plan for infrastructure investments in the United States. But what many people don’t realized yet is that the amount might be much, much bigger. Why? The concept of Public Private Partnerships (PPPs). PPPs were used by Obama under the Build America Investment Initiative that helped fund the Denver FasTracks commuter and light rail projects in Colorado, the Goethals Bridge reconstruction project linking New York City and New Jersey, and the Bayonne Water Joint Venture project in New Jersey. What PPPs do is match every $1 of private capital offered for a project with $1+ or more of fiscal stimulus money. So Trump’s $1 trillion will really end up resulting in $2+ trillion of infrastructure investment. Exciting stuff! Oh wait – a little bird just told us he has to deal with Congress to get this approved. Now that will be fun to watch.
BMR Companies and Commentary
Apple (AAPL: $112, +2%)
President-elect Trump recently spoke to Apple CEO Tim Cook. Trump asked Cook to think about opening multiple plants in the US to make their products. Trump said he will institute tax breaks for him to do this. Will Apple comply? Can Trump pull it off? What are the implications?
Trump doesn’t want Apple to continue going to China or Vietnam to manufacture iPhones. He wants Apple to do it right here in the US. Trump says it will be a major achievement for the US middle class if he can find the solution to make it happen.
The jury is still out on what it all means, however. Does the US have the skilled labor to do the task? Is this a waste of time because machines are soon going to be doing the work regardless? How many more jobs are we actually talking about here?
Trump’s first line of defense to force the issue on Apple is the threat to tax imports from China. However, China has already committed to a tit for tat trade policy against Trump (whatever he does they will respond equally). Not good. Trump must be careful.
We understand Cook very much wants to repatriate Apple’s foreign cash and Trump has mentioned that he will work on ways to reduce taxes to make this happen. We believe much of the money will likely go to dividends and repurchases. So we will be watching very closely to see if new incentives arise that detour the money into capital expenditures such as new manufacturing facilities.
BMR Take: As long as the repatriation of foreign cash happens, we are content either way with the outcome. If the money goes to dividends and stock repurchases, Apple will head a bit higher in the near-term. If the money goes back into re-building America, this better long term picture for US GDP would be a positive for all stocks.
Blackstone (BX: $27, flat)
Blackstone was solid this week, as we await a move to $30. What’s happening here? So many headlines: Key executive Jon Gray won’t be heading to DC to serve as Treasury Secretary; there is a lucrative deal swirling to pick-up some of Valeant Pharmaceuticals assets on the cheap; a deal is pending to sell a chunk of Japanese real estate holdings; the investment in Optiv has reached a successful exit through the recent $100 million IPO.
We think the big story is simply the broad-based strength seen in the US equity markets. US equity markets are breaking all-time highs. This is a major tailwind for Blackstone. The company has $350+ billion of capital invested where the fees coming back to shareholders are very closely linked to overall valuation levels of the market. The M&A frenzy we’ve recently seen, the return of a healthy IPO window, and the generally more positive sentiment about the US GDP outlook - it all means upside to earnings at Blackstone.
BMR Take: The consensus EPS outlook calls for nearly $3 of earnings in 2017. The current dividend yield is greater than 6%. Why is this not a $30 stock? Why is this not a $40 stock? What a bargain.
Tesla Motors (TSLA: $197, +6%)
Tesla moved up nicely last week. One driver is all the talk of rolling back regulation and placing bigger incentives are what matters most. Despite some of the negative press Tesla gets, you may be surprised to learn that Tesla receives nowhere near the government support of other industries. Perhaps the future for the company will include greater government support.
Tesla has received only a fraction of the subsidies the Big Three auto manufactures have received. Specifically, since inception Tesla has received about $2.4 billion of subsidies or tax breaks. About $1 billion of that was for tax breaks over a 20-year period that started in 2014 when Tesla started construction on the Gigafactory in Nevada. Tesla has yet to utilize those tax breaks and it will have to spend tens of billions of dollars in the state of Nevada over the next decade in order to fully take advantage of them. Look at what other US-based automakers have received over the years. Here are the report cards for Fiat/Chrysler, General Motors, and Ford, in that order: $17 billion, $50 billion, and $27 billion. Wow! Not even close!
Turning to the Energy industry, it’s hard to even quantify considering the influence of using national defense to protect oil interests. Most agree the numbers are much bigger than auto.
BMR Take: Tesla’s receives a lot of flak for the subsidies it receives, but the fact of the matter is that it’s not a lot of money compared to other companies and other industries. The subsidy discussion matters a lot particularly following the November approval by shareholders for the Solar City acquisition. We think Tesla is an even more exciting company with SolarCity and we don’t see a reason to think government support is going away.
Facebook (FB: $120, +3%)
Late last week, Facebook announced authorization to repurchase $6 billion in existing stock. At face value, the authorization reflects 23% of the 3Q16 cash balance and approximately 2% of the market cap. Assuming 100% repurchase in 2017, we estimate about 1-2% potential accretion to 2017 earnings. In terms of timing, the company indicated the repurchase program goes into effect in 1Q17, but gave no specific deadline. One could argue that Facebook is now prepared to act on expected future stock volatility post the 1Q earnings call. One could also argue the buyback announcement now suggests that Facebook sees the stock as attractive today.
BMR Take: We think Facebook is on track to be the greatest advertising machine ever. This repurchase authorization just further supports management’s confidence in the cash flow capability of the company. They must know something we don’t. Can Facebook hit $150 or higher and start to catch Google in market cap? (Facebook is at $347 billion. Google is at $430 billion.) We wouldn’t bet against them.
Welltower (HCN: $63, flat)
The entire Real Estate segment of the market has not been performing well these past few weeks for a variety of reasons. Rising rates hurts the value of real estate prices through higher cap rates. Tepid economic growth limits the ability of raise rents. Sector-specific concerns in Healthcare around drug prices and reimbursement rates have been severely impairing to some tenants.
That said, we continue to see compelling value in Welltower. Welltower is the largest Healthcare REIT and the sixth largest REIT in the US. The 85+ age population is set to double in the next 20 years and Welltower will directly benefit. In fact, the company is increasing its senior living concentration from 65% of the portfolio to 70% in order to capitalize on the opportunity. Compared to other larger diversified Healthcare REITs, Welltower claims the lowest leverage. The company’s real estate holdings touch all major markets in the US, offering strong diversification. The stability of the business is further supported by an investment grade credit rating. The 5.5% dividend yield is more than covered by cash flow, as the payout ratio is greater than 85%.
BMR Take: In real estate, Welltower is a blue chip. We think the 5.5% dividend yield is particularly attractive. We see continued cash flow growth translating into dividend increases, supported by the growth driver of an aging US population occupying Welltower’s real estate holdings.
Upcoming Economic News
Special Edition: 2017 Outlook
There are four key pillars forming our outlook:
--- We look for GDP in 2017 to expand just under 2%...again
--- Fiscal policy, though highly uncertain, should be more of a tailwind.
--- And monetary policy more of a headwind, as the Fed is expected to deliver two more hikes next year
--- Productivity growth will remain subdued
As 2016 draws to a close, the US economy appears to have grown at a hum-drum pace of about 1.8%, quite similar to last year’s 1.9% performance. We’ve been looking for a similar slow slog going forward next year, though recent political developments add an interesting mix to that otherwise boring forecast. On the one hand, if President-elect Trump and his Republican allies in Congress push through the large tax cuts and equally large increases in defense and infrastructure spending that he campaigned on, the implied fiscal stimulus could push growth above 3%. (We won’t mention the big deficits this will incur - ouch.) On the other hand, if the incoming administration prioritizes increasing import duties, the disruptions to critical supply chains could have a chilling effect on business activity. The likelihood of the former, more benign, outcome seems greater than that of the latter, although the change in the outlook for growth would be larger under the latter outcome. For the time being we are penciling in a small fiscal boost, which would add to annualized GDP growth beginning in 3Q17 and extend into 2018. Even with this fiscal stimulus, we only see GDP growth next year getting to 1.9%.
While policy can potentially lift aggregate demand next year, there are fewer reliable remedies for the slow productivity growth that has plagued the economy. This slow productivity growth is the reason that even growth in the neighborhood of 2% has been enough to support a robust need for businesses to keep hiring. And six consecutive years of job creation in excess of two million jobs per year has finally tightened labor markets to the point where we are seeing more convincing evidence of accelerating wage growth, albeit from a low starting point.
Consumer price inflation has only partly followed suit. After averaging 1.4% in 2015, core inflation has recently been running around 1.7%. The continued upward move in wages should put downward pressure on margins and upward pressure on prices, and we see core inflation getting back to the Fed’s target of 2.0% by the end of 2017. The ongoing progress toward the Fed's inflation and employment objectives should keep them on track to slowly normalize short-term interest rates: we look for a hike in December and two more next year.
Digging a little deeper into sector performance, we note the consumer was the mainstay of the economy in 2016, an outcome which we expect will continue in 2017. Although the pace of job growth may be slowing modestly, wage gains are picking up. This vigor in labor income could get added support from tax cuts, further boosting disposable personal income. Household balance sheets remain healthy, supported by ongoing valuation gains in stocks and, particularly, housing, and the appetite for debt growth has remained modest. Consumer sentiment has also been supportive, as households have been mostly unfazed by global stress and political uncertainties. The one fundamental that looks a little less supportive relative to last year is energy prices. The tailwind of earlier declines in retail gas prices helped fuel a spending binge in early 2016 that is moderating a bit as we head into 2017.
More Apple Info
CNBC has noted that “If the company’s massive cash pile was its own company, it would be the seventh largest in the S&P 500 and the 14th largest public company in the world.” This pile is now $238 billion and growing at almost $1 billion a week, so it is well over $240 billion now. We’ve noted many times that that cash can be used to invest in new products, buy other companies or be paid out to stockholders through dividends and stock repurchases. It seems to us that many investors just forget about it. We certainly don’t. We don’t understand. It’s like having a net worth of $1 million and having $400,000 in cash in Ireland. How would YOU feel? We say pretty good!
At current prices, Apple has a PE of about 13, a significant discount to the overall stock market with a PE of 19. The stock didn’t participate in the stock market rally post-election and there seem to be many rumors about why. We don’t think it is necessary to go into them all, as most of them are made-up, meaningless excuses, and in the long run the only thing that matters is where the company is going with new products and increased sales and earnings. We believe they are going in the right direction. The current Christmas quarter is always their best one – they continue to sell iPhones at extraordinary rates
Gilead Sciences News
Stifel Nicolaus initiated coverage on Gilead Sciences (GILD: $75, up 1%) in a research note issued on Monday. The firm set a buy rating and a $100 price target on the biopharmaceutical company’s stock. The price target price would indicate a potential upside of 33% from the company’s current price.
Several other equities analysts have also recently commented on Gilead. Piper Jaffray set a $108 price target and gave the stock a buy rating in a research note in August. Cowen set a $120 price target on the stock in October. RBC Capital Markets reaffirmed an outperform rating and set a $105 price target in July. 10 research firms rate the stock with a hold rating, 19 have assigned a buy rating and two have given a strong buy rating to the company’s stock. Gilead Sciences has a consensus rating of “Buy” and an average price target of $98.
BMR Take: What can we say. We think these analysts are secretly reading The Bull Market Report. We have a Target of $115 on the stock.
Netflix News
Brean Capital began coverage on shares of Netflix (NFLX: $117, up 2%) in a research note issued on Monday. The firm set a $145 price target on the stock. Several other research firms also recently weighed in on Netflix. Cantor Fitzgerald set a $135 target price on October 27th. Guggenheim reissued a “buy” rating and set a $140 target price on October 26th. Finally, FBN Securities reissued an “outperform” rating and set a $130 target price on October 21st. 8 analysts have rated the stock with a sell rating, 13 have issued a hold rating and 30 have given a buy rating to the company.
BMR Take: This stock is not for the weak. It has little in the way of earnings now, but huge potential down the road as it moves into the programming side of TV and movies. We have a price target of $133. And if this price is hit, we think it will go a lot higher in the coming years. But this stock could go to $100 before it gets to $133. In fact, it could go to $80 first. So be careful out there. We hereby change our Sell Price to $105, from “We would not sell Netflix.” Why? Well it all depends on Wall Street. With the Dow at 19,000 everything is rosy. But if the Trump rally fades with the market falling sharply, and the Dow heads to 17,000, this will bring all stocks down harshly. We just want you to be prepared.
A Letter to The Bull Market Report about First Solar
Hi Todd,
Hope you are well. It is hard to watch First Solar (FSLR: $31, up 5%) continue to plummet. I had lost on Solar in the past but bought on your recommendation. I am holding now as you feel it can double over the next year. What do you see as the catalyst?
Thanks.
Richard Reed
We said:
Richard -
First Solar looks sick, yes, but it will come back. It has done so many times in its history. And really, the world is poised for solar installations. But earnings are not going to happen until late 2017 and possibly on into 2018 and in the world of Wall Street this is a long time to wait. And the market will overdo it to the downside, especially now with higher interest rates on the horizon. They always do. So if you have strength and courage, you should stay in. If not, just call it quits. I am very upset about this outcome, Richard.
Todd
Hi Todd,
Thanks for your response. The tough thing for me was I held my nose buying this stock because your thesis made sense. Despite having lost on Solar stocks in the past I thought this may be the time. My tendency is to get out but I continue to hold on your recommendation. You have given up on some stocks recently so I know when you are sufficiently disenchanted you will sell. The question for me at this point is how much lower this will go before the possible upturn. I am assuming you feel that the risk-reward is in favor of holding. Thanks again.
Richard Reed
The Google vs. Amazon Race
Google (GOOG: $761, flat) and Amazon (AMZN: $780, up $20) were neck and neck last week, but look at the results for the past week. Amazon came back with a vengeance to take the lead in this race.
Now we want to add another stock to this complex race. Apple. Apple closed at $112, but they split their stock two years ago 7-1. So multiply by 7 and you have $784, the same price as Amazon. So we are adding Apple to the race. For fun, let’s put a time limit on this race. Let’s pick the end of the first quarter of 2017. Who do you think will win? Send your votes here: Info@BullMarket.com. Who do you think WE believe will win the race?
Tons of Cash Leads to Stock Buybacks
The biggest US companies are set to spend a record amount of cash buying their own shares in 2017, according to Goldman Sachs. Goldman estimates that S&P 500 buyback spending will total $780 billion next year. That would be more than their estimate of $600 billion in 2016, which is on track to be a record. Buybacks reduce the number of outstanding shares, boosting earnings per share. Some say the companies buy their own stock because they think the stock is undervalued, which we tend to agree with.
Goldman thinks the splurge on share repurchases it expects in 2017 will be driven by a 12% increase in total cash use and $2.6 trillion in spending. There’s a lot of cash held overseas and Trump has proposed to cut the rate to 15% from 35%, which Goldman thinks is very likely. And they think that most of the cash repatriated will go towards share repurchases. They even mention a number - $150 billion. That’s a lot of buying power.
Musk Says Tesla’s Solar Shingles Will Cost Less Than a Dumb Roof
Electricity is Just a Bonus
Tesla shareholders approved the acquisition of SolarCity. (85% of them voted yes.) And Chief Executive Officer Elon Musk didn’t take long to make his first big announcement as head of this new enterprise. Minutes after shareholders approved the deal, Musk told the crowd that he had just returned from a meeting with his new solar engineering team. Tesla’s new solar roof product, he proclaimed, will actually cost less to manufacture and install than a traditional roof - even before savings from the power bill. “Electricity,” Musk said, “is just a bonus.”
Well, we are taking this with a grain of salt, but it sure makes good headlines. Musk is making some big comments: He says: So the basic proposition will be: Would you like a roof that looks better than a normal roof, lasts twice as long, costs less and by the way generates electricity? Why would you get anything else?”
The company says that on a large house over a long period of time, the value of that electricity could exceed $100,000.
BMR Take: We’re drinking the Kool-Aid, just like everyone else. That’s why we keep saying that this company is risky and could go to $150 or lower before it goes to $250 and higher. Listen, we love this company and its leader. But again, be careful.
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
Bond markets have literally been beaten up since Donald Trump’s election, with 10-year Treasuries currently seeing 2.36% yields (up 30% from the 1.8% range!) and total losses at well over $1 trillion. Last week we wrote that one of the reasons for the plunge was the market discounting a new era of inflation - however, the exact reasons why bond markets are falling were and are still not entirely obvious. Does higher expected inflation really account for the steep rise in yields?
An article last week from Money and Market had some new information into what else is going on. It said that world governments were selling Treasury bonds hand over fist leading up to the election because of yuan-supporting in China and budget reasons in Saudi Arabia, so the market already had a lot of downward momentum. Also, investors may fear inflation, but they also are fearful of another huge pile of Treasury debt. The bottom line with all this is that no matter the reason, there are too many of them. Especially if you believe in any of the old investment maxims such as, "don't fight the Fed", "the trend is your friend", "don't fight the tape", and "don't catch falling knives," etc. Bonds are under pressure and likely to stay so until the new administration's agenda becomes more clearly understood.
In this wonderful new period of optimism for the market, we want to issue one caveat. Let's consider that the entire recovery, at least post 2010, has been built on fake economic data to perpetuate a fake narrative of growth. In other words, it may be much harder for a new administration to get the economy going again because the true condition of it has been "covered up." For example, according to Value Bit News last week, "There is no way on earth that the real unemployment rate is less than 5%. Over 45 million people are on food stamps and over 94 million people are out of the work force. Claiming unemployment is at 5% in the context of these two other data points is like claiming you’re in incredible shape provided you don’t count body fat or cardiovascular health".
It's well known that the US has yet to achieve a single year of 3% GDP growth in the last eight years. Moreover, many analysts say even these weak growth numbers were doctored and that in reality the US’s economy stripped of accounting gimmicks is in fact much worse. What we do know is that the recovery has been weak despite the US spending a truly staggering amount of money.
Again, according to Value Bit News, "During a period in which tax revenues have risen every year since 2009 with record tax revenues hitting in 2013, 2014, 2015 and soon to be 2016, the US Government has still managed to outspend this amount to the tune of $8.1 TRILLION. Put another way, despite the US Government raking in RECORD amounts of tax revenues in the last four years, it still managed to grow the debt by $2.5 trillion. And if you go back to 2009, the debt has grown $8 trillion. And what has the US got to show for it? Let’s be clear here. We’ve spent a staggering amount of money, increasing the US’s Debt to GDP ratio from 77% to 105%, and yet we’ve had the weakest recovery in US economic history…"
Trust in the media is at all-time lows and for good reason. Don't let media "noise" deflect you from staying focused on earnings and quality stocks if the mainstream narrative suddenly reverses in the coming months.
We don't doubt good things are on the way - we're just trying to temper expectations that it will be fast and easy to turn around an economy that probably isn't as strong as we have been led to believe.
Well, that is some powerful stuff to think about, Gary. We look forward to your input each week.
The Dollar and the Euro are Moving Towards Parity
The euro and the U.S. dollar could be trading one-for-one next year as Europe struggles with political uncertainty and the U.S. is expected to go on a fiscal splurge. Goldman Sachs predicted the two currencies will reach parity by the fourth quarter of 2017. The dollar has risen 4.4% against the euro, and 2% against a basket of world currencies since Donald Trump won the U.S. presidential election Nov. 8. The euro is currently trading at $1.06.
Investors have viewed Trump's proposals to spend heavily on infrastructure, while cutting taxes, as a catalyst for further domestic growth and inflation. They're also expecting more interest rate hikes from the Federal Reserve to match rising inflation. Other analysts expect the euro and dollar to reach parity even sooner. Nomura thinks it could hit as soon as six months, which would see parity as early as May. Citigroup said it had shifted its euro-dollar forecast “180 degrees.” The bank now predicts the euro will tumble to 98 cents in the next 6-12 months.
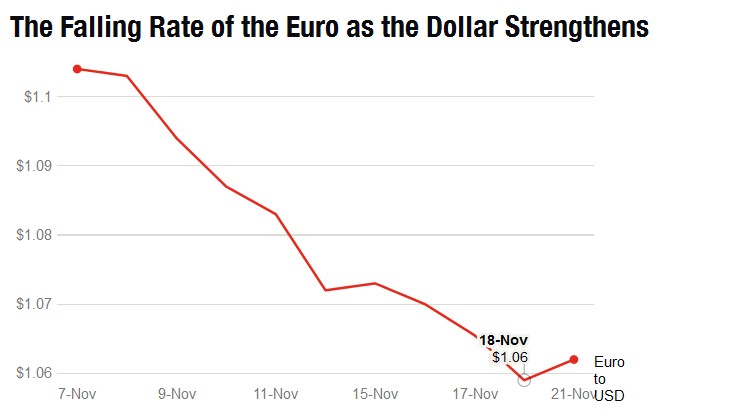
The market is watching Trump like a hawk, and the Fed is doing everything it can to strengthen the dollar, and at the same time the European Central Bank will probably do nothing to support the euro. If the Federal Reserve increases rates, expectations are the dollar would rise further by drawing money to the U.S. looking for higher returns. The European Central Bank, meanwhile, is showing no changes in monetary policy that has pushed rates into negative territory and includes a huge bond-buying program.
We have seen a 10-day losing streak for the euro against the U.S. dollar as we write this over the weekend. In the last two weeks, the euro has fallen 4% against the dollar, hitting $1.06, a level last seen 12 months ago.
Introduced in 1999, the common currency spent much of its early years below parity, falling to as low as 83 cents in 2000, when there was a strong U.S. economy and a weak one in Europe. But the currency has traded above $1 since late 2002, climbing to a high of $1.60 as the U.S. struggled with the financial crisis in 2008.
Goldman expects one interest-rate increase soon from the Fed, followed by three more in 2017, and thinks the ECB will extend its quantitative-easing program to the end of 2017.
Europe has already witnessed one political earthquake this year, when the British surprised investors by voting to leave the European Union. Now, the eurozone’s political diary is full of potential market shocks. Early next month, a constitutional referendum in Italy could sink the government of Prime Minister Matteo Renzi. The resignation of Mr. Renzi, one of Europe’s most reform-minded leaders, could freeze Italy’s economic overhaul and erase the meager growth the country has generated.
Also lining up are key elections in France, Germany and the Netherlands, all of which have seen populist right-wing parties move higher in the polls.
A strong dollar is good for the US, as it draws investment to the country, and it could actually be good for Europe as it makes their goods less expensive here in the US which should increase trade.
The High Yield Report
Due to internet issues, we don’t have the High Yield Report for this week. We will send it out as a News Flash as soon as we are able.
$8.2 billion Withdrawn from Bond funds
Investors withdrew $8.2 billion from U.S. bond funds in the week ending November 16, 2016, the largest outflow since June 2013. Investors have liquidated fixed-income funds more than they have over the past three years. This sell-off has depressed fixed-income fund prices, which have driven up the yields, as there is a negative correlation between the two.
Check out the price action over the past 14 days in several popular fixed-income funds. The iShares Barclays Aggregate Bond Fund (AGG) is down 2.4%, the iShares IBoxx Investment Grade Corporate Bond Fund (LQD) is both down 2%. The iShares iBoxx High Yield Corporate Bond (HYG) fund has rebounded, and is flat. While at first glance that may seem optimistic, recent developments in the junk bond market cause reason for concern.
The high-yield market has been smooth with more than $5 billion in debt issued following the election. High-yield has not been immune to withdrawals as in the three-week period ending November 16, investors liquidated $7.1 billion from junk bond funds, the largest three-week outflow since 2015.
The bottom line is that as long as we continue to see outflows in the fixed-income bond funds, prices will be depressed, and investors will be cautious. As we see a return to higher interest rates there could be an influx of money into U.S. fixed-income as the global hunt for yield continues. In Europe and Japan, pension funds and insurance companies remain hungry for yield, especially given the rise of negative interest rates.
Good Investing,
Todd Shaver
Founder and Editor in Chief
The Bull Market Report
Since 1998
November 21, 2016
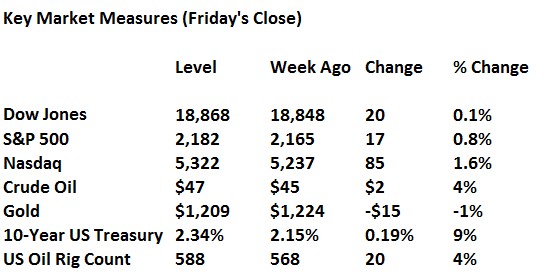
by Todd Shaver | Nov 21, 2016 | Monthly Newsletter Daily 6am if new
The Week Ahead
We finished this week above the fresh all-time highs set just a week ago. But we raise the question - have we come too far to fast? The frenzy seen post- election is seemingly pricing in a lot of good to come from new leadership in Washington. Are expectations reasonable or too aggressive? We note that Caterpillar recently said even if a $1 trillion infrastructure spending bill was passed today, it would take at least a year for projects to start, given the timelines for making the equipment needed. And we haven’t yet passed a $1 trillion infrastructure bill nor have we any clarity about how one would be funded. This infrastructure example highlights one market over-reaction to Trump, which is happening across many more sectors.
Good stock picks can make money in any market. This week we provide some insights on our latest thinking for Under Armour, Tesoro, Facebook, Amazon, and Microsoft.
Highlights From The Past Week
Repatriation. Many people are asking the question - If new leadership in Washington does lower repatriation taxes so that US companies bring home the $2+ trillion currently parked overseas, what will the money be used for?
The prevailing view at this time seems to be that much of the capital repatriated from overseas will be returned to shareholders, via repurchases and dividends. This is good for the stock market and for investors like us. However, we need to keep a close eye on how everything develops. Some are saying if the money just goes to buybacks and dividends rather than capital expenditures, then we won't see the big benefits to job growth and middle class income. There is talk of a flat 10% repatriation tax which should bring billions back to the US, but we’ll have to wait and see!
Fiscal Stimulus. Like Andrew Jackson’s populism, people are saying that we’re going to build an entirely new political movement: It’s everything related to jobs. They will be able to push a trillion-dollar infrastructure plan. With negative interest rates throughout the world, it’s the greatest opportunity to rebuild everything. Ship yards, iron works, new infrastructure projects get them all jacked up. We can just throw it up against the wall and see if it sticks. It will be as exciting as the 1930s, greater than the Reagan revolution. Exciting times! (We shall see.)
Interest Rates. The bond market bloodbath continues. The 10-year US Treasury yield is up a stunning 65 basis points from the Trump-win lows, spiking to 2.35% - the highest since December 2015. In fact, the entire Treasury yield curve is now higher in yield on the year, leaving most of everything newly issued in 2016 now under water. We are going to have to keep a close eye on where rates stand going forward. The cornerstone of fiscal stimulus will be low rates. But if the bond market re-prices rates much higher, the increased interest expense could throw a wrench in gears turning all of the current excitement.
BMR Companies and Commentary
Facebook (FB: $121, up 3% today)
Again, Facebook has found more miscalculated advertising metrics. The company said it has uncovered several more miscalculated metrics related to how consumers interact with content from marketers and publishers, and it unveiled additional independent review of some measurements to calm unease over the their data. An internal metrics audit found that discrepancies led to the undercounting or overcounting of four measurements, including the weekly and monthly reach of marketers' posts, the number of full video views and time spent with publishers' Instant Articles.
Does it matter? Should we be worried? What is the impact?
None of the metrics in question impact Facebook's billing. The only financial impact would be from customer perception about what has occurred, leading to customers shying away from spending money to advertise with Facebook because they have new concerns over these metrics. It is a stretch to go there. Facebook has well over 1 billion users. Just because a few mistakes were made on some back-office tasks doesn’t change how the business model connects advertisers to world. (We are not discounting this issue, but we think the market will perceive it to be a small matter. The company is already working on the PR to reduce the impact on perception.)
Let’s stay focused on what matters. Recall, it was a stellar quarter just recently reported. Facebook's Q3 earnings update that came in better than expected on top line revenues of $7.0 billion versus the $6.92 billion consensus and EPS of $1.09 was ahead of the Street's $0.97 expectations. Daily active users of 1.18 billion and monthly active users of 1.8 billion were both ahead of the Street's expectations as well. Management offered updated guidance on expense growth of 40-45% that was lower than the prior 45-50%. The negative takeaways were comments about decelerating revenue growth and heavy investments in 4Q16 and 2017. Many people think this was just management setting the bar low so they can beat it more easily. We agree.
BMR Take: If the first time miscalculated metrics didn’t shatter the Facebook growth story, we don’t think the second time around will. Clearly an operational mistake we don’t like to see, but we don’t see reason to exit our position in the stock over it. We think the company is set up to deliver better than expected financial results over the next several quarters. Stick around!
And this just in: Facebook will repurchase up to $6 billion in stock (first time they have ever done a stock buyback.) The buyback will start in the first quarter of 2017, using some of their $26 billion in cash. The market liked the news: the stock was up over a $1 in after-hours trading Friday.
BTW, we just noticed that Facebook’s all-time high is the same as Apple’s - $134. We wonder who will get their first. Our guess? Facebook. Why? Smaller market cap - $340 billion vs. $590 billion. Higher growth rate. So now we have two races to watch. Google vs. Amazon is the other. They both closed at the same price Friday. Love it!
Amazon (AMZN: $776, up 3% last week and up $16 today)
The word is CEO Jeff Bezos is telling executives to “Do what it takes to succeed” in India. Amazon fell a little behind in China early and business never quiet was able to recover to be as big as it could have been. Bezos is going on all in on India to ensure the same thing doesn’t happen twice.
Amazon had been India’s #2 ecommerce player. But that has changed. Bezos is now communicating to the market that Amazon has pulled ahead to be #1, with market share estimated around 28%.
India is a huge opportunity for Amazon. India has a population of 1.2 billion with about 40 million online shoppers. Goldman Sachs calls for ecommerce sales in India to grow 10-fold from today’s level of $11 billion over the next decade. And since only about one-third of Amazon’s sales are international, there is tremendous room for growth here. We understand that Bezos is going to invest another $3 billion in June into the India operation, in order to make the business even better. Amazon currently has over 80 million products selling in India. (This is not a misprint.) And they have more than 120,000 sellers, compared to 40,000 sellers a year ago. In June, the company said it will invest an additional $3 billion in India after it exhausted its earlier investment pledge of $2 billion. The company also launched its Prime membership program in July in more than 100 Indian cities, offering one-day and two-day delivery
BMR Take: Amazon’s stock has been down since the latest earnings report. The concern is that they are in a short term cycle of big investment spending. This news of more investments in India certainly plays right into the bearish outlook. Long-term, we think every dollar Bezos spends re-investing in the business will pay dividends later on. In the near-term, we brace for negative sentiment about how profits are being weighed down today due to these investments. Listen, we are not negative on the company nor the stock. We just want to give you both sides of the story. In fact, we think the market will shrug off this news and do what it always does, buy the story of bigger is better, awaiting huge profits in the future. But you never know…
Microsoft (MSFT: $61, up 2% last week)
Goldman Sachs upgraded the stock to Buy with a $68 price target. What’s the story here? Why did they upgrade? What are they now saying? Why is Microsoft all the sudden a buy?
The company got off to a strong start to FY17 as revenue and EPS came in above consensus estimates. The strength was driven by growth of Azure (the cloud business) and adoption of Office 365 (the web version of Office).
Many are now expecting the upcoming quarter to be an inflection point for Microsoft, as the company will complete the sale of its phone business and the acquisition of LinkedIn, signifying the end of the old and the beginning of the new.
We believe the integration of LinkedIn will enhance the value proposition of Microsoft’s entire platform, including Azure, Office 365, and Dynamics. As such, we believe the best is yet to come as we expect revenue growth acceleration and margin expansion ahead.
BMR Take: Glad to see Goldman Sachs come around to support our outlook. What a humbling game investing is. The world’s most powerful investment bank is playing catch up to a little tiny newsletter service out of Aspen, Colorado.
Goldman Sachs (GS: $210, +19% in the past two weeks)
Financials including Goldman Sachs rallied the most this past week. With rates finally rising, a steeper yield curve is good for banking and capital markets. More importantly, plans to roll back regulation are coming, which is huge for all of Financials, as they have had a bad stigma for years under the Elizabeth Warren era of denouncing Wall Street.
The regulatory discussion is currently all over the map right now about what we could see. The end of Dodd Frank? The termination of the Consumer Financial Protection Bureau? No more Volcker Rule allowing proprietary trading (again)? Some even say Glass-Steagall* could be on the table (again). Note that Trump has called for a general guideline of allowing new regulations to be implemented only if they replace two existing regulations. This all amounts to positive implications for Goldman Sachs.
*The Glass–Steagall Act describes four provisions of the U.S. Banking Act of 1933 that limited securities, activities, and affiliations within commercial banks and securities firms.
One more thing to ponder - who will Trump name as Treasury Secretary? The position once held by Alexander Hamilton is considered one of the highest honors in all of Finance for those asked to serve. Rumors are floating that Goldman’s CEO Lloyd Blankfein is possible candidate, as well as CEO Jamie Dimon of JP Morgan Chase.
BMR Take: Goldman is the #1 investment banking franchise. The investment banking business follows a boom-bust cycle. With the sharp rally recently, we are implementing a stop at $196 to protect our gains but we do not want you to miss more upside if the train keeps rolling. We added the stock at $147 in February, so we are up 43% in nine months.
Upcoming Economic News
Tuesday, November 22nd
Existing Home Sales – October
Time: 10:00 am
Forecast: 5.46 million
Existing home sales are projected to be little changed in October with tight inventories constraining transactions. Sales fell 0.4% year-over-year last quarter for the first decline of the past two years. Sharply rising Treasury bond rates will feed through into higher mortgage rates, adding another impediment to existing home sales growth.
Wednesday, November 23rd
Durable Goods Orders – October
Time: 8:30 am
Forecast: 1.0% overall, 0.2% ex transportation
Rising aircraft orders in October following two straight deep monthly declines can lead a strong overall gain in durable goods orders. Industrial demand has shown some recent promise; core capital goods orders increased 5.2% annualized in the third quarter against the previous quarter. Yet that recent burst in activity is tempered by the weak long-term trend; such orders fell 4.1% year-over-year during the same period.
New Home Sales – October
Time: 10:00 am
Forecast: 585,000
New home sales can dip a bit in October yet still point to strong long-term growth. Third quarter sales rose 23% year-over-year, as volumes continued to trend higher from depressed post-crisis levels. Though up substantially on an annual basis, last quarter’s 600,000 unit annualized pace trails the average rate of the past 20 years by 18%.
University of Michigan Consumer Sentiment – November
Time: 10:00 am
Forecast: 91.6
The post-election bounce in the stock market may ultimately feed into somewhat higher readings in consumer sentiment. The preliminary reading in the November Michigan survey was the highest in five months as consumers are reporting improved financial conditions. Renewed declines in oil prices can also spur stronger inclinations to increase spending on other items.
FOMC Meeting Minutes
Time: 2:00 pm
Given the jolt to interest rates and inflation expectations following the election, the minutes of the early November FOMC meeting will be somewhat stale. Yet the general push toward hiking the Fed Funds target in December will likely find additional support in the minutes. The next key question for monetary policy is how much policy tightening is likely in the year ahead. Economic projections released by the Federal Reserve next month will provide crucial guidance on this subject.
Twilio (TWLO: $37) had a good week, rising 17%. We’ve said many times how much we like this one, but the market has been hammering the stock these past few weeks. The turnaround in a week when most Tech stocks were hit hard, is impressive. Again, we think this is a $75 stock if they continue their phenomenal revenue gains that we saw in the past few years, and certainly last quarter. Twilio did $167 million in sales last year, up from $90 million the year before and the company is on a $1 billion annual run rate by the second half of 2018. Can’t wait for next quarter’s earnings. If strong, the stock should get back to the 50s and 60s in no time.
The Energy Corner
North Dakota’s crude-oil production in September dropped to the lowest level in more than two years. Crude production fell 1.1% on the month to 970,000 barrels a day in September, the lowest level since February 2014. North Dakota is home to the Bakken Shale formation, one of the world’s highest-cost oil fields. Growing confidence that crude prices will rise in coming months is sustaining the expansion of oil drilling in the shale patch. Rigs targeting crude rose 19 to 470 this week, the biggest increase in the last 16 months, according to Baker Hughes data reported Friday. Shale drillers have now added 155 rigs since an expansion started at the end of May. Gas rugs were flat, bringing the total for oil and gas up by 20 to 588.
This news just in - the Obama administration on Friday banned offshore drilling in the Arctic, setting a likely collision course with President-elect Donald Trump, who has vowed to “unleash” new energy production in the United States by rolling back restrictions on oil. Great – a new story for us to worry about.
So, US rig count is up sharply, which should produce greater volumes as we move into 2017. This counteracts the move by OPEC to cut production, which hasn’t been approved yet, and may indeed never happen
Interest Rate Corner
Federal Reserve Chairwoman Janet Yellen reiterated that an increase in short-term interest rates "could well become appropriate relatively soon" but offered no new signals about what the central bank will do at its meeting next month.
We are in the camp at The Bull Market Report that a ¼ point rise is baked in for December. Of course, she could surprise us with a ½ point rise, which would probably tank the markets like what happened last December. We hope she maintains some sense here. The 10-year Treasury note has exploded, from a low of 1.37% in July to 1.80% before the election to 2.34% Friday.
Tesla Update: It’s official: Tesla (TSLA: $187, down 2% last week) shareholders approved the acquisition of SolarCity. The company is now an unequivocal sun-to-vehicle energy firm. And Chief Executive Officer Elon Musk didn’t take long to make his first big announcement as head of this new enterprise. Minutes after shareholders approved the deal - about 85 %of them voted yes - Musk told the crowd that he had just returned from a meeting with his new solar engineering team. Tesla’s new solar roof product, he proclaimed, will actually cost less to manufacture and install than a traditional roof - even before savings from the power bill. “Electricity,” Musk said, “is just a bonus.”
If Musk’s claims prove true, this could be a real turning point in the evolution of solar power. The newly announced rooftop shingles are made of textured glass and are virtually indistinguishable from high-end roofing products. They also transform light into power for your home and your electric car.
“So the basic proposition will be: Would you like a roof that looks better than a normal roof, lasts twice as long, costs less and - by the way - generates electricity?” Musk said. “Why would you get anything else?” On a large house over a long period of time, the value of that electricity could exceed $100,000. The new roofing material he unveiled this past week is considerably cheaper, and it's considerably more promising for the future of rooftop solar power.
We love Musk. He never ceases to amaze and shock. Can he pull this off? Will he have enough cash to make it work? We think yes. But again, this stock could hit $150 before it hits $250. Volatile!
Goldman Sachs Maps Out Its Top Market Themes for 2017
They're heavily influenced by President-elect Trump.
Goldman Predicts: U.S. recession risk remains low in 2017
Goldman released its top 10 market themes for next year. "High growth, higher risk, slightly higher returns," is how their strategists view the year ahead - and it's clear that their outlook has been heavily influenced by the pending regime change in Washington.
Here's a brief summary some of the themes Goldman sees as forming the backdrop for investing in 2017. All thoughts and comments are for Goldman.
Expected returns: Only slightly higher
Relative to its 2016 forecasts, Goldman says owners of financial assets can reasonably able to expect more upside - but stresses that these returns will still likely remain low. The best improvement in the opportunity in global equities is in Asia ex-Japan, where we forecast returns of 12.5% (versus 3.8% for 2016.) At the other end of the equity spectrum, in Japan we are forecasting declines of 3.7% on the Topix (vs. +5.2% for 2016).
U.S. fiscal policy: A pro-growth agenda
President-elect Donald Trump's focus on infrastructure spending during his victory speech on Nov. 9 - rather than trade protectionism or immigration restrictions - catalyzed the risk-on sentiment that's pervaded markets.
Markets are starved for growth
This is plainly visible in the eagerness with which markets seized on Trump’s growth-focused message. It is also visible in the speed with which the market’s narrative on the economic outlook under Trump has shifted from uncertainty to growth. Fiscal stimulus in the U.S. will help reflate the economy, and stands a good chance of passing through Congress.
U.S. trade policy: Concerns are likely overdone
Goldman doesn't see an imminent trade war on the horizon, and expects any re-negotiation of agreements currently in place (like NAFTA) to focus on attempts to improve the prospects for the U.S. manufacturing sector. We think the popular media narrative on the downside risk of a trade war is overstated. Our tentative view is that Trump’s use of punitive tariffs will be just as pragmatic as President Obama’s, albeit more vocal.
Emerging markets risk: “Trump tantrum” is temporary
Emerging market assets have been crushed since the election, as the rise in Treasury yields has reduced the need to reach for yield overseas, and the potential for protectionist trade policies threatens to curtail growth opportunities.
Monetary policy: Focusing the toolkit on credit creation
Better-targeted monetary stimulus could help avoid some negative side effects associated with quantitative easing and negative rates that inhibit credit creation.
Corporate revenue growth recession: Signs of inflection
For years, S&P 500 companies have exceeded analysts' expectations on the bottom line more often than the top line during quarterly earnings seasons, as a combination of cost-cutting and shrinking share count, rather than soaring sales, fueled the growth in earnings per share. However, Goldman expects 2017 to confirm that the U.S. corporate sector has emerged from its recent 'revenue recession.' A firming global economy and recovery in oil prices from their February lows significantly buoys the outlook for revenue growth stateside.
For 2017, Goldman expects that modest improvements in the macroeconomic backdrop will help lift S&P 500 operating EPS by 10% and they have a year-end S&P 500 target of 2200, currently 2180 now. [Not terribly exciting if you ask us. We differ. We don’t normally predict, but we would certainly be looking for 2300 or 2400.]
Inflation: Moving higher across developed markets
Market-based measures of inflation expectations in the U.S. have spiked since the election, as traders bet that Donald Trump will be the inflation president.
What seems clear to us, as argued above, is that economic issues, notably tax cuts, infrastructure spending and defense spending, are high on the agenda - a recipe for reflation. We are forecasting large boosts to public spending in Japan, China, the U.S., and Europe, which should fuel inflationary pressures in those economies.
The next credit cycle: Kinder and gentler
While commodity-sensitive segments of the credit market have suffered pain in 2016, there hasn't been much in the way of contagion. Goldman's team expects more of the same in 2017, with the credit cycle not making a turn for the worse. The strong ‘business cycle’ component in the behavior of high yield defaults, and our view that U.S. recession risk remains low in 2017, leave us comfortable with the view that the inflection point is unlikely to materialize next year, despite the weak state of corporate balance sheets.
Mortgage Rates Surge After Election
Here is some news on the state of the mortgage market. Mortgage rates surged after the election win of Donald Trump. But housing experts say consumers shouldn't get carried away by the post-election wave. The advance of the past week or so, stoked by a surprise victory that turned economic expectations on their head, could soon settle.
"Consumers considering buying or refinancing now should stay patient, as we'll likely see rates stabilize once markets find a new equilibrium," says Zillow, the mortgage rate real estate company.
In the week ended Thursday, the average rate on the 30-year fixed-rate loan jumped to 3.94% from 3.57% the previous week, mortgage company Freddie Mac reported. A year ago the market was at 3.97%. The average for a 15-year mortgage climbed to 3.14% from 2.88%
The High Yield Corner
We have seen our first full post-Trump trading week, and it wasn’t bad. Actually, things were impressive considering the expectations and last week’s bull run. The S&P 500 rose nearly 1% by the end of the week, but the really interesting story is the difference between different stock groups. Large caps underperformed small caps significantly - this has a lot of important implications for high-yield investors, so is worth a closer look.
The Dow Jones Industrial was pretty much flat last week, while the Russell 2000 went up 2.6%. The difference between these two is the result of different trends between different investors: the risk-averse are more worried than the less risk-averse, who are willing to give small caps a chance in the hopes that they will deliver the higher-than-big-cap returns that they gave in the past. This has pushed small caps up to a 17% year-to-date return after rising 8% in the last month.
But here’s the really interesting part: the Dow Jones is up 10% year-to-date after a 4% return over the last month. The S&P, however, is up 7% year-to-date after rising 2% in the last month.
What this means is that risk appetites have grown in the last month while the more cautious are less eager to jump into the Trump rally. They aren’t avoiding it, but they aren’t going into it as much as the more risk-tolerant investors. In other words, we’re having a growing disagreement about future risks with the economy as a whole.
This is not uncommon, but wasn’t the case earlier in 2016. Both large caps and small caps had similar high returns for much of 2016 - and now that convergence is subsiding.
This is important for high yield investors for two reasons. First, junk bonds and BDCs tend to trade closely with small cap stocks as they attract similar investors: risk-tolerant institutions. Second, a market where the risk-averse are more cautious and the risk-hungry are less so often portends a bubble followed by a crash. That is not in the cards quite yet, but it does make one wonder if the industries getting a big boost - Financials in particular - might get overbought if they haven’t already.
With this as our backdrop, let’s take a look at how each asset class performed in the last week and why:
REITs - Initially REITs were the hardest hit by Trump’s victory on fears that his spending plans would kickstart inflation and thus increase REITs’ borrowing costs. This remains a concern, as the U.S. Treasury 10-year keeps going higher, but we’ve finally gotten to a point where the risks are priced in. Fortunately for REITs they already began correcting before the election, so this week’s return was just barely green, according to the SPDR Dow Jones REIT ETF (RWR: $89. Flat).
Results for individual REITs varied, but our picks did OK. Kimco Realty (KIM: $26) rose slightly, Digital Realty Trust (DLR: $90) rose over 1%, Omega Healthcare Investors (OHI: $28) was flat, Care Capital Properties (CCP: $24) rose 4%, and Government Properties Income Trust (GOV: $18.90) rose less than 1%. We also added a new REIT to our portfolio: Ventas (VTR: $60), which rose 2% this week. Ventas is one of the few REITs that is up year-to-date in the Healthcare space: rising 6% so far this year, but its price-to-FFO ratio and growth potential make it extremely attractive.
Junk bonds - The corporate bond market is now dominated with changing inflation expectations. Love him or hate him, but the market believes Trump is going to cause inflation to accelerate. This isn’t a testament to his failures or abilities, however; much of these expectations are the end result of the Fed’s constant efforts to improve inflation rates and a time when low oil prices and high supplies are priced in. There are many reasons beyond Trump to think inflation will not stay low forever, and having a president in the office (whoever it may be) who is focused on rising inflation with a House and Senate that will work with him, almost seems a perfect formula for rising inflation.
That is why junk bonds have done particularly badly after Trump, but the real surprising thing is that they didn’t do poorly for longer. Last week the SPDR Barclays High Yield Bond ETF (JNK: $36) rose over 1% and is now up 5% from the beginning of the year. Yet the fund has a near 7% dividend yield that is far higher than it has been in recent years. This is partly because of expectations of a rate cut for the fund*, which has happened in the past, so it’s important to keep in mind the more actively managed alternatives that aren’t tied to an index** and thus have more flexibility to ensure payouts remain constant. Note that the ETF recently registered $342 million asset inflows for a 3.15% increase.
*JNK's distribution cut is expected because the BofA High Yield index has fallen. Since JNK tracks that, its distribution should fall too.
**Active funds like PDI vs. passive indexing funds like JNK. In other words, “alternative funds that are actively managed" makes that clearer.
Our pick to take advantage of this strategy remains Pimco’s Dynamic Income Fund (PDI: $27), which had a nice 4% gain this week to offset last week’s massive decline. The fund is still down over 4% from a month ago which means it is poised to improve in recent weeks. The fund is also now flat year-to-date with a near 10% dividend and a looming special dividend that we believe will be at least 3%. That turns this fund into a 13% dividend payer with a sustainable dividend. That is almost impossible to find in the market (we know as we’ve looked for more, but Pimco’s fund seems to be it!)
Municipal bonds - Rising interest rates are a problem for all bonds, but they are actually worse for corporate bonds than municipal bonds because of the risks and the way these are structured. Yet looking at the municipal bond world lately, you’d think it’s the riskiest asset in the world. The iShares National Municipal Bond ETF (MUB: $108) fell 1% this week and is down 3% over the last month. The ETF is also down 2% for the year, making municipal bonds one of the few asset classes that has had negative returns for the year.
We have been wary of municipal bonds this year because of their massive run-up before the summer and rate hike concerns. We don’t believe rate hikes directly are a drain on municipal bonds, but fears about rate hikes often overshoot the real risks and cause a big and prolonged selloff. We saw this in 2015 and have seen this to a lesser extent this year. This is why we have only recommended one municipal bond fund this year: the Nuveen Enhanced AMT-Free Municipal Credit Opportunities Fund (NVG: $14:04). The fund is down 2% over the last week and is down 3% year-to-date. The most shocking figure is the three-months metric: the fund is down 14% in that time.
We expect these massive declines to reverse, but it is going to take a while for that to happen and it is difficult to time. While municipal bonds are already oversold, that does not mean the market knows they are oversold, and they can go down even lower. Nuveen’s fund is a good long-term hold and we expect it to hold its NAV for the long term, as it has done for over a decade already. However, we also expect greater volatility to hit this and all municipal funds. Anyone wishing to invest in munis now will have to endure these short-term price declines with patience, buying more as the stock goes down.
From one extreme of the risk/reward spectrum to the other, let’s turn to BDCs. The UBS BDC ETF (BDCS: $22) rose over 1% over the last week and has had a somewhat strong showing after the Trump election. While BDCs aren’t going up nearly as much as Financials, they are both rising for the same reason: an expectation that deregulation is going to cause credit to flow and the Financial sector to boom. BDCs cannot help but benefit from this, so they are rising with the Financial sector. However, they are not rising from an extreme bottom as Financials are, so the asset class’s 2% monthly return is a fraction of the double-digit returns of the Financial sector as a whole. This is unlikely to change.
At the same time, we have finally gotten to a point where Main Street Capital (MAIN: $36.50) has gotten overbought. The BDC is now up 16% from when we recommended it in April after rising 8% in the past month alone. We waited for this week’s dividend distribution to see if the stock would fall further after the payout, but it hasn’t; in fact the stock is up over 1% after its recent payout. That now means Main Street is selling at a 70% premium to its net asset value and it has passed our target price. We are keeping our price targets on Main Street, which means recommending selling at these levels and waiting for the price to correct before jumping back in. Main Street remains an excellent firm with impressive advisors and the capability to increase dividends for a long time, but the cost of that expertise and growth potential is too high now. We will buy again when the stock is more fairly priced.
Good Investing,
Todd Shaver, Founder and Editor in Chief
The Bull Market Report
