April 17, 2017
by Todd Shaver | Apr 17, 2017 | Earnings Preview 12 PM
Netflix (NFLX: $146)
Bull Market Report Target Price: $165
Bull Market Report Sell Price: $125
Earnings Date: Monday, 3:00 PM ET
Consensus: 1Q17
Revenues: $2.6B
EPS: $0.37
Year Ago Quarter Results
Revenues: $2.0B
EPS: $0.06
Key Things to Watch For in the Quarter
Wall Street analysts estimate that for 1Q17, Netflix will report healthy revenue growth at 35% to $2.64 billion and strong EPS growth of 517% to $0.37, although the percentage number is misleading since their last quarter was so tiny. Netflix beat analyst estimates in all 4 quarters of 2017. The stock reflected this success, climbing 32% over the past year. Despite beating estimates in the first two quarters of 2016, the stock fell over 10% following the earnings releases primarily due to skepticism of the firm’s ability to expand overseas memberships. However, the stock made up for these losses upon the release of 3Q16 earnings when it climbed 25%. As Netflix continues to produce positive growth numbers and expand its business abroad, we look forward to watching the price climb towards our $165 target.
Kinder Morgan (KMI: $21)
Bull Market Report Target Price: $27
Bull Market Report Sell Price: $18
Earnings Date: Wednesday, 4:30 PM ET
Consensus: 2Q17
Revenues: $3.4B
EPS: $0.18
Year Ago Quarter Results
Revenues: $3.2B
EPS: $0.18
Key Things to Watch For in the Quarter
Analyst estimates suggest that Kinder Morgan will report a 5% increase in sales to $3.35 billion and no change in EPS for 1Q17. Kinder Morgan missed analyst estimates this quarter last year, but made up for it in the last three quarters of 2016. Shares dropped 5% in the week following the firm’s release of 1Q16 earnings, however it has since made up for this small loss providing investors with a 15% return over the past year. The company has made significant progress on a number of growth projects, especially its Trans Mountain Expansion Project, which had faced pushback from environmentalists.
Kinder Morgan is one of the largest energy infrastructure companies in North America. It owns an interest in or operates approximately 84,000 miles of pipelines and 155 terminals. KMI’s pipelines transport natural gas, refined petroleum products, crude oil, condensate, CO2 and other products, and its terminals transload and store petroleum products, ethanol and chemicals, and handle products such as steel, coal and petroleum coke. It is also a leading producer of CO2 that is used for enhanced oil recovery projects primarily in the Permian basin.
Blackstone Group (BX: $29)
Bull Market Report Target Price: $36
Bull Market Report Sell Price: We would not sell Blackstone
Earnings Date: Thursday, 11:00 AM ET
Consensus: 1Q17
Revenues: $1.7B
EPS: $0.67
Year Ago Quarter Results
Revenues: $930 M
EPS: $0.31
Key Things to Watch For in the Quarter
Analysts across Wall Street expect Blackstone Group to report revenue growth of 80% to $1.7 billion and 115% growth in EPS to $0.67. The firm has beaten analyst estimates in the past 3 quarters. Share prices in the weeks following the earnings release of Q1-Q4 of 2016 reflected the company’s ability to meet analyst expectations. It’s a bit volatile after earnings releases, as in all four events, shares either climbed or dropped at least 5%. In a recent interview with CNBC, Blackstone CEO Steve Schwartzman mentioned that the firm is in advanced talks to acquire Ascend Learning, a U.S. maker of educational software, in an attempt to capitalize on the increased use of technology in American classrooms. The stock has remained relatively unchanged over the past year, but continues to provide a healthy dividend at over 5%, making it an attractive investment for dividend-seeking investors.
Visa (V: $89)
Bull Market Report Target Price: $95
Bull Market Report Sell Price: We would not sell Visa
Earnings Date: Thursday, 5:00 PM ET
Consensus: 2Q17
Revenues: $4.3B
EPS: $0.79
Year Ago Quarter Results
Revenues: $3.6B
EPS: $0.68
Key Things to Watch For in the Quarter
Analysts expect Visa will report modest growth in both earnings and revenue for 1Q17. Earnings are estimated to grow 16% to $0.79 and revenue 19% to $4.3 billion. The stock has reflected the company’s ability to beat analyst estimates throughout all of 2016 having climbed 9% over the past year. Visa leads the payment processing industry and still finds room to grow primarily because it has no direct competition within its market. Analysts expect international transaction revenues to be the engine of growth for a number of reasons, including international tourism growth. We look forward to resetting our $95 price target as the stock continues to appreciate.
by Todd Shaver | Apr 17, 2017 | Monthly Newsletter Daily 6am if new
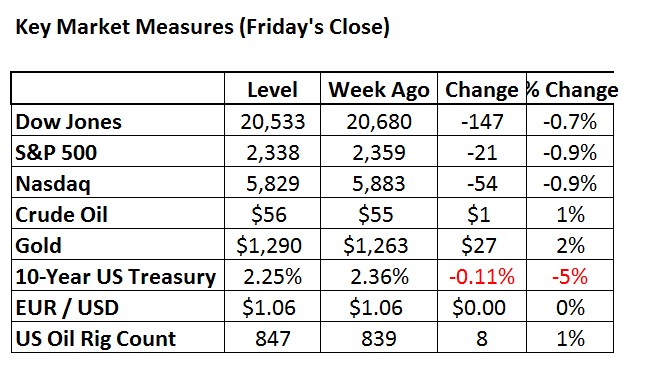
The Week Ahead
What did the Easter Bunny bring this April to the markets? Much lower interest rates! The 10-year dropped 11 bp to 2.25%. Who says interest rates are going up this year? Not us, for sure. Geopolitical worries are the primary culprit. North Korea, Syria, the Middle East, all the regular actors are to blame. The 10-year Treasury now rests around 5 month lows. Everyone will look to the Fed for guidance about where the markets are going. Interestingly, Trump is now praising Yellen in a public call for Fed consistency, which contradicts his accusations on the campaign trail that she was artificially manipulating the economy in a detrimental way. Hmmm…does Trump see an opportunity to take advantage of low borrowing costs for his $1 trillion infrastructure plan? His Treasury Secretary Steven Mnuchin has publicly expressed interest in doing big time deals for 100 year bonds. And we applaud this. We’ll have to wait and see.
There is always a bull market right here at The Bull Market Report! This week we highlight the following securities: Shopify, VMware, Amazon, Annaly, Apple, and Tesla.
Highlights From The Past Week
Watchful Eye On North Korea. US officials are saying the Trump administration is focusing its North Korea strategy on tougher economic sanctions, possibly including and oil embargo, banning its airline, intercepting cargo ships, and punishing Chinese banks doing business with Pyongyang. According to one official, US President Donald Trump has approved a preliminary broad approach on North Korea and asked his national security team to craft a more detailed framework for new international sanctions and other actions. The official said the administration is considering an array of stiffer sanctions that could be applied on a "sliding scale," proportionate to North Korean actions. Some steps could be applied unilaterally, with others through the United Nations.
Business Returning to the Center Stage in the USA. Business leaders are gaining more and more influence in Trump's White House. Most recently, Jared Kushner, the president's son-in-law, is trying to orchestrate more power for National Economic Council Director Gary Cohn while dampening the influence of chief strategist Steve Bannon. It is quiet the change in scenery to see Washington acting as a friend to business led by accomplished business people. All good news for the markets.
Infrastructure Bill On The Horizon. One of Trump's top policy advisers said the timing of the President's $1 trillion infrastructure package is still up in the air as the administration considers its best path forward. D.J. Gribbin, special assistant to the president for infrastructure policy, said the timeline will hinge on whether it moves as a standalone measure or if it is attached to another legislative priority. It adds that they are still crafting the infrastructure measure. Transportation Secretary Chao said the package could be unveiled as soon as next month. We can’t wait.
BMR Companies and Commentary
Shopify (SHOP: $71, +4%, all price changes in this report are for the past week)
Shopify had a solid week as talks of a takeover swirled. If true, we could see some very nice upside in the near-term. If not, that’s fine with us, as we still like the company’s fundamentals and prospects. Bottom line, Shopify still has room to run whether there is a takeover. Let’s re-visit why.
One can hardly kick back on the couch and watch CNBC or browse through your favorite financial publication these days for more than a few minutes before you come across a discussion of Amazon, as the online Retail juggernaut has skyrocketed to become an American business behemoth. And rightfully so.
For investors who want to capitalize on the undeniable secular growth trend of eCommerce, but who either missed the boat on Amazon or are wary of its nosebleed valuation, is there another road less traveled that they could embark on to get exposure to the eCommerce tidal wave? One that has impressive momentum and an ascendant stock price, but just not as frothy of a gain as Amazon? Yes there is. That’s Shopify.
Shopify not long ago announced its full-year financial results for 2016, and boasted 90% revenue growth and 99% growth in gross merchandise volume, (a term used in online retailing to indicate a total sales dollar value for merchandise sold through a particular marketplace over a certain time frame.) As an added bonus, Shopify's “Sell on Amazon” integration was made generally available to merchants in December. This mean Shopify now seamlessly connects store owners to the millions of customers searching for products to buy on Amazon, and merchants can now conveniently manage their product catalog for their eCommerce website, retail store, Amazon store, and other sales channels all in one place. This is big time! Since this integration just took place in December, we are only at the tip of the iceberg in terms of benefits and synergies from the move for Shopify.
BMR Take: The consensus calls for Shopify to more than double revenue from $600 million this year to $1.4 billion by 2020. This kind of explosive growth could cause the stock to double over the same period.
Amazon (AMZN: $884, down 1%)
A new week; Another big move brewing for Amazon. It is said that the eCommerce giant considered internally whether Whole Foods would help invigorate its nearly decade-long push into groceries. That is, Amazon kicked around the idea of buying the grocery chain!
Whole Foods has long been seen as a buyout target. Activist investor Jana Partners set off a new wave of speculation this week when it acquired a stake and urged the company to evaluate a sale. With a market valuation of $11 billion, the ailing organic-food retailer would be a powerful acquisition for Amazon -- dwarfing its 2009 purchase of online shoe retailer Zappos for about $1.2 billion. But the deal would turn Amazon into a grocery giant overnight and help it sideline Instacart, a startup that delivers grocery orders from Whole Foods stores in more than 20 states.
Jana has called for Whole Foods to overhaul its operations and brought in retail and food experts to help foster a turnaround. It also urged the company to consider a sale. A list of potential bidders includes Amazon, as well as traditional grocery chains such as Kroger and Albertsons. Whole Foods remains an attractive asset, even after a sales slump and the loss of market share to mainstream supermarkets, because the brand is strong and could be leveraged into something big.
BMR Take: Amazon and CEO Jeff Bezos are winning at everything. Why not grocery? Current Street earnings estimates call for $27 per share by 2020. With so much growth and strong earnings potential, the shares are compelling here.
Annaly Capital Management (NLY: $11.63, +5%)
Looking for yield in this market? Look here! Annaly Capital Management is a top pick in the Mortgage REIT sector.
Let’s review some of the reasons to like Annaly. Home price gains were up 6% in latest report from Case-Shiller, showing acceleration in home price increases. Tight supplies and rising prices may be deterring some people from trading up to a larger house, further aggravating supplies because fewer people are selling their homes. This is a good trend for Annaly. Annaly owns mortgages so rising home prices means the credit risk of owning the bonds is safer.
Annaly has a broad exposure across the US unlike other competitors more narrowly focused on only a particular market like New York. Yet another reason to like Annaly.
BMR Take: With a yield of 10.6% and a track record of over 20 years doing this, we continue to pound the table on Annaly. Look at this stock – up from $10.12 in mid-January in the midst of a strong interest rate rise with EVERY pundit saying that Annaly will be impacted sharply with the higher rates. Boy oh boy where they ever wrong. And boy oh boy were we ever right. Of course we’ve been saying this since we founded The Bull Market Report in 1998!
Apple (AAPL: $141, -2%)
Apple to buy Disney? Now that’s exciting! It could be more realistic than you think. Apple has the cash to pull off a $200 billion-plus takeover of Disney — creating a company worth $1 trillion with “almost limitless opportunities in content and technology.
A combined Apple-Disney would create an instant competitor to Netflix that would take advantage of the Mouse House’s content and Apple’s user base. Other benefits include: integrating Apple consumer tech as experiences in Disney’s theme parks; and landing global streaming sports rights for ESPN via Disney and Apple distribution and a strong balance sheet. Content is a major focus for Apple, target size is not an issue, and Disney offers an avenue to diversify away from hardware without diluting the strong Apple brand.
The M&A rumor mill got new grist last fall, when Apple chief Tim Cook told analysts that he was “open to acquisitions of any size.” In addition, Apple execs met with Time Warner honchos in 2015 in a discussion that raised the possibility of a merger - before AT&T moved on its $85 billion bid for Time Warner,
Per one analyst’s estimates, the merger of Apple and Disney would be highly accretive to earnings, to the tune of a 15%-20% increase in earnings per share based on the presumed 40% premium deal price and Disney’s low debt load. Nice!
BMR Take: We say it every week and we’ll say it again. Apple is really cheap compared to the current EPS outlook for this year of nearly $9. And all that cash put to good use through buying a storied franchise like Disney could be an exciting catalyst/prospect for the company.
Tesla (TSLA: $306, flat)
Tesla is a new entrant into the automobile, solar and battery storage businesses. Since Tesla’s current revenue is roughly 99% automobile related and, due to the Model 3 introduction and projected sales, this ratio will likely remain similar for quite some time. Thus, Tesla is an auto manufacturer, plain and simple. Panasonic supplies Tesla with batteries. Other companies provide Tesla with electric motors, tires, wheels, etc. Thus, with a few extraneous business lines, Tesla designs and assembles cars. Until Tesla’s battery storage business and solar equipment business become majority contributors, it will remain viewed as an auto company.
The good news is that’s okay!
Tesla CEO Elon Musk says his company will unveil its electric tractor-trailer truck this September, calling the vehicle “seriously next level” and praising the Tesla team for doing “an amazing job.” He also revealed that Tesla will show off an electric pickup truck in 18 to 24 months. Awesome innovation.
BMR Take: Street estimates call for sales growth from $7 billion last year to $11 billion this year to $33 billion in 2020. This is an exciting time for the business and the stock.
Note that Tesla was upgraded by Piper Jaffray from a "neutral" rating to an "overweight" rating last week. They now have a $368 price target on the stock, up previously from $223. We have a $325 Price Target on the stock.
Netflix (NFLX:$143, flat) had its price objective hoisted by Cowen from $165 to $170 in a research note released on Tuesday. Our Price Target is $165.
Upcoming Economic News
FRIDAY, APRIL 14 (Yes, this was on Friday – Good Friday)
Consumer Price Index
For March
Forecast: -0.1%
Actual: -0.1%
The Consumer Price Index was forecast to fall 0.1% in March following a 0.1% gain in February and 0.6% increase in January. It did. This was the first decline in the CPI since February 2016. Energy prices were a net drag on the CPI in March. The CPI for food and beverages rose 0.2% in February, the strongest since September 2013.
Retail Sales (This too was announced on Friday the 14th.)
For March
Forecast: -0.3%
Actual: -0.2%
Consensus expected retail sales to have dropped 0.3% in March following a 0.1% gain in February and 0.6% increase in January. Results were slightly better than expected. We believe weather was likely a small negative for sales. Non-store sales (online) have been contributing more to growth in retail sales recently. Already released data showed that unit vehicle sales dropped 5.5% in March and shaved 0.4% off total retail sales growth.
Tuesday, April 18th
Housing Starts
Period: March
8:30 AM
Consensus: 1,245,000
Prior: 1,288,000
Housing starts should continue to signal a healthy economy. The data reveals the number of housing units started in the United States. The U.S. Census Bureau's New Residential Construction release provides statistics on the construction of new privately-owned residential structures in the United States.
Thursday, April 20th
Leading Indicators
Period: March
10:00 AM
Consensus: 0.3%
Prior: 0.6%
This one is interesting to watch. Everybody is so focused on trying to figure out what direction the markets are heading. This is one of the key metrics that tells us. Leading indicators are economic series that tend to change direction ahead of shifts in the business cycle. There are 10 components of the U.S. Leading Composite Indicator published by The Conference Board. The index is constructed by averaging the individual components in order to smooth out a good part of the volatility of the individual series. Historically, the cyclical turning points in the leading index have occurred before those in actual economic activity.
Facebook Adds a Million Advertisers in 7 Months
There is a big move going on in the digital marketing world that many are not aware of. More than 5 million businesses are advertising on Facebook each month, Reuters reports. That is up from 4 million monthly advertisers in September 2016, and the 3 million monthly advertisers it had in March 2016. Significant upside remains as Facebook’s 5 million advertisers are less than 10% of the 65 million businesses that are active on the network.
Facebook is one of two undisputed leaders in digital advertising. Alongside Google, the company is expected to generate about half of online ad spend in 2018. Facebook generated close to $27 billion, and Google close to $80 billion, in ad revenue last year.
Small and midsize brands are flocking to advertise on Facebook. Big brands may drive the bulk of revenue in advertising markets, but there is still ample opportunity for growth with the smaller brand advertisers. The sheer volume of advertisers on Facebook reflects the company’s success in attracting these smaller firms its platform.
A few industries are generating the bulk of Facebook ad spend. E-commerce and Retail, and Entertainment and Media are the biggest industries represented in Facebook's advertiser base.
Facebook is doing a great job at building its advertising base overseas - over 75% of advertisers are outside of the US. India, Thailand, Brazil, Mexico and Argentina are the fastest-growing markets.
Mobile is big, as you know. Almost 50% of advertisers create ads on mobile devices. More than 90% of Facebook users access the network via mobile. And mobile advertising accounts for 85% of ad revenue. Creating mobile-first experiences is particularly key in emerging markets.
The biggest users of Facebook are the US at 220 million; India at 210 million; Brazil at 120 million; Indonesia at 75 million and Mexico at 65 million.
Our Take on SNAP
Snap (SNAP: $20) went public at $17 in early March and promptly opened at $24. They raised $3.4 billion making it the largest IPO since Alibaba went public in 2014, raising $20 billion. The market cap is now $23 billion and all of this for a company with no revenue in 2015, $400 million in 2016 and losses of $500 million in 2016. Ouch. More losses than revenues. Not a good business model.
Snapchat has grabbed the attention of a generation of younger smartphone users, who post and share photos and videos on the app that can disappear after a set amount of time. The app - developed by Stanford University students, two of whom are still executives at Snap had 160 million daily active users as of December 2016,
BMR Take: We are steering clear of this one. One might compare this a bit to Facebook, but Facebook had huge revenues and real earnings when it went public, and the growth since then has been phenomenal as you know. The Snap IPO has invigorated the IPO market and Wall Street is generally pleased, but for this company to get to $40 or $50 a share, we will have to see revenues of 10-20 times current levels, and big profitability, both of which may never materialize. We are steering clear.
The High Yield Report
By Michael Foster
Special to The Bull Market Report
It was a short week, but an eventful one. Already we’re seeing tons of articles about how the stock market is in crisis. Looking at volatility, there seems to be reason to think this; we went from a VIX of about 10 to nearly 16 in days. This means there is more caution in the market, and expectations of a short-term downturn. However, those expectations will disappear as they always do and the bull market will return as it always does.
We can already see pockets of optimism in the high yield world. In fact, We’d go so far as to say we’re beginning to see a sector rotation among investors that is benefitting parts of the high yield universe.
Before we get into that, though, let’s look at who is not winning. The UBS BDC ETF (BDCS: $23, down 1%) saw a soft week that was no worse than the broader market, but definitely was not good. This move is actually not that bad, considering that BDCs have had a massive run-up for months and has driven the entire sector higher. One well-known BDC analyst recently pointed out that the sector has beaten the S&P 500 since the start of 2014. This kind of cherry-picking time series doesn’t tell us much, but it does remind us that BDCs had an extremely vicious decline in 2013 and have been recovering for years since then as the market readjusts its understanding of what a rising rate environment means for these assets. It also means that the bargains in this odd corner of the business lending universe have dried up. That’s a shame, because The Bull Market Report is eagerly awaiting adding a BDC to the high yield portfolio, but this week’s 1% decline isn’t enough for us to do it. In fact, the recent decline may indicate that weaker prices might be just on the horizon, indicating a need to buy some BDCs when the price is right. Stay tuned as we keep focusing on this story.
So if BDCs aren’t benefiting from the fall in stocks this week, who is?
The answer is obvious: REITs. The SPDR Dow Jones REIT ETF (RWR: $94) was mostly flat for the last four days but is up 1% from last Friday - and comparing REITs to a week ago is really key here, because the momentum in REITs really started to kick off on Monday and has stayed strong with the many REITs in the Bull Market Report portfolio.
Let’s start with Kimco Realty (KIM: $22, up 4%), which shot up at the start of the week and has maintained its higher price level. Kimco is expected to report earnings by the end of this month, and analysts’ expectations are strong. Despite expectations of a 1% revenue decline, FFO expectations put Kimco’s dividend coverage in the 140% range. This means that Kimco is expected to far cover its dividend and have room to increase payouts. That should mean the company should be a low yielder, but this company’s 5% dividend yield indicates market expectations of risk are growing. Why the disconnect?
Simple: the decline in Retail.
Long story short, shopping malls are collapsing. The high-profile news of bankruptcies at Sears and JCPenny are making investors grow increasingly confident that the Retail sector is an apocalypse that no investor should come near. Of course these people are forgetting just how strong things are for Whole Foods, upscale outlet malls, Apple stores, and several other corners of the retail market that Kimco just happens to be focused on. In fact, Kimco’s tenants tend to be the most well-heeled and revenue-safe firms in the Retail landscape, so this collapse has little impact on them. Their occupancy rates have remained near 99% throughout. And although these issues are now high profile, they’ve been top of mind for Kimco management for a decade - and management has addressed these issues both in their strategic decisions and in their earnings calls.
In short, Kimco is not affected by the slowdown of the suburban American shopping mall.
Investors don’t know this, of course, so they’re throwing out the baby with the bathwater. That means now is a buying opportunity unlike no other. In fact, Kimco looks like one of the most attractive options for high yield investors. Of all our picks, Kimco looks like one of the most undervalued.
A similar story hit Government Properties Trust (GOV: $22, up 3%) over the past week, making it one of the top performers in a well-performing sector. Government Properties is heavily exposed to federal government tenants, and lower government spending has been seen as a real risk for the company. As a result of this fear, the company has looked to diversify by investing in office space that would be more insulated from the expected weaker demand in government properties. That has created a swiftly diversified portfolio that also has firm dividend coverage, but the market never really saw it that way. Instead, Government Properties is always seen as a risky option, which is why it often traded at an 11% yield. That’s what the stock was yielding when we first recommended it, and now it’s trading at less than an 8% yield, thanks entirely to capital gains. Sadly, that means buying more of Government Properties isn’t the greatest idea right now, but it does remain a solid hold thanks to its capital gains. The last week’s recent 3% jump is likely just the beginning; this company has a much safer income stream than its yield would indicate, meaning price gains are likely to come. We recommend staying in the stock to enjoy those gains as demand for REITs continues to rise.
Our other REITs did well this week too. Digital Realty Trust (DLR: $110, up 1%), Omega Healthcare Investors (OHI: $34, up 1%), and Care Capital Properties (CCP: $27, up 1%) all saw modest gains largely as a result of the continuation of a recent trend. CCP and OHI have been recovering recently from an oversold situation in healthcare REITs - in short, the market sold way too many of these because they thought a variety of risks (interest rates, cuts to Medicaid and Obamacare, etc.) would damage these firms permanently. These were considered long-tail risks not priced into the stocks, and yet these companies are doing fine and the risks the market has perceived are not materializing. In fact, they may never be real concerns for the companies. As a result, the stocks have no place to go but up. While we’re sitting on double-digit gains for Care Capital, we see more room to grow and thus recommend holding tight on these firms.
Finally, a word on municipal bonds. The iShares S&P National AMT-Free Municipal Bond Fund (MUB: $110, flat) didn’t move much this week although our muni bond picks did. Invesco Municipal Trust (VKQ: $13, up 1%) and the Nuveen AMT-Free Fund (NVG: $15, up 1%) outpaced the market, and we expect further gains in the municipal bond market to drive both of these funds higher. What’s going on is quite simply secular demand for munis returning to the market, largely a result of the higher uncertainty and fear that is driving stocks lower. In short, many retail investors are getting skittish and feel a need to pull out of risk and get lower risk assets.
This is driving a broad base of investors to demand more municipal bonds, driving up their value and in turn driving up the net asset values of these and other municipal bond funds. Since munis are far undervalued again due to risks that were feared but are not materializing, there is a lot more room for these funds to rise in price before they’re fairly valued. Thus muni fund holders should enjoy the gains they’re getting now but shouldn’t sell yet; if the market stays afraid these funds are destined to rise considerably. If the market gets more courageous, these funds are still destined to rise (although perhaps at a slower pace) because they have been massively undervalued due to ridiculous fears about muni bonds that aren’t materializing. Either way, the direction is clear: Keep and hold these funds and wait for their pricing to better match their real value.
Good Investing,
Todd Shaver
Editor, Founder and CEO
The Bull Market Report
Since 1998
April 16, 2017
by Todd Shaver | Apr 16, 2017 | Weekly Newsletter 7pm Sunday
The Week Ahead
What did the Easter Bunny bring this April to the markets? Much lower interest rates! The 10-year dropped 11 bp to 2.25%. Who says interest rates are going up this year? Not us, for sure. Geopolitical worries are the primary culprit. North Korea, Syria, the Middle East, all the regular actors are to blame. The 10-year Treasury now rests around 5 month lows. Everyone will look to the Fed for guidance about where the markets are going. Interestingly, Trump is now praising Yellen in a public call for Fed consistency, which contradicts his accusations on the campaign trail that she was artificially manipulating the economy in a detrimental way. Hmmm…does Trump see an opportunity to take advantage of low borrowing costs for his $1 trillion infrastructure plan? His Treasury Secretary Steven Mnuchin has publicly expressed interest in doing big time deals for 100 year bonds. And we applaud this. We’ll have to wait and see.
There is always a bull market right here at The Bull Market Report! This week we highlight the following securities: Shopify, VMware, Amazon, Annaly, Apple, and Tesla.
Highlights From The Past Week
Watchful Eye On North Korea. US officials are saying the Trump administration is focusing its North Korea strategy on tougher economic sanctions, possibly including and oil embargo, banning its airline, intercepting cargo ships, and punishing Chinese banks doing business with Pyongyang. According to one official, US President Donald Trump has approved a preliminary broad approach on North Korea and asked his national security team to craft a more detailed framework for new international sanctions and other actions. The official said the administration is considering an array of stiffer sanctions that could be applied on a "sliding scale," proportionate to North Korean actions. Some steps could be applied unilaterally, with others through the United Nations.
Business Returning to the Center Stage in the USA. Business leaders are gaining more and more influence in Trump's White House. Most recently, Jared Kushner, the president's son-in-law, is trying to orchestrate more power for National Economic Council Director Gary Cohn while dampening the influence of chief strategist Steve Bannon. It is quiet the change in scenery to see Washington acting as a friend to business led by accomplished business people. All good news for the markets.
Infrastructure Bill On The Horizon. One of Trump's top policy advisers said the timing of the President's $1 trillion infrastructure package is still up in the air as the administration considers its best path forward. D.J. Gribbin, special assistant to the president for infrastructure policy, said the timeline will hinge on whether it moves as a standalone measure or if it is attached to another legislative priority. It adds that they are still crafting the infrastructure measure. Transportation Secretary Chao said the package could be unveiled as soon as next month. We can’t wait.
BMR Companies and Commentary
Shopify (SHOP: $71, +4%, all price changes in this report are for the week)
Shopify had a solid week as talks of a takeover swirled. If true, we could see some very nice upside in the near-term. If not, that’s fine with us, as we still like the company’s fundamentals and prospects. Bottom line, Shopify still has room to run whether there is a takeover. Let’s re-visit why.
One can hardly kick back on the couch and watch CNBC or browse through your favorite financial publication these days for more than a few minutes before you come across a discussion of Amazon, as the online Retail juggernaut has skyrocketed to become an American business behemoth. And rightfully so.
For investors who want to capitalize on the undeniable secular growth trend of eCommerce, but who either missed the boat on Amazon or are wary of its nosebleed valuation, is there another road less traveled that they could embark on to get exposure to the eCommerce tidal wave? One that has impressive momentum and an ascendant stock price, but just not as frothy of a gain as Amazon? Yes there is. That’s Shopify.
Shopify not long ago announced its full-year financial results for 2016, and boasted 90% revenue growth and 99% growth in gross merchandise volume, (a term used in online retailing to indicate a total sales dollar value for merchandise sold through a particular marketplace over a certain time frame.) As an added bonus, Shopify's “Sell on Amazon” integration was made generally available to merchants in December. This mean Shopify now seamlessly connects store owners to the millions of customers searching for products to buy on Amazon, and merchants can now conveniently manage their product catalog for their eCommerce website, retail store, Amazon store, and other sales channels all in one place. This is big time! Since this integration just took place in December, we are only at the tip of the iceberg in terms of benefits and synergies from the move for Shopify.
BMR Take: The consensus calls for Shopify to more than double revenue from $600 million this year to $1.4 billion by 2020. This kind of explosive growth could cause the stock to double over the same period.
VMware (VMW: $91, -1.6%)
VMware made some waves this week announcing intentions to acquire Wavefront, the leading metrics monitoring service for cloud and modern application environments. Terms were not disclosed. The transaction is expected to close in calendar Q217. VMware does not expect this transaction to have a material impact on its 2017 operating results. But don’t write off the deal as not important just because the financial impact isn’t going to be seen in the near-term.
Digital enterprises face challenges of a new order of magnitude when monitoring modern applications -- consisting of hundreds of microservices in containers with lifespans of seconds -- spread across private and public clouds. To identify and fix operational issues in these dynamic cross-cloud environments, developers need new instrumentation for their applications, and teams require sophisticated real-time analytics on their high-scale distributed systems to adapt to problems before they impact the business.
Wavefront provides metrics to optimize clouds and modern applications by delivering operational insights using millions of data points per second in real-time. Operators and developers can interrogate real-time data streams to discover new ways to address problems, identify bottlenecks, and test algorithms and hypotheses. A cloud-hosted service, Wavefront ingests, stores, visualizes, and alerts on streaming data from clouds and modern applications enabling superior operational performance. The service can measure, correlate, and analyze data across servers, devices, applications, end-user behavior, multiple public cloud and data center attributes, and business metrics. (Now that’s a mouthful.)
This is big news for the underlying story at VMware, which is most exciting given the company’s increasing presence in the cloud marketplace. For seven-plus years, VMware has invested in solutions featuring advanced metrics and analytics to help customers simplify and automate how they manage, monitor and troubleshoot services in dynamic virtual and cloud environments. As all these investment start paying off, we see VMware as a top pick for Technology investors.
BMR Take: The company is currently generating $5-6 of EPS annually. The current valuation seems like a bargain considering all the progress with the cloud business. Our Price Target is $95 which would be a 2-year high and a more than double from the $44 low it hit in February last year. If the stock hits $95, we are moving our Price Target up into triple-digits, especially if revenues continue to soar. You know what we say about revenues and earnings: Revenues first, then earnings.
Amazon (AMZN: $884, down 1%)
A new week; Another big move brewing for Amazon. It is said that the eCommerce giant considered internally whether Whole Foods would help invigorate its nearly decade-long push into groceries. That is, Amazon kicked around the idea of buying the grocery chain!
Whole Foods has long been seen as a buyout target. Activist investor Jana Partners set off a new wave of speculation this week when it acquired a stake and urged the company to evaluate a sale. With a market valuation of $11 billion, the ailing organic-food retailer would be a powerful acquisition for Amazon -- dwarfing its 2009 purchase of online shoe retailer Zappos for about $1.2 billion. But the deal would turn Amazon into a grocery giant overnight and help it sideline Instacart, a startup that delivers grocery orders from Whole Foods stores in more than 20 states.
Jana has called for Whole Foods to overhaul its operations and brought in retail and food experts to help foster a turnaround. It also urged the company to consider a sale. A list of potential bidders includes Amazon, as well as traditional grocery chains such as Kroger and Albertsons. Whole Foods remains an attractive asset, even after a sales slump and the loss of market share to mainstream supermarkets, because the brand is strong and could be leveraged into something big.
BMR Take: Amazon and CEO Jeff Bezos are winning at everything. Why not grocery? Current Street earnings estimates call for $27 per share by 2020. With so much growth and strong earnings potential, the shares are compelling here.
Annaly Capital Management (NLY: $11.63, +5%)
Looking for yield in this market? Look here! Annaly Capital Management is a top pick in the Mortgage REIT sector.
Let’s review some of the reasons to like Annaly. Home price gains were up 6% in latest report from Case-Shiller, showing acceleration in home price increases. Tight supplies and rising prices may be deterring some people from trading up to a larger house, further aggravating supplies because fewer people are selling their homes. This is a good trend for Annaly. Annaly owns mortgages so rising home prices means the credit risk of owning the bonds is safer.
Annaly has a broad exposure across the US unlike other competitors more narrowly focused on only a particular market like New York. Yet another reason to like Annaly.
BMR Take: With a yield of 10.6% and a track record of over 20 years doing this, we continue to pound the table on Annaly. Look at this stock – up from $10.12 in mid-January in the midst of a strong interest rate rise with EVERY pundit saying that Annaly will be impacted sharply with the higher rates. Boy oh boy where they ever wrong. And boy oh boy were we ever right. Of course we’ve been saying this since we founded The Bull Market Report in 1998!
Apple (AAPL: $141, -2%)
Apple to buy Disney? Now that’s exciting! It could be more realistic than you think. Apple has the cash to pull off a $200 billion-plus takeover of Disney — creating a company worth $1 trillion with “almost limitless opportunities in content and technology.
A combined Apple-Disney would create an instant competitor to Netflix that would take advantage of the Mouse House’s content and Apple’s user base. Other benefits include: integrating Apple consumer tech as experiences in Disney’s theme parks; and landing global streaming sports rights for ESPN via Disney and Apple distribution and a strong balance sheet. Content is a major focus for Apple, target size is not an issue, and Disney offers an avenue to diversify away from hardware without diluting the strong Apple brand.
The M&A rumor mill got new grist last fall, when Apple chief Tim Cook told analysts that he was “open to acquisitions of any size.” In addition, Apple execs met with Time Warner honchos in 2015 in a discussion that raised the possibility of a merger - before AT&T moved on its $85 billion bid for Time Warner,
Per one analyst’s estimates, the merger of Apple and Disney would be highly accretive to earnings, to the tune of a 15%-20% increase in earnings per share based on the presumed 40% premium deal price and Disney’s low debt load. Nice!
BMR Take: We say it every week and we’ll say it again. Apple is really cheap compared to the current EPS outlook for this year of nearly $9. And all that cash put to good use through buying a storied franchise like Disney could be an exciting catalyst/prospect for the company.
Tesla (TSLA: $306, flat)
Tesla is a new entrant into the automobile, solar and battery storage businesses. Since Tesla’s current revenue is roughly 99% automobile related and, due to the Model 3 introduction and projected sales, this ratio will likely remain similar for quite some time. Thus, Tesla is an auto manufacturer, plain and simple. Panasonic supplies Tesla with batteries. Other companies provide Tesla with electric motors, tires, wheels, etc. Thus, with a few extraneous business lines, Tesla designs and assembles cars. Until Tesla’s battery storage business and solar equipment business become majority contributors, it will remain viewed as an auto company.
The good news is that’s okay!
Tesla CEO Elon Musk says his company will unveil its electric tractor-trailer truck this September, calling the vehicle “seriously next level” and praising the Tesla team for doing “an amazing job.” He also revealed that Tesla will show off an electric pickup truck in 18 to 24 months. Awesome innovation.
BMR Take: Street estimates call for sales growth from $7 billion last year to $11 billion this year to $33 billion in 2020. This is an exciting time for the business and the stock.
Note that Tesla was upgraded by Piper Jaffray from a "neutral" rating to an "overweight" rating last week. They now have a $368 price target on the stock, up previously from $223. We have a $325 Price Target on the stock.
Netflix (NFLX:$143, flat) had its price objective hoisted by Cowen from $165 to $170 in a research note released on Tuesday. Our Price Target is $165.
Upcoming Economic News
FRIDAY, APRIL 14 (Yes, this was on Friday – Good Friday)
Consumer Price Index
For March
Forecast: -0.1%
Actual: -0.1%
The Consumer Price Index was forecast to fall 0.1% in March following a 0.1% gain in February and 0.6% increase in January. It did. This was the first decline in the CPI since February 2016. Energy prices were a net drag on the CPI in March. The CPI for food and beverages rose 0.2% in February, the strongest since September 2013.
Retail Sales (This too was announced on Friday the 14th.)
For March
Forecast: -0.3%
Actual: -0.2%
Consensus expected retail sales to have dropped 0.3% in March following a 0.1% gain in February and 0.6% increase in January. Results were slightly better than expected. We believe weather was likely a small negative for sales. Non-store sales (online) have been contributing more to growth in retail sales recently. Already released data showed that unit vehicle sales dropped 5.5% in March and shaved 0.4% off total retail sales growth.
Tuesday, April 18th
Housing Starts
Period: March
8:30 AM
Consensus: 1,245,000
Prior: 1,288,000
Housing starts should continue to signal a healthy economy. The data reveals the number of housing units started in the United States. The U.S. Census Bureau's New Residential Construction release provides statistics on the construction of new privately-owned residential structures in the United States.
Thursday, April 20th
Leading Indicators
Period: March
10:00 AM
Consensus: 0.3%
Prior: 0.6%
This one is interesting to watch. Everybody is so focused on trying to figure out what direction the markets are heading. This is one of the key metrics that tells us. Leading indicators are economic series that tend to change direction ahead of shifts in the business cycle. There are 10 components of the U.S. Leading Composite Indicator published by The Conference Board. The index is constructed by averaging the individual components in order to smooth out a good part of the volatility of the individual series. Historically, the cyclical turning points in the leading index have occurred before those in actual economic activity.
Notes at the Margin
By Phil K. Verleger, Jr.
Former Director of the Office of Energy Policy
at the United States Department of Treasury
This item published by Platts Global Alert first caught my eye: “The Permian Basin [in Texas] is going to become the largest oil field in the world, surpassing the legendary Ghawar field of Saudi Arabia,” Bill Marko, managing director of Jefferies, said on the sidelines of the conference.
The basin holds an estimated 210 billion barrels of oil that will become economically recoverable in the future, or 325 billion barrels of oil equivalent when oil and natural gas liquids are counted, he said.
The 210 billion barrel estimate caught my attention. After all, Saudi Arabia’s reserves are put at “only” 260 billion barrels per the BP Statistical Review of World Energy. It is hard to believe that one US field has oil reserves equal to 80% of Saudi reserves.
The US Energy Information Administration recently published a short-term outlook predicting an 8% increase in US production from 8.8 million barrels per day in December 2016 to 9.5 million barrels per day in December 2017. Given recent trends, the estimate will likely need to be revised again, perhaps to 10 million barrels per day or more.
BMR Take: Phil – Knowing you the way I do, this is your way of jumping up and down and waving your arms like a madman. This is certainly big news. We have seen it coming to a certain extent but when you put it in writing the way you do, this is making us stand up and take notice. There are big changes afoot in the energy world. We would venture to say that $100 oil is not going to be seen for a long, long time to come. Prepare accordingly.
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
They honored Arnold Palmer this past weekend at the Masters Golf Tournament. He was one of the few greats who turned the game into a hugely popular spectator's sport. One of his best known quotes is: "Golf is deceptively simple and endlessly complicated."
As words of wisdom go, we can't think of a quote that could be any more applicable to the stock market. As simple as "buy low, sell high," to as complicated as the blackboard full of equations in Einstein's office. Our formula for investment success has always been "Success = preparation, recognition of value and proper seizing of opportunity." Preparation is fairly simple in the sense that it's mostly reading. But it takes a lot of reading and research on an endless basis. The complicated part is filtering out all the "noise" and learning what resources you can rely on and trust. Overall, we are believers in the KISS principle when applying our formula because we have learned over the years that the more complicated the investment process becomes, the harder it is to stay on track.
If you want to keep it as simple as possible, just think of one word - earnings. Good earnings signal a rising stock market. Weak earnings are normally a forecast of a weak or falling market.
That's where we are today. First quarter earnings season kicked off last week with several big banks reporting. First quarter earnings growth is expected to be 10%, the best since 2014. Sales growth, a laggard in the financial recovery, is expected to grow by 7.5% - its best pace since 2011! (Source: Thomson Reuters)
In addition to corporate earnings, investors will also likely monitor the economic calendar to be sure there is no unexpected deterioration in important statistical areas. And if you want to complicate it just a bit, throw in the fact that investors will probably just continue to wait for word from Washington on their pro-growth agenda. When that will actually be announced, and how long it takes to pass, are currently unknown and unknowable. So, while we may be stuck in a trading range pending the agenda results, earnings should provide a simple-to-understand reason to expect that the market will eventually work its way to a higher level.
Facebook Adds a Million Advertisers in 7 Months
There is a big move going on in the digital marketing world that many are not aware of. More than 5 million businesses are advertising on Facebook each month, Reuters reports. That is up from 4 million monthly advertisers in September 2016, and the 3 million monthly advertisers it had in March 2016. Significant upside remains as Facebook’s 5 million advertisers are less than 10% of the 65 million businesses that are active on the network.
Facebook is one of two undisputed leaders in digital advertising. Alongside Google, the company is expected to generate about half of online ad spend in 2018. Facebook generated close to $27 billion, and Google close to $80 billion, in ad revenue last year.
Small and midsize brands are flocking to advertise on Facebook. Big brands may drive the bulk of revenue in advertising markets, but there is still ample opportunity for growth with the smaller brand advertisers. The sheer volume of advertisers on Facebook reflects the company’s success in attracting these smaller firms its platform.
A few industries are generating the bulk of Facebook ad spend. E-commerce and Retail, and Entertainment and Media are the biggest industries represented in Facebook's advertiser base.
Facebook is doing a great job at building its advertising base overseas - over 75% of advertisers are outside of the US. India, Thailand, Brazil, Mexico and Argentina are the fastest-growing markets.
Mobile is big, as you know. Almost 50% of advertisers create ads on mobile devices. More than 90% of Facebook users access the network via mobile. And mobile advertising accounts for 85% of ad revenue. Creating mobile-first experiences is particularly key in emerging markets.
The biggest users of Facebook are the US at 220 million; India at 210 million; Brazil at 120 million; Indonesia at 75 million and Mexico at 65 million.
Our Take on SNAP
Snap (SNAP: $20) went public at $17 in early March and promptly opened at $24. They raised $3.4 billion making it the largest IPO since Alibaba went public in 2014, raising $20 billion. The market cap is now $23 billion and all of this for a company with no revenue in 2015, $400 million in 2016 and losses of $500 million in 2016. Ouch. More losses than revenues. Not a good business model.
Snapchat has grabbed the attention of a generation of younger smartphone users, who post and share photos and videos on the app that can disappear after a set amount of time. The app - developed by Stanford University students, two of whom are still executives at Snap had 160 million daily active users as of December 2016,
BMR Take: We are steering clear of this one. One might compare this a bit to Facebook, but Facebook had huge revenues and real earnings when it went public, and the growth since then has been phenomenal as you know. The Snap IPO has invigorated the IPO market and Wall Street is generally pleased, but for this company to get to $40 or $50 a share, we will have to see revenues of 10-20 times current levels, and big profitability, both of which may never materialize. We are steering clear.
The High Yield Report
By Michael Foster
Special to The Bull Market Report
It was a short week, but an eventful one. Already we’re seeing tons of articles about how the stock market is in crisis. Looking at volatility, there seems to be reason to think this; we went from a VIX of about 10 to nearly 16 in days. This means there is more caution in the market, and expectations of a short-term downturn. However, those expectations will disappear as they always do and the bull market will return as it always does.
We can already see pockets of optimism in the high yield world. In fact, We’d go so far as to say we’re beginning to see a sector rotation among investors that is benefitting parts of the high yield universe.
Before we get into that, though, let’s look at who is not winning. The UBS BDC ETF (BDCS: $23, down 1%) saw a soft week that was no worse than the broader market, but definitely was not good. This move is actually not that bad, considering that BDCs have had a massive run-up for months and has driven the entire sector higher. One well-known BDC analyst recently pointed out that the sector has beaten the S&P 500 since the start of 2014. This kind of cherry-picking time series doesn’t tell us much, but it does remind us that BDCs had an extremely vicious decline in 2013 and have been recovering for years since then as the market readjusts its understanding of what a rising rate environment means for these assets. It also means that the bargains in this odd corner of the business lending universe have dried up. That’s a shame, because The Bull Market Report is eagerly awaiting adding a BDC to the high yield portfolio, but this week’s 1% decline isn’t enough for us to do it. In fact, the recent decline may indicate that weaker prices might be just on the horizon, indicating a need to buy some BDCs when the price is right. Stay tuned as we keep focusing on this story.
So if BDCs aren’t benefiting from the fall in stocks this week, who is?
The answer is obvious: REITs. The SPDR Dow Jones REIT ETF (RWR: $94) was mostly flat for the last four days but is up 1% from last Friday - and comparing REITs to a week ago is really key here, because the momentum in REITs really started to kick off on Monday and has stayed strong with the many REITs in the Bull Market Report portfolio.
Let’s start with Kimco Realty (KIM: $22, up 4%), which shot up at the start of the week and has maintained its higher price level. Kimco is expected to report earnings by the end of this month, and analysts’ expectations are strong. Despite expectations of a 1% revenue decline, FFO expectations put Kimco’s dividend coverage in the 140% range. This means that Kimco is expected to far cover its dividend and have room to increase payouts. That should mean the company should be a low yielder, but this company’s 5% dividend yield indicates market expectations of risk are growing. Why the disconnect?
Simple: the decline in Retail.
Long story short, shopping malls are collapsing. The high-profile news of bankruptcies at Sears and JCPenny are making investors grow increasingly confident that the Retail sector is an apocalypse that no investor should come near. Of course these people are forgetting just how strong things are for Whole Foods, upscale outlet malls, Apple stores, and several other corners of the retail market that Kimco just happens to be focused on. In fact, Kimco’s tenants tend to be the most well-heeled and revenue-safe firms in the Retail landscape, so this collapse has little impact on them. Their occupancy rates have remained near 99% throughout. And although these issues are now high profile, they’ve been top of mind for Kimco management for a decade - and management has addressed these issues both in their strategic decisions and in their earnings calls.
In short, Kimco is not affected by the slowdown of the suburban American shopping mall.
Investors don’t know this, of course, so they’re throwing out the baby with the bathwater. That means now is a buying opportunity unlike no other. In fact, Kimco looks like one of the most attractive options for high yield investors. Of all our picks, Kimco looks like one of the most undervalued.
A similar story hit Government Properties Trust (GOV: $22, up 3%) over the past week, making it one of the top performers in a well-performing sector. Government Properties is heavily exposed to federal government tenants, and lower government spending has been seen as a real risk for the company. As a result of this fear, the company has looked to diversify by investing in office space that would be more insulated from the expected weaker demand in government properties. That has created a swiftly diversified portfolio that also has firm dividend coverage, but the market never really saw it that way. Instead, Government Properties is always seen as a risky option, which is why it often traded at an 11% yield. That’s what the stock was yielding when we first recommended it, and now it’s trading at less than an 8% yield, thanks entirely to capital gains. Sadly, that means buying more of Government Properties isn’t the greatest idea right now, but it does remain a solid hold thanks to its capital gains. The last week’s recent 3% jump is likely just the beginning; this company has a much safer income stream than its yield would indicate, meaning price gains are likely to come. We recommend staying in the stock to enjoy those gains as demand for REITs continues to rise.
Our other REITs did well this week too. Digital Realty Trust (DLR: $110, up 1%), Omega Healthcare Investors (OHI: $34, up 1%), and Care Capital Properties (CCP: $27, up 1%) all saw modest gains largely as a result of the continuation of a recent trend. CCP and OHI have been recovering recently from an oversold situation in healthcare REITs - in short, the market sold way too many of these because they thought a variety of risks (interest rates, cuts to Medicaid and Obamacare, etc.) would damage these firms permanently. These were considered long-tail risks not priced into the stocks, and yet these companies are doing fine and the risks the market has perceived are not materializing. In fact, they may never be real concerns for the companies. As a result, the stocks have no place to go but up. While we’re sitting on double-digit gains for Care Capital, we see more room to grow and thus recommend holding tight on these firms.
Finally, a word on municipal bonds. The iShares S&P National AMT-Free Municipal Bond Fund (MUB: $110, flat) didn’t move much this week although our muni bond picks did. Invesco Municipal Trust (VKQ: $13, up 1%) and the Nuveen AMT-Free Fund (NVG: $15, up 1%) outpaced the market, and we expect further gains in the municipal bond market to drive both of these funds higher. What’s going on is quite simply secular demand for munis returning to the market, largely a result of the higher uncertainty and fear that is driving stocks lower. In short, many retail investors are getting skittish and feel a need to pull out of risk and get lower risk assets.
This is driving a broad base of investors to demand more municipal bonds, driving up their value and in turn driving up the net asset values of these and other municipal bond funds. Since munis are far undervalued again due to risks that were feared but are not materializing, there is a lot more room for these funds to rise in price before they’re fairly valued. Thus muni fund holders should enjoy the gains they’re getting now but shouldn’t sell yet; if the market stays afraid these funds are destined to rise considerably. If the market gets more courageous, these funds are still destined to rise (although perhaps at a slower pace) because they have been massively undervalued due to ridiculous fears about muni bonds that aren’t materializing. Either way, the direction is clear: Keep and hold these funds and wait for their pricing to better match their real value.
Good Investing,
Todd Shaver
Editor, Founder and CEO
The Bull Market Report
Since 1998
April 2, 2017
by Todd Shaver | Apr 2, 2017 | Weekly Newsletter 7pm Sunday
The Week Ahead
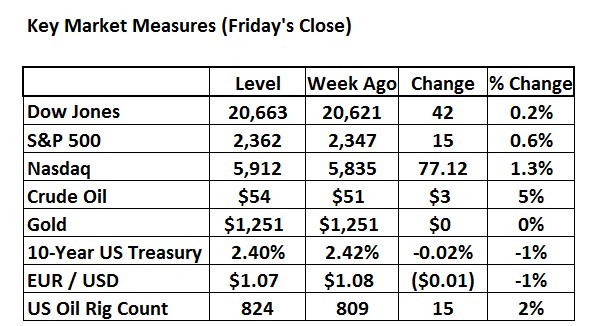
This past week was more of the same calm and collected march higher for the stock market. Optimism is at record highs for business and consumers. There are pockets of softness in the economy, like historically low labor force participation and declining commercial and industrial loan activity at banks, but with the credit market dealing with the stresses of low interest rates the stock market just keeps drawing interest from investors. We now head into April after what was a strong 1Q 2017. The consensus estimate for 2017 S&P 500 EPS is currently $129 revealing a reasonable 18x P/E multiple for today’s overall stock market.
The first quarter closed Friday with the S&P 500 notching its best quarter since 2015, up 5.5%. The Nasdaq had its best quarter since 2013, up 10%. The Volatility Index (^VIX), the fear gauge, posted its second lowest quarterly average in history at 12.37. And listen to this, the average daily percentage change for the Dow Jones during the quarter was the lowest since 1965. Things are CALM out there!
Apple (AAPL: $144, up 2%. All changes in this report are for the WEEK), a component in all three major indexes, jumped 24% during the quarter, nestled next to an all-time high set again this week. The company added $145 billion to its market cap in the quarter, besting its own record set in 2012 of adding more market cap in a quarter than any other company. It was the biggest gainer in the Dow Jones 30. Facebook, Amazon and Netflix all added 18%.
There is always a bull market right here at The Bull Market Report! This week we highlight the following securities: Visa, Amazon, Microsoft, Tesla, Splunk, and Shopify.
Highlights From The Past Week
Trump Talks Tough on U.S.-China Trade. President Trump appeared to follow through Friday on his promises to get tough on trade with China, less than a week before he is to meet with President Xi Jinping of China. In two executive orders, Mr. Trump called for tighter enforcement of tariffs imposed in anti-dumping and anti-subsidy trade cases, as well as a comprehensive review of the United States trade deficits - measures that reflect America’s economic tensions with China. Straightening out the US trade balance with China would be a major positive for US GDP growth, if Trump can accomplish the goal.
Why the Urge to Merge Could Return to Wall Street. Nothing appears to be off the table for the Trump administration as it seeks to pare back the regulations imposed on Wall Street and banks after the financial crisis. There has already been considerable talk about rolling back much of the Dodd-Frank Act of 2010, as well as the Volcker Rule that is intended to prevent Wall Street firms from engaging in proprietary trading. Already, the acting chairman of the Securities and Exchange Commission, Michael Piwowar, says his agency has stopped writing the rules and regulations mandated by Dodd-Frank - more than 20,000 pages so far - in anticipation of the confirmation of Jay Clayton as the commission’s new chairman. There is little doubt change is coming. But no one seems to be talking about whether Wall Street banks will again be able to engage in what has historically been one of their favorite pastimes: getting bigger through mergers and acquisitions. We could be in for an M&A boom across sectors not just Financials.
"Valeant Bet Was a ‘Huge Mistake," Hedge Fund Chief Ackman Says. It is rare that William Ackman, the brash activist investor, apologizes for anything. As a successful hedge fund manager, Mr. Ackman has made billions of dollars for himself and his investors with bold and counterintuitive bets. But this week he conceded that his firm’s biggest wager yet - on Valeant Pharmaceuticals International - was “a huge mistake” that has cost his hedge fund firm, Pershing Square Capital Management, “a tremendous amount.” “I deeply and profoundly apologize,” Mr. Ackman added in an annual letter to investors. It was an unusual moment of contrition for Mr. Ackman and a stark contrast to his emphatic support of Valeant in recent years. In the bigger picture, this event is just the latest of many recent developments pointing to troubling times for hedge fund managers as more and more investors turn to do-it-yourself and/or ETF investing.
BMR Companies and Commentary
Visa (V: $89, flat)
Samsung Electronics announced a strategic partnership with Visa to help bring Samsung Pay to online merchants. Starting later this year, Samsung Pay users will be able to shop online at hundreds of thousands of merchants around the world where Visa Checkout is accepted. The partnership just goes to show everybody in payments relies heavily on Visa.
Samsung Pay’s simple, secure checkout experience using fingerprint authentication gives users a more streamlined online shopping experience, eliminating the lengthy process of adding their payment card data, billing or shipping details each time they shop. Users with fingerprint authentication-enabled Samsung devices will be able to click the Visa Checkout/Samsung Pay co-branded button and touch the fingerprint sensor and the payment will proceed instantly, without needing to enter a user name and password for each purchase.
How cool! The days of filling out long forms or remembering usernames and passwords to make online purchases are continuing to wind down, as options like Visa Checkout’s open platform become accessible on hundreds of thousands of merchant sites, and companies like Samsung see the value in simplifying the process for both consumers and merchants.
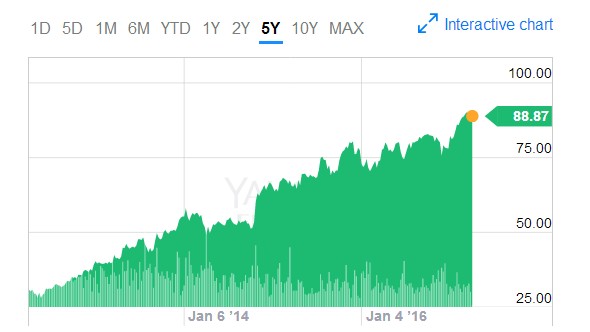
BMR Take: Visa trades at 26x the consensus estimate for this year’s fiscal EPS of $3.45. Take a look at this 5-year chart from Yahoo. Where do you think they are headed in 2017/8 and beyond?
Amazon (AMZN: $887, +5%)
Amazon is expected to enter the Australian market soon. Estimates call for this region to eventually contribute upward to $15 billion of sales to Amazon’s top line, which compares to this year’s sales tracking to be around $165 billion for the company.
What is great about Australia for Amazon? Online sales will account for just 12.5% of Australian retail sales by 2025, up from only 7% in 2016. In other words, Australia is just barely into the online sales phenomenon. We are likely heading to online sales being greater than 25% so there is just much growth runway ahead for Amazon in Australia.
What will be interesting to watch is what Amazon’s entry into Australia means for local retailers. Could it be an imminent disaster? Certainly, many local players will have to adjust to smaller store footprints, change pricing, and improve their customer engagement.
BMR Take: Amazon trades at 125x the consensus estimate for this year’s fiscal EPS of $7.09. It’s a big valuation, but growth is exceptional. EPS was a loss in 2014, $1.25 in 2015, and $4.90 in 2016 and now we see estimates for $7.10 in 2017, $12.35 in 2018, and almost $20 in 2019.
Consensus Ratings for Amazon
4 Hold Ratings, 45 Buy Ratings
Targets:
3/30/2017 Loop Capital $1,100
3/29/2017 Cantor Fitzgerald $970
3/28/2017 Stifel Nicolaus $1,025
3/17/2017 Pacific Crest $895
Apple (AAPL: $144, +2%)
In January, Forbes reported that a White House advisory panel issued a report recommending that the U.S. strengthen protection of the Semiconductor industry, especially against threats posed by Chinese policies to dominate the sector.
Then in March, Apple discussed publicly that the Japanese government is likely to ensure Toshiba is acquired. Prime Minister Shinzo Abe recently met with President Trump to discuss among other topics this one. There are now swirling talks that Apple is going to buy part of Toshiba. The deal could be executed for as much as $18 billion.
What does it all mean? Apple farms out their production for Macs, iDevices and accessories so that they can focus the bulk of their investments on software and engineering companies, setting up R&D centers around the world and building out new flagship Apple stores. We very well might be looking at the early signs of Apple soon making many of their products in the United States. Exciting.
BMR Take: Apple is again setting new all-time highs this week. The stock trades for just 15.5x this year’s consensus EPS estimate of $9.25. We are still seeing healthy EPS growth from Apple, as seen in the consensus forecast for EPS of $10.35 in 2018 and almost $11 in 2019.
Microsoft (MSFT: $66, +1%)
Last October Microsoft released the preview of Azure Analysis Services, which is built on the proven analytics engine in Microsoft SQL Server Analysis Services. With Azure Analysis Services, you can host data in the cloud. Users in your organization can then connect to your data models using tools like Excel, Power BI, and many others to create reports and perform ad-hoc data analysis. This is exciting stuff for the business community. You no longer need to run a big back office. You have Microsoft Azure!
Well, just this week, Microsoft announced that Azure Analysis Services is now available in two additional regions: Japan and the UK. This means that Azure Analysis Services is now available in the following regions: Australia, Canada, Brazil, Southeast Asia, North Europe, West Europe, the US, Japan and the UK.
BMR Take: Again a new all-time high for Microsoft this week as the cloud is taking over and Microsoft Azure is one of the top players. The stock trades at 21x this year’s EPS estimate of $3.10 though estimates call for EPS of $3.50 in 2018 and $4 in 2019.
Tesla (TSLA: $278, +6%)
Earlier this week, Tesla announced that Chinese Internet firm Tencent had acquired a 5% stake in the company for $1.8 billion. The cash infusion is good news for Tesla’s financial health, and the company’s growth prospects in the region.
In a recent filing, Tesla said that 2016 sales in China were $1.06 billion. That’s roughly a quarter of what the company made in the U.S. last year. And while the China figures represent significant growth from 2015, it’s still well below what CEO Elon Musk once imagined. In a 2014 interview with Bloomberg, Musk projected that China could eventually become the electric-car maker’s largest market. Admittedly, that day is a long way off, but we are moving closer and closer.
One big hurdle left to clear in China for Tesla is market share. According to CleanTechnica, 352,000 electric car sales were registered in China last year, which is nearly half of all plug-ins sold worldwide. Tesla, however, is the underdog. Despite being the best-selling foreign electric vehicle manufacturer to crack the Chinese market, the company only had a 3% share in 2016. Plenty of room left for improvement to drive more growth.
BMR Take: Tesla is selling cars in China like hotcakes. China LOVES Tesla and Elon Musk. We are excited to see the company make some progress in the attractive China market. The company is still losing money, basically because they are not making cars in mass quantities yet, so the extra money raised from the 5% stake sold is a welcomed boost of cash on the balance sheet. Tesla ended last quarter with over $8 billion in debt on total assets of $23 billion, a definitely elevated level.
Splunk (SPLK: $62, +2%)
An activist may have just shown up at the Splunk table. A notable language change in Splunk’s 10k filing was noticed this week. The new disclosure alerted investors to possible activist involvement in company operations.
The 2017 10-K included following phrasing absent from the previous year’s filing: "From time to time, public companies are subject to campaigns by investors seeking to increase short-term stockholder value through actions such as financial restructuring, increased debt, special dividends, stock repurchases or sales of assets or the entire company. If stockholders attempt to effect such changes or acquire control over us, responding to such actions would be costly, time-consuming and disruptive, which could adversely affect our results of operations, financial results and the value of our common stock. These factors could also make it more difficult for us to attract and retain qualified employees, executive officers and members of our board of directors."
BMR Take: The added language essentially fulfills the company’s legal obligation to warn investors of activist interference. So we would be in a for a nice catalyst here. We really like Splunk. All anybody ever talks about now is cybersecurity. The company has $1 billion in cash and just $100 million in debt. Consensus estimates call for meaningful growth from $0.40 of EPS last year to $0.60 this year and $0.90 next year.
Shopify (SHOP: $68, -1%)
There was a whirlwind of poor press circulating on the company this week. First of all, a research firm downgraded Shopify to a strong sell to reflect negative estimate revisions following an unimpressive full-year 2017 outlook and growing near-term headwinds. This is just near-term noise. We are focused on the longer term big picture, which is very attractive for Shopify. In particular, many investors are asking the question if it would make sense for Amazon to acquire Shopify. After all, the market cap is only $6 billion. This would be a rounding error on Amazon’s balance sheet.
Shopify offers an easy-to-use multi-channel commerce platform that targets small and medium-sized businesses. Its 2016 revenue was $390 million. This would be a bolt-on acquisition for the Amazon Web Services (AWS) business if the rumor is true. As far as what Amazon or another buyer might get for a bid of $7-8 billion or so, the Shopify website showed that more than 380,000 people have sold over $29 billion using Shopify. The service allows small and mid-sized businesses to fully customize their online stores and to add new sales channels, while managing unlimited products and inventory and tracking sales.
BMR Take: We are not worried that the stock took a few points of pullback this past week. This is a long-term investment that will pay off big in five years. EPS is expected to go from a slight loss this year of $0.18 to something like $1.25 by 2020. Given all the potential of Shopify’s technology and the earnings ramp set to occur, we remain excited about the future for this company.
Upcoming Economic News
It is a very quiet week ahead for economics news. Stay tuned for more economic news next week.
A Letter from a Reader
To: The Bull Market Report
From: Arthur Weed
Twilio, First Solar and Ferrellgas were all recommended at the high end of the price range. Shopify also is at the high end of the range in this market. Sometimes riding the market out for lower prices is a good option. I just prefer to watch for weakness and then go for it.
Hi Art –
OK, I understand. We all have our personal philosophies. I like to shoot for the fences with some of my assets. I missed Microsoft at 3 cents. And Apple at 11 cents . But I got AOL at $1 in the 90s and it went to $71. And I got Iomega at $17 even though the low was $3 for the year and it went to $330.
The facts:
Twilio was added after it dropped from its high of $71, and in fact, it had a fairly sharp drop from that level to $52 where we added it.
First Solar was added at $63 and a month later was $73. Revenues have fallen sharply.
The average price of Ferrellgas for the last 23 years is around $20. At $17 we thought we had a nice discount and an opportunity for it to go to $20 and then $25.
Our thoughts:
--- We believe Twilio will be a huge player in the internet communications marketplace. And we believe the stock can triple or more from $50.
--- First Solar has been a leader in this business for decades and until recently has the revenue to go with it. Unfortunately, we have to wait until 2019 for this one to play out. And that is not guaranteed, but we believe management can do it.
Note: First Solar was given a hold rating at JPMorgan Chase. They now have a $38.00 price target on the stock.
--- Ferrellgas has been a leader in the natural gas business forever. We didn’t know their big acquisition would go down as one of the worst in Wall Street history.
--- Shopify is the leader in e-Commerce by a wide margin and has big growth ahead of it. It is a potential Microsoft-like opportunity as the world is moving to mobile every single day, every week, every month, every year. We wish we had discovered it at $25 or $50. But if the stock goes to $100 and then $150-200 we won’t mind too much. We think this is quite possible over time.
Todd Shaver
A Letter from a Reader
From: Chet Malek
Sent: Thursday, March 30, 2017 9:07 AM
To: info@bullmarket.com
Subject: SNAP and Twitter
Todd – Do you have any thoughts on SNAP? Do you like Twitter better (I assume you do)?
Hi Chet –
We do not like Snap. They may surprise me and go to $50 and $100 but at the moment they are WAY behind where Facebook was when Facebook went public. And if you remember, they went public at $37, hit $43 that day, closed at $37 and then proceeded to go down to $16 in the next few months. Now the stock is at $142. BUT Facebook had big revenues and big profits at that time. Snap has good revenues but super negative earnings – They lost $515 million last year and $380 million in 2015! And they are a niche business unlike Facebook which covers it all.
We do like Twitter. One day they will figure it out. And one day someone will buy them at a 40% premium. If I were a gambling man I would buy 2-year LEAP options with a strike price of $25 or $30, cheap. [This is not for all. Consult your broker. High risk here.]
We really like Twilio – good business concept; strong revenues last quarter. No profits yet. But profits will come if the revenue is there, and it is.
Todd Shaver, Founder and Editor in Chief
Twilio Extends Relationship with Amazon
Twilio (TWLO: $29, flat) announced a further step in their relationship with Amazon. They said: Amazon Connect will use Twilio's programmable APIs to provide enhanced capabilities for customers.
(What are APIs? An Application Programming Interface is a set of subroutine definitions, protocols, and tools for building application software. In general terms, it is a set of clearly defined methods of communication between various software components. A good API makes it easier to develop a computer program by providing all the building blocks, which are then put together by the programmer. An API may be for a web-based system, operating system, database system, computer hardware or software library.)
From their public announcement Tuesday: Twilio, the leading cloud communications platform company, today announced support for Amazon Connect, the newly announced cloud-based contact center service from Amazon Web Services (AWS). Twilio's Programmable APIs will enable a range of new capabilities, including integrating phone intelligence lookup to personalize Amazon Connect contact flows, enhance customer contact details, and follow up with post-call surveys via text.
"We're pleased to further extend our work with Amazon Web Services by helping to power and further enhancing the capabilities of Amazon Connect," said Twilio CEO and co-founder Jeff Lawson. "Supporting the continued advancement of the contact center to its more agile future in software, frees developers and businesses from the legacy approach to contact centers -- an approach that simply can't keep pace with customer expectations today."
The announcement furthers the long-standing relationship between the two companies. Note that Twilio is built and globally deployed on the highly scalable AWS Cloud. Some say that Amazon can do what Twilio does and that all this hype is bad news for Twilio. We say the opposite. We think there is a symbiotic relationship here that appears to grow stronger and stronger each month.
Here’s what the company includes in their press releases:
About Twilio
Twilio's mission is to fuel the future of communications. Developers and businesses use Twilio to make communications relevant and contextual by embedding messaging, voice and video capabilities directly into their software applications. Founded in 2008, Twilio has over 650 employees, with headquarters in San Francisco and other offices in Bogotá, Dublin, Hong Kong, London, Madrid, Mountain View, Munich, Sweden, New York City, Singapore, and Tallinn [the capital of Estonia.]
Alphabet (GOOG: $830) is now covered by Barclays. They set an "overweight" rating and a target of $1,065. Our target is $900 but when that level is hit we fully expect to raise it to at least $1100. The only question is when.
The High Yield Corner
By Michael Foster, Special to The Bull Market Report
We start this week’s high yield summary with the GDP report. The headline news looks good: GDP grew at 2.1% versus 2% in the fourth quarter. Politically-minded Americans may want to dismiss this (and who isn’t politically minded these days?), arguing either things will get better or worse under Trump, depending on the flag they bear. We would suggest resisting the urge to devolve the topic to partisan bickering, because the details under this report are very important because they signal where exactly we are in the credit cycle. This, in turn, is important for one of the world’s biggest credit markets: U.S. corporate bonds.
The mainstream press focused on a couple of dynamics under the headline number, although both are relatively unimportant. A big theme, according to journalists, was consumer spending. This rose 3.5%, a sharp upwards revision from 3% previously. Since consumer consumption is the biggest driver of demand in the U.S., which in turn drives demand for the big industries abroad (manufacturing in China and Germany, exporting in Hong Kong and Singapore, commodities in Latin America, and so on), this is good news.
But it’s actually not the most important bit of good news from the report. The National Income and Product Accounts (NIPA) data, which makes up part of the GDP, gave significant and good surprises that have much more predictive power than consumer activity. According to the NIPA release, corporate profits rose after declining for three years. The “corporate profits” metric, jumped over 9% on a year-over-year basis in the 4th quarter of 2016, a sharp acceleration from the 2% increase seen in the 3rd quarter. Some economists have already said the so-called “corporate profit recession” has ended.
This decline, which was partly a result of the crash in commodity prices and partly the result of cash-strapped consumers pulling back, was a primary reason why the S&P 500 got more expensive. Because stock values are measured by dividing their current price by their earnings over a one-year period (the “price-to-earnings” ratio), stock values climbed higher and higher because profits were falling lower even as stock prices were going up. This caused the S&P 500 P/E ratio to shoot up to over 26 by the end of March, about 50% higher than its historical average. That definitely looked and smelled like an overbought market, but investors held their noses and bought stocks anyway.
We’re here to tell you that you can stop holding your nose. While the corporate profits measurement is not identical to the way S&P 500 companies report their earnings, they’re close enough. And with a 9% jump, that means the S&P 500’s one-year forward P/E ratio is less than 20, a very reasonable level.
At the same time, this increase in earnings is extremely good for corporate bonds, BDCs, and REITs for similar reasons. Let us go through these one by one to explain why.
Firstly, corporate bonds. The SPDR Barclays High Yield Bond ETF (JNK: $37) had a good week (up 1%) thanks in no small part to the GDP data, although investors are continuing to recognize what we have been saying for a long time: the default risks are over and will decline significantly because corporate profits are going up, meaning firms will have enough cash to pay their debts. What does this mean? All the risks that were priced into junk bonds back in 2015 are evaporating but the price hasn’t fully recovered on a real adjusted basis. Great news - this means we can buy junk bonds. But we can’t be indiscriminate about it. Well-managed funds like the PIMCO Dynamic Income Fund (PDI: $29) are ideally positioned to outperform. Last year PDI paid out a special dividend well over 4% of the fund’s value, bringing the annualized yield to over 13%. With the strength in junk bonds this type of return will be even easier for this fund to do this year, making it an obvious strong hold even though it is priced at a premium.
A similar rationale exists for why BDCs shot up this week: more corporate profits mean less concern companies will default on their debts. The UBS BDC ETF (BDCS: $24, up 2%) had an incredibly strong week as a result. However, we do not see this as a good enough reason to buy BDCs, especially the larger cap ones that are facing growing competition from banks that are increasing their middle market business lending practices. The market is cheering the macro conditions for BDCs, which are clearly much better than a year or two ago. However, the market is not taking into account the industry conditions for BDCs, which is more competitive and thus will force some BDCs to look for lower yielding or higher risk loans. This makes us cautious on BDCs just as we are more positive about their lower yielding competitors - namely, financial stocks.
Finally, let’s talk REITs. In the simplest sense, higher corporate profits mean more room to raise rents for industrial, commercial, and infrastructural tenants. Retail and commercial REITs make up a healthy chunk of the SPDR Dow Jones REIT ETF (RWR: $92, up 1%), but it also plays into the wheelhouse of The Bull Market Report’s favorite REITs.
Digital Realty Trust (DLR: $105, up 2.5%), Omega Healthcare Investors (OHI: $33, up 2%), Kimco Realty (KIM: $22, down 2%), Government Properties Trust (GOV: $21, up 2%), and Care Capital Properties (CCP: $27, up 6%) are all exposed to corporate and government tenants whose ability to tolerate raising rents is going up as corporate profits rise. This doesn’t mean the market is irrationally exuberant about the sector like they were in mid-2016, which again makes this a good sector to be into, especially if you’re choosing firms relying on commercial rents.
The market is stronger than the fearmongers would have you expect, and that strength is particularly acute in the high yield universe. It’s a great time to buy income.
Funny – as we write this last sentence above we think of all the folks out there who are thinking: How can I buy yield when interest rates are going to go up which means prices will go down? Well, we at The Bull Market Report don’t believe rates are going that much higher. In fact, if anything, we think rates could go lower, despite the Fed’s best wishes. Besides, as noted above and every week that we write this report, you surely notice that we are writing about strong companies with strong management who are well-aware of the world of interest rate risk. We believe in management of the companies we follow. Look at Annaly (NLY:$11.11). They paid a 30 cent divided this week (11% annualized), and the stock was flat. That’s a 2.7% gain for the week in our book. The stock is up over 10% from its low in December! And they’ve been doing this for 20 years.
Good Investing,
Todd Shaver
Founder and Editor in Chief
The Bull Market Report
Since 1998
March 26, 2017
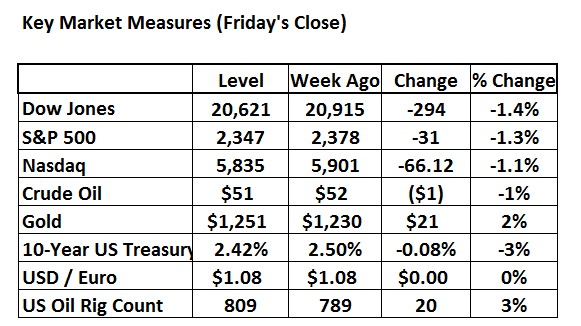
by Todd Shaver | Mar 26, 2017 | Weekly Newsletter 7pm Sunday
Highlights From the Past Week
The markets were a bit weaker last week. Friday’s close ended with uncertainty over Healthcare reform. Regardless of the outcome, some people are starting to ask tough questions. Is this Congress going to be able to deliver on the aggressive Trump agenda? Across the board, we are not just talking simply healthcare, but taxes, trade, regulations, the wall, and so on. This very first test for the new Congress will set the tone for the years ahead. And we are sure you heard what happened on Friday. No healthcare deal. Now what?
No matter what, there is always a bull market here! Week in and week out, we you can find it right here at The Bull Market Report. We currently see a bull market across many parts of the stock market. This week we highlight the following securities: Mazor Robotics, Apple, Google, Facebook, Home Depot, Celgene, and VMware.
Keystone XL Pipeline To Start Construction. The Trump administration announced on Friday that it would issue a permit for the construction of the Keystone XL pipeline, a long-disputed project that would link oil producers in Canada and North Dakota with refiners and export terminals on the Gulf Coast. The announcement by the State Department, reversed the position of the Obama administration. The pipeline has been the focus of a long fight between environmentalists and the project’s advocates, who say it would further the goals of energy independence and economic growth. The event marks a key inflection point for American’s refocusing on business.
The Markets Don't Care About Healthcare As Long As They Get Their Tax Cut. For the stock market, the drawn out effort to pass the healthcare bill may not matter after all. Regardless of whether Republicans can push the bill through (they didn’t), pro-growth and economic policies are next on the agenda. If so, markets win either way. They are not willing to hold economic growth/tax reform hostage to the Affordable Care Act reform any longer. This is a broad market-positive signal that bolsters the case for 2017 tax reform. Tax reform will start to take center stage this Spring.
Optimism Sweeps the Nation and Pulls Money Into Stocks. The surge in business and consumer sentiment reflects an assumption that is deeply rooted in the American psyche: that deregulation and tax cuts always unleash transformative pro-growth entrepreneurship. That is what we are seeing since late last year. Money has been flowing into exchange-traded funds like never before, helping to propel stocks higher. $130 billion has flowed into these index-tracking funds in the first two months of 2017. This follows a record-breaking year in 2016, when ETF managers gathered more than $390 billion in new cash. Moreover, the CBOE Volatility Index, the VIX, a popular gauge of market fear, is trading near historic lows. Even the somewhat pretentious term -- “animal spirits” -- has come back with a vengeance in the financial media.*
*People say "animal spirits" as in reference to optimism and capitalistic mentality. Additionally they mean there is business opportunity out there that is obvious, management has that and is going for it.
BMR Companies and Commentary
Mazor Robotics (MZOR: $29, +24% - all percentages in this letter are for the last week)
Mazor had a big week. Honestly, there was no specific news on the company. There doesn’t always have to be a “new” story. Sometime, people just get more comfortable with what’s happening at a business, and they start to accumulate the stock.
The latest public development at Mazor was the Hartford HealthCare news. Hartford HealthCare is Connecticut's most comprehensive healthcare network. A week or so ago Hartford announced it was joining forces with Mazor. The new partnership will bring unprecedented precision to surgeons performing spine surgery and the patients they serve. The Mazor X system was developed to enhance predictability and improve patient outcomes. It enables surgeons to be more precise, more efficient, and reduce the overall risk rate of spinal surgery.
Hartford is the first healthcare system in the state of Connecticut and throughout the Northeast to debut this technique. Physicians performed surgeries this week at the Bone & Joint Institute at Hartford Hospital and at MidState Medical Center.
BMR Take: Mazor is serving quite the niche - spine surgery - and doing a great job. We continue to like this stock pick. This week’s healthy stock performance reaffirms our conviction. The stock reached our Target Price of $29, and we are now up 70% since June when we added the stock at $16. What should you do? Obviously you could sell or you could hold from here. We are raising our Target to $36 and raising our Sell Price from $18 to $26.
Apple (AAPL: $141, +1%)
With Apple once again moving to record highs, it seems that all anyone talks about is the next big iPhone launch. Buzz surrounding the coming 10-year anniversary iPhone is growing ever louder. Sales of the iPhone 8 debut later this year will shatter expectations and help fuel estimate-beating profit growth.
Yet high hopes for the iPhone 8 aren’t the only reason to take a bigger bite out of Apple. Let’s not forget, it is one of the few technology companies that pays a cash dividend to shareholders. There is talk that the iPhone maker is poised to announce next month plans to significantly increase the capital it returns to shareholders with a $35 billion boost to its existing share buyback plan and a 15% dividend hike. (AND WAIT UNTIL TRUMP starts his tax reform plan with the cash repatriation proposal.)
Apple is a great value proposition. Warren Buffett’s Berkshire Hathaway became one of the company’s biggest shareholders late last year when it added the stock to its portfolio.
BMR Take: With the iPhone continuing to blow away its competition, and Apple’s high-margin services business continuing to race higher, there is just so much to like here.
Google (GOOG: $814, -4%)
Google has run into a bit of a rough patch here. We like it even more down here at this level.
Major advertisers are halting advertising on YouTube after Google said it was taking steps to protect its clients from inadvertently supporting hate. The controversy over ad placement, is now in its second week. We believe it to be way overblown. Chairman Eric Schmidt said Google could "get pretty close" to guaranteeing companies' ads won't be placed near hateful material.
Range Rover it was suspending its YouTube campaign in South Africa while it investigates. Nissan said it was "urgently reviewing" its campaign with Google. JP Morgan Chase and Ford suspended their YouTube ads on Thursday. AT&T, Johnson & Johnson, GlaxoSmithKline and Verizon Communications have joined the boycott in recent days, after the BBC, Volkswagen and Toyota said they had pulled ads in the UK.
BMR Take: We reiterate that we believe this is a good opportunity to buy more of one of the best technology companies on the planet. Admittedly, Google isn't yet fully addressing advertisers' concerns and needs to take stronger steps to regain the trust of brands. However, they will get it right, and when they do, it’s back to the great story we know - and a much higher stock price.
Facebook (FB: $141, flat)
According to one Wall Street analyst’s recent due diligence, they observed Facebook advertising spend volume growing 85% so far this year, from a year ago, across its client base and ahead of the company’s internal forecasts.
Why the strength? Facebook’s customer match offerings and the return on investment benefits of lower cost per click are driving demand strength. Remember, they have 1.9 billion customers. 1.9 billion customers!
Separately, Instagram continues to represent a larger share of Facebook’s overall revenue and is a key driver of growth. Higher engagement is being driven by increased video content. What does this mean? Very good things. Higher engagement means more opportunity to sell advertising. With ad pricing stable, this trend adds up to more and more revenue. You get it. More engagement doesn't just mean people are happier on the platform. More engagement triggers more advertising opportunities for the business model.
BMR Take: It always nice to hear about how the current quarter is going before the current quarter is reported. We sleep well at night thinking about the future for Facebook’s advertising revenue.
Home Depot (HD: $148, -1%)
The remodeling boom continues. Remodeling is so popular right now that homeowners are expected to spend nearly $325 billion dollars on remodeling and repairs this year, according to Harvard. Wow!
Usually you decide to remodel or renovate your home when you're ready to upgrade worn-out areas, want to add new features, or simply because you're ready for a change. But like any good investment, there are a few areas where you can make a nice return on the money you're spending.
The number one interior improvement that ups the value of a home is a kitchen remodel. This can run $20,000 to $50,000 and even much more.
When it comes to the outside of the home, buyers apparently value structural upgrades over decorative improvements to the interior. New roofs lately have been growing fast.
BMR Take: Home Depot is benefiting from this remodeling boom. Retailers like Sears and Macys may be coming under increased pressure from online retailers, but Home Depot is trucking along just fine.
VMware (VMW: $92, -1%)
VMware is in a unique situation in the escalating hybrid cloud war. The company has a strong presence in datacenters but needs large public cloud providers as partners, given the high capital requirements to offer these services in scale. In February 2016, VMware entered into a partnership with IBM to offer hybrid cloud products. In October, VMware announced an alliance with Amazon, the largest public cloud provider, to do the same.
Recent quarterly results from VMware showed rising interest by customers in these partnerships. Lately we’ve seen rising customer confidence in VMware's long-term cloud strategy and its future position in the technology industry.
IBM's large client base in IT outsourcing gives it a novel edge as the adoption of hybrid cloud grows. It also has the entire breadth of services required to move clients at their pace from a legacy architecture to the cloud. IBM is also the world's largest IT services vendor with expertise in design, consulting and re-engineering of legacy IT to cloud. IBM is a leading vendor of both software and IT services, unlike other major cloud providers that historically focused more on software. Its early move into cognitive products through Watson should also help it drive additional growth in hybrid cloud.
BMR Take: We continue to like this core story around the “hybrid” cloud for VMware. Amazon and IBM - what great companies to call your partners! We expect more good news about this business in the near-future.
Celgene (CELG: $123, -2%)
The Affordable Care Act saga in Washington has created a buying opportunity for Celgene. We describe the situation below. The bottom line is that Celgene is lumped into the conversation with other bad actors. The reality is Celgene will do just fine if drug prices come down. It’s the real bad actors like Mylan that will be hurt.
The ACA saga in Washington has created a buying opportunity for Celgene. We describe the situation below. The perception is that Celgene is lumped into the conversation with other bad actors. The reality is that Celgene will do just fine if drug prices come down. It’s the bad actors like Mylan that will be hurt.
When you rush any kind of massive project, you raise the risk that people get hurt. That's certainly the case with healthcare reform. As President Donald Trump and congressional Republicans have scrambled (and lost) to save their troubled attempt to repeal and replace the Affordable Care Act, they addressed Trump’s repeated rhetoric that drug pricing needs to be rationalized. This is such a broad statement; there is a lot of uncertainty about how lower drug prices will impact each player in the healthcare space. So many medicines carry massive price tags because most patients typically pay just a small fraction of those list prices, while insurers handle the rest. We are all in wait-and-see mode as to how the new insurance schemes will influence drug pricing.
BMR Take: Lower drug pricing does not ruin Celgene. This is actually an opportunity for you, with this lower stock price. Celgene is widely cited by Street analysts as a top pick in the space as the franchise is best in class. The company has a stacked pipeline of new drugs creating strong financial prospects.
Consensus Ratings for Celgene
Ratings Breakdown: 1 Sell Rating, 4 Hold Ratings, 23 Buy Ratings
Price Targets:
3/8/2017 Cowen and Company $150
3/6/2017 Oppenheimer Holdings $148
3/2/2017 Cann $148
2/28/2017 Jefferies Group $155
2/25/2017 Canaccord Genuity $156
2/18/2017 Cantor Fitzgerald $159
2/18/2017 Credit Suisse Group $148
2/17/2017 Robert W. Baird $162
Must be something the Street likes about Celgene!
Upcoming Economic News
TUESDAY, MARCH 28
S&P CoreLogic Case-Shiller Home Price Index – January
Time: 9:00 am
Forecast: 5.7% yearly change of 20-city index
Gains in home sales over the long-term amid tight supply can keep the Case-Shiller home price index rising in excess of 5% annually in January. Nationally home prices now lag their pre-crisis peak by 7%, as certain local markets are considered overvalued. Yet broadly, consistent price gains have greatly reduced the share of homeowners underwater on their mortgages, which allows the housing market to function more smoothly.
Conference Board Consumer Confidence – March
Time: 10:00 am
Forecast: 113.0
Consumer confidence as measured by the March Conference Board survey is forecast to remain strong, even if the index slips a bit from February’s 15-year high. In February, the share of survey participants anticipating rising incomes exceeded the share expecting their incomes to decline by 10% for only the second time in the past decade. That gap points to persistent wage gains and an upward bias to price growth.
WEDNESDAY, MARCH 29
Pending Home Sales Index – February
Time: 10:00 am
Forecast: 2.4%
The Pending Home Sales Index is expected to rise in February after sliding to the 12-month low in January. Though sales and home lending are on a long-term uptrend, the pace of gains has not been consistent. Those uneven results imply that further gains in mortgage rates can weigh negatively on housing activity after borrowing costs rose in recent weeks to the highest levels since 2014.
THURSDAY, MARCH 30
GDP – Fourth Quarter (Third Estimate)
Time: 8:30 am
Forecast: 2.0%
Though overall GDP growth slipped in the fourth quarter, output still found support from a hearty pace of consumer spending. That may not be the case in the current quarter after January’s 0.3% decline in real consumer spending equaled the largest shortfall since 2009. Though GDP growth may once again disappoint in the early months of the year, healthy gains in jobs and improved industrial production trends signal stronger underlying economic progress.
FRIDAY, MARCH 31
Personal Income & Spending – February
Time: 8:30 am
Forecast: 0.4% income, 0.2% spending
Personal income is projected to rise 0.4% for the second straight month in February, aided by somewhat faster wage growth. Annual income growth touched 4% in January for the first time in over a year, partly signaling increased labor market tightness. Further gains must be registered in order for real spending to keep ahead of the recent uptick in inflation.
University of Michigan Consumer Sentiment – March
Final Time: 10:00am
Forecast: 98.0
Sentiment in the final March reading of the Michigan survey is likely to continue to display the strong post-election bounce. The reading on current economic conditions reached the highest level in 17 years in the preliminary March survey. That points to ample consumer resources that can keep the aged economic expansion chugging along.
Apple Hits New High This Week at $142.80
Pacific Crest raised their bullish price target for Apple to $175 based on the prospect of a cash repatriation holiday. This is a common song on Wall Street these days, and as you know we have been pounding the table about this for some time now. There is $2.5 trillion of cash overseas. Bring a little more than half of that back and you have $1.5 trillion that would be set to go to work creating jobs and benefitting stockholders. We might see a huge increase in the dividend. Maybe even a large, special distribution of $10-20 a share.
Goldman Sachs reiterated their Buy rating and $150 price target on Apple, saying the iPhone 8 supply chain data points to higher-than-usual seasonality in February based on average sales from six of the company’s suppliers.
And note that Apple was upgraded to Buy by one of the biggest bears on the stock on Wall Street. Bernstein now has a price target of $175. Now THAT’S saying something.
You heard it here first. What price would Apple have to hit to be the first* trillion dollar company? $190. Sounds like it's pretty far away, doesn’t it? But when Apple hits $160, it will be a hop skip and a jump away. Food for thought...
*Alas, PetroChina (PTR) was the first trillion dollar company, hitting that number in 2007. It’s worth just $200 billion now. (So we’re not counting it!) Apple will be the first. Or maybe Google or Amazon or Tesla. The race is on!
Number of monthly active Facebook users worldwide as 4Q16
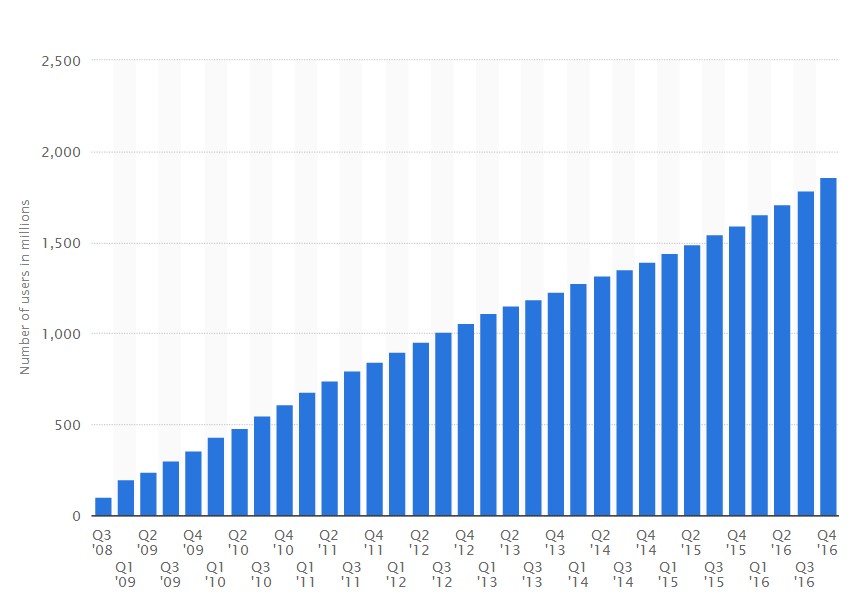
This statistic shows a timeline with the worldwide number of monthly active Facebook users from 2008 to 2016 in millions. As of the fourth quarter of 2016, Facebook had 1.86 billion monthly active users. Extrapolating, we'd say they are well over 1.9 billion. 2 billion look out!
Consensus Ratings for Facebook
Ratings Breakdown: 1 Sell Rating, 4 Hold Ratings, 39 Buy Ratings, 4 Strong Buy Ratings
Price Targets:
3/21/2017 BTIG Research $175
3/13/2017 Cantor Fitzgerald $175
3/6/2017 Royal Bank of Canada $170
3/3/2017 Nomura $155
3/3/2017 Citigroup $165
High Yield Corner
By Michael Foster
This was a particularly good week for many Bull Market Report picks even though the high yield markets were rather dull.
The SPDR Barclays High Yield Bond ETF (JNK: $37) ended the week flat despite some interesting excitement in the Treasury markets. The 10-year yield retreated throughout the week to 2.42%, a drop of over 8 bp from the start of the week. This is significant because that yield is a combination of economic growth and inflation expectations, and the yield has been driven higher by the Federal Reserve’s rate hike and forward guidance of more rate hikes throughout the year. With the 3-month Treasury yield up to 0.75% and market expectations of an end-of-year yield of 1.5%, the spread between short-term and long-term bonds has shrunk considerably in the last few months. This means the market does not believe rate hikes from the Fed will come hard and fast, but will happen very gradually over a longer time period.
Why does this matter? Rate hikes intrinsically sound like monetary tightening, which is particularly bad for bonds and other debt instruments. For high yield bonds, it’s especially bad because it suggests that yields need to go up to compensate for the risk as yields on Treasuries get bigger. Since yields and price are inverted, it also means high yield bonds currently issued will go down in price. That, in turn, would hit funds like the SPDR High Yield fund
However, the Federal Reserve is not tightening relative to expectations. That “relative” clause is key here. The Fed is making borrowing more expensive, but everyone in the market expects the Fed to do this. The real question is how fast and how often they do it. The market now thinks that the Fed will raise rates at a slower pace than the market used to think, which means the Fed is tightening less than expectations. This, paradoxically, is good for high yield bonds because it indicates the downside of a tight policy is already priced in.
Extraordinarily, that “priced in” moment came in 2015. We’re getting near the 2-year anniversary to that cycle of discounting corporate bonds for future rate hike action. And keep in mind that is after junk bonds were discounted for future rate hike action back in 2013. If you look at the price return for the SPDR fund over the last five years, the fund is down over 7%. In other words, junk bonds have been discounting the Fed’s future rate hikes for several years, and every time the rate hike schedule is delayed, it bolsters junk bonds’ value even further.
That doesn’t mean junk bonds have fully recovered, though. The market is still very cautious because of a lot of misunderstanding about what the rate hike really means for corporate bonds, causing money to be left on the sidelines. That makes junk still a good opportunity, although you can’t expect the 10% price returns on junk bonds that were so easy to get a year ago.
So with that in mind, there remain valuable funds with high yield and corporate bonds in them. BMR picks AGIC Equity and Convertible Income Fund (NIE: $19.11, down -1%) and the PIMCO Dynamic Income Fund (PDI: $29, flat) remain solid picks that are earning their dividends and have capital gains potential. Impressively, Pimco has already seen a 5% return in 2017 although we haven’t even gotten to spring yet! That doesn’t mean the performance will annualize at that rate by the end of the year, but it may. What it does mean is that the fund remains a market outperformer that can continue to pay out its current dividend in a market where many funds are cutting distributions.
The AGIC fund has not been as solid of a performer largely because of its equity holdings. The fund had a bad week, but has a 4% year-to-date performance when looking at its NAV. That lags the S&P 500, which is up 4.6% over the same period. That underperformance does not bother us for two reasons. Firstly, the fund has tremendous liquidity thanks to its high 8% yield. It also has maintained its 10%+ discount to NAV throughout the year because the market simply underappreciates this fund. Thanks to that discount, the fund’s management needs to get just a 7.1% return annualized to maintain payouts and not see NAV go down. Thanks to the market’s growth and high yields on convertible bonds, this not difficult for AGIC Equity to earn in the current market. While there are some other risk factors at hand, they aren’t significant enough at the moment for investors to be concerned with.
Elsewhere in the high yield world, things were quiet this week. The SPDR Dow Jones REIT ETF (RWR: $92, flat) saw little movement, but BMR picks fared far better. Digital Realty Trust (DLR: $104) and Kimco Realty (KIM: $23) ended the week flat alongside the broader market, but Omega Healthcare Investors (OHI: $32, up 3%), Government Properties Trust (GOV: $21, up 1%), and Care Capital Properties (CCP: $25, up 2%) fared significantly better than the index. We’re nowhere near overbought territory for these REITs, but we may get there if further price appreciation comes to these stocks.
One asset class was particularly hard hit this week, and it’s one that readers know we have been cautious about for several weeks now: BDCs. The UBS BDC ETF (BDCS: $23, down -1%) was one of the worst performers in the high yield world, but former BMR favorite Main Street Capital (MAIN: $37) did much worse, losing over 1% for the week. Now Main Street’s price is up only 1% for 2017, making it a market laggard. Nothing fundamentally has changed with Main Street, but the market has finally warmed up to this stock so much that it’s gotten far overpriced and thus is now a bad value. It trades at a tremendous premium to its NAV, as we’ve mentioned several times since The Bull Market Report pulled it from its High Yield portfolio. It remains a very high quality BDC with market dominance, but at a 6% yield excluding special dividends, it just doesn’t provide the income worth the risk of paying for such a high premium. We are happy for management to have earned a deserved price premium for the value they add for investors, but we are not willing to pay that premium. Main Street is fairly to slightly overvalued, which is what you would expect for a good company in a healthy stock market. We will wait to buy Main Street again if and when the market gets unhealthy.
Finally, a word on municipal bonds. In 2016 we were pounding the table aggressively on almost all high yield assets, but were tentative about municipal bonds. The asset class was overbought throughout 2016 and undersold before that run up, especially when compared to the more ridiculous panic selling elsewhere in REITs, junk bonds, and especially corporate bonds. We didn’t see muni bonds fairly priced until late 2016, and then they became near bargains a short time later. That is when we started to dip our toes in the asset class and see tremendous value in the market.
Slowly, the market is beginning to come our way. The iShares S&P National AMT-Free Municipal Bond Fund (MUB: $109, up 1%) had a very strong week, and that’s helped the fund return again to positive territory for 2017. BMR pick Nuveen AMT-Free Fund (NVG: $14.53, up 1%) had a similarly strong week and has a similar year-to-date performance. Yet its dividend yield is over twice the iShares fund and its capital gains potential is much greater as well. There is no reason to shy away from municipal bonds now, and we can only hope that the trend we saw last week will continue over the coming weeks. Muni bonds deserve more market demand - it’s only a question of when that market demand materializes.
Good Investing,
Todd Shaver
CEO, Editor and Founder
The Bull Market Report
Since 1998
