July 30, 2017

by Todd Shaver | Jul 30, 2017 | Weekly Newsletter 7pm Sunday
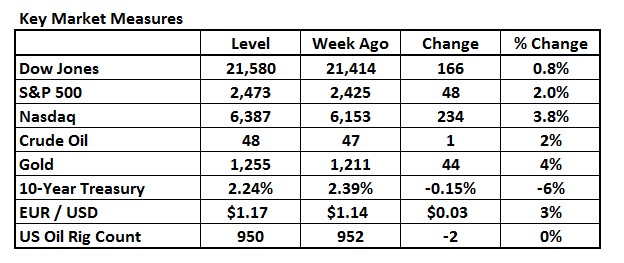
The Weekly Summary
North Korea test-fired its second intercontinental ballistic missile within a month on Friday, a provocation that heightens pressure on the U.S. and China to find ways to rein in Kim Jong Un’s nuclear ambitions. The U.S. said its top general called his South Korean counterpart to discuss “military response options.” The missile traveled about 620 miles. Trump called the launch a reckless and dangerous action and said "the United States will take all necessary steps to ensure the security of the American homeland and protect our allies in the region.” Why is this so important? It is more than the obvious geopolitical risks. The CBOE Volatility Index (^VIX) touched multi-decade lows earlier this past week at 8.84, but closing Friday at 10.29. It is really hard to see the markets remaining as calm as they are right now. This North Korea news is a fresh reminder that it is highly unlikely the markets remain this placid for long.
However, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks: Amazon, First Solar, Shopify, Square, Facebook, and AstraZeneca.
Highlights From The Past Week
Tech Slide in Week of Upbeat Earnings Underscores Growing Unease. Better earnings equals higher share prices, or so goes the customary thinking. For Technology stocks during this reporting season, it’s the exact opposite. Companies from Google to Microsoft announced quarterly results that beat analyst estimates by a combined 8%, more than any other industry group in the S&P 500 Index. Be reminded, that too much love can prove perilous when momentum reverses. In June, after investors had flocked to Tech stocks anticipating faster earnings growth in a move that pushed the Nasdaq 100 Index to rise twice as fast as the S&P 500, they rushed for the exit all at once, sparking the worst selloff since 2008 relative to the rest of the market.
Focus Turns To The Fed's Balance Sheet. If the Federal Reserve delivers any surprises in the near-future, it will probably come from news on when it plans to start shrinking its balance sheet. Economists don’t foresee an interest-rate hike anytime soon. Yet policy makers might update their language on inflation, because weakness in price data has persisted since they last met, but those changes should be minor.
A larger source of uncertainty stems from the timing of when the Fed will start to shrink its $4.5 trillion holdings of mainly Treasuries and mortgage-related debt. Everyone wants to know how the Fed will cut the bloat after building assets to record levels to help shield the U.S. economy during the financial crisis. Officials expect to begin the process this year and Chair Janet Yellen has said it could get under way “relatively soon.” Her lack of specific guidance has us looking toward the Fed’s meeting in September for an announcement. It sure seems like they would like to get the process started in the Fall. This will undoubtedly be a big shift for markets. But, it is expected and seems to be priced into the markets now. The 10-year Treasury is still very, very low from a historical standpoint at 2.29%. We don’t expect that to change much in the near future.
Howard Marks Sounds Alarm on Tech Stocks. We love to follow what the billionaires say. After all, they have made a lot of money and that is what we are trying to do. Just this week, billionaire Howard Marks, who’s warned of excessive risk in the markets for the past five years, is now sounding the alarm as hazards converge from red-hot Tech stocks, and investor confidence in SoftBank’s $100 billion fund raise. In a 22-page memo -- longer than most of his missives to clients -- the Oaktree Capital Group co-chairman said he sees several phenomena that by themselves seem reasonable but together reveal markets to be heated and risky. “Since we never know when risky behavior will result in a market correction, I’m going to issue a warning today rather than wait until one is upon us,” Marks said. “This warning is likely to feel premature, and perhaps it is, but I think it’s better to turn cautious too soon rather than wait until it’s too late.”
We’re not saying we are in this camp. To the contrary, we remain bullish on America and the stocks in our portfolio. But we want to let you know that there is another side to the bullishness and Marks above is just one of them. But this is nothing new. There are always two sides to every market and guess what? No one knows what the market is going to do in the future. So as we have said many times, if you find yourself with too much worry at night, move out of those stocks that make you nervous and move into the High Yield stocks in our High Yield and REIT portfolios. They are sleep-well stocks that are paying nice 5-10% dividends.
BMR Companies & Commentary
Amazon (AMZN: $1,020, down 1/2% - all changes are for the week)
Amazon traded lower after the company forecast a potential quarterly loss for the first time in two years, a reminder to investors that its reshaping of the worlds of Retailing and Cloud-computing industries doesn’t come without a cost. The company indicated the investment cycle is likely to continue, as it gave third quarter operating income guidance in the range of a $400 million loss to a $300 million profit. Amazon CFO Brian Olsavsky said the third quarter typically sees lower operating income because it has to prepare for the holiday peak season. Revenue guidance came in between $39 billion and $42 billion.
Amazon Web Services remains the company's main growth driver, growing 42% year-over-year, and generating $915 million in operating income. That's more than double the Amazon’s North American business's $435 million in operating income. Its international business continues to lose money with an operating loss of $725 million.
To accommodate exploding growth, the online giant has gone on a hiring spree, pledging to hire more than 100,000 people earlier this year.
The company blew away revenues but came up short on earnings. Revenues were $38 billion in the quarter, up from $30 billion a year ago. Earnings were 40 cents a share, vs. $1.78 last year.
Cash levels remain strong with over $21 billion on the balance sheet vs. just $8 billion in debt.
The company on Thursday said it is boosting spending on new warehouses to meet growing eCommerce demand, data centers for its Amazon Web Services division, video programming to keep customers engaged, and gadgets like the Echo line of voice-activated speakers to stay on the cutting edge of the emerging smart-home market. This comes after shares hit all-time highs Thursday, briefly making Jeff Bezos the richest man in the world. But Gates has staying power after Microsoft reported solid earnings, while Amazon missed estimates and the stock fell a bit.
While analysts remain optimistic about the future of Amazon and their growing revenue, the 2nd quarter earnings report from the company underscored the high cost of its business model. We at The Bull Market Report believe we are in the early stages of the shift of compute to the cloud and the transition of traditional retail online, and that the market is underestimating the long-term financial impact of both to Amazon. That said, Amazon continues to generate high returns on cash invested despite the growing scale of its investments, with significant value in early stage efforts in AI, voice, and robotics. The top line growth acceleration like that we saw in the second quarter is likely to continue in the long term
BMR Take: While EPS estimates are getting knocked around, don’t take your eye off the long term picture. Some analyst models are calling for EPS potential of near $25 in 2020. This could send the stock a lot higher. At the same time, there are many who believe Amazon is a bubble and that Bezos will never allow the company to report sizeable earnings. This is a tough one for us. We believe that Amazon will eventually turn the spigot on and report strong earnings. We aren’t sure when this will happen but we believe it will happen. But others say that he never will.
Oh my – the bulls and the bears fight it out in the end. We are sticking with our bullish stance as we believe revenues ultimately win out (as earnings are destined to follow.)
First Solar (FSLR: $49, up 8%)
First Solar raised this year’s profit forecast on improving terms for power plant sales and unexpectedly strong demand for technology that’s being phased out. This year’s EPS is now seen as up to $2.20, up from earlier guidance of 40 cents. Wow. Gross margins and sales will also come in higher after they shipped a record of 900 megawatts of its Series 4 panel in the second quarter. Big.
First Solar is benefiting from higher module prices in the U.S. as developers and distributors stock up ahead of a potential tariff on U.S. imports. First Solar’s thin-film technology has also seen gains. The sale of its 180-megawatt Switch Station solar farm also came in higher than expected, and management was optimistic for higher margins on two more plant sales later this year. They’re doing a better job of extracting cash out of their sales of plants and modules.
First Solar has begun installing equipment for its larger, more efficient Series 6 panel at its factory in Ohio and plans to ramp up production next year. Analysts estimate that panels can be produced for about 25 cents per watt, less than the 72 cents per watt floor price that may be imposed on imported panels by President Trump under a trade dispute later this year. Chief Executive Officer Mark Widmar said that he may extend production of the Series 4 module even as initial output of series 6 starts this year in Ohio and next year in Malaysia and Vietnam. Stable pricing globally and U.S. tariffs on competing suppliers will factor in that decision. The outlook sure looks good.
BMR Take: First Solar is a top player in a sweet market niche. Better energy efficiency is so important to our future. First Solar’s earnings are re-setting and returning to growth. The stock has almost doubled in the last three months.
Shopify (SHOP: $93, up 4%)
Shopify, the rising e-commerce platform dominated by small business owners, is teaming up with eBay to allow its merchants to sell directly through the online marketplace. The move adds another outlet for Shopify’s roughly 400,000 users. When Shopify signed a similar deal with Amazon in January, its stock surged as investors predicted a boost to revenue.
The company’s strategy has been to integrate with as many online channels as possible, letting its customers diversify away from their personal websites and sell on Twitter, Pinterest, Facebook, BuzzFeed and Amazon. Shopify also provides payment tools, shipping and small loans to help its users build their businesses.
Shopify is a growing player in the battle for turf in the rapidly growing world of online shopping. Instead of building a centralized marketplace such as Amazon and eBay, it provides tools for independent merchants, both large and small to sell online in various ways. It also provides point-of-sale software and hardware for physical stores, similar to Square.
Customers have been asking for Shopify to integrate with eBay for a while. We think a lot of merchants will gravitate toward this new announcement.
BMR Take: Like Amazon? Then you’ll like Shopify. It’s the same big picture story of massive eCommerce growth with a twist of being less widely known. With EPS on track to reach profitability next year, there is a big turn in the stock happening and now is an opportune time to be involved.
Square (SQ: $26, down 2%)
After building a unique payment solution that caters to micro and small merchants, Square is now in the process of rolling out more services (financing, payroll, capital) that accommodates a wider array of merchants and has been successfully moving up-market with a strengthening platform-based approach.
The company has entered a stretch where it’s investing to consolidate its services onto a singular platform with access to services, which should help improve already solid retention, and increase engagement with the company’s services driving robust volume growth. In addition, the company has successfully expanded into four countries outside the US (latest launch in the U.K.)
The company is complementing robust growth with a planned annual margin expansion from operational efficiencies utilizing machine learning and other artificial intelligence techniques.
BMR Take: Given the aforementioned factors, we believe Square is well-positioned to continue solid top-line momentum in 2017, continuing to capture the +$60 billion US market opportunity and beyond (6x opportunity globally) while driving leverage in the business. The company reports EPS on August 2nd. We see compelling upside ahead over the longer term.
Facebook (FB: $172, up 5%) Reported Earnings Last Week
For its second quarter, revenues spiked 45% year-over-year to $9.3 billion, and earnings per share came to $1.32, up 69%. Wall Street’s pros were looking for $1.13 per share in profits. They killed. The stock was up big last week in response, on top of a 44% year-to-date gain.
A few other highlights from the report:
• Daily active users (DAUs) reached 1.32 billion, while monthly active users (MAUs) hit 2.01 billion. Both were up a huge 17%.
• Mobile advertising revenues represented 87% of the total, compared to 84% in the same period a year ago. (We are amazed. 87% of revenues is astounding. We had to double-check what we read.) Remember when they went public and the world thought they had no mobile strategy? What a switch.
• During the past year, Facebook increased global headcount by 43% to 20,700.
• Facebook has $35 billion in the bank and no debt.
Here are the numbers for advertising:
Mobile ad revenue accounted for 87% of the company's total advertising revenue of $9.15 billion in the latest quarter, up from 84% a year earlier. Net income rose to $3.9 billion, or $1.32 per share, from $2.3 billion, or 78 cents per share, a year earlier.
Facebook's CFO once again warned the Street the company's revenue growth is being slowed down by a lower rate of advertisements on its properties, but the Street hardly cared, pushing price targets as high as $210, and the stock zoomed to half a trillion dollars in market capitalization, joining the exclusive club of Google, Microsoft and Apple.
The company noted that there are opportunities for incremental ad load on Instagram, increased engagement from Instagram stories, and potential for new monetization levers through Messenger and WhatsApp.
BMR Take: Facebook is an ad machine like the world has never seen. There is still so much potential ahead. With EPS pushing towards $10 over the next few years, we love this stock.
AstraZeneca (AZN: $30, down 11%)
AstraZeneca plunged after the U.K. drugmaker suffered a blow to its next-generation cancer therapy, with a new drug combination failing to do better than chemotherapy in checking the growth of lung tumors. This has posed a major setback to Chief Executive Officer Pascal Soriot’s ambitions. Imfinzi, used in combination with tremelimumab, didn’t meet a primary endpoint for progression-free survival in the study dubbed Mystic. The drugs were poised to generate more than $7 billion in sales by 2022, according to analysts’ estimates.
The failure calls into question Soriot’s ability to deliver on his growth strategy, put in place to keep the company independent when he rebuffed Pfizer Inc.’s $117 billion-takeover bid in 2014, and may make the firm vulnerable again. Imfinzi, which was poised to become Astra’s biggest medicine by sales, is the cornerstone of its cancer portfolio and key for meeting Soriot’s goal, set in 2014, of boosting revenue to $45 billion by 2023. Sales were $23 billion for 2016, so he has some serious work to do.
“Despite the outcome of the initial readout, we must be patient as the Mystic trial continues as planned to evaluate overall survival,” Soriot said in the statement. The study will continue to assess whether imfinzi or the combination of drugs can help improve life expectancy, with the results expected in the first half of next year.
The Mystic study was a crucial test for Astra’s two immuno- therapies -- a new class of drugs that activate the body’s defense system to attack tumors -- in a race with rivals including Merck, Roche Holding and Bristol-Myers Squibb to dominate the market for cancer treatments.
BMR Take: This is tough news to hear. We will keep a close eye on the situation and consider what to do about it after more careful analysis in the weeks ahead. We don’t like to panic. The stock dropped below our Sell Price of $32, so if you wish to get out you can do so on Monday. The stock came back over $1 on Friday and we are going to stick with it for a little bit more, watching the price closely.
Upcoming Economic News
Pending Home Sales Index
Monday, July 31st, 10:00 AM
Period: June
Consensus: 109.6
Prior: 108.5
Personal Consumption Expenditure
Tuesday, August 1st, 8:30 AM
Period: June
Consensus: 0.20%
Prior: 0.10%
Note: Monthly Personal Income and Outlays data are published by the U.S. Bureau of Economic Analysis. Personal consumption expenditures include consumer spending for all goods and services. These data are published on a quarterly basis in the GDP data release.
Total Light Vehicle Sales
Wednesday, August 2nd, 8:00 AM
Period: July
Consensus: 16.7 million
Prior: 16.4 million
Source: U.S. Bureau of Economic Analysis.
Average Workweek
Friday, August 4th, 8:30 AM
Period: July
Consensus: 34.5
Prior: 34.5
Note: Establishment survey data measuring the average workweek for production or nonsupervisory workers on private nonfarm payrolls.
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
It looks like it's a pretty done deal for the S&P 500 to hit 2500 based on a very good earnings trend reported so far. One exception was Google - it went down even though its gross revenues and underlying ad metrics were good. It also beat its earnings per share estimates, but the investment community figured out this beat was driven by taxes and that for the first time in 5 years, traffic acquisition spending outpaced revenue growth. This reminds us of the typical slaughter of a stock because its earnings missed by a penny.
When you think about investing to grow your money into the future, an investor has to be more of a longer-term investor than one single quarter. Big trends don't come and go on a single quarter's earnings. And, speaking of big trends, what giant long-term trends come to mind first? The "no-brainer" is of course Technology – everything from mobile, the cloud, augmented reality, artificial intelligence, alternative energy and autonomous cars. But there is a sector that is bigger than Technology and has beaten it by 300% since 1999.
Healthcare. In a way, it is comprised of a great deal of "technology" on its own – think biotechnology and all of the remarkable medical devices being created. Healthcare also offers just as much innovation and diversification as technology – there are 800 companies and 12 industries to choose from. And today, there is not one but four "mega-trends" fueling the long-term trend behind Healthcare.
The first and most important is of course the once-in-a-lifetime baby boomer demographic tsunami which will drive it for another decade. Secondly, there is a new age of genetics and medical technology which has ushered in unprecedented advances in scientific and medical research. Companies, investors and charities are pouring billions of dollars yearly into R&D, and this is a trend with no end in sight as they seek to find cures for every disease on earth. Thirdly, earnings have been a classic example of what a mega-trend looks like. In 2016, the Healthcare sector was responsible for nearly 20% of the earnings in the S&P 500, bigger than the Financial, Energy, and Telecom sectors combined.
Yes, we are aware there are concerns that the government will try and hold down drug prices. These are, we believe, going to be overcome by the simple concept that everyone can agree they do not want companies to stop trying to find a cure because they no longer can make a profit.
The last trend is that of mergers and acquisitions. The big Pharma companies need to keep their pipelines full and avoid the revenue drops created when patents expire. During this bull market, over $500 billion in deals have been done, mostly by big drug companies buying emerging Giotechs. While the pace of M&A may slow down, we believe it will always be a positive force driving values in the Healthcare sector - especially if any tax reform policy unleashes a tidal wave of overseas corporate cash onto US shores.
Thus, the moral of this story is: If you own a "mega-trend" such as Healthcare, don't let a bad quarter in the stock market make you react like the investor who bails out of a stock because it missed that quarter's expected numbers. Markets go up and down, but Healthcare is a mega- trend we believe won't stop this decade and probably not in the next one either. We think we are right in the middle of this one.
Tesla Update
Tesla (TSLA: $335, up 2%) announced the first deliveries of Its Model 3 on Friday. There was big fanfare and discussion of the 500,000 orders they have for the car and how they are going to ramp up production from 90,000 cars this year to 500,000 next year. We see a coming let-down on this number and we are sure Elon is working on the language now that he will use to tell us that he is not going to make the numbers. But with that said, the company is amazing. The cars are spectacular. Customers rave about their cars like never before. And in the next five years this firm will become one of the greatest firms in the world. (You heard that here first at The Bull Market Report!)
Here are a few tidbits of things the Elon Musk is talking about:
Musk said that by 2020 Tesla will likely be able to make its cars go as far as 745 miles per charge.
The current record for hypermiling in a Tesla is about 560 miles. What is hypermiling? By taking it easy on the gas pedal and brakes, hypermilers achieve gas mileage feats far beyond the fuel economy ratings given to cars by the Environmental Protection Agency. They coast to stop signs, accelerate slowly, and sometimes raise the ire of other drivers.
The official range for Tesla's Model S is about 315 miles per charge, and note that the Model 3 was announced Friday with a range of 310 miles, up from 220 miles that most thought. Do you think Tesla will NOT continue to enhance the batteries over time? If you don’t, you are delusional. There is no question about this in our mind.
Here is some of the Press Release from Tesla on Friday, paraphrased by Bloomberg.
“Three hundred ten.
“That’s the electric range of a $44,000 version of Tesla’s Model 3, unveiled in its final form Friday night. It’s a jaw-dropping new benchmark for cheap range in an electric car, and it’s just one of several surprises Tesla had in store as it handed over the keys to its first 30 customers.
“Tesla has taken in more than 500,000 deposits at $1,000 a piece, Chief Executive Officer Elon Musk told reporters ahead of the event. This has created a daunting backlog that could take more than a year to fulfill - and that was before Musk took the stage in front of thousands of employees, owners, and reservation-holders to lift the curtain on the company’s most monumental achievement yet.
“We finally have a great, affordable, electric car - that’s what this day means,” Musk said. “I’m really confident this will be the best car in this price range, hands down. Judge for yourself.”
Here’s some of what Tesla disclosed at its plant in Fremont, California:
Two Battery Versions
Tesla has simplified the manufacturing process “dramatically,” Musk said. In the same factory space where Tesla can build 50,000 Model S or Model X cars, it will soon be able to produce 200,000 Model 3s. Part of that is due to a simplified package of options.
The car comes in two battery types: standard and extended range. Here’s how they break down:
Standard Battery:
Price: $35,000
Range: 220 miles (EPA estimated)
Supercharging rate: 130 miles in 30 minutes
Zero to 60 mph time: 5.6 seconds
Long Range Battery:
Price: $44,000
Range: 310 miles
Supercharging rate: 170 miles in 30 minutes (Same as Tesla’s Model S)
Zero to 60 mph time: 5.1 seconds
Only one other electric car in the world has broken the 300-mile range barrier: The most expensive versions of Tesla’s Model S, an ultra-luxury car that costs $97,500 or more. The new Model 3 has cheaper range availability than the current record holder, the $37,500 Chevy Bolt, which is outclassed in nearly every way by the Model 3.
Take a look at this video of the introduction of the Model 3:
https://www.bloomberg.com/news/articles/2017-07-29/tesla-s-model-3-arrives-with-a-surprise-310-mile-range
The High Yield Report
By Michael Foster
Special to The Bull Market Report
One of the biggest stories this week in high yield was Welltower’s (HCN: $73) earnings report, which was a very slight disappointment. Revenue fell 2%, slightly short of expectations, to $1.06 billion. FFO of $1.06 was a one-cent beat, again demonstrating Welltower’s continued acumen at financial discipline. The stock was offer a minor 1% for the week.
What about the dividend? Well, the company’s annual dividends are currently $3.48, with an annualized dividend coverage of 122%. That’s good, but admittedly not fantastic - our general rule of thumb is 130% or more dividend coverage should be every REIT’s target. Yet the company’s massive scale - we’re talking about a $27 billion market capitalization company with $30 billion in assets on the balance sheet - indicates that the income stream is extremely well insulated from a sudden market shock. Welltower also reported some interesting developments both in this quarter and in the future, including two properties spanning over 100,000 square feet that are 100% fully occupied. Partly because of this, the company raised its guidance.
Also significantly, Welltower’s borrowing costs went down. The company has lowered its net debt and improved its debt ratio in the quarter - a wise move considering the higher borrowing costs that are impacting the entire high yield universe. This is another indication that Welltower’s dividend coverage, while slightly soft now, will improve over the coming quarters. For this reason, there is a good reason to hold firm and keep buying this stock.
Also this week, we saw Omega Healthcare Investors (OHI: $31) report results quite similar to Welltower, and it too fell over 1% following the news on that day. The company saw revenue rise 4% a touch short of expectations at $194 million with EPS of 87 cents, which was a 2 cent beat. Again financial discipline was at play for the dynamic. Adjusted FFO rose over 3% from a year ago and the company raised its guidance, now expecting full year FFO to be between $3.42 and $3.44. The company also raised its dividend by a penny, continuing its history of raising dividends every quarter.
How did it do this? A big part of the REIT’s results center around its financing strategy. The company retired some unsecured credit and borrowed with new senior lines of credit, helping to lower overall borrowing costs for the firm. Omega also spent $8 million in new investments in the first quarter while spending another $30 million to renovate existing and build new facilities. The new investments include $180 million worth of property - $115 million in the U. K. and the rest in America.
Omega is doing what it does best: expanding its footprint, finding new opportunities, and improving rent potential with existing properties while increasing its dividend. If the REIT reaches its FFO guidance, the dividend coverage ratio will stay over 130%. Yet the stock is down 3% for the week (after the 64 cent dividend Friday) and is yielding a monstrous 8.2%. This is clear irrationality, and tells us that Omega isn’t just a hold - it’s a strong buy. Investors long this stock should continue to appreciate the dividends and expect their growth to continue. Now is a good time to buy more.
Elsewhere in REIT earnings, Ventas (VTR: $67) reported a revenue beat with 5.6% year-over-year growth to $895 million and EPS of $1.06, a penny above expectations. The company also re-affirmed full-year guidance of $4.15 FFO per share, giving it a dividend coverage ratio of about 133%, around the same as Omega Healthcare. Ventas’s long history means that its yield is quite a bit lower as the market trusts this bigger company. Its $24 billion market cap shows strength and diversification. But 4.6% is a very strong income stream in today’s reality of low interest rates, so this stock continues to be a buy for investors who are looking for income.
What about their future? The company spent $110 million on investments in the second quarter to expand its footprint and provide greater dividend growth for investors in the future. There’s just one snag - Ventas funded this with common stock instead of debt, as Omega did. That’s a trifle concerning. Does the Ventas management believe their company’s stock is overpriced? Total liabilities of $13 billion are 56% of the company’s total assets, giving it a pretty decent debt-to-asset ratio that would justify more lending activity. So why is the company issuing shares, thus diluting investors’ positions in the firm?
A large part of it has to do with the relatively low yield on common shares right now - that 4.6% is lower than the rising borrowing costs that floating-rate loans would cost Ventas in the future. So there’s some logic to the move, whereas Omega’s 8% yield is far too costly to issue too many shares versus the 5% or less borrowing costs on debt that Omega can get through bonds and loans. Thus the financial activities of both REITs, while different, make a lot of sense in their own context.
It seems pretty clear that, in a busy week for Healthcare REITs, the recent earnings releases give renewed confidence to stay long these companies and to continue to collect their dividends. Omega seems to be the strongest buy right now, and it makes sense to buy the company at any point when the dividend is more than 8%. We suspect that won’t last long, so it makes sense to add on to your Omega positions now.
Good Investing,
Todd Shaver, CEO, Editor in Chief, Founder
The Bull Market Report
Since 1998
July 26, 2017
by Todd Shaver | Jul 26, 2017 | Earnings Preview 6 AM
We are a shade late this week. We had computer and internet issues. Sorry.
Alphabet (GOOG: $954)
Bull Market Report Target Price: $1000
Bull Market Report Sell Price: We would not sell Alphabet
Earnings Date: Monday, 4:00 PM ET
Consensus: 2Q17
Revenues: $26 billion
EPS: $5.01
Alphabet reported a heavy drop in 2Q17 EPS due to the $2.7 billion fine from the European antitrust regulators. Shares currently trade down about 3% as the company missed expectations on its cost per click which rose by 23%. We are still bullish on Alphabet as they continue to innovate and bring to market new technologies like their most recent Google Home.
****************************************************
Eli Lilly (LLY: $82)
Bull Market Report Target Price: $88
Bull Market Report Sell Price: $76
Earnings Date: Tuesday, 8:00 AM ET
Consensus: 2Q17
Revenues: $5.4 B
EPS: $1.05
Year Ago Quarter Results
Revenues: $5.5 B
EPS: $0.86
Lilly reported yesterday with revenues up 8% and earnings up a powerful 22% to $1.11. Despite having missed estimates in two of the past four quarters, the stock is up 3% since this time last year and is currently trading 28% above its 52-week-low. Like other companies in our portfolios, Eli Lilly is also trading relatively cheap in comparison to the overall industry. Eli’s PE is 40 while Healthcare industry PE is around 60.
****************************************************
Equity Residential (EQR: $66)
Bull Market Report Target Price: $85
Bull Market Report Sell Price: $55
Earnings Date: Tuesday, 4:00 PM ET
Consensus: 2Q17
Revenues: $610 M
EPS: $0.35
Year Ago Quarter Results
Revenues: $595 M
EPS: $0.59
Key Things to Watch For in the Quarter
The company reported yesterday that it had net income of $195 million, or 53 cents per share, well above the Street estimate. Revenues came in at $613 million. Although Equity Residential has beaten estimates in the past four quarters, the stock still trades down 5% from this time last year. However, EQR is trading 13% above its 52-week low indicating positive investor sentiment within the Real Estate industry. The stock currently trades at a PE ratio of 20, relatively low compared to the industry’s PE of 40.
****************************************************
PayPal (PYPL: $58)
Bull Market Report Target Price: $56
Bull Market Report Sell Price: We would not sell PayPal
Earnings Date: Wednesday, 11:00 AM ET
Consensus: 2Q17
Revenues: $3.1 B
EPS: $0.43
Year Ago Quarter Results
Revenues: $2.7 B
EPS: $0.36
Key Things to Watch For in the Quarter
Analysts across Wall Street expect that PayPal will report a healthy 16% growth in EPS to $0.36 and a 14% increase in revenue to $3.1 billion. PayPal has either met or beaten estimates in each of the past four quarters. This success has contributed to the 55% appreciation in the stock since this same time last year. We expect PayPal to continue its top line growth as more transactions shift away from cash and onto digital platforms.
PayPal has hit our Target of $56. We still love the company and expect big things in the future. We hereby raise our Price Target to $66, and maintain our Sell Price as “We would not sell PayPal.”
****************************************************
Facebook (FB: $165)
Bull Market Report Target Price: $165
Bull Market Report Sell Price: $140
Earnings Date: Wednesday, 4:00 PM ET
Consensus: 2Q17
Revenues: $9.2 B
EPS: $1.12
Year Ago Quarter Results
Revenues: $6.4 B
EPS: $0.97
Key Things to Watch For in the Quarter
Analysts across Wall Street expect that Facebook will report strong EPS growth of 15% growth to $0.97 and a 30% increase in revenue to $9.2 billion. Despite having missed estimates last quarter, Facebook’s stock has climbed 36% since this time last year. In addition to the flagship Facebook.com, Zuckerberg has been innovating through his various offerings which include WhatsApp, Instagram, and Oculus Virtual Reality. We expect Facebook will continue to thrive as it tries to connect people throughout the world.
Facebook has hit our Target of $165. We added the stock at $97 a year and half ago and have been beating the drums every chance we get. We are still beating the drums. This company is amazing and is changing the world. We hereby raise our Target Price to $178 and raise the Sell Price from $140 to $155.
****************************************************
Omega Healthcare Investors (OHI: $33)
Bull Market Report Target Price: $45
Bull Market Report Sell Price: $28
Earnings Date: Wednesday, 4:00 PM ET
Consensus: 2Q17
Revenues: $235 M
EPS: $0.49
Year Ago Quarter Results
Revenues: $185 M
EPS: $0.57
Key Things to Watch For in the Quarter
Analysts estimate that Omega will report a 20% increase in revenue to $235 million and a 14% decrease in EPS to $0.49. Although Omega beat estimates in three of the past four quarters, the stock is down 6% this past year. This price depreciation has provided investors with an opportunity for entry especially as the stock only trades at a PE of 16 compared to the industry average of 60.
The stock hasn’t gone anywhere in a year, but that’s OK as we love the almost 8% dividend it pays.
****************************************************
CBRE (CBG: $38)
Bull Market Report Target Price: $40
Bull Market Report Sell Price: $32
Earnings Date: Thursday, 8:00 AM ET
Consensus: 2Q17
Revenues: $3.4 B
EPS: $0.53
Year Ago Quarter Results
Revenues: $3.2 B
EPS: $0.52
Key Things to Watch For in the Quarter
CBRE is expected to report moderate revenue and EPS growth for 1Q17. Analysts estimate that CBRE will report a 6% increase in revenue to $3.4 billion and a 2% increase in EPS to $0.53. The firm reported earnings that beat estimates in 3 of the last 4 quarters and provided investors with a 31% return year-over-year. CBRE’s stock currently trades at a PE ratio of 20, which is extremely cheap compared to the industry’s average PE of 91.
We love this one and can’t wait for it to hit $40 so we can raise the Target. The company is doing amazing things in real estate, saving companies money and manpower, and they are so low-key very few investors know about the firm. The market cap is a shade under $13 billion now, and this coming weekend we will give you some examples of what they do for their customers and why $38 for this stock will seem cheap in a year. We hereby raise the Sell Price from $32 to $35. We don’t want to lose the 48% gains we have in the stock since we added it at $26 last year.
****************************************************
United Parcel Service (UPS: $113)
Bull Market Report Target Price: $125
Bull Market Report Sell Price: $106
Earnings Date: Thursday, 8:00 AM ET
Consensus: 2Q17
Revenues: $15.5 B
EPS: $1.47
Year Ago Quarter Results
Revenues: $14.6 B
EPS: $1.43
Key Things to Watch For in the Quarter
UPS is expected to report moderate revenue and EPS growth for 2Q17. Analysts estimate that UPS will report a 5% increase in revenue to $15.5 billion and a 3% increase in EPS to $1.47. The firm reported mixed earnings in the last four quarters. Having only beat estimates once, the stock has underperformed the market at a mere 2% increase. It currently trades at a PE ratio of 28, which is slightly high compared to its competitors in the 25 range.
We still like the company a lot, as they have to deliver all those packages from Amazon! We are maintaining our Price Target of $125.
****************************************************
Bristol Myers Squibb (BMY: $56)
Bull Market Report Target Price: $77
Bull Market Report Sell Price: $51
Earnings Date: Thursday, 8:00 AM ET
Consensus: 2Q17
Revenues: $5.1 B
EPS: $0.73
Year Ago Quarter Results
Revenues: $4.9 B
EPS: $0.69
Key Things to Watch For in the Quarter
Bristol Myers is expected to report moderate revenue and EPS growth for 2Q17. Analysts estimate that Bristol will report a 4% increase in revenue to $5.1 billion and a 6% increase in EPS to $0.73. Although Bristol Myer beat estimates in three of the past four quarters, the stock is down over 25% this past year. This price depreciation has provided investors with cheaper opportunities for entry especially as the stock only trades at a PE of 20 compared to the industry average of 60.
****************************************************
Celgene (CELG: $137)
Bull Market Report Target Price: $135
Bull Market Report Sell Price: $115
Earnings Date: Thursday, 8:00 AM ET
Consensus: 1Q17
Revenues: $3.2 B
EPS: $1.78
Year Ago Quarter Results
Revenues: $2.8 B
EPS: $1.44
Key Things to Watch For in the Quarter
Analysts across Wall Street expect that Celgene will report both strong revenue and EPS growth of 15% and 24% to $3.2 billion and $1.44 respectively. while Amazon will increase its revenues by 19% to $37 billion, it will decrease its EPS nearly 20% to $1.42. Amazon has beat estimates in all of the past 4 quarters and has helped return investors 27% since this time last year. Celgene still only trades at a PE ratio of 50, making it relatively cheap compared to the industry’s PE of 60.
Since June at $114, the stock has gone straight up. It has reached our Target of $135, but we still love this huge company ($107 billion market cap,) so we hereby raise our Price Target to $150 and raise our Sell Price from $115 to $125. We added the stock at $95 a year ago and are now up 44% as it just set a new all-time high last week. Lovin’ it.
****************************************************
Amazon (AMZN: $1,040 – a new all-time high)
Bull Market Report Target Price: $1,100
Bull Market Report Sell Price: $875
Earnings Date: Thursday, 4:00 PM ET
Consensus: 1Q17
Revenues: $37 B
EPS: $1.42
Year Ago Quarter Results
Revenues: $30 B
EPS: $1.78
Key Things to Watch For in the Quarter
Wall Street expects that while Amazon will increase its revenues by 19% to $37 billion, it will show a decrease in EPS of nearly 20% to $1.42. Amazon has beat estimates in three the past four quarters and has helped carry many tech heavy indices. Amazon traded at $765 this time last year and has since climbed over 35% to its current levels. This past Prime Day, Amazon’s version of Black Friday, the company broke its own record for the largest online shopping day in history.
We are keeping the Target Price at $1100, but raise our Sell Price to $970 from $875.
****************************************************
First Solar (FSLR: $45)
Bull Market Report Target Price: $55
Bull Market Report Sell Price: $28
Earnings Date: Thursday, 4:00 PM ET
Consensus: 2Q17
Revenues: $540 M
EPS: $0.10
Year Ago Quarter Results
Revenues: $935 M
EPS: $0.87
Key Things to Watch For in the Quarter
This company is regrouping, as we know, and the comparisons are not pretty. Analysts estimate that First Solar will report a decrease in revenues by 43% to $540 million and an 88% decrease in EPS to $0.10. Although First Solar has beat estimates in the past four quarters, the stock is down 5% this year.
The stock is inching its way back, little by little. We certainly had bad timing on the addition of the stock to our Special Opportunities portfolio last year in February, but we are believers in the business and the company and have had amazing patience with this one. We hereby raise the Sell Price from $28 to $39.
****************************************************
Ventas (VTR: $68)
Bull Market Report Target Price: $82
Bull Market Report Sell Price: $43
Earnings Date: Friday, 8:00 AM ET
Consensus: 2Q17
Revenues: $880 M
EPS: $0.44
Year Ago Quarter Results
Revenues: $850 M
EPS: $0.42
Key Things to Watch For in the Quarter
Wall Street expects that Ventas will report moderate EPS growth of 7% to $0.45 and a 4% increase in revenue to $880 million. Although the firm has beat estimates in the past four quarters, its stock is down 8% over the past year. The company’s 5% dividend and relatively cheap PE of 35 make it an attractive stock in today’s markets. This is not a small company, as the market cap of $25 billion tells us.
We hereby raise our Sell Price from $43 to $61.
****************************************************
Welltower (HCN: $73)
Bull Market Report Target Price: $84
Bull Market Report Sell Price: $60
Earnings Date: Friday, 8:00 AM ET
Consensus: 2Q17
Revenues: $1 B
EPS: $0.44
Year Ago Quarter Results
Revenues: $1 B
EPS: $0.54
Key Things to Watch For in the Quarter
Analysts estimate that Welltower will report no change in revenues at $1 billion and a 18% decrease in EPS to $0.44. Although Welltower has beat estimates in the past 4 quarters, its stock is down 7% this past year. This move has provided investors with cheaper opportunities for entry especially as the stock continues to pay a 5% dividend and trades at a PE that is 25% lower than its industry’s.
We hereby raise the Sell Price from $60 to $68.
July 23, 2017
by Todd Shaver | Jul 23, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
Have equity markets come too far too fast this year? Year-to-date the S&P 500 is up 12%. We are certainly not ringing any alarm bells. Rather we note that the market can’t just go up in a straight line for extended periods. While stock indexes ended the week higher, the underlining story is we are seeing the steadiest outflows of cash since 2009. Even as the S&P 500 clawed its way to a fresh record and squeezed out a third consecutive weekly gain, signs of fading enthusiasm in U.S. stocks have become increasingly difficult to ignore. The latest can be seen in the SPDR S&P 500 Trust, the biggest exchange-traded fund tracking the U.S. equity benchmark. As of Thursday, investors had pulled $3.8 billion out of it in July. That puts the fund on pace for a fourth consecutive monthly outflow, which would be the longest streak since the start of the bull rally in 2009. This push and pull will continue of course. The S&P 500 touched new highs this week before retreating as an intensifying investigation into President Donald Trump stoked concern that his economic agenda may stall. We expect more of the same in the week ahead.
However, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks: Microsoft, Visa, Athenahealth, Netflix, and Blackstone. We believe in these companies.
Highlights From The Past Week
Tech Index Eclipses Record From Dot-Com Era. Tech stocks broke a nearly two-decade-old record this past week. The S&P 500's Information-Technology sector ended the day on Wednesday at 992.29, closing above its previous all-time high of 988.49 set in March 2000 at the peak of the dot-com bubble. Tech stocks are by far the best-performing among the index's 11 sectors this year, up 23% after posting their ninth consecutive day of gains Wednesday.
Bank of America Chooses Dublin for Main EU Hub After Brexit. Bank of America has picked Dublin to locate its main European Union hub in preparation for Britain quitting the bloc in 2019, the latest global bank to finalize its contingency arrangements after Brexit. The bank will move some roles from London to the Irish capital and other cities across the EU. Bank of America already has a fully licensed operation in Dublin, and employs more than 700 people in the country. London has flourished as a hub for global finance in part because firms based in the capital have the right to do business across the 28-nation EU. British banks, as well as firms from the U.S., Japan and other non-EU countries with a base in London, stand to lose this “passport” after Brexit and may need to channel business throughout other locations in the bloc.
Dublin is the second most popular destination, after Frankfurt, for Financial Services companies seeking uninterrupted EU access post-Brexit. The city provides a low-tax English-speaking location and has similar laws and regulations to its U.K. neighbor. It is fascinating to watch the evolution of the European Union and what it means for business. There are certainly major changes ahead for companies.
Draghi Says ECB Isn't There Yet as Inflation Lag Takes Time. Mario Draghi said policy makers are still waiting for inflation to catch up with the economy’s recovery, as they put off any discussion on winding back stimulus until after the summer. Specifically, he said the EU is finally experiencing a robust recovery where one only has to wait for wages and prices to follow course. “We need to be persistent and patient and prudent, because we’re not there yet.” While the ongoing economic expansion provides confidence that inflation will gradually glide toward levels in line with the inflation aim, it has yet to translate into stronger inflation dynamics. A very substantial degree of monetary accommodation is still needed for underlying inflation pressures to gradually build up. What does this all mean? Continued easy money policy from Europe’s central bank is a big benefit for global equity markets including the US. Good for the US stock markets.
Congress Must Avoid Spooking Markets on Debt Limit. The U.S. debt limit needs to be raised in a calm, thoughtful manner that steers clear of political uncertainty that would spook markets. But will they do it? Congress must avoid any political standoff that could set in motion disruptive activities such as a need to choose which bills to pay and which to delay. The government will reach its statutory limit on borrowing in early October. President Donald Trump’s administration has asked Congress to raise the ceiling before then. Concerns have surfaced in the Treasuries market, with traders willing to pay more for bills maturing after October 19th to avoid being caught holding securities vulnerable to a technical default. Watch for the upcoming political discussion over the debt and let’s hope it doesn’t get contentious.
BMR Companies & Commentary
Microsoft (MSFT: $74, up 1% - all prices in the newsletter are for the week)
The company reported earnings this week. Revenue of $25 billion beat the consensus by 2% while EPS of 98 cents beat by a big 27 cents. Analysts were positive on the quarter itself, especially around commercial cloud and commercial bookings which both came in nicely above Street expectations. Commercial cloud growth accelerated and is also experiencing margin expansion which is helping increase both operating income and free cash flow generation. Some went further and talked on how Microsoft looks to be taking share from Amazon Web Services (AWS) and is becoming a larger force in the space.
Despite the strong revenue quarter, operating expenses came in higher than expected and the company is also seen to have a higher tax rate than estimated. On top of this, some wanted to see the “billings beat” seen in the quarter to flow into greater revenue guidance for Q1.
The cloud business – Azure - was the main story from the quarter due to 30% growth in commercial bookings. Office 365 and servers were both healthy, and execution on renewals was strong.
BMR Take: All in all a very solid quarter from Microsoft. The stock hit NATHs* this week and we see NATHs ahead. We believe the stock will hit $80 in the coming months, which represents 20x EPS. The market cap is now $570 billion, only topped by Apple at $780 billion and Google at $680 billion.
*NATH – New All-Time High
Visa (V: $100, up 3%)
Visa reported strong earnings. EPS beat on stronger revenue and the company raised expectations for the forward outlook.
Visa reported EPS of $0.86, $0.05 ahead of the Street. Visa is now guiding to approximately 20% EPS growth, which compares to the "high end of mid-teens" growth which was issued previously.
From management at the earnings announcement: “Results reflect strong growth in payments volume, cross-border volume, and processed transactions, which were powered by economic tailwinds in the U.S. and globally. Results and growth reflect the company’s strategy to pursue the conversion of cash and checks to electronic payments in partnership with our clients around the world.”
The story at Visa has been strong for decades and not much has changed. And that’s a good thing. Visa is a global payments technology company working to enable consumers, businesses, banks and governments to use digital currency. Visa connects billions of consumers, businesses, banks and governments in more than 200 countries and territories worldwide. The company is as close to an unstoppable machine as can be at this point.
Take a look at this chart of Visa for the past nine years:
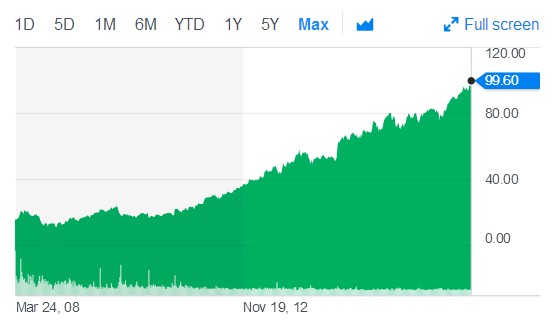
With a market cap of $230 billion, it is one of the greatest companies in the world. We would highly suggest you own some.
BMR Take: Consensus now sees EPS closing in on $5.00 in the next 1-2 years. With EPS growth running 20%, valuation looks awfully compelling to us still. We added the stock in early 2016 at $70. Our current Target is $95 which it has blown through this month, so we hereby raise our Price Target to $110. Our Sell Price remains “We would not sell Visa.”
Athenahealth (ATHN: $156, up 9%)
Athenahealth delivered an exciting quarter. The company believes it is at a key inflection point in its history and that 2017 will be a productive year for building out what differentiates them in the market. The company is demonstrating the power of its co-source model by simplifying and reducing client work. It’s building a new hospital service. It’s re-platforming AthenaNet. It’s grown its network to 100,000 providers, 98 million unique patient records, and 2.8 million covered lives, and is now positioned to be healthcare’s first true technology company. Stellar!
So many highlights from the quarter to discuss. Revenue increased 15% from last year to $293 million beating the consensus by $2 million. EPS of $0.51 crushed the consensus estimate of $0.39.
Moreover, the company continued the implementation waves at New York-Presbyterian Medical Groups, Adventist Health, and Tenet Health. The company gained access to the Centers of Medicare and Medicaid Services (“CMS”) claims data in certain states as a CMS Certified Qualified Entity. The company acquired Praxify Technologies to advance its platform strategy and mobile capabilities and accelerate its research and development initiatives by leveraging Praxify’s powerful app development platform. We could go on and on…
BMR Take: Athenahealth is a sleepy, off-the-radar company that is now firing on all cylinders. There is real upside potential ahead. Recall, big time activist investor Elliot Management has taken a stake in the company. Could we see all-time highs ahead which would be near $200? We feel this is a more than small probability.
Netflix (NFLX: $189, up 17%)
Netflix just does what it always does: Crushes expectations and the naysayers. The company delivered EPS of $0.15 just missing the consensus by a penny. But revenue of $2.8 billion was on the mark. The big story was the strength of subscriber growth and that was enough to send the stock soaring.
Netflix added 5.2 million net new subscribers in the June quarter vs. Wall Street's consensus estimate of 3.2 million. It also guided higher for the current quarter, with a forecast of 4.4 million net new subscribers, topping the consensus view for 4.0 million. This is huge subscriber growth. The company ended Q2 with 104 million subscribers worldwide, including 52 million in the U.S. and 52 million in foreign markets. Netflix's international streaming subscribers topped those in the U.S. for the first time.
Domestic net additions of 1.1 million represented the highest level of Q2 net adds since the second quarter of 2011. Better yet, Q3 guidance assumed much of this momentum will continue with the caveat that management is cognizant of the lessons of prior quarters when its over-forecasted.
The underlining fundamental story remains rock solid. With its content strategy paying off in strong member, revenue and profit growth. Management continues to believe that it is wise to continue to invest. In continued success, Netflix will deploy increased capital in content, particularly in owned originals, and, as management has said before, the business is likely to remain free cash flow negative for many years. That’s what it takes to build greatness!
The entertainment market is so broad that Netflix has now grown from zero to over 50 million streaming households in the US over the last 10 years. Netflix is growing with an expanding market, being co-pioneers of internet TV. The future is quite exciting.
BMR Take: Netflix is a premier growth story. The long term potential opportunity is quite big and we are still so early. This is one stock you just have to figure out how to own and hold onto.
The Blackstone Group (BX: $34, flat)
Blackstone delivered a decent quarter. EPS of $0.59 was just light of the $0.62 consensus. But revenue of $1.55 billion beat the $1.50 billion consensus. Total assets-under-management (AUM) was a ridiculous $370 billion. The $0.54 dividend was paid, giving the stock a dividend run-rate of 6.5%.
Management noted that it is continuing to see the benefits of its sustained large-scale capital deployment around the world, a patient focus on value creation in those investments, and then being able to choose the right moment to exit. They expect this momentum to continue. With pending realizations, including the historic sale of its European logistics portfolio, the company is on track for one of the best years for cash distributions to shareholders in its history. Wow!
In particular, the CEO said, the company’s distribution should not be viewed as one-off special dividends. They have demonstrated an ability to deliver consistently high payouts over time. Over the past three years for example, the company has distributed an average of nearly $2.50 per year, driven by over $130 billion of gains on investments.
BMR Take: EPS is running around $3.00 so the PE multiple is just over 10. The dividend yield strong and management is saying they can deliver you this dividend in the future as they have now done it now consistently for many years. We see compelling value here.
Upcoming Economic News
Existing Home Sales
Monday, July 24th, 10:00 AM
Period: June
Consensus: 5,560,000
Prior: 5,620,000
Consumer Confidence
Tuesday, July 25th, 10:00 AM
Period: July
Consensus: 116.0
Prior: 118.9
Note: The Conference Board's Consumer Confidence Survey is a monthly measure of the public's confidence in the health of the U.S. economy.
New Home Sales
Wednesday, July 26th, 10:00 AM
Period: June
Consensus: 615,000
Prior: 610,000
GDP
Friday, July 28th, 8:30 AM
Period: Q2
Consensus: +2.5%
Prior: +2.1%
Wall Street Consensus for Apple (AAPL: $150, up 1%)
Ratings Breakdown: 9 Hold Ratings, 39 Buy Ratings, No Sells
Targets
Wall Street Consensus Price Target: $16
7/22/2017 Wells Fargo $140
7/21/2017 Guggenheim $180
7/17/2017 Morgan Stanley $182
7/12/2017 Goldman Sachs Group $170
7/12/2017 Merrill Lynch $180
7/10/2017 Canaccord Genuity $180
7/9/2017 Credit Suisse Group $170
7/6/2017 Drexel Hamilton $202
BMR Take: Buy.
Wall Street Consensus for Opko Health (OPK: $6.59, up 8%)
Ratings Breakdown: 2 Hold Ratings, 6 Buy Ratings
Targets
Wall Street Consensus Price Target: $16
7/18/2017 Barrington Research $11
6/16/2017 Ladenburg Thalmann $19.50
6/12/2017 Jefferies Group $8
3/14/2017 Guggenheim $25
3/5/2017 Standpoint Research $14
1/3/2017 Laidlaw $19
BMR Take: We’re sticking with this one and are looking for a BIG upside. Look at what the brains of Wall Street think about the stock. We remain astounded that the stock has stayed down here for all this time. And the CEO and Founder just keeps buying shares.
Nutanix Insider Trading
We generally love it when insiders in a company are buying stock. Conversely, we get a little crazy when insiders are selling. Check this out about Nutanix (NTNX: $24), which had another great week, up 7%.
--- Director Jeffrey T. Parks sold 1,235,000 shares of the firm's stock in a transaction that occurred on July 14th. The stock was sold at an average price of $21.97, for a total transaction of $27,100,000.
--- Sr. VP Rajiv Mirani sold 20,000 shares of the firm's stock in a transaction that occurred on July 13th. The stock was sold at an average price of $19.63, for a total transaction of $400,000. Following the transaction, the senior vice president now directly owns 271,000 shares in the company, valued at $5,300,000. The sale was disclosed in a document filed with the Securities & Exchange Commission.
--- VP Kenneth W. Long III sold 30,000 shares of the firm's stock in a transaction that occurred on July 19th. The stock was sold at an average price of $24.00, for a total transaction of $720,000. Following the transaction, the vice president now directly owns 240,000 shares in the company, valued at $5,765,000. The sale was disclosed in a document filed with the Securities & Exchange Commission.
BMR Take: We are not happy about this. We want them to be buying the stock because as insiders, they know that the company is killing them and that the stock is going to go higher. This selling by insiders makes us very wary. We love this company and after adding the stock at $17.45 in late May, two months later we are up 36% and have high hopes for more gains. But our antennas are out do to these insider transactions and if the stock falls to the $22 level, we are out.
Amazon – A Discussion
People say Amazon (AMZN: $1,025, up 2.5%) is not making any money. The stock set a NATH this week and many see the stock peaking here, believing the stock is way over-valued since they are not making any money. We beg to differ.
The facts:
Profits the last five quarters, latest first:
$724,000,000
$749,000,000
$252,000,000
$857,000,000
$513,000,000
Revenues the past four years:
$136,000,000,000
$107,000,000,000
$89,000,000,000
$74,000,000,000
Check out this story about a new business to business website and operation in the UK and the US. This could be BIG:
http://www.businessinsider.com/interview-amazon-business-bill-burkland-017-7
A little survey on Amazon:
a) I have enough Amazon
b) I am thinking of buying more
c) I am going to buy more now
d) The stock price is too high – if they split I would buy some
e) The stock is way overvalued – their profits are too low and the PE at 190 is insanely too high.
Send your thoughts to us at Info@BullMarket.com
Home Depot, Best Buy Hit as Amazon Teams Up With Sears
Sears will sell Alexa-enabled Kenmore appliances via Amazon. But Whirlpool (WHR) and major sellers of appliances Home Depot (HD: $147, down 3%), Lowe's (LOW) and Best Buy (BBY) were hit. Home improvement chains Home Depot and Lowe's had been seen as Amazon-proof, or at least Amazon-resistant.
BMR Take: We are not ready to throw in the towel because of this one announcement, but we have to watch this development from Amazon. We added the stock to our Stocks for Success portfolio in early 2016 at $121 and are up 21%, so we don’t want to give up any of these gains. The market cap is $175 billion, they have $3.6 billion in cash supporting a sizeable debt load of $23 billion.
BMR Take: They are not going away anytime soon, but as noted above, Amazon is a monster that one needs to keep an eye on.
Google (GOOG: $973, up 2%)
July 3rd - $898. Today - $973. That’s an 8% move in three weeks.
BMR Take: Yes, they got fined big-time in Europe, but the $2.7 billion fine is peanuts to the company that has $92 billion in cash and virtually no debt, and makes over $20 billion a year. Yes, we have to watch the EU to see if there are any sanctions they will be putting on the company. But we believe the company will weather the storm and thrive. We await the break-through to NATHs of $988+ and raising our own Price Target from $1000 to $1100 or higher. Stay tuned. This just might happen sooner than you think.
Apollo Global Is Getting Ready to Take Security Firm ADT Public
Private-equity firm Apollo Global Management (APO: $28, up 2.5%) is preparing an initial public offering for ADT, just a year after it bought the home-security company.
The offering could value ADT at well over $15 billion, according to people familiar with the matter, making it one of the largest IPOs of the year. They paid $7 billion for the firm a little over a year ago. An offering would mark a quick turnaround for the private-equity firm, which began consolidating home-security providers two years ago.
BMR Take: This is just one example of the power of this firm. Apollo is way undervalued. With a 7% dividend, it's a joy waiting for a higher stock price.
The High Yield Corner
By Michael Foster
Special to The Bull Market Report
This week, we saw the AGIC Equity and Convertible Income Fund (NIE: $20) rise over 1% in the week thanks in no small part to a strong gain in the fund’s NAV. That increase was attributable to a solid week for the stocks in its portfolio, like Priceline (its second highest convertible holding) rising over 2% in the week. We’ve seen AGIC raise its equity exposure while using convertible bonds to provide a strong income stream throughout 2017, and that has resulted in two positives for investors. First, the dividend remains well-covered by investments; second, the fund has benefitted from this year’s bull market, despite how much many on the sidelines seem to hate this bull market. [That’s not us by the way. We like this bull market.]
The strong performance in the fund has helped its discount to NAV fall. This is the result of intense demand from investors for the fund, which is why the market price for the fund has risen over 11% YTD while its NAV has risen 6% over the same time period. We’re now seeing a discount of less than 10%, which is the fund’s highest since 2015. The AGIC fund has seen its discount shrink considerably from reaching a near 15% low in late 2016, which itself was an improvement from the near 20% discount at the start of 2016. This demonstrates continued interest in the fund from market participants, who see its 7.5% dividend yield as an attractive income stream, especially considering how sustainable it is.
Another Bull Market Report pick saw a similar gain this week. The Pimco Dynamic Income Fund (PDI: $30) rose nearly 1% for the week and is up 10% year-to-date. That’s not including the fund’s massive income stream, however. With an 8% yield from common dividends alone, Pimco Dynamic Income has already given an annualized return of 30%. Add in the special dividend and that number gets absolutely astronomic. This fund offered a similar return in 2016, thanks in part to its higher NAV but also thanks to investor demand. The fund has gone from a discount in 2016 to its current 7.4% premium to NAV, again indicating sustained demand for the fund from a variety of investors.
While diversified funds had a strong week, REITs were a bit less impressive. One of Bull Market Report’s top picks, Digital Realty Trust (DLR: $112), was flat for the week with little volatility. This is unusual; Digital Realty tends to bounce around a lot. But the fund has gone from a 6% yield in the past to now a 3% yield, thanks almost exclusively to its meteoric price appreciation. We’ve seen the stock jump 14% in 2017 alone, with 53% total capital gains in the last five years. It’s pretty obvious that, at this juncture, Digital Realty is no longer seen as a “high yield” risky opportunity, but is rather a low yielding REIT with long-term staying power. This makes sense; Digital Realty’s business of renting server space, is in no danger of shrinking anytime soon. This industry is also too new for us to determine whether it is cyclical or counter-cyclical. If it turns out that server space demand doesn’t go down during recessions in a cloud-computing world, then Digital Realty could quickly be perceived as one of the safest long term investments out there. For that reason, holding Digital Realty makes sense no matter what your investment profile or goals are, although the 3% yield is of course lower compared to many other REITs.
For instance, there’s Omega Healthcare Investors (OHI: $33), which also had a flat week with little volatility. Volume was much lower than average (nearly 50% of average daily shares traded). Omega has gone from a mid-8% yield to a mid-7% yield over the last couple of years, as investors have become much more aware of this stock. We’ve also seen the penny-per-quarter dividend jump continue, with dividend coverage ratios that demand respect.
There is much reason to believe this company is on solid ground, although the long-term and countercyclical sustainability of its business model (focusing on skilled nursing facilities - SNF) has been brought into question. Counterintuitively, we’ve seen an aging U.S. population be bad for SNFs for a variety of reasons. The relative wealth of aging baby boomers and the stigma associated with these facilities has made them much less popular than previous expectations. That, in turn, has put Omega and many of its peers under the spotlight, with mounting worries keeping stock prices muted (Omega is flat from a year ago and remains in the same range seen in late 2013). Five years ago and before, a lot of excitement around SNF-focused REITs drove price gains up a lot. The new perspective, and data from the industry, has kept investors more cautious.
Does this mean it’s time to sell Omega? Absolutely not. While the market is more competitive because demand is not as strong as previously expected, Omega Healthcare’s management has proven several times that they have the skill and acumen to identify and capitalize on those available opportunities in this tight market. The market, focused on the macro sentiment, has not priced in the premium that Omega Healthcare’s management should command. That makes them a buy, especially when the yield remains above 7%.
Looking ahead, investors should keep a close eye on the upcoming reports - Jobs, GDP, and Federal Reserve actions to come in late July and mid-August. This data is going to have a pretty significant impact on the future price trends for REITs and diversified funds. For now, however, The Bull Market Report’s High Yield stock picks look like solid holds, thanks to the high income stream and capital gains potential of a few of its constituents.
Good Investing,
Todd Shaver, CEO, Founder and Editor in Chief
The Bull Market Report
Since 1998
July 17, 2017
by Todd Shaver | Jul 17, 2017 | Monthly Newsletter Daily 12pm if new
The Weekly Summary
Billionaire CEO of JP Morgan Chase Jamie Dimon says being an American abroad is “almost an embarrassment.” The rant came on JP Morgan’s widely followed earnings call held Friday. Dimon says the media should focus more on major issues. He doesn’t like listening to the “stupid stuff” Americans have to deal with, expressing frustration over the nation’s inability to invest in infrastructure and overhaul the tax code. There would be much stronger growth if there were more intelligent decisions and less gridlock. Reporters should focus on the major issues the nation faces rather than the vagaries of the firm’s trading businesses, he said. The United States of America has to start to focus on policy which is good for all Americans, and that is infrastructure, regulation, taxation, education. He screamed, “Why you guys don’t write about it every day is completely beyond me. And, like, who cares about fixed-income trading in the last two weeks of June? I mean, seriously.” Dimon is one of the best businessmen in America and his words are known for being the hard truth. It makes sense to us that for the bull market to continue our citizens must wake up to the realities we face and take actions.
There is always a bull market here at The Bull Market Report! This week we highlight the following stocks: PayPal, Splunk, Microsoft, and Tesoro.
Highlights From The Past Week
US Bank earnings season started on Friday. Q2 earnings season for the banks kicked off on Friday morning with results from JP Morgan, Citigroup, Wells Fargo and PNC Financial. Some analysts have highlighted a more difficult setup for the group following a June rally on the back of higher bond yields and capital return announcements that beat elevated expectations. There have also been thoughts that earnings season could shift some of the focus back to the more challenging operating environment for the group. However, there really did not seem to be any meaningful discussion about downside risk to estimates. Analysts seem to be looking for the bulk of the support for Q2 to come from additional net interest margin expansion. This should offset sluggish loan growth and weaker capital markets (near double-digit declines). The latter dynamic has been widely discussed by bank executives and in the press and was a key driver of estimate reductions. Despite some pickup in concerns surrounding the Auto sector, credit is expected to remain benign. Analysts also highlighted expectations for another solid quarter of cost control. This is our first glimpse into the new earnings season.
More conjecture on ECB policy. There is further speculation on ECB policy where the ECB is likely to signal that it is gradually winding down its QE plan at its September 7th policy meeting, and President Draghi could use his appearance at the Fed Reserve's Jackson Hole conference in August to signal a policy shift. The ECB is wary of putting an end date to its QE plan. There is a need to retain flexibility in case the economic outlook sours and also the ECB wants to follow the Fed example of exiting the policy of retaining open-ended nature of program. A Reuters poll of over 75 economists showed consensus thinks the ECB is likely to shift away from ultra-easy policy in September. The Fed and ECB are two of the most powerful institutions in the world for capital markets. This is important stuff.
CBO says Trump budget would not balance. The Congressional Budget Office (CBO) said Trump’s fiscal 2018 budget would reduce the deficit by about a third over next decade. This is a smaller estimated deficit reduction than the White House forecast due to lower revenue projections. Trump’s budget would result in average GDP growth over next decade of 0.1% more than the CBO baseline. CBO also estimated that revenues under Trump’s budget would be almost $1 trillion lower than his estimates over the next decade. Trump budget's deficit reduction would stem from lower spending, including decreasing the $2 trillion base in mandatory spending, mostly from healthcare. Press reports said CBO’s findings creates new complications for Republicans who need to build a coalition of conservatives and moderates to vote for a single budget proposal. We need to start seeing some real progress out of the White House.
Britain acknowledges Brexit bill for the first time. Ahead of this week's Brexit talks between Brexit Secretary Davis and EU negotiator Barnier, a written statement was released to parliament, which acknowledged Britain has financial obligations to the EU, which will continue beyond Brexit. The Financial Times cited EU diplomats saying it goes further than UK Prime Minister May’s previous reference to Britain being willing to reach a “fair settlement” of unspecified obligations. It noted that Davis did not refer to financial issues when he released three position papers ahead of Brexit talks. The article pointed out that the British team sees the statement on financial obligations as an effort to improve the tone of talks rather than a change in substance. Meanwhile, at least 15 Conservative MPs are in talks with Labour on keeping Britain in the European Economic Area after Brexit, which would require accepting free movement of people and paying some money to the EU. The rationale for this approach is that it would give Britain time to reach a final deal with the EU and give certainty for businesses and workers. What a mess.
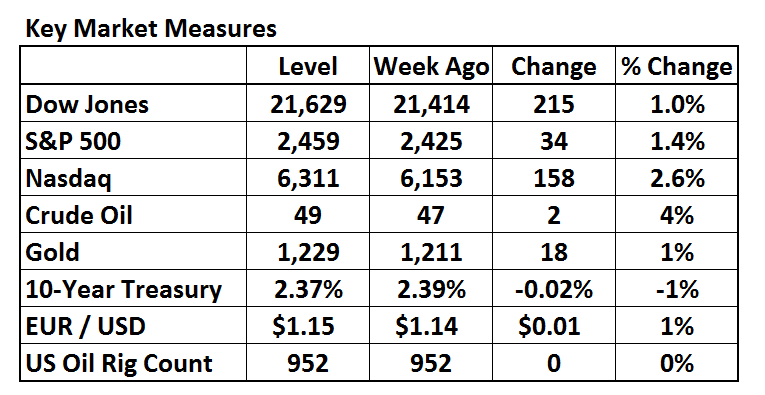
Dow, S&P 500 Hit Records to Close Winning Week
The S&P 500 hit a fresh record Friday and posted its best weekly performance since late May, and the Dow Industrials notched their third consecutive record close. Let’s keep this going!
BMR Companies & Commentary
PayPal (PYPL: $57, up 6% - new all-time high [NATH) set Friday)
The price target was raised to $70 from $54 at a research firm on the Street. PayPal is the firm's "top idea" for 2017, followed by Google (GOOG: $956, up $37, 4%). Coming opportunities with PayPal's Venmo and with partnerships caused the research firm to become even more bullish.
PayPal and Apple entered into an exciting major partnership this week that sent shares to all-time highs. PayPal and Apple have partnered to give users the ability to use PayPal as a payment method when paying for Apple’s services, which includes the App Store, Apple Music, and iTunes, to name a few. The feature will be introduced in 12 markets, including the US and the UK, and it will be integrated with several devices across Apple’s ecosystem, including the iPhone, iPod, Apple TV, and Apple Watch.
The immediate impact for PayPal is getting access to a massive revenue stream. Revenue from Apple services, which is mostly from the App Store, reached $7 billion in Q416, up 18% from last year. Although the financial terms of this deal have not been disclosed, we can estimate the potential impact. If PayPal were to charge Apple 1.25% per transaction, which is much lower than the 2.9% fee it often charges merchants, and if PayPal accounts for a third of spend on the App Store in 2017 — which will be based on consumers spending a total of $40 billion on the iOS App Store, according to Street sources — PayPal would see $165 million in revenue for 2017.
In the long run, PayPal’s partnership with Apple could give the firm an opportunity to integrate itself into additional Apple services. Over the last few years, Apple has indicated that it plans to turn its chat app, iMessage, into a robust ecosystem. The app now includes peer-to-peer payments, games, and other apps, with even more features coming in the fall with the launch of iOS 11. Although it hasn't been confirmed, it's reasonable to assume that one feature coming down the pipeline is the ability to buy products via iMessage. With PayPal already being a payment option within Apple's ecosystem, users may be more willing to use it going forward.
BMR Take: PayPal ranks among the best growth stories in all of technology and this Apple deal is just another reason as to why. Earnings are growing greater than 20% per year for as far as the eye can see and should break $3 by 2020.
Microsoft (MSFT: $73, up 5%, set a NATH* on Friday)
Early in the week Microsoft proposed a $10 billion effort to bring broadband internet to the rural U.S., an economic-development program aimed at a core constituency of the Trump administration. The plan, which calls for corporate and government cash, would send internet data over unused broadcast frequencies set aside for television channels. If developed, the initiative would help connect 23 million Americans in rural areas who lack high-speed internet access.
*NATH - New All-Time High
Broadband is important for all kinds of things. It’s not just streaming high-definition movies. Slow or nonexistent connections can hinder agriculture, business, education and healthcare. Broadband is arguable now a necessity of life. Microsoft’s proposal calls for a 5-year program of corporate investment and matching federal and state grants to end the gap between rural and urban access, starting with the company’s own efforts. The aim of Microsoft’s new Rural Airband Initiative is to be up and running in 12 states by next year and connect 2 million people over the next five years.
BMR Take: Doing big things like what is described above is why Microsoft is not just a tech titan, but a leader amongst the entire S&P 500. News like this continues to push the stock toward 20x consensus estimates of $4 per share of free cash flow. Do the math – that’s $80 a share.
Tesoro (TSO: $97, up 1%)
Tesoro has been a big winner and it could keep getting better. This week the company announced plans to study the possibility of turning vegetable oil into diesel fuel at its Dickinson refinery, which it purchased in 2016.
The crude oil refiner is making plans to retrofit an 8,000-barrel-per-day diesel hydrotreater to process soy and corn oil into renewable diesel alongside its Bakken crude oil processing. This $3.5 million project would use 17,000 gallons per day of vegetable oils to create a 5% renewable diesel mix to be marketed in North Dakota by the end of 2017. The North Dakota Industrial Commission granted the company a $500,000 grant to help cover the project's cost.
Compared to biodiesel that is blended into petroleum diesel at truck racks, renewable diesel is a superior quality product because, unlike biodiesel, renewable diesel is a pure hydrocarbon stream containing no oxygen. This results in a superior quality fuel that maintains vehicle performance. The company says the project is “unique and exciting.” Of course they do!
BMR Take: The stock continues to trade at a big discount to the consensus NAV* estimate of $120. In comparison, Buffet’s ownership of peer Phillips66 is valued at a premium to NAV in the market. Disconnect that the market will correct down the road? We think so. Tesoro still looks compelling to us even after the recent appreciation.
*NAV – net asset value
Upcoming Economic News
Export Price Index
Tuesday, July 18th, 8:30 AM
Period: June
Consensus: 0.05%
Prior: -0.70%
Note: The U.S. Bureau of Labor Statistics' International Price Program produces Import Price Indexes (MPI) and Export Price Indexes (XPI) containing data on changes in the prices of nonmilitary goods and services traded between the U.S. and the rest of the world.
Housing Starts
Wednesday, July 19th, 8:30 AM
Period: June
Consensus: 1,146,000
Prior: 1,092,000
Note: The number of housing units started in the United States.
Leading Economic Index
Thursday, July 20th, 10:00 AM
Period: June
Consensus: +0.30%
Prior: +0.30%
Note: The Conference Board Leading Economic Index (LEI) for the U.S. increased 0.3% in May to 127.0 (2010 = 100, following a 0.2% increase in April, and a 0.4% increase in March. Leading Indicators are economic series that tend to change direction ahead of shifts in the business cycle. There are 10 components of the U.S. Leading Composite Indicator* published by The Conference Board. The index is constructed by averaging the individual components in order to smooth out a good part of the volatility of the individual series. Historically, the cyclical turning points in the leading index have occurred before those in aggregate economic activity. Prior to 1996, the composite leading, coincident, and lagging indicators were calculated and published by the U.S. Department of Commerce.
* Average weekly hours, manufacturing
Average weekly initial claims for unemployment insurance
Manufacturers’ new orders, consumer goods and materials
ISM Index of New Orders
Manufacturers' new orders, non-defense capital goods excluding aircraft orders
Building permits, new private housing units
Stock prices, 500 common stocks
Leading Credit Index
Interest rate spread, 10-year Treasury bonds less federal funds
Average consumer expectations for business conditions
An Interview with Tim Cook
We read a lengthy interview of Apple CEO Tim Cook by Bloomberg Businessweek Editor Megan Murphy. We thought the following few paragraphs from it were particularly insightful:
Murphy: I was a little surprised the HomePod was pitched primarily as a music device when the competitive talk is of Amazon Echo’s Alexa and the immersive experience in the home. How will the HomePod better integrate Apple inside people’s lives?
Cook: We’re actually already in the home through the iPhone you take with you everywhere. It’s in your pocket or laying on a stand. Today, pre-HomePod, I can control my home using Siri through the iPhone. When I get up in the morning, my iPhone is my alarm clock. I say, “Good morning,” and all of a sudden, my lights come on. The temperature adjusts and a series of things occur. We’re also in the home through Apple TV. Many people use iPad as their computing device. The desktop Mac enjoys a place in the home. The thing that has arguably not gotten a great level of focus is music in the home. So we decided we would combine great sound and an intelligent speaker.
Murphy: So, it’s going to be a holistic process joining up all those touch points so people can exercise control over their lives, whether through Siri or iPad?
Cook: To put it in perspective, Siri is getting requests from 375 million devices right now. My guess is it’s the largest by far of any kind of assistant. Some of those requests are done in the home. Some of those are done on the go. That’s the platform that we build off. It’s very different from our starting point. We’re also in so many languages around the world: Siri isn’t just in English. We’re well-positioned around the world. So, again, what is the thing that’s missing in this equation? The combination of quality audio and instinct.
“I am so excited about it, I just want to yell out and scream”
Murphy: Do you think people will pay $349?
Cook: If you remember when the iPod was introduced, a lot of people said, “Why would anybody pay $399 for an MP3 player?” And when iPhone was announced, it was, “Is anybody gonna pay - whatever it was at that time - for an iPhone?” The iPad went through the same thing. We have a pretty good track record of giving people something that they may not have known that they wanted.
When I was growing up, audio was No. 1 on the list of things that you had to have. You were jammin’ out on your stereo. Audio is still really important in all age groups, not just for kids. We’re hitting on something people will be delighted with. It’s gonna blow them away. It’s gonna rock the house.
BMR Take: We were pleased to see Tim Cook’s responses for two reasons. 1) the iPhone is already the home controller of choice. We knew this, but Cook really put it in perspective. And 2) The takeover of a market is Apple’s modus operandi. Start late with a high price. Then lower prices and dominate. We have no doubt the home assistant will be any different. Amazon – watch out.
Nutanix Has a Rip-Roaring Week
The stock of Nutanix (NTNX: $22) was up 16% last week. We’ve been harping on this stock for weeks, and then along comes Goldman Sachs and says Nutanix is a “once-in-a-decade” opportunity and are looking for a $31 Target. Our Price Target is $30. Is Goldman reading The Bull Market Report? We certainly think so.
We’re already up 27% in the six weeks since we added the stock in late May. And we expect more good things from the company in the future. Nutanix is the leader in hyperconverged infrastructure, meaning it uses software to combine different storage and computing functions on one device. That space has been heating up among enterprises. More businesses are looking to adapt the technology, with 18% of chief information officers saying they expect to move to hyperconverged systems in the next two years, according to Goldman Sachs.
The company’s leadership in the space, including the combination of hardware and software it offers, makes it a “once-in-a-decade tech infrastructure story,” wrote the lead Goldman analyst on the note. They see Nutanix on a path for long-term double-digit growth, high gross margins and large operating leverage.
Additionally, in the shorter-term, Nutanix should benefit from changed accounting rules that will move its software revenues, which are currently deferred, to its profit and loss statement.
BMR Take: What more can we say? All good.
First Solar Continues its Tear
First Solar (FSLR: $43) was up another 9% this past week. We’re still down 30% or so on the stock but we are big believers in the company and management. Our timing on the addition to the Special Opportunities portfolio was bad. But we believe we will be winners in the long run. The stock is up over 55% in the last three months. Keep hanging in there.
Apple Back Up To $150.
Almost. Closed at $149, up $5 for the week. The market just can’t keep this one down. We sincerely hope you have some of this wonderful firm. You think it’s too high. Not on your life.
Annaly Just Keeps Chugging Along
And it is paying 10% a year in dividends. Annaly Capital Management (NLY: $12.33) added 2% last week. The stock has been paying double-digit dividends since inception in 1997. That’s right – 20 years. Where will the stock be in a year? Good question. We would say right about at this level, after paying another four quarterly dividends of 30 cents each. Do the math – that’s a shade under a 10% return. We love this one.
The High Yield Corner
By Michael Foster
Special to The Bull Market Report
We’re getting close to earnings season for Healthcare REITs, and the market’s expectations seem to be getting increasingly bullish. Over the last week, all of The Bull Market Report’s Healthcare REIT picks were in the green, with Omega Healthcare Investors (OHI: $33) leading the pack with a 2% gain for the week. That’s pushed the stock’s year-to-date performance much higher, with a 7% gain on top of half of the fund’s 8% dividend yield. There’s been a relatively low amount of volatility in Omega Healthcare relative to what we saw both in 2015 (where rate hike fears hit all REITs) and 2016 (when the REIT bull market suddenly corrected at the end of the year).
But what about the upcoming earnings report on July 27th? So far, analysts are expecting 86 cent FFO for the quarter, up from 83 cents from a year ago. The company has reaffirmed their 86 cent guidance as recently as early May, bringing the stock’s dividend coverage ratio to 134% if they hit the number. Gotta love it.
Before we discuss whether they will hit it or not, let’s take a quick look at Welltower (HCN: $74, up 1%), which had a similarly strong week and is also planning to release earnings soon - on July 28th before the market open. Welltower has far outperformed Omega for 2017, with a 10% price jump - although the lower dividend (5%) mostly offsets this. Like Omega Healthcare, Welltower is showing strikingly little volatility as of late, a development that makes a lot of sense given Welltower’s tremendous track record and strong dividend coverage. However, it’s surprising to see that Welltower’s dividend coverage is a shade lower than Omega’s at 128%. While that’s still good (general rule of thumb: any number over 115% is good for a REIT), it’s interesting to see how the dividend coverage ratio has slipped in the last couple of years as a result of falling funds from operations. Welltower’s earnings were down 6% from a year ago last quarter, and guidance suggests that decline is set to continue. But Welltower is also increasing dividends, which is a setup for a worrisome dynamic in which, eventually, the company will under-earn its dividend. How soon could that happen? At the current clip we’re safe for another 3-4 years, but the company clearly needs to adapt, lest it find itself suddenly in a position to halt or even cut dividends. For this reason, the company’s earnings results on the 28th and especially its forward guidance will be a key issue to watch for. We will keep a close eye on this.
Finally, Sabra Health Care REIT (SBRA: $23) had a flat week (up less than 1%) despite being one of the smallest Healthcare REITs in terms of market cap and property footprint. It’s quite unusual to see the smaller stock be less volatile than its bigger cousins, but Sabra is one of the less popular REITs out there (investors, especially retail investors, spend a lot more time focusing on Omega), and there was little news on the stock to justify much price action. On top of that, the company’s massive underperformance relative to its peers has soured a lot of investors on the company, while fundamental investors know this is a very good company with strong dividend coverage and growth potential.
So, if you have few sellers and few buyers, you end up with little price change. But how is Sabra doing as we near its earnings release at the end of July? Over the last 12 months, earnings have been weak relative to expectations, with two misses out of the last four quarters. But dividend coverage is impressive, at 132%. Some investors may be a bit concerned about the company’s relatively weak revenue growth, but it’s important to remember that Sabra is pausing on acquisitions right now and reorganizing its new property portfolio additions to maximize income. This process naturally makes revenue look bad, which again is why impatient investors have shied away. Nonetheless, the ongoing restructuring continues to be successful, as the strong dividend coverage ratio proves. Expect to see good things from Sabra in the future that will help the stock recover, but we may not see those developments for a year or more. For investors, that means sitting tight with your Sabra shares, collecting a 7% dividend while you wait for the market to catch up.
Now, with upcoming earnings for these stocks, we need to ask ourselves the likelihood of them hitting their numbers. While there are differences in each company that makes some stronger than others, the broader issue that impacts all of them is the regulatory overhang. A lot of chatter about the future of Obamacare and plans from the Republicans and President Trump to change or obliterate current regulations has left a lot of investors skittish on Healthcare for a long time. But interestingly, we’ve seen the market swiftly realize how silly these concerns are - at least as it impacts the Biopharma sector, which is up solidly for 2017 and is beating the S&P 500. But why isn’t that same relief coming to Healthcare REITs with the same speed?
Simply put, REIT investors are far more risk averse as a group, and they are much slower to recognize a change in the political landscape than growth stock investors. This puts those holding Healthcare REITs in the awkward position of needing to be patient. However, it is clear that there is little change to the regulatory environment coming, and some analysts are already noting that recent GOP proposals to change Obamacare actually look a lot like Obamacare. Whatever your political leanings and opinions on the subject, it seems pretty clear that the status quo isn’t going to change anytime soon.
Again, no matter your opinions on the growing D.C.-based controversies, there is a clear conclusion: Healthcare as it operates in America is not about to change anytime soon. Healthcare REITs have been discounted for a change that would negatively impact them. Putting these together, it’s a clear time to buy or to continue to hold Healthcare REITs both before and after the upcoming earnings season.
Good Investing,
Todd Shaver, Founder, Editor and CEO
The Bull Market Report
Since 1998
July 16, 2017
by Todd Shaver | Jul 16, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
Billionaire CEO of JP Morgan Chase Jamie Dimon says being an American abroad is “almost an embarrassment.” The rant came on JP Morgan’s widely followed earnings call held Friday. Dimon says the media should focus more on major issues. He doesn’t like listening to the “stupid stuff” Americans have to deal with, expressing frustration over the nation’s inability to invest in infrastructure and overhaul the tax code. There would be much stronger growth if there were more intelligent decisions and less gridlock. Reporters should focus on the major issues the nation faces rather than the vagaries of the firm’s trading businesses, he said. The United States of America has to start to focus on policy which is good for all Americans, and that is infrastructure, regulation, taxation, education. He screamed, “Why you guys don’t write about it every day is completely beyond me. And, like, who cares about fixed-income trading in the last two weeks of June? I mean, seriously.” Dimon is one of the best businessmen in America and his words are known for being the hard truth. It makes sense to us that for the bull market to continue our citizens must wake up to the realities we face and take actions.
There is always a bull market here at The Bull Market Report! This week we highlight the following stocks: PayPal, Splunk, Microsoft, and Tesoro.
Highlights From The Past Week
US Bank earnings season started on Friday. Q2 earnings season for the banks kicked off on Friday morning with results from JP Morgan, Citigroup, Wells Fargo and PNC Financial. Some analysts have highlighted a more difficult setup for the group following a June rally on the back of higher bond yields and capital return announcements that beat elevated expectations. There have also been thoughts that earnings season could shift some of the focus back to the more challenging operating environment for the group. However, there really did not seem to be any meaningful discussion about downside risk to estimates. Analysts seem to be looking for the bulk of the support for Q2 to come from additional net interest margin expansion. This should offset sluggish loan growth and weaker capital markets (near double-digit declines). The latter dynamic has been widely discussed by bank executives and in the press and was a key driver of estimate reductions. Despite some pickup in concerns surrounding the Auto sector, credit is expected to remain benign. Analysts also highlighted expectations for another solid quarter of cost control. This is our first glimpse into the new earnings season.
More conjecture on ECB policy. There is further speculation on ECB policy where the ECB is likely to signal that it is gradually winding down its QE plan at its September 7th policy meeting, and President Draghi could use his appearance at the Fed Reserve's Jackson Hole conference in August to signal a policy shift. The ECB is wary of putting an end date to its QE plan. There is a need to retain flexibility in case the economic outlook sours and also the ECB wants to follow the Fed example of exiting the policy of retaining open-ended nature of program. A Reuters poll of over 75 economists showed consensus thinks the ECB is likely to shift away from ultra-easy policy in September. The Fed and ECB are two of the most powerful institutions in the world for capital markets. This is important stuff.
CBO says Trump budget would not balance. The Congressional Budget Office (CBO) said Trump’s fiscal 2018 budget would reduce the deficit by about a third over next decade. This is a smaller estimated deficit reduction than the White House forecast due to lower revenue projections. Trump’s budget would result in average GDP growth over next decade of 0.1% more than the CBO baseline. CBO also estimated that revenues under Trump’s budget would be almost $1 trillion lower than his estimates over the next decade. Trump budget's deficit reduction would stem from lower spending, including decreasing the $2 trillion base in mandatory spending, mostly from healthcare. Press reports said CBO’s findings creates new complications for Republicans who need to build a coalition of conservatives and moderates to vote for a single budget proposal. We need to start seeing some real progress out of the White House.
Britain acknowledges Brexit bill for the first time. Ahead of this week's Brexit talks between Brexit Secretary Davis and EU negotiator Barnier, a written statement was released to parliament, which acknowledged Britain has financial obligations to the EU, which will continue beyond Brexit. The Financial Times cited EU diplomats saying it goes further than UK Prime Minister May’s previous reference to Britain being willing to reach a “fair settlement” of unspecified obligations. It noted that Davis did not refer to financial issues when he released three position papers ahead of Brexit talks. The article pointed out that the British team sees the statement on financial obligations as an effort to improve the tone of talks rather than a change in substance. Meanwhile, at least 15 Conservative MPs are in talks with Labour on keeping Britain in the European Economic Area after Brexit, which would require accepting free movement of people and paying some money to the EU. The rationale for this approach is that it would give Britain time to reach a final deal with the EU and give certainty for businesses and workers. What a mess.
Dow, S&P 500 Hit Records to Close Winning Week
The S&P 500 hit a fresh record Friday and posted its best weekly performance since late May, and the Dow Industrials notched their third consecutive record close. Let’s keep this going!
Special Profile - Leon Black of Apollo
Private equity firm Apollo Global Management (APO: $27, up 3%) this week agreed to acquire ClubCorp Holdings, one of the largest owners and operators of private golf and country clubs in the United States, for $1.1 billion. ClubCorp owns and operates 200 golf, country, business, sports and alumni clubs in 28 states, Washington D.C. and two foreign countries,
The deal comes three months after ClubCorp announced the retirement of is CEO Eric Affeldt and said it had decided not to pursue a "strategic transaction," after efforts to explore a sale did not result in any offer for the entire company. So much for those thoughts!
Apollo said it will pay a 31% premium over its closing price on Friday, in cash for ClubCorp, a but less than the 12-month high the shares reached in February.
Who is the man behind the curtain? Apollo Chairman and CEO Leon Black. He founded Apollo in 1990 to manage investment capital on behalf of a group of institutional investors, focusing on corporate restructuring, leveraged buyouts, and taking minority positions in growth-oriented companies. From 1977 to 1990, Mr. Black worked at Drexel Burnham Lambert, where he served as Managing Director, head of the Mergers & Acquisitions Group and co-head of the Corporate Finance Department. He now serves on the boards of directors of Apollo Global Management, and The Partnership for New York City. Mr. Black is Co-chairman of The Museum of Modern Art, and a trustee of Mount Sinai Hospital, The Metropolitan Museum of Art, and The Asia Society. He is a member of The Council on Foreign Relations. Mr. Black is also a member of the board of FasterCures and the Port Authority Task Force. He graduated summa cum laude from Dartmouth College with a major in Philosophy and History and received an MBA from Harvard Business School.
BMR Take: This man is a powerhouse and the success of your investment in Apollo will depend on Mr. Black. We put him in that category of people like Elon Musk, Steve Jobs and Bill Gates. We are big believers.
BMR Companies & Commentary
PayPal (PYPL: $57, up 6% - new all-time high [NATH) set Friday)
The price target was raised to $70 from $54 at a research firm on the Street. PayPal is the firm's "top idea" for 2017, followed by Google (GOOG: $956, up $37, 4%). Coming opportunities with PayPal's Venmo and with partnerships caused the research firm to become even more bullish.
PayPal and Apple entered into an exciting major partnership this week that sent shares to all-time highs. PayPal and Apple have partnered to give users the ability to use PayPal as a payment method when paying for Apple’s services, which includes the App Store, Apple Music, and iTunes, to name a few. The feature will be introduced in 12 markets, including the US and the UK, and it will be integrated with several devices across Apple’s ecosystem, including the iPhone, iPod, Apple TV, and Apple Watch.
The immediate impact for PayPal is getting access to a massive revenue stream. Revenue from Apple services, which is mostly from the App Store, reached $7 billion in Q416, up 18% from last year. Although the financial terms of this deal have not been disclosed, we can estimate the potential impact. If PayPal were to charge Apple 1.25% per transaction, which is much lower than the 2.9% fee it often charges merchants, and if PayPal accounts for a third of spend on the App Store in 2017 — which will be based on consumers spending a total of $40 billion on the iOS App Store, according to Street sources — PayPal would see $165 million in revenue for 2017.
In the long run, PayPal’s partnership with Apple could give the firm an opportunity to integrate itself into additional Apple services. Over the last few years, Apple has indicated that it plans to turn its chat app, iMessage, into a robust ecosystem. The app now includes peer-to-peer payments, games, and other apps, with even more features coming in the fall with the launch of iOS 11. Although it hasn't been confirmed, it's reasonable to assume that one feature coming down the pipeline is the ability to buy products via iMessage. With PayPal already being a payment option within Apple's ecosystem, users may be more willing to use it going forward.
BMR Take: PayPal ranks among the best growth stories in all of technology and this Apple deal is just another reason as to why. Earnings are growing greater than 20% per year for as far as the eye can see and should break $3 by 2020.
Splunk (SPLK: $60, up 4.5%)
Splunk has come under some selling pressure and stock is still below the highs of the year at $69 set in May, providing yet another buying opportunity as the company exits this seasonal lull. In a market where the "FAAMG*" stocks and other rapidly growing tech companies are making all-time highs, Splunk is down 43% from its high made in 2014. This comes despite Splunk more than tripling its revenue in the last three years and consistently beating analyst expectations.
*FAAMG – Facebook, Apple, Amazon, Microsoft and Google
In our view, Splunk has been one of the most consistent companies over the years and one of the best pure-plays of the Big Data movement. In June, Splunk's growing importance in this market was on display at Cisco Live!, the Data Works Summit and the Cloud Expo. A prime example of Splunk's expanded importance is with Cisco, which is now indexing approximately 9-10 terabytes per day with Splunk versus 2 TB per day in 2015, significantly above the 300 GB of data per day in 2010.
After reporting strong April quarter results during its seasonally weakest quarter of the year, Splunk came under selling pressure in late May and still has not recovered from this downdraft. The market got hung up on "inconsistent performance" during the April quarter that resulted in a leadership change, while license revenue missed forecasts given the strength in the company's cloud business that drove big upside in maintenance and services revenue. As Splunk begins to head into the stronger part of the year, we believe the stock can play catch-up.
Given rising security threats, including the WannaCry Ransomware attack in May, Splunk introduced Splunk Insights for Ransomware in late June. This new offering allows smaller organizations (they offer user-based pricing for up to 1,000 employees) to fight malware in real time with a cost-effective solution.
BMR Take: By leveraging a proprietary machine data technology to turn data into real-time operational intelligence, Splunk is benefiting from its position as a pioneer and leader in the world of machine data with its core software platform called Splunk Enterprise. We see substantial upside for the stock as the current valuation is only 6x revenue versus a high-water market of 28x. We’re up 29% on the stock in a little over a year, but we would await even better returns this next six months as the market comes to recognize how strong the company is.
Microsoft (MSFT: $73, up 5%, setting a NATH* on Friday)
Early in the week Microsoft proposed a $10 billion effort to bring broadband internet to the rural U.S., an economic-development program aimed at a core constituency of the Trump administration. The plan, which calls for corporate and government cash, would send internet data over unused broadcast frequencies set aside for television channels. If developed, the initiative would help connect 23 million Americans in rural areas who lack high-speed internet access.
*NATH - New All-Time High
Broadband is important for all kinds of things. It’s not just streaming high-definition movies. Slow or nonexistent connections can hinder agriculture, business, education and healthcare. Broadband is arguable now a necessity of life. Microsoft’s proposal calls for a 5-year program of corporate investment and matching federal and state grants to end the gap between rural and urban access, starting with the company’s own efforts. The aim of Microsoft’s new Rural Airband Initiative is to be up and running in 12 states by next year and connect 2 million people over the next five years.
BMR Take: Doing big things like what is described above is why Microsoft is not just a tech titan, but a leader amongst the entire S&P 500. News like this continues to push the stock toward 20x consensus estimates of $4 per share of free cash flow. Do the math – that’s $80 a share.
Tesoro (TSO: $97, up 1%)
Tesoro has been a big winner and it could keep getting better. This week the company announced plans to study the possibility of turning vegetable oil into diesel fuel at its Dickinson refinery, which it purchased in 2016.
The crude oil refiner is making plans to retrofit an 8,000-barrel-per-day diesel hydrotreater to process soy and corn oil into renewable diesel alongside its Bakken crude oil processing. This $3.5 million project would use 17,000 gallons per day of vegetable oils to create a 5% renewable diesel mix to be marketed in North Dakota by the end of 2017. The North Dakota Industrial Commission granted the company a $500,000 grant to help cover the project's cost.
Compared to biodiesel that is blended into petroleum diesel at truck racks, renewable diesel is a superior quality product because, unlike biodiesel, renewable diesel is a pure hydrocarbon stream containing no oxygen. This results in a superior quality fuel that maintains vehicle performance. The company says the project is “unique and exciting.” Of course they do!
BMR Take: The stock continues to trade at a big discount to the consensus NAV* estimate of $120. In comparison, Buffet’s ownership of peer Phillips66 is valued at a premium to NAV in the market. Disconnect that the market will correct down the road? We think so. Tesoro still looks compelling to us even after the recent appreciation.
*NAV – net asset value
Upcoming Economic News
Export Price Index
Tuesday, July 18th, 8:30 AM
Period: June
Consensus: 0.05%
Prior: -0.70%
Note: The U.S. Bureau of Labor Statistics' International Price Program produces Import Price Indexes (MPI) and Export Price Indexes (XPI) containing data on changes in the prices of nonmilitary goods and services traded between the U.S. and the rest of the world.
Housing Starts
Wednesday, July 19th, 8:30 AM
Period: June
Consensus: 1,146,000
Prior: 1,092,000
Note: The number of housing units started in the United States.
Leading Economic Index
Thursday, July 20th, 10:00 AM
Period: June
Consensus: +0.30%
Prior: +0.30%
Note: The Conference Board Leading Economic Index (LEI) for the U.S. increased 0.3% in May to 127.0 (2010 = 100, following a 0.2% increase in April, and a 0.4% increase in March. Leading Indicators are economic series that tend to change direction ahead of shifts in the business cycle. There are 10 components of the U.S. Leading Composite Indicator* published by The Conference Board. The index is constructed by averaging the individual components in order to smooth out a good part of the volatility of the individual series. Historically, the cyclical turning points in the leading index have occurred before those in aggregate economic activity. Prior to 1996, the composite leading, coincident, and lagging indicators were calculated and published by the U.S. Department of Commerce.
* Average weekly hours, manufacturing
Average weekly initial claims for unemployment insurance
Manufacturers’ new orders, consumer goods and materials
ISM Index of New Orders
Manufacturers' new orders, non-defense capital goods excluding aircraft orders
Building permits, new private housing units
Stock prices, 500 common stocks
Leading Credit Index
Interest rate spread, 10-year Treasury bonds less federal funds
Average consumer expectations for business conditions
A Word From Gary Jefferson
First Vice-President, Investments
UBS Financial Services, Inc.
Q2 GDP estimate - +2.7%. Anything above 2% is a real plus after eight years of mostly sub -2%, and should provide the momentum needed to get to the 3%+ level.
222,000 jobs added versus 170,000 expected – A lot more should come with passage of any of the three main Trump growth initiatives.
57.8 ISM - Manufacturing is highest since 2014 – This is just what the doctor ordered!
57.4 ISM Services is nice. 60.8 forward-looking New Orders component is even nicer.
None of this means the economy is safe forever. Another recession is inevitable. But what these stats are telling us is that it's just not coming anytime soon.
We still like the Technology, Healthcare, and Financial sectors. While some folks think some of the Tech stocks are bubbly, we agree with those who simply ask about why Tech has led, and if anything has changed. The answers are "earnings" and "no"………. or how about, "FANG is dead – long live FAAMG". [We think you might have to read this last paragraph a few times to get his point!]
2nd Quarter earnings season starts this week. If it lives up to expectations we shouldn't even have to worry about a pullback. Right now, the stats favor another good earnings session. We don't expect the Fed to raise rates until September, and that will depend on how year-end earnings guidance looks. The two dates which will probably have as much if not greater effect on the market are September 5th and 30th. If nothing gets done in Washington before the August recess on September 5th, it could signal the end of any chance for growth stimulus to happen this year. That will likely create a fairly strong headwind. On September 30th, government funding expires. Hopefully we won't have to endure another ridiculous dog-and-pony show in Washington and this will not become a major distraction for investors.
An Interview with Tim Cook
We read a lengthy interview of Apple CEO Tim Cook by Bloomberg Businessweek Editor Megan Murphy. We thought the following few paragraphs from it were particularly insightful:
Murphy: I was a little surprised the HomePod was pitched primarily as a music device when the competitive talk is of Amazon Echo’s Alexa and the immersive experience in the home. How will the HomePod better integrate Apple inside people’s lives?
Cook: We’re actually already in the home through the iPhone you take with you everywhere. It’s in your pocket or laying on a stand. Today, pre-HomePod, I can control my home using Siri through the iPhone. When I get up in the morning, my iPhone is my alarm clock. I say, “Good morning,” and all of a sudden, my lights come on. The temperature adjusts and a series of things occur. We’re also in the home through Apple TV. Many people use iPad as their computing device. The desktop Mac enjoys a place in the home. The thing that has arguably not gotten a great level of focus is music in the home. So we decided we would combine great sound and an intelligent speaker.
Murphy: So, it’s going to be a holistic process joining up all those touch points so people can exercise control over their lives, whether through Siri or iPad?
Cook: To put it in perspective, Siri is getting requests from 375 million devices right now. My guess is it’s the largest by far of any kind of assistant. Some of those requests are done in the home. Some of those are done on the go. That’s the platform that we build off. It’s very different from our starting point. We’re also in so many languages around the world: Siri isn’t just in English. We’re well-positioned around the world. So, again, what is the thing that’s missing in this equation? The combination of quality audio and instinct.
“I am so excited about it, I just want to yell out and scream”
Murphy: Do you think people will pay $349?
Cook: If you remember when the iPod was introduced, a lot of people said, “Why would anybody pay $399 for an MP3 player?” And when iPhone was announced, it was, “Is anybody gonna pay - whatever it was at that time - for an iPhone?” The iPad went through the same thing. We have a pretty good track record of giving people something that they may not have known that they wanted.
When I was growing up, audio was No. 1 on the list of things that you had to have. You were jammin’ out on your stereo. Audio is still really important in all age groups, not just for kids. We’re hitting on something people will be delighted with. It’s gonna blow them away. It’s gonna rock the house.
BMR Take: We were pleased to see Tim Cook’s responses for two reasons. 1) the iPhone is already the home controller of choice. We knew this, but Cook really put it in perspective. And 2) The takeover of a market is Apple’s modus operandi. Start late with a high price. Then lower prices and dominate. We have no doubt the home assistant will be any different. Amazon – watch out.
Nutanix Has a Rip-Roaring Week
The stock of Nutanix (NTNX: $22) was up 16% last week. We’ve been harping on this stock for weeks, and then along comes Goldman Sachs and says Nutanix is a “once-in-a-decade” opportunity and are looking for a $31 Target. Our Price Target is $30. Is Goldman reading The Bull Market Report? We certainly think so.
We’re already up 27% in the six weeks since we added the stock in late May. And we expect more good things from the company in the future. Nutanix is the leader in hyperconverged infrastructure, meaning it uses software to combine different storage and computing functions on one device. That space has been heating up among enterprises. More businesses are looking to adapt the technology, with 18% of chief information officers saying they expect to move to hyperconverged systems in the next two years, according to Goldman Sachs.
The company’s leadership in the space, including the combination of hardware and software it offers, makes it a “once-in-a-decade tech infrastructure story,” wrote the lead Goldman analyst on the note. They see Nutanix on a path for long-term double-digit growth, high gross margins and large operating leverage.
Additionally, in the shorter-term, Nutanix should benefit from changed accounting rules that will move its software revenues, which are currently deferred, to its profit and loss statement.
BMR Take: What more can we say? All good.
First Solar Continues its Tear
First Solar (FSLR: $43) was up another 9% this past week. We’re still down 30% or so on the stock but we are big believers in the company and management. Our timing on the addition to the Special Opportunities portfolio was bad. But we believe we will be winners in the long run. The stock is up over 55% in the last three months. Keep hanging in there.
Twilio Hanging in There
Twilio (TWLO: $29, up 3%) had a good week. It’s down from where we added it for sure, but slowly creeping back up as the Street slowly begins to realize the potential of this company. We are again looking for another strong revenue quarter in early August when they announce. That will show the Street!
Apple Back Up To $150.
Almost. Closed at $149, up $5 for the week. The market just can’t keep this one down. We sincerely hope you have some of this wonderful firm. You think it’s too high. Not on your life.
Annaly Just Keeps Chugging Along
And it is paying 10% a year in dividends. Annaly Capital Management (NLY: $12.33) added 2% last week. The stock has been paying double-digit dividends since inception in 1997. That’s right – 20 years. Where will the stock be in a year? Good question. We would say right about at this level, after paying another four quarterly dividends of 30 cents each. Do the math – that’s a shade under a 10% return. We love this one.
The High Yield Corner
By Michael Foster
Special to The Bull Market Report
We’re getting close to earnings season for Healthcare REITs, and the market’s expectations seem to be getting increasingly bullish. Over the last week, all of The Bull Market Report’s Healthcare REIT picks were in the green, with Omega Healthcare Investors (OHI: $33) leading the pack with a 2% gain for the week. That’s pushed the stock’s year-to-date performance much higher, with a 7% gain on top of half of the fund’s 8% dividend yield. There’s been a relatively low amount of volatility in Omega Healthcare relative to what we saw both in 2015 (where rate hike fears hit all REITs) and 2016 (when the REIT bull market suddenly corrected at the end of the year).
But what about the upcoming earnings report on July 27th? So far, analysts are expecting 86 cent FFO for the quarter, up from 83 cents from a year ago. The company has reaffirmed their 86 cent guidance as recently as early May, bringing the stock’s dividend coverage ratio to 134% if they hit the number. Gotta love it.
Before we discuss whether they will hit it or not, let’s take a quick look at Welltower (HCN: $74, up 1%), which had a similarly strong week and is also planning to release earnings soon - on July 28th before the market open. Welltower has far outperformed Omega for 2017, with a 10% price jump - although the lower dividend (5%) mostly offsets this. Like Omega Healthcare, Welltower is showing strikingly little volatility as of late, a development that makes a lot of sense given Welltower’s tremendous track record and strong dividend coverage. However, it’s surprising to see that Welltower’s dividend coverage is a shade lower than Omega’s at 128%. While that’s still good (general rule of thumb: any number over 115% is good for a REIT), it’s interesting to see how the dividend coverage ratio has slipped in the last couple of years as a result of falling funds from operations. Welltower’s earnings were down 6% from a year ago last quarter, and guidance suggests that decline is set to continue. But Welltower is also increasing dividends, which is a setup for a worrisome dynamic in which, eventually, the company will under-earn its dividend. How soon could that happen? At the current clip we’re safe for another 3-4 years, but the company clearly needs to adapt, lest it find itself suddenly in a position to halt or even cut dividends. For this reason, the company’s earnings results on the 28th and especially its forward guidance will be a key issue to watch for. We will keep a close eye on this.
Finally, Sabra Health Care REIT (SBRA: $23) had a flat week (up less than 1%) despite being one of the smallest Healthcare REITs in terms of market cap and property footprint. It’s quite unusual to see the smaller stock be less volatile than its bigger cousins, but Sabra is one of the less popular REITs out there (investors, especially retail investors, spend a lot more time focusing on Omega), and there was little news on the stock to justify much price action. On top of that, the company’s massive underperformance relative to its peers has soured a lot of investors on the company, while fundamental investors know this is a very good company with strong dividend coverage and growth potential.
So, if you have few sellers and few buyers, you end up with little price change. But how is Sabra doing as we near its earnings release at the end of July? Over the last 12 months, earnings have been weak relative to expectations, with two misses out of the last four quarters. But dividend coverage is impressive, at 132%. Some investors may be a bit concerned about the company’s relatively weak revenue growth, but it’s important to remember that Sabra is pausing on acquisitions right now and reorganizing its new property portfolio additions to maximize income. This process naturally makes revenue look bad, which again is why impatient investors have shied away. Nonetheless, the ongoing restructuring continues to be successful, as the strong dividend coverage ratio proves. Expect to see good things from Sabra in the future that will help the stock recover, but we may not see those developments for a year or more. For investors, that means sitting tight with your Sabra shares, collecting a 7% dividend while you wait for the market to catch up.
Now, with upcoming earnings for these stocks, we need to ask ourselves the likelihood of them hitting their numbers. While there are differences in each company that makes some stronger than others, the broader issue that impacts all of them is the regulatory overhang. A lot of chatter about the future of Obamacare and plans from the Republicans and President Trump to change or obliterate current regulations has left a lot of investors skittish on Healthcare for a long time. But interestingly, we’ve seen the market swiftly realize how silly these concerns are - at least as it impacts the Biopharma sector, which is up solidly for 2017 and is beating the S&P 500. But why isn’t that same relief coming to Healthcare REITs with the same speed?
Simply put, REIT investors are far more risk averse as a group, and they are much slower to recognize a change in the political landscape than growth stock investors. This puts those holding Healthcare REITs in the awkward position of needing to be patient. However, it is clear that there is little change to the regulatory environment coming, and some analysts are already noting that recent GOP proposals to change Obamacare actually look a lot like Obamacare. Whatever your political leanings and opinions on the subject, it seems pretty clear that the status quo isn’t going to change anytime soon.
Again, no matter your opinions on the growing D.C.-based controversies, there is a clear conclusion: Healthcare as it operates in America is not about to change anytime soon. Healthcare REITs have been discounted for a change that would negatively impact them. Putting these together, it’s a clear time to buy or to continue to hold Healthcare REITs both before and after the upcoming earnings season.
Good Investing,
Todd Shaver, Founder, Editor and CEO
The Bull Market Report
Since 1998
