September 4, 2017
by Todd Shaver | Sep 4, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
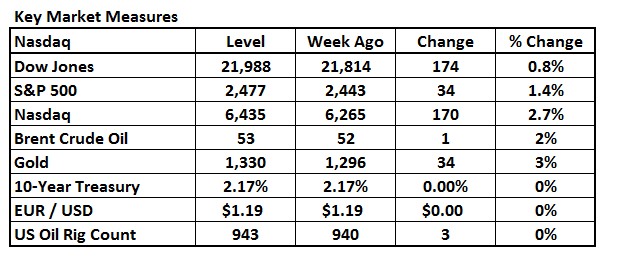
We sadly observed Hurricane Harvey devastate Texas this past week. 52,000 people are in shelters as thousands of homes are flooded. The state of Texas ranks as the 2nd largest contributor to GDP in the US trailing only California and ahead of New York. So the economic impact has yet to be fully seen. Real estate portfolios caught without flood and business disruption insurance may be seriously in trouble. Auto sales are already seeing a sizeable dip. Chemical plants are shut down. We could go on and on. What an unfortunately troublesome situation to watch and one with the potential for lingering negative impacts for months to come.
In other news, lawmakers decide to give bipartisanship a shot on healthcare. The Senate Health Committee will turn its attention to bipartisan legislation aimed at shoring up Obamacare markets for 2018. The drift toward compromise follows high profile repeal failures, but still faces an uphill battle as many Republicans have spent years railing against the health law. Staff has been working on it over the summer break and there is general agreement that insurer payments will continue, though specifics are sparse.
Separately, we have yet to see formal action following Trump’s opioid emergency declaration. No formal paperwork has been filed and no new policies have been announced. This appears to be new territory for the government as the national emergency designation is typically used for relief of temporary issues like natural disasters rather than chronic problems like opioid abuse. In addition, administration officials seem to have been caught off guard by Trump's statement. The White House has indicated that it is considering all options for action. Why should we care? This is a big deal for labor force participation, which is at historical lows. If we can get everybody back to work contributing to our economy and off drugs, that is the path to 3.0% GDP growth versus where we are now at 1-2%.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks where we think you can still make good money, including: Apple, Gilead, Bristol-Myers, Amazon, and PayPal.
BMR Companies and Commentary
Apple (AAPL: $164, up 1.5%, all prices are for the week)
Apple has officially scheduled its first-ever event in the company's Steve Jobs Theater, a September 12th invitation-only press conference expected to reveal the latest iPhones and possibly a revamped Watch and Apple TV. The company emailed invitations Thursday that read "Let's meet at our place," with an picture of an Apple logo in red, white and blue. The event, hosted at the company's new spaceship-style Apple Park headquarters is scheduled to start at 1 PM ET. For several years, Apple has revealed its latest iPhones in September, in time to promote them for the holiday season. This year, 10 years after the first iPhone hit the market, Apple is widely expected to reveal the iPhone 8, and the rumor mill has already churned out reports that the device will have a larger OLED* screen and a virtual home button. There are also reports Apple will reveal a Watch that has its own cellular connection and an Apple TV that adds 4K UHD. This is likely it—the big event for Apple’s new iPhone launch! We will all be watching closely.
* Organic light-emitting diode. An OLED display works without a backlight; thus, it can display deep black levels and can be thinner and lighter than a liquid crystal display (LCD). In low ambient light conditions (such as a dark room), an OLED screen can achieve a higher contrast ratio than an LCD.
The main risk to keep an eye on is prices. The argument is that costs are getting so high on new smartphones that customers will not be willing to keep paying up to get them. If this is so, we will see margin compression and perhaps fewer sales by Apple.
Apple Consensus on the Street
Apple was upgraded by analysts at Cleveland Research from a “neutral” rating to a “buy” rating in a report released on Tuesday, and they raised their price target to $197.
On the Street there are 10 Hold Ratings, 39 Buy Ratings, 1 Strong Buy Rating
9/1/2017 Royal Bank Of Canada Target: $180
8/29/2017 Cleveland Research Target: $197
8/24/2017 Bank of America Target: $180
8/24/2017 Drexel Hamilton Target: $208
8/22/2017 Canaccord Genuity Target: $180
8/14/2017 Sanford C. Bernstein Target: $175
BMR Take: Remember the big story for Apple is their services business. They have all these iPhones out there in use by a huge customer base. Can they now get more money from these customers through services? The iPhone 8 is a key part of the strategy. We note that Apple has $260 billion in cash now, which is the equivalent of $50 a share, and greater than 30% of the stock price. This is UNPRECEDENTED in the history of Wall Street. Apple remains an exciting investment opportunity. The services business is projected to double in revenue to $50 billion over the next several years. The Services business is much more profitable than hardware so the impact to earnings is even better. Don’t sell a share. We believe Apple has a lot more room to go on the upside.
Gilead Sciences (GILD: $84)
We removed Gilead from our Healthcare portfolio in February after holding them for a year with poor results. Things have changed dramatically since that time as management has tackled various issues head-on, so we give you an update as things have changed even more this past week.
Gilead announced a big acquisition. Gilead will acquire Kite Pharma for about $12 billion in cash; it was unanimously approved by both the Gilead and Kite Boards of Directors and is anticipated to close in the fourth quarter of 2017. The transaction will provide opportunities for diversification of revenues, and is expected to be neutral to earnings by year three and accretive thereafter.
The acquisition of Kite establishes Gilead as a leader in cellular therapy and provides a foundation from which to drive continued innovation for people with advanced cancers. We are greatly impressed with the Kite team and what they have accomplished, and believe they are on the cutting edge of cell therapy that will be the cornerstone of treating cancer. The field of cell therapy has advanced very quickly, to the point where the science and technology have opened a clear path toward a potential cure for patients. The two company’s similar cultures and histories of driving rapid innovation in order to bring more effective and safer products to as many patients as possible make this an excellent strategic fit.
BMR Take: Gilead is losing two major drugs this year with big revenues due to the expiration of their patents and was the reason we removed the stock earlier this year . Over the past several years they were among the largest sellers in the history of Healthcare so replacing them will be a tough uphill climb. Could Kite provide a way to do it? We will see.
Bristol-Myers Squibb (BMY: $60, up 3%)
This week Bristol-Myers will announce more than 60 presentations, including seven late-breaking abstracts, from its Oncology portfolio featured at the European Society for Medical Oncology 2017 Congress in Spain. Presentations of data from company-sponsored studies, clinical collaborations and research will explore the potential role of Opdivo (nivolumab) as monotherapy and in combination with Yervoy (ipilimumab) and with relatlimab, a fully human monoclonal antibody that targets lymphocyte activation gene-3 (LAG-3); or with chemotherapy in 13 types of cancer.
All this news matters a lot because healthcare investors love new data! We are seeing the stock pick up some momentum getting ready for what is likely to be a wave of good news.
BMR Take: We are still optimistic Bristol-Myers could be a take-out candidate. Activist investor Carl Icahn is in the stock and pushing for change. We believe we could see a 25-50% premium from today’s price if a sale gets done. Further supporting our view, we note Jana Partners is now also building a position in the stock. Jana had a big stake in Whole Foods, and was taken out by Amazon this past week as you know.
Amazon (AMZN: $978, up 4%)
Amazon announced 3,000 more jobs coming to Ohio. This follows news a few weeks ago about doing a major facility in New Jersey. We continue to highlight the Amazon machine because this single company alone is now a major driving force behind the economy.
The internet retailer received approval on Wednesday for state tax incentives for two distribution operations in Ohio. The project approved by the Ohio Tax Credit Authority will create 2,000 jobs. The company said it will invest $100 million at the site, which eventually will result in a 855,000 square-foot facility. The second distribution-center project, will result in an estimated 1,000 jobs if the company goes ahead with the project. Amazon had no presence in the state until recently.
BMR Take: The Amazon powerhouse is steamrolling the real economy and the stock market. With over $20 of EPS potential by 2020 according to analyst consensus estimates, we see a lot of potential ahead.
We noticed that the stock is on a little roll lately. The stock hit a closing high of $1052 a month ago in late July and then proceeded to drop over $140 to the low 900s. But this week the stock was up a little bit every day until Friday when it took a breather. We have watched these high-priced stocks for years and many times it is human nature to not be able to bring yourself to buy a stock that is almost $1000 a share. But we always mentally build in a stock split. Say 10-1 in Amazon’s case. If the stock were a $98 stock, would you buy 100 shares? Sure you would. So we just look to buy 10 shares for $980. Same difference. If you think the stock is going to $2000 a share in the future like we do, 10 shares here, 20 shares there, and 30 shares beyond, adds up to real money.
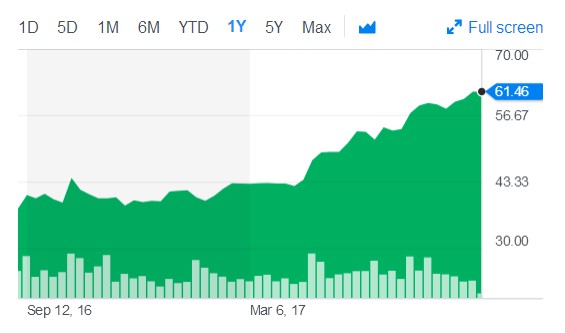
PayPal (PYPL: $61, up 2.5%)
PayPal customers in the U.S. can now earn cash back on every purchase online and in stores with the recent launch of the new PayPal Cashback Mastercard issued by Synchrony Bank. The PayPal Cashback Mastercard, designed exclusively for PayPal members, offers cardholders 2% cash back every day, on every purchase – everywhere Mastercard is accepted.
Unlike other rewards credit cards, there is no annual cash back limit, no minimum redemption amount, no restriction on how to spend cash rewards and no expiration. The PayPal Cashback Mastercard offers all the security and convenience expected from PayPal, plus all the traditional benefits of a Mastercard. All accounts are automatically added to the member’s PayPal wallet to simplify checkout and provide peace of mind.
The introduction of the PayPal Cashback Mastercard with Synchrony Bank continues PayPal’s commitment to provide customers with rewarding product experiences and a range of innovative credit options. By providing a simple way for people to earn cash rewards for the shopping they’re already doing, the PayPal Cashback Mastercard will give consumers yet another reason to shop with PayPal.
BMR Take: PayPal has 200 million customers on the way to over 1 billion longer-term (after all, Facebook has over 2 billion, showing the possibilities for a global internet-based business model). With EPS closing in on $3 by 2020, and EPS growth moving along in the mid-teens, we see growth at a reasonable price here in the stock and like it a lot!
Nutanix (NTNX: $22, flat)
We reported via News Flash on Friday on the stellar earnings report the company issued on Thursday. The stock shot higher on Friday, hitting $24, but settled at $22, flat for the week. We’re not traders as you know, but long term investors, and we have seen this many times in our career. We are going out on a limb here and will say that the stock will move higher from here over the coming weeks and months.
We mentioned the high level of sales that were booked but not reported as revenues – the backlog. Management indicated that billings growth was 40% year over year and that the company continued to build up a significant backlog of deals that booked but did not ship in the quarter. The sales transition toward large enterprise is progressing nicely. Management's next quarter guidance implies billings growth of 25% YoY compared to consensus of 17%, due to the significant backlog build.
To recap:
Fiscal 4Q 2017 Financials
Revenue: $226 million, up 62% year-over-year from $140 million in 4Q16
Net Loss: $50 million, compared to a net loss of $47 million in 4Q16
Operating Cash Flow: $6 million, compared to $2.5 million in 4Q16
Cash and Short-term Investments: $350 million, up 90% from 4Q16
Deferred Revenue: $525 million, up 77% from 4Q16*
Free Cash Flow: $(6.5) million, compared to $(6.5) million in the fourth quarter of fiscal 2016
Billings: $289 million, growing 40% year-over-year from $207 million in 4Q16
BMR Take: We added the stock in May at $17.45 and have a Target of $30. Our Sell Price at $14 is way too low, so we hereby raise it to $19. This was a great quarter and if Wall Street doesn’t wake up to the potential of this company, we would be very surprised.
Upcoming Economic News
Domestic Auto Sales
Monday, September 4th, 8:00 AM ET
Period: August
Consensus: 4.6 Million
Prior: 4.5 Million
Trade Balance
Wednesday, September 6th, 8:30 AM
Period: July
Consensus: -$44.5 billion
Prior: -$43.6 billion
Initial Claims
Thursday, September 7th, 8:30 AM
Period: 09/02
Consensus: 240,000
Prior: 236,000
Consumer Credit
Friday, September 8th, 3:00 PM
Period: July
Consensus: $15.0 billion
Prior: $12.4 billion
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
Over the previous weekend, these were the economic headlines:
--- Robust Retail Sales
--- Disappointing Durable Goods
--- Strong Business Inventories
--- Uneven Industrial Activity
--- Mixed Housing Data
Economic data suggests that things are good, but not great.
Fed Chair Janet Yellen's signaling of continued restraint on monetary policy at Jackson Hole triggered another rally in US stocks last week. This extends the current bull market to 102 months, surpassed in length only by the 113-month run leading up to the dotcom crash. Skepticism over valuations is even higher now with a record 46% of investors believing equities are overvalued.
While the bull market may be entering the later stages of the cycle, UBS strategists believe it can run further based on these observations:
--- The earnings yield on the S&P 500 is 4.8% compared with a yield of 2.17% for 10-year Treasuries.
--- At 18x, current market PE ratio is near long-term averages. Historically when valuations have been in an 18x to 23x range, the MSCI AC World Index has returned 6% over the subsequent six months (versus an overall average of 5%). And relative valuations of equities also suggest long-term outperformance versus bonds.
--- Corporate earnings growth remains robust, at 12% in the US and around 10% in the Eurozone in the last quarter. Synchronized global growth should continue to support this, with all 45 OECD economies on track to expand this year.
There are, however, some caution flags appearing here and there. We prefer to look at price-to-sales ratios rather than PE's, and they haven't been this high since the peak of the dotcom bubble in 1999. This means that new investors are paying more for every dollar of sales than at almost any time since the dotcom bust. However, if sales continue to grow as expected this ratio will normalize to some degree. Put another way, stocks are priced almost to perfection and if the earnings growth story were to falter, it could cause some real volatility.
VMware (VMW: $107, up 5%) Has 500,000 Customers
BMR Take: Think about this. Half a million customers. Can you imagine? We think this is just fabulous. We’re up 30% since we added them in January at $83. What a great company. Our Target is $108 which it hit Friday, an all-time high (not counting the euphoria 10 years ago when they went public). With a market cap of $44 billion, and Dell Technologies being the principal owner (80%+) we think very highly of this company. So we hereby raise our Target to $120 and raise the Sell Price from $90 to $100.
The Blackstone Group (BX: $33, up 4%) had its Target Price set at Credit Suisse Group at $45
A Few Wall Street research firm targets
8/30/2017 Credit Suisse Group $45
7/25/2017 Morgan Stanley $40
7/21/2017 Deutsche Bank $33
7/14/2017 Keefe, Bruyette & Woods $37
7/14/2017 Oppenheimer Holdings $38
5/28/2017 Citigroup $41
Blackstone Considers IPO of Gates Corp.
Blackstone Group is considering an initial public offering of Gates Corp. that could value the auto-parts maker at as much as $9 billion. Its products include belts, hoses, industrial power transmission, fluid power, and automotive. The company was founded by Charles Gates in 1911 and is headquartered in Denver. In 2014, the company was acquired by Blackstone in a deal worth $5.4 billion.
The private-equity giant is in the early stages of laying the groundwork for the possible offering, according to people familiar with the matter. The business could be worth $8 billion to $9 billion, one of the people said. It isn't clear whether that includes debt.
BMR Take: We can’t tell you how good this company is. Well, maybe we can: This company is great! Look at the wealth being created by this firm. In 3-4 years in this one deal alone, they have created $3-4 billion of equity. Absolutely amazing. Our Target is $35 but we are dying for the stock to hit this price so we can raise it to $42. This is a value stock like no other.
The High Yield Corner
By Michael Foster
Significant news came this week from AstraZeneca (AZN: $30, up 3%), helping the shares rise solidly by the end of the week. The biggest news is the company’s presentations at a conference in Spain that will demonstrate the company’s phase-3 study of imfinzi for non-small cell lung cancer and tagrisso for. EGFR cancers.* The science is complex and far for non-specialists to understand without a lot of deep reading, but the market is a great place because it prices in that knowledge instantaneously, which is why AstraZeneca shares rose 2% on the news.
* EGFR is short for estimated glomerular filtration rate. The EGFR is a number based on your blood test for creatinine, a waste product in your blood. It tells how well your kidneys are working.
Another intriguing tidbit from AstraZeneca: the company announced on Tuesday that it was recruiting Takeda Pharmaceutical to work on an antibody for Parkinson’s disease treatment. Again, more exciting developments that prove the mega-pharma company’s pipeline is very healthy. Remember a year ago when this was a primary concern on the company and thus the stock? Those concerns are gone now; instead, investors have finally realized that there is tremendous value in this company and it is still innovating; thus it’s no surprise shares are up 10% in 2017 so far. Paying a solid 3.1% dividend, we can see some dividend increases in the months and years ahead. We’ve got a $42 Price Target on the stock and would hope to see this level sometime next year.
Elsewhere in The Bull Market Report High Yield portfolio we see green across the board. There’s only one exception: Invesco Municipal Trust (VKQ: $12.93), which ended the week flat. No surprise; municipal bonds are a low volatility asset class, and there’s not really any news in the municipal bond market to warrant a massive jump. That includes the latest tragedy in Texas. While large storms and ecological disaster might intuitively seem like they will hurt municipal bond markets (lower economic activity should mean lower government revenue and thus higher default risks), it’s important to remember that this “common sense” is actually false. (Often, the common sense view doesn’t quite work in finance.) In reality, credit agencies do not downgrade bond issuers faced with economic disasters; furthermore, the lower revenue may make the state’s budget tighter in the short term, but the risk of that hurting municipal bonds is negligible. Additionally, natural disasters rarely result in massive new bond issuances to fund repairs, so it’s not like existing bonds will get priced out by new issues.
We saw Nuveen AMT-Free Municipal Credit Fund (NVG: $15. 64, up 1%) have a solid showing. Also a nice surprise from Nuveen this week: the company announced dividends for all of its closed-end funds, but did not lower dividends on NVG - although many other funds did see their distributions decline slightly. Again, good news for municipal bond investors long this fund.
The Bull Market Report’s other closed-end fund picks also ended the week in the green and announced distributions that were in-line with previous dividends. AllianzGI Equity & Convertible Fund (NIE: $20, up 1%) announced that its 38 cent quarterly dividend would continue at the same level, and PIMCO Dynamic Income Fund (PDI: $30, up 1%) also announced its monthly dividend would stay at the same level. These funds are paying 8% in income, year-in and year-out, while also seeing their share prices rise. Closed-end funds are typically income vehicles that aren’t often traded for short-term capital gains, but both funds have given investors that opportunity this year. AllianzGI is up 10% year-to-date and Pimco Dynamic is up 14% year-to-date - extremely impressive returns for such diversified funds. And the income does not look to be threatened anytime soon, so investors can continue to hold them with confidence.
Now, let’s turn to REITs. Digital Realty Trust (DLR: $118, flat) announced that its COO was leaving the company in September. Markets shrugged; while he obviously has done well for the company in the past, there’s no reason to assume he’s irreplaceable. We’re sure that his replacement will be skillful.
Despite little news elsewhere affecting REITs, we saw price gains for Omega Healthcare Investors (OHI: $32, up 3%), Government Properties Income Trust (GOV: $18.50, up 1%), Apollo Commercial Real Estate (ARI: $18.18, up 2%), Ventas (VTR: $69, up 1%), and Welltower (HCN: $74, up 2%).
Also, there wasn’t any real news on Kimco Realty (KIM: $20, flat), but it’s interesting to note that this retail-focused REIT has had a bit of a resurgence lately thanks to the surprising strength in retail. (Note that we removed Kimco from our portfolio in May, but we wanted to give you an update.) If you remember, several weeks ago in this column we wrote at length at how the “death of retail” cliché was really more about shock financial journalism trying to get clicks from disaster-starved readers and had little to do with the reality of our economy. Well, we were right. In addition to beats from Macy’s, Dollar General, Target, Wal-Mart, and several other retailers, even the near-death dogs like Sears Holdings and Abercrombie & Fitch impressed the market with their quarterly results, beating expectations. Retail is not the healthiest sector on Earth, but it isn’t dead or dying. But Kimco was priced for a dying retail sector. So what does that mean? Kimco shares are up 11% in the last three months.
We want to go on record with another prediction that drives bullishness on retail REITs like Kimco. Amazon’s recent acquisition of Whole Foods and their price drop at the supermarket is going to drive retail sales for two reasons. Firstly, Amazon Prime members will be incentivized to leave their computers and shop in person more. Secondly, more people can now afford Whole Foods and will shop there. That also means people are going to spend more time shopping at auxiliary stores adjacent to Whole Foods. This is a rising tide that is going to lift many boats, which is why buying retail REITs right now makes a lot of sense. Check back in after about six months and see if we’re right.
Good investing,
Todd Shaver, CEO, Founder and Editor
The Bull Market Report
Since 1998
August 27, 2017
by Todd Shaver | Aug 27, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
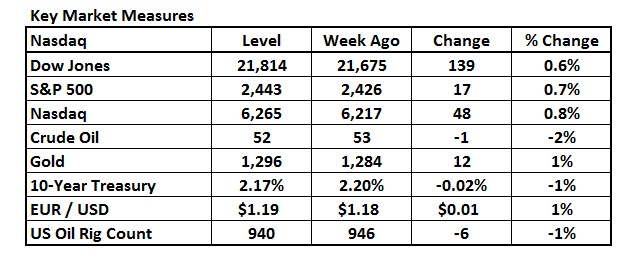
What a week. So much for a quiet end to the summer. Yellen made perhaps her final speech in Jackson Hole. Trump is battling a debt ceiling to fund The Wall. And the markets are partying like it’s 1999!
Federal Reserve Chair Janet Yellen, speaking in Jackson Hole, Wyoming, on Friday, issued her broadest defense so far of the government’s response to the 2008 financial-market meltdown while outlining some areas that regulators could review to improve efficiency in the financial system. “Any adjustments to the regulatory framework should be modest and preserve the increase in resilience at large dealers and banks associated with the reforms put in place in recent years,” Yellen said, in what could be her final speech as Fed chair at the annual gathering of central bankers. Her term expires in February.
President Donald Trump is spoiling for a fight with Congress over funding a border wall with Mexico, but he’ll have a hard time waging that battle because of a looming deadline to avert a U.S. debt default. Some of the president’s advisers consider a tough stand on border wall funding crucial to Trump’s credibility, two White House officials said. Some say that failure to make progress on the border wall -- or at least go to the mat on the issue -- may fracture what has been a solid political base for the president.
In 1999, then-Federal Reserve Chairman Alan Greenspan kicked off the central bank’s annual Jackson Hole symposium by highlighting the impact of rising stock prices on an economy that was then enjoying low inflation and low unemployment. Now today, eerily similar, buoyant asset prices and low unemployment argue for Yellen to press ahead with interest-rate increases -- or even accelerate them. Weak inflation suggests she might even want to consider providing more stimulus, not less. That would mimic the tack Greenspan took 18 years ago, when, faced with a frothy stock market, he continued to hike rates until May 2000. The result was a disaster for the stock market -- the technology-heavy Nasdaq Composite Index plunged by 78% over a 2.5 year period from its peak as the dotcom bubble deflated -- but was not all that bad for the economy. Gross domestic product did contract during 2001, but the fall was so small that former Fed Vice Chairman Alan Blinder has called it a “recessionette.” And inflation remained contained. “There are a lot of similarities,” between the late 1990s and today, said Laurence Meyer, who was a Fed governor from 1996 to 2002.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks/funds where we think you can still make good money, including: high yield equities like Annaly or larger caps like Amazon, Facebook, First Solar, Google, Microsoft, and Netflix, as well as small caps like Nutanix.
BMR Companies & Commentary
Amazon (AMZN: $945, down 1%, (for the week))
Amazon Announces New Online Teaching curriculum TenMarks Writing. TenMarks Writing is a new online curriculum designed for teachers to help their students improve their writing skills by using scaffolding, an instructional technique in which students learn step-by-step how the writing process builds.
TenMarks Writing incorporates natural language processing technology to provide students with automatic, personalized feedback and helps teachers deliver differentiated comments as students work through their compositions. It is available for $4 per student for an entire year.
BMR Take: This is just the latest example of another new innovative effort by Amazon. We call Amazon the innovation machine for a reason. Hardly a week goes by without something new and creative coming out from the company. We all know about their entry into food (Whole Foods is part of Amazon as of Monday) and now education. Will this be a major push by the firm? We shall see.
Facebook (FB: $166, flat)
Facebook Usage Growth May Slip among Teens, Young Adults. According to eMarketer's latest forecasts, usage rates for Facebook, Instagram and Snapchat are running roughly in parallel between the US and UK, with Instagram and Snapchat expected to rise by double digits. However, Facebook will see its user growth continue to slow in both countries as lessening usage among teens and young adults drags down overall user growth. Monthly Instagram usage in the US will grow 24% in 2017 to 85 million, also higher than previously forecast.
BMR Take: Do not be alarmed. We repeat. Do not worry. This news of “lowered estimates” and all the talk on TV of slowing engagement for Facebook means very little. It sounds bad. But the reality is engagement is healthy and the bigger factor is new user growth, which remains robust.
First Solar (FSLR: $47, down 1%)
First Solar Sells California Project. This week First Solar announced it completed the sale of the 280 Megawatt (MW) California Flats Solar Project in Monterey County to global private asset manager Capital Dynamics. Terms of the deal were not disclosed.
Located on approximately 2,900 acres of ranch land within the Jack Ranch owned by the Hearst Corporation near the San Luis Obispo and Monterey County borders, California Flats comprises two phases. The 130 MW first phase is expected to be commissioned in 4Q17, and is fully contracted under a long-term Power Purchase Agreement (PPA). The 150 MW second phase, which is currently under construction, is expected to be commissioned by the end of 2018, and is fully contracted under a long-term PPA.
BMR Take: We like this. We understand the cash is going to be reinvested in part of the business with much greater growth prospects. This is just want we want to see from the management teams running the companies we follow.
Google (GOOG: $915, up 1%)
Google and Walmart partner on Voice Shopping. Now people who own a Google Home will be able to order things by voice from Walmart. Cool! But this is copying Amazon Alexa, to be frank. If you can’t beat them join them.
The companies will also participate in the Google Express shopping marketplace, for which Google will eliminate the $95 annual membership fee. Shipping for orders through Google Home or Google Express will be $5 per order, or free if the order reaches a certain level. Costco, Walgreens, and PetSmart already sell via Google Home.
BMR Take: Good news for Google. Amazon is trailblazing the way forward with new innovations by spending tons of money. But there are competitive factors and various stakeholder conflicts, which creates room for companies like Google to jump in with little upfront capital investment, creating great investment opportunities. This could be the start of something big.
We've noticed that Google is lagging the rest of the market. After hitting $980 a month ago, the stock has faded a bit. It seems like a lot, but it's like a $98 stock dropping to $92, not really a big deal. So what do you do from here. You sit back and realize that the market is giving you a huge buying opportunity. Repeat after us: The market is giving you an opportunity to buy the stock a lot cheaper than its all-time high of $988 in June.
Microsoft (MSFT: $73, flat)
Microsoft Acquires Cycle Computing to Accelerate Big Computing in the Cloud. From finding a cure for cancer to making vehicles safer to fulfilling the promises of artificial intelligence, today’s complex problems require the ability to harness massive amounts of computing power. For too long, Big Computing has been accessible only to the most well-funded organizations. Microsoft believes that access to Big Computing capabilities in the cloud has the power to transform many businesses and will be at the forefront of breakthrough experimentation and innovation in the decades to come. Thus far, Microsoft has made significant investments across infrastructure, services and partner ecosystems to realize this vision.
As a further step in this direction, Microsoft recently acquired Cycle Computing, (no price details given), a startup specializing in helping companies perform heavy-duty computing. That includes crunching data for developing new drugs and analyzing risk in the financial services industry. This will make it easier than ever for customers to use High-Performance Computing and other Big Computing capabilities in the cloud. The cloud is quickly changing the world of Big Compute, giving customers the on-demand power and infrastructure necessary to run massive workloads at scale without the overhead. Your compute power is no longer measured or limited by the square footage of your data center.
BMR Take: We’ve already seen explosive growth on Microsoft Azure in the areas of artificial intelligence, the Internet of Things and deep learning. As customers continue to look for faster, more efficient ways to run their workloads, Cycle Computing’s depth and expertise around massively scalable applications make them a great fit for customers. We expect big growth ahead and see Microsoft’s business in a very healthy place.
Netflix (NFLX: $166, flat)
We are not afraid to tell you the good, bad, and the ugly. We know you count on it. We unfortunately have to report that Netflix will lose Disney content in 2019. Disney will end Netflix's film distribution deal as it launches its own streaming services starting with an ESPN service in 2018 and a Disney/Pixar service in 2019. Netflix had inked a deal with Disney to stream films and content just a year ago.
Netflix's stock traded lower on the news as investors see the premature end of the distribution deal as a loss of popular exclusive content. Some have compared the deal termination to the Starz (another Disney property) refusal to renew with Netflix in 2011 and see the move as another example of increasing license renewal risk and streaming competition.
BMR Take: The future of content creation is the holy grail of the media business. While Netflix can survive this one lost deal, the question is how much more of this will we see in the future. There is a long way to go until it is a big problem. But we are worried. Our Target is and has been $165. The stock was higher in July as it rocketed from $146 to $189 but it has fallen since. With a market cap of $72 billion and a PE of a ridiculous 215, we believe it is time for us to put this one to bed. We hereby remove the stock from our Stocks for Success portfolio with a gain of 65% since early 2016. There are lots of better places for your money at this time.
Have you taken the time to go onto the BullMarket.com website? Check out the six portfolios – you’ll find some interesting ideas here for the profits from Netflix.
Nutanix (NTNX: $22, flat)
Cisco Systems announced its intent to acquire Springpath, a leader in hyperconvergence software, for $320 million in cash, with the transaction expected to close in 1Q18. Springpath has developed a distributed file system purpose-built for hyperconvergence that enables server-based storage systems, and Cisco believes the acquisition will allow it to continue to deliver next-generation data center innovation to its customers.
In terms of Cisco, the acquisition was not a surprise, as the two companies have a relationship that goes back to Springpath's 2012 founding and Cisco previously making an investment in the company with an option to acquire it. That said, it is still a bummer for Nutanix. Analysts believed Cisco was a potential acquirer of Nutanix.
BMR Take: Hyperconvergence software is an exploding market. We expect Nutanix to do great things and generate big growth. The stock is hovering our Sell Price and we have had tons of calls and letters about whether we would “sell” the stock. First of all, we don’t own the stock. We don’t buy any of our recommendations as we want to remain clear of any conflict of interests. Secondly, the Target and Sell Prices are there for YOU to decide what to do with your investment. All of you are different. Some have multiple millions and some of you are just getting started. So you have to weigh every investment as it affects you and your family.
With that said, we believe Nutanix will be a big, big winner. Revenues are strong with last quarter coming in at $192 million vs. $115 million the year before. This is HUGE. But remember, this is a small cap stock – tiny in comparison to a Facebook or Google. The market cap is just $3.3 billion. So watch and wait and make a decision for yourself and your family. We think the company is a potential great one, but the market is stretching our patience.
We found this interesting too:
Firsthand Technology Value Fund, a publicly traded venture capital fund that invests in technology and cleantech companies, disclosed that its top five holdings as of July 31, 2017, included Nutanix. The fund’s investment in Nutanix consisted of 460,000 shares of common stock and represented approximately 7% of the fund’s total.
Upcoming Economic News
Consumer Confidence
Tuesday, August 29th, 10:00 AM ET
Period: August
Consensus: 120.0
Prior: 121.1
ADP Employment Survey
Wednesday, August 30th, 8:15 AM ET
Period: August
Consensus: 180,000
Prior: 177,700
Personal Consumption Expenditure
August 31th, 8:30 AM ET
Period: July
Consensus: 0.40%
Prior: 0.10%
Apple Has Debt Too
A few of you have written us and given us grief because we only report Apple’s cash position and don’t report the debt levels. Our internal excuse has always been that Apple’s debt is at very low interest rates. Here are some examples of Apple’s debt:
Apple 2.4% 5/03/2023 $5.5 billion
Apple 1.0% 5/03/2018 $4.0 billion
Apple 4.65% 2/23/2046 $4.0 billion
Apple 3.25% 2/23/2026 $3.25 billion
Apple 2.85% 5/06/2021 $3.0 billion
Apple 3.85% 5/04/2043 $3.0 billion
Apple 2.25% 2/23/2021 $3.0 billion
Apple 3.45% 5/06/2024 $2.5 billion
Here is some more detail:
From their latest financial reports, the last three yearly balance sheets ended September have shown that debt has risen from $29 million in 2014 to $53 million in 2015 and to $75 billion in 2016. At the same time cash has risen from $154 billion to $206 billion to $236 billion, reaching $260 billion in their last quarterly report on July 1st.
So: Big cash. And big debt. The NET CASH position at year-end September 2016 was approximately $160 billion. (And much higher now.)
We’ll take it.
Opko Health (OPK: $6.13, flat) Two weeks ago, the company reported earnings for 2Q17. Total revenues of $314 million were down 12% year over year from $357 million. Revenues included a $10 million payment associated with the commercial launch of Varuby in Europe in comparison to the $50 million payment related to a Rayaldee license in the same quarter in 2016.
Research and development expenses totaled $33 million, up 4%, while selling, general and administrative expenses amounted to $128 million, up 9% year over year. Consequently, loss from operations came in at $4 million, highlighting a significant decline from an operating income of $55 million in the prior-year quarter. The decline can be attributed to a rise in operating expenses owing to the company’s significant investments associated with the commercial launch of Rayaldee along with consistent investments in the pharmaceutical pipeline.
The company has $130 million in cash, unchanged from the quarter before.
This is a biotech company in an industry that is known for companies with years and years of little or no progress (and revenues) and then a big announcement of great success. Luckily Opko isn’t in the camp of no revenues. Revenues as you know are over $1 billion.
Chairman and CEO Frost On the Impact of Opko’s 4Kscore
Released in 2014, the 4Kscore Test is the only blood test that can accurately identify a patient's risk for aggressive prostate cancer, Opko claims. As calls to reduce health care costs across the United States grow louder, 4KScore is as a cost-effective alternative to biopsies, Frost said.
About 30 million tests are done each year to measure men’s prostate-specific antigens, or PSA. Of those, 4 million identify elevated PSA levels and typically would require biopsies.
“If you do the test after the elevated PSAs, you can avoid 50% of all biopsies,” Frost said. “This is the type of thing that if you wanted to be able to cut healthcare costs in this country, this has to be the easiest thing in the world to do.”
On why he continues to buy thousands of OPKO shares
“I always believe in investing in things that I know about rather than things I don’t,” Frost said.
BMR Take: Opko Health is a relatively small biotech firm with great potential. Many times “great potential” results in “no results.” This $3.4 billion market cap company is poised for success, but remains the most speculative stock in our six portfolios.
Splunk (SPLK: $65, up 10%)
Splunk had a great week. They reported earnings on Thursday after the close and they were stellar. This is what we have been waiting for. Revenue rose to $280 million from $213 million a year ago, for a percentage gain of 31%. Huge quarter. Adjusted earnings were $11 million or 8 cents a share.
Guidance is solid with next quarter revenue of $308 million. Operating margins are projected to be approximately 8%.. Growth in yearly revenues has been spectacular. For the last three years we have seen $450,000,000, $670,000,000 and $950,000,000. For fiscal year 2018, ending this coming January, revenue is now expected around $1.21 billion.
Billings in the quarter grew 32% year over year to $303 million. They again increased full fiscal-year 2018 guidance to call for billings of $1.45 billion.
Splunk has been ranked number one in worldwide IT Operations Analytics (ITOA), as well as Event and Log Management software market shares for 2016 by International Data Corporation. Splunk said that these two markets have witnessed the highest growth rates within the overall IT market, with ITOA seeing an increase of 33%, and Event and Log Management growing 23%. This is the third consecutive year that Splunk took the top spot in the ITOA software market, beating the competition of IBM, Microsoft, Hewlett Packard Enterprise and VMware.
More than 500 new customers were added during the quarter, including Athenahealth, Carnival Cruise Lines, the Department of Homeland Security, Harvard Business School, Shutterfly, Uber, and Verizon.
Splunk appears quite dominant in its machine data analytics niche. And the company's market opportunity is growing as its software, traditionally used for IT operational intelligence, gets adopted for security, fraud-detection, app analytics and other use cases.
BMR Take: Great quarter. Looking for continued growth for years to come. Our Target is $75 and our Sell Price remains $60. Note that Splunk has exceeded guidance for 11 straight quarters.
VMware Has a Strong Quarter
VMware ($103, up 7%) had a great week after reporting $1.9 billion in revenues up from $1.7 billion last year with net income of $335 million up from $265 million, $1.19 a share up from $0.97. Huge. Total cloud management bookings rose by a 13% year over year, and the company closed 10 deals valued at over $10 million. Network Virtualization (NVX) revenues were again strong, at over a 40% increase.
The company guided for the year: Revenue of $7.83 billion, EPS of $5.06, and free cash flow of $2.7 billion. These are big numbers.
VMware raised $4 billion earlier this month in a debt offering, mostly overseas, with coupons of 2.3% to 3.9%. Note that Dell Technologies owns 82% of VMware.
Take a look at this chart:
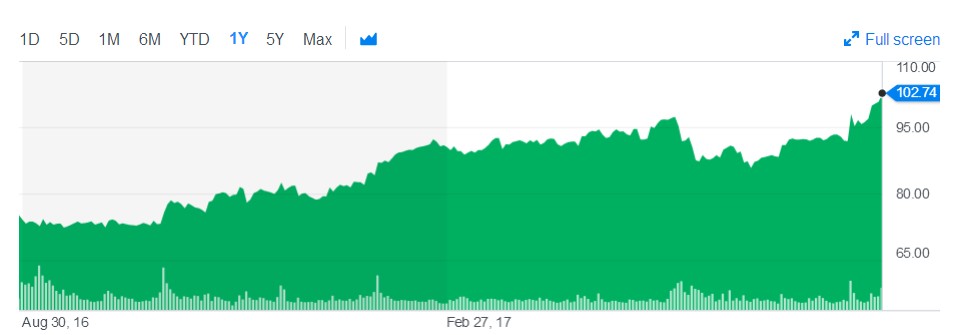
BMR Take: We think you get the drift!
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
As Alfred E. Neuman might say, "What – me worry?" ……as in why care about things such as 1) When will the Fed hike rates again and how many hikes can we expect? 2) Has the 2nd quarter economic rebound already been priced into stocks? 3) Are tax cuts still possible or has the pro-growth agenda been totally derailed by swamp politics? 4) Will we have a trade war with China? 5) Will we go to war with North Korea? 6) Are we headed into a recession?
Sure, we care and everyone else should care about getting tax relief. We have the worst tax system in the world if you don't count dictatorships. But we've lived in the current system for decades and so, while it would be a whole lot better if we got tax reform, investors and the stock market will survive if we don't. We also admit that of course we would care if we had a war. That is highly unlikely however, because none of the large powers has any desire to start WW III. Otherwise, worrying about all of the above is not a good idea - or, as Mom used to say, "If you worry too much, you'll worry yourself to death." So, we are adding a little bit of Alfred's advice to our medicine cabinet and are just going to go on about our business and not worry too much.
Business as usual with all these worries hanging around (stocks love to climb a wall of worry) generally means an investor should expect more volatility. We expect just that. We know stocks tumble way faster than they go up. Thus, we know not to panic - and that is a huge plus for every investor. Or, we might have a little cash to buy into any sale that may come along. Or, we have dividend stocks that will reinvest into more shares whenever they go on sale. And finally, we aren't going to worry about a recession now because the facts simply don't support it. We've looked at inflation, housing starts, retail sales, industrial production, oil prices -- there just isn't any "big trouble" in the economy today.
Not only that, it wasn't that long ago when the US economy seemed like the only regional power heading in the right direction. Europe had record joblessness and was teetering on the edge of recession. Japan was in its 20th year of malaise and China was headed for a hard landing if not a total crash.
Today, all of these regions are showing signs of renewed strength. European markets are doing better than expected. Japan also recently impressed with a +4% GDP growth rate - well above estimates - and China has emerged from a soft patch with a string of positive economic readings. With 40% of US corporate profits coming from abroad, all of the above is then a simple equation pointing to more earnings growth and share price appreciation ahead.
T. Rowe Price once said, "No one can see ahead three years, let alone five or ten." So, we aren't forecasting that conditions won't change in the immediate or distant future. But for the time being, we still see the glass as half full.
A Little Unsettling News
We follow the trends in cash flows into and out of mutual funds. We remember well, back in the 2004-2007 time frame the cash inflows into the stock market were consistent, month after month as cash poured into the market. But we noticed recently that cash outflows are continuing these past few months. U.S. equity funds suffered their longest streak of outflows in 13 years as growing signs of political deadlock in Washington cast doubt on a rally that has taken the S&P 500 Index to record highs.
Investors pulled $2.6 billion from U.S. stock funds in a 10th consecutive week of outflows. That takes total outflows since late June to $30 billion, which covered the week to Aug. 23.
BMR Take: This is serious stuff in our book. We’ve watched these stats for over 30 years and we have found it to be a strong indicator of future prices. We’re watching this one closely.
The High Yield Report
By Michael Foster
Senior Writer
The Bull Market Report
This week could best be described as dull. High yield investments neither enjoyed the euphoria that some assets enjoyed earlier this year, nor continued the panic that we saw in recent weeks due to political noise.
This is not terribly surprising; as we’ve said repeatedly in this column, the fundamentals are strong and there’s little reason to expect a selloff anytime soon. At the same time, however, there is little reason to believe the strong bull run of previous months is going to continue - a lot of the upside is already priced in. That puts us in the rather boring “hold and collect income” position, but when that income is 8% or more on high yield assets, that dullness is quite enriching.
So let’s get specific on a few of our high yield investments in this dull week. A number of Bull Market Report recommendations moved through the week quietly, including several REITs. Omega Healthcare Investors (OHI: $31, up 1%), Apollo Commercial Real Estate (ARI: $17.84, flat), and Ventas (VTR: $68, up 3%). These REITs suffered some volatility earlier this year but have had a much better long-term performance. Much more importantly for us, their dividends remain safe as ever - the recent market turmoil and even more recent market calm have not impacted the income streams of these funds.
Omega in particular is worth a close look because of its high yield and aggressive dividend growth policy. Its 8.2% dividend yield implies a lot of risk, but its dividend coverage ratio over the last twelve months is 134% - far higher than many comparable REITs, and even higher than a lot of lower-yielding REITs. We’ve pounded the table on Omega several times this year for this reason, and with good reason. There os just too much safety in this dividend relative to its yield; if you don’t already own Omega, ask yourself why you aren’t enjoying a growing 8.2% dividend that is more covered by FFO than several 3-4% yielding REITs? And if you have a good answer to that question, let us know, because we can’t imagine there is one.
Elsewhere, municipal bond funds had a quiet week, with both Nuveen AMT-Free Municipal Credit (NVG: $15.49) and Invesco Municipal Trust (VKQ: $12.94) ending the week flat. To understand this, let’s talk a bit about Treasury yields. A big reason why muni bonds fell so heavily in mid-2016 (which is why we waited to recommend them until the end of the year) is that the market was pricing in steep interest rate increases throughout 2017. While we’ve had two rate hikes so far and a third expected in December, (although the probability of even that is declining), that’s less than the Fed had hinted at in 2016. That’s good for municipal bonds, which is why muni bonds have had a strong showing in 2017. For instance, the Nuveen fund we’ve recommended is up 7.2% year-to-date on price alone - that’s less than 200 basis points less than the S&P 500, despite muni bonds’ much lower risk profile and the fund’s 5.6% dividend yield!
The reason for this strong run up in muni bonds - and their relative quiet last week - has to do with interest rates. The market priced into munis a fast pace of rate hikes in 2017, but the reality is that the rate hike schedule is getting longer and longer - meaning the value of munis isn’t going to go down as much as was previously expected. Since the downside was 100% priced in, the lesser downside means these assets were priced too cheaply. And so they’re going up in 2017. It’s also partly why muni bonds have seen relative volatile price movements both up and down in the last couple of years.
Is it still a good time to buy munis? Maybe - it isn’t as clear of a good buy as, say, Omega Healthcare, but holding these funds and collecting their tax-free income stream right now makes a lot of sense.
And there are other interesting options out there, such as the strong performing Digital Realty Trust (DLR: $118, up 3%) and AstraZeneca (AZN: $29, flat). Both of these names are riding a strong wave of momentum thanks to growth in the companies’ fundamental businesses. AstraZeneca was far underpriced last year due to fears of regulations that obviously are not coming anytime soon. Additionally, the drug pipeline is as strong as ever. Similarly, endless demand for server space has made Digital Realty Trust a no-brainer at almost any price. The only problem is that the price growth has lowered their yields - Digital Realty is yielding 3.2% and AstraZeneca is down to 4.8%. It’s becoming clearer and clearer that these two names really should be considered growth or value investments rather than high yield investments. If your goal is to secure a high rate of current income, these names aren’t exactly for you. However, if you appreciate companies with growth potential that haven’t had their future growth fully priced in, but have decent dividends, both names are definitely worth serious consideration.
In any case, the last few weeks have given us a very clear lesson again: Short-term panics based on political headlines are not reasons to sell investments, while fundamental trends in terms of economic demand and dividend coverage are. Financial considerations tell us there’s really nothing to worry about right now.
Good Investing,
Todd Shaver, CEO, Founder and Editor
The Bull Market Report
Founded 1998
August 21, 2017

by Todd Shaver | Aug 21, 2017 | Monthly Newsletter Daily 12pm if new
The Weekly Summary
It was rough week with lots of domestic and international issues popping up, producing anguish. In particular, nine CEOs turned their back on Trump. It all started when first Merck’s Kenneth Frazier, then Under Armour’s Kevin Plank and Intel’s Brian Krzanich stepped down from a White House business group set up to advise Donald Trump. While none mentioned the president, Frazier, one of the country’s most-prominent black chief executive officers, quit the council as Trump was being assailed for failing to quickly condemn white supremacists for deadly violence at a rally Saturday in Charlottesville. Frazier said he was acting on a “matter of personal conscience.” Trump shot back on Twitter Tuesday morning, saying, “For every CEO that drops out of the Manufacturing Council, I have many to take their place.
Then on Wednesday President Trump rushed to announce that he was shutting down the two advisory councils of business leaders, after the members had decided on their own to disband in the wake of the president’s comments on the events in Charlottesville. Of course, these kinds of advisory councils seldom accomplish much of anything.
Look, all this drama will pass. The market will move on. But there is definitely an unsettled feeling out there. It is good that the market showed signs of turning around at week’s end, but we did see a few glimpses of nasty selloffs in a few trading sessions this week. It was a rough week. If you are super worried, then we suggest you take some profits off the table. There are many choices for you to move your money to in the High Yield and the REIT portfolios. These are much more secure, stable stocks with very nice dividends that you can enjoy and sleep better with.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks/funds where we think you can still make good money, including: high yield equities like Annaly and larger caps like Apple, Google, Microsoft, Home Depot, and Visa,
BMR Companies & Commentary
Annaly Capital Management (NLY: $12.34, up 1%)
Annaly recently reported respectable earnings at the beginning of the month. Here are our thoughts on the outlook for the rest of the year and what to watch. Many people are cautious given Annaly’s fixed-rate agency exposure and the current valuation. We know that the company has a set yield on government guaranteed paper. So while there is no credit risk other than the full faith and credit of the United States, there is interest rate risk – we know this and accept this. The newer investments are coming on at lower rates with higher yielding holdings rolling off. And we know that if short term rates rise the current portfolio valuation will be sensitive to the movements. We are likely to see some pressure on Annaly’s business model.
But what can the company do? They can rotate into higher yielding MBS* investments. They can increase leverage. They can do a number of things to cover the dividend. Look, if you think a business model is flawless without risk then you don’t know it well enough. Annaly has rsk to higher rates, but higher rates are ultimately good for the company. And investors are missing all the offsetting possible moves management can take. Remember, this is a company that is 18x the size of the median mortgage REIT by market cap, has outperformed the S&P 500 by 3x since its IPO for total return, and has successfully raised $1.5 billion in new capital this year. They know the world they live in and have survived and thrived for 20 years.
* Mortgage-backed Securities
BMR Take: A Director at the company just bought 13,500 shares. Another one just bought 17,700 shares. We love love love to see that! We are looking at a $0.30 dividend paid quarterly for the time being which is good. The stock looks compelling based on this income stream, producing a dividend over 10%.
Apple (AAPL: $158, flat) is Getting into Programming
Apple has set a 12-month budget of $1 billion to develop original programming. Apple could buy and produce as many as 10 TV shows. Apple's first two efforts -- Planet of the Apps and Carpool Karaoke -- have not been warmly received by critics. Apple executives are talking with Hollywood agents about shows that Apple can buy.
BMR Take: Note that Apple has $260 billion in cash now, and with a market cap of $813 billion cash is 32% of the stock price. So $50 of the stock price is in cash. This is UNPRECEDENTED in the history of Wall Street. Apple remains an exciting investment opportunity. The services business is projected to double in revenue to $50 billion over the next several years. The Services business is much more profitable than hardware so the impact to earnings is even better. Don’t sell a share. We believe Apple has a lot more room to go on the upside.
And how about Apple's performance last week in a very tough week for equities.
Google (GOOG: $911, flat)
The Cloud is a huge opportunity in technology and all the industry giants are fighting to grab their fair share. Let's stipulate up front that Amazon Web Services (AWS) remains the top choice for most companies that are thinking about moving their data and software into cloud data centers. Having said that, however, Amazon's cloud is no longer the only option that companies consider. For example, those companies wanting extensive analytics are taking a good hard look at the Google Cloud Platform. And many firms are hedging their bets by using multiple cloud providers to avoid being stuck with one down the road.
While AWS is still the largest cloud provider by far, Microsoft and Google are coming on strong. AWS's revenue growth appears to be slowing, in part because it's hard for such a huge business - AWS is expected to produce $16 billion in revenue this year - to grow as fast as its younger, smaller incarnations. Startups are considering alternatives now for several reasons: standard cloud computing and storage services from the three top players are all seen as competitive, and no one thinks any of the three major cloud contenders is going away. Basically, AWS, Microsoft, and Google are seen as safe bets.
BMR Take: Google took a hit on the recent earnings report. Buy the dip. This company will generate over $40 of EPS in 2018. The stock is far from a stretched valuation.
Microsoft (MSFT: $72, up 1%)
As Internet-of-Things (IoT), artificial intelligence (AI), smart factories and intelligent applications continue to advance, businesses are increasingly turning to these technologies to create new business solutions with greater agility in order to drive competitive advantages. Microsoft launched its IoT Innovation Center in Taiwan last October to spur development between IoT partners and international enterprises and organizations. In September, Microsoft will hold its second IoT Expo in conjunction with the World Congress on Information Technology. Jason Zander, Corporate Vice President, Microsoft Azure, will deliver a keynote on "Leading Digital Transformation and Landing IOT Value with a Strong IoT Partner." Zander oversees the development and global deployment of cloud infrastructure and technology, including Microsoft Azure IoT. In addition to sharing the success of Microsoft's IoT Innovation Center and its partners, Mr. Zander will also provide Microsoft's vision of the development of IoT and in-depth analysis on the integrated application solutions of the world's leading IoT partners.
BMR Take: The Internet of Things is a megatrend. We are going from 10 billion devices connected to the internet to 30 billion. Your hair dryer will be connected to the internet someday. All of this is going to be a huge opportunity for Microsoft. The company is on track to generate $4 of EPS in 2018. The valuation remains compelling.
And note how strong Microsoft was last week in the very rough week on Wall Street. This company is solid.
Upcoming Economic News
Richmond Fed Index
August 22th, 10:00 AM
Period: August
Consensus: 12.0
Prior: 14.0
New Home Sales
August 23th, 10:00 AM
Period: July
Consensus: 614,000
Prior: 610,000
Building Permits
August 24th, 8:00 AM
Period: July
Consensus: 1,223,000
Prior: 1,223,000
Blackstone Entity Merging with Starwood Homes
Invitation Homes (INVH, $23), a portfolio company of The Blackstone Group (BX: $32, down 1%) , is merging with Starwood Waypoint Homes. The combined company, to be called Invitation Homes, will have 82,000 homes. Once the deal closes Invitation Homes stockholders will own about 59% of the combined company. The total enterprise value of the deal is $20 billion.
Invitation Homes, a U.S. home rental company, went public in February. Blackstone will own about 40% of Invitation.
--- The portfolio of homes will be focused on high-growth markets, with nearly 70% of revenue coming from the Western US and Florida.
--- The merger is expected to drive $50 million in annual synergies.
--- Continued strong performance with the combined company experiencing 7% same-store NOI growth in Q217 with over 95% occupancy.
--- The two companies have invested nearly $2 billion, an average of approximately $22,000 per home, in renovations and maintenance, improving resident experience and driving economic growth and job creation in local communities.
BMR Take: Just one more example of the innovation that Blackstone is involved with day in and day out. With a dividend of 7% and a leader (Schwarzman) dedicated 24-7 to moving the stock higher, what is there not to like. $38 billion market cap. Reaching the all-time high of $44 set in 2012 is surely on the horizon.
Tesla Near to Completion of Gigafactory
Tesla ($348, down 3%) has released some interesting pictures and a video of their gigafactory in Nevada, 95 times bigger (sic) than a football field. New drone footage shows how massive Tesla's Gigafactory is.
http://www.businessinsider.com/tesla-gigafactory-pictures-facts-2017-8
In other news, Tesla raised $1.8 billion in a bond sale on Friday, boosting the amount by $300 million to meet demand. The 8-year bonds were priced at a record-low yield of 5.3%. The 5.3% coupon is a record low for a bond of its rating and maturity, according to data compiled by Bloomberg. The sale was managed by Goldman Sachs Group and Morgan Stanley.
BMR Take: The bond market loves this company. We do too. But we know the risk involved here is on the high end of the scale. Tesla is either headed to $400 a share or $300. And one could make an argument for either. If it hits $400 and they continue to ramp up production as promised, then $500 is a great possibility. But if it goes to $300, $200 would be in range. You want a risky stock? Then Tesla is your baby.
Amazon Sells Bonds for Whole Foods Acquisition
Speaking of bond sales, Amazon (AMZN: $958, down 1%) went to the markets for money last week and sold $16 billion of unsecured bonds to fund its $14 billion acquisition of Whole Foods Market. And in a sign of market interest, the longest portion of the offering, a 40-year security, was sold at a yield of 1.45 percentage points above Treasuries.
BMR Take: Now that is just unreal low. The company has $21 billion in cash so they didn’t need to go to the bond market but did because rates are so low. Smart thinking, Jeff. The deal is the 4th largest this year, behind ATT and Microsoft.
Apple Goes to the Debt Market in Canada
Apple raised $2.5 billion at a rate of 2.51% in a 7-year note sale in Canada on Tuesday. At $2.5 billion the financing is the largest corporate non-financial borrowing in Canadian history.
Stocks Cheap Compared to Bonds
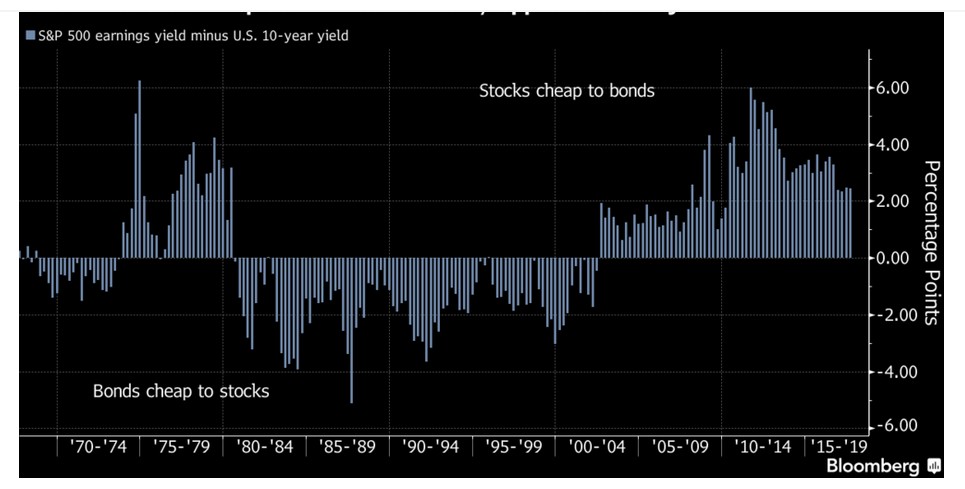 We’re Just Sayin’
The High Yield Report
By Michael Foster
We’re continuing to see market chaos and a lot of selling of high quality assets although the macro risks from political uncertainty are dwindling. But the current selloff is very different from the previous week’s in one very telling, interesting way: Not all assets are falling at the same rate, and some are actually doing very well.
To wit, take a look at The Bull Market Report’s Healthcare REIT pick Omega Healthcare Investors (OHI: $31) which had a strong showing this week after some initial weakness, helping Omega Healthcare end the week up 2%.
We’re seeing a lot of reshuffling in the markets, with investors rotating in and out of funds, stocks, and assets as they rise or fall due to market demand. This is the real “random walk” of Wall Street, and it’s a dynamic that makes short term trends for any individual asset to be unpredictable. In reality, we’re seeing a lot of individual investors making choices to buy on the dip - and they’re pulling money from other assets to do so.
What can an investor do in such an environment? Simple: sit tight. If you have extra cash on the sidelines, now is the time to deploy into the high yield picks that The Bull Market Report has been recommending for a long time. Last week we suggested buying more of Omega Healthcare shares; it’s up 2% since then. Now is the time to do the same with other REITs seeing irrational weakness like Sabra.
You can also consider adding Kimco Realty Corporation (KIM: $19.34) and Apollo Commercial Real Estate (ARI: $17.92) to your shopping list after Kimco fell over 3% in the last week and Apollo remained flat. There is no change in these companies FFO to justify the decline, and Kimco’s year-long weakness on the often-touted (and always inaccurate) “death of retail” has made it just that much more compelling. We have discussed at length here why Retail isn’t dead, and how Amazon’s recent purchase of Whole Foods indicates that the shift from pre-dotcom retail to mobile “bricks and clicks” commerce is far more complicated than the simple narrative of dying malls. In any case, Kimco doesn’t buy enclosed malls! It’s a high-quality strip mall-focused REIT, and Whole Foods (and thus soon Amazon) is one of its biggest tenants.
There are more buying opportunities beyond REITs, and investors are keen to lighten up their cash allocation to consider the other funds and stocks in the High Yield portfolio. However, there is one word of caution to consider when it comes to one of our best performing picks, the PIMCO Dynamic Income Fund (PDI: $29). This fund was flat last week.
What’s going on here is a pretty basic misunderstanding of the fund’s future income potential. You see, Pimco releases a monthly scorecard of net investment income (NII) on its website, while also calculating its dividend coverage ratio. And, simply put, the news isn’t good for the Dynamic Income Fund.
In the past, Pimco easily out-earned its dividend and had a tremendous amount of undistributed net investment income (UNII). That’s why the fund paid a special dividend of $1.45 at the end of 2016. By this time last year, the fund had around $1 in UNII, so it was pretty obvious that a big special dividend was coming (we discussed this at the time and estimated a strong special dividend at the end of last year – and nailed it). This year, however, the Dynamic Income fund has only 4 cents in UNII - a pretty tremendous drop from a year ago!
There are a few reasons why the fund isn’t earning as much income as it used to, most of which revolves around the crowding out of great investment opportunities in mortgage backed securities. The MBS is a pretty daunting asset made sinister by The Big Short and growing awareness of their role in the subprime housing crisis. However, that crisis is a decade behind us, and the quality of MBS investments has skyrocketed. While Pimco was one of the few asset managers aggressively buying up these assets in the past, there are now a lot of people wanting to buy them. That means lower yields for the assets, thus weaker income for the Dynamic Income Fund.
However, at the same time, it also means growing market prices for these assets. This fund’s NAV has risen by 10% so far in 2017, largely a result of that constant demand for MBS’s in the market. Last year, the Dynamic Income Fund’s NAV had risen by far less than 1% over the same time period, because the demand for these assets simply wasn’t there. That means that the fund is sitting on a lot of capital gains with dwindling income.
What does this mean for shareholders? In all honesty, it’s hard to tell. The fund hasn’t really faced a crowding out of supply due to strong demand since 2012. It has enjoyed both NAV and income gains in earlier years, and the end-of-year special dividends reflected that. We simply don’t know if the fund’s managers will decide to return some of those capital gains to shareholders or hold on to it and give a massively reduced special dividend at the end of the year.
It seems that the market has begun to price in the likelihood of a lower special dividend. The fund’s premium to NAV has plummeted from over 10% earlier this year to just 3%. It may fall even further as we get closer to December. If Pimco surprises and gives a big special payout at the end of the year, that could reverse quickly. If it doesn’t, we’ll probably see middling price growth throughout 2017.
The risk with the fund is that its Net Investment Income continues to fall and it fails to cover its dividend on a long-term basis. While we’ve seen hints of that now, it’s far too early to conclude that this risk is really here and it’s time to sell. But investors need to prepare for that eventuality. We will keep a close eye on this trend and advise you if it’s time to move out of this great fund. Hopefully we won’t have to recommend selling anytime soon.
How should you react? Holding the fund for its income stream makes sense now, and buying more when the fund’s premium disappears and it starts trading at a discount also makes sense. That means there’s no reason for investors to get scared and sell off the fund, but it also means investors shouldn’t expect a massive jump in the fund’s price throughout 2017. That’s not a bad thing - it really reflects what the fund should be seen as: A source of steady and reliable income.
Good Investing,
Todd Shaver, Founder, CEO and Editor
The Bull Market Report
Since 1998
August 20, 2017
by Todd Shaver | Aug 20, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
It was rough week with lots of domestic and international issues popping up, producing anguish. In particular, nine CEOs turned their back on Trump. It all started when first Merck’s Kenneth Frazier, then Under Armour’s Kevin Plank and Intel’s Brian Krzanich stepped down from a White House business group set up to advise Donald Trump. While none mentioned the president, Frazier, one of the country’s most-prominent black chief executive officers, quit the council as Trump was being assailed for failing to quickly condemn white supremacists for deadly violence at a rally Saturday in Charlottesville. Frazier said he was acting on a “matter of personal conscience.” Trump shot back on Twitter Tuesday morning, saying, “For every CEO that drops out of the Manufacturing Council, I have many to take their place.
Then on Wednesday President Trump rushed to announce that he was shutting down the two advisory councils of business leaders, after the members had decided on their own to disband in the wake of the president’s comments on the events in Charlottesville. Of course, these kinds of advisory councils seldom accomplish much of anything.
Look, all this drama will pass. The market will move on. But there is definitely an unsettled feeling out there. It is good that the market showed signs of turning around at week’s end, but we did see a few glimpses of nasty selloffs in a few trading sessions this week. It was a rough week. If you are super worried, then we suggest you take some profits off the table. There are many choices for you to move your money to in the High Yield and the REIT portfolios. These are much more secure, stable stocks with very nice dividends that you can enjoy and sleep better with.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks/funds where we think you can still make good money, including: high yield equities like Annaly and larger caps like Apple, Google, Microsoft, Home Depot, and Visa,
BMR Companies & Commentary
Annaly Capital Management (NLY: $12.34, up 1%)
Annaly recently reported respectable earnings at the beginning of the month. Here are our thoughts on the outlook for the rest of the year and what to watch. Many people are cautious given Annaly’s fixed-rate agency exposure and the current valuation. We know that the company has a set yield on government guaranteed paper. So while there is no credit risk other than the full faith and credit of the United States, there is interest rate risk – we know this and accept this. The newer investments are coming on at lower rates with higher yielding holdings rolling off. And we know that if short term rates rise the current portfolio valuation will be sensitive to the movements. We are likely to see some pressure on Annaly’s business model.
But what can the company do? They can rotate into higher yielding MBS* investments. They can increase leverage. They can do a number of things to cover the dividend. Look, if you think a business model is flawless without risk then you don’t know it well enough. Annaly has rsk to higher rates, but higher rates are ultimately good for the company. And investors are missing all the offsetting possible moves management can take. Remember, this is a company that is 18x the size of the median mortgage REIT by market cap, has outperformed the S&P 500 by 3x since its IPO for total return, and has successfully raised $1.5 billion in new capital this year. They know the world they live in and have survived and thrived for 20 years.
* Mortgage-backed Securities
BMR Take: A Director at the company just bought 13,500 shares. Another one just bought 17,700 shares. We love love love to see that! We are looking at a $0.30 dividend paid quarterly for the time being which is good. The stock looks compelling based on this income stream, producing a dividend over 10%.
Apple (AAPL: $158, flat) is Getting into Programming
Apple has set a 12-month budget of $1 billion to develop original programming. Apple could buy and produce as many as 10 TV shows. Apple's first two efforts -- Planet of the Apps and Carpool Karaoke -- have not been warmly received by critics. Apple executives are talking with Hollywood agents about shows that Apple can buy.
BMR Take: Note that Apple has $260 billion in cash now, and with a market cap of $813 billion cash is 32% of the stock price. So $50 of the stock price is in cash. This is UNPRECEDENTED in the history of Wall Street. Apple remains an exciting investment opportunity. The services business is projected to double in revenue to $50 billion over the next several years. The Services business is much more profitable than hardware so the impact to earnings is even better. Don’t sell a share. We believe Apple has a lot more room to go on the upside.
And how about Apple's performance last week in a very tough week for equities.
Google (GOOG: $911, flat)
The Cloud is a huge opportunity in technology and all the industry giants are fighting to grab their fair share. Let's stipulate up front that Amazon Web Services (AWS) remains the top choice for most companies that are thinking about moving their data and software into cloud data centers. Having said that, however, Amazon's cloud is no longer the only option that companies consider. For example, those companies wanting extensive analytics are taking a good hard look at the Google Cloud Platform. And many firms are hedging their bets by using multiple cloud providers to avoid being stuck with one down the road.
While AWS is still the largest cloud provider by far, Microsoft and Google are coming on strong. AWS's revenue growth appears to be slowing, in part because it's hard for such a huge business - AWS is expected to produce $16 billion in revenue this year - to grow as fast as its younger, smaller incarnations. Startups are considering alternatives now for several reasons: standard cloud computing and storage services from the three top players are all seen as competitive, and no one thinks any of the three major cloud contenders is going away. Basically, AWS, Microsoft, and Google are seen as safe bets.
BMR Take: Google took a hit on the recent earnings report. Buy the dip. This company will generate over $40 of EPS in 2018. The stock is far from a stretched valuation.
Microsoft (MSFT: $72, up 1%)
As Internet-of-Things (IoT), artificial intelligence (AI), smart factories and intelligent applications continue to advance, businesses are increasingly turning to these technologies to create new business solutions with greater agility in order to drive competitive advantages. Microsoft launched its IoT Innovation Center in Taiwan last October to spur development between IoT partners and international enterprises and organizations. In September, Microsoft will hold its second IoT Expo in conjunction with the World Congress on Information Technology. Jason Zander, Corporate Vice President, Microsoft Azure, will deliver a keynote on "Leading Digital Transformation and Landing IOT Value with a Strong IoT Partner." Zander oversees the development and global deployment of cloud infrastructure and technology, including Microsoft Azure IoT. In addition to sharing the success of Microsoft's IoT Innovation Center and its partners, Mr. Zander will also provide Microsoft's vision of the development of IoT and in-depth analysis on the integrated application solutions of the world's leading IoT partners.
BMR Take: The Internet of Things is a megatrend. We are going from 10 billion devices connected to the internet to 30 billion. Your hair dryer will be connected to the internet someday. All of this is going to be a huge opportunity for Microsoft. The company is on track to generate $4 of EPS in 2018. The valuation remains compelling.
And note how strong Microsoft was last week in the very rough week on Wall Street. This company is solid.
The Home Depot (HD: $147, down 4%)
Home Depot took a bad hit on earnings. But we feel this is a great time to initiate a position or add to an existing one. A few Wall Street analysts upgraded the stock to Buy reaffirming our confidence.
Revenue for the quarter was $28.1 billion versus the consensus for $27.8 billion. Revenue guidance for the year is $95 billion, short of the $99 billion consensus. EPS of $2.25 beat the consensus of $2.21. Chairman, CEO Craig Menear said: "We were pleased with our results this quarter as our customers rewarded us with the highest quarterly sales in company history. We also achieved the highest quarterly net earnings in company history."
So what happened? Analysts were largely upbeat on the results, with same store sales beating expectations despite a tough backdrop for all of the Retail industry. Specifically, same store comparable sales growth was +5.5% beating the +4.6% guidance. So all the momentum looked good this quarter but why the bad outlook for lower revenue? The shares traded down because of this guidance miss. But under the covers many people just think it is conservatism from management, not something serious.
BMR Take: We expect to see momentum continue over the rest of the year following what was the largest quarter ever, pointing to strong sales growth, operating margin expansion and EPS growth. With EPS heading to $9 in 2018 we this valuation is compelling right here to be buying.
Visa (V: $103, up 3%)
Visa announced a multi-year, global partnership with Marqeta, the open API payment card issuing platform, to drive further innovations in commercial and consumer payments. Additionally, Visa has made a strategic investment in Marqeta to support both company’s domestic and international growth objectives.
The Fintech industry is booming, Fintech being short for financial technology. Everybody in financial services from banks like JP Morgan to networks like Visa are having to figure out how to keep up with the technology revolution in finance. That is why this deal is so key for Visa. Visa is embracing the change and going to be delivering the most innovative solutions in payments for years to come. This supports why we love the Visa EPS growth story and believe the stock should be a core holding in your portfolio.
The initial efforts of the partnership will involve growing opportunities for virtual, physical and tokenized payments across a number of commercial markets and use cases that can benefit from Marqeta’s developer-friendly platform.
The market for electronic payments continues to grow in commercial payables, alternative lending, disbursements, eCommerce, on-demand services and P2P payments. To enable this growth, Marqeta’s platform allows companies of all sizes to authorize their own card transactions, fundamentally changing how companies engage with card issuing and transaction processing.
This is the latest partnership and investment for Visa with an emerging innovator within the payments ecosystem. As a global payments technology company, Visa continually evaluates technologies of all kinds – especially those that have the potential to advance digital payments for Visa’s clients and their customers. Recently, Visa has made investments in Chain, Klarna, Square and Stripe, among others.
BMR Take: Visa is a safe haven investment. With EPS heading to $4, we continue to see tremendous value here.
Upcoming Economic News
Richmond Fed Index
August 22th, 10:00 AM
Period: August
Consensus: 12.0
Prior: 14.0
New Home Sales
August 23th, 10:00 AM
Period: July
Consensus: 614,000
Prior: 610,000
Building Permits
August 24th, 8:00 AM
Period: July
Consensus: 1,223,000
Prior: 1,223,000
Blackstone (BX: $32, down 1%) Entity Merging with Starwood Homes
Invitation Homes (INVH, $23), a portfolio company of The Blackstone Group, is merging with Starwood Waypoint Homes. The combined company, to be called Invitation Homes, will have 82,000 homes. Once the deal closes Invitation Homes stockholders will own about 59% of the combined company. The total enterprise value of the deal is $20 billion.
Invitation Homes, a U.S. home rental company, went public in February. Blackstone will own about 40% of Invitation.
--- The portfolio of homes will be focused on high-growth markets, with nearly 70% of revenue coming from the Western US and Florida.
--- The merger is expected to drive $50 million in annual synergies.
--- Continued strong performance with the combined company experiencing 7% same-store NOI growth in Q217 with over 95% occupancy.
--- The two companies have invested nearly $2 billion, an average of approximately $22,000 per home, in renovations and maintenance, improving resident experience and driving economic growth and job creation in local communities.
BMR Take: Just one more example of the innovation that Blackstone is involved with day in and day out. With a dividend of 7% and a leader (Schwarzman) dedicated 24-7 to moving the stock higher, what is there not to like. $38 billion market cap. Reaching the all-time high of $44 set in 2012 is surely on the horizon.
Tesla Near to Completion of Gigafactory
Tesla ($348, down 3%) has released some interesting pictures and a video of their gigafactory in Nevada, 95 times (sic) bigger than a football field. New drone footage shows how massive Tesla's Gigafactory is.
http://www.businessinsider.com/tesla-gigafactory-pictures-facts-2017-8
In other news, Tesla raised $1.8 billion in a bond sale on Friday, boosting the amount by $300 million to meet demand. The 8-year bonds were priced at a record-low yield of 5.3%. The 5.3% coupon is a record low for a bond of its rating and maturity, according to data compiled by Bloomberg. The sale was managed by Goldman Sachs Group and Morgan Stanley.
BMR Take: The bond market loves this company. We do too. But we know the risk involved here is on the high end of the scale. Tesla is either headed to $400 a share or $300. And one could make an argument for either. If it hits $400 and they continue to ramp up production as promised, then $500 is a great possibility. But if it goes to $300, $200 would be in range. You want a risky stock? Then Tesla is your baby.
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
Earnings were everything expected, plus a little more. So here we are with about six weeks before the 3rd quarter comes to a close. Unemployment is low, interest rates are low, energy costs are low and consumer confidence is fairly high. Besides a garden variety correction, what could derail the markets? - not counting a war, which in our opinion and most experts we listen to is a fairly low probability. The most likely candidate would be a recession. With earnings growth better now than the past eight years, this critical element in the recession scenario seems relatively safe for the next several quarters.
However, after speaking with some very learned folks in the banking industry, there is one problem that has caught our attention. We have been told that it is very difficult for banks to make enough profit to lend money when short-term and long-term interest rates are less than 1%. Today, the difference between a 2-year Treasury note and a 10-year Treasury bond remains less than 1%. Rate hikes have a history of producing bear markets in the past and could do so again because there just isn’t enough profit for commercial banks to lend money. Recessions develop out of these situations. We are not yet in an "inverted yield curve" situation (where short-term rates are higher than long-term rates), which is a classic signal of a coming recession, and we don't believe banks are to the point that they are going to substantially curtail lending. However, it is something we will watch for over the coming quarters.
As we said last week, stocks don't go straight up forever. There will be volatility and pullbacks as Fed-tightening continues, but until we see actual signs of an approaching recession, we believe stocks continue to offer better value than bonds.
Amazon Sells Bonds for Whole Foods Acquisition
Speaking of bond sales, Amazon (AMZN: $958, down 1%) went to the markets for money last week and sold $16 billion of unsecured bonds to fund its $14 billion acquisition of Whole Foods Market. And in a sign of market interest, the longest portion of the offering, a 40-year security, was sold at a yield of 1.45 percentage points above Treasuries.
BMR Take: Now that is just unreal low. The company has $21 billion in cash so they didn’t need to go to the bond market but did because rates are so low. Smart thinking, Jeff. The deal is the 4th largest this year, behind ATT and Microsoft.
Apple Goes to the Debt Market in Canada
Apple raised $2.5 billion at a rate of 2.51% in a 7-year note sale in Canada on Tuesday. At $2.5 billion the financing is the largest corporate non-financial borrowing in Canadian history.
Stocks Cheap Compared to Bonds
We’re Just Sayin’
Cantor Fitzgerald: OPKO Health - Overweight Rating, $20 Price Target
And how about this:
In other Opko Health news, Director John A. Paganelli purchased 5,000 shares of the company’s stock on June 1st. Following the transaction, the director now owns 350,000 shares in the company. Director Richard A. Lerner purchased 10,000 shares of the company’s stock on June 5th. Insiders have bought a total of 1,600,000 shares of company stock worth $10,000,000 in the last three months. Insiders own 40% of the company’s stock.
There are eight research companies following Opko. Six have a buy rating; two have a hold. Their average price target is $16.40.
BMR Take: For those of you still hanging in there with Opko Health (OPK: $6.12, down 2%) this report from Cantor Fitzgerald is good news. $20 Wow. That is over three times the current price. What are we missing here? Oh – I know. We are missing a higher stock price! Well maybe, just maybe this is the start of the re-rising (is that a word?) of the stock to the $8 level and then $10 and then on to the races from there. Hope springs eternal, doesn’t it? Well, yes, but with all the good things this company has going for it, for it to stay at $6 any longer JUST DOESN’T MAKE ANY SENSE!
The High Yield Report
By Michael Foster
We’re continuing to see market chaos and a lot of selling of high quality assets although the macro risks from political uncertainty are dwindling. But the current selloff is very different from the previous week’s in one very telling, interesting way: Not all assets are falling at the same rate, and some are actually doing very well.
To wit, take a look at The Bull Market Report’s Healthcare REIT pick Omega Healthcare Investors (OHI: $31) which had a strong showing this week after some initial weakness, helping Omega Healthcare end the week up 2%.
We’re seeing a lot of reshuffling in the markets, with investors rotating in and out of funds, stocks, and assets as they rise or fall due to market demand. This is the real “random walk” of Wall Street, and it’s a dynamic that makes short term trends for any individual asset to be unpredictable. In reality, we’re seeing a lot of individual investors making choices to buy on the dip - and they’re pulling money from other assets to do so.
What can an investor do in such an environment? Simple: sit tight. If you have extra cash on the sidelines, now is the time to deploy into the high yield picks that The Bull Market Report has been recommending for a long time. Last week we suggested buying more of Omega Healthcare shares; it’s up 2% since then. Now is the time to do the same with other REITs seeing irrational weakness like Sabra.
You can also consider adding Kimco Realty Corporation (KIM: $19.34) and Apollo Commercial Real Estate (ARI: $17.92) to your shopping list after Kimco fell over 3% in the last week and Apollo remained flat. There is no change in these companies FFO to justify the decline, and Kimco’s year-long weakness on the often-touted (and always inaccurate) “death of retail” has made it just that much more compelling. We have discussed at length here why Retail isn’t dead, and how Amazon’s recent purchase of Whole Foods indicates that the shift from pre-dotcom retail to mobile “bricks and clicks” commerce is far more complicated than the simple narrative of dying malls. In any case, Kimco doesn’t buy enclosed malls! It’s a high-quality strip mall-focused REIT, and Whole Foods (and thus soon Amazon) is one of its biggest tenants.
There are more buying opportunities beyond REITs, and investors are keen to lighten up their cash allocation to consider the other funds and stocks in the High Yield portfolio. However, there is one word of caution to consider when it comes to one of our best performing picks, the PIMCO Dynamic Income Fund (PDI: $29). This fund was flat last week.
What’s going on here is a pretty basic misunderstanding of the fund’s future income potential. You see, Pimco releases a monthly scorecard of net investment income (NII) on its website, while also calculating its dividend coverage ratio. And, simply put, the news isn’t good for the Dynamic Income Fund.
In the past, Pimco easily out-earned its dividend and had a tremendous amount of undistributed net investment income (UNII). That’s why the fund paid a special dividend of $1.45 at the end of 2016. By this time last year, the fund had around $1 in UNII, so it was pretty obvious that a big special dividend was coming (we discussed this at the time and estimated a strong special dividend at the end of last year – and nailed it). This year, however, the Dynamic Income fund has only 4 cents in UNII - a pretty tremendous drop from a year ago!
There are a few reasons why the fund isn’t earning as much income as it used to, most of which revolves around the crowding out of great investment opportunities in mortgage backed securities. The MBS is a pretty daunting asset made sinister by The Big Short and growing awareness of their role in the subprime housing crisis. However, that crisis is a decade behind us, and the quality of MBS investments has skyrocketed. While Pimco was one of the few asset managers aggressively buying up these assets in the past, there are now a lot of people wanting to buy them. That means lower yields for the assets, thus weaker income for the Dynamic Income Fund.
However, at the same time, it also means growing market prices for these assets. This fund’s NAV has risen by 10% so far in 2017, largely a result of that constant demand for MBS’s in the market. Last year, the Dynamic Income Fund’s NAV had risen by far less than 1% over the same time period, because the demand for these assets simply wasn’t there. That means that the fund is sitting on a lot of capital gains with dwindling income.
What does this mean for shareholders? In all honesty, it’s hard to tell. The fund hasn’t really faced a crowding out of supply due to strong demand since 2012. It has enjoyed both NAV and income gains in earlier years, and the end-of-year special dividends reflected that. We simply don’t know if the fund’s managers will decide to return some of those capital gains to shareholders or hold on to it and give a massively reduced special dividend at the end of the year.
It seems that the market has begun to price in the likelihood of a lower special dividend. The fund’s premium to NAV has plummeted from over 10% earlier this year to just 3%. It may fall even further as we get closer to December. If Pimco surprises and gives a big special payout at the end of the year, that could reverse quickly. If it doesn’t, we’ll probably see middling price growth throughout 2017.
The risk with the fund is that its Net Investment Income continues to fall and it fails to cover its dividend on a long-term basis. While we’ve seen hints of that now, it’s far too early to conclude that this risk is really here and it’s time to sell. But investors need to prepare for that eventuality. We will keep a close eye on this trend and advise you if it’s time to move out of this great fund. Hopefully we won’t have to recommend selling anytime soon.
How should you react? Holding the fund for its income stream makes sense now, and buying more when the fund’s premium disappears and it starts trading at a discount also makes sense. That means there’s no reason for investors to get scared and sell off the fund, but it also means investors shouldn’t expect a massive jump in the fund’s price throughout 2017. That’s not a bad thing - it really reflects what the fund should be seen as: A source of steady and reliable income.
Good Investing,
Todd Shaver, Founder, CEO and Editor
The Bull Market Report
Since 1998
August 13, 2017
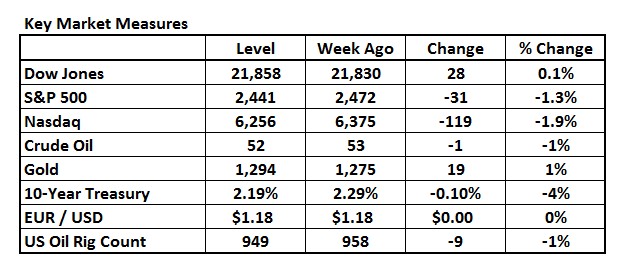
by Todd Shaver | Aug 13, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
Talk of “fire and fury, the likes of which the world has never seen” aimed at North Korea spooked anybody listening. The markets have been calm for so long and then BOOM, the VIX (^VIX: 15.45) spiked 44% in one day and 60% in two days of trading this week. Our take is that we had been in an unsustainable lull of inactivity. These things happen and you have to be prepared for them. But in the long run, they work themselves out and things get better. Stay the course. If you are worried, consider dialing back your exposure to some of the more aggressive equities out there in favor of looking toward our REIT and High Yield portfolios, where the income stream of dividends offers greater downside protection.
But no matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks/funds: Shopify, Apple, The Carlyle Group, Sabra, AstraZeneca, AllianzGI Equity & Convertible Income Fund, Twilio and Amazon.
BMR Companies & Commentary
Apple (AAPL: $158, up 1% - all prices are for the week)
Apple is hard at work sublet shifting its brand. Everybody knows Apple. But Apple isn’t the name of its products. Apple's greatest hits over the past 30 years don't have "Apple" in their name: Macintosh, PowerBook, iTunes, iPod, iPad, iPhone, Siri. The newer stuff that does carry the Apple moniker -- Apple Watch, Apple Music, Apple TV-- have been either outright disappointments or solid but not wildly popular businesses.
But Apple is as good a brand as any. Think Proctor & Gamble, Ford, General Electric - you get the point. It's hard to transition from a corporate brand to additional brand franchises, but if you can do it, the future is bright!
CEO Tim Cook is working hard to make it happen. The Apple brand speaks to the firm's culture and reputation to employees, shareholders and governments. A product brand communicates a specific message about the item's quality, design, or function to consumers. There is so much potential.
BMR Take: Apple is just one of the companies that always figures it out - just as we are seeing them do now with the focus on services revenue and rethinking the brand.
We remain very bullish. The stock is trading at 17x this year’s consensus EPS of $9.00. The Services business is on pace to double over the next few years. Our Target of $155 has now been breached. Yea! We hereby raise our Target Price to $170. This will bring the company close to a $900 billion valuation, now at $813 billion. Our Sell Price remains the same: “We would not sell Apple.”
The Carlyle Group (CG, $21, flat*)
Carlyle is really a master of the universe. The company’s private equity investments are behind so much of the world’s underlining economic activity it’s ridiculous. The latest example is with McDonald's.
This week McDonald's announced the successful completion of a strategic partnership with CITIC Capital Partners and The Carlyle Group. Ramping up a new era of growth and innovation, the partnership will operate and manage McDonald's businesses in mainland China and Hong Kong, leveraging combined expertise and strength to drive an expansion strategy.
The transaction has obtained China's regulatory approval and was completed on July 31st, creating the largest McDonald's franchisee outside of the United States. The sale to the new McDonald's China franchisee includes McDonald's existing businesses in Mainland China (2,500 restaurants) and Hong Kong (240 restaurants).
The new partnership announced a series of development initiatives for mainland China. Termed "Vision 2022," this strategy aims to drive double-digit sales growth in each of the next five years by increasing the number of restaurants from 2,500 to 4,500 by the end of 2022, bringing unparalleled convenience to Chinese customers. The opening pace of new McDonald's restaurants in mainland China is expected to progressively ramp up from approximately 250 per year in 2017 to 500 per year in 2022 under the new partnership. Vision 2022 also includes an increase of "Experience of the Future" restaurants to over 90%, which will enable the brand to offer a digitalized and personalized dining experience to more customers.
BMR Take: We believe Carlyle is heading to $30. Consensus is looking for a solid dividend of $1.80 next year and $2.15 the following. EPS is running closer to $3. Few institutional investors can buy the stock because the K1 tax structure creates issues. But that will change and when it does, look out on the upside.
* The stock was down 40 cents this week, but CG paid a 42 cent dividend on Thursday and when a stock pays a dividend the stock always opens that day down the amount of the dividend. Thus Carlyle was flat this past week.
Shopify (SHOP: $92, down 5%)
Shopify’s plan is to let half a million merchants run their business via Alexa and bots. Shopify wants its 500,000 merchants to be able to run their businesses almost entirely through the use of bots or voice apps like Alexa.
At F8, Facebook’s annual developer conference, Shopify announced plans to launch a Facebook Messenger bot, named “Kit”, the first commerce platform to do so. Through conversations on Facebook Messenger or SMS, Kit can do things like place a Facebook ad or start an email marketing campaign.
The development roadmaps of voice apps like the Shopify Alexa* skillset and text bots like Kit will begin to converge, so that the same merchant analytics available today by voice will become available in a text interface, and the same actions to run your business available today through text will someday be available with your voice.
* Shopify Alexa is a partnership with Amazon to use Alexa.
The Shopify Alexa skill first became available in January, but was launched with no marketing or promotion in order listen to the queries put forward by merchants to better understand the kinds of questions they want the skill to be able to answer. Before merchants are given the ability to run business operations in a conversational interface, a few other features will be added first.
Based on merchant feedback, more long-term business performance insights are on the way, and work will continue with engineers to ensure the bot can handle the range of questions a merchant has and understands the variety of ways a merchant may ask a question.
BMR Take: When we look at the core building blocks of how this company is advancing its growth potential of Total Addressable Market (TAM) is expanding. In addition, we see opportunities in international, in new merchant solutions and apps, and building scale with Shopify Plus, the company’s enterprise-focused solution. In our view, the valuation is supported by the long runway and expanding TAM given Shopify’s lower relative market share, still less than 5%. We reiterate our bullishness on the stock. The stock is currently trading at about 9 times the estimate of next year’s sales. This valuation is rich but justified.
Sabra Health Care REIT (SBRA: $21.45, down 7%)
We have decided to take our chips off the table in Sabra. Two reasons. First, the core senior housing portfolio growth is essentially flat so it’s hard to see any organic upside from the business. Second, the pending merger with Care Capital is being fought creating noise and possibly more risk.
Regarding the latter, two activist investors are urging Sabra to drop the Care Capital deal. They say shareholders of the healthcare-focused real estate investment trust should reject the merger at a shareholder meeting next month. Why? Sabra was overpaying for Care Capital's assets by up to 30%, the hedge fund said in a presentation. Ouch.
Consensus for Sabra Healthcare REIT:
1 Sell Rating, 6 Hold Ratings, 1 Buy Rating
BMR Take: We like to listen to the market and to other shareholders invested in the stocks we own. Especially when the other shareholders do great research and make objective points. We added the stock at $24 in May and are down a bit, but with the dividend, it wasn’t a great loss. Let’s move on to the next one.
AllianzGI Equity & Convertible Income Fund (NIE: $19.79, down 2%)
This fund seeks total return with capital appreciation and high current income through investment in convertible equity, income producing securities and through utilizing an options strategy. It’s top holdings are Microsoft, Apple, Amazon, Facebook, and Google. It does not use leverage. It does not hold fixed income.
60% of the stocks it holds are in the largest giant companies, and 37% in large cap companies. The Funds PE ratio is 19 versus the 17.2 benchmark, but sales, EPS, book value, and cash flow growth is all better than the benchmark.
See more discussion in The High Yield Report later in this newsletter.
BMR Take: Sometimes it is nice to own a fund and have some help picking all the right places to be. We like AllianzGI with its 7.7% yield. You can buy right now at a discount to the net asset value of $21.75, a very opportune entry point.
AstraZeneca (AZN: $29, flat*)
Fierce pharma rivals collaborating on cancer treatments are increasing the competitive landscape, hurting AstraZeneca. But we believe we must stay the course. AstraZeneca reported disappointing results for its clinical trials examining Tremelimumab combined with Imfinzi for the treatment of lung cancer. The market has become crowded with checkpoint inhibitors and immunotherapy drugs, which means that the number of such potential combinations of treatments is growing. Pharma rivals are now cooperating -- last week Merck bought half the rights to AstraZeneca's Lynparza, and in July Eli Lilly said it would out-license or co-develop one-third of its oncology pipeline.
BMR Take: Healthcare has been a minefield for months now. AstraZeneca has been beaten down. Analysts have been upgrading the stock on valuation. It is very cheap versus expectations for around $2 of EPS for next few years. Consider the 3% dividend yield on top of that. It’s a classic value here as the stock is truly undervalued. Our Target remains $42, and our Sell Price of $32 has been breached, so please make a decision with your own portfolio as to whether you personally wish to stay the course. We are trying to be patient here to give the company more time to perform.
*A dividend was paid on Wednesday of 45 cents.
Upcoming Economic News
Retail Sales
August 15th , 8:30 AM
Period: July
Consensus: 0.40%
Prior: -0.20%
Housing Starts
August 16th, 8:30 AM
Period: June
Consensus: 1,220,000
Prior: 1,215,000
Initial Claims
August 17th, 8:30 AM
Period: Through August 12
Consensus: 240,000
Prior: 244,000
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
Stocks finished mostly higher again the week before last, mainly because of good corporate earnings, a stronger-than-expected Jobs report, solid GDP performance, healthy Consumer Confidence and a little better than expected Export & Import numbers. Is it all "too good to be true?" [Well, indeed it was!]
According to the latest American Association of Individual Investors survey, individual investors are now holding their lowest cash allocation since 2000. They are now among the most invested in financial markets since 1988. The three other time periods with the lowest cash allocations were in 1998, 2000, and 2015, and all of these preceded times when investors probably wished they had more of a cushion.
We certainly do not think we're on the brink of another 1999 dotcom bubble or a 2008 financial crisis crater. But one thing's for sure, stocks don't always go straight up forever. There will be volatility and pullbacks as Fed-tightening continues. According to recent news reports, there is now a 50/50 chance the Fed will raise rates again in December. Whenever a pullback occurs, it is not going to be unexpected. It's overdue and as natural to the market as hot dogs are to ball games. With a backdrop of really solid earnings, we expect any pullback to be fairly brief in duration. If earnings keep growing and the job numbers keep getting stronger, pullbacks will just be setting up the next move higher. If Congress grows up and we get tax relief and corporate tax reform, investors will be saying, "Laissez les bon temps roulez".
Note what UBS has to say in their latest report on the Equity Markets: The bottom line: stocks are not cheap, BUT ARE NOT in "bubble" territory.
Amazon Update (AMZN: $968, down 2%)
The stock got hit last week as the rest of the market had some tough times as you know. There is an ongoing discussion over valuation with this company. We had a heated argument with a very astute investor who thinks the stock is overvalued saying that the company will NEVER report substantial earnings; that Bezos will ALWAYS have a new project in mind that will cause him to spend, spend, spend on new infrastructure.
We agree to a certain extent, but disagree with the profit story. As you know, we have said many times revenues are the key to all success in the market. Amazon had revenues of $89 billion, $107 billion and $136 billion in the last three calendar years. This year? Hard to say, but it looks like at least $175 billion? This is just huge of course. We remain bullish for as far as we can see forward.
We hereby raise our Price Target from $1000 to $1100 and leave the Sell Price at $900.
Twilio (TWLO: $31, up 7%)
Twilio had a huge week after reporting blowout revenues as we reported via News Flash on Tuesday. Total revenue – $96 million, up 49% from the second quarter of 2016 and 10% sequentially from the first quarter of 2017.
Loss from operations – $7 million, compared with a loss of $11 million for 2Q16.
And we love this stat: 43,000 Active Customer Accounts as of June 30, 2017, compared to 31,000 Active Customer Accounts as of June 30, 2016.
Profits are still at slightly below breakeven, but as you know, we are banking on the huge revenue gain.
Here is the consensus on the Street:
2 Hold Ratings, 15 Buy Ratings
Price Targets:
8/8/2017 Canaccord Genuity $38
8/8/2017 Robert W. Baird $39
8/8/2017 J P Morgan Chase $40
8/8/2017 Mitsubishi UFJ Financial Group $35
7/17/2017 Summit Redstone $36
BMR Take: We love this company and think it can be a monster. An Apple? A Microsoft? Hard to predict the next 10-15 years, but watch this one closely.
Wall Street Consensus for United Parcel Service (UPS: $111, up 1% in a very tough week, and after an 83 cent dividend on Thursday)
Consensus: 10 Hold Ratings, 5 Buy Ratings
Price Targets:
8/8/2017 Citigroup $128
7/3/2017 Sanford C. Bernstein $127
SNAP (SNAP: $11.83, down 13% - still at a $14 billion market cap)
Don’t buy SNAP
Don’t buy SNAP
Don’t buy SNAP
Revenues: $182 million up from $72 million
Loss: $443 million up from a loss of $116 million last year. WOW! (How is this actually possible?)
Don’t Buy SNAP
Don’t Buy SNAP
A Letter from a Subscriber about Netflix (NFLX: $171, down 5%)
From: Stan Makovsky [mailto:stan@stanxxxx.com]
Sent: Wednesday, August 09, 2017 3:11 PM
To: 'Todd at The Bull Market Report'
Subject: Netflix
Hi Todd,
Disney pulling out of Netflix seems to be a big deal for both stocks. Your thoughts please?
Best Regards,
Stan Makovsky
Our Response:
Hi Stan –
I am not really concerned too much. The market is getting slammed today as I write this [Wednesday] and Netflix is down just $4. If it were down $20 I’d be a little concerned. But I believe Disney needs Netflix more than Netflix needs Disney. Netflix is a force now and as you know is spending billions of dollars a year on programming. They will be just fine. The scary thing about Netflix is their profit level – which is tiny. This needs to change.
Todd Shaver
Founder and Editor in Chief
The Bull Market Report
A Powerful Financial Newsletter
Since 1998
@BullMarketRept on Twitter
The High Yield Report
By Michael Foster
Special to The Bull Market Report
It’s been a long time coming, but we finally see a bit of fear entering the market.
For high yield investors, this is a concern because downturns and mini-corrections tend to be amplified in high yield investments. The S&P 500 slid over 1% last week but many high yield investments fell much more, especially closed-end funds (CEF). The AllianzGI Equity and Convertible Income Fund (NIE: $19.80) fell nearly 2% over the last week due to a considerable decline in the fund’s NAV, which fell over 1% in a single day of trading last week. In many cases, a market correction will result in CEFs’ discounts widening as investors sell off the fund. Surprisingly, however, holders of the AGIC fund have been surprisingly calm, resulting in the discount staying less than 10% by the week’s end. Recently, the discount had shrunk to less than 9%, so this is definitely not as good as it has recently been. But it’s surprisingly not as bad as it could be.
Of course, if the selloff continues throughout the coming week, it would be more than reasonable to expect Allianz to see a larger discount as slower and more risk-averse investors finally get around to selling this and other closed-end funds. What does this mean for you? Well, we maintain a bullish outlook for the economy and for stocks, with corporate profits continuing to rise year-over-year and the Allianz fund in particular maintains a strong portfolio of respected and strong-performing stocks. There’s no reason to sell off amongst the fearful, but anyone with extra cash on the sidelines who wants a sustainable near-8% dividend stream could consider picking up some of this fund.
Similarly, The Bull Market Report’s second CEF pick, the Pimco Dynamic Income Fund (PDI: $29), had a rough week during the market’s selloff, falling over 4%, after paying out a 22 cent dividend on Wednesday. This has resulted in PDI’s premium price falling slightly, and now the fund trades at slightly over a 2% premium to NAV.
After the sell-off, investors may be eager to buy more of the Pimco fund and capture that 9% dividend yield plus the potential upside of special dividends at the end of the year. Before rushing to buy, however, there are a few things to consider. The fund’s NAV has risen 10% so far this year even after accounting for dividend payouts, which means the fund’s payout remains sustainable. However, this is a relatively weak performance compared to its past performance. Part of the reason for that is the growing burden of its promised payouts. Because it trades at a premium, it has been significantly harder for the fund to pay out dividends than to earn the comparable income in the open market. Since the fund’s premium rose to as much as 10% earlier this year, those dividend payouts were particularly burdensome for Pimco’s managers. Now that the premium is at its lowest point since November last year, that dividend is going to be slightly easier to pay.
Easier, but not easy. The real problem with this fund is that it has years and years of a solid track record thanks to its contrarian nature. The fund invested heavily in mortgage-backed securities (MBS’s) after 2008, when they were synonymous with financial ruin. In reality, however, many of these assets were extremely undervalued because of investor fear, and Pimco had the chops to find the good ones and buy them. Hence the fund’s massive outperformance.
However, 2008-2009 is becoming a fainter memory, and the market is finally realizing the huge mistake it made in avoiding many quite valuable MBS’s. As a result, more capital is coming into that market and creating more competition for Pimco. Ultimately, that means diminished returns for investors holding this fund.
Unfortunately, this has also happened as more investors have discovered the fund’s tremendous returns. Holding this fund has become a crowded trade. Back in 2013-2015, the fund almost always traded at a discount; in late 2015, shortly before The Bull Market Report recommended it, its discount fell to 11%. But now a flood of capital has come in and driven the fund to a consistent premium, while earning superior returns through MBS’s is getting harder for the fund.
This doesn’t mean you should sell the Pimco Dynamic Income Fund. But it does mean one has to wait before buying more and instead choose other strong dividend payers like the AllianzGI fund.
Finally, let’s briefly discuss REITs. These were a mixed bag, with pretty much all REITs down and some down much more than others. Omega Healthcare Investors (OHI: $30) fell 2% over the week alongside the broader market, with its greater volatility amplifying losses. Yet the similarly volatile Government Properties Trust (GOV: $18.13) fell about 1% over the same period, even beating the market. There are a couple of pretty obvious reasons for this. For one, Government Properties Trust’s big decline earlier this month means it’s found a bottom and can’t plunge much lower. Obviously this means buying now makes sense. Omega, however, hasn’t exactly found its bottom yet and only went negative YTD at the end of last month. There’s no fundamental reason for this – there is sustainable income, the dividend is still rising, and Omega’s expansionary plans are on track. But there is a lot of fear in the market, and that is reflected in the rapidly fluctuating price of this stock.
While buying Omega now is buying a bargain, investors should be prepared for more volatility. Government Properties, while not exactly strong, seems to have found a floor that is limiting further downside, making it a more appealing buy right now. But no matter what you do right now, selling is not a good idea. There is no fundamental reason to fear for the future of equities or high yield assets, so ignore the panic selling. It will be intense but brief-lived, as always.
Good Investing,
Todd Shaver, Editor, CEO and Founder
The Bull Market Report
Since 1998
