August 13, 2017
by Todd Shaver | Aug 13, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
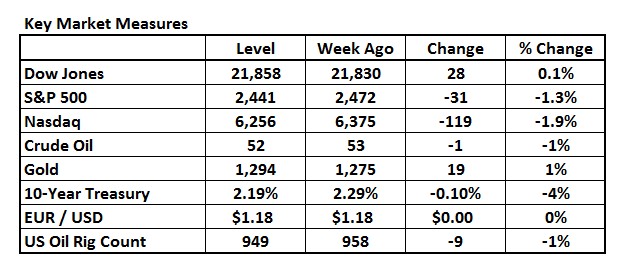
Talk of “fire and fury, the likes of which the world has never seen” aimed at North Korea spooked anybody listening. The markets have been calm for so long and then BOOM, the VIX (^VIX: 15.45) spiked 44% in one day and 60% in two days of trading this week. Our take is that we had been in an unsustainable lull of inactivity. These things happen and you have to be prepared for them. But in the long run, they work themselves out and things get better. Stay the course. If you are worried, consider dialing back your exposure to some of the more aggressive equities out there in favor of looking toward our REIT and High Yield portfolios, where the income stream of dividends offers greater downside protection.
But no matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks/funds: Shopify, Apple, The Carlyle Group, Sabra, AstraZeneca, AllianzGI Equity & Convertible Income Fund, Twilio and Amazon.
BMR Companies & Commentary
Apple (AAPL: $158, up 1% - all prices are for the week)
Apple is hard at work sublet shifting its brand. Everybody knows Apple. But Apple isn’t the name of its products. Apple's greatest hits over the past 30 years don't have "Apple" in their name: Macintosh, PowerBook, iTunes, iPod, iPad, iPhone, Siri. The newer stuff that does carry the Apple moniker -- Apple Watch, Apple Music, Apple TV-- have been either outright disappointments or solid but not wildly popular businesses.
But Apple is as good a brand as any. Think Proctor & Gamble, Ford, General Electric - you get the point. It's hard to transition from a corporate brand to additional brand franchises, but if you can do it, the future is bright!
CEO Tim Cook is working hard to make it happen. The Apple brand speaks to the firm's culture and reputation to employees, shareholders and governments. A product brand communicates a specific message about the item's quality, design, or function to consumers. There is so much potential.
BMR Take: Apple is just one of the companies that always figures it out - just as we are seeing them do now with the focus on services revenue and rethinking the brand.
We remain very bullish. The stock is trading at 17x this year’s consensus EPS of $9.00. The Services business is on pace to double over the next few years. Our Target of $155 has now been breached. Yea! We hereby raise our Target Price to $170. This will bring the company close to a $900 billion valuation, now at $813 billion. Our Sell Price remains the same: “We would not sell Apple.”
The Carlyle Group (CG, $21, flat*)
Carlyle is really a master of the universe. The company’s private equity investments are behind so much of the world’s underlining economic activity it’s ridiculous. The latest example is with McDonald's.
This week McDonald's announced the successful completion of a strategic partnership with CITIC Capital Partners and The Carlyle Group. Ramping up a new era of growth and innovation, the partnership will operate and manage McDonald's businesses in mainland China and Hong Kong, leveraging combined expertise and strength to drive an expansion strategy.
The transaction has obtained China's regulatory approval and was completed on July 31st, creating the largest McDonald's franchisee outside of the United States. The sale to the new McDonald's China franchisee includes McDonald's existing businesses in Mainland China (2,500 restaurants) and Hong Kong (240 restaurants).
The new partnership announced a series of development initiatives for mainland China. Termed "Vision 2022," this strategy aims to drive double-digit sales growth in each of the next five years by increasing the number of restaurants from 2,500 to 4,500 by the end of 2022, bringing unparalleled convenience to Chinese customers. The opening pace of new McDonald's restaurants in mainland China is expected to progressively ramp up from approximately 250 per year in 2017 to 500 per year in 2022 under the new partnership. Vision 2022 also includes an increase of "Experience of the Future" restaurants to over 90%, which will enable the brand to offer a digitalized and personalized dining experience to more customers.
BMR Take: We believe Carlyle is heading to $30. Consensus is looking for a solid dividend of $1.80 next year and $2.15 the following. EPS is running closer to $3. Few institutional investors can buy the stock because the K1 tax structure creates issues. But that will change and when it does, look out on the upside.
* The stock was down 40 cents this week, but CG paid a 42 cent dividend on Thursday and when a stock pays a dividend the stock always opens that day down the amount of the dividend. Thus Carlyle was flat this past week.
Shopify (SHOP: $92, down 5%)
Shopify’s plan is to let half a million merchants run their business via Alexa and bots. Shopify wants its 500,000 merchants to be able to run their businesses almost entirely through the use of bots or voice apps like Alexa.
At F8, Facebook’s annual developer conference, Shopify announced plans to launch a Facebook Messenger bot, named “Kit”, the first commerce platform to do so. Through conversations on Facebook Messenger or SMS, Kit can do things like place a Facebook ad or start an email marketing campaign.
The development roadmaps of voice apps like the Shopify Alexa* skillset and text bots like Kit will begin to converge, so that the same merchant analytics available today by voice will become available in a text interface, and the same actions to run your business available today through text will someday be available with your voice.
* Shopify Alexa is a partnership with Amazon to use Alexa.
The Shopify Alexa skill first became available in January, but was launched with no marketing or promotion in order listen to the queries put forward by merchants to better understand the kinds of questions they want the skill to be able to answer. Before merchants are given the ability to run business operations in a conversational interface, a few other features will be added first.
Based on merchant feedback, more long-term business performance insights are on the way, and work will continue with engineers to ensure the bot can handle the range of questions a merchant has and understands the variety of ways a merchant may ask a question.
BMR Take: When we look at the core building blocks of how this company is advancing its growth potential of Total Addressable Market (TAM) is expanding. In addition, we see opportunities in international, in new merchant solutions and apps, and building scale with Shopify Plus, the company’s enterprise-focused solution. In our view, the valuation is supported by the long runway and expanding TAM given Shopify’s lower relative market share, still less than 5%. We reiterate our bullishness on the stock. The stock is currently trading at about 9 times the estimate of next year’s sales. This valuation is rich but justified.
Sabra Health Care REIT (SBRA: $21.45, down 7%)
We have decided to take our chips off the table in Sabra. Two reasons. First, the core senior housing portfolio growth is essentially flat so it’s hard to see any organic upside from the business. Second, the pending merger with Care Capital is being fought creating noise and possibly more risk.
Regarding the latter, two activist investors are urging Sabra to drop the Care Capital deal. They say shareholders of the healthcare-focused real estate investment trust should reject the merger at a shareholder meeting next month. Why? Sabra was overpaying for Care Capital's assets by up to 30%, the hedge fund said in a presentation. Ouch.
Consensus for Sabra Healthcare REIT:
1 Sell Rating, 6 Hold Ratings, 1 Buy Rating
BMR Take: We like to listen to the market and to other shareholders invested in the stocks we own. Especially when the other shareholders do great research and make objective points. We added the stock at $24 in May and are down a bit, but with the dividend, it wasn’t a great loss. Let’s move on to the next one.
AllianzGI Equity & Convertible Income Fund (NIE: $19.79, down 2%)
This fund seeks total return with capital appreciation and high current income through investment in convertible equity, income producing securities and through utilizing an options strategy. It’s top holdings are Microsoft, Apple, Amazon, Facebook, and Google. It does not use leverage. It does not hold fixed income.
60% of the stocks it holds are in the largest giant companies, and 37% in large cap companies. The Funds PE ratio is 19 versus the 17.2 benchmark, but sales, EPS, book value, and cash flow growth is all better than the benchmark.
See more discussion in The High Yield Report later in this newsletter.
BMR Take: Sometimes it is nice to own a fund and have some help picking all the right places to be. We like AllianzGI with its 7.7% yield. You can buy right now at a discount to the net asset value of $21.75, a very opportune entry point.
AstraZeneca (AZN: $29, flat*)
Fierce pharma rivals collaborating on cancer treatments are increasing the competitive landscape, hurting AstraZeneca. But we believe we must stay the course. AstraZeneca reported disappointing results for its clinical trials examining Tremelimumab combined with Imfinzi for the treatment of lung cancer. The market has become crowded with checkpoint inhibitors and immunotherapy drugs, which means that the number of such potential combinations of treatments is growing. Pharma rivals are now cooperating -- last week Merck bought half the rights to AstraZeneca's Lynparza, and in July Eli Lilly said it would out-license or co-develop one-third of its oncology pipeline.
BMR Take: Healthcare has been a minefield for months now. AstraZeneca has been beaten down. Analysts have been upgrading the stock on valuation. It is very cheap versus expectations for around $2 of EPS for next few years. Consider the 3% dividend yield on top of that. It’s a classic value here as the stock is truly undervalued. Our Target remains $42, and our Sell Price of $32 has been breached, so please make a decision with your own portfolio as to whether you personally wish to stay the course. We are trying to be patient here to give the company more time to perform.
*A dividend was paid on Wednesday of 45 cents.
Upcoming Economic News
Retail Sales
August 15th , 8:30 AM
Period: July
Consensus: 0.40%
Prior: -0.20%
Housing Starts
August 16th, 8:30 AM
Period: June
Consensus: 1,220,000
Prior: 1,215,000
Initial Claims
August 17th, 8:30 AM
Period: Through August 12
Consensus: 240,000
Prior: 244,000
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
Stocks finished mostly higher again the week before last, mainly because of good corporate earnings, a stronger-than-expected Jobs report, solid GDP performance, healthy Consumer Confidence and a little better than expected Export & Import numbers. Is it all "too good to be true?" [Well, indeed it was!]
According to the latest American Association of Individual Investors survey, individual investors are now holding their lowest cash allocation since 2000. They are now among the most invested in financial markets since 1988. The three other time periods with the lowest cash allocations were in 1998, 2000, and 2015, and all of these preceded times when investors probably wished they had more of a cushion.
We certainly do not think we're on the brink of another 1999 dotcom bubble or a 2008 financial crisis crater. But one thing's for sure, stocks don't always go straight up forever. There will be volatility and pullbacks as Fed-tightening continues. According to recent news reports, there is now a 50/50 chance the Fed will raise rates again in December. Whenever a pullback occurs, it is not going to be unexpected. It's overdue and as natural to the market as hot dogs are to ball games. With a backdrop of really solid earnings, we expect any pullback to be fairly brief in duration. If earnings keep growing and the job numbers keep getting stronger, pullbacks will just be setting up the next move higher. If Congress grows up and we get tax relief and corporate tax reform, investors will be saying, "Laissez les bon temps roulez".
Note what UBS has to say in their latest report on the Equity Markets: The bottom line: stocks are not cheap, BUT ARE NOT in "bubble" territory.
Amazon Update (AMZN: $968, down 2%)
The stock got hit last week as the rest of the market had some tough times as you know. There is an ongoing discussion over valuation with this company. We had a heated argument with a very astute investor who thinks the stock is overvalued saying that the company will NEVER report substantial earnings; that Bezos will ALWAYS have a new project in mind that will cause him to spend, spend, spend on new infrastructure.
We agree to a certain extent, but disagree with the profit story. As you know, we have said many times revenues are the key to all success in the market. Amazon had revenues of $89 billion, $107 billion and $136 billion in the last three calendar years. This year? Hard to say, but it looks like at least $175 billion? This is just huge of course. We remain bullish for as far as we can see forward.
We hereby raise our Price Target from $1000 to $1100 and leave the Sell Price at $900.
Twilio (TWLO: $31, up 7%)
Twilio had a huge week after reporting blowout revenues as we reported via News Flash on Tuesday. Total revenue – $96 million, up 49% from the second quarter of 2016 and 10% sequentially from the first quarter of 2017.
Loss from operations – $7 million, compared with a loss of $11 million for 2Q16.
And we love this stat: 43,000 Active Customer Accounts as of June 30, 2017, compared to 31,000 Active Customer Accounts as of June 30, 2016.
Profits are still at slightly below breakeven, but as you know, we are banking on the huge revenue gain.
Here is the consensus on the Street:
2 Hold Ratings, 15 Buy Ratings
Price Targets:
8/8/2017 Canaccord Genuity $38
8/8/2017 Robert W. Baird $39
8/8/2017 J P Morgan Chase $40
8/8/2017 Mitsubishi UFJ Financial Group $35
7/17/2017 Summit Redstone $36
BMR Take: We love this company and think it can be a monster. An Apple? A Microsoft? Hard to predict the next 10-15 years, but watch this one closely.
Wall Street Consensus for United Parcel Service (UPS: $111, up 1% in a very tough week, and after an 83 cent dividend on Thursday)
Consensus: 10 Hold Ratings, 5 Buy Ratings
Price Targets:
8/8/2017 Citigroup $128
7/3/2017 Sanford C. Bernstein $127
SNAP (SNAP: $11.83, down 13% - still at a $14 billion market cap)
Don’t buy SNAP
Don’t buy SNAP
Don’t buy SNAP
Revenues: $182 million up from $72 million
Loss: $443 million up from a loss of $116 million last year. WOW! (How is this actually possible?)
Don’t Buy SNAP
Don’t Buy SNAP
A Letter from a Subscriber about Netflix (NFLX: $171, down 5%)
From: Stan Makovsky [mailto:stan@stanxxxx.com]
Sent: Wednesday, August 09, 2017 3:11 PM
To: 'Todd at The Bull Market Report'
Subject: Netflix
Hi Todd,
Disney pulling out of Netflix seems to be a big deal for both stocks. Your thoughts please?
Best Regards,
Stan Makovsky
Our Response:
Hi Stan –
I am not really concerned too much. The market is getting slammed today as I write this [Wednesday] and Netflix is down just $4. If it were down $20 I’d be a little concerned. But I believe Disney needs Netflix more than Netflix needs Disney. Netflix is a force now and as you know is spending billions of dollars a year on programming. They will be just fine. The scary thing about Netflix is their profit level – which is tiny. This needs to change.
Todd Shaver
Founder and Editor in Chief
The Bull Market Report
A Powerful Financial Newsletter
Since 1998
@BullMarketRept on Twitter
The High Yield Report
By Michael Foster
Special to The Bull Market Report
It’s been a long time coming, but we finally see a bit of fear entering the market.
For high yield investors, this is a concern because downturns and mini-corrections tend to be amplified in high yield investments. The S&P 500 slid over 1% last week but many high yield investments fell much more, especially closed-end funds (CEF). The AllianzGI Equity and Convertible Income Fund (NIE: $19.80) fell nearly 2% over the last week due to a considerable decline in the fund’s NAV, which fell over 1% in a single day of trading last week. In many cases, a market correction will result in CEFs’ discounts widening as investors sell off the fund. Surprisingly, however, holders of the AGIC fund have been surprisingly calm, resulting in the discount staying less than 10% by the week’s end. Recently, the discount had shrunk to less than 9%, so this is definitely not as good as it has recently been. But it’s surprisingly not as bad as it could be.
Of course, if the selloff continues throughout the coming week, it would be more than reasonable to expect Allianz to see a larger discount as slower and more risk-averse investors finally get around to selling this and other closed-end funds. What does this mean for you? Well, we maintain a bullish outlook for the economy and for stocks, with corporate profits continuing to rise year-over-year and the Allianz fund in particular maintains a strong portfolio of respected and strong-performing stocks. There’s no reason to sell off amongst the fearful, but anyone with extra cash on the sidelines who wants a sustainable near-8% dividend stream could consider picking up some of this fund.
Similarly, The Bull Market Report’s second CEF pick, the Pimco Dynamic Income Fund (PDI: $29), had a rough week during the market’s selloff, falling over 4%, after paying out a 22 cent dividend on Wednesday. This has resulted in PDI’s premium price falling slightly, and now the fund trades at slightly over a 2% premium to NAV.
After the sell-off, investors may be eager to buy more of the Pimco fund and capture that 9% dividend yield plus the potential upside of special dividends at the end of the year. Before rushing to buy, however, there are a few things to consider. The fund’s NAV has risen 10% so far this year even after accounting for dividend payouts, which means the fund’s payout remains sustainable. However, this is a relatively weak performance compared to its past performance. Part of the reason for that is the growing burden of its promised payouts. Because it trades at a premium, it has been significantly harder for the fund to pay out dividends than to earn the comparable income in the open market. Since the fund’s premium rose to as much as 10% earlier this year, those dividend payouts were particularly burdensome for Pimco’s managers. Now that the premium is at its lowest point since November last year, that dividend is going to be slightly easier to pay.
Easier, but not easy. The real problem with this fund is that it has years and years of a solid track record thanks to its contrarian nature. The fund invested heavily in mortgage-backed securities (MBS’s) after 2008, when they were synonymous with financial ruin. In reality, however, many of these assets were extremely undervalued because of investor fear, and Pimco had the chops to find the good ones and buy them. Hence the fund’s massive outperformance.
However, 2008-2009 is becoming a fainter memory, and the market is finally realizing the huge mistake it made in avoiding many quite valuable MBS’s. As a result, more capital is coming into that market and creating more competition for Pimco. Ultimately, that means diminished returns for investors holding this fund.
Unfortunately, this has also happened as more investors have discovered the fund’s tremendous returns. Holding this fund has become a crowded trade. Back in 2013-2015, the fund almost always traded at a discount; in late 2015, shortly before The Bull Market Report recommended it, its discount fell to 11%. But now a flood of capital has come in and driven the fund to a consistent premium, while earning superior returns through MBS’s is getting harder for the fund.
This doesn’t mean you should sell the Pimco Dynamic Income Fund. But it does mean one has to wait before buying more and instead choose other strong dividend payers like the AllianzGI fund.
Finally, let’s briefly discuss REITs. These were a mixed bag, with pretty much all REITs down and some down much more than others. Omega Healthcare Investors (OHI: $30) fell 2% over the week alongside the broader market, with its greater volatility amplifying losses. Yet the similarly volatile Government Properties Trust (GOV: $18.13) fell about 1% over the same period, even beating the market. There are a couple of pretty obvious reasons for this. For one, Government Properties Trust’s big decline earlier this month means it’s found a bottom and can’t plunge much lower. Obviously this means buying now makes sense. Omega, however, hasn’t exactly found its bottom yet and only went negative YTD at the end of last month. There’s no fundamental reason for this – there is sustainable income, the dividend is still rising, and Omega’s expansionary plans are on track. But there is a lot of fear in the market, and that is reflected in the rapidly fluctuating price of this stock.
While buying Omega now is buying a bargain, investors should be prepared for more volatility. Government Properties, while not exactly strong, seems to have found a floor that is limiting further downside, making it a more appealing buy right now. But no matter what you do right now, selling is not a good idea. There is no fundamental reason to fear for the future of equities or high yield assets, so ignore the panic selling. It will be intense but brief-lived, as always.
Good Investing,
Todd Shaver, Editor, CEO and Founder
The Bull Market Report
Since 1998
August 2, 2017

by Todd Shaver | Aug 2, 2017 | 7am News Flash
Shopify (SHOP: $104, up $12 – 13%)
August 2, 2017
Canadian e-commerce platform Shopify soared after beating analysts’ revenue estimates for a ninth quarter in a row, boosting the forecast for the current quarter and signing up a record number of new merchants. The second-quarter earnings report yesterday reaffirmed the company’s reputation as a stock market darling. The shares pushed Shopify’s market cap to more than $10 billion.
The company booked $152 million in sales, beating the average analyst estimate of $144 million and its own forecast of $143 million, which marked 75% growth from the prior year quarter. Adjusted operating loss -- which excludes stock-based compensation expense -- was $3 million, or 1.9% of revenue, versus $3.2 million, or 3.7% of revenue, in the prior year period.
Some analysts, from firms including Royal Bank of Canada and Goldman Sachs, have lowered their ratings on the stock recently, after such gains have made it one of the most expensive software stocks. However, while Shopify doesn’t yet turn a profit, this quarter’s loss of one penny was about as close to breakeven as it gets.
Shopify hit 500,000 customers during the quarter, with clients ranging from individuals selling handmade goods to web stores for major brands like Budweiser and Tesla. This was up from 300,000 a year ago. Wow. Chief Executive Officer Tobi Lutke said “500,000 merchants is just such a crazy number. I have lots of stories about being laughed out of VC offices because they told me the entire addressable market for my company was 40,000 stores.”
Shopify’s growth comes as more retail spending shifts online from physical stores, prompting a new wave of brick-and-mortar bankruptcies. The company is adding and growing new revenue streams, such as giving loans to its customers to help them grow and poaching bigger, more established customers from competitors.
The number of merchants shows growth of 67% from the same period last year. Average annual growth since 2012 has been 70%. Keeping up such a rapid pace will become harder though, CEO Lutke has said repeatedly.
BMR Take: When we look at the core building blocks of how this company is advancing we’re of the view that its growth potential of Total Addressable Market (TAM) is expanding. In addition, we see opportunities in international, in new merchant solutions and apps, and building scale with Shopify Plus, the company’s enterprise-focused solution. In our view, the valuation is supported by the long runway and expanding TAM given Shopify’s lower relative market share, still less than 5%. We reiterate our bullishness on the stock. The stock is currently trading at about 9 times the estimate of next year’s sales. This valuation is rich but could still move higher.
We added the stock four months ago at $73 so we are up 43% in that short time frame. The $90 Target was obliterated today – we purposely did not raise it over the weekend. We wanted to see how revenues looked. Needless to say we are quite pleased. We hereby raise our Target to $115 and our Sell Price from $65 to $93.
July 30, 2017

by Todd Shaver | Jul 30, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
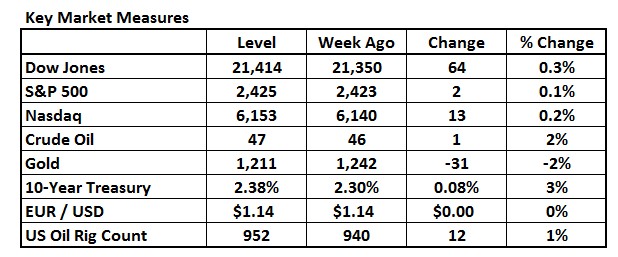
North Korea test-fired its second intercontinental ballistic missile within a month on Friday, a provocation that heightens pressure on the U.S. and China to find ways to rein in Kim Jong Un’s nuclear ambitions. The U.S. said its top general called his South Korean counterpart to discuss “military response options.” The missile traveled about 620 miles. Trump called the launch a reckless and dangerous action and said "the United States will take all necessary steps to ensure the security of the American homeland and protect our allies in the region.” Why is this so important? It is more than the obvious geopolitical risks. The CBOE Volatility Index (^VIX) touched multi-decade lows earlier this past week at 8.84, but closing Friday at 10.29. It is really hard to see the markets remaining as calm as they are right now. This North Korea news is a fresh reminder that it is highly unlikely the markets remain this placid for long.
However, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks: Amazon, First Solar, Shopify, Square, Facebook, and AstraZeneca.
Highlights From The Past Week
Tech Slide in Week of Upbeat Earnings Underscores Growing Unease. Better earnings equals higher share prices, or so goes the customary thinking. For Technology stocks during this reporting season, it’s the exact opposite. Companies from Google to Microsoft announced quarterly results that beat analyst estimates by a combined 8%, more than any other industry group in the S&P 500 Index. Be reminded, that too much love can prove perilous when momentum reverses. In June, after investors had flocked to Tech stocks anticipating faster earnings growth in a move that pushed the Nasdaq 100 Index to rise twice as fast as the S&P 500, they rushed for the exit all at once, sparking the worst selloff since 2008 relative to the rest of the market.
Focus Turns To The Fed's Balance Sheet. If the Federal Reserve delivers any surprises in the near-future, it will probably come from news on when it plans to start shrinking its balance sheet. Economists don’t foresee an interest-rate hike anytime soon. Yet policy makers might update their language on inflation, because weakness in price data has persisted since they last met, but those changes should be minor.
A larger source of uncertainty stems from the timing of when the Fed will start to shrink its $4.5 trillion holdings of mainly Treasuries and mortgage-related debt. Everyone wants to know how the Fed will cut the bloat after building assets to record levels to help shield the U.S. economy during the financial crisis. Officials expect to begin the process this year and Chair Janet Yellen has said it could get under way “relatively soon.” Her lack of specific guidance has us looking toward the Fed’s meeting in September for an announcement. It sure seems like they would like to get the process started in the Fall. This will undoubtedly be a big shift for markets. But, it is expected and seems to be priced into the markets now. The 10-year Treasury is still very, very low from a historical standpoint at 2.29%. We don’t expect that to change much in the near future.
Howard Marks Sounds Alarm on Tech Stocks. We love to follow what the billionaires say. After all, they have made a lot of money and that is what we are trying to do. Just this week, billionaire Howard Marks, who’s warned of excessive risk in the markets for the past five years, is now sounding the alarm as hazards converge from red-hot Tech stocks, and investor confidence in SoftBank’s $100 billion fund raise. In a 22-page memo -- longer than most of his missives to clients -- the Oaktree Capital Group co-chairman said he sees several phenomena that by themselves seem reasonable but together reveal markets to be heated and risky. “Since we never know when risky behavior will result in a market correction, I’m going to issue a warning today rather than wait until one is upon us,” Marks said. “This warning is likely to feel premature, and perhaps it is, but I think it’s better to turn cautious too soon rather than wait until it’s too late.”
We’re not saying we are in this camp. To the contrary, we remain bullish on America and the stocks in our portfolio. But we want to let you know that there is another side to the bullishness and Marks above is just one of them. But this is nothing new. There are always two sides to every market and guess what? No one knows what the market is going to do in the future. So as we have said many times, if you find yourself with too much worry at night, move out of those stocks that make you nervous and move into the High Yield stocks in our High Yield and REIT portfolios. They are sleep-well stocks that are paying nice 5-10% dividends.
BMR Companies & Commentary
Amazon (AMZN: $1,020, down 1/2% - all changes are for the week)
Amazon traded lower after the company forecast a potential quarterly loss for the first time in two years, a reminder to investors that its reshaping of the worlds of Retailing and Cloud-computing industries doesn’t come without a cost. The company indicated the investment cycle is likely to continue, as it gave third quarter operating income guidance in the range of a $400 million loss to a $300 million profit. Amazon CFO Brian Olsavsky said the third quarter typically sees lower operating income because it has to prepare for the holiday peak season. Revenue guidance came in between $39 billion and $42 billion.
Amazon Web Services remains the company's main growth driver, growing 42% year-over-year, and generating $915 million in operating income. That's more than double the Amazon’s North American business's $435 million in operating income. Its international business continues to lose money with an operating loss of $725 million.
To accommodate exploding growth, the online giant has gone on a hiring spree, pledging to hire more than 100,000 people earlier this year.
The company blew away revenues but came up short on earnings. Revenues were $38 billion in the quarter, up from $30 billion a year ago. Earnings were 40 cents a share, vs. $1.78 last year.
Cash levels remain strong with over $21 billion on the balance sheet vs. just $8 billion in debt.
The company on Thursday said it is boosting spending on new warehouses to meet growing eCommerce demand, data centers for its Amazon Web Services division, video programming to keep customers engaged, and gadgets like the Echo line of voice-activated speakers to stay on the cutting edge of the emerging smart-home market. This comes after shares hit all-time highs Thursday, briefly making Jeff Bezos the richest man in the world. But Gates has staying power after Microsoft reported solid earnings, while Amazon missed estimates and the stock fell a bit.
While analysts remain optimistic about the future of Amazon and their growing revenue, the 2nd quarter earnings report from the company underscored the high cost of its business model. We at The Bull Market Report believe we are in the early stages of the shift of compute to the cloud and the transition of traditional retail online, and that the market is underestimating the long-term financial impact of both to Amazon. That said, Amazon continues to generate high returns on cash invested despite the growing scale of its investments, with significant value in early stage efforts in AI, voice, and robotics. The top line growth acceleration like that we saw in the second quarter is likely to continue in the long term
BMR Take: While EPS estimates are getting knocked around, don’t take your eye off the long term picture. Some analyst models are calling for EPS potential of near $25 in 2020. This could send the stock a lot higher. At the same time, there are many who believe Amazon is a bubble and that Bezos will never allow the company to report sizeable earnings. This is a tough one for us. We believe that Amazon will eventually turn the spigot on and report strong earnings. We aren’t sure when this will happen but we believe it will happen. But others say that he never will.
Oh my – the bulls and the bears fight it out in the end. We are sticking with our bullish stance as we believe revenues ultimately win out (as earnings are destined to follow.)
First Solar (FSLR: $49, up 8%)
First Solar raised this year’s profit forecast on improving terms for power plant sales and unexpectedly strong demand for technology that’s being phased out. This year’s EPS is now seen as up to $2.20, up from earlier guidance of 40 cents. Wow. Gross margins and sales will also come in higher after they shipped a record of 900 megawatts of its Series 4 panel in the second quarter. Big.
First Solar is benefiting from higher module prices in the U.S. as developers and distributors stock up ahead of a potential tariff on U.S. imports. First Solar’s thin-film technology has also seen gains. The sale of its 180-megawatt Switch Station solar farm also came in higher than expected, and management was optimistic for higher margins on two more plant sales later this year. They’re doing a better job of extracting cash out of their sales of plants and modules.
First Solar has begun installing equipment for its larger, more efficient Series 6 panel at its factory in Ohio and plans to ramp up production next year. Analysts estimate that panels can be produced for about 25 cents per watt, less than the 72 cents per watt floor price that may be imposed on imported panels by President Trump under a trade dispute later this year. Chief Executive Officer Mark Widmar said that he may extend production of the Series 4 module even as initial output of series 6 starts this year in Ohio and next year in Malaysia and Vietnam. Stable pricing globally and U.S. tariffs on competing suppliers will factor in that decision. The outlook sure looks good.
BMR Take: First Solar is a top player in a sweet market niche. Better energy efficiency is so important to our future. First Solar’s earnings are re-setting and returning to growth. The stock has almost doubled in the last three months.
Shopify (SHOP: $93, up 4%)
Shopify, the rising e-commerce platform dominated by small business owners, is teaming up with eBay to allow its merchants to sell directly through the online marketplace. The move adds another outlet for Shopify’s roughly 400,000 users. When Shopify signed a similar deal with Amazon in January, its stock surged as investors predicted a boost to revenue.
The company’s strategy has been to integrate with as many online channels as possible, letting its customers diversify away from their personal websites and sell on Twitter, Pinterest, Facebook, BuzzFeed and Amazon. Shopify also provides payment tools, shipping and small loans to help its users build their businesses.
Shopify is a growing player in the battle for turf in the rapidly growing world of online shopping. Instead of building a centralized marketplace such as Amazon and eBay, it provides tools for independent merchants, both large and small to sell online in various ways. It also provides point-of-sale software and hardware for physical stores, similar to Square.
Customers have been asking for Shopify to integrate with eBay for a while. We think a lot of merchants will gravitate toward this new announcement.
BMR Take: Like Amazon? Then you’ll like Shopify. It’s the same big picture story of massive eCommerce growth with a twist of being less widely known. With EPS on track to reach profitability next year, there is a big turn in the stock happening and now is an opportune time to be involved.
Square (SQ: $26, down 2%)
After building a unique payment solution that caters to micro and small merchants, Square is now in the process of rolling out more services (financing, payroll, capital) that accommodates a wider array of merchants and has been successfully moving up-market with a strengthening platform-based approach.
The company has entered a stretch where it’s investing to consolidate its services onto a singular platform with access to services, which should help improve already solid retention, and increase engagement with the company’s services driving robust volume growth. In addition, the company has successfully expanded into four countries outside the US (latest launch in the U.K.)
The company is complementing robust growth with a planned annual margin expansion from operational efficiencies utilizing machine learning and other artificial intelligence techniques.
BMR Take: Given the aforementioned factors, we believe Square is well-positioned to continue solid top-line momentum in 2017, continuing to capture the +$60 billion US market opportunity and beyond (6x opportunity globally) while driving leverage in the business. The company reports EPS on August 2nd. We see compelling upside ahead over the longer term.
Facebook (FB: $172, up 5%) Reported Earnings Last Week
For its second quarter, revenues spiked 45% year-over-year to $9.3 billion, and earnings per share came to $1.32, up 69%. Wall Street’s pros were looking for $1.13 per share in profits. They killed. The stock was up big last week in response, on top of a 44% year-to-date gain.
A few other highlights from the report:
• Daily active users (DAUs) reached 1.32 billion, while monthly active users (MAUs) hit 2.01 billion. Both were up a huge 17%.
• Mobile advertising revenues represented 87% of the total, compared to 84% in the same period a year ago. (We are amazed. 87% of revenues is astounding. We had to double-check what we read.) Remember when they went public and the world thought they had no mobile strategy? What a switch.
• During the past year, Facebook increased global headcount by 43% to 20,700.
• Facebook has $35 billion in the bank and no debt.
Here are the numbers for advertising:
Mobile ad revenue accounted for 87% of the company's total advertising revenue of $9.15 billion in the latest quarter, up from 84% a year earlier. Net income rose to $3.9 billion, or $1.32 per share, from $2.3 billion, or 78 cents per share, a year earlier.
Facebook's CFO once again warned the Street the company's revenue growth is being slowed down by a lower rate of advertisements on its properties, but the Street hardly cared, pushing price targets as high as $210, and the stock zoomed to half a trillion dollars in market capitalization, joining the exclusive club of Google, Microsoft and Apple.
The company noted that there are opportunities for incremental ad load on Instagram, increased engagement from Instagram stories, and potential for new monetization levers through Messenger and WhatsApp.
BMR Take: Facebook is an ad machine like the world has never seen. There is still so much potential ahead. With EPS pushing towards $10 over the next few years, we love this stock.
AstraZeneca (AZN: $30, down 11%)
AstraZeneca plunged after the U.K. drugmaker suffered a blow to its next-generation cancer therapy, with a new drug combination failing to do better than chemotherapy in checking the growth of lung tumors. This has posed a major setback to Chief Executive Officer Pascal Soriot’s ambitions. Imfinzi, used in combination with tremelimumab, didn’t meet a primary endpoint for progression-free survival in the study dubbed Mystic. The drugs were poised to generate more than $7 billion in sales by 2022, according to analysts’ estimates.
The failure calls into question Soriot’s ability to deliver on his growth strategy, put in place to keep the company independent when he rebuffed Pfizer Inc.’s $117 billion-takeover bid in 2014, and may make the firm vulnerable again. Imfinzi, which was poised to become Astra’s biggest medicine by sales, is the cornerstone of its cancer portfolio and key for meeting Soriot’s goal, set in 2014, of boosting revenue to $45 billion by 2023. Sales were $23 billion for 2016, so he has some serious work to do.
“Despite the outcome of the initial readout, we must be patient as the Mystic trial continues as planned to evaluate overall survival,” Soriot said in the statement. The study will continue to assess whether imfinzi or the combination of drugs can help improve life expectancy, with the results expected in the first half of next year.
The Mystic study was a crucial test for Astra’s two immuno- therapies -- a new class of drugs that activate the body’s defense system to attack tumors -- in a race with rivals including Merck, Roche Holding and Bristol-Myers Squibb to dominate the market for cancer treatments.
BMR Take: This is tough news to hear. We will keep a close eye on the situation and consider what to do about it after more careful analysis in the weeks ahead. We don’t like to panic. The stock dropped below our Sell Price of $32, so if you wish to get out you can do so on Monday. The stock came back over $1 on Friday and we are going to stick with it for a little bit more, watching the price closely.
Upcoming Economic News
Pending Home Sales Index
Monday, July 31st, 10:00 AM
Period: June
Consensus: 109.6
Prior: 108.5
Personal Consumption Expenditure
Tuesday, August 1st, 8:30 AM
Period: June
Consensus: 0.20%
Prior: 0.10%
Note: Monthly Personal Income and Outlays data are published by the U.S. Bureau of Economic Analysis. Personal consumption expenditures include consumer spending for all goods and services. These data are published on a quarterly basis in the GDP data release.
Total Light Vehicle Sales
Wednesday, August 2nd, 8:00 AM
Period: July
Consensus: 16.7 million
Prior: 16.4 million
Source: U.S. Bureau of Economic Analysis.
Average Workweek
Friday, August 4th, 8:30 AM
Period: July
Consensus: 34.5
Prior: 34.5
Note: Establishment survey data measuring the average workweek for production or nonsupervisory workers on private nonfarm payrolls.
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
It looks like it's a pretty done deal for the S&P 500 to hit 2500 based on a very good earnings trend reported so far. One exception was Google - it went down even though its gross revenues and underlying ad metrics were good. It also beat its earnings per share estimates, but the investment community figured out this beat was driven by taxes and that for the first time in 5 years, traffic acquisition spending outpaced revenue growth. This reminds us of the typical slaughter of a stock because its earnings missed by a penny.
When you think about investing to grow your money into the future, an investor has to be more of a longer-term investor than one single quarter. Big trends don't come and go on a single quarter's earnings. And, speaking of big trends, what giant long-term trends come to mind first? The "no-brainer" is of course Technology – everything from mobile, the cloud, augmented reality, artificial intelligence, alternative energy and autonomous cars. But there is a sector that is bigger than Technology and has beaten it by 300% since 1999.
Healthcare. In a way, it is comprised of a great deal of "technology" on its own – think biotechnology and all of the remarkable medical devices being created. Healthcare also offers just as much innovation and diversification as technology – there are 800 companies and 12 industries to choose from. And today, there is not one but four "mega-trends" fueling the long-term trend behind Healthcare.
The first and most important is of course the once-in-a-lifetime baby boomer demographic tsunami which will drive it for another decade. Secondly, there is a new age of genetics and medical technology which has ushered in unprecedented advances in scientific and medical research. Companies, investors and charities are pouring billions of dollars yearly into R&D, and this is a trend with no end in sight as they seek to find cures for every disease on earth. Thirdly, earnings have been a classic example of what a mega-trend looks like. In 2016, the Healthcare sector was responsible for nearly 20% of the earnings in the S&P 500, bigger than the Financial, Energy, and Telecom sectors combined.
Yes, we are aware there are concerns that the government will try and hold down drug prices. These are, we believe, going to be overcome by the simple concept that everyone can agree they do not want companies to stop trying to find a cure because they no longer can make a profit.
The last trend is that of mergers and acquisitions. The big Pharma companies need to keep their pipelines full and avoid the revenue drops created when patents expire. During this bull market, over $500 billion in deals have been done, mostly by big drug companies buying emerging Giotechs. While the pace of M&A may slow down, we believe it will always be a positive force driving values in the Healthcare sector - especially if any tax reform policy unleashes a tidal wave of overseas corporate cash onto US shores.
Thus, the moral of this story is: If you own a "mega-trend" such as Healthcare, don't let a bad quarter in the stock market make you react like the investor who bails out of a stock because it missed that quarter's expected numbers. Markets go up and down, but Healthcare is a mega- trend we believe won't stop this decade and probably not in the next one either. We think we are right in the middle of this one.
Tesla Update
Tesla (TSLA: $335, up 2%) announced the first deliveries of Its Model 3 on Friday. There was big fanfare and discussion of the 500,000 orders they have for the car and how they are going to ramp up production from 90,000 cars this year to 500,000 next year. We see a coming let-down on this number and we are sure Elon is working on the language now that he will use to tell us that he is not going to make the numbers. But with that said, the company is amazing. The cars are spectacular. Customers rave about their cars like never before. And in the next five years this firm will become one of the greatest firms in the world. (You heard that here first at The Bull Market Report!)
Here are a few tidbits of things the Elon Musk is talking about:
Musk said that by 2020 Tesla will likely be able to make its cars go as far as 745 miles per charge.
The current record for hypermiling in a Tesla is about 560 miles. What is hypermiling? By taking it easy on the gas pedal and brakes, hypermilers achieve gas mileage feats far beyond the fuel economy ratings given to cars by the Environmental Protection Agency. They coast to stop signs, accelerate slowly, and sometimes raise the ire of other drivers.
The official range for Tesla's Model S is about 315 miles per charge, and note that the Model 3 was announced Friday with a range of 310 miles, up from 220 miles that most thought. Do you think Tesla will NOT continue to enhance the batteries over time? If you don’t, you are delusional. There is no question about this in our mind.
Here is some of the Press Release from Tesla on Friday, paraphrased by Bloomberg.
“Three hundred ten.
“That’s the electric range of a $44,000 version of Tesla’s Model 3, unveiled in its final form Friday night. It’s a jaw-dropping new benchmark for cheap range in an electric car, and it’s just one of several surprises Tesla had in store as it handed over the keys to its first 30 customers.
“Tesla has taken in more than 500,000 deposits at $1,000 a piece, Chief Executive Officer Elon Musk told reporters ahead of the event. This has created a daunting backlog that could take more than a year to fulfill - and that was before Musk took the stage in front of thousands of employees, owners, and reservation-holders to lift the curtain on the company’s most monumental achievement yet.
“We finally have a great, affordable, electric car - that’s what this day means,” Musk said. “I’m really confident this will be the best car in this price range, hands down. Judge for yourself.”
Here’s some of what Tesla disclosed at its plant in Fremont, California:
Two Battery Versions
Tesla has simplified the manufacturing process “dramatically,” Musk said. In the same factory space where Tesla can build 50,000 Model S or Model X cars, it will soon be able to produce 200,000 Model 3s. Part of that is due to a simplified package of options.
The car comes in two battery types: standard and extended range. Here’s how they break down:
Standard Battery:
Price: $35,000
Range: 220 miles (EPA estimated)
Supercharging rate: 130 miles in 30 minutes
Zero to 60 mph time: 5.6 seconds
Long Range Battery:
Price: $44,000
Range: 310 miles
Supercharging rate: 170 miles in 30 minutes (Same as Tesla’s Model S)
Zero to 60 mph time: 5.1 seconds
Only one other electric car in the world has broken the 300-mile range barrier: The most expensive versions of Tesla’s Model S, an ultra-luxury car that costs $97,500 or more. The new Model 3 has cheaper range availability than the current record holder, the $37,500 Chevy Bolt, which is outclassed in nearly every way by the Model 3.
Take a look at this video of the introduction of the Model 3:
https://www.bloomberg.com/news/articles/2017-07-29/tesla-s-model-3-arrives-with-a-surprise-310-mile-range
The High Yield Report
By Michael Foster
Special to The Bull Market Report
One of the biggest stories this week in high yield was Welltower’s (HCN: $73) earnings report, which was a very slight disappointment. Revenue fell 2%, slightly short of expectations, to $1.06 billion. FFO of $1.06 was a one-cent beat, again demonstrating Welltower’s continued acumen at financial discipline. The stock was offer a minor 1% for the week.
What about the dividend? Well, the company’s annual dividends are currently $3.48, with an annualized dividend coverage of 122%. That’s good, but admittedly not fantastic - our general rule of thumb is 130% or more dividend coverage should be every REIT’s target. Yet the company’s massive scale - we’re talking about a $27 billion market capitalization company with $30 billion in assets on the balance sheet - indicates that the income stream is extremely well insulated from a sudden market shock. Welltower also reported some interesting developments both in this quarter and in the future, including two properties spanning over 100,000 square feet that are 100% fully occupied. Partly because of this, the company raised its guidance.
Also significantly, Welltower’s borrowing costs went down. The company has lowered its net debt and improved its debt ratio in the quarter - a wise move considering the higher borrowing costs that are impacting the entire high yield universe. This is another indication that Welltower’s dividend coverage, while slightly soft now, will improve over the coming quarters. For this reason, there is a good reason to hold firm and keep buying this stock.
Also this week, we saw Omega Healthcare Investors (OHI: $31) report results quite similar to Welltower, and it too fell over 1% following the news on that day. The company saw revenue rise 4% a touch short of expectations at $194 million with EPS of 87 cents, which was a 2 cent beat. Again financial discipline was at play for the dynamic. Adjusted FFO rose over 3% from a year ago and the company raised its guidance, now expecting full year FFO to be between $3.42 and $3.44. The company also raised its dividend by a penny, continuing its history of raising dividends every quarter.
How did it do this? A big part of the REIT’s results center around its financing strategy. The company retired some unsecured credit and borrowed with new senior lines of credit, helping to lower overall borrowing costs for the firm. Omega also spent $8 million in new investments in the first quarter while spending another $30 million to renovate existing and build new facilities. The new investments include $180 million worth of property - $115 million in the U. K. and the rest in America.
Omega is doing what it does best: expanding its footprint, finding new opportunities, and improving rent potential with existing properties while increasing its dividend. If the REIT reaches its FFO guidance, the dividend coverage ratio will stay over 130%. Yet the stock is down 3% for the week (after the 64 cent dividend Friday) and is yielding a monstrous 8.2%. This is clear irrationality, and tells us that Omega isn’t just a hold - it’s a strong buy. Investors long this stock should continue to appreciate the dividends and expect their growth to continue. Now is a good time to buy more.
Elsewhere in REIT earnings, Ventas (VTR: $67) reported a revenue beat with 5.6% year-over-year growth to $895 million and EPS of $1.06, a penny above expectations. The company also re-affirmed full-year guidance of $4.15 FFO per share, giving it a dividend coverage ratio of about 133%, around the same as Omega Healthcare. Ventas’s long history means that its yield is quite a bit lower as the market trusts this bigger company. Its $24 billion market cap shows strength and diversification. But 4.6% is a very strong income stream in today’s reality of low interest rates, so this stock continues to be a buy for investors who are looking for income.
What about their future? The company spent $110 million on investments in the second quarter to expand its footprint and provide greater dividend growth for investors in the future. There’s just one snag - Ventas funded this with common stock instead of debt, as Omega did. That’s a trifle concerning. Does the Ventas management believe their company’s stock is overpriced? Total liabilities of $13 billion are 56% of the company’s total assets, giving it a pretty decent debt-to-asset ratio that would justify more lending activity. So why is the company issuing shares, thus diluting investors’ positions in the firm?
A large part of it has to do with the relatively low yield on common shares right now - that 4.6% is lower than the rising borrowing costs that floating-rate loans would cost Ventas in the future. So there’s some logic to the move, whereas Omega’s 8% yield is far too costly to issue too many shares versus the 5% or less borrowing costs on debt that Omega can get through bonds and loans. Thus the financial activities of both REITs, while different, make a lot of sense in their own context.
It seems pretty clear that, in a busy week for Healthcare REITs, the recent earnings releases give renewed confidence to stay long these companies and to continue to collect their dividends. Omega seems to be the strongest buy right now, and it makes sense to buy the company at any point when the dividend is more than 8%. We suspect that won’t last long, so it makes sense to add on to your Omega positions now.
Good Investing,
Todd Shaver, CEO, Editor in Chief, Founder
The Bull Market Report
Since 1998
July 9, 2017
by Todd Shaver | Jul 9, 2017 | Weekly Newsletter 7pm Sunday
Climbing A Wall Of Worry
At the moment, everyone’s focus is on Trump’s G20 meeting as well as his first sit down with Vladimir Putin. Why care? Well… The G20 is comprised of the world’s wealthiest nations, so it is quite a powerful platform for business discussion. The big takeaway from the meeting was leaders like China’s Xi Jinping promoting an open world economy that contrasts Trump’s nationalist push. Trump believes in fair trade as opposed to free trade. Global trade policy has a huge potential impact on the bull market so watch closely.
Trump also sat down with Putin for their first face to face meeting. The two confronted issues over election meddling in addition to a variety of topics. Everybody is on guard about Russia and North Korea starting another war, so again this is really important stuff, in terms of watching out for the next Recession. But for now, the outlook is bright and the bull market continues to climb a wall of worry, which it has done for 100 years. In fact, there are no good old days. The market wakes up every day and worries about something. And the market generally goes higher, decade after decade.
There is always a bull market here at The Bull Market Report! This week we highlight the following stocks: Tesla, Shopify, Apple, Facebook, Square, and PayPal.
Highlights From The Past Week
Concerns over falling oil prices just won’t go away. After rig count falling for the first time this year last week, Baker Hughes reports US oil rig count rose once again for the 23rd week in the last 24. To support prices in the mid-$50s, OPEC would need to lower production by another 200,000-300,000 barrels a day and extend the output agreement to the end of 2018. We find this unlikely. OPEC cuts have had a tough impact on the oil market, driving prices much lower. Based on current trends, the oil market will be oversupplied again in 2018. Accordingly, we are likely to see the U.S. rig count steady to lower to keep oil output from flooding the market in the next 12-18 months. Ouch! More pain for oil ahead!
Second quarter numbers are in. The Nasdaq was up 4%, the Dow was up 3%, and the S&P 500 was up 2.6%. Not a bad quarter. So despite the Tech falloff since June 9th, the Nasdaq outshone the overall market. What will the third quarter bring? Well wouldn’t you like to know! We are not telling. We know, but aren’t telling. Well – not really. No one knows of course, but we think the Tech selloff will blow over as the FAAMG* stocks report fabulous earnings and the buying resumes.
* FAAMG – Facebook, Apple, Amazon, Microsoft and Google. Over $2.8 trillion in market cap.
Are central banks blowing bubbles? Wall Street strategists are calling attention to how central banks policies around the world are promoting inequality through Wall Street inflation coupled with Main Street deflation. In other words, the rich get richer from low interest rates spurring asset price bubbles, and the poor struggle against lackluster real economic growth. Now central banks need to quickly and painlessly undo their error. There are only two ways to cure inequality - you can make the poor richer or you can make the rich poorer. What a mess. They need to get GDP growth actually going again and normalize interest rates. So far not much progress to report.
This week we observed that the Swiss government could have issued a 50-year bond at a negative yield. Does this make any sense? If so, feel free to send us your money here at The Bull Market Report along with some interest and we are sure to be happy to hold onto it for you and return it in 50 years!
Tech titans could trigger rewrite of antitrust rules. Investors have spotted a vulnerability in the giant companies like Alphabet, Facebook, and Amazon. Since June 26 - the day before European regulators fined Google a record $2.7 billion in an antitrust case - the search giant’s stock has fallen 5%, versus a flat performance for the S&P 500. That works out to more than $30 billion in market value erased. Europe regulators have challenged the monopolistic business models Silicon Valley is printing money with. Well, stay tuned. There is a bunch of talk these tech titans will soon fight back. This may be the beginning of a big buying opportunity in Tech.
BMR Companies & Commentary
Tesla (TSLA: $313, down 11%)
After a week full of abysmal news for Tesla, the weekend couldn't come fast enough for Elon Musk. Tesla registrations in the country fell 10% in April from a year ago, based on IHS Markit data. The latest report showing a plateau for Tesla's products comes amid both investor concerns that demand for Tesla's luxury Model S sedan is waning ahead of the mass market Model 3 launch. With the sales of its Model X actually declining. Tesla may likely have to kiss its aggressive growth forecasts goodbye. Then again, they may not. There is lot going on here at the company and the future is wide open.
Tesla said that second-quarter global deliveries rose 53% from a year earlier, to just over 12,000 of the Model S and over 10,000 of the Model X. Musk blamed battery pack production problems for holding back vehicle output in the second quarter until early June, even though Tesla produced 2,000 more cars than it sold.
BMR Take: Things don’t always go right. That’s life. That’s business. But Elon Musk has been here before. This is what he does best. He solves problems. He innovates. He overcomes. It’s a controversial mood in the stock market for Tesla. But that creates a buying opportunity. While the company is losing money now, the Street consensus is for $12 in 2020, making this situation very interesting. As we have said many a time, this stock is not for the faint of heart. It could go to $250 or $200 before it goes to $400 or $500. But if you can handle the volatility, we believe it can get to $500 and beyond in the years ahead.
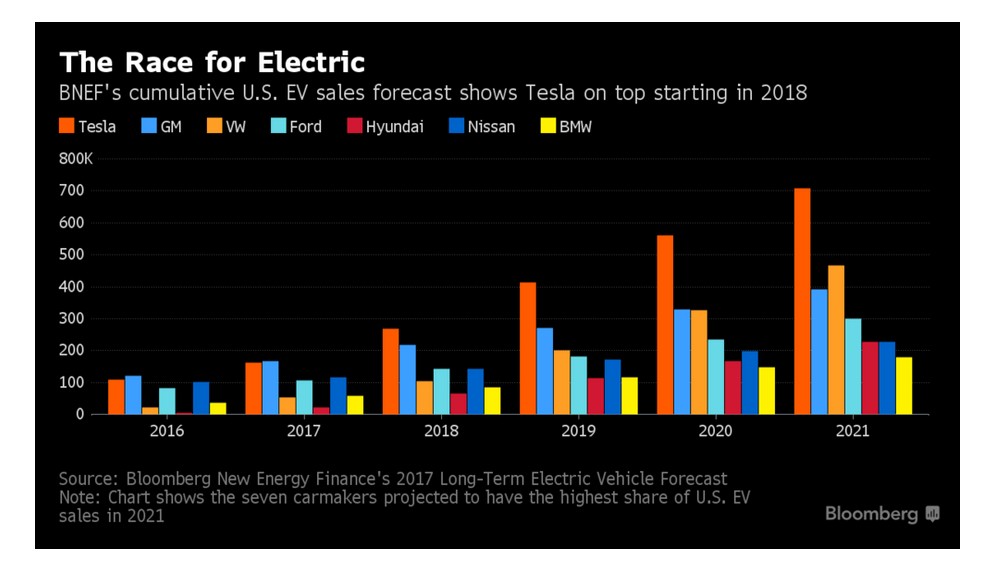
We saw a pretty good article from Bloomberg recently. The headline was “Tesla Projected to Win U.S. Electric-Car Race.” More than a dozen automakers are jostling to lead the U.S. electric-car race, but Bloomberg New Energy Finance (BNEF) sees a clear winner separating from the pack: Tesla.
BNEF expects Toyota’s Prius Prime plug-in hybrid to be the exception and hold the title of best-selling electrified vehicle in the U.S. this year. Tesla will get off to too late of a start with its Model 3 to catch up, with Musk planning to hold a handover party for its first 30 sedan customers on July 28. The company is aiming to ramp-up production to a rate of 20,000 cars per month in December.
“In the long term, we see battery electric vehicles winning because of the battery cost curve,” Bloomberg said.
Shopify (SHOP: $89, up 2%)
This past week, as you logged in to Shopify to check your sales or fulfill orders, you noticed a change: Shopify has had a makeover. The new look and feel is part of a broader effort to build the future of Shopify and supporting apps with one design mind, using the same set of guidelines. The improved design is now live in every Shopify store.
Why does it matter? Change can be hard sometimes, but these changes were actually designed to simplify the day-to-day navigation. The fresh look brings consistency across Shopify products, helps pages load faster, and makes content and menus easier to find and read.
BMR Take: Shopify is among the most exciting growth stories in the market today. EPS is expected to go from negative this year to $1.25 by 2020 starting what is expected to be a long term trail of sustainable EPS growth.
Apple (AAPL: $144, flat)
Apple has declined 7% from its all-time closing high of $156.10 in May, but the recent selloff represents yet another buying opportunity as investors turn their focus to the iPhone 8 launching this fall. Apple's quarterly results will be less important this summer as investors focus on the iPhone 8 this fall, along with the company's increased dividends and stock buybacks, lower valuation and new innovations as showcased at Apple’s Worldwide Developers Conference.
The upcoming iPhone cycle is setting up Apple to reach fresh all-time highs in the next 12 months, which would value the iPhone maker at over a trillion dollars. Apple's current market capitalization is around $750 billion. Wow!
There has long been an expectation that the next high-end version of the iPhone would have a new type of screen called an OLED (organic light-emitting diode). OLED screens boast more vivid colors and improved battery life. But they are also more difficult to produce, particularly at the levels that Apple requires for the iPhone. We believe that Apple will introduce this screen in the iPhone 8.
BMR Take: Apple remains among the most underappreciated stocks in the world. We looking at about $9 of EPS this year heading toward $11 in the next 1-2 years, giving it a forward PE of 13. Very low in our opinion.
Facebook (FB: $151, flat)
Facebook is building a village that will include housing, a grocery store and a hotel. Billions of people spend a lot of time living their lives on Facebook's social network. Now Facebook wants to try its hand at creating a community in the real world. In short, Facebook wants to build its own town.
Facebook unveiled plans on Thursday for the massive new construction project at its Menlo Park, California corporate campus, which is part of Facebook's plans to expand its home base. The 56-acre site, which Facebook bought in 2015 for $400 million, is located directly across the street from Facebook's headquarters. It will offer 1.6 million square feet of housing, or 1,500 units.
In a blog post announcing the plans, Facebook described the future development as a "mixed-use village" that will provide residents, many of which will be Facebook employees, with housing, transportation services and other amenities.
It will take roughly a decade to build. The initial phase of the project, which will include the housing and a grocery store, will be wrapped up in the first half of 2021. The subsequent phases will be completed every two years.
BMR Take: What can we take from this? The company is pretty confident in their 10-year plan and the outlook for their business to be making these kinds of internal investments. This year’s EPS of $5 is expected to double by 2020. With 2 billion users now, don’t miss being involved in this adverting giant’s success.
Mark Zuckerberg was quoted in the past week: “Give people the power to build community and bring the world closer together." Zuckerberg called the statement an extension of the company's original mission of making the world "more open and connected."
Facebook's unprecedented reach can be a powerful tool for tackling global problems and democratizing access to people and knowledge. "We feel like our responsibility is expanding, especially around passing this milestone of 2 billion people in the community," he said. "We’ve been thinking about what our responsibility is in the world and what we need to do."
We’re with you, Zuck!
PayPal (PYPL: $54, flat)
PayPal launched a campaign to reward freelancers in India. PayPal India has launched two new campaigns - Shopping Buddy and Go Global. The new campaigns will encourage Indian consumers and freelancers to buy and sell across outside of the country. Both campaigns will work on the concept of referrals. Available in more than 200 markets around the world, the PayPal platform, including Braintree, Venmo and Xoom, enables its over 200 million users to receive money in more than 100 currencies, withdraw funds and hold balances in their PayPal accounts.
Why did PayPal design the campaigns specially for the Indian market? India is the 2nd largest freelancer market outside of the US. India is also a hub for software exports, hence software and web related services constitute a significant portion of the freelancing business. Additionally, skilled women who have taken a break from their careers to manage the household, and retired professionals also contribute to this growing number in India.
BMR Take: PayPal is quietly emerging as a global payments power. India is so important to winning this battle and the above news is a great step in the right direction and a demonstration of the company being locked in on what needs to be done. With greater than 20% EPS growth as far as the eye can see, how can you not be involved here?
Square (SQ: $24, up 1%)
Payment-processing stocks had a hot week after a $10 billion deal between two industry players was announced. The news that Vantiv was buying London-based Worldpay for $10 billion has investors suddenly thinking about other combinations. Square shares rose 4% on Wednesday as result and finished the week strong.
For Square investors, consolidation in the payments industry is encouraging, because it means the fast-growing company could also be thought of as an acquisition target. PayPal is a much larger company than Square, with a market value of $66 billion, compared to $9 billion for Square, and it’s less likely a target. In fact, it’s a company that likes to acquire.
However, you look at it, the market is quickly realizing that the world is migrating to eCommerce and Square is as best-positioned as anybody.
BMR Take: Square is currently growing revenue at a 30% clip. Takeout valuations could be anywhere over a 20% premium to the current stock price. A compelling opportunity.
Upcoming Economic News
Consumer Credit SA
Monday, July 10, 3:00 PM
Period: MAY
Actual: N/A
Consensus: $13.3B
Prior: $8.2B
Note: Federal Reserve Statistical Release G. 19, Consumer Credit, reports most short- and intermediate-term credit extended to individuals, excluding loans secured by real estate.
JOLTS Job Openings
Tuesday, July 11, 10:00 AM
Period: MAY
Actual: N/A
Consensus: 5,975K
Prior: 6,044K
Note: Part of the US Bureau of Labor Statistics, the Job Openings and Labor Turnover Survey (JOLTS) program produces a monthly study that has been developed to address the need for data on job openings, hires, and separations. With the release of May 2003 data, the JOLTS program began publishing industry estimates based on the North American Industry Classification System (NAICS).
PPI ex-Food & Energy
Thursday, July 13, 8:30 AM
Period: JUN
Actual: N/A
Consensus: 0.10%
Prior: 0.30%
Note: The Producer Price Index (PPI) for all items less food and energy, often referred to as Core PPI, excludes the two most volatile components of the overall PPI for Finished Goods.
Manufacturing Production M/M
Friday, July 14, 9:15 AM
Period: JUN
Actual: N/A
Consensus: 0.10%
Prior: -0.39%
Note: Manufacturing production index measures real output in manufacturing. According to the NAICS, manufacturing relates to the mechanical, physical, or chemical transformation of materials, substances, or components into new products. Data is percentage change in relation to the last month.
An Update on Government Properties Income Trust (GOV: $17.90, down 2%)
This is what we said a week ago Wednesday, June 28th:
“First Potomac Realty Trust (FPO) is being acquired in a $1.4 billion deal announced today. The stock of Government Properties (GOV) is down 7% this morning to $20.25. First Potomac is a REIT with 11 million square feet of office space in and around Washington, DC. Government Properties, at a market cap of $1.4 billion, will now have an opportunity to prove its worth and assimilate the properties. This is creating a buying opportunity if you believe that management can turn around this company We believe they can and would be buyers of the stock here at the $20 level.”
Then last week we wrote this:
“Government Properties Income Trust (GOV: $18, down 19%)
“Don’t fall over in your chair! The stock got crushed this week, but it was because of an acquisition. Let us explain.
“First Potomac Realty Trust (FPO) will be acquired by Government Properties. To finance the deal, the company sold 25 million shares in a secondary at $18.50, raising over $450 million. They had to knock the stock lower to get the funds they needed. This is typical. We believe the deal will work out well, and that we will see a full recovery and then some.
“And the underwriters have been granted a 30-day option to purchase up to an additional 3,750,000 common shares. Two things: These overallotments are exercised about 99% of the time so expect to see another $65 million of cash in the bank. And expect to see the stock stay around this level for a month. Then there is a great likelihood that the stock will move back into the low 20s.
“You should be excited. The acquisition of First Potomac Realty Trust enables Government Properties to expand its business strategy to include the acquisition, ownership and operation of office properties leased to both government and private sector tenants in the metropolitan Washington, D.C. market area. The metropolitan Washington market area is one of the largest office markets in the U.S. and the nation’s largest beneficiary of spending by the U.S. government. Outside of the metropolitan Washington market area, Government Properties will continue to focus on acquiring, owning and operating office properties that are majority leased to government tenants.
“In addition to this transaction providing Government Properties with new potential growth opportunities, management expects to realize approximately $11 million of annual general and administrative expense savings compared to First Potomac Realty Trust on a standalone basis.
“Management is very pleased that they were able to achieve an attractive per share purchase price. Their preliminary estimates call for meaningful accretion and more detail will be forthcoming.
“BMR Take: NAV was $20.90 prior to raising some equity at $18.50. We don’t see any reason for the stock to trade at a discount to the lower level of $18.50. This is a buying opportunity for sure. Why do you think institutional investors just took down 25 million shares at $18.50? Get on board and put new money to work at a 9.4% yield right here in this name!”
Here’s our Take this week:
There have been no changes in the situation since the announcement. The stock is down 2% this past week, which is just noise, but we see that the stock has stabilized here at the $18 level, and in our opinion the only move the stock can make from here is up. The stock is paying a 9.6% dividend which is a bit too high historically, and thus a higher stock price will lower the dividend to the 8-9% ranges which we believe is quite sustainable. We are holding here and await the move back to the $20 level in the next few months.
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc
An old stock market adage is "Calling a market top is a fool's errand." A Wall Street research firm wrote last week that calling a market top in today's market is just such a fool's errand because there is simply too much empirical evidence against it. First, the employment picture is pretty good from the standpoint of new jobs creation. (Of course, "if" new job numbers begin to substantially decline, it would be a red flag). Secondly, the latest Consumer Confidence Board report topped expectations. This indicates that consumers (70% of our economy is consumerism) are going to continue to consume. This is the engine that drives earnings. Lastly, the usual red flags that signal a major top just aren't visible – things like an inverted yield curve, a major technical breakdown (Nasdaq plunging below its 50 or 100-day moving averages), or, on a global basis, a major event such as a default by Italy or an economic collapse in China.
This is by no means to say that the market won't have a "top" in the sense of a "10% correction". It can happen even when nothing has really changed the fundamentals of the corporate earnings picture or for no real reason except media-hyped panic. There are many things happening in the market today that historically signal the possibility of a pullback in the 3-7% range. But long-term investors don't sweat the small stuff. It just isn't worth the aggravation and mental stress to try to time market corrections other than to possibly raise a little cash or to have some ready cash available to buy the dip. This is because it is nearly impossible to exit a stock, watch it drop 10% and then get back in before it jumps back up 5% before the opening bell one morning. It is literally impossible for anyone to successfully employ this kind of strategy.
The greatest risk ahead now seems to be what happens in Washington over the next few months, which is unfortunate. These events could either cause a market melt-up or a worse than average pullback – neither of which is predictable. Regardless of current conditions, in 90% of any market environment it makes sense to dollar-cost average large cash positions over several months as opposed to going all-in. That's because (quoting Ben Bernanke), "…….the 'market' is a very difficult subject. I've compared it to trying to learn how to repair a car when the engine is running…." It is difficult, but a long-term investor who is diversified and in quality assets will be just fine.
The High Yield Corner
By Michael Foster
Special to The Bull Market Report
The week was a bit harsh to many high yield investments, but a quick glance at The Bull Market Report picks shows that this is the result of a weak and temporarily frightened market The fundamentals, however, remain as strong as ever.
Starting with REITs, we saw Welltower (HCN: $73) fall 2% for the week, with those losses occurring almost entirely on Thursday. The marketwide weakness we saw did not leave REITs alone, so the decline was particularly pronounced here. However, Welltower shareholders should not despair; they’re up 9% year-to-date including the current near 5% dividend yield thanks to a dividend increase earlier this year. And dividend increases are very likely to continue. Over the last 12 months, Welltower has earned Funds from Operations (FFO) of $4.45, which gives the company a 130% dividend coverage ratio. As a rule of thumb, anything over 120% in REITs is healthy and anything over 125% indicates that the current schedule of dividend increases is likely to continue. For Welltower, that means a once-yearly pay raise is likely to continue.
This is a pretty big relief because higher borrowing costs in recent months have not been offset by higher rents for many REITs. That’s caused a lot of panicked selloffs throughout the sector, and Omega Healthcare Investors (OHI: $32) is no exception. The stock has been pretty heavily range bound after falling significantly in late 2016 - it's down 5% from a year ago - as it has been several times in 2017. Fortunately, the stock is up 3% from the start of the year so the bearish trend is clearly over even if we haven’t seen a breakout.
The interesting thing with Omega Healthcare is that investors frequently fret over the company’s dividend coverage. Omega’s management increases the dividend by a penny per share every quarter - and that is attractive to shareholders while also threatening the dividend coverage ratio. The only way Omega can cover those higher payouts is to aggressively expand. That causes frequent panics and a lot of anxiety, but a quick look at the numbers shows how silly those worries are. For the last four quarters, Omega’s FFO of $3.45 is far above the $2.50 annualized payouts at the current dividend rate and still higher if we assume penny-per-quarter payouts for the next four quarters. Either way, we’re talking about a dividend coverage ratio in excess of 130%, indicating that the dividend is absurdly safe despite the 8% yield that the stock currently offers.
In addition to the dividend payout growth fears, Omega has suffered from worries about uncertainty in Healthcare and the future funding of Medicare. Of course, Omega isn’t the only REIT suffering from this concern. Sabra Health Care REIT (SBRA: $23) fell 4% in the last week at a much higher rate than the marketwide decline in REITs. Fortunately, however, Sabra has been doing extremely well for a long time, meaning this selloff has little significant for long term shareholders. The stock is up over 12% from a year ago excluding its 7% dividend payout. And, as with Omega, the dividend is being covered by strong FFO - over the last 12 months the dividend coverage ratio for Sabra has been 130%, which is extremely solid, as with Omega. But investors fret over politics more often than they should, meaning Sabra isn’t getting the buy-in from investors that it deserves. That will change when the market goes back into risk-on mode*.
* When the market goes back to having an appetite for things like growth stocks, junk bonds, and REITs, instead of plowing into Treasuries.
Finally, Ventas (VTR: $67) is The Bull Market Report’s third Healthcare REIT pick that is known for its longer history and reliable dividend payments. As such, its yield is 4.6% following the near 3% price decline for the week. But as with our other Healthcare picks, Ventas is up for 2017 - up a solid 7% since the start of the year. The panicked Healthcare REIT selloff of late 2016 has been correcting itself in recent weeks and that is likely to restart again in the future as soon as this week’s hysterical fear ceases. No one knows when that will come, but it surely will; we’ve seen the market freak out suddenly several times since President Trump’s election, but the selloffs tend to be very brief and very shallow.
An interesting question to ponder is how this selloff and fear-based selling impacts municipal bonds, a safe haven for risk-averse investors. So far, 2017 has been pretty good for the asset class after a brutal 2016 selloff thanks to risk-hungry investors shifting to stocks. So far for the year, Invesco Municipal Trust (VKQ: $12.69) is up 4% - but the stock is still down 10% from a year ago. That gives the fund plenty of room to run in 2017, especially when we consider the fact that the fund is trading at a 6% discount to its net asset value. Similarly, Nuveen Municipal (NVG: $15.15) is up 5% for the year but is down 7% from a year ago. Like the Invesco fund, this is trading at a 6% discount to its NAV, providing another opportunity for gains as the market gets more excited about municipal bonds as a viable and lower-risk alternative to stocks and Treasuries, especially given the extra value that late 2016’s selloff provided. We are at the beginning of a trend in that direction, and it is likely to continue for quite some time.
Good Investing,
Todd Shaver
Founder, CEO and Editor
The Bull Market Report
June 19, 2017

by Todd Shaver | Jun 19, 2017 | Monthly Newsletter Daily 12pm if new
The Week Just Passed and the Week Ahead
Amazon set fire to the market on Friday as they announced a major deal to buy Whole Foods. Grocery stocks plunged as everybody wonders how much havoc Amazon will have in the new industry vertical. The M&A announcement re-energized the market that had been sagging due to FAAMG* stocks slowing down. But clearly there is a reason the FAAMG stocks are market leaders: they are the most innovative, the most savvy, and the most aggressive companies on the planet when it comes to raising the bar. The bull market in Technology that everybody was questioning just last week is alive and well!
* FAAMG – Facebook, Apple, Amazon, Microsoft and Google.
We are pleased to see the market come back strongly today, Monday, as we write this. The market is up 110 points on the Dow, with Apple, Facebook and Shopify making strong moves. And good old Amazon, which we profile below, just hit $1000 a share again. Go Bull Market.
There is always a bull market here at The Bull Market Report! This week we highlight the following stocks: Amazon, Apple, Facebook, Tesla, Annaly, and Google.
Highlights From The Past Week
Trump Says ‘Very Good’ GDP Numbers Are Coming. He May Be Right. President Donald Trump said Thursday that “some very good numbers” are coming out soon on U.S. economic growth. If he’s talking about the second quarter, he’s probably right, though the figures are about six weeks away from publication. While the White House didn’t immediately respond to a request to clarify Trump’s comments, there are wide expectations among researchers that the rate of expansion in the April-to- June period will rebound from a first-quarter slowdown. The pace of gross domestic product gains was dragged down earlier this year by temporary factors such as warm weather that resulted in lower utility bills. Seeing a pick-up in GDP growth is a major positive for the stock market.
The Sweetest Stretch of Bull Run Since 1995 is At Risk as Buy-The-Dip Strategy Fails. The sell-off in the Tech sector that started a week ago has erased $250 billion from the value of technology shares and is threatening to end the industry’s longest stretch of uptrend in more than two decades. Down around 4% since the decline started, this move has put the Tech sector on the edge of breaking its 50-day moving average. It’s stayed above the threshold for 131 consecutive days, the longest stretch since 1995. Are the good days ending? The last two times when the 50-day average was broken, Tech shares did poorly in the next few months. What do we make of this? Stocks can’t go up forever. We are seeing the Tech sector take a breather and would buy this weakness.
Don’t Be Tempted To Buy High-Flying Equities. Stick With Solid Stock Picks Recommended By The Bull Market Report. Bond investor Bill Gross warned on Tuesday that investors should reduce their risk appetite, given the U.S. growth rate is stunted by secular forces "which monetary and even future fiscal policies seem unable to reverse." In his June investment outlook letter, Gross of Janus Henderson said: "Strategies involving risk reduction should ultimately outperform 'faux' surefire winners generated by central bank printing of money.” He continued, "It’s the real economy that counts and global real economic growth is and should continue to be below par." Gross runs the $2.1 billion Janus Henderson Global Unconstrained Bond Fund.
BMR Companies & Commentary
Amazon (AMZN; $988, +1% for the week; up $23 on Friday)
Amazon is guided by four principles: customer obsession rather than competitor focus; passion for invention; commitment to operational excellence; and long-term thinking. Customer reviews, 1-Click shopping, personalized recommendations, Prime, Fulfillment by Amazon, Amazon Web Services - AWS, Kindle Direct Publishing, Kindle, Fire tablets, Fire TV, Amazon Echo, and Alexa are some of the products and services pioneered by Amazon.
Amazon and Whole Foods Market announced that they have entered into a definitive merger agreement under which Amazon will acquire Whole Foods Market for $42 per share in an all-cash transaction valued at $13.7 billion, including debt. This is Amazon’s biggest acquisition ever. Whole Foods will continue to operate stores under the Whole Foods Market brand and continue to buy from trusted vendors and partners around the world. John Mackey will remain as CEO of Whole Foods and the headquarters will stay in Austin. The deal is expected to close by the end of this year.
For Amazon, the deal marks an ambitious push into the mammoth grocery business, an industry that in the United States accounts for around $800 billion in annual sales. Amazon is also amplifying the competition with Walmart, which has been struggling to play catch-up to the online juggernaut. Amazon has designs on expanding beyond online retail into physical stores. The company is slowly building a fleet of outlets, and much attention has been focused on its supermarket dreams. It has already made an initial push through AmazonFresh, its grocery delivery service. Now, BANG, just like that, they will have 430 stores in place for delivery and warehousing. Is Bezos smart or is Bezos smart?
BMR Take: The current consensus EPS outlook calls for almost $7 this year going to $27 by 2020. That’s explosive growth and the innovation machine known as Amazon is far from done. Amazon remains one of our top favorites. And DO NOT be disconcerted by the price of the stock. If you want to buy $15,000 of Amazon, buy 15 shares. Don’t agonize over it. Just be invested in this great company.
Apple (AAPL; $142, down 4.5%)
After an action-packed world-wide developers conference (WWDC) with a plethora of new software and hardware announcements last week, the stock was under pressure all week. The sell-off in Apple represents yet another buying opportunity. With the expanding capabilities of Apple's network of hardware and software products, Apple is very well-positioned to capitalize on the trend toward more "things" becoming a computer. Last week, Apple filled key gaps in its portfolio with entry into the digital home assistant market with HomePod, combined with new AR and VR initiatives* to support these important trends. This further expands the breadth and depth of Planet Apple, making it more difficult for competitors to offer an experience at the same level of Apple.
* Augmented and Virtual Reality
BMR Take: Earnings are expected to be $9 this year and increasing toward $11 over the next 2 years. The business is steadily generating a massive amount of money – $800 million a week, totaling over $255 billion now. The naysayers will be proven wrong on Apple again – remember when it hit $91 exactly a year ago, after peaking at the $125 level in 2015? Well guess what – the new all-time high is $156 set just last month. That number is sitting there ready to be broken again
Facebook (FB; $151, up 1%)
Facebook is focused on building products that enable people (better yet – the world) to connect and share through mobile devices, personal computers and other surfaces. The company's products include Facebook, Instagram, Messenger, WhatsApp and Oculus.
Facebook has hired more than 150 counterterrorism experts and is increasingly using artificial intelligence that can understand language and analyze images to try to keep terrorists from using the social network for recruiting and propaganda. Facebook says, “We agree with those who say that social media should not be a place where terrorists have a voice.” The move comes as Facebook is being hounded by governments to do more to combat terrorism.
Mark Zuckerberg, Facebook’s co-founder and chief executive officer, has also been trying to position the company as a positive force for building communities both online and off. This new emphasis from Zuckerberg has followed discussion over Facebook’s role in the proliferation of false news accounts during the U.S. election campaign last year, as well as the spread of extreme content posted to Facebook.
Many of these new hires have backgrounds in law enforcement and they collectively speak almost 30 languages. In addition, Facebook has thousands of employees and contractors around the world that respond to reports of violations of its terms of service, whether that’s online bullying, posting inappropriate content or hate speech.
BMR Take: One of the major risks in front of Facebook is dealing with free speech rights versus meeting obligations to be a model corporate citizen. We are glad to see steps in the right direction. EPS is expected to go from almost $5 this year to $9.50 in 2020. This stock can go much higher if the company can avoid a few key risks.
Google (GOOG; $940, down 1%)
Google spans Internet products, such as Search, Ads, Commerce, Maps, YouTube, Google Cloud, Android, Chrome and Google Play, as well as its hardware initiatives. Google is engaged in advertising, sales of digital content, applications and cloud offerings, and sales of hardware products. This is a mouthful, so one other way of looking at Google is: Most of their revenue comes from search. Period.
This week Google launched a new cloud computing platform in Singapore that aims to reduce data transmission delays for its cloud customers here, as it seeks to gain ground against rivals Amazon and Microsoft globally. It has opened dedicated cloud platform servers - called a "Google Cloud Platform (GCP) region" - in Singapore and this is the group's first GCP region in South-east Asia.
The Singapore cloud platform is the company's third in Asia, after Taiwan and Tokyo, and it is looking to launch dedicated servers in Mumbai and Sydney as well, they added. The launch of the Singapore service has significantly reduced latency, which refers to delays in data transfer over a network connection, for Google's cloud platform customers and users in Singapore and South-east Asia. The platform offers products and services such as application hosting, security, language translation and analytics.
Businesses can save anywhere from 50-70% by using a cloud platform in general compared to other options such as hosting data storage themselves. The migration to the cloud is a mega-trend and Google is in the forefront of this new world.
We mention these new events to give you the scope of what this company is doing. While you and I worry about what’s happening here in our own little worlds, Google is out there setting the stage for controlling and profiting from places around the world this year, next and for decades to come.
BMR Take: EPS is on track for $34 this year going to $55 by 2020. We see a compelling opportunity in this large cap tech giant.
Upcoming Economic News
Current Account
Tuesday, June 20th, 8:30 AM
Period: Q1
Actual: N/A
Consensus: -$121B
Prior: -$112B
Notes: The international transactions accounts are a quarterly statistical summary of transactions between U.S. and foreign residents organized into three major categories: The current account, the capital account, and the financial account. The current account includes exports and imports of goods, services, income, and current transfers. The capital account includes capital transfers, such as debt forgiveness. The financial account includes transactions for official assets, for U.S. Government assets other than official reserve assets, for direct investment, for portfolio investment, and for other investment.
Existing Home Sales
Wednesday, June 21st 10:00 AM
Period: MAY
Actual: N/A
Consensus: 5,545,000
Prior: 5,570,000
Notes: Each month, the National Association of Realtors (NAR) collects data on existing single-family home sales from Boards or multiple listing services (MLS) nationwide. NAR estimates that it captures between 30-40% of all existing home sale transactions with its monthly survey. The data provide the total number of closed existing home sales in each area as well as total sales within price categories ranging from less than $30,000 at the bottom to more than $500,000 at the top.
Leading Indicators
Thursday, June 22nd,10:00 AM
Period: MAY
Actual: N/A
Consensus: 0.40%
Prior: 0.30%
Notes: Leading indicators are economic series that tend to change direction ahead of shifts in the business cycle. There are 10 components of the U.S. Leading Composite Indicator published by The Conference Board. The index is constructed by averaging the individual components in order to smooth out a good part of the volatility of the individual series. Historically, the cyclical turning points in the leading index have occurred before those in economic activity.
New Home Sales SAAR
Friday, June 23rd, 10:00 AM
Period: MAY
Actual: N/A
Consensus: 600,000
Prior: 569,000
Notes: The U.S. Census Bureau collects new home sales based upon the following definition: "A sale of the new house occurs with the signing of a sales contract or the acceptance of a deposit." The house can be in any stage of construction: not yet started, under construction, or already completed.
Tesla Week
Tesla (TSLA: $371, up 4%) had a great week, in spite of the Fed and the Tech sell-off and everything else. Up 4%. Huge. The stock was upgraded by Berenberg Bank from a "hold" rating to a "buy" rating. They now have a $464 price target on the stock, up previously from $193.
BMR Take: This is a car company and this is a Tech company, and it is run by a one of the smartest men on the planet.
Annaly Update
We love this stock. We have been following Annaly Capital Management (NLY: $12.36, up 2%) since 1997 when they first went public. They have survived thick and thin: bull markets and bear; high interest rates and low; recessions and boom. And they continue to give you a 10% dividend, year in and year out.
With that said however, it may be time to take some profits in the stock. We added the stock in early 2016 at $10 and it is now over $12, up 25%. The key is book value. It is currently at $11.23, thus trading at 10% over book. Annaly generally sells right at book, so it is getting ahead of itself. Our Target is $12, so one could certainly sell now and be happy campers. Or you could watch and wait. We are going to watch book like a hawk. If it keeps moving higher we are golden. But if it stalls, and the stock moves back towards $12, we will most likely be saying so long to a great company.
Letter to the Editor about Shopify (SHOP: $87, down 5%)
From: John Hoogerheide [mailto:johnhooger17@xxxx.net]
Sent: Thursday, June 15, 2017 11:23 AM
To: Todd at The Bull Market Report
Subject: SHOP
Todd - A while back you had suggested Shopify as a stock just to own and forget in your portfolio as it will have very large daily bounces. In your reports you indicated the stock COULD be a likely candidate for a buyout and that their fundamentals looked solid. Shopify had been on a tear but the Nasdaq fallout has killed the stock. I assume the Nasdaq fallout is only temporary and things will go back to normal. BUT has anything changed in your attitude towards Shopify? Thanks Todd
Hi John –
No. Just the price. And it is very frustrating. I’m trying to be patient and get through the Fed raise which is just about done. The bond market was WAY up yesterday (10-year Treasury down big to 2.13%. Up a tad today, but not much.) Then the question is – are we in a Tech AND overall stock selloff? If so, then we should move to high yield, like Apollo, Annaly, etc., and bide our time until things become normal in Washington. If not, then the bull market continues. Where ELSE can you put your money? And this is not an idle question. People have been say it for YEARS, with interest rates at historic lows. And they are STILL at historic lows, really. Thus, we have this amazing bull market since 2009.
Note that I don’t believe we ever said you could put it away and not look at it. But we certainly feel that it is a long term hold and the prospects look good.
Todd Shaver, Founder and Editor in Chief
And then on Friday we wrote to him:
Nice bounce-back yesterday and today, John, after hitting $81.50 at the low point yesterday.
This one is real.
The sell-off was not.
Let’s hope it holds.
Todd Shaver
[Note that the stock closed at $87 Friday. Our take? This is a volatile stock in a nervous Tech market right now. If it’s too hot for you get out of the kitchen. Again, we are trying to be patient here with this amazing company.]
More (Good) News on Shopify
Shopify sold 5.5 million shares at $91 on May 24th in a secondary, raising $500 million. Then just last week they completed the overallotment. Do you know what that is? It is an extra block of stock that can be sold as part of the original secondary if there is demand. Well, there was, and Shopify sold another 825,000 shares at the same price worth $75 million. Not bad. So now the company is sitting on a ton of cash (we believe the total to be close to $1 billion), they have no debt, and revenues are growing like a weed.
So here dear Bull Market Reader, are a few thoughts on Sell and Target prices:
When we add a stock to our portfolio we have a Target and a Sell Price. The Target is where we think it can go and the Sell Price is the price that if it hits, you have some thinking to do. The Sell Price is usually 10-15% below the price where we added the stock. Taking a 10-15% hit is a big deal, and some may even say that if a stock drops 5-7% you should get out. Everyone has their own rules to follow. However, there are companies that are young and unproven that we feel have the potential to be 2-baggers and 5-baggers and more. Cloudera, Twilio and Nutanix are three of these. What happens with these stocks is that the world as a whole doesn’t recognize their greatness yet, and aren’t willing to hold them through tough times. It’s called the Market. (There were times in Amazon’s young life when the market sold off the stock because of various reasons. The strong held on, the weak got out.)
The problem however, is that hindsight is 20-20 and we at The Bull Market Report a) might be wrong on a stock, or b) might be early. Both of these scenarios can cause a Cloudera to go from $23 on June 6th when we added it, to the level it is at today. Not pretty, but this is the life we lead when we invest.
Now, with that said, what do we mean with the Sell Price? The answer actually is not what do WE do, it is what YOU do. The Bull Market Report very rarely tells you to SELL a stock. We SUGGEST things to you based on FACTS. We leave it up to you to decide as intelligent human beings. In this case we believed in Cloudera at $23, and now at $17.40 we believe in it more. Why? The only thing that has changed is the PRICE. It is less expensive than it was. We still think it can go to $28, and $40 and beyond, and now it is cheaper. Yea! BUT – WHAT IF IT GOES LOWER FROM HERE? What if it goes to $14? What if it goes to $10? Then we have a big problem as you can see.
So the safest thing to do is to “Sell.”* We take a licking in our portfolio, and if you follow suit, you do too, and it prevents a disaster if it goes to $14 or $10. BUT, what if this recent Tech sell-off is over now. What if Apple and the rest of them start to shoot higher over the coming weeks, which we fully expect? And what if Cloudera heads back into the 20s like we believe it will do?
No guaranteed answers here as you can see. But plenty of food for thought. Speaking of thoughts, if you have a question about this or anything else, please write us at Info@BullMarket.com.
* No one at The Bull Market Report buys or owns the stocks in our portfolios. We don’t play that game.
The High Yield Corner
By Michael Foster
The biggest news of the week was the interest rate hike, but before we get to that, let’s talk a little bit about Digital Realty Trust (DLR: $117, up 4%, plus a 93 cent dividend paid on Tuesday.)
This data center REIT has been a Bull Market Report pick since March last year. Since then the stock has gone up 38% while paying 4% in dividends. A 42% return in a little over a year is breathtaking for any type of investment, but it’s relatively uncommon in the high yield world where you often sacrifice big short-term gains for cash flow. But Digital Realty is different.
The reason is simple: Digital Realty isn’t just a high yield stock; it’s also a Tech stock. Digital Realty has a very simple business model that positions it to benefit from the hypergrowth of tech companies: it rents out server space for firms that exist in the cloud. Any cloud computing startup depends on Digital Realty for the bare infrastructure that makes their product possible; and, unlike startups, Digital Realty’s revenue stream and profitability come first.
From that perspective, Digital Realty is a very attractive business; it’s part utility and part a hypergrowth tech stock. It’s rare to find a company that combines the two extremes of the finance world - dull safety with cutting-edge high-risk technological innovation - but Digital Realty has combined the best of both worlds for years. As a result, the company has attracted capital slowly over time, but the stock was limited until the middle of 2015 by one risk factor: competition from others in the space. At the end of 2015, Digital Realty initiated some expansion efforts that essentially gave the business a “moat” and protected it from competition. The firm very smartly placed facilities in ideal geographical positions to get the attention and demand from telecommunications giants and government agencies, putting the company at a distinct competitive advantage.
The stock market swiftly reacted, and the stock has doubled since the middle of 2015. Insiders have also taken notice, which is why DuPont Fabros Technology (DFT: $64) announced it would merge with Digital Realty in an all-stock transaction*. What exactly does this merger mean for Digital Realty shareholders? Well, the stock initially fell on the news but very swiftly recovered (it’s now up about 4% for the week following the initial decline). Apparently the market first thought the merger was a bad idea and then changed their minds. The market loved the news for DuPont, however; that stock is up 20% following the news.
* June 9, 2017 San Francisco's Digital Realty Trust has agreed to acquire Washington, D.C.-based data center developer Dupont Fabros Technology for $7.6 billion in stock, bolstering its reach in and around Silicon Valley. The companies operate as real estate investment trusts that rent out space to corporations to house their high-powered computer servers, used in cloud supercomputing, streaming video and data storage. Dupont Fabros has a dozen such complexes, including one in Santa Clara, two near Chicago and nine in Northern Virginia.
The merger is extremely good for Digital Realty shareholders for one simple reason: it adds a new dimension to the company’s incremental expansion efforts. Now with DuPont’s properties, Digital Realty will have 157 properties in 12 different countries added to its portfolio. The combined firm is going to have 26 data centers operating at 97% occupancy. Remember that Digital Realty had been mostly a U.S. focused REIT with most of its properties in Northern Virginia, Chicago, and Silicon Valley. The firm clearly saw an opportunity in providing for the government’s and tech startups’ growing digital footprint.
Note that the market cap of Digital Realty is $19 billion. After the merger it will be around the $25 billion mark.
But this also means buying and holding Digital Realty has become a very different game. When The Bull Market Report originally recommended the stock, it was yielding 4%; even with dividend hikes, the stock is now yielding a little more than 3%. The company will undoubtedly have enough funds from operations to keep growing payouts, but Digital Realty has become more of a tech growth stock than a high yielding stock. Holding it now is more a bet on capital gains appreciation than a way to capture a high stream of income.
The big news for the market last week was the Federal Reserve’s rate hike. Now for the first time in over a decade the Federal funds rate is over 1%. This sounds like big news, but the market shrugged. the S&P 500 was down slightly and the Dow and Nasdaq flat following the announcement, indicating the very risk-on and risk-averse equity investors agree that this isn’t important news.
What’s even more shocking is the bond market. With higher interest rates on the short end of the curve, you’d naturally expect higher interest rates on the long end of the curve. But interest rates barely budged following the announcement, and actually went down sharply shortly before the announcement. There are a lot of ways to interpret this, but each is a variation on a singular theme: the bond market is daring the Fed to raise rates further. Either the bond market isn’t expecting the Fed to keep raising rates (the next rate hike, Yellen pretty much said, is coming at the end of this year), or bond traders are waiting until the last possible moment to sell Treasuries, or there is too much demand for Treasuries and not enough supply. Each of these moves is either a bet on or a hope for the Federal Reserve to go more dovish in the future.
Personally, we disagree. We think the Fed will blink first and slow their rate hike plans. This is essential to avoiding an inverted yield curve, which generally portends a recession here in the United States. At the Fed’s currently stated rate of rate hikes, that inverted yield curve would likely come at the end of 2018 or the beginning of 2019, indicating a recession in the middle to end of 2019. A slower rate of increases would delay that eventuality to more like 2020 or 2021.
In either case, all indications suggest that we are nowhere near a market downturn or an economic contraction. While the interest rate hikes have been big financial news for years now, and many doomsayers have said this portends a sharp downturn soon, a more reasonable interpretation is that we still have at least two years before the first sign of trouble. So it isn’t time to sell yet, but vigilance will slowly become more and more important.
There is one more pressing issue, however, especially for the high yield world: Higher interest rates on the short end and lower interest rates on the long end cut the profitability of leverage. This makes it tougher for Mortgage REITs, although a few particularly well-managed and differently structured firms (such as Bull Market Report’s recent pick, Apollo Commercial Real Estate Finance (ARI: $18.92), and Annaly Capital Management (NLY: $12.36)) are exceptions to this rule. It’s also a concern for business development corporations, which have suffered “yield compression” for years and are now suffering higher borrowing costs on top of that.
The trend is also not good for junk bonds, although many junk bond funds have priced this in over the last two years, so it’s not a major issue. However, if the Federal Reserve continues on its promised rate hike path, high yield investors will need to get ready to rotate out of the most at-risk asset classes. We’re not quite at that point yet, but it is definitely visible on the horizon.
Good Investing,
Todd Shaver, CEO, Founder and Editor in Chief
The Bull Market Report
Since 1998
