November 19, 2017

by Todd Shaver | Nov 19, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
The big story this week was the sale of a Leonardo da Vinci painting for $450 million. Leonardo da Vinci’s Salvator Mundi went to auction Wednesday night at Christie’s in New York and the selling price broke sales records. Watching the top part of the market is an interesting tell. It is noticeable when the luxury art market hits fresh highs. We further note that luxury apartment prices in New York City are down 10% to an average of $8.1 million this month compared to a year ago.
Construction is under way setting new height records of high-rise buildings in cities like Los Angeles and Philadelphia. What does this mean? Things are good, though often new peaks signal a top. We must watch very closely. When the luxury market starts hitting new records, you have to step back and realize trees don’t grow to the sky, and that this bull market is not guaranteed to last forever.
Don't get us wrong. We're still very bullish and expect a strong earnings year in 2018. But it never hurts to be a bit cautious.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks/funds where we think you can still make good money, including: VMware, Annaly, Shopify, Tesla, Nutanix, and Celgene.
BMR Companies & Commentary
VMware (VMW: $123, up 1%)
Singaporean communications company M1 Limited and software and services provider VMware announced a new cloud offering made for digital start-ups, and small-and-medium enterprises. The service will enable budding tech businesses to develop software-based products quickly in addition to growing their business without an expensive infrastructure expenditure.
M1 said it is improving its next-generation software-defined data center, which is powered by the VMware cloud provider program, with shipping support from Pivotal Container Service. The new cloud offering provides advanced technology that allows businesses to run faster and introduce new products quicker.
BMR Take: It is great to see new product development! VMware is expected to produce earnings of $5 per share this year and $6 by 2020. With such a solid market presence and brand, we see additional upside in the stock.

----------------------------------------------------------------
Annaly (NLY: $11.49, up 2%)
CEO & President Kevin Keyes bought 300,000 shares of stock this week in the open market. There is nothing like insider buying to signal a stock is a good buy. Who is Mr. Keyes?
Kevin Keyes serves as President and Chief Executive Officer of Annaly and is a member of the Board of Directors. Prior to joining Annaly in 2009, Mr. Keyes worked for 20 years in senior Investment Banking and Capital Markets roles in the Real Estate and Financial Institution Industries among others. From 2005-2009, Mr. Keyes served in senior management and business origination roles in the Global Capital Markets and Banking Group at Merrill Lynch. Prior to that, he worked at Credit Suisse First Boston from 1997-2005 in various Capital Markets Origination roles and Morgan Stanley from 1990-1997 in the Mergers and Acquisitions Group and Real Estate Investment Banking Group. Mr. Keyes holds a B.A. in Economics and a B.S. in Business Administration from the University of Notre Dame.
BMR Take: Mr. Keyes is a smart businessman. Annaly is currently producing earnings of about $1.20 and pays this out in a dividend yielding over 10%. Follow the smart money here. The company has been successful over 20 years through bull markets and bear. With a market cap of $13 billion, this stock is rock steady.
----------------------------------------------------------------
Shopify (SHOP: $105, up 5%)
Shopify is just not the ‘short’ some of the naysayers say. The best way for the company to prove it and crush the shorts is by building the underlining business. The truth is that while the stock market is a voting-machine in the short-term, over the long-term it is a weighing machine. You build a great business with earnings and the stock goes higher, every time. This is just what Shopify is doing.
Just in time for the holiday season, UPS and Shopify are unveiling a platform integration that make UPS's premium services available to small businesses. Shopify’s hundreds of thousands of small U.S. business customers will now receive competitive, pre-negotiated domestic and international rates that save on list prices, along with a streamlined shipping and fulfillment solution.
By embedding UPS natively into Shopify’s platform, merchants will get the breadth and reliability of UPS’s services to more than 220 countries and territories, while easily managing all aspects of shipping and fulfillment in one place
BMR Take: The consensus outlook calls for Shopify to put up EPS of $0.05 this year, $0.27 next year, $0.75 the following year, and over $2.00 in 2020. Look up “earnings growth” in your financial dictionary. We suspect you might find a picture of Shopify’s logo!
We wonder if Andrew Left knows when to throw in the towel? Remember, Mr. Big Short has to BUY BACK his stock to get out of the positions. MY OH MY we can’t wait to see him get SQUEEZED with this amazing company.
----------------------------------------------------------------
Tesla (TSLA: $315, up 4%)
Tesla made a huge announcement this week. Electric semi-trucks. They go 500+ miles and cost $1.26/mile to operate, and can haul 80,000 pounds. It might even one day drive itself. Companies like Walmart, JB Hunt, and UPS all immediately placed orders. This is going to be huge and change the entire infrastructure of the trucking industry.
Environmentally, the impact is massive. Every truck you move with electricity instead of diesel has an outsize effect on the health of the planet and everything living on it. Eighteen-wheelers are the ultimate force multiplier. This green effect is worth real money to the world.
BMR Take: Yes, Tesla is losing money. Specifically, they will lose almost $9 per share this year. But recall that the list of other companies down this path include Amazon and Netflix. Elon Musk will go down in history as a visionary. Let the man build a better world. There will be surreal profits for shareholders over the course of time.
ANOTHER TAKE ON TESLA
In case you missed it, here are a couple of views of the new Tesla semi-truck. Gorgeous! Unbelievably awesome features!
https://www.tesla.com/semi - Just view and scroll down for a brief video and beautiful photos.
This one is a 9 minute condensation of the 51 minute presentation. It shows all the outrageously wonderful features of the truck.
https://www.youtube.com/watch?v=5n9xafjynJA
And how about the new Roadster that they announced with speeds of just 1.9 seconds for 0 to 60 and 4.2 seconds for 0 to 100. It can handle a quarter-mile in 8.9 seconds. And it’s only $200,000!
(Funny – Porsche announced the new 911 two days before Tesla had this big PR event and said their Porsche was super-fast, going from 0 to 60 in 2.9 seconds. And then Tesla comes out and blows them away!)
This will be the fastest production car ever produced.
Check this out here:
https://techcrunch.com/2017/11/16/tesla-unveils-the-new-roadster
BMR Take: Are these new vehicles going to help the bottom line this year? No. How about next year? No. Is a lot of these new announcements hype until they actually start producing these new vehicles? Yes. But if you believe in Elon Musk it may just make you want to own more stock in this amazing company. We personally believe he will make it work. The losses will be stemmed next year as the Model 3 is delivered (500,000 orders are on the books. At $45,000 each, that’s $22 billion in revenue for just the orders on the books. Can you imagine the new orders they will receive when your best friends get one delivered and they RAVE about it?)
Is this stock an investment for the conservative investor? Not really. But for money that you can afford to lose, some say Tesla could be worth $1000 a share by 2020.
----------------------------------------------------------------
Nutanix (NTNX: $29, up 1%)
This stock is on fire. Let’s review why.
Nutanix closed its fiscal year with a bang recording 62% Q4 revenue growth year over year, exceeding analyst expectations. For the 2017 fiscal year, Nutanix grew revenue 72% from 2016. Other notable highlights from the most recent quarter include a record number of large deals, 75% growth in adoption of the AHV hypervisor product that is the future, and 875+ new customers added. The company guidance for its fiscal 1Q18 was above Wall Street expectations.
Other notable metrics highlighted:
• 96% increase in software-only bookings in fiscal 2017
• Closed the quarter with a strong balance sheet with approximately $350 million in cash and NO debt
• 4th year in a row with a customer satisfaction score of 90+
• Total customers of 7,000+, with enviable repeat purchase metrics of 4.1x for all customers greater than 18 months, and 8.1x for the Global 2000 greater than 18 months
• 404 customers that have purchased greater than $1 million lifetime to date; 39 customers that have purchased greater than $5 million; and 11 customers with greater than $10 million in business lifetime.
BMR Take: Nutanix could be the stock of the next decade. The company could cut marketing expenses and deliver earnings of over $1.00 per share tomorrow versus $0.05 expected by analysts. But why do that when you are adding new customers like mad and generating 50% revenue growth? Invest in the future with this company. One of our favorites.

----------------------------------------------------------------
Celgene (CELG: $104, up 2%)
Scripps Research Institute hopes for a royalty windfall from the potential blockbuster drug, ozanimod. If the new drug achieves blockbuster status, it could generate tens of millions of dollars a year in royalties for Scripps, and provide relief from the ongoing financial challenges facing the nonprofit lab. Scripps won't say how much it stands to receive from sales of this drug, a drug that slows brain atrophy in patients with multiple sclerosis. Scripps discovered the drug, then partnered with Celgene to shepherd the medicine through clinical trials. Celgene expects to begin marketing the drug to multiple sclerosis patients in late 2018.
The drug is expected to generate sales of $4 billion, all but 2% of that would go to Celgene. Dr. Hugh Rosen, a Scripps researcher who's the co-inventor of ozanimod, said the institute's agreement with Celgene calls for royalty payments through 2033.
BMR Take: Don’t lose faith in Celgene. This business is a core part of the Healthcare sector and is not going anywhere. The company will continue to find big opportunities as highlighted above. Celgene is still likely to double revenue and deliver over $12 of earnings by 2020. Look out - this stock can roar back!
----------------------------------------------------------------
----------------------------------------------------------------
Upcoming Economic News
Leading Indicators
Monday, November 20th at 10:30 AM Eastern
Period: October
Consensus: 0.80%
Prior: -0.20%
Existing Home Sales
Tuesday, November 21st at 10:30 AM
Period: October
Consensus: 5,440K
Prior: 5,390K
Durable Orders
Wednesday, November 22nd at 8:30 AM
Period: October
Consensus: 0.30%
Prior: 2.0%
Initial Claims
Thursday, November 23rd at 8:30 AM
Period: 11/18
Consensus: 240,000
Prior: 249,000
----------------------------------------------------------------
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
In the UBS 2018 Market Outlook report we discuss "What worries us the most?" UBS answer: "Inflation - a sudden return that is independent of growth (e.g. persistent oil-price spike,
supply-side bottlenecks) is one worry. We show that, at least in the context of labor-market dynamics, this risk is still reasonably low. The flip side of the same coin reflects the risk of policy "overtightening" despite stale inflation. Low inflation, however, allows policy makers the optionality to reverse course and stabilize markets……"
As we mentioned last week, there seems to be a lack of broad-based inflation with respect to the sizable gains in stock valuations and the rise in earnings growth rates. Yet, UBS believes the markets need to worry for two reasons: first, a sudden surge in inflation without matching earnings growth, and secondly, a lack of inflation accompanied by continued Fed rate hikes. While UBS rates the inflationary risks as low, we believe the bond markets (and yield curves) will help alert the markets to the occurrence of any substantial inflationary problems on the horizon.
Meanwhile, the good news is that UBS believes that the markets still have room to grow in 2018.
With that said, bonds are not signaling "full speed ahead." When President Trump was elected, the yield on the 30-year Treasury bond surged from 2.60% to almost 3.20%. This was probably because the bond market reassessed the likely influence this political shock would mean for the markets.
As a reminder, there were three key pieces to the accelerating economic growth argument: Increased infrastructure spending, deregulation (mainly the repeal of Obamacare), and most importantly, tax reform.
Unfortunately, the once-in-a-lifetime Republican trifecta is 0-3, and right now the 'smart money' in the bond market is not impressed with how things are going in both D.C., and the broader US economy.
The 30-year yield has retraced almost all its post-election move higher and is now only slightly higher than it was pre-election, and the 10-year yield curve has flattened rather than steepened.
Meanwhile, progress on tax reform, the real engine behind the stock rally, has been pretty slow. As we have said numerous times, the market needs tax reform to happen or we can expect a correction. At this moment in time, our best guess on tax reform getting passed isn't any better than a coin flip.
Bottom line, while stocks climb to new highs due to optimism about tax reform and the subsequent improving uptick in growth, the bond market continues to display doubts about the health of the economy and the general outlook for risk assets, both medium and longer term. Maybe that's another wall of worry that the market likes to climb. It is, however, very much worth monitoring.
For now, though, most stock gurus still give the benefit of the doubt to the stock bulls based on momentum alone. Today, the stock market is in the hands of tax reform. But tomorrow, next year, and as it always is for the long-term, it will be in the hands of earnings growth.
----------------------------------------------------------------
PayPal (PYPL: $76, up 3%) Gets a Target Upgrade
Jefferies ups PayPal’s target. After rolling forward their valuations to reflect 2019 estimates, Jefferies raised their price target for PayPal to $86 from $80. The market cap is now $92 billion. Most people have no idea this company is so big. With the stock setting a new all-time high Friday we are going to jump on the band wagon and raise our Target. Wait. They are jumping on OUR band wagon as we added the stock in January of last year at $31, so we are up 145% on the stock. We hereby raise our Price Target to $87.

----------------------------------------------------------------
Square (SQ: $44, up 13%) Gets Some Target Upgrades
What a week for our favorite payments company, Square. Wait a minute – what about PayPal? Ah yes, we love them both. But Square is a pipsqueak compared to PayPal. Just $17 billion (up from $10 billion a few short months ago.) Jefferies raised its target for Square to $47 from $44
The Square price target was raised to $48 from $45 at Nomura Instinet saying the company is "well underway to becoming a major disruptor in the payments ecosystem." After speaking with Sarah Friar, Square's CFO, the company raised its long-term estimates for the company. They see Square's revenue and profits being lifted by its "intuitive and cohesive software ecosystem."

----------------------------------------------------------------
The High Yield Corner
By Michael Foster
After tons of big news stories coming at us hard and fast, it was nice to have a bit of a quiet week with little news relating to The Bull Market Report’s High Yield portfolio. A lot of picks remained flat over the week as a result, such as Nuveen AMT-Free Municipal Credit (NVG: $15.43), Welltower (HCN: $68), and Government Properties Income Trust (GOV: $18.85).
Government Properties’ dull week was a bit of a sea change. We wrote about the intense reaction to the REIT’s slightly disappointing earnings results a few weeks ago, predicting a recovery. We’re now at price levels we saw in mid-October, so it seems that the market has realized its initial shock was overblown. Furthermore, growing stability in the credit market and the realization that REITs are already positioned for next year’s interest rate hikes has also helped this and other REITs stabilize. For instance, Apollo Commercial Real Estate (ARI: $18.41, up 1%) had a healthy albeit somewhat quiet week, and we fully expect the market to slowly pour back into REITs in the coming weeks thanks to a better understanding of the robustness of the balance sheets throughout the sector. This is a good time to sit back and wait for capital gains to continue to roll in.
Of course, there are exceptions to the quiet in REIT-land. Most notably, Omega Healthcare Investors, Inc (OHI: $27, down 3%) continued its protracted sell-off. This was partly to be expected. As we wrote a couple of weeks ago, the market is going to panic about this company’s cash flow in the short run until they realize their mistake in the long run (probably in early 2018 after the company’s next earnings report).
This is a good buying opportunity, and staging into the fund if you have cash on the sidelines would be a great way to secure this stock’s now 9.6% dividend yield. We’re approaching 10% yields - an unthinkable feat, but not impossible. We can’t imagine the market being that horrified about a company that is out-earning its dividend by a large margin. But the market’s short-term irrationality has surprised us before.
Another Healthcare REIT handpicked by The Bull Market Report did a bit better, but still didn’t do great: Ventas (VTR: $64, down 1%) dipped again slightly for a simple and silly reason: contagion. The worries about Omega Healthcare Investors is spreading to other REITs in the sector, because Omega’s problem stems from the fact that skilled nursing facilities (SNFs) are struggling to generate revenue and thus pay their rent. We’ve already discussed how Omega has positioned themselves to weather that storm, so let us discuss Ventas. Long ago, Ventas saw the dangers in the SNF sector and slowly but steadily worked to get out. They did so by diversifying into life science research facilities and medical office buildings. These buildings have a higher rent tolerance threshold, which is good for Ventas.
What we mean is that they can easily push rent hikes over time, because their revenues are significant thanks to growing demand and the deep pockets of the tenants. Universities have big endowments, and doctors have large profit margins from expensive short-term visits from patients. Both put Ventas in a very financially healthy position. In fact, the company’s dividend coverage ratio is 134%, which is above our 130% threshold. This remains a solid hold, and we dismiss the slight downturn this week as noise due to an irrational fear of the SNF market, which affects Ventas less and less over time.
Another REIT with a bit of a bad week was Digital Realty Trust (DLR: $118, down 2%), which has been a fascinating stock to track over the year. Almost all of those losses happened on Friday on little news, but we suspect the sell-off is a result of the continued fear that server space demand is going to decline over time as servers themselves get smaller, which in theory should mean less square footage will be necessary to hold those smaller servers. We discussed this weeks ago when the controversy first came up over a Silicon Valley investor’s vague prognostications, but let us reiterate the most important point: demand for server space is growing at a breakneck pace. All those Millennials uploading selfies to Instagram, sending short videos on Snapchat, and having political debates on Twitter increase the demand for server space. So we are not worried in the slightest.
We’ve also seen a growing trend in social media away from deleting previous data to lower storage space. Instead, these companies realize that more data gives them advantages they cannot ignore. Hence more demand for server space. Can this growth outstrip the technological advancements that make servers smaller? So far it has, and there’s no semiconductor or other tech development lately to suggest this trend will end anytime soon. For that reason, Digital Realty is a great buy on weakness, although we want to see dividend hikes increase radically next year.
Finally, let’s discuss AstraZeneca (AZN: $33, up 2%). A ton of news has hit the company since it beat revenue and earnings expectations on November 9th. This week, the FDA approved expanded use of the company’s new breast cancer medicine Faslodex and approved its asthma medicine Benralizumab. The company is also presenting to medical experts on clinical trials for its cancer drugs at a conference in Singapore this weekend. Little news has come out about those presentations so far, but if they are strong enough we could see the market react on today, Monday. Holding this stock remains advisable considering its tremendous and improving track record when it comes to research and development. We’re already sitting on 23% price gains in the last year. More is likely to come.
Good Investing,
Todd Shaver, CEO, Founder and Editor
The Bull Market Report
Since 1998
October 22, 2017
by Todd Shaver | Oct 22, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
Earnings-day blowups, leverage warnings in China, Apple’s worst rout since August. Oh, and a sixth straight week of gains for the S&P 500. No matter what happens lately, stocks just keep rising, with record closes piling up in U.S. markets at a rate that is starting to defy precedent. The Nasdaq 100 Index has finished at all-time highs 62 different times this year, on par with the most ever in 1999, while the S&P 500 and Dow Jones Industrial Average are closing in on historic levels, too. For bears, the elongating list of highs bespeaks euphoria, particularly when the market has been spared a 3% pullback for more than a year. Investors have ignored bad news ranging from North Korea to political drama at the White House to what may be the biggest profit slowdown in six years. It has been a great ride this year. We remind you, our dear reader, it certainly will not always be this good.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks where we think you can still make good money, including: PayPal, Shopify, Celgene, WageWorks, Amazon, and Blackstone.
BMR Companies & Commentary
PayPal (PYPL: $71, up 3%)
PayPal delivered another great quarter for investors. The company not only showed no signs that its platform growth is slowing, it demonstrated that it is actually increasing its rate of growth as the network effects that management has repeatedly cited during the past couple of years continue in earnest. Yet many of its initiatives – the monetization of social peer-to-peer payment app Venmo, the expansion of instant-checkout feature One Touch, customer choice – are still in the very early innings of the game.
Toss in the $7.1 billion in cash that PayPal had on its balance sheet that could be used to fund M&A initiatives and the potential of the company’s worldwide network becomes daunting. We recall that PayPal acquired Braintree – the online and mobile payment platform that has fueled much of the company’s recent growth – in 2013 for just $800 million. And Braintree had spent just $26 million to purchase Venmo, which is a game-changing driver of revenue and earnings for PayPal.
BMR Take: PayPal has been the best way for equity investors to play the global growth of mobile payments. Again we see PayPal deliver an exceptional quarter backing up that point of view. We find nothing to critique about the firm. We raised our Target from $67 to $77 last week. We look forward to raising it again.

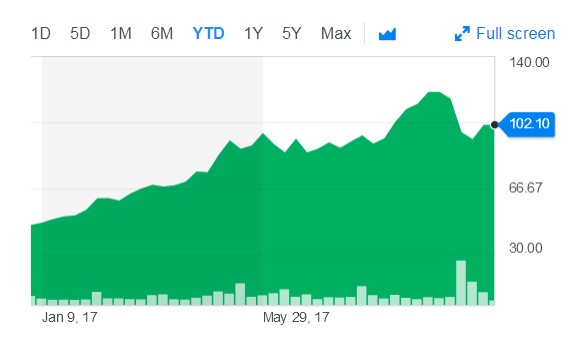
Now THERE’s a great chart. What’s next? 75? $80? $100. We think they are all possible.
Shopify (SHOP: $102, up 9%)
Remember that scary short seller, Andrew Left of Citron. Well the short call they were making on Shopify is turning out to be terribly wrong. Ouch! What good news for us and all the other shareholders behind the company.
Since 2014, Shopify, the leading multi-channel commerce platform, has been steadily building its presence in Waterloo, the cornerstone of Canada’s technology Corridor. Just recently, the company announced that it plans to grow its full-time, Waterloo-based workforce by 300-500 new jobs over the next couple of years. Growth continues!
These new positions in Waterloo will focus on growing Shopify Plus, which supports the largest and most complex customers on the Shopify platform. Roles in engineering, product, sales, and merchant services will range from entry-level to senior manager-level, and all will focus on developing innovative solutions capable of scaling for the changing retail landscape.
To accommodate this growth, Shopify also formally announced the opening of their second building in Waterloo. Steps from their current building, the new space will nearly double their physical footprint and further demonstrates Shopify’s dedication to building a strong and sustainable economy. The new space is expected to open in the first quarter of 2018.
BMR Take: It was admittedly a bit nerve-racking to see a short seller like Citron, who nailed Valeant, come out against one of our holdings. But we trust our research and our hard work. Shopify is a remarkable well-positioned technology company for the future of eCommerce.
Celgene (CELG: $121, down 11%)
Rough week for Celgene. Celgene announced the discontinuation of the Phase III REVOLVE trial in GED-0301 for Crohn’s disease (CD). This was unexpected and unfortunate news.
Celgene’s decision comes after recommendation by the independent data monitoring committee upon its review of
the overall benefit/risk during a recent interim futility analysis. The company points to no meaningful safety imbalances identified during this analysis, suggesting a lack of efficacy for the drug.
At this time, Celgene has chosen to not initiate the Phase III DEFINE trial in CD. The company is awaiting review of the full dataset from the Phase II trial of GED-0301 in ulcerative colitis to determine next steps in this situation.
In our opinion, this represents more of a psychological blow than a fundamental one to the company. Recall that Celgene paid $710 million upfront to Nogra Pharma Limited for the rights to this drug in 2014 and has since funded development of the asset.
BMR Take: Sometimes you just have to sift through the headlines to find the real facts. This one drug was only supposed to be a $1 billion revenue contributor. But the company is expected to still do more than $20 billion by 2020. So we see no reason to panic. We added the stock at $95 a little over a year ago so we have a nice 28% return and our Target is still a hefty $150. We continue to believe in Celgene. But if you are worried, then get out of the kitchen. There are lots of other choices for your money.

WageWorks (WAGE: $65, up 1%)
WageWorks a little over a year ago acquired Automatic Data Processing’s Consumer Health Spending Account (CHSA) and Consolidated Omnibus Reconciliation Act (COBRA) businesses. This transaction further strengthened WageWorks' leadership position in the Consumer-Directed Benefits market.
Why do we bring it up? Because WageWorks is eating ADP’s lunch and sometimes it’s good to reflect and remind ourselves why.
ADP’s CHSA and COBRA businesses provide a range of services including HSA, HRA, FSA, commuter benefits, and direct bill administration to approximately 10,000 employer clients in the United States.
Not long after this deal, WageWorks won a contract to service the entire federal government with consumer benefits programs, taking away the business from Automatic Data Processing.
BMR Take: WageWorks is serving a niche in the world of payments running consumer benefits programs for employers. It’s a tricky business. The global opportunity is huge and they are just getting started. We don’t hear a lot out of WageWorks week in and week out, but that doesn’t mean it's not exciting. Remember, the company just raised equity and we could see another acquisition occur in the near future.
Amazon (AMZN: $982, down 2%)
Amazon and Google (GOOG: $988) are at virtually the same price. Who will be first to $1100? Let the race begin. We think Amazon will win.
Why? Just look at the craze around the world competing for Amazon’s new headquarters. You can just see the excitement.
New York City mayor Bill de Blasio said that key landmarks around the city like the Empire State Building, billboards, and Wi-Fi charging stations are going to light up in Amazon’s signature orange color. The four bids that New York is pitching Amazon on - including areas upstate and in the city - just aren’t enough, so New York is also going for frills and extra decorations to pretty up its proposal.
Tucson certainly whipped out the big guns when its economic development group hauled a 21-foot saguaro cactus to Amazon’s main Seattle headquarters via a truck. The plan didn’t turn out the way that Tucson’s economic group had hoped: Amazon refused to accept the gift.
Kansas City mayor Sly James is not one to let the competition outdo him. He wrote 1,000 reviews about Amazon products, giving them all five stars. His reviews had slick one-liners like, “I live in beautiful Kansas City where the average home price is just $122K, so I know luxe living doesn’t have to cost a ton.“ Of course, in every review, he never failed to drop a mention of why Kansas City is great. Then, he posted a trendy “unboxing” video on social media to share his efforts. You gotta love this guy.
On Tuesday, Ottawans were told to cheer for Amazon during intermission for a hockey game between the Vancouver Canucks and the Ottawa Senators. A gauge showed up on screen, with Calgary at the bottom if the audience made the least noise and Ottawa on top. It being Canada, of course, the message to make noise was reiterated in French: “Faites du bruit!”
Pittsburgh has local restaurant Primanti Bros. offering free sandwiches to every Amazon employee who ends up working there. Each Pitts-Burger and Cheese sandwich goes for $7.39 normally, so if each of the 50,000 new employees got a sandwich, that would run for a total of $350,000, the Pittsburgh Post-Gazette hypothesizes.
Birmingham tried wooing Amazon online and in person. The city set up three giant Amazon boxes around town. It also set up giant replicas of Amazon’s Dash Buttons that send pregenerated flirty tweets to the company, according to AP, like “Amazon, we got a 100% match on Bumble. Wanna go on a date?” Another tweet reads, "We are Chipotle and these other cities are Taco Bell.”
Honestly, it’s hard to top this next one: This small, recently formed town, located close to Atlanta, offered to rename itself Amazon, Georgia. Stonecrest’s proposal also includes 345 acres of land if Amazon selects it as the HQ destination.
BMR Take: Amazon is the world’s greatest innovation machine. We think the new headquarters is going to spur even more great things and send the stock much higher.
The Blackstone Group (BX: $34, up 5%)
The U.S. real estate market may have slowed down, but Blackstone Group President Tony James still sees plenty of opportunities for profit. “Real estate is a gargantuan market. There are always undermanaged assets,” he said.
Blackstone has been investing heavily in logistics real estate, hoping to capitalize in the rise of online retail, and more acquisitions are possible.
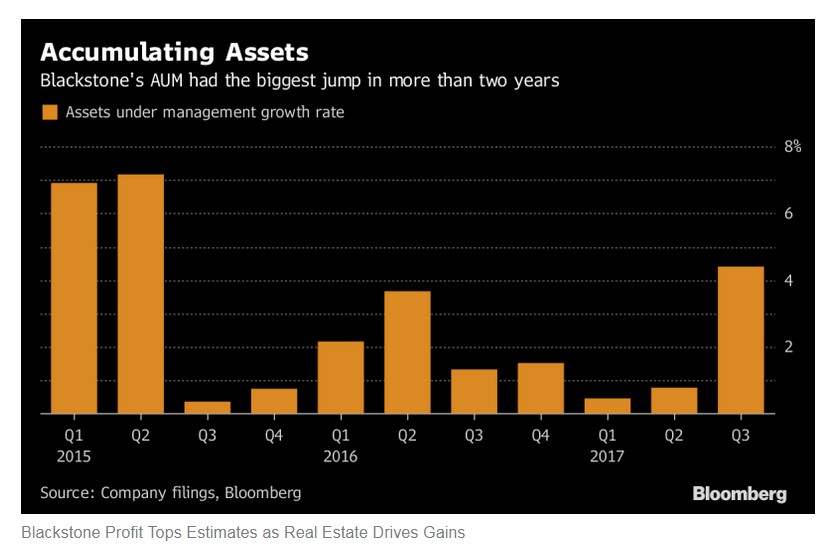
Blackstone’s real estate assets under management grew to $110 billion in the second quarter, up 9% from $102 billion a year ago. Its core-plus portfolio, which includes Stuyvesant Town-Peter Cooper Village, grew 36% to $18 billion.
In May, Blackstone won a $20 billion commitment from Saudi Arabia’s sovereign wealth fund for a new infrastructure investment fund, but it may be a while before the money gets spent. Saudi Arabia’s commitment depends on Blackstone raising additional cash from other investors, and the firm has only just began marketing the fund.
Real estate continues to fuel gains for Blackstone, which reported a jump in third-quarter profit that exceeded all analysts’ estimates. Economic net income, a measure of earnings that reflects both realized and unrealized investment gains, was $835 million, or 69 cents a share, compared with $690 million a year earlier.
Real estate led the charge for Blackstone’s asset sales in the quarter. The unit, sold $3.1 billion in holdings, including a U.K. office property and a portfolio of French hotels. The firm also continued trimming its stake in Hilton, selling shares it held in both its real estate and private equity funds.
Asset sales helped fuel $625 million of distributable earnings, which reflect profits on those disposals and fund management fees, compared with $590 million a year earlier. The metric is on track for its second-best year ever, President Tony James said on a call with media Thursday. Blackstone plans to draw from that pool to pay stockholders a dividend of 44 cents a share on Nov. 6.
BMR Take: We are really excited about Blackstone, especially real estate. Real estate is a “hard asset” meaning the value is more stable than for instance technology or biotech companies where the value is based on expectations of future growth. This real estate angle to Blackstone should give you less downside risk in a tough market.
Our Target is $36 and we fully expect to see this shortly. We can’t wait to raise the Target to the all-time high set in 2015 at $44. This $42 billion market cap company ought to be in the mid-40s for sure.
Upcoming Economic News
New Home Sales
Wednesday, October 25th, 10:00 AM
Period: September
Consensus: 552,500
Prior: 560,000
Initial Claims
Thursday, October 26th, 8:30 AM
Period: 10/21
Consensus: 231,500
Prior: 222,000
GDP
Friday, October 27th, 8:30 AM
Period: Q3
Consensus: 2.2%
Prior: 2.2%
The Word on the Street about Apple
Street Consensus Ratings for Apple (AAPL: $156, flat)
Ratings Breakdown: 7 Hold, 41 Buy Ratings
Consensus Price Target: $193
Wall Street Targets:
10/16/2017 KeyCorp $187
10/16/2017 Pacific Crest $187
10/15/2017 Rosenblatt Securities $150
10/13/2017 Barclays $161
10/11/2017 Piper Jaffray $196
10/11/2017 Morgan Stanley $199
10/10/2017 Royal Bank Of Canada $180
10/9/2017 Drexel Hamilton $208
Microsoft (MSFT: $79, up 2%) Sets New All-Time High
My Oh My. What shall we do? What shall we do with this stock at its all-time high of $79? Sell, Hold, Buy more?
BMR Take: WE SAY THE LATTER. Why would you sell one of the greatest companies in the history of the world? Yes, revenues are slowing, but profits are increasing and the profitability of software is second to none. For the year ended June 30th the company did $90 billion in revenue and had $21 billion in net income AFTER TAX. That’s 23% after tax. Wow. So for every $1 of software they sell, 23 cents goes to the bottom line, and much of that is in cash. The company has over $130 billion in cash, albeit over $80 billion in debt, much of it taken out at historically low interest rates. With a $607 billion market cap there are only two stocks higher. – Google at $690 billion and Apple at $810 billion.
We hereby raise our Target from $78 to $84. Go M S F T!
The Word on the Street about AstraZeneca
Street Consensus Ratings for AstraZeneca (AZN: $35, flat)
Ratings Breakdown: 2 Sell Ratings, 9 Hold Ratings, 14 Buy Ratings
Consensus Price Target: $37
Wall Street Targets:
10/17/2017 Cowen $37
09/6/2017 BMO Capital Markets $38
09/1/2017 Argus $35
BMR Take: We added the stock just below $30 last year. We are being very patient with this one. We have a 17% gain in over a year and the 2.6% dividend helps, but we would like to see this thing take off to our Target of $42. It’s no small company at a $85 billion market cap. Revenues are solid at $23 billion and profitability is strong at $5 billion but we want to see more in 2018. If you have patience, you will win.
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
We are getting ready to get down to the nitty-gritty of tax-reform. Listening to all the political pundits (which is extremely hard to stomach), it appears that the odds are now slightly favoring the failure of tax reform happening this year. Admittedly, we are talking about a government which is trillions of dollars in debt already, but that number seems to be "just a number". How do we actually comprehend a trillion dollars? One market guru described it as follows:
"Numbers, like billions and trillions tend to numb the mind. They are too large to grasp in any “real” sense. Thirty years ago an older member of the NYSE gave me a graphic and memorable example. “Young man,” he said, “would you like a million dollars?” “I sure would, sir!”, I replied anxiously. “Then just put aside $500 every week for the next 40 years.” I have never forgotten that a million dollars is enough to pay you $500 per week for 40 years (and that’s without benefit of interest). To get a billion dollars you would have to set aside $500,000 dollars per week for 40 years. And a trillion that would require $500 million every week for 40 years. Even with these examples, the enormity is difficult to grasp."
Despite our debt, the market wants and believes that a smaller government (lower taxes) will result in a higher GDP which in turn means higher tax revenues. Thus, the argument that the government has to "pay" for any tax cuts - by raising taxes on the left hand if lowering them on the right hand so as to keep the "debt" constant - is tantamount to keeping the status quo and, ultimately, the same drag on business that we have today. It is apparent that the $5 trillion gain in the overall stock market since the election is because of both increased earnings and the perception that those earnings will continue to grow in part due to lower taxes which drop directly to the bottom line of businesses. Our view is that it will be difficult for the market to act as if tax reform failure is a non-event. It's a major event that could make US companies more competitive in world markets and super-charge domestic small business like nothing has for the past 20 or 30 years.
Business and the markets both need an overhaul of a tax system that is so out-of-control that, as a generality, if one hundred experts file the same tax return, there will be ninety-nine different results. That said, tax reform failure by itself should not derail the current bull market - rather it will likely result in a "reset", or as the pundits like to say, a "consolidation of gains" before the next move higher. Until we see a recession or a bad policy move that, for example, results in an inverted yield curve, we expect that the market will continue to grind higher based on the quality and stability of earnings growth.
The High Yield Corner
By Michael Foster
Let’s start with the elephant in the room.
Government Properties Income Trust (GOV: $18.22, down -2%*) fell just 1% on Friday after receiving an unfavorable mention on Jim Cramer’s Mad Money. This move surprised us for two reasons. Firstly, we didn’t think anyone still watched Cramer’s show, and, secondly, we didn’t think anyone actually listened to him for investing advice. Apparently this failed hedge funder still has a following, though, and the selloff is a result of that.
* The company paid a 43 cent dividend on Friday and a stock that goes x-dividend always opens up down the amount of the dividend on that day, so in reality, the stock was down just a touch last week.
And what exactly is Cramer’s thesis? To be honest, we’re not sure. We’ve seen the clips and read a couple of takes, but the dismissal seems to be without any substance beyond “it’s a high dividend stock and it’s not for me.” No close look at FFO, dividend coverage, or revenue growth.
So, we will give you that here.
Let’s start with revenues. Government Properties Trust saw a 9% year-over-year increase last quarter, an acceleration from a decline at the start of 2016. Revenue growth acceleration has been occurring for nearly two years now, fueled in part by acquisitions and the company’s diversification away from government offices and towards office space leased to think tanks, public companies, private contractors, and so on. That investment has cost money, which means FFO has been weaker than it was back in 2014-2015, which also means dividend coverage is below 100% (it’s actually about 76% over the last 12 months).
Investors should in theory be rewarded for that lower dividend coverage with a higher yield, and at 9% that is exactly what they are getting. But really what we need to think about is the REIT’s ability to generate cash from operations to fuel the distribution in a sustainable manner.
If its expansion efforts bear fruit, this is exactly what we should see. But keep in mind that a bet on Government Properties is a bet on its future growth potential - and with revenue growth still accelerating, it remains a REIT growth stock. The second we see that sales growth weaken is the second we reconsider the stock. No matter what the bald guy on CNBC says.
Elsewhere in REIT land, things were extremely quiet. Omega Healthcare Investors, Inc (OHI: $32, up 1.5%) saw slight gains, whereas we saw a little dip in Ventas (VTR: $63, flat). Welltower (HCN: $68) ended the week flat, as did Apollo Commercial Real Estate (ARI: $18.44). One other REIT had a very fine showing, which is little surprise to us, since it’s been doing a lot of that lately.
Namely, Digital Realty Trust (DLR: $124, up 1%) had another strong week that pushed its dividend yield even lower, and we’ve finally hit the 3% mark yet again. Last week we discussed the significance of this barrier, and it’s not too surprising that it was hit. That should also make investors pause and consider why exactly they’re in the stock. At a 3% dividend or less, it’s more than generous to call Digital Realty a high yield stock. Yet it is unquestionably a high growth stock. Revenue growth, at 10% last quarter, fell from the 20%+ growth of 2016, but considering just how tough it was to compare revenues to 2016’s figures, that slowdown was more than expected. And at near 10% sales growth, the company is still growing like a weed. That has helped FFO growth accelerate markedly, which should indicate more aggressive dividend increases are on their way.
That leads us to the question: what to do with this stock. If you aren’t in need of a high yield, Digital Realty is a great place to be, because you’re essentially Google and Amazon’s landlord for their most precious assets: their data and global presence. But if your goal is to target a 7% income stream or higher, you could easily make do with removing allocations to Digital Realty with a nice profit and move into other higher yielding stocks in our two high-dividend-paying stocks. That’s especially true now that we’ve seen Digital’s stock soar 83% in 3 years. Yes, more upside is on the way, but maybe not as quickly and as profoundly as we’ve seen so far this year and in recent history.
Now let’s move on to the other, somewhat smaller elephant in the room: PIMCO Dynamic Income Fund (PDI: $30, down 4%), which wasn’t the worst performing Pimco fund of the week, although it was pretty close. Across the board, the market punished Pimco’s funds after the company announced that net investment income for most of its funds was far from covering distributions. This wasn’t a surprise, but the market has mostly ignored this issue until just now. Both the Dynamic fund and other Pimco funds have seen dividend coverage slip to less than 100%, although Dynamic’s coverage is not the worst of the lot. Still, the market is worried that the fund won’t be able to cover its payouts.
This is an overly simplistic view. Dynamic’s NAV has gone up 12% in 2017 - more than many bond funds and even some other Pimco funds. Since closed-end funds can fund distributions from Net Investment Income (NII), this just means Dynamic’s payouts can come from capital gains instead of NII. There are some tax issues here, but in terms of dividend sustainability, Dynamic’s distributions are fine.
But there is one implication many aren’t talking about, and we have addressed it earlier this year: the specials. Dynamic is famous for paying a huge special dividend at the end of the year, which has historically come from massive NII. Now that NII is weak, Pimco has a great excuse to tell investors, “Worry, income was weak, so no big special dividend this year.” We are not sure this will happen, but we’re leaning more to this being likely than we were earlier this year. If you were depending on this fund’s special distribution like the big one we saw last year, be prepared for disappointment. Also be prepared for that to hit the stock at the end of the year.
Is this a bad thing? Not really. The regular dividends are still safe, and the fund’s yield is a very nice 9%. And we could see NII improve significantly next year. There’s definitely more to come with Pimco funds in the coming months! But, if you don’t like drama, take your profits and squirrel them away in Annaly Mortgage (NLY – 10% div.) or any of the other stocks in our two high-yield portfolios and sleep like a baby.
Good Investing,
Todd Shaver, Founder and CEO
The Bull Market Report
Since 1998
October 8, 2017
by Todd Shaver | Oct 8, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
It’s market mania for assets around the world! Financial markets posted fresh records this week, as the upswing in global manufacturing added fresh legs to the relentless rally in equity and credit markets around the world. The most eye-catching: The U.S. stock market’s volatility gauge set an all-time low Thursday while the S&P 500 Index jumped to a fresh high, its sixth consecutive record close -- a feat last repeated back in 1997. Global stocks posted new record highs amid strong economic data. Credit premiums hit fresh post-crisis lows. Let the good times roll.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks where we think you can still make good money, including: Celgene, PayPal, Google, WageWorks, VMware, and Blackrock.
BMR Companies & Commentary
Celgene (CELG: $139, down 5% - all prices herein are for the week)
Celgene entered into a long-term strategic alliance with Nimbus Therapeutics (private) centered on autoimmune disorders.
Nimbus’s preclinical programs target central mediators of inflammation. Nimbus competes in this area against Bristol-Myers and Gilead. But given Nimbus’s demonstrated track record of success and the promising nature of the targets, the consensus view this alliance as particularly encouraging and indicative of Celgene’s dedication to expanding its presence in immunology and inflammation. Awesome!
Celgene will be given an option to acquire each program. Nimbus will receive an upfront payment and potential milestone payments per program that Celgene chooses to acquire. In the interim, Nimbus will retain full control of R&D activities for each program. Financial terms will be disclosed only in the event that Celgene chooses to acquire a program.
BMR Take: We remain bullish on Celgene as total revenues are expected to rise from $13 billion this year to $21 billion by 2020. We expect Celgene’s four blockbuster drugs (Revlimid, Abraxane, Otezla, and Pomalyst) to drive the revenue growth, while the recent acquisitions of Receptos and Delinia as well as investments in collaborators like Acceleron, Epizyme, Agios, and others will ensure growth from 2017 and beyond. We continue to view Celgene as a top large-cap pick in Healthcare.
PayPal (PYPL: $66, up 3%)
Mastercard and PayPal announced a significant expansion of their longstanding partnership into Canada, Europe, Latin America and the Caribbean, and the Middle East and Africa, to make Mastercard the clear payment option within PayPal across the globe. With the addition of these markets – and following the recent expansion of their partnership into the U.S. and Asia Pacific – Mastercard and PayPal have now reached a global agreement.
Similar to previous agreements, the global expansion will create a number of joint growth opportunities that will advance Mastercard and PayPal’s shared vision to offer consumers greater choice and flexibility to manage and move their money.
For example, PayPal will have the opportunity to expand its presence at the point of sale by utilizing services from Mastercard, allowing consumers to use their Mastercard in their PayPal Wallet to make in-store purchases at more than 6.5 million contactless-enabled locations across the globe. Consumers will also have the ability to quickly cash out funds held in their PayPal accounts to a Mastercard debit card.
BMR Take: People everywhere know and trust the familiar Mastercard brand, whether they’re paying in the physical or digital world. The expanded partnership with PayPal affirms the attractive growth outlook for PayPal’s users could go from the current 200 million to upwards of 1 billion, in our view. This should take the stock much higher.
Google (GOOG: $979, up 2%)
Google parent Alphabet’s internet-by-balloon Project Loon tweeted that they hoped to bring emergency connectivity to Puerto Rico after Hurricanes Irma and Maria left more than 90% of the island without cellphone coverage. Just 7 days later, the Federal Communications Commission Friday gave the company a green light to fly 30 balloons over Puerto Rico and the US Virgin Islands for up to 6 months.
If all goes to plan, Alphabet's balloons will soon help replace the thousands of cellphone towers knocked down by hurricane-strength winds. The balloons would provide voice and data service through local carriers to users’ phones.
Alphabet has previously deployed Loon to provide emergency phone service in Peru following flooding there earlier this year. They had already been working closely with a local wireless network, Telefonica, to coordinate spectrum use and prepare handsets to work with its balloons.
Project Loon was born in Alphabet’s moonshot X division, with the aim of serving the half of the world’s population that is still without internet access. It has launched several successful pilot projects, but Loon has yet to be deployed commercially on a wide scale.
BMR Take: This is such a cool innovative initiative to see from one of the US’s leading tech companies. They are truly improving the world. Companies that do that tend to improve the performance of your portfolio. We remain bullish on Google. We see EPS heading to $60 over the next 3-5 years pushing the stock much higher.
We have been reminding you that this stock was cheap in March at $815 and after setting highs in June, got cheap again in July at $900. It has been on one of these slow Google rolls lately, moving up $3-6 a day for weeks now. We sure hope you have some of this great company. And if you don’t it is NOT too late to buy. It is within a whisker of an all-time high at $988 and we can see it breaking four figures and moving much higher from there.
WageWorks (WAGE: $63, up 4%)
WageWorks cares about people and wants to empower everyone - employers, employees, and their families - to lead healthier, happier, and more productive lives. The company simplifies the complex world of Consumer-Directed Benefits. They make benefits programs easier to understand and use so that everyone can take advantage of pre-tax savings and focus on what matters most.
The latest new development is a partnership with none other than Uber! WageWorks and Uber are revolutionizing your commute, giving you more options on how to get to and from work.
WageWorks has entered into a first-in-market partnership with Uber, the world’s leading rideshare company, to offer you the convenience of using a WageWorks Commuter Prepaid MasterCard, WageWorks Visa Prepaid Commuter Card and TransitChek QuickPay Prepaid Visa Card to pay for uberPOOL rides. This new partnership gives the customer the flexibility to use his or her pre-tax funds to pay for uberPOOL rides when they commute.
What does this mean? Customers can now save up to 40% when they rideshare to work via uberPOOL. That’s more money back in their pocket every month. Use of WageWorks commuter benefits with Uber is currently available in the following markets: Atlanta, Boston, Chicago, Denver, Las Vegas, Los Angeles, Miami, New York, Philadelphia, San Diego, San Francisco, Seattle, Washington D.C., and the state of New Jersey. And this will expand dramatically in the coming year.
BMR Take: WageWorks is on track to generate $1.75 of EPS this year. We see a sizeable market opportunity where earnings can double over the next 5 years. WageWorks serves a unique market niche and is an off-the-radar business many people have never heard of, making this name a unique opportunity to outperform the S&P500
VMware (VMW: $112, up 2%)
VMware announced that it is helping Partner Communications (PTNR: $5.20) implement a novel approach to network functions virtualization (NFV) that has resulted in a rapid conversion to NFV and a reduction in cost-per-customer to deliver network services.
What does this mean? First, we will give you the technical jargon. Then, we’ll break it down, as we do best.
Partner Communications, a leading Israeli Telco group, selected Cloudify and VMware to launch its new solution called V-NET. V-NET is delivered through a unique, cloud-based approach to network service orchestration using an incremental approach referred to as "orchestration first."
In layman’s terms, NFV is fundamentally changing the way communications services are provided. The Partner V-NET platform creates intelligent management of communications networks, services and cloud access, enabling IT managers to have direct access to any point or branch of the management interface, while saving significant manpower, time, hardware and money.
BMR Take: VMware has been a solid performer since we started covering the name. We see EPS settling in at around the $5-$6 level. We will continue to scan the opportunities in front of the company for reasons to reassess our EPS outlook higher. This deal above, is just another small reason for the great success of this not-so-small $46 billion market cap company. Remember Dell Technologies owns 83% of VMware. It’s only a matter of time before they make an offer for the 17% it doesn’t own.
We added the stock in January at $83 and currently have a $120 target. We see no reason why this can’t be reached later this year if the stock market stays steady.
BlackRock (BLK: $463, up 4%)
BlackRock is in discussions to invest in financial technology company Capital Preferences to help bolster its focus on retail investors.
Capital Preferences gathers data to help wealth managers understand the risk tolerance and preferences of clients, allowing firms to create portfolios suited to investors’ needs. The talks, which are preliminary, include determining ways of incorporating the company’s software into BlackRock’s existing technology offerings.
The world’s largest asset manager is investing in technology in part to diversify revenue as investor money flows into cheaper passive strategies. BlackRock is also using technology to indirectly expand its reach to retail investors, who are typically charged higher fees than institutions.
BlackRock, which manages $5.7 trillion in assets, has made several strategic investments in startups in recent years with the aim to eventually acquire some. It owns FutureAdvisor and has participated in a funding round for iCapital Network, an online marketplace that offers ultra-wealthy investors and their financial advisers alternative investments.
CEO Larry Fink has recently said that he hopes technology will account for 30% of revenue in the next five years up from 7% currently. BlackRock is counting on its risk management system, known as Aladdin, to help push it toward that goal.
BlackRock's Rob Goldstein, the chief operating officer of BlackRock, thinks there are a lot of misconceptions around one of the biggest trends overtaking Wall Street. BlackRock. One, for instance, is the name.
"We actually believe one of the greatest misnomers is this word “passive” because we don't believe any investment decision is a passive decision."
Passive investing, which means tracking a market-weighted index rather than actively trading single stocks, has steadily eaten away at active-investment management over the past several decades. Index investing has been revolutionary for investors, allowing them to bypass high-fee investment managers, many of which have not performed well. The firms that specialize in index investing and exchange-traded funds, another form of passive investing, have become giants of the industry.
BlackRock is one of them. They pulled in more money into its ETF arm in the first half of this year than all of last year.
And Goldstein added this:
My sales pitch is very simple: BlackRock is a growth company. BlackRock is a growth technology company and we're growing our technology functions. We have a very ambitious plan that we call "Tech 2020." And as part of that, we are looking to extend the 2,000-plus technologists we already have within BlackRock. And we're really excited about the opportunity to take BlackRock, which is already at the forefront of technology in its industry, and keep expanding that.
BMR Take: BlackRock is among the best-positioned companies in investment management, owning the top Exchange Traded Fund franchise (iShares), that is growing rapidly due to “passive” investing, as well as an increasing product portfolio of technology. Recall, there are several top hedge funds on the list of shareholders in BlackRock. With EPS set to approach $30 over the next 3 years, this stock is among our favorites. What a great week the stock had, and we expect much more of the same. Don’t be put off by the high stock price. Think Google at $980 a share!
Upcoming Economic News
JOLTS Job Openings
Wednesday, October 11th,10:00 AM
Period: August
Consensus: 6,170,000
Prior: 6,170,000
PPI ex-Food & Energy
Thursday, October 12th, 8:30 AM
Period: September
Consensus: 2.0%
Prior: 2.0%
Retail Sales ex-Auto
Friday, October 13th, 8:30 AM
Period: September
Consensus: 0.80%
Prior: 0.20%
Update on Shopify
We were able to get our hands on a report from Morgan Stanley recently. Here are some excerpts from it.
Shopify (SHOP: $98, down 16%) Trading at roughly 18 times its forward sales estimate and having never turned a profit, Shopify certainly looks expensive. The company has delivered impressive sales growth so far, but even then, investors are paying a premium for the promise of its business. That tends to be a risky proposition, but sometimes it's one worth pursuing. With that in mind, we think Shopify's momentum and expansion potential actually make the stock cheap, even as it currently trades at all-time highs.
For those unfamiliar with the company, Shopify provides e-commerce platforms as a service -- allowing sellers to quickly launch and conveniently maintain online sales portals. It mostly caters to small- and medium-sized businesses. However, it also counts some larger brands, including Budweiser and Red Bull, among its customers. All told, the company provides service to over 500,000 merchants worldwide -- up from 165,000 roughly two years ago. That's an impressive reach for a young company, but it still leaves lots of room for expansion.
Last quarter saw revenues climb 75% year over year, and the company is doing a good job of growing sales relative to expenses even as it prioritizes expansion over near-term earnings. With Shopify's current customers more or less locked in, reducing its advertising and marketing expenses could quickly shift the company to profitability.
While Shopify is not cheap by the established guidelines of value investing, ownership involves a greater degree of speculation than some investors will be comfortable with. However, Shopify's current price could look like an absolute steal five years from now.
BMR Take: This report was written before this ridiculous Andrew Left started shorting the stock and making a fool of himself on Bloomberg TV and elsewhere. We believe he is wrong and we believe the market will prove him wrong. He is “winning” at the moment as the stock dropped $13 on Wednesday when he went public with his diatribe, $3 on Thursday and $3 on Friday. It had hit $93 on Thursday, so it came back sharply. But he will lose in the end. Remember, he has to BUY BACK his short position at some time, pushing the stock up when he does.
We have to say that the stock was quite strong in the weeks leading up to this Wednesday. This maniac had been shorting the stock in a big way, putting downward pressure on the stock, and yet the stock was moving higher and higher since the middle of August when it was at the $95 level. That tells us there is buying power out there, and as soon as this blows over we expect the stock to start moving back up again. We could easily just bow out of the stock, since we added it in the spring at $73 and thus have a nice gain. But we are going to stay with it because we believe in the company, plus their revenue growth is huge – on the order of 75% last quarter. And you know what we are going to say here: Revenues always win out in the end.
Here is some more from Morgan Stanley:
With Shopify declining 16% this week following circulation of a short report, investors have been digging into details on the company's model. We continue to believe that Shopify has a strong core business model and highlight several of the more frequent questions asked, along with responses:
--- How does Shopify's model compare to a pyramid marketing model?
Answer: Shopify has a success-based model where its revenue is reliant on the success of its merchants. Unlike some pyramid models, there is typically little upfront investment required by merchants on the Shopify platform with no annual commitment required. If a merchant is not successful on SHOP's platform, it can exit the platform with little cost of failure. Historically, we believe churn has been high but Shopify's growth has been supported by the growth of its successful merchants which have outweighed the cost of those that have failed on its platform.
--- How does the company's affiliate marketing platform work?
Answer: Shopify has over 13,000 ad agencies, consultants, and partners that support its marketing efforts with over 500,000 merchants now on its platform. When a partner refers business into Shopify, they can be eligible to receive a bounty. Where bounties are paid, Shopify may continue paying fees associated with referred merchants while they remain on the platform. Affiliate marketing models are not uncommon among small to medium sized web services vendors.
--- How much revenue does Shopify generate from its business exchange?
Answer: Shopify rolled out a myriad of new products and services for its merchants this year. The company's exchange was rolled out this summer and, like other services, is in its early stages and its size is not yet disclosed. We do not believe the company has generated a meaningful amount of revenue from this platform yet. Last quarter, 47% of the company's revenue was generated from Subscription Solutions (subscriptions, themes and apps).
The remainder of the company's revenue (53% of total) can be attributed to its Merchant Solutions business which is primarily payments driven and benefited from approximately $5.8 billion sold over the platform.
--- How much do bloggers contribute to the company's customer acquisition?
Answer: Shopify does not disclose this number. However, the company has stated that most of its merchants are introduced to the platform organically. Paid advertising is the second most meaningful source of new merchants followed by partners, of which bloggers are a subset.
--- To what extent do non-Plus merchants contribute to revenue growth?
Answer: We do not have a breakout of total revenue by merchant category but for Subscription Solutions, management stated that Shopify Plus merchants accounted for over 18% of total monthly recurring revenue last quarter compared to 13% for 2Q16, implying approximately 127% growth for Shopify Plus and 55% for non-Plus business. On the Merchant Solutions side, the company has disclosed that Advanced and Shopify Plus merchants are responsible for over 50% of volume processed over its platform.
Update on Tesla’s Delivery “Problems”
Excerpted from a BusinessInsider article
Tesla has over-promised and under-delivered ever since the company was founded. But investors continue to believe in the genius who runs the company.
Tesla does not benefit from being normal. The company is organized around being special, different, extraordinary. You don't change the world by restraining yourself. And Wall Street doesn't care. Over the past two years, Tesla's stock is up over 1,200% since the company's 2010 IPO.
Tesla's third-quarter delivery numbers were both impressive and depressing. The carmaker is on pace to sell 100,000 vehicles this year for the first time in its 14-year history. But it's also far, far behind with the production of its new Model 3 sedan, the vehicle that's supposed to bring Tesla to the masses and spell the beginning of the end for gas-powered cars.
Getting to 20,000 in monthly production by December now seems like a hopeless expectation, as does CEO Elon Musk's prediction that Tesla will be manufacturing 500,000 vehicles annually by the end of 2018. But the markets are unconcerned. Tesla stock is still up 65% in 2017 and the brand has lost none of its captivating aura.
But it's also obvious that for a car maker that's been around as long as Tesla, they aren’t good at building vehicles.
So why is Tesla struggling to build the Model 3 on its own admittedly ambitious schedule?
1. The Model 3 is all-new production.
Tesla is reasonably good at manufacturing its expensive, luxurious Model S sedans and Model X SUV. Production of these vehicles was designed around a run-rate of about 100,000 per year, and Tesla will hit that mark most likely in 2018.
Of course, the Model X endured "production hell," as Musk memorably put it, during its roll-out in 2016. The Model S also endured early production issues that were later corrected. And Musk declared that production hell would be back for the Model 3.
Musk talks about Model 3 production in terms of an "S curve," with a very slow ramp rapidly speeding up before leveling off at a desired point. But Tesla also has a second S curve, related to learning. It doesn't know, exactly, how to build the Model 3. Established automakers build cheaper cars in volume all the time; Tesla never has.
2. Tesla enjoys endless patience from everybody.
Tesla's brand equity is probably its most valuable asset. And Tesla knows it. Yes, we aren't going to make our goals — but we also aren't going to lose focus on the big picture, which isn't to sell more cars, but rather to save the planet.
3. Tesla isn't actually mass-producing the Model 3 yet.
Even if Tesla had hit its goal of 1,500 Model 3s in September, it would still be a long way from the levels of production needed to meet demand. The low numbers, which the company chalked up to production "bottlenecks," suggest that the ramp to just pre-mass-production is taking longer than expected.
If Tesla hadn't fallen so short of its own run-rate for September, we could assume some bobbles, but unfortunately, it looks more like the decision to forego the process of testing out the Model 3 assembly line before trying to accelerate the production ramp isn't working out.
4. The Model 3 looks simpler then the Model S and Model X — but is it?
The Model X is complicated. The Model 3 is supposed to be simple. Tesla designed the Model 3 to be easier to build than the Model S and Model X, but compared with electric cars that have now been in production for a while - the Chevy Bolt and the Nissan Leaf, for example - there's a lot of "clean slate" to the newest Tesla.
To build an EV that they can get to market quickly, build easily, and price below $40,000, other manufacturers are just adapting existing gas-car platform to the task. The Bolt doesn't feel all that futuristic inside, and the Leaf has a fairly conventional interior. Neither car is dramatic to look at on the outside.
Tesla has eliminated as much dashboard instrumentation as possible with the Model 3, going for a very clean, minimalist vibe that stars a single, horizontal touchscreen. Although that might sound like it makes everything easier, it doesn't necessarily because it's a major departure from how cars are currently put together.
Ultimately, Tesla's plan to simplify will pay off, but in the short term, negotiating the learning curve could slow them down.
BMR Take: As we’ve said many times, this company is speculative. But it sure is fun being on the ride with them.
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services
Some good news – bad news. According to Stock Trader's Almanac (STA), October is the last month of the “Worst Six Months” for DJIA and S&P 500 and the last month of Nasdaq’s “Worst Four Months”. The bad news is that in post-election years, the DJIA has been up 11 times in 17 years with an average gain of 0.7%, but in the last three years ending in “7,” October has been trouble. In 2007, the bull ended and the financial crisis began, in 1997 the Dow plunged 12% and in 1987 the market crashed on "Black Monday", a day we will never forget. [We don’t buy these types of things at The Bull Market Report.]
The good news is that, looking back through history, a big upside move of over a 5% gain on the S&P 500 during the Worst Six Months (or the “Sell in May” period) from May through October has usually been followed by great gains in the overall market. Thus far, that 5% gain has happened. There is just one month left in the Worst Six Months. So if the market can pick up further gains in October and not succumb to the historical and often self-fulfilling prophecy of "Octoberphobia" – and particularly the curse of the 7th year - that would be, according to STA, a solid indication for stronger gains over the next Best Six Months (November to April) and 2018.
We understand the argument that this bull market is way long in the tooth. However, there is another maxim of Wall Street that says, "Bull markets don't die of old age; they die because of recessions or policy mistakes". We see nothing on the horizon indicating we are headed for a recession. The Fed could overplay its hand by hiking interest rates too high and too fast. However, we think if the Fed errs it will be on the side of "too little" rather than "too much" because, so far, it has been very conservative in its approach to normalizing both its balance sheet and interest rates. We do think it will be a "policy mistake" for Congress not to pass meaningful tax reform – the market is 100% counting on this happening and if it doesn't, good earnings might keep the market afloat, but probably won't be enough of a catalyst to produce meaningful gains until some of the PE multiple expansions are digested. Bottom line: Tax cuts are now the most credible and legitimate “bullish” or “bearish” wildcard remaining for the markets in 2017.
From a bullish standpoint, real tax cuts could easily push the S&P 500 up another 4% or 5% because that will increase expected 2018 EPS to a conservative $145/share.
From a bearish standpoint, while tax cuts aren’t quite yet "fully" priced into stocks, there is the expectation they will get done, especially regarding foreign profit repatriation. If tax cuts, like healthcare, fail, then we’re now sitting with a market at 18X next year’s earnings and no identifiable future growth catalyst (and a Fed raising rates). We believe that will cause investors to reduce exposure and, if we had to make a guess based on these fundamentals, we would expect a potential pullback in the 5-10% range should Congress fail to enact promised tax reforms, compared to anticipated 5-10% gains over the next Best Six Months if reforms are passed.
An Update on Teva Pharmaceuticals
The FDA approves Mylan's generic Copaxone, Teva shares lower
Shares of Mylan (MYL; $38, up 23%) are 18% higher while shares of Teva Pharmaceuticals (TEVA: $15.94, down 9%) drop sharply following the FDA's approval of Mylan's generic Copaxone: Glatiramer Acetate Injection. Teva management followed up the announcement with a press release estimating the impact of the two launches to its Q4 earnings of at least $0.25/share and while they have planned for the introduction of eventual generic competition and remain confident in Copaxone, but that it is too soon to officially comment on any change to their full year business outlook.
Most analysts see it as a clear negative for Teva as the generic approval comes earlier than expected with most firms anticipating a 1Q18 arrival. That said, this is a long anticipated event and firms estimated the impact to shares should be closer to the 5% range with some preferring to see the news as removing an overhang on shares that could clear the deck for management.
For Mylan, analysts call it a significant win/positive, given the process was a long drawn out 7-year pursuit and Mylan landed the first approval with potential exclusivity.
The firms suggest that any generic entry may take some time and/or over a protracted period, which could make the opportunity for Mylan quite long-tailed with high margins and thus quite negative for Teva.
This is the day that TEVA investors have dreaded for many years. We believe the bulk of the downside from the loss of Copaxone sales is already priced into TEVA shares.
This news comes earlier than Teva expected and some investors had thought possible. Given the potential $0.25 impact per quarter and applying this to full year 2018, it is possible Teva's new 2018 guidance could fall well below $3.00.
BMR Take: We’ve had it. We have put up with a lot of negatives with this company. What’s next? What will they disappoint us with next?
We’re out. We added the stock in May at $29 and it has gone straight down. Bad choice on our part. We are truly sorry.
If you want to stay in and wait, you can. These suggestions of ours are just that. It is always up to you depending on your own goals. More than likely the stock will stay at this level for months and if things go well, will slowly inch back up. We say this is likely, but if things get worse, we could see $13 at this time next year.
The High Yield Corner
By Michael Foster
For a long time, the market simply didn’t believe the Federal Reserve would hike rates three times in 2017. The probability of a rate hike in December, as calculated by Treasury futures markets, was far below 30% for a long time. Then in September Janet Yellen made it very clear that a rate hike was coming. Even through the fog of “Fed speak,” the Fed’s intentions are incredibly clear, and futures markets responded accordingly. As of this time of writing, the futures market is implying an 89% probability of rates going up.
We’ve been here before. In 2015, the market reacted swiftly to Yellen’s public statements, and we saw a lot of carnage in the high yield world as a result. If you were in the market back then, you remember seeing just about anything with a big yield, from BDCs to municipal bonds and everything in between, falling hard at the end of the year. Several analysts (myself included) rightly called this a buying opportunity of a lifetime. Since the start of 2016 to now, many high yield investments, including those recommended by The Bull Market Report, rose by double digits not including dividends. That’s big.
Yet with this reversal in market expectations, the high yield market has remained mostly unfazed. Traders and investors have learned their lesson: A sudden collapse in yield just means a buying opportunity, because the income stream from these investments remains largely sound and trustworthy. This is why the recent Fed announcements haven’t caused as much of a buying opportunity as they did two years ago.
There are, however, exceptions. Unsurprisingly, those exceptions tend to be very popular with retail investors who are somewhat risk averse and tend to sell off too aggressively in times of caution. This is why we’re seeing a pretty big hit among some high yielding REITs, although there’s been virtually no news to suggest there’s any problem with any of these companies.
Among Bull Market Report picks, Welltower (HCN: $68, down 3%) was hit the hardest last week. While there hasn’t been any news that has any material impact on the REIT, Welltower shares continued a protracted slide that began in mid-September and has been aggravated by the Fed’s comments. Nothing has changed in the company’s business operations, and its FFO still exceeds payouts by a healthy margin (although, it must be admitted, not the healthiest). Now shares are yielding 5%, the highest yield since March of this year. And just like March was a great buying opportunity, so is right now, although we may see yields climb up to 5.5% before the stock bottoms, as we saw happen in November 2016 when, you guessed it, investors sold off in a panic over rising interest rates.
Considering the stock is similar to Welltower in many ways, it is not surprising to see Ventas (VTR: $63, down 3%) react similarly. At a 4.6% yield, Ventas’s recent slide also brings it to its lowest point since March, although there’s no news to indicate the firm is facing any new hardships. In fact, one of the exciting things about Ventas is that it’s been diversifying aggressively into the medical office space, where capitalization rates can often grow faster than with skilled nursing facilities. Additionally, medical offices are less exposed to the whims of regulators and Medicare funding. The market isn’t rewarding this shift - at least not yet. Instead, traders are focusing on interest rate issues. Considering Ventas’s size gives it a relatively low borrowing cost, its 0.56 debt-to-asset ratio is conservative in the REIT sector. It’s clear that the selling pressure on this stock is unjustifiable. That doesn’t mean it won’t go lower in the coming weeks, but it does mean the stock is quite likely to go higher after the rate hike and the market realizes this actually didn’t hurt their balance sheet.
Elsewhere in the REIT space, we saw a lot of dull action. Digital Realty Trust (DLR: $118) and Apollo Commercial Real Estate Finance (ARI: $18.20) ended the week flat, despite both REITs’ relative price outperformance throughout 2017. Similarly, we saw Nuveen AMT-Free Municipal Credit Fund (NVG: $15.43) and Invesco Municipal Trust (VKQ: $12.72) stay flat for the week. While comparing muni funds to REITs is very much apples to oranges, in this case the comparison is illuminating. Here we’re seeing a trend that encompasses much of the high yield universe - the market is largely shrugging off Yellen’s rate hike talk. In part that’s because municipal bonds, especially after the recent hurricanes, and these REITs in particular (thanks to their cloud computing and complex financial structure, respectively) are less popular with retail investors right now and more popular with institutional investors, who tend to react less aggressively to upcoming rate hikes.
What, then, should high yield investors do? Right now, there’s no reason to sell anything in The Bull Market Report portfolio. What’s more, the more aggressively sold-off REITs are becoming increasingly attractive. What we are seeing is a buying opportunity more than a cause for concern. Sadly, it’s not as good of an opportunity as late 2015, but we should be grateful for whatever we can get in this incessant bull market.
Good Investing,
Todd Shaver
CEO, Founder and Editor
The Bull Market Report
Since 1998
September 4, 2017
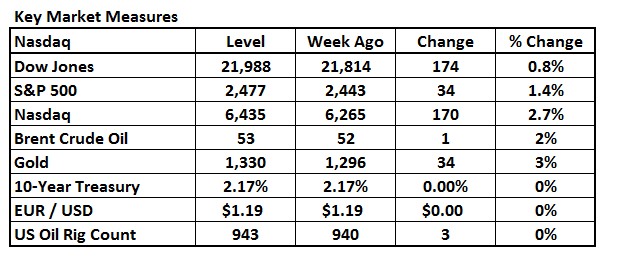
by Todd Shaver | Sep 4, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
We sadly observed Hurricane Harvey devastate Texas this past week. 52,000 people are in shelters as thousands of homes are flooded. The state of Texas ranks as the 2nd largest contributor to GDP in the US trailing only California and ahead of New York. So the economic impact has yet to be fully seen. Real estate portfolios caught without flood and business disruption insurance may be seriously in trouble. Auto sales are already seeing a sizeable dip. Chemical plants are shut down. We could go on and on. What an unfortunately troublesome situation to watch and one with the potential for lingering negative impacts for months to come.
In other news, lawmakers decide to give bipartisanship a shot on healthcare. The Senate Health Committee will turn its attention to bipartisan legislation aimed at shoring up Obamacare markets for 2018. The drift toward compromise follows high profile repeal failures, but still faces an uphill battle as many Republicans have spent years railing against the health law. Staff has been working on it over the summer break and there is general agreement that insurer payments will continue, though specifics are sparse.
Separately, we have yet to see formal action following Trump’s opioid emergency declaration. No formal paperwork has been filed and no new policies have been announced. This appears to be new territory for the government as the national emergency designation is typically used for relief of temporary issues like natural disasters rather than chronic problems like opioid abuse. In addition, administration officials seem to have been caught off guard by Trump's statement. The White House has indicated that it is considering all options for action. Why should we care? This is a big deal for labor force participation, which is at historical lows. If we can get everybody back to work contributing to our economy and off drugs, that is the path to 3.0% GDP growth versus where we are now at 1-2%.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks where we think you can still make good money, including: Apple, Gilead, Bristol-Myers, Amazon, and PayPal.
BMR Companies and Commentary
Apple (AAPL: $164, up 1.5%, all prices are for the week)
Apple has officially scheduled its first-ever event in the company's Steve Jobs Theater, a September 12th invitation-only press conference expected to reveal the latest iPhones and possibly a revamped Watch and Apple TV. The company emailed invitations Thursday that read "Let's meet at our place," with an picture of an Apple logo in red, white and blue. The event, hosted at the company's new spaceship-style Apple Park headquarters is scheduled to start at 1 PM ET. For several years, Apple has revealed its latest iPhones in September, in time to promote them for the holiday season. This year, 10 years after the first iPhone hit the market, Apple is widely expected to reveal the iPhone 8, and the rumor mill has already churned out reports that the device will have a larger OLED* screen and a virtual home button. There are also reports Apple will reveal a Watch that has its own cellular connection and an Apple TV that adds 4K UHD. This is likely it—the big event for Apple’s new iPhone launch! We will all be watching closely.
* Organic light-emitting diode. An OLED display works without a backlight; thus, it can display deep black levels and can be thinner and lighter than a liquid crystal display (LCD). In low ambient light conditions (such as a dark room), an OLED screen can achieve a higher contrast ratio than an LCD.
The main risk to keep an eye on is prices. The argument is that costs are getting so high on new smartphones that customers will not be willing to keep paying up to get them. If this is so, we will see margin compression and perhaps fewer sales by Apple.
Apple Consensus on the Street
Apple was upgraded by analysts at Cleveland Research from a “neutral” rating to a “buy” rating in a report released on Tuesday, and they raised their price target to $197.
On the Street there are 10 Hold Ratings, 39 Buy Ratings, 1 Strong Buy Rating
9/1/2017 Royal Bank Of Canada Target: $180
8/29/2017 Cleveland Research Target: $197
8/24/2017 Bank of America Target: $180
8/24/2017 Drexel Hamilton Target: $208
8/22/2017 Canaccord Genuity Target: $180
8/14/2017 Sanford C. Bernstein Target: $175
BMR Take: Remember the big story for Apple is their services business. They have all these iPhones out there in use by a huge customer base. Can they now get more money from these customers through services? The iPhone 8 is a key part of the strategy. We note that Apple has $260 billion in cash now, which is the equivalent of $50 a share, and greater than 30% of the stock price. This is UNPRECEDENTED in the history of Wall Street. Apple remains an exciting investment opportunity. The services business is projected to double in revenue to $50 billion over the next several years. The Services business is much more profitable than hardware so the impact to earnings is even better. Don’t sell a share. We believe Apple has a lot more room to go on the upside.
Gilead Sciences (GILD: $84)
We removed Gilead from our Healthcare portfolio in February after holding them for a year with poor results. Things have changed dramatically since that time as management has tackled various issues head-on, so we give you an update as things have changed even more this past week.
Gilead announced a big acquisition. Gilead will acquire Kite Pharma for about $12 billion in cash; it was unanimously approved by both the Gilead and Kite Boards of Directors and is anticipated to close in the fourth quarter of 2017. The transaction will provide opportunities for diversification of revenues, and is expected to be neutral to earnings by year three and accretive thereafter.
The acquisition of Kite establishes Gilead as a leader in cellular therapy and provides a foundation from which to drive continued innovation for people with advanced cancers. We are greatly impressed with the Kite team and what they have accomplished, and believe they are on the cutting edge of cell therapy that will be the cornerstone of treating cancer. The field of cell therapy has advanced very quickly, to the point where the science and technology have opened a clear path toward a potential cure for patients. The two company’s similar cultures and histories of driving rapid innovation in order to bring more effective and safer products to as many patients as possible make this an excellent strategic fit.
BMR Take: Gilead is losing two major drugs this year with big revenues due to the expiration of their patents and was the reason we removed the stock earlier this year . Over the past several years they were among the largest sellers in the history of Healthcare so replacing them will be a tough uphill climb. Could Kite provide a way to do it? We will see.
Bristol-Myers Squibb (BMY: $60, up 3%)
This week Bristol-Myers will announce more than 60 presentations, including seven late-breaking abstracts, from its Oncology portfolio featured at the European Society for Medical Oncology 2017 Congress in Spain. Presentations of data from company-sponsored studies, clinical collaborations and research will explore the potential role of Opdivo (nivolumab) as monotherapy and in combination with Yervoy (ipilimumab) and with relatlimab, a fully human monoclonal antibody that targets lymphocyte activation gene-3 (LAG-3); or with chemotherapy in 13 types of cancer.
All this news matters a lot because healthcare investors love new data! We are seeing the stock pick up some momentum getting ready for what is likely to be a wave of good news.
BMR Take: We are still optimistic Bristol-Myers could be a take-out candidate. Activist investor Carl Icahn is in the stock and pushing for change. We believe we could see a 25-50% premium from today’s price if a sale gets done. Further supporting our view, we note Jana Partners is now also building a position in the stock. Jana had a big stake in Whole Foods, and was taken out by Amazon this past week as you know.
Amazon (AMZN: $978, up 4%)
Amazon announced 3,000 more jobs coming to Ohio. This follows news a few weeks ago about doing a major facility in New Jersey. We continue to highlight the Amazon machine because this single company alone is now a major driving force behind the economy.
The internet retailer received approval on Wednesday for state tax incentives for two distribution operations in Ohio. The project approved by the Ohio Tax Credit Authority will create 2,000 jobs. The company said it will invest $100 million at the site, which eventually will result in a 855,000 square-foot facility. The second distribution-center project, will result in an estimated 1,000 jobs if the company goes ahead with the project. Amazon had no presence in the state until recently.
BMR Take: The Amazon powerhouse is steamrolling the real economy and the stock market. With over $20 of EPS potential by 2020 according to analyst consensus estimates, we see a lot of potential ahead.
We noticed that the stock is on a little roll lately. The stock hit a closing high of $1052 a month ago in late July and then proceeded to drop over $140 to the low 900s. But this week the stock was up a little bit every day until Friday when it took a breather. We have watched these high-priced stocks for years and many times it is human nature to not be able to bring yourself to buy a stock that is almost $1000 a share. But we always mentally build in a stock split. Say 10-1 in Amazon’s case. If the stock were a $98 stock, would you buy 100 shares? Sure you would. So we just look to buy 10 shares for $980. Same difference. If you think the stock is going to $2000 a share in the future like we do, 10 shares here, 20 shares there, and 30 shares beyond, adds up to real money.
PayPal (PYPL: $61, up 2.5%)
PayPal customers in the U.S. can now earn cash back on every purchase online and in stores with the recent launch of the new PayPal Cashback Mastercard issued by Synchrony Bank. The PayPal Cashback Mastercard, designed exclusively for PayPal members, offers cardholders 2% cash back every day, on every purchase – everywhere Mastercard is accepted.
Unlike other rewards credit cards, there is no annual cash back limit, no minimum redemption amount, no restriction on how to spend cash rewards and no expiration. The PayPal Cashback Mastercard offers all the security and convenience expected from PayPal, plus all the traditional benefits of a Mastercard. All accounts are automatically added to the member’s PayPal wallet to simplify checkout and provide peace of mind.
The introduction of the PayPal Cashback Mastercard with Synchrony Bank continues PayPal’s commitment to provide customers with rewarding product experiences and a range of innovative credit options. By providing a simple way for people to earn cash rewards for the shopping they’re already doing, the PayPal Cashback Mastercard will give consumers yet another reason to shop with PayPal.
BMR Take: PayPal has 200 million customers on the way to over 1 billion longer-term (after all, Facebook has over 2 billion, showing the possibilities for a global internet-based business model). With EPS closing in on $3 by 2020, and EPS growth moving along in the mid-teens, we see growth at a reasonable price here in the stock and like it a lot!
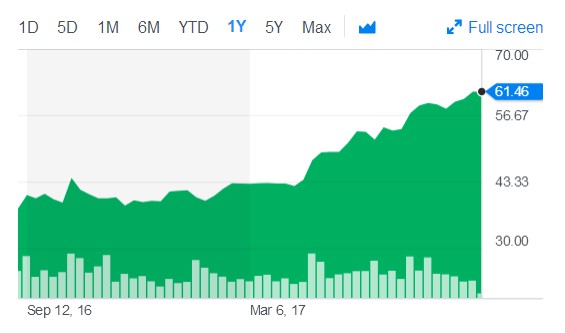
Nutanix (NTNX: $22, flat)
We reported via News Flash on Friday on the stellar earnings report the company issued on Thursday. The stock shot higher on Friday, hitting $24, but settled at $22, flat for the week. We’re not traders as you know, but long term investors, and we have seen this many times in our career. We are going out on a limb here and will say that the stock will move higher from here over the coming weeks and months.
We mentioned the high level of sales that were booked but not reported as revenues – the backlog. Management indicated that billings growth was 40% year over year and that the company continued to build up a significant backlog of deals that booked but did not ship in the quarter. The sales transition toward large enterprise is progressing nicely. Management's next quarter guidance implies billings growth of 25% YoY compared to consensus of 17%, due to the significant backlog build.
To recap:
Fiscal 4Q 2017 Financials
Revenue: $226 million, up 62% year-over-year from $140 million in 4Q16
Net Loss: $50 million, compared to a net loss of $47 million in 4Q16
Operating Cash Flow: $6 million, compared to $2.5 million in 4Q16
Cash and Short-term Investments: $350 million, up 90% from 4Q16
Deferred Revenue: $525 million, up 77% from 4Q16*
Free Cash Flow: $(6.5) million, compared to $(6.5) million in the fourth quarter of fiscal 2016
Billings: $289 million, growing 40% year-over-year from $207 million in 4Q16
BMR Take: We added the stock in May at $17.45 and have a Target of $30. Our Sell Price at $14 is way too low, so we hereby raise it to $19. This was a great quarter and if Wall Street doesn’t wake up to the potential of this company, we would be very surprised.
Upcoming Economic News
Domestic Auto Sales
Monday, September 4th, 8:00 AM ET
Period: August
Consensus: 4.6 Million
Prior: 4.5 Million
Trade Balance
Wednesday, September 6th, 8:30 AM
Period: July
Consensus: -$44.5 billion
Prior: -$43.6 billion
Initial Claims
Thursday, September 7th, 8:30 AM
Period: 09/02
Consensus: 240,000
Prior: 236,000
Consumer Credit
Friday, September 8th, 3:00 PM
Period: July
Consensus: $15.0 billion
Prior: $12.4 billion
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
Over the previous weekend, these were the economic headlines:
--- Robust Retail Sales
--- Disappointing Durable Goods
--- Strong Business Inventories
--- Uneven Industrial Activity
--- Mixed Housing Data
Economic data suggests that things are good, but not great.
Fed Chair Janet Yellen's signaling of continued restraint on monetary policy at Jackson Hole triggered another rally in US stocks last week. This extends the current bull market to 102 months, surpassed in length only by the 113-month run leading up to the dotcom crash. Skepticism over valuations is even higher now with a record 46% of investors believing equities are overvalued.
While the bull market may be entering the later stages of the cycle, UBS strategists believe it can run further based on these observations:
--- The earnings yield on the S&P 500 is 4.8% compared with a yield of 2.17% for 10-year Treasuries.
--- At 18x, current market PE ratio is near long-term averages. Historically when valuations have been in an 18x to 23x range, the MSCI AC World Index has returned 6% over the subsequent six months (versus an overall average of 5%). And relative valuations of equities also suggest long-term outperformance versus bonds.
--- Corporate earnings growth remains robust, at 12% in the US and around 10% in the Eurozone in the last quarter. Synchronized global growth should continue to support this, with all 45 OECD economies on track to expand this year.
There are, however, some caution flags appearing here and there. We prefer to look at price-to-sales ratios rather than PE's, and they haven't been this high since the peak of the dotcom bubble in 1999. This means that new investors are paying more for every dollar of sales than at almost any time since the dotcom bust. However, if sales continue to grow as expected this ratio will normalize to some degree. Put another way, stocks are priced almost to perfection and if the earnings growth story were to falter, it could cause some real volatility.
VMware (VMW: $107, up 5%) Has 500,000 Customers
BMR Take: Think about this. Half a million customers. Can you imagine? We think this is just fabulous. We’re up 30% since we added them in January at $83. What a great company. Our Target is $108 which it hit Friday, an all-time high (not counting the euphoria 10 years ago when they went public). With a market cap of $44 billion, and Dell Technologies being the principal owner (80%+) we think very highly of this company. So we hereby raise our Target to $120 and raise the Sell Price from $90 to $100.
The Blackstone Group (BX: $33, up 4%) had its Target Price set at Credit Suisse Group at $45
A Few Wall Street research firm targets
8/30/2017 Credit Suisse Group $45
7/25/2017 Morgan Stanley $40
7/21/2017 Deutsche Bank $33
7/14/2017 Keefe, Bruyette & Woods $37
7/14/2017 Oppenheimer Holdings $38
5/28/2017 Citigroup $41
Blackstone Considers IPO of Gates Corp.
Blackstone Group is considering an initial public offering of Gates Corp. that could value the auto-parts maker at as much as $9 billion. Its products include belts, hoses, industrial power transmission, fluid power, and automotive. The company was founded by Charles Gates in 1911 and is headquartered in Denver. In 2014, the company was acquired by Blackstone in a deal worth $5.4 billion.
The private-equity giant is in the early stages of laying the groundwork for the possible offering, according to people familiar with the matter. The business could be worth $8 billion to $9 billion, one of the people said. It isn't clear whether that includes debt.
BMR Take: We can’t tell you how good this company is. Well, maybe we can: This company is great! Look at the wealth being created by this firm. In 3-4 years in this one deal alone, they have created $3-4 billion of equity. Absolutely amazing. Our Target is $35 but we are dying for the stock to hit this price so we can raise it to $42. This is a value stock like no other.
The High Yield Corner
By Michael Foster
Significant news came this week from AstraZeneca (AZN: $30, up 3%), helping the shares rise solidly by the end of the week. The biggest news is the company’s presentations at a conference in Spain that will demonstrate the company’s phase-3 study of imfinzi for non-small cell lung cancer and tagrisso for. EGFR cancers.* The science is complex and far for non-specialists to understand without a lot of deep reading, but the market is a great place because it prices in that knowledge instantaneously, which is why AstraZeneca shares rose 2% on the news.
* EGFR is short for estimated glomerular filtration rate. The EGFR is a number based on your blood test for creatinine, a waste product in your blood. It tells how well your kidneys are working.
Another intriguing tidbit from AstraZeneca: the company announced on Tuesday that it was recruiting Takeda Pharmaceutical to work on an antibody for Parkinson’s disease treatment. Again, more exciting developments that prove the mega-pharma company’s pipeline is very healthy. Remember a year ago when this was a primary concern on the company and thus the stock? Those concerns are gone now; instead, investors have finally realized that there is tremendous value in this company and it is still innovating; thus it’s no surprise shares are up 10% in 2017 so far. Paying a solid 3.1% dividend, we can see some dividend increases in the months and years ahead. We’ve got a $42 Price Target on the stock and would hope to see this level sometime next year.
Elsewhere in The Bull Market Report High Yield portfolio we see green across the board. There’s only one exception: Invesco Municipal Trust (VKQ: $12.93), which ended the week flat. No surprise; municipal bonds are a low volatility asset class, and there’s not really any news in the municipal bond market to warrant a massive jump. That includes the latest tragedy in Texas. While large storms and ecological disaster might intuitively seem like they will hurt municipal bond markets (lower economic activity should mean lower government revenue and thus higher default risks), it’s important to remember that this “common sense” is actually false. (Often, the common sense view doesn’t quite work in finance.) In reality, credit agencies do not downgrade bond issuers faced with economic disasters; furthermore, the lower revenue may make the state’s budget tighter in the short term, but the risk of that hurting municipal bonds is negligible. Additionally, natural disasters rarely result in massive new bond issuances to fund repairs, so it’s not like existing bonds will get priced out by new issues.
We saw Nuveen AMT-Free Municipal Credit Fund (NVG: $15. 64, up 1%) have a solid showing. Also a nice surprise from Nuveen this week: the company announced dividends for all of its closed-end funds, but did not lower dividends on NVG - although many other funds did see their distributions decline slightly. Again, good news for municipal bond investors long this fund.
The Bull Market Report’s other closed-end fund picks also ended the week in the green and announced distributions that were in-line with previous dividends. AllianzGI Equity & Convertible Fund (NIE: $20, up 1%) announced that its 38 cent quarterly dividend would continue at the same level, and PIMCO Dynamic Income Fund (PDI: $30, up 1%) also announced its monthly dividend would stay at the same level. These funds are paying 8% in income, year-in and year-out, while also seeing their share prices rise. Closed-end funds are typically income vehicles that aren’t often traded for short-term capital gains, but both funds have given investors that opportunity this year. AllianzGI is up 10% year-to-date and Pimco Dynamic is up 14% year-to-date - extremely impressive returns for such diversified funds. And the income does not look to be threatened anytime soon, so investors can continue to hold them with confidence.
Now, let’s turn to REITs. Digital Realty Trust (DLR: $118, flat) announced that its COO was leaving the company in September. Markets shrugged; while he obviously has done well for the company in the past, there’s no reason to assume he’s irreplaceable. We’re sure that his replacement will be skillful.
Despite little news elsewhere affecting REITs, we saw price gains for Omega Healthcare Investors (OHI: $32, up 3%), Government Properties Income Trust (GOV: $18.50, up 1%), Apollo Commercial Real Estate (ARI: $18.18, up 2%), Ventas (VTR: $69, up 1%), and Welltower (HCN: $74, up 2%).
Also, there wasn’t any real news on Kimco Realty (KIM: $20, flat), but it’s interesting to note that this retail-focused REIT has had a bit of a resurgence lately thanks to the surprising strength in retail. (Note that we removed Kimco from our portfolio in May, but we wanted to give you an update.) If you remember, several weeks ago in this column we wrote at length at how the “death of retail” cliché was really more about shock financial journalism trying to get clicks from disaster-starved readers and had little to do with the reality of our economy. Well, we were right. In addition to beats from Macy’s, Dollar General, Target, Wal-Mart, and several other retailers, even the near-death dogs like Sears Holdings and Abercrombie & Fitch impressed the market with their quarterly results, beating expectations. Retail is not the healthiest sector on Earth, but it isn’t dead or dying. But Kimco was priced for a dying retail sector. So what does that mean? Kimco shares are up 11% in the last three months.
We want to go on record with another prediction that drives bullishness on retail REITs like Kimco. Amazon’s recent acquisition of Whole Foods and their price drop at the supermarket is going to drive retail sales for two reasons. Firstly, Amazon Prime members will be incentivized to leave their computers and shop in person more. Secondly, more people can now afford Whole Foods and will shop there. That also means people are going to spend more time shopping at auxiliary stores adjacent to Whole Foods. This is a rising tide that is going to lift many boats, which is why buying retail REITs right now makes a lot of sense. Check back in after about six months and see if we’re right.
Good investing,
Todd Shaver, CEO, Founder and Editor
The Bull Market Report
Since 1998
August 27, 2017
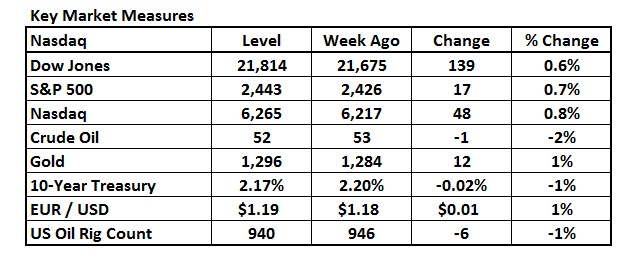
by Todd Shaver | Aug 27, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
What a week. So much for a quiet end to the summer. Yellen made perhaps her final speech in Jackson Hole. Trump is battling a debt ceiling to fund The Wall. And the markets are partying like it’s 1999!
Federal Reserve Chair Janet Yellen, speaking in Jackson Hole, Wyoming, on Friday, issued her broadest defense so far of the government’s response to the 2008 financial-market meltdown while outlining some areas that regulators could review to improve efficiency in the financial system. “Any adjustments to the regulatory framework should be modest and preserve the increase in resilience at large dealers and banks associated with the reforms put in place in recent years,” Yellen said, in what could be her final speech as Fed chair at the annual gathering of central bankers. Her term expires in February.
President Donald Trump is spoiling for a fight with Congress over funding a border wall with Mexico, but he’ll have a hard time waging that battle because of a looming deadline to avert a U.S. debt default. Some of the president’s advisers consider a tough stand on border wall funding crucial to Trump’s credibility, two White House officials said. Some say that failure to make progress on the border wall -- or at least go to the mat on the issue -- may fracture what has been a solid political base for the president.
In 1999, then-Federal Reserve Chairman Alan Greenspan kicked off the central bank’s annual Jackson Hole symposium by highlighting the impact of rising stock prices on an economy that was then enjoying low inflation and low unemployment. Now today, eerily similar, buoyant asset prices and low unemployment argue for Yellen to press ahead with interest-rate increases -- or even accelerate them. Weak inflation suggests she might even want to consider providing more stimulus, not less. That would mimic the tack Greenspan took 18 years ago, when, faced with a frothy stock market, he continued to hike rates until May 2000. The result was a disaster for the stock market -- the technology-heavy Nasdaq Composite Index plunged by 78% over a 2.5 year period from its peak as the dotcom bubble deflated -- but was not all that bad for the economy. Gross domestic product did contract during 2001, but the fall was so small that former Fed Vice Chairman Alan Blinder has called it a “recessionette.” And inflation remained contained. “There are a lot of similarities,” between the late 1990s and today, said Laurence Meyer, who was a Fed governor from 1996 to 2002.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks/funds where we think you can still make good money, including: high yield equities like Annaly or larger caps like Amazon, Facebook, First Solar, Google, Microsoft, and Netflix, as well as small caps like Nutanix.
BMR Companies & Commentary
Amazon (AMZN: $945, down 1%, (for the week))
Amazon Announces New Online Teaching curriculum TenMarks Writing. TenMarks Writing is a new online curriculum designed for teachers to help their students improve their writing skills by using scaffolding, an instructional technique in which students learn step-by-step how the writing process builds.
TenMarks Writing incorporates natural language processing technology to provide students with automatic, personalized feedback and helps teachers deliver differentiated comments as students work through their compositions. It is available for $4 per student for an entire year.
BMR Take: This is just the latest example of another new innovative effort by Amazon. We call Amazon the innovation machine for a reason. Hardly a week goes by without something new and creative coming out from the company. We all know about their entry into food (Whole Foods is part of Amazon as of Monday) and now education. Will this be a major push by the firm? We shall see.
Facebook (FB: $166, flat)
Facebook Usage Growth May Slip among Teens, Young Adults. According to eMarketer's latest forecasts, usage rates for Facebook, Instagram and Snapchat are running roughly in parallel between the US and UK, with Instagram and Snapchat expected to rise by double digits. However, Facebook will see its user growth continue to slow in both countries as lessening usage among teens and young adults drags down overall user growth. Monthly Instagram usage in the US will grow 24% in 2017 to 85 million, also higher than previously forecast.
BMR Take: Do not be alarmed. We repeat. Do not worry. This news of “lowered estimates” and all the talk on TV of slowing engagement for Facebook means very little. It sounds bad. But the reality is engagement is healthy and the bigger factor is new user growth, which remains robust.
First Solar (FSLR: $47, down 1%)
First Solar Sells California Project. This week First Solar announced it completed the sale of the 280 Megawatt (MW) California Flats Solar Project in Monterey County to global private asset manager Capital Dynamics. Terms of the deal were not disclosed.
Located on approximately 2,900 acres of ranch land within the Jack Ranch owned by the Hearst Corporation near the San Luis Obispo and Monterey County borders, California Flats comprises two phases. The 130 MW first phase is expected to be commissioned in 4Q17, and is fully contracted under a long-term Power Purchase Agreement (PPA). The 150 MW second phase, which is currently under construction, is expected to be commissioned by the end of 2018, and is fully contracted under a long-term PPA.
BMR Take: We like this. We understand the cash is going to be reinvested in part of the business with much greater growth prospects. This is just want we want to see from the management teams running the companies we follow.
Google (GOOG: $915, up 1%)
Google and Walmart partner on Voice Shopping. Now people who own a Google Home will be able to order things by voice from Walmart. Cool! But this is copying Amazon Alexa, to be frank. If you can’t beat them join them.
The companies will also participate in the Google Express shopping marketplace, for which Google will eliminate the $95 annual membership fee. Shipping for orders through Google Home or Google Express will be $5 per order, or free if the order reaches a certain level. Costco, Walgreens, and PetSmart already sell via Google Home.
BMR Take: Good news for Google. Amazon is trailblazing the way forward with new innovations by spending tons of money. But there are competitive factors and various stakeholder conflicts, which creates room for companies like Google to jump in with little upfront capital investment, creating great investment opportunities. This could be the start of something big.
We've noticed that Google is lagging the rest of the market. After hitting $980 a month ago, the stock has faded a bit. It seems like a lot, but it's like a $98 stock dropping to $92, not really a big deal. So what do you do from here. You sit back and realize that the market is giving you a huge buying opportunity. Repeat after us: The market is giving you an opportunity to buy the stock a lot cheaper than its all-time high of $988 in June.
Microsoft (MSFT: $73, flat)
Microsoft Acquires Cycle Computing to Accelerate Big Computing in the Cloud. From finding a cure for cancer to making vehicles safer to fulfilling the promises of artificial intelligence, today’s complex problems require the ability to harness massive amounts of computing power. For too long, Big Computing has been accessible only to the most well-funded organizations. Microsoft believes that access to Big Computing capabilities in the cloud has the power to transform many businesses and will be at the forefront of breakthrough experimentation and innovation in the decades to come. Thus far, Microsoft has made significant investments across infrastructure, services and partner ecosystems to realize this vision.
As a further step in this direction, Microsoft recently acquired Cycle Computing, (no price details given), a startup specializing in helping companies perform heavy-duty computing. That includes crunching data for developing new drugs and analyzing risk in the financial services industry. This will make it easier than ever for customers to use High-Performance Computing and other Big Computing capabilities in the cloud. The cloud is quickly changing the world of Big Compute, giving customers the on-demand power and infrastructure necessary to run massive workloads at scale without the overhead. Your compute power is no longer measured or limited by the square footage of your data center.
BMR Take: We’ve already seen explosive growth on Microsoft Azure in the areas of artificial intelligence, the Internet of Things and deep learning. As customers continue to look for faster, more efficient ways to run their workloads, Cycle Computing’s depth and expertise around massively scalable applications make them a great fit for customers. We expect big growth ahead and see Microsoft’s business in a very healthy place.
Netflix (NFLX: $166, flat)
We are not afraid to tell you the good, bad, and the ugly. We know you count on it. We unfortunately have to report that Netflix will lose Disney content in 2019. Disney will end Netflix's film distribution deal as it launches its own streaming services starting with an ESPN service in 2018 and a Disney/Pixar service in 2019. Netflix had inked a deal with Disney to stream films and content just a year ago.
Netflix's stock traded lower on the news as investors see the premature end of the distribution deal as a loss of popular exclusive content. Some have compared the deal termination to the Starz (another Disney property) refusal to renew with Netflix in 2011 and see the move as another example of increasing license renewal risk and streaming competition.
BMR Take: The future of content creation is the holy grail of the media business. While Netflix can survive this one lost deal, the question is how much more of this will we see in the future. There is a long way to go until it is a big problem. But we are worried. Our Target is and has been $165. The stock was higher in July as it rocketed from $146 to $189 but it has fallen since. With a market cap of $72 billion and a PE of a ridiculous 215, we believe it is time for us to put this one to bed. We hereby remove the stock from our Stocks for Success portfolio with a gain of 65% since early 2016. There are lots of better places for your money at this time.
Have you taken the time to go onto the BullMarket.com website? Check out the six portfolios – you’ll find some interesting ideas here for the profits from Netflix.
Nutanix (NTNX: $22, flat)
Cisco Systems announced its intent to acquire Springpath, a leader in hyperconvergence software, for $320 million in cash, with the transaction expected to close in 1Q18. Springpath has developed a distributed file system purpose-built for hyperconvergence that enables server-based storage systems, and Cisco believes the acquisition will allow it to continue to deliver next-generation data center innovation to its customers.
In terms of Cisco, the acquisition was not a surprise, as the two companies have a relationship that goes back to Springpath's 2012 founding and Cisco previously making an investment in the company with an option to acquire it. That said, it is still a bummer for Nutanix. Analysts believed Cisco was a potential acquirer of Nutanix.
BMR Take: Hyperconvergence software is an exploding market. We expect Nutanix to do great things and generate big growth. The stock is hovering our Sell Price and we have had tons of calls and letters about whether we would “sell” the stock. First of all, we don’t own the stock. We don’t buy any of our recommendations as we want to remain clear of any conflict of interests. Secondly, the Target and Sell Prices are there for YOU to decide what to do with your investment. All of you are different. Some have multiple millions and some of you are just getting started. So you have to weigh every investment as it affects you and your family.
With that said, we believe Nutanix will be a big, big winner. Revenues are strong with last quarter coming in at $192 million vs. $115 million the year before. This is HUGE. But remember, this is a small cap stock – tiny in comparison to a Facebook or Google. The market cap is just $3.3 billion. So watch and wait and make a decision for yourself and your family. We think the company is a potential great one, but the market is stretching our patience.
We found this interesting too:
Firsthand Technology Value Fund, a publicly traded venture capital fund that invests in technology and cleantech companies, disclosed that its top five holdings as of July 31, 2017, included Nutanix. The fund’s investment in Nutanix consisted of 460,000 shares of common stock and represented approximately 7% of the fund’s total.
Upcoming Economic News
Consumer Confidence
Tuesday, August 29th, 10:00 AM ET
Period: August
Consensus: 120.0
Prior: 121.1
ADP Employment Survey
Wednesday, August 30th, 8:15 AM ET
Period: August
Consensus: 180,000
Prior: 177,700
Personal Consumption Expenditure
August 31th, 8:30 AM ET
Period: July
Consensus: 0.40%
Prior: 0.10%
Apple Has Debt Too
A few of you have written us and given us grief because we only report Apple’s cash position and don’t report the debt levels. Our internal excuse has always been that Apple’s debt is at very low interest rates. Here are some examples of Apple’s debt:
Apple 2.4% 5/03/2023 $5.5 billion
Apple 1.0% 5/03/2018 $4.0 billion
Apple 4.65% 2/23/2046 $4.0 billion
Apple 3.25% 2/23/2026 $3.25 billion
Apple 2.85% 5/06/2021 $3.0 billion
Apple 3.85% 5/04/2043 $3.0 billion
Apple 2.25% 2/23/2021 $3.0 billion
Apple 3.45% 5/06/2024 $2.5 billion
Here is some more detail:
From their latest financial reports, the last three yearly balance sheets ended September have shown that debt has risen from $29 million in 2014 to $53 million in 2015 and to $75 billion in 2016. At the same time cash has risen from $154 billion to $206 billion to $236 billion, reaching $260 billion in their last quarterly report on July 1st.
So: Big cash. And big debt. The NET CASH position at year-end September 2016 was approximately $160 billion. (And much higher now.)
We’ll take it.
Opko Health (OPK: $6.13, flat) Two weeks ago, the company reported earnings for 2Q17. Total revenues of $314 million were down 12% year over year from $357 million. Revenues included a $10 million payment associated with the commercial launch of Varuby in Europe in comparison to the $50 million payment related to a Rayaldee license in the same quarter in 2016.
Research and development expenses totaled $33 million, up 4%, while selling, general and administrative expenses amounted to $128 million, up 9% year over year. Consequently, loss from operations came in at $4 million, highlighting a significant decline from an operating income of $55 million in the prior-year quarter. The decline can be attributed to a rise in operating expenses owing to the company’s significant investments associated with the commercial launch of Rayaldee along with consistent investments in the pharmaceutical pipeline.
The company has $130 million in cash, unchanged from the quarter before.
This is a biotech company in an industry that is known for companies with years and years of little or no progress (and revenues) and then a big announcement of great success. Luckily Opko isn’t in the camp of no revenues. Revenues as you know are over $1 billion.
Chairman and CEO Frost On the Impact of Opko’s 4Kscore
Released in 2014, the 4Kscore Test is the only blood test that can accurately identify a patient's risk for aggressive prostate cancer, Opko claims. As calls to reduce health care costs across the United States grow louder, 4KScore is as a cost-effective alternative to biopsies, Frost said.
About 30 million tests are done each year to measure men’s prostate-specific antigens, or PSA. Of those, 4 million identify elevated PSA levels and typically would require biopsies.
“If you do the test after the elevated PSAs, you can avoid 50% of all biopsies,” Frost said. “This is the type of thing that if you wanted to be able to cut healthcare costs in this country, this has to be the easiest thing in the world to do.”
On why he continues to buy thousands of OPKO shares
“I always believe in investing in things that I know about rather than things I don’t,” Frost said.
BMR Take: Opko Health is a relatively small biotech firm with great potential. Many times “great potential” results in “no results.” This $3.4 billion market cap company is poised for success, but remains the most speculative stock in our six portfolios.
Splunk (SPLK: $65, up 10%)
Splunk had a great week. They reported earnings on Thursday after the close and they were stellar. This is what we have been waiting for. Revenue rose to $280 million from $213 million a year ago, for a percentage gain of 31%. Huge quarter. Adjusted earnings were $11 million or 8 cents a share.
Guidance is solid with next quarter revenue of $308 million. Operating margins are projected to be approximately 8%.. Growth in yearly revenues has been spectacular. For the last three years we have seen $450,000,000, $670,000,000 and $950,000,000. For fiscal year 2018, ending this coming January, revenue is now expected around $1.21 billion.
Billings in the quarter grew 32% year over year to $303 million. They again increased full fiscal-year 2018 guidance to call for billings of $1.45 billion.
Splunk has been ranked number one in worldwide IT Operations Analytics (ITOA), as well as Event and Log Management software market shares for 2016 by International Data Corporation. Splunk said that these two markets have witnessed the highest growth rates within the overall IT market, with ITOA seeing an increase of 33%, and Event and Log Management growing 23%. This is the third consecutive year that Splunk took the top spot in the ITOA software market, beating the competition of IBM, Microsoft, Hewlett Packard Enterprise and VMware.
More than 500 new customers were added during the quarter, including Athenahealth, Carnival Cruise Lines, the Department of Homeland Security, Harvard Business School, Shutterfly, Uber, and Verizon.
Splunk appears quite dominant in its machine data analytics niche. And the company's market opportunity is growing as its software, traditionally used for IT operational intelligence, gets adopted for security, fraud-detection, app analytics and other use cases.
BMR Take: Great quarter. Looking for continued growth for years to come. Our Target is $75 and our Sell Price remains $60. Note that Splunk has exceeded guidance for 11 straight quarters.
VMware Has a Strong Quarter
VMware ($103, up 7%) had a great week after reporting $1.9 billion in revenues up from $1.7 billion last year with net income of $335 million up from $265 million, $1.19 a share up from $0.97. Huge. Total cloud management bookings rose by a 13% year over year, and the company closed 10 deals valued at over $10 million. Network Virtualization (NVX) revenues were again strong, at over a 40% increase.
The company guided for the year: Revenue of $7.83 billion, EPS of $5.06, and free cash flow of $2.7 billion. These are big numbers.
VMware raised $4 billion earlier this month in a debt offering, mostly overseas, with coupons of 2.3% to 3.9%. Note that Dell Technologies owns 82% of VMware.
Take a look at this chart:
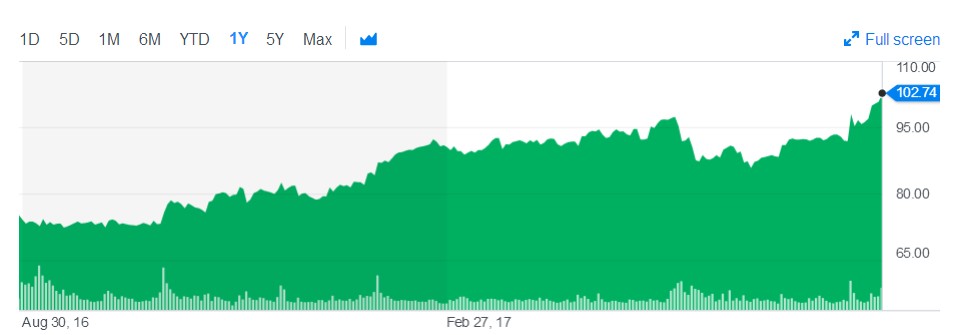
BMR Take: We think you get the drift!
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
As Alfred E. Neuman might say, "What – me worry?" ……as in why care about things such as 1) When will the Fed hike rates again and how many hikes can we expect? 2) Has the 2nd quarter economic rebound already been priced into stocks? 3) Are tax cuts still possible or has the pro-growth agenda been totally derailed by swamp politics? 4) Will we have a trade war with China? 5) Will we go to war with North Korea? 6) Are we headed into a recession?
Sure, we care and everyone else should care about getting tax relief. We have the worst tax system in the world if you don't count dictatorships. But we've lived in the current system for decades and so, while it would be a whole lot better if we got tax reform, investors and the stock market will survive if we don't. We also admit that of course we would care if we had a war. That is highly unlikely however, because none of the large powers has any desire to start WW III. Otherwise, worrying about all of the above is not a good idea - or, as Mom used to say, "If you worry too much, you'll worry yourself to death." So, we are adding a little bit of Alfred's advice to our medicine cabinet and are just going to go on about our business and not worry too much.
Business as usual with all these worries hanging around (stocks love to climb a wall of worry) generally means an investor should expect more volatility. We expect just that. We know stocks tumble way faster than they go up. Thus, we know not to panic - and that is a huge plus for every investor. Or, we might have a little cash to buy into any sale that may come along. Or, we have dividend stocks that will reinvest into more shares whenever they go on sale. And finally, we aren't going to worry about a recession now because the facts simply don't support it. We've looked at inflation, housing starts, retail sales, industrial production, oil prices -- there just isn't any "big trouble" in the economy today.
Not only that, it wasn't that long ago when the US economy seemed like the only regional power heading in the right direction. Europe had record joblessness and was teetering on the edge of recession. Japan was in its 20th year of malaise and China was headed for a hard landing if not a total crash.
Today, all of these regions are showing signs of renewed strength. European markets are doing better than expected. Japan also recently impressed with a +4% GDP growth rate - well above estimates - and China has emerged from a soft patch with a string of positive economic readings. With 40% of US corporate profits coming from abroad, all of the above is then a simple equation pointing to more earnings growth and share price appreciation ahead.
T. Rowe Price once said, "No one can see ahead three years, let alone five or ten." So, we aren't forecasting that conditions won't change in the immediate or distant future. But for the time being, we still see the glass as half full.
A Little Unsettling News
We follow the trends in cash flows into and out of mutual funds. We remember well, back in the 2004-2007 time frame the cash inflows into the stock market were consistent, month after month as cash poured into the market. But we noticed recently that cash outflows are continuing these past few months. U.S. equity funds suffered their longest streak of outflows in 13 years as growing signs of political deadlock in Washington cast doubt on a rally that has taken the S&P 500 Index to record highs.
Investors pulled $2.6 billion from U.S. stock funds in a 10th consecutive week of outflows. That takes total outflows since late June to $30 billion, which covered the week to Aug. 23.
BMR Take: This is serious stuff in our book. We’ve watched these stats for over 30 years and we have found it to be a strong indicator of future prices. We’re watching this one closely.
The High Yield Report
By Michael Foster
Senior Writer
The Bull Market Report
This week could best be described as dull. High yield investments neither enjoyed the euphoria that some assets enjoyed earlier this year, nor continued the panic that we saw in recent weeks due to political noise.
This is not terribly surprising; as we’ve said repeatedly in this column, the fundamentals are strong and there’s little reason to expect a selloff anytime soon. At the same time, however, there is little reason to believe the strong bull run of previous months is going to continue - a lot of the upside is already priced in. That puts us in the rather boring “hold and collect income” position, but when that income is 8% or more on high yield assets, that dullness is quite enriching.
So let’s get specific on a few of our high yield investments in this dull week. A number of Bull Market Report recommendations moved through the week quietly, including several REITs. Omega Healthcare Investors (OHI: $31, up 1%), Apollo Commercial Real Estate (ARI: $17.84, flat), and Ventas (VTR: $68, up 3%). These REITs suffered some volatility earlier this year but have had a much better long-term performance. Much more importantly for us, their dividends remain safe as ever - the recent market turmoil and even more recent market calm have not impacted the income streams of these funds.
Omega in particular is worth a close look because of its high yield and aggressive dividend growth policy. Its 8.2% dividend yield implies a lot of risk, but its dividend coverage ratio over the last twelve months is 134% - far higher than many comparable REITs, and even higher than a lot of lower-yielding REITs. We’ve pounded the table on Omega several times this year for this reason, and with good reason. There os just too much safety in this dividend relative to its yield; if you don’t already own Omega, ask yourself why you aren’t enjoying a growing 8.2% dividend that is more covered by FFO than several 3-4% yielding REITs? And if you have a good answer to that question, let us know, because we can’t imagine there is one.
Elsewhere, municipal bond funds had a quiet week, with both Nuveen AMT-Free Municipal Credit (NVG: $15.49) and Invesco Municipal Trust (VKQ: $12.94) ending the week flat. To understand this, let’s talk a bit about Treasury yields. A big reason why muni bonds fell so heavily in mid-2016 (which is why we waited to recommend them until the end of the year) is that the market was pricing in steep interest rate increases throughout 2017. While we’ve had two rate hikes so far and a third expected in December, (although the probability of even that is declining), that’s less than the Fed had hinted at in 2016. That’s good for municipal bonds, which is why muni bonds have had a strong showing in 2017. For instance, the Nuveen fund we’ve recommended is up 7.2% year-to-date on price alone - that’s less than 200 basis points less than the S&P 500, despite muni bonds’ much lower risk profile and the fund’s 5.6% dividend yield!
The reason for this strong run up in muni bonds - and their relative quiet last week - has to do with interest rates. The market priced into munis a fast pace of rate hikes in 2017, but the reality is that the rate hike schedule is getting longer and longer - meaning the value of munis isn’t going to go down as much as was previously expected. Since the downside was 100% priced in, the lesser downside means these assets were priced too cheaply. And so they’re going up in 2017. It’s also partly why muni bonds have seen relative volatile price movements both up and down in the last couple of years.
Is it still a good time to buy munis? Maybe - it isn’t as clear of a good buy as, say, Omega Healthcare, but holding these funds and collecting their tax-free income stream right now makes a lot of sense.
And there are other interesting options out there, such as the strong performing Digital Realty Trust (DLR: $118, up 3%) and AstraZeneca (AZN: $29, flat). Both of these names are riding a strong wave of momentum thanks to growth in the companies’ fundamental businesses. AstraZeneca was far underpriced last year due to fears of regulations that obviously are not coming anytime soon. Additionally, the drug pipeline is as strong as ever. Similarly, endless demand for server space has made Digital Realty Trust a no-brainer at almost any price. The only problem is that the price growth has lowered their yields - Digital Realty is yielding 3.2% and AstraZeneca is down to 4.8%. It’s becoming clearer and clearer that these two names really should be considered growth or value investments rather than high yield investments. If your goal is to secure a high rate of current income, these names aren’t exactly for you. However, if you appreciate companies with growth potential that haven’t had their future growth fully priced in, but have decent dividends, both names are definitely worth serious consideration.
In any case, the last few weeks have given us a very clear lesson again: Short-term panics based on political headlines are not reasons to sell investments, while fundamental trends in terms of economic demand and dividend coverage are. Financial considerations tell us there’s really nothing to worry about right now.
Good Investing,
Todd Shaver, CEO, Founder and Editor
The Bull Market Report
Founded 1998