October 31, 2017
by Todd Shaver | Oct 31, 2017 | 1pm News Flash
Shopify (SHOP: $98, down 11) today posted a better-than-expected jump in revenue and improved outlook, but its shares fell as investors digested its response to a short-seller's attack.
Revenue jumped 72% as it reported adjusted profit for the first time as a public company and raised its fourth-quarter forecasts. Revenue was $171 million, above expectations for sales of $166 million. The company earned 5 cents a share, its first ever-operating profit as a public company and beating third-quarter estimates. Shopify expects revenue of $207 million this quarter.
The stock has been shorted heavily by Andrew Left of Citron. Founder and Chief Executive Officer Tobi Lutke said Shopify's external legal counsel had dismissed Left's claims as "preposterous."
Shopify said it signed up another 60,000 new merchants in the three months to Sept. 30, adding to the more than 500,000 existing customers who use its commerce software.
Shopify mostly serves small and medium-sized businesses with services including payment processing, inventory management and shipping solutions. It also is building a higher-end service for larger customers.
BMR Take: Revenues will win out in the end. Revenues will win out in the end. Revenues will win out in the end. 72% revenue growth in the quarter. 560,000+ customers love this company. A year from now we’ll look back at Andrew Left’s huge losses on his short position, and on your own big profits in the stock.
October 30, 2017
by Todd Shaver | Oct 30, 2017 | Earnings Preview 6 AM
Omega Healthcare Investors (OHI: $32)
Bull Market Report Target Price: $45
Bull Market Report Sell Price: $28
Earnings Date: Monday, 4:00 PM ET
Consensus: 3Q17
Revenues: $238 million
EPS: $0.46
Year Ago Quarter Results
Revenues: $185 million
EPS: $0.40
Key Things to Watch For in the Quarter
Omega Healthcare is expected to report a 15% increase in earnings per share and a 30% increase in revenues for 3Q17. The stock has had mixed earnings results over the past four quarters, missing estimates twice and beating twice. This lack of certainty has been reflected in the stock’s performance over the past year, as it has barely moved from its price of $32 this time last year. Although the stock has underperformed the market over the past year, we are still very bullish for Omega as they continue to grow their sales and yield a very attractive 8% dividend.
-----------------------------------------------------------------------------------------------------------------------------
The Carlyle Group (CG: $22)
Bull Market Report Target Price: $28
Bull Market Report Sell Price: $20
Earnings Date: Tuesday, 8:00 AM ET
Consensus: 3Q17
Revenues: $680 million
EPS: $0.49
Year Ago Quarter Results
Revenues: $540 million
EPS: $0.21
Key Things to Watch For in the Quarter
Analysts expect The Carlyle Group to report a 26% increase in revenues and a 133% increase in earnings per share for 3Q17. Although the stock has beaten estimates in only two of the past four quarters, it has still managed to outperform the S&P 500 over the past year, providing shareholders with 44% return. We love this stock! It returns an 8% dividend and currently trades at a PE ratio of only 16, which is quite cheap compared to most of its competitors which are in the 18-20 range.
-----------------------------------------------------------------------------------------------------------------------------
Shopify (SHOP: $107)
Bull Market Report Target Price: $115
Bull Market Report Sell Price: $105
Earnings Date: Tuesday, 8:30 AM ET
Consensus: 3Q17
Revenues: $165 million
EPS: -$0.01
Year Ago Quarter Results
Revenues: $99 million
EPS: -$0.11
Key Things to Watch For in the Quarter
Analysts estimate Shopify will report a 66% increase in revenues and a reduction of its earnings deficit for 3Q17. The stock has been one of the best performers in all of our portfolios this past year, as it appreciated 160%. The company’s ability to growth its profits has been demonstrated over the past three years or so. Since 2014, Shopify has to increased its bottom line by 300%. We expect to see continued growth from Shopify as it continues to provide value for its customers with its cloud-based multi-channel commerce platform.
-----------------------------------------------------------------------------------------------------------------------------
Government Properties Income Trust (GOV: $18.14)
Bull Market Report Target Price: $23
Bull Market Report Sell Price: $15
Earnings Date: Thursday, 11:00 AM ET
Consensus: 3Q17
Revenues: $70 million
EPS: $0.05
Year Ago Quarter Results
Revenues: $65 million
EPS: $0.16
Key Things to Watch For in the Quarter
Government Properties is expected to report an 8% increase in revenues and a 68% reduction in earnings per share for 3Q17. Despite having beaten estimates in three of the past four quarters, the stock has fallen about 5% since this time last year and is currently trading 21% below its 52-week high of $23. The stock took a big hit in July this year when the company announced a secondary offering of 25,000,000 common shares, plus an overallotment sale of 2.9 million shares, raising close to $500 million. Although this action took a toll on the stock in the short term, we don’t see it affecting the performance of the underlying company moving forward. In fact, we love it when a company sells stock and raises capital. We remain bullish on Government Properties and continue to look forward to the 10% dividends that come with this stock.
-----------------------------------------------------------------------------------------------------------------------------
Annaly Capital Management (NLY: $11.61)
Bull Market Report Target Price: $12
Bull Market Report Sell Price: $11
Earnings Date: Wednesday, After Market Close
Consensus: 3Q17
Revenues: $625 million
EPS: $0.30
Year Ago Quarter Results
Revenues: $560 million
EPS: $0.29
Key Things to Watch For in the Quarter
Annaly Capital Management is expected to report an 11% increase in revenues and a 3% increase in earnings per share for 3Q17. The stock has beaten analyst estimates in each of the past four quarters and is up 12% over the past year. The stock returns a 10% dividend and currently trades at a PE of 4, making it one of the cheapest (compared to earnings) stocks in our portfolio. Our confidence in Annaly has increased with recent insider trades from their Chief Investment Officer, David Finkelstein. Just last month, he purchased $1.25 million worth of Annaly’s stock, showing his faith in the company moving forward over the long term.
-----------------------------------------------------------------------------------------------------------------------------
Facebook (FB: $177)
Bull Market Report Target Price: $190
Bull Market Report Sell Price: $155
Earnings Date: Wednesday, 5:00 PM ET
Consensus: 3Q17
Revenues: $10 billion
EPS: $1.28
Year Ago Quarter Results
Revenues: $9 billion
EPS: $1.09
Key Things to Watch For in the Quarter
Analysts estimate that Facebook will report an 11% increase in sales and an 18% increase in earnings for 3Q17. Facebook has beaten estimates in three of the past four quarters, contributing to the stock’s 35% gain over the past year. Facebook’s reinvestment back into the company has been driving growth and innovation, and with increasing capital expenditures we don’t see this growth slowing any time soon.
-----------------------------------------------------------------------------------------------------------------------------
Tesla (TSLA: $320)
Bull Market Report Target Price: $350
Bull Market Report Sell Price: $280
Earnings Date: Wednesday, 5:30 PM ET
Consensus: 3Q17
Revenues: $3.0 billion
EPS: -$2.29
Year Ago Quarter Results
Revenues: $2.3 billion
EPS: $0.71
Key Things to Watch For in the Quarter
Analysts estimate that Tesla will report a 30% increase in revenues and a large earnings deficit for 3Q17. Although Tesla has only managed to beat estimates in two of the past four quarters, the stock is up 60% over the past year. You've heard us speak about Tesla and being patient, and how speculative the stock is. Be careful.
-----------------------------------------------------------------------------------------------------------------------------
Apple (AAPL: $163)
Bull Market Report Target Price: $170
Bull Market Report Sell Price: We would not sell Apple
Earnings Date: Thursday, 5:00 PM ET
Consensus: 3Q17
Revenues: $51 billion
EPS: $1.87
Year Ago Quarter Results
Revenues: $47 billion
EPS: $1.50
Key Things to Watch For in the Quarter
Apple is expected to increase its revenues by 8% and its earnings by 25% for 3Q17. The stock has beatdn earnings estimates in three of the past four quarters and is up nearly 45% since this time last year. This quarter was interesting for Apple, as we saw a number of product releases, namely its iPhone 8 and X. We also suspect an increase in the sale of Apple’s iPad over the next few quarters, which, although isn’t the largest revenue driver, will definitely continue to help push Apple’s top line higher.
-----------------------------------------------------------------------------------------------------------------------------
CBRE (CBG: $39)
Bull Market Report Target Price: $40
Bull Market Report Sell Price: $35
Earnings Date: Friday, 7:00 AM ET
Consensus: 3Q17
Revenues: $3.5 billion
EPS: $0.54
Year Ago Quarter Results
Revenues: $3.2 billion
EPS: $0.50
Key Things to Watch For in the Quarter
CBRE is expected to report a 9% increase in revenues and a 9% increase in earnings for 3Q17. CBRE has beaten analyst estimates in each of the past four quarters, which has been reflected in the stock’s 50% appreciation over the past year. Although the stock doesn’t pay a dividend, it does trade at a reasonable PE ratio of 19. We view this stock as one of the best growth investments in our Stocks for Success Portfolio.
October 29, 2017
by Todd Shaver | Oct 29, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
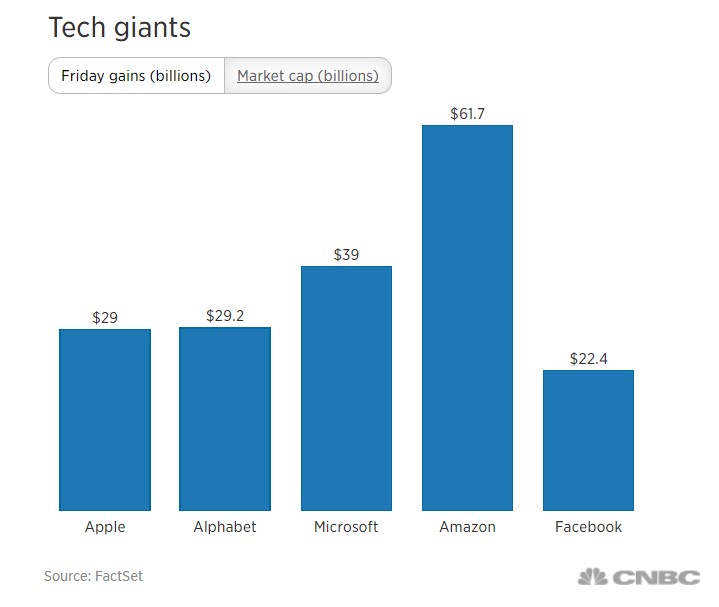
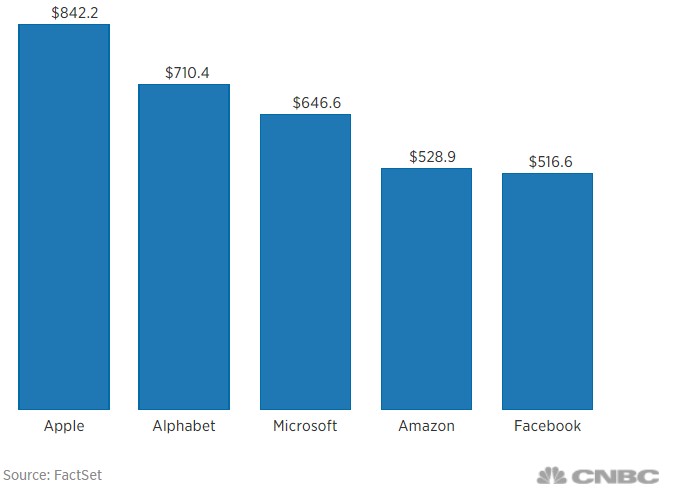
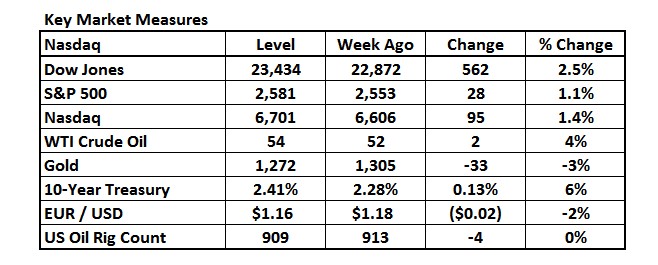
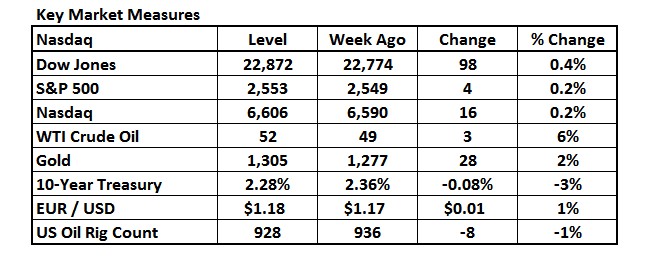
US equities finished the week higher on Friday again. There was a notable rally in Tech with several mega-cap names hitting all-time highs after earnings. Apple, Alphabet, Microsoft, Amazon and Facebook, the world's five most valuable public companies, added $180 billion to their combined market value on Friday. Investors piled into the group a day after Alphabet, Microsoft and Amazon reported better-than-expected earnings. For the stock market, it was more of the same. Those five companies have gained almost $900 billion in market cap over the past year.
Shares of Amazon and Google both surged past the $1,000 mark and approached all-time highs, with Amazon closing above $1100. To many people’s surprise, we continue to see favorable broad market trends with US equities seeing $14 billion of inflows over the last three weeks.
Friday's Gains:
Market Caps:
There was nothing particularly incremental on tax overhaul this week, as the House narrowly adopted the Senate budget, paving the way for release of initial tax legislation next week. Trump is leaning toward Powell for Fed chair, and the official announcement is expected next week.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks where you can still make good money, including: Apple, Microsoft, Amazon, Celgene, Bristol-Myers, and UPS and a few others.
BMR Companies & Commentary
Apple (AAPL: $163, up 4%)
Well, Apple has still got it! Apple sold out iPhone X pre-orders. Thousands of Apple fans from around the world flooded the website to lock in their pre-orders for the iPhone X. Apple sold out pre-orders for the phone to arrive on the November 3rd launch day in 17 minutes, and the wait time has grown to five to six weeks.
Apple said, "We can see from the initial response, customer demand is off the charts. We're working hard to get this revolutionary new product into the hands of every customer who wants one, as quickly as possible."
Why is this so important? Despite major concerns over manufacturing the deluxe iPhone, and the high price of $999, demand is not lacking at all. This finding bodes well for the stock and future prospects.
BMR Take: Apple sold 41 million iPhones last quarter and will sell over 200 million this year. The holiday quarter is the busiest season of the year, of course, and this year Apple is projected to sell over 80 million iPhones in the Christmas quarter, a new record. With iPhone sales fueling great than 10% EPS growth, we continue to see bright prospects for the stock.
Microsoft (MSFT: $84, up 6%)
Microsoft crushed the quarter. Revenue of $24.5 billion increased 12% from a year ago and beat expectations for $23.5 billion. EPS of $0.84 increased 17% from a year ago and smashed expectations for $0.71.
Earnings rose to $6.6 billion, or 84 cents a share, from $5.7 billion, or 72 cents a share, a year earlier. They are still making 27% profits on sales, AFTER TAX! The strength was broad based.
Analysts were most impressed by momentum in cloud that pushed Commercial Cloud above the company's $20 billion targeted goal they set two years ago approximately three quarters ahead of schedule.
Microsoft’s Azure's cloud revenue increased 90% in the period and has exceeded Amazon’s AWS growth for at least eight straight quarters, but Microsoft has yet to break out the unit's sales. AWS controls 34% of the market while Azure has 12%. However, Microsoft is picking up high-profile clients as it adds features, lowers prices and expands data center capacity around the world.
Amazon’s AWS brought in $4.6 billion in sales, which represents an annualized run rate of $18.3 billion. So you heard it here first, Microsoft is leading Amazon in the world of cloud.
Microsoft continues to increase its share in overall IT spending, and momentum in its results was a clear theme this quarter. Margin performance and free cash flow generation also stood out in the quarter.
BMR Take: With the cloud business tracking way ahead of plan, free cash flow per share forecasts now closing in on $5, and with so many other great things happening at Microsoft we continue to view this stock as a core tech holding for any portfolio. The stock blew through our Target of $78 to a new all-time high, so we hereby adjust it to $92. Our Sell Price remains “We would not sell Microsoft.”
Amazon (AMZN: $1,100, up 13% - $129 a share on Friday!)
Revenue: $43.7 billion growing 34% from last year, but only $1.3 billion in sales included from Whole Foods, which Amazon acquired in late-August. North American sales were $25.4 billion, up 35% from last year, while international sales grew 29% to $13.7 billion. Amazon gave fourth quarter guidance in the range of $56-60 billion. Wow.
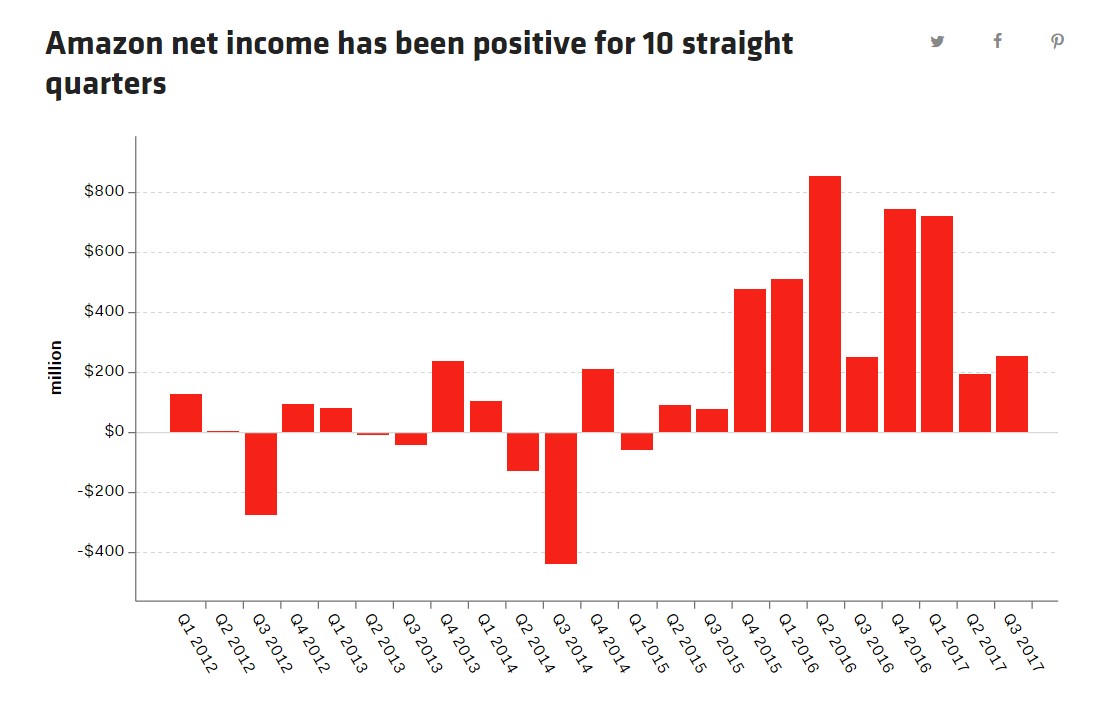
The company’s net income was $256 million, or 52 cents a share. Analysts on average expected earnings of 2 cents a share. (Now THAT is funny. 2 cents a share expected and they report 52 cents! Gotta love this company.

Here we go again! Another industry is about to get “Amazon-ed”. This should be fun to watch and great for the stock:
Pharmacies and Healthcare Distributors continue to trade lower following news that Amazon eying the space. The St. Louis Post-Dispatch reported that Amazon has received approval for wholesale pharmacy licenses in at least 12 states. The topic was discussed further on Amazon’s earnings conference call with the company noting that hospitals and labs were among the areas that could be served under its Amazon Business initiatives. Both distributors and pharmacies are reacting negatively to the perceived threat.
And one potential competitor has jumped the gun by looking to buy a Healthcare company. CVS Health is offering to buy Aetna (AET: $173, down 3% Friday) for more than $200 per share, which would value the company at more than $66 billion. Aetna rallied 12% after the reports. According to the WSJ sources, the merger proposal was spurred by expectations that Amazon might enter the pharmacy business. A tie-up between a retailer like CVS and a health insurer like Aetna may seem surprising on the surface. But experts say both parties need to make strategic moves to address the changes in the sector, including the possible threat from Amazon.
While the above news stole the news headlines this week, keep in mind the core business delivered stellar results.
Revenue beat across all three segment. AWS revenue grew 42% - matching Q2's growth rate, assuaging fears of a deterioration, and beating consensus AWS income by $130 million.

BMR Take: Amazon didn’t just hit smash $1,000 again, the stock rolled right on to $1,102, closing up $128 a share to a new all-time high. With the potential entry into pharmacy, the “innovation machine” called Amazon is alive and well. We see EPS heading to $20 taking the stock much higher over time. We hereby raise our Target of $1100 which it will hit Monday morning, to $1300. Our Sell Price is raised from $970 to $1030.
Celgene (CELG: $98, down 19%)
Celgene had the biggest drop in 17 years on Thursday. Celgene has stumbled, but now is the time to stick with it and accumulate. Why?
Let’s take out all the noise. The fact is the company’s long-term EPS guidance was hardly cut at all from $13 to $12.50. We are still looking at greater than 20% EPS growth through 2020 as revenue explodes from $13 to $20 billion. Specifically, consensus EPS currently resides at $7.30 in 2017, $8.80 in 2018, $10.50 in 2019, and $12.60 in 2020.
Admittedly, it may take a while and we must be patient. There is all sorts of debate about how R&D expenses could disappoint and there are no major catalysts on the drug development front foreseeable in the next 12 months. Then there is also a camp out there that believes that any day now management could make a transformation acquisition that re-ignites excitement about the prospects for the business.
BMR Take: Celgene is the 7th largest component of the Healthcare sector and a $77 billion market cap juggernaut. You have to trust that the franchise is viable and will learn and progress past this current point of disappointment. This looks to us like a classic case of Wall Street exuberance on the downside with this out-of-favor sentiment swing. Take advantage of the drop and accumulate the stock down here.
Bristol-Myers Squibb (BMY: $60, down 7%)
Oh Bristol-Myers. Thou shalt no longer disappoint us at The Bull Market Report. Overall third-quarter revenue rose 7% to $5.25 billion, meeting Wall Street estimates. Earnings rose to $845 million, or 51 cents a share, from $385 million, or 24 cents a share, a year earlier.
Bristol said its gross margin as a percentage of revenue fell to 70% from 73.5% a year earlier due to product mix and higher costs, including a $70 million write-off of inventory for hepatitis C products.
Sales of cancer immunotherapy Opdivo rose 39% to $1.27 billion, in line with the average estimate of $1.21 billion, while sales of blood thinner Eliquis rose 38% to $1.23 billion, matching analyst estimates.
Bristol’s Chairman & CEO had this to say, “We had a good quarter, demand for Eliquis and Opdivo was strong and we advanced our portfolio with important clinical and regulatory milestones, including exciting data for kidney cancer patients with Opdivo + Yervoy. Looking forward, our focus is on continuing to deliver strong commercial performance, advancing our pipeline and ensuring our resources are applied to priority areas of our portfolio for sustainable, long-term growth.”
That said, there remains plenty of merger and acquisition talk, so we are sticking around for what could be a one-day 20-30% premium or higher.
BMR Take: Remember, activist investor Carl Icahn who has a stellar long-term track record is in the stock as one of the largest shareholders. He believes the business is suspect to being taken over and such a sale could unlock tremendous value for shareholders overnight. Stay the course!
The quarter looked pretty good to us. We wouldn’t worry about it too much. The stock may sell off for a few weeks, but we expect it to slowly start to move higher by Christmas.
UPS (UPS: $121, up 1%)
UPS forecasts record holiday delivery of about 750 million packages globally in the 25 days between Thanksgiving and New Year’s Eve. The record-breaking seasonal global delivery volume is about 5% above last year’s season. Of the 21 holiday delivery days before December 25th, 17 are expected to exceed 30 million delivered packages. Mind boggling!
With the launch of UPS Saturday ground pickup and delivery service, customers in nearly 4,700 cities and towns across the country will benefit from five additional ground pickup and delivery days between Thanksgiving and Christmas.
Online and mobile commerce has transformed the retail industry, and UPS is ideally positioned to serve both consumer and business customers during even these busiest of times.
According to the National Retail Federation, retail sales in November and December are forecast to increase 4%, reaching between $680 billion. During the busy holiday shipping season, UPS flexes its global delivery network to process nearly double the regular daily volume of 19 million packages and documents.
UPS continues to invest in the operational and consumer technologies and facility improvements that enable the company to deliver the holidays for customers. Enhanced customer visibility tools, increased consumer convenience, and the availability of the new Saturday ground delivery and pick-up services are all part of the expanding solutions UPS is providing customers, to take full advantage of the holiday season.
This peak season, UPS plans to employ 95,000 temporary seasonal workers, including drivers, delivery helpers who ride with drivers, package sorters, and loaders. Candidates for seasonal jobs can apply on UPSjobs.com. This holiday work often is an entry point for future permanent jobs and career advancement. Almost 35% of those hired seasonally over the last three years now have permanent jobs with the company.
BMR Take: It is crazy to think about just where our country would be without UPS. This business is the backbone of our culture and our economy. It is a must-own in any portfolio. With EPS on track to crack $20 in a few years, the stock remains a good value.
Upcoming Economic News
Personal Income
Monday, October 30th, 8:30 AM
Period: September
Consensus: 0.40%
Prior: 0.20%
Consumer Confidence
Tuesday, October 31st, 10:00 AM
Period: October
Consensus: 121.0
Prior: 119.8
ADP Employment Survey
Wednesday, November 1st, 8:15 AM
Period: October
Consensus: 200,000
Prior: 135,000
Total Light Vehicle Sales
Thursday, November 2nd, 8:00 PM
Period: October
Consensus: 17,500,000
Prior: 18,500,000
Update on Tesla (TSLA: $321, down 7%)
Tesla had a rough week in the markets, dropping $24. We uncovered some information about how the firm is doing in China. It looks like Tesla is making great progress in the difficult China market after all. Elon is great! 🙂
Tesla is moving to begin manufacturing in China. The firm won agreement with Shanghai's government to build a wholly-owned factory in the city's free-trade zone, the first arrangement of its kind in China for a foreign auto maker. Generally, the government makes firms partner with a Chinese company. They didn’t require that in this case with Tesla.
The deal would help Tesla slash its production costs as it would bring down shipping costs and the final price on its electric cars. More significant, it would give Tesla a base from which to export to the rest of Asia. Beijing has mandated a dramatic increase in production of electric vehicles.
BMR Take: The ride with Tesla has its bumps in the road for sure. This week is a further indication of that. They are close to starting substantial deliveries of the Model 3 this year, as they hold cash deposits for almost 500,000 cars. But just as they get closer, production snafus are leaking out from the company and the stock gets hit.
You should only be an investor in this company if you are breathing the happy gas that Elon Musk is sending out. Again, the stock can go to $500 from here, or $200. We’re just not sure which will come first.
A Word From Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services
What's Right with the Market?
As we mentioned last week there had to first be a move to get 51 votes or "it was all just a waste of time". Well, the Senate did pass a budget bill which sets the stage for tax legislation later this year. The significance of the budget passage is that it allows the Senate to now pass their tax legislation with a simple majority of 51 votes rather than the needed 60 votes without one. And since literally no Democrats appear willing to vote for the plan, this was a crucial step for the administration to get their plan approved. The President's plan to cut corporate and individual taxes and to make other business-friendly changes to the tax code have helped to push stocks higher. And, under this potential first major overhaul in about 30 years, corporations would see their top tax rate cut from 35% to 20% - which should obviously be a continuing tailwind for shareholders.
[BMR: Of course, whether this happens or not is certainly not clear. But we will say this: If it doesn’t happen, we are going to see a lower stock market.]
Some thoughts about the length of this bull market and stock overvaluations.
When Treasuries are paying less than 3%, certificates of deposit (CDs) less than 2% and cash less than 1%, it makes quite a bit of sense to continue to use stocks in a portfolio, and not pile into bonds that are tied to the fate of a bond market where when rates rise, bond prices fall.
Anything else right with the market?
Yes. Earnings season started strong and consumer sentiment hit a 13-year high. Companies have started releasing their 3rd quarter earnings reports, and so far, 78% of them beat bottom-line expectations. Corporate earnings have been strong since 4Q16, and this quarter will likely continue that trend, although it may come in a little light due to all the natural disasters. And, the University of Michigan's consumer sentiment poll for September revealed that consumers held positive perspectives overall - across income, age, and political spectrums. Last month's reading reported the highest consumer sentiment since 2004.
One final note – don't get faked out by another 1000 point move in the Dow. That’s because, as the market rises, each 1,000-point advance becomes smaller in percentage terms. For example, the rally between 10,000 and 11,000 in 1999 was, of course, a 10% rise, while the climb from 20,000 to 21,000 for the Dow marked a 5% rise. It's still a good thing, but a 1,000 points is not what it used to be.
That said, next year we may have to get concerned about extended valuations if earnings don't keep up, the length of this bull market if the yield curve inverts, the bearish tendencies of midterm election years, and the ever present Geopolitical risk (N. Korea). Thus, there will still be a wall of worry for the market to climb ……..but this is a good thing. For now, at least, we can enjoy the fact that the "trend is your friend".
Ventas (VTR: $62.50, down 1%)
The company owns more than 1200 healthcare properties in the United States, Canada and the United Kingdom. They are paying a 5% dividend (just raised 6%) and the firm just keeps humming along.
The real estate investment trust, based in Chicago, said it had funds from operations of $373 million, or $1.04 per share, in the period. Funds from operations takes net income and adds back items such as depreciation and amortization. The company had net income of $615 million, or $1.71 per share, on revenue of $900 million in the period.
Ventas expects full-year funds from operations in the range of $4.13 to $4.16 per share.
“We delivered yet another strong quarter for our shareholders. With positive earnings and property growth, improved financial strength and recognition of over $500 million in gains from our ongoing divestiture of our skilled nursing assets, we are in an excellent position,” said Debra A. Cafaro, Ventas Chairman and Chief Executive Officer.
Note that Cafaro was recognized by the Harvard Business Review as one of “The Best-Performing CEOs in the World.” She is one of 23 CEOs named to the Harvard Business Review list for four consecutive years and one of only two women on this year’s list. Ventas’s financial performance ranked 32nd of 900 companies globally for Ms. Cafaro’s tenure, which exceeds 18 years.
During and immediately following the quarter, Ventas sold properties and received final repayments on loans receivable for proceeds of $630 million, with gains exceeding $500 million, consisting principally of the Company’s completed sales of 29 of its Kindred Healthcare skilled nursing facilities (“SNFs”) for proceeds of approximately $570 million. The Company continues to expect total aggregate proceeds of $700 million from sales of its 36 Kindred SNFs in 2017, representing a 7% yield on cash.
The Company has excellent liquidity with $2.9 billion of available borrowing capacity and over $100 million of cash on hand.
BMR Take: We have a Target of $72 so we have a ways to go, but we are happy collecting the dividend and looking for a move to the upper 60s when the world finally wakes up to what a great company this is. Our Sell Price is $58. If you are nervous about the stock market as a whole (and we are not) then moving assets from the Tech sector to Ventas would be a smart move. Big, solid, growth.
From: Trent Thompson [mailto:Trent@xxxxx.com]
Sent: Wednesday, October 25, 2017 2:23 PM
To: info@bullmarket.com
Subject: Options on Nutanix
Hi Mr. Shaver,
I have profited nicely from Nutanix. I have also done well on options strategies as recommended by Bull Market for both Twitter and Microsoft.
I am wondering if you can propose a simple bullish option strategy for Nutanix.
Thanks, Trent.
PS - I very much appreciate your newsletter especially the weekly and ad-hoc reports!
Trent Thompson wanted to see an options strategy for Nutanix (NTNX: $28, up 5%) in his letter above. Good idea, Trent.
So here it is:
Dear Trent:
[Note that this is a RISKY STRATEGY – check with your broker or advisor.]
I like to buy in-the-money LEAPS if I can and if they exist (some stocks don’t have LEAPS.) The reason is that you are not paying as much time premium for the LEAP. Time premium always goes away – it disappears over time and you can be left with losses.
I also like to sell calls against the long LEAP in order to get that time premium back. It’s like selling a covered call but using the LEAP instead of the stock.
The 2020 LEAPs exist, so that is good, but note that the spread is high (bid-ask) so that makes the numbers a little tougher. We are looking for the stock which is currently $28 to go to $40 or higher by January 2020, over two years from now. If this happens we have a home run.
You can buy the 20 LEAP for about $14. With the stock at $28 that means that $8 is the intrinsic part of the price of the option and $6 is the time premium. In order to get some of the time premium back you can sell some options against it. I like to go out 3-6 months to sell the calls and when they expire, just do it again. You can sell the January 30s for about $2 and if the stock stays below $30 they will expire worthless, lowering your price of the LEAP by that $2, to $12. (If it goes over $30, that’s a good thing and you can just buy back the 30 call and sell a 35 call or another option.) You could also sell the April 35 for $2 if you don’t want to get too close to stock price. Or you could sell the April 30 for $3. There are lots of choices!
If the stock is at $30 or below in January, you then sell the June 35s for another $2, lowering the cost basis to $10. Then in June if the stock is at $30 or $35, you sell the January 35 or 40 for another $3-4, lowering your cost basis to $6. NOW WE’RE TALKING! Now you have an option you paid $6 for that is worth $15 if the stock is at $35 and $20 if the stock is at $40.
Obviously this is a very movable strategy and you have to watch the stock and move in and out of the short calls. Plus it is very risky, as the stock could go below $20 and you would lose all of your money. Some of you don’t like to have to watch things so closely, in which case this is not for you. But if you pay attention you can get the cost basis close to zero and if the stock goes to $35 or $40 in two years your return can be very, very big. Did someone say infinity?
With that said, good luck to you, Trent! (And all of our readers.)
Todd Shaver, CEO
The Bull Market Report
I use this site for my pricing, but there are others.
https://finance.yahoo.com/quote/NTNX/options?p=NTNX&date=1579219200
Letter from a Subscriber about Cloudera (CLDR: $14.90, down 8%)
From: Robert Jolliffe [mailto:rjolly1@xxxxxx.com]
Sent: Thursday, October 26, 2017 1:41 PM
To: The Bull Market Report
Subject: Re: News Flash for October 26, 2017: Celgene Lowers 2020 Guidance – Stock Gets Killed
I feel your pain and feel the same with Cloudera. They beat as well and have been falling like a rock the last couple of weeks. I've looked everywhere and can't find anything negative about Cloudera. In fact they just picked up Hitachi as a customer*. WTF! I doubled down here and hope no bad news comes out in the near future.
Our Answer:
I can’t agree more, Robert. What can we do now when we like a company so much, but the market is not cooperating? We can have faith, buy more down here and hope there are no skeletons in the attic.
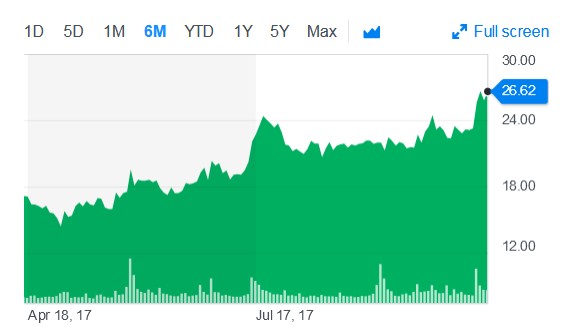
Look what Nutanix has done lately. And Shopify. And Square. Square has been AWESOME. (Nutanix too.)
Even little old Opko Health. Eventually good companies win out in the end ESPECIALLY when they have GOOD REVENUES. Last quarter saw revenues of $89 million up from $64 million in the year ago quarter, a 39% jump.
Todd Shaver, CEO
The Bull Market Report
* Earlier in the month, Cloudera announced a strategic partnership with Hitachi to offer customers advanced services, support, and training to strengthen adoption of Cloudera Enterprise, the leading machine learning and analytics platform. "Developments in Cloudera's sweet spots - such as machine learning and IoT - are already starting to transform businesses across Asia Pacific and Japan," said Mark Micallef, Vice President, Asia Pacific and Japan at Cloudera. "Partnering with Hitachi is a critical milestone in our journey to simplify the creation of IoT, machine learning, and analytic solutions. It offers a great deal of promise to global enterprises looking to use data to generate new business models and revenue sources, enrich the customer experience and innovate industries."
Some Research from the Street on Shopify (SHOP: $107, up 5%)
We uncovered a research report on Shopify from a big-name Wall Street firm. We found it timely in that the company has been under attack from a firm called Citron, run by Andrew Left. He has made a name for himself by shorting various stocks including Valeant Pharmaceuticals. That was his big winner, but he has had losers too. He shorted Nvidia at $108 in December and it is now at $195. And he has had others.
From the research report we gathered the following:
We expect Shopify to deliver strong 3Q results with revenue and operating income exceeding Barclays and consensus estimates when it reports earnings on October 31. Shares of SHOP have pulled back by 15% in the last month (vs. S&P 500 up 3%) after bearish reports on the company's customer acquisition strategies but are still trading up 130% YTD (S&P 500 up 8%) despite FY18 revenue estimates only increasing by 25% YTD. At 10x FY2 revenues, SHOP's valuation is still a significant premium to peers. We are bullish on SHOP's competitive position in the Small Business ecommerce platform space and the opportunity with Shopify Plus in mid-market category.
Key Metrics for 3Q17: In terms of key metrics, we are modeling total revenue of $166m (+67% y/y), in-line with consensus, near the high-end of company guidance. SHOP has exceeded the high-end of its revenue guidance by an average of 6% over the last five quarters.
FY17 Guidance: Despite the recent pullback, expectations are high for SHOP to raise its FY outlook on 3Q earnings. We forecast FY17 revenues of $650 million, near the high-end of SHOP's current guidance, but we think buy-side expectations are higher.
Subscription Services: We are modeling subscription revenue of $80m in 3Q, up +61% or 5-pt deceleration on 2-yr basis.
BMR Take: We’ve been saying the same thing for a long time. We sure hope the company doesn’t disappoint on Halloween when they report earnings. Because if they do, the stock is going to the 80s. If they produce, like they have been for the past few years, the stock will stay at its current level and may even shoot higher as Mr. Manic, Andrew Left, will have to BUY BACK HIS STOCK. We love short sellers!
But – note what we just said above. The stock could get sacked or it might shoot higher. This stock is not for the faint of heart. If you don’t like the story here then you have two days to sell. You can always get back in.
The Carlyle Group (CG: $22.40) was down 8% this week due to the changeover in leadership. We’re really not concerned and in fact think it was a good move as the founders have reached their late 60s (that’s really young if you know what I mean) and they have outlined the management progression plan that investors are always concerned with. Here’s the gist of the announcement this week:
The Carlyle Group Names New Executive Leadership Team
Glenn Youngkin and Kewsong Lee to Become Co-CEOs
Peter Clare to Become Co-CIO Alongside William Conway
Global alternative asset manager The Carlyle Group announced the following executive leadership changes, effective January 1, 2018: Kewsong Lee and Glenn A. Youngkin will become Co-Chief Executive Officers of The Carlyle Group. Peter J. Clare will become Co-Chief Investment Officer alongside current CIO William E. Conway, Jr.
Carlyle’s current Chairman Daniel A. D’Aniello will become Chairman Emeritus and continue to serve on the Carlyle Board and Executive Group
Current Co-CEOs David M. Rubenstein and William E. Conway, Jr. will become Co-Executive Chairmen of the Board and continue to serve on the Carlyle Executive Group
Glenn, Kewsong and Peter will join the Carlyle Board of Directors
Carlyle Co-Founders Conway, D’Aniello and Rubenstein said, “These promotions ensure continuity in our leadership and maintain the investment processes that have driven our success for 30 years. “As Founders, we are passionate about Carlyle. We will continue to be actively engaged at Carlyle. We are fully committed to and confident in the firm’s future and will continue to be substantial investors in Carlyle funds for years to come.”
BMR Take: This stock is vastly undervalued. We would back up the truck. The dividend is 5.3% and the Chairman of the Board, David Rubenstein, is not selling a share until it hits $30.
The Carlyle Group was founded in 1987 and is based in Washington, DC with additional offices in 33 countries across six continents (North America, South America, Asia, Australia, Europe, and Africa). Carlyle is a global alternative asset manager with $170 billion of assets under management across 300 investment vehicles
Our Price Target is $28 and our Sell Price is moved up from $13 to $20. It’s hard for us to like a stock more.
The High Yield Corner
By Michael Foster
It was a really busy week for The Bull Market Report's High Yield portfolio, with earnings releases and other news events causing a lot of excitement. But at the end of the week, the numbers actually didn’t move all that much.
Of course, there are exceptions. Digital Realty Trust, Inc. (DLR: $117, down 5.5%) saw a sharp decline over the week after reporting earnings that were far above expectations on both the top and bottom lines. The company saw 12% year-over-year revenue growth and FFO growth of 5%. At $1.51 per share, FFO is covering dividends at an even higher rate, which again indicates the need for aggressive dividend increases as we have mentioned over the last few weeks.
Dividend increases should be extremely easy to fund if the company meets its pretty modest guidance. Digital Realty is looking for full-year FFO at $6.00-$6.10, which is about a 3 cent increase from previous guidance. Revenue guidance also bumped up to $2.4-$2.5 billion for the full year.
So why did the stock get hammered so much?
The devil is always in the details, and this time is no different. Digital Realty announced a 4% decline in lease renewals as a result of a 11% decline in Turn-Key Flex renewals (see explanation below.) That was offset by increases for colocation and Powered Base Building products, which combined are slightly more in square feet than Turn-Key. But the massive size of Turn-Key as part of Digital Realty’s entire operations inspired a lot of panic.
So why were the renewals down? It has to do with falling prices. Keep in mind that the decline is in dollar terms, so what happened is a lot of companies renewed at lower prices, driving total revenue for the Turn-Key services lower.
So what exactly is this Turn-Key Flex? Simply put, it’s a 5-year old product that allows renters to design their own server space - meaning electrical, cooling, and other control systems are custom made before the customer moves in. This is different from colocation services, where you simply rent out offsite data facilities without bothering to design the space.
You might be able to see the problem. Turn-Key Flex is obviously a really big ticket item for really big spenders. It’s the kind of white glove service that companies paying 7 or 8 figures are going to demand. And these big customers, who are also dominating tech as the sector gets more consolidated (think Amazon destroying little competitors like Blue Apron), are demanding more discounts as they expand.
That means low sales growth or dollar sales declines, which is what we’ve seen for Digital Realty. But this is hardly a bad thing - it means big clients are spending more with Digital Realty and, as a result, are negotiating lower prices. It’s an understandable trend and actually a good one for Digital Realty.
Note that the company’s data center experts have designed, developed and currently manage over 3.6 million square feet of enterprise-quality data center space throughout the U.S., Europe and Asia Pacific, with over 500,000 square feet of additional, fully improved data center space under construction.
Digital Realty's customers include domestic and international companies across multiple industry verticals ranging from information technology and Internet enterprises, to manufacturing and financial services. Digital Realty's 157 properties comprise approximately 26 million square feet. Digital Realty's portfolio is located in 33 markets throughout Europe, North America, Singapore and Australia.
Elsewhere in earnings news, we saw Ventas (VTR: $63) fall slightly on the week thanks to a Friday recovery on earnings. Revenues rose 4% to beat expectations slightly, but $1.03 FFO was a slight 1 cent miss from expectations. That wasn’t really enough to hurt the stock by the end of the week, and definitely isn’t enough to adjust our expectations for this company.
Again, the details are key. Ventas announced it is expanding its university-based life science operations, meaning the firm is continuing to focus renting space for university research. This is incredibly good, because its mainstay in senior housing is not a growth industry. As paradoxically as it seems, the aging American demographic trend hasn’t actually been as good for senior housing as expected, partly because a lot of aging boomers don’t want to live in senior facilities. But much more importantly, there is a structural reason: seniors can’t afford massive rent raises, which limits organic growth for a senior housing provider.
Seeing this problem, Ventas has diversified into research facility rents, where growth is easy. Why? Because university tuitions keep going up and up, and universities have an incentive to spend as much as they can on research facilities without the market discipline of being cost conscious. In many cases, the signaling benefit of renting shiny new research facilities far outweighs expense concerns for universities struggling to compete in prestige, so that’s a nice profitable business to be in. And Ventas is getting more and more into it, which should result in better margins and a brighter future for Ventas shareholders.
While most of the High Yield portfolio was flat or down 1%, we did see municipal bond funds slide. This is not going to stop anytime soon. Nuveen AMT-Free Municipal Credit (NVG: $15.17, down 2%) and Invesco Municipal Trust (VKQ: $12.33, down 2%) are down largely as a result of selling in anticipation of end-of-year tax-loss harvesting and retail investors taking bets off bonds because of the December interest rate hike that seems a given by the market. While investors could sell these funds to save a possible 1-2% decline in the coming weeks, an even better long-term strategy would be to buy more and more of these funds over the next couple weeks as their yields get closer to 6%. Municipal bonds remain a great place for tax-free income, and the fears of muni regulations changing to remove that tax-advantaged status have dissipated entirely. Washington can’t touch munis. As a result, demand for munis is going to trickle in, especially from the start of 2018. Why not get ahead of that and buy now?
Good Investing,
Todd Shaver
CEO, Editor and Founder
The Bull Market Report
Since 1998
October 22, 2017
by Todd Shaver | Oct 22, 2017 | Weekly Newsletter 7pm Sunday
The Weekly Summary
Earnings-day blowups, leverage warnings in China, Apple’s worst rout since August. Oh, and a sixth straight week of gains for the S&P 500. No matter what happens lately, stocks just keep rising, with record closes piling up in U.S. markets at a rate that is starting to defy precedent. The Nasdaq 100 Index has finished at all-time highs 62 different times this year, on par with the most ever in 1999, while the S&P 500 and Dow Jones Industrial Average are closing in on historic levels, too. For bears, the elongating list of highs bespeaks euphoria, particularly when the market has been spared a 3% pullback for more than a year. Investors have ignored bad news ranging from North Korea to political drama at the White House to what may be the biggest profit slowdown in six years. It has been a great ride this year. We remind you, our dear reader, it certainly will not always be this good.
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks where we think you can still make good money, including: PayPal, Shopify, Celgene, WageWorks, Amazon, and Blackstone.
BMR Companies & Commentary
PayPal (PYPL: $71, up 3%)
PayPal delivered another great quarter for investors. The company not only showed no signs that its platform growth is slowing, it demonstrated that it is actually increasing its rate of growth as the network effects that management has repeatedly cited during the past couple of years continue in earnest. Yet many of its initiatives – the monetization of social peer-to-peer payment app Venmo, the expansion of instant-checkout feature One Touch, customer choice – are still in the very early innings of the game.
Toss in the $7.1 billion in cash that PayPal had on its balance sheet that could be used to fund M&A initiatives and the potential of the company’s worldwide network becomes daunting. We recall that PayPal acquired Braintree – the online and mobile payment platform that has fueled much of the company’s recent growth – in 2013 for just $800 million. And Braintree had spent just $26 million to purchase Venmo, which is a game-changing driver of revenue and earnings for PayPal.
BMR Take: PayPal has been the best way for equity investors to play the global growth of mobile payments. Again we see PayPal deliver an exceptional quarter backing up that point of view. We find nothing to critique about the firm. We raised our Target from $67 to $77 last week. We look forward to raising it again.

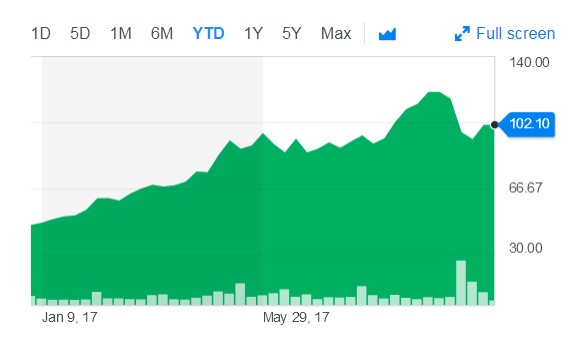
Now THERE’s a great chart. What’s next? 75? $80? $100. We think they are all possible.
Shopify (SHOP: $102, up 9%)
Remember that scary short seller, Andrew Left of Citron. Well the short call they were making on Shopify is turning out to be terribly wrong. Ouch! What good news for us and all the other shareholders behind the company.
Since 2014, Shopify, the leading multi-channel commerce platform, has been steadily building its presence in Waterloo, the cornerstone of Canada’s technology Corridor. Just recently, the company announced that it plans to grow its full-time, Waterloo-based workforce by 300-500 new jobs over the next couple of years. Growth continues!
These new positions in Waterloo will focus on growing Shopify Plus, which supports the largest and most complex customers on the Shopify platform. Roles in engineering, product, sales, and merchant services will range from entry-level to senior manager-level, and all will focus on developing innovative solutions capable of scaling for the changing retail landscape.
To accommodate this growth, Shopify also formally announced the opening of their second building in Waterloo. Steps from their current building, the new space will nearly double their physical footprint and further demonstrates Shopify’s dedication to building a strong and sustainable economy. The new space is expected to open in the first quarter of 2018.
BMR Take: It was admittedly a bit nerve-racking to see a short seller like Citron, who nailed Valeant, come out against one of our holdings. But we trust our research and our hard work. Shopify is a remarkable well-positioned technology company for the future of eCommerce.
Celgene (CELG: $121, down 11%)
Rough week for Celgene. Celgene announced the discontinuation of the Phase III REVOLVE trial in GED-0301 for Crohn’s disease (CD). This was unexpected and unfortunate news.
Celgene’s decision comes after recommendation by the independent data monitoring committee upon its review of
the overall benefit/risk during a recent interim futility analysis. The company points to no meaningful safety imbalances identified during this analysis, suggesting a lack of efficacy for the drug.
At this time, Celgene has chosen to not initiate the Phase III DEFINE trial in CD. The company is awaiting review of the full dataset from the Phase II trial of GED-0301 in ulcerative colitis to determine next steps in this situation.
In our opinion, this represents more of a psychological blow than a fundamental one to the company. Recall that Celgene paid $710 million upfront to Nogra Pharma Limited for the rights to this drug in 2014 and has since funded development of the asset.
BMR Take: Sometimes you just have to sift through the headlines to find the real facts. This one drug was only supposed to be a $1 billion revenue contributor. But the company is expected to still do more than $20 billion by 2020. So we see no reason to panic. We added the stock at $95 a little over a year ago so we have a nice 28% return and our Target is still a hefty $150. We continue to believe in Celgene. But if you are worried, then get out of the kitchen. There are lots of other choices for your money.

WageWorks (WAGE: $65, up 1%)
WageWorks a little over a year ago acquired Automatic Data Processing’s Consumer Health Spending Account (CHSA) and Consolidated Omnibus Reconciliation Act (COBRA) businesses. This transaction further strengthened WageWorks' leadership position in the Consumer-Directed Benefits market.
Why do we bring it up? Because WageWorks is eating ADP’s lunch and sometimes it’s good to reflect and remind ourselves why.
ADP’s CHSA and COBRA businesses provide a range of services including HSA, HRA, FSA, commuter benefits, and direct bill administration to approximately 10,000 employer clients in the United States.
Not long after this deal, WageWorks won a contract to service the entire federal government with consumer benefits programs, taking away the business from Automatic Data Processing.
BMR Take: WageWorks is serving a niche in the world of payments running consumer benefits programs for employers. It’s a tricky business. The global opportunity is huge and they are just getting started. We don’t hear a lot out of WageWorks week in and week out, but that doesn’t mean it's not exciting. Remember, the company just raised equity and we could see another acquisition occur in the near future.
Amazon (AMZN: $982, down 2%)
Amazon and Google (GOOG: $988) are at virtually the same price. Who will be first to $1100? Let the race begin. We think Amazon will win.
Why? Just look at the craze around the world competing for Amazon’s new headquarters. You can just see the excitement.
New York City mayor Bill de Blasio said that key landmarks around the city like the Empire State Building, billboards, and Wi-Fi charging stations are going to light up in Amazon’s signature orange color. The four bids that New York is pitching Amazon on - including areas upstate and in the city - just aren’t enough, so New York is also going for frills and extra decorations to pretty up its proposal.
Tucson certainly whipped out the big guns when its economic development group hauled a 21-foot saguaro cactus to Amazon’s main Seattle headquarters via a truck. The plan didn’t turn out the way that Tucson’s economic group had hoped: Amazon refused to accept the gift.
Kansas City mayor Sly James is not one to let the competition outdo him. He wrote 1,000 reviews about Amazon products, giving them all five stars. His reviews had slick one-liners like, “I live in beautiful Kansas City where the average home price is just $122K, so I know luxe living doesn’t have to cost a ton.“ Of course, in every review, he never failed to drop a mention of why Kansas City is great. Then, he posted a trendy “unboxing” video on social media to share his efforts. You gotta love this guy.
On Tuesday, Ottawans were told to cheer for Amazon during intermission for a hockey game between the Vancouver Canucks and the Ottawa Senators. A gauge showed up on screen, with Calgary at the bottom if the audience made the least noise and Ottawa on top. It being Canada, of course, the message to make noise was reiterated in French: “Faites du bruit!”
Pittsburgh has local restaurant Primanti Bros. offering free sandwiches to every Amazon employee who ends up working there. Each Pitts-Burger and Cheese sandwich goes for $7.39 normally, so if each of the 50,000 new employees got a sandwich, that would run for a total of $350,000, the Pittsburgh Post-Gazette hypothesizes.
Birmingham tried wooing Amazon online and in person. The city set up three giant Amazon boxes around town. It also set up giant replicas of Amazon’s Dash Buttons that send pregenerated flirty tweets to the company, according to AP, like “Amazon, we got a 100% match on Bumble. Wanna go on a date?” Another tweet reads, "We are Chipotle and these other cities are Taco Bell.”
Honestly, it’s hard to top this next one: This small, recently formed town, located close to Atlanta, offered to rename itself Amazon, Georgia. Stonecrest’s proposal also includes 345 acres of land if Amazon selects it as the HQ destination.
BMR Take: Amazon is the world’s greatest innovation machine. We think the new headquarters is going to spur even more great things and send the stock much higher.
The Blackstone Group (BX: $34, up 5%)
The U.S. real estate market may have slowed down, but Blackstone Group President Tony James still sees plenty of opportunities for profit. “Real estate is a gargantuan market. There are always undermanaged assets,” he said.
Blackstone has been investing heavily in logistics real estate, hoping to capitalize in the rise of online retail, and more acquisitions are possible.
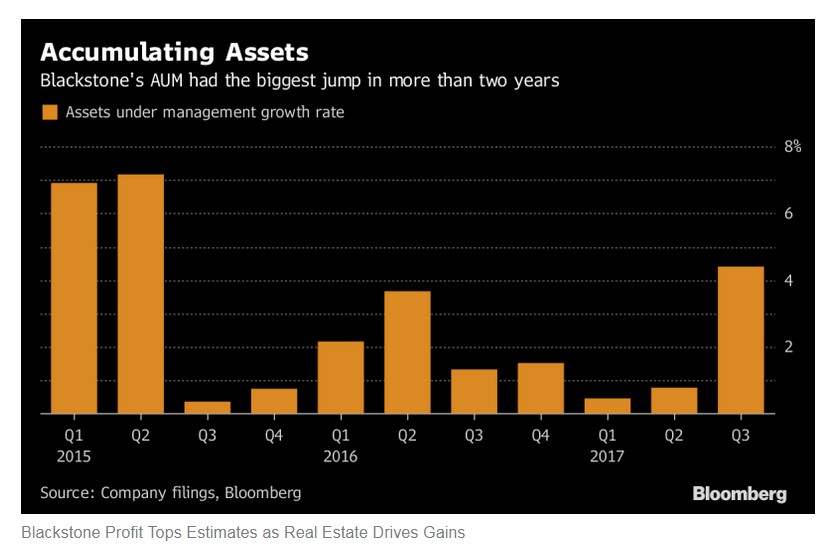
Blackstone’s real estate assets under management grew to $110 billion in the second quarter, up 9% from $102 billion a year ago. Its core-plus portfolio, which includes Stuyvesant Town-Peter Cooper Village, grew 36% to $18 billion.
In May, Blackstone won a $20 billion commitment from Saudi Arabia’s sovereign wealth fund for a new infrastructure investment fund, but it may be a while before the money gets spent. Saudi Arabia’s commitment depends on Blackstone raising additional cash from other investors, and the firm has only just began marketing the fund.
Real estate continues to fuel gains for Blackstone, which reported a jump in third-quarter profit that exceeded all analysts’ estimates. Economic net income, a measure of earnings that reflects both realized and unrealized investment gains, was $835 million, or 69 cents a share, compared with $690 million a year earlier.
Real estate led the charge for Blackstone’s asset sales in the quarter. The unit, sold $3.1 billion in holdings, including a U.K. office property and a portfolio of French hotels. The firm also continued trimming its stake in Hilton, selling shares it held in both its real estate and private equity funds.
Asset sales helped fuel $625 million of distributable earnings, which reflect profits on those disposals and fund management fees, compared with $590 million a year earlier. The metric is on track for its second-best year ever, President Tony James said on a call with media Thursday. Blackstone plans to draw from that pool to pay stockholders a dividend of 44 cents a share on Nov. 6.
BMR Take: We are really excited about Blackstone, especially real estate. Real estate is a “hard asset” meaning the value is more stable than for instance technology or biotech companies where the value is based on expectations of future growth. This real estate angle to Blackstone should give you less downside risk in a tough market.
Our Target is $36 and we fully expect to see this shortly. We can’t wait to raise the Target to the all-time high set in 2015 at $44. This $42 billion market cap company ought to be in the mid-40s for sure.
Upcoming Economic News
New Home Sales
Wednesday, October 25th, 10:00 AM
Period: September
Consensus: 552,500
Prior: 560,000
Initial Claims
Thursday, October 26th, 8:30 AM
Period: 10/21
Consensus: 231,500
Prior: 222,000
GDP
Friday, October 27th, 8:30 AM
Period: Q3
Consensus: 2.2%
Prior: 2.2%
The Word on the Street about Apple
Street Consensus Ratings for Apple (AAPL: $156, flat)
Ratings Breakdown: 7 Hold, 41 Buy Ratings
Consensus Price Target: $193
Wall Street Targets:
10/16/2017 KeyCorp $187
10/16/2017 Pacific Crest $187
10/15/2017 Rosenblatt Securities $150
10/13/2017 Barclays $161
10/11/2017 Piper Jaffray $196
10/11/2017 Morgan Stanley $199
10/10/2017 Royal Bank Of Canada $180
10/9/2017 Drexel Hamilton $208
Microsoft (MSFT: $79, up 2%) Sets New All-Time High
My Oh My. What shall we do? What shall we do with this stock at its all-time high of $79? Sell, Hold, Buy more?
BMR Take: WE SAY THE LATTER. Why would you sell one of the greatest companies in the history of the world? Yes, revenues are slowing, but profits are increasing and the profitability of software is second to none. For the year ended June 30th the company did $90 billion in revenue and had $21 billion in net income AFTER TAX. That’s 23% after tax. Wow. So for every $1 of software they sell, 23 cents goes to the bottom line, and much of that is in cash. The company has over $130 billion in cash, albeit over $80 billion in debt, much of it taken out at historically low interest rates. With a $607 billion market cap there are only two stocks higher. – Google at $690 billion and Apple at $810 billion.
We hereby raise our Target from $78 to $84. Go M S F T!
The Word on the Street about AstraZeneca
Street Consensus Ratings for AstraZeneca (AZN: $35, flat)
Ratings Breakdown: 2 Sell Ratings, 9 Hold Ratings, 14 Buy Ratings
Consensus Price Target: $37
Wall Street Targets:
10/17/2017 Cowen $37
09/6/2017 BMO Capital Markets $38
09/1/2017 Argus $35
BMR Take: We added the stock just below $30 last year. We are being very patient with this one. We have a 17% gain in over a year and the 2.6% dividend helps, but we would like to see this thing take off to our Target of $42. It’s no small company at a $85 billion market cap. Revenues are solid at $23 billion and profitability is strong at $5 billion but we want to see more in 2018. If you have patience, you will win.
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
We are getting ready to get down to the nitty-gritty of tax-reform. Listening to all the political pundits (which is extremely hard to stomach), it appears that the odds are now slightly favoring the failure of tax reform happening this year. Admittedly, we are talking about a government which is trillions of dollars in debt already, but that number seems to be "just a number". How do we actually comprehend a trillion dollars? One market guru described it as follows:
"Numbers, like billions and trillions tend to numb the mind. They are too large to grasp in any “real” sense. Thirty years ago an older member of the NYSE gave me a graphic and memorable example. “Young man,” he said, “would you like a million dollars?” “I sure would, sir!”, I replied anxiously. “Then just put aside $500 every week for the next 40 years.” I have never forgotten that a million dollars is enough to pay you $500 per week for 40 years (and that’s without benefit of interest). To get a billion dollars you would have to set aside $500,000 dollars per week for 40 years. And a trillion that would require $500 million every week for 40 years. Even with these examples, the enormity is difficult to grasp."
Despite our debt, the market wants and believes that a smaller government (lower taxes) will result in a higher GDP which in turn means higher tax revenues. Thus, the argument that the government has to "pay" for any tax cuts - by raising taxes on the left hand if lowering them on the right hand so as to keep the "debt" constant - is tantamount to keeping the status quo and, ultimately, the same drag on business that we have today. It is apparent that the $5 trillion gain in the overall stock market since the election is because of both increased earnings and the perception that those earnings will continue to grow in part due to lower taxes which drop directly to the bottom line of businesses. Our view is that it will be difficult for the market to act as if tax reform failure is a non-event. It's a major event that could make US companies more competitive in world markets and super-charge domestic small business like nothing has for the past 20 or 30 years.
Business and the markets both need an overhaul of a tax system that is so out-of-control that, as a generality, if one hundred experts file the same tax return, there will be ninety-nine different results. That said, tax reform failure by itself should not derail the current bull market - rather it will likely result in a "reset", or as the pundits like to say, a "consolidation of gains" before the next move higher. Until we see a recession or a bad policy move that, for example, results in an inverted yield curve, we expect that the market will continue to grind higher based on the quality and stability of earnings growth.
The High Yield Corner
By Michael Foster
Let’s start with the elephant in the room.
Government Properties Income Trust (GOV: $18.22, down -2%*) fell just 1% on Friday after receiving an unfavorable mention on Jim Cramer’s Mad Money. This move surprised us for two reasons. Firstly, we didn’t think anyone still watched Cramer’s show, and, secondly, we didn’t think anyone actually listened to him for investing advice. Apparently this failed hedge funder still has a following, though, and the selloff is a result of that.
* The company paid a 43 cent dividend on Friday and a stock that goes x-dividend always opens up down the amount of the dividend on that day, so in reality, the stock was down just a touch last week.
And what exactly is Cramer’s thesis? To be honest, we’re not sure. We’ve seen the clips and read a couple of takes, but the dismissal seems to be without any substance beyond “it’s a high dividend stock and it’s not for me.” No close look at FFO, dividend coverage, or revenue growth.
So, we will give you that here.
Let’s start with revenues. Government Properties Trust saw a 9% year-over-year increase last quarter, an acceleration from a decline at the start of 2016. Revenue growth acceleration has been occurring for nearly two years now, fueled in part by acquisitions and the company’s diversification away from government offices and towards office space leased to think tanks, public companies, private contractors, and so on. That investment has cost money, which means FFO has been weaker than it was back in 2014-2015, which also means dividend coverage is below 100% (it’s actually about 76% over the last 12 months).
Investors should in theory be rewarded for that lower dividend coverage with a higher yield, and at 9% that is exactly what they are getting. But really what we need to think about is the REIT’s ability to generate cash from operations to fuel the distribution in a sustainable manner.
If its expansion efforts bear fruit, this is exactly what we should see. But keep in mind that a bet on Government Properties is a bet on its future growth potential - and with revenue growth still accelerating, it remains a REIT growth stock. The second we see that sales growth weaken is the second we reconsider the stock. No matter what the bald guy on CNBC says.
Elsewhere in REIT land, things were extremely quiet. Omega Healthcare Investors, Inc (OHI: $32, up 1.5%) saw slight gains, whereas we saw a little dip in Ventas (VTR: $63, flat). Welltower (HCN: $68) ended the week flat, as did Apollo Commercial Real Estate (ARI: $18.44). One other REIT had a very fine showing, which is little surprise to us, since it’s been doing a lot of that lately.
Namely, Digital Realty Trust (DLR: $124, up 1%) had another strong week that pushed its dividend yield even lower, and we’ve finally hit the 3% mark yet again. Last week we discussed the significance of this barrier, and it’s not too surprising that it was hit. That should also make investors pause and consider why exactly they’re in the stock. At a 3% dividend or less, it’s more than generous to call Digital Realty a high yield stock. Yet it is unquestionably a high growth stock. Revenue growth, at 10% last quarter, fell from the 20%+ growth of 2016, but considering just how tough it was to compare revenues to 2016’s figures, that slowdown was more than expected. And at near 10% sales growth, the company is still growing like a weed. That has helped FFO growth accelerate markedly, which should indicate more aggressive dividend increases are on their way.
That leads us to the question: what to do with this stock. If you aren’t in need of a high yield, Digital Realty is a great place to be, because you’re essentially Google and Amazon’s landlord for their most precious assets: their data and global presence. But if your goal is to target a 7% income stream or higher, you could easily make do with removing allocations to Digital Realty with a nice profit and move into other higher yielding stocks in our two high-dividend-paying stocks. That’s especially true now that we’ve seen Digital’s stock soar 83% in 3 years. Yes, more upside is on the way, but maybe not as quickly and as profoundly as we’ve seen so far this year and in recent history.
Now let’s move on to the other, somewhat smaller elephant in the room: PIMCO Dynamic Income Fund (PDI: $30, down 4%), which wasn’t the worst performing Pimco fund of the week, although it was pretty close. Across the board, the market punished Pimco’s funds after the company announced that net investment income for most of its funds was far from covering distributions. This wasn’t a surprise, but the market has mostly ignored this issue until just now. Both the Dynamic fund and other Pimco funds have seen dividend coverage slip to less than 100%, although Dynamic’s coverage is not the worst of the lot. Still, the market is worried that the fund won’t be able to cover its payouts.
This is an overly simplistic view. Dynamic’s NAV has gone up 12% in 2017 - more than many bond funds and even some other Pimco funds. Since closed-end funds can fund distributions from Net Investment Income (NII), this just means Dynamic’s payouts can come from capital gains instead of NII. There are some tax issues here, but in terms of dividend sustainability, Dynamic’s distributions are fine.
But there is one implication many aren’t talking about, and we have addressed it earlier this year: the specials. Dynamic is famous for paying a huge special dividend at the end of the year, which has historically come from massive NII. Now that NII is weak, Pimco has a great excuse to tell investors, “Worry, income was weak, so no big special dividend this year.” We are not sure this will happen, but we’re leaning more to this being likely than we were earlier this year. If you were depending on this fund’s special distribution like the big one we saw last year, be prepared for disappointment. Also be prepared for that to hit the stock at the end of the year.
Is this a bad thing? Not really. The regular dividends are still safe, and the fund’s yield is a very nice 9%. And we could see NII improve significantly next year. There’s definitely more to come with Pimco funds in the coming months! But, if you don’t like drama, take your profits and squirrel them away in Annaly Mortgage (NLY – 10% div.) or any of the other stocks in our two high-yield portfolios and sleep like a baby.
Good Investing,
Todd Shaver, Founder and CEO
The Bull Market Report
Since 1998
October 16, 2017
by Todd Shaver | Oct 16, 2017 | Monthly Newsletter Daily 12pm if new
The Weekly Summary
Tulip Mania was a period in the Dutch Golden Age when the price of bulbs reach ridiculously high levels in a craze only to eventually have the price crash badly in 1637. While we are not seeing broad-based craze in today’s markets, we must be mindful that there are pockets of risk out there, and that while market prices today haven’t reached “ridiculously high levels” they have still come a long way, raising the bar for how much risk lingers around out there. For example, this week the mainstream news media extensively covered Wall Street’s junk market bond binge. Junk rated companies are raising debt at the fastest pace since 2012. Not just is the issuance up a lot, but the terms of the deals (i.e. the debt covenants) are getting looser and looser, and thus easier to borrow money. We only raise these points to say, please be mindful of the risks, but there remains plenty of opportunity for future profits!
No matter what is happening out there, there is always a bull market here at The Bull Market Report! This week we highlight some of our favorite stocks/funds where we think you can still make good money, including: Nutanix, Opko, Apple, Annaly and BlackRock.
BMR Companies & Commentary
Another week, another all-time record high. Does this scare you? Not us. Why should it scare you? The economy is strong. We have 325 million people who are trying to better themselves by starting companies, by investing in real estate, by buying equities and bonds. No one thing or no one event can bring down the entrepreneurial nature of this country. The market is climbing a wall of worry. Trump, North Korea, breaking the Iran deal, the Taliban, our war in Afghanistan (that Trump is escalating now – ouch), Trump – oh wait, we just said that above. Yes, climbing a wall of worry. But the stock market has been doing this for over 100 years. Seriously. Look what it has been through and look where it is now. Look where our economy is now. Amazing. So Dow 23,000 look out and who knows, maybe in a year or two we will be saying “Dow 30,000 look out.”
If you really are worried and/or if things do get worse, sell your growth stocks and buy some income producing stocks from our REIT portfolio or our High Yield portfolio. Annaly Capital Mortgage (NLY: $12.22, up 1%) has been paying over 10% for over 20 years. I am going to repeat this for you here: Annaly Capital Mortgage has been paying over 10% for over 20 years. Since 1997 they have operated through bull and bear markets in stocks and bonds and they have survived and thrived. You’re worried about the stock market? Buy some Annaly – it is non-correlated with the market.*
*It has a beta of 0.30. A beta of 1 means it follows the overall stock market equally – if the market is up 1%, Annaly is up 1%. But no, Annaly has a beta of 0.30% meaning little to no correlation. The beta of an investment indicates whether the investment is more or less volatile than the market as a whole. In general, a beta less than 1 indicates that the investment is less volatile than the market, while a beta more than 1 indicates that the investment is more volatile than the market Beta can be zero. Some zero-beta assets are risk-free, such as treasury bonds and cash.
You want diversification? There are many other stocks in those two portfolios that pay from 4% to 9% dividends. Buy a basket of them and sit back and sleep like a baby at night!
Nutanix (NTNX: $27, up 15%)
Goldman Sachs called Nutanix the investment opportunity of a decade. Why?
The demand pendulum appears to be swinging toward emerging, best-of-breed vendors with more modern approaches, and away from traditional, one-stop shop vendors that are often viewed to be out-of-step with the latest trends.
The proof is in the success or failure of new clients. Just this past quarter Nutanix had a strong quarter for large deals, including multiple deals in the high seven-figure range (several of these in the public sector). Nutanix is now working with a big chunk of the Fortune 500.
The big exciting part about Nutanix is that the company has doubled the number of clients in the past year. The typical client starts with a small contract, but then increases the amount of business they do, often 3x, 5x, or even 10x within a few years. So if Nutanix does nothing else but take care of the clients it already has, we should see strong growth in the years ahead.
BMR Take: We think Nutanix is a must-buy at current levels. Don't be worried about the current valuation. Let's look at why. This year the consensus is for EPS of $0.07, which is nothing much. However, the company is plowing money into sales and marketing to grow the business. Did you know they could save a few hundred million dollars tomorrow generating $1.50+ of EPS if they wanted to stop investing for growth? You see this analysis reveals the serious earnings power embedded in the business model, which is why we like the company so much.
Opko Health (OPK: $6.95, flat)
Opko is a diversified healthcare company that seeks to establish industry leading positions in large, rapidly growing markets. The diagnostics business includes BioReference Laboratories, the nation's third largest clinical laboratory with a core genetic testing business and a 400 person sales and marketing team to drive growth and leverage new products, including the 4Kscore® prostate cancer test and the Claros® 1 in-office immunoassay platform. The pharmaceutical business features Rayaldee, an FDA approved treatment for Secondary hyperparathyroidism in stage 3-4 chronic kidney disease (CKD) patients with vitamin D insufficiency.
Opko recently announced that it has entered into an exclusive agreement with Japan Tobacco (JT) for the development and commercialization in Japan of Rayaldee for the treatment of SHPT in dialysis patients with chronic kidney disease. This is great news for growth!
Under the terms of the agreement, JT will make an upfront payment to Opko of $6 million with another $6 million payment to be made upon initiation of Opko’s planned phase 2 study of Rayaldee in US dialysis patients. In addition, Opko will be eligible to receive up to an additional $31 million in development and regulatory milestones and $75 million in sales-based milestones. JT will also pay Opko tiered, double digit royalties on net product sales. Wow!
BMR Take: Consensus calls for about $1.2 billion of revenue for the company this year heading to $2 billion in a few years. We could be in for some major upside to estimates. Now wouldn’t that be nice, after being so patient with this little $3.9 billion company.
Apple (AAPL: $157, up 1%)
Apple could be disrupting more industries soon.
Barclays, the British bank, will need to defend its advantages in the payments business from encroachment by technology companies including Amazon and Apple, according to Barclay’s CEO Jes Staley.
There are some tectonic shifts going on, driven by tech and the geopolitical environment. The banks are very focused on the payments space and that may be where the battleground of finance is fought over the next 15 years. Could you imagine if Apple started taking share of the banking business from the world’s largest banks (like Barclays, JP Morgan, and Wells Fargo) as well as the world’s largest payments companies (like Visa and MasterCard). This would be another huge long-term growth driver.
BMR Take: Note that Apple has $260 billion in cash now, and with a market cap of $810 billion cash is 32% of the stock price. So more than $50 of the stock price is in cash. This is UNPRECEDENTED in the history of Wall Street. Apple remains an exciting investment opportunity. The services business is projected to double in revenue to $50 billion over the next several years. The Services business is much more profitable than hardware so the impact to earnings is even better. Don’t sell a share. We believe Apple has a lot more room to go on the upside.
BlackRock (BLK: $475, up 3%)
BlackRock, the world's largest money manager with $5.7 trillion in assets under management, reported better-than-expected earnings on Wednesday, which sent its stock to a record high.
And shares could go even higher, according to Credit Suisse (and us!) Following 3Q17 results, BlackRock remains the best-positioned traditional asset manager in the world with EPS growth expected to run 15-20% through 2019.
Most of the company's growth has come from its wildly successful exchange-traded fund business, known as iShares, which now accounts for half of all US investments in the products. There continues to be strong demand for iShares's ETFs driven by the evolution of the US retail channel (from commission-based to fee-based) and increased adoption by institutional clients and pricing reductions in its core series. Year to date, iShares accounted for about 50% of total ETF flows in the US.
Passive investments, like ETFs and other products that track a weighted index rather than a single equity, have steadily eaten away at active managers' portfolios in recent years.
BMR Take: BlackRock is among the best-positioned companies in investment management owning the top ETF franchise that is growing rapidly due to passive investing, as well as an increasing product portfolio of technology. Recall, there are several top hedge funds on the list of shareholders in BlackRock. With EPS set to approach $30 over the next 3 years, this stock pick is among our favorites.
Upcoming Economic News
Industrial Production
Tuesday, October 17, 2017 09:15 AM
Period: September
Consensus: 0.30%
Prior: -0.90%
Housing Starts
Wednesday, October 18th, 8:30 AM
Period: September
Consensus: 1,180,000
Prior: 1,180,000
Continuing Jobless Claims
Thursday, October 19th, 8:30 AM
Period: October
Consensus: 1,895,000
Prior: 1,889,000
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
The 4th quarter is off and running strongly, which is not uncommon. Even though it includes October (Octoberphobia), Q4 has historically been the strongest quarter of the year for the S&P 500. Since 1950, the S&P 500 has gained 4% on average in the fourth quarter, advancing 79% of the time. Oil dipped back under $50 per barrel and gold has fallen over 7% in just the last month because the US Dollar has strengthened due to the belief that the Fed will hike rates again in December. Maybe or maybe not. We still think tax reform is a bigger wild card than another Fed hike. The expectation of tax reform has resulted in just about everything with the exception of energy being up for the year, but even energy has some building tailwinds.
According to Boone Pickens Advisors, worldwide demand is soaring and set to hit 100 million barrels per day next year – a feat that was only expected around 2025 by most long-term forecasts including those from OPEC and Exxon. Growing energy demand is normally associated with growing economies, so this continues to be good news for future market gains based on earnings growth. The point being made is that if the market suffers a setback due to the failure of tax reform, it should not develop into a real bear market because of the support to be found in continued earnings growth. If Boone Pickens Advisors is right about soaring demand for energy, there is plenty of upside left in this bull.
General Electric (GE: $23, down 10% this week, and down from $32 in December - wow)
The drop in the stock in the last 10 months is almost 30%. With a market cap of $200 billion GE is not going away. But they are the Dog of the Dow. You know what the Dogs of the Dow are, right? They are the five worst performing stocks of the 30 Dow stocks. GE is gunning for THE DOG of the Dow this year. Many value money managers love this stuff. They buy the Dogs and historically, they have been big winners the following year and years.
We are thinking of adding GE to our Stocks For Success portfolio, not just because of the thinking in the above paragraph but for a host of other reasons. It has just had a shakeup in management, which will continue for the next few months. Old CEO out (Immelt), new CEO in (John Flannery). Lots of executives leaving or getting pushed out. Dividend is 4% which is pretty darn good for a Dow stock. 100+ year history of success as a global business leader. Lots going on with this huge company.
A note about the dividend. Some analysts think the dividend could get cut in order to conserve cash. This would be bad and good news. The stock would probably get nailed by another 10% down to $21 or even lower, but that would most likely mark the bottom. So if you are thinking of taking a position, keep this in mind. In other words, keep some cash around (keep your powder dry) in order to buy more at a lower price. If this dividend cut doesn’t happen, then buy some more as the stock moves up over the coming 24 months as it gets back into the $30s. The all-time high is about $58 back in 2000, right after the bubble started bursting in the dotcoms. It dropped to $24 in 2002 and then rallied to $41 in 2007. It got whacked to $12 in 2009 in the financial crisis and has moved straight up for eight years to $32 in 2016. We think there is a good possibility of seeing $30 and $40 in this great franchise as we move into the latter stages of the twenty teens.
Again, we are thinking of writing a research piece on GE soon. We believe it is a long term winner for the super conservative investor.
Update on Shopify
As you know, we love Shopify (SHOP: $94, down 4%) but along came Andrew Left and his firm Citron announcing that he was short the stock, that it was going way down, and that the company was fraudulent, among other silly claims. Many analysts jumped in this past week on the story. Here’s what one of them said:
"Citron’s Argument is Weak
"Let’s call a spade a spade - Shopify is selling a dream.
"So, is the Shopify stock news on-point? Is Shopify using illegal marketing tactics in selling that dream? That’s a gray area to be sure, but is the marketing message remarkably more misleading than the TV commercials inviting consumers to participate in class action lawsuits that mostly enrich attorneys, but rarely pan out as well as expected for the actual plaintiffs?
"Is a vision of a healthy cancer patient within a television commercial for a cancer drug some sort of unspoken guarantee of long-term survival? Does a young man that uses the Axe brand of personal-hygiene products actually expect to be besieged by young women, as depicted in Axe’s television commercials?
"The answer to all these questions is, of course, no. The FTC tolerates the imagery simply because it knows it has to give consumers at least a modicum of credit in distinguishing the difference between a contract and a commercial.
"And as for Shopify’s lack of profits, Shopify is in good company. Most young companies don’t turn a profit until after they’ve matured, but savvy investors know the time to get into some of them is before, not after, that fact. Look at Amazon, the most prominent of the rags-to-riches stories. It’s been one of the best long-term investments anyone could have made over the course of the past couple of decades. Investors don’t care where a company is, they care about where it’s going.
"Looking Ahead for SHOP Stock
"Don’t misread the message. The FTC might crack down on Shopify’s advertising. The company might never turn a profit. The market might not care if Shopify does eventually turn a profit. Nobody really knows the future. That’s the speculative nature of stock-picking.
"Andrew Left, however, seems to be grasping at straws with this one. Though he certainly rattled shareholders by generating some rather alarming Shopify stock news headlines, this time his claims are more bark than bite.
"If your gut is telling you this may be a time to scoop up shares at bargain prices, you may want to trust your gut."
BMR Take: Again, this was an opinion of a consensus of Wall Street analysts. But we certainly concur. We think this guy Left is out in left field. Here’s a chart of the last six months. You can see that the stock is where it was in August, just two short months ago. In April it was $71. We think there is tremendous value here with this company and believe Andrew Left will be left high and dry.
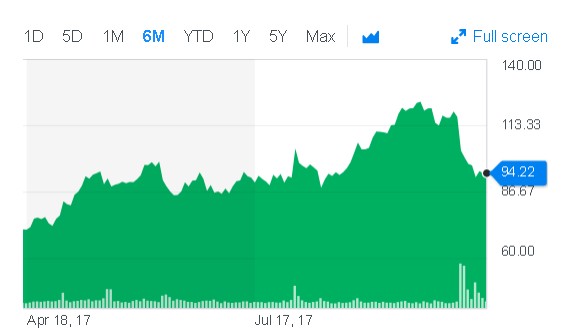
The High Yield Corner
By Michael Foster
Remember the slight volatility we recently saw in REITs? That’s gone. Instead, 4 of the 6 REITs in the High Yield portfolio were up this week, while two were flat. While not rising the most, Omega Healthcare Investors, Inc (OHI: $32, up 1%) is the most important and interesting story of the week. Extremely cautious, risk-averse investors dislike this stock because of its high yield (8%) and relative youth. Having been around since the late 1990s, it lacks the history of many dividend growth stocks. It also had a pretty disastrous collapse in its dividend back in 2000. However, that’s all long history by now. More recently, Omega Healthcare has devoted itself to a penny-per-quarter dividend hike that makes it a uniquely high yielding dividend growth stock. Some will warn that these dividend increases are unsustainable, and that may be true. But if the hikes last 10 years instead of 2 quarters and you avoid it because it won’t last forever, you’re giving up some extreme gains over a decade. This is how risk averse behavior cuts into returns.
The more aggressive investors who own Omega realize this, which is why they look at both the firm’s FFO and its dividend growth rate like a hawk. Last week, Omega yet again gave investors a penny-per-share raise. At the new payout, FFO covers the dividend pretty well - at a 125% rate. Bear in mind that that’s below the 130% threshold that we frequently write about here, which makes us cautious about the longevity of the rate hikes. We need to see FFO per share slow significantly before that dividend coverage ratio gets hurt and a cut becomes a mathematical necessity.
But how long could that take? Our best guess is that we have at least three years until a cut becomes necessary, but there are two factors that could grossly change that estimate. For one, shares outstanding growth. The more shares Omega releases, the more dividends it has to pay, which makes its FFO less powerful in covering payouts. Total shares outstanding have risen to 197 million from 196 million in the last year - a pretty small jump. But shares were just 68 million a decade ago, meaning an 11% annualized growth rate in total shares outstanding. That brings us to our second factor: FFO - funds from operations. During that same decade, FFO has risen 22% annualized over the same period. So you can see how Omega has been able to grow far beyond its obligations to shareholders and keep that growth rate going!
Can Omega continue? The real answer is no one knows, but there is reason to be concerned. The growth rate has slowed significantly in recent years, especially since Omega was smart to expand during the post-2009 years when all real estate was on sale. Deals are harder to find now, making growth a lot harder.
There’s another lever Omega can pull, though: Getting strong rent hikes. Keep in mind that Omega’s wheelhouse is a customer base that struggles with inflation, which makes rent hikes particularly challenging. For that reason, we think the long term trend of strong growth at Omega is definitely a thing of the past, and the penny-per-quarter hike cannot continue forever. But selling now and missing out on years of high yield dividend growth would be folly. Instead, we need to keep our positions and look closely at the numbers before jumping out. Now is not the time.
Our strongest REIT of the week is in many ways the exact opposite of Omega. Digital Realty Trust (DLR: $122, up 3%) saw a really strong week without too much relevant news. Last week the firm announced it would expand its Silicon Valley Connected Campus, with a new six-megawatt facility planned for 1Q18 delivery. This is a really small part of Digital Realty’s portfolio, comprising just a $75 million investment, so it isn’t enough to move the needle. Also, as counterintuitive as it sounds, Digital Realty’s strength isn’t in the Valley but in its distributed presence around the country. The company has many retail-facing clients, as well as the U.S. government, where the need is to have many hubs where human beings who use the Valley’s services are located.
Digital Realty is on track to grow that business, but the real story of last week’s price movement is more technical than fundamental. The stock has retreated from its 52-week high hit last month ($127), and after this week’s gains is approaching it yet again. The dividend yield is also nearing the sub-3% level, which it hit in September briefly before rising. We fear we may have a repeat of that in the short term - but that’s hardly a cause for concern. It simply means that Digital Realty is for the most part range bound right now, and we need to content ourselves with that while we wait for the company to aggressively ramp up its dividend. The last rate hike was in March, and another one by the end of the year would be nice. In reality, this company’s management has settled itself into a predictable pattern of one-per-year dividend hikes despite a rapid acceleration in FFO growth. FFO per share is now over double payouts - an absurd ratio to say the least! We would like to see Digital Realty aggressively ramp up its dividend hike schedule.
We doubt we’ll see it anytime soon, but we do think it’s an inevitability with this company. Simply put, it cannot stop making money, and its business is growing too rapidly for it to be at risk anytime soon. Eventually, Digital Realty will need to start increasing its dividend more frequently or doing much more aggressive dividend hikes. Either way, its 3% yield at current prices is destined to turn into more of a 5% yield in the next 3-5 years. For that reason, investors long the stock should stay tight even if you’ve been in it for the past year and are sitting on some attractive capital gains.

Good Investing,
Todd Shaver, CEO, Founder and Editor
The Bull Market Report
Since 1998
Now wouldn't you want to get this newsletter every week? You bet you would! Just click here or go to BullMarket.com/subscription. You'll be glad you did!