November 20, 2016
by Todd Shaver | Nov 20, 2016 | Weekly Newsletter 7pm Sunday
The Week Ahead
We finished this week above the fresh all-time highs set just a week ago. But we raise the question - have we come too far to fast? The frenzy seen post- election is seemingly pricing in a lot of good to come from new leadership in Washington. Are expectations reasonable or too aggressive? We note that Caterpillar recently said even if a $1 trillion infrastructure spending bill was passed today, it would take at least a year for projects to start, given the timelines for making the equipment needed. And we haven’t yet passed a $1 trillion infrastructure bill nor have we any clarity about how one would be funded. This infrastructure example highlights one market over-reaction to Trump, which is happening across many more sectors.
Good stock picks can make money in any market. This week we provide some insights on our latest thinking for Under Armour, Tesoro, Facebook, Amazon, and Microsoft.
Highlights From The Past Week
Repatriation. Many people are asking the question - If new leadership in Washington does lower repatriation taxes so that US companies bring home the $2+ trillion currently parked overseas, what will the money be used for?
The prevailing view at this time seems to be that much of the capital repatriated from overseas will be returned to shareholders, via repurchases and dividends. This is good for the stock market and for investors like us. However, we need to keep a close eye on how everything develops. Some are saying if the money just goes to buybacks and dividends rather than capital expenditures, then we won't see the big benefits to job growth and middle class income. There is talk of a flat 10% repatriation tax which should bring billions back to the US, but we’ll have to wait and see!
Fiscal Stimulus. Like Andrew Jackson’s populism, people are saying that we’re going to build an entirely new political movement: It’s everything related to jobs. They will be able to push a trillion-dollar infrastructure plan. With negative interest rates throughout the world, it’s the greatest opportunity to rebuild everything. Ship yards, iron works, new infrastructure projects get them all jacked up. We can just throw it up against the wall and see if it sticks. It will be as exciting as the 1930s, greater than the Reagan revolution. Exciting times! (We shall see.)
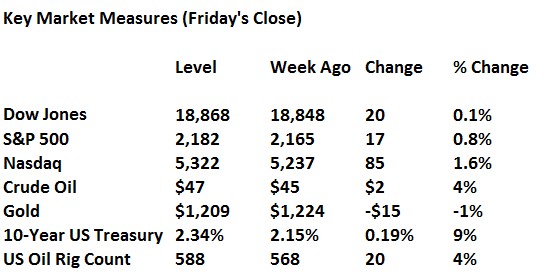
Interest Rates. The bond market bloodbath continues. The 10-year US Treasury yield is up a stunning 65 basis points from the Trump-win lows, spiking to 2.35% - the highest since December 2015. In fact, the entire Treasury yield curve is now higher in yield on the year, leaving most of everything newly issued in 2016 now under water. We are going to have to keep a close eye on where rates stand going forward. The cornerstone of fiscal stimulus will be low rates. But if the bond market re-prices rates much higher, the increased interest expense could throw a wrench in gears turning all of the current excitement.
BMR Companies and Commentary
Under Armour (UA: $31, down 3% for the week)
Sneaker outlet Foot Locker reported earnings. The CFO commented that inventory is fresh and well-positioned for the important holiday selling season, which keeps the company on track to achieve mid-single digit comparable-store sales gains and double-digit earnings growth.
So the shoe business is going well? Perhaps not so much for Under Armour. Foot Locker’s CEO raised concerns that the Curry 3.0 is not selling as well as anticipated. The CEO said the third iteration of the Curry basketball shoe is off to a slower start than the first two. Recall that Under Armour recently signed NBA All Star Stephen Curry of the Golden State Warriors to an endorsement contract. They took him on a marketing trip through China to stir up excitement, and expectations for what Curry and his dedicated shoe line-up could do for Under Armour’s brand and revenue have been set high.
Under Armour ended the week near a fresh 52-week low after the comments out of Footlocker hit the market.
BMR Take: We think all of the above is just market noise. The Under Armour brand is growing because Stephen Curry is now on the team. Whether his shoes sell a little more or less doesn’t really matter. Literally, the revenue doesn’t move the needle for the company, and it doesn’t change the fact that more and more big name athletes are increasingly likely to sign with Under Armour over Nike. We view weakness in the stock as a buying opportunity.
Tesoro (TSO: $83, down 3%)
Tesoro announced a $6.4 billion acquisition of Western Refining (WNR: $37, up 29%) It’s good news. The company expects 2018 EPS to go up 10-13% because of the deal.
Through the purchase, Tesoro adds two very respected refineries to the portfolio - El Paso, TX and St Paul, MN. This expands Tesoro’s footprint beyond the West Coast, which makes Tesoro’s portfolio even more attractive to a potentially larger buyer one day.
There are an estimated $350 to $425 million of cost synergies to be realized in the deal. This level represents about 33-45% of Western Refining’s normalized EBITDA. That is a big percentage! Typically, in M&A perhaps you see 10% synergies. The number is so big in this deal because of the nature of the refining business. It’s all about scale.
BMR Take: The Western Refining acquisition is yet another solid deal by Tesoro to build out the portfolio, which already ranked as the best asset on the West Coast. Net asset value post the deal is now expected to be around $140 versus the current stock price of $83. We, along with many people on Wall Street, see a lot of value management can create for shareholders by realizing net asset value. With this common knowledge on the Street why isn’t the stock trading at $125 or $140 now? You have to sell assets to unlock net asset value. Until then Wall Street will just give you credit for the cash flow you are generating from the assets. Phillips 66 (PSX: $84) trades at 120% of NAV because everybody thinks Warren Buffett is going to buy it. Right now Tesoro is a big lumbering asset that is just producing income. So the gap in valuation for Tesoro from the current price to NAV would close quickly if management were to sell off some assets, raising cash and reducing debt and readying itself for sale (to Warren Buffett.)
Facebook (FB: $117, -2%)
Again, Facebook has found more miscalculated advertising metrics. The company said it has uncovered several more miscalculated metrics related to how consumers interact with content from marketers and publishers, and it unveiled additional independent review of some measurements to calm unease over the their data. An internal metrics audit found that discrepancies led to the undercounting or overcounting of four measurements, including the weekly and monthly reach of marketers' posts, the number of full video views and time spent with publishers' Instant Articles.
Does it matter? Should we be worried? What is the impact?
None of the metrics in question impact Facebook's billing. The only financial impact would be from customer perception about what has occurred, leading to customers shying away from spending money to advertise with Facebook because they have new concerns over these metrics. It is a stretch to go there. Facebook has well over 1 billion users. Just because a few mistakes were made on some back-office tasks doesn’t change how the business model connects advertisers to world. (We are not discounting this issue, but we think the market will perceive it to be a small matter. The company is already working on the PR to reduce the impact on perception.)
Let’s stay focused on what matters. Recall, it was a stellar quarter just recently reported. Facebook's Q3 earnings update that came in better than expected on top line revenues of $7.0 billion versus the $6.92 billion consensus and EPS of $1.09 was ahead of the Street's $0.97 expectations. Daily active users of 1.18 billion and monthly active users of 1.8 billion were both ahead of the Street's expectations as well. Management offered updated guidance on expense growth of 40-45% that was lower than the prior 45-50%. The negative takeaways were comments about decelerating revenue growth and heavy investments in 4Q16 and 2017. Many people think this was just management setting the bar low so they can beat it more easily. We agree.
BMR Take: If the first time miscalculated metrics didn’t shatter the Facebook growth story, we don’t think the second time around will. Clearly an operational mistake we don’t like to see, but we don’t see reason to exit our position in the stock over it. We think the company is set up to deliver better than expected financial results over the next several quarters. Stick around!
And this just in: Facebook will repurchase up to $6 billion in stock (first time they have ever done a stock buyback.) The buyback will start in the first quarter of 2017, using some of their $26 billion in cash. The market liked the news: the stock was up over a $1 in after-hours trading Friday.
BTW, we just noticed that Facebook’s all-time high is the same as Apple’s - $134. We wonder who will get their first. Our guess? Facebook. Why? Smaller market cap - $340 billion vs. $590 billion. Higher growth rate. So now we have two races to watch. Google vs. Amazon is the other. They both closed at the same price Friday. Love it!
Amazon (AMZN: $760, up $21, +3%)
The word is CEO Jeff Bezos is telling executives to “Do what it takes to succeed” in India. Amazon fell a little behind in China early and business never quiet was able to recover to be as big as it could have been. Bezos is going on all in on India to ensure the same thing doesn’t happen twice.
Amazon had been India’s #2 ecommerce player. But that has changed. Bezos is now communicating to the market that Amazon has pulled ahead to be #1, with market share estimated around 28%.
India is a huge opportunity for Amazon. India has a population of 1.2 billion with about 40 million online shoppers. Goldman Sachs calls for ecommerce sales in India to grow 10-fold from today’s level of $11 billion over the next decade. And since only about one-third of Amazon’s sales are international, there is tremendous room for growth here. We understand that Bezos is going to invest another $3 billion in June into the India operation, in order to make the business even better. Amazon currently has over 80 million products selling in India. (This is not a misprint.) And they have more than 120,000 sellers, compared to 40,000 sellers a year ago. In June, the company said it will invest an additional $3 billion in India after it exhausted its earlier investment pledge of $2 billion. The company also launched its Prime membership program in July in more than 100 Indian cities, offering one-day and two-day delivery
BMR Take: Amazon’s stock has been down since the latest earnings report. The concern is that they are in a short term cycle of big investment spending. This news of more investments in India certainly plays right into the bearish outlook. Long-term, we think every dollar Bezos spends re-investing in the business will pay dividends later on. In the near-term, we brace for negative sentiment about how profits are being weighed down today due to these investments. Listen, we are not negative on the company nor the stock. We just want to give you both sides of the story. In fact, we think the market will shrug off this news and do what it always does, buy the story of bigger is better, awaiting huge profits in the future. But you never know…
Microsoft (MSFT: $60, +2%)
Goldman Sachs upgraded the stock to Buy with a $68 price target. What’s the story here? Why did they upgrade? What are they now saying? Why is Microsoft all the sudden a buy?
The company got off to a strong start to FY17 as revenue and EPS came in above consensus estimates. The strength was driven by growth of Azure (the cloud business) and adoption of Office 365 (the web version of Office).
Many are now expecting the upcoming quarter to be an inflection point for Microsoft, as the company will complete the sale of its phone business and the acquisition of LinkedIn, signifying the end of the old and the beginning of the new.
We believe the integration of LinkedIn will enhance the value proposition of Microsoft’s entire platform, including Azure, Office 365, and Dynamics. As such, we believe the best is yet to come as we expect revenue growth acceleration and margin expansion ahead.
BMR Take: Glad to see Goldman Sachs come around to support our outlook. What a humbling game investing is. The world’s most powerful investment bank is playing catch up to a little tiny newsletter service out of Aspen, Colorado.
Goldman Sachs (GS: $210, up 5%)
Another strong week for Goldman as the stock reached its highest level of 2015 and well as this year. It was only higher in 2007, hitting $248. Keep a tight stop in case the market starts to sell off, to protect your gains. But there’s a good chance we might see new all-time highs in Goldman in 2017.
Upcoming Economic News
Tuesday, November 22nd
Existing Home Sales – October
Time: 10:00 am
Forecast: 5.46 million
Existing home sales are projected to be little changed in October with tight inventories constraining transactions. Sales fell 0.4% year-over-year last quarter for the first decline of the past two years. Sharply rising Treasury bond rates will feed through into higher mortgage rates, adding another impediment to existing home sales growth.
Wednesday, November 23rd
Durable Goods Orders – October
Time: 8:30 am
Forecast: 1.0% overall, 0.2% ex transportation
Rising aircraft orders in October following two straight deep monthly declines can lead a strong overall gain in durable goods orders. Industrial demand has shown some recent promise; core capital goods orders increased 5.2% annualized in the third quarter against the previous quarter. Yet that recent burst in activity is tempered by the weak long-term trend; such orders fell 4.1% year-over-year during the same period.
New Home Sales – October
Time: 10:00 am
Forecast: 585,000
New home sales can dip a bit in October yet still point to strong long-term growth. Third quarter sales rose 23% year-over-year, as volumes continued to trend higher from depressed post-crisis levels. Though up substantially on an annual basis, last quarter’s 600,000 unit annualized pace trails the average rate of the past 20 years by 18%.
University of Michigan Consumer Sentiment – November
Time: 10:00 am
Forecast: 91.6
The post-election bounce in the stock market may ultimately feed into somewhat higher readings in consumer sentiment. The preliminary reading in the November Michigan survey was the highest in five months as consumers are reporting improved financial conditions. Renewed declines in oil prices can also spur stronger inclinations to increase spending on other items.
FOMC Meeting Minutes
Time: 2:00 pm
Given the jolt to interest rates and inflation expectations following the election, the minutes of the early November FOMC meeting will be somewhat stale. Yet the general push toward hiking the Fed Funds target in December will likely find additional support in the minutes. The next key question for monetary policy is how much policy tightening is likely in the year ahead. Economic projections released by the Federal Reserve next month will provide crucial guidance on this subject.
Twilio (TWLO: $37) had a good week, rising 17%. We’ve said many times how much we like this one, but the market has been hammering the stock these past few weeks. The turnaround in a week when most Tech stocks were hit hard, is impressive. Again, we think this is a $75 stock if they continue their phenomenal revenue gains that we saw in the past few years, and certainly last quarter. Twilio did $167 million in sales last year, up from $90 million the year before and the company is on a $1 billion annual run rate by the second half of 2018. Can’t wait for next quarter’s earnings. If strong, the stock should get back to the 50s and 60s in no time.
Two Questions from The Bull Market Report:
Last week, we asked you if a high stock price intimidates you. And we asked which stock, Google or Amazon that are both trading at virtually the same price, will win the ultimate race. Here is a letter from John Herlihy, one of our subscribers.
Hi Todd, To answer your first question, Yes, I do feel intimidated by the high price of those two stocks, although I am not sure "intimidated" is the right word. Logic demands some common sense, so that if a person's stock purchase gains by 2%, it doesn't matter whether you have 500 shares of an expensive stock or 5,000 shares of a less expensive stock, if the amount spent is the same. I play around with about $100,000. At $750 a share, that's about 135 shares. Doesn't sound like much. A $25 stock would be 4,000 shares. Just sounds better even if the profit would be the same on a percentage gain.
To answer your second question: I would go for Google. Amazon seems to be more at the risk of the market place and the consumer spender, while Google just seems to be a powerhouse, not necessarily at the whim of the consumer.
As always, I value (and treasure) The Bull Market Report and its stock advice. I couldn't do without it.
John Herlihy
University Professor
Qatar University
Doha, Qatar
And this was our response:
Hi John –
Just what we thought about a high-priced stock. It’s that good old human nature thing. And of course this is the reason that most companies split their stock. Of course, Google and Amazon don’t give a damn. Apple finally succumbed with the 7-1 split in 2014. (I wonder if they will ever succumb on giving back some of their cash!)
Hard to say who will win – tough to count out Bezos though, as his Cloud operation is exploding.
Thanks and good investing.
Todd Shaver, Editor in Chief
The Bull Market Report
A Powerful Financial Newsletter
@BullMarketRept on Twitter
A Word from Gary Jefferson
Jefferson Financial Group
First Vice-President, Investments
UBS Financial Services, Inc.
Yogi Berra proved once again last week why he's the greatest philosopher of the modern era with his Yogism "It ain't over 'til it's over." Instead of the Trump crash predicted by 99% of all the financial pundits, the market took off for its best week in over five years.
The Financial Times published an article last week laying out the seven key ways that Donald Trump is set to change America, and in doing so, change the investment landscape and financial markets:
1.Trade - Where Trump may tear up trade agreements and start a trade war by raising tariffs on China to 45%. We didn't come to the same conclusion as this fairly radical interpretation, but rather that he wants a level playing field for US companies. Remember, Trump's expertise is in making deals, not breaking them, and we believe the end result will be good for American business.
2. Foreign policy - Likely to change under Trump, such as abandonment of the deal with Iran and closer ties with Russia.
3. Healthcare - Likely to drastically change (for the better), as Trump has said he will get rid of Obamacare. We think this is a BIG deal for healthcare, big pharma and especially biotech companies, all of which should have a real tailwind next year from the expected changes. [Trump is already tempering his position, so stay tuned.]
4. Tax reform will be another huge area where Trump wants radical reform, promising that companies will not pay more than 15% tax and individuals less than now. This should be big for equities and not so good for bonds. In fact, bonds are already getting hit hard. The total global value of bonds declined by over $1 trillion these past eight days as U.S. President-elect Donald Trump’s policies are seen boosting spending and quickening inflation, according to Bloomberg. Bank of America Merrill Lynch data indicates that the $1 trillion-plus weekly plunge has only happened twice in two decades. Where is all that bond money going? The total global value of equities increased by $1.3 trillion during that same period.
5. The Supreme Court - Trump is likely to be able to easily replace one or two judges with his conservative picks.
6. Climate change policy - Trump has called climate change a “hoax” and says he wants to cancel the Paris accord and cut funding to UN climate initiatives.
7. Immigration - Trump wants to dramatically tighten immigration policy.
All of these policies tell us several things: overweight equities versus bonds; buy American companies with a higher degree of sales and production inside the US; be sure to include biotechs, pharma and healthcare in portfolios. If earnings growth next year is in the 12-14% range, we should have a very good equity market over the next 12 months. And, if the 10-year Treasury rate rises to 3%-3 ½% as some predict, bonds should struggle as will interest rate sensitive equities like utilities.
The Energy Corner
North Dakota’s crude-oil production in September dropped to the lowest level in more than two years. Crude production fell 1.1% on the month to 970,000 barrels a day in September, the lowest level since February 2014. North Dakota is home to the Bakken Shale formation, one of the world’s highest-cost oil fields. Growing confidence that crude prices will rise in coming months is sustaining the expansion of oil drilling in the shale patch. Rigs targeting crude rose 19 to 470 this week, the biggest increase in the last 16 months, according to Baker Hughes data reported Friday. Shale drillers have now added 155 rigs since an expansion started at the end of May. Gas rugs were flat, bringing the total for oil and gas up by 20 to 588.
This news just in - the Obama administration on Friday banned offshore drilling in the Arctic, setting a likely collision course with President-elect Donald Trump, who has vowed to “unleash” new energy production in the United States by rolling back restrictions on oil. Great – a new story for us to worry about.
So, US rig count is up sharply, which should produce greater volumes as we move into 2017. This counteracts the move by OPEC to cut production, which hasn’t been approved yet, and may indeed never happen
Interest Rate Corner
Federal Reserve Chairwoman Janet Yellen reiterated that an increase in short-term interest rates "could well become appropriate relatively soon" but offered no new signals about what the central bank will do at its meeting next month.
We are in the camp at The Bull Market Report that a ¼ point rise is baked in for December. Of course, she could surprise us with a ½ point rise, which would probably tank the markets like what happened last December. We hope she maintains some sense here. The 10-year Treasury note has exploded, from a low of 1.37% in July to 1.80% before the election to 2.34% Friday.
Tesla Update: It’s official: Tesla (TSLA: $188, down 2%) shareholders approved the acquisition of SolarCity. The company is now an unequivocal sun-to-vehicle energy firm. And Chief Executive Officer Elon Musk didn’t take long to make his first big announcement as head of this new enterprise. Minutes after shareholders approved the deal - about 85 %of them voted yes - Musk told the crowd that he had just returned from a meeting with his new solar engineering team. Tesla’s new solar roof product, he proclaimed, will actually cost less to manufacture and install than a traditional roof - even before savings from the power bill. “Electricity,” Musk said, “is just a bonus.”
If Musk’s claims prove true, this could be a real turning point in the evolution of solar power. The newly announced rooftop shingles are made of textured glass and are virtually indistinguishable from high-end roofing products. They also transform light into power for your home and your electric car.
“So the basic proposition will be: Would you like a roof that looks better than a normal roof, lasts twice as long, costs less and - by the way - generates electricity?” Musk said. “Why would you get anything else?” On a large house over a long period of time, the value of that electricity could exceed $100,000. The new roofing material he unveiled this past week is considerably cheaper, and it's considerably more promising for the future of rooftop solar power.
We love Musk. He never ceases to amaze and shock. Can he pull this off? Will he have enough cash to make it work? We think yes. But again, this stock could hit $150 before it hits $250. Volatile!
Goldman Sachs Maps Out Its Top Market Themes for 2017
They're heavily influenced by President-elect Trump.
Goldman Predicts: U.S. recession risk remains low in 2017
Goldman released its top 10 market themes for next year. "High growth, higher risk, slightly higher returns," is how their strategists view the year ahead - and it's clear that their outlook has been heavily influenced by the pending regime change in Washington.
Here's a brief summary some of the themes Goldman sees as forming the backdrop for investing in 2017. All thoughts and comments are for Goldman.
Expected returns: Only slightly higher
Relative to its 2016 forecasts, Goldman says owners of financial assets can reasonably able to expect more upside - but stresses that these returns will still likely remain low. The best improvement in the opportunity in global equities is in Asia ex-Japan, where we forecast returns of 12.5% (versus 3.8% for 2016.) At the other end of the equity spectrum, in Japan we are forecasting declines of 3.7% on the Topix (vs. +5.2% for 2016).
U.S. fiscal policy: A pro-growth agenda
President-elect Donald Trump's focus on infrastructure spending during his victory speech on Nov. 9 - rather than trade protectionism or immigration restrictions - catalyzed the risk-on sentiment that's pervaded markets.
Markets are starved for growth
This is plainly visible in the eagerness with which markets seized on Trump’s growth-focused message. It is also visible in the speed with which the market’s narrative on the economic outlook under Trump has shifted from uncertainty to growth. Fiscal stimulus in the U.S. will help reflate the economy, and stands a good chance of passing through Congress.
U.S. trade policy: Concerns are likely overdone
Goldman doesn't see an imminent trade war on the horizon, and expects any re-negotiation of agreements currently in place (like NAFTA) to focus on attempts to improve the prospects for the U.S. manufacturing sector. We think the popular media narrative on the downside risk of a trade war is overstated. Our tentative view is that Trump’s use of punitive tariffs will be just as pragmatic as President Obama’s, albeit more vocal.
Emerging markets risk: “Trump tantrum” is temporary
Emerging market assets have been crushed since the election, as the rise in Treasury yields has reduced the need to reach for yield overseas, and the potential for protectionist trade policies threatens to curtail growth opportunities.
Monetary policy: Focusing the toolkit on credit creation
Better-targeted monetary stimulus could help avoid some negative side effects associated with quantitative easing and negative rates that inhibit credit creation.
Corporate revenue growth recession: Signs of inflection
For years, S&P 500 companies have exceeded analysts' expectations on the bottom line more often than the top line during quarterly earnings seasons, as a combination of cost-cutting and shrinking share count, rather than soaring sales, fueled the growth in earnings per share. However, Goldman expects 2017 to confirm that the U.S. corporate sector has emerged from its recent 'revenue recession.' A firming global economy and recovery in oil prices from their February lows significantly buoys the outlook for revenue growth stateside.
For 2017, Goldman expects that modest improvements in the macroeconomic backdrop will help lift S&P 500 operating EPS by 10% and they have a year-end S&P 500 target of 2200, currently 2180 now. [Not terribly exciting if you ask us. We differ. We don’t normally predict, but we would certainly be looking for 2300 or 2400.]
Inflation: Moving higher across developed markets
Market-based measures of inflation expectations in the U.S. have spiked since the election, as traders bet that Donald Trump will be the inflation president.
What seems clear to us, as argued above, is that economic issues, notably tax cuts, infrastructure spending and defense spending, are high on the agenda - a recipe for reflation. We are forecasting large boosts to public spending in Japan, China, the U.S., and Europe, which should fuel inflationary pressures in those economies.
The next credit cycle: Kinder and gentler
While commodity-sensitive segments of the credit market have suffered pain in 2016, there hasn't been much in the way of contagion. Goldman's team expects more of the same in 2017, with the credit cycle not making a turn for the worse. The strong ‘business cycle’ component in the behavior of high yield defaults, and our view that U.S. recession risk remains low in 2017, leave us comfortable with the view that the inflection point is unlikely to materialize next year, despite the weak state of corporate balance sheets.
Mortgage Rates Surge After Election
Here is some news on the state of the mortgage market. Mortgage rates surged after the election win of Donald Trump. But housing experts say consumers shouldn't get carried away by the post-election wave. The advance of the past week or so, stoked by a surprise victory that turned economic expectations on their head, could soon settle.
"Consumers considering buying or refinancing now should stay patient, as we'll likely see rates stabilize once markets find a new equilibrium," says Zillow, the mortgage rate real estate company.
In the week ended Thursday, the average rate on the 30-year fixed-rate loan jumped to 3.94% from 3.57% the previous week, mortgage company Freddie Mac reported. A year ago the market was at 3.97%. The average for a 15-year mortgage climbed to 3.14% from 2.88%
The High Yield Corner
We have seen our first full post-Trump trading week, and it wasn’t bad. Actually, things were impressive considering the expectations and last week’s bull run. The S&P 500 rose nearly 1% by the end of the week, but the really interesting story is the difference between different stock groups. Large caps underperformed small caps significantly - this has a lot of important implications for high-yield investors, so is worth a closer look.
The Dow Jones Industrial was pretty much flat last week, while the Russell 2000 went up 2.6%. The difference between these two is the result of different trends between different investors: the risk-averse are more worried than the less risk-averse, who are willing to give small caps a chance in the hopes that they will deliver the higher-than-big-cap returns that they gave in the past. This has pushed small caps up to a 17% year-to-date return after rising 8% in the last month.
But here’s the really interesting part: the Dow Jones is up 10% year-to-date after a 4% return over the last month. The S&P, however, is up 7% year-to-date after rising 2% in the last month.
What this means is that risk appetites have grown in the last month while the more cautious are less eager to jump into the Trump rally. They aren’t avoiding it, but they aren’t going into it as much as the more risk-tolerant investors. In other words, we’re having a growing disagreement about future risks with the economy as a whole.
This is not uncommon, but wasn’t the case earlier in 2016. Both large caps and small caps had similar high returns for much of 2016 - and now that convergence is subsiding.
This is important for high yield investors for two reasons. First, junk bonds and BDCs tend to trade closely with small cap stocks as they attract similar investors: risk-tolerant institutions. Second, a market where the risk-averse are more cautious and the risk-hungry are less so often portends a bubble followed by a crash. That is not in the cards quite yet, but it does make one wonder if the industries getting a big boost - Financials in particular - might get overbought if they haven’t already.
With this as our backdrop, let’s take a look at how each asset class performed in the last week and why:
REITs - Initially REITs were the hardest hit by Trump’s victory on fears that his spending plans would kickstart inflation and thus increase REITs’ borrowing costs. This remains a concern, as the U.S. Treasury 10-year keeps going higher, but we’ve finally gotten to a point where the risks are priced in. Fortunately for REITs they already began correcting before the election, so this week’s return was just barely green, according to the SPDR Dow Jones REIT ETF (RWR: $89. Flat).
Results for individual REITs varied, but our picks did OK. Kimco Realty (KIM: $26) rose slightly, Digital Realty Trust (DLR: $89) rose over 1%, Omega Healthcare Investors (OHI: $28) was flat, Care Capital Properties (CCP: $24) rose 4%, and Government Properties Income Trust (GOV: $18.70) rose less than 1%. We also added a new REIT to our portfolio: Ventas (VTR: $60), which rose 2% this week. Ventas is one of the few REITs that is up year-to-date in the Healthcare space: rising 6% so far this year, but its price-to-FFO ratio and growth potential make it extremely attractive.
Junk bonds - The corporate bond market is now dominated with changing inflation expectations. Love him or hate him, but the market believes Trump is going to cause inflation to accelerate. This isn’t a testament to his failures or abilities, however; much of these expectations are the end result of the Fed’s constant efforts to improve inflation rates and a time when low oil prices and high supplies are priced in. There are many reasons beyond Trump to think inflation will not stay low forever, and having a president in the office (whoever it may be) who is focused on rising inflation with a House and Senate that will work with him, almost seems a perfect formula for rising inflation.
That is why junk bonds have done particularly badly after Trump, but the real surprising thing is that they didn’t do poorly for longer. Last week the SPDR Barclays High Yield Bond ETF (JNK: $36) rose over 1% and is now up 5% from the beginning of the year. Yet the fund has a near 7% dividend yield that is far higher than it has been in recent years. This is partly because of expectations of a rate cut for the fund*, which has happened in the past, so it’s important to keep in mind the more actively managed alternatives that aren’t tied to an index** and thus have more flexibility to ensure payouts remain constant. Note that the ETF recently registered $342 million asset inflows for a 3.15% increase.
*JNK's distribution cut is expected because the BofA High Yield index has fallen. Since JNK tracks that, its distribution should fall too.
**Active funds like PDI vs. passive indexing funds like JNK. In other words, “alternative funds that are actively managed" makes that clearer.
Our pick to take advantage of this strategy remains Pimco’s Dynamic Income Fund (PDI: $27), which had a nice 4% gain this week to offset last week’s massive decline. The fund is still down over 4% from a month ago which means it is poised to improve in recent weeks. The fund is also now flat year-to-date with a near 10% dividend and a looming special dividend that we believe will be at least 3%. That turns this fund into a 13% dividend payer with a sustainable dividend. That is almost impossible to find in the market (we know as we’ve looked for more, but Pimco’s fund seems to be it!)
Municipal bonds - Rising interest rates are a problem for all bonds, but they are actually worse for corporate bonds than municipal bonds because of the risks and the way these are structured. Yet looking at the municipal bond world lately, you’d think it’s the riskiest asset in the world. The iShares National Municipal Bond ETF (MUB: $108) fell 1% this week and is down 3% over the last month. The ETF is also down 2% for the year, making municipal bonds one of the few asset classes that has had negative returns for the year.
We have been wary of municipal bonds this year because of their massive run-up before the summer and rate hike concerns. We don’t believe rate hikes directly are a drain on municipal bonds, but fears about rate hikes often overshoot the real risks and cause a big and prolonged selloff. We saw this in 2015 and have seen this to a lesser extent this year. This is why we have only recommended one municipal bond fund this year: the Nuveen Enhanced AMT-Free Municipal Credit Opportunities Fund (NVG: $14:04). The fund is down 2% over the last week and is down 3% year-to-date. The most shocking figure is the three-months metric: the fund is down 14% in that time.
We expect these massive declines to reverse, but it is going to take a while for that to happen and it is difficult to time. While municipal bonds are already oversold, that does not mean the market knows they are oversold, and they can go down even lower. Nuveen’s fund is a good long-term hold and we expect it to hold its NAV for the long term, as it has done for over a decade already. However, we also expect greater volatility to hit this and all municipal funds. Anyone wishing to invest in munis now will have to endure these short-term price declines with patience, buying more as the stock goes down.
From one extreme of the risk/reward spectrum to the other, let’s turn to BDCs. The UBS BDC ETF (BDCS: $22) rose over 1% over the last week and has had a somewhat strong showing after the Trump election. While BDCs aren’t going up nearly as much as Financials, they are both rising for the same reason: an expectation that deregulation is going to cause credit to flow and the Financial sector to boom. BDCs cannot help but benefit from this, so they are rising with the Financial sector. However, they are not rising from an extreme bottom as Financials are, so the asset class’s 2% monthly return is a fraction of the double-digit returns of the Financial sector as a whole. This is unlikely to change.
At the same time, we have finally gotten to a point where Main Street Capital (MAIN: $36.50) has gotten overbought. The BDC is now up 16% from when we recommended it in April after rising 8% in the past month alone. We waited for this week’s dividend distribution to see if the stock would fall further after the payout, but it hasn’t; in fact the stock is up over 1% after its recent payout. That now means Main Street is selling at a 70% premium to its net asset value and it has passed our target price. We are keeping our price targets on Main Street, which means recommending selling at these levels and waiting for the price to correct before jumping back in. Main Street remains an excellent firm with impressive advisors and the capability to increase dividends for a long time, but the cost of that expertise and growth potential is too high now. We will buy again when the stock is more fairly priced.
That’s all for this week.
Good Investing,
Todd Shaver, Founder and Editor in Chief
The Bull Market Report
October 30, 2016
by Todd Shaver | Oct 30, 2016 | Weekly Newsletter 7pm Sunday
The Week Ahead
What a wild end to the week. In the last several hours of trading the probability of a Fed rate hike in December dropped from 75% to 70% as the US election noise started getting louder and louder. There is heightened uncertainty right now. In addition, late Friday FBI Director James Comey informed top members of Congress in a letter that the bureau had “learned of the existence of emails that appear to be pertinent to the investigation.” And the market sagged. After being up 100 points by mid-day it promptly dropped 150 points, before closing flat for the day.
Fortunately, US GDP roared back 2.9% in 3Q16. Moreover, we observed many companies deliver respectable 3Q16 earnings results. We continue to see equity to be much more attractive than bonds or cash. This week we highlight Qualcomm, Bristol-Myers Squibb, Under Armour, Visa, Alphabet, and Equity Residential.
Highlights From The Past Week
Global private equity leader switches gears. KKR ranks among the list of the best investment shops in the world. Earlier in the year they backed up the truck and bought distressed energy and commodity bonds during February lows and on Brexit concerns. They now say those distressed investments they made are paying off handsomely, in fact much faster than anticipated. Accordingly, they now see more balanced risk/reward and are exiting those trades.
Recession risk is rising. While many US labor market indicators look rosy, one is flashing lights of caution. We are referring to the Fed Labor Market Conditions Index, in particular the year over year growth rate trend. After falling just three times from 2012 to 2015, the index has fallen every month of 2016 except for one. And in July the annual change from July 2015 turned negative. That's only the eighth time in nearly 40 years the index was down on a year-over-year basis. This event occurred in 2002 and 2007 prior to the proceeding recessions. Again we can’t help but wonder - is this cycle coming to an end?
Mergers set a monthly record as election eve looms. We observed $245 billion of M&A this month, surpassing the prior record of $240 billion in July 2015, with last week’s $177 billion of volume the all-time high weekly record. We have recently seen a wave of major deals getting pushed through by Wall Street. Bankers are clearly not sitting on their hands and taking advantage of what might be the last window of opportunity, in terms of both market conditions and considering the election, they have to rake in big time fees. We’ve seen announcements of AT&T buying Time Warner, Qualcomm buying NXP, the FedEx/UPS of China go public, and now the long awaited IPO of Snapchat finally coming. Snapchat is expected to raise as much as $4 billion in its planned IPO at a valuation of $40 billion, making it the biggest social media company to go public since Twitter's IPO in 2013. These sorts of deals are clear signs of aggressive market behavior. The question is if and how long it can last?
BMR Companies and Commentary
Qualcomm (QCOM: $68, up 1% for the week – all prices are for the week)
Well, the rumor turned out to be true. Qualcomm announced it is buying NXP Semiconductors (NXPI: $100, down 2%) for $110 per share. The offer is all cash, which will be funded using offshore monies and newly issued debt of $11 billion. Putting the two companies together, annual revenues will be over $35 billion. The deal is expected to close by the end of 2017 subject to regulatory approvals. Consensus expectations call for the deal to lift Qualcomm’s existing EPS outlook by 20-30%.
The deal is a good one for Qualcomm on many levels. Qualcomm has been focused on expanding its business beyond mobile into a number of growing businesses. NXP has a strong automotive presence, which boosts Qualcomm's presence in a market that management has frequently said they want to target. The deal also comes with $500 million of expected cost synergies. Lastly, there will be ample free cash flow to maintain the dividend and grow it, all while de-leveraging.
The consensus 2018 EPS outlook now calls for EPS of $5.00. At $70, shares are now at a fair to lofty level of 12x an EPS figure that is far away. Recall, this stock’s PE can quickly flip to 10x as seen in the past. We think the risk/reward here is now balanced.
BMR Take: The most important question is, what do we do now? We continue to like the business, and the acquisition is a good strategic fit, but the stock is fairly valued, so we are exiting our position.
We added the stock to our portfolio at $43 in February and are exiting at $68.40 for a 59% gain. Now, what should YOU do with your stock? That’s up to you, of course. We like Qualcomm and believe in them long term so you may wish to stay in a little longer. The NXP deal is not done yet so there is some uncertainty here of course. If you think they are going higher, you can put a stop in place and if it hits a certain price below the current price then your order will get executed. This is a good way to ride a stock upwards, protecting your profits all the way up.
Bristol Myers Squibb (BMY: $51, up 2%)
It was a really strong quarter. The stock traded up as much as 8% on Thursday on the earnings release. We think this is the turnaround now starting. We are excited to see the shares regain confidence and momentum and start to make a run at the 52-week high of $77.
The immuno-oncology franchise has recently stumbled, but the core business is healthy and there remains prospects for a turnaround in immuno-oncology. Management says they are working through recent disappointing results from Opdivo and will still build a valuable immuno-oncology franchise. Moreover, just to provide some re-assurance, a new operating model was announced along with 3Q16 earnings that commits to roughly flat operating expenses through 2020.
If that wasn’t enough, in conjunction with earnings, the company announced a new $3.0 billion share repurchase authorization, that is incremental to the existing authorization with $1 billion remaining. This new buyback cushions the 2017 EPS outlook providing for $3.00 of EPS.
One of the reasons we really like the stock is the solid balance sheet and the downside protection it provides us. The company ended the quarter with $8.4 billion of cash with debt of $6.8 billion.
BMR Take: We believe now is an opportune time to be accumulating a position in this blue chip Healthcare stock. The nearly 3% dividend yield is a cushion while you wait for a turnaround.
Under Armour (UA: $31, down 18%).
We wanted to follow up on Under Armour considering the shock this quarter and our continued strong interest in the name. We believe buying the pullback presents a very attractive risk/reward proposition.
While management lowered their 2018 operating income targets, the fundamentals have just not changed. The company still has a roadmap to $7.5 billion of revenue in 2018 and to ultimately be a $10 billion revenue business, as compared to $4.9 billion of sales expected this year. That is explosive growth. Under Armour is one of the Top 3 fastest revenue growers out of all of the S&P 500. All that is happening at the moment is that management is taking down near-term profits a bit by increasing marketing expenses in order to ensure sales growth continues for a long time.
We expect Under Armour to continue to beat revenue guidance based on ongoing investments in faster growth segments like footwear and international, and aggressive demand due to its major marketing pushes with endorsements in golf and basketball.
Even with ramped up expenses, the outlook still calls for greater 20% EPS growth per year. The future is bright!
BMR Take: We think the pullback is an opportunity to accumulate shares. Under Armour is the new Nike. There are years ahead of good performance you don’t want to miss out on. The all-time high is $50, which is an attainable mark to beat as the revenue base is on track to double from here in the next 3-4 years.
Visa (V: $82, flat)
It was a solid earnings quarter for Visa. The stock traded down 0.4% following the Q416 earnings release this week, which included better than expected bottom line results of $0.79 on revenue of $4.3 billion that was modestly above consensus expectations. The issue was soft 2017 guidance, where management forecast annual revenue growth of 17% and EPS growth in the mid-teens as compared to consensus of 20%, and 19.5% respectively.
While the forward outlook was disappointing, we were pleased to see decently strong revenue this quarter. The drivers were healthy, in fact accelerating cross-border volume, US credit growth acceleration, new wins like USAA and Costco, and moderating headwinds from foreign currency and the oil patch. We are optimistic these factors can continue to drive further revenue upside. Our outlook is shared by Goldman Sachs, as they are calling for the 2017 revenue outlook provided by management to be very beatable.
BMR Take: Solid results. As expected. No big surprises. Just what we love about Visa. Steady. Stable. Consistent. We raise our price target from $85 to $95.
Equity Residential (EQR: $60, down 1%)
The company reported 3Q16 FFO (an EPS proxy of cash flow for real estate companies) of $0.78, which was in line with the consensus expectation, though down from $0.89 a year ago. Overall, this quarter’s result was okay.
However, the forward outlook was worse than expected. Organic income growth guidance was reduced again, to 3.95% from 4.00% prior on higher operating expense growth. Higher expenses were driven by a combination of real estate taxes, tenant incentives, and personnel costs as apartment deliveries have created a competitive environment.
With income growing by just 2.4% during 3Q16 versus a high of nearly 7.0% during 2015, we see 2017 (and possibly 2018) as being a very challenged in terms of upside to growth trends. Of course, the outlook is mixed. The top net operating income growth markets include Seattle and Southern California, up 6.4% and 6.0% respectively. Though there are lagging markets like New York, Washington DC, and Boston, which experienced -4.0%, 0.7%, and 1.5% growth respectively from a year ago this quarter. San Francisco and New York continued to be highly pressured markets due to new construction and decelerating job growth.
Also, the company is working on seven new apartment communities under construction, which are about 70% completed and 70% leased and will come online by 2018 to help cushion net operating income growth. But putting it all together, we see Equity Residential struggling to grow much from here over the next two years.
BMR Take: We like Equity Residential as a leader in the apartment real estate business, but are starting to view shares as fairly valued. You just received a special dividend of $3.50 on October 14th, which followed the $8.00 special dividend paid out in March 2016. This should have helped cushion your performance. While the current valuation is a 21% discount to net asset value, most don’t expect the valuation gap to close. We’d be inclined to remove this stock here, but in reality we’re doing ok here. We added the stock at $62 in June and have received $4 in dividends so our net cost is $58. But if it goes to $55, our Sell Price, we are indeed going to remove it.
Alphabet (GOOG: $795, down 1%)
Revenue of $22.5 billion beat the consensus of $22.0 billion and was up from $18.8 billion last year. EPS of $9.06 beat the consensus of $8.62 and was up from $7.35 last year. Great results! Alphabet is now the second most valuable company in all of the S&P 500 with a market cap of $550 billion, trailing only Apple at $613 billion.
What did we like about the quarter? First, websites revenue was up 23% driven by mobile search, YouTube, and programmatic advertising. Many once called for Google’s demise due to the smartphone, but mobile search was the largest contributor to growth as it benefited from increased engagement and a number of new search ad formats.
Second, we liked the fact that paid clicks accelerated to 33% growth, which was much faster than 29% seen last quarter, as strong YouTube engagement was a huge contributor. Recall that we believe Google has the best asset in all of media by way of YouTube.
Third, YouTube growth remains elevated, as it now reaches nearly half of US adults between 18-54 at least once per month. Our key point here is that while growth is good, they still only have half of the target market on board, so there is clear runway ahead for more and more improvement.
BMR Take: Very solid results. We are raising our price target from $850 to $900. This stock remains an excellent core holding.
Upcoming Economic News
Monday, October 31st
Personal Income & Spending – September
Time: 8:30 am
Forecast: 0.4% income, 0.4% spending
Personal spending looks to expand strongly in September after showing no change in August. Yet the long-term trend for consumer spending appears less hearty, with retail sales excluding autos and fuel rising a subdued 3.7% year-over-year in the third quarter. Income trends are restraining consumer outlays, as disposable income rose 3.4% year-over-year in the three months ending August - the slowest pace in over two years.
Tuesday, November 1st
ISM Manufacturing Index – October
Time: 10:00 am
Forecast: 51.5
The ISM Manufacturing Index is projected to continue showing positive but not overly strong levels in October. Manufacturing output rose in three of the past four months, yet was unchanged year-over year in September.
Vehicle Sales – October
Forecast: 17.3 million
Vehicle sales are forecast to fall back in October after spiking by 5% in September. Heavy incentives are needed to keep auto sales afloat after an extended boom period has faded out. The 1.2% yearly decline of vehicle sales last quarter is one of the poorest results in the past seven years.
FOMC Rate Decision
Time: 2:00 pm
Forecast: 0.25%-0.5% fed funds target range
The coming election and the lack of a post-meeting press conference rule out any probability of a November rate hike, despite policymaker protests to the contrary. Solid job figures in line with September’s results will allow for the first and only fed funds increase of this year in December. But consistently meek price growth trends may long delay further tightening to well after that point.
Friday, November 4th
Trade Balance – September
Time: 8:30 am
Forecast: -$41.8 billion
Rising commodity costs will widen the trade deficit in September. Moody’s Industrial Metals Price Index rose 11% year-over-year last month, the largest such gain in two years. This will ultimately raise the cost of imports to the US.
A Few Words from Gary Jefferson
First Vice-President, Investments
Jefferson Financial Group
UBS Financial Services
The third quarter earnings season is now in full swing and actual results so far have been solid. In fact, S&P 500 companies are beating consensus expectations by the largest amount in over four years. With results from 28% of the S&P 500 market cap reported we can say goodbye to the earnings recession. The numbers should continue to rise modestly as the remaining 72% of the market reports results. This gives us greater confidence that our estimate for 3% year-over-year growth for the quarter is on track.
Keep in mind that this is the first quarter of positive EPS growth in over a year. We expect EPS growth will continue to accelerate into 2017 as the drag from the Energy sector turns into a tailwind as comparisons get easier. We forecast 8% EPS growth for full year 2017.
Financials have been a key positive driver. An improvement in trading and investment banking revenues for the big banks has been a key positive driver so far this quarter, reversing very weak trends earlier in the year. While these businesses can be hard to predict, the initial read on fourth quarter trends is favorable. In fact, Q4 estimates for the sector have actually moved higher during earnings season. With global economic growth intact, inflation firming and the Fed likely to resume raising the fed funds rate (we expect a rate hike in December and two more in 2017) fundamentals look poised to continue to improve. As a result (and in conjunction with low valuations), we upgraded Financials from neutral to moderate overweight this month.
Growth segments of IT* remain strong. Results from Microsoft confirmed earlier results from Accenture, Adobe and Red Hat that Tech companies that are on the right side of the secular trends (cloud transition) are doing fine. On the other hand, legacy IT products and services remain challenging, as confirmed by IBM.
*Information Technology
Oil and gas weighing on industrials. Numerous industrial companies (including GE) have suggested that weakness in oil and gas spending has continued. While trends in spending will likely improve into next year, the recovery looks like it will be slow and shallow. As a result, EPS growth will likely lag the overall market.
We have long argued the market is more about earnings than anything else. However, it has been flat for a very long time and it seems apparent that the market is waiting for something to happen. The election being settled is an obvious and temporary concern. No one can predict how any election will affect the economy, but we believe it's safe to say that no President can single-handedly drive up nor destroy the markets. No matter which way it goes on the 8th, our market is part of a global marketplace where hundreds of inter-connected factors beyond just our President will determine what the future holds – and, again, we believe earnings are one of the most important.
We also suspect that once the election is over, the markets will seriously begin to wonder about how the economy will look with higher rates and a stronger dollar in place. An interest rate hike could, as it did last December, cause much greater volatility than what the election may bring.
Bottom line: Tune out the noise from the media. Scary headlines touting doom and gloom are more often than not unnerving to even the most even-keeled investor. The markets may experience some turbulence in the coming months. But, these short-term fluctuations shouldn't affect long-term portfolio performance. It's a cliché, but yes, volatility (a/k/a bad down days) often presents sound investment opportunities.
If we continue to have the expected earnings numbers come in, coupled with "no recession" on the horizon, the market has a real opportunity to break out to new highs by year-end. The only caveat to this scenario is a rate hike – it could cause a disruption. But, relying on a track record going back decades, keep in mind that stocks historically do just fine during the first two to three years of a new rising-rate cycle.
An upgrade: Kinder Morgan (KMI: $20, down 3%) was upgraded by Raymond James Financial from an "outperform" rating to a "strong-buy" rating. They now have a $27 price target on the stock, up from its previous target of $23. Kinder Morgan was also upgraded by BMO Capital Markets from a "market perform" rating to an "outperform" rating. They raised their target to $26 from $21.
Twilio (TWLO: $35, down 14%) Twilio is obviously not for the faint of heart. We like it immensely and think it is a double or triple from here, but it is very tough watching it go down each week. There is something going on and we’re not sure what it is, but we believe a year from now it will be a lot higher.
With that said, it is painful and you may not wish to stay along for the currently painful ride. And of course, the stock may go lower. Many days the stock will jump 5% in the morning and then fade during the day, so you know there are serious buyers out there. We all know that it is a recent IPO with a high PE. We know that it is volatile, but seeing it drop from the $60 level to almost half of that is disheartening. So if you can’t stand the heat, get out of the kitchen now. We think it will take until the next earnings release for investors to see that the company is still on track for big revenue and earnings gains ahead.
This is what we say in our research report that is on the website – the stock is in our Special Opportunities portfolio:
“Twilio has 30,000 customers – from small developers to large enterprises – who use Twilio to power some 75 billion annual connections that reach 1 billion devices. Match.com makes matches without revealing phone numbers; Airbnb sends rental notifications, and the American Red Cross deploys volunteers, all through Twilio. ING, the European banking giant, recently announced it was closing down 17 hardware and software systems across its global call centers and replacing all of it with Twilio. Twilio’s largest customer, WhatsApp, uses them to verify customer accounts and logins. Apps from Lyft, Expedia, Netflix, Coca-Cola, Salesforce and the New York Times all have Twilio inside. The company saw 70% growth last quarter.”
The stock went public at $15 in June and closed the first day at $29, up 92%. Here’s your chance to buy it at a reasonable valuation.
Apple Corner
Apple (AAPL: $114, down 2%) announced a new record stockpile – of cash: $238 billion, up $6 billion in the quarter. So that means they are producing cash at the rate of $460 million a week, or $92 million per work day. Unreal. And yes, most of that cash is overseas, in Ireland. As we’ve said before, this doesn’t upset us or concern us. It’s like being worth $10 million personally, and having $9 million of it in Ireland. That works for us!
Tim Cook says he has no plans to change where the cash resides as it would cost him 40% in taxes to bring it back. We at The Bull Market Report believe the tax code will be changed sometime in the next few years and that will allow the cash to come back and be put to work harder than it is now. Stock buybacks, buying new technology, super big dividend distributions – all of these will be in the cards in the future.
Again, $44 of every share you buy is in cash - 38% of every share. This is unprecedented in financial history.
AmerisourceBergen Takes a Hit
McKesson (MCK) hit a 52-week low Friday, falling 23% Friday, reaching $114 per share before bouncing back to $125 before market's close. The company reported worse than expected earnings of $2.94 per share, missing consensus estimates of $3.05 per share. McKesson also adjusted its earnings outlook lower.
This miss was attributed to pressure put on the drug pricing industry that the company doesn't expect to let up any time soon. Investors balked at the news, causing not only McKesson, but its peers, to fall. Competitors Cardinal Health (CAH) and AmerisourceBergen (ABC: $69) also fell Friday - 10% and 13% respectively - on the news.
This is devastating to us. We expected a lot more from ABC. We added them in April at $91 and were looking for triple digits this year. Instead, they have disappointed every step of the way. This is the last straw. We aren’t waiting for our Sell Price of $67. We are removing the stock now.
Tesla Posts Best Sales Ever and a Quarterly Profit
Tesla Motors (TSLA: $200, flat) posted its second quarterly profit as a public company and its best sales period on record, helped by the new Model X sport-utility vehicle. The stock hit $213 on Thursday but settled later in the day and Friday. Profits were $22 million, or 14 cents a share, compared with a loss of $230 million, or $1.78 a share, a year earlier. On an adjusted basis, it had per-share earnings of 71 cents. Revenue shot up to $2.3 billion. The increased sales and profit come as CEO Elon Musk pushes the company to create new models, including the Model 3 sedan slated for next year, and to finish building the world's largest battery factory.
The company announced new products - solar-powered glass roof tiles that eliminate the need for traditional panels and longer-lasting batteries aimed at helping to realize Musk's vision of selling a fossil fuel free lifestyle to consumers. Unlike most solar panels in the market (which are made of photo voltaic steels that are installed over traditional roofs), Tesla’s solar roofs are made of quartz glass. This means that there is no need for a roof, if you are using Tesla’s product. In addition to being aesthetically pleasing and remarkably like standard roofing tiles in appearance, Tesla’s tiles are also durable.
But note that much of this announcement of new products is contingent on the merger going through with Solar City. Boy, he’s living on the edge.
BMR Take: Musk is at it again. Big announcements for the future. And profits in the present. Gotta hand it to this guy. Again, this stock is very volatile – be careful. It’s on the way to $300 a share but may pass through $150 first. And if it hits $300, it’s going to $400.
Blackstone Group (BX: $25.50, up 6%) The company sold $7.2 billion in real-estate assets in the third quarter and investors have poured $70 billion into its funds in the first nine months of the year, pushing Blackstone’s assets under management to a record $360 billion. They have $100 billion available to spend on new investments.
Blackstone has been selling assets to the Chinese in a big way this year and for the last three. They sold 25% of Hilton Worldwide Holdings for $6.5 billion and sold Strategic Hotels and Resorts for $5.5 billion. It also unloaded the Waldorf Astoria for $1.95 billion. The firm is awash in liquidity and that bodes well for the firm for 2017.
But the stock continues to lag, which is killing CEO and co-founder Steve Schwarzman. We have said and will say again that he is doing everything in his power to get the stock higher and HE WILL SUCCEED. It may not be this year, but it will happen. No one is going to stop this man, who just happens to be the firm’s largest shareholder.
High Yield Corner
Politics stole the headlines just as the markets were getting ready to end the week. With news that the FBI is investigating Hillary Clinton’s emails again, the market took a nose-dive, causing the S&P 500 to end down nearly 1% for the week. No matter your political leanings, it seems clear that the market does not like what this investigation means for the election. Additionally, those concerns are even bigger for just about all high yield asset classes.
There are a couple of reasons for this. First is liquidity. If the market decides the presidential election is bad news for the economy and/or stocks, it’s going to hit the S&P, but it’s going to hit the corporate bond market even harder. This is because suddenly risk-averse investors will pull money out of the bond market, meaning less liquidity. Mutual funds, institutional investors, pension funds, and other big market participants who need to offload corporate bonds will find it harder to locate a buyer, causing prices to fall. Yields will rise as a result (prices up - yields down), which means borrowing money will cost even more for companies. This, in turn, will cause default rates to go higher and cause less companies to take out loans in the first place. With less access to capital, companies will stop investing, which will in turn lower productivity and GDP growth.
This is a downward spiral that could happen if the market panics - and the longer the panic, the worse the effects.
Of course, this is an extreme scenario. It would take months of investor panic to cause corporate bonds to go in this direction, and it’s unlikely that a presidential election could cause such a long-term reaction. In fact, when presidential election results impact the market, they tend to do so for a month or two at the most - not enough to cause the kind of disaster in the bond market we’re describing. However, this is no ordinary election, and the market has priced corporate bonds very, very high. As a result, there is greater danger in corporate bonds than we’ve seen in a long time.
To demonstrate just how expensive corporate bonds are, we only need to take a look at the BofA Merrill Lynch US High Yield Master II Effective Yield index. It’s a mouthful, but it’s an important financial metric that focuses on one thing: What is the average interest rate junk bond-rated companies need to pay on their debt. Back in February, that rate was 10%. It’s now 6%.
Let’s think about this for a minute. U.S. Treasuries are yielding a bit less than 2%. A-rated municipal bonds are yielding around 3%, with lower-rated municipalities yielding around 4%. Yet even among low-rated municipalities, the default rates are far less than 1%. Corporate bond default rates are approaching 6%. Is that higher risk really worth an extra 2% yield?
In a low-rate world, the answer would seem to be yes - but the Federal Reserve is looking to raise interest rates. By itself, this will raise yields on corporate bonds. Additionally, it will also cause less money to flow into corporate bonds and encourage higher yields. The low corporate yields in the current market, the promise of higher interest rates, and the political unrest could spell danger for corporate bonds.
This is a complex and multi-faceted situation, but understanding the context is important. Right now corporate bonds are priced to perfection and the coming storms indicate weakness might be around the corner. The corporate bond market is beginning to wake up to this. The SPDR High Yield Bond Fund (JNK: $36) fell over 1% this week. More declines are likely to come, especially since junk bonds have recovered from their correction this summer.
What’s even more worrying is the lack of movement in the BDC space. The UBS Etracs BDC Fund (BDCS: $21) ended the week flat, but BDC investors should be aware that this space is even more susceptible to defaults than the junk bond market. Investors should be hedging their BDC exposure in response to this, but they are not. This is likely being driven by two factors. Firstly, a lot of BDC investors have come into the sector in search of yield, and find few alternatives elsewhere. Secondly, and most crucially, a lot of BDC investors are relatively unsophisticated. Corporate bond markets involve institutional investors managing more money than there is in the stock market; BDCs, however, have a combined market cap in the tens of billions of dollars, meaning the entire industry is smaller than many investment banks and a few hedge funds. This is an inefficiency that will eventually result in greater BDC volatility.
Where does that leave us when we consider our one BDC pick - Main Street Capital (MAIN: $34)? Main Street ended the week up 1% yet again and is now up 17% year-to-date despite its NAV remaining relatively stable. We recognize there is greater risk in holding Main Street now than before, which is why we’re lowering our target price to $35 from $40. We want to hold onto Main Street to capture the December special dividend, but we also need to recognize the greater potential volatility in BDCs right now and the market’s stubborn refusal to acknowledge this mounting risk.
Finally, a word on REITs. What an awful week for this class of assets. The SPDR Dow Jones REIT fund (RWR: $90) fell over 3%. Again, Federal Reserve moves are causing fear in this sector. We still love Omega Healthcare Investors (OHI: $31, down 3%, after 61 cent dividend), Kimco Realty (KIM: $26, down 6%), and Digital Realty Trust (DLR: $93, down 3%). We recommend adding on the recent weakness here.
Government Properties Income Trust (GOV: $19, down 8%). It is hard to watch the market punish this company. They own great assets, have a solid dividend and strong coverage of the dividend. But we also think the market will punish it more as the market sours on REITs broadly. Some might say that the risks aren’t worth the potential reward right now, so you will have to make up your own minds on this. For the time being we are sticking with the company since we are still above the price where we added the stock in April at $17. But be prepared for a lower price on this one. We just feel there is so much value here that we can’t bring ourselves to remove the stock from our portfolio.*
*Note that the stock is in our Special Opportunities portfolio, but we are moving it over to the High Yield Portfolio.
Good Investing,
Todd Shaver
Editor in Chief
The Bull Market Report
October 26, 2016
by Todd Shaver | Oct 26, 2016 | Earnings Preview 6 AM
October 26, 2016
Tesla (TSLA: $203)
Earnings Date: Wednesday, 4:30 PM ET
Consensus: 3Q2016
Revenues: $2.3B
EPS: $0.07
Year Ago Quarter Results
Revenues: $965M
EPS: -$0.57
Key Things to Watch For in the Quarter
Tesla will announce its third quarter earnings results for 2016 today after the close. Analysts are estimating earnings of $0.07 per share, a drastic increase from 2015’s third quarter loss of 53 cents. From a sales perspective, Wall Street’s consensus forecasts a 91% increase in revenue to $2.3 billion. It’s been a rough ride for Tesla shareholders this year, from flaming cars, to the electric car company’s acquisition of its cousin SolarCity. With all of these ups and downs the stock has held steady for the past year, basically flat. However, with the South African native Elon Musk, at the wheel, innovation is always in the headlights. The firm’s $5 billion GigaFactory for the in-house production of batteries is likely just a glimpse of what’s to come.
Tesla has a busy quarter ahead of them. They recently released a new update for their autopilot that will curb safety concerns. The SolarCity deal has continued to be a drag on the stock. The key driving growth factor for this company is a multitude of projects and continued growth. They are also meeting their increased output goals new car sales.
Alphabet (GOOG: $813)
Earnings Date: Thursday, 4:00PM ET
Consensus: 3Q2016
Revenues: $22.0B
EPS: $8.62
Year Ago Quarter Results
Revenues: $18.7B
EPS: $7.35
Key Things to Watch For in the Quarter
Analysts estimate that Google will report earnings of $8.62 per share, a 17% increase from 2015’s third quarter. Revenues are also expected to climb about 17% to $22 billion.
Alphabet continues to grow at an incredibly fast rate due to its hold over the online advertising industry. Their main source of revenue (search) continues to grow and be profitable for the company. Investors have reacted strongly to the last six of seven earnings events in the first trading session following its announcement, so watch out. Year-to-date, shares have strongly outperformed the Nasdaq by about 9 points (14% to 5% respectively). We love this company. Will they split again when it hits $900?
Blackstone (BX: $25)
Earnings Date: Thursday, 6:00 AM ET
Consensus: 3Q2016
Revenues: $1.55B
EPS: $0.65
Year Ago Quarter Results
Revenues: $1.2B
EPS: -$0.35
Key Things to Watch For in the Quarter
Analysts forecast fairly significant growth for Blackstone this quarter, with an estimated 29% increase in revenue to $1.55 billion and earnings of 65 cents per share compared to last year’s third quarter loss of 35 cents.
The stock is currently trading at the low end for the year, within $3 of its 52-week low of $22.30 (the high was $34). In 2015, the company raised a record $95 billion from long-term investors, displaying an inconsistency between the stock’s performance and long-term trust of investors. The stock is attractive to those seeking an alternative to this low interest rate environment, with a dividend yield of 7%. With projected growth of earnings, we may very well see the stock’s dividend increased over the coming quarters. We have continually stated that the stock is undervalued - 13 stock analysts who cover the stock have an average target of $32. We expect to be right in a big way later this year and next.
United Parcel Service (UPS: $108)
Earnings Date: Friday, 4:00PM ET
Consensus: 4Q2016
Revenues: $14.7B
EPS: $1.44
Year Ago Quarter Results
Revenues: $14.2B
EPS: $1.39
Key Things to Watch For in the Quarter
United Parcel Service will announce its third quarter earnings for 2016 after the closing bell on Friday. Wall Street analysts estimate moderate growth since the same quarter last year. Per share earnings are expected to increase 4% to $1.44. Revenue is also expected to grow 4% to an estimated $14.7 billion.
Increased investments in technology and productivity are paying off for UPS as it continues to be a bastion of growth in the eCommerce world. The company’s 2.9% dividend yield also makes UPS a great stock, as this added benefit of ownership provides investors an alternative to low yielding bond markets. Other strengths include good cash flow from operations and notable return on equity. Year-over-year, the stock is outperforming the overall market a bit, appreciating 5%. We see it to be undervalued.
October 25, 2016
by Todd Shaver | Oct 25, 2016 | 7am News Flash
Visa (V: $83) reported a 28% rise in quarterly profit yesterday. Net income rose to $1.93 billion, or 79 cents per share in its fiscal fourth quarter ending September 30, from $1.51 billion, or 62 cents per share, a year earlier. Total operating revenue rose 19% to $4.26 billion.
The world's largest payments network operator had a great quarter. We expect even better things from Visa in the future.
Apple (AAPL: $117)
Earnings Date: Tuesday 4:10 PM ET
Consensus: Fiscal 4Q2016
Revenues: $46.9B
EPS: $1.65
Year Ago Quarter Results
Revenues: $51.5B
EPS: $1.96
Key Things to Watch For in the Quarter
Analysts throughout Wall Street forecast that Apple will earn $1.65 per share in the third quarter. This value represents a 16% decrease in comparison to last year’s third quarter. Revenues are also forecast to slip, by about 9% to $46.9 billion. So far this year the Silicon Valley technology goliath has underperformed revenue estimates in both of the previous quarters.
In addition to releasing their quarterly earnings report, this week Apple is expected to launch its newest MacBook Pro, a major event for the firm given the year-over-year decline in iPhone sales. This will benefit them in the interim between now and the release of the 10th anniversary iPhone next summer. Apple won’t let that magical date go without releasing something major. An increase of sales is expected.
Since the meltdown of Samsung’s Note 7, Apple shares have gained approximately $15 indicating that the market expects the Silicon Valley technology machine to regain some market share in the smartphone space from the Korean company.
Under Armour (UA: $38)
Earnings Date: Tuesday, 4:00 PM ET
Consensus: 3Q2016
Revenues: $1.45B
EPS: $0.25
Year Ago Quarter Results
Revenues: $1.2B
EPS: $0.23
Key Things to Watch For in the Quarter
Under Armour has made a lot of positive strides over the years. It has seen 25 consecutive quarters of uninterrupted growth. This quarter’s analysts’ consensus puts EPS flat while reaching $1.45 billion in revenue, representing a 20% climb from last year’s third quarter.
For the fourth quarter, consensus calls for earnings of 28 cents per share, up from 24 cents a year-ago. Revenue is expected to jump by 22% percent to $1.43 billion.
Under Armour is expected to report 2016 earnings per share of 59 cents on revenues of $4.95 billion. This represents an 11% increase in profits and a 25% increase in revenue.
With strong management, led CEO Kevin Plank, the sportswear company has continued to grow over the past two decades with much thanks to its increased brand visibility. This can be credited to its athlete endorsers including NBA MVP Stephen Curry, NFL MVP Cam Newton and MLB National League MVP Bryce Harper. Currently, the stock is undervalued. We will continue investing in a company that is filled with high growth and great potential. Although the firm has beat estimates in the past two quarters, the stock is down 20% year-over-year, making it an amazing value for growth investors. We hereby beat the drums for Under Armour.
Equity Residential (EQR: $61)
Earnings Date: Tuesday, 4:00 PM ET
Consensus: 3Q2016
Revenues: $602 M
EPS: $0.78
Year Ago Quarter Results
Revenues: $666 M
EPS: $0.80
Key Things to Watch For in the Quarter
Consensus for the third quarter of 2016 has Equity Residential’s earnings decreasing approximately 10% to $0.78. Revenue estimates are also expected to decline 10%, to $600 million. Of the past four quarters, Equity Residential has met EPS expectations of analysts twice, in 1Q16 and 4Q15. This residential Real Estate Investment Trust (REIT) with primary holdings in New York, Los Angeles and San Francisco, has long been benefiting from the high rental market. The company strategically avoided the threats of Hurricane Matthew by liquidating large holdings of apartments in Florida last quarter, giving the firm flexibility to diversify its portfolio with other emerging cities throughout the nation. The healthy 3.3% dividend also makes it an attractive play as investors struggle to find reasonable returns in today’s low interest rate environment. The stock is down 23% year-to-date giving us an opportunity to invest in one of the finest apartment owning company in the country.
CBRE Group (CBG: $28)
Earnings Date: Wednesday, 6:00 AM ET
Consensus: 3Q2016
Revenues: $3.3B
EPS: $0.50
Year Ago Quarter Results
Revenues: $2.7B
EPS: $0.51
Key Things to Watch For in the Quarter
The firm is a commercial real estate services and investment company that operates through its subsidiary divisions: The Americas; Europe, Middle East and Africa; Asia Pacific; Global Investment Management, and Development Services.
Revenue is strong this quarter as they continue to expand into other real estate markets. Last year’s quarter revenues were at $2.7 billion compared to the expected revenues of $3.3 billion this quarter.
CBRE is one of those under-the-radar companies. We find this amazing for a company worth $9 billion, but we have exposure to some of the things the company is doing and believe the stock to be very undervalued. The company has a wide range of tentacles in the US real estate market, all of which are designed to make money for their clients and produce revenue for CBRE itself. They also have strong international exposure. The company continues to grow and enhance their global geographic reach. Their stellar management and trajectory puts them on a path for continued growth.
October 25, 2016
September 19, 2016

by Todd Shaver | Sep 19, 2016 | Monthly Newsletter Daily 6am if new
The Week Ahead
It was a week of ups and downs last week, with the Nasdaq up big, due to Apple and other Tech, and two out of the three major indices ending flat. There is clear confusion. World class investors at the Delivering Alpha Conference hosted by CNBC in NYC this week could not even agree which way the market is heading. While volatility has started to rise, we believe the moderation that was seen toward week end reflects a wait and see attitude surrounding what the Fed will do next week at their meeting. The probability for a rate hike is only 20%, but we are bracing for a potential surprise, as the Fed needs to prove to the market that it will hike rates, counter to low market probabilities, in order to demonstrate that they are leading the market and not the other way around. With all the volatility and uncertainty, we continue to stress top quality stocks as the place to be.
Here is How Last Week Progressed:
Monday (9/12) – S&P 500 +1.8%
— Markets rallied after Friday’s big selloff. Goldman Sachs issued a report calling for last week’s bond market selloff, triggered by UK concerns and Japan monetary policy, to extend into the 4th quarter, with US Treasuries reaching 2% by year-end (currently 1.69%).
— In Energy, a ratings agency issued a new report discussing how recovery rates for 15 US exploration and production bankruptcies averaged a “catastrophic” 20% last year, well below the historical average of 60%. (So out of those that go bankrupt, lenders are getting back just 20 cents on the dollar vs. 60 cents. Not good.)
— In Financials, Wells Fargo (WFC: $45, down 7% last week)admitted to secretly creating millions of bank and credit card accounts over the past five years without their customers’ knowledge or consent. An entire arm of the bank was fired over the matter and the stock is down sharply.
Tuesday (9/13) – S&P 500 -1.5%
— Monday’s recovery turned wobbly as concerns of general global economic conditions are increasing.
— The Delivering Alpha Conference in NYC hosted some of the brightest and richest minds in investing. Billionaire Paul Singer issued cautionary words for the path ahead discussing how it’s a very dangerous time in the global economy and global financial markets, adding that gold was under-represented in investors’ portfolios. Billionaire Ray Dalio warned that the current environment is analogous to the 1935 to 1945 period in America where we reached the limits of central banking’s ability to stimulate the economy and raise global asset prices.
— A US think tank warned that Australia has about six weeks or so to turn their situation around or face a massive hit to property valuations.
— Another Fed president has decided to call it a day. President of the Atlanta Fed Dennis Lockhart announced he will be stepping down on February, 2017.
Wednesday (9/14) – S&P 500 -0.1%
— Markets stood still.
— Goldman Sachs issued reports reducing their odds for a hike next week to 25% from 40% previously.
— CNBC hosted numerous conversations about the volatile mechanics of the stock and bond markets simultaneously selling off over the past week.
— In Healthcare, an undercover investigation by the Government Accountability Office found that 100% of their fictitious enrollees were able to sign-up and maintain Obamacare coverage and taxpayer subsidies despite submitting fictitious documents and/or refusal to submit any documentation at all.
Thursday (9/15) – S&P 500 +1.1%
— The morning began with news of the biggest German M&A deal in history. Monsanto accepted Bayer’s takeover offer for $66 billion creating an agriculture giant.
— More concerns about markets soon followed. Former Fed Chairman Allen Greenspan made public comments discussing how this is the worst economic and political environment that he has ever been remotely related to, noting that the U.S. is headed toward stagflation. New data soon after the statement confirmed Greenspan’s concerns.
— Year-over-year growth in Retail Sales rose just 1.9%, which represented the weakest level since March’s plunge and is now worryingly in historical recession territory.
Friday (9/16) – S&P 500 -0.9%
— Market performance was soft into the weekend. In Autos, just weeks after warning that sales had reached a plateau, Ford is now warning investors that operating profit will fall in 2017 and as a result the company is relocating small car production to Mexico.
— In Transportation, bankrupt shipping giant Hanjin said that as of this morning it had 93 vessels, including 79 container ships, stranded at 51 ports in 26 countries.
— Gearing up for next week’s Fed meeting, former Fed leader Ben Bernanke was out with some noteworthy comments foreshadowing the future path of interest rates in the US – negative! Specifically, he said, “The fact that negative rates would be temporary and deployed only during severely adverse economic conditions, would be an advantage. Like quantitative easing, which was also unpopular in many quarters, a period of negative rates would probably be tolerated by politicians if properly motivated and explained.”
Bull Market Report Companies and Commentary
Microsoft (MSFT: $57) Microsoft is a high quality bellwether. Recent reports indicate that channel partners* see strong business trends for the company’s Cloud product, Azure. Azure is a key pillar of expected EPS growth embedded in consensus forecasts. Accordingly, it is a good sign to hear that Azure is on track with expectations.
* A channel partner is a company that partners with a manufacturer or producer to market and sell the manufacturer’s products, services, or technologies, usually done through a co-branding relationship. Channel partners may be distributors, vendors, retailers, consultants, systems integrators (SI), technology deployment consultancies, and value-added resellers (VARs) and other such organizations.
To be more specific, channel partners are seeing strong sustained growth for Microsoft Cloud products, with a couple of partners underscoring a pronounced uptick with respect to Azure. One partner recently observed a renewed push by Microsoft to make inroads into the federal government vertical with its government Cloud. Lastly, a few channel partners referred to overall softness in their legacy Microsoft practices, partially driven by a faster-than-expected transition into the Cloud. This should be read as good news. Basically, the use of office desktop products is slowing because companies are transitioning to the Cloud.
We like that trend. We are fine with the legacy Microsoft business declining if the customers are moving to the Microsoft Cloud. It’s quicker and better, and a higher valuation is applied by the Street for the Cloud versus the desktop business
While Microsoft’s Azure product faces fierce competition from Amazon’s comparable AWS offering, one channel partner noted that Microsoft’s head start in the market with Office 365, along with their inherent long term relationships in Enterprise IT gives Microsoft a slight advantage in the Cloud space as compared to Amazon.
In fact, there is currently talk of an enormous energy conglomerate that has physical data centers in multiple countries which they are finding incredibly difficult to manage and scale and hence is thinking of moving to a Cloud infrastructure model. While this company has engaged both Microsoft and Amazon, the company appears to have a preference to go with Microsoft Azure because of the long standing relationship with Microsoft. This case study reinforces the storyline that Microsoft has created enough of a reputation now so that Amazon doesn’t seem like the only company in the public Cloud space.
BMR Take: The Cloud business is booming. Microsoft’s Azure product is recording revenue growth of greater than 100% a year. Channel partners are suggesting momentum is building. We view Microsoft as a high quality portfolio holding with an attractive dividend yield and substantial upside ahead.
Facebook (FB: $128) Weak sentiment surrounding the stock presents a buying opportunity. Facebook has delivered three consecutive quarters of 60%+ ad revenue growth, with an acceleration in four of the past five quarters. Street estimates have an upward revision bias with the 2017 consensus EPS having increased 35% so far this year. The overall lack of enthusiasm is reflected in the lower forward PE multiple and creates an opportunity.
One debatable topic right now is ad growth. Despite management’s caution on the 2Q16 earnings call, ad loads still have room to increase. Ad loads are a less significant growth driver of EPS estimates than many appreciate. Street estimates now call for slowing ad load growth to around 10% this year and actually declining in 2017-2018. Though there are several levers for management to focus on to drive improvement. For example, the company is currently working on ad targeting, relevancy, formats, and profitability in ways that don’t alter the user experience. Facebook still has opportunity ahead for ad load growth despite the recent near term headwinds.
Another debatable topic right now is engagement. Despite a small sequential drop in 2Q16 daily and monthly active users across all regions, the overall ratio of daily to monthly active users remains steady at 66%, which highlights the stickiness of the customer base. Moreover, Facebook’s share of US mobile Internet time of 13% is 2x greater than Snapchat, Twitter, Instagram combined, which highlights how healthy engagement remains. Recent product changes such as prioritizing friends and family in the Facebook and Instagram feeds and the launch of Instagram Stories may acknowledge shifting usage and increased competition, at least in certain demographics, but we expect Facebook to remain innovative on products. We are not concerned about a slight slowing of engagement.
BMR Take: We think weak sentiment surrounding ad growth and engagement presents a buying opportunity. Street price targets are as high as $170, framing the compelling upside potential. We added the stock in February at $97, and we are approaching our Price Target of $140. We are pleased.
Tesla (TSLA: $206) Tesla released an Autopilot update announcing advanced signal processing capabilities for its radar, which can now act as a primary control sensor and does not require the camera to confirm visual image recognition. It is just another sign of the transformational shift in auto manufacturing, where Tesla is leading the way,
Digging into the new technology a bit, the software upgrade collects more data in order to better determine the risk of a collision and prevent unnecessary braking. All very exciting stuff. In fact, just in the past few days at Ford’s annual investor day, Chairman Bill Ford acknowledged that “the technology is here in the world of autonomous driving, but there are a lot of things to work through and we have something to learn from every competitor [inferring Tesla]”. This was quiet the notable endorsement for the direction Tesla is heading.
Note that Robert W. Baird set a $338 price target on Tesla on Monday. FBN Securities upped their price target from $260 to $275 and gave the stock an outperform rating. Morgan Stanley reaffirmed an equal weight rating and set a $245 price target. Six research analysts have rated the stock with a sell rating, 13 have a hold, 10 have a buy rating and two have assigned a strong buy to the company. The consensus target price is $253.
BMR Take: We view the AutoPilot announcement as a positive that shifts focus back to Tesla’s core competitive advantage as a leader in the development, distribution, and monetization of ground-breaking automotive technologies. With that said, we await more news of the Gigafactory progress; the progress of the integration of SolarCity into the future of Tesla; and how in the world they can deliver on the 400,000 orders for the new Model 3 (for which they received $400 million in cash from the down payments.) These are the big picture items. And again, Tesla is RISKY. The stock could go to $400 in the next year or two, or it could go to $70. Or both. This one is volatile and not for the faint of heart.
Visa (V: $82) We have seen some big headlines in the stock market in recent weeks, but this company just quietly continues to perform. We want to be sure this stock doesn’t fall off your radar.
There are several catalysts that appear to be pushing stronger top line revenue growth including improved cross-border volumes, new deal wins (Costco, USAA), price increases (adds 100 bps to the growth rate), and accretion from the Visa Europe deal.
On cross-border volume, Visa is optimistic about improving trends as oil and the stronger US dollar comparables ease. Visa isn’t seeing any pricing pressure on cross border fees and is seeing significant growth in online commerce (the growth of digital grows at double the rate of offline). Cross border is 6-7x more profitable than domestic transactions.
Another big opportunity coming out soon is their entering the China market. Although there is no specific timeline yet, there is a big future opportunity to process Chinese domestic volumes and more Chinese cross-border transactions. In fact, some analysts size the opportunity to be $3 billion of revenue by 2020. Currently, Visa is focused on adding-single branded Visa cards to the Chinese market, while the cobrand relationships move towards expiration.
BMR Take: Visa is a very steady business model and a proven stock. The global opportunity to convert cash to electronic forms of payments remains lucrative. We continue to view this stock as a long term core holding.
Qualcomm (QCOM: $63) With all the news out on the Apple iPhone 7 launch, we can’t overlook the implications to Qualcomm. Eyes are on the Intel baseband share of the iPhone 7 business because the remaining share falls to Qualcomm.
Multiple reports have surfaced claiming to be able to discern the amount of share that Intel has taken in the iPhone 7. It is a bit premature to make a pronouncement on this, given that Apple is likely only slowing letting Intel into their phones. Either way, the impact is confined to only a 65% subset of iPhones that are non-CDMA* capable. Moreover, it is very likely that Apple is very slowly introducing Intel into the product line, considering recent major disruptions others in the industry have experienced, like with Samsung’s recent migration to a new chip stumbled.
*CDMA stands for code division multiple access, which is a channel access method used by various radio communication technologies. It often determines what network (Verizon, AT&T, etc.) your iPhone will work on).
To be clear, Qualcomm is expected to continue to hold 100% share in CDMA capable smartphones. According to industry estimates, CDMA capable smartphones represented 30% of total iPhone unit volume over the past 12 months and 35% in the 2nd quarter. As referenced above, the 65% of 2Q unit volume that was not CDMA capable is where Intel is possibly taking share. Some more aggressive expectations presume Intel may take the lion’s share of this 65% bucket. However, more in-depth analysis from industry experts points out that it is entirely possible that even where Apple is using Intel they may also be using Qualcomm in the same model. Bottom line, the Intel versus Qualcomm market share discussion in the iPhone remains pure speculation at this point, but is a must-watch trend going forward.
The most important trend to watch, however, is overall smartphone demand which remains strong.
BMR Take: We continue to like the prospects for the Apple ecosystem, which includes Qualcomm. Moreover, shares look attractive here with a 3.3% dividend yield. Qualcomm is a cash machine riding the smartphone wave to higher levels.
Home Depot (HD: $126) Management was on the road these past two weeks meeting with investors. Several favorable takeaways on the business surfaced. The Western part of the US continues to see strength, as Home Depot attributes it to more than just a California story, with a mini Silicon Valley forming in the Northwest states and great momentum around this build out. Phoenix is also improving and they believe there is a strong upside to the market based on how much there is left for that housing market to appreciate to reach the prior peak. Home Depot generates 1/3rd of its sales in the West.
Management highlights that the Pros customer base (professionals) are a little less price conscious given that they want to be able to know their costs and seem to have less patience for following promotions. Recall that 40% of sales is generated by the Pro customer.
Lastly, management noted that their second half guidance is not just based on the strength of the housing market but also feedback from the Pro customer base; that the project pipeline is strong for at least the next six months. Management noted that the Pros are taking vacations for the first time in years based on the healthy labor market.
BMR Take: Solid trends are seen over at Home Depot. The implications are good for the broad economy and stock market. We continue to favor this blue chip.
Gilead Sciences (GILD: $79) We thought we would give you some news on recent upgrades and research reports have been issued on Gilead. A large bank in Germany issued a buy rating and a $112 price target on the stock. Barclays reaffirmed an overweight rating. RBC Capital Markets set a $105 target price on Gilead and gave the stock a buy rating. Morgan Stanley has a price target of $103. Nine research analysts rate the stock with a hold, 18 have a buy and two have issued a strong buy rating on the company. The company has a consensus rating of Buy and a consensus price target of $105.
Gilead last posted its earnings results on July 25th. They reported $3.08 EPS for the quarter with revenue of $7.8 billion. On average, equities analysts predict that Gilead Sciences will post $11.80 for the current year.
The business also recently announced a quarterly dividend, to be paid on September 29th. The $1.88 annualized dividend produces a yield of 2.4%, paying out just 17% of earnings. There is plenty of room for growth in the dividend here.
Hedge funds and other institutional investors have recently added to their stakes in the company. Norges Bank acquired a new position in Gilead valued at about $1.3 billion. Bank of Montreal acquired a new position in Gilead Sciences during the second quarter valued at $430 million. Capital World Investors boosted its position in Gilead Sciences by 28% in the second quarter. They now own stock valued at $1.3 billion. Investec Asset Management acquired a new position during the first quarter of $280 million. Finally, Parnassus Investments CA boosted its position by 45% in the second quarter. Parnassus now owns $700 million. 78% of the stock is owned by institutional investors and hedge funds.
BMR Take: The stock has a market cap of $102 billion and a price-to-earnings ratio of 7. The stock is grossly undervalued and we expect the stock to go back to the triple-digit level late this year or next.
Upcoming Economic News
It is a very light week for economic news. The focus will be on the FOMC statement out Wednesday. The probability of a rate hike is just 20% with >50% odds that a hike will not occur until December. But who knows! Yellen now has Bernanke in her corner prescribing possible negative rates.

Under Armour Update:
Kevin Plank, CEO and Founder of Under Armour (UA: $39) announced that he will be selling 2.1 million shares of stock starting in October. A subscriber wrote in and asked our opinion of the situation, as he thought this was a bad thing.
Here’s what we wrote back:
“Hi Samuel –
“We generally don’t mind if executives sell stock. Plank currently owns 34 million shares of the company’s Class B stock, 135,000 shares of Class A stock and 34 million shares of Class C stock, representing 65% of the voting power in the company. So 2 million shares is a small part of his holdings. He is just diversifying.”
That’s how we feel. Of course, we secretly wish we had 2 million shares to sell of our own, and we admire Plank and all the others that have created all of the amazing companies out there, like Amazon and Facebook and Google, and so on. This is America. The entrepreneurs and the risk takers shall reap the rewards. Again, we would not even blink a negative eye over this CEO selling a small part of his stake in the company. Bill Gates has been selling 20 million shares a quarter since 2002. Wow. And we still love Microsoft.
THE APPLE CORNER
Apple had a great week. The stock was up $12, or 11%, closing at $115. I hope you are listening to us here at The Bull Market Report as we’ve been pounding the table on Apple for months! The stock saw its strongest four-day streak in over two years and is destroying short sellers who bet against it. The newest fuel was Apple’s announcement that initial quantities of the iPhone 7 Plus have sold out globally. Sprint said sales set records, far out-pacing sales of the iPhone 6 two years ago. That sent the stock up 3% on Thursday, after a 3% rise on Wednesday.
It was the strongest 4-day percentage increase since 2014, when Apple shot 13% higher over four days after the company increased its share buybacks and announced better-than-expected quarterly result.
Apple was responsible for much of this week’s gains in the Dow Jones Industrial Average. If Apple had been unchanged this week, the Dow would have been down 0.1%, instead of the 0.2% gain it recorded.
Apple on Tuesday made available new software (at no charge) for iPads and iPhones bringing huge enhancements to Messages, Maps, Siri, Photos, Apple Music, News, and more. This is what customers love about the company. And this is what WE at The Bull Market Report love about the company.
BMR Take: The stock trades at a PE of 14 times its past 12 months of earnings compared with 20 for the S&P 500. Will we see new highs ($134) in the stock by Christmas?
Good Investing,
Todd Shaver
Editor in Chief
